


1. Introduction
The optimal asset allocation problem has long been an important topic in financial economics. Merton [Reference Merton30,Reference Merton31] pioneered the study of an optimal asset allocation problem in a continuous-time modeling setting, where the objective was to maximize an expected utility. He employed stochastic optimal control theory, in particular dynamic programming, to discuss the optimal asset allocation problem. For a power utility function, Merton obtained a closed-form solution to the problem which is known as the Merton ratio. Pliska [Reference Pliska34], Karatzas et al. [Reference Karatzas, Lehoczky and Shreve17] and Cox and Huang [Reference Cox and Huang5] pioneered a martingale approach to optimal asset allocation in continuous time. The general principle of the martingale approach is not unlike that of the martingale pricing, or risk-neutral pricing, of a derivative security, where an equivalent martingale measure, or a pricing kernel, is a key tool.
Recognizing that structural changes in economic conditions may have significant impacts on asset allocation decisions, much attention has recently been given to optimal asset allocation in Markovian, regime-switching, asset price models. There is quite a large amount of work in the literature on this topic. Some examples are Zhou and Yin [Reference Zhou and Yin42], Honda [Reference Honda16], Sass and Haussmann [Reference Sass and Haussmann36], Baeuerle and Rieder [Reference Baeuerle and Rieder1], Nagai and Runggaldier [Reference Nagai, Runggaldier, Dalang, Dozzi, Russo and Birkhaeuser32], Sotomayor and Cadenillas [Reference Sotomayor and Cadenillas41], Elliott et al. [Reference Elliott, Siu and Badescu11], Liu [Reference Liu28], Korn et al. [Reference Korn, Siu and Zhang24], Siu [Reference Siu38,Reference Siu40], Capponi and Figueroa-López [Reference Capponi and Figueroa-López3], Fu et al. [Reference Fu, Wei and Yang13], Barucci and Marazzina [Reference Barucci and Marazzina2], and Shen and Siu [Reference Shen and Siu37]. Some of these works considered the situation where the underlying Markov chain was observable while others considered the situation where the chain was hidden. In the latter case, filtering of the hidden state was discussed. Basically, in these works three major approaches, namely the dynamic programming approach, the martingale approach together with Malliavin calculus, and the backward stochastic differential equations approach, were used to discuss stochastic optimal control problems arising from optimal asset allocation in Markovian, regime-switching, asset price models. One may refer to, for example, Siu [Reference Siu40] for some related discussions.
The optimal asset allocation problem with derivative securities has been studied by some authors; some examples are Korn and Trautmann [Reference Korn and Trautmann22], Haugh and Lo [Reference Haugh and Lo14], Kraft [Reference Kraft25], Liu and Pan [Reference Liu and Pan29], Detemple and Rindisbacher [Reference Detemple and Rindisbacher8], Cui et al. [Reference Cui, Oldenkamp and Vellekoop6], and Fu et al. [Reference Fu, Wei and Yang13]. Korn and Trautman [Reference Korn and Trautmann22] studied an optimal consumption–investment problem with derivative securities in the presence of trading constraints. They considered a continuous-time model with multiple risky assets, where the price processes of these assets were described by a multi-dimensional geometric Brownian motion. They combined the option replication approach with the martingale approach to derive an explicit solution to the utility maximization problem. Haugh and Lo [Reference Haugh and Lo14] studied an optimal asset allocation problem when the underlying risky security followed a geometric Brownian motion, where the drift and the volatility were functions of the current time and the current value of the risky security. Liu and Pan [Reference Liu and Pan29] considered an optimal asset allocation problem in the presence of derivative securities in a stochastic-volatility-jump model. Kraft [Reference Kraft25] introduced an elasticity approach to optimal asset allocation with derivative securities. Detemple and Rindisbacher [Reference Detemple and Rindisbacher8] considered optimal asset allocation with interest-rate derivatives in the presence of stochastic interest rates and investment constraints. Cui et al. [Reference Cui, Oldenkamp and Vellekoop6] studied the impacts of adding derivative securities on asset allocation of pension funds. Fu et al. [Reference Fu, Wei and Yang13] discussed an optimal asset allocation problem with derivative securities when the risky asset followed a Markovian, regime-switching, geometric Brownian motion, where the drift and the volatility were modulated by a continuous-time, finite-state, observable Markov chain. However, in practice, the ‘true’ state of an economy may not be directly observable and its evolution over time may be better described by a hidden Markov chain. Though Fu et al. [Reference Fu, Wei and Yang13] provided a possible solution to an optimal asset allocation problem with derivatives in a Markovian regime-switching model where the underlying economic state was assumed to be observable, the problem under a more realistic situation where the underlying economy is hidden remains unresolved.
In this paper an optimal asset allocation problem is studied in a continuous-time, hidden Markovian regime-switching economy, where the investment opportunities include a money market account, an ordinary share, and a derivative security. We suppose that the price dynamics of the share are governed by a hidden Markov-modulated geometric Brownian motion. The objective of an economic agent is to select an optimal mix of these assets dynamically over time so as to maximize an expected utility of terminal wealth. Standard filtering theory is first applied to transform the original economy with partial observations into one with complete observations, where the latter is termed a ‘filtered’ economy. The optimal asset allocation problem is then discussed in the filtered economy. To discuss the optimal asset allocation problem in the presence of the derivative security, the price dynamics of the derivative security under a real-world probability measure is required. To derive this price dynamics, the concepts of a generalized delta-hedging self-financing portfolio and generalized elasticity of the derivative security are introduced. These generalizations take account of the presence of the information state process which describes the probability belief of an economic agent on the hidden economic state as new information emerges. These generalizations were not considered by Fu et al. [Reference Fu, Wei and Yang13] and aim to provide a convenient way to characterize how the information about the hidden states of the economy affects the hedge and optimal portfolio ratios. A stochastic partial differential equation governing the derivative price under the real-world probability measure is derived. Then, in the filtered economy, the optimal asset allocation problem is discussed using a martingale approach together with the Clark–Ocone formula and Malliavin calculus. First, for a general utility function, a solution of the optimal asset allocation problem is characterized in terms of Malliavin derivatives. Then three types of utility functions, namely an exponential utility, a power utility, and a logarithmic utility, are considered. For a logarithmic utility, a compact solution to the optimal asset allocation problem is obtained. In particular, an optimal portfolio mix is represented in terms of the generalized elasticity or the generalized delta-hedged ratio of the derivative security. The solution looks intuitively appealing and may generalize some results in Fu et al. [Reference Fu, Wei and Yang13] in the sense that the stringent assumption of an observed economy is relaxed. Furthermore, the martingale approach adopted here may be applied to a more general, for example non-Markovian, situation than the dynamic programming approach adopted by Fu et al. [Reference Fu, Wei and Yang13]. The former does not require consideration of those sophisticated functional properties discussed in Fu et al. [Reference Fu, Wei and Yang13].
The rest of this paper is structured as follows. The next section presents the model dynamics. In Section 3 the optimal asset allocation problem is presented. The stochastic partial differential equation governing the derivative price under the real-world probability measure and the corresponding wealth equation are derived. In Section 4 the martingale approach is used to discuss the optimal asset allocation problem. The final section gives some concluding remarks.
2. Market dynamics and filtering
A continuous-time market economy with a money market account B, an ordinary share S, and a derivative security O written on the share S is considered. Some standard assumptions for securities markets are imposed. First, these investment securities are tradeable continuously over time. Secondly, the market is frictionless, (i.e. there are no transaction costs and taxes). Thirdly, any fractional units of the investment securities can be traded, and shorting is allowed. Lastly, there is one rate of interest for borrowing and lending.
Uncertainty is described by a complete probability space
 $(\Omega, {\cal F}, \mathbb{P})$
, where
 $\mathbb{P}$
is a real-world probability measure. Write
 ${\cal T}$
for the time parameter set [0, T], where
 $T < \infty$
. To model the evolution of the hidden state of an economy over time, a continuous-time, finite-state, hidden Markov chain
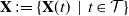 ${\bf X} \,:\!= \{ {\bf X} (t) \mid t \in {\cal T} \}$
is considered. The chain X is defined on
 $(\Omega, {\cal F}, \mathbb{P})$
and, following the notation in Elliott et al. [Reference Elliott, Aggoun and Moore10], the state space of the chain X is taken as a set of unit vectors
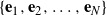 $\{ {\bf e}_1, {\bf e}_2, \ldots, {\bf e}_N \}$
in
 $\mathbb{R}^N$
, where the jth component of
 ${\bf e}_i$
is the Kronecker delta
 $\delta_{ij}$
for each
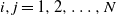 $i, j = 1, 2, \ldots, N$
. As usual, the probability law of the chain X is specified by a family of rate matrices
 $\{ {\bf A} (t) \mid t \in {\cal T} \}$
, where
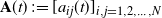 ${\bf A} (t) \,:\!= [ a_{ij} (t) ]_{i, j = 1, 2, \ldots, N}$
and
 $a_{ij} (t)$
is the instantaneous rate of transition of the chain X from state
 ${\bf e}_i$
to state
 ${\bf e}_j$
at time t. We assume that
 $a_{ij} (t)$
is bounded on
 $[0,\infty)$
for all
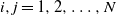 $i, j = 1, 2, \ldots, N$
. Write
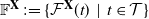 $\mathbb{F}^{\bf X} \,:\!=
\{ {\cal F}^{\bf X} (t) \mid t \in {\cal T} \}$
for the right-continuous,
 $\mathbb{P}$
-augmented, natural filtration generated by the chain X.
Let r (t) be the instantaneous continuously compounded interest rate of the bond B at time t, for each
 $t \in {\cal T}$
. To simplify the discussion, we suppose that r (t) is a deterministic function of time t. This assumption may not be unreasonable when the time horizon under consideration is short. Then the price process of the money market account
 $\{ B (t) \mid t \in {\cal T} \}$
is given by
 \begin{eqnarray*}
B (t) = \exp \bigg ( \int^{t}_{0} r (u) {\rm d} u \bigg).
\end{eqnarray*}
For technicality, we suppose that r (t) is bounded for all
 $t \in {\cal T}$
.
For each
 $t \in {\cal T}$
, let
 $\theta (t)$
be the instantaneous market price of risk of the share S at time t. We suppose that
 \begin{eqnarray*}
\theta (t) = \langle \boldsymbol{\theta}, {\bf X} (t) \rangle,
\end{eqnarray*}
where
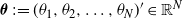 $\boldsymbol{\theta} \,:\!= (\theta_1, \theta_2, \ldots, \theta_N)^{\prime} \in \mathbb{R}^N$
and
 $\theta_i$
is the market price of risk of the share S corresponding to the ith state of the hidden economy;
 ${\bf y}^{\prime}$
is the transpose of a vector, or a matrix, y; and
 $\langle \cdot \, , \cdot \rangle$
is the scalar product in
 $\mathbb{R}^N$
. Note that
 ${\bf X} (t)$
is not observable, and so
 $\theta (t)$
is not observable either, for each
 $t \in {\cal T}$
.
Let
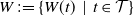 $W \,:\!= \{ W (t) \mid t \in {\cal T} \}$
be a standard Brownian motion on
 $(\Omega, {\cal F}, \mathbb{P})$
. For each
 $t \in {\cal T}$
, let
 $\sigma (t)$
be the instantaneous volatility of the share S at time t. To simplify the discussion, we suppose that
 $\sigma (t)$
is a deterministic function of time t, where
 $\sigma (t) > 0$
, for all
 $t \in {\cal T}$
. For technical reasons, we assume that
 $\sigma (t)$
and
 $\sigma^{-1} (t)$
are bounded, for all
 $t \in {\cal T}$
. Furthermore, as in Elliott et al. [Reference Elliott, Aggoun and Moore10], p. 214, it is supposed that the standard Brownian motion W is independent of the chain X under
 $\mathbb{P}$
. Then we assume that under
 $\mathbb{P}$
the share price process
 $\{ S (t) \mid t \in {\cal T} \}$
evolves over time as
 \begin{eqnarray}
{\rm d} S(t) &=& ( r (t) + \sigma (t) \theta (t)) S (t) {\rm d} t + \sigma (t) S (t) {\rm d} W (t),\\
S (0) &=& s_0 \gt 0.\end{eqnarray}
Note that the share price process
 $\{ S (t) \mid t \in {\cal T} \}$
is observable; however, the market price of the risk process
 $\{ \theta (t) \mid t \in {\cal T} \}$
and the Brownian motion
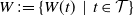 $W \,:\!= \{ W (t) \mid t \in {\cal T} \}$
are unobservable.
Let
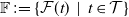 $\mathbb{F} \,:\!= \{ {\cal F}(t) \mid t \in {\cal T} \}$
be the right-continuous,
 $\mathbb{P}$
-augmented, natural filtration generated by the share price process
 $\{ S (t) \mid t \in {\cal T} \}$
. This represents the observed information structure in the model. Define an enlarged filtration
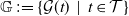 $\mathbb{G} \,:\!= \{ {\cal G} (t) \mid t \in {\cal T} \}$
, where
 \begin{eqnarray}
{\cal G} (t) \,:\!= {\cal F}(t) \vee {\cal F}^{\bf X} (t).
\label{eqn2}
\end{eqnarray}
Here,
 ${\cal E}_1 \vee {\cal E}_2$
is the minimal
 $\sigma$
-field containing the
 $\sigma$
-fields
 ${\cal E}_1$
and
 ${\cal E}_2$
. The enlarged filtration
 $\mathbb{G}$
represents the full information structure of the model.
In what follows, standard filtering theory is adopted to turn the above economy with partial observations into one with complete observations. The results presented here are standard. Similar results were presented in, for example, Sass and Haussmann [Reference Sass and Haussmann36], Elliott et al. [Reference Elliott, Siu and Badescu11], Korn et al. [Reference Korn, Siu and Zhang24], and Siu [Reference Siu38]. First, the separation principle, or the innovations approach, is used to transform partially observed dynamics into completely observed ones. The separation principle has been widely used to discuss stochastic optimal control problems with partial observations. For excellent discussions on this approach, one may refer to, for example, Kallianpur [Reference Kallianpur21], Elliott et al. [Reference Elliott, Aggoun and Moore10], and Lipster and Shiryaev [Reference Lipster and Shiryaev27]. Secondly, filtering equations for the hidden Markov chain are presented.
Write, for each
 $t \in {\cal T}$
,
 \begin{eqnarray*}
\phi (t) &\,:\!=& \frac{r (t) + \sigma (t) \theta (t) }{\sigma (t)}.
\end{eqnarray*}
Define
 $\{ {\widehat {\bf X}} (t) \mid t \in {\cal T} \}$
to be an
 $\mathbb{F}$
-optional projection of
 $\{ {\bf X} (t)
\mid t \in {\cal T} \}$
, and further define, for each
 $t \in {\cal T}$
,
 \begin{align*}
&\widehat{\theta} (t) \,:\!= \langle \boldsymbol{\theta}, {\widehat{\bf X} }(t) \rangle,\\
&\widehat{\phi}(t) \,:\!=\frac{r (t) + \sigma (t) \widehat{\theta} (t) }{\sigma (t)}.
\end{align*}
Then
 $\{\widehat{\theta} (t) \mid t \in {\cal T} \}$
is an
 $\mathbb{F}$
-optional projection of
 $\{\theta (t) \mid t \in {\cal T} \}$
, and
 $\{\widehat{\phi}(t) \mid t \in {\cal T} \}$
is an
 $\mathbb{F}$
-optional projection of
 $\{\phi(t) \mid t \in {\cal T} \}$
.
Define another process
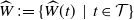 $\widehat{W} \,:\!= \{ {\skew2\widehat W} (t) \mid t \in {\cal T} \}$
, where
 \begin{eqnarray}
{\skew2\widehat W} (t) \,:\!= W (t) + \int^{t}_{0} ( \phi (u) - {\widehat \phi} (u) ) {\rm d} u.
\label{eqn3}
\end{eqnarray}
Then
 $\skew2\widehat W$
is an
 $(\mathbb{F}, \mathbb{P})$
-standard Brownian motion (see, for example, Kallianpur [Reference Kallianpur21] and Lipster and Shiryaev [Reference Lipster and Shiryaev27]).
Under the real-world measure
 $\mathbb{P}$
, the share price process
 $\{ S (t) \mid t \in {\cal T} \}$
can be represented in terms of the innovations process
 $\skew2\widehat W$
as follows:
 \begin{eqnarray*}
{\rm d} S(t) = ( r (t) + \sigma (t) {\widehat \theta} (t)) S (t) {\rm d} t + \sigma (t) S (t) {\rm d} {\skew2\widehat W} (t).
\end{eqnarray*}
Let
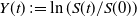 $Y (t) \,:\!= \ln (S (t) / S(0))$
for each
 $t \in {\cal T}$
, where Y (t) is the logarithmic return from the share S in the time interval [0, t]. For each
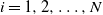 $i = 1, 2, \ldots, N$
, let
 \begin{eqnarray}
\mu_i (t) \,:\!= r (t) + \theta_i \sigma (t) - \frac{1}{2} \sigma^2 (t).
\label{eqn4}
\end{eqnarray}
From the boundedness conditions for r (t) and
 $\sigma (t)$
(see the paragraph preceding (1)), we know that
 $\mu_i (t)$
is bounded for each
 $t \in {\cal T}$
and each
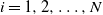 $i = 1, 2, \ldots, N$
.
Write
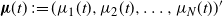 $\boldsymbol{\mu} (t) \,:\!= (\mu_1 (t), \mu_2 (t), \ldots, \mu_N (t))^{\prime}$
. Then
 \begin{eqnarray}
Y (t) &=& \int^{t}_{0} \langle {\boldsymbol{\mu}} (u), {\bf X} (u) \rangle {\rm d} u + \int^{t}_{0} \sigma (u) {\rm d} W (u) \nonumber\\
&=& \int^{t}_{0} \langle {\boldsymbol{\mu}} (u), {\widehat {\bf X}} (u) \rangle {\rm d} u + \int^{t}_{0} \sigma (u) {\rm d} {\skew2\widehat W} (u).
\label{eqn5}\end{eqnarray}
To derive the filtering equation for the hidden chain X given observations about the return process Y, we adopt the reference probability approach as discussed in, for example, Elliott et al. [Reference Elliott, Aggoun and Moore10]. We start with a reference probability measure
 $\mathbb{P}^{\dagger}$
equivalent to
 $\mathbb{P}$
on
 ${\cal G} (T)$
, under which
1. the process
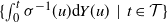 $\{ \int^{t}_{0} \sigma^{-1} (u) {\rm d} Y (u) \mid t \in {\cal T} \}$
is a standard Brownian motion;
2. the process
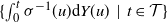 $\{ \int^{t}_{0} \sigma^{-1} (u) {\rm d} Y (u) \mid t \in {\cal T} \}$
is independent of the hidden chain X;
3. the hidden chain X has the same probability law as that under
 $\mathbb{P}$
.
Such a probability measure can be constructed as follows. First, define the
 $\mathbb{G}$
-adapted process
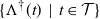 $\{ \Lambda^{\dagger} (t) \mid t \in {\cal T} \}$
by putting
 \begin{eqnarray*}
\Lambda^{\dagger} (t) \,:\!= \exp \bigg ( \int^{t}_{0} \langle {\boldsymbol{\mu}} (u), {\bf X} (u) \rangle \sigma^{-1} (u) {\rm d} Y (u) - \frac{1}{2} \int^{t}_{0} \langle {\boldsymbol{\mu}} (u), {\bf X} (u) \rangle^2 \sigma^{-2} (u) {\rm d} u \bigg ).
\end{eqnarray*}
We can then define a probability measure
 $\mathbb{P}^{\dagger}$
equivalent to
 $\mathbb{P}$
on
 ${\cal G} (T)$
as follows:
 \begin{eqnarray*}
\frac{{\rm d} \mathbb{P}^{\dagger}} {{\rm d} \mathbb{P}} \bigg |
_{{\cal G} (T)} \,:\!= ( \Lambda^{\dagger} (T) )^{-1}.
\end{eqnarray*}
Note that the process
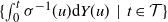 $\{ \int^{t}_{0} \sigma^{-1} (u) {\rm d} Y (u) \mid t \in {\cal T} \}$
is independent of the hidden chain X under the reference measure
 $\mathbb{P}^{\dagger}$
. Consequently,
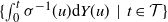 $\{ \int^{t}_{0} \sigma^{-1} (u) {\rm d} Y (u) \mid t \in {\cal T} \}$
remains a standard Brownian motion under the enlargement of filtration from
 $\mathbb{F}$
to
 $\mathbb{G}$
; that is, the process
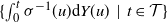 $\{ \int^{t}_{0} \sigma^{-1} (u) {\rm d} Y (u) \mid t \in {\cal T} \}$
is a
 $(\mathbb{G}, \mathbb{P}^{\dagger})$
-standard Brownian motion. It may be noted that this situation is different from a Brownian bridge, where the enlargement of filtration is related to the terminal value of a Brownian motion which depends on the Brownian motion itself. Consequently, the integral with respect to the
 $(\mathbb{G}, \mathbb{P}^{\dagger})$
-standard Brownian motion
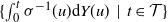 $\{ \int^{t}_{0} \sigma^{-1} (u) {\rm d} Y (u) \mid t \in {\cal T} \}$
is interpreted as a stochastic integral in the Itô sense with respect to the enlarged filtration
 $\mathbb{G}$
under the reference measure
 $\mathbb{P}^{\dagger}$
. Furthermore, due to the boundedness of
 ${\boldsymbol{\mu}} (t)$
and
 $\sigma^{-1} (t)$
,
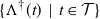 $\{ \Lambda^{\dagger} (t) \mid t \in {\cal T} \}$
is a
 $(\mathbb{G}, \mathbb{P}^{\dagger})$
-(exponential) martingale. It is, however, under the real-world measure
 $\mathbb{P}$
that the process
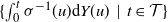 $\{ \int^{t}_{0} \sigma^{-1} (u) {\rm d} Y (u) \mid t \in {\cal T} \}$
depends on the hidden chain X. See, for example, Elliott et al. [Reference Elliott, Aggoun and Moore10], p. 214.
Write, for each
 $t \in {\cal T}$
, the unnormalized filter as follows:
 \begin{eqnarray*}
{\bf q} (t) \,:\!= \mathbb{E}^{\dagger} [ \Lambda^{\dagger} (t) {\bf X} (t) | {\cal F} (t) ] \in \mathbb{R}^N,
\end{eqnarray*}
where
 $\mathbb{E}^{\dagger}$
is the expectation taken with respect to
 $\mathbb{P}^{\dagger}$
.
Then a Zakai filtering equation for the unnormalized filter
 ${\bf q} (t)$
is given by
 \begin{eqnarray}
{\bf q} (t) &=& {\bf q} (0) + \int^{t}_{0} {\bf A} (u) {\bf q} (u) {\rm d} u + \int^{t}_{0} {\bf H} (u) {\bf q} (u) \sigma^{-1} (u) {\rm d} Y (u),
\label{eqn6}
\end{eqnarray}
where
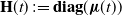 ${\bf H} (t) \,:\!= {\bf diag} ( {\boldsymbol{\mu}} (t))$
, a diagonal matrix with the diagonal elements being the components in the vector
 ${\boldsymbol{\mu}} (t)$
. See, for example, Elliott et al. [Reference Elliott, Siu and Badescu11], Korn et al. [Reference Korn, Siu and Zhang24], and Siu [Reference Siu38], and the relevant references therein.
To simplify the Zakai equation, a gauge transformation technique of Clark [Reference Clark and Skwirzynski4] is commonly used in the filtering literature.
Define, for each
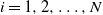 $i = 1, 2, \ldots, N$
, the
 $\mathbb{F}$
-adapted process
 $\{ \Sigma_i (t) \mid t \in {\cal T} \}$
by
 \begin{eqnarray*}
\Sigma_i (t) \,:\!= \exp \bigg ( \int^{t}_{0} \mu_{i} (u) \sigma^{-2} (u) {\rm d} Y (u) - \frac{1}{2} \int^{t}_{0} \mu^2_{i} (u) \sigma^{-2} (u) {\rm d} u \bigg ).
\end{eqnarray*}
Write, for each
 $t \in {\cal T}$
,
 \begin{eqnarray*}
\boldsymbol{\Sigma} (t) &\,:\!= &{\bf diag} (\Sigma_1 (t), \Sigma_2 (t), \ldots, \Sigma_N (t)) \in \mathbb{R}^N \otimes \mathbb{R}^N,\nonumber\\
{\bar {\bf q}} (t) &\,:\!=& \boldsymbol{\Sigma}^{-1} (t) {\bf q} (t).
\end{eqnarray*}
A (pathwise) linear ordinary differential equation satisfied by
 ${\bar {\bf q}} (t)$
is given by
 \begin{eqnarray}
\frac{{\rm d} {\bar {\bf q}} (t)} {{\rm d} t} = \boldsymbol{\Sigma}^{-1} (t) {\bf A} (t) \boldsymbol{\Sigma} (t) {\bar {\bf q}} (t), \quad {\bar {\bf q}} (0) = {\bf q} (0).
\label{eqn7}
\end{eqnarray}
See, for example, Elliott et al. [Reference Elliott, Siu and Badescu11], Korn et al. [Reference Korn, Siu and Zhang24], and Siu [Reference Siu38], and the relevant references therein.
3. Asset allocation in the filtered economy
In this section an optimal asset allocation problem is firstly presented in the filtered economy. Then the price dynamics of the derivative security and the wealth equation under
 $\mathbb{P}$
are derived.
Recall from the last section that in the filtered market, under
 $\mathbb{P}$
, the share price process
 $\{ S (t) \mid t \in {\cal T} \}$
is governed by
 \begin{eqnarray*}
{\rm d} S(t) = ( r (t) + \sigma (t) {\widehat \theta} (t)) S (t) {\rm d} t + \sigma (t) S (t) {\rm d} {\skew2\widehat W} (t).
\end{eqnarray*}
Furthermore, the information state process in the filtered market is given by the unnormalized filter (6):
 \begin{equation}
{\bf q} (t) = {\bf q} (0) + \int^{t}_{0} {\bf A} (u) {\bf q} (u) {\rm d} u + \int^{t}_{0} {\bf H} (u) {\bf q} (u) \sigma^{-1} (u) {\rm d} Y (u).
\label{eqn8}
\end{equation}
This is related to the dynamics of the probability belief of an economic agent on the hidden economic state, which also evolves over time.
Consider the
 $\mathbb{F}$
-adapted process
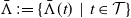 ${\bar \Lambda} \,:\!= \{ {\bar \Lambda} (t) \mid t \in {\cal T} \}$
defined by putting
 \begin{eqnarray*}
{\bar \Lambda} (t) \,:\!=\exp \bigg (\!-\! \int^{t}_{0} {\widehat \theta} (u) {\rm d} {\skew2\widehat W} (u) - \frac{1}{2} \int^{t}_{0} {\widehat \theta}^2 (u) {\rm d} u \bigg ).
\end{eqnarray*}
Then
 ${\bar \Lambda}$
is an
 $(\mathbb{F}, \mathbb{P})$
-(local)-martingale. Note that
 $\{ {\widehat \theta} (t) \mid t \in {\cal T} \}$
is bounded, and so
 ${\bar \Lambda}$
is an
 $(\mathbb{F}, \mathbb{P})$
-martingale.
Define a new probability measure
 $\mathbb{Q}$
equivalent to
 $\mathbb{P}$
on
 ${\cal F} (T)$
by putting
 \begin{eqnarray}
\frac{{\rm d} \mathbb{Q}}{{\rm d} \mathbb{P}} \bigg |_{{\cal F} (T)} \,:\!= {\bar \Lambda} (T).
\label{eqn9}
\end{eqnarray}
The measure
 $\mathbb{Q}$
is the unique equivalent martingale measure in the filtered market.
Consider a standard European-style contingent claim C written on the share S with payoff C(S(T)) at the maturity T, for some measurable function
 $C \,:\, \mathbb{R}_+ \rightarrow \mathbb{R}_+$
, where
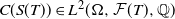 $C (S(T)) \in L^2 (\Omega, {\cal F} (T), \mathbb{Q})$
and
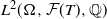 $L^2 (\Omega, {\cal F} (T), \mathbb{Q})$
is the space of
 ${\cal F} (T)$
-measurable, square-integrable, random variables. Write
 $\{ O (t) \mid t \in {\cal T} \}$
for the (no-arbitrage) price process of the claim C in the filtered market.
For each
 $t \in {\cal T}$
, let
 $\pi_o (t)$
and
 $\pi_s (t)$
be the amounts of money invested in the claim C and the share S at time t, respectively. Let
 $\{ \boldsymbol{\pi} (t) \mid t \in {\cal T} \}$
be a self-financing portfolio process such that for each
 $t \in {\cal T}$
,
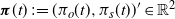 $\boldsymbol{\pi} (t) \,:\!= (\pi_o (t), \pi_s (t))^{\prime} \in \mathbb{R}^2$
. Write
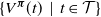 $\{ V^{\boldsymbol{\pi}} (t) \mid t \in {\cal T} \}$
for the wealth process corresponding to the portfolio process
 $\{ \boldsymbol{\pi} (t) \mid t \in {\cal T} \}$
. To simplify the notation we suppress the superscript
 $\boldsymbol{\pi}$
in
 $V^{\boldsymbol{\pi}} (t)$
and write V (t) for
 $V^{\boldsymbol{\pi}} (t)$
unless otherwise stated. Then, for each
 $t \in {\cal T}$
, the amount of money invested in the money market account at time t is
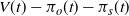 $V (t) - \pi_o (t) - \pi_s (t)$
. Since the portfolio process
 $\{ \boldsymbol{\pi} (t) \mid t \in {\cal T} \}$
is self-financing,
 \begin{eqnarray*}
{\rm d} V (t) &=& \pi_o (t) \frac{{\rm d} O (t)}{O (t)} + \pi_s (t) \frac{{\rm d} S (t)}{S (t)} + (V(t) - \pi_o (t) - \pi_s (t)) \frac{{\rm d} B (t)}{B (t)} %,
\nonumber\\
&=& \pi_o (t) \frac{{\rm d} O (t)}{O (t)} + \pi_s (t) \frac{{\rm d} S (t)}{S (t)} + (V(t) - \pi_o (t) - \pi_s (t)) r (t) {\rm d} t, \nonumber\\
V (0) &\,:\!=& v,
\end{eqnarray*}
where v is the initial wealth and
 $v > 0$
.
A self-financing portfolio process
 $\{ \boldsymbol{\pi} (t) \mid t \in {\cal T} \}$
is said to be admissible if
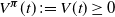 $V^{\boldsymbol{\pi}} (t) \,:\!= V (t) \ge 0$
,
 $\mathbb{P}$
-a.s., for each
 $t \in {\cal T}$
. We also suppose here that an admissible self-financing portfolio process
 $\{ \boldsymbol{\pi} (t) \mid t \in {\cal T} \}$
is
 $\mathbb{F}$
-adapted, where
 $\mathbb{F}$
is the natural filtration generated by the share price process
 $\{ S (t) \mid t \in {\cal T} \}$
as defined in the paragraph preceding (2). Note that
 $\mathbb{F}$
describes the information structure in the filtered market. Write
 ${\cal A} (v, {\bf q})$
for the space of admissible self-financing portfolio processes starting with an initial wealth v and an initial information state q.
Let
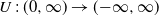 $U \,:\, (0, \infty) \rightarrow (\!-\!\infty, \infty)$
be a utility function on the terminal wealth. As usual, we assume that U is strictly increasing, strictly concave, and continuously differentiable on
 $(0, \infty)$
such that the derivative
 $U^{\prime}$
of U satisfies the following Inada conditions:
 \begin{eqnarray*}
U^{\prime} (0) \,:\!= \lim_{x \downarrow 0} U^{\prime} (x) = \infty, \quad U^{\prime} (\infty) \,:\!= \lim_{x \uparrow \infty} U^{\prime} (x) = 0.
\end{eqnarray*}
The objective of an economic agent is to select an optimal portfolio process in the class
 ${\cal A} (v, {\bf q})$
so as to maximize the expected utility on the terminal wealth V (T). Write, for each
 $\boldsymbol{\pi} \in {\cal A} (v, {\bf q})$
,
 \begin{eqnarray}
{\skew5\tilde J}_{\boldsymbol{\pi}} (v) \,:\!= \mathbb{E}^{v} [ U (V^{\boldsymbol{\pi}} (T) ) ],
\label{eqn10}
\end{eqnarray}
where
 $\mathbb{E}^v$
is the conditional expectation under
 $\mathbb{P}$
given
 $V (0) = v$
.
Then the economic agent faces the following optimization problem in the filtered market:
 \begin{eqnarray}
{\tilde \Phi} (v) = \max_{\boldsymbol{\pi} \in {\cal A} (v, {\bf q}) } {\skew5\tilde J}_{\boldsymbol{ \pi}} (v).
\label{eqn11}
\end{eqnarray}
The maximization problem will be discussed using a martingale approach together with the Clark–Ocone formula and Malliavin calculus in the next section.
In what follows, a partial differential equation (PDE) governing the (no-arbitrage) price of the claim C will be presented. Then a stochastic partial differential equation (SPDE) for the price dynamics of the claim C under
 $\mathbb{P}$
as well as the wealth equation under
 $\mathbb{P}$
will be derived. Though the price and wealth dynamics under
 $\mathbb{P}$
are required, to determine the (no-arbitrage) price of the claim C, we still need to consider the equivalent martingale measure
 $\mathbb{Q}$
in the filtered economy, which was defined in (9). Then, in the filtered economy the arbitrage-free price of the claim at time
 $t \in {\cal T}$
is given by
 \begin{eqnarray*}
O (t) = \mathbb{E}^{\mathbb{Q}} \bigg [ \exp \bigg (\!-\! \int^{T}_{t} r (u) {\rm d} u \bigg ) O (S(T)) \mid {\cal F} (t) \bigg ],
\end{eqnarray*}
where
 $\mathbb{E}^{\mathbb{Q}}$
is the expectation taken with respect to
 $\mathbb{Q}$
.
The rationale of considering the equivalent martingale measure
 $\mathbb{Q}$
in the filtered economy is to mark the derivative position into the model. However, for studying an optimal asset allocation problem, it is the real-world probability measure
 $\mathbb{P}$
which is relevant. Note that the market in the filtered economy is complete. Nevertheless, instead of considering hedging the derivative position, where the risk-neutral measure
 $\mathbb{Q}$
should be used, we consider here an optimal investment problem with the derivative position. The derivative position may provide a leveraging effect to the risk–return profile of the investment portfolio under the real-world probability measure
 $\mathbb{P}$
. In this case the real-world appreciation rate of the underlying stock as well as the risk preference of the investor would be relevant.
Note that
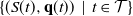 $\{ (S (t), {\bf q} (t) ) \mid t \in {\cal T} \}$
is jointly Markovian with respect to the observed filtration
 $\mathbb{F}$
. So if
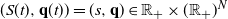 $(S (t), {\bf q} (t)) = (s, {\bf q}) \in \mathbb{R}_+ \times (\mathbb{R}_+)^N$
, by a version of the Bayes’ rule,
 \begin{align*}
O(t)={{\mathbb{E}}^{\mathbb{Q}}}[\exp (-\int_{t}^{T}{r}(u)\text{d}u)C(S(T))|F(t)]\\
&=\mathbb{E}[{{\bar{\Lambda }}^{-1}}(t)\bar{\Lambda }(T)\exp (-\int_{t}^{T}{r}(u)\text{d}u)C(S(T))|F(t)]\\
&=\mathbb{E}[\exp (-\int_{t}^{T}{r}(u)\text{d}u-\int_{t}^{T}{{\hat{\theta }}}(u)\text{d}2\hat{W}(u)\\-\frac{1}{2}\int_{t}^{T}{{{{\hat{\theta }}}^{2}}}(u)\text{d}u)C(S(T))|(S(t),\mathbf{q}(t))].
\end{align*}
So O(t) is a function of
 $(S(t),{\bf q} (t))$
. With a slight abuse of notation, define
 \begin{eqnarray}
O (t, s, {\bf q})&\,:\!=& \mathbb{E} \bigg [ \!\exp \bigg (\!-\! \int^{T}_{t} r (u) {\rm d} u - \int^{T}_{t} {\widehat \theta} (u) {\rm d} {\skew2\widehat W} (u)
- \frac{1}{2} \int^{T}_{t} {\widehat \theta}^2 (u) {\rm d} u \bigg ) \nonumber\\
&& \quad \times\ C (S(T)) \,\Big|\, (S (t), {\bf q} (t)) = (s, {\bf q}) \bigg ]. \nonumber
\end{eqnarray}
We can see that
 $O (t, s, {\bf q})$
is a measurable function in
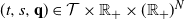 $(t, s, {\bf q}) \in {\cal T} \times \mathbb{R}_+ \times (\mathbb{R}_+)^N$
, and
 \begin{align*}
O(t)= O (t, S (t), {\bf q} (t)).
\end{align*}
The following lemma gives a PDE for the arbitrage-free price of the claim C. The result follows from applying Itô’s differentiation rule and the fact that the discounted price process of the claim C is an
 $(\mathbb{F}, \mathbb{Q})$
-martingale. The proof is standard, so it is omitted. The techniques used in the proof can be found in, for example, Siu [Reference Siu, Mamon and Elliott39] and Elliott and Siu [Reference Elliott and Siu12].
Lemma 1. Suppose
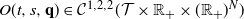 $O (t, s, {\bf q}) \in {\cal C}^{1, 2, 2} ({\cal T} \times \mathbb{R}_+ \times (\mathbb{R}_+)^N)$
, where
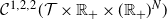 ${\cal C}^{1, 2, 2} ({\cal T} \times \mathbb{R}_+ \times (\mathbb{R}_+)^N)$
is the space of measurable functions which are continuously differentiable in
 $t \in {\cal T}$
and twice continuously differentiable in
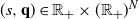 $(s, {\bf q}) \in \mathbb{R}_+ \times (\mathbb{R}_+)^N$
. For each
 $t \in {\cal T}$
, let
 \begin{eqnarray*}
{\bf A}^{\mathbb{Q}} (t) \,:\!= {\bf A} (t) + \sigma^{-1} (t) \bigg ( r (t) - \frac{1}{2} \sigma^2 (t) \bigg ) {\bf H} (t)+\hat{\theta}(t){\bf H} (t).
\end{eqnarray*}
Then
 $O (t, s, {\bf q})$
satisfies the following PDE:
 \begin{align}
& \frac{\partial O (t,s,{\bf q})} {\partial t} + \frac{\partial O (t,s,{\bf q})}{\partial s} (r (t)+\sigma(t)\hat{\theta}(t)) s
+ \bigg \langle \frac{\partial O (t,s,{\bf q})}{\partial {\bf q}}, {\bf A}^{\mathbb{Q}} (t) {\bf q} \bigg \rangle \nonumber\\
& +s \bigg \langle \frac{\partial^2 O (t,s,{\bf q})}{\partial {\bf q} \partial s}, \sigma(t) {\bf H} (t) {\bf q} \bigg \rangle + \frac{1}{2} \frac{\partial^2 O (t,s,{\bf q})}{\partial s^2} \sigma^2 (t) s^2 + \frac{1}{2} {\bf q}^{\prime} {\bf H}^{\prime} (t) \frac{\partial^2 O (t,s,{\bf q})}{\partial {\bf q}^2} {\bf H} (t) {\bf q}\nonumber\\
&= r (t) O (t,s,{\bf q}).
\label{eqn12}\end{align}
Remark 1. The PDE (12) in Lemma 1 may be related to the partial differential-integral equations for option prices presented by Siu [Reference Siu, Mamon and Elliott39] and Elliott and Siu [Reference Elliott and Siu12]. In Siu [Reference Siu, Mamon and Elliott39], a partial differential-integral equation was given for the price of a European-style option in a filtered market corresponding to a hidden Markovian regime-switching jump-diffusion market. In a sense, the partial differential-integral equation in Siu [Reference Siu, Mamon and Elliott39] is more general than the PDE in Lemma 1. Elliott and Siu [Reference Elliott and Siu12] derived a partial differential-integral equation for the price of a European-style option in a filtered market where both the share price and trading volumes processes were observable processes.
An SPDE for the price process
 $\{ O (t) \mid t \in {\cal T} \}$
of the claim C under
 $\mathbb{P}$
is now derived. In Fu et al. [Reference Fu, Wei and Yang13] a delta-neutral, self-financing portfolio was considered to derive such a price process. Here, a generalized delta-neutral, self-financing portfolio is introduced which is used for the derivation of the SPDE. The generalized delta-neutral, self-financing portfolio may be thought of as an extension of that in Fu et al. [Reference Fu, Wei and Yang13] and takes into account the information state process
 $\{ {\bf q} (t) \mid t \in {\cal T} \}$
in the filtered market. Consequently, in addition to the delta
 \begin{equation*}\frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)},\end{equation*}
the hedge quantity in the generalized delta-neutral portfolio also involves the gradient
 \begin{equation*}\frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}.\end{equation*}
It wasoted in Fu et al. [Reference Fu, Wei and Yang13] that it may not be easy to use the elasticity approach, which was introduced to optimal asset allocation in Kraft [Reference Kraft25], to discuss the optimal asset allocation problem in a Markovian regime-switching market since the market is incomplete. They introduced a functional operator to articulate the problem. Here, the market described by the filtered economy is complete and it also has complete observations. Consequently, the contingent claim may be perfectly hedged by the generalized delta-neutral, self-financing portfolio and the generalized elasticity approach may work well in the filtered economy.
We first recall the concept of delta-neutral, self-financing portfolio in Fu et al. [Reference Fu, Wei and Yang13]. For each
 $t \in {\cal T}$
, let
 ${\bar \psi}
(t)$
be the number of units of the share S held in the delta-neutral, self-financing portfolio at time t and let
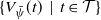 $\{ V_{\bar \psi} (t) \mid t \in
{\cal T} \}$
denote the value process of the delta-neutral, self-financing portfolio. Then, according to Equation (16) on p. 187 of Fu et al. [Reference Fu, Wei and Yang13],
 \begin{eqnarray*}
V_{\bar \psi} (t) = - O (t) + {\bar \psi} (t) S (t),
\end{eqnarray*}
where
 \begin{eqnarray*}
{\bar \psi} (t) = \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)}.
\end{eqnarray*}
The self-financing property of the portfolio means that
 \begin{eqnarray*}
{\rm d} V_{\bar \psi} (t) = - {\rm d} O (t) + {\bar \psi} (t) {\rm d} S (t) = - {\rm d} O (t) + \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} {\rm d} S (t).
\end{eqnarray*}
For each
 $t \in {\cal T}$
, let
 $\psi (t)$
be the number of units of the share S held in the generalized delta-neutral, self-financing portfolio at time t. Let
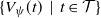 $\{ V_{\psi}(t) \mid t \in {\cal T} \}$
be the value process of the generalized delta-neutral, self-financing portfolio. Then
 \begin{eqnarray*}
V_{\psi}(t) = - O (t) + \psi (t) S (t).
\end{eqnarray*}
Since the portfolio is self-financing,
 \begin{eqnarray*}
{\rm d} V_{\psi}(t) = - {\rm d} O (t) + \psi (t) {\rm d} S (t).
\end{eqnarray*}
In the generalized delta-hedging self-financing portfolio, we take
 \begin{eqnarray*}
\psi (t) \,:\!= \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} + \bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)}, {\bf H} (t) {\bf q} (t) \bigg \rangle \,\sigma^{-2} (t) S^{-1} (t).
\end{eqnarray*}
Then
 \begin{align*}
{\rm d} V_{\psi}(t)
= &- {\rm d} O (t)
+ \bigg ( \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} \\
&+ \bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)}, {\bf H} (t) {\bf q} (t) \bigg \rangle \,\sigma^{-2} (t) S^{-1} (t) \bigg ) {\rm d} S (t).
\end{align*}
Comparing the delta-neutral, self-financing portfolio in Fu et al. [Reference Fu, Wei and Yang13], the generalized delta-neutral, self-financing portfolio has an additional term given by
 \begin{eqnarray*}
\bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)}, {\bf H} (t) {\bf q} (t) \bigg \rangle \,\sigma^{-2} (t) S^{-1} (t).
\end{eqnarray*}
Note that the additional term involves the gradient
 \begin{equation*}\frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)}\end{equation*}
multiplied by the ratio of the information state
 ${\bf q} (t)$
and the share price S (t) adjusted by their respective volatilities. The derivative,
 \begin{equation*}\frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)},\end{equation*}
describes the sensitivity of the price of the claim O with respect to the information state
 ${\bf q} (t)$
, whereas the ratio of the information state
 ${\bf q} (t)$
and the share price S(t) adjusted by their respective volatilities may take account of the ‘co-movement’ between the information state
 ${\bf q} (t)$
and the share price S(t). Consequently, the generalized delta-neutral, self-financing portfolio
 $\psi (t)$
can be decomposed as the sum of two hedge components. The first component hedges the price risk attributed to fluctuations in the underlying share’s price. The second component hedges the information risk due to stochastic evolution of the information state process, which may be interpreted as the variation of the information quantity about the hidden economic state that is observed by the econometrican over time. The second hedge component also takes account of the ‘co-movement’ of the information state and the share price.
Suppose that the delta-neutral portfolio is self-financing. Then
 \begin{align*}
{\rm d} V_{\psi}(t) = &- {\rm d} O (t, S(t), {\bf q}(t))\\
& + \bigg(\frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)}+ % \left
\bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)}, {\bf H} (t) {\bf q}(t) % \right
\bigg \rangle \,\sigma^{-2} (t) S^{-1} (t) \bigg) {\rm d} S (t).
\end{align*}
Now the concept of the elasticity of the option price with respect to an underlying security price discussed in Fu et al. [Reference Fu, Wei and Yang13] is generalized to incorporate the information state process
 $\{ {\bf q} (t) \mid t \in {\cal T} \}$
in the filtered market. Note that the elasticity approach to optimal asset allocation with derivative securities was discussed in Kraft [Reference Kraft25] in a modeling framework without regime shifts. Indeed, the notion of elasticity appears in price theory, which is mostly called microeconomics nowadays. Specifically, in the theory of demand, the concept of the price elasticity of demand is introduced, which is defined as the ratio of the proportional change in quantity purchased and the proportional change in price. The rationale of considering elasticity rather than a direct measure of sensitivity given by the ratio of the changes in the two quantities is that the former does not depend on the units of measurement, say dimension-free, while the latter does. See, for example, Section 5.2 of the monograph by Hirshleifer and Hirshleifer [Reference Hirshleifer and Hirshleifer15] for related discussions. Similarly, the elasticity of the option price with respect to the underlying security price in, for example, Fu et al. [Reference Fu, Wei and Yang13], can be defined as the proportional change in the option price divided by the proportional change in the underlying security price, and it is dimension-free. The dimension-free property of the elasticity is useful when we define the concept of generalized elasticity in the following.
Recall that in the filtered market the option price
 $O (t, S(t), {\bf q}(t))$
depends on both the underlying security price S(t) and the information state
 ${\bf q}(t)$
. Consequently, a change in the option price may be attributed to changes in S(t),
 ${\bf q}(t)$
, or both, and so when the notion of the elasticity of the option price is defined, it should take account of the changes in both S(t) and
 ${\bf q}(t)$
. This motivates the following definition of the concept of generalized elasticity of an option price. Define, for each
 $t \in {\cal T}$
,
 $\eta_s (t)$
to be the generalized elasticity of the price of the claim O with respect to the underlying state variables
 $(S(t), {\bf q} (t))$
in the filtered market as follows:
 \begin{align*}
\eta_s (t) \,:\!=& \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} \frac{S (t)}{O (t)} + % \left
\bigg \langle\frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)}, {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle \,\sigma^{-2} (t) \frac{1}{O (t)} \nonumber\\
=& \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} \frac{S (t)}{O (t)} + % \left
\bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)}, {\bf H} (t) \boldsymbol{ \Sigma} (t) {\bar {\bf q}} (t) % \right
\bigg \rangle \,\sigma^{-2} (t) \frac{1}{O (t)} .
\end{align*}
Note that the generalized elasticity
 $\eta_s (t)$
can be decomposed as the sum of two components. The first component,
 \begin{equation*}\frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} \frac{S (t)}{O (t)},\end{equation*}
is the same as the elasticity of the option price with respect to the underlying security price in Fu et al. [Reference Fu, Wei and Yang13]. For the second component, we first note that the information state process
 $\{ {\bf q} (t) \mid t \in {\cal T} \}$
in the filtered market may be interpreted as a proxy or a measure for the information quantity about the hidden economic regimes that is observed by an econometrician over time. Heuristically, without taking into account multiplication and division by vectors or matrices, the second component might be put in the following ‘tentative’ form:
 \begin{align*}
\bigg ( \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)} \cdot \frac{{\bf q} (t)}{O (t)} \bigg ) \cdot \bigg ( \frac{{\bf H} (t) \sigma^{-1} (t)}{\sigma (t)} \bigg ).
\end{align*}
The term
 \begin{equation*}\frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q} ={\bf q} (t)} \cdot \frac{{\bf q} (t)}{O (t)}\end{equation*}
gives the ratio of the proportional change in the option price and the proportional change in the quantity of information about the hidden economic regimes that is observed by the econometrician. Consequently, it can be interpreted as the elasticity of the option price with respect to the information quantity about the hidden economic regimes. The term
 \begin{equation*}\frac{{\bf H} (t) \sigma^{-1} (t)}{\sigma (t)}\end{equation*}
is the ratio of the volatility of the information state process
 $\{ {\bf q} (t) \mid t \in {\cal T} \}$
and the share price price
 $\{ S (t) \mid t \in {\cal T} \}$
. The role played by this term is to adjust the volatility of the information quantity in the evaluation of the elasticity of the option price with respect to the information quantity. Putting the first and second components together, the generalized elasticity
 $\eta_s (t)$
describes the aggregate proportional change in the option price with respect to the proportional changes of the two state variables in the filtered market, namely the underlying security price and the information quantity about the hidden economic regimes that is observed by the econometrician.
The generalized elasticity
 $\eta_s (t)$
can be related to the generalized delta-hedged ratio
 $\psi (t)$
as follows:
 \begin{eqnarray*}
\eta_s (t) = \frac{S (t)}{O (t)} \psi (t).
\end{eqnarray*}
Then
 $\eta_s (t)$
may be interpreted as the generalized delta-hedged ratio expressed in the number of units of the derivative security. From now on, we assume that
 $\eta_s (t) \neq 1$
, for all
 $t \in {\cal T}$
. An economic interpretation for this assumption is that the aggregate proportional change in the derivative price with respect to the proportional changes in the underlying security’s price and the information quantity is different from one. This intends to preclude the degenerate case that this aggregate proportional change in the option price is identical to one.
The following lemma gives the SPDE governing the price process
 $\{ O (t) \mid t \in {\cal T} \}$
of the claim C under
 $\mathbb{P}$
in the filtered market.
Lemma 2. Suppose that
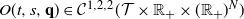 $O (t, s, {\bf q}) \in {\cal C}^{1, 2, 2} ({\cal T} \times \mathbb{R}_+ \times (\mathbb{R}_+)^N)$
. Then, under
 $\mathbb{P}$
,
 \begin{eqnarray*}
\frac{ {\rm d} O (t, S(t), {\bf q} (t)) } {O (t, S(t), {\bf q}(t)) } &=& (r (t) + \sigma (t) {\widehat \theta} (t) \eta_s (t) ) {\rm d} t + \eta_s (t) \sigma (t) {\rm d} {\skew2\widehat W} (t).
\end{eqnarray*}
Proof. The first statement follows from the joint Markovian property of
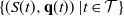 $\{ (S (t), {\bf q} (t)) \!\mid\!\! t \in {\cal T} \}$
. The arguments used in the rest of the proof are similar to those used in Section 4 of Fu et al. [Reference Fu, Wei and Yang13]. Applying Itô’s differentiation to
 $O (t, S(t), {\bf q} (t))$
gives:
 \begin{align}
& {\rm d} O (t, S(t), {\bf q} (t))) \\
=& \bigg (\frac{\partial O (t,s,{\bf q})} {\partial t}\bigg|_{s=S(t),{\bf q}={\bf q}(t)} + S(t) % \left
\bigg \langle \frac{\partial^2 O (t,s,{\bf q})}{\partial {\bf q} \partial s}\bigg|_{s=S(t),{\bf q}={\bf q}(t)}, \sigma(t){\bf H} (t) {\bf q} (t) % \right
\bigg \rangle \\
&+ \frac{1}{2} \frac{\partial^2 O(t,s,{\bf q}(t))}{\partial s^2}\bigg|_{s=S(t)} \sigma^2 (t) S(t) ^2 + \frac{1}{2} \sigma^{-1} (t) {\bf q}^{\prime} (t) {\bf H}^{\prime} (t).
\frac{\partial^2 O (t,S(t),{\bf q})}{\partial {\bf q}^2} \bigg|_{{\bf q}={\bf q}(t)} {\bf H} (t) {\bf q} (t) \bigg ) {\rm d} t \\
& + \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} {\rm d} S (t)
+ \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)} {\rm d} {\bf q} (t) \\
=& \bigg (\frac{\partial O (t,s,{\bf q})} {\partial t}\bigg|_{s=S(t),{\bf q}={\bf q}(t)}
+ S(t) % \left
\bigg \langle \frac{\partial^2 O (t,s,{\bf q})}{\partial {\bf q} \partial s}\bigg|_{s=S(t),{\bf q}={\bf q}(t)}, \sigma(t) {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle \\
& + \frac{1}{2} \frac{\partial^2 O (t,s,{\bf q}(t))}{\partial s^2}\bigg|_{s=S(t)} \sigma^2 (t) S(t) ^2
+ \frac{1}{2} \sigma^{-1} (t) {\bf q}^{\prime} (t) {\bf H}^{\prime} (t) \frac{\partial^2 O (t,S(t),{\bf q})}{\partial {\bf q}^2}\bigg|_{{\bf q}={\bf q}(t)} {\bf H} (t) {\bf q} \\
& + % \left
\bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}, {\bf A}^{\mathbb{Q}} (t) {\bf q} (t) % \right
\bigg \rangle \bigg ) {\rm d} t + % \left
\bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}, {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle {\widehat \theta} (t) {\rm d} t \\
&+ \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} {\rm d} S (t) + % \left
\bigg \langle \frac{\partial O(t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}, {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle {\rm d} {\skew2\widehat W} (t) \\
=& \bigg(r(t)O(t,s,q)- \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)}r(t)S(t)- % \left
\bigg \langle \frac{\partial O(t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}, {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle {\widehat \theta} (t)\bigg) {\rm d} t \\
& + \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} {\rm d} S (t) + % \left
\bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}, {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle {{\rm d} {\skew2\widehat W} (t)},
\label{eqn13}\end{align}
where the last equation follows by (12). Substituting for
 ${\rm d} S(t)$
in (13) we obtain
 \begin{align*}
& {\rm d} O (t,S(t),{\bf q}(t)) \\
&= \bigg(r(t)O(t,S(t),{\bf q}(t))- % \left
\bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}, {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle {\widehat \theta} (t)\\
&+\frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} \sigma(t)\widehat{\theta}(t)S(t)\bigg) {\rm d} t \\
&+\bigg(\frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} \sigma(t)S (t) + % \left
\bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}, {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle\bigg) {{\rm d} {\skew2\widehat W (t)}}
\\
&= \bigg ( r (t) O (t,S(t),{\bf q}(t)) + \sigma (t) {\widehat \theta} (t) S(t) \frac{\partial O(t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)}\\
& + \sigma (t) {\widehat \theta} (t) % \left.
\bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}, {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle \,\sigma^{-1} (t) \bigg ) {\rm d} t % \\ &
+ \bigg ( \frac{\partial O (t,s,{\bf q}(t))}{\partial s}\bigg|_{s=S(t)} + \\ % \left
& \bigg \langle \frac{\partial O (t,S(t),{\bf q})}{\partial {\bf q}}\bigg|_{{\bf q}={\bf q}(t)}, {\bf H} (t) {\bf q} (t) % \right
\bigg \rangle \,\sigma^{-1} (t) S^{-1} (t) \bigg ) \sigma (t) S(t) {\rm d} {\skew2\widehat W} (t).
\end{align*}
From the SPDE in Lemma 2, we can see that the information state process
 $\{ {\bf q} (t) \mid t \in {\cal T} \}$
affects the ‘real-world’ expected return on the option through the market price of risk of the underlying share and the elasticity of the option. The former may be understood as the speculative component of the ‘real-world’ expected return on the option while the latter may be thought of as the hedging component of the ‘real-world’ expected return on the option. Consequently, the information state process, or the probability belief of the economic agent on the hidden economic state, influences both the speculative and hedging components of the ‘real-world’ expected return on the option.
Remark 2. The dynamics of the price processes of the option under a real-world probability measure were also derived by Korn and Kraft [Reference Korn and Kraft23] and Fu et al. [Reference Fu, Wei and Yang13]. However, in Korn and Kraft [Reference Korn and Kraft23] the focus was on stochastic interest rates and a modeling framework without regime shifts was considered, while in Fu et al. [Reference Fu, Wei and Yang13] the underlying Markov chain was observable. Consequently, in both Korn and Kraft [Reference Korn and Kraft23] and Fu et al. [Reference Fu, Wei and Yang13] filtering was not discussed, and so, unlike in Lemma 2 above, the price processes of option prices under the real-world probability measure in Korn and Kraft [Reference Korn and Kraft23] and Fu et al. [Reference Fu, Wei and Yang13] did not involve the filtering equation for the unnormalized filter
 $\{ {\bf q} (t) \mid t \in {\cal T} \}$
.
For each
 $t \in {\cal T}$
, let
 \begin{eqnarray}
{\widehat \zeta} (t) \,:\!= {\widehat \theta} (t) \eta_s (t).
\label{eqn14}
\end{eqnarray}
This may be interpreted as the market price of risk of the claim O at time t in the filtered market.
Then, by Lemma 2 and (14) we can observe that, under
 $\mathbb{P}$
, the price dynamics
 $\{ O (t) \mid t \in {\cal T} \}$
of the claim are governed by
 \begin{eqnarray*}
\frac{ {\rm d} O (t) } {O (t) } = (r(t) + \sigma (t) {\widehat \zeta} (t) ) {\rm d} t + \eta_s (t) \sigma (t) {\rm d} {\skew2\widehat W} (t).
\end{eqnarray*}
Recall that the wealth equation is given by
 \begin{eqnarray*}
{\rm d} V(t) = \pi_o (t) \frac{{\rm d} O (t)}{O (t)} + \pi_s (t) \frac{{\rm d} S (t)}{S (t)} + (V (t) - \pi_o (t) - \pi_s (t)) r (t) {\rm d} t.
\end{eqnarray*}
Then, under
 $\mathbb{P}$
the wealth equation in the filtered market is governed by
 \begin{eqnarray*}
&&{\rm d} V (t) = ( r (t) V (t) + \sigma (t) \pi_o (t) {\widehat \zeta} (t) + \sigma (t) \pi_s (t) {\widehat \theta} (t) ) {\rm d} t \nonumber\\
&&\qquad\quad\ \ +\ (\pi_o (t) \eta_s (t) + \pi_s (t)) \sigma (t) {\rm d} {\skew2\widehat W} (t).
\end{eqnarray*}
4. An optimal solution by the martingale approach
In this section we consider the martingale approach that has been used to study optimal asset allocations under hidden Markovian regime-switching markets (see, for example, Korn et al. [Reference Korn, Siu and Zhang24], Siu [Reference Siu38,Reference Siu40], and the relevant references therein). However, it does not seem that the martingale approach has been used to discuss optimal asset allocation problems with derivative securities under hidden Markovian regime-switching models in the aforementioned literature. Note also that a combination of the martingale approach with the option replication approach has also been used by Korn and Trautmann [Reference Korn and Trautmann22] to derive an explicit solution to an optimal consumption–investment problem with multiple risky assets and derivative securities in the presence of trading constraints. However, they did not consider the presence of regime shifts in the price processes of the risky assets in their model. Here, using the martingale approach together with the Clark–Ocone formula and Malliavin calculus, an optimal portfolio strategy for a general utility function is firstly characterized in terms of Malliavin derivatives of some quantities and the generalized elasticity. As in Fu et al. [Reference Fu, Wei and Yang13], the optimal proportion of wealth invested in the share can be decomposed into a speculative component and a hedging component for the general utility function case. Then, three types of utility functions including an exponential utility, a power utility, and a logarithmic utility are considered. For the cases of the exponential utility and the power utility, the speculative component can be further decomposed into two parts, one part depending explicitly on the risk preference parameter and the other depending explicitly on the market price of risk. For a logarithmic utility, a compact formula for an optimal portfolio strategy is obtained. The formula represents the optimal portfolio strategy in terms of the generalized elasticity or the generalized delta-hedged ratio of the derivative security.
In Fu et al. [Reference Fu, Wei and Yang13], a compact solution to an optimal asset allocation problem with derivatives for a power utility function was also derived in a Markovian regime-switching modeling framework. However, they considered the situation where the modulating Markov chain is observable. The situation considered here may be more general. Furthermore, in Fu et al. [Reference Fu, Wei and Yang13] a Hamiltonian–Jacobi–Bellman (HJB) dynamic programming approach was used to discuss the optimal asset allocation problem. Here the martingale approach is used to discuss the problem. The results presented below are derived from the standard martingale approach based on classical convex dual arguments in, for example, Karatzas [Reference Karatzas18], Karatzas et al. [Reference Karatzas, Lehoczky, Shreve and Xu20], and Cvitanic and Karatzas [Reference Cvitanic and Karatzas7]. For the equivalence between the original asset allocation problem and the one in the filtered market, we follow the arguments in Rieder and Bäuerle [Reference Rieder and Bäuerle35].
Recall that under the real-world probability measure
 $\mathbb{P}$
, the wealth equation in the filtered economy is given by
 \begin{eqnarray}
{\rm d} V (t) &=& (r (t) V (t) + \pi_o (t) \sigma (t) {\widehat \zeta} (t) + \pi_s (t) \sigma (t) {\widehat \theta} (t) ) {\rm d} t \nonumber\\
&& +\ (\pi_o (t) \eta_s (t) + \pi_s (t)) \sigma (t) {\rm d} {\skew2\widehat W} (t).
\label{eqn15}\end{eqnarray}
This is the dynamic budget constraint for the optimization problem in (11).
For each
 $t \in {\cal T}$
and
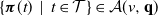 $\{ \boldsymbol{ \pi} (t) \mid t \in {\cal T} \} \in {\cal A} (v, {\bf q})$
with
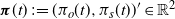 $\boldsymbol{ \pi} (t) \,:\!= (\pi_o (t), \pi_s (t))^{\prime} \in \mathbb{R}^2$
, let
 \begin{eqnarray}
{\bar \pi} (t) &\,:\!=& \pi_o (t) \eta_s (t) + \pi_s (t).
\label{eqn16}
\end{eqnarray}
It is obvious that the process
 $\{ {\bar \pi} (t) \mid t \in {\cal T} \}$
is adapted to the observed filtration
 $\mathbb{F}$
in the filtered market. Write
 ${\bar {\cal A}} (v, {\bf q})$
for the space of all such processes
 $\{ {\bar \pi} (t) \mid t \in {\cal T} \}$
. Then, under
 $\mathbb{P}$
, the wealth equation corresponding to
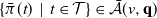 $\{ {\bar \pi} (t) \mid t \in {\cal T} \} \in {\bar {\cal A}} (v, {\bf q})$
becomes
 \begin{eqnarray}
{\rm d} V (t) = (r (t) V (t) + {\bar \pi} (t) \sigma (t) {\widehat \theta} (t) ) {\rm d} t + {\bar \pi} (t) \sigma (t) {\rm d} {\skew2\widehat W} (t).
\label{eqn17}
\end{eqnarray}
Note that
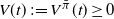 $V (t) \,:\!= V^{\bar \pi} (t) \ge 0$
,
 $\mathbb{P}$
-a.s., and so
 ${\bar {\cal A}} (v, {\bf q})$
may be interpreted as the space of admissible portfolio processes.
For each
 ${\bar \pi} \in {\bar {\cal A}} (v, {\bf q})$
and
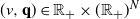 $(v, {\bf q}) \in \mathbb{R}_+ \times (\mathbb{R}_+)^N$
, let
 \begin{eqnarray*}
{\skew5\tilde J}_{\bar \pi} (v) \,:\!= \mathbb{E}^v [ U ( V^{\bar \pi} (T) ) ].
\end{eqnarray*}
Assume that
 \begin{eqnarray*}
\mathbb{E}^v [ U^- (V^{\bar \pi} (T)) ] < \infty,
\end{eqnarray*}
where
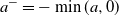 $a^- = - \min (a, 0)$
, (i.e.
 $a^-$
is the negative part of a real number a).
Since the wealth processes in (15) and (17) are the same, the optimization problem in (11) can be translated into the following ‘Merton’ problem:
 \begin{eqnarray}
{\tilde \Phi} (v) \,:\!= \max_{{\bar \pi} \in {\bar {\cal A}} (v, {\bf q})} {\skew5\tilde J}_{\bar \pi} (v),\nonumber
\end{eqnarray}
subject to the dynamic budget constraint given by (17).
Note that
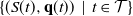 $\{ (S (t), {\bf q} (t)) \mid t \in {\cal T} \}$
is the joint state process in the filtered market. Write, for each
 ${\bar \pi} \in {\bar {\cal A}} (v, {\bf q})$
and each
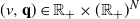 $(v, {\bf q}) \in \mathbb{R}_+ \times (\mathbb{R}_+)^N$
,
 \begin{eqnarray}
J_{\bar \pi} (v, {\bf q}) \,:\!= \mathbb{E}^{(v, {\bf q})} [U(V^{\bar \pi} (T))],\nonumber
\end{eqnarray}
where
 $\mathbb{E}^{(v, {\bf q})}$
is the conditional expectation under
 $\mathbb{P}$
given that
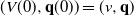 $(V (0), {\bf q} (0)) = (v, {\bf q})$
.
Then the ‘Merton’ problem in the filtered market is given by
 \begin{eqnarray}
\Phi (v, {\bf q}) \,:\!= \max_{{\bar \pi} \in {\bar {\cal A}} (v, {\bf q})} J_{\bar \pi} (v, {\bf q})
= J_{{\bar \pi}^{\dagger}} (v, {\bf q}), \quad
% \forall
\text{for all} \ (v, {\bf q}) \in \mathbb{R}_+ \times (\mathbb{R}_+)^N.
\label{eqn18}
\end{eqnarray}
Here,
 $\Phi (v, {\bf q})$
is the ‘Merton’ problem in the filtered market;
 ${\bar \pi}^{\dagger}$
is an optimal portfolio process and
 ${\bar \pi}^{\dagger} \in {\bar {\cal A}}
(v, {\bf q})$
.
We now prove the following lemma which gives the equivalence between the natural filtration generated by
 $\{ Y (t) \mid t \in {\cal T} \}$
and the natural filtration generated by
 $\{ {\skew2\widehat W} (t) \mid t \in {\cal T} \}$
. This result was stated in Rieder and Bäuerle [Reference Rieder and Bäuerle35], Lemma 1. However, it does not seem that a proof was given there. This result will be used in the theorem below which shows that the optimization problem in the filtered market is the one with complete observations.
Lemma 3.
 $\mathbb{F} = \mathbb{F}^Y = \mathbb{F}^{\skew2\widehat W}$
, where
 $\mathbb{F}^Y$
is the
 $\mathbb{P}$
-augmentation of the natural filtration generated by
 $\{ Y (t) \mid t \in {\cal T} \}$
and
 $\mathbb{F}^{\skew2\widehat W}$
is the
 $\mathbb{P}$
-augmentation of the natural filtration generated by
 $\{ {\skew2\widehat W} (t) \mid t \in {\cal T} \}$
.
Proof. Firstly, by recalling that
 $\mathbb{F}\,:\!=\mathbb{F}^S$
and
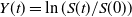 $Y(t)=\ln(S(t)/S(0))$
, the statement
 $\mathbb{F} = \mathbb{F}^Y$
follows immediately. Then we shall show that
 ${\cal F}^{\skew2\widehat W} (t) \subseteq {\cal F}^Y (t)$
, for all
 $t \in {\cal T}$
. From the definition of the process
 $\{ {\skew2\widehat W} (t) \mid t \in {\cal T} \}$
[see (3)] we know that the process is
 $\mathbb{F}$
-adapted and that it is also
 $\mathbb{F}^Y$
-adapted since
 $\mathbb{F}^Y = \mathbb{F}$
. This implies that
 ${\skew2\widehat W} (t)$
is
 ${\cal F}^Y (t)$
-measurable for all
 $t \in {\cal T}$
. By the definition of
 ${\cal F}^{\skew2\widehat W} (t)$
,
 ${\cal F}^{\skew2\widehat W} (t) \subseteq {\cal F}^Y (t)$
, for all
 $t \in {\cal T}$
.
In what follows, we shall prove that
 ${\cal F}^Y (t) \subseteq {\cal F}^{\skew2\widehat W} (t)$
, for all
 $t \in {\cal T}$
. To prove this statement, we shall first show that
 ${\widehat {\bf X}} (t)$
is
 ${\cal F}^{\skew2\widehat W} (t)$
-measurable for all
 $t \in {\cal T}$
.
From (5), we have:
 \begin{eqnarray}
Y (t) &=& \int^{t}_{0} % \left
\langle \boldsymbol{{\mu}} (u), {\bf X} (u) % \right
\rangle {\rm d} u + \int^{t}_{0} \sigma (u) {\rm d} W (u) \nonumber\\
&=& \int^{t}_{0} % \left
\langle \boldsymbol{{\mu}} (u), {\widehat {\bf X}} (u) % \right
\rangle {\rm d} u + \int^{t}_{0} \sigma (u) {\rm d} {\skew2\widehat W} (u).
\label{eqn19}\end{eqnarray}
 \begin{eqnarray}
{\rm d} {\bf q}(t) &=& {\bf A}(t) {\bf q}(t) {\rm d} t + {\bf H}(t) {\bf q}(t) \sigma^{-1} (t) {\rm d} Y (t) \nonumber\\
&=& {\bf A}(t) {\bf q}(t) {\rm d} t + {\bf H}(t) {\bf q}(t) \sigma^{-1} (t) % \left(\left
( \langle\boldsymbol{{\mu}}(t), {\widehat {\bf X}} (t) % \right
\rangle {\rm d} t + \sigma (t) {\rm d} {\skew2\widehat W} (t) %\right
).
\label{eqn20}\end{eqnarray}
It is known that, by a version of the Bayes’ rule,
 \begin{eqnarray}
{\widehat {\bf X}}(t) \,:\!=\mathbb{E}[X(t)\mid{\cal F} (t)] = \frac{{\bf q}(t)} { \langle{\bf q} (t), {\bf 1} \rangle},
\label{eqn21}
\end{eqnarray}
where
 ${\bf 1}$
is the vector of all ones in
 $\mathbb{R}^N$
.
 \begin{eqnarray}
{\rm d} {\bf q}(t) = {\bf A}(t) {\bf q} (t) {\rm d} t + {\bf H}(t) {\bf q}(t) \sigma^{-1} (t) \bigg ( \frac{ \langle\boldsymbol{{\mu}} (t), {\bf q}(t) \rangle}{ \langle{\bf q}(t), {\bf 1} \rangle}
{\rm d} t + \sigma (t) {\rm d} {\skew2\widehat W} (t) \bigg ).
\label{eqn22}
\end{eqnarray}
From (22), it can be seen that
 ${\bf q} (t)$
is
 ${\cal F}^{\skew2\widehat W} (t)$
-measurable for all
 $t \in {\cal T}$
. This, together with (21), imply that
 ${\widehat {\bf X}}(t)$
is
 ${\cal F}^{\skew2\widehat W} (t)$
-measurable for all
 $t \in {\cal T}$
. Since
 ${\widehat {\bf X}} (t)$
is
 ${\cal F}^{\skew2\widehat W} (t)$
-measurable, by using (19) again Y (t) is
 ${\cal F}^{\skew2\widehat W} (t)$
-measurable for all
 $t \in {\cal T}$
. This implies that
 ${\cal F}^Y (t) \subseteq {\cal F}^{\skew2\widehat W} (t)$
for all
 $t \in {\cal T}$
.
The following theorem shows that the optimization problem in the filtered market is the one with complete observations. This is an adaptation of the result in Theorem 1 of Rieder and Bäuerle [Reference Rieder and Bäuerle35] to the filtered market considered here.
Theorem 1. For each
 $\boldsymbol{ \pi} \in {\cal A} (v, {\bf q})$
and each
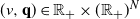 $(v, {\bf q}) \in \mathbb{R}_+ \times
(\mathbb{R}_+)^N$
,
 \begin{eqnarray}
J_{\bar \pi} (v, {\bf q}) = {\skew5\tilde J}_{\bar \pi} (v) %,
\label{eqn23}
\end{eqnarray}
and
 \begin{eqnarray}
\Phi (v, {\bf q}) = {\tilde \Phi} (v).
\label{eqn24}
\end{eqnarray}
Proof. The proof follows from that of Theorem 1 in Rieder and Bäuerle [Reference Rieder and Bäuerle35]. First, from Lemma 3,
 \begin{eqnarray}
\mathbb{F} = \mathbb{F}^Y = \mathbb{F}^{\skew2\widehat W}.
\label{eqn25}
\end{eqnarray}
From (6) and (19), the information state process in the filtered market can be written as
 \begin{eqnarray}
{\bf q} (t) &=& {\bf q} (0) + \int^{t}_{0} {\bf A} (u) {\bf q} (u) {\rm d} u + \int^{t}_{0} {\bf H} (u) {\bf q} (u) \sigma^{-1} (u) \nonumber\\
&& \times ( %\left
\langle \boldsymbol{{\mu}} (u), {\widehat {\bf X}} (u) % \right
\rangle {\rm d} u + \sigma (u) {\rm d} {\skew2\widehat W} (u) ).
\label{eqn26}\end{eqnarray}
Consequently, by (19), (25), and (26), the three statements in Lemma 1 of Rieder and Bäuerle [Reference Rieder and Bäuerle35] hold. Hence, the first statement (23) follows (see Rieder and Bäuerle [Reference Rieder and Bäuerle35], p. 365). The second statement (24) follows directly from the first statement.
Define the
 $\mathbb{F}$
-adapted process
 $\{ Z_0 (t) \mid t \in {\cal T} \}$
by putting
 \begin{eqnarray*}
Z_0 (t) \,:\!= \exp \bigg (\!-\! \int^{t}_{0} r (u) {\rm d} u \bigg ) {\bar \Lambda} (t).
\end{eqnarray*}
This is the state price density in the filtered economy. In the finance literature,
 $Z_0 (t)$
is called the stochastic discount factor or the pricing kernel. Since the market in the filtered economy is complete,
 $Z_0 (t)$
is uniquely determined.
To make the problem in (18) meaningful, as in Standing Assumption 5.1 on p. 708 of Karatazs et al. [Reference Karatzas, Lehoczky, Shreve and Xu20], the following condition on the value function
 $\Phi (v, {\bf q})$
is required:
 \begin{eqnarray}
\Phi (v, {\bf q}) < \infty %,
\quad % \forall
\text{for all}\ (v, {\bf q}) \in \mathbb{R}_+ \times (\mathbb{R}_+)^N.
\label{eqn27}
\end{eqnarray}
We now impose the following assumption on the utility function as in (5.4) on p. 708 of Karatzas et al. [Reference Karatzas, Lehoczky, Shreve and Xu20]:
 \begin{eqnarray}
U (x) \le c_1 + c_2 x^{\delta},
\label{eqn28}
\end{eqnarray}
where
 $c_1 > 0$
,
 $c_2 > 0$
, and
 $\delta \in (0, 1)$
.
From the definition of the market price of risk
 $\theta (t)$
(called the relative risk process in Karatzas et al. [Reference Karatzas, Lehoczky, Shreve and Xu20] on p. 708, defined on p. 5, and with its filtered estimate
 ${\widehat \theta} (t)$
on p. 6) we have:
 \begin{eqnarray*}
{\widehat \theta} (t) = % \left
\langle \boldsymbol{ \theta}, {\widehat {\bf X}} (t) % \right
\rangle.
\end{eqnarray*}
It is not difficult to see that the following finite energy condition is satisfied in the filtered market:
 \begin{eqnarray}
\int^{T}_{0} | {\widehat \theta} (t) |^2 {\rm d} t \le K, \quad \mbox{$\mathbb{P}$-a.s.},
\label{eqn29}
\end{eqnarray}
for some given positive constant K. Here we borrow the terminology of ‘finite energy condition’ from p. 769 of Cvitanic and Karatzas [Reference Cvitanic and Karatzas7].
As noted in Remark 5.2 on p. 708 of Karatzas et al. [Reference Karatzas, Lehoczky, Shreve and Xu20], the finite energy condition in the filtered market in (29) together with the assumption in (28) imply that the condition in (27) is satisfied. Alternatively, as noted in Remark 6.4 on p. 774 of Cvitanic and Karatzas [Reference Cvitanic and Karatzas7], if r (t) and
 ${\widehat \theta} (t)$
are uniformly bounded in
 $(t, \omega) \in {\cal T} \times \Omega$
and the utility function U (x) satisfies the growth condition that
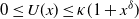 $0 \le U (x) \le \kappa (1 + x^{\delta})$
for all
 $x \in (0, \infty)$
, for some given constants
 $\kappa \in (0, \infty)$
and
 $\delta \in (0, 1)$
, then the condition in (27) is satisfied.
Write
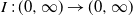 $I\,:\,(0, \infty) \rightarrow (0, \infty)$
for the inverse map of
 $U^{\prime}$
, where
 $U^{\prime}$
is the first derivative of the utility function U. It is supposed that the inverse map I is continuously differentiable, (i.e. the derivative
 $I^{\prime}$
exists and is continuous). Define, for each
 $\lambda \in (0, \infty)$
,
 \begin{eqnarray*}
L (\lambda) \,:\!= \mathbb{E} [ Z_0 (T) I ( \lambda Z_0 (T)) ].
\end{eqnarray*}
Assume that
 $L (\lambda) < \infty$
for all
 $\lambda \in (0, \infty)$
as in (7.8) of Karatzas et al. [Reference Karatzas, Lehoczky, Shreve and Xu20]. Let
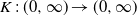 $K \,:\, (0, \infty) \rightarrow (0, \infty)$
be the inverse map of L. The inverse map K of L is well defined under the assumption that
 $L (\lambda) < \infty$
for all
 $\lambda \in (0, \infty)$
; see, for example, p. 712 of Karatzas et al. [Reference Karatzas, Lehoczky, Shreve and Xu20]. Then, using the standard martingale approach (see, for example, Lemma 7.2 in Cvitanic and Karatzas [Reference Cvitanic and Karatzas7]), the optimal terminal wealth of the Merton problem in (18) is given by
 \begin{eqnarray*}
V^{\dagger} (T) = I (K (v) Z_0 (T)),
\end{eqnarray*}
where
 $V^{\dagger} (T)$
satisfies the following two conditions:
1.
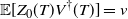 $\mathbb{E} [ Z_0 (T) V^{\dagger} (T) ] = v$
;
2.
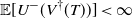 $\mathbb{E} [ U^- (V^{\dagger} (T)) ] < \infty$
.
Define, for each
 $t \in {\cal T}$
,
 \begin{eqnarray*}
M (t) \,:\!= \mathbb{E} [ Z_0 (T) V^{\dagger} (T) | {\cal F} (t) ].
\end{eqnarray*}
This is an
 $(\mathbb{F}, \mathbb{P})$
-martingale. Note that the discounted optimal wealth process is an
 $(\mathbb{F}, \mathbb{Q})$
-martingale, and so
 \begin{eqnarray*}
M (0) = \mathbb{E} [ Z_0 (T) V^{\dagger} (T) ] = v.
\end{eqnarray*}
By the martingale representation theorem (see, for example, Section 3.4 of Karatzas and Shreve [Reference Karatzas and Shreve19]), there is an
 $\mathbb{F}$
-progressively measurable,
 $\mathbb{R}$
-valued process
 $\{ \varphi (t) \mid t \in {\cal T} \}$
satisfying
 \begin{eqnarray*}
\int^{T}_{0} | \varphi (t) |^2 {\rm d} t < \infty, \quad \mbox{$\mathbb{P}$-a.s.},
\end{eqnarray*}
such that
 \begin{eqnarray}
M (t) = v + \int^{t}_{0} \varphi (u) {\rm d} {\skew2\widehat W} (u), \quad \mbox{$\mathbb{P}$-a.s.}
\label{eqn30}
\end{eqnarray}
Using the standard martingale approach (see, for example, Theorem 7.4 in Cvitanic and Karatzas [Reference Cvitanic and Karatzas7]), the optimal portfolio process
 $\{ {\bar \pi}^{\dagger} (t) \mid t \in {\cal T} \}$
of the Merton problem in (18) is given by:
 \begin{eqnarray*}
{\bar \pi}^{\dagger} (t) = \sigma^{-1} (t) \bigg ( \frac{\varphi (t)} {Z_0 (t)} + {\widehat \theta} (t) V^{\dagger} (t) \bigg ).\label{optimal-pi}
\end{eqnarray*}
Therefore, any admissible pair
 $(\pi_0(t),\pi_s(t))$
that satisfies the constraint
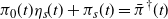 $\pi_0(t)\eta_s(t)+\pi_s(t)={\bar \pi}^{\dagger} (t)$
is an optimal strategy for the original optimal asset allocation problem in (11). That is, any admissible pair satisfying the constraint in (16) gives rise to the same level of the expected utility on the terminal wealth in (11).
The optimal portfolio process
 $\{ {\bar \pi^{\dagger} } (t) \mid t \in {\cal T} \}$
involves the integrand process
 $\{ \varphi (t) \mid t \in {\cal T} \}$
in the martingale representation for
 $\{ M (t) \mid t \in {\cal T} \}$
in (30). In what follows, the Clark–Ocone formula and Malliavin calculus will be used to determine the integrand process
 $\{ \varphi (t) \mid t \in {\cal T} \}$
. Indeed, the Clark–Ocone formula and Malliavin calculus have been quite widely used to derive optimal asset allocation strategies in the literature. Some examples are Sass and Haussmann [Reference Sass and Haussmann36], Lakner and Nygren [Reference Lakner and Nygren26], Detemple and Rindisbacher [Reference Detemple and Rindisbacher8], and Liu [Reference Liu28], amongst others. In particular, Sass and Haussmann [Reference Sass and Haussmann36] and Liu [Reference Liu28] adopted the Clark–Ocone formula and Malliavin calculus to derive optimal portfolio strategies in continuous-time, hidden Markovian regime-switching diffusion models. However, neither Sass and Haussmann [Reference Sass and Haussmann36] nor Liu [Reference Liu28] considered the presence of derivative securities as investment opportunities. Detemple and Rindisbacher [Reference Detemple and Rindisbacher8] adopted the martingale approach together with Malliavin calculus to study optimal asset allocation in the presence of stochastic interest rates and investment constraints. An interest-rate derivative for hedging interest rate risk was included in the investment opportunities set in Detemple and Rindisbacher [Reference Detemple and Rindisbacher8]. However, Detemple and Rindisbacher [Reference Detemple and Rindisbacher8] did not consider the presence of the Markovian regime-switching effect in their modeling framework.
For each
 $t \in {\cal T}$
, let
 $D_t M (T)$
be the Malliavin derivative of M (T) with respect to the Brownian motion
 $\{ {\skew2\widehat W} (t) \mid t \in {\cal T} \}$
evaluated at time t. For the definition of Malliavin derivatives with respect to Brownian motions, one may refer to Chapter 5 of Nualart [Reference Nualart33]. Then, by the Clark–Ocone formula (see, for example, Proposition 1.3.14 of Nualart [Reference Nualart33]),
 \begin{eqnarray*}
M (T) = Z_0 (T) V^{\dagger} (T) = v + \int^{T}_{0} \mathbb{E} [ D_t M (T) | {\cal F} (t) ] {\rm d} {\skew2\widehat W} (t), \quad \mbox{$\mathbb{P}$-a.s.}
\end{eqnarray*}
By the uniqueness of the integrand process of the martingale representation (see, for example, Section 3.4 of Karatzas and Shreve [Reference Karatzas and Shreve19]),
 \begin{eqnarray}
\varphi (t) = \mathbb{E} [ D_t M (T) | {\cal F} (t) ], \quad \mbox{$\mathbb{P}$-a.s.}
\label{eqn31}
\end{eqnarray}
It remains to evaluate
 $D_t M (T)$
. By the product rule (see, for example, Theorem 3.4 in Di Nunno et al. [Reference Di Nunno, Øksendal and Proske9]),
 \begin{eqnarray*}
D_t M (T) = Z_0 (T) D_t V^{\dagger} (T) + V^{\dagger} (T) D_t Z_0 (T).
\end{eqnarray*}
Note that
 \begin{eqnarray*}
V^{\dagger} (T) = I (K(v) Z_0 (T)).
\end{eqnarray*}
Then, by the chain rule (see, for example, Theorem 3.5 in Di Nunno et al. [Reference Di Nunno, Øksendal and Proske9]),
 \begin{eqnarray*}
D_t V^{\dagger} (T) = I^{\prime} (K(v) Z_0 (T)) K (v) D_t Z_0 (T).
\end{eqnarray*}
Consequently,
 \begin{eqnarray}
D_t M (T) = ( I^{\prime} (K(v) Z_0 (T)) K(v) Z_0 (T) + I (K(v) Z_0 (T)) ) D_t Z_0 (T).
\label{eqn32}
\end{eqnarray}
By Corollary 3.19 in Di Nunno et al. [Reference Di Nunno, Øksendal and Proske9],
 \begin{eqnarray}
D_t \bigg ( \int^{T}_{0} {\widehat \theta} (u) {\rm d} {\skew2\widehat W} (u) \bigg )
&=& {\widehat \theta} (t) + \int^{T}_{0} D_t {\widehat \theta} (u) {\rm d} {\skew2\widehat W} (u) \nonumber\\
&=& {\widehat \theta} (t) + \int^{T}_{t} D_t {\widehat \theta} (u) {\rm d} {\skew2\widehat W} (u).
\label{eqn33}\end{eqnarray}
The last equality follows from the fact that
 $D_t G = 0$
for an
 ${\cal F} (u)$
-measurable random variable G with
 $u< t$
(see, for example, Corollary 3.13(ii) in Di Nunno et al. [Reference Di Nunno, Øksendal and Proske9]). Equation (33) together with the chain rule give:
 \begin{eqnarray*}
D_t Z_0 (T) = - Z_0 (T) \bigg ( \int^{T}_{t} {\widehat \theta} (u) D_t {\widehat \theta} (u) {\rm d} u
+ {\widehat \theta} (t) + \int^{T}_{t} D_t {\widehat \theta} (u) {\rm d} {\skew2\widehat W} (u) \bigg ).
\end{eqnarray*}
To simplify the notation, write, for each
 $t \in {\cal T}$
,
 \begin{eqnarray}
\Gamma (t, T) \,:\!= \int^{T}_{t} {\widehat \theta} (u) D_t {\widehat \theta} (u) {\rm d} u + {\widehat \theta} (t) + \int^{T}_{t} D_t {\widehat \theta} (u) {\rm d} {\skew2\widehat W} (u).
\label{eqn34}
\end{eqnarray}
Then
 \begin{equation}
D_t Z_0 (T) = - Z_0 (T) \Gamma (t, T).
\label{eqn35}
\end{equation}
This, along with (31) and (32), gives:
 \begin{eqnarray}
\varphi (t) = - \mathbb{E} [ ( I^{\prime} ( K (v) Z_0 (T)) K(v) Z_0 (T) + I (K(v) Z_0 (T)) ) Z_0 (T) \Gamma (t, T) | {\cal F} (t) ].
\label{eqn36}
\end{eqnarray}
Note that
 $\Gamma (t, T)$
may be interpreted as the negative of the relative change in the state price density in the filtered market with respect to the random shock in the filtered market.
From (31), it can be seen that the key for the Clark–Ocone formula for the integrand of the martingale representation to hold is the Malliavin differentiability of
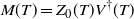 $M (T) = Z_0 (T) V^{\dagger} (T)$
. That is, whether the random variable
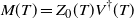 $M (T) = Z_0 (T) V^{\dagger} (T)$
belongs to the domain of Malliavin derivatives with respect to the Brownian motion
 $\{ {\skew2\widehat W} (t) \mid t \in {\cal T} \}$
. From (32), (34), and (35), we can see that the Malliavin differentability of M (T) can be proved by checking the Malliavin differentiability of
 ${\widehat \theta} (t)$
, say the existence of the Malliavin derivative
 $D_t {\widehat \theta} (u)$
. Alternatively, from (36), it can be seen that the integrand
 $\varphi (t)$
of the martingale representation from the Clark–Ocone formula depends on the term
 $\Gamma (t, T)$
. This is the only term in the integrand
 $\varphi (t)$
which involves Malliavin derivatives, and the only Malliavin derivative involved is
 $D_t {\widehat \theta} (u)$
.
Again, it is known that, by a version of Bayes’ rule,
 \begin{eqnarray}
{\widehat \theta} (t) = \frac{\langle \boldsymbol{ \theta}, {\bf q} (t) \rangle }{ \langle {\bf q} (t), {\bf 1} \rangle},
\label{eqn37}
\end{eqnarray}
where
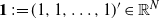 ${\bf 1} \,:\!= (1, 1, \ldots, 1)^{\prime} \in \mathbb{R}^N$
.
Again, using the chain rule and product rule for Malliavin derivatives, for
 $u > t$
,
 \begin{eqnarray}
D_t {\widehat \theta} (u) = \frac{ \langle \boldsymbol{ \theta}, D_t {\bf q} (u) \rangle}{ \langle {\bf q} (u), {\bf 1} \rangle}
- \frac{\langle \boldsymbol{ \theta}, {\bf q} (u) \rangle\, \langle D_t {\bf q} (u), {\bf 1} \rangle}{ \langle {\bf q} (u), {\bf 1} \rangle^2}.
\label{eqn38}
\end{eqnarray}
From (38), the existence of the Malliavin derivative
 $D_t {\widehat \theta} (u)$
can be proved by the existence of the Malliavin derivative
 $D_t {\bf q} (u)$
.
To prove the existence of the Malliavin derivative
 $D_t {\bf q} (u)$
, we follow the proof of Proposition 4.2 in Sass and Haussmann [Reference Sass and Haussmann36] to check that the boundedness conditions in Proposition 8.2 in Sass and Haussmann [Reference Sass and Haussmann36] are satisfied.
We now take:
 \begin{eqnarray}
{\bf f}^{\bf q} (t, {\bf q}) = {\bf A} (t) {\bf q} \in \mathbb{R}^N, \quad {\bf g}^{\bf q} (t, {\bf q}) = {\bf H} (t)
{\bf q} \sigma^{-1} (t) \in \mathbb{R}^N.
\label{eqn39}
\end{eqnarray}
Then
 ${\bf f}^{\bf q} (t, {\bf q})$
and
 ${\bf g}^{\bf q} (t, {\bf q})$
are measurable and continuously differentiable functions. Also, from (8), we can see that the dynamics for the unnormalized filter
 ${\bf q} (t)$
can be written as
 \begin{eqnarray*} \label{filtermodifed}
{\rm d} {\bf q} (t) = {\bf f}^{\bf q} (t, {\bf q} (t)) {\rm d} t + {\bf g}^{\bf q} (t, {\bf q} (t)) {\rm d} Y (t).
\end{eqnarray*}
Write, for each
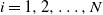 $i = 1, 2, \ldots, N$
,
 $f^{\bf q}_i (t, {\bf q})$
and
 $g^{\bf q}_i (t, {\bf q})$
for the ith element of
 ${\bf f}^{\bf q} (t, {\bf q})$
and
 ${\bf g}^{\bf q} (t, {\bf q})$
, respectively. Also, write
 $q_k$
for the kth element of q, for each
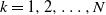 $k = 1, 2, \ldots, N$
. Consequently, by noting the boundedness of
 $a_{i,j}(t)$
(model assumption),
 $\mu_i(t)$
[see the paragraph below (4)], and
 $\sigma^{-1}(t)$
(model assumption), we can observe that the following two boundedness conditions are satisfied by
 ${\bf f}^{\bf q} (t, {\bf q})$
and
 ${\bf g}^{\bf q} (t, {\bf q})$
defined in (39):
 \begin{eqnarray}
\sup_{t \in [0, T], {\bf q} \in \mathbb{R}^N} \bigg ( \bigg | \frac{\partial f^{\bf q}_i (t, {\bf q})}{\partial q_{k}} \bigg |
+ \bigg | \frac{\partial g^{\bf q}_i (t, {\bf q})}{\partial q_{k}} \bigg | \bigg ) < \infty, \quad % \forall
\text{for all}\ i, k = 1, 2, \ldots, N,
\label{eqn40}
\end{eqnarray}
and
 \begin{eqnarray}
\sup_{t \in [0, T]} \bigg ( | f^{\bf q}_i (t, {\bf q}) | + | g^{\bf q}_i (t, {\bf q}) | \bigg ) < \infty, \quad % \forall
\text{for all}\ i = 1, 2, \ldots, N.
\label{eqn41}
\end{eqnarray}
Note that (40) and (41) are the two boundedness conditions in Proposition 8.2 of Sass and Haussmann [Reference Sass and Haussmann36]. Consequently, the Malliavin derivative
 $D_t {\bf q} (u)$
exists.
Recall that any admissible pair
 $(\pi_0(t),\pi_s(t))$
that satisfies
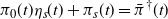 $\pi_0(t)\eta_s(t)+\pi_s(t)={\bar \pi}^{\dagger} (t)$
is an optimal strategy for the original optimal asset allocation problem in (11). Therefore, the portfolio strategy
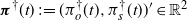 $\boldsymbol{ \pi}^{\dagger} (t) \,:\!= (\pi^{\dagger}_o (t), \pi^{\dagger}_s (t))^{\prime} \in \mathbb{R}^2$
determined below is an optimal strategy:
 \begin{eqnarray}
&&{\bar \pi}^{\dagger} (t) = \pi^{\dagger}_o (t) \eta_s (t) + \pi^{\dagger}_s (t),\nonumber\\
&&V^{\dagger} (t) = \pi^{\dagger}_o (t)+ \pi^{\dagger}_s (t).
\label{eqn42}\end{eqnarray}
Since the optimal strategy,
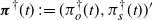 $\boldsymbol{ \pi}^{\dagger} (t) \,:\!= (\pi^{\dagger}_o (t), \pi^{\dagger}_s (t))^{\prime}$
, satisfies (42), it is a strategy that invests nothing into the money market (bond). Note that this particular strategy may not give rise to the maximum terminal wealth level. Nevertheless, it gives the maximum level of the expected utility on the terminal wealth in (11).
Solving the above equations gives:
 \begin{eqnarray}
\pi^{\dagger}_o (t) = \frac{V^{\dagger} (t) - {\bar \pi}^{\dagger} (t)} {1 - \eta_s (t)}
\label{eqn43}
\end{eqnarray}
and
 \begin{eqnarray}
\pi^{\dagger}_s (t) = \frac{{\bar \pi}^{\dagger} (t)}{1 - \eta_s (t)} - \frac{\eta_s (t) V^{\dagger} (t) }{1 - \eta_s (t)},
\label{eqn44}
\end{eqnarray}
where
 \begin{eqnarray*}
{\bar \pi}^{\dagger} (t) = \sigma^{-1} (t) \bigg ( \frac{\varphi (t)}{Z_0 (t)} + {\widehat \theta} (t) V^{\dagger} (t) \bigg ),
\end{eqnarray*}
 \begin{eqnarray*}
\varphi (t) = - \mathbb{E} [ ( I^{\prime} (K (v) Z_0 (T)) K (v) Z_0 (T) + I (K (v) Z_0 (T)) ) Z_0 (T) \Gamma (t, T) \mid {\cal F} (t) ].
\end{eqnarray*}
From (37) and the definition of
 ${\bar {\bf q}} (t)$
,
 \begin{eqnarray*} \label{thetahat1}
{\widehat \theta} (t) = \frac{ \langle \boldsymbol{ \theta}, {\bf q} (t) \rangle }{ \langle {\bf q} (t), {\bf 1} \rangle} = \frac{ \langle \boldsymbol{ \theta}, \boldsymbol{ \Sigma} (t) {\bar {\bf q}} (t) \rangle }{\langle \boldsymbol{ \Sigma} (t) {\bar {\bf q}} (t), {\bf 1} \rangle}.
\end{eqnarray*}
Remark 3. The optimal portfolio process depends on the robust filter
 ${\bar {\bf q}} (t)$
via the term
 ${\widehat \theta} (t)$
. This robust filter satisfies the (pathwise) linear, matrix-valued differential equation in (7).
For each
 $t \in {\cal T}$
, define
 ${\bar \pi}^{\dagger}_o (t)=\frac{ \pi^{\dagger}_o (t)}{V^{\dagger} (t)}$
and
 ${\bar \pi}^{\dagger}_s (t)=\frac{\pi^{\dagger}_s(t)}{V^{\dagger} (t)}$
. They represent the optimal proportions of wealth invested in the claim O and the share S at time t, respectively. It follows by (43) and (44) that
 \begin{eqnarray*}
{\bar \pi}^{\dagger}_o (t) = - \frac{\sigma^{-1} (t) \varphi (t) ( V^{\dagger} (t) )^{-1} Z^{-1}_0 (t) + \sigma^{-1} (t) {\widehat \theta} (t) }{1 - \eta_s (t)} + \frac{1}{1 - \eta_s (t)} %,
\end{eqnarray*}
and
 \begin{eqnarray*}
{\bar \pi}^{\dagger}_s (t) = \frac{\sigma^{-1} (t) \varphi (t) ( V^{\dagger} (t) )^{-1} Z^{-1}_0 (t) + \sigma^{-1} (t) {\widehat \theta} (t) }{1 - \eta_s (t)} - \frac{\eta_s (t)}{1 - \eta_s (t)}.
\end{eqnarray*}
As in Fu et al. [Reference Fu, Wei and Yang13], the optimal proportion of wealth invested in the share
 ${\bar \pi}^{\dagger}_s (t)$
can be decomposed into two components. The first component is the speculative component and is given by
 \begin{eqnarray*}
\frac{\sigma^{-1} (t) \varphi (t) ( V^{\dagger} (t) )^{-1} Z^{-1}_0 (t) + \sigma^{-1} (t) {\widehat \theta} (t) }{1 - \eta_s (t)}.
\end{eqnarray*}
The second component is the hedging component and is given by
 \begin{eqnarray*}
- \frac{\eta_s (t)}{1 - \eta_s (t)}.
\end{eqnarray*}
In the following we analyze the optimal strategy constructed above for three types of utility functions, namely an exponential utility, a power utility, and a logarithmic utility. In particular, for the logarithmic utility a compact solution to the optimal asset allocation is obtained.
4.1. Case I: Exponential utility
The utility function has the following form:
 \begin{eqnarray*}
U (x) = - \exp (\!-\!\alpha x), \qquad \alpha > 0, \ x > 0.
\end{eqnarray*}
In this case it can be shown that the optimal terminal wealth is given by
 \begin{eqnarray*}
V^{\dagger} (T) = - \frac{1}{\alpha} \ln \bigg ( \frac{K (v) Z_0 (T)}{\alpha} \bigg ),
\end{eqnarray*}
and that the integrand process
 $\{ \varphi (t) \mid t \in {\cal T} \}$
is given by
 \begin{eqnarray*}
\varphi (t) & = & \frac{1}{\alpha} \mathbb{E} \bigg [ \bigg ( 1 + \ln Z_0 (T) - \alpha v \exp\bigg\{\int^{T}_{0} r (u) {\rm d} u \bigg\} \\
& & \qquad \quad -\ \mathbb{E} [ {\bar \Lambda} (T) \ln Z_0 (T) ] \bigg ) Z_0 (T) \Gamma (t, T) \,\Big|\, {\cal F} (t) \bigg ].
\end{eqnarray*}
This term depends on the risk preference parameter
 $\alpha$
of the exponential utility. Then, the speculative component in the optimal proportion of wealth invested in the share
 ${\bar \pi}^{\dagger}_s (t)$
may be further decomposed into two parts. The first is given by
 \begin{eqnarray*}
\frac{\sigma^{-1} (t) \varphi (t) Z^{-1}_0 (t) }{1 - \eta_s (t)}.
\end{eqnarray*}
This term depends on the risk preference parameter
 $\alpha$
via
 $\varphi (t)$
and may be called the preference-dependent speculative component. The second part is given by
 \begin{eqnarray*}
\frac{\sigma^{-1} (t) {\widehat \theta} (t) }{1 - \eta_s (t)}.
\end{eqnarray*}
This part depends on the market price of risk
 ${\widehat \theta} (t)$
in the filtered market and may be called the risk-dependent speculative component.
4.2. Case II: Power utility
In this case, the utility function has the following form:
 \begin{eqnarray*}
U (x) = \frac{x^{\gamma}}{\gamma}, \qquad \gamma < 1, \ \gamma \neq 0.
\end{eqnarray*}
Then the optimal terminal wealth is given by:
 \begin{eqnarray*}
V^{\dagger} (T) = (K (v))^{\frac{1}{\gamma - 1}} ( Z_0 (T) )^{\frac{1}{\gamma - 1}},
\end{eqnarray*}
where
 \begin{eqnarray*}
K(v) = \frac{v^{\gamma - 1}}{ ( \mathbb{E} [ ( Z_0 (T) )^{\frac{\gamma}{\gamma - 1}} ] )^{\gamma - 1}}.
\end{eqnarray*}
The integrand process
 $\{ \varphi (t) \mid t \in {\cal T} \}$
is given by
 \begin{eqnarray*}
\varphi (t) = \frac{v \gamma}{1 - \gamma} \frac{ \mathbb{E} [ ( Z_0 (T) )^{\frac{\gamma}{\gamma - 1}} \Gamma (t, T) | {\cal F} (t) ] } { \mathbb{E} [ (Z_0 (T))^{\frac{\gamma}{\gamma - 1} } ] }.
\end{eqnarray*}
Similarly to Case I (i.e. the exponential utility case),
 $\varphi (t)$
depends on the risk preference parameter
 $\gamma$
in the power utility function. Furthermore, the speculative component of the optimal proportion invested in the share
 ${\bar \pi}^{\dagger}_s (t)$
can be decomposed into the preference-dependent speculative part and the risk-dependent speculative part as in Case I.
4.3. Case III: Logarithmic utility
The utility function has the following form:
 \begin{eqnarray*}
U (x) = \ln (x).
\end{eqnarray*}
Again, by some algebra, the optimal terminal wealth is given by
 \begin{eqnarray*}
V^{\dagger} (T) = \frac{1}{K (v) Z_0 (T)},
\end{eqnarray*}
and the integrand process
 $\{ \varphi (t) \mid t \in {\cal T} \}$
is given by
 \begin{eqnarray*}
\varphi (t) = - \mathbb{E} [ ( I^{\prime} (K (v) Z_0 (T)) K (v) Z_0 (T) + I (K (v) Z_0 (T)) ) Z_0 (T) \Gamma (t, T) | {\cal F} (t) ] = 0.
\end{eqnarray*}
Consequently,
 \begin{eqnarray*}
{\bar \pi}^{\dagger} (t) \,:\!= \sigma^{-1} (t) {\widehat \theta} (t) V^{\dagger} (t).
\end{eqnarray*}
Therefore, the compact solution to the optimal asset allocation problem is given by
 \begin{eqnarray*}
\pi^{\dagger}_o (t) = - \frac{ \sigma^{-1} (t) {\widehat \theta} (t) V^{\dagger} (t)}{1 - \eta_s (t)} + \frac{V^{\dagger} (t)}{1 - \eta_s (t)} %,
\end{eqnarray*}
and
 \begin{eqnarray*}
\pi^{\dagger}_s (t) = \frac{ \sigma^{-1} (t) {\widehat \theta} (t) V^{\dagger} (t) } {1 - \eta_s (t)}
- \frac{\eta_s (t) V^{\dagger} (t) }{1 - \eta_s (t)}.
\end{eqnarray*}
Then
 \begin{eqnarray*}
{\bar \pi}^{\dagger}_o (t) = - \frac{ \sigma^{-1} (t) {\widehat \theta} (t)}{1 - \eta_s (t)} + \frac{1}{1 - \eta_s (t)} %,
\end{eqnarray*}
and
 \begin{eqnarray*}
{\bar \pi}^{\dagger}_s (t) = \frac{ \sigma^{-1} (t) {\widehat \theta} (t) } {1 - \eta_s (t)} - \frac{\eta_s (t) }{1 - \eta_s (t)}.
\end{eqnarray*}
Expressing these in terms of the robust filter
 ${\bar {\bf q}} (t)$
in (7),
 \begin{eqnarray*}
{\bar \pi}^{\dagger}_o (t) = - \frac{ \langle \boldsymbol{ \theta}, \boldsymbol{ \Sigma} (t) {\bar {\bf q}} (t) \rangle }{
\sigma (t) (1 - \eta_s (t)) \langle {\bf 1}, \boldsymbol{ \Sigma} (t) {\bar {\bf q}} (t) \rangle } + \frac{1}{1 - \eta_s (t)} %,
\end{eqnarray*}
and
 \begin{eqnarray*}
{\bar \pi}^{\dagger}_s (t) = \frac{ \langle \boldsymbol{ \theta}, \boldsymbol{ \Sigma} (t) {\bar {\bf q}} (t) \rangle }{
\sigma (t) (1 - \eta_s (t)) \langle {\bf 1}, \boldsymbol{ \Sigma} (t) {\bar {\bf q}} (t) \rangle } - \frac{\eta_s (t) }{1 - \eta_s (t)}.
\end{eqnarray*}
In this case, the speculative component has a similar form to the Merton ratio and is given by
 \begin{eqnarray*}
\frac{ \langle \boldsymbol{ \theta}, \boldsymbol{ \Sigma} (t) {\bar {\bf q}} (t) \rangle }{\sigma (t) (1 - \eta_s (t)) \langle {\bf 1}, \boldsymbol{ \Sigma} (t) {\bar {\bf q}} (t) \rangle }.
\end{eqnarray*}
The speculative component only contains the risk-dependent speculative part. This is consistent with the absence of the risk preference parameter in the logarithmic utility function. The hedging component is given by
 \begin{eqnarray*}
- \frac{\eta_s (t)}{1 - \eta_s (t)}.
\end{eqnarray*}
Recall that the generalized elasticity
 $\eta_s (t)$
can be represented in terms of the generalized delta-hedged ratio
 $\psi (t)$
as follows:
 \begin{eqnarray*}
\eta_s (t) = \frac{S (t)}{O (t)} \psi (t).
\end{eqnarray*}
Then the hedging component can be written as
 \begin{eqnarray*}
- \frac{\frac{S (t)}{O (t)} \psi (t)}{1 - \frac{S (t)}{O (t)} \psi (t)}.
\end{eqnarray*}
Note that both the speculative and hedging components depend on the information state
 ${\bf q} (t)$
. When the volatility of the share increases, the speculative component decreases and more money is allocated to the hedging component. The solution to the optimal asset allocation problem here is related to that for the single-regime case with a power utility in Fu et al. [Reference Fu, Wei and Yang13]. The former seems to be more general than the latter since the former takes into account the unobservability of the economic environment.
5. Conclusion
Filtering theory and the martingale approach were used to study optimal asset allocation with derivative securities in a hidden Markovian, regime-switching, model. Two related concepts, namely, the generalized delta-hedged ratio and the generalized elasticity, were introduced to take into account the presence of derivative securities and the information state process in the filtered market. An SPDE for the option price process under the real-world probability measure was derived. This gave a characterization for the relationship between the probability belief of the economic agent on the hidden economic state and the ‘real-world’ expected return on the option. Using the Clark–Ocone formula together with Malliavin derivatives, an optimal solution to the asset allocation problem was characterized for a general utility function. The optimal solution for the general utility function was decomposed into a speculative component and a hedging component. For the cases of an exponential utility and a power utility, the speculative component was further decomposed into a preference-dependent speculative component and a risk-dependent component. A compact solution to the problem was obtained for a logarithmic utility function.
Acknowledgements
The authors would like to thank the referee for insightful comments. Tak Kuen Siu would like to acknowledge the Discovery Grants from the Australian Research Council (ARC), (Project No.: DP1096243; Project No.: DP130103517). Jinxia Zhu would like to acknowledge 2018 BSRG grants from UNSW Business School. Hailiang Yang would like to acknowledge the Research Grants Council of the Hong Kong Special Administrative Region (Project No. HKU 17305018).


