Traditionally joint stock corporations have been seen as indispensable to rapid economic progress because they foster capital pooling, risk sharing, and governance (e.g., Cochran Reference Cochran1977; Chandler Reference Chandler1977), but recent research has shown that when alternative forms were available in history, specifically the private limited liability company (PLLC), then the joint-stock form was adopted much less frequently. Timothy Guinnane et al. (Reference Guinnane, Harris and Lamoreaux2007) document that laws introducing the PLLC first emerged in 1892 in Germany with the Gesellschaft mit beschränkter Haftung (GmbH). Britain authorized PLLCs to be established from 1907 and France's version of the PLLC, the Société à Responsabilité Limitée, was widely adopted following its introduction in 1925. When the United States provided a systematic framework for the organization of PLLCs in the late twentieth century, Guinnane et al. argue that small- and medium-sized business owners were finally liberated from the restrictions associated with the corporate form.
This article studies the adoption and performance of business organizational forms in Japan during the late nineteenth and early twentieth centuries. While adoption has been studied extensively in a number of country contexts, lack of data has precluded performance assessments. This is an important omission because evaluating the performance of enterprises by their organizational form permits much broader conjectures to be made concerning the relationship between the structure of enterprise and economic progress. For example, Thomas Owen (Reference Owen1991) argues that economic growth was constrained in the Russian Empire by especially restrictive corporate laws and bureaucratic regulation, while Timur Kuran (Reference Kuran2005) maintains that an aversion to the corporation in Islamic law held back the development of the Ottoman Empire.
New data were assembled from Japanese governmental reports and consist of a long panel on the organization and performance of enterprise for the 47 prefectures from 1896 to 1939. The dataset is constructed at the level of legal form, by industry, by prefecture, and by year. For the 44-year time period the dataset includes the number of enterprises by type of legal organizational structure, and financial variables including the value of authorized and paid-up capital. During the early 1920s the Division of Statistics of the Ministry of Agriculture and Commerce started to collect additional data on the net profits and losses of joint stock corporations [Kabushiki Kaisha], limited partnerships [Goushi Kaisha], and unlimited partnerships [Goumei Kaisha]. Therefore, between 1922 and 1939 performance outcomes can by analyzed.
The article has five main parts. First, I provide a brief historical background. Second, I document the data construction effort and present descriptive evidence on enterprises by type of legal organization over time, across prefectures and industries. Heavy use of the joint stock form stands out. Joint stock companies accounted for the largest share of all registered enterprises, followed by limited partnerships and unlimited partnerships. The share of enterprises by type remained roughly the same across prefectures. The largest share of joint stock firms existed in transportation, a sector relying heavily on external finance. As would be expected, joint stock firms were considerably larger than limited and unlimited partnerships.
Third, I relate the descriptive evidence to the existing literature to provide potential explanations for why the use of the joint stock form was so dominant. While a range of idiosyncratic factors mattered, main explanations involve the provision of external finance, development phase and industrial structure, and culture and public policy. Specifically, work by Yoshiro Miwa and J. Mark Ramseyer (Reference Miwa and Mark Ramseyer2002) highlights that Japanese businesses relied heavily on equity as opposed to bank debt. As such, external finance considerations would have biased organizational choices towards the joint stock form. So too would the capital intensity demands of modernization (Tang, Reference Tang2011). In terms of industry structure the conglomerate form, or zaibatsu, is inextricably linked with Japanese enterprise history. After about 1910 most zaibatsu began to reorganize from unlimited or limited partnerships to joint stock enterprises under a holding company arrangement. Finally, policy makers chose to make the joint stock form widely accessible, while cultural factors meant joint stock corporations had a particularly high prestige status.
Fourth, the new data are used to consider the economic significance of enterprises as measured by their financial performance. For the period between 1922 and 1939 joint stock corporations accounted for most of aggregate profits and panel regressions show they performed better than unlimited and limited partnerships on a return on equity (ROE) basis. Additional specifications attempt to address the possibility that better performing business owners (in ROE terms) may have chosen to adopt the joint stock form, perhaps to attract more outside capital. While endogeneity concerns cannot be ruled out, linking the descriptive results with existing evidence from the literature helps to isolate potential mechanisms and selection effects.
Fifth, it could be argued that the heavy use of the joint stock form may be unsurprising because an intermediate form of enterprise like the PLLC was unavailable. Therefore, I use additional descriptive data to examine changes in the organization of enterprise following the passage of laws promulgating the Yugen Kaisha, Japan's form of PLLC.Footnote 1 The Yugen Kaisha was instituted under the Private Limited Liability Company Law [Yugen Kaisha Hou] of 1938 and it came into force in 1940. Exploiting the period after Japan introduced the PLLC means that a fuller menu of organizational forms becomes observable.
Following the legal reform the share of joint stock companies remained roughly the same because the PLLC displaced limited and unlimited partnerships. This finding contrasts with Guinnane et al. (Reference Guinnane, Harris and Lamoreaux2007) who show that in Britain and France legislation promulgating PLLCs led to a relative drop in the formation of joint stock corporations. In Germany the cost of incorporation was particularly high and therefore the number of corporations was quite small. The GmbH substituted mainly for ordinary partnerships. Regardless of these differences, in Britain, France, and Germany the PLLC gave owners the flexibility to create structures that balanced tradeoffs associated with issues such as protecting against untimely dissolution and providing concessions to minority shareholders, which negated joint stock ownership. In Japan the tradeoffs between a joint stock and a PLLC form appear to have been much less extreme.
Several factors help to account for the heavy use of the joint stock form for the time period when the PLLC became available. Japan's rapid post-WWII growth created opportunities for joint stock enterprises that were able to access external capital markets (Hoshi and Kashyap Reference Hoshi and Kashyap2004). A growth in stock ownership by banks and the connection of corporations through cross-shareholding keiretsu reinforced the corporate organization. Cultural norms favoring joint stock enterprise persisted, while imperfect regulatory boundaries did little to separate small closely-held enterprises from large dispersed ownership firms. This meant more limited substitution between the PLLC and the joint stock form as the PLLC appealed mostly to Japanese business owners who had previously chosen to organize as limited and unlimited partnerships.
HISTORICAL BACKGROUND
Business enterprise contributed significantly to Japan's remarkable process of modernization. Economic growth from the late nineteenth to the mid-twentieth century represented the product of, among other factors, institutional reform, infrastructure investment, technological development, and the marginalization of the old feudal system of the Tokugawa era (e.g., Mosk Reference Mosk2001; Morck and Nakamura Reference Morck and Nakamura2007; Mitchener and Ohnuki Reference Mitchener and Ohnuki2009; Nicholas Reference Nicholas2011). Although growth was faster during the post-WWII era than in the pre-WWII era (Hayashi and Prescott Reference Hayashi and Prescott2008), the Japanese “economic miracle” of the former years was not independent of the foundations established during the latter years (Kelley and Williamson Reference Kelley and Williamson1974).
In categorizations of countries around the world by their civil and common law origin (e.g., La Porta, Lopez-de-Silanes, and Shleifer Reference La Porta, Lopez-de-Silanes and Shleifer2008) Japan is classified as following the German tradition. This makes some sense up to the mid-twentieth century given that Japan replicated elements of most of the five major German codes, and a major reform in 1911 was based on the German Handelsgesetzbuch, which had replaced the original 1861 legislation relating to companies in that country.Footnote 2 However, the interpretation of codes by judges, rather than relying on precedent as in common-law countries, had very little effect on the actual governance of enterprises.
The multifaceted nature of laws pertaining to enterprises is revealed in a close inspection of the Commercial Code, which established Japan's system of business organization consisting of joint stock corporations, limited partnerships, and unlimited partnerships.Footnote 3 Although the initial 1890 version was developed by a German employed by the Japanese government named Hermann Roesler, a 1911 translation of the 1899 Commercial Code (which replaced an 1893 version) makes implicit references to the use of French Commercial Code. French names are retained to denote the various forms of enterprise even though German-based concepts are used in substantive areas such as defining member liability and liquidation procedures.Footnote 4
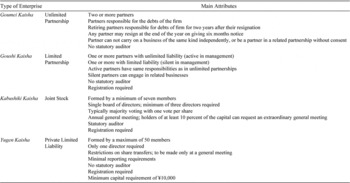
The main attributes of each organizational form are given in Table 1. It is well known that the joint stock form created benefits and costs: it facilitated access to external finance but gave rise to moral hazard through limited liability. The Japanese joint stock form was distinct only in a few minor respects from that used in other countries, including fuller disclosure requirements and an increase in the scope of decisions that needed to be ratified at a general meeting. These efforts were designed to protect minority shareholders (Baum and Takahashi Reference Baum, Takahashi and Röhl2005, p. 376).
The organization of enterprise in this way represented a break from the pre-Meiji era where merchant houses run by prominent families and the guild system dominated. Japanese policy makers promoted joint stock companies according to the belief that they would facilitate large-scale capital intensive enterprise. This was considered to be a crucial factor for catch-up industrialization. As Eiichi Shibusawa (1840–1931) a prominent Meiji reformer stated: “To make the nation truly prosperous, we must enrich the country; to enrich the country, we must make scientific progress and help commerce and industry thrive; to help commerce and industry thrive, we must establish joint-stock corporate organizations” (Shimada Reference Shimada2012, p. 9).
The joint stock form had an important impact on Japanese business organization. Zaibatsu enterprises—large diverse business conglomerates—started as ordinary partnerships but became joint stock corporations. Most took advantage of limited liability for partnerships under the Commercial Code, which mitigated downside risk without requiring family owners to disclosure financial statements. However, public pressures to disclose, along with governance considerations led many to form as joint stock enterprises. As the economy became increasingly militarized during the 1930s, the influence of the traditional family-owned zaibatsu waned, but new zaibatsu rose to preeminence especially in heavy industries geared for the war effort. New zaibatsu like Asano and Nissan exploited the joint stock form, performing more favorably in terms of profitability and sales growth than the old zaibatsu firms such as Mitsui (Frankl Reference Frankl1999).
MAIN DETAILS OF ORGANIZATIONAL FORMS

Notes:
Details compiled from various editions of the Report of the United States Industrial Commission (Washington, D.C.) and editions of the journal International Law Notes: A Quarterly Bulletin of Matters of Interest to International Lawyers. The minimum capital requirement for Yugen Kaisha was changed to ¥100,000 in 1951 and ¥3 million in 1990.
Yet, while much of the existing evidence points to the significance of the joint stock form, lack of data on the universe of enterprises leaves open questions about the relative usage of different organizational forms and especially the comparative performance of enterprise. Notwithstanding zaibatsu enterprises controlled about one-third of Japan's capital stock (Frankl Reference Frankl1999, p. 997) empirical studies relying on these enterprises alone leave two-thirds of the capital stock unexplored. The remainder of the article introduces and analyses new data on all registered enterprises in Japan to address these fundamental questions.
DATA AND DESCRIPTIVE EVIDENCE
New data were collected from Japanese government reports. Established in 1881, the Ministry of Agriculture and Commerce (MAC) collected statistics on agriculture, commerce, and industry. In 1925 when the MAC was reorganized the newly established Ministry of Commerce and Industry collected information on companies from prefectural authorities. Using the Statistical Report of the Ministry of Agriculture and Commerce [Noushoumu Toukei-hyo] and the Ministry of Commerce's Report on Business Companies [Kaisha Toukei-hyo], I constructed a consistent data series on the number of enterprises and capital from 1896 to 1939.
The main dataset is a panel covering 47 prefectures from 1896 to 1939, three legal forms (limited and unlimited partnerships and joint stock companies), and six industries (agriculture, fisheries, commercial, industrial, mining, and transport). Hence, I observe each legal form by industry, by prefecture, and by year. Exploiting an expansion of data collection efforts by prefectures and the government, I added financial statistics for enterprises to the data from 1922 on. From 1896 figures for capital held by shareholders and owners of partnerships plus reserves are reported, and starting in the 1920s prefectural authorities also compiled data on profits and losses, dividends, and debentures. Data on profitability become available from 1922 and are reported both for profitable and loss-making enterprises, which represents a particularly rich source of information. To adjust for prices changes, I convert the financial variables into 1939 prices using the consumer price index (Officer and Williamson Reference Officer and Williamson2013).
Some advantages and disadvantages of the data are worth emphasizing. First, it is important to note that the data cover the universe of registered enterprises, yet the majority of Japanese enterprises were sole proprietorships and traditional Kumiai (analogous to Anglo-Saxon partnerships or German stille Gesellschaften) that did not have to register (they were regulated by Civil Code provisions) and had no separate legal personality. As such, the entrepreneurial foundations of Japanese enterprise formation cannot be fully explored. Second, the financial data are not aggregated by business group and therefore the analysis cannot capture the performance of each zaibatsu. In other words, the panel tracks the performance of the average “representative” registered enterprise by legal form. Third, changes in enterprise form at the firm level are not observed. This precludes estimation by firm fixed effects, thereby ruling out controls for omitted variables related to business owners choosing legal forms for reasons, such as unobservable investment requirements, that were constant over time but variable across enterprises. By using a higher level of aggregation as a unit of analysis, the approach trades off some level of identification in order to achieve universal coverage of registered enterprises.
Main Trends
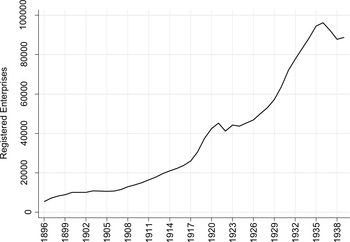
Beginning with the raw data, Figure 1 shows trends in the number of registered enterprises. The kink in the series during the early 1920s is caused by two factors. First, data for the pre-1921 period slightly overstates the number of enterprises and thus the growth rate because these years include enterprises in suspension of business. Data from 1921 onwards do not include suspensions. Second, the Great Earthquake of 1923 caused data for certain areas of Tokyo and Kanagawa prefectures to be destroyed. A fall in the number of enterprises during the late 1930s coincides with the Sino-Japanese War (1937–1945). As Takafusa Nakamura (Reference Nakamura, Nakamura and Odaka2003, p. 55) puts it: “the direct and indirect effects of the war on Japan's economy were profound, undermining the foundations of the national, business and household economies.”
A clear trend to emerge from Figure 1 is the rapid development of business enterprise over time. Approximately 5,000 enterprises were registered in 1896, but by 1939 there were more than 88,000, representing an annual average growth rate of 7 percent. Although Japan was starting from a low base given its early stage of development, and according to metrics like the number of corporations per capita or corporate share capital (at market or book) as a percentage of gross domestic product (GDP), Japan was considerably behind the leading industrial countries (Hannah Reference Hannah2015), the growth rate is systematically pronounced across the Meiji, Taisho, and early Showa eras.
THE NUMBER OF ENTERPRISES 1896–1939

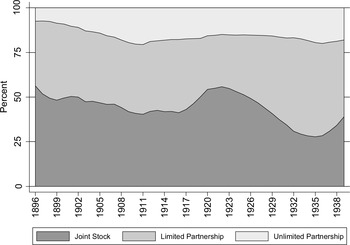
Figure 2 highlights the changing organizational structure of Japanese business over time. For the period as a whole, joint stock companies accounted for the largest share of all enterprises (44 percent), followed by limited partnerships (around 40 percent), and unlimited partnerships (around 16 percent). Over time, the share of joint stock firms reached a peak during the early 1920s before falling to a low point during the mid-1930s and rebounding by the end of the time period. In 1939 joint stock firms accounted for around 40 percent of registered enterprises. At the prefecture-level, these shares remained approximately the same. Kanto and Kinki, and to a lesser extent Chibu (a region in-between Kanto, including large cities like Tokyo and Yokohama, and Kinki, where the cities of Kyoto, Osaka, and Kobe are located), were dominant areas in absolute terms accounting for almost three quarters of enterprises between 1896 and 1939.
SHARE OF ENTERPRISES 1896–1939 BY LEGAL FORM

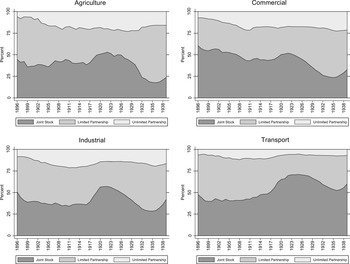
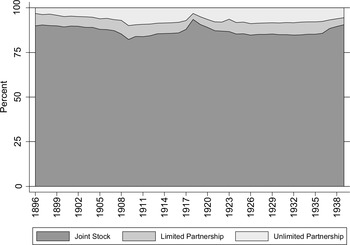
Figure 3 breaks down the data by industry. All the major sectors covered by the data (fisheries and mining are excluded because the number of observations is too small to generate annual shares) exhibit similar approximate time series changes. In terms of levels, the transportation sector stands out with the highest proportion of joint stock firms. According to Figure 4 joint stock companies accounted for around four-fifths of total capital, which remained roughly constant throughout the time period. Calculations using the financial data show that from 1922 to 1939 joint stock firms accounted for 94 percent of aggregate profits. Overall, joint stock enterprise was significant numerically, in terms of capital intensity and profits.
EXPLANATIONS FOR THE ADOPTION OF THE JOINT STOCK FORM
Three broad explanations are particularly useful for understanding the prevalence of the joint stock form. The first is that a joint stock enterprise facilitates access to external finance through the issuance of shares in public equity markets. Despite the development of a well-functioning banking sector during the Meiji era (Mitchener and Ohnuki Reference Mitchener and Ohnuki2009), firms relied heavily on public equity capital rather than bank debt for long-term financing.
SHARE OF ENTERPRISES 1896–1939 BY INDUSTRY

SHARE OF CAPITAL 1896–1939 BY LEGAL FORM

The principal evidence for this explanation derives from research by Miwa and Ramseyer. They reject the Gerschenkron-based argument that bank intermediation was critical to the provision of long-term capital in Japan. Firms sold equity, issued bonds, or funded investment projects through retained earnings, with bank debt being a source of capital mostly for operating expenses. Flow of funds data reveals a mean ratio of bank debt to gross assets of between 2 and 8 percent between 1919 and 1941, whereas firm-level data for cotton spinning, railroad, and electrical utility firms indicate a heavy reliance on stock and bond issues.
A precocious organization of stock exchanges facilitated this form of financing. Japan had two stock exchanges in 1878 (Tokyo and Osaka), as many as 46 by the turn of the century as a result of relaxed regulations, and following a rationalization phase, around 10 for the remainder of the prewar era (Hamao et al. Reference Hamao, Hoshi, Okazaki, Ito and Rose2009, p. 57). These stock exchanges were both numerous and of a high quality. Raghuram Rajan and Luigi Zingales’ (Reference Rajan and Zingales2003, Table 3) figures highlight that Japan had a higher ratio of stock market capitalization to GDP than Germany or the United States for all the prewar benchmark years of 1913, 1929, and 1938. In fact, Japan ranks highest by the Rajan-Zingales metric by some margin for all countries in 1938.
A second reason for the prevalence of the joint stock form relates to Japan's early stage of development and its industry structure. According to Guinnane et al. (Reference Guinnane, Harris and Lamoreaux2007, p. 3) “the corporate form was important for enterprises such as railroads that had to raise enormous sums of capital on the market.” In 1896 four out of the five largest joint stock companies in transport in Japan were railroad concerns and they collectively held ¥85.3 million in assets compared to the five largest joint stock companies in manufacturing (cotton or flax spinning concerns) which held ¥10.9 million in assets (Wray Reference Wray1984, p. 281).Footnote 5 The development of transportation infrastructure, which required state intervention and external financing, played a key role in facilitating urban growth during the process of Japanese economic modernization (Mosk Reference Mosk2001). Furthermore, joint stock appears to have been associated with effective governance in Japan's nascent industries. For example, most enterprises in the cotton industry were joint stock concerns so enterprises could grow and be managed beyond the boundaries of the family (Braguinsky et al. Reference Braguinsky, Ohyama and Okazaki2014).
Even zaibatsu enterprises ultimately became joint stock corporations. Access to external capital was not a dominant reason for the switch since the zaibatsu relied heavily on family finance. Rather public pressures for increased disclosure and changes in governance structures played important roles. Mitsui, a major zaibatsu that can be traced back to the early seventeenth century, expanded from banking into mining, trade, and manufacturing and was the first zaibatsu to alter its organizational form. In 1909 Mitsui transformed its four main constituent enterprises into joint stock companies, which were held by family members using a limited partnership. This partnership became a joint stock corporation in 1937 (Morikawa Reference Morikawa1992, p. 184).
A third reason can be broadly categorized as public policy and culture. Beyond the efforts of the Meiji reformers to promote joint stock organization, legislative changes had an important effect on enterprise legal form. A law in 1905 doubled the taxes on partnerships, and it also imposed taxes on retained earnings in mostly family-owned enterprises to fund the Russo-Japanese War. Joint stock companies were exempt from the tax increases. Furthermore, Mark Fruin (Reference Fruin1992, p. 76) writes: “especially after the 1920 revision in which taxes were levied on dividends and bonuses paid to individuals, family-controlled firms adopted the joint stock form of ownership as a means of reducing taxes.” The joint stock form was ascribed a high level of prestige by Japanese business owners within the menu of enterprise choices, which meant that they were willing to subsume the additional administrative costs and complexities associated with forming a corporation (Matsui Reference Matsui, Nottage, Wolff and Anderson2008, p. 112).
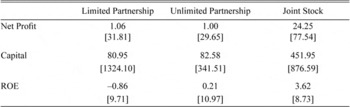
DESCRIPTIVE STATISTICS

Notes:
Monetary values in thousands of real Japanese yen (1939=100). ROE in percent and pertains to the period 1922 to 1939. Standard deviations in square brackets.
Source:
See the text.
RETURN ON EQUITY SPECIFICATIONS AND RESULTS
Measuring Performance
Performance measures are absent from most historical studies of law and enterprise form, but the Japanese data permits such an analysis. ROE makes the most sense as a performance measure in this case given the rich data provided in the governmental reports on the capital held in enterprises and net profits. Although joint stock firms were larger than partnerships and generated more profits, it does not necessarily follow that they were more efficient in the use of capital. Several studies have shown that private firms have higher ROE than public ones (e.g., Faccio et al. Reference Faccio, Marchica and McConnell2012) or that firms experience a decline in profitability once they undergo an initial public offering (e.g., Loughran and Ritter Reference Loughran and Ritter1997). Numerous scholars have identified an inverse correlation between firm size and equity returns (e.g., Banz Reference Banz1981) and equity capitalization is a priced factor in the asset-pricing model of Eugene Fama and Kenneth French (Reference Fama and French1995).
Table 2 reports descriptive statistics on the financial variables of interest and basic difference in means tests. These show that the level of capital and net profits were significantly higher in joint stock firms compared to both limited and unlimited partnerships. Variables inputted directly from the data volumes can be used to construct ROE estimates, which are calculated using the formula below, where f denotes type of organizational form, i industry, p prefecture, and t denotes year. Table 2 shows that joint stock firms generated an average ROE of approximately 3.6 percent per annum between 1922 and 1939 compared to −0.69 percent for limited partnerships and 0.53 percent for unlimited partnerships. These are estimates for the universe of enterprises in Japan. For benchmarking purposes Tetsuji Okazaki (Reference Okazaki2001, p. 255) reports an average ROE of 8.9 percent per annum for 135 major firms active in Japan between 1922 and 1936.
![\[
\begin{array}
{ROE}_{fpit} = [net profit / capital]_{fpit} t = 1922 \ldots 1939.
\end{array}
\](https://static.cambridge.org/binary/version/id/urn:cambridge.org:id:binary:20160921010134415-0988:S0022050715000649:S0022050715000649_eqn1.gif?pub-status=live)
In a multivariate context the data can be used to specify an ROE estimating equation in the following form to examine the relationship between enterprise form and performance:

ROE is the performance measure and the main parameters are α1 and α2 for two dummy variables, which measure ROE for limited partnerships (LP) and unlimited partnerships (UP) relative to the baseline excluded category of joint stock companies. To control for the impact of leverage on returns (i.e., the possibility that higher ROE may be driven by the greater use of debt financing) and differences in size, LEV measures leverage as the average ratio of debenture debt to capital and CAP measures the average capital of enterprises. With variation in ROE for each organizational form by industry, prefecture, and year, γ i , γ p , and γ t represent fixed effects to control for unobservable sector-specific, spatial, or macroeconomic shocks, respectively.
An obvious issue with this econometric approach is selection. Rather than being randomly determined, organizational form is a choice on the part of business owners and assuming a hierarchy of forms, then successful business owners may have simply selected to organize as a joint stock corporation. According to the explanations outlined above for the adoption of the joint stock form, business owners may have chosen this structure to access external finance and achieve higher growth rates, especially in capital intensive industries, or because of development stage and industry structure, or public policy and cultural factors, or a simultaneous mixture of all of these factors. Given the life cycle of firms, it is plausible that limited and unlimited partnerships accounted for the majority of early stage enterprises and would therefore exhibit a greater degree of entrepreneurial “churn” through successes and failures (Haltiwanger Reference Haltiwanger2012). If these categories reflect the main margin of adjustment, the effect would be to depress average ROE for limited and unlimited partnerships relative to the joint stock category.
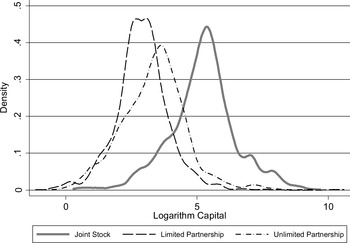
Although ultimately the parameter estimates from equation (2) cannot be interpreted as causal, some progress can be made in addressing these and other potentially confounding issues. As robustness checks, separate regressions are run to test for spatial differences by excluding the main industrial areas of Kanto and Kinki and for major time period differences given that the Japanese economy became even more militarized during the 1930s, and enterprises may have performed differently in a market-based economy with free entry and exit of the entrepreneurial labor supply as opposed to in an increasingly autarkic context. Using a specification with interactions between LP and UP dummies and sector-specific variables, ROE estimates are also provided by type of enterprise organization for each industry relative to the joint stock form. Furthermore, because the data volumes separately record net profits for both profitable and unprofitable enterprises it is possible to analyze the extent to which ROE differences are being driven by successful or unsuccessful business owners; that is, whether better entrepreneurs who generated higher ROE may have selected in to the joint stock form. Finally, following research in the finance literature, (e.g., Asker, Farre-Mensa, and Ljungqvist Reference Asker, Farre-Mensa and Ljungqvist2013), matching methods are used. Figure 5 illustrates large differences by organizational form with respect to the distribution of capital, suggesting that organizational form and performance may simply reflect fundamental variation between different types of businesses. Matching is not a remedy for endogeneity concerns or omitted variable bias, but it can be used to usefully examine ROE by enterprise type within overlapping areas of these capital distributions.
Baseline Estimates and Robustness Checks
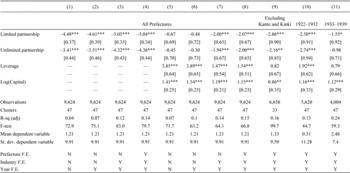
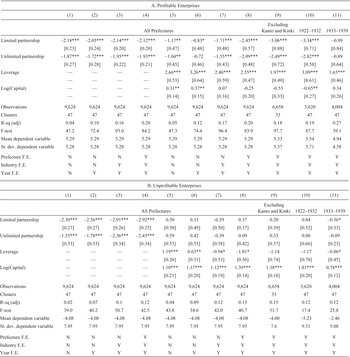
Table 3 reports ordinary least square (OLS) estimates from equation (2). Columns 1 to 4 sequentially add the prefecture, industry, and year fixed effects and columns 5 to 8 follow the same strategy while also including controls for leverage and capital. Column 9 presents the estimates excluding prefectures in the regions of Kanto and Kinki, which represent the largest concentrations of enterprises, and columns 10 and 11 partition the data according to time periods when the Japanese economy was less and more exposed to militarization.Footnote 6 The dependent variable, ROE, is measured in percentage points. Standard errors account for the clustering of observations within prefectures. Given missing observations in the data volumes for some of the variables, the regressions are estimated symmetrically across specifications with 9,624 cells.Footnote 7
THE DISTRIBUTION OF CAPITAL 1922–1939

Estimates in columns 1 to 4 reveal large negative and statistically significant effects on the category dummy variables for both limited and unlimited partnerships. At the legal form, by industry, by prefecture, by year level the ROE of limited partnerships was between 4.5 and 5 percentage points lower than that of joint stock enterprises, the baseline category. The ROE of unlimited partnerships was between 3.4 and 4.4 percentage points lower. Both estimates are large compared to the ROE sample mean of 1.2 percent. The estimates are reasonably stable across columns 1 to 4 with the addition of the year, industry, and prefecture fixed effects.
ROE ESTIMATES

Notes:
Dependent variable is ROE. Limited Partnership and Unlimited Partnership are dummy variables, with the reference category being Joint Stock. Leverage measures the average ratio of debenture debt to capital and Capital measures the average capital of enterprises. A unit of observation is at the level of legal form, by industry, by prefecture, and by year. Standard errors in square brackets are clustered by prefecture: ***p < 0.01, **p < 0.05, *p < 0.1.
Source:
See the text.
In columns 5 and 6 the parameters on the dummy variables become statistically insignificant with the addition of controls for leverage and capital. Leverage enters positively and significantly, implying that enterprises with greater leverage had higher ROE, which may stem from the fact that if business owners can borrow capital at less than the marginal rate it can be earned within the enterprise, then ROE should be mechanically higher. More surprisingly, the coefficient on the logarithm of capital is positive, implying that larger enterprises had higher ROE, all else being equal. This contrasts with the negative relationship between market performance and size found in the finance literature (e.g., Fama and French Reference Fama and French1995). Potential explanations would be larger Japanese enterprises being able to benefit from scale and scope economies (Chandler, Amatori, and Hikino Reference Chandler, Amatori and Hikino1997), or that size correlates with unobserved managerial ability.
While the coefficients on the limited and unlimited partnership dummy variables are statistically insignificant in columns 5 and 6, they become statistically significant in columns 7 and 8 with the introduction of industry and prefecture fixed effects, respectively. These estimates indicate that limited and unlimited partnerships underperformed joint stock enterprises by approximately 2 percentage points. The coefficients on the leverage and capital variables remain economically large and statistically significant. In column 9 the exclusion of prefectures in Kanto and Kinki leads to slightly larger differences in ROE between limited and unlimited partnerships and joint stock enterprises, whereas the effects of leverage and capital on ROE are smaller. Columns 10 and 11 show that the largest performance differences between enterprises are observed in a free market setting between 1922 and 1932, although average ROE (the mean of the dependent variable) was much higher between 1933 and 1939 in an environment where rising government spending and low interest rates may have promoted investment and business expansion. Overall, the baseline results and additional checks indicate that limited and unlimited partnerships underperformed in ROE terms relative to their joint stock counterparts.
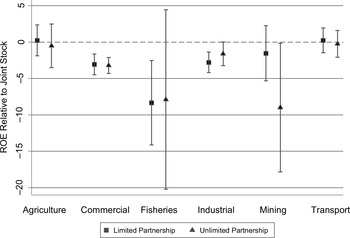
To explore sector specific variation in ROE performance, Figure 6 plots point estimates and 95 percent confidence intervals from specifications where the dummy variables LP and UP are interacted with dummy variables for each sector. Joint stock enterprises act as the baseline category. Most of the sector-specific point estimates are negative, although perhaps surprisingly the confidence intervals overlap with zero in the transport sector where the joint stock form may have been expected to have advantages as a conduit to external finance.Footnote 8 The point estimates for fisheries and mining are negative, but the confidence intervals are large because the number of observations in these industries is somewhat smaller. In the industrial sector the relative ROE estimates for limited and unlimited partnerships are negative and statistically significant at the 5 percent level. The most precise, statistically significant negative ROE effect for limited and unlimited partnerships is estimated in the commercial sector, which includes activities such as banking, insurance, and services. The commercial sector accounts for approximately 53 percent of enterprises in the dataset between 1896 and 1939 and approximately 52 percent of enterprises between 1922 and 1939. As a further robustness check, the specification in column 8, Table 3 was re-estimated without the commercial sector. The parameters on the limited and unlimited partnership dummies are −1.79 (s.e. 0.84) and −1.62 (s.e. 0.86), respectively.
ROE ESTIMATES BY SECTOR

ROE for Profitable and Unprofitable Enterprises and Matching
Tables 4A and 4B decompose the ROE outcome variable into components that can be attributable to profitable and unprofitable enterprises. For each observation cell profits are recorded in the data volumes for successful (i.e., positive net profit) and unsuccessful (i.e., negative net profit) enterprises. Tables 4A and 4B report estimates from regressions where the dependent variable, ROE, is calculated using profits for each group of enterprises separately.
The first four columns of Tables 4A and 4B show that profitable and unprofitable enterprises account for approximately equivalent contributions to the generation of the results in Table 3. For example, the coefficient on the limited partnership dummy in Table 4A, column 1 is −2.18 when only the net profits of profitable enterprises are included in the calculation of the numerator of equation (1) and −2.30 in Table 4B, column 1 when only the net losses of unprofitable enterprises are included. These estimates sum to the coefficient of −4.48 in Table 3 column 1. However, introducing controls for leverage, capital, and fixed effects reveals key differences across the specifications. In columns 5 to 11 of Table 4A the coefficients are mostly large, negative and statistically significant, whereas they are small and almost always fail to clear thresholds for statistical significance in Table 4B. This implies that the differences in ROE by organizational form in Table 3 are being driven largely by the differences present in profitable enterprises. These results would be consistent with superior entrepreneurs selecting joint stock status, or joint stock status facilitating ROE gains. Loss making enterprises are statistically indistinguishable from one another by ROE across the different organizational forms.
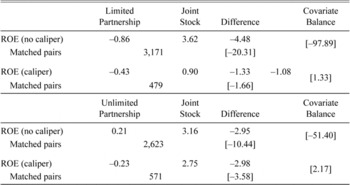
Finally, Table 5 introduces matching estimates. Whereas the baseline OLS estimates assume that the groups of enterprises by organizational form are balanced in their observable characteristics, matching relaxes that particular assumption so that only closely comparable observations determine the calculation of the relative ROE difference.
Using the full set of variables in column 8 of Table 3 a propensity score was used to estimate assignment probabilities into the categories of enterprises by their legal form. The ROE outcome was then estimated by comparing limited partnerships with joint stock corporations and by comparing unlimited partnerships with joint stock corporations. The first row in each set of results provides a nearest-neighbor match where all observations in the data are included to generate the estimates. The second row uses caliper nearest-neighbor matching to select matches within certain tolerance limits of the propensity score. The limits, or calipers, were set at a width of 0.2 times the standard deviation of the propensity scores. The final column reports a test to check the matching estimates statistically balance enterprises by size.
DISAGGREGATED ROE ESTIMATES

Notes:
Dependent variable is ROE where the numerator is restricted to only profitable enterprises. Limited Partnership and Unlimited Partnership are dummy variables, with the reference category being Joint Stock. Leverage measures the average ratio of debenture debt to capital and Capital measures the average capital of enterprises. A unit of observation is at the level of legal form, by industry, by prefecture, and by year. Standard errors in square brackets are clustered by prefecture: ***p < 0.01, **p < 0.05, *p < 0.1.
Source:
See the text.
Dependent variable is ROE where the numerator is restricted to only unprofitable enterprises. Limited Partnership and Unlimited Partnership are dummy variables, with the reference category being Joint Stock. Leverage measures the average ratio of debenture debt to capital and Capital measures the average capital of enterprises. A unit of observation is at the level of legal form, by industry, by prefecture, and by year. Standard errors in square brackets are clustered by prefecture: ***p < 0.01, **p < 0.05, *p < 0.1.
Source:
See the text.
MATCHING RESULTS

Notes:
Matching results use nearest neighbor without replacement and in the relevant rows, a caliper of 0.2 times the standard deviation of the propensity scores. The propensity scores were generated using all the variables in the specification in Table 3, column 8. The covariate balance test is a t-test of the difference in means between the capital of observations in the respective groups. Values in squared brackets are t-statistics.
Source:
See the text.
In the first row of Table 5 it can be seen that the mean difference between limited partnerships and joint stock enterprises is large, with a difference of −4.5 percentage points. However, the covariate balance test rejects the null hypothesis that the two groups of enterprises are closely matched according to their capital. Caliper matching in the second row of Table 5 provides more favorable balancing properties, establishing a mean difference of −1.3 percentage points in the ROE of limited partnerships compared to observationally similar joint stock enterprises. Although caliper matching leads to a substantial drop off in the number of matching pairs, reassuringly the matching estimates in Table 5 of −1.3 to −4.5 percentage points bound the baseline estimate of around −2.0 percentage points in column 8 of Table 3.
The third and fourth rows of Table 5 follow the same approach for comparing the mean ROE of unlimited partnerships with joint stock enterprises. The mean differences are large and negative, as in in column 8 of Table 3, although the covariate balance test fails to reject the null hypothesis of observational overlap in terms of capital. Although a variety of mechanisms can explain ROE variation (e.g., correlations between the size of enterprises, the selection of organizational form and performance, or superior ROE enabling a change in form over the life cycle of businesses), the upshot of the matching results is to add robustness to the baseline finding of a positive relationship between joint stock enterprises and ROE.
INTRODUCTION OF THE YUGEN KAISHA, (JAPAN'S PLLC)
So far the analysis has shown that the joint stock form was heavily used in Japan during the late nineteenth and early twentieth centuries, and that it was associated with superior performance. Yet, both factors could be explained by an intermediate form of organization being unavailable. Some business owners may have been constrained optimizers and have chosen the PLLC over limited and unlimited partnerships, or the joint stock form, had it been available, as it was in other countries such as Britain, Germany, and France. One way of addressing this issue is to examine what happened to organizational choices once the PLLC was introduced.
The Yugen Kaisha, which is often considered to be Japan's version of the PLLC, was brought about by a 1938 reform, which came into effect in 1940. While much of the more general reforms at this time were based on the 1937 German Aktiengesetz, or stock corporation law, the intuition behind the Yugen Kaisha followed that of the German GmbH from 1892, although the precise structure of these respective legal forms differed in fundamental ways. Given the close historical correspondence between Japanese and German laws it is perhaps surprising that policy makers did not introduce the Yugen Kaisha earlier.
On the other hand, to the extent that Japanese policy makers designed the Commercial Code as an “eclectic body of law embodying the best principles of the commercial laws of all other civilized nations” (De Becker Reference De Becker1913, p. 207) it could be argued that the introduction of the Yugen Kaisha almost one-half of a century after it first appeared in Germany was a reflection of the suitability of existing forms. It is possible there was no demand for a structure that in the language of Guinnane et al. (Reference Guinnane, Harris and Lamoreaux2007, p. 2), “combined the advantages of legal personhood and joint stock with a flexible internal organizational structure.” Takashi Shimizu (Reference Shimizu2012) argues, for example, that flexible governance could be achieved by business owners under the existing Goushi Kaisha, and that the principal contribution of the Yugen Kaisha was only to extend the scope of limited liability.
Japanese policy makers had considered a flexible limited liability structure in the original Meiji draft of the Commercial Code. Asagi (Reference Asagi1995) documents that Hermann Roesler included the idea of Sakin Kaisha, which allowed some partners to be unlimited liability partners through agreement among all partners in the articles of association. This idea was not included in the final text. According to Harald Baum and Eiji Takahashi (Reference Baum, Takahashi and Röhl2005, p. 378) the major momentum for legislative change towards the Yugen Kaisha only originated in 1917 and 1918 with two academic studies published by Naojiro Sugiyama, from Tokyo University. Sugiyama pointed out that many countries had invoked laws promulgating PLLCs and the rapid take-up of the new form in those places implied Japanese small firms, which proliferated around the time of World War I, could also benefit from the new organizational form. In 1929, the Tokyo Chamber of Commerce and Industry investigated laws in relation to various forms of enterprises, especially those with limited liability. Drawing on the findings of this investigation and academic studies, in 1931 the Legislative Council of the Ministry of Justice announced that it would “provide through a special law, recognition for a special form of company equivalent to a limited liability company under foreign laws, or a private company under English laws” (Asagi Reference Asagi1995). A bill on the Yugen Kaisha was submitted seven years later to the Imperial Diet, and it was enacted in 1940 along with other laws revising the Commercial Code.
The Yugen Kaisha provided for limited liability (though not as flexibly as the GmbH), was capped by a maximum of 50 shareholding members (the GmbH had no member caps), imposed restrictions on the transfer of shares but required only one director, and limited reporting requirements. Unlike in the case of the GmbH, no voluntary undertaking of additional contractual obligations by means of the articles of association was permissible. Japan did not recognize any deviation from the limits of liability set out in it laws. With respect to membership caps, the Yugen Kaisha was more similar to the 1907 British PLLC. In an effort to exclude very small businesses, a minimum capital requirement was initially set at ¥10,000 (approximately $100,000 in today's U.S. dollars). Yet, the 50 member cap was sufficiently high to permit larger enterprises to exploit the new form.Footnote 9 In effect the Yugen Kaisha law established an intermediary form between the limited and unlimited partnership and the joint stock form.
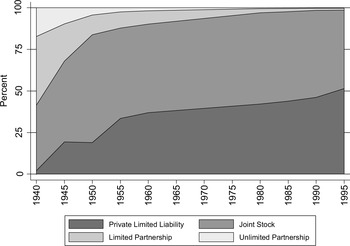
SHARE OF ENTERPRISES 1940–1995 BY LEGAL FORM

Figure 7 presents time series data on the concentration of business forms in Japan from 1940 to 1995. Two striking patterns emerge. First, the adoption of the PLLC was immediate and rapid despite the disruption of World War II. Within two decades the PLLC accounted for 37 percent of all registered enterprises, and by the end of the twentieth century it accounted for more than 50 percent.Footnote 10 A second clear trend to emerge from the data is that the PLLC displaced limited and unlimited partnerships not joint stock enterprises. In this sense, the Japanese experience is much closer to that of Germany, than Britain or France where the PLLC started to substitute for the joint stock form (Guinnane et al. Reference Guinnane, Harris and Lamoreaux2007).
Despite the introduction of the Yugen Kaisha the joint stock form remained in heavy use for several reasons. As in the prewar era, external finance considerations continued to be important, but rather than being advantageous for accessing equity markets, the joint stock form offered benefits for accessing bank debt, which became a considerably more important financing channel in the postwar years (Franks, Mayer, and Miyajima Reference Franks, Mayer and Miyajima2014). Although several zaibatsu were eliminated or restructured as a consequence of the allied occupation, cross-shareholding developed under the new keiretsu, and banks and financial institutions became both creditors and shareholders of the new industrial groups (Shishido Reference Shishido2001, p. 664). Reforms from 1945 to 1952 led to the reconfiguration of corporate power and authority between the shareholders meeting, the board of directors, and corporate auditors as investor protections in joint stock businesses were strengthened; but in the long run regulations protecting shareholders at the expense of business owners were less stringent in Japan than in other countries (Hannah Reference Hannah2014). A culture favoring the joint stock form persisted through the postwar era as it signaled advantages when, for example, engaging in procurement contracting or in developing relationships with banks. Joint stock was a prestigious type of organization more generally despite being associated with higher administrative costs and more stringent public disclosures (Matsui Reference Matsui, Nottage, Wolff and Anderson2008).
CONCLUSION
This article has assembled new data on the organization of enterprise in Japan, with a view to placing the Japanese experience in the context of the broader research agenda initiated by Guinnane et al. (Reference Guinnane, Harris and Lamoreaux2007). Their findings convincingly show that the joint stock corporation was not a superior form of business organization in many advancing industrial nations. When governments offered business owners the opportunity to have a flexible system of organization that was embodied in the PLLC, the take-up was generally rapid, and this process occurred in nations with both Anglo-American and French, or German, legal institutions. As such this body of works casts strong doubts on the alleged domination of both joint stock corporations and country-specific legal origins as being major determinants of economic growth.
Japan appears to be a unique case, which both confirms and differs from some of this established wisdom. On the one hand, it was ostensibly a civil law country in which the joint stock form was probably just as popular as it was in the United States where a common law legal tradition existed. On the other hand, the role of the joint stock corporation was likely more pivotal in the process of Japanese modernization during the late nineteenth and early twentieth centuries than it was in many other countries, including Germany, Britain, and France. It was prevalent over time, across prefectures and sectors and it was superior in terms of ROE performance. Joint stock enterprises accounted for 94 percent of aggregate profits between 1922 and 1939, a striking illustration of this particular organizational form's dominance.
Even when the PLLC was introduced, providing an ex post insight into the potential selection preferences of business owners, the share of enterprises organized under joint stock ownership remained high. The Yugen Kaisha offered an intermediate choice to small- and medium–sized business owners, but the specific Japanese legal and historical context meant there was limited substitution with the joint stock form. Moreover, while the Yugen Kaisha ultimately accounted for more than one-half of all registered enterprises, its relevance for satisfying the needs of both business owners and the government was severely negated in the long run. Progressive revisions to Japanese company law effectively narrowed the legal and organizational gap between the Yugen Kaisha and joint stock ownership. Under reforms in 2005, the Yugen Kaisha was abolished and replaced with the Godo Kaisha, which was modeled on the U.S. limited liability form.