Over the past 200 years, the fundamental logics of organizational structures in the insurance industry have changed substantially. Traditional mutual principles of organizing insurance, which played a prominent role in early insurance in countries like Britain, German, France and Sweden, have undergone structural reforms, while stock forms of organization have expanded in insurance markets (Westall Reference Westall1997; Pearson Reference Pearson2002; Strauss Reference Strauss, Borscheid and Haueter2012; Borscheid Reference Borscheid, Borscheid and Haueter2012; Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012). Stock insurers have expanded considerably in property insurance, while the mutual structures have maintained a strong position on non-property insurance markets, indicating that the competitive advantages of the two organizational forms differ across lines of insurance (Pearson Reference Pearson2002; Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012).
The mechanisms leading to organizational changes in insurance markets have attracted contemporary and historical research examining propositions based foremost on the information asymmetry and principal agent literature (Smith and Stutzer Reference Smith and Stutzer1995; Westall Reference Westall1997; Zanjani Reference Zanjani2007; Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012; Ho, Lai and Lee Reference Ho, Lai and Lee2013). However, empirical research addressing the ownership structure has had problems finding conclusive evidence of the competitive advantage of organizational forms (Westall Reference Westall1997; Zanjani Reference Zanjani2007; Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012). The theoretical implications of organizational forms are also far from conclusive. Principal agency and adverse selection theory suggest that mutual insurers should be associated with less risky activities than stock companies, while arguments from efficient risk-sharing theories imply that mutual insurers should underwrite more risky activities and unknown risk distributions (Doherty and Dionne Reference Doherty and Dionne1993; Smith and Stutzer Reference Smith and Stutzer1995; Birkmaier and Laster Reference Birkmaier and Laster1999; Skogh Reference Skogh1999).
To examine the mechanisms underlying organizational changes on insurance markets, this article addresses the issue of how organizational form is associated with the risk characteristics of insurance companies. In order to examine the variation in risk characteristics of stock and mutual insurance companies, this article focuses on the property insurance industry. This is motivated by the fact that the property insurance market contains a greater variation of risk characteristics and organizational forms than the non-property insurance market. The organizational structure has also changed differently over time. Although stock organizational forms have increased in the long run, the interwar period saw growing market shares for mutual companies in countries such as Sweden and the US (Zanjani Reference Zanjani2007; Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012). In Sweden, the mutual market share was extended across all lines of property insurance (except for vehicle insurance during World War I), in contrast to the preceding and succeeding periods (Enskilda försäkringsanstalter; Bergander Reference Bergander1967; Larsson, Lönnborg and Svärd Reference Larsson, Lönnborg and Svärd2005).
Although previous studies have examined factors underlying underwriting and reinsurance in Swedish property insurance, few studies have taken into account the mix of different lines (fire, marine, vehicle and specialized property insurance). This omission is not trivial since risk taking and spreading risk are key issues in understanding the development of insurance. This article addresses this issue by comparing different lines of insurance. Such a comparison makes it possible to trace how organizational form is related to different risk structures and how risk is spread across lines. In contrast to previous studies on property insurance (Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012), we focus on the volatility of claims experience and not the level of risk. The analysis of volatility helps us to more accurately capture companies' difficulties in predicting risk based on the previous year's business. Claims volatility as a measure of risk is advantageous since the level of risk only captures how large premiums need to be to cover claims.
Our study integrates how substantial changes in the business environment and in risk structures were related to the organizational changes on the property insurance market. From previous studies, we note that the insurance market was affected by short-term changes in demand during the boom and bust that characterized the macro economy in the 1920s and 1930s, and the structural changes in capital formation in the industry and dwelling sectors (Andersson, Eriksson and Lindmark Reference Andersson, Eriksson and Lindmark2010). Also, technological innovation and the diffusion of the combustion engine in vehicles and shipping, together with changes in heating systems in urban housing and electric power for manufacturing production, may have caused changes in the characteristics of risk underwritten by insurance companies (Schön Reference Schön2012). We believe that the analysis of how the structure of a firm's property (ownership structure) and its activities (underwriting risk) are related can be more fully examined during a period in which the business environment changed, as a firm's environment helps identify the appropriateness of an ownership structure.
The study can be motivated in at least three principal regards. Firstly, we believe that this is one of few theoretically grounded and empirically based historical studies that explicitly test the impact of organizational structures on risk taking during the development of insurance markets. Secondly, it may extend the knowledge of how information asymmetry issues affect organizational structure in insurance markets across different lines of business. Thirdly, as the implication of the owner–customer relationship on risk taking has attracted few empirical studies (see MacMinn and Ren Reference Macminn and Ren2011), a study such as ours can provide a wider understanding of how different organizational forms take on and spread risk across lines of insurance. By using a multi-level panel model that compares how risk taking is related to the level of lines (vehicle, fire, marine and specialized property) and the level of companies, this study offers a more robust testing of the mechanisms governing the relationship between risk and organizational form than previous studies.
The remainder of this article is organized as follows. Sections I, II and III outline the growth and structural changes on the Swedish property insurance market from 1913 to 1939. Section IV introduces the theoretical framework, while Section V describes the data, variables and model applied in the study. Section VI presents the empirical results and Section VII concludes.
I
The Swedish economy underwent a rapid transformation during the late nineteenth century. Investment in productive assets such as infrastructure, machinery and buildings in the manufacturing and services industry fostered economic growth from 1913 to 1939 (Andersson and Lindmark Reference Andersson and Lindmark2008). Structural changes and the spatial reallocation of economic activities also put pressure on investing in household buildings in the growing urban areas.
The capital formation process in the nineteenth and early twentieth centuries was closely related to developments in the insurance market. In its capacity to alleviate risk and work as a financial intermediary between the corporate and household sectors, the insurance sector was an integrated part of the growth process (Adams et al. Reference Adams, Andersson, Andersson and Lindmark2009). The life insurance industry was important for securing investments in human capital and accumulating savings for productive investments (Andersson, Eriksson and Lindmark Reference Andersson, Eriksson and Lindmark2010). The property insurance industry played a key role in the mitigation and transfer of risk from investor to third party (Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012). By insuring property, capital assets could supply both a capital service in the manufacturing sector and a collateral service in the financial sector.
From 1913 to 1939, the aggregated growth of the real produced capital stock (buildings, machinery and equipment) equaled the growth of real gross premiums in the property insurance industry. Also, measured in current prices, it is shown that the relationship between insurance premiums and produced capital was fairly similar from 1913 to 1939. However, the aggregated and long-term development may overlook substantial changes in the structure of assets and the relationship to different lines of insurance. To uncover such developments, we have compiled the capital structures and premium incomes by line of insurance.
Figure 1 shows the asset value (in current prices) by type of property from 1913 to 1939. At the beginning of the period, it is shown that the values of dwellings and manufacturing industries are fairly similar, while the values of transport equipment and trade are lower. At the end of the period, the value of dwellings is higher than that of the manufacturing industries. The relative value of ships and trade has also declined, whereas the value of vehicles has increased in relation to other assets.
Asset value by kind of property (trade and ships, vehicles, manufacturing machinery, buildings and supplies, dwellings) in million SEK, current prices in Sweden 1913–39
Source: Appendix.

If the claims experiences and insurance coverage had remained the same throughout the period and the market had been highly competitive, one could argue that changes in the premium structure perfectly reflect changes in asset value. The historical evidence, however, shows that the growth rates in capital and premiums were not fully similar across all lines. In fire insurance, the premium income grew by 3.6 percent, and the asset value of dwellings and manufacturing industry increased by 5.1 percent. In marine insurance (hull and cargo insurance), the premiums grew by 4.3 percent, while the assets and the trade and ships value increased by 4.1 percent. The growth rate in vehicle insurance (covering general liability, automobile and traffic insurance) was 23.6 percent, and the value of vehicles grew by 21.7 percent annually (in current prices). The comparison shows that the relationship between premium and asset value declined in fire insurance (–1.4 percent) and increased in marine (0.2 percent) and vehicle insurance (1.6 percent). Given the aforementioned assumptions regarding the premium and capital relationship, the lower premium growth rate in fire insurance indicates that the level of risk declined, while the level of risk increased in marine and vehicle insurance. However, any such change in the aggregated level of risk overlooks the difficulties for the companies in predicting the risk based on claims experiences. High risk at the micro level provides a more complex issue to manage as high claims volatility requires measures to mitigate changes in expenditure from year to year.
To indicate how risk developed across different lines of insurance, previous studies have frequently used the variance of the loss ratio (Lamm-Tennant and Starks Reference Lamm-tennant and Starks1993). However, as such a measure uses the same weight whenever losses go up and down, the risk of, for example, insolvency is difficult to interpret. The calculation of variance is useful for descriptive purposes, but less attractive for econometric analysis. As such a descriptive measure reduces observations when calculated, it downgrades the robustness of parameter estimation. To overcome the deficits of the previously used variance measure, we apply a measure that seeks to capture the main problem of risk taking, the risk that the incurred losses become too large in relation to the anticipated claims. Since, during the period being studied, property insurance companies could not rely on actuarial science as life insurance companies could, the anticipated risk was based on past experiences of underwriting risk. Accident statistics and detailed risk assessments for each risk underwritten were used to predict future claims (Kalderén Reference Kalderén1938). On the basis of anticipated risk, insurance companies collected premiums to cover for future claims for each risk. To account for the experience-based underwriting practice on the level of line (for each company), we use ex-ante premium income by lines as an indication of anticipated risk. Incurred losses are indicated by ex-post claims at the level of line. Risk taking is measured as the ratio between ex-ante premiums and ex-post claims on each line of insurance normalized for company size (see details in Equation 1, Section V).
Figure 2 gives an overview of developments on risk taking across line and time. The descriptive statistics on mean value and disparity between companies show that risk taking was not equal across lines and over time. The risk taking variable shows that, on average, specialized insurance insured less risk than other lines of property insurance. It is shown that fire insurance and vehicle insurance insured relatively more risk taking than specialized insurance. On average, marine insurance was the riskiest line. However, as the outline of different lines shows below, the companies' risk taking was not the same over time and nor were the underlying factors of risk taking similar across lines.
Risk taking in vehicle, fire, marine and specialized insurance
Source: Enskilda försäkringsanstalter, Sveriges officiella statistik.
The development of risk taking over time shows that the fire insurance market underwent only minor changes. Companies' risk taking went up during the late 1910s and early 1920s, but later went down to pre-war levels on average. Deviations from mean value show that risk taking converged among companies over time. Figure 2 shows that movements in risk taking were part of an incremental process featuring small changes in the years studied.
The companies' risk taking was also related to the occurrence of major fire events (≥SEK100,000). However, the figures on fire events, systematically reported in the Swedish insurance trade journal since the late 1920s (Gjallarhornet, 1913–39), do not indicate a stable trend, but more of a declining level of risk over time on aggregate. In that sense, the fire event figures fit more with the premium/capital relationship reported previously. Most of the losses reported occurred in the manufacturing industry, of which most took place in forest industrial plants. The claims experience (for large fire events) was divided into a 52/137 relationship between mutual and stock insurers respectively. These figures almost perfectly match the overall division of the claims experience (for all fire events) between the two organizational forms, suggesting that the company forms had a fairly similar distribution between their overall and topmost risk objects. Industrial and non-industrial objects were distributed unevenly across the organizational forms. Mutual companies covered 38 percent (or over twice their overall market share) of the non-industrial claims and only 17 percent of the industrial claims.
The finding of large claims and market segmentation shows that agglomerative effects were of significant importance. The agglomerative effect in urban areas implied that dwellings were highly exposed to devastating fire events. Preventive measures at the time seem not to have overcome such agglomerative effects as mutual insurers, despite their specialization in non-industrial objects, experienced claims from the most devastating fires at the same rate as stock companies.
Also, the marine insurance market was segmented by organizational form. Mutual companies provided hull insurance and stock insurers provided insurance for commodities conveyed by ship (Petersson Reference Petersson2011). During the inter-war period, the risk exposure for both mutual and stock marine insurers changed with the diffusion of motor vessels. Sailing vessels, which were predominant up until the late nineteenth century, were declining and the number of vessels propelled by steam or diesel increased rapidly in the post-1913 period. After World War I, the volume (net tons) of sailing vessels was less than 15 percent of all vessels, and at the end of the period only 5 percent of the merchant fleet was sailing vessels. Most of the vessels were propelled by steam although the share of diesel engines was rising. From an almost non-existent share in 1913, vessels with diesel propulsion had a 10 percent share in 1920 and a share close to 40 percent in 1939 (Historisk Statistik, 1960). The new technology of diesel propulsion was perceived as a problem for the marine insurers. As noted by Petersson (Reference Petersson2011), the main difficulty was the lack of experience, causing problems with pricing risk. Marine insurers still perceived motor engines as comparatively safe.
To examine how the introduction of steam and motor vessels changed marine accidents, we have employed the figures on accidents reported annually to the National Board of Trade from 1910 to 1922 (Kommerskollegium 1910 and 1922). To avoid the effects of war, our comparison is based on the years 1912 and 1922. The figures show that accidents at sea were quite common. Accidents affected approximately 20 percent of the total merchant fleet (measured in gross tons) annually. Most accidents were minor (70 percent) and serious accidents were less common (20 percent), while shipwrecks were only a minor part (7 percent). When comparing sailing vessels with motor and steam vessels, it is shown that accidents more frequently affected non-sailing vessels. Of the total sailing tonnage, some 10 percent were affected by accidents in both 1912 and 1922, while 24 percent of the non-sailing vessels were affected by accidents. Accidents by cause shows that natural hazards (e.g. storms) and navigation failure (own or others) were fairly similar for both sailing and motorized vessels. The difference in the number of accidents arises in part because of engine failure, but is mostly explained by other failures (loading failures, fire on board, etc.). The higher risk introduced by the new technologies may be one of the reasons why premiums grew faster than the asset value of the merchant fleet.
Risk taking among marine insurers also seems to have increased during the inter-war period. In the years following World War I, where state-governed war insurance was put in place to cover war risks, average risk taking increased for a couple of years. Companies' risk taking later declined during the crisis in the 1920s. During the recovery phase (1923–6), risk taking increased again and reached a peak in the late 1920s. During the Great Depression, risk taking declined, but went up later in the mid 1930s.
At the micro level, the disparity in risk taking also changed over time. During World War I, some companies seem to have underwritten highly risky trade, while other companies took on less risky trade. After the war, the disparity between companies declined as risk taking became more similar among companies. The same pattern also holds for most of the 1930s with the exception of 1939.
Vehicle insurance, which included general liability, automobile and traffic insurance, was an emerging line of insurance during the inter-war period. Until the late 1920s, the vehicle insurance line was fairly small and not split between general, automobile and traffic insurance in the statistics (Enskilda försäkringsanstalter, 1913–26). Starting in the late 1920s, the vehicle line expanded substantially. Most of the expansion was due to the growing segment of automobile and traffic insurance, which had an 80 percent share of the vehicle line in 1927. To ensure that all car owners were covered by third-party insurance, compulsory traffic insurance was enacted in 1929 (Andersson et al. Reference Andersson, Bennich, Hall and Ottosson1939). After this, the market for traffic insurance expanded rapidly, making traffic insurance larger than both automobile and general insurance in the 1930s.
The booming liability insurance market was largely the outcome of the rapid spread of vehicles. The number of vehicles grew by 18 percent annually between 1913 and 1939, of which the largest segment (70 percent) was private cars, followed by trucks (20 percent), and buses and tractors used for road transport. In the years before World War II, between 10 and 15 percent of all households were car-owners in Sweden (Statistisk årsbok 1939).
Figures on accidents and damage in traffic show that the amount of damage to cars increased during the 1930s mainly due to the rising number of cars. The share of cars damaged in traffic was close to 20 percent on average in 1930. At the end of the 1930s, the share of cars damaged was down to 15 percent (Enskilda försäkringsanstalter, 1936–9). Similarly, figures on traffic accidents reported from the mid 1930s show that the number of accidents per vehicle went down. Although the amount of damage went down, average damage costs went up more, making the incurred costs for the insurance companies somewhat larger over time in relation to the capital stock of vehicles.
Risk taking among vehicle insurance companies was fairly low in the 1910s. In the early 1920s, risk taking shifted upwards for most companies. Through the 1920s and 1930s, risk taking underwent on average only minor changes. In the 1930s, it seems that risk taking went down somewhat at the same time as disparity across companies was reduced.
In comparison with specialized insurance, risk taking on the vehicle insurance market seems fairly similar to the fire insurance market during the 1920s and 1930s. Vehicle insurers were, however, taking on less risk on average than marine insurers (see Figure 2). In turn, companies underwriting small and specialized niche products (specialized insurance) seem to have been taking less risk than companies underwriting liability insurance.
The specialized lines of insurance included an expanding number of insurance products dedicated to windows, horses, hailstorms, jewelry, etc. In 1913, specialized insurance included eight products of which land transport insurance (railways) was the largest. In terms of size, specialized insurance in total never accounted for more than 2 percent of the property market during the period. By the early 1920s, land transport insurance had diversified into three segments and other (non-transport) specialized insurance products had diversified into three new segments. At the end of the period, specialized insurance included 14 different sub-lines.
Risk taking within specialized insurance was lower compared to the specialized property insurance lines for most of the period. In the late 1910s, however, risk taking went up substantially. After a peak in 1919, risk taking went down to pre-war levels in the early 1920s. For most of the 1920s and 1930s, specialized insurance inherited less risk taking than the other lines of property insurance.
II
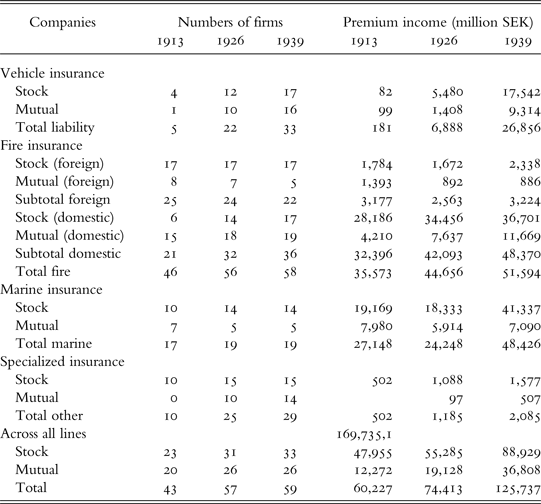
The organizational structure of Swedish property insurance was evolving during the period 1913–39. From the early 1910s, mutual insurers kept a 20 percent share of the property market. After having an expanding market share in the early 1910s, mutual companies lost position during World War I. The mutual market share went up in the 1920s, making up a 26 percent share in the mid 1920s. As the mutual expansion continued, the mutual market share went up to almost 30 percent in the late 1930s. To identify the underlying changes in market share, the underlying company demographics have been examined in total and by line.
The total number of domestic firms on the market increased from 46 in 1913 to 63 in 1939 (aggregated by line). Of the net increase, 31 were entries and 15 were exits. The market was most turbulent during the first half of the period, when roughly 75 percent of the entries and two-thirds of the exits occur. Most of the exiting firms were merged into new firms or were part of acquisitions.
One of the more dynamic lines was vehicle insurance. The market was initially only a minor part of the total property insurance market. In the early 1910s, only five stock companies and one mutual company operated on the market. The only mutual company underwrote railway risk – a risk that was initially a substantial part of the vehicle market (55 percent). With the expansion of vehicles, a growing number of mutual and stock companies entered the market. Although the number of companies was almost the same, stock insurers supplied most of the traffic and automobile insurance products. In 1926, stock companies controlled 80 percent of all premium income. As the market matured, mutual companies expanded their share. In 1939, mutual companies controlled 35 percent of premium incomes in vehicle insurance.
Only stock insurance companies underwrote specialized insurance risk in the early 1910s. As the market expanded, both mutual and stock companies entered. Although more mutual than stock companies entered the market between 1913 and 1926, the growth of premium incomes was substantially larger among stock insurers. As the market consolidated in the 1930s, the mutual market share expanded from 8 to 24 percent between 1926 and 1939.
The structure of the property insurance market by number of firms and real premium income in thousand SEK, 1913 year price level, 1913, 1926 and 1939
The booming marine insurance market during World War I led to the rather turbulent entry and exit of companies. In the aftermath of the 1920s crisis, the market consolidated in favor of the stock form of organization. Mutual companies, which initially had 37 percent of the market, lost position and had a market share close to 25 percent in 1926. The main company demographic events were the exit of two mutuals and the entry of two stock insurers. While the premium income of mutuals was contracting in current prices, stock insurers expanded rapidly from the mid 1920s up to the late 1930s. In 1939, the mutual share was only 15 percent.
The expansion of stock insurers in marine insurance was the outcome of a highly segmented market where mutual companies continued to specialize in hull insurance alone, while stock companies took on all merchandise conveyed by ship as well as an increasing share of hull insurance. One of the reasons for the specialization was that mutual companies were mainly owned by the shipping companies who had less interest in insuring trading companies outside the insurance pool. Being more of an insurance pool of ship-owners, mutual marine insurance could potentially have benefited from lower information asymmetry and thus reduced adverse selection and moral hazard.
The fire insurance market was a highly mature market, growing slowly compared to the other lines of property insurance. Fire insurance was still the dominant line of property insurance from 1913 to 1939. The market became increasingly domestic over time as foreign companies lost most of their market share to domestic insurers. The market was dominated by stock insurers who underwrote 80 percent of the market in 1913. Over time, stock insurers lost position as the mutual companies expanded their market share from 12 to 23 percent between 1913 and 1939.
When comparing their underwriting portfolios, we find that mutual companies were generally less diversified than stock companies. All mutual companies were single-line operators in 1913, while stock companies operated in more than one line on average. Over time, we find that both mutual and stock companies expanded the number of lines in which they were active. The diversity, measured as average number of active lines per company, had increased to 1.6 (mutuals) and 2.3 (stock companies) by 1939. This implies that the growth in the number of firms by line was largely the outcome of a diversification process.
Taken together, the examination of company dynamics across lines shows that stock companies, making up just over half of the companies, underwrote around four-fifths of the property market's premium incomes. There were fewer mutual companies and they held a smaller share of the market. The higher income per company across company forms is largely attributed to the stock companies' greater size. Most companies active in marine insurance were stock companies, while most companies on the fire insurance market were mutuals. Even though an increasing number of stock companies engaged in fire insurance during the period, mutual fire insurance companies steadily increased their share of the fire insurance market.
III
The insurance market underwent substantial institutional changes during the early twentieth century (Enskilda försäkringsanstalter). The Insurance Act in 1903 introduced more stringent licensing and solvency monitoring by the Swedish insurance industry regulator – the National Private Insurance Inspectorate – during the period of our analysis (Lindmark, Andersson and Adams Reference Lindmark, Andersson and Adams2006). The Insurance Act of 1903 required government approval of actuarial foundations, strict solvency requirements, disclosure of information, and continuous public solvency monitoring by the insurance inspectorate agency. The institutional framework put in place remained almost entirely unchanged until the Insurance Act of 1948 (Hägg and Göran Reference Hägg and Göran1998). The institutional framework had forced the industry to become homogeneous in those areas where regulation constrained its discretion until the establishment of the new regulatory regime in 1948. Still, mutual and stock companies targeted market segments with different growth potentials, as the changes in market shares indicate.
Business practices on the insurance market were also affected by the voluntary institutional arrangement. One strategy for improving the transfer of risk and standardizing the underwriting of risk was the formation of the Swedish Fire Tariff Organization and the Marine Tariff Organization in the late nineteenth century (Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012; Petersson Reference Petersson2011). The fire organization included both Swedish and foreign joint-stock companies and also, during our period of investigation, a few large mutual organizations. Affiliated companies could more easily purchase reinsurance, as common tariffs meant that information asymmetries between primary insurers and reinsurers could be more efficiently addressed. During the period of study, the collaboration between fire insurers deepened. In 1913 and 1922, the companies agreed on expanded collaboration regarding statistics, and in 1927 a group of companies formed a bureau of fire-damage statistics. As actuarial innovation rendered the tariff system increasingly complex, by the end of the period around 400 tariff decisions were being made each month by the tariff organization. In 1937, the tariff organization was reorganized to have its own executive board (Holmgren Reference Holmgren1943, pp. 6–10). The cooperation in marine insurance also deepened, with its tariff organization adopting formal ties to enforce majority voting and the ability to impose fines on member companies from 1918 (Petersson Reference Petersson2011, pp. 128–30). Both these organizations were part of the practical self-regulation of the Swedish insurance market. While central regulation such as stringent licensing and solvency monitoring had been in place since the Insurance Act of 1903, no major legal regulatory change occurred until 1948 (Hägg and Göran Reference Hägg and Göran1998).
One key feature of the collaboration associated with the tariff agreement is the bias towards stock forms of organization. As a tariff agreement is a cartel, it conflicts with mutual principles because the cartel places a wedge between company and buyer. For mutual companies, the sharing of tariff standards did not apply. An additional difference is that reinsurance, which was highly associated with the tariff organizations, became less attainable for mutual insurance. Given less access to reinsurance, the risk-spreading strategies would arguably have differed from stock insurers. To more fully examine the mechanisms underlying the organizational structure and risk characteristics in property insurance, the next section outlines the competing models of underwriting risk.
IV
Previous research on risk assessment strategies and organizational forms draws heavily on principal agency and information asymmetry literature. It has been recognized that mutual insurance firms accept fairly well-known and homogeneous risk types for which they are able to control information asymmetry problems (i.e. adverse selection) (Smith and Stutzer Reference Smith and Stutzer1990, Reference Smith and Stutzer1995). Due to such characteristics, mutual insurers are expected to be strong in local niche sectors of the domestic insurance market such as property fire insurance (Andersson, Eriksson and Lindmark Reference Andersson, Eriksson and Lindmark2010). Such small mutuals have ‘club-like’ characteristics and, as such, have advantages in managing moral hazard by reducing the likelihood of fraudulent or excessive claims. One reason for such behavior is that the mutual insurance pool is obligated to act responsibly once insurance has been taken out, in order to avoid unnecessary depletion of accumulated reserves. Pressure from members in the pool, and possibly also the threat of negative social effects of immoral or fraudulent behavior, will tend to bind the interests together and reduce the risk of moral hazard problems (Smith and Stutzer Reference Smith and Stutzer1990, Reference Smith and Stutzer1995). One downside, however, is that mutual pools may run into problems when the ability to use social proximity reduces with growing size, as shown by Guinnane and Streb in their study of German health insurance (Guinnane and Streb Reference Guinnane and Streb2011). Drawing on this reasoning, it can be hypothesized that the competitive advantages of mutual insurance come from insuring homogeneous risks, and that mutuals maintain a stronger position on small or local niche markets.
Large mutual fire insurers could not benefit from the competitive advantages of close socio-economic and geographical proximity that a small local mutual ensured. An alternative strategy for binding interest together might have been to pool financial capital. By accumulating financial capital in large reserves, large mutual companies could bind interest more tightly among policyholders (Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012). Such a strategy might have enabled national mutual insurers to reward the ‘loyalty’ of their policyholders by enabling them to participate in underwriting profits through annual and terminal policy bonuses and/or by cross-subsidizing premium rates with investment income. These financial attributes of the national mutual insurance structure allowed these companies to increase their share of domestic market premiums and diversify assumed risks through national expansion, and thus compete successfully with large stock insurance companies. Therefore, we hypothesize that mutual organizations used larger reserves (low leverage) and less reinsurance in underwriting risk.
Competitive advantages of stock insurers may also arise for a number of reasons. Mayers and Smith (Reference Mayers and Smith1990) expect that the stock form of organization is advantageous in markets characterized by more heterogeneous and diversified risk structures as managers are granted more discretion when selecting e.g. price level, reinsurance, and business mix. This argument find support in empirical studies such as that by Abdul Kader et al. (Reference Abdul kader, Adams, Andersson and Lindmark2010), where it is shown that reinsurance was higher among stock insurers and that the reinsurers were an important factor behind the market expansion of stock insurers. Stock companies may also have become more profitable given that incentive structures for managers were guided by the interest of maximizing yield and dividends to owners. Similarly, the more effective corporate control that owners in stock companies may have in relation to customer-owners in mutual companies may provide an advantage, as highlighted by Cummins and Danzon (Reference Cummins and Danzon1997). Given that stock companies are guided by different incentives and mechanisms, we expect stock insurers to take on more heterogeneous and mixed structures of risk. Predicting risk may, however, become more difficult in such a setting, making the deviations between anticipated risk and loss incurred relatively larger compared to more homogeneous risks.
Stock companies may also underwrite higher risk because of adverse selection problems. Given that adverse selection exists, Laux and Muermann (Reference Laux and Muermann2010) argue that stock companies are expected to suffer more as customers may prefer to transfer the risk to external owners, rather than share the risk with other policyholders alone. Therefore, stock companies may take on higher risk because of the free-rider behavior of policyholders in lines with high aggregated risk.
Conversely, Doherty and Dionne (Reference Doherty and Dionne1993) and Doherty (Reference Doherty1991) argue that mutual companies are more efficient in underwriting high-risk segments. Drawing on the difference in efficiency of risk sharing between participatory and non-participatory policies, they argue that mutuals have an advantage when the risk is not easily diversifiable. Therefore, mutuals have an advantage in combining policy and equity claims into a single package. As the customers are also the owners, risk sharing is more efficient than prepaid risk transfer given that the risk is not (easily) diversifiable. Based on this line of reasoning, Dionne and Doherty (Reference Dionne, Doherty and Dionne1992) suggest that since the mutual organizational form is a more efficient risk-sharing arrangement, mutual companies should also underwrite in more high-risk lines of insurance than stock companies. Such a line of reasoning could explain empirical findings of mutual predominance in highly specialized lines such as fishing vessel insurance and crop insurance (MacMinn and Ren Reference Macminn and Ren2011). Stock companies will, in turn, be more competitive on lines where the risk is more predictable and where access to external (owner) capital is greater (Mayers and Smith Reference Mayers and Smith1986). Investors in the insurance market are expected to invest in lines where risk is more predictable, making the small specialized lines of less predictable risks less attractive for investors. Mutual companies may, therefore, be seen as the outcome of a situation where risk is difficult to diversify and access to external capital is difficult or very expensive.
V
Our data set covers 1913–39 and comprises an unbalanced panel of 2,361 observations on lines/years distributed over vehicle (529 observations), fire (802 observations), marine (477 observations) and specialized insurances (555 observations). Data on firm level includes 1,456 firms/year observations. All financial and economic data for the 112 companies active during the period of analysis were obtained from the Swedish Official Statistics Series for Private Insurance (Enskilda försäkringsanstalter, 1913–39). This source publishes key annual financial statistics (e.g. by-line-of-business premiums written, losses incurred, reinsurance premiums ceded, investment earnings, and so on) for all entities with insurance operations in Sweden.
From the data set, a number of key variables have been constructed to examine the hypothesis. Since the variables we use in the present study are measured on a ratio basis, our data set is given at current prices. Yearly notations per company have been merged with data on each company's activities in four lines of insurance. In accordance with accounting practices, the lines of insurance are treated as different activities but as sub-divisions within each company. While central financial assets, like loans, are posted on company level, variables such as income and risk-distribution are posted for each line. To combine the two levels, company-level data are weighted yearly using each company's premium incomes from their active lines of insurance. The weight (w) is created using the share of the company's premium incomes from each line (Pl) divided by the company's premium incomes from all its active lines (Pc) [Pl/Pc].
The dependent variable, risk taking, is measured as the ratio between ex-ante premiums (P) and ex-post claims (C) on every line (l) of insurance. To control for differences in company size, we use a normalized measure following Davis et al. (Reference Davis, Haltiwanger and Schuh1996) (according to Equation 1) to which we have added a two-year running average of ex-ante premiums (Equation 2):
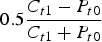 $$0.5{{C}_{t1}-{P}_{t0} \over {C}_{t1}+{P}_{t0}}$$
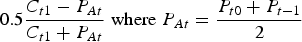 $$0.5{C_{t1}- {P}_{At}\over {C}_{t1} + P_{At}} \; {\rm where}\; P_{At} = {P_{t0} + P_{t-1} \over 2}$$
The relationship between premiums and claims is measured in absolute and relative change.
The intuition of the risk measurement is that a larger value indicates more risk taking (claims exceed previous year's premiums). The measurement will take a value <0 when premiums are higher than claims, and a value >0 when claims are higher than premiums. The lower the value, the less is the risk and vice versa.
Given the aforementioned reasoning on competing models of underwriting risk, the independent variable's key factor is organizational form. The organizational form is indicated by a dummy variable where 1 denotes stock companies and 0 mutual companies. To control for other company-specific attributes that may impact on risk taking, we have employed a number of control variables.
The first control variable is underwriting profitability. Underwriting profitability is measured by the normalizing profit margin at the level of line (premiums minus claims and overhead expenses normalized by premiums). When profits are high, costs in relation to income are kept low.
Leverage is measured by dividing claims by assets. This alternative leverage ratio (leverage is more frequently measured as net premiums to reserves, see e.g. Adams et al. Reference Adams, Andersson, Lindmark and Veprauskaite2012) shows to what extent claims are backed by assets. A high ratio may be seen as a disciplining factor as managers need to ensure sufficiently large cash-flow to meet payments to fixed claimants (Jensen Reference Jensen1986). Such an advantage of high leverage seems, however, less obvious, as it can restrict the company from expanding in order to avoid insolvency risk (Cummins and Danzon Reference Cummins and Danzon1997). In this study, we anticipate a higher leverage of stock companies and a lower leverage of mutual companies.
According to Abdul Kader et al. (Reference Abdul kader, Adams, Andersson and Lindmark2010), company size is indicated by total assets. The variable is transformed to log scale in order to avoid the confounding impact of possible extreme values. Grøn (Reference Grøn1994) argues that size may indicate possible positive scale and scope effect in the underwriting of risk, making large insurers more effective. In Abdul Kader et al. (Reference Abdul kader, Adams, Andersson and Lindmark2010), reinsurance is measured as the relationship between reinsurance expenditures and gross premium income. By ceding part of the risk to reinsurers, the primary insurers can reduce both underwriting and insolvency risk. Reinsurance may also be seen as a means of smoothing income and expenditure flows, as highlighted in contemporary guidance to insurance business (Kalderén Reference Kalderén1938).
According to Adams et al. (Reference Adams, Andersson, Lindmark and Veprauskaite2012), we measure liquidity as cash holdings to total liabilities. Low liquidity can be seen as a higher risk of insolvency, especially if a company with low liquidity underwrites highly volatile risk portfolios. Therefore, companies with low liquidity are expected to either underwrite less volatile risk portfolios or cede a larger part of their business to reinsurers.
Investment earnings are measured as the ratio between capital income and invested assets (assets net of equity). Andersson et al. (Reference Andersson, Lindmark, Adams and Upreti2013) show that mutual insurers were more successful in generating investment returns than stock insurers. They also show that mutuals on average received a larger capital to premium income because of larger returns and larger reserves (to premium income) than stock insurers, thus potentially making it possible to substitute underwriting profitability with capital income, as suggested by Smith (Reference Smith1989).
The bank loans variable is calculated as the ratio of bank loans (L) to annual premium income. Bank loans provide insight into the extent to which loans were used to finance the expansion of business. Bank loans could be also used as a means of compensating large-scale fluctuation in expenditure. Given such a mechanism, we expect a higher level of short-term bank loans in companies with highly volatile risk portfolios.
An alternative measure of compensating for large-scale fluctuation in expenditure is the use of ex-post premiums. To indicate such behavior, an ex-post premium dummy is applied. The dummy variable takes the value of 1 if underwriting profitability is negative and 0 otherwise. We apply a dummy variable for organizational form where stock companies = 1 and, for descriptive purposes, diversity denotes the number of lines the company operates. Dummies are also created to account for the lines of insurance in line1, line2 and line3.
To seek determinants of risk across lines of insurance nested within insurance companies of different organizational forms, we employ a multilevel mixed-effect panel data model. The multilevel approach is useful because the character of our data is explicitly hierarchical since we know risk varies across lines of insurance and organizational form. It separates the effect of the independent variables on the repeated measurements of risk from the environmental context in which variations in risk may arise because of being measured in a specific line or in a company of a specific type. We envisage a hierarchy where observations depend on insurance line and insurance line, in turn, depends on companies in the random part of our model. The fixed part will include the independent variables theoretically motivated above.
The multilevel approach is also motivated by the way companies kept their portfolios from different lines of insurance separate. The variables of risk, underwriting profitability, claims experience, reinsurance and ex-post premiums are line-level variables to both us and the accountants at the time. Determined by the way the insurance companies ran their lines as integrated divisions of the company, other variables, such as bank loans, are inherently company-specific. Separate loans were not taken out by divisions dedicated to a particular line of insurance, but by the company as a whole. Company-level variables are diversity, bank loans, investment earnings, liquidity, firm size and leverage. Yearly notations per company have been merged with data on each company's activities in the four lines of insurance. To combine the two levels, company-level data are weighted yearly using each company's mix of premium incomes from their active lines of insurance. Data on different lines of insurance have also been aggregated to company level, so that all our scale variables are available on both company level and insurance line level.
Weighting the company line data avoids duplication of company-level values such as company size, which would otherwise appear in full power three times for each year in companies active in three lines. Weighting spreads the volume of the company line variables onto the data set, enabling regressions that are not skewed by duplicated company-level variables. On the other hand, the mix of line-level data with weighted company line data creates a tension in the data set that can be illustrated by the construction of our leverage variable. Leverage on line level is generated as the line's claims divided by the total weighted assets. Assets, being a company-level variable, are thus weighted using the line-level premium income. The tension arises as the premium to claims ratio on this line might be divergent from that of other lines which would skew the leverage of the part of the company that is active in that line of insurance.
Considering the pros and cons of weighting company line variables, we conclude that some kind of weighting is necessary for an analysis on the line level. We judge the tension in mixing the weighted variables with the indigenous line-level variables to be negligible for the outcome of the regression. As for choosing premium income share as the weight, the per-line variables for claims, premium incomes and reinsurance all have an almost perfect, highly significant correlation with each other over the entire data set. The use of premium income seems theoretically valid, as it indicates the market share of each company's activity in a given line of insurance.
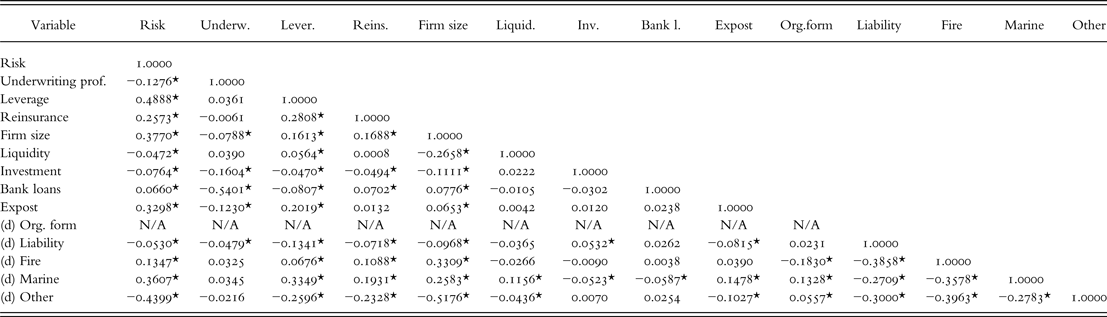
Correlation matrix of line-level data
*significant at the 5% level.
Source: Enskilda försäkringsanstalter, Sveriges officiella statistik.
Organizational form is non-applicable to the correlation matrix of line level-data, since the sample is unbalanced and organizational form cannot fluctuate between lines for any given company for one year. On aggregated company level, however, organizational form is significantly correlated with all other variables except investment earnings. Separate relationships between the variables for stock and mutual companies confirm our hypothesis that stock companies generally used more reinsurance (0.501 to 0.424 on line level) and that they had higher leverage and thus lower reserves (0.287 to 0.170 on company level) – both t-tested significant at the 0.1 percent level.
VI
To analyze the impact of organizational form on risk taking across different lines of insurance, we apply a multilevel (mixed) model approach. When running the basic model (Equation 1), the average observation by unit (line nested by company) is 17 and the maximum is 26. One observation is omitted due to the lag technique applied. In addition to the basic model, an alternative specification is applied to control for the sensitivity of using a one-year lag approach. Based on Equation 2 (see Section V), the alternative two-year lag approach assumes that anticipated risk is proxied by an average of the past two years' premium incomes.
While the alternative approach (Equation 2) controls for late payments and dodges the effect of sudden loss in premium income in year t-1, it should be pointed out that premium incomes include all income for year t0, not only income from newly underwritten risk. We believe that the premium income of year t0 only contains the necessary expectation of a company's expected claims for year t1, but will use Equation 2 to evaluate this assumption.
When running both the basic and alternative specifications, we find that the mixed multilevel model is justified as the LR-test to control for the strength of the random effect levels significantly rejects the NULL-hypothesis of the absence of random effect. In fact, a high share of the variation of the risk measure is explained by clustering by line and company. At 19 and 31 percent respectively for company and line, intraclass correlation is consistent with the previous findings in this study of risk as varying across both lines of insurance and organizational form. These intraclass correlations are high, and leave only half of the effect of risk to be explained by the relationship of the individual observations to company financial characteristics.
The alternative risk measure (according to Equation 2), with a running mean of ex-ante premiums to measure risk, is used to control the accuracy of the assumption in Equation 1 that premiums in year t0 contain the necessary indication of a company's expectations of claims in year t1. As we increase the number of past years of the running mean of premium, little substantial change appears in the fixed-effect part of the model. On the random side, the explanatory power increases until a seven-year running mean as the risk measure gains similarity within clusters.
To capture any interaction between financial characteristics and organizational form, a series of interaction variables based on stock companies is included. The interactive effect captures how stock companies deviate from their mutual counterparts. Thereby, the interaction term may help to explain how the unique company characteristics of stock companies impact on risk taking. As we have identified a negative impact of stock form of organization on risk taking in the multivariate analysis, but higher risk taking by stock companies in the descriptive analysis, the interaction effect may be telling. The dummy variable for organizational form captures the overall impact of organizational form as such, while the interaction variables indicate stock company-specific coefficients for that characteristic which may be picked up alongside the overall effect of organizational form or respective company characteristics' variables.
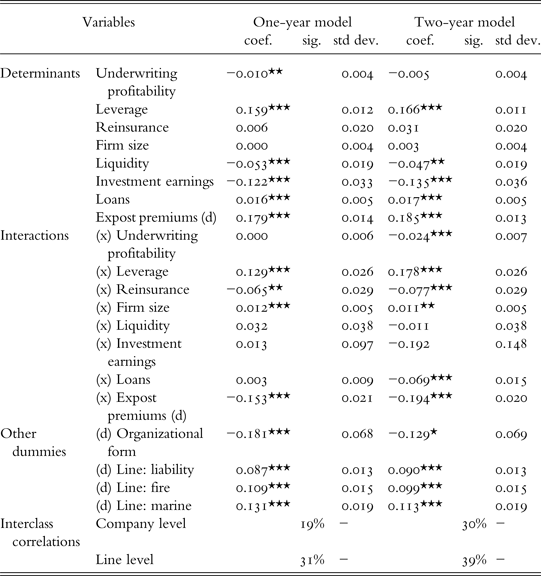
Multivariate results
Note: Variables are statistically significant at the 5% (*), 1% (**) and 0.1% (***) level.
Source: Enskilda försäkringsanstalter, Sveriges officiella statistik, 1913–39.
The results show that mutual organizational form (mutuals coded as 0) has on average a negative impact on risk taking, suggesting that the accumulated effect across all lines is that stock companies managed to reduce risk more efficiently. Although stock companies had a higher risk exposition, as indicated by the descriptive statistics, the risk is significantly downplayed when controlling for factors other than organizational form.
Underwriting profitability has a negative and significant association with risk which could imply that more profitable companies are less exposed to the risk. An alternative interpretation would be that excessive claims downplay profitability.
On average, highly leveraged companies (low reserves to business underwriting) take on more risk, suggesting that small reserves indicate high risk taking. Although one would expect that reinsurance would also indicate risk taking, we cannot find any significant impact of reinsurance. Nor has company size a significant impact on risk taking.
Liquidity has a significant negative relationship with risk taking, indicating that companies with more cash holdings are less associated with risk. One reason for such a relationship could be that excessive claims empty cash reserves. Risk taking is also negatively associated with investment earnings which could imply that companies making high investment returns tend to take less risk in their underwriting business. Companies with large bank loans are associated with more risk on average. One interpretation could be that companies mitigate the short-term impact of excessive claims (high risk) by taking up loans. For the full model, we also find that excessive claims induce a strategy to increase premiums ex-post to mitigate the financial constraints, as indicated by the significant and positive impact of the ex-post variable.
The multivariate results also confirm that risk taking was not similar across lines of business. Underwriting in the marine insurance business implied taking on higher risk compared to fire, vehicle and specialized property insurance. This is expected considering the distribution of size and variation of the hazardous risk of objects in these lines compared to vehicle insurance, where both the size of individual objects and their hazardous risk were more homogeneous.
The interactive result shows that stock companies used reinsurance more efficiently. Reinsurance had a negative impact on risk taking, suggesting that reinsurance had a disciplining effect and/or that reinsurance helped to underwrite more business, which helped the companies use the law of large numbers. Leverage in stock companies had a stronger positive association with risk taking, which would suggest that stock companies' leverage positions were more affected by excessive claims than mutual companies. Company size is positively associated with risk, showing that large stock companies took on larger risks than their mutual counterparts. Given that stock companies were larger and more leveraged, this may also help to explain why the organization dummy variable is downplayed when controlling for such effects. In addition, we also find that the strategy of using higher ex-post premiums to cover excessive claims is negative for the interaction term, but positive for the full model, showing that mutual companies employed ex-post premiums because of excessive claims while stock companies did not.
VII
In this article, we have examined the relationship between risk distribution and organizational form on the Swedish property insurance market from 1913 to 1939. The article has tested the hypothesis that the mutual organizational form had a competitive advantage in underwriting homogeneous or normally distributed risk pools, while stock companies were more likely to underwrite skewed risk distributions. Our empirical analysis shows that companies' risk taking, measured as the relationship of ex-ante premiums to ex-post claims, was generally lower among mutual companies than stock companies. Our use of a multilevel mixed model to capture the explanatory strength of risk variation in insurance lines and on company level seems adequate. It reveals, apart from significant financial characteristics, that the line and company in which risk is observed explain approximately half of its variation. Such complexity demands both a historic context and an analysis that considers the insurers' diverse activities in multiple lines to accurately write the history of risk distribution and its relationship to organizational form in the Swedish case.
The period studied is one of changing risk structures in both existing and emerging markets, notably in vehicle insurance. Mutual and stock companies competed in all lines of insurance. In doing so, they focused on different market segments and/or used different financial adaptations to accommodate risk. The division into lines has shown a greater complexity. However, in general, stock companies preferred reinsurance and company diversity, while mutuals targeted more homogeneous markets using methods such as high leverage and post-premiums. In this study, we have shown that these financial adaptations are linked, through the risk levels they used to insure, to the very company characteristics of mutual and stock company forms, and we have also shown how these forms varied across lines of insurance.
Appendix