




No CrossRef data available.
EMPIRICAL LIKELIHOOD FOR GARCH MODELS
Published online by Cambridge University Press: 15 March 2006
Abstract
This paper develops an empirical likelihood approach for regular generalized autoregressive conditional heteroskedasticity (GARCH) models and GARCH models with unit roots. For regular GARCH models, it is shown that the log empirical likelihood ratio statistic asymptotically follows a χ2 distribution. For GARCH models with unit roots, two versions of the empirical likelihood methods, the least squares score and the maximum likelihood score functions, are considered. For both cases, the limiting distributions of the log empirical likelihood ratio statistics are established. These two statistics can be used to test for unit roots under the GARCH framework. Finite-sample performances are assessed through simulations for GARCH models with unit roots.This research was supported in part by Hong Kong Research grants Council Grants CUHK4043/02P and HKUST6273/03H. The authors thank two referees and the Co-Editor, Bruce Hansen, for insightful and helpful comments about the relationship between QMLE and MELE, which led to substantial improvement of the presentation. Computational assistance from Jerry Wong and Chun-Yip Yau is also gratefully acknowledged.
Information
- Type
- Research Article
- Information
- Copyright
- © 2006 Cambridge University Press
1. INTRODUCTION
For independent and identically distributed (i.i.d.) random variables y1,…,yn, the distribution F of yi is usually estimated by the empirical distribution function

subject to the constraints

. This empirical distribution is maximized at pi = 1/n, i = 1,…,n. Owen (1988, 1990) defines the empirical likelihood ratio as

where pi = dF(yi) = P(Y = yi). If the distribution function F is characterized by an unknown parameter λ, then the probabilities pi should be subject to some restrictions on the parameter λ. For example, when F is characterized by the mean μ, then pi needs to satisfy the first-order restriction

. More generally, if λ satisfies a k-dimensional vector equation g(xi,λ) = 0, then the first-order restriction on pi is

For this restriction, the (profile) empirical likelihood ratio is given by

For a given λ, a unique maximum exists if zero lies inside the convex hull of the points g(xi,λ), i = 1,…,n. The maximum of R(λ) can be found via a simple Lagrange multiplier argument. Let

where a and b are Lagrange multipliers. Taking derivatives with respect to pi and using the restriction (1.1) and

, one obtains

As shown in Qin and Lawless (1994), if the k × k matrix

is positive definite, by the inverse function theorem there exists a continuous differentiable function b(λ) of λ such that

The (profile) log empirical likelihood function can be defined as

Its minimizer

is called the maximum empirical likelihood estimator (MELE). In practice, one is mainly interested in the value of the MELE

evaluated at the corresponding empirical likelihood ratio statistic defined by

This statistic can be used to test for the hypothesis H0 : λ = λ0. Owen (1988) demonstrates that the empirical likelihood approach provides an accurate confidence region for the parameter in finite-sample cases.
When g(x,λ) = x − μ and under some mild conditions, Owen (1988, 1990) proves that WE(μ0) converges in distribution to χp2 as n → ∞, where p is the dimension of μ. Owen (1991) and Kolaczyk (1994) extend this methodology to general regression problems including linear, generalized linear, and projection pursuit models, Qin and Lawless (1994) to general independent unbiased estimating functions, and more recently Chuang and Chan (2002) to unstable autoregressive models studied in Chan and Wei (1988).
As pointed out in Owen (1990), the empirical likelihood approach plays a similar role to the bootstrap method. On the other hand, it is also well known that bootstrap methods work less efficiently for serially correlated data than for independent data. It is therefore interesting to explore whether the empirical likelihood approach provides another feasible means to supplement the bootstrap methodology to conduct statistical inference for time series data.
The main goal of this paper is to study the effect of the empirical methodology for unit root models with generalized autoregressive conditional heteroskedasticity (GARCH) errors. It is well known that unit root testing has played an important role in econometrics during the last two decades. Although one can apply the Dickey–Fuller tests for unit root models with GARCH errors (see Pantula, 1989), by accounting for the heterogeneity presented in the GARCH component, more powerful unit root tests based on the quasi-maximum likelihood estimator (QMLE) can be constructed (see Ling and Li, 1998, 2003; Seo, 1999). Simulation studies based on quasi-maximum likelihood estimation can be found in Seo (1999) and Ling, Li, and McAleer (2003). Given these findings, it is interesting to examine unit root tests based on the empirical method (see, e.g., Wright, 1999).
This paper proceeds as follows. Section 2 develops the empirical likelihood for GARCH models and gives its asymptotic properties. Section 3 studies the empirical likelihood for the unit root with GARCH models. The asymptotic properties of the MELEs are obtained, and the unit root test statistics using the empirical likelihood are proposed. Section 4 reports simulation results, and Section 5 concludes. Proofs of the results are given in the Appendix.
Throughout the paper, the following notation will be used: o(1) (op(1)) denotes a term (a random variable) that converges to zero (in probability); O(1) (Op(1)) denotes a term (a random variable) that is bounded (in probability); ∥·∥ denotes the Euclidean norm; and

denotes convergence in distribution as the sample size n tends to infinity.
2. EMPIRICAL LIKELIHOOD FOR GARCH MODELS
Consider the GARCH model defined by the equation

where ηt are i.i.d. random variables with mean zero and variance 1. Let λ = (ω,α1,α2,…,αr,β1, …,βs)′ and let the parameter space Θ be a compact subset of Rr+s+1. Let λ = λ0 ∈ Θ be the true parameter. Assume that λ0 is an interior point and for each λ ∈ Θ, it satisfies the following conditions.
Assumption 2.1.

, and

have no common roots.
Given the observations εn,…,ε1 and the initial value ε0 = {εt : t ≤ 0}, the log-likelihood function (modulus of a constant) can be written as

where ht(λ) is a function of εt and λ is the vector of parameters defined in (2.1). Because ηt may not be normally distributed, strictly speaking, the function (2.2) is the quasi-likelihood function and its maximizer is the QMLE. The score function and the information matrix are, respectively,

Let Dt(λ) = ∂lt(λ)/∂λ and Pt(λ) = ∂2lt(λ)/∂λ∂λ′. The QMLE is the solution of the score function

. Using this score function Dt(λ), the (profile) log empirical likelihood function can be constructed as follows:

where b(λ) is the Lagrange multiplier, that is, a solution to the equation

The global minimizer

of (2.3) is the QMLE and

. Define the empirical likelihood ratio statistic for testing H0 : λ = λ0 as

We have the following result.
THEOREM 2.1. If Assumption 2.1 holds and Eηt4 < ∞, then

under H0.
Remark 2.1. If one is only interested in testing for a subset of parameters, one can construct the empirical likelihood ratio statistic along the lines of Theorem 1 in Kitamura (1997). See Kitamura (1997) and Kitamura, Tripathi, and Ahn (2004) for a proof of consistency of the global minimizer of the log empirical likelihood function.
3. UNIT ROOT WITH GARCH MODELS
Consider the following unit root with GARCH(1,1) model:


where ηt are i.i.d. random variables with mean zero and variance 1. Let δ = (ω,α,β)′ and let the parameter space Θ be a compact subset of R3 and δ = δ0 ∈ Θ be the true parameter. Assume that δ0 is an interior point in Θ and for each δ ∈ Θ, it satisfies the following conditions.
Assumption 3.1. ω,α,β > 0 and α + β < 1.
The results of this section can be extended to a higher order GARCH(r,s) model by means of the results in Ling and Li (1998). It is also straightforward to extend the results of this section to the nearly unit root case as in Chan and Wei (1987) and Chuang and Chan (2002).
In general, the autoregressive parameter φ can be estimated by two methods: least squares estimator (LSE) and QMLE. When the LSE is used, the score function is given by

As in Section 1, this equation gives the form of the empirical likelihood function as

where b(φ) is the Lagrange multiplier, which is a solution to the equation

The minimizer

of (3.2) is the LSE of φ0 = 1. The empirical likelihood ratio statistic for testing H0 : φ0 = 1 is

The following theorem gives the limiting distribution of WE(φ0).
THEOREM 3.1. If Assumption 3.1 holds, then

as n → ∞, where B(τ) is a standard Brownian motion.
Consider now the empirical likelihood ratio statistic based on the quasi-likelihood score. The quasi-likelihood function conditional on the initial value y0 = 0 can be written as

where λ = (φ,δ) and εt(λ) = yt − φyt−1 is a function of yt and λ. Then

Let Dt(λ) = ∂lt(λ)/∂λ and Pt(λ) = ∂2lt(λ)/∂λ∂λ′. Using this score function as in Section 1, the empirical likelihood function can be constructed as

where b(λ) is the Lagrange multiplier that is a solution to the equation

The minimizer

of (3.3) is the QMLE of λ0, the true parameter of λ. The empirical likelihood ratio statistic for testing H0 : λ0 = (1,δ0′)′ is

THEOREM 3.2. If Assumption 3.1 holds and E|ηt|4+ι < ∞ for some ι > 0, then

as n → ∞, where Ω and κ are defined as in Lemma A.2 with r = s = 1 and the two components in the limiting distribution are independent. Herein, (ω1(τ),ω2(τ)) is a bivariate Brownian motion with covariance

where

and

.
If we are interested in testing the unit root model (3.1), we have to find the constrained empirical likelihood minφ=1 LE(λ). The empirical likelihood test for testing φ = 1 is defined as

Let LE(δ) = LE(λ)|λ=(1,δ) and its minimizer be denoted by

. Here, the number of estimating equations is four, whereas that of unknown parameters is three. Thus,

is no longer the same as the QMLE of δ0 in the finite sample. The following lemma gives the existence of

.
LEMMA 3.1. If Assumption 3.1 holds and E|ηt|4+ι < ∞ for some ι > 0, then there exists a point

in the interior of the ball

for some

such that

with probability approaching 1 and

.
Because

is always zero, we only need to find

numerically. The following corollary gives the limiting distributions of the

.
COROLLARY 3.1. Under the assumptions of Lemma 3.1, it follows that

as n → ∞, where ρ2 = 1/(σ2K) ∈ (0,1), σ2 = Eht, ξ ∼ N(0,1), and B(τ) is a standard Brownian motion that is independent of ξ.
Remark 3.1. F = K when κ = 2. The limiting distributions in Corollary 3.1 are the same as those given in Seo (1999) and Ling and Li (2003). Some of the critical values can be found in Ling et al. (2003).
4. SIMULATIONS
Finite-sample performances of the unit root tests based on the QMLE and the MELE are examined via Monte Carlo experiments in this section.
The model is given in (3.1) with ηt ∼ N(0,1) and the parameters (ω,α,β) assume the same values given in Table 1. Furthermore, the parameter φ takes the values φ = 1.0,0.99,0.95, and 0.9. The sample size is 200, and 1,000 replications are conducted in all cases. Let

denote the square of the t-test based on the QMLE given in Ling and Li (1998), that is,

, which has the same asymptotic distribution as

in Corollary 3.1. The critical values of

are computed by 20,000 replications of the integral of standard Brownian motion appearing on the right-hand side of Corollary 3.1, which is approximated by a discrete random walk model using normal errors. From Table 1, we see that the sizes of both tests are almost identical and are very close to the nominal level 0.05. This is similar to the results reported by Chuang and Chan (2002), who compare the unit root tests based on the empirical likelihood and the LSE methods for the autoregressive (AR) model with i.i.d errors. The powers of

are smaller than those of

, however. One possible explanation is that the calculation of the MELE of δ0 is not as efficient as the QMLE in finite samples. We need to solve seven highly nonlinear equations to obtain the minimum of LE(δ) in

when evaluating the MELE.
Powers of lower tail unit root tests at 5% level for AR(1)-GARCH(1,1) models based on empirical critical values with standard normal errors: n = 200 and 1,000 replications

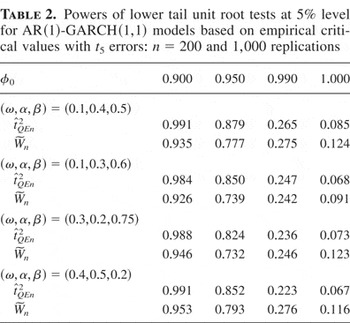
In Table 2, we repeat the simulations with the distribution of ηt being replaced by t5 in Table 1. It is now observed that the sizes of both tests are distorted, with the MELE test

suffering more seriously. As in the normal error case, the powers of

are lower than those of

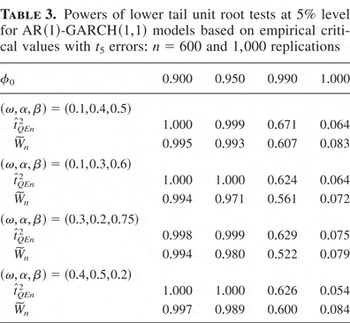
, except for φ = 0.99. When the sample size is increased to 600 in Table 3, the sizes of both tests become much better, and powers have also been increased. Differences between the powers of two tests become smaller and for φ = 0.99, the power of

becomes lower than

. Because φ = 0.99 is so close to the unit root case, the power of

is affected by its overrejection when the sample size n is 200, but this overrejection becomes less serious when n is increased to 600.
Powers of lower tail unit root tests at 5% level for AR(1)-GARCH(1,1) models based on empirical critical values with t5 errors: n = 200 and 1,000 replications

Powers of lower tail unit root tests at 5% level for AR(1)-GARCH(1,1) models based on empirical critical values with t5 errors: n = 600 and 1,000 replications

In general, the unit root test based the MELE does not perform better than that based on the QMLE in finite samples. Although the simulation results are somewhat disappointing, if it were not for the asymptotic results established in Theorem 3.2, it would not be possible to conduct the comparison between the empirical likelihood and MLE methods, so we would never know how they perform relative to each other. The knowledge gained by conducting this study is valuable. In the i.i.d. case, Kitamura (2001) showed that the empirical likelihood ratio test is no less powerful than any regular test as the sample size goes to infinity. Our finding only reveals finite-sample situations, which cannot be considered evidence contradictory to his findings. It remains, however, a challenging theoretical problem to derive a similar conclusion as in Kitamura (2001) for the MELE in the unit root case.
5. CONCLUDING REMARKS
This paper develops the empirical likelihood approach for GARCH models and GARCH models with unit roots. For GARCH models, it is shown that the log empirical likelihood ratio statistic asymptotically follows a χ2 distribution. For GARCH models with unit roots, the empirical likelihood method based on the least squares score and the maximum likelihood score functions is investigated. In both cases, the limiting distributions of the log empirical likelihood ratio statistics are established and the unit root tests based on the MELEs are constructed. Numerical simulations are conducted to assess the finite performance.
APPENDIX: Proofs
For ease of reference, Lemma A.2 of Ling (2006) is repeated as follows. In the lemma, εt and ht(λ) are defined as in Section 2. Proof of this statement can be found in Ling (2006).
Lemma A.2 of Ling (2006). If Assumption 2.1 holds, then there exist a neighborhood Θ0 of λ0, a constant C > 0, and a constant ρ ∈ (0,1) such that for any constant ι1 > 0, it follows that

The proof of Theorem 2.1 follows a similar idea as in Owen (1990) and Qin and Lawless (1994). We first present two lemmas.
LEMMA A.1 If Assumption 2.1 holds and Eηt4 < ∞, then

where i,j,k = 1,…,r + s + 1 and Θ0 is some neighborhood of λ0.
Proof. By Lemma A.2 of Ling (2006), we have

where

for some constants ρ ∈ (0,1) and C > 0 and for any ι1 > 0. By the two inequalities, it is easy to show that (a) and (b) hold. Using the same method as in Lemma A.2 of Ling (2006), it follows that

from which part (c) follows. █
LEMMA A.2. If Assumption 2.1 holds and Eηt4 < ∞, then

where op(1) terms hold uniformly in λ ∈ V0n = {λ : ∥λ − λ∥ ≤ n−0.5M} for each constant M > 0, Ω = E{[∂ht(λ)/∂λ][∂ht(λ)/∂λ′]/2ht2(λ)]}|λ=λ0 and κ = Eηt4 − 1.
Proof. By part (b) of the preceding lemma, E(supΘ0∥Pt(λ)∥0.5)2 < ∞ for some neighborhood Θ0 of λ0. Furthermore, because {supΘ0∥Pt(λ)∥} is strictly stationary, it follows that

Here, we use the fact that, if {Xn} is an identically distributed sequence with EXt2 < ∞, then max1≤t≤n|Xt| = op(n−0.5); see, for example, Chung (1968, p. 93). Thus,

Part (a) follows.
Now consider part (b). By part (a) of the preceding lemma, E∥Dt(λ0)∥2 < ∞. Similar to part (a), we have

By the previous two equations,

Part (b) follows.
For part (c), let ε > 0 be given.

as n → ∞, by means of part (b) of the preceding lemma and the dominated convergence theorem. By the ergodic theorem,

By the previous two equations, (c) holds.
Finally, by Taylor's expansion, and parts (a)–(c) of this lemma, when λ ∈ V0n, it follows that

where the op(1) term holds uniformly in V0n and λ* lies between λ0 and λ. By the ergodic theorem,

By the previous two equations, part (d) follows. █
Proof of Theorem 2.1. Denote

Let b = ρθ with ∥θ∥ = 1. Observe that

where

. By the central limit theorem,

. Furthermore, by Lemma A.2(c), we have

uniformly in λ ∈ V0n where V0n is defined in Lemma A.2. By Lemma A.2(d), θ′Sn(λ)θ ≥ κa/2 + op(1) uniformly in λ ∈ V0n, where a is the smallest eigenvalue of Ω. By virtue of equations (A.2) and (A.3) and this fact, we have

uniformly in λ ∈ V0n. Furthermore, by part (b) of our Lemma A.2, we have

uniformly in λ ∈ V0n. Let γt = b′Dt(λ), where b is the solution of equation Q1n(λ,b) = 0. By part (b) of our Lemma A.2,

uniformly in λ ∈ V0n. Let

. Taking the derivative with respect to λi (the ith element of λ), we have

By virtue of the previous equation, Lemma A.1(c), and our Lemma A.2(a) and (c), it follows that

where γt is defined as in (A.4). Taking the derivative with respect to b,

Furthermore, by Lemma A.2(c), we have

Note that op(1) in (A.5) and (A.6) holds uniformly in V0n. Similarly, we can show that

where op(1) holds uniformly in V0n. By virtue of this fact and equations (A.5) and (A.6), it follows that

where op(1) holds uniformly in V0n.
By Lemma A.2(d), it follows that

uniformly in λ ∈ V0n. Thus,

Because

is the QMLE, by Theorem 2.2 in Francq and Zakoïan (2004) (see also Lee and Hansen, 1994), we have that
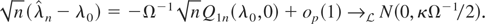
Using Taylor's expansion at

, (A.7), and the preceding two equations, we have

as n → ∞, where the last step follows in view of (A.8). This completes the proof of Theorem 2.1. █
The proof of Theorem 3.1 is similar to Theorem 3.2. Thus, we only present the proof of Theorem 3.2. We first need two preliminary lemmas.
LEMMA A.3. If Assumption 3.1 holds and Eηt4 < ∞, then it follows that

where Nn = diag{n−0.5,I3} and F and K are defined in Theorem 3.2.
Proof. Parts (a) and (b) follow from Lemmas 4.7 and 4.8 in Ling and Li (2002) and Theorem 2.2 in Ling et al. (2003). The proof of part (c) is similar to that of Lemma 4.7 in Ling and Li (2003) and Theorem 2.2 in Ling et al. (2003), and hence the details are omitted. █
LEMMA A.4. If Assumption 3.1 holds and E|ηt|4+ι < ∞ for some ι > 0, then it follows that

where op(1) holds uniformly in

for each constant M > 0 and some constant

.
Proof. By Lemma 4.2 of Ling and Li (2003) and the continuous mapping theorem, it follows that max1≤t≤n|yt| = Op(n1/2). Thus,

where Op(n−0.5) holds uniformly in V1n and in t = 1,…,n. Using a similar method as for Lemma A.6(ii) in Ling (2006), we can show that

where op(1) holds uniformly in V1n and in t = 1,…,n, and ht is defined as in (2.1) with r = s = 1 and λ = δ0. Because E|ηt|4+ι < ∞, there is a small

such that

as ι0 is zero or small enough. Hence,

Because |εt−k(λ)|ht−1/2(λ) = O(β−k/2) as k ≥ 1, and max1≤t≤n|yt| = Op(n1/2), we have


where Op(·) holds uniformly in λ ∈ V1n.

Note that ht(λ) ≥ ω0 /2 as λ ∈ V1n and n is large enough. By equations (A.10)–(A.14),

as

is small enough. Using the identity x/(a + x) ≤ xι0 /2 for any ι0 > 0 as a,x > 0, we have

for any ι0 > 0 and a constant 0 < ρ < 1, where

. Similarly, it can be easily seen that

In view of equations (A.10)–(A.12) and the previous three equations, it follows that

for some small

. Similarly, it follows that

Using this equation with (A.15) and (A.16), part (a) follows.
For part (b), because

, by (A.12), it follows that

Furthermore, it is straightforward to show that

By means of (A.17) and this fact, we have

for a sufficiently small

. Using Taylor's expansion and part (a) of this lemma, part (b) is established.
For part (c), using (A.10)–(A.12) and the same arguments used in Theorem C of Ling and Li (2003), it can be shown that

Part (c) follows. Finally, using parts (a)–(c) of this lemma and Lemma A.3(b), we can show that (d) holds. This completes the proof. █
Proof of Theorem 3.2. Using the idea in Chuang and Chan (2002), let

. Furthermore, let

with ∥θ∥ = 1. Denote

Similar to proving equation (A.2), it can be shown that

where

. By Lemmas A.3(a) and (b) and Lemma A.4(c), we have

uniformly in λ ∈ V1n defined in Lemma A.4. By Lemmas A.3(c) and A.4(d),

for a positive random variable a, as λ ∈ V1n. Thus, using equations (A.19) and (A.20), we have

Furthermore, by Lemma A.4(b), it is seen that

uniformly in λ ∈ V1n. Let

, where

is the solution of

. Then

uniformly in λ ∈ V1n.
Let

. Following the same procedure as in the proof of Theorem 2.1,

uniformly in λ ∈ V1n.
In view of this fact, Lemma A.3(c), and Lemma A.4(d), it follows that

uniformly in λ ∈ V1n. By Lemma A.3(a) and (b) and Lemma A.4(c), we have

Because

is the QMLE of λ0, by Theorem 3.2 in Ling, Li, and McAleer (2003), we have

Using a Taylor's expansion at

, the previous two equations, and Lemma 6.3 with the same method as for Theorem 2.1, we can show that

as n → ∞, where the last two steps follow from Lemma A.3. This completes the proof. █
Proof of Lemma 3.1. Using the idea in Chuang and Chan (2002), let

. Furthermore, let

with ∥θ∥ = 1. Denote

Similar to proving equation (A.2), it can be shown that
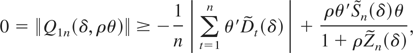
where

. Let

, where

is the first element of

. Denote

. By Lemma A.3(a) and (b) and Lemma A.4(c), we have

uniformly in λ ∈ V1n. By Lemmas A.3(c) and A.4(d),

for a positive random variable a, uniformly in λ ∈ V1n. Thus, using equations (A.23) and (A.24), we have

Furthermore, by Lemma A.4(b), it is seen that

uniformly in δ ∈ V1n. Let

, where

is the solution of

. Then

uniformly in δ ∈ V1n.

uniformly in δ ∈ V1n. By Lemma A.3(a),

. Furthermore, by Lemma A.4(c),
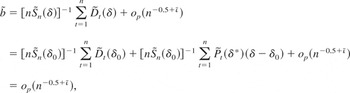
uniformly in δ ∈ V1n. By Taylor's expansion,

where, for some finite B > 0,

as n → ∞. Thus, by Lemmas A.3(c) and A.4(d), it follows that

uniformly in δ ∈ V1n. Denote

, where ∥u∥ = 1. By means of equations (A.25)–(A.28) and Lemmas A.3(b) and (c) and A.4(c) and (d), we have

uniformly in u, which happens with probability at least 1 − ε for any given ε > 0, where c = δmin/κ and δmin is the smallest eigenvalue of Ω. Let

be the solution of

. By (A.23) and Lemma A.4(b) and (d), it is not difficult to see that

Similar to (A.29), we can show that

Because LE(δ) is continuous in δ, by (A.29) and (A.31), LE(δ) achieves its minimum value in the interior of Vn so that the minimizer

satisfies ∂LE(δ)/∂δ = 0. Finally, because

, the proof is complete. █
Proof of Corollary 3.1. Let

, where

is defined as in (A.22). Then

if and only if

where

is defined as in (A.22) and

is defined as in (A.24) .
Following the same method as for Theorem 2.1 and using Lemmas A.3 and A.4, we can show that

uniformly in δ ∈ Vn, where

is the (1,1)th element of

defined following (A.23). Using Taylor's expansion, we have


Let

, where

are the first element of

, respectively. By (A.32) and (A.33), it follows that

Furthermore, by (A.30) and Lemma A.3, we have

Using a Taylor's expansion at

and the previous equations, we can show that

By the expansion in (A.21) and (A.34), it follows that

Let B1(τ) = ω1(τ)/σ and B2(τ) = −σ−1(σ2K − 1)−1/2ω1(τ) + σ(σ2K − 1)−1/2ω2(τ), where σ2 = Eht. Then B1(τ) and B2(τ) are two independent standard Brownian motions. Denote the limiting distribution in (A.35) by ζ2. As shown in Ling and Li (1998), we obtain that

The second term of this equation can be simplified as

, where ξ is a standard normal random variable that is independent of

(see Phillips, 1989). Then

where

. Furthermore, by (A.35), we have

This completes the proof of Corollary 3.1. █
References
REFERENCES
Chan, N.H. &
C.Z. Wei
(1987)
Asymptotic inference for nearly nonstationary AR(1)
processes.
Annals of Statistics
15,
1050–1062.CrossRefGoogle Scholar
Chan, N.H. &
C.Z. Wei
(1988)
Limiting distributions of least squares estimates of unstable
autoregressive processes.
Annals of Statistics
16,
367–401.CrossRefGoogle Scholar
Chuang, C.S. &
N.H. Chan
(2002)
Empirical likelihood for autoregressive models with applications to
unstable time series.
Statistica Sinica
12,
387–407.Google Scholar
Chung, K.L.
(1968)
A Course in Probability Theory.
Academic Press.
Francq, C. &
J.M. Zakoïan
(2004)
Maximum likelihood estimation of pure GARCH and ARMA-GARCH
processes.
Bernoulli
10,
605–637.CrossRefGoogle Scholar
Kitamura, Y.
(1997)
Empirical likelihood methods with weakly dependent processes.
Annals of Statistics
25,
2084–2102.CrossRefGoogle Scholar
Kitamura, Y.
(2001)
Asymptotic optimality of empirical likelihood for testing moment
restrictions.
Econometrica
69,
1661–1672.CrossRefGoogle Scholar
Kitamura, Y.,
G. Tripathi, &
H. Ahn
(2004)
Empirical likelihood-based inference in conditional moment
restriction models.
Econometrica
72,
1667–1714.CrossRefGoogle Scholar
Kolaczyk, E.D.
(1994)
Empirical likelihood for generalized linear models.
Statistica Sinica
4,
199–218.Google Scholar
Lee, S.-W. &
B.E. Hansen
(1994)
Asymptotic theory for GARCH(1,1) quasi-maximum likelihood
estimator.
Econometric Theory
10,
29–52.CrossRefGoogle Scholar
Ling, S.
(2006)
Self-weighted and local quasi-maximum likelihood estimators for
ARMA-GARCH /IGARCH models.
Journal of Econometrics,
submitted.Google Scholar
Ling, S. &
W.K. Li
(1998)
Limiting distributions of maximum likelihood estimators for unstable
autoregressive moving-average time series with general autoregressive
heteroskedastic errors.
Annals of Statistics
26,
84–125.Google Scholar
Ling, S. &
W.K. Li
(2003)
Asymptotic inference for unit root with GARCH(1,1) errors.
Econometric Theory
19,
541–564.CrossRefGoogle Scholar
Ling, S.,
W.K. Li, &
M. McAleer
(2003)
Estimation and testing for unit root processes with GARCH (1,1)
errors: Theory and Monte Carlo study.
Econometric Reviews
22,
179–202.CrossRefGoogle Scholar
Owen, A.
(1988)
Empirical likelihood ratio confidence intervals for a single
functional.
Biometrika
75,
237–249.CrossRefGoogle Scholar
Owen, A.
(1990)
Empirical likelihood ratio confidence regions.
Annals of Statistics
18,
90–120.CrossRefGoogle Scholar
Owen, A.
(1991)
Empirical likelihood for linear models.
Annals of Statistics
19,
1725–1747.CrossRefGoogle Scholar
Qin, J. &
J. Lawless
(1994)
Empirical likelihood and general estimating equations.
Annals of Statistics
22,
300–325.CrossRefGoogle Scholar
Pantula, S.G.
(1989)
Estimation of autoregressive models with ARCH errors.
Sankhya B
50,
119–138.Google Scholar
Phillips, P.C.B.
(1989)
Partially identified econometric models.
Econometric Theory
5,
181–240.CrossRefGoogle Scholar
Seo, B.
(1999)
Distribution theory for unit root tests with conditional
heteroskedasticity.
Journal of Econometrics
91,
113–144.CrossRefGoogle Scholar
Wright, J.
(1999)
An empirical likelihood ratio test for a unit root, problem
99.2.1.
Econometric Theory
15,
257.Google Scholar
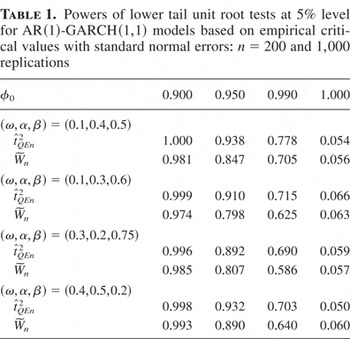
Powers of lower tail unit root tests at 5% level for AR(1)-GARCH(1,1) models based on empirical critical values with standard normal errors: n = 200 and 1,000 replications
Powers of lower tail unit root tests at 5% level for AR(1)-GARCH(1,1) models based on empirical critical values with t5 errors: n = 200 and 1,000 replications
Powers of lower tail unit root tests at 5% level for AR(1)-GARCH(1,1) models based on empirical critical values with t5 errors: n = 600 and 1,000 replications
 You have
Access
- 50
- Cited by