


1. INTRODUCTION
Two approaches to studying the asymptotics of long memory, fractional integration, and cointegration models have been developed in recent literature. In the first of these, which we call the “time domain moving average” model, the fractionally integrated process is commonly written as

where L represents the lag operator, |d| < ½, and ut is a short memory (weakly dependent) process. As is well known, the binomial expansion of (1 − L)−d yields the infinite moving average representation

where

and Γ() denotes the gamma function. Under the indicated restriction on d the lag coefficients are square summable, and the process is accordingly covariance stationary. In many applications we consider the linear case where

with {εt} i.i.d.(0,σ2) and

, having absolutely summable coefficients. See, for example, Granger and Joyeux (1980), Hosking (1981), Beran (1994), and many related references.
In the second approach, the frequency domain harmonizable representation of the process is adopted. Define

where i is the imaginary unit and W is a complex-valued Gaussian random measure with the properties


Observe that xt is always real-valued because the integrals over [−π,0] and [0,π] are complex conjugates. The term h(eiλ) is called the transfer function or frequency response function of the process. If xt is independent and identically distributed (i.i.d.) then

(constant), but otherwise we wish to think of it at this stage merely as some function of λ, complex-valued in general, to be specified by the context. It is, however, related to the spectral density of the process by f (λ) = σ2|h(eiλ)|2, and in the long memory case the latter function is often represented in the generic form

where d matches the parameter in (1.1) and L(λ) is at most slowly varying at 0.1
Here, L() is the standard generic notation for a slowly varying function, not to be confused with the lag operator L.
The object of this paper is to show that there are, in fact, important differences between these models as commonly represented and that, in particular, alternative versions of the fractional model lead to different limit processes. The differences are not trivial, and they may have completely different implications for joint distributions in the multivariate case. Section 2 describes a class of harmonizable representations of fractional Brownian motion, all sharing a common spectrum apart from scale constants, and shows how they can be derived as the weak limits of forward- and/or backward-looking linear moving average processes. Section 3 considers the multivariate case and examines the cross-spectra and covariance functions of different members of the class. Section 4 considers the distribution of the stochastic integral of one process with respect to the increments of another, and generalizations of the weak convergence results of Chan and Terrin (1995) are proved. Section 5 presents a complementary analysis of time domain representations, generalizing the model first proposed by Mandelbrot and van Ness (1968), and gives a generalized weak convergence result for this class using the approach of Davidson and de Jong (2000). Finally, Section 6 discusses our results in the context of the existing literature and shows how they resolve a number of puzzles and contradictory features of this literature. Proofs are gathered in the Appendix.
2. HARMONIZABLE REPRESENTATIONS OF FRACTIONAL BROWNIAN MOTION
In this section we introduce a class of continuous time Gaussian processes,

where W is a complex-valued Gaussian process on

satisfying the conditions of (1.3) and

is a complex-valued transfer function having the general form

for real constants d,κ,a, where −½ ≤ d < ½, 0 ≤ a ≤ d/2 for d > 0 and d/2 ≤ a ≤ 0 for d < 0, and 0 ≤ κ ≤ 1.
We mention two points of clarification at the outset. The first is to emphasize that this model class is introduced as a vehicle for developing and illustrating the representation issues addressed in the paper. We do not attempt to assign any particular interpretation to the parameters κ and a, which, as we show, can be thought of as indexing different distributed lead/lag structures. We will, in fact, argue that most practical applications in econometrics are covered by one particular case (see (2.8)). Second, note that in what follows we use the generic notation X(r) to denote any member of the class, so that dependence on the three parameters is taken as implicit. This is chiefly for notational clarity, because the expressions involving several coordinates of X would otherwise become unwieldy.
Now, note the identity

where sgn(λ) = 1 if λ ≥ 0 and −1 otherwise. Thus, (2.2) can also be written as

where

Further note that

(defining K(d,κ,a)) and so the spectral densities of this class (apart from scale factors) take the form

Alternatively, the variance of a process increment of width δ > 0, for any r ∈ [0,1 − δ], is

where the last equality can be verified from Gradshteyn and Ryzhik (2000) (henceforth GR), relation 3.823. Applying the identity

for any r1,r2,r3,r4 ∈ [0,1] with r1 < r2 and r3 < r4, formula (2.6) can be used to derive the covariance of any pair of segments of the process. The covariance structure of these processes therefore depends on a and κ only through the scale factor K(d,κ,a) and otherwise matches that of what is usually called fractional Brownian motion. Because in general σ2 is unknown, these parameters are accordingly unidentified from the point of view of a single process.
Any of these processes are candidates to be referred to as fractional Brownian motion, and some leading examples of the class have been proposed in the literature. Setting κ = 1 and a = 0 yields

(see, e.g., Reed, Lee, and Truong, 1995). Setting a = d/2 on the other hand (in which case κ drops out) yields

which, apart from an at most slowly varying component, is the model examined extensively by Chan and Terrin (1995). As a further variant, set κ = ½ and a = 0 to yield

The last case has not been proposed to date, to our knowledge, but provides an alternative to (2.9) as a way of representing symmetry of the backward- and forward-looking dependence. As we show, this property is implicit in any model having a real-valued transfer function.
As noted, Chan and Terrin (1995), in common with other contributions to this literature, allow slowly varying components in the transfer function and spectral density. Our class of models might easily be elaborated to include, for example, a slowly varying, even function of λ as a factor in (2.3). Such extensions would complicate the analysis but would not change the basic conclusions. Although these issues would be of interest to explore further, we choose to focus the present discussion on the model as given.
One way to motivate our class is by considering a corresponding class of discrete processes in the time domain. We may then show how the Brownian motions derived previously can be viewed as weak limits as the time intervals shrink to zero. Let

represent a serially independent Gaussian process with mean 0 and variance σ2 and so consider a “two-sided” moving average process

where

It is easily verified that the lag structure is a convolution of the binomial series associated with fractional integration. Thus,


for j > 0. Note that

for 0 < A < ∞ and similarly

Hence, with d > 0 this process has long memory with parameter d “in the tails” of the lag-lead distributions. However, different choices of a and κ, given d, influence the amount of short-run memory relative to long-run memory, either symmetrically forward and backward or asymmetrically.
The case a = 0, κ = 1 yields g(L) = (1 − L)−d. This, of course, corresponds uniquely to the one-sided (causal) model, with bj = 0 for j > 0 (lags but no leads). With a = 0, κ = 0, we have g(L) = (1 − L−1)−d (leads but no lags). On the other hand, with a = d/2 the model does not depend on κ and g(L) = (2 − L − L−1)−d/2, so that bj = b−j for each j > 0. The symmetry property also holds for the case κ = ½. Otherwise, with a lying strictly between zero and d/2, the models exhibit different degrees of forward and backward memory.
On substituting the harmonizable representation of ut into (2.11), we obtain2
Observe that in the symmetric example a = d/2 noted in the text, the transfer function g(e−iλ) = (2 − e−iλ − eiλ)−d/2 = (2 − 2 cos λ)−d/2 is simply the square root of the spectral density.
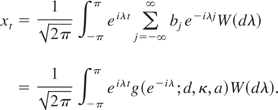
Introducing a change of variable from λ to λ/n, consider the partial sum process

and note that

where ≈ means that the approximation improves as n increases. Following the first part of Theorem 3.3 of Chan and Terrin (1995), we can formalize this intuition as follows, where X is defined by (2.1).
THEOREM 2.1.

for any 0 ≤ d < ½, 0 ≤ κ ≤ 1, and 0 ≤ a ≤ d/2.
Note that, unlike Chan and Terrin's theorem, this result covers the standard Brownian motion case d = 0. It still does not cover the case of −½ < d < 0, for which weak convergence is a well-established property of the time domain representation (see, among others, Davidson and de Jong, 2000). It turns out that our proof does not work for this case, because the integral in the majorant side of (A.1) in the Appendix is nonconvergent. However, we also note that where the discrete-time process is both linear and Gaussian, because uniform tightness holds it is sufficient, in view of the identities in (2.7) and (3.7), to establish that the limit of the variances of the partial-sum process matches that of X. Accordingly, we can prove the following result.
THEOREM 2.2. If

for −½ < d < ½, and Xn(r) is defined by (2.13), then

where X(r) is defined by (2.8).
Although this statement of the result is given only for the causal member of our class having κ = 1 and a = 0, note that both the finite-n and limiting variance expressions are generalized to the cases with 0 ≤ κ ≤ 1 and d/2 ≤ a ≤ 0 simply by applying the factor K(d,κ,a)2. The result may be easily extended in this way to our complete class of Gaussian linear processes.
3. THE MULTIVARIATE CASE
It is clear that all processes xt defined by (2.11) have the same spectral density function, and accordingly the limiting partial-sum processes have the same autocovariance structure, the one usually identified with fractional Brownian motion. However, it is also the case that these processes are distinct, and we now consider how they might be distinguished. This can only be in terms of the relations between different processes.
Consider processes X1 and X2 defined as in (2.1) with parameters (d1,κ1,a1) and (d2,κ2,a2) and driving processes W1, W2. The latter are complex-valued Gaussian random measures with the properties (for j,k = 1,2)


In this section and the one following we let 0 ≤ dj < ½ for j = 1,2. We do not attempt to treat the cases dj < 0 explicitly, although we conjecture that these extensions might be developed on the lines of Theorem 2.2.
Define

where


Observe, from (2.1), that the cross-spectrum of the increments is defined as

We can notice, for example, that f12(λ) is real-valued in the “time symmetric” cases, where either a1 = d1 /2 and a2 = d2 /2, or κ1 = κ2 = ½, although not in general. However, we can potentially learn more by considering time domain covariances of the Brownian motions, extending the formulation in (2.6).
Consider the case of contemporaneous increments.
PROPOSITION 3.1. For δ > 0 and 0 ≤ r ≤ 1 − δ,

Note that this formula reduces to (2.6) in the case X1 = X2 = X. We cannot use it to derive the covariances of noncoincident increments of the two processes, because there is no counterpart to identity (2.7). However, for the case of nonoverlapping increments the following result can be shown directly.
PROPOSITION 3.2. For 0 ≤ r1 < r2 ≤ r3 < r4 ≤ 1,
(i) if d1 + d2 > 0,

where

(ii) if d1 = d2 = 0,

To deal with the case r2 > r3, such that the increments are overlapping, this result may be used in conjunction with (3.3) and the identity

Consider, for example, the case of nonoverlapping segments where X1 is a backward-looking process, with κ1 = 1 and a1 = 0, and X2 a forward-looking process, with κ2 = 0 and a2 = 0. In this case θ1 = θ2 = θ4 = 0, and ξ3 = ½(d1 + d2); hence (3.4) vanishes, as we should expect because the lags and leads do not overlap anywhere. However, if κ2 = 1 and κ1 = 0, so that the segment of the forward-looking process on r2 − r1 precedes the segment of the backward-looking process on r4 − r3, then θ1 = θ2 = θ3 = 0, and the expression in (3.6) reduces to

Observe the symmetry of this formula, which is invariant to the interchange of d1 and d2. In particular, cases where long memory is a property only of the forward-looking process (d1 = 0) or of the backward-looking process (d2 = 0) are observationally equivalent. However, if both segments are backward looking, such that θ1 = 1 and θ2 = θ3 = θ4 = 0, we get

which vanishes only if d2 = 0.
4. STOCHASTIC INTEGRALS WITH RESPECT TO FRACTIONAL BROWNIAN MOTION
Although the results of the previous section may be of general interest, it is the distributions of stochastic integrals, random variables of the form

, that are the chief practical concern in econometric analysis. It is well known that these are not Itô integrals in the case of fractional processes, and their derivation requires methods different from those used in the case of semimartingales such as regular Brownian motion. The problem is addressed in Chan and Terrin (1995) for the particular case they consider, which corresponds effectively
3The Chan and Terrin (1995) model allows for slowly varying components, which are, however, absorbed into their normalizing sequence, so that the asymptotic analysis is equivalent in the two cases.
We follow these authors in defining the differential of (2.1) by replacement of the term (eiλr − 1)/iλ with its derivative, so that

For the case d1 + d2 > 0, the expected value of this random variable is

where the form of the last expression can be obtained from (3.2). This formula can be further shown to have the following closed form.
PROPOSITION 4.1. If d1 + d2 > 0,

where

Note the following corollary of Propositions 4.1 and 3.1.
COROLLARY 4.1. If d1 + d2 > 0,

Also note that the case d1 = d2 = 0 has to be excluded from these results because our formula in (4.2) then reduces to

Although its integrand is an odd function, the integral on the right-hand side has the form ∞ − ∞, so that the expectation is undefined.
Now consider some contrasting cases of (4.2). We obtain the last term of Chan and Terrin's formula (3.11), apart from scale factor, by setting aj = dj /2 with arbitrary κj, for j = 1,2. In this case we obtain the closed form

A feature of this model, consequent on the forward-backward symmetry of the lag structure, is that the formula is symmetric in d1 and d2. We are not able to distinguish between the case of longer memory integrand with shorter memory integrator and the converse case.
In the case of the causal model, in which κ1 = κ2 = 1 and a1 = a2 = 0, on the other hand, we obtain

Note, in a result that parallels (3.8), how this quantity vanishes when d2 = 0, although not when d1 = 0.
We next proceed to generalize the second part of Chan and Terrin's Theorem 3.3, which establishes weak convergence of the stochastic integral. Letting x1t, x2t be defined as in (2.11) with parameters (dj,κj,aj) for j = 1,2, our result is as follows.
THEOREM 4.1. If 0 ≤ d1 < ½, 0 ≤ d2 < ½, and d1 + d2 > 0 then

Observe that our conditions here are weaker than the min(d1,d2) > 0 imposed by Chan and Terrin, permitting cases where either X1 or X2 is standard Brownian motion. However, the case d1 = d2 = 0 is again problematic, not withstanding that the conditions for mean-squared convergence established in the theorem are still satisfied. This follows from the fact noted in (4.5) that the limit specified by formula (4.1) is not an integrable random variable.
The problem arising here can be seen to stem from the approximation of the extreme high-frequency components implicit in the Fourier transformation. This approximation is negligible in the long memory case thanks to nonsummability of the autocovariances. In standard Brownian motions, however, it is well known that the equality in (4.4) requires an additional term σ12 on the left-hand side, representing the contemporaneous correlation of the processes. It is also well known that replacing the partial sum

in (4.6) by ½(S1t + S1,t+1) yields the Stratonovich integral
4See, among others, Duncan, Hu, and Pasik-Duncan (2000).
5. VARIANTS OF FRACTIONAL BROWNIAN MOTION IN THE TIME DOMAIN
Let B denote Brownian motion on

with variance E [B(1) − B(0)]2 = σ2. The Gaussian stochastic process on the unit interval [0,1] with representation

was termed “fractional Brownian motion” by Mandelbrot and van Ness (1968). Marinucci and Robinson (1999) have subsequently dubbed this process “fractional Brownian motion of Type I,” in contrast with the Type II case in which the second term is discarded. Type II fractional Brownian motion is sometimes rationalized as the weak limit of a process in which the forcing sequence takes the truncated form ut I(t ≥ 1). However, it is important to note that the resulting weak limit has a different distribution and is not to be regarded as an approximation to (5.1).
It is well known (see, e.g., Davidson and de Jong, 2000) that the increment variance of Type I fractional Brownian motion is defined by

where

The second equality in (5.2) is a consequence of the following lemma, whose proof we give, for the record, in the Appendix.
LEMMA 5.1.

In this section, we extend this time domain representation to a class of the processes whose harmonizable representation is discussed in Section 2. To be precise, we consider just the cases with 0 ≤ κ ≤ 1 and a = 0, because for these the extension of (5.1) is simple and transparent. Let

Defining the filtration

note that

are an adapted pair in the case κ = 1, which corresponds to (5.1). This is another way to express the notion of a causal process. Otherwise, X is

-measurable at all points and hence not adapted to

. With κ = ½, such that the forward- and backward-looking moving averages are symmetric, note that this model corresponds to case (2.10), whereas with κ = 1 it corresponds to (2.8).
We remark parenthetically that there appears to be no natural way to define a “Type II” variant of this class of model. Thus, the process {X(r), 0 ≤ r ≤ 1} obtained by deleting the second and third terms of (5.3) corresponds to the weak limit of a fractionally integrated process whose forcing sequence takes the form ut I(1 ≤ t ≤ [nr]) for each r. One could truncate the forcing sequence at n and hence the third integral at 1, instead of deleting it, but this option forgoes the benefits of simplicity and seems equally arbitrary. There are many ways to construct stochastic processes having correlated increments, subject to a parameter d, but not all of them have relevance to econometric modeling.
The next proposition derives the general formula for the increment variances.
PROPOSITION 5.1. E [X(r + δ) − X(r)]2 = Vδ2d+1 where

We need to check the relationship between this formula and (2.6) obtained in the harmonizable representation for the case a = 0. The following proposition shows that they are identical.
PROPOSITION 5.2.

.
The main implication to be remarked here is that the Mandelbrot–van Ness model (5.1) is shown to be equivalent to the causal variant (2.8) of the harmonizable representation, these being Gaussian processes with identical covariance structure. This fact may suggest a further need for caution in adopting the Type II variant of time domain fractional Brownian motion in the causal model. Having nonstationary increments, the Type II variant evidently does not possess a harmonizable representation.
Because empirical processes will always be subject to an unknown scale factor σ, it is not possible to distinguish the processes represented by (5.3) from one another in isolation, and κ is unidentified. However, similar arguments allow us to show that for processes X1 and X2 the covariances of process segments, and

, depend on κ1,κ2. This can be verified simply by considering the harmonizable representations in Sections 3 and 4, which yield equivalent formulas.
It is known (Davidson and de Jong, 2000, Thm. 3.1) that if xt = (1 − L)−dut, where {ut} satisfies fairly weak regularity conditions and

then

where X is defined by (5.1) and

denotes weak convergence in the space D[0,1] of cadlag functions on the unit interval, equipped with the Skorokhod topology (see, e.g., Davidson, 1994, Ch. 28). We can now extend this result as follows.
THEOREM 5.1. If

for any d ∈ (−½,½) and κ ∈ [0,1], and Xn is defined in (5.4), then

under the assumptions on ut specified by Theorem 3.1 of Davidson and de Jong (2000).
We refer the reader to the cited source for details of the specified conditions, which are quite complicated to state. It suffices to say that they specify weak dependence in the form of L2-near-epoch dependence on a mixing process, at specified sizes. These conditions are invariant to time reversal, which allows the extension of the results specified in the proof of the present proposition. Also note that this proposition is not redundant in view of Theorem 2.1, not merely because it covers the cases d < 0, but because it allows a very general class of weakly dependent shock processes. Although it is possible to introduce additional weak dependence in Theorem 2.1 (we avoid this for the sake of simplicity) note that Gaussianity is a necessary condition in the spectral approach.
6. DISCUSSION
In the literature on fractional Brownian motion, there is a tendency to assume the existence of a single Gaussian process having the characteristics of interest. In the time domain, the formulation most often cited is the one of Mandelbrot and van Ness (1968). Among many references in the engineering, statistics, and econometrics literature see Flandrin (1989), Samorodnitsky and Taqqu (1994, Sect. 7.2), and Reed et al. (1995).
However, there is less consensus regarding the so-called harmonizable representation of fractional Brownian motion. Samorodnitsky and Taqqu (1994, Sect. 7.2), which is perhaps the chief reference source on these topics, refers to one of the “time symmetric” members of our class, that having a = d/2 and arbitrary κ, as the (integral representation of) “standard” fractional Brownian motion, and Chan and Terrin (1995) follow suit. On the other hand, Reed et al. (1995) cite the “causal” form (κ = 1, a = 0). Kim and Phillips (2001) actually cite the causal version in the statement of their model, but then they switch to the time symmetric case in their work, while following the Chan and Terrin analysis. This apparent confusion is very likely attendant on the fact that the underlying stationary driving processes all have the same spectrum. Indeed, Chan and Terrin (1995) explicitly set up their model by citing the spectral density of interest (|λ|1−2H multiplied by a possibly slowly varying scale component) and then selecting the square root of this function as the transfer function to define their harmonizable representation.
However, as we have shown in this paper, the Mandelbrot–van Ness time domain model and the time symmetric model discussed by Samorodnitsky and Taqqu, Chan and Terrin, and other authors have very different implications for multivariate analysis, despite the stationary increment processes sharing the same spectrum, apart from scale constants. We note that Chan and Terrin invoke econometric applications explicitly in their introduction, introduce a unit root autoregressive (backward-looking) model, and even quote the one-sided time domain representation (1 − L)dyt to motivate their formal analysis of the long memory errors. This suggests that they did not fully appreciate the modeling implications of their chosen harmonizable representation. When the applications of interest are in time series econometrics, we ought to point out that for most applications only a single member of our class should generally be considered: the causal (i.e., exclusively backward-looking) Mandelbrot–van Ness model, with harmonizable representation (2.8) having κ = 1, a = 0 in the Gaussian case. Time series processes in econometrics are almost always thought of as adapted to the filtration representing “events to present date,” because any other setup would contradict our usual understanding of economic behavior.5
Two-sided models could have applications in random field representations involving spatial correlations, for example.
Frequency domain analysis is a popular research methodology in time series econometrics, especially in the analysis of long memory and fractional integration and cointegration. We can cite, for example, the many contributions of Peter Robinson and co-authors. Robinson (1994a, 1994b), Robinson and Marinucci (2001, 2003), and Marinucci and Robinson (1999, 2000, 2001) is a nonexhaustive list covering just one aspect of this research. One obvious motivation for this methodology is the greater mathematical tractability often available in the asymptotic analysis of long memory models. By the same token, however, we see a need to emphasize the potential pitfalls of modeling dynamic relationships in a framework that may conceal the important role of causal orderings.
APPENDIX: Proofs
A.1. Proof of Theorem 2.1.
Our proof is based on the first part of Theorem 3.3 of Chan and Terrin (1995). We modify their notation by substituting d + ½ for H1, n−1/2−d for an,

for an−1Un, and

for KH1−1BH1 where they define

and KH1 = [π−1H1Γ(2H1)sin πH1]1/2. (The definition of the normalizing constant KH1 will depend on the member of the class of processes we consider, of which Chan and Terrin's case is only one, but we will not state these explicitly. Be careful to note that Chan and Terrin assume W has unit variance and also note the error in their definition of KH1, omitting the square root (Chan and Terrin, 1995, line following (3.10), p. 1671)). We neglect the possibility of slowly varying components, which in practice must be incorporated into the normalizing sequence an, thereby obtaining the same limiting formulas for moments, etc.
Following Chan and Terrin, we cite Taqqu (1975, Thm. 2.1) to establish tightness of the sequence and accordingly prove weak convergence of the finite-dimensional distributions by showing that

for each r ∈ [0,1]. Note that Chan and Terrin's expression for Un (p. 1672, line 7 from bottom) is generalized to our class by replacing |λ|1/2−H1 by

, which entails inserting the factor ϒ(λ;d,κ,a) defined by (2.4). Chan and Terrin's case is

where ϒ(λ;d,κ,a) = 1. However, their expressions

and

carry over unchanged. Therefore, we need to demonstrate that the following sequence (the counterpart of Chan and Terrin's equation (3.12)) must converge to 0 as n → ∞:

Because Dn(r,λ) → D(r,λ) pointwise on

, to show that the first majorant term vanishes it suffices to show that

uniformly in n. Note first that

Therefore, using the results

and

for integer k ≥ 0, observe that

To show that the second majorant term in (A.1) vanishes as n → ∞, note that

Taking the first right-hand-side term under the modulus in (A.5), note that

where

The same treatment of the second right-hand-side term yields an expression ϖ2n(λ,a,d) = O(n−1) similarly. Note that ϖ1n(λ,a,d) and ϖ2n(λ,a,d) depend on λ only through its sign, and hence the squared modulus in (A.5) depends on λ only through |λ|−2d. We therefore complete the proof by applying (A.4) as before. █
A.2. Proof of Theorem 2.2.
We show that E [Xn(r)2] → E [X(r)2] for each r ∈ [0,1]. As remarked in the text, this condition is sufficient for the weak convergence, because the sequence members are linear and Gaussian for each n ≥ 1 and uniform tightness holds as before, by appeal to Taqqu (1975, Thm. 2.1).
The spectral representation of Xn(r) is

The integrand can be rewritten as

The variance of Xn(r) is therefore equal to

By GR, relation 3.621(1),

where the second equality follows after some manipulation using the properties of the gamma function. Next,

where the penultimate equality follows from GR, relation 3.631(9). Upon substitution of these expressions into the expression for the variance we obtain

In the limit, as n → ∞, the contribution of the first term in the parentheses vanishes. For the second term we use

Hence,

The right-hand side is equal to the variance of the fractional Brownian motion process

To show this observe that the integrand can be rewritten as

and hence the variance of X(r) takes the form

where the last equality follows from GR, relation 3.823. █
A.3. Proof of Proposition 3.1.

Substituting from (3.2), note that the last integral has four terms, with typical form

(see GR, relations 3.761 and 3.823). Direct substitution into (A.7) gives (3.3). █
A.4. Proof of Proposition 3.2.

Rearranging the terms with the exponents gives

Next, define integrals


and note that

The expression for the covariance can accordingly be rewritten as

The integrand in Φ1 can be rearranged using a trigonometric identity as

Applying GR, relation 3.762(1), then yields

where U(d1,d2) is given by (3.5). Note that Φ1 = 0 for d1 + d2 = 0.
For Φ2, use GR, relations 3.763(1) and (3), to obtain

Substituting these results in (A.9) yields (3.4) for the case d1 + d2 > 0. The case d1 = d2 = 0 implies a1 = a2 = 0. Hence, ξj = 0 for j = 1,2,3,4 and

█
A.5. Proof of Proposition 4.1.
Because 0 ≤ r ≤ 1 we have sgn(λ) = sgn(λr), and making the change of variables x = λr we can integrate with respect to r independently. This yields the general formula

where P12 is defined in (3.2), containing terms of the type exp(iπξj sgn(λ)), where ξj is one of the indicated functions of d1,d2,a1,a2. For any such term we can rewrite the corresponding component of the integral over the real line in (A.10) (say, C(ξj)), as

where

denotes complex conjugation and

Using (A.12) in (A.11),

and

where

and direct substitution yields (4.3). █
A.6. Proof of Corollary 4.1.
Note that E(X1(1)X2(1)) is given by setting δ = 1 in (3.3). We show that this formula matches the sum of (4.2) and the complementary expression having 1 and 2 interchanged. First note, using the relations

that

Next, from (4.3), using the fact that

and also the trigonometric identities


we complete the proof by noting that

█
A.7. Proof of Theorem 4.1.
Following Chan and Terrin (1995, p. 1674) define

and

We prove, analogous to (3.14) of Chan and Terrin (1995), that

as n → ∞. Note that

where

, gi(L) = g(L;di,κi,ai), and Ki = K(di,κi,ai), for i = 1,2, and

The factor 1[−nπ,nπ]2(μ,λ) can be optionally included in (A.14) because it does not change the value of the integral in (A.13).
It is required to show that both the terms of the majorant of (A.13) converge to 0. It is easy to see that Bn(μ,λ) − B(μ,λ) → 0 pointwise in

, and so in respect of the first term it suffices to show that

uniformly in n.
At points inside [−πn,πn] × [−πn,πn],

where


and Sn is the complex conjugate of Sn. Consider the last two terms in (A.15). Note that

where in the second equality we did a change of variable from λ to −λ and in the third we collected terms and canceled odd components.
Consider first the integral with respect to λ:

using |(sin x)/x| ≤ 1. Next consider the integral with respect to μ. Using (A.2) and (A.3) we have

Substituting these bounds in (A.16) yields

Next, considering the first term in (A.15), note that

Observe that this term vanishes for d2 > 0, although not for d2 = 0.
The same argument can be invoked again to show that the second majorant term of (A.13) vanishes, provided Φn(λ,μ) is bounded uniformly in n, and converges to 0 pointwise in

. To show this, recall that

where

From (2.12) the expression n−d1−d2g(e−iμ/n;d1,κ1,a1)g(e−iλ/n;d2,κ2,a2) can be decomposed similarly, into terms with coefficients κ1κ2, (1 − κ1)(1 − κ2), κ1(1 − κ2), and (1 − κ1)κ2. Pairing up these matching terms, Φn(λ,μ) can be therefore be decomposed (defining functions φkn, k = 1,…,4 in the obvious manner) as

We consider the term φ1n as representative. This takes the form

Note that

and hence

It can be verified that φ1n(μ,λ) is absolutely bounded everywhere in

, and φ1n(μ,λ) = O(n−1) follows similarly to (A.6). Precisely parallel arguments apply to the terms φkn(μ,λ) for k = 2,3,4. This completes the proof. █
A.8. Proof of Lemma 5.1.
We need to compute the integral

for −½ < d < ½. Denote the integrand by f (x). Note that for d = 0 the integral is trivially zero. For 0 < d < ½ we have limx→±∞| f (x)| = 0, limx→0| f (x)| = 1, and the function is integrable, for both positive and negative x. For −½ < d < 0, we have limx→±∞| f (x)| = 0, and f (x) has a singularity at x = 0 with limx→0| f (x)x−2d| = 1. Hence, is it integrable on the positive half-line. For x < 0 it also has a singularity at x = −1 with limx→−1| f (x)(x + 1)−2d| = 1 and therefore is also integrable on the negative half-line.
Thus, consider the auxiliary integral

It is easy to see that for d ≠ 0 this integral equals zero:

Next, divide the range of integration into (−∞,−1), (−1,0), and (0,∞). For the first interval change of variables

gives

For the second interval we have

where in the last integral we used change of variables x = x + 1. The integral over the third interval is simply G(d). Adding the integrals over these three intervals we obtain

or,

Note that this expression formally captures the result G(0) = 0. Further, using the functional relationships

we can express the integral equivalently as

or

█
A.9. Proof of Proposition 5.1.
By (5.3) and the orthogonality of Brownian motion, we may write

and the proposition follows directly on rearrangement. Note that the second equality makes a change of variable and the third one substitutes the complete beta function and also the result of Lemma 5.1. █
A.10. Proof of Proposition 5.2.
Use the properties of the gamma function

to do the following transformation:

Substituting this equality yields

█
A.11. Proof of Theorem 5.1.
Write xt = κxbt + (1 − κ)xft where

The result

, where

and Xb is the process in (5.1), follows from Theorem 3.1 of Davidson and de Jong (2000).
To deal with Xfn, the forward-looking increment process can be converted into a backward-looking process by reversing the time ordering. Define vnt = un−t+1 for −∞ < t < ∞ and let

Then,

Although {vnt} and {znt} are technically arrays, note that they are stationary processes. Their distribution is invariant to n, and they satisfy the conditions of Davidson and de Jong (2000, Assump. 1) for any choice of n. In effect, Xfn is equivalent to a backward-looking partial-sum process in which the starting date shifts backward in time as n increases, with a fixed terminal date. However, the sequence of distributions defined by letting n → ∞ is invariant to these shifts and matches that of the conventional “fixed start” process at each point. Hence, Theorem 3.1 of Davidson and de Jong (2000) can be invoked to establish the joint weak convergence of each term in (A.17), and

by the continuous mapping theorem. The limiting random variable for each r takes the form

where the second and third equalities follow by changes of variables and rearrangement.
Finally, it further follows by the continuous mapping theorem that

Note that this argument depends on the {ut} process being reversible without altering the dependence structure. Thus, if the initial functional central limit theorem was established using the assumption that ut was a martingale difference, the second stage of the argument would fail. However, the theorem of Davidson and de Jong (2000) specifies that ut is L2-near-epoch dependent on a mixing process, and this characterization of dependence is preserved under time reversal. █


