


1. INTRODUCTION
Consider the first-order autoregressive AR(1) process {Xk} defined by the equations

where ρ is a deterministic parameter and {εk} some noise sequence. These processes are well understood if dealing with independent, identically distributed errors having a finite variance. Exploiting its recursive structure, it can be shown that the defining equations (1.1) allow for a unique causal (i.e., future-independent), strictly stationary solution if and only if |ρ| < 1. It should be noted, however, that, in case |ρ| > 1, strictly stationary solutions exist that are future-dependent. Detailed expositions on this topic and on more basic properties of AR(1) processes and their generalizations may be found in Brockwell and Davis (1991, Ch. 3).
Assuming for simplicity that the AR(1) process is initialized with X0 = 0, statistical inference for the unknown parameter ρ can be carried out, for example, by the least squares estimator

given observations of X1,…, Xn. Its limiting behavior has been examined thoroughly. If |ρ| < 1, then

converges in distribution to a normal law with mean 0 and variance 1 − ρ2. The situation turns out to be more complicated for explosive AR(1) processes. Under the additional assumption of a Gaussian noise sequence {εk}, White (1958) showed that in the case of a fixed |ρ| > 1 the limit distribution of

is standard Cauchy if normalized with ρn/(1 − ρ2). In general, however, the limit distribution depends on the distribution of the noise, as was pointed out by Anderson (1959), and hence no central limit theorem applies on the explosive side.
One of the major concerns in econometrics, which has been discussed for several decades now, is to validate or reject the so-called random walk hypothesis: To what extent can econometric time series such as (logarithms of changes in) stock-market prices be modeled by AR(1) processes with parameter ρ = 1, that is, by random walks? Evidence has, for instance, been found in the contributions of Fama (1965) and, more recently, Nelson and Plosser (1982). Commonly, the testing problem is tackled using derivatives of the popular test statistics introduced by Dickey and Fuller (1979, 1981), which can, for example, be based on the least squares estimator in (1.2). However, these tests feature a low power because of the lack of difference of the test procedures under the random walk hypothesis and the possible alternatives |ρ| < 1, ρ > 1, or ρ ≠ 1.
Moreover, it has been found that in some financial applications (see Phillips, 1988, and the references therein) the parameter ρ tends to 1 with increasing sample size. To accommodate this observation, ρ = ρn is allowed to depend on n, the number of observations, such that ρn → 1 as n → ∞. The process is then referred to as near-integrated. Depending on whether ρn < 1 or ρn > 1, it is called near-stationary or mildly explosive. Most of the existing literature is devoted to the so-called local to unity case ρn = 1 + c/n. For instance, Chan and Wei (1987, 1988) studied both the near-stationary and the mildly explosive case and determined the limiting behavior of the estimator

, which is defined in (2.6). Lately, Phillips and Magdalinos (2007) (see also Giraitis and Phillips, 2006) investigated the general parameter case in the near-integrated setting assuming that ρn → 1 with a rate slower than 1/n (so-called moderate deviations from unity).
All papers cited in the previous paragraph are working under the assumption of a finite variance along with independent, identically distributed or weakly dependent errors. However, extensive empirical research conducted shows that this assumption seems to be violated for quite a variety of time series. Thus, Mandelbrot (1963, 1969) already argued for what he called the infinite variance hypothesis and suggested modeling noise sequences by stable random variables. Although, in general, there is still controversy as to whether or not stable variables can reasonably describe financial data, we mention the monograph by Mittnik and Rachev (2000), who happen to concur with Mandelbrot's approach.
Consequently, we will focus on giving a corresponding limit theory for the serial correlation coefficient in the mildly explosive setting with moderate deviations from a unit root if the innovations {εk} are heavy-tailed, that is, in the domain of attraction of an α-stable law, where α ∈ (0,2]. Pioneering work has been carried out by Chan and Tran (1989) in the random walk case ρ = 1 and by Chan (1990), who studied the local to unity case on both the stationary and explosive sides.
To start with, we will introduce the model and basic assumptions, and we state the result in Section 2, which also contains those properties of strictly α-stable random variables, which are important in the discourse. The proof is relegated to Section 3.
2. MAIN RESULT
We study the following sequence of first-order autoregressive AR(1) models. Let

where, for simplicity, the initial values X0(n) = ε0 are constant. To take into account the infinite variance hypothesis, the innovation sequence {εk} is assumed to consist of independent, identically distributed random variables in the domain of attraction of a strictly α-stable law.
A random variable ξα is called strictly α-stable, α ∈ (0,2], if its characteristic function has the form

The definition includes the normal law (α = 2) and the Cauchy law (α = 1). There are no explicit expressions for densities or distribution functions of random variables in the domain of attraction of an α-stable law, so there exist various indirect ways of defining them. For convenience (they are more easily applicable in the proof), we choose the characteristic function version.
The class of stable distributions has become more and more important in theory in addition to its importance in applications. Stable laws appear in a natural way in areas such as radio engineering, electronics, biology, and economics (see Zolotarev, 1986, Ch. 1). For other extensive expositions on α-stable random variables and processes consult Samorodnitsky and Taqqu (1994) and Bingham, Goldie, and Teugels (1987).
The assumption that {εk} is in the domain of attraction of a strictly α-stable law implicitly contains the limit result (cf. Ibragimov and Linnik, 1971, Thm. 2.1.1).

which bears some resemblance to the classical central limit theorem but is obviously more general: if α ∈ (0,2), in which case variances do not exist, then L(x) > 0, x > 0, is a slowly varying function at infinity, that is,

If α = 2, then we choose

, and condition (2.3) becomes the central limit theorem with ξ2* being a standard normal random variable. Moreover, (2.2) yields that Eε1 = 0 for α ∈ (1,2]. Note that we have used ξ2* instead of ξ2,β*, because β is not used in the definition (2.2) if α = 2. The same reasoning applies to the case α = 1.
It is assumed that the model parameter ρn satisfies

Because the latter condition implies that, for large n, ρn > 1 is farther away from unity than

, this setting is referred to as mildly explosive with moderate deviations from a unit root. Denote by

the least squares estimator for ρn. Then, the serial correlation coefficient

has, under a suitable normalization, a limit that consists of a fraction of two independent strictly stable random variables distributed as ξα,β* in (2.3).
THEOREM 2.1. Let {Xk(n)} follow (2.1) and let conditions (2.3) and (2.5) be satisfied. Then

where

is defined in (2.6) and ξα,β and ζα,β denote independent strictly α-stable random variables distributed as ξα,β* in (2.3).
If α = 2, that is, if the innovations {εk} satisfy the central limit theorem, Theorem 2.1 has already been proved in Phillips and Magdalinos (2007). Here, ξ2 and ζ2 are independent standard normally distributed, and thus the limit ξ2 /ζ2 becomes a standard Cauchy random variable. The result is also in accordance with the asymptotics of

in the fixed parameter case ρ > 1 (see Mijnheer, 2002). However, the results of Chan (1990) indicate that the asymptotics in the local to unity case, where the limit is given as a function of integrals of α-stable processes, are qualitatively different from Theorem 2.1 and more closely related to the unit root case ρ = 1 treated in Chan and Tran (1989).
3. PROOF
First, we collect some facts that are used throughout the proof. Let

The mean-value theorem and condition (2.5) imply that ncn → ∞ as n → ∞.
Let L(x) be a slowly varying function at infinity. Then,

and for any δ > 0 and T > 0 there is a constant C > 0 such that for all n ≥ 1

Both relations follow from Corollary 3.1 in Csörgő and Horváth (1993, p. 420). The bound in (3.3) is well known and can be found, for instance, in Ibragimov and Linnik (1971). Moreover, (3.2) is a direct consequence of (3.3), which can be seen by letting n = 1/cn and u = ncn in (3.3).
A process {Wα,β(t) : t ≥ 0} is called strictly α-stable if its increments are strictly α-stable random variables. The assumption of {εk} being in the domain of attraction of a strictly α-stable law yields the functional version of the central limit theorem (2.3) for all α ∈ (0,2]. By Gikhman and Skorohod (1969, pp. 479–481; see also Petrov, 1975, Sect. IV.2), the finite-dimensional distributions of the partial sum process converge to those of a strictly α-stable process, and the partial sum process is tight. Consequently, we have that, for any T > 0,

where

denotes weak convergence in the Skorohod space

.
Furthermore, as another consequence of (2.3),

If α = 2, then Eε12 < ∞, so (3.5) follows from the weak law of large numbers. If α ∈ (0,2), then (2.3) holds if and only if

where K(x) is a slowly varying function at infinity and limn→∞ P{|ε1| ≥ n1/αL(n)} = 1. Because

with

slowly varying at infinity, we get that ε12 is in the domain of attraction of a strictly α/2-stable law. Because also limn→∞ P{ε12 ≥ n2/αL2(n)} = 1, we get that

with some β* ∈ [−1,1].
Next, we will outline the proof steps. It is clear from (2.1) and (2.6) that

Hence, we need to derive the asymptotics of both sums on the right-hand side. To do so, a representation of Xk(n) in terms of the innovations εj, where j ≤ k, will be applied. Because by assumption ε0 = X0(n),

exploiting the recursive structure of model (2.1). Lemma 3.1 deals with the partial sums of the Xk−1(n)εk, and the partial sums of the Xk−12 are handled in Lemma 3.2. Finally, their joint convergence is established in Lemma 3.3. Theorem 2.1 will follow readily from these auxiliary results.
Let T > 0 and denote by [lfloor ]·[rfloor ] the integer part. Then, using (3.7),

It will be shown that RT,3(n) is the leading term, whereas RT,1(n) and RT,2(n) do not contribute to the limit distribution. For α ∈ (0,2] and x > 0 set Nα(x) = x1/αL(x).
LEMMA 3.1. Let the assumptions of Theorem 2.1 be satisfied.
(i) For every T > 0 and ε > 0,

where RT,1(n) is defined in (3.8).
(ii) For every ε > 0,
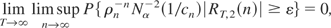
where RT,2(n) is defined in (3.8).
Proof. Set M = [lfloor ]T/cn[rfloor ]. It follows from (3.1) that M → ∞ as n → ∞.
(i) We recall that

It is easy to see that

On the other hand, by Abel's summation, we have

Hence, on combining the previous equations, we arrive at

We will work on the right-hand side of equation (3.9) term by term.
Set S(x) = ε0 + ··· + ε[lfloor ]x[rfloor ]. Note that S(x) is a right-continuous function and, hence, integration by parts implies

By (3.4) and the definition of M, it holds that

and

so we conclude that

Hence, using ncn → ∞, we obtain

as n → ∞, showing that the first term on the right-hand side of (3.9) is negligible.
As a consequence of (2.3), integration by parts in combination with standard estimates give for the third term in equation (3.9)

for any fixed T > 0 as n → ∞. To obtain the rate

, apply (3.11) and

which follows from the fact that, for large n, ρn−t ≤ 1 and from (3.4).
Finally, (3.5) yields

for any fixed T > 0 as n → ∞. Because

, the proof of (i) is complete.
(ii) Note that, similarly as in part (i),

Starting with the second sum on the right-hand side, we get from (3.2) and (3.5)

for any fixed T > 0 as n → ∞, where δ > 0 can be chosen arbitrarily.
It remains to examine the first sum in (3.12). Observe that

It is clear that

Now, integration by parts and a subsequent change of variables yield

The central limit theorem for strictly α-stable random variables in (2.3) implies

for all δ > 0 according to (3.2). Also, with 0 < ν < min{α,1}, an application of Markov's inequality leads to

By Minkowski's inequality for integrals (see Kaczor and Nowak, 2003, p. 49) we have

Using Theorem 6.1 of de Acosta and Giné (1979) and (3.3), we arrive at

with any δ > 0 and some constant C > 0. Thus, we have proved

Now, for the second term in (3.14) we write

First, Abel's summation formula gives

Therein we conclude from (3.2)

for all δ > 0 as n → ∞. Also, (3.4) implies that

Moreover,

by Taylor expansion. Hence, relation (3.2) gives

for all δ > 0 as n → ∞. Finally, (3.4) and (3.2) yield

for all δ > 0 as n → ∞. Abel's summation formula, along the lines of (3.20), gives

On applying (2.5) and (3.2) we obtain

for all δ > 0 as n → ∞. Let 0 < ν < min{1,α}. As in (3.17), Markov's inequality, Minkowski's inequality for integrals (cf. Kaczor and Nowak, 2003, p. 49), and Theorem 6.1 of de Acosta and Giné (1979) imply

for any δ > 0 and some constant C, where we also applied relation (3.3). Hence

Next, we show that

Because we proved that

(3.23) is established if we verify

Toward this end, write

We have already shown that

Because {εk} is a sequence of independent, identically distributed random variables we get

and, thus, we have by (3.24) that

This completes the proof of (3.23). Putting together (3.12)–(3.14), (3.18), (3.19), and (3.22), we obtain part (ii) of Lemma 3.1. █
Thus it suffices to investigate the term RT,3(n) to obtain the limit distribution. The second part of the proof deals with the partial sums of the Xk2(n). Again let T > 0. Then, we obtain that

The next lemma identifies ST,3(n) as the leading term by showing that ST,1(n), ST,2(n), and ST,4(n) are asymptotically small.
LEMMA 3.2. Let the assumptions of Theorem 2.1 be satisfied.
(i) For every T > 0 and ε > 0,

where ST,1(n) is defined in (3.25).
(ii) For every ε > 0,

where ST,2(n) is defined in (3.25).
(iii) For every ε > 0,

where ST,4(n) is defined in (3.25).
Proof. Recall that M = [lfloor ]T/cn[rfloor ] and S(x) = ε0 + ··· + ε[lfloor ]x[rfloor ].
(i) Note that

Because by (3.4)

we get for the first term of the right-hand side

for any fixed T > 0 as n → ∞. By (3.11), we obtain for the second term

for any fixed T > 0 as n → ∞. This proves part (i) of the lemma.
(ii) Arguments similar to those used in part (i) of the proof give the estimate

We will proceed termwise again. At first, note that by (3.4) and the definition of M,

Therefore, we obtain the following asymptotics for the first term:

for any δ > 0 as n → ∞, where we have used (3.2). Next observe that, because ρn−M = exp(−2T)(1 + o(1)),

by (2.3) and (3.2). It is obvious that by (2.4)

Moreover,

Thus, we conclude

for all ε > 0. Finally,

where the parts involving ρn are clearly bounded. Ultimately, choose 0 < ν < ½ min{1,α}. Repeating the arguments used in (3.21) we obtain that

so by Markov's inequality we have that

for all ε > 0. Hence, the proof of part (ii) of Lemma 3.2 is complete.
(iii) Omitted. █
Lemma 3.1 tells us that it suffices to derive the limit distribution of the remaining term RT,3(n). Checking the remaining summation ranges in the corresponding double sum in (3.8) shows us that RT,3(n) is a product of two independent factors, whose limits can be calculated separately. We also note that the square of one of the terms in RT,3(n) is the only random part in ST,3(n).
LEMMA 3.3. Let the assumptions of Theorem 2.1 be satisfied. Then

for any fixed T > 0, where {Wα,β(1)(x) : x ≥ 0} and {Wα,β(2)(x) : x ≥ 0} denote two independent strictly α-stable processes.
Proof. The proof is given in two steps, each of them investigating one of the components of the vector of interest. The joint behavior is obtained on combining both results.
(i) Observe that

Hence, integration by parts and (2.3) give the convergence in distribution result for the first coordinate, because Nα−1(1/cn) is clearly asymptotically negligible.
(ii) Note that

We have shown that, for any T* > 0,

where M* = [lfloor ]T*/cn[rfloor ]. Next, we write, as in (3.20), that

Condition (2.3) implies that

Similarly to (3.17), Theorem 6.1 of de Acosta and Giné (1979) yields, for all T > 0,

It follows from the proof of (3.21) that

Let 0 < ν < min{1,α}. Applications of Minkowski's inequality and the self-similarity of Wα,β yield

So, by Markov's inequality we have

Therefore, the proof of the convergence of the second coordinate of the vector in Lemma 3.3 is complete. █
LEMMA 3.4. Let the assumptions of Theorem 2.1 be satisfied. Then

as n → ∞.
Proof. Recalling that M = [lfloor ]T/cn[rfloor ], it is easy to see that

as n → ∞. Let ε, δ > 0. By Lemmas 3.1 and 3.2 there are n0 and T0 such that

Also,

for all T ≥ T0 and n ≥ n0. Because Lemma 3.3 holds true for any T > 0, the proof is complete. █
We are now in a position to derive the limit distribution of the serial correlation coefficient.
Proof of Theorem 2.1. Let α ∈ (0,2]. We show that for any strictly α-stable process Wα,β(t) the integral

is also a strictly α-stable random variable multiplied with α−1/α. The claim is trivial if α = 2, so we assume α ∈ (0,2). Let ξ1,ξ2,… be an independent sequence of strictly α-stable random variables. Then, by (3.10) and (3.11),

The characteristic function of the ξi is φα,β(t) given in (2.2). Therefore, if α ≠ 1, the characteristic function of Zn satisfies

as n → ∞, because clearly sgn(ρn−kt) = sgn(t) and

(Note that, by Taylor expansion, 1 − ρn−α = αcn(1 + o(1)).) A similar argument applies also in the case α = 1.
In Lemmas 3.1 and 3.2 we have identified the leading terms of the two partial sums determining the difference

in (3.6). According to Lemma 3.4, these leading terms jointly converge toward stochastic integrals with respect to (independent) strictly α-stable processes. Hence, the assertion follows from the previous paragraph. █


