Most empirical knowledge on the long-term performance of financial investments is derived from the experience of the most successful markets. Those of the United States – and more broadly Anglo-Saxon countries – have been termed survivor markets.Footnote 2 The United States, in particular, suffered no war on their national territory in more than a century, limited inflation and no true socialism. Anglo-Saxon countries developed modern financial theory and empirical studies earlier, so that their performance influences heavily what we think today about financial markets. Much of the rest of the world was not so fortunate. The Russian stock exchanges and securities, which were thriving before World War I,Footnote 3 disappeared for 70 years. Clearly, the fate of investors in Russian securities from 1917 to 1992 can be understood without portfolio indices. However, Russian stocks and bonds were part of many foreign portfolios (not least French ones) up until the Soviet Revolution, so that any measure of global performance must take them into account. The same is true for other markets such as those of Austria–Hungary or even China. In between happy Americans and poor Russians, most of Western Europe's stock exchanges suffered a chaotic twentieth century, though without complete disruption (Germany being the extreme case because of the 1923 hyperinflation and the post-1945 dismantlement). Recent research has tried to broaden the sample of markets studied to include the European stock exchanges that were most developed up until World War I or even during the interwar period (Brussels, Amsterdam, Paris, Berlin, Milan, etc.), and weigh substantially in today's global portfolio. The synthesis by Dimson, Marsh and Staunton includes data on the twentieth century for 16 countries, and concludes on an optimistic note, although less enthusiastic than most of the literature on the US case.Footnote 4 They show that with the exception of Sweden, Western European exchanges performed worse on average than those of overseas Anglo-Saxon countries (Canada, the US, Australia and South Africa) and the UK.Footnote 5 They attribute the poorer Italian, French, German or Belgian performances to wars, inflation and nationalisations. But their data suggest that even in the worst case – Belgium – the long-term stock market performance remains positive (2.5 per cent yearly real return over the twentieth century), and superior to that of other investments.
In this article, we claim that a more detailed look at the methodology used in constructing stock market indices is required before any valid international comparison. Concentrating on the French case, we show that widely accepted indices built on particular sets of assumptions can seriously mislead empirical finance research. If the theory and practice of indices has long been mastered by economists and statistical institutions (a 1922 book by Irving Fisher being still a major referenceFootnote 6), stock market indices have been built in many countries up until recently with different objectives than the measure of the return for the investor.Footnote 7 The Cowles commission in the 1930s was a pioneer in using indices in order to measure stock market performance from the point of view of an investor.Footnote 8 In spite of this, even the Standard & Poor's index suffers serious flaws.Footnote 9 In France, the only early attempt to build indices in that same perspective, that of the newspaper Agefi in the 1930s, was short lived.
In this article, we propose a new stock index for the French stock market from 1854 to 1998. Our index is the first one built in order to measure variations in French stock prices from the point of view of the investor. We first describe the index's methodology, which is based on Euronext's CAC-40, adapting it slightly to take into account some constraints from historical data. Basically, the index is a monthly weighted index of the 40 most prominent shares among French firms, ranked by market capitalisation. Our index is weighted by market capitalisations, with its composition and weights adjusted yearly to avoid survivor bias. These characteristics, which are standard for today's indices, were frequently absent in older indices, which may explain a significant difference in their outcomes.
A major contribution of this article is to provide new estimates of the long-term returns obtained by holders of such a portfolio of French stocks. We show that the price index (without dividends) didn't protect its investors against inflation. Its real performance was positive up until 1914 (in a period of stable prices), but it was substantially negative for the twentieth century in spite of the rapid growth of stock prices since the 1980s.
When one turns to total return (including the dividend yield, supposedly tax-exempted), the performance was remarkable from 1854 to 1914 (more than 5 per cent annual total return net of inflation), but very low for the twentieth century as a whole. Since 1914, gold has proved to be a better investment than stocks.
These results contrast strongly with those of Arbulu and Gallais-Hamonno, who link the official twentieth-century indices to similarly constructed new indices for the nineteenth century and form the basis for French investment performance in the Dimson, Marsh and Staunton synthesis.Footnote 10 We show that the reason for the divergence rests on the methodology adopted by Arbulu and the official indices, which suffer both survivor bias and weighting problems. In particular, they don't weigh stocks by capitalisation, thus assigning much higher implicit weights to small caps, which leads to a seriously overvalued index in the long run.
Compared to the well-known results for the US, the low equity premium that we observe in France is in line with most models of risk aversion.Footnote 11 We suggest that if our revisionist approach to French indices can be extended to other European markets, the equity premium puzzle may disappear in many of the cases discussed, for example, by Barro, and end up (as some earlier studies have already argued) as a mostly US phenomenon.Footnote 12
Finally, we argue that the evolution of the CAC-40 in the twentieth century can be understood as a result of wars and inflationary periods, suggesting that the impact of major wars on private wealth has been underestimated up until now. The first section presents in detail the methodology of our index. Differences between earlier indices and ours are discussed together with some robustness checks in the next section. We then present the main results and discuss the main changes in policy regimes that may explain the index performance in the long run.
I
The aim of this section is to detail the methodology used to build the new index. In the very long run, even details matter, since any error is magnified by the effect of compounded interest. The index concentrates on stocks of French firms; this is not because French investors held only French stocks (they actually held many foreign ones, especially up until World War IFootnote 13), but because focusing on national securities is the first step generally used before considering the effects of international diversification, which could be measured using various foreign indices.
The procedure we use can be summarised as follows. The prices, dividends and number of shares are collected for all French stocks listed on the Paris official stock exchange for the first Friday of each year. Capitalisations are calculated for that date. We then take the 40 highest capitalisations for inclusion in the index for the following year, with two exceptions: when various securities of the same firm are listed, we only consider stock with the highest capitalisation; we also exclude firms with less than 10,000 shares. For the 40 firms in the index, we gather monthly prices and calculate the market index by weighting these prices by market capitalisations, in order to make it reflect the actual market.Footnote 14
We chose to build a blue chips index because the most important shares it includes are precisely those held by most investors.Footnote 15 Small firms were as a norm heavily dominated by family owners, as in most continental Europe;Footnote 16 their shares were sometimes listed in spite of being closely held because no constraint on minimum free float existed. This led these stocks to be illiquid, which was a major concern for ordinary investors (and led financial advisors to recommend avoiding themFootnote 17). Family control could also lead to agency problems and price manipulation, thus threatening ordinary investors. Furthermore, both low liquidity and price deviations would represent a problem for building an index and its interpretation.Footnote 18 So limiting it to blue chips should help our index to better represent the behaviour of investorsFootnote 19 and to avoid including significant liquidity or risk premia, so that the long-term decline in returns could not be misinterpreted.Footnote 20 These reasons explain the dominance of blue chips indices in financial analysis today.
Our index concentrates on French firms, which are defined by their legal status, not by the place where they have their activity: the Suez and the first Panama canals are French firms; so are French subsidiaries of foreign firms such as Thomson-Houston. We consider for inclusion firms listed on all French exchanges: in practice, almost all blue chips were listed on the official Paris Bourse, but there were a few exceptions, such as some coal mines in northern France that were listed in Lille up to the early 1920s.
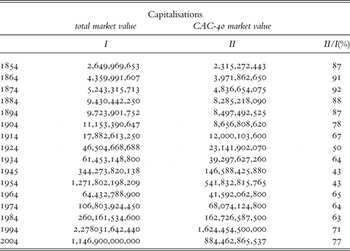
Diversification is usually considered sufficient to eliminate specific risk when the number of stocks in a portfolio reaches 30.Footnote 21 For an index weighted by stock market capitalisations, a somewhat higher number is better. We chose 40 stocks in order to satisfy these requirements and to facilitate the linkage with today's CAC-40, the major Euronext-Paris index. It might be argued that the number of stocks included should increase over time in line with the development of the stock market. Actually, the Paris stock exchange was well developed (for example, in terms of market capitalisation to GDP) quite early, and suffered a decline during the twentieth century from which it recovered only in the last 30 years:Footnote 22 as shown in Table 1, the proportion of our 40 firms in total market capitalisation varied a lot but remained quite high, with only a weak declining trend. These reasons – and the search for simplicity – led us to hold constant the number of firms in our index.
Market capitalisation of the Paris Bourse (I) and that of the 40 firms in our index (II),all in current francs (euros in 2004)

The list of the stocks included in the index is fixed following a stable, simple and transparent formula in order to avoid ex post insight. This requires us to avoid today's practice of choosing the stocks composing the CAC-40 among the 100 biggest capitalisations listed in Euronext-Paris, with the help of a scientific committee that we cannot reinvent for previous periods. We therefore include more simply the 40 stocks with the biggest capitalisations, and we rebalance the portfolio each year at the beginning of the year. Annual rebalancing allows us to eliminate the survivor bias that affects many retrospective studies of stock prices. This is all the more important since a number of major firms failed during the period under study, and should not be excluded.Footnote 23
We added two minor criteria to the capitalisation for the selection of stocks included in the index. The first one is a liquidity criterion: we decided to exclude from the index all firms with less than 10,000 shares. The reasons for this choice can be traced to the functioning of the nineteenth-century Paris Bourse, which sometimes listed stocks without wondering about the potential for an active market.Footnote 24 This was the case for some firms with a very small number of shares, especially insurance companies whose statutes frequently even required the agreement of their board for any stock transaction to be valid. We chose a low number, as 10,000 corresponds to one-fourth of the average number of shares of all the firms listed on the market in 1853, the last year for which the number of firms satisfying the requirements for inclusion in the index is below 40 (which is why we start the index in 1854). In any case, that liquidity constraint only excludes a small number of firms and only during a short period, so that it cannot significantly affect the long-term performance of the index.Footnote 25
Our last criterion is the limitation to one category of stock per firm for inclusion in the index. Firms frequently had various categories of shares, especially in the nineteenth century: preference shares were less widespread than in the US, but the relationship between ordinary and other shares was sometimes similar to that between ordinary and preference shares in the US. For example, actions de jouissance (enjoyment shares) were shares whose nominal value had been reimbursed (something frequent in the period, and even statutory in many firms whose activity depended on terminable concessions from the government, typically in railroads, electricity distribution and other utilities); this gave them no right to the ‘interest’ part of the dividend on ordinary shares (usually 5 per cent of the nominal value), but a right to the ‘superdividend’ above that ‘interest’. Parts de fondateurs (founders' shares) were special shares, which were usually given to the firms' founders and gave them a right to a fixed portion of the total payments of ‘superdividend’ to all other shareholders. Shares with multiple votes became frequent in the 1920s and were prohibited by law at the end of that decade.Footnote 26 Since the rights to dividends of these various shares differ, their prices don't move identically (the prices of founders' shares and enjoyment shares are more volatile). Usually, founders' shares were quite closely held and would not qualify for the previous criteria; enjoyment shares increase in numbers and can become dominant in the long run for some firms.
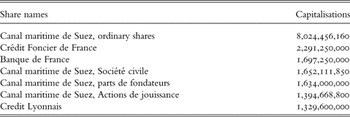
We measure the capitalisation of each category and include in the index only the stock with the highest capitalisation (which proves to be almost invariably ordinary shares). Another solution would be to amalgamate the various categories into a single one or to include all categories satisfying the previous criteria. We decided to follow the described approach for three reasons. Firstly, it is used today by Euronext for the calculation of the CAC-40.Footnote 27 Secondly, the addition of all categories into a single capitalisation would create biases, since the rights on profits of various shares were usually different, as were their risks, justifying differences in prices and in price variations among them. Lastly, our method is likely to reflect the behaviour of investors, who probably, and with good reason, did not consider the holding of different securities in the same firm as useful diversification. In any case, this choice mostly affects a few railway companies' actions de jouissance in the nineteenth century, and the Suez Canal in the interwar period. The year most affected is 1936, in which the activity and share price of the Canal were recovering while the French market suffered overall decline. During that year, not only were the ordinary shares of the Canal the first (by far) capitalisation of the Paris Bourse, but its other shares represented more than the second and the third capitalisations put together (Table 2). Nevertheless, giving the Suez Canal a weight in the index similar to that of all its shares in the capitalisation would probably make the index too dependent on a single firm (at the peak, its ordinary shares represented 22.93 per cent of the CAC, and the total of its shares as much as 32.02 per cent).Footnote 28
First seven capitalisations on the Paris Bourse, the weight of Suez, January 1936

The prices used for the index are all transaction prices. On the Paris stock exchange, prices were set up until 1986 thanks to Walras-style auctioneers, who gathered demands and offers for every stock and determined an equilibrium price (the fixing price) in a centralised manner at a fixed moment in the morning. Other prices could be quoted later in the day if transactions were sufficiently important. We chose to use the last price of the day for our index because some of the periodicals we used only mentioned that price.
The index is calculated using various periodicals, among which the most important is the official list price of the Paris Bourse, the Cote Officielle. We use a few other journals in order to complete data for missing issues, and for the shares that were not traded on the official market but on the unofficial Coulisse Footnote 29 or on provincial exchanges instead. The first step was to collect for the first Friday of every January the name, last price, nominal value, paid value, number of shares and dividends for every share mentioned in our sources (a number which varied from 100 to more than 600 during our periodFootnote 30). This first collection allowed us to calculate the capitalisation of all important listed shares, and then to select the 40 most important ones. The second step consisted in collecting monthly prices for these 40 stocks for the first Friday of each month.Footnote 31
Within each year, our index is calculated using individual stock prices weighted by their capitalisation, from January to January. Monthly returns are calculated as:
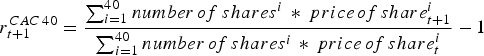
where the numbers of shares are constant within each year.
Components are modified every January, using the new capitalisation data, and each year's index is chained to the next one using January's value as a basis. This index is based on the value of the official CAC-40 index when it was created on 31 December 1987, which was taken as 1000.
Some technical choices were made, which we believe have no lasting impact on the level of the index. First, when a price was missing, the previous listed price was used. This happens rather frequently in the nineteenth century when repeated prices represent almost 16 per cent of the total, compared to only 4.5 per cent after 1914. Nevertheless, the impact should be limited because missing prices concerned mostly the smallest stocks in the sample (they represent only 2.6 per cent of the prices of the biggest capitalisation in the index, compared to 16.4 per cent for the smallest). The ten biggest capitalisations, which weigh 61 per cent of the index on average, have only 3.88 per cent missing prices. Although one may consider these proportions as high, they are standard in historical finance,Footnote 32 and they are actually a major reason for calculating blue chip indices rather than comprehensive ones. Most importantly, we don't think that our choice has any impact on our index's long-term performance.
Regarding our second choice, although the precise date at which dividends are paid have a short-term impact on equity prices payments, we don't adjust prices for that effect. This is because precise payments' dates are frequently not mentioned in our sources, but, most importantly, because our aim is to measure long-term changes in prices, which are certainly not affected. For the same reason, we make no adjustment for capital changes (except for stock splits, for which prices were adjusted) or for firms appearing or disappearing during the year (IPOs, mergers, nationalisations, bankruptcies). Firms appearing during the year and big enough to be admitted in the CAC-40 are included the next January. Firms disappearing are maintained up to the next January with the last price being used for all months to that date (these repeated prices are included in those mentioned above). All these assumptions slightly decrease within-year volatility, but don't affect year-to-year changes in the index (at least as suggested by a check on the 1987–97 period discussed in more detail below). Furthermore, these choices affect a limited number of prices, making it unlikely that the index is significantly modified.
The described methodology was followed to build the pure price index. From the same sources we computed the return from dividends at the beginning of each year, which was then added to the price index in order to obtain an index for total return. In what follows, the term ‘index’ refers always to our pure price index, unless dividends or total returns are explicitly mentioned.
II
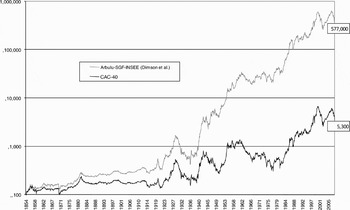
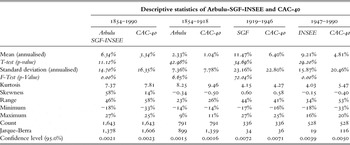
Figure 1 compares our index to the main existing indices which are usually linked to cover the whole period,Footnote 33 and which we jointly call the Arbulu-SGF-INSEE index, with a common basis in 1854 = 108. Table 3 provides evidence that these differences were statistically significant for the periods covered by the three different authors. The discrepancies are enormous, but also surprisingly easy to explain.
Our CAC-40 price index, Arbulu-SGF-INSEE price index. 1854 = 108 basis (allows to join the official CAC-40 at 1,000 in 1988)

Descriptive statistics for our price index and the Arbulu-SGF-INSEE price indices

The Arbulu-SGF-INSEE index links an index built by Arbulu for the 1802-1913 period to those built at the time by Statistique Générale de la France (SGF), the official statistical office, and later by its successor INSEE. This index – or part of it – has been used by all recent studies on the long-run performance of the Paris stock exchange, mostly due to lack of alternatives and because of the inclusion of its most official parts in official publications.Footnote 34
The index built by SGF in the interwar period – as well as those of many other statistical institutions at the time – did not aim to measure the performance of a portfolio of stocks but rather to observe or anticipate fluctuations in macroeconomic activity.Footnote 35 For that reason, it did not focus on long-term level change. In order not to miss any impending crisis or recovery, industry indices included as many firms as possible, all of them on an equal basis since they all could equally signal down- or upturns. The aggregate index was weighted by industry capitalisation but was based on these unweighted industry indices. This method was maintained with little change by INSEE after 1945.Footnote 36 It was also the method used retrospectively by Arbulu.Footnote 37
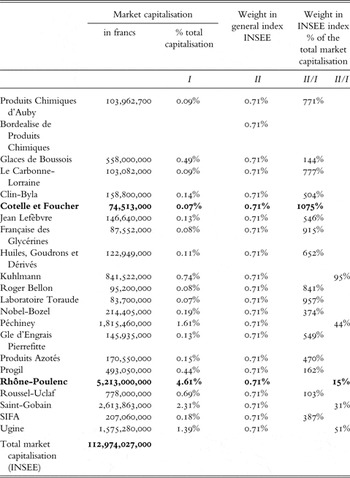
The upward bias stemming from broad unweighted indices can be enormous, as one example will show. In 1963, Rhône-Poulenc was the most important French listed firm, with a market capitalisation of 5.21 billion francs, or 4.6 per cent of a total market capitalisation of 112 billion.Footnote 38 Within our CAC-40 index, Rhône-Poulenc's weight is 10.35 per cent, since the total capitalisation of the 40 first shares is 50 billion. In the SGF-INSEE methodology, Rhône-Poulenc is one among 22 firms in the Produits chimiques, électro-métallurgie et verreries group (mostly chemicals), whose weight is 15.6 per cent in the official index. The impact of Rhône-Poulenc shares is then 15.6/22 or 0.71 per cent, compared to its 10.35 per cent in our index. At the other end of the spectrum, Cotelle et Foucher – Javel La Croix, a chemical firm with a capitalisation of 74 million francs (or 0.066 per cent of the market, 70 times less than Rhône-Poulenc) also weighed 0.71 per cent in the index. Table 4 provides a measure of the discrepancies between weights for the chemical industry in 1963, showing that the overrepresentation of small firms was a general phenomenon, and one that could affect the index enormously. If, as we now know, the performance of smaller firms is on average superior to that of bigger ones, this overrepresentation of small firms creates an upward bias in the index.Footnote 39 For example, if the average difference in performance between firms included in our CAC-40 and the rest is 1 per cent a year, and the CAC-40 includes only a tenth of the firms included in the SGF-INSEE index, that index should outperform the CAC-40 by almost 1 per cent a year.
Actual share in total capitalisation, weight in the INSEE index of stocks included in the ‘chemical’ industry index, and their ratio

Note: All for 1963. Shares over-represented in the INSEE index (II/I >100 per cent) are in column 4, which gives the degree of over-representation. The same for under-representation in column 5.
Other choices also cause substantial biases in the existing index. Arbulu's calculations suffer substantial survivor bias, since he chooses the shares to be included partly on the basis of their stability; more precisely he eliminates all shares which didn't remain listed for at least five years, which makes him omit the Union générale (sixth capitalisation by size in 1882, 5.51 per cent of our CAC-40, failed in 1882) or the Panama canal (ninth capitalisation in 1884, also soon failed), and the substantial downward impact of their failure on contemporary portfolios and attitudes towards stock investment.Footnote 40
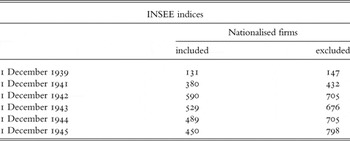
A major flaw of the official indices built by INSEE after SGF is their treatment of nationalisations. Nationalised firms are excluded ex post. They represented an enormous proportion of listed firms and even more of our CAC-40, since they included all the railways in 1937, and all the electricity, gas, coal, bank and insurance industries in 1945. We could not find details on how the SGF calculated the impact of 1936-7 nationalisations. Concerning the 1944-5 nationalisations, which represented 28 per cent of early 1939 CAC-40 capitalisation, the official index excludes the firms concerned from 1939 on,Footnote 41 which leads to a important divergence between that index and one that would include them, as reported by INSEE insiders somewhat laterFootnote 42 (Table 5).
INSEE indices including or excluding firms nationalised in 1944

Source: Laforest and Sallee, ‘Le pouvoir d'achat des actions’.
In our own index, we treat nationalisations using the same rules as for other firms exiting the index. When a firm is nationalised and stops being listed, we retain the last quoted prices for the rest of the year and don't try to introduce non-market prices (such as the compensations paid by the government). The main banks were nationalised by the law of 2 December 1945, with application on 1 January 1946; as a result, there are no missing prices. In the gas and electricity industries, only one firm still belonged to our index in January 1946, in spite of the fact that the nationalisation project was only presented in March 1946. This suggests that the market clearly anticipated these nationalisations, which were mentioned in the programme of the Conseil National de la Résistance of March, 1944. The nationalisation of coal mines was announced on 14 December 1944 (with no details on compensations); their stocks remained listed in 1945, but their prices decreased quickly, so that none belonged to the CAC-40 in January 1945. Finally, no insurance firm was large enough to enter the CAC-40. Nationalised firms then disappeared progressively from the CAC-40 as they disappeared from the portfolios of investors, who turned to other stocks. Our methodology mimics that behaviour just by maintaining its own rules consistently. It is likely that the negative impact of nationalisations on the portfolios of their holders is underestimated since, in some cases, the government blocked the shareholders' investments during a long (highly inflationary) period before they obtained compensation that could be sold and reinvested in other shares, whereas we assume this was done at the end of the year when the last price was quoted. Unsurprisingly, that period is the one with most divergences between our CAC-40 and the official index.
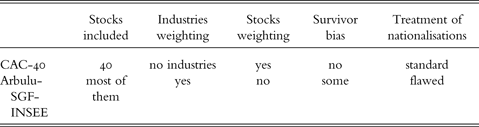
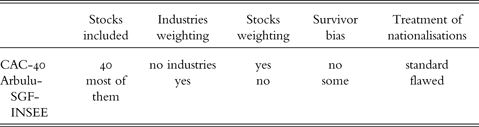
We argue that the latter methodology makes it highly inadequate to measure the actual performance that could be obtained by investors, and that using it for that purpose would lead to a severe overestimation of performance.Footnote 43 We summarise the key methodological differences between our index and the Arbulu-SGF-INSEE index in Table 6.
Summary of the differences between the CAC-40 and the Arbulu-SGF-INSEE index
Of course, simply identifying its built-in biases might not be enough to prove the superior quality of our CAC-40 index, so we carry out further robustness checks.
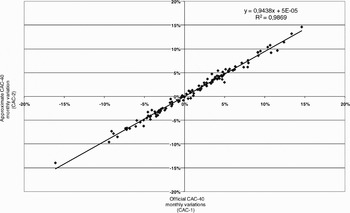
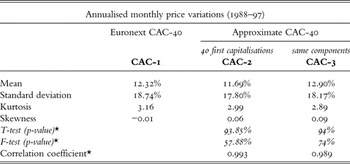
A direct way to validate our own methodology is to compare it to the true CAC-40. We did so for the first decade of its existence (1987-97). Both indices are highly correlated, as can be seen in Figure 2.
Correlation between the monthly price variations of the official and our index methodology, 1988–97

Nevertheless, our own index performs slightly worse than Euronext's (7.5 per cent less growth over 10 years, compared to a global rise of 185 per cent, or a 4 per cent difference). This difference is not significant: tests do not reject the hypothesis of identical means, variances, skewness, kurtosis or distribution.Footnote 44 If it were statistically significant, it would probably result from the choices in Euronext's selection method, which allowed smaller or more dynamic firms to be included, compared to our automatic selection method. In any case, that divergence is small compared to the one we observed between the Arbulu-SGF-INSEE index and our own.
We also use this period to distinguish the consequences of our selection method (strictly 40 first capitalisations) and our simplifying assumptions (rebalancing of the selection only once a year, no treatment within the year of mergers, nationalisation or failure, little correction for some capital modifications). For that purpose, we calculate another index, CAC-3, which is composed as the authentic one at the start of each year, but not recomposed during the year, and to which we apply our simplifying assumptions.
Table 7 shows that – contrary to our index – this index performs better than the authentic CAC-40, suggesting that sample selection is the major cause of the negative difference between our index and the official one, and that our simplifying technical assumptions per se would more probably bias the index upward – if there is a bias. This would then mainly reinforce our conclusions.
Comparison of Euronext's CAC-40 (CAC-1), our index (CAC-2) and an index using the official CAC composition in each January but without the within-year adjustments (CAC-3)

* compared with Euronext CAC-40.
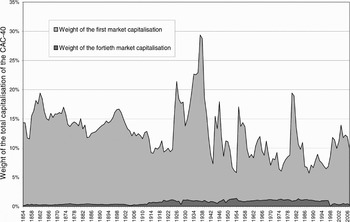
The official CAC-40 also includes an assumption that we did not apply to our historical reconstruction: it imposes a 15 per cent maximum on the weight of any stock. Our historical data (Figure 3) show that the share of the biggest firm (even when restricted to its most important share, as described above) varies heavily, and that this 15 per cent ceiling was bypassed in 21 years of our sample. But recalculating our index with a 15 per cent ceiling showed no significant impact. Since such an assumption has little theoretical support, we preferred to retain our unlimited index.
Shares of the biggest and smallest capitalisations in our CAC-40

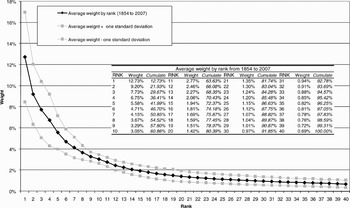
Another robustness check considers the impact of the number of stocks included in the index. As we explained above, we chose a blue chips index in order to mimic the behaviour of most investors and to maximise the data quality. We chose 40 stocks for continuity with today's CAC-40 and because we considered 40 as a sufficient number for diversification purposes. Somewhat higher numbers would also be consistent with this rationale, but not necessary; broadening the index to 50 stocks would not change much, in any case, because the marginal stocks have very small capitalisations compared to the first 40. Figure 4 shows that the weight of the last 10 stocks included in the CAC-40 is 8 per cent on average between 1854 and 2006, the weight of the fortieth one being 0.69 per cent on average. Adding a few more stocks would probably have little effect on the index. Admittedly, a constant number of stocks in the index implies a varying weight of the CAC-40 firms within total market capitalisation of Paris-listed stocks, but as we mentioned earlier, this variation has no trend. We consider this is not as important an issue as the standard diversification behaviour of investors.
Average weight of the firms in the CAC-40 ordered by weight

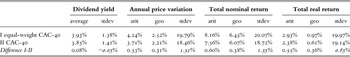
A last robustness check is provided by the calculation of an equally weighted index based on the same sample as ours. Unsurprisingly, the performance of the equally weighted index, which overweights the (relatively) small firms in the index, is better than that of our capitalisation-weighted index (Table 8). This confirms the importance of a strict selection method and of the frequent adjustments in sample and weights.
Differences between equal-weight and market cap weight CAC-40 (1854–1997)

III
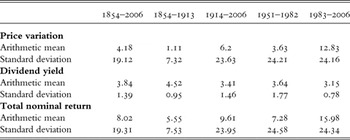
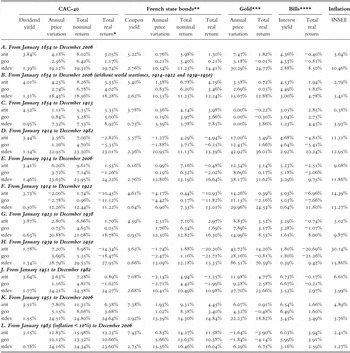
We now turn to the nominal performance of our index. Table 9 summarises the price variations, dividend yields and total nominal return of the CAC-40 from 1854 to 2006 and for various subperiods (the choice of which we explain below). Over the whole period, total nominal return was 8.02 per cent (arithmetic mean), of which the dividend yield represented 3.84 per cent per year, almost as much as capital gains – price variations in the index – which attained 4.18 per cent per year on average. If we exclude the 1914-50 ‘wars’ period for the moment, total nominal return increased from 5.55 per cent before 1914 to 7.28 per cent from 1951 to 1982 and a record 15.98 per cent from 1983 to 2006.
Major characteristics of the CAC-40 either returns (distinguishing price variation and dividend yield) for various periods (in percentage)

Over the period, the relative contributions of dividends and capital gains varied substantially. Their relative volatilities were also very different. Capital gains almost permanently increased, from a very low level of 1.11 per cent per year before 1914 to 2.8 per cent in the interwar period, 3.63 per cent from 1951 to 1982 and 12.83 per cent in the recent 1983-2006 period. It is not surprising, then, that dividends represented a decreasing proportion of total return. While dividend yields averaged 4.52 per cent before World War 1 (more than 80 per cent of total return), they decreased to 3.87 per cent in the interwar period, 3.64 per cent from 1951 to 1982 and 3.15 per cent from 1983 to 2006.
Unsurprisingly, prices were much more volatile than dividends, with respective standard deviations of 19.12 per cent and 1.39 per cent for the whole period. The volatility of the pure-price index increased from a low 7.32 per cent before 1914 to 20.88 per cent in the interwar period and around 24 per cent after 1950.
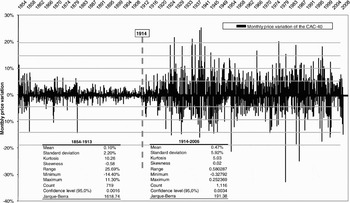
World War 1 appears as a break in volatility series (Figure 5). After a long period of decreasing volatility from 1854 to 1914, it increased sharply and remained high throughout the twentieth century. On average, standard deviation almost tripled from the nineteenth century to the twentieth. A chi-squared test comparing the distribution of monthly variations for 1854-1913 and the same number of months after 1914 clearly rejects the hypothesis of identical distributions.Footnote 45 This much higher volatility could be interpreted as the sign of a high inflation risk, although its persistence in the most recent period suggests that another explanation may be necessary.
Monthly price variation of the CAC-40 index, 1854–2006

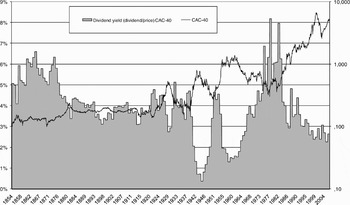
The volatility of dividends was much lower and more stable, with a standard deviation below 2 per cent during all subperiods. Actually, dividend smoothing was probably a standard practice in the short run, as can be seen in Figure 6, where most of the short-run changes in dividend yield can be accounted for by variations in stock prices rather than by autonomous changes in dividends.
Dividend yield for CAC-40 firms

Overall, the decreasing importance of dividends is consistent with the change of dividend behaviour that has been documented in various countries for the period around World War I. It can be interpreted as a tax optimisation choice, since in many countries (including France) the taxation of dividends increased substantially during that period compared to that of capital gains. It can also result from changes in corporate governance and investment strategies, especially the emergence of modern corporations in which shareholders were marginalised by managers and profits were increasingly reinvested.Footnote 46
Up to now, our results are more or less in line with the standard history of stock prices, in which the most significant changes are the acceleration of capital gains and the relative decrease of dividends in the twentieth century, in relation to the emergence of general inflation in that period. What is most specific to France is the real performance, once inflation is taken into account.
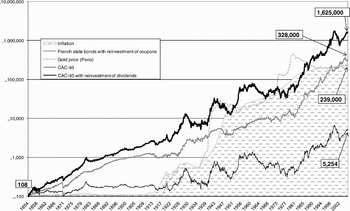
The real long-term performance of the CAC-40 index (without dividends) was significantly negative from 1854 to 2006: with on average a 4.18 per cent increase, the CAC-40 was far from the average inflation of 5.64 per cent (see Figure 7 and Table 10, section A). Real returns actually reflect mostly the impact of inflation: they were slightly positive (0.7 per cent per year) before 1914, negative from 1914 to 1982 (-7.4 per cent per year) and again positive since 1983 (10.42 per cent on average).
Long-term performance of investment strategies in various French assets

Returns for investments in various French assets for 1854 to 2006 and various subperiods

arit: arithmetic mean; geo: geometric mean; stdev: standard deviation.
* An F-test between stocks and bonds (total nominal return) can reject an equal variance for all periods, whereas a T-test can not reject (5% level) an equal mean for F,G,J,K,L.
** Rente 3%, 5% after 1950 and after 1970, taux obligations Etat à long terme (Caisse des Dépôts et Consignations).
*** Gold price in Paris, annual interpolated (Banque de France and INSEE).
**** Before 1951: discount rate open market Paris, monthly data (NBER).
Annual data interpolated, Banque de France's taux de l'escompte (INSEE) only before 1863, 1914–1925, 1940–1951.
1952–2008: taux moyen du marché monétaire, monthly data (Banque de France).
To our knowledge, a negative return for such a long period is unique to the French market. One may wonder whether the problems lie in the consumer price indices we used. We don't think so, for a number of reasons. Firstly, since the late nineteenth century French price indices have been developed by high-quality and up-to-date statisticians involved in international methodological discussions, so there is no reason for French indices to be more upward-biased than those of other countries.Footnote 47 Secondly, contrary to stock market indices, they have been checked for consistency with other macroeconomic variables for decades.Footnote 48 Thirdly, biases could also be downward, since underestimates during periods of price controls (wars in particular, but for some products in France up to the 1980s) may not have been corrected in the later periods. Fourthly, the underestimation of quality changes, which is the most-argued reason for upward biases in consumer price indices, is likely to be more important in low-inflation and service-dominated economies such as the French one in the recent period, precisely the only one during which the real performances of the stock market are high.
One may argue that a correct measure must include the reinvestment of dividends to appreciate the total return. On that account, the average total real return from 1854 to 2006 was only 3.05 per cent, far from the 8.3 per cent observed for US stocks.Footnote 49 Furthermore, this performance was not constant over time. A clear regime change appeared with World War I. From 1854 to 1913, the CAC-40 holder who reinvested all his dividends earned a 5.39 per cent yearly real total return, slightly below the 5.58 per cent nominal one, when from 1914 to 2006, the nominal total return increased to 9.61 per cent, but real total return decreased to 1.53 per cent (and a negative –1.26 per cent in geometric mean). These period-to-period changes are all statistically highly significant, and the radical departure from nineteenth-century metallic standards and price stability with the start of World War I makes it unnecessary to use technical tools to identify the watershed date. One must conclude that investment in French equities just protected wealth against inflation during that period, even when reinvesting all dividends, something which has been observed in other countries, but never for such a long period.Footnote 50
The literature has already highlighted the negative impact of wars on the returns on equity investments,Footnote 51 but has never found it as important and long lasting as we do. In order to distinguish the immediate impact of the wars from more lasting impact on returns, sections F and H of Table 10 measure the impact of both wars, including in the ‘war period’ the years until GDP returned to its pre-war level (1922 after World War I, 1950 after World War II). The total yearly returns of the CAC-40 during these two war periods are particularly bad, below –10 per cent in both cases in real terms, in particular because of high average inflation rates (during World War II dividends were legally capped, which may have contributed to low returns). A broader view, in line with the characterisation (by no less than Winston Churchill) of the whole 1914-45 period as the ‘Second Thirty Years War’,Footnote 52 suggests that we consider the entire 1914-50 period as one of war and reconstruction, in which low returns were the price paid by wealth owners for the destruction and costs of the wars. That perspective fits well with our data, which show that the annual real total return of the CAC-40 was hardly positive during the 1923-39 period (a consequence of some remaining inflation in the mid 1920s, of the Great Depression, and of renewed inflation in the run-up to the war from 1936 onward).
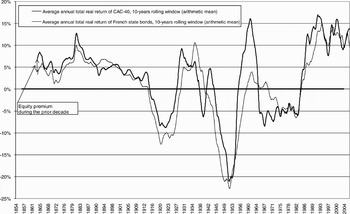
We could then consider that the ‘normal period’ only resumed in 1951. Does this period represent a comeback to the sort of performances the French financial market provided before World War I? The answer to that question is not straightforward, as can be inferred from Figure 8. On the one hand, the 1951-2006 period considered as a whole presents very similar returns to those of the pre-1914 period (6.38 per cent yearly real total return between 1951 and 2006, compared to 5.39 per cent; see Table 10), even if volatility remains much higher (24.64 per cent compared to 8.86 per cent before 1914 for standard deviation of real returns). On the other hand, this period is quite heterogeneous according to many criteria.
Average total real return of CAC-40 and French government bonds (10 years rolling window)

A first criterion – a major one for our subject – is inflation. If one wonders when the long inflationary experience that started in 1914 ended, two dates stand out as worth investigating. The first is 1958, when France established a new Republic, adopted a convertible currency under the Bretton-Woods system and implemented the stabilisation policy that was considered necessary in order to do so (the Pinay-Rueff plan). The decade from 1959 was actually one of stable prices and a stable French currency anchored on the gold standard. But it may be considered a parenthesis, since inflation again rose above 5 per cent a year as soon as 1969. The second possible regime change is the ‘tournant de la rigueur’ (move to a policy of ‘austerity’) under President Mitterrand, when Keynesian macroeconomic policies were abandoned and monetary stabilisation made a priority (a move dated either from the second devaluation of June 1982 or, more frequently, from March 1983). From 1983 on, the inflation rate remained below 10 per cent by year. And the average inflation rate, which was as high as 15 per cent during the ‘Second Thirty Years War’, and still 6.5 per cent from 1950 to 1982, fell to only 2.5 per cent after 1983. This suggests that 1983 was the actual end of the long inflation episode.
Another reason for considering the 1983 change as important can be seen in Figures 1 and 8: the 1958 stabilisation actually does not correspond to any marked change in the CAC-40, which was increasing up until 1955 and started decreasing from 1962 until it reached three minimum values in August 1967 (468 points), February 1978 (307 points) and July 1981 (370 points). However, a clear switch to a period of sharply rising stock prices can be observed in 1983. We then give in Table 10 (sections J, K, B and L) the values for long-term performances for the 1951-82 period as well as for the 1951-2006 period, and for 1854-1913 and 1983-2006 for comparison. The real performance of the CAC-40 changed from approximately 5 per cent per year before 1914 to null or slightly negative from 1951 to 1982, and to a positive 10.6 per cent from 1983 to 2006. That glorious final period brings the average yearly real returns during the second half of the twentieth century to levels above those of the late nineteenth century.
Then, we may consider that the major reason for the low performance of the CAC-40 index in the twentieth century is the succession of two world wars in the first half of the century. If we exclude these periods (as in section B of Table 10) the CAC-40 performs reasonably well over the very long run, although not as well as the US stock market. This is also true if we consider only the second half of the twentieth century. Nevertheless, it remains intriguing that this period includes two such different subperiods. This suggests that not only the world wars, but maybe also policy regime changes may have a role in explaining the long-term performances of the Paris stock market.
In summary, when the nineteenth century appears as a normal and comprehensible period from the point of view of contemporary stock markets, the twentieth century proves more difficult to assess. Two different accounts of the twentieth century are possible. The first considers the long war period as the only reason for low stock returns, and insists on the normal level of equity returns over the very long term after 1950. The other, consistent with the ‘short twentieth century’ (here 1914-82) view,Footnote 53 considers that the period of exceptionally low real returns stopped only in 1983, a moment at which those who owned (or bought) stocks benefited from an exceptional increase in prices and returns, lasting up until recently. That view also claims that the recent period (since 1983) does not appear as a return to the nineteenth century: not only are overall real returns higher (which may result mostly from a shorter period, which incorporates little bear market), but volatility remains very high (actually slightly higher than in the ‘short twentieth century’) and dividends remain low.
IV
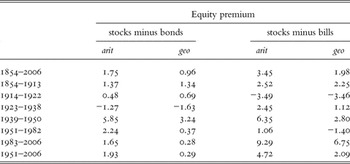
A well-known result of US long-term investment is the equity premium puzzle: in the long run, equities perform not only better than other investments, but the return they provide is higher than what their higher volatility requires as a compensation for risk. Although no explanation for this fact has found widespread acceptance, it has provoked much discussion; its validity outside the US still requires detailed scrutiny using high-quality data. In the French case, an equity premium also exists for the whole of our long period, but it remains low. Stocks are the best investment despite long periods of negative real returns since bonds and the money market perform even worse. As shown in Table 11, the equity premium compared to bonds was 1.75 per cent on average from 1854 to 2006, and was below 2.5 per cent during all subperiods except World War II and the most recent period.
Equity premium compared to bonds or bills for various periods (in percentage)

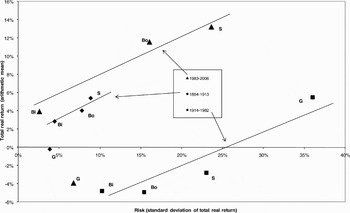
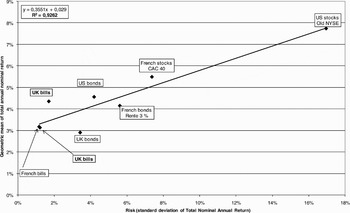
This level of equity premium seems more consistent with standard financial theory than the levels found in the US. Figure 9 draws a risk line for the French financial market for various subperiods and Table 10 gives detailed data for all periods. Although the evidence is indicative rather than conclusive, given the limited number of separate points included, Figure 9 suggests that returns were to some extent related to risks, with no excessive risk premium for equities.
Risk–return line for the French financial market, over three periods

Two points are striking. One is that the risk line moved a lot during the 1914-82 period, compared to its position for the previous and subsequent periods. The second is the high risk and high return for investments in gold precisely from 1914 to 1982. In a period of unstable monetary regime, during which France was on the verge of hyperinflation at least once (at the end of World War II), gold became a valeur refuge that was highly priced by French investors.Footnote 54 Holding gold allowed one to escape both taxation and monetary confiscation, and provided sufficient liquidity despite the legal risks. In particular, gold was internationally valued and then provided for international diversification when it was forbidden by exchange controls. This was not an absurd behaviour, as has frequently been argued, since gold obtained the highest average return during that period despite paying no income. From the position of gold on the risk line, we can argue that an optimal French portfolio in keeping with the Markowitz definition should have included a significant proportion of gold from 1914 to 1982. This suggests that French investors were rational in investing so much in gold, even if it may have been costly in terms of lost economic growth. On the other hand, gold was an underperforming asset during periods of stable prices, even if recent events suggest it can still protect against some risks.
In summary, when stocks dominate gold (in stable periods) they also dominate bonds, while when gold beats stocks (in inflationary periods) it also beats bonds. Then, the issue for French investors was not one of choosing over financial instruments but whether to invest in the (French) financial market or not.
Investments in real estate may have been even better than gold. Existing data suggest not only that the return on a flat bought and rented out in Paris was approximately as high as the return on gold, but also that the risk was much lower.Footnote 55 This may explain why real estate investment was so much favoured by the French as a protection against inflation. Nevertheless, these high performances may also result from a simple liquidity premium and a survivor bias, since the success of Paris as a major international city cannot be compared to that of many other French towns, not to mention rural areas whose population fell during the period. It may well be that although the owners of Parisian flats did well by renting and reselling them (with a negative period of rent constraint mostly limited to 1914-50), the result cannot be extended to other real-estate investments.
Our data also look consistent with the performances of other markets: the risk line for 1854-1913 drawn on Figure 10 suggests that returns in France were consistent with those for various financial assets on other markets. Jorion and Goetzmann suggested that the equity premium in the US may be the result of a survivor bias at the level of the American market as a whole, compared to the global stock market, and that the US actually diverged from most European countries after 1914, since they were much less affected by the two world wars.Footnote 56 Our data suggest that the US market performance was already very high before 1914, but also that this was the normal price to be paid to those willing to participate in such a risky market compared to the French one,Footnote 57 making its holding consistent with an optimal international allocation of capital.Footnote 58
International risk–return line, 1854–1913

The poor performance of the French stock index for the ‘short twentieth century’ might also result from inefficient pricing or from exogenous shocks on the French economy. We show below that the behaviour of the index cannot be separated from the long decline in financial markets in twentieth century France, itself a by-product of its economic and political history.
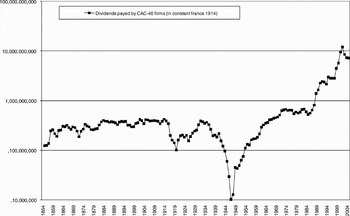
In fact we argue that the trajectory of the CAC-40 must be related to unique structural changes in the French financial market during the twentieth century. The first one is the impact of wars. This is visible in the evolution of dividend payments (Figure 11), which fell after World War I and even more after World War II (beyond the cap imposed during the war). It resulted partly from the negative impact of the wars on profits, and partly from inflation, which made nominal profits and dividends appear higher than their true level, and exposed them to high taxes. In the case of public utilities subject to government price regulation, inflation frequently led to price caps and to a reduction in profits.Footnote 59 As already mentioned, the decrease in dividend yields may have resulted from an adaptation of firms to the rise in corporate and personal income taxes, a rise which was very sharp during and after World War I and was followed by a gradual decrease that only really started in 1960.Footnote 60 The 1914 level of overall dividend payments by the CAC-40 firms was not surpassed until 1968.
Dividends paid by CAC-40 firms, 1854–2006

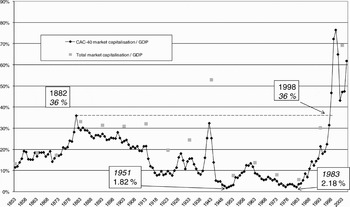
The main explanation for this is not an overall stagnation of the economy or even of profits. It is the government interference in many firms, and especially the nationalisation of many of the biggest corporations. The nationalised firms were certainly not always as profitable as they had been previously, as in the case of the railways, whose profits had been stagnating for years (partly because of regulation). Nevertheless, the nationalisation of the arms industry and the railways (1937), and after World War II that of the electricity, coal, gas, insurance and banking industries (including the Bank of France), deprived the stock markets of many of their biggest listed securities. The last (short-lived) case was the 1982 nationalisation of major industrial firms (Thomson, Saint-Gobain, Rhône-Poulenc, Pechiney-Ugine-Kuhlman, Usinor) and the remaining big banks (Indosuez, Paribas, CIC, Crédit du Nord, CCF, Rothschild). This explains the evolution of the ratio of CAC-40 firms (and of total capitalisation) to GDP (Figure 12).
Ratio of the capitalisation of CAC-40 firms and the total capitalisation of French listed firms to GDP

In 1983, the ratio of CAC-40 capitalisation to GDP was at its historic minimum.Footnote 61 It rose sharply in the next two decades thanks to two radical moves: the privatisation of almost all the government-owned manufacturing, financial and utilities firms, and the rise in the stock index. This rise was also largely the result of the regime change of 1983, by which the French government allowed the financial market to play a major role in the economy again. A substantial rise in profits, which was a condition for French firms to attract investors, followed, and French stock prices became well integrated with international markets (especially after the suppression of the last exchange controls in 1986). From 1983 onwards, then, the stock index again provides a measure that is relevant for the study of the French economy. This is confirmed by a simple measure: the most important sudden (month-to-month) variations in the CAC-40 during our period (those above 3 standard deviations from the mean) correspond almost exclusively to political events during the ‘short twentieth century’, but almost never during the periods before 1914 or after 1983. From that last date, international financial crises replaced political news as the most influential factor on the stock market. Our data then confirms the intuition by Goetzmann that international and national politics can have a long-lasting impact on stock market performances.Footnote 62
V
We have proposed here a new index of French stock prices. Compared to previous indices, ours is much more consistent with modern stock index methodologies that aim to measure portfolio performances for the investor. Because they had different objectives, previous indices dramatically overestimated the return in stock prices. Adequately measured stock returns, as in our CAC-40, present a radical regime change in 1914: because of a combination of the war's impact on profits and assets, of war inflation and of the rise of taxation (the impact of which was multiplied by inflation, since it was applied to nominal incomes), stock prices decreased sharply in real terms. The same phenomenon occurred during World War II. In between, the stock market caught up a little, just to be hit by the Great Depression. Soon, nationalisation affected a large proportion of listed firms, so that the size of the stock market decreased sharply. Up until the next regime change, the stock index performed badly. At the same time, by and large, the economic function of the stock market was restricted to a small proportion of the French economy, in which most large corporations were state-owned. This was reversed in the 1980s, which explains the recent rise in the size of the stock market.
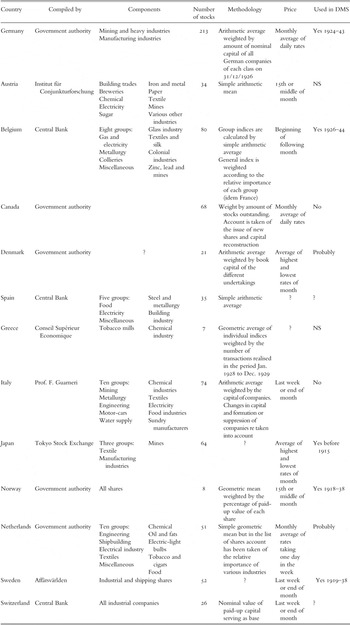
We consider this interpretation more consistent than the one according to which stock prices have risen in France almost as if no significant event had affected the country in the twentieth century. More importantly, we wonder whether the same story – or a variation on it – may apply to many other European countries since the same destructive wars provided similar experiences of financial repression, taxation and inflation throughout Europe. Actually, the same methodological problems we have mentioned affected at least some foreign indices during some periods. For example, during the interwar period, most of them included only manufacturing firms, excluding financial services and utilities which weigh heavily in actual portfolios. In many cases, indices were also built without weighting by market capitalisation (either without weighting or weighting by nominal capital, book value or transaction volumes). At least in some cases, these indices are still in use today when one looks at these periods (Table 12). As we have seen in the French case, this may mean that the performances of investment in some stock markets have been grossly overestimated.
Methodology of the stock market indices published by the League of Nations

Note: This table summarises the main elements of the methods of the indices published under the title ‘Indices of market value of industrial shares’ by the League of Nations in its Statistical Yearbooks (the information here comes from the 1938 edition, p. 249) in order to compare the evolutions of stock markets during the interwar period. In the last column, we tried to document whether these indices have been used, directly or indirectly, in Dimson et al., Triumph of the Optimists.
More broadly, optimistic assessments of the long-term performances of stock investment must be tempered: equities clearly provided a better return than other financial assets in the very long run in France as elsewhere. However, the frequent extrapolation from Siegel's results on the US market to the existence of a ‘Siegel's constant’ of 6 to 7 per cent yearly total real return for such investments must be mitigated.Footnote 63 Equities provided no mysterious premium in France. The total real return on the CAC-40 varied from –18 per cent to 13 per cent, depending on the period, with an average of only 1.17 per cent for the whole 1854-2006 period and, more comparably, of 5.5 per cent if one excludes the world wars. Even after World War II, returns were negligible for a long time, up to the 1983 regime change. Policies hostile to stock markets, affecting their role in economic development, also affected the return on equities. If equities protected investors reasonably well against inflation outside the war periods, they protected them only modestly against political risks; this was true not only in the short but also in the long term. In the very long run, equities may still have been the best investment, but this was not the case for all generations of investors. If the 1914 to 1982 period was a parenthesis, it was a long one, and one that provides us with non-negligible experience; an experience which may also explain common elements in the attitude towards financial markets among the European countries that experienced it.
Appendix 1. Sources for the index
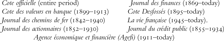
Appendix 2. Yearly values of our CAC-40 price index and total return index