1. Introduction
In the time of low interest rates, investors seek for other sources of income, e.g. dividend payments. Indeed, a dividend is a payout that a company can make to its stockholders. Since the dividends typically reflect the company’s earnings, the return on investment can exceed the riskless yields available on the market considerably.
Usually, investors seek to diversify their risks and invest in companies abroad. On the other hand, large companies expand to other countries and offer their shareholders the possibility to payout the dividends in the local currency. This exposes investors to the additional risk of currency fluctuations.
In order to show how an investor can be affected by exchange rate movements, let us consider the following example. BP plc is one of the world’s biggest oil and gas companies, and therefore one of the most popular companies to invest in. On the company’s website (www.bp.com) one finds the following information: “BP declares the dividend in US dollars. BP ordinary shareholders will receive the dividend in sterling and the amount they receive each quarter may vary as a result of changing foreign exchange rates”. Since December 2014, the quarterly dividend payments of BP for ordinary shareholders equals $0.10/share. However, the actual payments in pound sterling amounted, e.g., to £0.066342 on 18 December 2015 and to £0.063769 on 19 December 2014 (confer www.bp.com/content/dam/bp/pdf/investors/bp-cash-dividends-ordinary-shareholders.pdf). An increase of more than 4% is due to the strengthening of the American dollar.
And vice versa, if the company’s earnings/dividends are growing or at least not decreasing but its domestic currency (in our case pound sterling) increases versus dollar, the dividend payments become less worthy than in the United States. For instance, in 2009 the quarterly dividend payments of BP for ordinary shareholders equalled $0.14/share (confer www.nasdaq.com/symbol/bp/dividend-history), which corresponded to £0.09584 on 8 June 2009 and to £0.08503 on 8 September 2009, showing a decrease of more than 11% just within a 3-month period.
To mention an example from the insurance/reinsurance industry, Swiss Re declares its regular dividend, paid annually, in CHF. That is, the dividend income of an investor from EU would depend on the exchange rate CHF/EU like described above.
The dividend maximisation problem with different constraints has a long history. Shreve et al. (Reference Shreve, Lehoczky and Gaver1984) maximised the expected discounted dividends up to ruin minus some penalty for a general diffusion process as a surplus process of the considered insurance entity. Asmussen & Taksar (Reference Asmussen and Taksar1997) found an explicit solution for a Brownian motion with drift as a surplus. Hubalek & Schachermayer (Reference Hubalek and Schachermayer2004) looked at the problem under a utility function applied on the dividend rates, Grandits et al. (Reference Grandits, Hubalek, Schachermayer and Zigo2007) maximised the expected utility of the present value of dividends. Since this paper is not supposed to be a survey on the topic, we refer, e.g., to Albrecher & Thonhauser (Reference Albrecher and Thonhauser2009) or to Schmidli (Reference Schmidli2008) and references therein.
Consider now an insurance company seeking to maximise the expected discounted dividends, whereas the dividends are declared or paid in a foreign currency. The surplus of the considered company is assumed to follow a Brownian motion with drift, and the factor describing the currency fluctuations is given by a geometric Lévy process, which is the basic set-up for practical applications (confer, for instance, Brigo & Mercurio, Reference Brigo and Mercurio2006: 452). It is assumed that the preference rate of the considered economic agent in the domestic market is given by a real constant. It turns out that the problem can be simplified to a dividend maximisation problem under a related preference rate in the foreign market. Here, we find that the strategic decisions should be taken under the foreign currency. We consider the cases where the dividend payments are restricted or unrestricted and also allow for dependency between the surplus process and currency movements.
To the best of our knowledge, the problem of dividend maximisation if the dividends are paid in a foreign currency has not been considered before. Usually, one assumes that the discounting/preference rate is a positive deterministic constant. In Eisenberg (Reference Eisenberg2015), the dividends were maximised under the assumption of a geometric Brownian motion as a discounting factor. Since a Brownian motion is a Lévy process, the model considered in the present manuscript is a generalisation of the one considered in Eisenberg (Reference Eisenberg2015). Similar to Eisenberg (Reference Eisenberg2015), we are able to calculate the value function and the optimal strategy explicitly. The results are illustrated by examples.
2. The Value Function and the Optimal Strategy
Consider an insurance company whose surplus is given by a Brownian motion with drift X t =x+μt+σW t , where {W t } is a standard Brownian motion, μ, σ>0 and x>0 the initial capital. The insurance company is allowed to payout dividends at any amount up to the current surplus at any time, where the accumulated dividends until t are given by D t , yielding for the ex-dividend surplus X D :
 $$X_{t}^{{\bf D}} \,{\rm {\equals}}\,x{\plus}\mu t{\rm {\plus}}\sigma W_{t} {\minus}{\bf D}_{t} $$
The consideration will be stopped at the ruin time of X
D
, i.e., at time τ
D
: =inf{t≥0: X
D
(t)=0}. We merely assume that the underlying filtration
 $\{ {\cal F}_{t} \} $
is complete, right-continuous and that W is an
 ${\cal F}{\rm {\minus}Brownian}$
motion. In this paper, we consider two sets of admissible dividend strategies. At first, we allow just for dividend strategies
 ${\bf D}_{t} \,{\rm {\equals}}\,{\int}_0^t {u_{s} \:ds} $
with u progressively measurable and 0≤u
t
≤ξ for some boundary ξ>0. Moreover, we denote the class of those dividend strategies by
 ${\cal A}_{r} $
and we sometimes write D={u
t
} to indicate that
 ${\bf D}_{t} \,{\rm {\equals}}\,{\int}_0^t {u_{s} \:ds} $
. Later, we allow for unrestricted dividend pays at any time, i.e., D is allowed to be any right-continuous increasing and adapted process with ΔD
t
≤X
t
−D
t− and we denote the class of those processes by
 ${\cal A}_{u} $
.
As a risk measure, we consider the value of expected discounted dividends, where the dividends are discounted by a constant preference rate
 $$\delta \in{\Bbb R}$$
, i.e., the discounting factor is given by e
−δt
for t≥0 in the domestic market. Since we assume that the considered insurance company generates its income in a foreign currency but pays dividends in its home currency we need to model the exchange rate as well. The price of one unit of the foreign currency is modelled by a geometric Lévy process, i.e., the exponential of a Lévy process L starting in some level
 $l\in{\Bbb R}$
(cf. Sato, Reference Sato1999). As usual we assume that L is an
 $${\cal F}{\rm {\minus}L}\'{e} {\rm vy}$$
process. Moreover, for the moment we assume that the Lévy process L is independent of the Brownian motion W driving the surplus process X; for dependencies confer further Remark 2.5. We define the return function corresponding to some admissible strategy D={u
t
} to be
 $$V^{{\bf D}} {\rm (}l{\rm ,}\,x{\rm )\,\colon\,{\equals}}\,{\Bbb E}\left[ {{\int}_0^{\tau ^{{\bf D}} } {e^{{{\minus}\delta t{\minus}L_{t} }} u_{t} \:dt} } \right]$$
for
 $(l,\,x)\in{\Bbb R}{\times}{\Bbb R}_{{\plus}}\!$
. Since an investor seeks to maximise the return he tries to find an admissible strategy D* such that
 $$V^{{{\bf D}^{\asterisk}}} (l,\,x){\equals}\mathop {{\rm sup}}\limits_{{\bf D}\in{\cal A}_{r} } \,V^{{\bf D}} (l,\,x)$$
Note that for an arbitrary strategy
 ${\bf D}\in{\cal A}_{r} $
we have
 $$V^{{\bf D}} {\rm (}l,\,x{\rm )}\,{\equals}\,{\Bbb E}\left[ {{\int}_0^{\tau ^{{\bf D}} } {e^{{{\minus}\delta t{\minus}L_{t} }} u_{t} \:dt} } \right]\,{\equals}\,e^{{{\minus}l}} {\Bbb E}\left[ {{\int}_0^{\tau ^{{\bf D}} } {e^{{{\minus}\delta t{\minus}{\rm (}L_{t} {\minus}l)}} u_{t} \:dt} } \right]\,{\equals}\,e^{{{\minus}l}} V^{{\bf D}} (0,\,x)$$
which greatly simplifies the dependency on the current level
 $l\in{\Bbb R}$
of the log-exchange rate.
Let us introduce some further notation, namely, let (A, ν, γ) be the Lévy–Khintchine triplet associated with the Lévy process L (cf. Sato, Reference Sato1999, definition 8.2). We also define an artificial preference rate
 $$\beta \,\colon\,{\equals}\,\delta {\minus}{A \over 2}{\minus}\mathop{\int}_{\Bbb R} (e^{{{\minus}h}} {\minus}1{\plus}h1_{{\{ \,\mid\,h\,\mid\,\leq 1\} }} )\nu (dh){\plus}\gamma $$
in case that
 ${\int}_{{\minus}\infty}^{{\minus}1} {e^{{{\minus}x}} v(dx)\,\lt\,\infty} $
and β :=−∞ otherwise. Note that the control problem (1) is well posed if and only if β>0. Indeed, assume −∞<β≤0, choose
 $\widetilde{{\bf D}}\,{\equals}\,\left\{ {{\mu \over 2}} \right\}$
and denote by
 $\tau {{\widetilde^{{\bf D}}}} $
the ruin time of the surplus process
 $X_{t}{{\widetilde^{{\bf D}}}} $
under the dividend strategy
 $\widetilde{{\bf D}}$
. Then (confer, for instance, Borodin & Salminen, Reference Borodin and Salminen1998: 295), one has
 $${\Bbb P}\left[ {\tau {{\widetilde^{{\bf D}}}} \,{\equals}\,\infty} \right]{\equals}1{\minus}e^{{{\minus}\mu x\,/\,\sigma ^{2} }} $$
, implying for x>0
 $$V(x)\geq V{{\widetilde^{{\bf D}}}} (x){\equals}{\mu \over 2}{\Bbb E}\left[ {{\int}_0^{\tau {{\widetilde^{{\bf D}}}} } e^{{{\minus}\beta t}} \,dt} \right]\,{\equals}\,\infty$$
which shows that the control problem (1) is not well posed if β≤0. The case β=−∞ can be treated similarly. Thus, in the following we assume β>0.
The Hamilton–Jacobi–Bellman (HJB) equation corresponding to the problem is given by
 $$\eqalignno{ & {A \over 2}V_{{ll}} (l,\,x){\plus}{\int} \left( {V(l{\plus}h,\,x){\minus}V(l,\,x)\,{\minus}\,h1_{{\{ \,\mid\,h\,\mid\,\leq 1\} }} V_{l} (l,\,x)} \right)\nu (dh) \cr & \quad {\minus}\gamma V_{l} (l,\,x){\plus}\mu V_{x} (l,\,x){\plus}{{\sigma ^{2} } \over 2}V_{{xx}} (l,\,x){\minus}\delta V(l,\,x){\plus}\mathop {{\rm sup}}\limits_{u\in[0,\,\xi ]} \,u\left\{ {e^{{{\minus}l}} {\minus}V_{x} (l,\,x)} \right\}\,{\equals}\,0 $$
which by equation (2) and the definition of β simplifies to
 $$\mu V_{x} \left( {0,\,x} \right){\plus}{{\sigma ^{2} } \over 2}V_{{xx}} \left( {0,\,x} \right){\minus}\beta V\left( {0,\,x} \right){\plus}\mathop{{{\rm sup}}}\limits_{{_{u} _{{\in[0,\,\xi ]}} }} \,u\left\{ {1{\minus}V_{x} \left( {0,\,x} \right)} \right\}\,{\equals}\,0$$
Thus, β can be interpreted as the preference rate in the considered foreign market. Equation (3) has been studied by several authors and the solution is discussed in detail in Schmidli (Reference Schmidli2008: 97–104). We summarise the implications in Proposition 2.1 below.
In case of unrestricted dividend payments, the decision maker seeks to maximise V
D
for
 $D\in{\cal A}_{u} $
, i.e., we want to find an admissible strategy
 $D^{{\asterisk}} \! \in\!{\cal A}_{u} $
such that
 $$V^{{D^{{\asterisk}} }} (l,\,x){\equals}\mathop {{\rm sup}}\limits_{D\in{\cal A}_{u} } \,V^{D} (l,\,x)$$
As in equation (2), we get V
D
(l, x)=e
−l
V
D
(0, x) for any strategy
 $D\in{\cal A}_{u} $
. The corresponding HJB reads
 $$\eqalignno{ & {\rm max}\left\{ {{A \over 2}V_{{ll}} \left( {l,\,x} \right){\plus}{\int} {\left( {V\left( {l{\plus}h,\,x} \right){\minus}V(l,\,x){\minus}h1_{{\{ \left| h \right|{\rm }\leq {\rm }1\} }} V_{l} \left( {l,\,x} \right)} \right)} } \right.\nu \left( {dh} \right) \cr & \left. {\quad \quad \quad \;{\minus}\gamma V_{l} \left( {l,\,x} \right){\plus}\mu V_{x} \left( {l,\,x} \right){\plus}{{\sigma ^{2} } \over 2}V_{{xx}} \left( {l,\,x} \right){\minus}\delta V\left( {l,\,x} \right),\,e^{{{\minus}l}} {\minus}V_{x} \left( {l,\,x} \right)} \right\}{\equals}\,0 $$
and simplifies to
 $${\rm max}\left\{ {\mu V_{x} \left( {0,\,x} \right){\plus}{{\sigma ^{2} } \over 2}\,V_{{xx}} \left( {0,\,x} \right){\minus}\beta V\left( {0,\,x} \right),\,1{\minus}V_{x} \left( {0,\,x} \right)} \right\}{\rm {\equals}}\,0$$
Again, this equation has been treated extensively in Schmidli (Reference Schmidli2008: 102).
Define now the following auxiliary quantities:
 $$\eqalignno{ & \theta \,\colon\,{\equals}{{{\minus}\mu {\plus}\sqrt {\mu ^{2} {\plus}2\beta \sigma ^{2} } } \over {\sigma ^{2} }}\quad \quad \:{\rm and}\quad \quad \zeta \,\colon\,{\equals}{{{\minus}\mu {\minus}\sqrt {\mu ^{2} {\plus}2\beta \sigma ^{2} } } \over {\sigma ^{2} }} \cr & \eta \,\colon\,{\equals}{{\xi {\minus}\mu {\minus}\sqrt {(\xi {\minus}\mu )^{2} {\plus}2\beta \sigma ^{2} } } \over {\sigma ^{2} }} $$
Proposition 2.1 In the restricted case, the value function V solves HJB equation (3) and is given by V(l, x)=e −l F(x), where
 $$F(x)\,\colon\,{\equals}\left\{ {\matrix{ {{\xi \over \beta }(1{\minus}e^{{\eta x}} )} & {\beta \geq {\minus}\xi \eta } \cr {{{e^{{\theta x}} {\minus}e^{{\zeta x}} } \over {\theta e^{{\theta x_{r} }} {\minus}\zeta e^{{\zeta x_{r} }} }}} & {\beta \,\lt\,{\minus}\xi \eta \;{\rm and}\;x\leq \;x_{r} } \cr {{\xi \over \beta }{\plus}{1 \over \eta }e^{{\eta (x{\minus}x_{r} )}} } & {\beta \,\lt\,{\minus}\xi \eta \;{\rm and}\;x\,\gt\;x_{r} } \cr } } \right.$$
and the optimal strategy
 ${\bf D}^{{\rm {\asterisk}}} {\rm {\equals}}\left\{ {u_{s}^{{\asterisk}} } \right\}$
is
 $$u_{s}^{{\asterisk}} \left( x \right)\,{\equals}\,\xi {\bf I}_{{[X_{s}^{{{\bf D^{\rm {\asterisk}}}}} \,\gt\,x_r]}} $$
with
 $${{x_{r} \,\colon\,{\equals}{\rm ln}\left( {1{\rm }{\minus}\zeta \left( {{\xi \over \delta }{\plus}{1 \over \eta }} \right)} \right){\minus}{\rm ln}\left( {1{\minus}\theta \left( {{\xi \over \delta }{\plus}{1 \over \eta }} \right)} \right)} \over {\theta \,{\minus}\,\zeta }}{\rm }{\equals}{{{\rm ln}\left( {{{\zeta ^{2} {\minus}\eta \zeta } \over {\theta ^{2} {\minus}\eta \theta }}} \right)} \over {\theta \,{\minus}\,\zeta }}$$
In the unrestricted case, the value function V solves HJB equation (4) and is given by V(l, x)=e −l G(x), where
 $$G(x)\,\colon\,{\equals}\left \{ {\matrix{ {{{e^{{\theta x}} {\minus}e^{{\zeta x}} } \over {\theta e^{{\theta x_{u} }} {\minus}\zeta e^{{\zeta x_{u} }} }}} & {x\leq x_{u} } \cr {{\mu \over \beta }{\plus}x{\minus}x_{u} } & {x\,\gt\,x_{u} } \cr } } \right.$$
with the optimal strategy
 $D_{t}^{{\asterisk}} {\equals}{\rm max}\left\{ {\mathop{{{\rm sup}}}\limits_{{{{0\leq s\leq t\wedge\tau ^{{D^{\rm {\asterisk}}}} }} }} \,X_{t} {\minus}x_{u} ,\,0} \right\}$
, and
 $$x_{u} \,\colon\,{\equals}{{{\rm ln}\left( {{{\zeta ^{2} } \over {\theta ^{2} }}} \right)} \over {\theta {\minus}\zeta }}$$
Proof: See Schmidli (Reference Schmidli2008: 101, 103).□
Let us make a simple example showing that the optimisation problem can be well posed even in the presence of a negative preference rate δ.
Example 2.2
Let δ :=−1/4, A=1/2, b
1 :=log(5), b
2 :=log(5/4), N
(1), N
(2)
be independent standard Poisson processes, i.e., they are Poisson processes with jump intensity 1 and jump height 1, and let B be a standard Brownian motion independent of W, where B, N
(1)
and N
(2)
are
 ${\cal F}{\minus}adapted$
. Define
 $$L_{t} \,\colon\,{\equals}\sqrt A \,B_{t} {\plus}b_{1} N_{t} ^{{(1)}} {\minus}b_{2} N_{t} ^{{(2)}} ,\quad t\geq 0$$
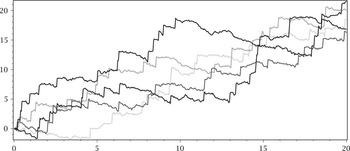
Then, β=1/20 and hence Proposition 2.1 yields that the optimisation problem is well posed. Sample path simulations suggest that the paths of L t +δt tend to ∞ as t→∞ as one expects and which can be easily verified (cf. Figure 1 ).
Realisations of the process {L t +δt} with a negative preference rate δ.

Another example is to use a normal inverse Gaussian (NIG) process for the exchange rate.
Example 2.3
Let L be an NIG process with parameters (σ
2, θ, κ)=(0.19, 0, 1) in the sense of
Cont & Tankov (Reference Cont and Tankov2004
, table 4.5) and assume that δ=0.5. Then
 $\beta \,{\equals}\,\delta {\plus}{1 \over \kappa }\left( {1{\minus}\sqrt {1{\minus}\sigma ^{2} \kappa {\plus}2\theta \kappa } } \right)\,{\equals}\,0.6\,\gt\,0$
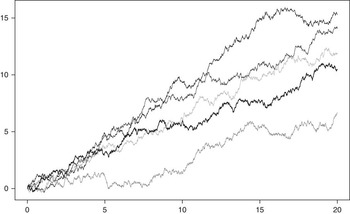
and hence Proposition 2.1 yields that the optimisation problem is well posed. Sample path simulations for {L
t
+δt} can be found in
Figure 2
.
Remark 2.4 Let now the constants defined in (5) and correspondingly the optimal barriers x r and x u be functions of β, where we substitute β by a non-negative variable y. It is straightforward to show that x r (y) and x u (y) are strictly decreasing in y. In particular, it means that the dividend barrier should be adjusted to the expectations of the insurance company concerning the future development of the exchange rate.
Remark 2.5 (Incorporating dependencies between L and W .) It seems to be a natural extension to allow for dependencies between the Lévy process L and the Brownian motion W.
However, the only way to introduce dependencies between a Lévy process L and a Brownian motion W, adapted to the same filtration, is to let the continuous martingale part L
c
of the Lévy process L depend on the Brownian motion W. The remainder L
r
:=L−L
c
is a Lévy process again, and (L
r
, W) is a two-dimensional semimartingale whose characteristics in the sense of
Jacod & Shiryaev (Reference Jacod and Shiryaev2003
, definition II.2.6) is deterministic.
Jacod & Shiryaev (Reference Jacod and Shiryaev2003
, theorem II.4.15, corollary II.4.19) yields that (L
r
, W) is a Lévy process. Thus, L
r
must be independent of W and L
r
is independent of L
c
, which is simply a scaled Brownian motion. A natural way would be to correlate L
c
and W so that (W, L
c
) is a two-dimensional Brownian motion. Then, L
r
is independent of (W, L
c
) and can be removed from the consideration by adjusting
 $\delta _{{{\rm new}}} \,{\equals}\,\delta \,{\minus}\mathop{\int}_{\Bbb R} \left( {e^{{{\minus}h}} {\minus}1{\plus}h1_{{\{ \,\mid\,h\,\mid\,\leq 1\} }} } \right)\nu {\rm (}dh{\rm )}{\plus}\gamma $
as before. The remaining problem has been solved in
Shreve et al. (Reference Shreve, Lehoczky and Gaver1984)
and
Asmussen & Taksar (Reference Asmussen and Taksar1997).
Realisations of the process {L t +δt} with δ=0.5 and a normal inverse Gaussian process L with parameters (0.19, 0, 1).

In the present paper, we consider the case where the real interest rates are substituted by preference rates. Taking the interest rates on the domestic and foreign markets into consideration will add complexity to the considered problem. We believe that the solution to such a problem cannot be determined easily. For instance, in Eisenberg (Reference Eisenberg2015), by modelling the interest rate by an Ornstein–Uhlenbeck process, one could show that the value function is a viscosity solution to the corresponding HJB equation.
Acknowledgements
The research of the first author was supported by the Austrian Science Fund, grant no. P26487. The authors thank unknown referees for various helpful comments.