


1. Introduction
Reinsurance plays a crucial role in insurers’ risk management strategies and receives extensive attention in practice. As a primary method for insurers to transfer risk exposure, reinsurance enhances underwriting capacity, stabilizes profits, and safeguards against the catastrophic losses. The reinsurance optimization problems under various objective functions have become a popular research topic in the actuarial literature. Common objective functions include minimizing the probability of ruin/drawdown (for example, Liang and Young, Reference Liang and Young2018; Cohen and Young, Reference Cohen and Young2020; Gatto, Reference Gatto2020), maximizing expected utility of terminal wealth (for example, Zou and Cadenillas, Reference Zou and Cadenillas2014; Mereu and Stelzer, Reference Mereu and Stelzer2017; Brachetta and Ceci, Reference Brachetta and Ceci2020) and mean-variance optimization criterion (for example, Guo et al., Reference Guo, Ye and Yin2012; Yang et al., Reference Yang, He and Zhu2022; Li et al., Reference Li, Guo and Tian2024).
Although a large body of works on optimal reinsurance problems has been carried out, several frontier questions merit further exploration. On the one hand, existing studies mainly focus on the optimal reinsurance problem under the assumption of decision-maker’s (DM’s) neutral attitude toward ambiguity and precisely measurable model parameters. However, critical real-world parameters such as claim intensity or expected value of claims often defy high-precision estimation. In the literature, there exist several approaches to tackle the optimization problems when model uncertainty is taken into account. One tractable framework is assuming that the insurer has multiple perspectives in the presence of ambiguity, and each perspective associated with a known probability measure called prior probability measure. The DM aims to maximize the minimal mean-variance cost functional:
 \begin{align*}\inf_{\mathbb{Q}\in\mathcal{Q}}\left\{\mathbb{E}^{\mathbb{Q}}(X)-\frac{\gamma}{2}\mathrm{Var}^{\mathbb{Q}}(X)+h_{\beta}(\mathbb{Q}|\mathbb{P})\right\},\end{align*}
where X is a random payoff,
 $\gamma$
is the risk-aversion parameter,
 $\mathcal{Q}$
is a set of prior probability measures,
 $h_{\beta}(\mathbb{Q}|\mathbb{P})$
is a relative penalty to a measure
 $\mathbb{Q}$
with respect to (w.r.t.)
 $\mathbb{P}$
, and the ambiguity parameter
 $\beta$
reflects the DM’s relative level of confidence for the reference measure
 $\mathbb{P}$
. This approach to robustness has been developed extensively in the robust optimal reinsurance problems with mean-variance preference, which can be found in Zeng et al. (Reference Zeng, Li and Gu2016), Zhao et al. (Reference Zhao, Shen, Zeng and Zhang2019), Yuan et al. (Reference Yuan, Liang and Han2022), Wang et al. (Reference Wang, Siu and Fan2024), just to name a few.
It has been shown that the insurer with maxmin mean-variance preference is extremely ambiguity-averse and only considers the payoff in the worst-case scenario. However, the DM may not always be negative toward the ambiguity. Through a series of experiments, Health and Tversky (Reference Heath and Tversky1991) and Kocher et al. (Reference Kocher, Lahno and Trautmann2015) claimed that people reveal ambiguity-seeking attitudes when they have their own knowledge and inside information about the relevant context. In an effort to distinguish conceptually between ambiguity and ambiguity attitude, Marinacci (Reference Marinacci2002) and Ghirardato et al. (Reference Ghirardato, Maccheroni and Marinacci2004) introduced the
 $\alpha$
-maxmin expected utility (
 $\alpha$
-MEU) preference with the form:
 \begin{align*}\alpha\inf_{\mathbb{Q}\in\mathcal{Q}}\mathbb{E}^{\mathbb{Q}}(U(X))+(1-\alpha)\sup_{\mathbb{Q}\in\mathcal{Q}}\mathbb{E}^{\mathbb{Q}}(U(X)),\end{align*}
where
 $\alpha\in[0,1]$
measures the ambiguity attitude. Specially,
 $\alpha=\frac{1}{2}$
represents the ambiguity-neutral attitude,
 $\alpha=0$
represents the extremely ambiguity-seeking attitude, and
 $\alpha=1$
represents extremely ambiguity-averse attitude. The
 $\alpha$
-MEU brings about the challenge of time-inconsistency due to the linear aggregation of the expected payoffs under two distinct priors. Recently, the problems under
 $\alpha$
-MEU criteria have attracted more attention in the literature. For example, Li et al. (Reference Li, Luo and Xiong2019) examined the maximization problem under the
 $\alpha$
-MEU framework and derived the corresponding open-loop equilibrium strategies. Yang et al. (Reference Yang, Li, Zeng and Liu2025) assumed that the uncertain expected return rate of the risky asset was parameterized by a nonempty set. Chen et al. (Reference Chen, Liu and Zhao2025) obtained the
 $\alpha$
-robust optimal investment strategy and the adjustment strategy under longevity risk.
Inspired by the
 $\alpha$
-MEU preference, Li et al. (Reference Li, Li and Xiong2016) proposed a new class of
 $\alpha$
-maxmin mean-variance (MV) criterion of the form:
 \begin{align*}\alpha \inf_{\mathbb{Q}\in \mathcal{Q}} \left\{ \mathbb{E}^\mathbb{Q}(X) - \frac{\gamma}{2} \mathrm{Var}^\mathbb{Q}(X) + \mathbb{E}^\mathbb{Q}[h_\beta(\mathbb{Q} \mid \mathbb{P})] \right\} + (1-\alpha)\sup_{\mathbb{Q} \in \mathcal{Q}} \left\{ \mathbb{E}^\mathbb{Q}(X) - \frac{\gamma}{2} \mathrm{Var}^\mathbb{Q}(X) - \mathbb{E}^\mathbb{Q}[h_\beta(\mathbb{Q} \mid \mathbb{P})] \right\}\!,\end{align*}
under which the optimal reinsurance and investment strategies are derived. Zhang and Li (Reference Zhang and Li2021) extended this framework by enlarging the range of
 $\alpha$
from
 $[\frac{1}{2},1]$
to [0, 1] and by studying the optimal reinsurance form under the expected value premium principle. Following Zhang and Li (Reference Zhang and Li2021), Zhang et al. (Reference Zhang, Wu, Zhao and Wang2024b) investigated an optimal reinsurance problem involving contagious catastrophe claims and secondary claims, while Wu et al. (Reference Wu, Zhang and Zhao2025) determined the optimal reinsurance-investment strategy under negative dependence between the insurance and financial markets. It is worth noting that Zhang et al. (Reference Zhang, Wu, Zhao and Wang2024b) restricted the analysis to the ambiguity-averse case
 $\alpha\in[\frac{1}{2},1]$
, whereas Wu et al. (Reference Wu, Zhang and Zhao2025) allowed
 $\alpha\in[0,1]$
but imposed additional admissibility conditions that rule out excessively strong ambiguity-seeking behavior under high ambiguity levels. In this sense, Zhang and Li (Reference Zhang and Li2021) remain closely related to the present paper in explicitly emphasizing the full ambiguity-attitude spectrum
 $\alpha\in[0,1]$
.
Although the
 $\alpha$
-maxmin MV preference has been considered in the past few years, the aforementioned studies are all carried out from the insurer’s perspective only, neglecting the reinsurer’s interests. However, Borch (Reference Borch1969) revealed that the insurer and reinsurer have conflicting interests over the reinsurance premium. An optimal reinsurance contract for an insurer would be not optimal for a reinsurer since one aims to seek its profit and the other wants to control risks. Kihlstrom and Roth (Reference Kihlstrom and Roth1982) pointed out that the insurer and reinsurer take the price as given in a competitive market. Therefore, it is essential to price reinsurance claims and investigate conditions when insurance and reinsurance companies can agree on the price to trade. The study of reinsurance demand and supply for insurer and reinsurer has attracted much attention in the field of actuarial science. For instance, Garven and Tennant (Reference Garven and Tennant2003) investigated the valuation effects of reinsurance purchases in a contingent claims framework. Boonen et al. (Reference Boonen, Tan and Zhuang2016) employed the Nash bargaining solution framework to derive optimal reinsurance contracts and their corresponding pricing mechanisms. Altuntas et al. (Reference Altuntas, Garven and Rauch2018) found that after controlling for firm-level factors, country-level factors have economically as well as statistically significant effects on the demand for reinsurance. The empirical results in Desjardins et al. (Reference Desjardins, Dionne and Kone2022) showed positive bi-causal effects between liquidity creation and reinsurance demand for small insurers. Cao et al. (Reference Cao, Li, Young and Zou2023) examined reinsurance contracting and competition in a market with two reinsurers using Stackelberg game and noncooperative Nash game modeling frameworks.
Hence, the abovementioned works inspire us to consider the reinsurance demand and supply at the same time. The demand–supply framework captures the essence of reinsurance transactions, that is, the matching of supply and demand for risk transfer. Although reinsurance contracts contain numerous customized clauses, the ceding proportion is the core decision variable in all proportional reinsurance contracts, which directly determines the allocation of risks between the insurer and the reinsurer. The model abstracts the insurer and the reinsurer as the demander and supplier of risk protection, respectively. It characterizes the process of the two parties reaching an agreement on the core ceding proportion through the market clearing condition, which is the most critical link in the negotiation of customized reinsurance contracts. The equilibrium price is uniquely defined as the price that aligns these two optimal strategies. This mechanism accurately captures the two-way bargaining process that characterizes real-world reinsurance negotiations. In the literature, this modeling framework has been adopted in Zhang et al. (Reference Zhang, Liang and Yuan2024a) to describe the conflict between insurer and reinsurer under mean-variance criteria. Based on the work of Zhang et al. (Reference Zhang, Liang and Yuan2024a), Cheng et al. (Reference Cheng, Deng, Liu and Zeng2025) determined the equilibrium reinsurance price under the utility maximization framework.
In this paper, we investigate the equilibrium reinsurance price for the insurer and reinsurer under the stochastic reinsurance demand–supply game. In reinsurance market, as the demand side of protection, the insurer chooses the optimal reinsurance demand strategy, while the reinsurer, as the supplier determines the optimal reinsurance supply strategy. Both the two parts have the
 $\alpha$
-maxmin MV preferences. Different from Zhang and Li (Reference Zhang and Li2021), we apply the second-order approximation to deal with the entropy penalty term. Since the time inconsistency caused by the
 $\alpha$
-maxmin MV, we borrow the idea of Björk and Murgoci (Reference Björk and Murgoci2010) to derive the extended Hamilton–Jacobi–Bellman (HJB) systems to characterize the optimal reinsurance demand-supply strategy as well as the value functions. Under the market clearing condition, we prove the existence and uniqueness of the equilibrium reinsurance price for ambiguity-averse/neutral insurer and ambiguity-averse/neutral reinsurer. For the ambiguity-seeking insurer, the optimal demand strategy may not be unique, and the market clearing condition will not be achieved when the ambiguity parameter is relative larger. Meanwhile, two parties cannot reach a contract when the reinsurer is ambiguity-seeking. Finally, we present a detailed sensitivity analysis to illustrate the influences of different ambiguity attitudes and model parameters on the equilibrium reinsurance price. To the best of our knowledge, there is no published work discussing the stochastic reinsurance demand–supply game between the insurer and the reinsurer under
 $\alpha$
-maxmin MV preference. This paper is dedicated to filling up this research gap. In Table 1, we conduct a detailed review of Li et al. (Reference Li, Li and Xiong2016), Zhang and Li (Reference Zhang and Li2021), and Zhang et al. (Reference Zhang, Liang and Yuan2024a) and compare them to the current paper.
Comparison between the works of Li et al. (Reference Li, Li and Xiong2016), Zhang and Li (Reference Zhang and Li2021), and Zhang et al. (Reference Zhang, Liang and Yuan2024a).

Table 1. Long description
The table compares the works of Li et al. (2016), Zhang and Li (2021), and Zhang et al. (2024a) with the current paper. It has five rows and four columns. The columns are labeled as This paper, Li et al. (2016), Zhang and Li (2021), and Zhang et al. (2024a). The rows are labeled as Model uncertainty, Ambiguity seeking, Reinsurance price, Variance premium, and Reinsurance game. Each cell contains a check mark or a cross indicating the presence or absence of the respective factor in the study. For example, the current paper includes model uncertainty, ambiguity seeking, reinsurance price, and reinsurance game but does not include variance premium. Li et al. (2016) includes model uncertainty and reinsurance price but does not include ambiguity seeking, variance premium, or reinsurance game. Zhang and Li (2021) includes model uncertainty and reinsurance price but does not include ambiguity seeking, variance premium, or reinsurance game. Zhang et al. (2024a) includes model uncertainty, reinsurance price, and reinsurance game but does not include ambiguity seeking or variance premium.
Our paper is by no means a trivial extension of either Zhang et al. (Reference Zhang, Liang and Yuan2024a) or previous works on
 $\alpha$
-maxmin MV problem with the insurer’s interest taken into account only. The contributions of this paper are threefold. First, we introduce a stochastic demand–supply game to describe the conflict of interest between the insurer and the reinsurer, which facilitates the explanation of the phenomenon of imbalance between supply and demand in the reinsurance market. In this sense, the current paper extends the work of Zhang and Li (Reference Zhang and Li2021) from single-agent optimization problem to a stochastic differential game under
 $\alpha$
-maxmin MV criteria. Second, a three-step approach has been proposed to solve the stochastic demand–supply game problem. This approach enables us to determine the equilibrium reinsurance price endogenously through market clearing. Our results unveils that different ambiguity attitudes affect the market equilibrium. The existence and uniqueness of the equilibrium reinsurance price have been proved under the ambiguity aversion/neutral preference. The reinsurance contracts cannot be successfully reached when the reinsurer is ambiguity-seeking. Third, the method of second-order approximation to the entropic penalty for ambiguity is first applied in the
 $\alpha$
-maxmin MV problem. This preserves analytical tractability and simplifies the analysis of optimal strategies while retaining the core behavioural features of ambiguity-averse agents. It is worth noting that this paper assumes the existence of a representative insurer and a representative reinsurer in the market. This setting is consistent with the common practice of “one-to-one exclusive negotiations” in the reinsurance market, especially in the fields of catastrophe reinsurance and special risk reinsurance.
The rest of the paper is organized as follows. In Section 2, we formulate the stochastic reinsurance demand–supply game and the player’s
 $\alpha$
-maxmin mean-variance optimization problems. In Section 3, the optimal reinsurance demand–supply strategy and equilibrium reinsurance price are discussed. We also provide some numerical example to demonstrate the impact of some important parameters on the equilibrium strategies and price. Section 4 concludes the paper. All the technical proofs are postponed to the Online Appendix.
2. Model setting
Let
 $(\Omega, \mathcal{F}, \mathbb{F}=\{ \mathcal{F}_t \}_{0\leqslant t \leqslant T}, \mathbb{P})$
be a complete filtered probability space in which all stochastic quantities in this paper are well defined. Here,
 $\mathbb{F}$
is a filtration that satisfies the usual conditions and
 $T\gt 0$
is a finite time horizon.
2.1. Reinsurance market
Suppose that the insurer receives premium at a constant rate
 $c\gt 0$
and is exposed to aggregate risks
 $C=\{C(t)\}_{t\geqslant 0}$
that follows the compounded Poisson process. In other words, the insurer’s surplus process
 $X_1=\{X_1(t)\}_{t\geqslant 0}$
is described by the classical Cramér–Lunderg risk model, that is,
 \begin{equation}\mathrm{d} X_1(t)=c\mathrm{d} t-\mathrm{d} C(t)=c\mathrm{d} t-\mathrm{d}{\left(\sum_{i=1}^{N(t)}Z_i\right)}, \ \ \ X(0)=x_0 \gt 0,\end{equation}
where
 $x_0$
is the initial wealth;
 $c\gt 0$
is the premium rate; N(t) is a homogeneous Poisson process with intensity
 $\lambda$
and represents the number of claims up to time t; the claim sizes
 $\{Z_i,i=1,2\dots\}$
are a series of independent and identically distributed (i.i.d.) positive random variables with common cumulative distribution function F(z), finite expectation
 $m_1$
, and finite second moment
 $m_2$
. For simplicity, we use Poisson random measure
 $N(\mathrm{d} t, \mathrm{d} z)$
to denote the compound Poisson process C(t), and the surplus process (1) is equivalent to
 \begin{equation}\mathrm{d} X_1(t)=c\mathrm{d} t-\mathrm{d} C(t)=c\mathrm{d} t-\int_{0}^{\infty}zN(\mathrm{d} t,\mathrm{d} z), \ \ \ X (0)=x_0 \gt 0.\end{equation}
The so-called compensated Poisson random measure is
 $\tilde{N}(\mathrm{d} t,\mathrm{d} z)=N(\mathrm{d} t,\mathrm{d} z)-\nu(\mathrm{d} t,\mathrm{d} z)$
, with
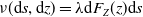 $\nu(\mathrm{d} s,\mathrm{d} z)=\lambda\mathrm{d} F_Z(z) \mathrm{d} s$
.
To manage the uncertain risk, the insurer is allowed to continuously transfer her risk by purchasing proportional reinsurance. Let
 $q_1=\{q_1(t)\}_{t\geqslant0}$
denote the demand ratio at time t. It means that the insurer would cover
 $100(1-q_1(t))\%$
of each claim and transfer the remaining part to the reinsurer at time t. Apparently, this reinsurance is not for free and has a cost. We assume that the reinsurance premium rate paid at time t is calculated via the variance premium principle, that is,
 \begin{align*}\delta(t,q_1)=\lambda q_1(t)m_1+\frac{\eta}{2}\lambda q_1(t)^{2}m_2,\end{align*}
where
 $\eta$
is the nonnegative loading factor, and it is called reinsurance price hereafter. We suppose that
 $\delta(t,1)\gt c$
, otherwise, there will exist arbitrage. Therefore, in the presence of proportional reinsurance treaty, the surplus process of the insurer is given by
 \begin{equation}\mathrm{d} X_1(t)=\left(c-\lambda m_1-\frac{\eta}{2}\lambda q_1(t)^{2}m_2\right)\mathrm{d} t-\int_{0}^\infty (1-q_1(t))z\tilde{N}(\mathrm{d}t,\mathrm{d}z),X_1(0)=x_1.\end{equation}
Correspondingly, the surplus process of the reinsurer evolves according to
 \begin{equation}\mathrm{d} X_2(t)=\frac{\eta}{2}\lambda q_2(t)^{2}m_2\mathrm{d} t-\int_{0}^\infty q_2(t)z\tilde{N}(\mathrm{d}t,\mathrm{d}z),X_2(0)=x_2,\end{equation}
where
 $q_2=\{q_2(t)\}_{t\geqslant0}$
represents the supply proportion of the reinsurer for the reinsurance business. Here, we can see that there exist two strategies in our model. One is the reinsurance demand strategy
 $q_1(t)$
, which is chosen by the insurer. The other is the reinsurance supply strategy
 $q_2(t)$
decided by the reinsurer. We do not initially require the condition
 $q_1(t)=q_2(t)$
in the individual optimization problem, but obtain the individually optimal strategy for insurer and reinsurer, respectively. Then, we discuss the existence of the market equilibrium price under the market-clearing condition (i.e.,
 $q_1(t)=q_2(t)$
for
 $t\in[0,T]$
). This approach is essentially different from the Stackelberg differential game which can be referred to Chen and Shen (Reference Chen and Shen2019), Guan et al. (Reference Guan, Liang and Song2024), Yuan et al. (Reference Yuan, Yuen and Wang2025), just to name a few. In the Stackelberg model, the follower’s strategy is a direct response to the leader’s strategy, thus naturally satisfying
 $q_1(t)=q_2(t)$
, while in the supply-demand framework adopted in this paper, we take price as the core variable to coordinate the decisions of both parties. It makes the independent optimal strategies of both parties reach an agreement through price adjustment, which is more consistent with the actual process of “simultaneous bargaining over price and quantity” in the reinsurance market.
Remark 2.1. Our model focuses on proportional reinsurance contracts because this class of contracts keeps both parties’ strategies analytically tractable and allows us to isolate the effect of model ambiguity on the equilibrium of the reinsurance market. Zhang and Li (Reference Zhang and Li2021) studied optimal reinsurance problem under the
 $\alpha$
-maxmin mean-variance criterion and showed that excess-of-loss reinsurance is optimal for ambiguity-averse decision-makers, while ambiguity-seeking preferences may destroy the uniqueness of the optimal reinsurance form. Extending the present supply–demand game framework to other reinsurance contract forms, such as deductible and excess-of-loss reinsurance, is therefore a natural direction for future research.
2.2. Model uncertainty
In practice, the parameter estimations, such as the intensity of the counting process N(t), are always not entirely accurate and reliable due to the complex and adverse environment. Many previous works have shown that agents face significant utility loss when ignoring ambiguity. Hence, the DM usually has to take the inaccuracy in parameter estimation into consideration. She is skeptical about the reference measure denoted by
 $\mathbb{P}$
and willing to consider some alternative measures that are equivalent to
 $\mathbb{P}$
. The set
 $\mathcal{Q}$
consisting of all the alternative probability measures is defined by
 \begin{equation*} \mathcal{Q}\,:\!=\,\{ \mathbb{Q}^{\phi} \mid \mathbb{Q}^{\phi} \sim \mathbb{P} \},\end{equation*}
where the equivalent probability measure
 $\mathbb{Q}^{\phi}$
is defined by the probability distortion function
 $\phi(t), t\in[0,T]$
, satisfying the following conditions:
-
(i)
 $\phi(t)$
is a deterministic function of t.
-
(ii)
$\exp\{\lambda\int_0^T[(1-\phi(t))\ln(1-\phi(t))+\phi(t)]\mathrm{d}t\}\lt \infty$
. -
(iii) There exists a constant
$\xi\gt 0$
such that
$\phi(t)\leqslant 1-\xi$
for
$t\in[0,T]$
.


Denote
 $\phi=\{\phi(t)\}_{t\geqslant0}$
. The set of all functions
 $\phi$
that satisfy the above conditions is denoted by
 $\Phi$
. For each
 $\phi\in\Phi$
, we define the process
 $\Lambda^{\phi}$
as
 \begin{equation*} \Lambda^{\phi}(t)\,:\!=\,\exp\left\{\int_0^t\int_0^\infty\ln(1-\phi(s))\tilde{N}(\mathrm{d} z,\mathrm{d} s)+\int_0^t\int_0^\infty[\ln(1-\phi(s))+\phi(s)]\nu(\mathrm{d} z)\mathrm{d} s\right\}\!,\end{equation*}
which is a
 $\mathbb{P}$
-martingale. Then, the corresponding Radon–Nikodym derivative of
 $\mathbb{Q}^{{\phi}}$
w.r.t.
 $\mathbb{P}$
can be defined as
 \begin{equation*} \frac{\mathrm{d}\mathbb{Q}^{\phi}}{\mathrm{d}\mathbb{P}}\vert_{\mathcal{F}_{T}}\,:\!=\,\Lambda^{\phi}(T).\end{equation*}
It follows from the Girsanov’s Theorem that
 $\tilde{N}^{\mathbb{Q}^{{\phi}}}(\mathrm{d} t,\mathrm{d} z)=\tilde{N}(\mathrm{d} t,\mathrm{d} z)+\phi(t)\nu(\mathrm{d} z)\mathrm{d} t$
is the compensated Poisson random measure under
 $\mathbb{Q}^{{\phi}}$
with compensator
 $(1-\phi(t))\nu(\mathrm{d}z)$
. It is worth noting that the distributions of claim variable Z are assumed to be identical under the reference measure
 $\mathbb{P}$
and distorted measure
 $\mathbb{Q}^{{\phi}}$
. The consideration of model ambiguity is imposed on the claim-arrival intensity. More specifically, the rate
 $\lambda$
is essentially replaced with
 $\lambda(1-\phi(t))$
when we change the measure from
 $\mathbb{P}$
to
 $\mathbb{Q}^{\phi}$
, which requires
 $\phi(t)\lt 1$
. In particular,
 $\phi(t)\lt 0$
indicates that the insurer believes the true intensity to be higher than that under the reference measure. Thus, the surplus processes of the insurer and reinsurer under respective measures
 $\mathbb{Q}^{{\phi}_1}$
and
 $\mathbb{Q}^{{\phi}_2}$
can be modified as
 \begin{equation}\left\{\begin{split}\mathrm{d} X^{\mathbb{Q}^{{\phi}_1}}_1(t)=&\left[c-\lambda q_1(t)m_1-\frac{\eta}{2}\lambda q_1(t)^{2}m_2-\lambda(1-\phi_1(t))(1-q_1(t))m_1\right]\mathrm{d} t\\&-\int_{0}^\infty (1-q_1(t))z\tilde{N}^{\mathbb{Q}^{{\phi}_1}}(\mathrm{d}t,\mathrm{d}z),\\\mathrm{d} X^{\mathbb{Q}^{{\phi}_2}}_2(t)=&\left[\lambda q_2(t)m_1+\frac{\eta}{2}\lambda q_2(t)^{2}m_2-\lambda(1-\phi_2(t)) q_2(t)m_1\right]\mathrm{d} t-\int_{0}^\infty q_2(t)z\tilde{N}^{\mathbb{Q}^{{\phi}_2}}(\mathrm{d}t,\mathrm{d}z),\\X^{\mathbb{Q}^{{\phi}_1}}_1(0)=&x_1,X^{\mathbb{Q}^{{\phi}_2}}_2(0)=x_2.\end{split}\right.\end{equation}
In other perspective, the model ambiguity reinforces the theoretical rationale for adopting this demand-supply framework. The ambiguity not only amplifies insurers’ demand for reinsurance protection but also increases reinsurers’ required compensation for bearing model risk and constrains their effective underwriting capacity. Consequently, excessive ambiguity widens the valuation gap between counterparties and impedes market clearing. This interpretation aligns with well-established empirical evidence from catastrophe reinsurance markets. Froot and O’Connell (Reference Froot and O’Connell1997) and Froot (Reference Froot2001) found that catastrophe reinsurance prices and the availability of protection are strongly driven by supply-side capital constraints and risk-bearing capacity. It highlighted the critical role of supply-side frictions in determining market outcomes. Lane and Mahul (Reference Lane and Mahul2008) further demonstrated that catastrophe risk prices are driven by expected losses, as well as broader market conditions and transaction-specific characteristics. This finding underscored the critical need for a modeling framework that explicitly accounts for both demand and supply dynamics. Dietz and Niehörster (Reference Dietz and Niehörster2021) provided direct evidence that ambiguity affects catastrophe reinsurance pricing through explicit ambiguity loadings, which is consistent with our modeling approach where ambiguity parameters shape both parties’ risk preferences and equilibrium outcomes. We now present the formal definition of the agent’s individually admissible strategies.
Definition 2.1. Given the reinsurance price
 $\eta$
, the reinsurance demand–supply strategy
 $(q_1(t),q_2(t))$
for the insurer and reinsurer is said to be individually admissible if the following conditions are satisfied:
-
(i)
$q_i(t)$
is the deterministic function depending only on time t for
$i=1,2$
; -
(ii)
$q_i(t)\in[0,1]$
for
$i=1,2,$
and
$t\in[0,T]$
; -
(iii) the state equations of
$X_1^{\mathbb{Q}^{{\phi}_1}}(t)$
and
$X_2^{\mathbb{Q}^{{\phi}_2}}(t)$
have unique strong solutions.


Let
 $\mathcal{A}_1\times\mathcal{A}_2$
be the space of all admissible strategies, where
 $\mathcal{A}_1$
and
 $\mathcal{A}_2$
are the admissible sets of insurer’s and reinsurer’s strategies, respectively. Furthermore, the reinsurance contract can be reached if and only if
 $q_1(t)=q_2(t) $
holds for
 $t\in[0,T]$
.
2.3. Optimization problem
We formulate the reinsurance demand–supply game between the insurer and reinsurer under the
 $\alpha$
-maxmin mean-variance criterion. Similar to Zhang and Li (Reference Zhang and Li2021) and Zhang et al. (Reference Zhang, Liang and Yuan2024a), the insurer and reinsurer both maximize the following
 $\alpha$
-maxmin MV cost functional:
 \begin{equation}J_i(t,x_i;\,q_i)\,:\!=\,\alpha_i\underset{\phi_i\in\Phi}{\inf} \underline{J}_{\,i}^{\,\phi_i}(t,x_i;\,q_i)+(1-\alpha_i)\underset{\phi_i\in\Phi}{\sup\,}\overline{J}_{\,i}^{\,\phi_i}(t,x_i;\,q_i),i=1,2,\end{equation}
where
 \begin{equation}\left\{\begin{split}&\underline{J}_{i}^{\phi_{i}}(t,x_i;\,q_i)\,:\!=\,\mathbb{E}_{t,x_i}^{{\phi_{i}}}\big[X_i^{q_i}(T)\big]-\frac{\gamma_i}{2} \mathrm{Var}_{t,x_i}^{{\phi_{i}}}\big[X_i^{q_i}(T)\big]+\frac{1}{\beta_i}\int_t^T h(\phi_i(s))\mathrm{d} s,i=1,2,\\&\overline{J}_{i}^{\phi_{i}}(t,x_i;\,q_i)\,:\!=\, \mathbb{E}_{t,x_i}^{{\phi_{i}}}\big[X_i^{q_i}(T)\big] - \frac{\gamma_i}{2} \mathrm{Var}_{t,x_i}^{{\phi_{i}}}\big[X_i^{q_i}(T)\big] - \frac{1}{\beta_i}\int_t^T h(\phi_i(s))\,\mathrm{d} s,i=1,2.\end{split}\right.\end{equation}
In (7), we penalize the mean-variance performance for ambiguity in the claim intensity
 $\lambda$
. The nonnegative parameter
 $\beta_i$
measures the individual’s level of ambiguity. The limiting case
 $\beta_{i}\rightarrow 0$
yields the non-robust reference model (with the objective defined for
 $\beta_i\gt 0$
). Larger values of
 $\beta_i$
correspond to greater ambiguity level of the insurer/reinsurer, that is, the insurer/reinsurer has less faith in the reference measure.
Assumption 2.1. The parameters
 $\beta_1$
and
 $\beta_2$
satisfy the conditions
 $0\lt \beta_1\lt (m_1+\frac{\gamma_1}{2}m_2)^{-1}$
and
 $0\lt \beta_2\lt (m_1+\frac{\gamma_2}{2}m_2)^{-1}$
.
To apply the change of measure, we need to introduce these constraints on the parameters
 $\beta_1$
and
 $\beta_2$
, which ensure
 $1-\phi_i(t)\geqslant\xi\gt 0$
for later analysis. This assumption is not only for mathematical convenience, but also has its economic interpretation. This restriction guarantees that the induced optimal distortions remain in the admissible region and that ambiguity is measured around the reference model. This assumption is consistent with the results in Zhang and Li (Reference Zhang and Li2021), which has shown that when decision maker is ambiguity-seeking, high ambiguity levels may generate complicated responses, such as nonuniqueness, discontinuity, or even ambiguity-averse behavior. Therefore, the upper bounds on
 $\beta_i$
allow us to focus on a tractable ambiguity region in which ambiguity-seeking behavior can be meaningfully analyzed. The penalty term is a component of the relative entropy, namely,
 \begin{align*}\int_t^Th(\phi_i(s))\mathrm{d} s=\int_t^T\lambda[(1-\phi_i(s))\ln(1-\phi_i(s))+\phi_i(s)]\mathrm{d} s.\end{align*}
Similar to Li and Young (Reference Li and Young2019), we apply one additional approximation to our robust optimization problem. To be precise, we replace
 $(1-\phi_i)\ln(1-\phi_i)+\phi_i$
with its second-order approximation, that is,
 \begin{equation*} (1-\phi_i)\ln(1-\phi_i)+\phi_i\approx\frac{\phi_i^2}{2}.\end{equation*}
The parameter
 $\alpha_i\in[0,1]$
represents the different attitudes toward ambiguity. As
 $\alpha_i$
increases, the DM becomes more averse to ambiguity. When
 $\alpha_i\in[0,\frac{1}{2})$
, the DM exhibits ambiguity-seeking behavior toward the ambiguous prospect and a smaller
 $\alpha$
implies a larger preference for ambiguity. On the contrary, when
 $\alpha_i\in(\frac{1}{2},1]$
, the DM is ambiguity-averse. Specially,
 $\alpha_i=\frac{1}{2}$
represents that the DM has the ambiguity-neutral attitude, which is non-robust case.
The problems to maximize (6) are both time inconsistent in the sense that dynamic programming principle fails. We follow the convention in the literature (Björk and Murgoci, Reference Björk and Murgoci2010) and define the time-consistent reinsurance demand–supply strategy. Meanwhile, we define the equilibrium market and reinsurance price in our model.
Definition 2.2. Let
 $q^*=(q_1^*,q_2^*)\in\mathcal{A}_{1}\times\mathcal{A}_{2}$
be a reinsurance demand–supply strategy for the insurer and reinsurer. For any
 $t\in[0,T]$
and a fixed constant
 $\varepsilon\gt 0$
, we define a perturbed strategy as
 \begin{equation}q^{\varepsilon}_i(s)\,:\!=\,\left\{\begin{split}&q_i(s),&t\leqslant s\lt t+\varepsilon,\\&q_i^*(s),&t+\varepsilon\leqslant s\leqslant T, \end{split} \right.\end{equation}
where
 $q_i(s)\in\mathcal{A}_i$
. If
 \begin{align*}\liminf_{\varepsilon\rightarrow0^+}\frac{J_i\big(t,x_i;\,q_i^*\big) -J_{i}\big(t,x_i;\,q_i^{\varepsilon}\big) }{\varepsilon}\geqslant0,\end{align*}
for any
 $q_i(s)\in\mathcal{A}_i$
, then
 $q_i^*$
is the equilibrium reinsurance strategy and the value function for the insurer/reinsurer problem is defined by
 $V_i(t,x_i)\,:\!=\,J_{i}(t,x_i;\,q^*_i).$
Definition 2.3 (Market equilibrium). We say that the reinsurance market is in equilibrium and that
 $\eta^*\gt 0$
is the equilibrium reinsurance price if (i) for
 $i=1,2$
,
 $q_i^*(t;\,\eta^*)\in\mathcal{A}_i$
is an equilibrium strategy in the sense of Definition 2.2 given
 $\eta=\eta^*$
, and (ii) the following market clearing condition for the reinsurance is satisfied:
 $q_1^*(t;\,\eta^*)=q_2^*(t;\,\eta^*)\gt 0,$
for all
 $t\in[0,T]$
.
We can derive the above defined equilibrium reinsurance strategy and equilibrium reinsurance price under the reinsurance demand–supply game in three steps:
-
Step 1: Under the given reinsurance price
$\eta$
, we derive the optimal reinsurance demand strategy
$q_1^*(\eta)$
for the insurer; -
Step 2: Under the given reinsurance price
$\eta$
, the reinsurer chooses the optimal supply strategy
$q_2^*(\eta)$
; -
Step 3: To reach an equilibrium, the insurance company’s demand is matched by the supply of the reinsurance company, and we determine the price of reinsurance
$\eta^*\gt 0$
when
$q^*_1(\eta^*)=q^*_2(\eta^*)\gt 0$
.


The equilibrium problem for the insurer and reinsurer in the demand–supply game can be divided into three sub-problems.
-
(i) Insurer’s problem: The insurer determines the demand strategy to maximize the
$\alpha$
-maxmin MV objective functional, that is, (9)where
\begin{equation}\begin{split}\sup_{q_1\in\mathcal{A}_1}\left\{\alpha_1\underset{\phi_1\in\Phi}{\inf} \underline{J}_{1}^{\phi_{1}}(t,x_1;\,q_1)+(1-\alpha_1)\underset{\phi_1\in\Phi}{\sup}\overline{J}_{1}^{\phi_{1}}(t,x_1;\,q_1)\right\}\!,\end{split}\end{equation}
$q_1^*$
is the optimal reinsurance demand strategy to achieve the supremum.
-
(ii) Reinsurer’s problem: The reinsurer chooses the supply strategy to maximize the
$\alpha$
-maxmin MV objective functional, that is, (10)where
\begin{equation}\sup_{q_2\in\mathcal{A}_2}\left\{\alpha_2\underset{\phi_2\in\Phi}{\inf} \underline{J}_{2}^{\phi_{2}}(t,x_2;\,q_2)+(1-\alpha_2)\underset{\phi_2\in\Phi}{\sup}\overline{J}_{2}^{\phi_{2}}(t,x_2;\,q_2)\right\}\!,\end{equation}
$q_2^*$
is the optimal reinsurance supply strategy to achieve the supremum.
-
(iii) Equilibrium pricing problem: After solving the insurer’s and reinsurer’s problems, we obtain the optimal reinsurance demand–supply strategy
$(q^*_1(t;\,\eta),q^*_2(t;\,\eta))$
under the given reinsurance price
$\eta$
. When the market clearing condition is satisfied, we derive the equilibrium price
$\eta^*$
, which satisfies the following equation: for
\begin{align*}q_1^*(t;\, \eta^*)=q^*_2(t;\,\eta^*)\gt 0,\end{align*}
$t\in[0,T]$
, and
$q_1^*(t;\,\eta^*)$
,
$q_2^*(t;\,\eta^*)$
are called the equilibrium volume.


3. Main results
In this section, we solve the problems faced by the insurer and reinsurer via verification lemmas that characterize the value functions and corresponding equilibrium strategies. In Section 3.1, we derive the insurer’s equilibrium reinsurance demand strategy
 $q_1^*(\eta)$
given the premium strategy
 $\eta$
. Then, in Section 3.2, we study the reinsurer’s problem and obtain the equilibrium reinsurance supply strategy
 $q_2^*(\eta)$
for the reinsurer given the premium strategy
 $\eta$
. Finally, we solve the equilibrium reinsurance price
 $\eta^*$
under the market clearing condition (
 $q_1^*(\eta)=q_2^*(\eta)$
) in Section 3.3.
3.1. Solving insurer’s problem
First, we solve the insurer’s problem formulated in (9). For any reinsurance price
 $\eta$
and function
 $\psi(t,x_1)\in\mathcal{C}^{1,2}([0,T]\times\mathbb{R})$
, we define the integro-differential operator
 $\mathcal{L}^{q_1,\phi_1}_1$
for the insurer by
 \begin{align*}\mathcal{L}^{q_1,\phi_1}_{1}\psi(t,x_1)=\psi_t+\left(c-\lambda q_1m_1-\frac{\eta}{2}\lambda q_1^{2}m_2\right)\psi_{x_1}+\lambda(1-\phi_1)\!\int_0^\infty\! [\psi(t,x_1-(1-q_1)z)-\psi(t,x_1)]\mathrm{d}F(z),\end{align*}
where
 $\psi_t$
and
 $\psi_{x_1}$
represent the first-order partial derivatives w.r.t. corresponding variables. We present the insurer’s verification results in Lemma 3.1. We omit the proof because it is similar to that of Theorems 3.1 in Li et al. (Reference Li, Li and Xiong2016).
Lemma 3.1. Suppose that there exist
 $V_1(t,x_1),\underline{g}_1(t,x_1)$
and
 $\overline{g}_1(t,x_1)$
satisfying the following conditions:
-
(i) For any
$(t,x_1)\in[0,T]\times \mathbb{R}$
, (11)and
\begin{equation} \begin{split}0 &= \underset{q_1\in \mathcal{A}_1}{\sup}\Bigg\{\alpha_1 \underset{\phi_1\in\Phi}{\inf}{\kern-1pt}\left[\!\mathcal{L}^{q_1,\phi_1}_{1}V_1(t,x_1) - \frac{\gamma_1}{2}\mathcal{L}^{q_1,\phi_1}_{1}\underline{g}_1(t,x_1) ^2+ \gamma_1\underline{g}_1(t,x_1)\cdot\mathcal{L}^{q_1,\phi_1}_{1}\underline{g}_1(t,x_1) + \frac{\lambda\phi_1(t)^2}{2\beta_1}\right] \\&\quad +(1-\alpha_1)\underset{\phi_1\in\Phi}{\sup}{\kern-1pt}\left[\!\mathcal{L}^{q_1,\phi_1}_{1}V_1(t,x_1) - \frac{\gamma_1}{2}\mathcal{L}^{q_1,\phi_1}_{1}\overline{g}_1(t,x_1)^2+\gamma_1\overline{g}_1(t,x_1)\cdot\mathcal{L}_{1}^{q_1,\phi_1}\overline{g}_1(t,x_1) - \frac{\lambda\phi_1(t)^2}{2\beta_1}\right]\!\bigg\},\end{split}\end{equation}
$(q_1^*,\underline{\phi}^*_1,\overline{\phi}^*_1)$
denote the optimal values to achieve the supremum in
$q_1$
, infimum and supremum in
$\phi_1$
, respectively.
-
(ii) For any
$(t,x_1)\in[0,T]\times \mathbb{R}$
,
\begin{equation*}V_1(T,x_1) = x_1,\mathcal{L}_{1}^{q_1^*,\underline{\phi}^*_1}\underline{g}_1(t,x_1) = \mathcal{L}_1^{q_1^*,\overline{\phi}_1^*}\overline{g}_1(t,x_1) = 0,\underline{g}_1(T,x_1) = \overline{g}_1(T,x_1)=x_1.\end{equation*}
-
(iii) For any
$(t,x_1)\in[0,T]\times \mathbb{R}$
,
$\overline{\phi}_1^*(t)$
and
$\underline{\phi}_1^*(t)$
are independent of
$x_1$
.


Then
 $q_1^*$
is the equilibrium reinsurance demand strategy of the insurer and
 $V_1(t,x_1)$
is the equilibrium value function for the problem (9). In addition, we have
 $\underline{g}_1(t,x) = \mathbb{E}_{t,x_1}^{\underline{\phi}_1^*}[X_1^{q_1^*}(T)]$
and
 $\overline{g}_1(t,x_1) = \mathbb{E}_{t,x_1}^{\overline{\phi}_1^*}[X_1^{q_1^*}(T)]$
.
We omit the tedious calculations and simplify the extended HJB equation (11) as
 \begin{equation}\begin{split}0 = \underset{q_1\in[0,1]}{\sup} \bigg\{&V_t + \left(c-\lambda q_1m_1-\frac{\lambda\eta}{2}q_1^2m_2\ \right) V_x + \alpha_1 \underset{\phi_1\in\Phi}{\inf} \left\{ L^{\phi_1}(V_1, \underline{g}_1) + \frac{\lambda\underline{\phi}_1^2}{2\beta_1} \right\} \\&\quad + (1-\alpha_1)\underset{\phi_1\in\Phi}{\sup} \bigg\{ L^{\phi_1}(V_1, \overline{g}_1) - \frac{\lambda\overline{\phi}_1^2}{2\beta_1} \bigg\}\bigg\},\end{split}\end{equation}
where
 \begin{align*}L^{\phi_1}(V_1,g_1) = \lambda(1-\phi_1) \left[ \mathbb{E} \left( V_1(t,x_1-(1-q_1)Z) - V_1(t,x_1)\right) - \frac{\gamma_1}{2} \mathbb{E} \left( g_1(t,x_1-(1-q_1)Z) - g_1(t,x_1) \right)^2 \right]\!.\end{align*}
By the first-order condition on (12) w.r.t.
 $\phi_1$
, the infimum and supremum of
 $\phi_1$
in (12) are respectively achieved at
 \begin{equation*} \left\{\begin{split}&\overline{\phi}^*_1(t)=-\beta_1\left[ \mathbb{E} \left( V_1(t,x_1-(1-q_1)Z) - V_1(t,x_1)\right) - \frac{\gamma_1}{2} \mathbb{E} \big( \overline{g}_1(t,x_1-(1-q_1)Z) - \bar{g}_1(t,x_1) \big)^2 \right],\\&\underline{\phi}^*_1(t)=\beta_1\left[ \mathbb{E} \left( V_1(t,x_1-(1-q_1)Z) - V_1(t,x_1)\right) - \frac{\gamma_1}{2} \mathbb{E} \big( \underline{g}_1(t,x_1-(1-q_1)Z) - \underline{g}_1(t,x_1) \big)^2 \right]. \end{split} \right. \end{equation*}
Consider the following ansatz:
 \begin{equation}V_1(t,x_1)=x_1+A_1(t),\underline{g}_1(t,x_1)=x_1+\underline{B}_1(t),\overline{g}_1(t,x_1)=x_1+\overline{B}_1(t),\end{equation}
where
 $A_1(t),\underline{B}_1(t),\overline{B}_1(t)$
are deterministic functions with boundary conditions
 $A_1(T)=\underline{B}_1(T) = \overline{B}_1(T)=0$
. By substituting (13) into (12), the extended HJB equation changes to
 \begin{align*}A_1'(t) + c+\sup_{q_1\in[0,1]}\left\{-\lambda m_1q_1-\frac{\eta}{2}\lambda m_2q_1^2-\lambda h_1(q_1)+\frac{\lambda}{2}f(\alpha_1,\beta_1)h_1(q_1)^2\right\}=0,\end{align*}
where
 $h_1(q_1)=(1-q_1)m_1+\frac{\gamma_1}{2}(1-q_1)^2m_2$
and
 $f(\alpha_1,\beta_1)=(1-2\alpha_1)\beta_1$
. Equivalently, the optimal reinsurance demand strategy
 $q_1^*$
is determined by
 \begin{equation}\begin{split}q_1^*(\eta)&=\arg\inf_{q_1\in[0,1]}F(q_1)\\&=\arg\inf_{q_1\in[0,1]}\left\{m_1q_1+\frac{\eta}{2}m_2q_1^2+h_1(q_1)-\frac{1}{2}f(\alpha_1,\beta_1)h_1(q_1)^2\right\}\!.\end{split}\end{equation}
The remainder of this subsection is to examine the global minimum of
 $F(q_1)$
and find a more explicit expression for the demand strategy
 $q_1^*$
. The discussion of (14) is separated in two cases:
 $\alpha_1\in[\frac{1}{2},1]$
and
 $\alpha_1\in[0,\frac{1}{2})$
. The insurer is ambiguity-averse/neutral in the former case, while ambiguity-seeking in the latter case. The next lemma gives the results of (14) when
 $\alpha_1\in[\frac{1}{2},1]$
.
Lemma 3.2. When
 $\alpha_1\in[\frac{1}{2},1]$
, the global minimum point
 $q_1^*$
of function
 $F(q_1)$
is the unique solution of the following equation in the interval (0, 1):
 \begin{equation}m_1+\eta m_2q_1+h^{'}_1(q_1)-f(\alpha_1,\beta_1)h_1(q_1)h^{'}_1(q_1)=0.\end{equation}
Specially, when
 $\alpha_1=\frac{1}{2}$
, the global minimum point
 $q_1^*$
has the explicit form:
 \begin{align*}q_1^*(\eta)=\frac{\gamma_1}{\eta+\gamma_1}.\end{align*}
Proof. See Online Appendix A.1.
In Lemma 3.2, it is interesting to find that the optimal reinsurance demand strategy
 $q_1^*$
naturally falls in the interval (0, 1). For the ambiguity-averse/neutral insurer, she is always willing to transfer the insurance business to the reinsurer whatever the reinsurance price is. In the following corollary, we provide some interesting properties of the optimal reinsurance demand strategy
 $q_1^*$
. The proof is plain, and hence we omit it.
Corollary 3.1. When
 $\alpha_1\in[\frac{1}{2},1]$
, the optimal reinsurance demand strategy
 $q_1^*(\eta)$
satisfies the following properties:
-
(i)
$q_1^*(\eta)$
decreases w.r.t.
$\eta$
, and
$\lim_{\eta\rightarrow0^+}q_1^*(\eta)=1,\lim_{\eta\rightarrow\infty}q_1^*(\eta)=0.$
-
(ii)
$q_1^*(\eta)$
increases with
$\gamma_1$
within the admissible parameter region. Its lower-boundary limits are We do not state the limit as
\begin{equation*} \lim_{\gamma_1\rightarrow0}q_1^*(\eta)=\left\{\begin{split}&\displaystyle\frac{f(\alpha_1,\beta_1)m_1^2}{f(\alpha_1,\beta_1)m_1^2-\eta m_2}\gt 0, \ \ \ \ \alpha_1\in\left(\frac{1}{2},1\right],\\&0, \qquad \qquad\qquad \qquad \qquad \alpha_1=\frac{1}{2}. \end{split} \right. \end{equation*}
$\gamma_1\to\infty$
, because it leaves the admissible parameter region of the given
$\beta_1$
in Assumption 2.1.


As the reinsurance premium increases, the insurer retains more risk and reduces reinsurance demand. Within the admissible parameter region, demand increases with risk aversion. Importantly, when
 $\alpha_1\gt \frac12$
, ambiguity aversion alone generates strictly positive demand even at the boundary
 $\gamma_1\rightarrow0$
; only the ambiguity-neutral case has a zero limit. Indeed, when
 $\gamma_1\rightarrow 0$
, the ambiguity-averse insurer decides to retain part of the business because the model uncertainty increases the future risk. Moreover, when DM is ambiguity-neutral (i.e.,
 $\alpha_1=\frac{1}{2}$
), it is optimal for insurer to purchase no reinsurance due to the non-cheap reinsurance premium.
In what follows, we focus on the problem (14) in the ambiguity-seeking case. The analysis of ambiguity-seeking case is much more sophisticated than that in the ambiguity-averse/neutral case. For notational convenience, we define the following functions:
 \begin{equation} \left\{\begin{split} &D_0\,:\!=\,\frac{\gamma_1m_2}{(m_1+\frac{\gamma_1}{2}m_2)(m_1+\gamma_1m_2)},\\ &D_1(\alpha_1,\beta_1)\,:\!=\,\left[-\gamma_1+\frac{m_1^2}{m_2}f(\alpha_1,\beta_1)\right]_{+},\\ &D_2(\alpha_1,\beta_1)\,:\!=\,\left[-\gamma_1+\frac{(m_1+\gamma_1m_2)^2+(m_1+\frac{\gamma_1}{2}m_2)\gamma_1m_2}{m_2}f(\alpha_1,\beta_1)\right]_{+}, \end{split} \right.\end{equation}
where the notation
 $[\cdot]_+$
stands for
 $\max\{0,\cdot\}$
. The global minimum of function
 $F(q_1)$
under ambiguity-seeking case is summarized in the following lemma.
Lemma 3.3. When
 $\alpha_1\in[0,\frac{1}{2})$
, the global minimum of function
 $F(q_1)$
admits to one of the following two cases:
-
(1) When
$(\frac{1-D_0/\beta_1}{2})_+\leqslant\alpha_1\lt \frac{1}{2}$
, the function
$F(q_1)$
has the following properties:-
(1.i) If
$0\leqslant\eta\lt D_2(\alpha_1,\beta_1)$
, the function
$F^{''}(q_1)$
has the unique zero
$\ddot{q}_1$
in the interval of (0, 1), which is given by The global minimum
\begin{align*}\ddot{q}_1=1+\frac{3m_1-\sqrt{3m_1^2+\frac{6m_2(\eta+\gamma_1)}{f(\alpha_1,\beta_1)}}}{3\gamma_1m_2}. \end{align*}
$q_1^*=\dot{q}_1$
is the unique solution of the Equation (15) in the interval of
$(\ddot{q}_1,1)$
.
-
(1.ii) If
$\eta\geqslant D_2(\alpha_1,\beta_1)$
, the function
$F(q_1)$
has the global minimum
$q_1^*=\hat{q}_1,$
where
$\hat{q}_1$
is the unique solution of the Equation (15) in the interval of (0, 1).
-
-
(2) When
$0\leqslant\alpha_1\lt (\frac{1-D_0/\beta_1}{2})_{+}$
, the function
$F(q_1)$
has the following properties:-
(2.i) If
$0\leqslant\eta\leqslant D_1(\alpha_1,\beta_1)$
or
$\eta\geqslant D_2(\alpha_1,\beta_1)$
, the function
$F(q_1)$
has the global minimum
$q_1^*=0$
. -
(2.ii) If
$D_1(\alpha_1,\beta_1)\lt \eta\lt D_2(\alpha_1,\beta_1)$
, the global minimum of function
$F(q_1)$
admits to one of the following two cases:-
(2.ii.a) When
$F^{'}(\ddot{q}_1)\geqslant0$
, we have the global minimum
$q_1^*=0$
. -
(2.ii.b) When
$F^{'}(\ddot{q}_1)\lt 0$
, the global minimum
$q_1^*$
is given by where
\begin{align*} q_1^*=\arg\inf_{q_1\in\{0,\dot{q}_{12}\}} F(q_1),\end{align*}
$\dot{q}_{12}$
is the unique solution of the Equation (15) in the interval of
$(\ddot{q}_1,1)$
.
-
-


Proof. See Online Appendix A.2.
Remark 3.1. In mildly ambiguity-seeking case, that is,
 $(\frac{1-D_0/\beta_1}{2})_{+}\leqslant\alpha_1\lt \frac{1}{2}$
, we find that the insurer always chooses to transfer partial risk to the reinsurer no matter of the reinsurance premium rate
 $\eta$
, which is parallel to the results in the ambiguity-averse/neutral case. In other words, if the ambiguity aversion level
 $\beta_1$
is relatively small (
 $0\lt \beta_1\leqslant\frac{D_0}{1-2\alpha_1}$
), it means that the insurer is relatively confident about the reference model under probability measure
 $\mathbb{P}$
. As a result, she is still willing to purchase reinsurance protection. However, when the ambiguity aversion parameter
 $\beta_1$
is relatively large (
 $\beta_1\gt \frac{D_0}{1-2\alpha_1}$
), the insurer is suspicious of the reference model under
 $\mathbb{P}$
and exhibits the behavioural characteristics of ambiguous preference.
Remark 3.2. In severely ambiguity-seeking case, that is,
 $0\leqslant\alpha_1\lt (\frac{1-D_0/\beta_1}{2})_{+}$
, the optimal reinsurance demand strategy is dependent on the price
 $\eta$
, and may be not unique. Some interesting results are given as follows:
-
(i) When the reinsurance price is relatively low (
$\eta\lt D_1$
), the ambiguity-seeking insurer will keep all the insurance risk
$(q_1^*=0)$
if
$f(\alpha_1,\beta_1)\gt \frac{(\eta+\gamma_1)m_2}{m_1^2}$
, which is a surprising result for us. Here, we can see that this case exists when the ambiguity level
$\beta_1$
is high and
$\alpha_1$
is close to 0. To be precise, the insurer considers herself more knowledgeable or competent than the others and declines to transfer any business even under a cheap reinsurance premium. -
(ii) When the reinsurance price is relatively high (
$\eta\gt D_2$
), the ambiguity-seeking insurer directly chooses to refuse any reinsurance protection, which is different from the results when the insurer is ambiguity-averse/neutral. That is, the expensive reinsurance price plays a dominant role and discourages the insurer from purchasing reinsurance protection. -
(iii) When the reinsurance price
$\eta\in(D_1,D_2)$
, we can see that the optimal reinsurance demand strategy may not be unique for the ambiguity-seeking insurer. There exists an indifference price curve for the ambiguity-seeking insurer as For fixed
\begin{align*}l\,:\!=\,\{(f,\eta)|F(0)=F(\dot{q}_{12})\}.\end{align*}
$f(\alpha_1,\beta_1)$
, if the reinsurance price
$\eta$
is below the indifference price curve l, the optimal reinsurance demand strategy is
$q_1^*=\dot{q}_{12}$
. In contrast, the insurer does not purchase the reinsurance business when the reinsurance price is expensive.


Note that
 \begin{equation*}\lim_{f\rightarrow0+} D_1(\alpha_1,\beta_1)=\lim_{f\rightarrow0+} D_2(\alpha_1,\beta_1)=0.\end{equation*}
Hence, some cases will be trivial in the Lemma 3.3. In the following corollary, we give the limiting case of our results.
Corollary 3.2. When
 $\alpha_1\in[0,\frac{1}{2})$
, we have the following results:
-
(i) If
$\alpha_1\rightarrow\frac{1}{2}-$
or
$\beta_1\rightarrow0+$
, the function
$F(q_1)$
has the global minimum
$q_1^*=\hat{q}_1$
. -
(ii) If
$\gamma_1=0$
, the function
$F(q_1)$
has the global minimum
$q_1^*=0$
.


To help the reader understand the variation of the optimal reinsurance demand strategy when in the severely ambiguity-seeking case (
 $0\leqslant\alpha_1\lt (\frac{1-D_0/\beta_1}{2})_{+}$
), we provide the following illustrative figures. The parameters are set as follows:
 $m_1=1,m_2=2$
and
 $\gamma_1=3$
.
Figure 1 shows that as the reinsurance price
 $\eta$
increases, the optimal reinsurance demand strategy decreases to 0. In fact, we observe a threshold of the reinsurance price in this example. The insurer’s optimal decision is to choose partial insurance risk exposure
 $(q_1^*\gt 0)$
when the reinsurance price is below the threshold and to purchase no reinsurance
 $(q_1^*=0)$
as the premium increases above the threshold. Figure 2 illustrates a similar pattern of the optimal strategy to Figure 1. As the ambiguity attitude
 $\alpha_1$
decreases or
 $\beta_1$
increases, the optimal reinsurance demand strategy
 $q_1^*$
decreases to 0. On the one hand, a smaller value of
 $\alpha_1$
implies that the insurer is more ambiguity-seeking and imposes a less weight on the worst-case scenario (
 $\alpha_1\rightarrow0$
). In other words, the insurer is sufficiently optimistic and prefers the uncertainty. On the other hand, the increase of
 $\beta_1$
indicates that the insurer lays smaller weight on the deviation of the ambiguous measure from the reference measure, reflecting the insurer’s higher level of ambiguity attitude.
The optimal reinsurance demand strategy under different reinsurance price
 $\eta$
given
 $f=D_0+0.1$
.

The optimal reinsurance demand strategy under different preference functions f given
 $\eta=0.2$
.

Now we are ready to present the optimal reinsurance demand strategy and value function of the insurer’s problem in the following theorem, which are immediate corollaries of Lemmas 3.2 and 3.3. Denote the related regions as follows:
 \begin{equation*}\mathcal{O}_1=\mathcal{M}_1^c\wedge\mathcal{M}_2\wedge\mathcal{M}_4, \ \ \ \ \mathcal{O}_2=\mathcal{M}_1\wedge\mathcal{M}_3, \ \ \ \ \mathcal{O}_3=\mathcal{M}_1\wedge\mathcal{M}_3^c, \ \ \ \ \mathcal{O}_4=\mathcal{M}_1^c\wedge\mathcal{M}_2\wedge\mathcal{M}^c_4,\end{equation*}
where
 \begin{equation}\left\{\begin{split}&\mathcal{M}_1=\{(\eta,f)\,:\,f(\alpha_1,\beta_1) \lt D_0,\eta\geqslant 0\}, \ \ \ \ \mathcal{M}_2=\{(\eta,f) \, : \, D_1(\alpha_1,\beta_1) \lt \eta \lt D_2(\alpha_1,\beta_1)\},\\&\mathcal{M}_3=\{(\eta,f) \, : \, \eta\geqslant D_2(\alpha_1,\beta_1)\}, \qquad \quad \, \ \mathcal{M}_4=\{(\eta,f) \, : \, F(0)\lt F(\dot{q}_{12})\}.\end{split}\right.\end{equation}
Theorem 3.1. Given the reinsurance price
 $\eta$
, we have the following results:
-
(i) The optimal reinsurance demand strategy
$q_1^*(\eta)$
of insurer is given by where
\begin{align*}q_1^*(\eta)=\hat{q}_1\cdot1_{\{(\eta,f)\in\mathcal{O}_2\}}+\dot{q}_1\cdot1_{\{(\eta,f)\in\mathcal{O}_3\}}+\dot{q}_{12}\cdot1_{\{(\eta,f)\in\mathcal{O}_4\}},\end{align*}
$\hat{q}_1$
is the unique solution of the Equation (15) in the interval (0, 1), and
$\dot{q}_{12}$
the unique solution of the equation
$F^{'}(q_1)=0$
in the interval
$(\ddot{q}_1,1)$
.
-
(ii) The corresponding equilibrium value function is given by
\begin{align*}V_1(t,x_1)=x_1+\left[c-\lambda m_1q_1^*-\frac{\lambda \eta}{2}(q_1^*)^2m_2-\lambda h(q_1^*)+\frac{1}{2}f(\alpha_1,\beta_1)\lambda h_1(q_1^*)^2\right](T-t).\end{align*}
-
(iii) The associated probability distortion functions of extremely ambiguity-averse measure and the extremely ambiguity-seeking measure are given by
\begin{align*}(\overline{\phi}^*_1(t),\underline{\phi}^*_1(t))=(\beta_1h_1(q_1^*),-\beta_1h_1(q_1^*)).\end{align*}


It is worth noting that the probability distortion functions
 $\bar{\phi}_1^*(t)$
and
 $\underline{\phi}_1^*(t)$
are both bounded under the Assumption 2.1. It naturally satisfies the jump-exponential martingale integrability condition, which defines a new probability measure. To illustrate the results in each region more clearly, we provide the Figure 3 to show the optimal reinsurance demand strategy of the insurer.
The optimal reinsurance demand strategy for different risk and ambiguity attitudes.

Table 2. Long description
A table comparing optimal reinsurance demand strategies for different risk and ambiguity attitudes. The table has four rows and three columns. The columns are labeled ‘Ambiguity attitude’, ‘Risk-neutral (γ_1 = 0)’, and ‘Risk-averse (γ_1 > 0)’. The rows are labeled ‘Ambiguity-averse (α_1 ∈ (1/2, 1])’, ‘Ambiguity-neutral (α_1 = 1/2)’, and ‘Ambiguity-seeking (α_1 ∈ [0, 1/2))’. Row 1: Ambiguity-averse (α_1 ∈ (1/2, 1]), Risk-neutral (γ_1 = 0), q_1* ∈ (0, 1); Risk-averse (γ_1 > 0), q_1* ∈ (0, 1). Row 2: Ambiguity-neutral (α_1 = 1/2), Risk-neutral (γ_1 = 0), q_1* = 0; Risk-averse (γ_1 > 0), q_1* = γ_1/(γ_1+η). Row 3: Ambiguity-seeking (α_1 ∈ [0, 1/2)), Risk-neutral (γ_1 = 0), q_1* = 0; Risk-averse (γ_1 > 0), q_1* ∈ ["0", 1].", "EDH": "
The sketch of the optimal reinsurance demand strategy in each region.

We end this subsection by discussing the influence of different risk and ambiguity attitudes on the optimal demand strategy
 $q^*_1$
in Table 2. Due to the expensive reinsurance premium principle, the risk-neutral insurer prefers to keep all the insurance business
 $(q_1^*=0)$
.
3.2. Solving reinsurer’s problem
For any reinsurance price
 $\eta$
and function
 $\psi(t,x_2)\in\mathcal{C}^{1,2}([0,T]\times\mathbb{R})$
, we define the integro-differential operator
 $\mathcal{L}^{q_2,\phi_2}_2$
for the reinsurer by
 \begin{align*}\mathcal{L}^{q_2,\phi_2}_{2}\psi(t,x_2)\,:\!=\,\psi_t+\left(\lambda q_2m_1+\frac{\eta}{2}\lambda q_2^{2}m_2\right)\psi_{x_2}+\lambda(1-\phi_2)\int_0^\infty[\psi(t,x_2-q_2z)-\psi(t,x_2)]\mathrm{d}F(z).\end{align*}
Next, we present the reinsurer’s verification lemma and omit the proof because it is similar to the proof of Lemma 3.1.
Lemma 3.4. Suppose that there exist
 $V_2(t,x_2),\underline{g}_2(t,x_2)$
and
 $\overline{g}_2(t,x_2)$
satisfying the following conditions:
-
(i) For any
$(t,x_2)\in[0,T]\times \mathbb{R}$
, (18)and
\begin{equation} \begin{split}0 = &\underset{q_2\in [0,1]}{\sup}\Bigg\{\alpha_2 \underset{\phi_2\in\Phi}{\inf}\left[\!\mathcal{L}^{q_2,\phi_2}_{2}V_2(t,x_2) - \frac{\gamma_2}{2}\mathcal{L}^{q_2,\phi_2}_{2}\underline{g}_2(t,x_2)^2+ \gamma_2\underline{g}_2(t,x_2)\cdot\mathcal{L}^{q_2,\phi_2}_{2}\underline{g}_2(t,x_2) + \frac{\lambda\phi_2(t)^2}{2\beta_2}\right] \\&+(1-\alpha_2)\underset{\phi_2\in\Phi}{\sup}{\kern-1pt}\left[\!\mathcal{L}^{q_2,\phi_2}_{2}V_2(t,x_2) - \frac{\gamma_2}{2}\mathcal{L}^{q_2,\phi_2}_{2}\overline{g}_2(t,x_2)^2+\gamma_2\overline{g}_2(t,x_2)\cdot\mathcal{L}^{q_2,\phi_2}_2\overline{g}_2(t,x_2) - \frac{\lambda\phi_2(t)^2}{2\beta_2}\right]\!\bigg\},\end{split}\end{equation}
$(q_2^*,\underline{\phi}^*_2,\overline{\phi}^*_2)$
denote the optimal values to achieve the supremum in
$q_2$
, infimum and supremum in
$\phi_2$
, respectively.
-
(ii) For any
$(t,x_2)\in[0,T]\times \mathbb{R}$
,
\begin{equation*}V_2(T,x_2) = x_2, \ \ \ \ \mathcal{L}_{2}^{q_2^*,\underline{\phi}^*_2}\underline{g}_2(t,x_2) = \mathcal{L}_2^{q_2^*,\overline{\phi}_2^*}\overline{g}_2(t,x_2) = 0, \ \ \ \ \underline{g}_2(T,x_2) = \overline{g}_2(T,x_2)=x_2.\end{equation*}
-
(iii) For any
$(t,x_2)\in[0,T]\times \mathbb{R}$
,
$\overline{\phi}_2^*(t)$
and
$\underline{\phi}_2^*(t)$
are independent of
$x_2$
.


Then,
 $q_2^*$
is the optimal reinsurance supply strategy of the reinsurer and
 $V_2(t,x_2)$
is the equilibrium value function to the problem (10). In addition, we have
 $\underline{g}_2(t,x_2) = \mathbb{E}_{t,x_2}^{\underline{\phi}_2^*}[X_2^{q_2^*}(T)]$
and
 $\overline{g}_2(t,x_2) = \mathbb{E}_{t,x_2}^{\overline{\phi}_2^*}[X_2^{q_2^*}(T)]$
.
Similar to the discussion in the insurer’s problem, the optimal reinsurance supply strategy
 $q_2^*(\eta)$
for the reinsurer is determined by
 \begin{equation}\begin{split}q_2^*(\eta)&=\arg\inf_{q_2\in[0,1]}G(q_2)\\&=\arg\inf_{q_2\in[0,1]}\left\{-m_1q_2-\frac{\eta}{2}m_2q_2^2+h_2(q_2)-\frac{1}{2}f(\alpha_2,\beta_2)h_2(q_2)^2\right\},\end{split}\end{equation}
where
 $h_2(q_2)= m_1q_2+\frac{\gamma_2}{2}m_2q_2^2$
and
 $f(\alpha_2,\beta_2)=(1-2\alpha_2)\beta_2$
. We present the local minimum point
 $q_2^*$
of function
 $G(q_2)$
in the following lemmas. It is worth pointing out that the results for reinsurer are totally different from those in the insurer’s problem. For convenience, we donate that
 \begin{equation*} \left\{\begin{split}&\tilde{D}_1(\alpha_2,\beta_2)=\left[\gamma_2-f(\alpha_2,\beta_2)\frac{m_1^2}{m_2}\right]_{+},\\&\tilde{D}_2(\alpha_2,\beta_2)=\left[\gamma_2-f(\alpha_2,\beta_2)\frac{(m_1+\frac{\gamma_2}{2}m_2)(m_1+\gamma_2m_2)}{m_2}\right]_{+},\\&\tilde{D}_3(\alpha_2,\beta_2)=\left[\gamma_2-f(\alpha_2,\beta_2)\frac{(m_1+\gamma_2m_2)^2+(m_1+\frac{\gamma_2}{2}m_2)\gamma_2m_2}{m_2}\right]_{+},\\&\tilde{D}_4(\alpha_2,\beta_2)=\left[\gamma_2-f(\alpha_2,\beta_2)\frac{(m_1+\frac{\gamma_2}{2}m_2)^2}{m_2}\right]_{+}, \end{split} \right.\end{equation*}
and
 $0\lt \tilde{D}_1(\alpha_2,\beta_2)\lt \tilde{D}_4(\alpha_2,\beta_2)\lt \tilde{D}_2(\alpha_2,\beta_2)\lt \tilde{D}_3(\alpha_2,\beta_2)$
when
 $f(\alpha_2,\beta_2)\lt 0$
. In the next lemma, we provide the global minimum of function
 $G(q_2)$
when the reinsurer is ambiguity-averse, that is,
 $\alpha_2\in(\frac{1}{2},1]$
.
Lemma 3.5. When
 $\alpha_2\in(\frac{1}{2},1]$
, the function
 $G(q_2)$
has the following properties:
-
(i) If
$\eta\leqslant\tilde{D}_1(\alpha_2,\beta_2)$
, then the function
$G(q_2)$
has the global minimum
$q_2^*(\eta)=0$
. -
(ii) If
$\tilde{D}_1(\alpha_2,\beta_2)\lt \eta\lt \tilde{D}_2(\alpha_2,\beta_2)$
, the global minimum
$q_2^*$
is the unique solution of the following equation in the interval of (0, 1): (20)
\begin{equation} -m_1-\eta m_2q_2+h_2^{'}(q_2)-f(\alpha_2,\beta_2)h_2(q_2)h_2^{'}(q_2)=0. \end{equation}
-
(iii) If
$\eta\geqslant \tilde{D}_2(\alpha_2,\beta_2)$
, we have the global minimum
$q_2^*(\eta)=1$
.


Proof. See Online Appendix B.1.
From Lemma 3.5, we can see that the ambiguity-averse reinsurer tends to retain more insurance risk when the premium rate
 $\eta$
increases, which is in line with the actual situation. More precisely, the reinsurer is unwilling to sign the reinsurance contract
 $(q_2^*=0)$
when
 $\eta\leqslant \tilde{D}_1(\alpha_2,\beta_2)$
. Furthermore, when
 $\eta\geqslant \tilde{D}_2(\alpha_2,\beta_2)$
, the reinsurer accepts all the risk coming from the insurer. For this reason, we call
 $\tilde{D}_1(\alpha_2,\beta_2)$
and
 $\tilde{D}_2(\alpha_2,\beta_2)$
as the non-reinsurance supply and full-reinsurance supply points, respectively. The reinsurance price can be divided into three subregions:
-
(i)
$\tilde{\mathcal{O}}_1:$
Non-reinsurance supply (
$q_2^*=0$
); -
(ii)
$\tilde{\mathcal{O}}_2:$
Partial-reinsurance supply (
$q_2^*\in(0,1)$
); -
(iii)
$\tilde{\mathcal{O}}_3:$
Full-reinsurance supply (
$q_2^*=1$
).


Meanwhile, we find that
 \begin{align*}\frac{\partial\tilde{D}_1(\alpha_2,\beta_2)}{\partial\alpha_2}\gt 0, \quad \frac{\partial\tilde{D}_1(\alpha_2,\beta_2)}{\partial\beta_2}\gt 0, \quad \frac{\partial\tilde{D}_1(\alpha_2,\beta_2)}{\partial\gamma_2}\gt 0,\end{align*}
 \begin{align*}\frac{\partial\tilde{D}_2(\alpha_2,\beta_2)}{\partial\alpha_2}\gt 0, \quad \frac{\partial\tilde{D}_2(\alpha_2,\beta_2)}{\partial\beta_2}\gt 0, \quad \frac{\partial\tilde{D}_2(\alpha_2,\beta_2)}{\partial\gamma_2}\gt 0,\end{align*}
which means that the price threshold for reinsurer entering the reinsurance market increases w.r.t. the parameters
 $\alpha_2$
,
 $\beta_2$
, and
 $\gamma_2$
.
Lemma 3.6. When
 $\alpha_2\in[0,\frac{1}{2})$
, the function
 $G(q_2)$
has the global minimum as follows:
 \begin{equation*}q_2^*(\eta)=\left\{\begin{split}&0,&\eta\lt \tilde{D}_4(\alpha_2,\beta_2),\\&1,&\eta\gt \tilde{D}_4(\alpha_2,\beta_2),\\&0\text{or}1,&\eta=\tilde{D}_4(\alpha_2,\beta_2).\end{split}\right.\end{equation*}
Specially, when
 $\alpha_2=\frac{1}{2}$
, the global minimum point
 $q_2^*$
has the explicit form:
 \begin{align*}q_2^*(\eta)=\tilde{q}_2\cdot\mathbf{1}_{\{\eta=\gamma_2\}}+\mathbf{1}_{\{\eta\gt \gamma_2\}},\end{align*}
where
 $\tilde{q}_2$
is the arbitrary constant in [0, 1].
Proof. See Online Appendix B.2.
Lemma 3.6 suggests that the reinsurer’s optimal reinsurance supply strategy is a bang–bang control when she is ambiguity-seeking/neutral. The bang–bang control is widely adopted in economical decision-making for its simplicity and convenience, see, for example, Evstigneev et al. (Reference Evstigneev, Schürger and Taksar2004) and Chen et al. (Reference Chen, Liu and Weng2019). There exists a price threshold
 $\tilde{D}_4(\alpha_2,\beta_2)$
, which leads to the completely different results. When the reinsurance price is lower than
 $\tilde{D}_4(\alpha_2,\beta_2)$
, the ambiguity-seeking/neutral reinsurer provides no reinsurance protection to the insurer. When the reinsurance price is in excess of the threshold, full reinsurance is accepted by the reinsurer. It is worth noting that
 $q_2^*$
can take value in 0 or 1 when
 $\eta=\tilde{D}_4(\alpha_2,\beta_2)$
.
The optimal reinsurance supply strategy for the reinsurer and value function are presented in the following theorem, which are immediate corollaries of Lemmas 3.5 and 3.6.
Theorem 3.2. Given the reinsurance price
 $\eta\gt 0$
, we have the following results:
-
(i) When
$\alpha_2\in(\frac{1}{2},1]$
, the optimal reinsurance supply strategy
$q_2^*(\eta)$
of reinsurer is given by where
\begin{equation*} q_2^*(\eta)=\hat{q}_2\cdot\mathbf{1}_{\{\tilde{D}_1(\alpha_2,\beta_2)\lt \eta\lt \tilde{D}_2(\alpha_2,\beta_2)\}}+\mathbf{1}_{\{\eta\geqslant\tilde{D}_2(\alpha_2,\beta_2)\}}, \end{equation*}
$\hat{q}_2$
is the unique solution of (20), and when
$\alpha_2\in[0,\frac{1}{2})$
, When
\begin{equation*} q_2^*(\eta)=\left\{\begin{split} & 0,&\eta\lt \tilde{D}_4(\alpha_2,\beta_2),\\ &1,&\eta\gt \tilde{D}_4(\alpha_2,\beta_2),\\ & 0 \ \text{or} \ 1,&\eta=\tilde{D}_4(\alpha_2,\beta_2). \end{split} \right. \end{equation*}
$\alpha_2=\frac{1}{2}$
, the optimal reinsurance supply strategy
$q_2^*(\eta)$
is where
\begin{align*}q_2^*(\eta)=\tilde{q}_2\cdot\mathbf{1}_{\{\eta=\gamma_2\}}+\mathbf{1}_{\{\eta\gt \gamma_2\}},\end{align*}
$\tilde{q}_2$
is the arbitrary constant in [0, 1].
-
(ii) The corresponding value function is given by
\begin{align*}V_2(t,x_2)=x_2+\left[\lambda m_1q_2^*+\frac{\lambda \eta}{2}(q_2^*)^2m_2-\lambda h_2(q_2^*)+\frac{1}{2}f(\alpha_2,\beta_2)\lambda h_2(q_2^*)^2\right](T-t).\end{align*}
-
(iii) The associated probability distortion functions of extremely ambiguity-averse measure and the extremely ambiguity-seeking measure are given by
\begin{align*}(\overline{\phi}^*_2(t),\underline{\phi}^*_2(t))=(\beta_2h_2(q_2^*),-\beta_2h_2(q_2^*)).\end{align*}


Here, it is obvious that the probability distortion functions are bounded, that is,
 $\underline{\phi}^*_2(t)\in(-1,1)$
and
 $\bar{\phi}^*_2(t)\in(-1,1)$
. Hence, the exponential term in jump-exponential martingale integrability condition is a bounded value. It remains bounded after exponentiation, which ensures that the new probability measure is well defined. We provide Figure 4 to illustrate the optimal reinsurance supply strategy for the reinsurer. In Figure 4(a), the whole region is divided into three subregions, which have been given in Lemma 3.5. The x-intercept accurately captures how the parameters affect the optimal supply strategy. In Figure 4(b), it can be seen that the region
 $\tilde{\mathcal{O}}_2$
disappears since we have
 $\tilde{D}_1=\tilde{D}_2$
when
 $\gamma_2=0$
. At this point, the reinsurer is risk-neutral and only cares about the expectation return of the terminal wealth. Hence, she chooses to fully accept or refuse the reinsurance business, which depends on the reinsurance price and ambiguity-attitude.
The sketch of the optimal reinsurance supply strategy.

Then, we turn to investigate the influence of risk attitudes on the optimal reinsurance supply strategy. The ambiguity-neutral and ambiguity-averse reinsurers behave in the same way with risk-neutral preference. While the behavior of risk-averse reinsurer shows no difference under the ambiguity-averse and ambiguity-neutral preferences. The corresponding results are summarized in Table 3.
The optimal reinsurance supply strategy for different risk and ambiguity attitudes.

Table 3. Long description
A table comparing reinsurance supply strategies for different risk and ambiguity attitudes. The table has 3 rows and 3 columns. Column headers are Reinsurance supply, Risk-neutral (γ2 = 0), and Risk-averse (γ2 > 0). Row labels are Ambiguity-averse (α2 ∈ (1/2, 1]), Ambiguity-neutral (α2 = 1/2), and Ambiguity-seeking (α2 ∈ [0, 1/2)). Row 1: Ambiguity-averse (α2 ∈ (1/2, 1]), Risk-neutral (γ2 = 0) q2* = 0 or q2* = 1, Risk-averse (γ2 > 0) q2* ∈ [0, 1]. Row 2: Ambiguity-neutral (α2 = 1/2), Risk-neutral (γ2 = 0) q2* = 1, Risk-averse (γ2 > 0) q2* ∈ [0, 1]. Row 3: Ambiguity-seeking (α2 ∈ [0, 1/2)), Risk-neutral (γ2 = 0) q2* = 1, Risk-averse (γ2 > 0) q2* = 0 or q2* = 1.
3.3. Equilibrium reinsurance price
In Sections 3.1 and 3.2, the individual optimal reinsurance demand and supply strategies are derived for the insurer and reinsurer, respectively. In this section, we aim to derive the market-feasible equilibrium strategies under the market clearing condition (
 $q_1^*(t)=q^*_2(t)$
for
 $t\in[0,T]$
). For convenience, we recall the results and present the scope of the optimal strategies with different ambiguity attitudes in the following table.
From Table 4, we can see the requirement for the success of the market clearing condition is that the reinsurer should be ambiguity-averse or ambiguity-neutral. If the reinsurer is ambiguity seeking (
 $\alpha_2\in \left[0,\frac{1}{2}\right]$
), she is willing to accept all the insurance risk (
 $q_2^*=1$
) if the reinsurance premium loading is large (
 $\eta\gt \tilde{D}_4(\alpha_2,\beta_2)$
), while refuses any risk (
 $q_2^*=0$
) if the reinsurance premium loading is small (
 $\eta\lt \tilde{D}_4(\alpha_2,\beta_2)$
). Therefore, it is impossible for the insurer and reinsurer to sign the reinsurance contract under the market clearing condition. To this end, we first consider the ambiguity-neutral reinsurer in the market. According to the optimal results in Theorem 3.2, we find that the market clearing condition can be reached if and only if
 $\eta^*=\gamma_2$
because the reinsurer is indifferent to accepting any reinsurance business in this case. Hence, the equilibrium price can be attained when the optimal demand is strictly positive given
 $\eta=\gamma_2$
. The following proposition summarizes the key results of our analysis.
The optimal reinsurance demand and supply strategies for different ambiguity attitudes.

Table 4. Long description
A table comparing reinsurance demand and supply strategies for different ambiguity attitudes. The table has three rows and three columns. The columns are labeled as Ambiguity attitude, Reinsurance demand, and Reinsurance supply. The rows are labeled as Averse, Neutral, and Seeking. Row 1: Ambiguity attitude, Averse; Reinsurance demand, q subscript 1 asterisk is in the interval (0, 1); Reinsurance supply, q subscript 2 asterisk is in the interval [0, 1]. Row 2: Ambiguity attitude, Neutral; Reinsurance demand, q subscript 1 asterisk is equal to gamma subscript 1 divided by (gamma subscript 1 plus n); Reinsurance supply, q subscript 2 asterisk is in the interval [0, 1]. Row 3: Ambiguity attitude, Seeking; Reinsurance demand, q subscript 1 asterisk is in the interval [0, 1]; Reinsurance supply, q subscript 2 asterisk is equal to 0 or q subscript 2 asterisk is equal to 1.
Proposition 3.1. Given the optimal demand function
 $q_1^*(\eta)$
in Theorem 3.1, when the reinsurer is ambiguity-neutral and risk-averse, the reinsurance market has the unique equilibrium reinsurance price
 $\eta^*=\gamma_2$
if and only if
 $q_1^*(\gamma_2)\gt 0$
.
Then, we move on to discussing the case of ambiguity-averse reinsurer. Before that, we summarize the property of the optimal demand strategy
 $q_1^*(\eta)$
and supply strategy
 $q_2^*(\eta)$
in Table 5.
The properties of the optimal demand strategy
 $q_1^*(\eta)$
and supply strategy
 $q_2^*(\eta)$
.

Table 5. Long description
A table comparing the properties of optimal demand and supply strategies. The table has four rows and five columns. Column headers are Strategy, Ambiguity attitude, Continuity, Monotonicity, and Limiting values. Row 1: Strategy q subscript 1 (eta), Ambiguity attitude alpha subscript 1 element of open bracket (1 minus D subscript 0 over 2 beta), 1 close bracket, Continuity Continuous, Monotonicity Non-increasing, Limiting values q subscript 1 (0 plus) equals 1, q subscript 1 (infinity) equals 0. Row 2: Strategy q subscript 1 (eta), Ambiguity attitude alpha subscript 1 element of open bracket 0, (1 minus D subscript 0 over 2 beta) close bracket, Continuity (Dis)continuous, Monotonicity /, Limiting values q subscript 1 (D subscript 1) equals 0, q subscript 1 (D subscript 2) equals 0. Row 3: Strategy q subscript 2 (eta), Ambiguity attitude alpha subscript 2 element of open bracket (1 over 2), 1 close bracket, Continuity Continuous, Monotonicity Non-decreasing, Limiting values q subscript 2 (0 plus) equals 0, q subscript 2 (infinity) equals 1.
a The strategy
 $q_1^*(\eta)$
is discontinuous and non-unique in
 $(D_1,D_2)$
when
 $F(0)=F(\dot{q}_{12})$
.
Case I: Ambiguity-averse/neutral insurer
In this case, the optimal reinsurance demand strategy
 $q^*_1(\eta)\in(0,1)$
for the insurer satisfies the Equation (15). Meanwhile, we have the optimal reinsurance supply strategy
 $q^*_2(\eta)\in[0,1]$
for the reinsurer. Therefore, it is possible for the insurer and reinsurer to sign the reinsurance contract, and we have the following proposition.
Proposition 3.2. When the insurer is ambiguity-averse/neutral and reinsurer is ambiguity-averse, the reinsurance market has the unique equilibrium reinsurance price
 $\eta^*$
, which satisfies the market clearing condition.
Proof. See Appendix C.1.
Note that the equilibrium reinsurance price must belong to the price negotiation area
 $(\tilde{D}_1,\tilde{D}_2)$
from Lemma 3.5. In other words, it is only possible for insurer and reinsurer to sign the reinsurance contract in the price negotiation area. In the next corollary, we state the influence of some important model parameters on the equilibrium results.
Corollary 3.3 When the insurer is ambiguity-averse/neutral and reinsurer is ambiguity-averse, the following statement holds:
-
• The equilibrium reinsurance price
$\eta^*$
increases w.r.t.
$\gamma_1$
,
$\gamma_2$
,
$\alpha_1$
and
$\alpha_2$
. -
• The reinsurance price negotiation area
$(\tilde{D}_1(\alpha_2,\beta_2),\tilde{D}_2(\alpha_2,\beta_2))$
is enlarged with the increase of
$\gamma_2$
and
$\alpha_2$
, while independent of
$\gamma_1$
and
$\alpha_1$
. -
• The equilibrium reinsurance price
$\eta^*$
increases w.r.t.
$\beta_1$
and
$\beta_2$
.


We observe that the equilibrium reinsurance price increases w.r.t.
 $\gamma_1$
and
 $\gamma_2$
. These dynamics are consistent with the reasoning presented in Corollary 3.1. A lager
 $\gamma_1$
(
 $\gamma_2$
) reflects a greater risk aversion of the insurer (reinsurer), which drives the insurer (reinsurer) to increase (decrease) the reinsurance demand (supply). At this point, the reinsurance market turns to be a “seller’s market.” Hence, the higher reinsurance price will be reached. Meanwhile, the higher ambiguity-parameter
 $\alpha_1$
(
 $\alpha_2$
) increases (reduces) the insurer’s (reinsurer’s) willingness to enter the reinsurance contract, which puts up the price. Finally, a higher value of
 $\gamma_2$
(
 $\alpha_2$
) indicates a more risk-averse (ambiguity-averse) reinsurer, making her less willing to sign the reinsurance contract. This leads to an increase in the thresholds
 $\tilde{D}_1$
and
 $\tilde{D}_2$
, and the reinsurer requires more premium for the uncertainty from non-reinsurance to full-reinsurance. It expands the range of price to for signing the reinsurance contract, but reduces the equilibrium demand/supply strategy. When
 $\beta_1$
increases, the insurer’s confidence in the reference claim model decreases. As a result, it increases the demand for reinsurance protection. With the reinsurance supply unchanged, an increase in demand will drive up the equilibrium price. Similarly, when
 $\beta_2$
increases, the reinsurer is more uncertain about claim risk, and it will require a higher risk premium to compensate for the ambiguous risks. It leads to a leftward and upward shift of the reinsurance supply curve. With demand unchanged, a decrease in supply will also drive up the equilibrium price. The following example demonstrates our conclusions.
Example 3.1. We give an example to show the influence of the parameters
 $\gamma_1$
,
 $\gamma_2$
,
 $\alpha_1$
, and
 $\alpha_2$
on the optimal results for ambiguity-averse/neutral insurer and equilibrium price. The benchmark parameters are set as follows:
 $m_1=0.1$
,
 $m_2=0.2$
,
 $\beta_1=0.5$
,
 $\beta_2=0.3$
,
 $\gamma_1=1.5$
,
 $\gamma_2=0.5$
,
 $\alpha_1=1$
,
 $\alpha_2=1$
. The optimal reinsurance demand and supply of the game and the equilibrium price are depicted in Figures 5–7.
The influence of parameters
 $\gamma_1$
and
 $\alpha_1$
on equilibrium price.

The influence of parameters
 $\gamma_2$
and
 $\alpha_2$
on equilibrium price.

The influence of parameters
 $\beta_1$
and
 $\beta_2$
on equilibrium price.

Figure 7. Long description
Panel A: The line graph shows the influence of parameter beta 1 on equilibrium price. The horizontal axis is labeled eta ranging from 0 to 2, and the vertical axis ranges from 0 to 1. Three lines represent different values of beta 1: 0.5 in blue, 1 in red dashed, and 1.5 in green dashed. The lines intersect at a point marked with a black dot. Panel B: The line graph illustrates the influence of parameter beta 2 on equilibrium price. The horizontal axis is labeled eta ranging from 0 to 8, and the vertical axis ranges from 0 to 1. Three lines represent different values of beta 2: 0.5 in blue, 1 in red dashed, and 1.5 in green dashed. The lines intersect at a point marked with a black dot.
Case II: Ambiguity-seeking insurer
In this case, we can see that the optimal reinsurance demand strategy
 $q_1^*$
is still unique if
 $f(\alpha_1,\beta_1)\leqslant D_0$
, while may have a negative jump if
 $f(\alpha_1,\beta_1)\gt D_0$
. To be precise, the insurer’s demand will jump to 0 when she is relatively ambiguity-seeking. We conclude the main results in the following proposition. The proof is similar to that of Proposition 3.2 and we omit it.
Proposition 3.3. When the insurer is ambiguity-seeking, we have the following results:
-
(i) When
$(\frac{1-D_0/\beta_1}{2})_{+}\leqslant\alpha_1\lt \frac{1}{2}$
, the equilibrium reinsurance price
$\eta^*$
exists and is unique for
$\eta\in(\tilde{D}_1(\alpha_2,\beta_2),\tilde{D}_2(\alpha_2,\beta_2))$
. -
(ii) When
$0\leqslant\alpha_1\lt (\frac{1-D_0/\beta_1}{2})_{+}$
, the equilibrium reinsurance price
$\eta^*$
only exists and is unique if there exists
$\eta_0\in(0,\infty)$
such that
$q_1^*(\eta_0)\lt q_2^*(\eta_0)$
.


Similarly, we provide a numerical example to show the influence of some important model parameters on the optimal results for ambiguity-seeking insurer.
Example 3.2. The parameters are set as follows:
 $m_1=0.1$
,
 $m_2=0.2$
,
 $\beta_1=0.5$
,
 $\beta_2=0.3$
,
 $\gamma_1=1.5$
and
 $\gamma_2=0.5$
. The optimal reinsurance demand and supply strategy and the equilibrium price are depicted in Figure 8.
The influence of parameters
 $\gamma_1$
on equilibrium price for ambiguity-seeking insurer.

In Figure 8, we obverse that there exists a threshold
 $\eta_0\in[0,\infty)$
for ambiguity-seeking insurer. The optimal reinsurance demand strategy has a drop, which immediately decreases to 0 after
 $\eta_0$
. The threshold
 $\eta_0$
of reinsurance purchase for insurer depends on the ambiguity attitude parameter
 $\alpha_1$
. Comparing the results under
 $\alpha_1=0.45$
,
 $\alpha_1=0.4$
, and
 $\alpha_1=0.35$
, we find that the the threshold
 $\eta_0$
decreases as
 $\alpha_1$
increases, indicating a decreasing incentive of insurer for reinsurance when she is more ambiguity-seeking. Meanwhile, the ambiguity-seeking insurer is willing to retain more insurance business under the same reinsurance price. On the other hand, we observe that the equilibrium reinsurance price only exist when the insurer is less ambiguity-seeking. In addition, with the decrease of
 $\alpha_1$
, the reinsurance market becomes a “Buyer’s market,” and the equilibrium reinsurance price turns to go down.
So far, we have discussed the equilibrium price in ambiguity-averse/neutral and ambiguity-seeking cases and investigated the existence and uniqueness in details. The main results are summarized in Table 6.
The existence and uniqueness of equilibrium price for different ambiguity attitudes.

Table 6. Long description
Panel A: Table with columns for insurer’s attitude, reinsurer’s attitude, existence, and uniqueness. Panel B: Insurer’s attitude ranges from alpha 1 in [1/2, 1] to alpha 1 in [0, 1/2]. Panel C: Reinsurer’s attitude ranges from alpha 2 in (1/2, 1] to alpha 2 in [0, 1/2]. Panel D: Existence varies from always exists to not exists. Panel E: Uniqueness varies from unique to unique if exists.
4. Conclusion
In this paper, we investigate the equilibrium reinsurance price problem for the insurer and reinsurer from the demand–supply perspective. Both parties are concerned with the
 $\alpha$
-maxmin mean-variance performance of the terminal wealth. Based on the second-order approximation to the relative entropy penalty, we derive the optimal reinsurance demand and supply strategies for the insurer and reinsurer, respectively. Under the market clearing condition, the equilibrium reinsurance is determined by the system of equations and we prove the existence and uniqueness for the ambiguity-averse/neutral insurer and ambiguity-averse/neutral reinsurer. Meanwhile, the necessary condition for the existence of equilibrium reinsurance prices for ambiguity-seeking insurer has been investigated. From the optimal results, we have several important findings: (i) When the ambiguity-seeking insurer is more ambiguous toward the reference model (larger value of
 $\beta$
), there exists a threshold of reinsurance price and the optimal reinsurance demand strategy instantaneously decreases to 0 when the price is above the threshold; (ii) With the ambiguity-seeking preference, the reinsurer’s reinsurance supply strategy is a bang–bang control. The reinsurer chooses to either provide the full protection for the insurance company or refuse any reinsurance purchase, which is highly dependent on the market price; and (iii) the equilibrium reinsurance price exists and is unique for the ambiguity-averse/neutral insurer. The market equilibrium may not be reached when the insurer is ambiguity-seeking; (iv) Compared with the ambiguity attitude parameter
 $\alpha$
, the ambiguity parameter
 $\beta$
plays a more important role in insurer’s decision.
There are some interesting avenues of future research. First, one can consider alternative specifications for the insurer’s risk preference including value at risk, conditional value at risk, and expected utility. Second, as in Yuan et al. (Reference Yuan, Yuen and Wang2025), it is an appealing future work to investigate the equilibrium reinsurance demand and supply when reinsurer’s own business is assumed to be dependent on the insurer’s claims. Finally, one can consider multiple suppliers of the reinsurance protection and incorporate the competition among reinsurers in the stochastic demand-supply game. Undoubtedly, these modeling features can result in more challenging and complex optimization problems. However, they can also enable richer characterization of reinsurance contracting and provide more insightful economic implications.
Acknowledgements
The authors acknowledge the editor and two anonymous referees for their helpful and insightful comments. The research of Yu Yuan was supported by the National Natural Science Foundation of China (Grant No. 12201311). The research of Ning Wang was supported by Futures Scheme at Australian National University. The research of Liming Zhang was supported by the National Natural Science Foundation of China (Grant No. 12201006), the Anhui Provincial Universities Scientific Research Project (Grant No. 2024AH050083), and the Anhui University High-level Talent Research Start-up Fund (Grant No. S020318033/006).
Supplementary material
The supplementary material for this article can be found at https://doi.org/10.1017/asb.2026.10118
Competing interests
The authors declare none.


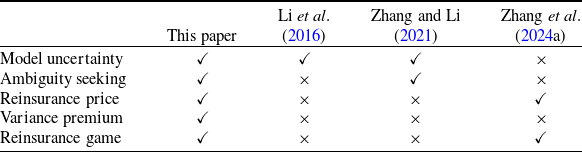
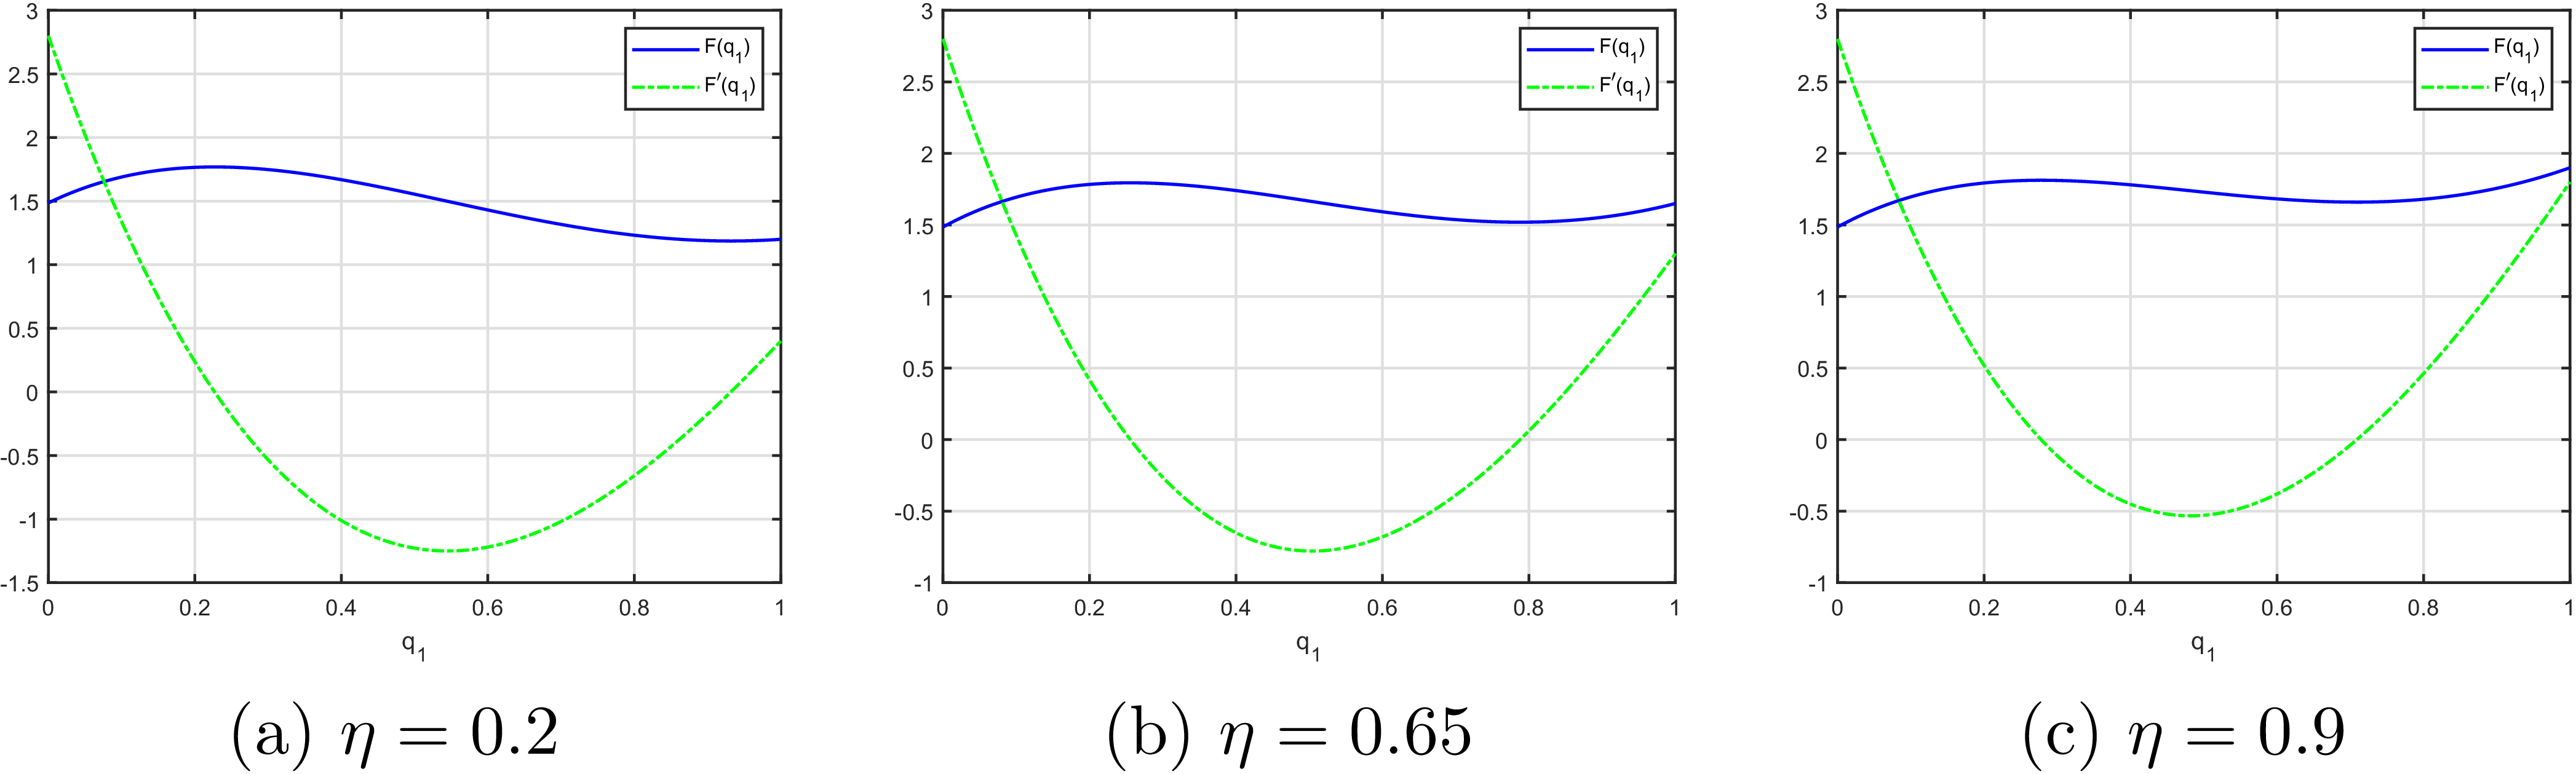
 η
 f=D0+0.1
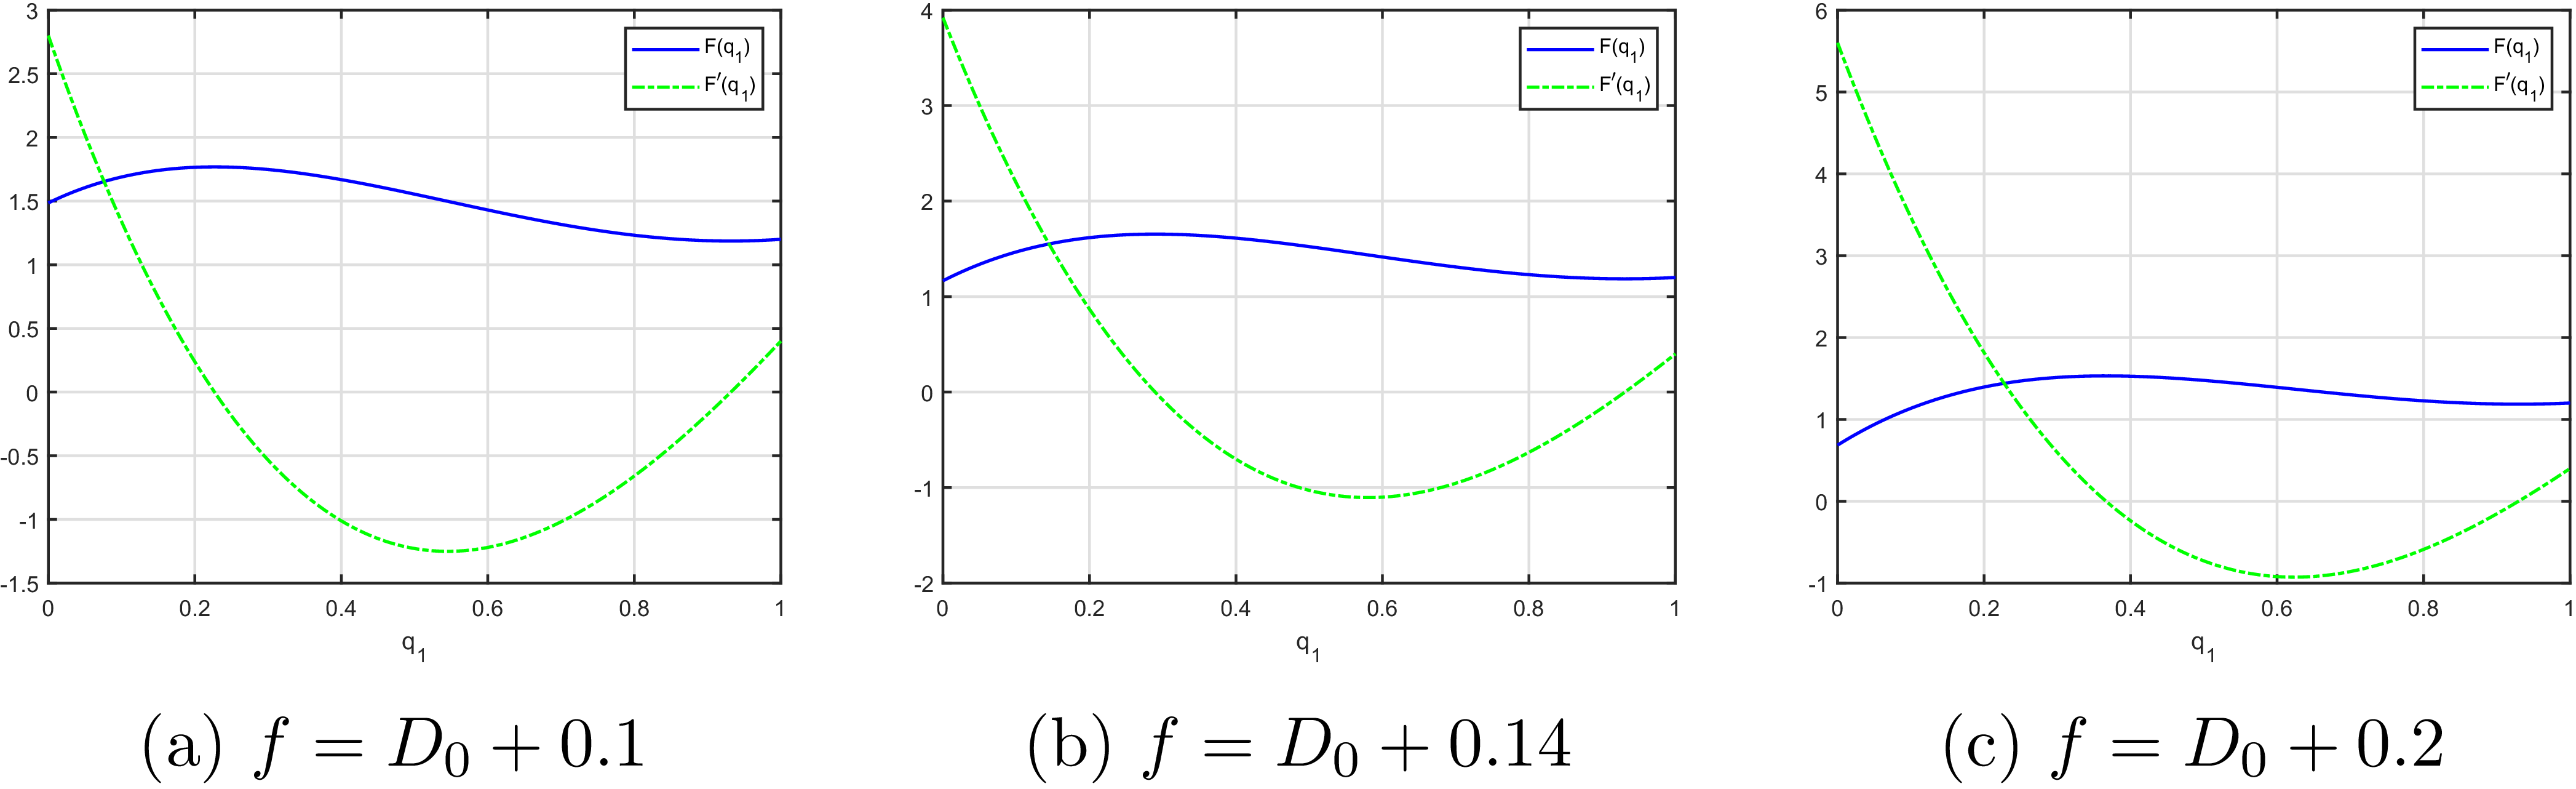
 η=0.2
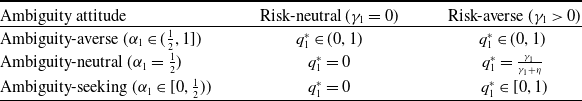
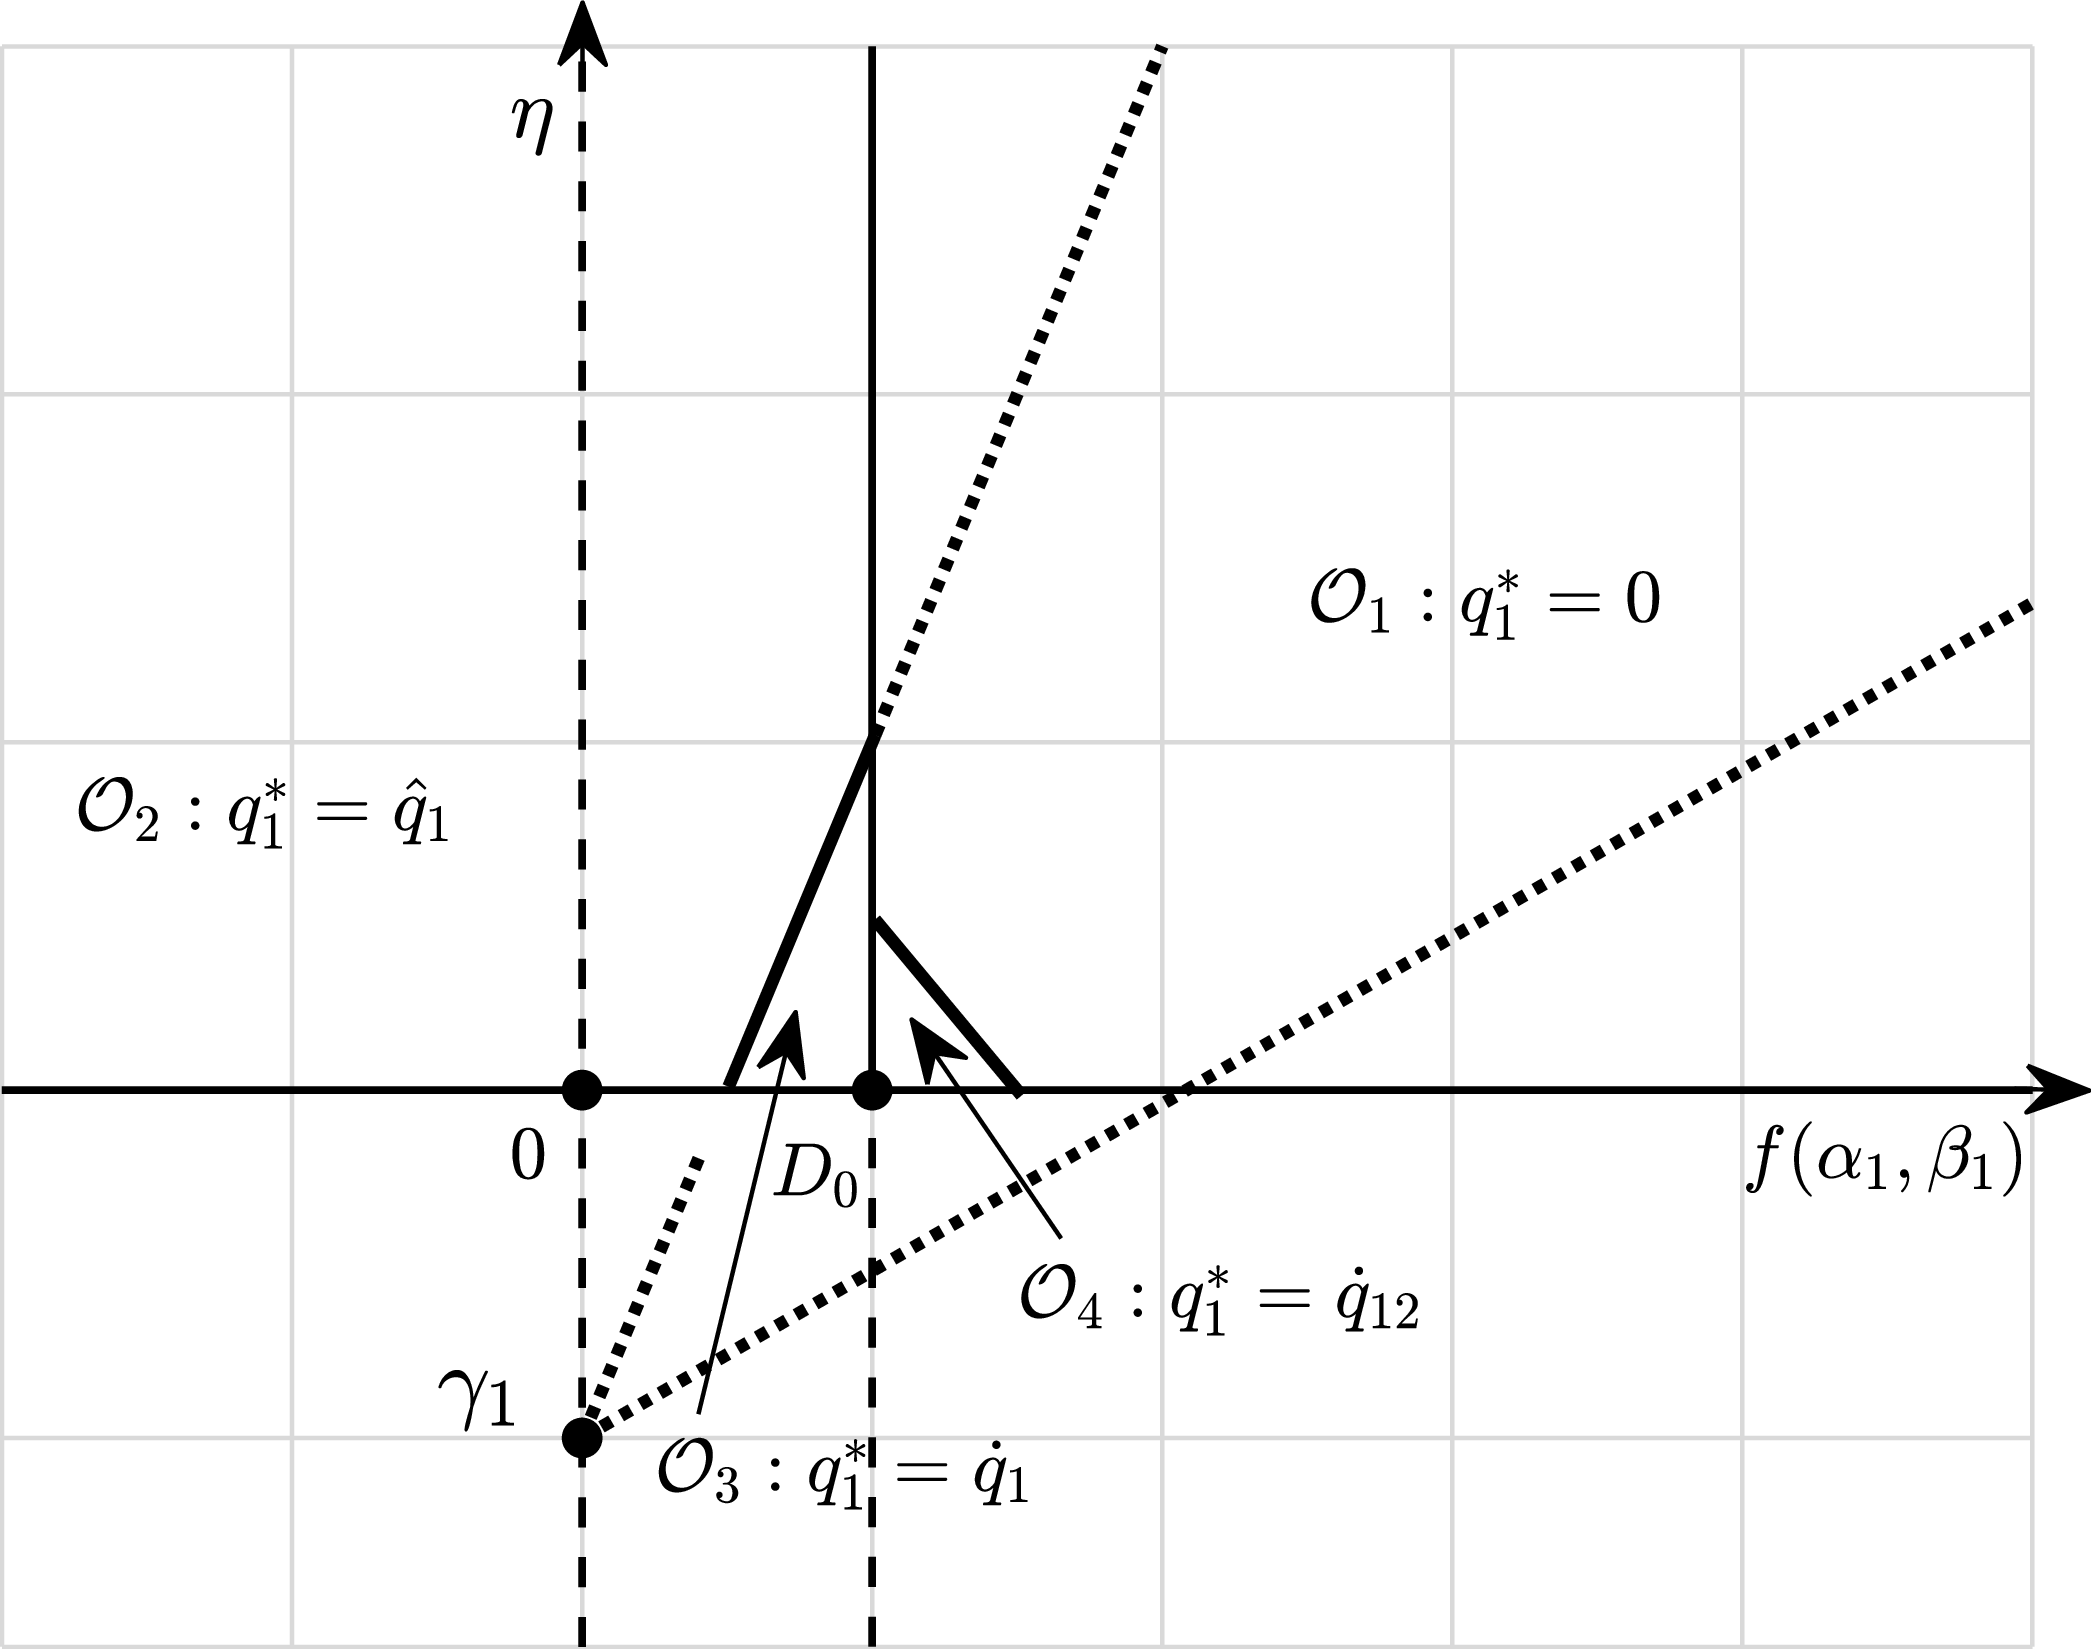
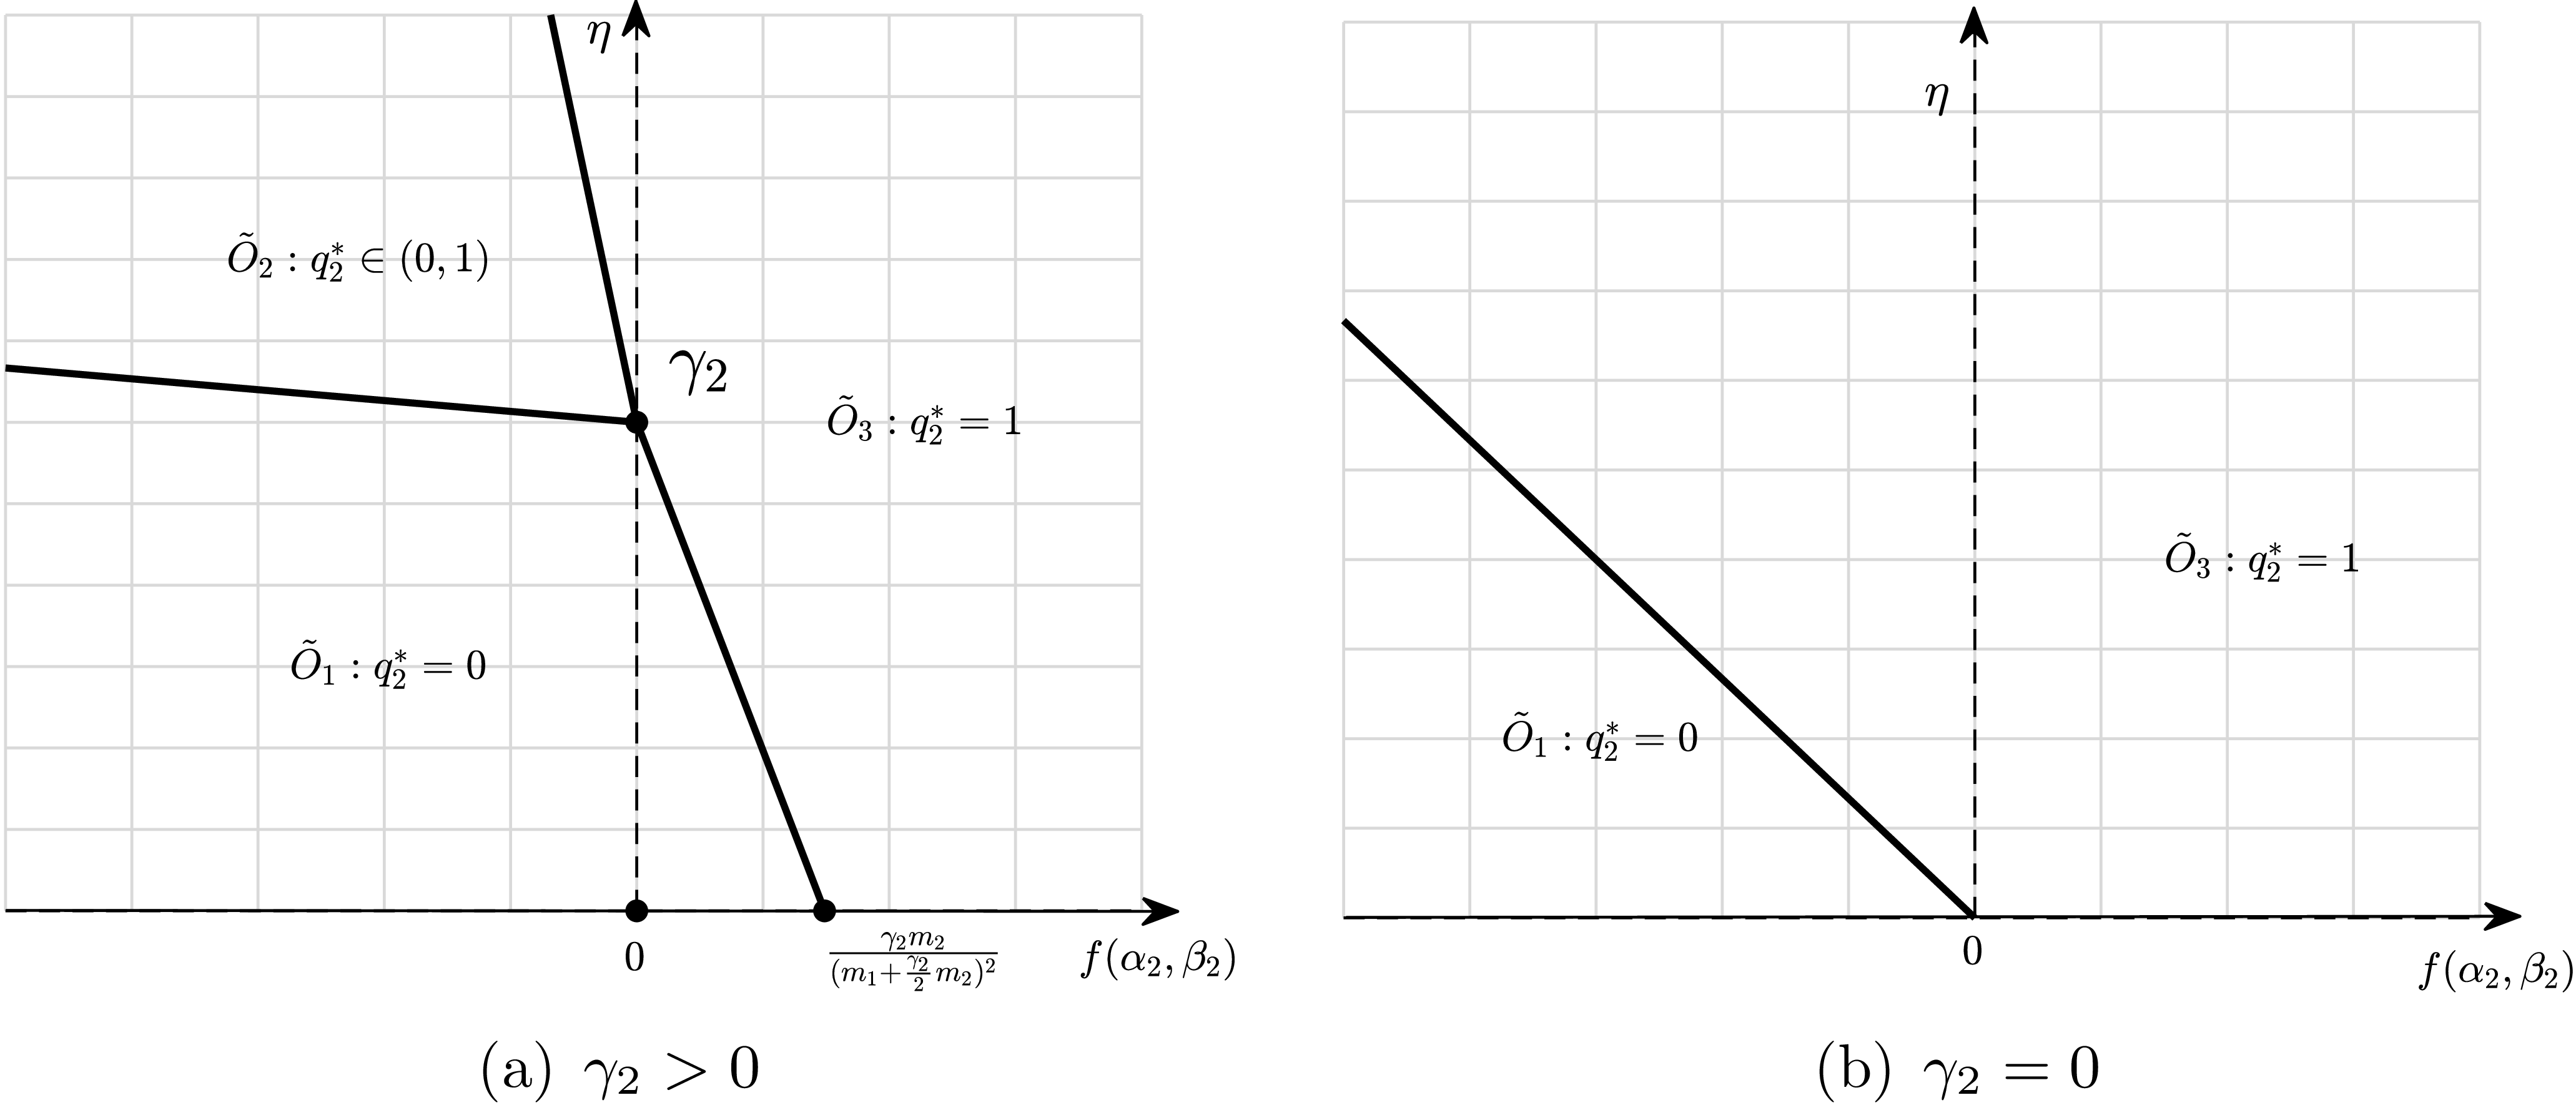
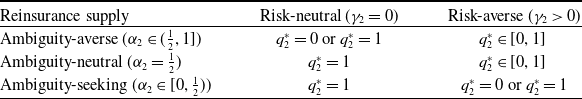
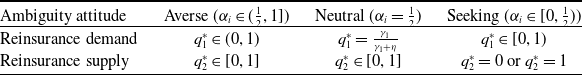
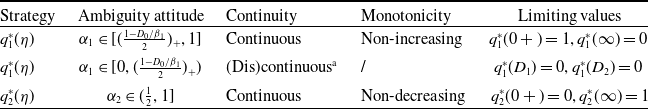
 q1∗(η)
 q2∗(η)

 γ1
 α1

 γ2
 α2

 β1
 β2
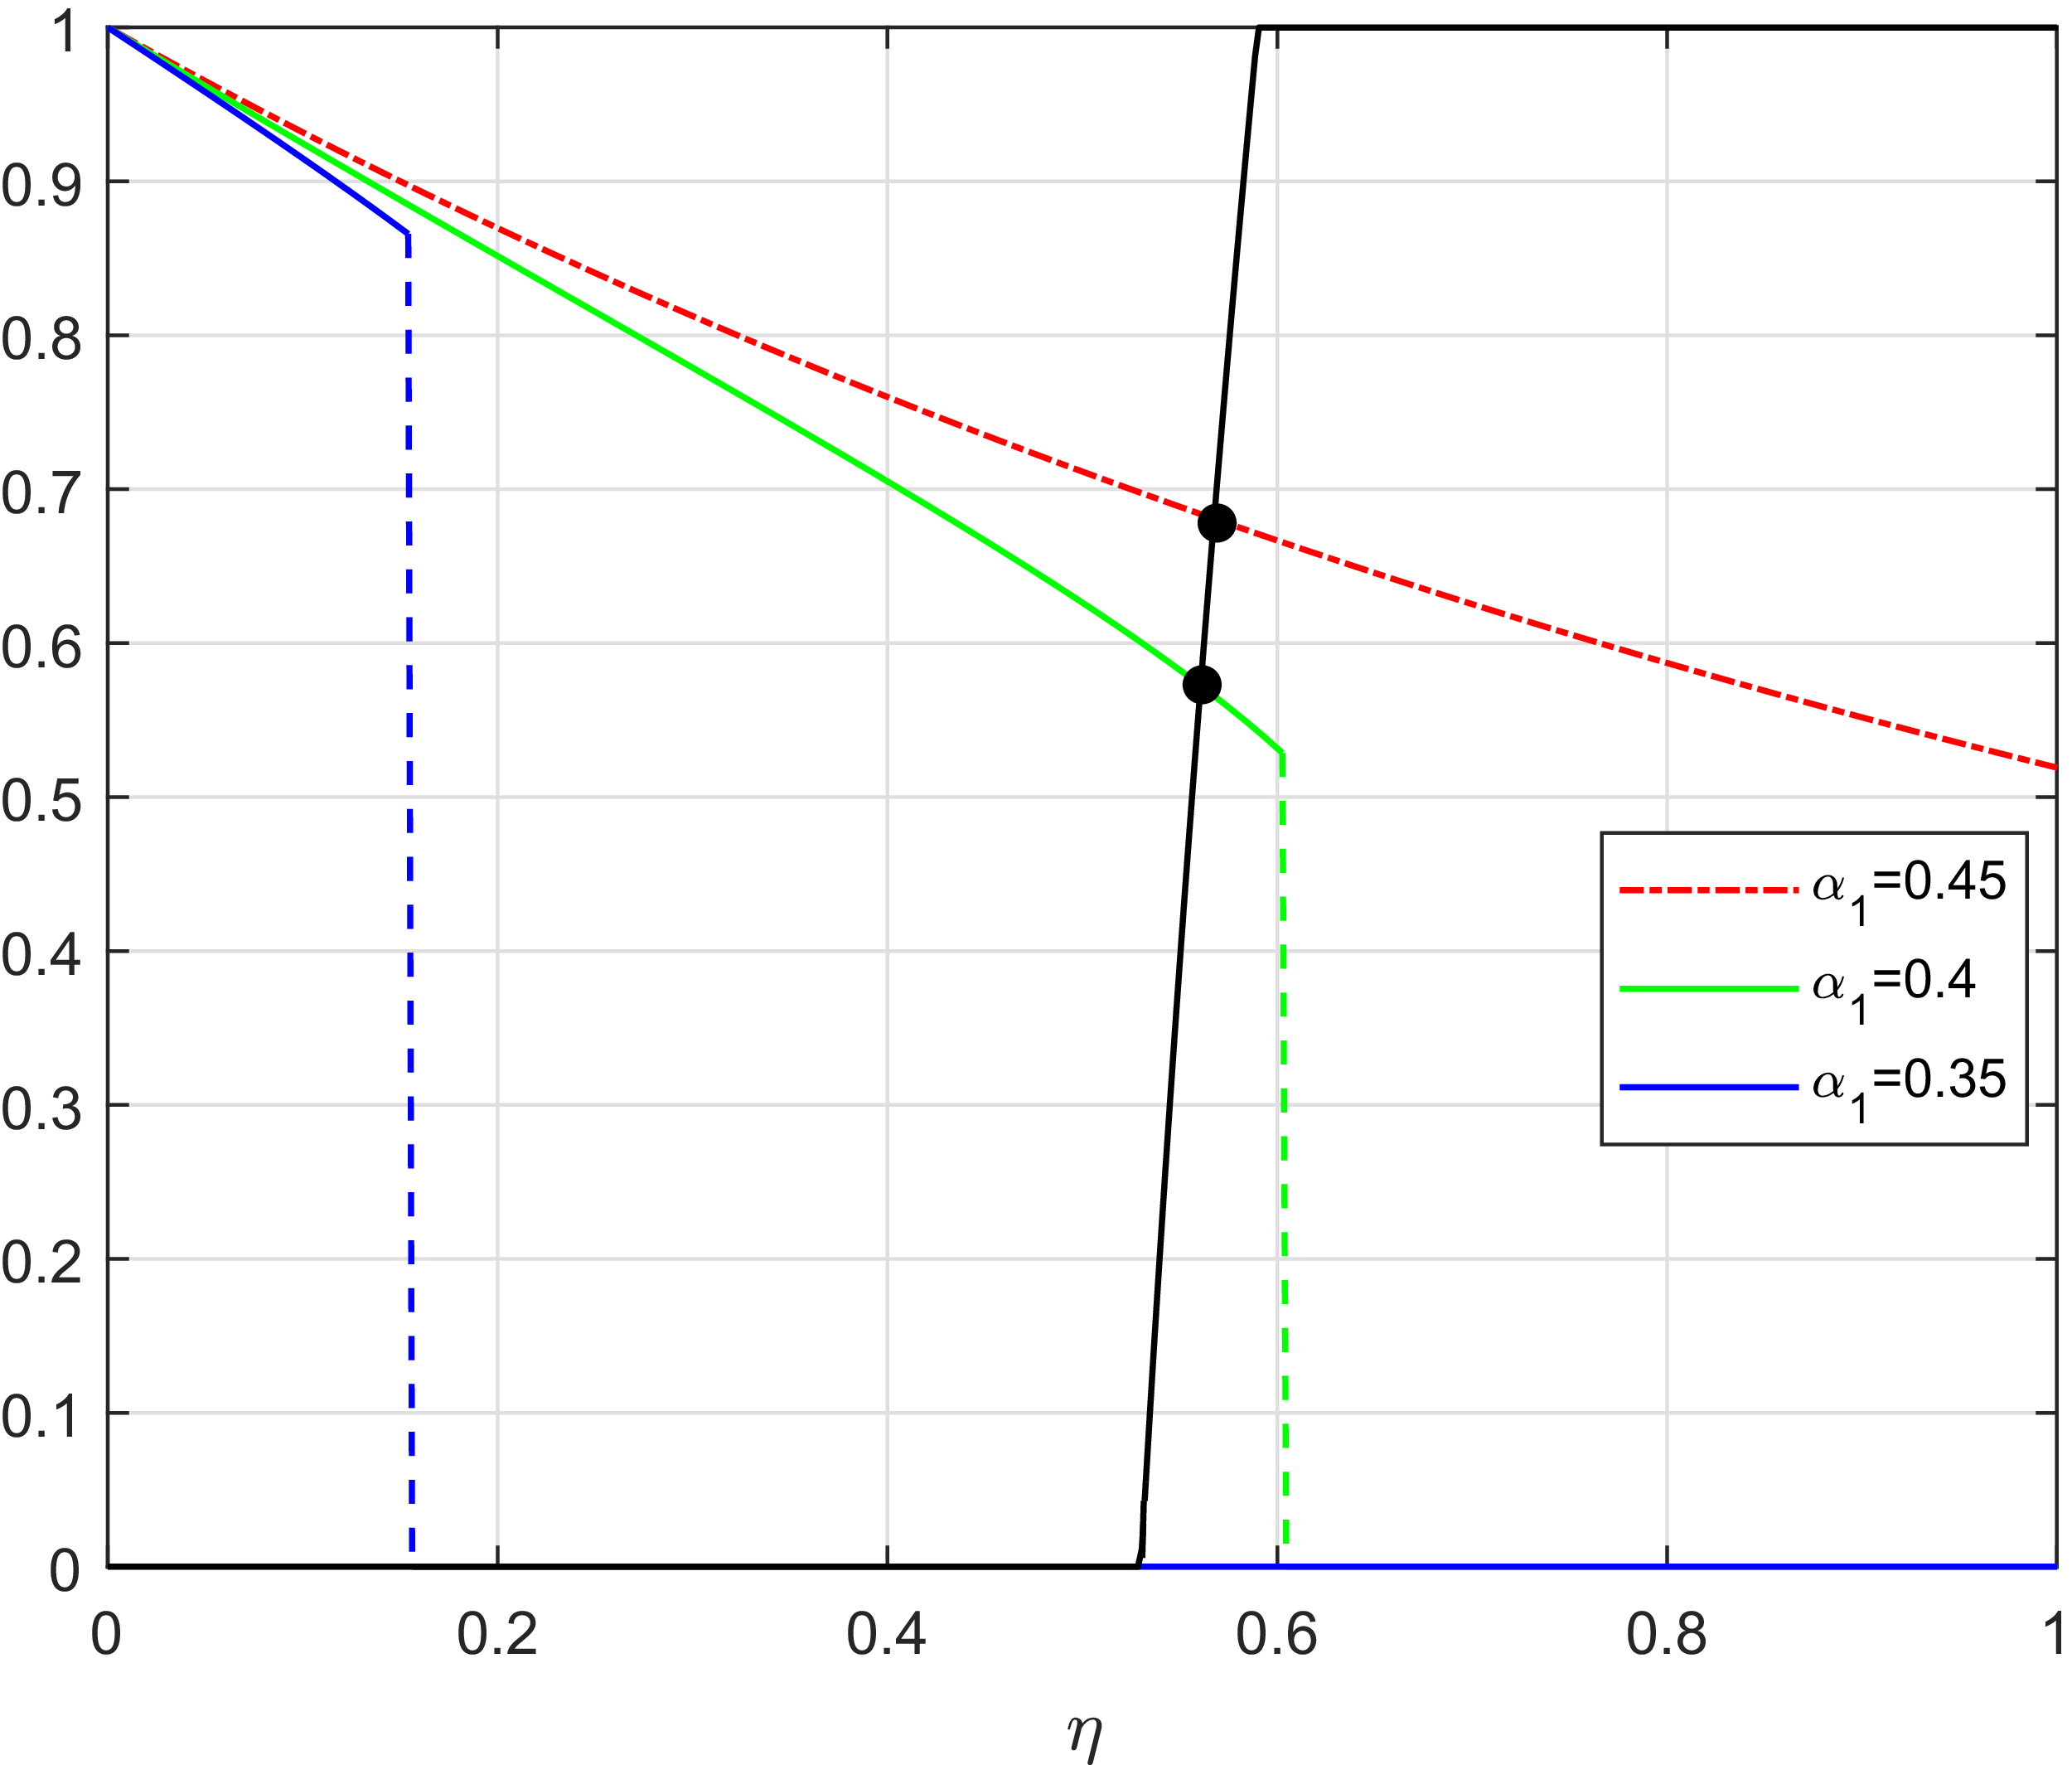
 γ1
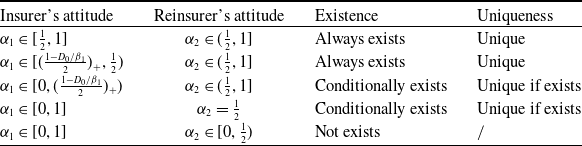


 Open access

