




No CrossRef data available.
IDIOSYNCRATIC SHOCKS AND ASSET RETURNS IN THE REAL-BUSINESS-CYCLE MODEL: AN APPROXIMATE ANALYTICAL APPROACH
Published online by Cambridge University Press: 14 July 2005
Abstract
The present paper uses an analytical approach to derive approximate closed-form solutions for the asset moments of a real-business-cycle model with idiosyncratic risk. To preserve analytical tractability, risk sharing is completely shut down. Further, the firm is assumed to maximize a variant of value maximization, given that its usual objective is no longer well defined under market incompleteness. When idiosyncratic risk is incorporated into the model, the asset moments can be decomposed into their value under identical households plus a new idiosyncratic term. Under full constrained persistence, in which case the same household determines the asset moments every period, the model is able to generate the risk premium in the data with reasonable parameter values, but it cannot generate the risk return trade-off. While the quantitative impact of idiosyncratic risk is smaller when there is only some persistence in who is constrained, the qualitative predictions are unaltered.
Information
- Type
- ARTICLES
- Information
- Copyright
- © 2005 Cambridge University Press
INTRODUCTION
As documented by several authors, such as Rouwenhorst (1995), Lettau and Uhlig (2002), or Lettau (2003), the standard real-business-cycle (RBC) model with a representative agent is unable to explain the main features of U.S. asset returns. Some authors, such as Jermann (1998), Boldrin et al. (2001), Danthine and Donaldson (2002), or Guvenen (2003), have obtained more success by combining several frictions, such as capital adjustment costs, habit persistence, labor market frictions, or limited stock market participation. In addition, authors such as Carceles-Poveda (2003) or Krusell and Smith (1997) have explored the impact of shareholder heterogeneity and incomplete financial markets, showing that, if one allows for asset trade subject to sufficiently loose trading limits, the model still generates counterfactual asset pricing implications.
In the present paper, we follow the latter approach and investigate the effects of extending the basic model with an idiosyncratic labor earnings shock. Whereas previous studies with heterogeneous households mainly rely on numerical solutions, however, we propose to use an approximate analytical approach, giving a deeper insight of the channels through which idiosyncratic uncertainty may affect asset returns, and providing therefore a clearer understanding of the pitfalls of the model.
To obtain approximate closed-form solutions, we extend the methodology used by Lettau (2003), who derives closed-form solutions for the asset moments in the standard RBC model with a representative agent. In particular, the relevant equations are first approximated in log-linear form, and the elasticities of the macroeconomic aggregates with respect to the state variables are calculated as functions of the model parameters using the method of undetermined coefficients. Then, the decomposition of unexpected returns due to Campbell and Shiller (1994) is used to obtain closed-form solutions for the different asset moments as functions of the elasticities of the macroeconomic variables.
When extending Lettau's methodology to our model, we have to deal with several issues. First, to preserve analytical tractability, we shut down all the trading opportunities. Although this implies that our analysis is done under an extreme form of market incompleteness, we still believe that it can help to evaluate the potential of idiosyncratic shocks to explain the different asset moments. Second, given that we study a two-agent economy, no trade can be obtained as an equilibrium outcome by setting the trading limit on each security to one half of its total supply, in which case the unconstrained household uniquely determines the implied price of the nontraded asset. On the other hand, since this household might change over time, we have to redefine the asset moments as functions of the probabilities of being unconstrained in the future. Finally, the fact that markets are incomplete implies that the usual objective for the firm used by Lettau (2003) is not longer well defined. In the present framework, we follow Grossman and Hart (1979) by assuming that the firm maximizes the present discounted value of its net cash flow, using as a discount factor the weighted average of the shareholders' marginal rates of substitution. As illustrated by the authors, this objective is suitable for a multiperiod setup, and we also show that it can be derived from the shareholders' preferences under the no-trade assumption.
When idiosyncratic risk is incorporated into the model, we show that the asset moments can be decomposed into their value under identical households and a new idiosyncratic term, directly affected by the household risk aversion, the idiosyncratic innovation variance, and the idiosyncratic shock persistence. Further, the risky-asset moments also depend on the future probabilities that a household is unconstrained. We find that the effects of idiosyncratic risk are maximized under full constrained persistence, implying that a household is always (un)constrained and therefore determines the asset moments every period, while they disappear if there is no persistence in who is constrained. Given this, the potential of the model to generate reasonable asset moments is first analyzed under full constrained persistence, arising in two cases of general interest. First, full constrained persistence would be the outcome of a model where a representative household subject to labor income risk determines the asset moments, a case that has been studied by several authors in the literature, including Heaton and Lucas (1996). Alternatively, full constrained persistence would arise under limited stock market participation, a case that has been studied by authors such as Danthine and Donaldson (2002), Guo (in press), or Guvenen (2003). After doing this, the assumption of full constrained persistence is relaxed, and the model is also analyzed assuming a different initial distribution for the idiosyncratic shocks of the two agents, leading to different degrees of (less than full) constrained persistence, depending on the initial shock value.
With full constrained persistence, the model is able to generate the right equity premium in the data with a reasonable parameterization. Since the household risk aversion and the idiosyncratic innovation variance enter the idiosyncratic components in a multiplicative way, the asset moments are found to be highly sensitive to an increase in these two parameters. In addition, we also find that the increase in the premium is accompanied by a more than proportional effect on the two asset return variabilities, which are too high as compared to the data. This result can be improved by increasing the idiosyncratic shock persistence, which dampens the effect of an increase in the previous parameters on the asset return variances, but one would need too high a persistence to generate the Sharpe ratio in the data. Although the results are quantitatively smaller with less than full constrained persistence, the qualitative findings are very similar. We therefore conclude that models with heterogeneous shareholders need to generate enough persistence in who is constrained to be successful. Here, it is important to emphasize that our model is derived under autarky, and the reader should not focus on the quantitative results, which are likely to disappear in the presence of asset trade, but rather on the qualitative findings.
Finally, we should mention that our work is also related to a vast literature, following Mehra and Prescott (1985), trying to explain equilibrium asset returns in a context with two heterogeneous shareholders and incomplete financial markets. Among others, Telmer (1993), Lucas (1994), Heaton and Lucas (1996), and Marcet and Singleton (1999) have studied such a framework under the assumption of exogenously determined consumption processes. In the present work, however, we go one step further by incorporating a nontrivial production sector, offering a better foundation of asset prices than the standard exchange economy.
In addition, we are not the only ones who have used approximate closed-form solutions to study asset prices. Lettau and Uhlig (2002) use the same approach to study the effects of different preferences on the Sharpe ratio, and Jermann (1998) and Guo (in press) decompose the asset prices in a similar way to that the present paper, while they still solve the underlying model numerically. Here, a final question that naturally arises is the accuracy of our log-linear approximation. Lettau (2003) discusses this issue in the context of the representative-agent framework, pointing out that log-linear approximations perform well as long as the innovation variance of the technology shock is not too high. Given this, we choose to work with moderate idiosyncratic variance levels.
The rest of the paper is organized as follows. The following section presents the model, while Section 3 briefly extends the log-linear solution method to the case in which households are heterogeneous. The results are discussed in Section 4. Finally, Section 5 summarizes and concludes.
MODEL
Households
The economy is populated by a firm f and by two (classes of) households, indexed by i={1, 2}, and only distinguished by the realization of an idiosyncratic labor productivity shock εi. At period t, each household solves the following problem:

s.t.


Equation (2) represents the households' budget constraint, and it implies that they can potentially invest in equity shares of the firm (θ), providing a claim to the firm's dividends (D) from period t+1 onward, and in risk-free one-period bonds (b), providing a claim to one unit of consumption at period t+1. As usual, we assume that there is a single outstanding equity share, while bonds are in zero net supply. Further, the initial asset holdings are assumed to be symmetric; that is, households hold initially zero debt and one half of the equity share of the firm.
Apart from their asset income, households receive labor income, equal to the aggregate wage rate paid by the firm (W) times the idiosyncratic productivity shock. If households are identical, εit=0.5; otherwise,


Note that one can think about the previous setup as households having one fixed unit of labor, which they can transform into εit efficiency labor units that will be supplied to the firm. Under this assumption, the aggregate labor supply is always equal to 1, and idiosyncratic uncertainty has no effects on the aggregate macroeconomic variables through the aggregate supply of labor.1
The unbounded support of the normal distribution implies that ε1t cannot be restricted to be less than 1. Therefore, we calibrate the process parameters so that the probability of this event is almost zero. Note also that the shocks have the same mean and variance for the two households, while they exhibit a slight asymmetry due to the difference of higher-order moments. On the other hand, given that the processes differ more at the tails, where the distribution has the lowest mass, we do not think that this has any significant consequences for the results.
Finally, as shown by equation (3), households are also subject to trading constraints in the two asset markets, implying that the resulting market structure is incomplete. If we denote by Mt+ji,t=βj(Cit+j/Cit)−γ, the marginal rate of substitution of household i between periods t and t+j, the first-order conditions for the problem above lead to the following Euler equations determining the two asset prices:


As stated earlier, it is only possible to obtain a closed-form solution under the assumption that households cannot use the asset markets to insure against uncertainty, a limiting outcome that obtains by setting the two asset constraints in the previous setup at Kb=0 and Ke=0.5, respectively. Under this assumption, the equilibrium asset holdings will always be equal to the initial ones; that is, bit=0 and θit=0.5, leading to the following equilibrium consumption process:

In addition, there will be a constrained household every period, while the other household will determine the two asset prices. To see this, note that, since the constraints are only on borrowing and not on lending, they will be binding for a household if he wants to hold less than one half of the share or negative amounts of the bond. In particular, the agent receiving a good shock at period t will want to increase his asset holdings and will therefore determine the period t asset prices, whereas the poor agent will want to short-sell more at the equilibrium prices but will be unable to do so. Given this, we can define the pricing kernel as the marginal rate of substitution of the household that is unconstrained and write the previous pricing equations as equalities as follows2
Telmer (1993) and Lucas (1994) use the same approach to numerically compute the implied prices of nontraded assets. In particular, in a similar model with no production, the last author uses the reservation values of the household receiving the positive shock to compute the implied prices for the nontraded equity shares and risk-free one-period bonds. It is important to note that this can only be done in the absence of asset trade. Otherwise, the presence of wealth accumulation might lead to a situation where a household wants to short-sell more of an asset and go long in another.


where Rjt+1 is the gross return of asset j, and the subscript ut corresponds to the household that is unconstrained at period t; that is, if the first (second) household is unconstrained at period t, ut=1 (ut=2).
The Firm
Apart from the two households, the economy is populated by a firm that owns the entire capital stock (K), which it combines with labor (L) from the households to produce output (Y). Investment (I) is entirely financed by retained earnings or profits, defined as output net of wage payments, and the residual of profits and investment is paid out as dividends (D) to the shareholders.
Concerning the objective of the firm, note that, under identical households (or complete markets), the marginal rates of substitution would be equalized across them, and the usual market value maximization objective would be given by

On the other hand, because the shareholders' marginal rates of substitution will not equalize any more under market incompleteness, the previous objective is no longer well defined. In the present paper, we follow Grossman and Hart (1979) by assuming that the firm discount factor is given by the weighted average of the shareholders' marginal rates of substitution, with the weights being equal to their original shareholdings
. Therefore, the firm maximizes3
This objective was originally proposed by Grossman and Hart (1979) and derived by the authors under the assumption of competitive price perceptions. In Appendix A.1, we show that it can also be derived from shareholders' preferences without using this assumption, as long as there is no trade in equity shares. For a good survey of the literature on the firm objective problem when markets are incomplete, see Dreze (1985) or Grossman and Stiglitz (1977). Further, for a discussion of the quantitative effects of different firm objectives, see Carceles-Poveda (2003, 2004).

s.t.


where Z is an aggregate technology shock (Z), assumed to be independent from the idiosyncratic shock of the households. The first-order conditions for the problem above imply that


where we have imposed the labor market-clearing condition. The first equation determines the aggregate wage rate, and it implies that Dt=αYt − It, whereas the second determines the law of motion of the capital stock.
Market Clearing
The market-clearing conditions closing the model are given by


Although capital cannot be used to insure against labor market risk in the present framework, the first equation shows that capital accumulation still takes place in response to fluctuations in the technology shock, and the economy is therefore not equivalent to the pure exchange economies studied by Telmer (1993), Lucas (1994), or Heaton and Lucas (1996). In particular, although the derivation of the asset moments is essentially the same, results not reported here show that it is much easier to generate a sizesable risk premium in these cases by just increasing the risk aversion parameter, even in the absence of idiosyncratic risk.
APPROXIMATED ANALYTICAL SOLUTION
In what follows, we present an analytical solution to the previous equation system following Campbell (1994), Lettau (2003), and Uhlig (1999). We denote by lower-case letters the variables in logs, while the log of εit is denoted by
. Since the solution under identical households is extensively discussed by Lettau, we concentrate on our extension, incorporating idiosyncratic risk into the model.
Macroeconomic Variables
Log-linearizing the system of equations that determines the macroeconomic aggregates, we observe that the presence of idiosyncratic risk has no effects on the variables due to its symmetric nature; that is, the elasticities of capital, output, aggregate consumption, investment, and dividends with respect to kt−1 and zt are the same as under identical households, while the elasticity of these variables with respect to the idiosyncratic shock is equal to zero.4
Appendix A.2. illustrates how to solve for the macroeconomic elasticities following Campbell (1994).


where xt={yt, it, ct, dt}, Θx=(ηxkηkz − ηxzηkk)/ηxz, and wx(εzt)=ηxzεzt. On the other hand, equations (4), (5), and (8) imply that the individual consumptions can be expressed as the sum of aggregate consumption plus a second component capturing the effect of idiosyncratic uncertainty, leading to the following expressions for the expected and unexpected individual consumption growth:


where ηcε is the individual consumption elasticity with respect to the idiosyncratic shock, and εit is the idiosyncratic shock innovation, with ε2t=−ε1t. As we see, expected and unexpected individual consumption growth have both an aggregate and an idiosyncratic component, a property that will allow for a similar decomposition of the different asset moments.
Asset Moments
To compute the asset return moments, we can log-linearize the two asset pricing equations in (10) and (11), obtaining


The risk-free rate
The preceding equation shows that the risk-free rate is just a function of the pricing kernel, equal to the individual marginal rate of substitution of the unconstrained household. If we suppress the constant terms involving the discount factor and the variance of individual consumption growth, the risk-free rate can be writen as5
A more detailed derivation of the asset moments discussed along the section is provided in Appendix A.3. Further, the derivations of the terms with the superscript *, whose exact expressions are also provided in the Appendix, can be found in Lettau (2003).

where
is the idiosyncratic innovation of the household that is unconstrained at period t and
.
It is easy to verify that the first term on the right-hand side of the equation is equal to the ARMA(2,1) risk-free rate process that would arise under identical households. Further, the presence of idiosyncratic risk leads to an additional AR(1) term, which only depends on the idiosyncratic shock innovation. Using the independence of the two shock innovations and the infinite period representation of the previous process, we can compute its unconditional standard deviation, given by

The first term in the brackets, only affected by the aggregate shock, is equal to the risk-free rate variance under identical households, while the second term is the contribution to the total variance of the idiosyncratic shock. Note that the risk-free rate variance is independent of the household that is unconstrained at period t, since σ2(εit)=σ2ε for i=1, 2.
The equity premium
The expected risk premium, adjusted for the effect of Jensen's inequality, is equal to the covariance of the equity return with the individual consumption growth; that is,

As shown earlier, the unexpected consumption growth can be decomposed into its expected value and its innovation terms with respect to the two shocks. On the other hand, to calculate the unexpected equity return, we can use the decomposition of unexpected returns due to Campbell and Shiller (1994) into revisions in expectations of future dividend changes and revisions in expectations of future returns, implying that6
Equivalently, we could also write the unexpected equity return in terms of the second agent's idiosyncratic innovation. In this case the equity return elasticity would have the opposite sign, while the resulting equity premium would be the same.

where

As we see, the unexpected equity return has both an aggregate and an idiosyncratic component, and it is again easy to show that the aggregate shock elasticity
is the same as under identical households. Further, we observe that the idiosyncratic shock elasticity
depends on the future probability that the first household is unconstrained, which we denote by Pt+j+1=prob(ut+j+1=1). Given this, the expected equity premium is equal to

where Pt=prob(ut=1) denotes the probability that the first household is unconstrained at period t, and we have used the fact that
.
The Sharpe ratio
In the present model, the Sharpe ratio is given by

where

As with the other asset moments, the first term in the brackets of the previous equation represents the equity return variance under identical households, while the second is the contribution to the total variance of the idiosyncratic shock.
Constrained persistence
As shown above, the idiosyncratic components of the risky asset moments crucially depend from the future probability that the first household is unconstrained. In what follows, we say that there is constrained persistence if this probability is higher than one half. Note that, if it is equal to one half, both households have exactly the same chance of being unconstrained, and we say that there is no constrained persistence. On the other hand, if it is constant and equal to 1 (or 0), we say that there is full constrained persistence, in the sense that, if a household is unconstrained (constrained) at a certain period, it will be unconstrained (constrained) with certainty in the future. To see how the degree of constrained persistence affects the risky asset moments, recall that these components are given by


We first note that, if Pt is constant over time, it is possible to obtain an exact closed-form solution for the previous expressions, given by


Clearly, a constant probability arises in the presence of full constrained persistence, in which case the effects of idiosyncratic risk are also maximized, since the probability is equal to 1 in this case.7
Alternatively, a constant probability would also arise if the two households were subject to i.i.d. shocks with different means, a case that can be incorporated in our model by assuming a mean for ε1 that is different from one half and ψε=0.
, there exists a period k after which the terms in the sums are negligible. In this case, the effects of idiosyncratic uncertainty will be maximized if the probabilities are sufficiently close to one during the first k periods. We therefore conclude that, for idiosyncratic uncertainty to have an effect on the risky asset moments, one needs persistence in who is constrained.
While assuming full constrained persistence might seem unrealistic, since this implies that the same household determines the asset moments every period, note that this would arise in the following situations. First, full constrained persistence trivially arises in the presence of a representative household that is subject to aggregate and idiosyncratic risk, a setup that has been analyzed by several authors in the literature to study the potential of a model to replicate the asset return moments.8
As an example, Heaton and Lucas (1996) study an exchange economy with two agents and trade in a stock and a risk-free one-period bond, while they also analyze the case in which the asset moments are determined by a representative household subject to labor income risk. They show that, when consumption is equated to the individual labor income process, the predicted equity premium becomes much larger.
Results not reported here show that, in this case, the consumption elasticities of the shareholder would be very similar to the ones in the full-participation model. Therefore, the restricted stock market participation outcome can be approximated relatively well by setting Pt=1 in the previous model.
Finally, while full constrained persistence is an interesting case, it does not arise in the presence of two households that are given the option to invest in the two asset markets. In particular, a household is (un)constrained in this case if his shock is higher (lower) than one half, in which case he wants to smooth consumption by investing in (selling) the assets. Using the normal distribution, it is easy to see that, if εit=0.5 for both households, Pt+1+j=0.5. In other words, if households are subject to the same initial shock, they will have the same chance of being (un)constrained in the future, and the model generates no constrained persistence. A similar result has been obtained by Lettau (2002) in a model with a continuum of households and independent idiosyncratic shocks. As shown by the author, when consumption is equated to labor income, the idiosyncratic effects cancel out with constant relative risk aversion preferences, a result that could be interpreted as a lack of constrained persistence, since each agent has zero mass, and the probability that the same household determines the asset moments in future periods is therefore essentially zero. Given this, the model will be analyzed assuming a different initial distribution for the two idiosyncratic shocks. While the asset moments can be obtained by using the first k periods of the previous infinite sums, the probabilities conditional on the initial shock value, denoted by
, can be calculated using the normal distribution, since
, where

To summarize, we first solve the model under full constrained persistence by setting Pt=1. As discussed previously, the results in this case constitute an upper bound for the different asset moments. Afterward, the assumption of full constrained persistence is relaxed, and the model is solved with different initial shock values for the two agents. As we will see, the quantitative impact of idiosyncratic risk is smaller in this case, while the qualitative results are, on average, very similar to the full-persistence case.
RESULTS
Identical Households
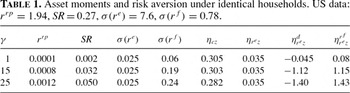
The main purpose of the present section is to obtain a benchmark for comparison with our incomplete market economies.10
The results in Lettau (2003) cannot be used because the author uses a different dividend specification.

As already shown by Lettau (2003), the RBC model with a representative agent is unable to replicate the main asset return moments in the data. Although the benchmark parameterization leads to an almost zero equity premium and to a Sharpe ratio that is approximately 100 times lower than in the data, the different asset moments are highly insensitive to an increased risk aversion, whose positive effect is mitigated by two different forces. First, a higher risk aversion leads to a smoother consumption pattern or a lower consumption elasticity (ηcz), having a negative impact on the premium. Second, a higher risk aversion increases the return elasticity component due to revisions in the future risk-free rate
, while it decreases the component due to revisions in future dividend changes
, leading to a negligible change in the total return elasticity
. Given this, the model has no chance of generating reasonable asset moments, even with an unrealistically high risk aversion parameter.
Heterogenous Households
In what follows, we analyze the impact on the different asset return moments of the presence of a second source of uninsurable uncertainty. The benchmark parameterization is the same as before. In addition, the two idiosyncratic shock parameters (ψε, σε) are quarterly adjusted estimates of the annual estimates used by different authors studying asset pricing with idiosyncratic labor income shocks (see for example, Storesletten et al. (2004)). In this literature, the annual estimates are in relatively wide ranges, given by ψaε∈(0.6, 0.95) and σaε∈(0.1, 0.32). Since we want to make sure that the shock is between 0 and 1 without having to truncate the distribution, we restrict the persistence and annual standard deviation to be in the following ranges: ψaε∈(0.6, 0.9) and σaε∈(0.1, 0.15).
Asset moments with full constrained persistence
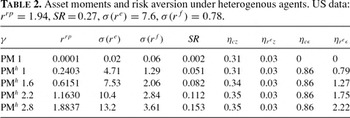
Table 2 displays the asset moments generated by the model under full constrained persistence for different values of the household risk aversion and for the two idiosyncratic parameter values at the lower end; that is, (ψaε, σaε)=(0.6, 0.1). For comparison, the moments generated by the identical household economy are also displayed in the first row of the tables.
Looking at Table 2, we see that the presence of idiosyncratic uncertainty leads to a dramatic improvement in the different asset moments. In particular, only a risk aversion of 2.8 is needed to approximately generate the risk premium in the data. In this case, the Sharpe ratio is equal to 0.15, much higher than under identical households, while the asset return variabilities are also closer to reality.

To understand the mechanisms leading to these results, recall that idiosyncratic uncertainty affects the mean and variability of the different asset moments through a new idiosyncratic component in the expressions of the unexpected equity return and the unexpected individual consumption growth. As we have seen, this leads in turn to a new term in the expressions for the premium and asset return variabilities, which we can now decompose into their value under identical households plus the value of the new term, accounting for approximately 99.5% of the total value. The following equations display this new component for the three asset moments:


where


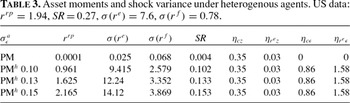
As reflected in the equations, the risk aversion parameter appears in the three terms, multiplying both the idiosyncratic consumption elasticity (ηcε) and the idiosyncratic innovation variance (σ2ε). Since these variables are independent from γ, an increase in risk aversion will clearly lead to a considerable increase in the different asset moments, as reflected by the previous tables. Using the same reasoning, it becomes clear that a similar effect will obtain if we increase the idiosyncratic innovation variance while leaving constant the risk aversion parameter. This is shown by Table 3, displaying the moments for (γ, ψaε)=(2, 0.6) and for different values of the standard deviation along the estimated range.

As predicted, the sensitivity of the different moments to an increase in the shock innovation variance is very high. With a risk aversion of 2 and the idiosyncratic standard deviation at the upper end, the model is also able to approximately generate the mean premium in the data. In this case, the Sharpe ratio is again around 0.15, while the two return variabilities are similar to the ones obtained earlier. Thus, both the household risk aversion and the idiosyncratic innovation variance are key determinants of the size of the asset moments, since they enter the new terms in a multiplicative way.
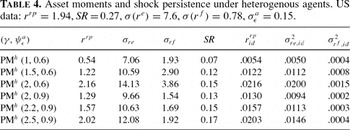
In spite of the considerable improvement, however, the results are not completely satisfactory, given that the Sharpe ratio is still around one half its value in the data. In other words, the equity return variability generated by the model is too high, while the same happens with the variability of the risk-free rate. As shown by the tables, this happens when varying both γ and σε. In what follows, we investigate the robustness of this result to a change in the idiosyncratic shock persistence ψε, which is the third parameter directly affecting the new components. The following tables display the results of increasing the risk aversion parameter for the two idiosyncratic persistence levels at the lower and upper ends.
Table 4 shows that a higher persistence level leads to an improvement in the results concerning the risk-return trade-off predicted by the model. While a risk aversion of 2 generates the mean premium in the data with the lower persistence level, a risk aversion of 2.5 generates the same mean premium with ψaε=0.9, with a lower variability of the equity return in this case, leading also to a higher Sharpe ratio. In addition, the standard deviation of the risk-free rate is approximately one half of the one obtained with ψaε=0.6.

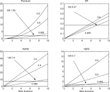
Clearly, the improvement in the variabilities is caused by the effect of the shock persistence on the new components entering the three asset moments, displayed in the last three columns of the table. It is easy to show that, for a given risk aversion parameter, these three terms are decreasing in the shock persistence. This can also be seen in the tables when moving from the third to the fourth row. In addition, it can also be shown that the sensitivity of the idiosyncratic return variance components to an increase in risk aversion is lower with a higher persistence. In other words, the more than proportional effect on the equity return variance caused by an increase in risk aversion is partly mitigated by the higher persistence level. These effects are further illustrated by Figure 1.

Asset moments for different persistence levels.
The figure shows the effects of a higher risk aversion, displayed on the x axis, on the different asset moments for the lower-end innovation variance and the lower- and upper-end persistence levels, as well as for ψaε=0.985, which is the persistence level needed to generate the right risk-return trade-off. The straight line represents the value of the different moments in the data. As discussed earlier, the slope of the lines determining the asset moments decreases with a higher shock persistence. In addition, while a persistence level inside the estimated range has no chance of generating the right return variabilities, we see that the third line, corresponding to ψaε=0.985, intersects the U.S. line in the same risk aversion region for the premium, the equity return variance, and the Sharpe ratio. With the mentioned persistence, a risk aversion of around 6 generates the three moments in the data, while the risk-free rate variability is around 1.2%, slightly higher than the U.S. level. Note, however, that this is only possible with an annual idiosyncratic persistence outside the estimated range of ψaε=(0.6, 0.95). In this sense, we could say that the success of the model is only partial.
Asset moments with partial constrained persistence
In what follows, we display the same asset moments for different initial values of the first household's idiosyncratic shock, calculated without assuming full constrained persistence. As stated earlier, we use the true probabilities conditional on the initial shock value
, and only sum over the first k-periods to approximate the idiosyncratic terms, where k is endogenously determined depending on the parameterization.11
The number k varies with the parameterization. As an example, with Pt=1, the lower-end persistence level and a household risk aversion of 1, ten periods would lead to a difference between the true and the approximated moments of less than 1e − 03 if we use the lower idiosyncratic innovation variance, while 17 periods would lead to the same result if we use the variance at the upper end.

The first three columns Table 5 display the results for a risk aversion of 1, and the last three show the same numbers when the risk aversion is increased to 3. For comparison, the results obtained under full persistence are displayed in the first row of the table. Further, the next five rows display the results for different values of the initial shock, and the last row averages the numbers obtained with different initial shock values. As we see, the qualitative results are very similar to the full-persistence case, whereas the quantitative impact is considerably smaller when the initial shock value is closer to 0.5, in which case the model generates a low constrained persistence. On the other hand, even in this case, an increase in risk aversion has a considerable impact. As an example, a risk aversion of 3 already generates a premium of 1.2% when the initial shock is equal to 0.6 for the first household, while, averaging over initial shock values, a risk aversion of γ=3.3 generates the same numbers as under full-persistence and γ=3. As reflected in Table 6, a similar pattern can be obtained when increasing the idiosyncratic shock variance.

The first three columns of Table 6 display the numbers for an innovation standard deviation of 0.1 in annual terms, while the last three columns assume an annual standard deviation of 0.15. As we see, the results are again similar to the full-persistence case when the initial shock value is close to 1. In this case, the autoregressive structure of the shock and the fact that it is relatively persistent itself implies that household 1 will be unconstrained with a high probability in the future, increasing the impact of idiosyncratic risk. In addition, we still observe a relatively big effect with respect to the identical household economy when the shock is close to 0.5. In particular, with the higher shock variance, a risk aversion of γ=2 generates a premium of 0.97%; when averaging over initial shock values, a risk aversion of γ=2.3 is needed to obtain the same results as under full-persistence and γ=2. Finally, we have also calculated the moments for different values of the idiosyncratic shock persistence, displayed in Table 7.

As before, the idiosyncratic shock persistence in annual terms is increased from 0.6 to 0.9. The first three columns of the table display the full-persistence case, while the last three display the results for initial shock values of 0.6 and 0.9, respectively. Further, we have reported the results for initial shock values of 0.6 and 0.9. As we see, a higher idiosyncratic shock persistence improves the results concerning the risk-return trade-off. In particular, the improvement is higher than under full persistence because of the effect of ψε on the probabilities, which reduces the impact of an increase in risk aversion of the equity return variability. In spite of this, results not reported here show that the model still has a problem in replicating the right risk-free rate variability.
To summarize, given a certain parameterization, the quantitative impact of idiosyncratic risk with less than full constrained persistence is lower than before. On the other hand, the general qualitative predictions obtained earlier are essentially unaltered. In all cases, the asset moments are considerably higher than under identical households, and they are very sensitive to an increase in the household risk aversion and in the idiosyncratic innovation variance. Further, a higher idiosyncratic shock persistence leads to a better Sharpe ratio, but the model still fails with respect to the risk-free rate variability.
SUMMARY AND CONCLUSIONS
The present paper has extended the approximated analytical approach used by Lettau (2003) to study the asset pricing implications of extending the standard RBC model with an idiosyncratic labor income shock. To be able to obtain closed-form solutions for the asset moments, we have assumed that households cannot use the asset markets to insure against uncertainty, resulting in an incomplete financial market structure. Further, given that the usual value maximization objective is no longer well defined under shareholder heterogeneity and market incompleteness, the firm is assumed to maximize a variant of market value maximization, consisting of the present discounted value of net cash flows, discounted by the weighted average of the shareholders' marginal rates of substitution, with the weights being their original shareholdings. In addition, we assume that the firm owns the entire capital stock, decides on the investment level, and pays the residual of profits (output net of wage payments) and investment out as dividends.
We show that the presence of a symmetric idiosyncratic labor income shock leads to a new idiosyncratic component in the expressions of the pricing kernel and of the unexpected equity return. Concerning the last, the idiosyncratic component arises from the fact that news about future returns can only be due to news about future risk-free rates in the model, given the constant risk premium over time. Since the risk-free rate is directly affected by idiosyncratic risk, its presence in the expression of the unexpected equity return implies that this return will also contain an idiosyncratic component. We show that this component crucially depends on the degree of constrained persistence, that is, from the degree at which the same household is constrained for a certain number of periods. In particular, idiosyncratic uncertainty has an effect as long as there is constrained persistence. We study the results under two assumptions. We first assume that there is full constrained persistence, corresponding to the case in which the asset moments are computed by a representative household subject to labor income risk. Alternatively, the results can also be interpreted as the outcome of a model with restricted stock market participation. In a second exercise, we assume that households have different initial shock values, leading to different degrees of (less than full) constrained persistence. In both cases, we are able to decompose the equity premium and the two asset return variabilities into their value under identical households and a new term, only affected by idiosyncratic risk.
Under full constrained persistence, the presence of the new idiosyncratic term, which accounts for approximately 99.5% of the moments, implies that the model is able to generate the right equity premium in the data with a reasonable parameterization. In this case, it is possible to obtain closed-form solutions for the idiosyncratic components, which are essentially driven by three parameters: the household risk aversion, the idiosyncratic innovation variance, and the idiosyncratic shock persistence. Since the first two enter the new terms in a multiplicative way, all the asset moments are found to be highly sensitive to an increase in these two parameter values. In addition, we find that an increase in the premium, due to a higher risk aversion or a higher innovation variance, is accompanied by a more than proportional effect on the two asset return variabilities, which are too high relative to the data. This result can be improved by increasing the idiosyncratic shock persistence, which dampens the effect of an increase in risk aversion on the two return variabilities. To generate the right risk-return trade-off, however, a too-high persistence would be needed. Therefore, we can say that the success of the model is only partial. Finally, when the assumption of full constrained persistence is relaxed, the qualitative findings are essentially the same, while the quantitative impact is smaller for a given parameterization.
Several final remarks are worth noting. First, our results cannot be directly extrapolated to models with asset trade, in which case the behavior of the accumulated asset wealth also plays a crucial role. In addition, one has to be careful in assesing the potential effects of idiosyncratic risk on the basis of the present results since it has been shown by several authors that the presence of asset trade leads to a considerable amount of risk sharing, and the results in this case are therefore very similar to the identical-household (or complete-markets) counterpart. On the other hand, our findings provide a good overview of the mechanisms by which idiosyncratic risk could affect the different asset moments. Further, they suggest that highly persistent idiosyncratic shocks are not sufficient to generate reasonable asset return moments, but one also needs persistence in who is constrained. Among other things, this would suggest that models with restricted stock market participation seem to be good candidates to obtain more realistic asset return moments.
APPENDIX
THE GROSSMAN AND HART FIRM OBJECTIVE
In the economy of Section 2, the budget constraint of consumer i is given by

Denote the production plan of the firm by y and suppose that the economy is in equilibrium relative to this production plan. Consider now the consequences of the firm changing its production plan from y to some
. Following Grossman and Hart (1979), we consider an infinitesimal change in the direction of
, (y+∂y), by defining
, where 0[les ]λ[les ]1, and by investigating the effect of a change from y to yλ for a small λ>0. Note that, in the presence of trade in equity shares among the firm's shareholders, this change would affect them in two ways: First, the dividends paid by the firm would be altered and, second, they would have to pay a different price to acquire or sell their shares. On the other hand, the absence of trade implies that shareholders in our economy will only be affected by the change in the dividend stream. In particular, denote the consumer's maximized utility with respect to the old production plan by
, and suppose that the firm changes its plan. This will lead to the following utility change12
As in Grossman and Hart (1979), we assume that consumers react to the change in the production plan by keeping consumption and shareholdings fixed, implying that equation (2) represents a lower bound on the utility change.

Given this, the maximum amount of date t income that consumer i would give up to put the new plan into effect is equal to

where Mit+j=[U′(Cit+j)]/[U′(Cit)] and Mit=1. Further, summing over all shareholders, we obtain

Note that the firm should make the change in the direction of
if and only if [sum ]Ii=1bit>0, implying that it will be possible to compensate the shareholders that are made worse off by the change. Given this, the production plan chosen by the firm should therefore maximize

which exactly coincides with the proposed PM firm objective.
THE MACROECONOMIC ELASTICITIES
The following log-linearized system of equations is used to solve for the elasticities of the macroeconomic aggregates:

where the coefficients denoted by λ are constants, depending on the parameters of the model Φ={α, δ, β, ψ, σz, γ, ψε, σε}. Guessing that logged aggregate consumption takes the form

where ηxy is the elasticity of variable x with respect to variable y, it is easy to show that the elasticities of output, capital, investment, and dividends with respect to the two state variables are given by


Substituting for the corresponding variables in the capital stock expectational equations, setting Etzt+1=ψzt, and using the method of undetermined coefficients, we can obtain the consumption elasticities with respect to the two state variables by solving the following two equations:

where Q0, Q1, and Q2 are constants that differ for the two firm objectives and depend on the model parameters Φ, and f is a nonlinear function. From the system above, it becomes clear that, once we have solved for the two consumption elasticities, we can easily obtain the elasticities for the other endogenous variables. On the other hand, the log-linearized budget constraint implies that the individual consumptions are given by13
The expression for
is obtained by doing a first-order Taylor expansion of equation (5) in the main text around
, whose steady-state level is assumed to be 0.5.

where


where

ASSET MOMENTS
The Risk-free Rate
The infinite period representation of the risk-free rate is given by

where

Therefore, the unconditional standard deviation of the process is equal to

where


Unexpected Equity Return
The unexpected equity return can be calculated using the decomposition of unexpected returns due to Campbell and Shiller (1994) into revisions in expectations of future dividend changes and revisions in expectations of future returns, implying that

To calculate the infinite sums, we first note that expected risk premia are constant in the model, and only news of the expected future risk-free rate can lead to an unexpected equity return, implying that

where ρ=β in our model. Second, since dividends are only affected by the aggregate technology shock, the first sum on the right-hand side is the same as under identical households; that is,

where

Further, substituting for the risk-free rate process into the second sum, we obtain

where

and
is the innovation of the household that is unconstrained at period t+j+1. If we let
, the unexpected equity return can then be written as

Finally, let Pt+j+1=prob(ut+j+1=1); that is, Pt+j+1 denotes the probability that the first household is unconstrained at period t+j+1. Using the fact that ε2t=−ε1t, each of the terms in the previous infinite sum can be expressed as (ρψε)j[Pt+j+1ε1t+1+(1 − Pt+j+1)(−ε1t+1)]=(ρψε)j(2Pt+j+1 − 1)ε1t+1, implying that


Sharpe Ratio
An expression for the Sharpe ratio can be directly obtained from the excess return pricing equation, implying that

where ρt denotes a conditional correlation and the last equality follows from the the fact that, in our lognormal environment,


I would like to thank two anonymous referees, Antoni Calvo Armengol, Morten Ravn, Albert Marcet, Harald Uhlig, and Martin Lettau for their valuable comments and suggestions. In addition, I am very greatful to my thesis defense committe members Wouter den Haan, Lars Ljungqvist, Kjetil Storesletten, Javier Suarez, and Juanjo Dolado for their comments.
References
Boldrin M.
J. Christiano, and
J. Fisher
2001
Habit persistence, asset returns and the business cycle.
American Economic Review
91,
149–
166.Google Scholar
Campbell J.Y.
1994
Inspecting the mechanism, An analytical approach to the stochastic growth model.
Journal of Monetary Economics
33,
463–
506.Google Scholar
Campbell J.Y. and
R. Shiller
1994
The dividend price ratio and expectations of future dividends and discount factors.
Review of Financial Studies
1,
195–
228.Google Scholar
Carceles-Poveda E.
2003
Asset Prices and Business Cycles Under Market Incompleteness.
Working Paper, SUNY at Stony Brook.
Carceles-Poveda E.
2004
Capital adjustment costs and firm risk aversion.
Economic Letters
81,
101–
107.Google Scholar
Danthine J.P. and
J.B. Donaldson
2002
Labor relations and asset returns.
Review of Economic Studies
69,
41–
64.Google Scholar
Grossman S.J. and
O.D. Hart
1979
A theory of competitive equilibrium in stock market economies.
Econometrica
47,
293–
330.Google Scholar
Grossman S.J. and
J.E. Stiglitz
1977
On value maximization and alternative objectives for the firm.
Journal of Finance
32,
389–
402.Google Scholar
Guo H. (in press)
Limited stock market participation and asset prices in a dynamic economy.
Journal of Financial and Quantitative Analysis.
Guvenen F.
2003
A Parsimonious Macroeconomic Model of Asset Pricing: Habit Formation or Cross Sectional Heterogeneity?
Working paper.
Heaton J. and
D. Lucas
1996
Evaluating the effects of incomplete markets on risk sharing and asset pricing.
Journal of Political Economy
104,
443–
487.Google Scholar
Jermann U.J.
1998
Asset pricing in production economies.
Journal of Monetary Economics
41,
257–
275.Google Scholar
Krusell P. and
A. Smith
1997
Income and wealth heterogeneity, portfolio choice, and equilibrium asset returns.
Macroeconomic Dynamics
1,
387–
422.Google Scholar
Lettau M.
2002
Idiosyncratic risk and volatility bounds, or, can models with idiosyncratic risk solve the equity premium puzzle?
Review of Economics and Statistics
84,
376–
380.Google Scholar
Lettau M.
2003
Inspecting the mechanism: The determination of asset prices in the real business cycle model.
Economic Journal
113,
550–
575.Google Scholar
Lettau M. and
H. Uhlig
2002
Can habit formation be reconciled with real business cycle facts?
Review of Economic Dynamics
3,
79–
99.Google Scholar
Lettau M. and
H. Uhlig
2002
Sharpe ratios and preferences: An analytical approach.
Macroeconomic Dynamics
6,
242–
265.Google Scholar
Lucas J. D.
1994
Asset pricing with undiversifiable income risk and short sale constraints. Deepening the equity premium puzzle.
Journal of Monetary Economics
34,
325–
341.Google Scholar
Marcet A. and
K. Singleton
1999
Equilibrium asset prices and savings of heterogeneous agents in the presence of incomplete markets and portfolio constraints.
Macroeconomic Dynamics
3,
243–
277.Google Scholar
Mehra R. and
E.C. Prescott
1985
The equity premium: A puzzle.
Journal of Monetary Economics
15,
145–
161.Google Scholar
Rouwenhorst K.G.
1995
Asset prices implications of equilibrium business cycle models.
In T.F. Cooley (ed.),
Frontiers of Business Cycle Research,
pp. 294–
330.
Princeton, NJ:
Princeton University Press.
Storesletten K.,
C. Telmer and
A. Yaron
2004
Cyclical dynamics in idiosyncratic labor market risk.
Journal of Political Economy
112,
695–
717.Google Scholar
Telmer C.
1993
Asset pricing puzzles and incomplete markets.
Journal of Finance
48,
1803–
1832.Google Scholar
Uhlig H.
1999
A toolkit for analyzing nonlinear dynamic stochastic models easily.
In R. Marimon and
A. Scott (eds.),
Computational Methods for the Study of Dynamic Economies,
pp. 30–
61.
Oxford:
Oxford University Press.
Asset moments and risk aversion under identical households. US data: rrp=1.94, SR=0.27, σ(re)=7.6, σ(rf)=0.78.
Asset moments and risk aversion under heterogenous agents. US data: rrp=1.94, SR=0.27, σ(re)=7.6, σ(rf)=0.78.
Asset moments and shock variance under heterogenous agents. US data: rrp=1.94, SR=0.27, σ(re)=7.6, σ(rf)=0.78.
Asset moments and shock persistence under heterogenous agents. US data: rrp=1.94, SR=0.27, σ(re)=7.6, σ(rf)=0.78, σaε=0.15.
Asset moments for different persistence levels.
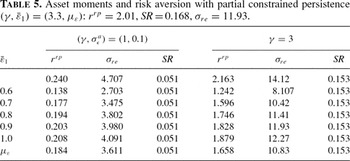
Asset moments and risk aversion with partial constrained persistence $(\gamma,\bar{\varepsilon}_{1})=(3.3,\mu_{\varepsilon})$: rrp=2.01, SR=0.168, σre=11.93.
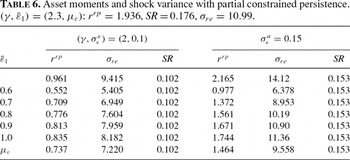
Asset moments and shock variance with partial constrained persistence. $(\gamma,\bar{\varepsilon}_{1})=(2.3,\mu_{\varepsilon})$: rrp=1.936, SR=0.176, σre=10.99.
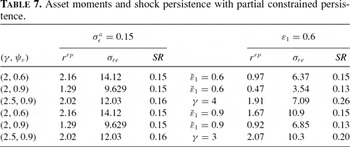
Asset moments and shock persistence with partial constrained persistence.
 You have
Access
- 9
- Cited by