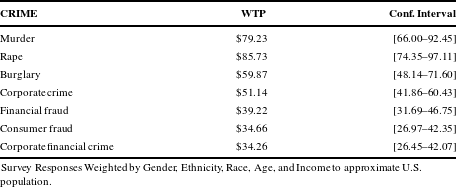1. Introduction
Economists have long had differing views over how to properly account for stolen money in a benefit-cost analysis. One view is that theft and fraud are simply transfers of wealth from one party to another and thus there is no “social cost” associated with these illegal activities. Another view is that they can be considered an “externality” similar to pollution – where the transfer was not part of a voluntary transaction between the offender and the victim (Cohen, Reference Cohen2005). Regardless of whether one considers the money transfer to be an externality or a social cost, however, many thefts and frauds involve losses that are far beyond pure monetary transfers to victims. For example, a victim of identity theft might spend considerable time dealing with financial institutions to clear up the consequences of the theft – time that could be valued. Similarly, a victim of financial fraud who loses her home due to inability to pay might suffer severe psychological harm that an economist might also value. Finally, the very existence of Internet fraud and identity theft causes potential victims to take costly actions to avoid victimization. Thus, victims of white-collar and corporate crimes – as well as potential victims - may suffer in many ways beyond any money transfers.
Regulatory agencies such as the Federal Trade Commission (FTC), the Securities and Exchange Commission (SEC), and the Consumer Financial Protection Bureau (CFPB) regulate various types of consumer, investor, and financial frauds. The SEC, for example, recently issued guidance on conducting economic analysis in their rulemakings that called for quantification of benefits when possible,Footnote 1 while the CFPB is required by law to conduct benefit-cost analysis of any proposed rules.Footnote 2 Despite the sophisticated economic analysis conducted by both the SEC and CFPB and required benefit-cost assessments of regulation by federal agencies, to date the “cost” of any misleading or fraudulent behavior is generally assumed to be any additional cost paid by the consumer – oftentimes the monetary transfer itself. Researchers who conduct benefit-cost analyses have also published their findings assuming that out-of-pocket losses are the only costs of fraud (see e.g., Welsh, Farrington & Sherman, Reference Welsh, Farrington and Sherman2000). Yet, to the extent society wishes to optimally deter such crimes, without better data on nonmonetary costs, any benefit-cost analyses of criminal justice or prevention programs designed to reduce these crimes will inevitably underestimate program benefits.
Previous research on the costs of street crime has adopted various approaches to value nonmonetary harms (see Cohen, Reference Cohen, Roman, Dunworth and Marsh2010 for a review of this literature). Researchers who conduct benefit-cost analyses of such diverse programs as early childhood education (Belfield et al., Reference Belfield, Nores, Barnett and Schweinhart2006), policing (Levitt, Reference Levitt1997), and incarceration (Owens, Reference Owens2009) routinely use nonmonetary benefits of reductions in street crime in their analyses. Perhaps more importantly, government agencies are also beginning to incorporate nonmonetary costs into their crime policy analyses. For example, Washington State includes the intangible costs to victims in their policy analyses (see Aos and Drake, Reference Aos and Drake2010 and more generally http://www.wsipp.wa.gov/BenefitCost), and the Department of Justice recently utilized willingness-to-pay (WTP) estimates of the cost of rape in its regulatory impact assessment of prison rape regulations (U.S. DOJ, 2012). Without using nonmonetary cost estimates, the Prison Rape Elimination Regulatory Impact Assessment would have only included the out-of-pocket costs of rape (medical costs, wage losses, etc.) and the final prison rape rule never could have been justified using benefit-cost analysis.
This paper begins the process of extending estimates of the nonmonetary costs of crime to white-collar and corporate offenses. In a sample of 1100 U.S. survey respondents, we find considerable similarity between the public’s WTP to reduce white-collar and corporate crime compared to traditional street crimes. Section 2 briefly reviews the theory and empirical evidence to date on the nonmonetary costs of white-collar and corporate crime. Section 3 describes the survey methodology. Section 4 reports on the survey findings related to the seriousness of white-collar and corporate crime, while Section 5 presents estimates of the public’s WTP to reduce these crimes. Concluding remarks are contained in Section 6.
2. Evidence on the nonmonetary costs of white-collar and corporate crime
While the impact of white-collar and corporate crime is felt most directly on victims, taxpayers and society at large incur many costs as well. Moreover, these costs are oftentimes nonmonetary yet real. For example, consider a victim of mortgage fraud who ultimately pays a higher interest rate and fees that were not disclosed. While the victim’s loss includes these higher fees, there might be collateral consequences such as a reduced credit rating or higher cost of borrowing. In an extreme case, the victim might lose her home and incur moving costs, higher rent payments, longer commute times, or other serious inconveniences. The victim might also suffer intangible losses such as increased anxiety or fear. Law enforcement officials or regulators might become involved, with costs accruing to government agencies and courts. Finally, and perhaps as important as any other cost, the fact that all consumers are exposed to the risk of fraudulent mortgage brokers prompts us all to take expensive precautions to avoid becoming victimized. We might be less inclined to do business with smaller, newer, yet legitimate companies or individuals who we fear might be defrauding us and thus pay a “risk premium” for doing business with more established institutions. Some consumers might simply refuse to purchase a home and continue to rent due to their fear of being victims of fraudulent mortgage lenders. Thus, the fear of becoming a white-collar crime victim might cause the public to lose faith in governmental and/or economic institutions (see e.g., Meier & Short, Reference Meier, Short, Geis, Meier and Salinger1995 and Shover, Litton Fox & Mills, Reference Shover, Litton Fox and Mills1994). The bottom line is that the costs of white-collar and corporate crime are far-reaching – to offenders, victims, and society at large.
There is very little literature to date either quantifying or monetizing the costs of white-collar and corporate crime. Most of that literature focuses solely on the out-of-pocket losses and thus is of little help in understanding the total costs of white-collar and corporate crime. A few studies have documented the psychological harm that might accrue to victims of fraud. For example, Ganzini, McFarland and Bloom (Reference Ganzini, McFarland and Bloom1990) obtained police records from 77 victims of a Ponzi scheme and found that 45% suffered from “generalized anxiety disorder” compared to 15% of a control group, and 29% had a “major depressive episode” vs. 2% of controls. Similarly, Sharp et al. (Reference Sharp, Shreve-Neiger, Fremouw, Kane and Hutton2004) obtained police records for 29 identity theft victims and found that more than 50% had unresolved depression or anxiety, with two victims reported seeking professional help. While these studies were based on convenience samples, their findings are clear – the costs of fraud far exceed monetary losses in some cases.
In order to go beyond the pure monetary costs of victimization, economists have applied various survey techniques to estimate the costs of white-collar crimes. The most typical approach is a “bottom up” estimate of the individual components of the costs of crime. For example, the FTC (2003, 2007) has commissioned several surveys of identity theft victims and asked them how much was stolen, how much they ultimately had to pay out-of-pocket, and how much time they spent dealing with the consequences of the theft. While victims of identity theft frequently reported other negative consequences such as being harassed by debt collectors, denied credit cards, utilities cut off, etc., these costs are not monetized in the FTC studies. In theory, each of these cost components can be individually estimated and added up to estimate the cost of identity theft. However, even if all victim costs are included, all of these “bottom up” approaches ignore some very important components of the costs of crime – including expenditures or actions taken by the public to avoid the risk of crime, as well as any residual “fear of crime,” or loss to the community such as decreased business development.
An alternative approach is to estimate costs from the “top down,” by eliciting information on the public’s WTP for reduced crime (Cohen et al., Reference Cohen, Rust, Steen and Tidd2004). In theory, the “top down” and “bottom up” approaches should lead to the same estimate if the latter is all-inclusive. Cohen (Reference Cohen, Roman, Dunworth and Marsh2010) compared these two approaches in the case of street crimes and concluded that the “bottom up” approaches thus far have not fully captured the costs of crime. Piquero, Cohen and Piquero (Reference Piquero, Cohen and Piquero2010) utilized a “top down” approach to estimate the public is willing to pay $73–$87 annually to reduce identity theft by 25%–75%. This translates into a WTP of between $1526 and $3842 per identity theft – compared to direct victim costs (including dollar losses and the value of victim’s time) that were estimated to be $1392. To date, identity theft is the only white-collar crime that has been studied using the WTP approach. Cohen (Reference Cohen, Van Slyke, Cullen and Bensonforthcoming) contains a review of the literature on estimating the costs of white-collar and corporate crime.
3. Survey methodology
A web-based survey was designed and administered in January and February 2013. The survey respondents were part of “e-Lab” – an ongoing web panel maintained by Vanderbilt University. Participants have previously opted in to this panel and receive periodic requests to fill out a web-based survey in exchange for a chance to receive cash prizes that are randomly awarded to participants (generally about $100 to $250). Participants in this study were limited to U.S. adults over age 18, and a total of 27,223 invitations were sent out to panel members. A total of 1099 responses were received, resulting in a 4% response rate. Note that once our quota of approximately 1100 responses was obtained, the survey was closed, so it is possible that a higher response rate would have been achieved.
The survey was designed to closely replicate two previous surveys to ensure comparability. A series of questions on the perceived seriousness of various white-collar crimes were taken from the National Public Survey on White Collar Crime (Huff, Desilets & Kane, Reference Huff, Desilets and Kane2010) (“NPSWCC”). Questions related to the public’s WTP for crime reduction policies were patterned directly after questions about street crime in a survey conducted in 2000 by Cohen et al. (Reference Cohen, Rust, Steen and Tidd2004). Because these surveys were being replicated almost verbatim, there was no need for an extensive survey development and pretesting process.
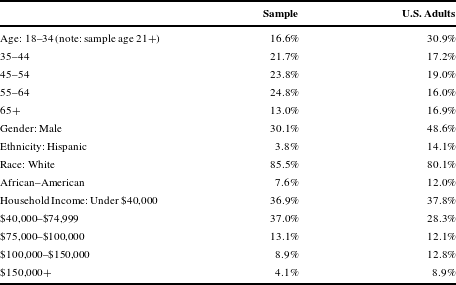
Table 1 reports on the demographics of the 1099 e-Lab respondents. Survey respondents were more likely to be older, female, white, and have a lower income than the U.S. population. While the e-Lab panel is not a nationally representative sample, as members choose to participate and are clearly Internet savvy, demographic information does permit weighting to be representative of the national adult population on criteria such as age, gender, ethnicity, race, and income. In the results that follow, all respondents were weighted by age, gender, race, ethnicity, and income to be representative of the U.S. population on these characteristics.
Demographics of sample respondents vs. U.S. adult population.

4. How serious is white-collar and corporate crime?
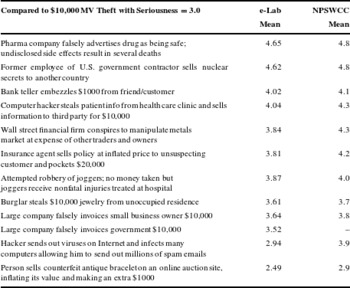
Respondents were asked to compare the seriousness of various crimes to a base case of “someone stealing a parked car on the street that is worth $10,000.” These questions were identical to the nationally representative sample of the U.S. public conducted in 2010 (Huff et al., Reference Huff, Desilets and Kane2010). Respondents were given a five-point Likert scale: 1
 $=$
much less serious; 2
 $=$
more serious; 3
 $=$
about as serious; 4
 $=$
more serious; and 5
 $=$
much more serious. As shown in Table 2, the ranking results are strikingly similar, although the e-Lab respondents consistently reported slightly lower seriousness than the NPSWCC respondents.Footnote
3
In both samples, almost all of the white-collar and corporate offenses are deemed to be more serious than the motor vehicle theft. One particularly interesting difference is that the e-Lab sample ranked the “hacker who sends out viruses on Internet and infects many computers allowing him to send out millions of spam emails” a full point lower than the NPSWCC sample. Although purely speculative, this might be an indication of the sample difference – with the e-Lab sample being sophisticated and regular Internet users who might either be less sympathetic to such victims or feel they have little risk of being victimized themselves due to precautions they already take.
Seriousness of white-collar and corporate crimes (e-Lab weighted sample compared to National Public Survey on White Collar Crime).

One deviation from the NPSWCC survey was to randomize the question involving a $10,000 false invoice by a large firm. The NPSWCC question indicated that the victim was a “small business.” In the e-Lab sample, the victim was randomized with half of victims being a “small business” and half being a “government.” While the differences are not statistically significant, the average seriousness score was higher for the small business victim (3.64) than for the government (3.52).
In an earlier study of the public’s WTP for street crime reductions, Cohen, Roland and Steen (Reference Cohen, Rust and Steen2006) asked respondents to allocate a fixed budget among a potential tax rebate and various crime policies – including prison, drug and alcohol treatment programs for nonviolent offenders, police, and youth prevention programs.Footnote 4 One of the conclusions at the time was that the public valued youth prevention programs most highly, and valued a tax rebate over longer prison sentences. Here, 50% of e-Lab respondents were asked the identical questions as the Cohen et al. (Reference Cohen, Rust and Steen2006) sample, while the other half were given the same questions with one additional option – “law enforcement resources to combat white-collar and corporate crime.” The exact question was:
For the next question, I want you to put yourself in the shoes of your local mayor. The Federal government has given your city $1000 per household. You may spend all or part of that money on crime control or crime prevention, or you may give all or part of it back to your local residents. [Four/Five] different crime control strategies have been recommended to you:
-
(1) Longer prison sentences for street criminals.
-
(2) More drug and alcohol treatment programs for offenders convicted of nonviolent crimes.
-
(3) More police on the street.
-
(4) More prevention programs to help keep youth out of trouble.
-
(5) More law enforcement resources to combat white-collar and corporate crime.
-
(6) Rebate to local residents.
You have $1000 to allocate among these options. You can allocate all of it to any one category or split it up in any amount you want. To make things easier, when you type in an amount we will show you how much you have left to allocate. You can change the amounts at any time until you are comfortable with the allocation.
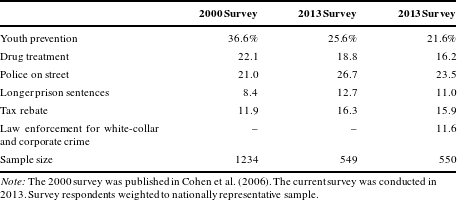
The first two columns of Table 3 compare the mean percentage of money that was allocated to each option in the 2000 survey as reported in Cohen et al. (Reference Cohen, Rust and Steen2006) to that in the e-Lab sample that was conducted in 2013. While the responses are similar, the more recent sample appears to be less interested in prevention programs and more interested in prison or incarceration than the earlier sample. The extent to which these differences represent a change in public sentiment from 2000 to 2013 versus the potential nonrepresentativeness of the e-Lab sample is unknown. In both cases, however, longer prison sentences for street offenders are given lower priority than a tax rebate. For our purposes, the last column is of most interest. It appears that increased law enforcement for white-collar and corporate crime is given a lower priority than all options except longer prison sentences – and those differences are statistically insignificant. In addition to placing higher priority on street crime prevention, survey respondents would prefer more money going to a tax rebate than white-collar and corporate crime law enforcement programs.
Tax rebate vs. crime control/prevention policies (e-Lab weighted sample compared to Cohen et al. (Reference Cohen, Rust and Steen2006)).

Note: The 2000 survey was published in Cohen et al. (Reference Cohen, Rust and Steen2006). The current survey was conducted in 2013. Survey respondents weighted to nationally representative sample.
5. Willingness to pay to reduce white-collar and corporate crime
Finally, respondents were asked a series of questions designed to elicit their WTP to reduce white-collar and corporate crimes. Once again, respondents were given virtually identical questions to an earlier survey on WTP to reduce street crime, and direct comparisons could be made with the earlier study Cohen et al. (Reference Cohen, Rust, Steen and Tidd2004).Footnote 5
The actual language used in the survey was:
…now I want to ask you how much of your own money you would be willing to pay to reduce certain crimes. In each case, I am going to ask you to vote “yes” or “no” to a proposal that would require your household and each household in your community to pay money to prevent crime in your community.
Remember that any money you agree to spend on crime prevention is your money that could otherwise be used for your own food, clothing, or whatever you need. Unlike the previous question, where the government was planning to give you money back, now I want you to think about actually taking more money out of your pocket. While we are not asking you to actually pay anything, we want you to think about this question honestly and consider your own situation – how much you have to spend on other priorities and whether or not you would personally be willing to spend money on the following:
Last year, a new crime prevention program supported by your community successfully prevented one in every ten [CRIME] from occurring in your community.
Would you be willing to pay $100 per year to continue this program?
If the respondent answered yes, they were then asked if they would be willing to pay $200. If they answered no, they were asked if they were willing to be $50.Footnote 6 In all cases, they were asked to explain their final answer in an open-ended response.
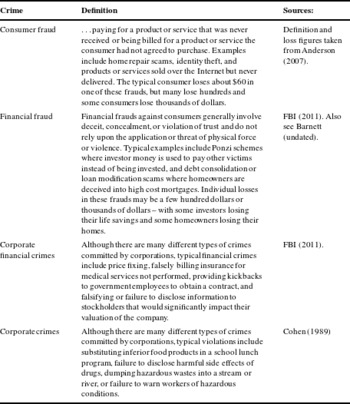
Each respondent was asked about three different crimes – one of three randomly chosen street crimes (burglary, rape or murder), one white-collar crime (“consumer fraud” or “financial fraud”), and one “corporate crime” (“corporate crime” or “corporate financial fraud”). While the street crimes were not defined, respondents were given definitions for their corresponding white-collar or corporate crimes, shown in Table 4.
White-collar and corporate crime definitions used in e-Lab survey.

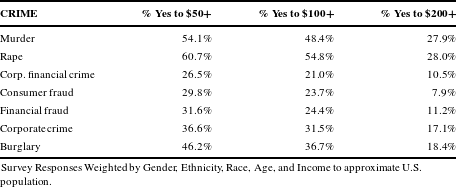
Table 5 reports on the distribution of “yes” votes for respondents’ WTP for individual crime reduction programs.Footnote
7
For example, 54.1% of respondents were willing to pay at least $50 annually to reduce murder by 10%, compared to 31.6% who reportedly were willing to pay that amount to reduce financial frauds. Most of the differences in the first two columns of Table 5 are statistically significant at
 $p<0.05$
.Footnote
8
Similarly, only 27.9% are willing to pay at least $200 to reduce murder by 10%, compared to only 11.2% who are willing to pay that amount to reduce financial frauds.Footnote
9
Respondents were given the option of saying “I don’t know” or “I’d rather not say.” These responses were considered to be “no” for purposes of estimating WTP. About 14%–16% of responses were “don’t know” (with the highest percentage being for street crimes). However, less than 1% of responses were refusals (indicating they would rather not say).
Distribution of “yes” votes for crime reduction programs.

Survey Responses Weighted by Gender, Ethnicity, Race, Age, and Income to approximate U.S. population.
Based on these responses, Table 6 reports on the average WTP for a 10% reduction in each type of crime. This is conservative, as it is assumed that if someone is unwilling to pay $50, their WTP is zero, and if someone is willing to pay at least $200, they are not willing to pay more.
Willingness to pay for 10% crime reduction.

Survey Responses Weighted by Gender, Ethnicity, Race, Age, and Income to approximate U.S. population.
The crime with the highest WTP is rape ($85.73), followed by murder ($79.23), although the difference between these two figures is not statistically significant.Footnote
10
The WTP for a 10% reduction in burglary is estimated to be $59.87, while corresponding figures are $51.14 for corporate crime; $39.22 for financial fraud; $34.66 for consumer fraud; and $34.26 for corporate financial crime. While differences between burglary and corporate crime are statistically significant from each other (and for all other crimes), the differences between last three offenses are not statistically significant. Thus, if a
 $p<.05$
statistical significance criterion is used to distinguish higher WTP, survey respondents provided the following four hierarchical groupings: (1) murder and rape, (2) burglary, (3) corporate crime, and (4) financial fraud, consumer fraud, and corporate financial fraud. While these comparisons are consistent with the 95% confidence intervals shown in Table 6, the latter also show overlap between corporate crime and the other three white-collar offenses.
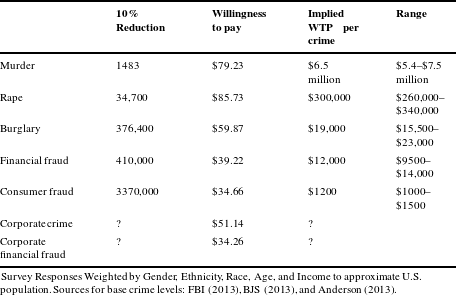
The fact that the average WTP to reduce murder is only twice that of financial fraud, for example ($79.23 compared to $39.22), might at first appear counterintuitive. However, the fact is that while murder is an extremely harmful and costly crime, it is also rare – and a 10% reduction annually amounts to about 1500 fewer murders. In contrast, the FTC (Anderson, Reference Anderson2013) estimated there were 4.1 million financial frauds in 2011 – so a 10% reduction is 410,000 offenses – more than 250 times the number of murders reduced.Footnote 11
To convert the average WTP for a 10% reduction in crime into a “cost per crime,” data is required on the number of crimes committed annually as well as the U.S. household population. For example, based on the 14,827 murders reported by the FBI in 2012, a 10% reduction is 1483 murders. Since there were approximately 121.1 million households in the U.S. in 2012, if every household paid $79.23 toward murder reduction, a total of $9.6 billion would be spent to reduce murders by 1483. Dividing $9.6 billion by this amount results in an estimated value per murder reduction of about $6.5 million per murder.
Table 7 reports on the implied WTP to reduce one crime in the U.S.Footnote 12 The highest figure is for murder at $6.5 million, followed by rape ($300,000), burglary ($19,000), financial fraud ($12,000), and consumer fraud ($1200). Because of the lack of data on the prevalence of corporate crimes, no WTP can be calculated for the two corporate crime categories.
Implied willingness to pay per crime.

Survey Responses Weighted by Gender, Ethnicity, Race, Age, and Income to approximate U.S. population. Sources for base crime levels: FBI (2013), BJS (2013), and Anderson (Reference Anderson2013).
Note that the three street crimes are similar – although somewhat lower than previous estimates using the same methodology and language in 2000, reported in Cohen et al. (Reference Cohen, Rust, Steen and Tidd2004). In that earlier study, the WTP was estimated to be $9.7 million for murder, $237,000 for rape, and $25,000 for burglary. Thus, adjusting for inflation, the e-Lab estimates produce somewhat lower values although the magnitudes and rankings are similar. This is consistent with the fact that crime rates in the U.S. are lower now than they were when the earlier survey was conducted.Footnote 13 The estimate of $6.5 million for murder is also within the range of the $4 million to $9 million estimate (median $7 million) for the value of a statistical life typically found in the U.S. based on labor market data (Viscusi & Aldy, Reference Viscusi and Aldy2003), and consistent with the range of $2 million to $11.1 million found in four meta-analyses summarized by Cropper, Hammitt and Robinson (Reference Cropper, Hammitt and Robinson2011).
Why does willingness to pay differ across respondents?
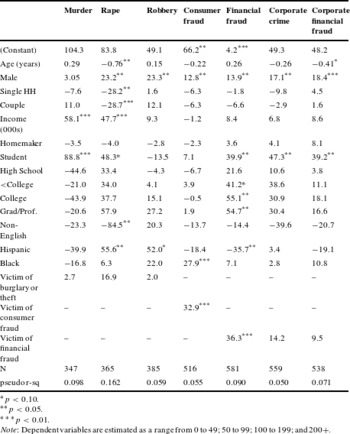
Previous literature suggests that individual WTP for reduced crime varies with income and perhaps by individual risk factors (Cohen et al., Reference Cohen, Rust, Steen and Tidd2004). Table 8 reports on a series of interval regressions where the dependent variable is the estimated WTP for each crime type in this study.Footnote 14 Similar to the findings in Cohen et al. (Reference Cohen, Rust, Steen and Tidd2004), WTP is generally higher with higher income, although this is only statistically significant for murder and rape – not any of the white-collar or corporate offenses. WTP is also generally declining with age. Somewhat surprising, males and respondents who are currently students (presumably in college, since the minimum respondent age is 18), generally had a higher WTP. Educational attainment only mattered in the case of financial frauds – with those having attained a college degree or graduate-level education willing to pay significantly more to reduce these offenses.
Demographic characteristics and WTP for reduced crime (Dependent variable: willingness to pay; interval regression).

*
 $p<0.10$
.
**
 $p<0.05$
.
***
 $p<0.01$
.
Note: Dependent variables are estimated as a range from 0 to 49; 50 to 99; 100 to 199; and 200
 $+$
.
A series of questions at the end of the survey asked respondents about their household’s victimization experience in the previous 12 months. Two questions asked about recent burglary or theft victimization. A dummy variable was included for these victimizations in the street crime regressions in Table 8; although none were significant. One question asked about nonfinancial consumer fraud victimization. Victims of consumer fraud reported an average WTP of $39.73 higher for consumer fraud reduction; thus victims are willing to pay more than double the average WTP overall for that crime (
 $p<0.05$
). Similarly, victims of financial frauds were willing to pay $39.12 more to reduce that crime (
 $p<0.05$
). Although not shown here, similar regressions were estimated using a combined victimization variable in each regression. While the results are similar, the magnitude of the significant coefficients was considerably higher when victimization was matched to the crime question. This suggests that prior victimization is highly salient in consumer WTP.
Reasons for “unwillingness” to pay
As noted earlier, respondents were given an opportunity to answer an open-ended question after each WTP scenario explaining their “yes” or “no” response. Reasons given by respondents for their unwillingness to pay the requested amount generally fell into several categories. The most common reason given was that the respondent had limited income and/or already paid enough taxes. A small percentage of respondents were unhappy with the 10% crime reduction, indicating that they would require a larger reduction before being willing to invest. Of course, this is another way of saying that the asking price was too high. In addition, a small percentage of respondents to the consumer and financial fraud questions were clearly focused on caveat emptor – oftentimes indicating that victims needed to take better care in avoiding the crime. Another similar response was that the individual already felt adequately protected because they buy identity theft insurance, or their banks and credit cards already limit their losses. Some respondents clearly displayed altruistic behavior. For example, one respondent who agreed to pay $100 but not $200 to reduce financial frauds explained, “the scams are somewhat avoidable – buyer beware – and I would pay something to help others avoid them but not over $100 – feel like if I am careful I can avoid these crimes.”
6. Concluding remarks
The main purpose of this study was to examine whether the public’s WTP to reduce white-collar and corporate crimes such as consumer fraud exceeds the economic losses associated with those crimes. Anecdotal evidence has demonstrated that economic crimes may have serious consequences to victims and society that far exceed any dollar losses, yet there is little systematic evidence to date about the magnitude of these losses or the public’s WTP to avoid them.
The most recent FTC survey finds that the median loss to victims of consumer fraud was $100 in 2011 (Anderson, Reference Anderson2013, Table 8), with the 75th percentile loss being $300. Yet, when converted to a “per crime” cost, the mean WTP for a reduction in an incidence of consumer fraud in this survey is $1200.
Although the sample of victims in the FTC study was too small to draw inferences about all financial frauds, the median losses for credit repair and pyramid schemes ranged from $200 to $250, with the 75th percentile loss being $500 for each type of crime (Anderson, Reference Anderson2013, Table 8). When converted to a “per crime” basis, the WTP in this survey was $12,000 for financial frauds (range $9500 to $14,000) – a figure that is close to the WTP for burglary, $19,000 (range $15,500 to $23,000).
The fact that the public is willing to pay significantly more than the typical cost to victims is consistent with the earlier findings on street crime (Cohen et al., Reference Cohen, Rust, Steen and Tidd2004, Table 4), where WTP was estimated to range between two and ten times monetary victim and criminal justice costs. It is also consistent with the one previous WTP study of identity theft (Piquero et al., Reference Piquero, Cohen and Piquero2010). From a policy perspective, these findings have important implications for regulators – especially in the realm of consumer and financial fraud. Without considering the full cost of these crimes, policies judged on a benefit-cost criterion will be underfunded.
While this study provides a first step in our understanding of the costs of white-collar and corporate crime, it only scratches the surface of our ultimate need for knowledge in this area. Among the most pressing needs is a better understanding of the components of WTP (e.g., whether respondents consider avoidance behavior or private expenditures when determining their WTP), how individual risk factors and preventive behavior might affect WTP, whether offender characteristics (e.g., corporate versus individual offenders) matter, and methodologically how framing of the survey questions might alter responses.
Acknowledgments
The author would like to thank participants of seminars at the University of Maryland, Vanderbilt University, and the 2014 Annual Conference of the Society for Benefit-Cost Analysis for several helpful comments and suggestions. Funding for this research is gratefully acknowledged from the Dean’s Fund for Summer Research at the Owen Graduate School of Management, Vanderbilt University.