


1. Introduction
The investment and reinsurance are important ways for insurers to manage risk. Insurers can purchase reinsurance contracts to reduce insurable risk and enhance profit by investing their wealth in the financial market simultaneously. This stimulates numerous literature focusing on optimal reinsurance–investment strategy problems. For example, Browne [Reference Browne9] aims to find an optimal investment strategy for an insurer by maximizing the expected utility of the terminal wealth. Schmidli [Reference Schmidli20] derives the optimal investment and reinsurance strategies in a diffusion setup by minimizing the probability of ruin. Yang and Zhang [Reference Yang and Zhang32] study the optimal investment policies for an insurer with a jump-diffusion risk process when the utility function is exponential. Jin et al. [Reference Jin, Yin and Wu16] study a stochastic reinsurance game between two insurers under a regime-switching jump-diffusion model.
Originally from Markowitz [Reference Markowitz18] who proposes the modern portfolio selection theory, the mean–variance criteria has attracted considerable attention. Bäuerle [Reference Bäuerle3] first points out that the mean–variance setup can also be of interest in insurance practices, and considers an optimal reinsurance problem under the benchmark and mean–variance criteria, where the surplus process is modeled by the classical Cramér–Lundberg model. Thereafter, due to the theoretical interest and practical importance, the investigation of the insurer's optimal investment and reinsurance strategies under mean–variance models has been widely studied. For example, Delong and Gerrard [Reference Delong and Gerrard10] consider some mean–variance problems that include a running cost penalizing the deviations of the insurer's wealth from a specified profit-solvency target. Bai and Zhang [Reference Bai and Zhang2] incorporate a viscosity solution to solve an optimal investment–reinsurance problem with constraints under the mean–variance criterion. Zeng et al. [Reference Zeng, Li and Liu35] obtain the closed-form expressions for the optimal investment policies under the benchmark and mean–variance criteria by stochastic maximum principle, when the surplus is modeled by a jump-diffusion process. Wang et al. [Reference Wang, Jin and Wei24] study a time-consistent mean–variance portfolio strategy under a non-Markovian regime-switching model. Further investigations on the modeling of reinsurance–investment problems in the presence of mean–variance criteria include Zeng and Li [Reference Zeng and Li34], Shen and Zeng [Reference Shen and Zeng21], and Yi et al. [Reference Yi, Viens, Li and Zeng33].
For mean–variance problems, it is apparent that the variance term is not a linear function of the expected value. This results in the lack of iterated-expectation property. Thus, the dynamic mean–variance problem does not have access to Bellman optimality principle in the multi-period and continuous-time settings. The problem becomes time-inconsistent and Hamilton–Jacobi–Bellman (HJB) equations cannot be applied directly. All papers mentioned above obtain a precommitted optimal strategy to overcome the time-inconsistency, which are only economically meaningful in certain circumstances.
To solve time-inconsistent problems, Strotz [Reference Strotz22] recognizes that time-inconsistent problems can be solved via time-consistent approaches. The original time-inconsistent problem is embedded within the framework of game theory, where a series of objected functions are formulated according to a progression of times and uses the equilibrium strategies to solve a family of optimization problems instead of the optimal strategies. Following the idea in Strotz [Reference Strotz22], Björk and Murgoci [Reference Björk and Murgoci5], and Björk et al. [Reference Björk, Khapko and Murgoci7] derive the extended standard HJB equations in the discrete-time and continuous-time settings to find the subgame perfect Nash equilibrium strategy and also prove the associated verification theorem, respectively. Since then, the extended HJB equations have been adopted in reinsurance–investment problems. Zeng and Li [Reference Zeng and Li34] investigate an optimal time-consistent investment–reinsurance problem by applying the extension of HJB equations. Li et al. [Reference Li, Zeng and Lai17] derive the time-consistent reinsurance–investment strategies under the Henston stochastic volatility model. Hernández and Possamaï [Reference Hernández and Possamaï12] extend the work of Björk et al. [Reference Björk, Khapko and Murgoci7] by redefining the closed-loop equilibrium strategies.
The aforementioned literature is devoted to deriving closed-loop equilibrium strategies. If we enlarge the opportunity set for the control, then we have another approach to study time-inconsistent problems, which is proposed by Hu et al. [Reference Hu, Jin and Zhou13]. Hu et al. [Reference Hu, Jin and Zhou13] introduce an explicit open-loop equilibrium strategy for the time-inconsistent stochastic linear-quadratic control problem with constant and state-dependent trade-off between mean and variance by applying a series of FBSDEs. Hu et al. [Reference Hu, Jin and Zhou15] continue to obtain the uniqueness of open-loop equilibrium controls for two special cases. From Ni et al. [Reference Ni, Li, Zhang and Krstic19], we observe that the existence of closed-loop equilibrium control implies the existence of open-loop equilibrium control. Hence, the class of closed-loop control is a subset of open-loop ones and the former one is often a special case of the latter. Open-loop control and closed-loop control are essentially different. Comparing with the closed-loop equilibrium strategy, it is easier to show that the open-loop equilibrium strategy is unique. Due to the advantage of open-loop approach, there also exits a number of literature that focus on the open-loop equilibrium strategies to solve time-inconsistent problems. Wei and Wang [Reference Wei and Wang28] extend the work of Hu et al. [Reference Hu, Jin and Zhou13] by considering a mean–variance asset-liability management problem under the random coefficients setting. Then, Wang et al. [Reference Wang, Wang and Wei25] study an open-loop equilibrium reinsurance–investment problem with the Vasicek stochastic interest rate model and the Heston stochastic volatility model. Yan and Wong [Reference Yan and Wong31] derive the explicit solutions of a open-loop equilibrium reinsurance–investment problem under the mean–variance criterion with stochastic volatility and also prove the uniqueness of equilibrium control pair. Alia [Reference Alia1] studies the open-loop equilibrium controls for a general class of time-inconsistent stochastic control problems under jump-diffusion SDEs with deterministic coefficients. For more related studies, we refer the readers to Hamaguchi [Reference Hamaguchi11], Yan and Wong [Reference Yan and Wong30], and Sun et al. [Reference Sun, Yuen and Guo23].
Besides, the literature listed above only consider the investment and reinsurance problem of a single insurer under the mean–variance criteria. However, the financial market is competitive and the insurer should consider the strategic interaction (competition or cooperation) with their competitors. Thus, it is natural to introduce game theory with reinsurance–investment problems to reflect the cooperation and competition among insurers. For example, Bensoussan et al. [Reference Bensoussan, Siu, Yam and Yang4] study a non-zero-sum stochastic differential investment and reinsurance problem between two insurance companies, where the relative performance of two insurers is modeled by the difference of their wealth surplus processes. Weng et al. [Reference Weng, Zhao, Shen and Zeng29] take into account the interests of both an insurer and a reinsurer jointly under the mean–variance criterion. Zhu et al. [Reference Zhu, Guan and Li37] derive the closed-form equilibrium strategies for a time-consistent non-zero-sum stochastic differential reinsurance and investment game under default and volatility risks by using extended HJB equations. Wang et al. [Reference Wang, Zhang, Jin and Qian26] investigate a reinsurance–investment game between two insurers under VaR constraints.
In our paper, we focus on the time-consistent non-zero-sum stochastic differential reinsurance and investment game between two insurers with a state-dependent mean expectation. We assume that both insurers can purchase reinsurance treaties to reduce insurance risk and invest their wealth in a financial market modeled with stochastic volatility. We also assume that the claim processes of two insurers are dependent, which are modeled by drifted Brownian motions. The objective for each insurer is to find the state-dependent trade-off between the expectation and variance of relative terminal performance, respectively. Following the method of Wang et al. [Reference Wang, Wang and Wei25], we use a series of FBSDEs to describe sufficient conditions for equilibrium strategies and show that the conditions are necessary conditions. By solving these equations, we obtain the open-loop equilibrium strategies and corresponding value functions for two insurers. Furthermore, we investigate the explicit solutions for the Hull–White stochastic volatility model and the non-leveraged Heston model.
The main contribution of this paper is that we are the first one to study the open-loop equilibrium strategies for two competing insurers under the mean–variance framework. Comparing with Zhu et al. [Reference Zhu, Guan and Li37] and Wang et al. [Reference Wang, Zhang, Jin and Qian27] who apply the extended HJB equations to derive the closed-form equilibrium strategies, we choose a series of FBSDEs to describe the conditions and prove that the strategies derived are indeed open-loop equilibrium strategies. The open-loop controls embrace feedback controls as special cases. We extend the work of Yan and Wong [Reference Yan and Wong31] in which only a single insurer is considered, to a non-zero-sum stochastic differential game by introducing the game theory to reflect the competition between two insurers. The relative performance of two insurers is modeled by the difference of their wealth surplus processes. This adds the difficulties of finding the sufficient and necessary conditions for equilibrium strategies. In addition, the state-dependent mean expectation is also considered in our paper. We consider a state-dependent mean–variance utility function, which is not studied in Zhu et al. [Reference Zhu, Guan and Li37] who only study the game problem between two insurers with constant risk aversion. The insurer's risk preference relies on how the relative wealth he has in the market in reality, which coincides with the economic investment wisdom in Björk et al. [Reference Björk, Murgoci and Zhou6]. Furthermore, our paper includes volatility risk and dependence between claim processes. These assumptions make our model more practical in the insurance and financial market.
The rest of paper is organized as follows. The formulation of asset and claim processes, and assumptions are presented in Section 2. Section 3 derives the sufficient and necessary conditions for the open-loop equilibrium strategies, and presents the equilibrium strategies and the corresponding value functions as well as the efficient frontiers. Section 4 illustrates the applications to the special cases: Hull–White model and Heston model. Numerical examples are conducted in Section 5. Section 6 concludes this paper.
2. Formulation
Let  $T>0$ be a finite time horizon and
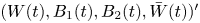 $(W(t),B_1(t),B_2(t),\bar {W}(t))^{\prime }$ be a four-dimensional standard Brownian motion defined on a probability space
 $(\Omega,\mathcal {F},\mathrm {F},\mathrm {P})$. Denote
 $\mathrm {F}=\{\mathcal {F}_{t}\}_{t\in [0,T]}$ to be an augmented filtration generated by Brownian motions. We assume that standard Brownian motions
 $W(t)$ and
 $\bar {W}(t)$ are correlated with coefficient of correlation
 $\rho _1$,
 $B_1(t)$ and
 $B_2(t)$ are correlated with coefficient of correlation
 $\rho _2$, and for
 $i=1,2$,
 $W(t)$ and
 $B_i(t)$ are independent. Throughout the paper, in a filtered complete probability, for
 $p\geq 1$, we define:
 \begin{align*} L_{\mathcal{F}_t}^{p}(\Omega;\mathrm{R})& =\{X:\Omega\rightarrow\mathrm{R}\,|\,X(t)\text{ is } \mathcal{F}_{t}\text{-measurable}, \mathrm{E}[|X^{p}|]<\infty\},\\ L_{\mathrm{F}}^{2}(s,t;\mathrm{R})& =\left\{X:[s,t]\times\Omega\rightarrow\mathrm{R}\,|\,X(t) \text{ is } \mathrm{F}\text{-adapted}, \vphantom{\left[\int_s^{t}|X(\nu)|^{2}\,d\nu\right]}\right.\\ & \qquad\left.\mathrm{E}\left[\int_s^{t}|X(\nu)|^{2}\,d\nu\right]<\infty\right\},\\ L_{\mathrm{F}}^{p}(\Omega;L^{2}(s,t;\mathrm{R}))& =\left\{X:[s,t]\times\Omega\rightarrow\mathrm{R}\,|\,X(t) \text{ is F-adapted},\vphantom{\left[\left(\int_s^{t}|X(\nu)|^{2}\,d\nu\right)^{p}\right]}\right.\\ & \qquad\left.\mathrm{E}\left[\left(\int_s^{t}|X(\nu)|^{2}\,d\nu\right)^{p}\right]<\infty\right\},\\ L_{\mathrm{F}}^{p}(\Omega;C([s,t];\mathrm{R}))& =\left\{X:[s,t]\times\Omega\rightarrow\mathrm{R}\,|\,X(t) \text{ is bounded F-adapted, }\vphantom{\left[\sup_{\nu\in[s,t]}|X(\nu)|^{p}\right]}\right.\\ & \qquad\left.\text{has continuous paths and } \mathrm{E}\left[\sup_{\nu\in[s,t]}|X(\nu)|^{p}\right]<\infty\right\}. \end{align*}
We use  $\mathrm {R}^{+}$ to denote the set of non-negative real numbers.
2.1. The surplus process
Let  $K_i(t)$ be the surplus of the insurer
 $i$ at time
 $t$, for
 $i=1,2$, the dynamics is given by
 \begin{equation} \left\{\begin{aligned} & dK_i(t)=l_i(t)\,dt-dL_i(t),\quad t\in[0,T],\\ & K_i(0)=k_{i0}>0, \end{aligned}\right. \end{equation}
where  $l_i(t)=(1+\eta _i(t))\alpha _i(t)$ is the premium rate received by the insurer with the safety loading
 $\eta _i(t)>0$. As in Wang et al. [Reference Wang, Wang and Wei25], we assume that the claim process
 $L_i(t)$ for insurer
 $i$,
 $i=1,2$, is generated by
 \begin{equation} dL_i(t)=\alpha_i(t)\,dt-\beta_i(t)\,dW(t)-c_i(t)\,dB_i(t), \end{equation}
where  $\alpha _i(t)$,
 $\beta _i(t)$,
 $c_i(t)$ are positive, bounded, and continuous
 $\mathrm {F}\text {-adapted processes}$.
We suppose that insurers are allowed to purchase the proportional reinsurance contracts  $p_i(t)$ to control insurable risks, for
 $i=1,2$. For any claim occurring at time
 $t$, the insurer
 $i$ pays
 $100(1-p_i(t))\%$ while the reinsurance company covers the rest. Furthermore, the insurer pays the reinsurance premium to the reinsurer continuously at rate
 $c_{0i}(t)=[1+\eta _{0i}(t)]\alpha _i(t)p_i(t)$, where
 $\eta _{0i}(t)\geq \eta _i(t)$ is the reinsurance safety loading. For simplicity, we only consider the
 $\eta _{0i}(t)=\eta _i(t)$, which is easy to extend the case
 $\eta _{0i}(t)>\eta _i(t)$.
Taking into account the reinsurance strategy, the surplus process  $K_i(t)$ of the insurer
 $i$, for
 $i=1,2,$ becomes
 \begin{equation} \left\{\begin{array}{l} dK_i(t)=[1-p_i(t)]\eta_i(t)\alpha_i(t)\,dt+[1-p_i(t)][\beta_i(t)\,dW(t)+c_i(t)\,dB_i(t)],\quad t\in[0,T],\\ K_i(0)=k_{i0}>0. \end{array}\right. \end{equation}
Insurers are also allowed to invest in the risky asset to enhance profits. We consider an incomplete financial market consisting of a risk-free asset and a risky asset within the time horizon  $[0,T]$. The risk-free asset
 $A(t)$ evolves as
 \begin{equation} \left\{\begin{array}{l} dA(t)=r(t)A(t)\,dt, \quad t\in[0,T],\\ A(0)=a_{0}>0, \end{array}\right. \end{equation}
where the interest rate  $r(t)>0$ is a bounded deterministic function. The price of the risky asset
 $S(t)$ with a stochastic volatility process
 $V(t)$ on a complete probability space is generated by
 \begin{equation} \left\{\begin{array}{l} dS(t)=\mu(t,S(t),V(t))\,dt+\sigma(t,S(t),V(t))\,dW(t), \quad t\in[0,T],\\ S(0)=s_{0}>0,\\ dV(t)=b_1(t,V(t))\,dt+b_2(t,V(t))\,d\bar{W}(t),\\ V(0)=v_{0}>0, \end{array}\right. \end{equation}
where the expected return rate process  $\mu$ and the corresponding volatility process
 $\sigma$ are unbounded functions of
 $t, S(t)$, and
 $V(t)$. The volatility process parameters
 $b_1$ and
 $b_2$ are the functions of
 $t$ and
 $V(t)$. We assume that throughout the paper
 $\mu (t,S(t),V(t))>r(t)$. In general,
 $\mu (t,S(t),V(t))$ and
 $\sigma (t,S(t),V(t))$ can be non-Markovian and unbounded. The standard Brownian motion
 $W(t)$ and
 $\bar {W}(t)$ are correlated with coefficient of correlation
 $\rho _1$.
Let  $\pi (t)$ be the dollar amount invested in the risky asset and
 $R(t)$ be the wealth asset in the financial market. The dynamics of the wealth process is given by
 \begin{equation} \left\{\begin{array}{l} dR(t)=[r(t)R(t)+\theta(t)u(t)]\,dt+{u}(t)\,dW(t), \quad t\in[0,T],\\ R(0)=r_0, \end{array}\right. \end{equation}
where the risk premium  $\theta (t)={[\mu (t,S(t),V(t))-r(t)S(t)]}/{\sigma (t,S(t),V(t))}$ and
 $u(t)=\pi (t)\sigma (t,S(t),V(t))S(t)^{-1}$.
Combining the investment and reinsurance strategies, for the insurer  $i$,
 $i=1,2$, the dynamics of the surplus process
 $X_i(t)$ is modeled by
 \begin{equation} \left\{\begin{aligned} dX_i(t) & =[r(t)X_i(t)+[1-p_i(t)]\eta_i(t)\alpha_i(t)+\theta(t)u_i(t)]\,dt\\ & \quad+\{u_i(t)+[1-p_i(t)]\beta_i(t)\}\,dW(t)\\ & \quad+[1-p_i(t)]c_i(t)\,dB_i(t), \quad t\in[0,T],\\ X_i(0) & =x_{i0}. \end{aligned}\right. \end{equation}
Reasonably, we assume the independence between the insurance market and financial market, thus  $B_i(t)$ is independent of
 $W(t)$ and
 $\bar {W}(t)$.
2.2. A two-player non-zero-sum game problem
In our work, we construct a non-zero-sum game problem between two insurers, where the relative performance of two insurers is modeled by the difference of their wealth surplus processes  $(1-w_i)X_i(t)+w_i(X_i(t)-X_j(t))$, where
 $i, j\in \{1,2\},i\neq j$, and
 $1-w_i$,
 $w_i$ are the weights of absolute wealth and relative wealth. The competition between two insurers formulates a game with two players.
 $w_i$ captures the degree of dependence on the terminal wealth of competitor of insurer
 $i$. Each insurer can choose reinsurance and investment strategies based on his competitor's choice. A larger
 $w_i$ means that the insurer is more concerned about the relative performance of his competitor.
Problem 2.1. For any initial state  $(t,X_i(t)-w_iX_j(t))$,
 $i,j\in \{1,2\},\ i\neq j$, we assume that the insurer is guided by the mean–variance criteria over terminal wealth
 $X_i(T)-w_iX_j(T)$. The objective for each insurer is to find equilibrium reinsurance–investment strategies to balance the expectation and variance of terminal wealth, namely, to minimize
 \begin{align*} J_1(t,x_1,x_2;u_1,p_1)& ={-}\lambda_1(x_1-w_1x_2)\,\mathrm{E}_t[X_1(T)-w_1X_2(T)]\\ & \quad+\tfrac{1}{2}\,\mathrm{Var}_t[X_1(T)-w_1X_2(T)],\quad t\in[0,T],\\ J_2(t,x_1,x_2;u_2,p_2)& ={-}\lambda_2(x_2-w_2x_1)\,\mathrm{E}_t[X_2(T)-w_2X_1(T)]\\ & \quad+\tfrac{1}{2}\,\mathrm{Var}_t[X_2(T)-w_2X_1(T)],\quad t\in[0,T], \end{align*}
where for  $i=1,2$,
 $X_i(t)=x_i$ at time
 $t$,
 $\lambda _i > 0$ is a constant and mean expectation is state-dependent.
 $\mathrm {E}_t[\cdot ]$ and
 $\mathrm {Var}_t[\cdot ]$ are the conditional expectation and variance under probability measure
 $\mathrm {P}$, respectively.
We aim to investigate equilibrium reinsurance strategies  $\bar {u}_i(t)$ and investment polices
 $\bar {p}_i(t)$ such that
 \begin{align*} & J_1(t,x_1,x_2;\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t))\leq J_1(t,x_1,x_2;u_1(t),p_1(t),\bar{u}_2(t),\bar{p}_2(t))\\ & J_2(t,x_1,x_2;\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t))\leq J_2(t,x_1,x_2;\bar{u}_1(t),\bar{p}_1(t),u_2(t),p_2(t)). \end{align*}
In next section, we present the existence of equilibrium strategies for this non-zero-sum stochastic differential game problem.
3. Equilibrium strategies
3.1. Sufficient conditions for the open-loop equilibrium strategies
Problem 2.1 is a time-inconsistent problem due to the existence of the variance term. We cannot have access to the iterated expectations which means that it does not follow the Bellman optimality principle and we cannot use HJB equations to derive the optimal investment and reinsurance strategies directly. Instead, we try to find the equilibrium strategies to solve this time-inconsistent problem. Inspired by Hu et al. [Reference Hu, Jin and Zhou13], we adopt the tool of BSDEs to investigate the open-loop equilibrium strategies.
Given a control pair  $\bar {u}_i(t)\in L_{\mathrm {F}}^{2}(0,T;\mathrm {R})$ and
 $\bar {p}_i(t)\in L_{\mathrm {F}}^{2}(0,T;\mathrm {R}^{+})$,
 $i=1,2$, for any
 $t\in [0,T]$,
 $\nu _{1i}\in L_{\mathrm {F}}^{2}(0,T;\mathrm {R})$ and
 $\nu _{2i}\in L_{\mathrm {F}}^{2}(0,T;\mathrm {R}^{+})$, perturb strategies are defined as follows:
 \begin{align} u_1^{t,\varepsilon,\nu_{11}}(s)& =\bar{u}_1(s)+\nu_{11}I_{[t,t+\varepsilon]}(s), \quad s\in[t,T], \end{align}
 \begin{align} u_2^{t,\varepsilon,\nu_{12}}(s)& =\bar{u}_2(s)+\nu_{12}I_{[t,t+\varepsilon]}(s), \quad s\in[t,T], \end{align}
 \begin{align} p_1^{t,\varepsilon,\nu_{21}}(s)& =\bar{p}_1(s)I_{[t+\varepsilon,T]}(s)+\nu_{21}I_{[t,t+\varepsilon]}(s), \quad s\in[t,T], \end{align}
 \begin{align} p_2^{t,\varepsilon,\nu_{22}}(s)& =\bar{p}_1(s)I_{[t+\varepsilon,T]}(s)+\nu_{22}I_{[t,t+\varepsilon]}(s), \quad s\in[t,T], \end{align}
where  $\varepsilon >0$ and
 $I_{[\cdot ]}$ is the indicator function. We employ the notation of
 $u_1^{t,\varepsilon,\nu _{11}}(s)$ and
 $u_2^{t,\varepsilon,\nu _{12}}(s)$ of Hu et al. [Reference Hu, Jin and Zhou13]. As the reinsurance proportion
 $p_1(t)$ and
 $p_2(t)$ are non-negative, the perturb strategies
 $p_1^{t,\varepsilon,\nu _{21}}(s)$ and
 $p_2^{t,\varepsilon,\nu _{22}}(s)$ follow the one proposed by Hu et al. [Reference Hu, Huang and Li14]. Thus, we have the following definition of the open-loop equilibrium strategies.
Definition 3.1. For  $i=1,2$, let
 $(\bar {u}_i(t), \bar {p}_i(t)) \in L_{\mathrm {F}}^{2}(0,T;\mathrm {R})\times L_{\mathrm {F}}^{2}(0,T;\mathrm {R}^{+})$ be a given strategy pair and
 $\bar {x}_i(t)$ be the corresponding state process. For any
 $t\in [0,T], \varepsilon >0$, the controls
 $\bar {u}_i(t)$ and
 $\bar {p}_i(t)$ are called equilibrium strategies if
 $$\liminf_{\varepsilon\downarrow 0}\frac{J_1(t,\bar{x}_1,\bar{x}_2;u_1^{t,\varepsilon,\nu_{11}}(t),p_1^{t,\varepsilon,\nu_{21}(t)},\bar{u}_2(t),\bar{p}_2(t))-J_1(t,\bar{x}_1,\bar{x}_2;\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t))}{\varepsilon}\geq 0,$$
and
 $$\liminf_{\varepsilon\downarrow 0}\frac{J_2(t,\bar{x}_1,\bar{x}_2;\bar{u}_1(t),\bar{p}_1(t),u_2^{t,\varepsilon,\nu_{12}}(t),p_2^{t,\varepsilon,\nu_{22}}(t))-J_2(t,\bar{x}_1,\bar{x}_2;\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t))}{\varepsilon}\geq 0,$$
where  $u_1^{t,\varepsilon,\nu _{11}}(t)$,
 $p_1^{t,\varepsilon,\nu _{21}}(t)$,
 $u_2^{t,\varepsilon,\nu _{12}}(t)$,
 $p_2^{t,\varepsilon,\nu _{22}}(t)$ are perturb strategies defined by (3.1), (3.3), (3.2), and (3.4). The corresponding value functions for two insurers are given by
 \begin{align} & J_1(t,\bar{x}_1,\bar{x}_2)= J_1(t,\bar{x}_1,\bar{x}_2;\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t)), \end{align}
 \begin{align} & J_2(t,\bar{x}_1,\bar{x}_2)=J_2(t,\bar{x}_1,\bar{x}_2;\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t)). \end{align}
In the remaining of this section, we derive time-consistent, open-loop equilibrium reinsurance–investment strategies in the sense of Definition 3.1. Firstly, we offer equivalent conditions for the open-loop equilibrium strategies.
Theorem 3.2. For  $i=1, 2$,
 $\bar {u}_i(t)\in L_{\mathrm {F}}^{2}(0,T;\mathrm {R})$ and
 $\bar {p}_i(t)\in L_{\mathrm {F}}^{2}(0,T;\mathrm {R}^{+})$ are open-loop equilibrium strategies if for any
 $t\in [0,T]$, there exist processes
 $Y_i(s;t)$,
 $Z_i(s;t)$,
 $\bar {Z}_i(s;t)$,
 $U_i(s;t)$, and
 $M_i(s;t)$ that solve the following FBSDEs
 \begin{equation} \left\{\begin{aligned} d\bar{D}_1(s) & =\{r(s)\bar{D}_1(s)+[1-\bar{p}_1(s)]\eta_1(s)\alpha_1(s)\\ & \quad -w_1[1-\bar{p}_2(s)]\eta_2(s)\alpha_2(s)+\theta(s)\bar{u}_1(s)-w_1\theta(s)\bar{u}_2(s)\}\,ds\\ & \quad +\{\bar{u}_1(s)-w_1\bar{u}_2(s)+[1-\bar{p}_1(s)]\beta_1(s)-w_1[1-\bar{p}_2(s)]\beta_2(s)\}\,dW(s)\\ & \quad +[1-\bar{p}_1(s)]c_1(s)\,dB_1(s)-w_1[1-\bar{p}_2(s)]c_2(s)\,dB_2(s),\quad s\in[0,T],\\ \bar{D}_1(0) & =\bar{x}_{10}-w_1\bar{x}_{20},\\ dY_1(s;t) & ={-}r(s)Y_1(s;t)\,ds+Z_1(s;t)\,dW(s)+\bar{Z}_1(s;t)\,d\bar{W}(s)+U_1(s;t)\,dB_1(s)\\ & \quad +M_1(s;t)\,dB_2(s), \quad s\in[t,T],\\ Y_1(T;t) & =\bar{D_1}(T)-\mathrm{E}_t[\bar{D}_1(T)]-\lambda_1 \bar{D}_1(t), \end{aligned}\right. \end{equation}
and
 \begin{equation} \left\{\begin{aligned} d\bar{D}_2(s) & =\{r(s)\bar{D}_2(s)+[1-\bar{p}_2(s)]\eta_2(s)\alpha_2(s)\\ & \quad-w_2[1-\bar{p}_1(s)]\eta_1(s)\alpha_1(s)+\theta(s)\bar{u}_2(s)-w_2\theta(s)\bar{u}_1(s)\}\,ds\\ & \quad +\{\bar{u}_2(s)-w_2\bar{u}_1(s)+[1-\bar{p}_2(s)]\beta_2(s)-w_2[1-\bar{p}_1(s)]\beta_1(s)\}\,dW(s)\\ & \quad +[1-\bar{p}_2(s)]c_2(s)\,dB_2(s)-w_2[1-\bar{p}_1(s)]c_2(s)\,dB_1(s),\qquad s\in[0,T],\\ \bar{D}_2(0) & =\bar{x}_{20}-w_2\bar{x}_{10},\\ dY_2(s;t) & ={-}r(s)Y_2(s;t)\,ds+Z_2(s;t)\,dW(s)+\bar{Z}_2(s;t)\,d\bar{W}(s)+U_2(s;t)\,dB_1(s)\\ & \quad +M_2(s;t)\,dB_2(s), \quad s\in[t,T],\\ Y_2(T;t) & =\bar{D_2}(T)-\mathrm{E}_t[\bar{D}_2(T)]-\lambda_2 \bar{D}_2(t), \end{aligned}\right. \end{equation}
where  $\bar {D}_1(s)=\bar {X}_1(s)-w_1\bar {X}_2(s)$ and
 $\bar {D}_2(s)=\bar {X}_2(s)-w_2\bar {X}_1(s)$ are relative performance for two insurers corresponding with equilibrium strategies
 $(\bar {u}_1(t), \bar {p}_1(t))$ and
 $(\bar {u}_2(t), \bar {p}_2(t))$, respectively. The conditions for the open-loop equilibrium strategies are
 \begin{align} \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\left[\int_t^{t+\varepsilon}\Lambda_{11}(s;t)\,ds\right]=0,\quad \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\left[\int_t^{t+\varepsilon}\Lambda_{21}(s;t)\,ds\right]\geq 0,\quad {\rm a.s.}, \end{align}
 \begin{align} \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\left[\int_t^{t+\varepsilon}\Lambda_{12}(s;t)\,ds\right]=0,\quad \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\left[\int_t^{t+\varepsilon}\Lambda_{22}(s;t)\,ds\right]\geq 0,\quad {\rm a.s.}, \end{align}
where
 \begin{equation} \begin{aligned} \Lambda_{11}(s;t) & =Y_1(s;t)\theta(s)+\rho_1 \bar{Z}_1(s;t)+Z_1(s;t),\quad s\in[t,T],\\ \Lambda_{21}(s;t) & =Y_1(s;t)\eta_1(s)\alpha_1(s)+\beta_1(s)[Z_1(s;t)+\rho_1 \bar{Z}_1(s;t)]\\ & \quad +c_1(s)U_1(s;t)+\rho_2c_1(s)M_1(s;t), \quad s\in[t,T], \end{aligned}\end{equation}
 \begin{equation} \begin{aligned} \Lambda_{12}(s;t) & =Y_2(s;t)\theta(s)+\rho_1 \bar{Z}_2(s;t)+Z_2(s;t),\quad s\in[t,T],\\ \Lambda_{22}(s;t) & =Y_2(s;t)\eta_2(s)\alpha_2(s)+\beta_2(s)[Z_2(s;t)+\rho_1 \bar{Z}_2(s;t)]\\ & \quad +c_2(s)M_2(s;t)+\rho_2c_2(s)U_2(s;t), \quad s\in[t,T]. \end{aligned} \end{equation}
Proof. Here, it suffices to provide sufficient conditions for the first insurer's equilibrium strategies, since conditions for the second insurer's equilibrium strategies can be obtained by following the same argument.
Given  $u_1^{t,\varepsilon,\nu _{11}}(t)$ and
 $p_1^{t,\varepsilon,\nu _{21}}(t)$ in (3.1) and (3.3), we denote
 $\bar {D}_1(t)$ and
 $D_1^{t,\varepsilon,\nu }(t)$ to be the state processes associated with equilibrium strategies
 $\bar {u}_1(t)$,
 $\bar {p}_1(t)$ and perturb strategies
 $u_1^{t,\varepsilon,\nu _{11}}(t)$,
 $p_1^{t,\varepsilon,\nu _{21}}(t)$ for fixed
 $\bar {u}_2(t)$,
 $\bar {p}_2(t)$, respectively. Define
 $F_1^{t,\varepsilon,\nu }(t)=D_1^{t,\varepsilon,\nu }(t)-\bar {D}_1(t)$, we have
 \begin{equation} \left\{\begin{aligned} dF_1^{t,\varepsilon,\nu}(s) & =\{r(s)F_1^{t,\varepsilon,\nu}(s)+\{\eta_1(s)\alpha_1(s)[\bar{p}_1(s)-\nu_{21}(s)]+\theta(s)\nu_{11}(s) \}I_{[t,t+\varepsilon]}(s)\}\,ds\\ & \quad +\{\nu_{11}(s)+\beta_1(s)[\bar{p}_1(s)-\nu_{21}(s)]\}I_{[t,t+\varepsilon]}(s)\,dW(s)\\ & \quad +\{c_1(s)[\bar{p}_1(s)-\nu_{21}(s)]\}I_{[t,t+\varepsilon]}(s)\,dB_1(s), \quad s\in[t,T],\\ F_1^{t,\varepsilon,\nu}(t) & =0, \end{aligned}\right. \end{equation}
and  $F_1^{t,\varepsilon,\nu }(t)\in L_{\mathrm {F}}^{2}(\Omega ;C([t,T];\mathrm {R}))$. It is easy to obtain the difference of value function associated with perturb strategies and equilibrium strategies
 \begin{align*} & J_1(t,\bar{D}_1(t);u_1^{t,\varepsilon,\nu_{11}}(t),p_1^{t,\varepsilon,\nu_{21}}(t),\bar{u}_2(t),\bar{p}_2(t)) -J_1(t,\bar{D}_1(t);\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t))\\ & \quad =J_{11}(t)+J_{12}(t), \end{align*}
where
 \begin{align} & J_{11}(t)= \tfrac{1}{2}\mathrm{E}_t[(F_1^{t,\varepsilon,\nu}(T)- \mathrm{E}_t[F_1^{t,\varepsilon,\nu}(T)])F_1^{t,\varepsilon,\nu}(T)], \end{align}
 \begin{align} & J_{12}(t)= \mathrm{E}_t[(\bar{D}_1(T)-\mathrm{E}_t[\bar{D}_1(T)]-\lambda_1 \bar{D}_1(t))F_1^{t,\varepsilon,\nu}(T)]. \end{align}
Obviously,
 \begin{align*} J_{11}(t)& =\tfrac{1}{2}[\mathrm{E}_t[(F_1^{t,\varepsilon,\nu}(T))^{2}]- (\mathrm{E}_t[F_1^{t,\varepsilon,\nu}(T)])^{2}]\\ & =\tfrac{1}{2}\mathrm{Var}_t[F_1^{t,\varepsilon,\nu}(T)]\geq 0. \end{align*}
To prove the conditions are equivalent, we only need to verify that  $J_{12}(t)>0$ is satisfied. The pair
 $(Y_1(s;t),Z_1(s;t),\bar {Z}_1(s;t),U_1(s;t),M_1(s;t))$ solves the backward equation in (3.7). Applying Itô's formula, we have
 \begin{align*} d(Y_1(s;t)F_1^{t,\varepsilon,\nu}(s))& = \{Y_1(s;t)\{\eta_1(s)\alpha_1(s)[\bar{p}_1(s)-\nu_{21}(s)]+\theta(s)\nu_{11}(s)\}\\ & \quad +[\rho_1 \bar{Z}_1(s;t)+Z_1(s;t)]\{\nu_{11}(s)+\beta_1(s)[\bar{p}_1(s)-\nu_{21}(s)]\}\\ & \quad+\{[\rho_2c_1(s)M_1(s;t)+U_1(s;t)c_1(s)][\bar{p}_1(s)-\nu_{21}(s)]\}\}I_{[t,t+\varepsilon]}(s)\,ds\\ & \quad+ \{Y_1(s;t)\{\nu_{11}(s)+\beta_1(s)[\bar{p}_1(s)-\nu_{21}(s)]\}I_{[t,t+\varepsilon]}(s) +Z_1(s;t)F_1^{t,\varepsilon,\nu}(s)\}\,dW(s)\\ & \quad+\{Y(s;t)c_1(s)[\bar{p}_1(s)-\nu_{21}(s)]\}I_{[t,t+\varepsilon]}(s) +U_1(s;t)F_1^{t,\varepsilon,\nu}(s)\}\,dB_1(s)\\ & \quad+\bar{Z}_1(s;t)F_1^{t,\varepsilon,\nu}\,d\bar{W}(s)+M_1(s;t)F_1^{t,\varepsilon,\nu}\,dB_2(s). \end{align*}
By the integrability of  $Y_1(s;t)$,
 $Z_1(s;t)$,
 $\bar {Z}_1(s;t)$,
 $U_1(s;t)$, and
 $M_1(s;t)$, we have
 \begin{align*} & \mathrm{E}_t[(\bar{D}_1(T)-\mathrm{E}_t[\bar{D}_1(T)]-\lambda_1 \bar{D}_1(t))F_1^{t,\varepsilon,\nu}(T)] \\ & \quad=\mathrm{E}_t\int_t^{T}\{\Lambda_{11}(s;t)\nu_{11}(s)+\Lambda_{21}(s;t) [\bar{p}_1(s)-\nu_{21}(s)]\}I_{[t,t+\varepsilon]}(s)\,ds, \end{align*}
and
 \begin{align*} & \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon} [J_1(t,\bar{D}_1(t);u_1^{t,\varepsilon,\nu_{11}}(t),p_1^{t,\varepsilon,\nu_{21}}(t), \bar{u}_2(t),\bar{p}_2(t))-J_1(t,\bar{D}_1(t);\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t))]\\ & \quad \geq\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t \int_t^{T}\{\Lambda_{11}(s;t)\nu_{11}(s)+\Lambda_{21}(s;t)[\bar{p}_1(s)-\nu_{21}(s)]\} I_{[t,t+\varepsilon]}(s)\,ds. \end{align*}
By the condition specified in (3.9), we can see that
 \begin{equation} \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t \int_t^{t+\varepsilon}\{\Lambda_{11}(s;t)\nu_{11}(s)+\Lambda_{21}(s;t) [\bar{p}_1(s)-\nu_{21}(s)]\}\,ds\geq 0. \end{equation}
Then, we have
 $$\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon} [J_1(t,\bar{D}_1(t);u_1^{t,\varepsilon,\nu_{11}}(t),p_1^{t,\varepsilon,\nu_{21}}(t),\bar{u}_2(t),\bar{p}_2(t))- J_1(t,\bar{D}_1(t);\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t))]\geq 0,$$
which implies conditions are equivalent.
For insurer 2, given  $u_2^{t,\varepsilon,\nu _{12}}(t)$ and
 $p_2^{t,\varepsilon,\nu _{22}}(t)$ in (3.2) and (3.4), we define
 $F_2^{t,\varepsilon,\nu }(t)=D_2^{t,\varepsilon,\nu }(t)-\bar {D}_2(t)$. Denote
 $\bar {D}_2(t)$ and
 $D_2^{t,\varepsilon,\nu }(t)$ to be the state processes associated with controls
 $\bar {u}_2(t)$,
 $\bar {p}_2(t)$ and perturb strategies
 $u_2^{t,\varepsilon,\nu _{12}}(t)$,
 $p_2^{t,\varepsilon,\nu _{22}}(t)$ for fixed
 $\bar {u}_1(t)$,
 $\bar {p}_1(t)$, respectively.
 \begin{equation} \left\{\begin{aligned} dF_2^{t,\varepsilon,\nu}(s) & =\{r(s)F_2^{t,\varepsilon,\nu}(s)+\{\eta_2(s)\alpha_2(s)[\bar{p}_2(s)-\nu_{22}(s)]+\theta(s)\nu_{12}(s) \}I_{[t,t+\varepsilon]}(s)\}\,ds\\ & \quad +\{\nu_{12}(s)+\beta_2(s)[\bar{p}_2(s)-\nu_{22}(s)]\}I_{[t,t+\varepsilon]}(s)\,dW(s)\\ & \quad +\{c_2(s)[\bar{p}_2(s)-\nu_{22}(s)]\}I_{[t,t+\varepsilon]}(s)\,dB_2(s), \quad s\in[t,T],\\ F_2^{t,\varepsilon,\nu}(t) & =0, \end{aligned}\right. \end{equation}
and  $F_2^{t,\varepsilon,\nu }(t)\in L_{\mathrm {F}}^{2}(\Omega ;C([t,T];\mathrm {R}))$. By using the same argument, we can get that
 $$\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon} [J_2(t,\bar{D}_2(t);\bar{u}_1(t),\bar{p}_1(t),u_2^{t,\varepsilon,\nu_{12}}(t),p_2^{t,\varepsilon,\nu_{22}}(t))- J_2(t,\bar{D}_2(t);\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t))]\geq 0.$$
The proof is completed.
Remark 3.3. It is not straight to construct the open-loop equilibrium strategies through conditions which involve a limit. For any  $t_1, t_2\in [0,T]$, the solutions to the backward equations in (3.7) and (3.10) satisfy
 $Y_i(s; t_1)=Y_i(s; t_2), Z_i(s; t_1)=Z_i(s; t_2),\bar {Z}_i(s; t_1)=\bar {Z}_i(s; t_2), U_i(s; t_1)=U_i(s; t_2), M_i(s; t_1)=M_i(s; t_2)$,
 $i=1,2,$ for a.e.
 $s\geq \max(t_1, t_2)$. Therefore, inspired by Wei and Wang [Reference Wei and Wang28] and Yan and Wong [Reference Yan and Wong30], in the following part of the paper, we use a stronger version
 \begin{equation} \Lambda_{11}(t;t)=0;\quad\Lambda_{21}(t;t)\geq 0;\quad\Lambda_{12}(t;t)=0;\quad \Lambda_{22}(t;t)\geq 0. \end{equation}
Hence,
 \begin{equation} \begin{aligned} 0 & =\Lambda_{11}(t;t)=Y_1(t;t)\theta(t)+\rho_1 \bar{Z}_1(t;t)+Z_1(t;t),\\ 0 & \leq\Lambda_{21}(t;t)=Y_1(t;t)\eta_1(t)\alpha_1(t)+\beta_1(t)[Z_1(t;t)+\rho_1 \bar{Z}_1(t;t)]\\ & \quad +c_1(t)U_1(t;t)+\rho_2c_1(t)M_1(t;t), \end{aligned} \end{equation}
 \begin{equation} \begin{aligned} 0 & =\Lambda_{12}(t;t)=Y_2(t;t)\theta(t)+\rho_1 \bar{Z}_2(t;t)+Z_2(t;t),\\ 0 & \leq\Lambda_{22}(t;t)=Y_2(t;t)\eta_2(t)\alpha_2(t)+\beta_2(t)[Z_2(t;t)+\rho_1 \bar{Z}_2(t;t)]\\ & \quad +c_2(t)M_2(t;t)+\rho_2c_2(t)U_2(t;t). \end{aligned} \end{equation}
3.2. The existence of the open-loop equilibrium strategies
In this subsection, we construct open-loop equilibrium reinsurance–investment strategies  $\bar {u}_1(t)$,
 $\bar {p}_1(t)$,
 $\bar {u}_2(t)$, and
 $\bar {p}_2(t)$ for two insurers. To solve FBSDEs (3.7) and (3.8) subject to the conditions (3.19) and (3.20), respectively, we introduce BSDEs to find solutions. We suppose that
 $Y_1(s;t)$ and
 $Y_2(s;t)$ can be expressed as
 $$Y_1(s;t)=P_1(s)\bar{X}_1(s)-\mathrm{E}_t[P_1(s)\bar{X}_1(s)] -w_1\{P_2(s)\bar{X}_2(s)-\mathrm{E}_2[P_1(s)\bar{X}_2(s)]\}-\lambda_1P_0\bar{D}_1(t),$$
and
 $$Y_2(s;t)=P_2(s)\bar{X}_2(s)-\mathrm{E}_t[P_2(s)\bar{X}_2(s)] -w_2\{P_1(s)\bar{X}_1(s)-\mathrm{E}_t[P_2(s)\bar{X}_1(s)]\}-\lambda_2 P_0\bar{D}_2(t),$$
where  $P_0=\exp \{\int _t^{T}r(s)\,ds\}$, for
 $s\in [t,T]$. For
 $i=1,2$,
 $(P_i(t),Q_i(t), \bar {Q}_i(t), N_i(t), G_i(t))\in L_{\mathrm {F}}^{p}(\Omega ;C([0,T];\mathrm {R}))\times L_{\mathrm {F}}^{p}(\Omega ;L^{2}(0,T;\mathrm {R}^{4}))$ are the solutions to the following BSDEs:
 \begin{equation} \left\{\begin{aligned} dP_i(s) & ={-}f_i(s,P_i(s),Q_i(s),\bar{Q}_i(s),N_i(s),G_i(s))\,ds+Q_i(s)\,dW(s)\\ & \quad +\bar{Q}_id\bar{W}(s)+N_i(s)\,dB_1(s)+G_i(s)\,dB_2(s),\quad s\in[0,T],\\ P_i(T) & =1, \end{aligned}\right. \end{equation}
where the expressions of  $f_1(s,P_1,Q_1,\bar {Q}_1,N_1,G_1)$ and
 $f_2(s,P_2,Q_2,\bar {Q}_2,N_2,G_2)$ are shown as (suppressing the variable
 $s$)
 \begin{align*} f_1(s,P_1,Q_1,\bar{Q}_1,N_1,G_1)& =2P_1r-Q_1\theta+\lambda_1P_0\theta^{2} -\rho_1\bar{Q}_1\theta+(\rho_1\bar{Q}_1+Q_1)(\lambda_2P_0\theta-\rho_1\bar{Q}_1-Q_1\\ & \quad-w_1w_2\lambda_2P_0\theta+w_1w_2\rho_1\bar{Q}_1+w_1w_2Q_1)-w_1(\rho_1\bar{Q}_2+Q_2) (w_2\lambda_1P_0\theta\\ & \quad-w_2\rho_1\bar{Q}_1-w_2Q_1-w_2\lambda_2P_0\theta+w_1\rho_1\bar{Q}_1+w_1Q_1)\\ & \quad+\frac{[(\rho_2G_1+N_1)c_1+P_1(\eta_1\alpha_1-\beta_1)]}{P_1c_1^{2}(1-w_1w_2\rho_2^{2})} \left\{\lambda_1P_0\eta_1\alpha_1- \lambda_1P_0\beta_1-c_1N_1\vphantom{\frac{\rho_2c_1w_1}{c_2}}\right.\\ & \quad -\rho_2c_1G_1+\frac{\rho_2c_1w_1}{c_2}[-\lambda_2P_0w_2\eta_2\alpha_2+\lambda_2w_2\beta_2P_0+w_2c_2G_1\\ & \quad\left.+w_2\rho_2c_2N_1]\vphantom{\frac{\rho_2c_1w_1}{c_2}}\right\}- \frac{w_1[(\rho_2N_2+G_2)c_2+P_2(\eta_2\alpha_2-\beta_2)]}{P_2c_2^{2}(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_2w_2}{c_1}\right.\\ & \quad[\lambda_1P_0\eta_1\alpha_1- \lambda_1P_0\beta_1-c_1N_1-\rho_2c_1G_1]-\lambda_2P_0w_2\eta_2\alpha_2\\ & \left.\quad+\lambda_2w_2P_0\beta_2+w_2c_2G_1+w_2\rho_2c_2N_1\vphantom{\frac{\rho_2c_2w_2}{c_1}}\right\}, \end{align*}
 \begin{align*} f_2(s,P_2,Q_2,\bar{Q}_2,N_2,G_2)& =2P_2r-Q_2\theta+\lambda_1P_0\theta^{2} -\rho_1\bar{Q}_2\theta+w_2(\rho_1\bar{Q}_1+Q_1)({-}w_1\rho_1\bar{Q}_2-w_1Q_2\\ & \quad-\lambda_1P_0\theta-w_1\lambda_1P_0\theta+w_1\rho_1\bar{Q}_2+w_1Q_1)-(\rho_1\bar{Q}_2+Q_2) (w_2w_1\lambda_1P_0\theta\\ & \quad-w_1\rho_1\bar{Q}_2-w_1w_2Q_2-\lambda_2P_0\theta+\rho_1\bar{Q}_2+Q_2)\\ & \quad+\frac{[(\rho_2G_1+N_1)c_1+P_1(\eta_1\alpha_1-\beta_1)]}{P_1c_1^{2}(1-w_1w_2\rho_2^{2})} \left\{\lambda_1P_0\eta_1\alpha_1- \lambda_1P_0\beta_1\vphantom{\frac{\rho_2c_1}{c_2}}\right.\\ & \quad\left.-c_1N_2-\rho_2c_1G_2+\frac{\rho_2c_1}{c_2}[-\lambda_2P_0\eta_2\alpha_2+\lambda_2P_0\beta_2 +c_2G_2+\rho_2c_2N_2]\right\}\\ & \quad-\frac{[(\rho_2N_2+G_2)c_2+P_2(\eta_2\alpha_2-\beta_2)]}{P_2c_2^{2}(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_2w_2}{c_1}[\lambda_1P_0\eta_1\alpha_1\right.\\ & \quad- w_1\lambda_1P_0\beta_1-w_1c_1N_2-w_1\rho_2c_1G_2]-\lambda_2P_0\eta_2\alpha_2\\ & \quad \left.+\lambda_2P_0\beta_2+c_2G_2+\rho_2c_2N_2\vphantom{\frac{\rho_2c_2w_2}{c_1}}\right\}. \end{align*}
Following from Theorem 10 in [Reference Briand and Confortola8] and using the same method in Wei and Wang [Reference Wei and Wang28],  $(P_i(t), Q_i(t), \bar {Q}_i(t), N_i(t), G_i(t))\in L_{\mathrm {F}}^{p}(\Omega ;C([0,T]); \mathrm {R}) \times L_{\mathrm {F}}^{p}(\Omega ;L^{2}(0,T;\mathrm {R}^{4}))$,
 $i=1,2$, are unique solutions to (3.21).
We now introduce equilibrium reinsurance and investment strategies  $\bar {p}_1(t)$,
 $\bar {u}_1(t)$,
 $\bar {p}_2(t)$, and
 $\bar {u}_2(t)$ associated with corresponding process
 $\bar {X}_1(t)$ and
 $\bar {X}_2(t)$ for two insurers. Follows Lemmas 4.5 and in Yan and Wong [Reference Yan and Wong31], we define
 $(\bar {u}_i(t),\bar {p}_i(t))$ in a for
 $i=1,2$, in a set of control pairs:
 \begin{align*} \mathcal{U}^{+}& =\{(u_i,p_i)\in L_{\mathrm{F}}^{2}(0,T;\mathrm{R})\times L_{\mathrm{F}}^{2}(0,T;\mathrm{R}^{+})\,|\,X_i(t)>0, \ {\rm a.s.}, \ {\rm a.e.}, \ t\in[0,T]; \\ & \qquad X_i(t)\in L_{\mathrm{F}}^{2}(\Omega;C([0,T];\mathrm{R}))\}. \end{align*}
The equilibrium strategies are given by
 \begin{align} \bar{p}_1(t)& =\frac{-1}{P_1(t)c_1^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\lambda_1P_0(t)(\bar{X}_1(t)-w_1\bar{X}_2(t))(\eta_1(t)\alpha_1(t)-\beta_1(t)) \vphantom{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right.\nonumber\\ & \quad-\bar{X}_1(t)(c_1(t)N_1(t)+\rho_1c_1(t)G_1(t))+w_1\bar{X}_2(c_1(t)N_2(t)+\rho_2c_1(t)G_2(t))\nonumber\\ & \quad+\frac{\rho_2c_1(t)w_1}{c_2(t)}[\lambda_2P_0(t)(\bar{X}_2(t)-w_2\bar{X}_1(t)) (\eta_2(t)\alpha_2(t)-\beta_2(t))-\bar{X}_2(t)(c_2(t)G_2(t)\nonumber\\ & \quad\left.+\rho_2c_1(t)N_2(t)) +w_2\bar{X}_1(t)(c_2(t)G_1(t)+\rho_2c_1(t)N_1(t))]\vphantom{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right\}+1, \end{align}
 \begin{align} \bar{p}_2(t)& =\frac{-1}{P_2(t)c_2^{2}(t)(1-w_1w_2\rho_2^{2})}\left\{\frac{\rho_2c_2(t)w_2}{c_1(t) }[\lambda_1P_0(t)(\bar{X}_1(t)-w_1\bar{X}_2(t)))(\eta_1(t)\alpha_1(t)-\beta_1(t))\right.\nonumber\\ & \quad-\bar{X}_1(t)(c_1(t)N_1(t)+\rho_1c_1(t)G_1(t))+w_1\bar{X}_2(t)(c_1(t)N_2(t) +\rho_2c_1(t)G_2(t))]\nonumber\\ & \quad+\lambda_2P_0(t)(\bar{X}_2(t)-w_2\bar{X}_1(t))(\eta_2(t)\alpha_2(t)-\beta_2(t))- \bar{X}_2(t)(c_2(t)G_2(t)\nonumber\\ & \quad\left.+\rho_2c_1(t)N_2(t))+w_2\bar{X}_1(c_2(t)G_1(t) +\rho_2c_1(t)N_1(t))\vphantom{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right\}+1, \end{align}
 \begin{align} \bar{u}_1(t)& =\frac{1}{P_1(t)(1-w_1w_2)}\{\lambda_1P_0(t)(\bar{X}_1(t)-w_1\bar{X}_2(t))\theta(t) -\rho_1(\bar{X}_1(t)\bar{Q}_1(t)\nonumber\\ & \quad-w_1\bar{X}_2(t)\bar{Q}_2(t))-P_1(t)(1-\bar{p}_1(t))\beta_1(t) +w_1P_2(t)(1-\bar{p}_2(t))\beta_2(t)\nonumber\\ & \quad+w_1Q_2(t)\bar{X}_2(t) +w_1[\lambda_2P_0(t)(\bar{X}_2(t) -w_2\bar{X}_1(t))\theta(t)-\rho_1(\bar{X}_2(t)\bar{Q}_2(t)\nonumber\\ & \quad-w_2\bar{X}_1(t)\bar{Q}_1(t))-P_2(t)(1-\bar{p}_2(t))\beta_2(t) +w_2P_1(t)(1-\bar{p}_1(t))\beta_1(t)\nonumber\\ & \quad+w_2Q_1(t)\bar{X}_1(t)]\}, \end{align}
 \begin{align} \bar{u}_2(t)& =\frac{1}{P_2(t)(1-w_1w_2)}\{w_2[\lambda_1P_0(t)(\bar{X}_1(t) -w_1\bar{X}_2(t))\theta(t)-\rho_1(\bar{X}_1(t)\bar{Q}_1(t)\nonumber\\ & \quad-w_1\bar{X}_2(t)\bar{Q}_2(t))-P_1(t)(1-\bar{p}_1(t))\beta_1(t) +w_1P_2(t)(1-\bar{p}_2(t))\beta_2(t)\nonumber\\ & \quad+w_1Q_2(t)\bar{X}_2(t)]+\lambda_2P_0(t)(\bar{X}_2(t)-w_2\bar{X}_1(t))\theta(t) -\rho_1(\bar{X}_2(t)\bar{Q}_2(t)\nonumber\\ & \quad-w_2\bar{X}_1(t)\bar{Q}_1(t))-P_2(t)(1-\bar{p}_2(t))\beta_2(t) +w_2P_1(t)(1-\bar{p}_1(t))\beta_1(t)\nonumber\\ & \quad+w_2Q_1(t)\bar{X}_1(t)\}. \end{align}
The following lemma shows  $\bar {D}_i(t)\in L_{\mathrm {F}}^{2}(\Omega ;C([0,T];\mathrm {R}))$ with controls
 $\bar {u}_i(t)$ and
 $\bar {p}_i(t)$,
 $i=1,2,$ and then, we prove the existence result for the open-loop equilibrium controls.
Lemma 3.4. We assume that  $|\theta (t)|^{2}\in L_{\mathrm {F}}^{2p}(\Omega ;L^{2}(0,T;\mathrm {R}^{4}))$, then the relative performance
 $\bar {D}_i(t)\in L_{\mathrm {F}}^{2}(\Omega ;C([0,T];\mathrm {R}))$.
Proof. By solving (3.7), the relative performance for insurer 1 can be derived
 \begin{align*} \bar{D}_1(t)& =e^{\int_0^{t}r_s\,ds}x_0+\int_0^{t}e^{-\int_0^{s}r_v\,dv} \{[1-\bar{p}_1(s)]\eta_1(s)\alpha_1(s)\\ & \quad-w_1[1-\bar{p}_2(s)]\eta_2(s)\alpha_2(s)+\theta(s)\bar{u}_1(s)-w_1\theta(s)\bar{u}_2(s)]\}\,ds\\ & \quad+\int_0^{t}e^{-\int_0^{s}r_v\,dv}\{\bar{u}_1(s)-w_1\bar{u}_2(s)+[1-\bar{p}_1(s)]\beta_1(s) -w_1[1-\bar{p}_2(s)]\beta_2(s)\}\,dW(s)\\ & \quad+\int_0^{t}e^{-\int_0^{s}r_v\,dv}[1-\bar{p}_1(s)]c_1(s)\,dB_1(s) -\int_0^{t}e^{-\int_0^{s}r_v\,dv}w_1[1-\bar{p}_2(s)]c_2(s)\,dB_2(s). \end{align*}
As  $(P_i(s),Q_i(s),\bar {Q}_i(s),N_i(s),G_i(s))\in L_{\mathrm {F}}^{p}(\Omega ;C([0,T]; \mathrm {R}))\times L_{\mathrm {F}}^{p}(\Omega ;L^{2}(0,T;\mathrm {R}^{4}))$,
 $i=1,2$, and
 $|\theta (s)|^{2}\in L_{\mathrm {F}}^{2p}(\Omega ;L^{2}(0,T;\mathrm {R}^{4}))$, we have
 \begin{align*} & \mathrm{E}\left[\sup_{0\leq t \leq T}\left|\int_0^{t}\{[1-\bar{p}_1(s)]\eta_1(s)\alpha_1(s)-w_1[1-\bar{p}_2(s)]\eta_2(s)\alpha_2(s)\right.\right.\\ & \qquad\left.\left. +\theta(s)\bar{u}_1(s)-w_1\theta(s)\bar{u}_2(s)\}\,ds\vphantom{\int_0^{t}}\right|^{p}\right]\\ & \quad \leq C\mathrm{E}\left[\left(\int_0^{t} (\eta_1^{2}(s)\alpha_1^{2}(s)+w_1\eta_2^{2}(s)\alpha_2^{2}(s)+(1-w_1)\theta^{2}(s))\,ds\right.\right.\\ & \qquad\left.\left.+\int_0^{t} [\bar{u}_1^{2}(s)+\bar{u}_1^{2}(s)+\bar{p}_1^{2}(s)+\bar{p}_2^{2}(s)]\,ds\right)^{{p}/{2}}\right] \\ & \quad\leq C\mathrm{E}\left[\left(\int_0^{t} (\eta_1^{2}(s)\alpha_1^{2}(s)+w_1\eta_2^{2}(s)\alpha_2^{2}(s)+(1-w_1)\theta^{2}(s))\,ds\right)^{{p}/{2}}\right]\\ & \qquad+C\mathrm{E}\left[\left(\int_0^{t} [u_1^{2}(s)+u_1^{2}(s)+p_1^{2}(s)+p_2^{2}(s)]\,ds\right)^{{p}/{2}}\right] <\infty, \end{align*}
and similarly, we have
 \begin{align*} & \mathrm{E}\left[\sup_{0\leq t \leq T}| \{\bar{u}_1(s)-w_1\bar{u}_2(s)+[1-\bar{p}_1(s)]\beta_1(s)-w_1[1-\bar{p}_2(s)]\beta_2(s)\}\,dW(s)\right.\\ & \quad\left. +[1-\bar{p}_1(s)]c_1(s)\,dB_1(s)-w_1[1-\bar{p}_2(s)]c_2(s)\,dB_2(s) |^{p}\vphantom{\sup_{0\leq t \leq T}} \right]< \infty, \end{align*}
where  $C$ is a constant that can be different from line to line. Thus, we get
 $$\mathrm{E}\left[\sup_{0\leq t \leq T}|\bar{D}_1(t)|^{2} \right]<\infty.$$
Therefore,  $\bar {D}_1(t) \in L_{\mathrm {F}}^{2}(\Omega ;C([0,T];\mathrm {R}))$. Mimicking the same procedure, we deduce
 $\bar {D}_2(t) \in L_{\mathrm {F}}^{2} (\Omega ;C([0,T];\mathrm {R}))$. We omit details here.
Now, we show the existence of open-loop equilibrium reinsurance and investment strategies.
Theorem 3.5. The strategies  $\bar {u}_i(t),\bar {p}_i(t)$, for
 $i=1,2$, given by (3.22), (3.24), (3.23), and (3.25) are open-loop equilibrium strategies with the corresponding relative performance processes
 $\bar {D}_i(t)$ for Problem 2.1.
Proof. Firstly, we show that for  $t\in [0,T]$,
 $Y_1(s;t)$,
 $Z_1(s;t)$,
 $\bar {Z}_1(s;t)$,
 $U_1(s;t)$, and
 $M_1(s;t)$ are solutions to the backward equation in (3.7). As mentioned above, we assume that
 $Y_1(s;t)$ can be expressed as
 $$Y_1(s;t)=P_1(s)\bar{X}_1(s)-\mathrm{E}_t[P_1(s)\bar{X}_1(s)] -w_1\{P_2(s)\bar{X}_2(s)-\mathrm{E}_t[P_1(s)\bar{X}_2(s)]\}-\lambda_1P_0\bar{D}_1(t).$$
By Itô's formula, we have (suppressing the variable  $s$)
 \begin{align*} d(P_1\bar{X}_1)& =\{P_1[r\bar{X}_1+(1-\bar{p}_1)\eta_1\alpha_1+\theta \bar{u}_1]-f_1\bar{X}_1+(\rho_1\bar{Q}_1+Q_1) [\bar{u}_1+(1-\bar{p}_1)\beta_1]\\ & \quad+(\rho_2G_1+N_1)(1-\bar{p}_1)c_1\}\,ds+\{P_1[\bar{u}_1+(1-\bar{p}_1)\beta_1]+Q_1\bar{X}_1\}\,dW\\ & \quad +\bar{X}_1\bar{Q}_1\,d\bar{W}+[P_1c_1(1-\bar{p}_1)+N_1\bar{X}_1]\,dB_1+[G_1\bar{X}_1]\,dB_2, \end{align*}
and
 \begin{align*} d(P_2\bar{X}_2)& =\{P_2[r\bar{X}_2+(1-\bar{p}_2)\eta_2\alpha_2+\theta \bar{u}_2]-f_2\bar{X}_2+(\rho_1\bar{Q}_2+Q_2) [\bar{u}_2+(1-\bar{p}_2)\beta_2]\\ & \quad +(\rho_2N_2+G_2)(1-\bar{p}_2)c_2\}\,ds+\{P_2[\bar{u}_2+(1-\bar{p}_2)\beta_2] +Q_2\bar{X}_2\}\,dW\\ & \quad +\bar{X}_2\bar{Q}_2\,d\bar{W}+[N_2\bar{X}_2]\,dB_1 +[P_2c_2(1-\bar{p}_2)+G_2\bar{X}_2]\,dB_2. \end{align*}
It is easy to yield
 \begin{align*} d\mathrm{E}_t[P_1\bar{X}_1]& =\mathrm{E}_t\{P_1[r\bar{X}_1+(1-\bar{p}_1)\eta_1\alpha_1+\theta \bar{u}_1]-f_1\bar{X}_1+(\rho_1\bar{Q}_1+Q_1) [\bar{u}_1+(1-\bar{p}_1)\beta_1]\\ & \quad+(\rho_2G_1+N_1)(1-\bar{p}_1)c_1\}\,ds, \end{align*}
and
 \begin{align*} d\mathrm{E}_t[P_2\bar{X}_2]& =\mathrm{E}_t\{P_2[r\bar{X}_2+(1-\bar{p}_2)\eta_2\alpha_2+\theta \bar{u}_2]-f_2\bar{X}_2+(\rho_1\bar{Q}_2+Q_2) [\bar{u}_2+(1-\bar{p}_2)\beta_2]\\ & \quad+(\rho_2N_2+G_2)(1-\bar{p}_2)c_2\}\,ds. \end{align*}
Thus, we obtain
 \begin{align*} dY_1& =\{P_1[r\bar{X}_1+(1-\bar{p}_1)\eta_1\alpha_1+\theta \bar{u}_1]-f_1\bar{X}_1+(\rho_1\bar{Q}_1+Q_1) [\bar{u}_1+(1-\bar{p}_1)\beta_1]\\ & \quad+(\rho_2G_1+N_1)(1-\bar{p}_1)c_1-w_1\{P_2[r\bar{X}_2+(1-\bar{p}_2)\eta_2\alpha_2\\ & \quad+\theta\bar{u}_2]-f_2\bar{X}_2+(\rho_1\bar{Q}_2+Q_2) [\bar{u}_2+(1-\bar{p}_2)\beta_2]+(\rho_2N_2+G_2)(1-\bar{p}_2)c_2\}\}\,ds\\ & \quad+\{P_1[\bar{u}_1+(1-\bar{p}_1)\beta_1]+Q_1\bar{X}_1 -w_1\{P_2[\bar{u}_2+(1-\bar{p}_2)\beta_2]+Q_2\bar{X}_2\}\}\,dW\\ & \quad+\bar{X}_1\bar{Q}_1 -w_1\bar{X}_2\bar{Q}_2\,d\bar{W}+[P_1c_1(1-\bar{p}_1)+N_1\bar{X}_1-w_1N_2\bar{X}_2]\,dB_1\\ & \quad+\{G_1\bar{X}_1-w_1[P_2c_2(1-\bar{p}_2)+G_2\bar{X}_2]\}\,dB_2\\ & \quad +\mathrm{E}_t\{P_1[r\bar{X}_1+(1-\bar{p}_1)\eta_1\alpha_1+\theta \bar{u}_1]-f_1\bar{X}_1+(\rho_1\bar{Q}_1+Q_1) [\bar{u}_1+(1-\bar{p}_1)\beta_1]\\ & \quad+(\rho_2G_1+N_1)(1-\bar{p}_1)c_1-w_1\{P_2[r\bar{X}_2+(1-\bar{p}_2)\eta_2\alpha_2+\theta \bar{u}_2]-f_2\bar{X}_2\\ & \quad+(\rho_1\bar{Q}_2+Q_2)[\bar{u}_2+(1-\bar{p}_2)\beta_2]+(\rho_2N_2+G_2)(1-\bar{p}_2)c_2\}\}\,ds -r\lambda_1P_0(\bar{X}_1(t)-w_1\bar{X}_2(t)). \end{align*}
Plugging the expressions of  $f_1(s,P_1(s),Q_1(s),\bar {Q}_1(s),N_1(s),G_1(s))$,
 $\bar {u}_1(s)$,
 $\bar {p}_1(s)$ and comparing coefficients, we have
 \begin{align*} Z_1(s;t)& =P_1(s)[\bar{u}_1(s)+(1-\bar{p}_1(s))\beta_1(s)]+Q_1(s)\bar{X}_1(s)-w_1\{P_2(s)[\bar{u}_2(s)\\ & \quad +(1-\bar{p}_2(s))\beta_2(s)]+Q_2(s)\bar{X}_2(s)\},\\ \bar{Z}_1(s;t)& =\bar{X}_1(s)\bar{Q}_1(s)-w_1\bar{X}_2(s)\bar{Q}_2(s),\\ U_1(s;t)& =P_1(s)c_1(s)(1-\bar{p}_1(s))+N_1(s)\bar{X}_1(s)-w_1N_2(s)\bar{X}_2(s),\\ M_1(s;t)& =G_1(s)\bar{X}_1(s)-w_1[P_2(s)c_2(s)(1-\bar{p}_2(s))+G_2(s)\bar{X}_2(s)]. \end{align*}
It is straight to see that, for any  $t\in [0,T]$,
 $Y_1(s;t)$,
 $Z_1(s;t)$,
 $\bar {Z}_1(s;t)$,
 $U_1(s;t)$, and
 $M_1(s;t)$ are the solutions to the backward equation in (3.7).
Furthermore, we prove that equilibrium strategies given by (3.22), (3.24), (3.23), and (3.25) satisfy the conditions in Theorem 3.2. According to (3.16), conditions (3.9) can be rewritten as
 \begin{equation} \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon} \{\Lambda_{11}(s;t)\nu_{11}(s)+\Lambda_{21}(s;t)[\bar{p}_1(s)-\nu_{21}(s)]\}\,ds\geq 0, \end{equation}
which implies that
 \begin{align} & \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon} \{[Y_1(s;t)\theta(s)+\rho_1\bar{Z}_1(s;t)+Z_1(s;t)\nu_{11}(s)\nonumber\\ & \quad+[Y_1(s;t)\eta_1(s)\alpha_1(s)+\beta_1(s)[Z_1(s;t)+\rho_1 \bar{Z}_1(s;t)]][\bar{p}_1(s)-\nu_{21}(s)]\}\,ds\geq 0. \end{align}
To prove the equilibrium strategies satisfy the conditions (3.11), we only need to verify that (3.27) is satisfied. We move on the following equation firstly
 \begin{equation} \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon} [Y_1(s;t)\theta(s)+\rho_1\bar{Z}_1(s;t)+Z_1(s;t)]\nu_{11}(s)\,ds. \end{equation}
Plugging expressions of  $Y_1(s;t)$,
 $Z_1(s;t)$,
 $\bar {Z}_1(s;t)$,
 $U_1(s;t)$, and
 $M_1(s;t)$ into (3.28), we obtain
 \begin{align*} [Y_1(t;t)\theta(t)+\rho_1 \bar{Z}_1(t;t)+Z_1(t;t)]\nu_{11}(t) & ={-}\lambda_1P_0(t)D_1(t)\theta(t)+\rho_1\bar{X}_1(t)\bar{Q}_1(t)\\ & \quad-w_1\bar{X}_2(t)\bar{Q}_2(t) P_1(t)[\bar{u}_1(t)+(1-\bar{p}_1(t))\beta_1(t)]\\ & \quad+Q_1(t)\bar{X}_1(t)-w_1\{P_2(t)[\bar{u}_2(t)+(1-\bar{p}_2(t))\beta_2(t)]\\ & \quad+Q_2(t)\bar{X}_2(t)\}. \end{align*}
Incorporating the expressions of  $\bar {u}_1(t)$ and
 $\bar {p}_1(t)$ given by (3.22), (3.24), we have
 $$[Y_1(t;t)\theta(t)+\rho_1 \bar{Z}_1(t;t)+Z_1(t;t)]\nu_{11}(t)=0.$$
Then
 \begin{align*} & \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon}|[Y_1(s;t)\theta(s)+\rho_1 \bar{Z}_1(s;t)+Z_1(s;t)]\nu_{11}(s)\\ & \qquad -[Y_1(s;s)\theta(s)+\rho_1\bar{Z}_1(s;s)+Z_1(s;s)]\nu_{11}(s)|\,ds\\ & \quad =\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon}| P_1(s)\bar{X}_1(s)-\mathrm{E}_t[P_1(s)\bar{X}_1(s)]\\ & \qquad+w_1P_2(s)\bar{X}_2(s)-w_1\mathrm{E}_t[P_2(s)\bar{X}_2(s)]\nu_{11}(s)|\,ds\\ & \quad \leq C\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon}\{ |\bar{X}_1(s)-\mathrm{E}_t[\bar{X}_1(s)]|\\ & \qquad+|w_1P_2(s)\bar{X}_2(s)-w_1\mathrm{E}_t[P_2(s)\bar{X}_2(s)]|\}|\nu_{11}(s)|\,ds, \end{align*}
where  $C>0$ is a constant. Since
 $\mathrm {E}[\int _0^{T}|\nu _{11}(s)|^{2}\,ds]<\infty$, a.e., for
 $t\in [0,T]$, and
 $\bar {X}(t)$ is continuous, we have
 \begin{align*} & \mathrm{E}\left\{\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon} |\bar{X}(s)-\mathrm{E}_t[\bar{X}(s)]||\nu_{11}(s)|\,ds\right\}\\ & \quad \leq\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E} \left\{E_t\int_t^{t+\varepsilon}|\bar{X}(s)-\mathrm{E}_t[\bar{X}(s)]| |\nu_{11}(s)|\,ds\right\}\\ & \quad =\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E} \left\{\int_t^{t+\varepsilon}|\bar{X}(s)-\mathrm{E}_t[\bar{X}(s)]| |\nu_{11}(s)|\,ds\right\} \\ & \quad \leq\liminf_{\varepsilon\downarrow 0}\left\{\frac{1}{\varepsilon}\mathrm{E} \left[\int_t^{t+\varepsilon}|\bar{X}(s)-\mathrm{E}_t[\bar{X}(s)]|^{2}\,ds\right] \frac{1}{\varepsilon}\mathrm{E}\left[\int_t^{t+\varepsilon} |\nu_{11}(s)|^{2}\right]\right\}^{{1}/{2}}\,ds=0. \end{align*}
Thus, we obtain
 \begin{equation} \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\int_t^{t+\varepsilon}\mathrm{E}[| \bar{X}_1(s)-\mathrm{E}_t[\bar{X}_1(s)]|^{2}]\,ds=0, \end{equation}
which implies that
 \begin{align*} & \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon} [Y_1(s;t)\theta(s)+\rho_1\bar{Z}_1(s;t)+Z_1(s;t)]\nu_{11}(s)\,ds\\ & \quad=\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon} [Y_1(s;s)\theta(s)+\rho_1\bar{Z}_1(s;s)+Z_1(s;s)]\nu_{11}(s)\,ds= 0. \end{align*}
If we can prove
 \begin{equation} \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon}\{ [Y_1(s;t)\eta_1(s)\alpha_1(s)+\beta_1(s)[Z_1(s;t)+\rho_1 \bar{Z}_1(s;t)]][\bar{p}_1(s)-\nu_{21}(s)]\}\,ds\geq 0, \end{equation}
then (3.27) can be verified. In the following, we give the proof of (3.30). Plugging expressions of  $Y_1(s;t)$,
 $Z_1(s;t)$,
 $\bar {Z}_1(s;t)$,
 $U_1(s;t)$, and
 $M_1(s;t)$ and comparing the coefficients, we obtain
 \begin{align} & \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon}\{| [Y_1(s;s)\eta_1(s)\alpha_1(s)+\beta_1(s)[Z_1(s;s)+\rho_1\bar{Z}_1(s;s)]\nonumber\\ & \quad +c_1(s)U_1(s;s)+\rho_2c_1(s)M_1(s;s)][\bar{p}_1(s)-\nu_{21}(s)]|\}\,ds\geq 0. \end{align}
Since  $\mathrm {E}[\int _0^{T}|\bar {p}_1(s)|^{2} \,ds]<\infty$ and
 $\mathrm {E}[\sup |D_1(s)|^{2}]<\infty$. Repeating the procedure, we can show that
 \begin{align} & \liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon}\{ [Y_1(s;t)\eta_1(s)\alpha_1(s)+\beta_1(s)[Z_1(s;t)+\rho_1 \bar{Z}_1(s;t)]\nonumber\\ & \qquad +c_1(s)U_1(s;t)+\rho_2c_1(s)M_1(s;t)][\bar{p}_1(s)-\nu_{21}(s)]\}\,ds\nonumber\\ & \quad =\liminf_{\varepsilon\downarrow 0}\frac{1}{\varepsilon}\mathrm{E}_t\int_t^{t+\varepsilon}\{ [Y_1(s;s)\eta_1(s)\alpha_1(s)+\beta_1(t)[Z_1(s;s)+\rho_1 \bar{Z}_1(s;s)]\nonumber\\ & \qquad+c_1(s)U_1(s;s)+\rho_2c_1(s)M_1(s;s)][\bar{p}_1(s)-\nu_{21}(s)]\}\,ds\geq 0, \quad {\rm a.e.}, \ t\in[0,T],\ {\rm a.s.} \end{align}
Thus, the controls  $\bar {p}_1(t)$ and
 $\bar {u}_1(t)$ given by (3.22) and (3.24) satisfy conditions. Using the same method, we can also prove that the controls
 $\bar {p}_2(t)$ and
 $\bar {u}_2(t)$ given by (3.23) and (3.25) are indeed open-loop equilibrium strategies. Here, we omit details. The proof is completed.
Corollary 3.6. The equilibrium value functions of insurers corresponding to  $\bar {u}_1(t)$,
 $\bar {p}_1(t)$,
 $\bar {u}_2(t)$, and
 $\bar {p}_2(t)$ are given by (suppressing the variable
 $s$)
 \begin{align} J_1(t,\bar{x}_1,\bar{x}_2;\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t)) & =\frac{1}{2}\mathrm{E}_t\int_t^{T}\{[P_1[\bar{u}_1+(1-\bar{p}_1)\beta_1]+Q_1\bar{X}_1 -w_1[P_2[\bar{u}_2+Q_2\bar{X}_2\nonumber\\ & \quad+(1-\bar{p}_2)\beta_2]]]^{2}+[\bar{X}_1\bar{Q}_1-w_1\bar{X}_2\bar{Q}_2]^{2} +[P_1c_1(1-\bar{p}_1)\nonumber\\ & \quad+N_1\bar{X}_1-w_1N_2\bar{X}_2]^{2}+[G_1\bar{X}_1-w_1[P_2c_2(1-\bar{p}_2)\nonumber\\ & \quad+G_2\bar{X}_2]]^{2}\}\,ds -\lambda_1(\bar{X}_1(t)-w_1\bar{X}_2(t))[P_1(t)\bar{X}_1(t)\nonumber\\ & \quad-w_1P_2(t)\bar{X}_2(t)].\\ J_2(t,\bar{x}_1,\bar{x}_2;\bar{u}_1(t),\bar{p}_1(t),\bar{u}_2(t),\bar{p}_2(t)) & =\frac{1}{2}\mathrm{E}_t\int_t^{T}\{[P_2[\bar{u}_2+(1-\bar{p}_2)\beta_1]+Q_2\bar{X}_2 -w_2[P_1[\bar{u}_1+Q_1\bar{X}_1\nonumber\\ & \quad+(1-\bar{p}_1)\beta_2]]]^{2}+[\bar{X}_2\bar{Q}_2-w_2\bar{X}_1\bar{Q}_1]^{2} +[P_2c_2(1-\bar{p}_2)\nonumber\\ & \quad+N_2\bar{X}_2-w_2N_1\bar{X}_1]^{2}+[G_2\bar{X}_2-w_2[P_1c_1(1-\bar{p}_1)\nonumber\\ & \quad+G_1\bar{X}_1]]^{2}\}\,ds -\lambda_1(\bar{X}_2(t)-w_2\bar{X}_1(t))[P_2(t)\bar{X}_2(t) \cr & \quad-w_2P_1(t)\bar{X}_1(t)]. \end{align}
Proof. Here, again it suffices to show insurer 1's value function  $J_1(t,\bar {x}_1,\bar {x}_2;\bar {u}_1(t),\bar {p}_1(t),\bar {u}_2(t),\bar {p}_2(t))$. Using same procedure, the corresponding value function for insurer 2 can also be derived. Since
 $P_1(T)=1$ and
 $P_2(T)=1$, we have
 $$\bar{X}_1(T)-w_1\bar{X}_2(T)=P_1(T)\bar{X}_1(T)-w_1P_2(T)\bar{X}_2(T).$$
By Itô's formula, we obtain (suppressing the variable  $s$)
 \begin{align*} d(P_1(t)\bar{X}_1(t)-w_1P_2(t)\bar{X}_2(t)) & =[P_1[\bar{u}_1+(1-\bar{p}_1)\beta_1]+Q_1\bar{X}_1 -w_1[P_2[\bar{u}_2+(1-\bar{p}_2)\beta_2]\\ & \quad+Q_2\bar{X}_2]\,dW+[\bar{X}_1\bar{Q}_1-w_1\bar{X}_2\bar{Q}_2]\,d\bar{W}\\ & \quad+[P_1c_1(1-\bar{p}_1)+N_1\bar{X}_1\\ & \quad-w_1N_2\bar{X}_2]\,dB_1+[G_1\bar{X}_1-w_1[P_2c_2(1-\bar{p}_2)+G_2\bar{X}_2]]\,dB_2. \end{align*}
Thus,
 \begin{align*} \bar{X}_1(T)-w_1\bar{X}_2(T)& =P_1(t)\bar{X}_1(t)-w_1P_2(t)\bar{X}_2(t) +\int_t^{T}\{P_1[\bar{u}_1+(1-\bar{p}_1)\beta_1]\\ & \quad+Q_1\bar{X}_1-w_1[P_2[\bar{u}_2+(1-\bar{p}_2)\beta_2]+Q_2\bar{X}_2\}\,dW\\ & \quad+\int_t^{T}\{\bar{X}_1\bar{Q}_1-w_1\bar{X}_2\bar{Q}_2\}\,d\bar{W}\\ & \quad +\int_t^{T}\{P_1c_1(1-\bar{p}_1)+N_1\bar{X}_1-w_1N_2\bar{X}_2\}\,dB_1\\ & \quad+\int_t^{T}\{G_1\bar{X}_1-w_1[P_2c_2(1-\bar{p}_2)+G_2\bar{X}_2]\}\,dB_2. \end{align*}
Therefore,
 $$\mathrm{E}_t[\bar{X}_1(T)-w_1\bar{X}_2(T)]=P_1(t)\bar{X}_1(t)-w_1P_2(t)\bar{X}_2(t).$$
Taking conditional expectations, we have
 \begin{align*} \mathrm{E}_t[[\bar{X}_1(T)-w_1\bar{X}_2(T)]^{2}] & =[P_1(t)\bar{X}_1(t)-w_1P_2(t)\bar{X}_2(t)]^{2} +\mathrm{E}_t\int_t^{T}\{[P_1[\bar{u}_1+(1-\bar{p}_1)\beta_1]\\ & \quad+Q_1\bar{X}_1-w_1[P_2[\bar{u}_2+(1-\bar{p}_2)\beta_2]+Q_2\bar{X}_2]]^{2} +[\bar{X}_1\bar{Q}_1-w_1\bar{X}_2\bar{Q}_2]^{2}\\ & \quad+[P_1c_1(1-\bar{p}_1)+N_1\bar{X}_1-w_1N_2\bar{X}_2]^{2}\\ & \quad+[G_1\bar{X}_1-w_1[P_2c_2(1-\bar{p}_2)+G_2\bar{X}_2]]^{2}\}\,ds. \end{align*}
4. Applications to stochastic volatility models
In this section, we apply our results to concrete stochastic volatility models: Hull–White model and Henston model. For simplicity, we assume that for  $i=1,2$,
 $\eta _i(t)$,
 $\alpha _i(t)$,
 $\beta _i(t)$,
 $c_i(t)$ are bounded deterministic functions. Then, we obtain the closed-form expressions for open-loop equilibrium reinsurance and investment strategies.
4.1. The Hull–White model
Here, we consider the Hull–White stochastic volatility model, which is a typical non-leveraged stochastic model:
 \begin{equation} \left\{\begin{aligned} dS(t) & =S(t)[(r(t)+\lambda(t))\,dt+\sqrt{V(t)}\,dW(t)], \quad t\in[0,T],\\ S(0) & =s_{0}>0,\\ dV(t) & =b_1(t)V(t)\,dt+b_2(t)V(t)\,d\bar{W}(t),\\ V(0) & =v_{0}>0, \end{aligned}\right. \end{equation}
where the Wiener processes  $W(t)$ and
 $\bar {W}(t)$ are independent, that is
 $\rho _1=0$.
 $\lambda (t)$,
 $b_1(t)$, and
 $b_2(t)$ are deterministic bounded positive functions .
Proposition 4.1. Let  $S(t)$ and
 $V(t)$ be given by (4.1). The reinsurance and investment strategies for two insurers are derived by
 \begin{align} \bar{p}_1(t)& =\frac{-1}{(A_1(t)V^{{-}1}(t)+B_1(t))c_1^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_1(t)w_1}{c_2(t)}[\lambda_2P_0(t)\bar{D}_2(t)(\eta_2(t)\alpha_2(t)-\beta_2(t))]\right.\nonumber\\ & \quad \left.+\lambda_1P_0(t)\bar{D}_1(t)(\eta_1(t)\alpha_1(t)-\beta_1(t)) \vphantom{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right\}+1, \end{align}
 \begin{align} \bar{p}_2(t)& =\frac{-1}{(A_2(t)V^{{-}1}(t)+B_2(t))c_2^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_2(t)w_2}{c_1(t) }[\lambda_1P_0(t)\bar{D}_1(t)(\eta_1(t)\alpha_1(t)-\beta_1(t))]\right.\nonumber\\ & \quad \left.+\lambda_2P_0(t)\bar{D}_2(t)(\eta_2(t)\alpha_2(t)-\beta_2(t)) \vphantom{\{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right\}+1, \end{align}
 \begin{align} \bar{u}_1(t)& =\frac{1}{(A_1(t)V^{{-}1}(t)+B_1(t))(1-w_1w_2)}\{w_1[\lambda_2P_0(t) \bar{D}_2(t)\theta(t)-(A_2(t)V^{{-}1}(t)+B_2(t))(1\nonumber\\ & \quad-\bar{p}_2(t))\beta_2(t)+w_2(A_1(t)V^{{-}1}(t)+B_1(t))(1-\bar{p}_1(t)) \beta_1(t)]+\lambda_1P_0(t)\bar{D}_1(t)\theta(t)\nonumber\\ & \quad-(A_1(t)V^{{-}1}(t)+B_1(t))(1-\bar{p}_1(t))\beta_1(t)\nonumber\\ & \quad+w_1(A_2(t)V^{{-}1}(t)+B_2(t))(1-\bar{p}_2(t))\beta_2(t)\}, \end{align}
 \begin{align} \bar{u}_2(t)& =\frac{1}{(A_2(t)V^{{-}1}(t)+B_2(t))(1-w_1w_2)}\{w_2[\lambda_1P_0(t)\bar{D}_1(t)\theta(t) -(A_1(t)V^{{-}1}(t)+B_1(t))(1\nonumber\\ & \quad-\bar{p}_1(t))\beta_1(t)+w_1(A_2(t)V^{{-}1}(t)+B_2(t))(1-\bar{p}_2(t))\beta_2(t)] +\lambda_2P_0(t)\bar{D}_2(t)\theta(t)\nonumber\\ & \quad-(A_2(t)V^{{-}1}(t)+B_2(t))(1-\bar{p}_2(t))\beta_2(t)\nonumber\\ & \quad+w_2(A_1(t)V^{{-}1}(t)+B_1(t))(1-\bar{p}_1(t))\beta_1(t)\}. \end{align}
where
 \begin{align*} & A_1(t)=A_2(t)=\lambda_1\exp^{\int_t^{T}r(s)\,ds}\int_t^{T}\lambda^{2}(s) \exp^{-\int_s^{t}(r(u)-b_1(u)+b_2^{2}(u))\,du}\,ds,\\ & B_1(t)=\exp^{\int_t^{T} 2 r(s)\,ds}+\lambda_1\Phi_1^{2}(t)\exp^{\int_t^{T}r(s)\,ds}\int_t^{T}\exp^{-\int_s^{t}r(u)\,du}\,ds,\\ & B_2(t)=\exp^{\int_t^{T} 2 r(s)\,ds}+\lambda_1\Phi_2^{2}(t)\exp^{\int_t^{T}r(s)\,ds}\int_t^{T}\exp^{-\int_s^{t}r(u)\,du}\,ds, \end{align*}
and
 \begin{align*} & \Phi_1(t)=\frac{\eta_1(t)\alpha_1(t)-\beta_1(t)}{c_1^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\lambda_1\eta_1(t)\alpha_1(t)-\lambda_1\beta_1(t) +\frac{\rho_2c_1(t)w_1}{c_2(t)}[-\lambda_2w_2\eta_2(t)\alpha_2(t)+\lambda_2w_2\beta_2(t)]\right\}\\ & \quad-\frac{w_1(\eta_2(t)\alpha_2(t)-\beta_2(t))}{c_2^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_2(t)w_2}{c_1(t)}[\lambda_1\eta_1(t)\alpha_1(t)- \lambda_2\beta_1(t)]-\lambda_2w_2\eta_2(t)\alpha_2(t)\right.\\ & \quad\left.+\lambda_2w_2\beta_2(t)\vphantom{\frac{\rho_2c_2(t)w_2}{c_1(t)}}\right\},\\ \Phi_2(t)& =\frac{\eta_2(t)\alpha_2(t)-\beta_2(t)}{c_2^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\lambda_2\eta_2(t)\alpha_2(t)-\lambda_2\beta_2(t) +\frac{\rho_2c_2(t)w_2}{c_1(t)}[-\lambda_1w_1\eta_1(t)\alpha_1(t)+\lambda_1w_1\beta_1(t)]\right\}\\ & \quad- \frac{w_2(\eta_1(t)\alpha_1(t)-\beta_1(t))}{c_1^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_1(t)w_1}{c_2(t)}[\lambda_2\eta_2(t)\alpha_2(t)- \lambda_1\beta_2(t)]-\lambda_2w_1\eta_1(t)\alpha_1(t)\right.\\ & \quad\left.+\lambda_1w_1\beta_1(t)\vphantom{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right\}, \end{align*}
Proof. The deterministic parameters imply that  $Q_i(t)=0$,
 $N_i(t)=0$, and
 $G_i(t)=0$, for
 $i=1,2$. We have
 $\theta (t,V(t))=\lambda (t) V^{-{1}/{2}}(t)$. By the nonlinear Feynman–Kac formula, we consider the following PDEs:
 \begin{equation} \left\{\begin{aligned} & F_{i,t}(t,v)+F_{i,v}(t,v)b_1(t)v+\tfrac{1}{2}F_{i,vv}(t,v)b_2^{2}(t)v^{2}+f_i(t,F_i(t,v),b_2(t)vF_{i,v}(t,v))=0,\\ & F_i(T,v)=P_i(T). \end{aligned}\right. \end{equation}
By Itô's formula, we know that, for  $i=1,2$,
 $$(P_i(t), \bar{Q}_i(t))=(F_i(t,v),b_2(t)vF_{i,v}(t,v)).$$
We consider the ansatz:
 \begin{equation} \begin{aligned} & (P_1(t), \bar{Q}_1(t))=(A_1(t)V^{{-}1}(t)+B_1(t),-b_2(t)A_1(t)V^{{-}1}(t)),\\ & (P_2(t), \bar{Q}_2(t))=(A_2(t)V^{{-}1}(t)+B_2(t),-b_2(t)A_2(t)V^{{-}1}(t)). \end{aligned} \end{equation}
Plugging (4.7) into (4.6), we obtain
 \begin{equation} \left\{\begin{aligned} & A_{1,t}(t)v^{{-}1}+b_2^{2}(t)A_1(t)v^{{-}1}-b_1(t)A_1(t)v^{{-}1}+2A_1(t)v^{{-}1}r(t)\\ & \quad +\lambda_1P_0(t)\lambda^{2}v^{{-}1}=0,\quad t\in[0,T],\\ & A_1(T)=0,\\ & B_{1,t}(t)+2B_1(t)r(t)+P_0(t)\Phi_1(t)=0,\quad t\in[0,T],\\ & B_1(T)=1, \end{aligned}\right. \end{equation}
and
 \begin{equation} \left\{\begin{aligned} & A_{2,t}(t)v^{{-}1}+b_2^{2}(t)A_2(t)v^{{-}1}-b_1(t)A_2(t)v^{{-}1}+2A_2(t)v^{{-}1}r(t)\\ & \quad +\lambda_1P_0(t)\lambda^{2}v^{{-}1}=0,\quad t\in[0,T],\\ & A_2(T)=0,\\ & B_{2,t}(t)+2B_2(t)r(t)+P_0(t)\Phi_2(t)=0,\quad t\in[0,T],\\ & B_2(T)=1. \end{aligned}\right. \end{equation}
By solving (4.8) and (4.9), the equilibrium controls are derived.
4.2. The Henston model
In this subsection, we consider the price of risky asset  $S(t)$ in the incomplete financial market follows Henston's model:
 \begin{equation} \left\{\begin{aligned} & dS(t)x=S(t)[(r(t)+\lambda(t)V(t))\,dt+\sqrt{V(t)}\,dW_t)], \quad t\in[0,T],\\ & S(0)=s_{0}>0,\\ & dV(t)=k(t)(\xi(t)-V(t))\,dt+\Psi(t)\sqrt{V(t)}\,d\bar{W}_t,\\ & V(0)=v_{0}>0,\\ & dW(t)\,d\bar{W}(t)=\rho_1\,dt, \end{aligned}\right. \end{equation}
where  $\lambda (t)$,
 $k(t)$,
 $\xi (t)$,
 $\Psi (t)$ are deterministic bounded positive functions and
 $\theta (t,V(t))=\lambda (t)\sqrt {V(t)}$. We require
 $2k(t)\xi (t)\geq \Psi ^{2}(t)$ to ensure that
 $V(t)$ is almost surely non-negative.
Remark 4.2. To find the explicit open-loop equilibrium strategies, we apply the nonlinear Feynman–Kac formula. Thus, we obtain
 \begin{equation} \left\{\begin{aligned} & P_{1,t}(t,v)+P_{1,v}(t,v)k(t)(\xi_t-v)+\tfrac{1}{2}P_{1,vv}(t,v)\Psi^{2}(t)v\\ & \quad+f_i(t,P_1(t,v),\Psi(t)\sqrt{v}P_{1,vv}(t,v))=0, \quad t\in[0,T],\\ & P_1(T)=1, \end{aligned}\right. \end{equation}
and
 \begin{equation} \left\{\begin{aligned} & P_{2,t}(t,v)+P_{2,v}(t,v)k(t)(\xi_t-v)+\tfrac{1}{2}P_{2,vv}(t,v)\Psi^{2}(t)v\\ & \quad+f_i(t,P_2(t,v),\Psi(t)\sqrt{v}P_{2,vv}(t,v))=0, \quad t\in[0,T],\\ & P_2(T)=1. \end{aligned}\right. \end{equation}
However, it is difficult to solve (4.11) and (4.12) explicitly so that we simplify the model with no leveraging effect, that is,  $\rho _1=0$. Thus, we have the following proposition.
Proposition 4.3. For the Henston's stochastic volatility model with the non-leveraged risky asset, the investment strategies and reinsurance strategies are given by
 \begin{align} \bar{p}_1(t)& =\frac{-1}{(A_3(t)V(t)+B_3(t))c_1^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_1(t)w_1}{c_2(t)}[\lambda_2P_0(t)\bar{D}_2(t)(\eta_2(t)\alpha_2(t)-\beta_2(t))]\right.\nonumber\\ & \quad \left.+\lambda_1P_0(t)\bar{D}_1(t)(\eta_1(t)\alpha_1(t)-\beta_1(t)) \vphantom{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right\}+1, \end{align}
 \begin{align} \bar{p}_2(t)& =\frac{-1}{(A_4(t)V(t)+B_4(t))c_2^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_2(t)w_2}{c_1(t) }[\lambda_1P_0(t)\bar{D}_1(t)(\eta_1(t)\alpha_1(t)-\beta_1(t))]\right.\nonumber\\ & \quad\left.+\lambda_2P_0(t)\bar{D}_2(t)(\eta_2(t)\alpha_2(t)-\beta_2(t)) \vphantom{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right\}+1, \end{align}
 \begin{align} \bar{u}_1(t)& =\frac{1}{(A_3(t)V(t)+B_3(t))(1-w_1w_2)}\{w_1[\lambda_2P_0(t) \bar{D}_2(t)\theta(t)-(A_4(t)V(t)+B_4(t))(1-\bar{p}_2(t))\beta_2(t)\nonumber\\ & \quad+w_2(A_3(t)V(t)+B_3(t))(1-\bar{p}_1(t))\beta_1(t)] +\lambda_1P_0(t)\bar{D}_1(t)\theta(t)\nonumber\\ & \quad-(A_3(t)V(t)+B_3(t))(1-\bar{p}_1(t))\beta_1(t)\nonumber\\ & \quad+w_1(A_4(t)V(t)+B_4(t))(1-\bar{p}_2(t))\beta_2(t)\}, \end{align}
 \begin{align} \bar{u}_2(t)& =\frac{1}{(A_4(t)V(t)+B_4(t))(1-w_1w_2)}\{w_2[\lambda_1P_0(t)\bar{D}_1(t)\theta(t) -(A_3(t)V(t)+B_3(t))(1-\bar{p}_1(t))\beta_1(t)\nonumber\\ & \quad+w_1(A_2(t)V(t)+B_2(t))(1-\bar{p}_2(t))\beta_2(t)] +\lambda_2P_0(t)\bar{D}_2(t)\theta(t)\nonumber\\ & \quad-(A_4(t)V(t)+B_4(t))(1-\bar{p}_2(t))\beta_2(t)\nonumber\\ & \quad+w_2(A_3(t)V(t)+B_3(t))(1-\bar{p}_1(t))\beta_1(t)\}, \end{align}
where
 \begin{align*} A_3(t)& =A_4(t)=\lambda_1\exp^{\int_t^{T}r(s)\,ds}\int_t^{T}\lambda^{2}(s)\exp^{-\int_s^{t}(r(u)-k(u))\,du}\,ds,\\ B_3(t)& =\exp^{\int_t^{T} 2 r(s)\,ds}+\int_t^{T}\exp^{-\int_s^{t}2r(u)\,du}[\lambda_1\Phi_3^{2}(s)\exp^{\int_s^{t}r(u)\,du}+k(s)\xi(s)A_3(s)]\,ds,\\ B_4(t)& =\exp^{\int_t^{T} 2 r(s)\,ds}+\int_t^{T}\exp^{-\int_s^{t}2r(u)\,du}[\lambda_1\Phi_4^{2}(s)\exp^{\int_s^{t}r(u)\,du}+k(s)\xi(s)A_4(s)]\,ds, \end{align*}
and
 \begin{align*} \Phi_3(t)& =\frac{\eta_1(t)\alpha_1(t)-\beta_1(t)}{c_1^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\lambda_1\eta_1(t)\alpha_1(t)- \lambda_1\beta_1(t)+\frac{\rho_2c_1(t)w_1}{c_2(t)}[-\lambda_2w_2\eta_2(t)\alpha_2(t)+\lambda_2w_2\beta_2(t)]\right\}\\ & \quad-\frac{w_1(\eta_2(t)\alpha_2(t)-\beta_2(t))}{c_2^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_2(t)w_2}{c_1(t)}[\lambda_1\eta_1(t)\alpha_1(t)- \lambda_1\beta_1(t)]-\lambda_2w_2\eta_2(t)\alpha_2(t)\right.\\ & \quad\left.+\lambda_2w_2\beta_2(t)\vphantom{\frac{\rho_2c_2(t)w_2}{c_1(t)}}\right\},\\ \Phi_4(t)& =\frac{\eta_2(t)\alpha_2(t)-\beta_2(t)}{c_2^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\lambda_2\eta_2(t)\alpha_2(t)- \lambda_2\beta_2(t)+\frac{\rho_2c_2(t)w_2}{c_1(t)}[-\lambda_1w_1\eta_1(t)\alpha_1(t)+\lambda_1w_1\beta_1(t)]\right\}\\ & \quad-\frac{w_2(\eta_1(t)\alpha_1(t)-\beta_1(t))}{c_1^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_1(t)w_1}{c_2(t)}[\lambda_2\eta_2(t)\alpha_2(t)- \lambda_2\beta_2(t)]-\lambda_1w_1\eta_1(t)\alpha_1(t)\right.\\ & \quad\left.+\lambda_1w_1\beta_2(t)\vphantom{\frac{\rho_2c_2(t)w_2}{c_1(t)}}\right\}. \end{align*}
Proof. The deterministic parameters imply that  $Q_i(t)=0$,
 $N_i(t)=0$, and
 $G_i(t)=0$, for
 $i=1,2$. By the nonlinear Feynman–Kac formula, we consider the following PDEs:
 \begin{equation} \left\{\begin{aligned} & F_{i,t}(t,v)+F_{i,v}(t,v)k(t)(\xi(t)-v)+\tfrac{1}{2}F_{i,vv}(t,v)\Psi^{2}(t)v \\ & \quad+f_i(t,F_i(t,v),\Psi(t)\sqrt{v}F_{i,v}(t,v))=0, \quad t\in[0,T],\\ & F_i(T,v)=P_i(T). \end{aligned}\right. \end{equation}
By Itô's formula, we know that, for  $i=1,2$,
 $$(P_i(t), \bar{Q}_i(t))=(F_i(t,v),\Psi(t)\sqrt{v}F_{i,v}(t,v)).$$
We consider the ansatz:
 \begin{equation} \begin{aligned} & (P_1(t), \bar{Q}_1(t))=(A_3(t)V(t)+B_3(t),\Psi(t)A_3(t)\sqrt{V(t)}),\\ & (P_2(t), \bar{Q}_2(t))=(A_4(t)V(t)+B_4(t),\Psi(t)A_4(t)\sqrt{V(t)}). \end{aligned} \end{equation}
Plugging (4.18) into (4.17), we obtain
 \begin{equation} \left\{\begin{aligned} & A_{3,t}(t)v-vk(t) A_3(t)+2A_3(t)vr(t)+\lambda_1P_0(t)\lambda^{2}(t)v=0,\quad t\in[0,T],\\ & A_3(T)=0,\\ & B_{3,t}+k(t)\xi(t)A_3(t)+2B_3(t)r(t)+P_0(t)\Phi_3(t)=0,\quad t\in[0,T],\\ & B_3(T)=1, \end{aligned}\right. \end{equation}
and
 \begin{equation} \left\{\begin{aligned} & A_{4,t}(t)v-vk(t) A_4(t)+2A_4(t)vr(t)+\lambda_1P_0(t)\lambda^{2}(t)v=0,\quad t\in[0,T],\\ & A_4(T)=0,\\ & B_{4,t}+k(t)\xi(t)A_4(t)+2B_4(t)r(t)+P_0(t)\Phi_4(t)=0,\quad t\in[0,T],\\ & B_4(T)=1. \end{aligned}\right. \end{equation}
By solving (4.19) and (4.20), the equilibrium controls are derived.
Remark 4.4. When the financial market is complete and all the parameters are deterministic, that is,  $V^{-1}(t)=\sigma ^{-2}(t)$,
 $\lambda (t)=\mu (t)-r(t)$, and
 $b_1(t)=b_2(t)=0$. Thus, in this case, the equilibrium strategies become
 \begin{align} \bar{p}_1(t)& =\frac{-1}{(A(t)\sigma^{{-}2}(t)+B(t))c_1^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_1(t)w_1}{c_2(t)}[\lambda_2P_0(t)\bar{D}_2(t)(\eta_2(t)\alpha_2(t)-\beta_2(t))]\right.\nonumber\\ & \quad\left.+\lambda_1P_0(t)\bar{D}_1(t)(\eta_1(t)\alpha_1(t)-\beta_1(t)) \vphantom{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right\}+1, \end{align}
 \begin{align} \bar{p}_2(t)& =\frac{-1}{(A(t)\sigma^{{-}2}(t)+C(t))c_2^{2}(t)(1-w_1w_2\rho_2^{2})} \left\{\frac{\rho_2c_2(t)w_2}{c_1(t) }[\lambda_1P_0(t)\bar{D}_1(t)(\eta_1(t)\alpha_1(t)-\beta_1(t))]\right.\nonumber\\ & \quad+\left.\lambda_2P_0(t)\bar{D}_2(t)(\eta_2(t)\alpha_2(t)-\beta_2(t)) \vphantom{\frac{\rho_2c_1(t)w_1}{c_2(t)}}\right\}+1, \end{align}
 \begin{align} \bar{u}_1(t)& =\frac{1}{(A(t)\sigma^{{-}2}(t)+B(t))(1-w_1w_2)}\{w_1[\lambda_2P_0(t) \bar{D}_2(t)\theta(t)-(A(t)\sigma^{{-}2}(t)+C(t))(1\nonumber\\ & \quad-\bar{p}_2(t))\beta_2(t)+w_2(A(t)\sigma^{{-}2}(t)+B(t))(1-\bar{p}_1(t)) \beta_1(t)] +\lambda_1P_0(t)\bar{D}_1(t)\theta(t)\nonumber\\ & \quad-(A(t)\sigma^{{-}2}(t)+B(t))(1-\bar{p}_1(t))\beta_1(t) \nonumber\\ & \quad+w_1(A(t)\sigma^{{-}2}(t)+C(t))(1-\bar{p}_2(t))\beta_2(t)\}, \end{align}
 \begin{align} \bar{u}_2(t)& =\frac{1}{(A(t)\sigma^{{-}2}(t)+C(t))(1-w_1w_2)}\{w_2[\lambda_1P_0(t)\bar{D}_1(t)\theta(t) -(A(t)\sigma^{{-}2}(t)+B(t))(1\nonumber\\ & \quad-\bar{p}_1(t))\beta_1(t)+w_1(A(t)\sigma^{{-}2}(t)+C(t))(1-\bar{p}_2(t))\beta_2(t)] +\lambda_2P_0(t)\bar{D}_2(t)\theta(t)\nonumber\\ & \quad-(A(t)\sigma^{{-}2}(t)+C(t))(1-\bar{p}_2(t))\beta_2(t)\nonumber\\ & \quad+w_2(A(t)\sigma^{{-}2}(t)+B(t))(1-\bar{p}_1(t))\beta_1(t)\}. \end{align}
where
 \begin{align*} & A(t)=\lambda_1\exp^{\int_t^{T}r(s)\,ds}\int_t^{T}(\mu(s)-r(s))^{2}\exp^{-\int_s^{t}(r(u))\,du}\,ds,\\ & B(t)=\exp^{\int_t^{T} 2 r(s)\,ds}+\lambda_1\Phi_1^{2}(t)\exp^{\int_t^{T}r(s)\,ds}\int_t^{T}\exp^{-\int_s^{t}r(u)\,du}\,ds,\\ & C(t)=\exp^{\int_t^{T} 2 r(s)\,ds}+\lambda_1\Phi_2^{2}(t)\exp^{\int_t^{T}r(s)\,ds}\int_t^{T}\exp^{-\int_s^{t}r(u)\,du}\,ds. \end{align*}
Remark 4.5. When  $w_1=w_2=0$, our model is reduced to the case without competition. If the price of risky asset
 $S(t)$ follows the Hull–White model, the equilibrium reinsurance strategy
 $\bar {p}(t)$ and investment policy
 $\bar {u}(t)$ are given by
 \begin{align*} \bar{p}(t)& =\frac{-1}{(A(t)V^{{-}1}(t)+B(t))c^{2}(t))}+1,\\ \bar{u}(t)& =\frac{1}{(A(t)V^{{-}1}(t)+B(t))} \{\lambda P_0(t)\bar{X}(t)\theta(t)-(A(t)V^{{-}1}(t)+B(t))(1-\bar{p}(t))\beta(t)\}, \end{align*}
where
 \begin{align*} & A(t)=\lambda\exp^{\int_t^{T}r(s)\,ds}\int_t^{T}\lambda^{2}(s)\exp^{-\int_s^{t}(r(u)-b_1(u)+b_2^{2}(u))\,du}\,ds,\\ & B(t)=\exp^{\int_t^{T} 2 r(s)\,ds}+\lambda\Phi^{2}(t)\exp^{\int_t^{T}r(s)\,ds}\int_t^{T}\exp^{-\int_s^{t}r(u)\,du}\,ds, \end{align*}
and
 $$\Phi(t)=\frac{\eta(t)\alpha(t)-\beta(t)}{c^{2}(t)}[\lambda\eta(t)\alpha(t)- \lambda\beta(t)],$$
which coincides with results in previous literature about time-consistent mean–variance reinsurance–investment problems.
5. Numerical examples
In this section, to better understand the impacts of parameters of the financial market on equilibrium investment and reinsurance strategies for two insurers, we study some numerical examples of the reinsurance–investment strategy pairs under the Hull–White model. Throughout the section, inspired by Yan and Wong [Reference Yan and Wong31] and Zhu et al. [Reference Zhu, Cao and Zhu36], the basic parameters are given by:  $T=10$,
 $r=0.12$,
 $\lambda =0.4$,
 $w_1=0.4$,
 $w_2=0.6$,
 $\lambda _1=0.2$,
 $\eta _1=1.2$,
 $\eta _2=1$,
 $\alpha _1=0.5$,
 $\alpha _2=0.7$,
 $\beta _1=0.1$,
 $\beta _2=0.1$,
 $c_1=0.2$,
 $c_2=0.2$,
 $k=1.2$,
 $\xi =1$,
 $\Psi =0.2$,
 $\rho _2=0.3$,
 $v_0=1$,
 $x_{10}=1$,
 $x_{20}=1$.
In Figure 1, we observe that equilibrium reinsurance strategies  $\bar {p}_i(t)$ and equilibrium investment strategies
 $\bar {\pi }_i(t)$, for
 $i=1,2$ change at each time point. The subgraph
 $(\mathrm {a})$ shows that the equilibrium reinsurance strategy
 $\bar {p}_i(t)$ for insurer
 $i$ decreases as decision time
 $t$ increases, implying that the insurance risk exposure increases and the insurer prefers to raise the retention level of reinsurance as time passes. The subgraph
 $(\mathrm {b})$ illustrates that the equilibrium investment strategy
 $\bar {\pi }_i(t)$ for insurer
 $i$ has an upward trend, which demonstrates that both insurers invest heavily in the risky asset over given time period.
The value of reinsurance and investment strategies  $\bar {p}_i(t)$ and
 $\bar {\pi }_i(t)$ , for
 $i=1,2$.

Figure 2 plots that how the impacts of the weight of relative wealth  $w_i$,
 $i=1,2$, on the equilibrium reinsurance strategies
 $\bar {p}_i(0)$ for two insurers at the initial time. From the subgraph
 $(\mathrm {a})$ and subgraph
 $(\mathrm {b})$, we observe that
 $\bar {p}_i(0)$ decreases with an increasing
 $w_i$ for insurer
 $i$. Higher
 $w_i$ means that the insurer
 $i$ pays more attention to the performance compared with that of his competitor. The insurer
 $i$ should retain less share of claim to decrease risk exposure. However, the cost spent on reinsurance contracts will increase when purchasing more reinsurance contracts to reduce risk, which causes a decrease in the value of terminal wealth. Therefore, to avoid higher reinsurance fee, insurers will choose to purchase less proportion reinsurance. Figure 3 depicts the effects of relative performance parameters
 $w_i$,
 $i=1,2$, on the equilibrium investment strategies
 $\bar {\pi }_i(0)$ for two insurers. We see that the insurer would like to invest more in the risky asset if he is more concerned about the relative performance.
Impacts of  $w_i$ on
 $\bar {p}_i(0)$, for
 $i=1,2$.

Impacts of  $w_i$ on
 $\bar {\pi }_i(0)$, for
 $i=1,2$.

Figure 4 displays the impacts of relationship between two insurers's claim processes on the equilibrium reinsurance strategies, where subfigure (a) illustrates insurer 1's proportion reinsurance in equilibrium, and subfigure (b) plots that of insurer 2. The correlation is represented by correlation coefficient  $\rho _2$ between two standard Brownian motions
 $B_1(t)$ and
 $B_2(t)$. If two claim processes are exposed to a common shock and therefore positively correlated, then the total claim process for each insurer may not be diversifiable. In other words, the positive stronger relationship induces positive externalities to both insurers. Therefore, insurers will purchase more reinsurance protections.
Impacts of  $\rho _2$ on
 $\bar {p}_i(0)$, for
 $i=1,2$.

Now, we move on the study of equilibrium investment strategies with respect of parameter  $\lambda$. Subfigures in Figure 5 show that the equilibrium investment strategies
 $\bar {\pi }_1(0)$ and
 $\bar {\pi }_2(0)$ both have upward trends over
 $\lambda$, respectively.
 $\lambda$ captures the rate of return of risky asset. As parameter
 $\lambda$ increases, insurers will increase investment in the risky asset because the risky asset is more attractive and can enhance benefits for insurers.
Remark 5.1. The stochastic process  $V(t)$ impacts the volatility of the risky asset's price. Leverage effect captures the relationship between volatility and price of risky asset, that is,
 $\rho _1$. This effect refers to the trend that volatility increases with the decline of prices and decreases with the rise of prices. As shown in Li et al. [Reference Li, Zeng and Lai17], if
 $\rho _1>0$, the risky asset price and its volatility process move in the same direction. Thus, the optimal investment strategy increases with decrease in volatility. If
 $\rho _1<0$, the risky asset price and its volatility process move in the different direction, then the insurer invest more in the risky asset with increase in volatility. As we mentioned in Section 4, it is difficult to solve the nonlinear PDE explicitly. To find explicit solutions, we assume that the risky asset has no leveraging effect in two cases.
Impacts of  $\lambda$ on
 $\bar {\pi }_i(0)$, for
 $i=1,2$.

When the financial is complete and all the parameters are deterministic, we can see from Figure 6, both insurers will decrease investment in the risky asset because the risky asset is more volatile. This is consistent with investment wisdom.
Impacts of  $\sigma$ on
 $\bar {\pi }_i(0)$, for
 $i=1,2$.

6. Conclusion
This paper focuses on a class of time-consistent non-zero-sum stochastic differential reinsurance and investment game with state-dependent trade-off between mean and variance in an incomplete market with stochastic volatility. The objective for each insurer is to find the tradeoff between the expectation and variance of relative terminal performance. Applying the approach of FBSDEs, we obtain expressions for the open-loop equilibrium reinsurance and investment strategies for two insurers and the corresponding value functions. Moreover, we apply our results to two special cases: Hull–White model and Heston model.
Note that our consideration only covers the existence of open-loop equilibrium strategies. It is worthwhile to investigate the uniqueness of equilibrium strategies. We need more dedicated technique to develop uniqueness results and will consider this problem in the future research. It is also worthy to extend to the excess-of-loss reinsurance, which is of practical interests but more challenging than the proportional reinsurance in the context of game theory.



