




No CrossRef data available.
Article contents
STATIONARITY AND MEMORY OF ARCH(∞) MODELS
Published online by Cambridge University Press: 05 March 2004
Abstract
We establish the necessary and sufficient conditions for covariance stationarity of ARCH(∞), for both the levels and the squares. The result applies to any form of the conditional variance coefficients. This includes GARCH(p,q) and also specifications with hyperbolically decaying coefficients, such as the autoregressive coefficients of the autoregressive fractionally integrated moving average model. The covariance stationarity condition for the levels rules out long memory in the squares.I thank Peter M. Robinson for useful comments on previous versions of the paper. Also, I am grateful to the co-editor (Bruce E. Hansen) and an anonymous referee whose suggestions greatly improved the paper.
Information
- Type
- Research Article
- Information
- Copyright
- © 2004 Cambridge University Press
1. INTRODUCTION
Introduced by the seminal work of Engle (1982), the autoregressive conditional heteroskedastic (ARCH) models are certainly the most popular class of nonlinear time series models, in particular thanks to the development of the generalized autoregressive conditional heteroskedastic model of order p,q (GARCH(p,q)) by Bollerslev (1986) defined by


where ω > 0, βi ≥ 0, αj ≥ 0 (i = 1,…, p, j = 1,…,q) for integers p ≥ 0 and q > 0 and a.s. means almost surely. The minimum conditions, which we assume hereafter, imposed on the rescaled innovation zt are i.i.d.-ness, |zt| < ∞ a.s., and zt2 not degenerate. When p = 0, one gets the ARCH(q).
Giraitis, Kokoska, and Leipes (2000) find sufficient conditions for strict stationarity of the ARCH(∞). This is the most general formulation of GARCH processes, generalizing (2) to

where τ ≥ 0 and ψk ≥ 0. The ARCH(∞) was introduced by Robinson (1991), who considered finite parameterizations of the ψk to build classes of alternatives in deriving score tests for no-ARCH. (See also the work of Hong, 1997, who proposes a one-sided test for no-ARCH that employs the ARCH(∞) as a class of alternatives.)
The ARCH(∞) representation of GARCH(p,q) model (2) is obtained choosing exponentially decaying ψk; e.g., the GARCH(1,1) follows setting τ = ω/(1 − β1) and ψj = α1 β1j−1; the ARCH(q) model is obtained when τ = ω and ψj = 0 for j > q. Although hyperbolic behavior of the ARCH coefficients ψj is allowed for, the strict stationarity condition of Giraitis et al. (2000),

implies a bounded second moment of the εt. Indeed, for GARCH(1,1) (4) works out to E(β1 + α1 zt2) < 1, the well-known covariance stationarity condition for the εt (see Bollerslev, 1986), which is more restrictive than the necessary and sufficient strict stationarity condition (see Nelson, 1990).
Exploiting the well-known linear ARMA(m, p) (with m = max[p,q]) representation of GARCH(p,q), introduced by Bollerslev (1986), the autocovariance function (ACF) of the squares εt2 can be readily shown to be proportional to the ACF of an ARMA(m, p) once the bounded fourth moment condition of the εt is imposed. The critical step is precisely calculating this constant of proportionality, given by E [zt2 − E(zt2)]2E(σt4). For general GARCH(p,q) the solution has been found independently by He and Teräsvirta (1999) and Karanasos (1999), extending the GARCH(1,2) and GARCH(2,1) cases analyzed by Bollerslev (1986). Noting that the previous results are either based on un-primitive assumptions or establish only necessity but not sufficiency, Ling (1999) and Ling and McAleer (2002) fill these gaps, providing the necessary and sufficient higher order moment conditions for GARCH(p,q).
This paper shows how to evaluate E(σt4) for ARCH(∞) σt2. It uses the linear representation of εt2 in a martingale difference sequence. The cases of both exponentially (such as GARCH(p,q)) and hyperbolically decaying coefficients ψj are comprised. In particular, necessary and sufficient conditions for weak stationarity of the levels εt and the squares εt2 are established. This is done in Section 2. Finally, we discuss in Section 3 the implications of the covariance stationarity conditions on the memory of the squares. It follows that covariance stationarity of the εt precludes long memory in the εt2. This strengthens the result of Giraitis et al. (2000), who found that a sufficient condition for covariance stationarity of the εt2 rules out long memory. The proofs for the results are given in the Appendix.
2. STATIONARITY OF ARCH(∞)
The minimal condition for covariance stationarity of the εt, is κ = E(zt2) < ∞, by (1). Following Robinson (1991), who considers the case κ = 1, setting

, we can rewrite (3) as
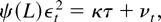
setting νt := εt2 − κσt2. By (1) and the i.i.d.-ness of the zt,
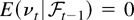
, where

is the σ-field of events induced by the εs (s ≤ t) (for the definition of conditional expectations when the corresponding unconditional expectations may not exist, see Loève, 1978, Sect. 27.2).
Assume that, for complex-valued z, the following “invertibility” condition holds:

A sufficient condition for (6) is
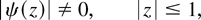
implying ψ(1) > 0, but we want to allow for the possibility that ψ(1) = 0 such as when the ψj are the AR(∞) coefficients of the autoregressive fractionally integrated moving average (ARFIMA) filter:

L being the lag operator (Lzt = zt−1) with d > 0 (by summability of the ψj) and where the finite-order polynomials a(L), b(L) have zeros outside the unit circle in the complex plane. Indeed, note that (6) does not imply absolute summability of the δj.
Given (6), (5) can be rewritten as

These simple manipulations suggest that τ, κ < ∞, and
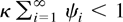
imply covariance stationarity of the εt. Indeed, it turns out that these are the necessary and sufficient conditions for E(εt2) < ∞. This is developed in Theorem 1, where the necessary and sufficient conditions for covariance stationarity of the squares εt2 are also established.
THEOREM 1. Assume that condition (6) holds.
(i) The necessary and sufficient conditions for E(σt2) < ∞ are


Under these conditions
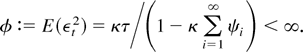
(ii) The necessary and sufficient conditions for E(σt4) < ∞ are



setting
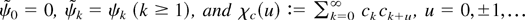
, for any square summable sequence ci.
Under these conditions the εt2 are covariance stationary with ACF
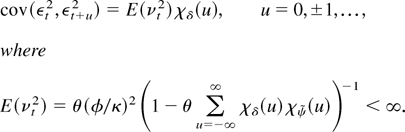
Remark 1.1. The ACF of the squares εt2 for GARCH(p,q) can be obtained as follows. We first establish the ARCH(∞) representation of GARCH(p,q). Exploiting the ARMA(max(p,q), p) representation of GARCH(p,q), by standard arguments (see Nelson and Cao, 1992) one obtains
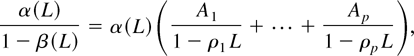
where α(L) := α1 L + ··· + αq Lq, β(L) := β1 L + ··· + βp Lp, ρi (i = 1,…, p) define the inverse of the roots of |1 − β(z)| = 0, assumed all outside the unit circle in the complex plane and distinct, and
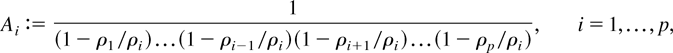
where Ap = A1 = 1 for p = 1. The ARCH(∞) coefficients ψj of GARCH(p,q) are then

with μj := A1(ρ1)j + ··· + Ap(ρp)j, j ≥ 0. Based on the previous definitions, Theorem 1 yields the ACF of GARCH(p,q) εt2 with
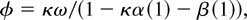
deriving the

and the χδ(u), and thus E(νt2), based on (15) and deriving the δi from (6).
Remark 1.2. Necessary and sufficient conditions for covariance stationarity of GARCH(p,q) εt2 have been independently established by He and Teräsvirta (1999) and Karanasos (1999). When considering GARCH(p,q), these results and (12)–(14) are equivalent, but formal derivation of their equivalence is very cumbersome. He and Teräsvirta (1999) is closer to our result, because their work considers the slightly more general case of nonstandardized zt, though from a computational point of view our conditions (12)–(14) seem more appealing because they permit immediate use of known results for the theoretical ACF of ARMA(p,q).
As an example, for GARCH(1,1), setting κ = 1 and π1 := α1 + β1, i.e., the “persistence” parameter, we get
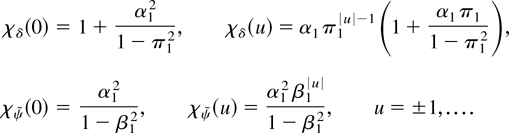
When the zt have zero fourth-order cumulant (such as for Gaussian zt) then θ = 2. Under this condition, by simple manipulations, (14) yields the well-known covariance stationarity conditions for εt2 (cf. Bollerslev, 1986, Sect. 3)

which, in turn, implies (11): E(zt2)α(1) + β(1) < 1.
For the ARCH(2), namely, ψk = 0, k ≥ 3, setting (1 − ξ1−1L)(1 − ξ2−1L) := (1 − ψ1 L − ψ2 L2) and assuming that the roots ξ1, ξ2 are greater than one in modulus (cf. (6)) and satisfy, for simplicity's sake, ξ1 ≠ ξ2, one gets
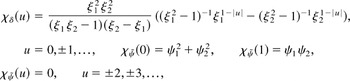
when κ = 1 (see Brockwell and Davis, 1987, Example 3.3.5). Using

and by simple manipulations, from (14) one gets the covariance stationarity condition for ARCH(2) εt2 (cf. Milhøj, 1985, Theorem 3; He and Teräsvirta, 1999, equation (12)), setting θ = 2,
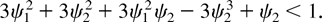
Remark 1.3. When
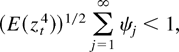
Giraitis et al. (2000, Theorem 2.1) show that E(σt4) < ∞. However, (17) is more restrictive than (14). For instance, for GARCH(1,1) with θ = 2κ = 2, their condition becomes
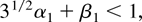
strictly implying (16), unless β1 = 0, the ARCH(1).
Remark 1.4. Hyperbolically decaying specifications of the ψi and hence of the δi are allowed for. Note, however, that from (11),
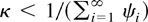
and thus κ = 1 is ruled out when
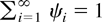
. Thus, unless κ < 1, (7) is not compatible with covariance stationary εt.
Imposing κ = 1, a choice compatible with covariance stationary levels is obtained using the autoregressive coefficients of the ARFIMA filter as follows. Set (cf. (7))

where d > 0 and a(L) and b(L) are finite-order polynomials, all of whose roots are outside the unit circle in the complex plane. Assuming that the nonnegativity constraints on the coefficients hold, i.e., ψi ≥ 0, set ψi = ψi (i ≥ 2) and ψ1 = ψ1ε for some given 0 < ε < 1. Condition (14) is more involved, but again by suitable modification of the first n (say) coefficients ψj (j = 1,…, n), a feasible sequence of coefficients can be obtained from (18).
Remark 1.5. An alternative, frequency domain characterization of (14) is

setting
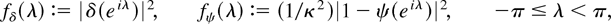
where κ2fψ(λ) = 1 + fδ−1(λ) − 2Re(δ−1(eiλ)) (−π ≤ λ < π) and Re(·) denotes the real part of its argument. This frequency domain specification seems easier to compute than (14). For instance, when considering parameterization (7) of the ψj (as for GARCH(p,q)) this allows us to exploit the much greater computational simplicity of rational power spectra compared with their Fourier transforms. This might be relevant when imposing covariance stationarity of the εt2 in practical estimation, e.g., when estimating ARCH(∞) using the Whittle estimator (see Giraitis and Robinson, 2001).
The equivalent (19) representation of (14) could be used to show that (14) strictly implies (11). In fact, setting θ = 2κ = 2 for simplicity's sake, (19) can be rewritten as
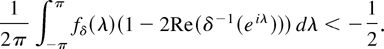
However, fδ(λ) ≥ 0 (−π ≤ λ < π), and it is arbitrary, necessarily requiring
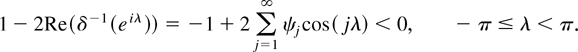
Given the nonnegativity of the ψi and cos(jλ) ≤ 1, with the equality achieved for λ = 0 (mod. 2π), this is equivalent to
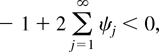
strictly implying ψ(1) > 0.
Finally, exploiting the relation between the ψi (i ≥ 1) and the δj (j ≥ 0) (cf. (6)), (19) allows us to express the time domain characterization (14) more simply as
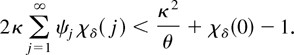
Remark 1.6. The original formulation of ARCH(∞), analogous to Robinson (1991) but allowing κ ≠ 1, is

for some

. The reparameterization (20) is clearly permitted only for covariance stationary εt, i.e., when ψ(1) > 0, given that

. In fact, assume that one starts directly from (20) rather than from (3). By the nonnegativity constraint
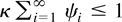
because ψ(1) < 0 is not allowed. Imposing ψ(1) = 0 and assuming (6), the linear moving average representation (8) for the εt2 would then be

for any constant ζ, given that ψ(L)εt2 = ψ(L)εt2 − ψ(1)ζ = ψ(L)(εt2 − ζ), which is meaningless.
Remark 1.7. (9)–(11) and (12)–(14) are the necessary and sufficient conditions for E(εt2) < ∞ and for E(εt4) < ∞, respectively.
3. MEMORY OF ARCH(∞)
Giraitis et al. (2000, Proposition 3.1) show that (17) implies absolute summability of the ACF for the εt2, ruling out long memory. However, considering that (17) is more restrictive than effectively required to obtain covariance stationary εt2, it is important to assess the impact of the weaker condition (14) on the memory of the εt2.
Insights can be obtained by looking at the linear representation (8) for εt2. In fact, it follows that the memory of the εt2 is expressed by the asymptotic behavior of δj as j → ∞. Surprisingly, it turns out that even the much weaker covariance stationarity condition (11) for the levels εt rules out long memory in the εt2. In fact, from (6) and (11),

Expression (14) ensures that the uncorrelated νt have finite variance but the rate of decay of the δj, imposed by (11), is already quick enough to imply their absolute summability. We summarize our results on the memory of the εt2 as follows.
THEOREM 2. Assume that conditions (6) and (11) hold. Then

where

When the ψi decay toward zero more slowly than exponentially, namely, ψi /ζi → ∞ as i → ∞ for any 0 < ζ < 1, (21) implies that, as u → ∞,

for some 0 < C < ∞, with c(x) ∼ d(x) as x → x0, meaning that c(x)/d(x) → 1.
Remark 2.1. When ψi ∼ ci−δ as i → ∞ for 0 < c, δ − 1 < ∞, as for the parameterization described in Remark 1.4, E(εt2) < ∞ implies
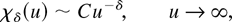
for some 0 < C < ∞, ruling out long memory in the εt2. Under the same assumptions on the asymptotic behavior of the ψi, the exact rate in (24) was also obtained in Giraitis et al. (2000, Proposition 3.2), although they impose (17), a sufficient condition for E(εt4) < ∞.
Remark 2.2. Theorem 2 makes it clear that whereas the bounded second moment conditions (9)–(11) impart the degree of memory of the εt2, the stronger bounded fourth moment conditions (12)–(14) ensure that the martingale difference sequence νt (the innovations in the linear representation (8) of the squares) are square integrable, without changing the memory implications of the model. This double role of the coefficients is simply a by-product of ARCH(∞) nonlinearity.
Remark 2.3. In the case of exponentially decaying ψi, i.e., when there does exist 0 < ζ < 1 such that ψi /ζi → c as i → ∞ for some 0 < c < ∞, it clearly follows that
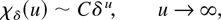
for some 0 < δ < 1, 0 < C < ∞, as in the GARCH(p,q) case.
APPENDIX
Proof of Theorem 1. Part (i). Assume that E(σt2) < ∞. The necessary condition of (9)–(11) follows, taking expectation on both sides of (3). Sufficiency of (9)–(11) for E(σt2) < ∞ is proved in Giraitis et al. (2000, Theorem 2.1). Part (ii). Assume that E(σt4) < ∞. Then (12)–(14) follow, squaring both terms in (3) and taking expectations,
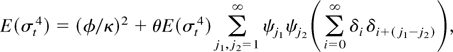
using
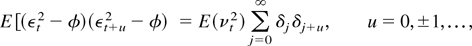
as the νt are square integrable martingale differences and
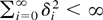
by (6). Given (12)–(14), E(εt2) = φ < ∞ by part (i). Therefore εt is strictly stationary. Next, setting
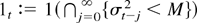
for some constant M < ∞ where 1(A) equals one when the event A holds and zero otherwise, for any arbitrary sequence of constants sj ≥ 0, j = 1,2,…,

Writing εt−j2 = εt−j2 − φ + φ, using (8), squaring and rearranging terms yields, as M → ∞,

setting
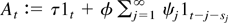
. For the expectation of the first two terms on the right-hand side of (A.1), as M → ∞,
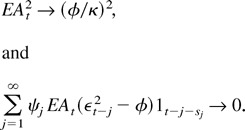
By the law of iterated expectations, setting P(A) = E1(A) for any event A,

the latter equality holding by strict stationarity. Finally, setting sj1 = k1, sj2 = k2, taking expectations and collecting terms in (A.1) yields

Proof of Theorem 2. From
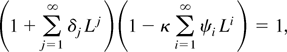
by the fundamental theorem for polynomials and simple yet tedious calculations, (22) follows. We now establish that

for some constant 0 < ζ < ∞. By (11), for any M < ∞
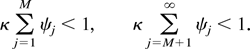
Consider a large enough k such that M < k for one of such M. Then, split the right-hand side of (22) as

where [·] is the integer part of its argument and

Let us dispose of the first sum on the right-hand side of (A.3). As l ≤ [k/M] , one obtains three terms:

with


and the “mixed” term
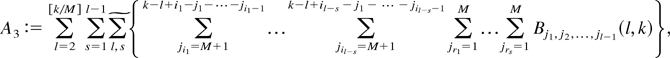
where
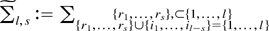
, i.e., it selects all the groups of indexes of dimension s (with s = 1,…, l − 1) drawn from a number l of them and thus for any s and any permutation ji1 + ··· + jil−s + jr1 + ··· + jrs = j1 + ··· + jl. Note that

.
For A1, for some 0 < ζ < 1, writing
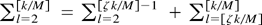
yields, as k → ∞,
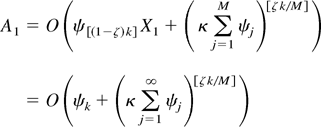
since

Concerning A2, along the same lines, as k → ∞,

For the “mixed” term, by means of the same truncation, one obtains A3 = A3′ + A3′′ where A3′ = O(ψk X2) = O(ψk) as k → ∞, setting
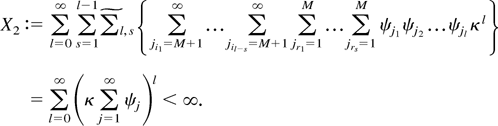
Likewise

For the second term on the right-hand side of (A.3), l > [k/M] implies that for at least one summation, say,
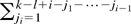
, then k − l + i − j1 − ··· − ji−1 < M. Thus, decomposition (A.5) is not feasible. However, the previous bounds developed for the case [ζk/M] ≤ l ≤ [k/M] can still be applied. In fact

given maxk≥1 ψk < ∞ and ψk ≥ 0 for any k. Then, apply (A.5) to the expression on the right-hand side of (A.9) and proceed as indicated previously.
Condition (11) ensures summability of the δj. On the other hand when
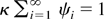
, (A.2) is loose, suggesting a rate of decay of δj slower than ψj. For instance, for case (7) with κ = 1 and d > 0 it follows that ψj ∼ cj−d−1 and δj ∼ c′jd−1 as j → ∞ for some 0 < c, c′ < ∞. Finally, note that when ψj ≥ 0 (j ≥ 1) then (22) implies δj ≥ 0 (j ≥ 0).
Hence, for any u > 0 and some 0 < c < ∞,
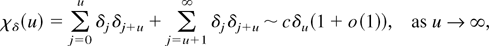
given that, for large enough u,
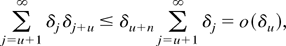
for some constant 1 ≤ n < ∞. Finally, comparing (A.2) with (22) and given κ > 0, ψi ≥ 0 (i ≥ 1), yields δk ∼ c ψk as k → ∞. █
References
REFERENCES
Bollerslev, T.
(1986)
Generalized autoregressive conditional heteroskedasticity.
Journal of Econometrics
31,
302–327.Google Scholar
Brockwell, P. &
R. Davis
(1987)
Time Series: Theory and Methods.
Springer-Verlag.
Engle, R.F.
(1982)
Autoregressive conditional heteroskedasticity with estimates of the
variance of the United Kingdom.
Econometrica
50,
987–1007.Google Scholar
Giraitis, L.,
P. Kokoska, &
R. Leipes
(2000)
Stationary ARCH models: Dependence structure and central limit
theorem.
Econometric Theory
16,
3–22.Google Scholar
Giraitis, L. &
P.M. Robinson
(2001)
Whittle estimation of ARCH models.
Econometric Theory
17,
608–631.Google Scholar
He, C. &
T. Teräsvirta
(1999)
Fourth moment structure of the GARCH(p,q) process.
Econometric Theory
15,
824–846.Google Scholar
Hong, Y.
(1997)
One-sided testing for conditional heteroskedasticity in time series
models.
Journal of Time Series Analysis
18,
253–277.Google Scholar
Karanasos, M.
(1999)
The second moment and the autocovariance function of the squared
errors of the GARCH model.
Journal of Econometrics
90,
63–76.Google Scholar
Ling, S.
(1999)
On the probabilistic properties of a double threshold ARMA
conditional heteroskedasticity model.
Journal of Applied Probability
36,
688–705.Google Scholar
Ling, S. &
M. McAleer
(2002)
Necessary and sufficient moment conditions for the GARCH(r,
s) and asymmetric power GARCH(r, s) models.
Econometric Theory
18,
722–729.Google Scholar
Loève, M.
(1978)
Probability Theory II,
4th ed.
Springer-Verlag.
Milhøj, A.
(1985)
The moment structure of ARCH processes.
Scandinavian Journal of Statistics
12,
281–292.Google Scholar
Nelson, D.
(1990)
Stationarity and persistence in the GARCH(1,1) model.
Econometric Theory
6,
318–334.Google Scholar
Nelson, D. &
C. Cao
(1992)
Inequality constraints in the univariate GARCH model.
Journal of Business and Economic Statistics
10,
229–235.Google Scholar
Robinson, P.M.
(1991)
Testing for strong serial correlation and dynamic conditional
heteroskedasticity in multiple regression.
Journal of Econometrics
47,
67–84.Google Scholar
 You have
Access
- 38
- Cited by