1. Introduction
The rise in total spending by central and local governments was one of the most profound economic changes of the twentieth century (Evenett, Reference Evenett2000). This is consistent with Public Finance theory as propounded by Wagner (1863) and Baumol (Reference Baumol1967) – an increase in GDP is accompanied by an increasing role of the state in maintaining law and order, providing essential services such as education and health, and contributing to other significant economic activities. This also means that the government in its various forms – central and sub-central as well as state-owned enterprises – spends a considerable sum of money on procuring goods and services in keeping with its growing responsibilities. Typically, figures for government procurement range from 10% to 15% of GDP across countries. The OECD (2002) estimates that government procurement (inclusive of defence and compensation of employees) accounts for almost 20% of GDP in OECD countries and between 9% and 20% of GDP in developing countries. An immediate implication is that through procurement, the state has a huge influence over the allocation of resources in market economies. An important aspect of this is the preponderance of domestic suppliers in meeting the procurement requirements of governments throughout much of the post-World War II period, possibly suggesting that public procurement acts as a non-tariff barrier to trade.
The procurement literature has used the theory of auctions and asymmetric information to develop models that show that discrimination may be necessary to minimize average procurement costs.Footnote 1 Moreover, minimizing procurement costs is not the only argument in the government's objective function. Governments are also saddled with political economy considerations and other non-economic objectives such as the promotion of domestic industry, encouraging the transfer of technology, promoting small, medium and artisan firms, and state enterprises, and the promotion of national security. This means that goods and services may not always be bought from the least-cost or most efficient supplier, further embedding discrimination in public procurement.
However, even if discrimination is an optimal policy outcome, the net welfare benefits are likely to be modest. Rather, the cost savings for procuring entities and greater profits for domestic firms that favouritism generates will tend to be offset by increased average prices (Deltas and Evenett, Reference Deltas, Evenett, Hoekman and Mavroidis1997). Moreover, the optimal discriminating mechanism is specific to the underlying conditions, so that even small deviations can eliminate any gains. On the other hand, studies have shown that cost savings through competitive bidding are in the range of 30% (Transparency International, 1997; World Bank, 1994).
This pragmatic argument in favour of non-discrimination is the cornerstone on which most international disciplines on government procurement are based. These measures include efforts undertaken by the EC as a part of its internal market reform and deregulation programmes, disciplines already present and those being negotiated in various preferential trade agreements, and the non-binding proposals of the APEC and the UNCITRAL Model Law (United Nations Commission on International Trade Law). Arguably, the most important of such initiatives has been the WTO's plurilateral Agreement on Government Procurement (GPA).
In this paper, we examine whether the GPA has been able to increase non-discriminatory procurement by looking at the pattern of public purchases in two countries – Japan and Switzerland – since the implementation of the Uruguay Round GPA (URGPA). The choice of countries in this analysis was primarily determined by data availability. Both countries have submitted detailed procurement data consistently since the URGPA, in a form that is amenable to the statistical analysis. But there were other considerations as well: both are large open services-intensive economies (services account for 75% of GDP) and both have large governments, federal and sub-federal. The average share of total government expenditure in GDP over 1996–2002 was almost 50% in Japan and 37% in Switzerland.
Data on government procurement were assembled from these countries' submissions to the WTO's Committee on Government Procurement. Shingal (Reference Shingal2002) and Evenett and Shingal (Reference Evenett and Shingal2006) analyzed these data in the case of Japan and found that the compliance mechanisms of the GPA ‘failed to prevent reductions in foreign penetration to Japan's state procurement markets’. The analysis was undertaken for both goods and services contracts awarded up to 1999 and concluded that ‘the proportion of total contracts awarded to foreigners in 1998 and 1999 was lower than in 1990 and 1991. In the absence of these changes, the value of contracts awarded to foreign firms would have been approximately 25% higher in 1998 and 1999’. In this paper, we build on this earlier work by developing new metrics, extending the period of analysis, and focusing exclusively on services procurement.
Our results indicate that, at least for these two countries, foreign market access in services procurement has not increased through the 1990s since the coming into effect of the GPA. In fact, the proportions of services contracts awarded to foreigners have declined over 1996/97–2002/03 for both countries, and, in the absence of this decline, the value of services contracts awarded to foreign firms would have been more than 15 times higher in the case of Japan and nearly 68 times more in the case of Switzerland! We also find that for the same services categories, the Japanese government is not purchasing as much from abroad as its private sector, a finding that further points to the home-bias in that government's public purchase decisions.
The structure of the paper is as follows. Section 2 discusses the GPA, including the scope of the Agreement and the availability of data that form the basis of the analysis in the paper. Section 3 looks at the methodology employed while Section 4 analyzes the individual country procurement patterns of the two countries in our sample and discusses the evolution of counterfactuals over time and in comparison with the private sector. Section 5 concludes.
2. The GPA and foreign procurement of services
2.1 The background
The GPA is a plurilateral agreement that was first negotiated during the Tokyo Round of Multilateral Trade Negotiations (1973–79) and came into effect on 1 January 1981. A 1987 Protocol amended the Tokyo Round Procurement Code and the new version entered into force on 1 January 1988. The GPA, as it stands today, was negotiated in parallel with the Uruguay Round of the GATT and came into effect on 1 January 1996. The URGPA has 40 Contracting Parties as its signatories.Footnote 2 Article XIX: 5 of the GPA requires that all Contracting Parties report data on procurement by government entities to the Committee on Government Procurement. These data pertain to the value and the number of contracts awarded by government procuring entities to winning suppliers who bid for them through one of the three procurement practices outlined in the Agreement – open tendering, selective tendering, and limited tendering. The GPA requires that only procurement above a certain threshold value be subject to international competitive bidding (ICB).
2.2 Scope and coverage of the Agreement
The GPA does not apply to all government procurement undertaken by its Contracting Parties. The Annexes of the GPA outline government entities and purchases of goods and services that are potentially disciplined by the Agreement. The GPA applies only to entities listed in Appendix 1 of the Agreement. This contains five Annexes for each signatory. Annex 1 lists covered central government entities, Annex 2 lists sub-central government entities, and Annex 3 is a ‘catch-all’ category that lists all other entities (such as utilities) that procure in accordance with the provisions of the GPA. Annex 4 lists covered services, and Annex 5 covered construction services. In addition, the URGPA's requirement of ICB does not apply to all procurement by the covered entities. Coverage depends on whether the value of the procurement is at or above a certain threshold.
Thresholds differ depending on the type of procurement and on the level of government making the purchase and are stated in terms of the IMF's accounting unit, the SDR. For Annex 1 central government entities, the threshold values are SDR 130,000 for procurement of goods and services and SDR 5 million for procurement of construction services. For Annex 2 sub-central government entities, the thresholds are SDR 200,000 for goods and services (except for the United States and Canada which apply a SDR 355,000 threshold) and SDR 5 million for construction services (with the exception of Japan and the South Korea, which apply a SDR 15 million threshold). For Annex 3 entities, the threshold values are SDR 400,000 for goods and services (with the exception that the United States applies a US$ 250,000 threshold for federally owned utilities) and SDR 5 million for construction services (barring Japan and Korea, which apply a threshold of SDR 15 million). Additionally, the General Notes of individual signatories may specify higher thresholds for particular Contracting Parties in a bid to ensure reciprocity.Footnote 3 Exceptions from the obligations of the Agreement are allowed for developing countries in certain situations outlined in Article V of the URGPA, while general exceptions are contained in Article XXIIIFootnote 4.
2.3 Data and their availability
Statistics submitted by the signatories to the WTO Secretariat are the primary source of data. Article XIX: 5 of the GPA requires that Contracting Parties submit procurement-related data to the Committee on Government Procurement. Article XIX: 5(a) of the URGPA requires the submission of information on the value of contracts awarded both above and below the threshold. Article XIX: 5(b) requires data on procurement above the threshold to be classified by procuring entities and by goods and services according to the nationality of the winning supplier, irrespective of whether the supplier is located in a Contracting Party to the GPA. Data also need to be provided on the use of limited tendering practices, broken down by entity and by categories of goods and services (Article XIX: 5(c)), and on derogations from the principles of Most Favoured Nation and National Treatment (Article XIX: 5(d)).
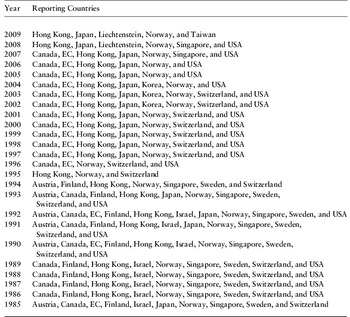
Unfortunately, only half of the 40 Contracting Parties (Canada, EU-15, Hong Kong, Japan, Norway, and the United States) have made statistical submissions regularly since the URGPA came into being (details provided in Annex Table 1).Footnote 5 Even amongst these, there are significant differences, both in terms of what is included and how it is included, and the need for consistency has thus determined the choice of sample countries for the analysis that follows. A point to note also is the seriousness with which Contracting Parties to the GPA have met their commitments under Article XIX: 5, with almost half of the membership not making this information available, either at all or consistently over time. In the absence of any enforcement mechanism related to data requirements or any punitive action/public censure for non-submission, Contracting Parties seem not to have taken their responsibilities in this regard very seriously. Submitting data on procurement is one of the best ways of ensuring transparency in public procurement and highlighting any break in trend in public purchase decisions that signals discrimination.
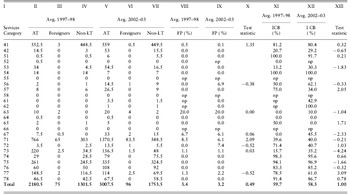
Japanese services contracts by number

Notes: (1) ‘np’ denotes no AT procurement. (2) Values exceeding 1.645 in columns X and XIII denote rejection of the null hypothesis (non-decline in foreign procurement and use of non-LT over time) at the 5% level of significance. (3) Data are averaged over 1997–98 and 2002–03.
Source: WTO (various years); own calculations.
One problem in making inter-temporal comparisons is that different procurement codes were applicable in different time periods and these necessitated different data requirements. For instance, the Tokyo Round procurement code did not require data to be reported on the value and number of contracts awarded under derogations to the GPA. Furthermore, prior to the Uruguay Round procurement code, the scope of the GPA was limited to goods alone and to those services that were incidental to the procurement of such goods. With the Uruguay Round, the scope of the GPA was expanded to explicitly incorporate services (including construction services) and as such, data from before 1996 refer to goods alone while those post-1996 involve both goods and services. This imposes an additional challenge in the analysis of services procurement.Footnote 6
3. Methodology
The GPA promises two major potential benefits for its signatories: the transparency requirements and the competition the GPA induces result in the public receiving better value for money on government procurement activities, and the increase in exports resultant from improved market access offers the prospect of greater profits for foreign supplying firms. In what follows, we examine whether market access has actually increased by undertaking an economic analysis of the statistical submissions. The methodology compares actual outcomes against two counterfactuals, one against time and the other against the private sector.
For the purpose of these counterfactuals, we define the following metrics:
• the value of above-threshold (AT) contracts as a proportion of all contracts,
• the value of contracts awarded to foreigners (FP) as a proportion of total above-threshold contracts,
• the value of contracts awarded using non-limited tendering (non-LT) methods as a proportion of total above-threshold contracts.Footnote 7
These metrics give an idea of how governments might be using their procurement practices to restrict market access. Governments can, for instance, split contracts to keep them below GPA thresholds and this would be reflected in the declining share of AT contracts in total procurement. Governments may also choose to award fewer contracts to foreign suppliers or to award them mostly by limited tendering methods, which would limit the size of procurement open to international competition. Thus, the value of contracts above threshold awarded using non-LT methods would serve as a measure of international competition in procurement or an indicator of the volume of procurement subject to ICB. This would be a measure of the potential openness in procurement markets. On the other hand, the value of above-threshold contracts actually awarded to foreigners would measure the actual extent of foreign procurement (FP) and reflect the de facto openness in procurement markets.
To develop the counterfactual against time, we calculate the potential value of contracts in period ‘t’ by multiplying the actual value of contracts in period ‘t’ by a metric in period ‘t – 1’. If the metric in period ‘t – 1’ was greater than that in period ‘t,’ which would be the case with metrics that declined over time, the potential value would exceed the actual value and the difference can be read as the unrealized market access associated with that metric.
We thus define
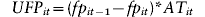
where
UFP it=unrealized foreign market access in the ‘ith’ service category in year ‘t’,
fp it–1=share of foreign procurement in above-threshold procurement in the ‘ith’ service category in year ‘t – 1’ and similarly for year ‘t’,
ATit=value of above-threshold procurement in the ‘ith’ service category in year ‘t’,
and
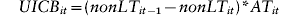
where
UICB it=unrealized internationally competitive bidding in the ‘ith’ service category in year ‘t’,
nonLT it–1=share of non-limited tender contracts by value in above-threshold procurement in the ‘ith’ service category in year ‘t – 1’ and similarly for year ‘t’,
AT it=value of above-threshold procurement in the ‘ith’ service category in year ‘t’.
An implicit assumption in this methodology is with respect to the choice of the base period. Given that our methodology attempts to carry out an ex-post impact assessment of the GPA in terms of market access, the base period should ideally pre-date the coming into effect of the GPA. However, since the data coverage of services in the GPA began only with the URGPA, the second best alternative is to consider as base a period just after the URGPA came into effect, as market access in this initial period is unlikely to be affected by the disciplining mechanisms of the GPA. The use of our methodology is thus based on the premise that by the later years of our sample period, the disciplining mechanisms of the GPA would have had time to have a positive impact on market access in services procurement.
A limitation of this methodology, however, is that it assumes constant all other factors that may be responsible for a change in the metrics. A change in domestic or foreign production structures, for instance, could lead to a re-orientation towards domestic suppliers. The change could also be dictated by macroeconomic factors such as a recession or by reasons of political economy, such as governments being in an election cycle. If we could actually hold all these other factors constant, procurement would be characterized by declining metrics over time only if governments chose to restrict market access on purpose. Since we cannot make such corrections, however, our results must be considered as more suggestive than conclusive. This said, as we shall see below, the deviations from counterfactuals in our analyses are large enough in magnitude to suggest quite strongly that the disciplines of the GPA have not been a binding force in ensuring non-discrimination in the award of services contracts.
Another way of illustrating any home-bias in government procurement is by comparing import intensities in the public and private sectors for the same services categories. The theoretical justification for this comparison is provided by Baldwin (Reference Baldwin1970, Reference Baldwin, Jones and Kenen1984) who shows that in a Hecksher−Ohlin model with a home-bias in government procurement, the reduction in imports from the government is compensated by a corresponding increase in the imports of the private sector.Footnote 8 For the second counterfactual, therefore, the comparator used is the private sector and the intuition involves simulating the effect of private-sector importing practices in public purchase decisions. Given that private-sector efficiency is a benchmark for most governments, such a comparison is perfectly appropriate.
While constructing this counterfactual, we assume that all other variables that have a bearing on public and private purchase decisions remain constant or affect these decisions identically. We simulate the effect of private-sector decision-making in public procurement decisions by using private-sector import intensities in the share of total government procurement in each service category which is above-threshold and, hence, potentially subject to ICB. This provides an estimate of the ‘foreign procurement’ in each service category which would have been ‘undertaken’ by the private sector had it been making government procuring decisions. From this we subtract the actual value of the foreign procurement undertaken by the government in each service category to get a differential, which is termed as the Private–Public Purchase Differential (PPPD).
We thus define
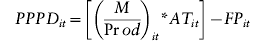
where
PPPD it=private–public purchase differential in the ‘ith’ service category in year ‘t’,
(M/Prod)it=ratio of imports to gross output in the ‘ith’ service category in year ‘t’,
AT it=value of above-threshold procurement in the ‘ith’ service category in year ‘t’,
FP it=value of foreign procurement in the ‘ith’ service category in year ‘t’.
A positive PPPD indicates that if the public sector had applied the private-sector import share in that service category, foreign procurement would have exceeded actual levels in it, which suggests a home-bias in government procurement.
4. Analyses of country services procurement patterns
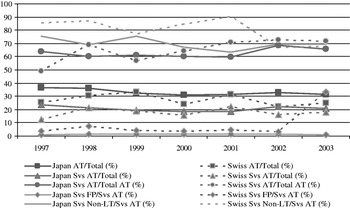
Figure 1 provides a snapshot of the procurement patterns in Japan and Switzerland over the period 1997–2003. The AT/Total (above- and below-threshold) procurement shares are low in both countries (averaging 33% in Japan and 27.5% in Switzerland), which, prima facie, constricts the contestable procurement market in both countries. While these shares have fallen over time in Japan, Switzerland shows more fluctuations and a virtual reversion in 2003 to the 1997 share. Focusing on services procured above threshold, these average more than 60% of total AT procurement in both countries and these shares have also risen over time. However, as a share of total above- and below-threshold procurement, the shares of services procured above threshold are much lower in both countries and less than 20% in the case of Switzerland. The shares of non-LT in AT services procurement have been high in both countries, averaging 70% in Japan and 80% in Switzerland, but these have also fallen over time in both countries, considerably in the case of Switzerland from 86% to 68%. Thus, for both these countries, prima facie, the share of the market open to unimpeded international competition has shrunk. The share of foreign procurement in AT services procurement has been very low in Japan, averaging 1.4% over 1997–2003, and relatively higher in Switzerland with an average of 4.4% over 1997–2002, without showing huge fluctuations around this mean. However, the Swiss share jumped to 33.4% in 2003 as several high value contracts were awarded to foreign firms in technical, scientific, and consulting services (category 14), a single category that accounts for more than half of all services procured above-threshold by Switzerland. In fact, if we exclude this category, then the share of foreign procurement in services purchased by Swiss central government entities would be close to the 4.4% mean again. Unfortunately, 2003 is the last year for which data on government procurement are available in the case of Switzerland and it is therefore not possible to know whether or not they signal a change in the trend of Swiss services procurement. We therefore regard the year as an outlier and omit it from our statistical analyses of Swiss services procurement.
A snapshot of country procurement patterns

4.1 Japanese services procurement
We begin by looking at Japanese submissions on services procurement averaged over 1997–98 and 2002–03 and compare both the percentage number and value of contracts awarded to foreign firms as well as those awarded using non-LT methods during these periods in Tables 1 and Table 2. We consider all services, including construction, included by Japan in Annexes 4 and 5 of Appendix 1 of the GPA; the list is provided in Annex Table 2 of this paper.
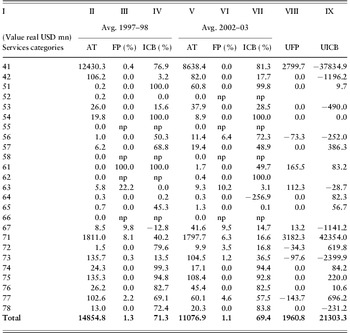
Japanese services contracts by value

Notes: (1) ‘np’ denotes no AT procurement. (2) Categories 41 and 71 reported large-value contracts. (3) Data are averaged over 1997–98 and 2002–03. (4) Contract values in SDR converted to real US dollar using the SDR-USD exchange rate and the US GDP Implicit Price Deflator.
Source: WTO (various years); own calculations.
Table 1 reports for 1997–98 and for 2002–03 the average number of services contracts that were awarded above-the-threshold, the number of these contracts that were awarded to foreign bidders, and the number of above-the-threshold contracts where limited tendering procedures were not used. Columns VIII and IX of this table report the proportion of contracts awarded to foreigners in 1997–98 and 2002–03, and columns XI and XII report the proportion of contracts awarded in the same years without resort to limited tendering procedures. Finally, columns X and XIII, respectively, report the results from statistically testing for each service category if the proportion of contracts awarded to foreigners in 1997–98 was the same as that in 2002–03 and if the proportion of above-the-threshold contracts that did not involve the use of limited tendering in 1997–98 was the same as that in 2002–03.Footnote 9
In 1997–98, there were, on average, 2,180.5 services contracts awarded above the threshold, of which 3.4% were awarded to foreign firms. Sixty per cent of these contracts did not involve the use of limited tendering procedures. In 2002–03, the average number of contracts had risen to 3,007.5, the percentage awarded to foreigners had fallen marginally to 3.2%, and the percentage of these contracts that did not employ limited tendering was lower at 58%. Ceteris paribus, these findings are not indicative of greater foreign access to Japanese services procurement. However, the test statistic in the bottom line of Table 1 under column X takes the value of 0.49, thereby failing to reject the hypothesis that the true probability of a contract being awarded to a foreign firm was no lower in 2002–03 than in 1997–98. Having said that, column X of Table 1 reveals that categories 41 (construction services) and 71 (computer-related services) saw statistically significant reductions in the proportion of contracts awarded to foreign firms (at the 10% and 5% levels of significance, respectively) and these categories accounted for 64.2% of all services contracts awarded by number and 94.2% of all services contracts awarded by value during 2002–03.
To examine the proposition that foreign access may have been unrealized more in larger-value services, we recalculated the test statistic by weighting contracts by their value in calculating the test statistics. The results from this recalculation suggested a statistically significant reduction in access to foreign suppliers only in the case of computer-related services.
The final column of Table 1 reports the test statistic for the maximum proportion of purchases in each services category that are subject to internationally competitive bidding and as with foreign share in procurement, the finding in the bottom row does not support the contention that the proportion of above-threshold procurement contracts subject to internationally competitive bidding fell over time. However, once again, individual categories suggest such reductions as in the case of freight transport (57), enhanced fax (65), and repair services (77), all statistically significant at 5%. On the other hand, the value of the test statistic in column XIII also suggests that the proportion of above-threshold procurement contracts subject to internationally competitive bidding actually increased over time in the case of other land transport (53), on-line information and/or data processing (67), advertising (73), and building cleaning services (75).
To look at the role of larger-value services, we again recalculated the test statistic by weighting contracts by value. The results from this recalculation suggested a statistically significant reduction in internationally competitive bidding for services on the whole (significant at 10%) as well as for the individual categories of enhanced fax (65), computer-related (71), market-research (72), and repair services (77). Thus, both potential and actual foreign access to the Japanese government procurement market may have been unrealized more in larger-value services.
Looking next at contract values (averaged over 1997–98 and 2002–03 and expressed in real terms using the US GDP Implicit Price Deflator) in Table 2, we see that Japanese services procurement fell by roughly 25% from USD 14.8 bn to USD 11 bn over 1997–98 and 2002–03. The share of foreign procurement dropped from 1.3 to 1.1%, while the use of non-LT fell from 71.3 to 69.4%. Construction, followed by computer-related services, dominates services procurement in Japan, together accounting for 95% of all services contracts in value, but the average above-threshold values for both these services fell over time. Further, fewer of these services were awarded to foreign suppliers in 2002–03 than in 1997–98. On the other hand, the use of non-LT increased slightly in the case of construction services, but declined sharply for computer-related services, suggesting a net constriction in the market open to international competition.
These declining metrics together translate into an unrealized foreign market access of USD 1.96 bn and an unrealized internationally competitive bidding worth USD 21.3 bn (reported in columns VIII and IX of Table 2). These are very large amounts – for instance, had the shares of foreigner-won and non-LT-awarded contracts in above-threshold contracts by value not declined over time, foreign services procurement in 2002–03 would have been more than 15 times higher (ratio of total UFP to total actual FP in 2002–03) and the value of contracts open to ICB would have been almost three times larger (ratio of total UICB to total actual ICB in 2002–03).
4.2 Swiss services procurement
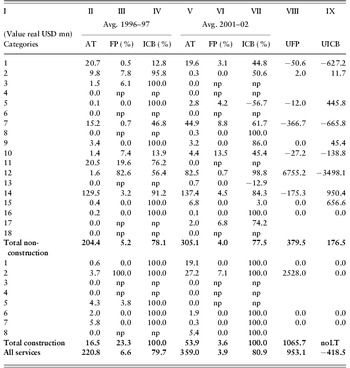
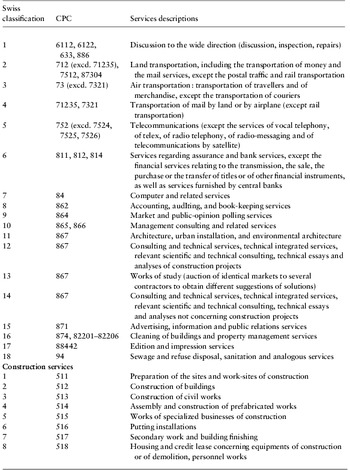
In the case of Switzerland, considering the year 2003 to be a statistical outlier, we conduct analogous analyses comparing Swiss submissions on services procurement averaged over 1996–97 and 2001–02. Data on Swiss contracts numbers are reported in Table 3 and on contracts value in Table 4. We consider both non-construction (categories 1–18) and construction (categories 1–8) services included by Switzerland in Annexes 4 and 5 of Appendix 1 of the GPA; the list is provided in Annex Table 3 of this paper.
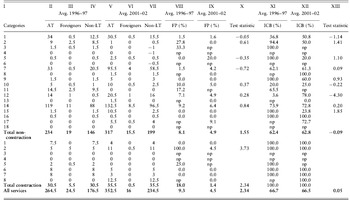
Swiss services contracts by number

Notes: (1) ‘np’ denotes no AT procurement. (2) Values exceeding 1.645 in columns X and XIII denote rejection of the null hypothesis (non-decline in foreign procurement and use of non-LT over time) at the 5% level of significance. (3) Data are averaged over 1996–97 and 2001–02.
Source: WTO (various years); own calculations.
Swiss services contracts by value

Notes: (1) ‘np’ denotes no AT procurement and ‘no LT’ denotes non-use of limited tendering. (2) Categories 1, 7, 12, and 14 among non-construction and categories 1and 2 among construction services reported large-value contracts. (3) Data are averaged over 1996–97 and 2001–02. (4) Contract values in SDR converted to real US dollar using the SDR-USD exchange rate and the US GDP Implicit Price Deflator.
Source: WTO (various years); own calculations.
From Table 3 we see that in 1996–97, there were 264.5 services contracts awarded on average by the Swiss above threshold, of which 9.3% were awarded to foreign firms. Of these contracts, 66.7% did not involve the use of limited tendering procedures. In 2001–02, the average number of contracts had risen to 352.5, but the percentage awarded to foreigners had fallen to 4.5%, and the percentage of these contracts that did not employ limited tendering was also marginally lower at 66.5%. Ceteris paribus, therefore, a la Japan, these findings are not indicative of greater foreign access to Swiss services procurement.
Supporting this contention, the test statistic in the bottom line under column X of Table 3 takes the value of 2.34, suggesting that the true proportion of contracts awarded to foreign firms was lower in 2001–02 than in 1996–97. (The same result holds true for total construction and total non-constructions services; the latter significant at 10%.) On the other hand, the test statistic in the bottom line of column XIII does not point to statistically significant reductions in the proportion of above-threshold contacts awarded using non-LT methods, though categories 2 (land transport) and 15 (advertising) do actually suggest such reductions (at the 10% and 5% levels of significance, respectively).
The results from this analysis survive the recalculation of the test statistics to examine the role of the larger-value services in the evolution of actual and potential foreign access over time, which suggests that the home-bias in Swiss government procurement was no more in large-value services than in small-value ones.
In terms of contract values reported in Table 4 (averaged over 1996–97 and 2001–02 and expressed in real terms using the US GDP Implicit Price Deflator), average Swiss services procurement (excluding that in construction) rose by nearly half from USD 204 mn to USD 305 mn over 1996–97 and 2001–02, while construction services witnessed a more than three-fold increase from USD 16.5 mn to USD 53.9 mn. Within non-construction services, the share of foreign procurement in services fell from 5.2% to 4%, while the use of non-LT fell marginally from 78% to 77.5%. Construction services, driven primarily by general building construction work (category 2), witnessed a huge fall in foreign procurement from 23.3% to 3.6%. Data also suggest that the Swiss government did not resort to limited tendering practices in the award of construction services contracts. On the whole, the share of foreign procurement in services fell from 6.6% to 3.9%, while the use of non-LT increased from 80% to 81%. Technical, scientific, and consulting services (categories 12 and 14), followed by computer-related (category 7) and construction and repair services (category 1) dominate Swiss services procurement, accounting for more than 90% of all services contracts in value terms, and barring repair services (category 1) the average above-threshold procurement for the other major categories increased over time. The foreign procurement share in these services fell sharply for technical, scientific, and consulting (category 12) and construction services, while the use of non-LT fell in the case of technical, scientific, and consulting services (category 14).
The results from counterfactual analysis in the case of Swiss services procurement, reported in columns VIII and IX of Table 4, translate into an unrealized foreign market access of USD 953 mn, a value that is proportionately even larger than the comparable figure for Japan: had the shares of foreigner-won above-threshold contracts by value not declined over time, foreign services procurement in 2001–02 would have been nearly 68 times higher (ratio of total actual UFP to total actual FP in 2001–02)! On the other hand, UICB is −418.5 mn, which suggests that the de jure openness increased. However, this result emanates from the Swiss government's non-use of limited tendering in awarding construction services contracts. If we consider only non-construction services, UICB is USD 176.5 mn – the value of non-construction services contracts open to ICB would have been 75% more (ratio of total actual UICB in non-construction to total actual ICB in non-construction in 2001–02) had the use of non-LT in these services not declined over 1996–97, 2001–02.
4.3 Private–public purchase differentials
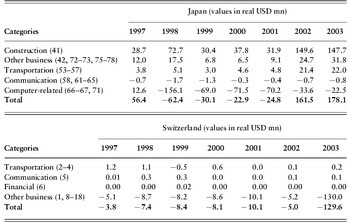
Finally, results from the counterfactual analysis against the private sector for both Japan and Switzerland are reported in Table 5. Data on sectoral output and imports for the two countries are taken from the OECD's STAN database for structural analysis and trade in services by service category, respectively. Unfortunately, sector-specific data on imports and gross output are not available for all services categories; hence, the individual services categories for the two countries have been aggregated into broader categories (the composition is shown in brackets against each category in Table 5) to enable better analysis. Even then, the absence of import data for Swiss construction and computer-related services over our sample period meant that the counterfactuals even for these broad categories could not be calculated in the case of Switzerland.
Private–public purchase differentials

Notes: (1) Import data were not available for construction and computer-related services in the case of Switzerland; hence, the counterfactuals are missing for these categories. (2) Financial services are not included by Japan in Annexes 4 and 5 of Appendix 1 of the GPA. (3) The numbers in brackets against each broad category indicate the individual services categories listed in Annex Tables 2 and 3 that were aggregated to form that broad category.
Source: WTO (various years); OECD (various years); own calculations.
Table 5 reveals that Japanese services in these categories, especially construction, have seen large private–public purchase differentials over time, a finding that is consistent with Baldwin's (Reference Baldwin1970, Reference Baldwin, Jones and Kenen1984) ‘neutrality proposition’ and the home-bias in Japanese services procurement. The differential for total services was a positive USD 56.4 mn in 1997, but became negative in the next four years on account of rising public purchase of computer-related services from foreign suppliers, a category which therefore showed negative differentials from 1998 to 2003. The differentials were always positive in the case of construction, other business, and transportation services and also showed huge increases in these categories in 2002 and 2003, which offset the negative differential in computer-related services during these years to yield a positive differential for services on the whole. Moreover, the magnitude of the differential itself increased three-fold from 1997 to 2003. Thus, had the private-sector propensity to import been applied to government procurement decisions in these services, the foreign share of procurement would have been much higher. Communication services, on the other hand, always report a negative differential, which suggests that the Japanese government was not favouring domestic firms in this sector.
The absence of comparable data for a broader range of Swiss services renders a similar analysis less conclusive. Swiss services see a positive but declining differential for transportation services (suggesting reduced importance of the home-bias), effectively a zero differential for financial services (absence of above-threshold procurement) and a positive and nearly constant differential for communication services over 2000–03 (suggesting no change over time in the importance of the home-bias). The differential for other business services is always negative (suggesting no home-bias) but jumps to USD −130 mn in 2003, a result that supports the choice of this year as a statistical outlier in the case of Switzerland.
On the whole, the results from this counterfactual analysis suggest that at least the Japanese government has not been purchasing as much from abroad as its private sector is importing from the rest of the world for the same services categories. These results are thus consistent with those from the preceding analyses on the home-bias in Japanese services procurement patterns.
5. Conclusion
The results from the analyses undertaken in this paper suggest that the URGPA has not really been effective in increasing or even sustaining market access for foreigners in the procurement markets of two of its signatories – Japan and Switzerland. We have examined data from two of the 40 Contracting Parties to the GPA that have submitted detailed data in a form amenable to our statistical analysis; hence, the results are specific to these countries. The two cases, however, do point in the same direction, suggesting a home-bias in the award of government services contracts.
A careful reading of the results further suggests that this may be due to a combination of incomplete/ineffective provisions and a weak enforcement mechanism. For instance, despite the requirements of Article XIX:5, only half of the 40 Contracting Parties have submitted procurement data to the WTO consistently over time, which points to weak enforcement and, in turn, could be due to the absence of any punitive action or public censure for non-submission. From the two countries we have studied, there is enough argument for addressing the loopholes in the GPA (too many exclusions/exemptions allowed; non-price discrimination is allowed while more efficient price preferences are explicitly banned) and for giving it more teeth (public censure for non-adherence to data reporting commitments; provision of incentives to whistle-blowers revealing corruption in procurement). The WTO's Trade Policy Review Mechanism could also work through peer-pressure by highlighting non-compliance with Article XIX: 5 and/or pointing out distinct breaks in past patterns of public procurement that signal a move towards discrimination.
Finally, while the evidence of discrimination reported above may be more suggestive than definitive, the fact that the GPA did not increase ex-post foreign market access in services in these two governments' public purchases is undeniable. Furthermore, if this result were repeated in all countries, it must then reflect home biases in government procurement, because not every country can increase its domestic efficiency relative to its partners. In examining actual trade data relative to counterfactuals, the analysis in this paper is similar to analyses examining the residuals from gravity models to illustrate protection in goods markets. From that perspective at least, our results do quite strongly suggest discrimination against foreign suppliers in the government procurement markets for services in the two countries studied and that the GPA may not be having the strong effects that many hoped for.
Statistical submissions made to the Committee on Government Procurement

Source: WTO (various years).

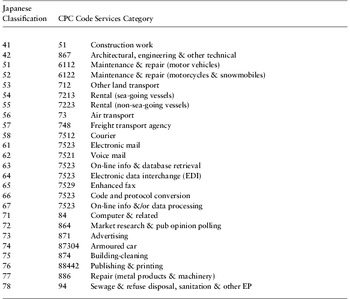
List of services procured by the Swiss

Note: The table has been translated into English from French.
Source: WTO (various years); UNSC (2002).