



1. Introduction and main results
Strong andweak convergence of numerical schemes for stochastic differential equations (SDEs) with regular coefficients have enjoyed considerable investigation; see the monographs available, e.g. [Reference Kloeden and Platen12]. As we know, (forward) Euler–Maruyama (EM) is the simplest algorithm to discretize SDEs whose coefficients are of linear growth. However, an EM scheme is invalid once the coefficients of the SDEs involved are of nonlinear growth; see e.g. [Reference Hutzenthaler, Jentzen and Kloeden10] for some illustrative counterexamples. Hence other variants of the EM scheme were designed to treat SDEs with non-global Lipschitz conditions; see [Reference Higham, Mao and Stuart7] and [Reference Higham, Mao and Yuan8] for the backward EM scheme, [Reference Dareiotis, Kumar and Sabanis2] and [Reference Hutzenthaler, Jentzen and Kloeden11] for the tamed EM algorithm, and [Reference Mao18] concerning the truncated EM method, to name a few. Today the convergence analysis of numerical algorithms for SDEs with irregular coefficients also receives a great deal of attention; see e.g. [Reference Gyöngy and Rásonyi5] for SDEs with Hölder-continuous diffusions via the Yamada–Watanabe approximation approach, [Reference Yan31] for SDEs whose drift terms are Hölder-continuous with the aid of the Meyer–Tanaka formula and estimates on local times, and [Reference Bao, Huang and Yuan1] and [Reference Pamen and Taguchi24] for SDEs whose drifts are Hölder(–Dini)-continuous by regularities of the corresponding backward Kolmogorov equations. In the past few years, numerical approximations of SDEs with discontinuous drifts have also gained a lot of interest; see e.g. [Reference Halidias and Kloeden6], [Reference Leobacher and Szölgyenyi16], [Reference Leobacher and Szölgyenyi17], [Reference Müller-Gronbach and Yaroslavtseva20], and [Reference Neuenkirch, Szölgyenyi and Szpruch21]. Until now, most of the existing literature on strong approximations of SDEs with discontinuous drift coefficients have been implemented under the additional assumption that the drift term is piecewise Lipschitz-continuous.
Since the pioneering work of Zvonkin [Reference Zvonkin34], the well-posedness of SDEs with irregular coefficients has made great progress in several ways; see e.g. [Reference Flandoli, Gubinelli and Priola3], [Reference Gyöngy and Martinez4], [Reference Krylov and Röckner14], [Reference Xie and Zhang30], and [Reference Zhang32] for SDEs driven by Brownian motions or jump processes, and [Reference Huang and Wang9] and [Reference Röckner and Zhang25] for McKean–Vlasov (or distribution-dependent or mean-field) SDEs. There also exist a number of works on numerical simulation of SDEs with low regularity. In particular, [Reference Ngo and Taguchi22] is concerned with the strong convergence rate of the EM scheme for SDEs with irregular coefficients, where the one-sided Lipschitz condition is imposed on the drift term. Subsequently, the one-sided Lipschitz condition applied in [Reference Ngo and Taguchi22] was dropped in [Reference Ngo and Taguchi23], whereas one-dimensional SDEs are barely affected. At this point, our goal in this paper has been evident. More precisely, motivated by the previous literature, we aim to investigate the convergence rate of EM for multidimensional SDEs with low regularity, where the drift terms need not be piecewise Lipschitz-continuous; see e.g. [Reference Halidias and Kloeden6], [Reference Leobacher and Szölgyenyi16], [Reference Leobacher and Szölgyenyi17], [Reference Müller-Gronbach and Yaroslavtseva20], and [Reference Neuenkirch, Szölgyenyi and Szpruch21].
Now we consider the following SDE:
 \begin{equation} {\text{d}} X_{t}=b(X_t)\,{\text{d}} t+\sigma(X_t)\,{\text{d}} W_{t}, \quad t\ge 0,\ X_{0}=x\in\mathbb{R}^d,\end{equation}
where
 $b\colon \mathbb{R}^d\rightarrow\mathbb{R}^d$
,
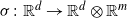 $\sigma\colon \mathbb{R}^d\rightarrow\mathbb{R}^d\otimes\mathbb{R}^m$
, and
 $(W_t)_{t\ge 0}$
is an m-dimensional Brownian motion on some filtered probability space
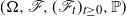 $(\Omega,\mathscr F,(\mathscr F_t)_{t\ge 0},\mathbb P)$
. For the drift b and the diffusion
 $\sigma$
, we assume the following.
-
(A1)
 $\|b\|_{\infty}\colon= \sup_{x\in\mathbb{R}^d}|b(x)|<\infty$
, and there exists a constant
$p>{{d}/{2}}$
such that
$|b|^2\in L^p(\mathbb{R}^d)$
, the usual
$L^p$
-space on
$\mathbb{R}^d$
.
-
(A2) There exist constants
$\gamma\ge 2$
,
$\alpha_\gamma>0,$
and a continuous decreasing function
$\phi_\gamma\colon (0,\infty)\rightarrow(0,\infty)$
with
$\int_0^l\phi_\gamma(s)\,{\text{d}} s<\infty$
for arbitrary
$l>0$
such that
\begin{equation*}\dfrac{1}{ s^{{{d}/{2}}}}\int_{\mathbb{R}^d}|b(x+y)-b(x+z)|^\gamma\text{{e}}^{-{{1}/{s}}|x|^2}{\text{d}} x\leq\phi_\gamma(s)|y-z|^{\alpha_\gamma},\quad y,z\in\mathbb{R}^d,\ s>0.\end{equation*}
-
(A3) There exist constants
$\breve{\lambda}_0,\hat\lambda_0,L_0>0$
such that (1.2)
\begin{align}&\breve{\lambda}_0|\xi|^2\le\langle (\sigma\sigma^*)(x)\xi,\xi\rangle \le\hat\lambda_0|\xi|^2,\quad x,\xi\in\mathbb{R}^d,\end{align}
(1.3)
\begin{align}&\|\sigma(x)-\sigma(y)\|_{\text{HS}} \le L_0|x-y|,\quad x,y\in\mathbb{R}^d,\end{align}
where
$\sigma^*$
means the transpose of
$\sigma$
and
$\|\cdot\|_{\text{HS}}$
stands for the Hilbert–Schmidt norm.
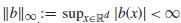


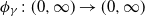
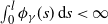


Below we make some comments on the assumptions (A2) and (A3).
Remark 1.1. If
 $\phi_\gamma$
is bounded, then we can replace
 $\phi_\gamma(s)$
in (A2) with
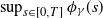 $\sup_{s\in [0,T]}\phi_\gamma(s)$
, which is automatically decreasing. Let
 \[\omega_{n,\delta }(\phi_\gamma)=\sup_{x,y\in [n\delta ,(n+1)\delta ]}|\phi_\gamma(x)-\phi_\gamma(y)|.\]
Instead of
 $\phi_\gamma$
decreasing, we can assume that
 $\phi_\gamma$
satisfies
 \begin{equation}\sup_{0<\delta \leq 1}\biggl(\delta \sum_{k=1}^{\lfloor T/\delta \rfloor}\omega_{k,\delta }(\phi_\gamma)\biggr)<+\infty.\end{equation}
Then, for any
 $\kappa_0>0$
,
 \begin{align*}\sum_{k=1}^{\lfloor T/\delta \rfloor}\phi_\gamma(\kappa_0 k\delta)\delta &\leq \sum_{k=1}^{\lfloor T/\delta \rfloor}\int_{k\delta }^{(k+1)\delta } \phi_\gamma(\kappa_0 t)\,{\text{d}} t+ \delta \sum_{k=1}^{\lfloor T/\delta \rfloor}\omega_{n,\delta }(\phi_\gamma(\kappa_0 \cdot))\\&\leq \kappa_0^{-1}\biggl(\int_0^{\kappa_0 T}\phi_{\gamma}(t)\,{\text{d}} t+\sup_{0<\delta \leq 1}\biggl(\delta \sum_{k=1}^{\lfloor T/\delta \rfloor}\omega_{n,\delta }(\phi_\gamma)\biggr)\biggr)\\&<\infty.\end{align*}
It is not easy to check (1.4) for
 $\phi_\gamma$
with
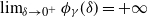 $\lim_{\delta \rightarrow 0^+} \phi_\gamma(\delta)=+\infty$
. However, if
 $\phi_\gamma$
is decreasing, then
 \begin{equation*}\sup_{0<\delta \leq 1}\biggl(\delta \sum_{k=1}^{\lfloor T/\delta \rfloor}\omega_{n,\delta }(\phi_\gamma)\biggr) =\sup_{0<\delta \leq 1}\biggl(\delta \sum_{k=1}^{\lfloor T/\delta \rfloor}(\phi_\gamma(k\delta)-\phi_\gamma((k+1)\delta))\biggr) = \delta \phi_{\gamma}(\delta).\end{equation*}
Hence, in this case, (1.4) holds if and only if there is
 $C>0$
such that
 $ \phi_{\gamma}(x)\leq {{C}/{x}}$
.
Remark 1.2. For
 $x\in\mathbb{R}^d$
, let
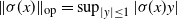 $\|\sigma(x)\|_{\text{op}}=\sup_{|y|\le1}|\sigma(x)y|$
, the operator norm of
 $\sigma(x)$
. By the Cauchy–Schwarz inequality, it follows from (1.2) that
 \begin{equation*}\|\sigma(x)\|_{\text{op}}^2\leq \sum_{i=1}^d\sup_{|y|\le 1}\langle y,\sigma(x)^*e_i\rangle ^2\le\|\sigma^*(x)\|_{\text{HS}}^2 = \sum_{i=1}^d\langle (\sigma\sigma^*)(x)e_i,e_i\rangle \le d\hat\lambda_0,\quad x\in\mathbb{R}^d,\end{equation*}
where
 $\{e_i\}_{i=1}^d$
is the orthogonal basis of
 $\mathbb{R}^d$
. Then we arrive at
 \begin{equation}\|\sigma(x)\|_{\text{op}}\le \|\sigma(x)\|_{\text{HS}}=\|\sigma^*(x)\|_{\text{HS}}\le \sqrt {d\hat\lambda_0},\quad x\in\mathbb{R}^d.\end{equation}
Under (A1) and (A3), (1.1) has a unique strong solution
 $(X_t)_{t\ge 0}$
; see e.g. [Reference Huang and Wang9, Lemma 3.1]. (A2) is imposed to reveal the convergence rate of the EM scheme corresponding to (1.1), which is defined as follows: for any
 $\delta \in(0,1), $
 \begin{equation}{\text{d}} X^{(\delta)}_t= b\left( X^{(\delta)}_{t_\delta }\right)\,{\text{d}} t+\sigma\left(X^{(\delta)}_{t_\delta }\right)\,{\text{d}} W_t, \quad t\ge 0,\ X^{(\delta)}_0=X_0 ,\end{equation}
with
 $t_\delta \colon= \lfloor t/\delta \rfloor\delta$
, where
 $\lfloor t/\delta \rfloor$
denotes the integer part of
 $t/\delta $
. We emphasize that
 $\left(X^{(\delta)}_{k\delta }\right)_{k\ge 0}$
is a homogeneous Markov process; see e.g. [Reference Mao and Yuan19, Theorem 6.14]. For
 $t\ge s$
and
 $x\in\mathbb{R}^d$
, let
 $p^{(\delta)}(s,t,x,\cdot)$
denote the transition density of
 $ X^{(\delta)}_t$
with starting point
 $X_s^{(\delta)}=x$
. Set
 \begin{align*}\mathscr{K}_1&\colon= \biggl\{(p,q)\in(1,\infty)\times(1,\infty)\colon \dfrac{d}{p}+\dfrac{2}{q}<2\biggr\},\quad \gamma_0\colon= \dfrac{1}{1-1/q-d/2p},\ (p,q)\in \mathscr{K}_1,\\\mathscr{K}_2&\colon= \biggl\{(p,q)\in(1,\infty)\times(1,\infty)\colon \dfrac{d}{p}+\dfrac{1}{q}<1\biggr\}.\end{align*}
Our first main result in this paper is stated as follows.
Theorem 1.1. Assume
 $({\bf A1})$
–
 $({\bf A3})$
. Then, for
 $\beta\in(0,\gamma)$
,
 $(p,q)\in \mathscr{K}$
, and
 $T>0$
, there exist constants
 $C_1,C_2>0$
independent of
 $\delta $
such that
 \begin{equation} \mathbb E\biggl(\sup_{0\le t\le T}\left|X_t-X_t^{(\delta)}\right|^\beta\biggr) \le C_1\exp \left(C_2 \left(1+\||b|^2\|_{ L^{p}}^{\gamma_0}\right)\right) \left(\delta ^{{{\beta}/{2}}}+\delta ^{ {{\alpha_\gamma\beta}/{(2\gamma)}} }\right).\end{equation}
Compared with [Reference Ngo and Taguchi22], in Theorem 1.1 we get rid of the one-sided Lipschitz condition for the drift coefficients. On the other hand, [Reference Ngo and Taguchi23] is extended to the multidimensional set-up. We point out that an
 $\mathcal {A}$
approximation is given in advance in [Reference Ngo and Taguchi22, Reference Ngo and Taguchi23] to approximate the drift term. So, in contrast to the assumption set in [Reference Ngo and Taguchi22, Reference Ngo and Taguchi23], assumption (A2) is much more explicit. On the other hand, by a close inspection of the argument of Lemma 2.2 below, assumption (A2) can indeed be replaced by the other alternatives. For instance, (A2) may be replaced by (A2′
) below.
-
(A2′ ) There exist constants
$\gamma\ge 2, \beta_\gamma,\theta_\gamma>0$
such that, for some constant
$C>0$
,
\begin{equation*}\dfrac{1}{(rs)^{d/2}}\sup_{z\in\mathbb{R}^d}\int_{\mathbb{R}^d\times\mathbb{R}^d}|b(x)-b(y)|^\gamma\text{{e}}^{-{{|x-z|^2}/{s}}}\text{{e}}^{-{{|y-x|^2}/{r}}}\,{\text{d}} y \,{\text{d}} x\le C r^{\theta_\gamma} s^{\beta_\gamma-1},\quad s,r>0.\end{equation*}
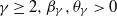


The drift b satisfying (A2′
) is said to be of the Gaussian–Besov class with index
 $(\beta_\gamma,\theta_\gamma)$
, written as
 $\text{GB}^\gamma_{\beta_\gamma,\theta_\gamma}(\mathbb{R}^d)$
. The index
 $\theta_\gamma$
is used to characterize the order of continuity and
 $\beta_\gamma$
is used to characterize the type of continuity. Note that functions with the same order of continuity may enjoy a different type of continuity; see e.g.
 $f(x)=|x|^{{1}/{2}}$
with
 $(1,\frac12)$
and
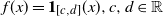 $f(x)={\bf1}_{[c,d]}(x),c,d\in\mathbb{R}$
, with
 $(\frac12,\frac12)$
. We refer to Example 4.2 below for the drift
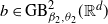 $b\in\text{GB}^2_{\beta_2,\theta_2}(\mathbb{R}^d)$
. For
 $\theta\in(0,1)$
and
 $p\ge 1$
, let
 $W^{\theta,p}(\mathbb{R}^d)$
be the fractional-order Sobolev space on
 $\mathbb{R}^d$
. Nevertheless,
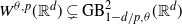 $ W^{\theta,p}(\mathbb{R}^d) \subsetneq \text{GB}^2_{1-{{d}/{p}},\theta}(\mathbb{R}^d)$
,
 $\theta>0$
,
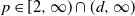 $p\in[2,\infty)\cap(d,\infty)$
; see Example 4.3 for more details. Furthermore, [Reference Suo, Yuan and Zhang29, Example 2.3] shows that the drift b constructed therein satisfies (A2′
) but need not be piecewise Lipschitz-continuous (see e.g. [Reference Leobacher and Szölgyenyi16] and [Reference Leobacher and Szölgyenyi17]).
In Theorem 1.1, the integrability condition (i.e.
 $|b|^2\in L^p(\mathbb{R}^d)$
) seems to be a little bit restrictive, which rules out some typical examples, e.g.
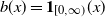 $b(x)={\bf1}_{[0,\infty)}(x)$
. Below, by implementing a truncation argument, the integrability condition can indeed be dropped. In such a set-up (i.e. without the integrability condition), we can still derive the convergence rate of the EM algorithm, which is presented below.
Theorem 1.2. Assume
 $({\bf A1})$
–
 $({\bf A3})$
without
 $|b|^2\in L^p\big(\mathbb{R}^d\big)$
. Then, for
 $\beta\in(0,2)$
,
 $(p,q)\in\mathscr{K}_2$
, and
 $T>0$
, there exist constants
 $C_1,C_2>0$
independent of
 $\delta $
such that
 \begin{align} &\mathbb E\biggl(\sup_{0\le t\le T}\left|X_{t}-X^{(\delta)}_t\right|^\beta\biggr)\notag \\ &\quad \leq C_1\biggl\{\exp\biggl(C_2\biggl(- \frac{\beta}{2}\biggl(1\wedge\frac{\alpha_\gamma}{\gamma}\biggr)\log\delta \biggr)^{{{d\gamma_0}/{(2p)}}}\biggr) +1\biggr\}\bigl(\delta ^{{{\beta}/{2}}}+\delta ^{ {{\alpha_\gamma\beta}/{(2\gamma)}} }\bigr).\end{align}
We remark that the right-hand side of (1.8) approaches zero since
 \begin{equation*} \lim_{\delta \rightarrow0} \exp\biggl(C_2\biggl(-\frac{\beta}{2}\biggl(1\wedge\frac{\alpha_\gamma}{\gamma}\biggr)\log\delta \biggr)^{{{d\gamma_0}/{(2p)}}}\biggr)\delta ^{\frac{\beta}{2}(1\wedge{({\alpha_\gamma}/{\gamma})})} =0\end{equation*}
due to the fact that
 \[\lim_{x\rightarrow\infty}\frac{\text{{e}}^{C_2x^{{{d\gamma_0}/{(2p)}}}}}{\text{{e}}^x} =0\]
whenever
 $(p,q)\in\mathscr{K}_2$
.
The remainder of this paper is organized as follows. In Section 2, by employing Zvonkin’s transform and establishing Krylov’s estimate and Khasminskii’s estimate for the EM algorithm, which is based on a Gaussian-type heat kernel estimate, we complete the proof of Theorem 1.1. In Section 3 we aim to finish the proof of Theorem 1.2 by adopting a truncation argument. In Section 4 we provide some illustrative examples to demonstrate our theory. In the Appendix we show explicit upper bounds of the parameters associated with Gaussian heat kernel estimates concerned with the exact solution and the EM scheme.
2. Proof of Theorem 1.1
Before finishing the proof of Theorem 1.1, we prepare several auxiliary lemmas. Set
 \begin{align}\Lambda_1&\colon= 2\biggl\{\dfrac{\|b\|_\infty}{ \sqrt {\breve{\lambda}_0}}+2\sqrt {d}L_0\left(\hat\lambda_0/\breve{\lambda}_0\right)^{2} + d^{{{d}/{2}}+1}d!\left(\hat\lambda_0/\breve{\lambda}_0\right)^{d} L_0\biggr\}\exp\biggl(\frac{\|b\|_\infty^2T}{\hat\lambda_0}\biggr)\notag \\[3pt]&\quad\,\,\vee\Bigl\{ 2\sqrt {\hat\lambda_0} \|b\|_\infty+(\|b\|_\infty^2+2\hat\lambda_0L_0\sqrt d)(\sqrt d+2) +2^{m+11}\breve{\lambda}_0^{-1}(L_0+2\|b\|_\infty)\notag \\[3pt]&\quad\,\,\times( \|b\|_\infty^3+(d\hat\lambda_0)^{{{3}/{2}}} +\breve{\lambda}_0^{{{1}/{2}}}(\|b\|_\infty^2 +d\hat\lambda_0)) \Bigr\}\dfrac{2^{{{(d+1)}/{2}}}}{\breve{\lambda}_0}\exp\biggl(\frac{(\|b\|_\infty +\|b\|_\infty^2)T}{\hat\lambda_0}\biggr)\end{align}
and
 \begin{equation} \Lambda_2\colon= \exp\biggl(\frac{\|b\|_\infty T}{2\hat\lambda_0}\biggr)\sum_{i=0}^{\infty}\dfrac{(\Lambda_1\sqrt {\pi T} ((1+24d)\hat\lambda_0/\breve{\lambda}_0)^d)^i}{\Gamma(1+{{i}/{2}})},\end{equation}
where
 $\Gamma({\cdot})$
denotes the gamma function. Due to Stirling’s formula,
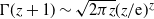 $\Gamma(z+1)\sim\sqrt {2\pi z}(z/\text{{e}})^z$
, we have
 $\Lambda_2<\infty$
.
The lemma below provides an explicit upper bound of the transition kernel for
 $\left(X_t^{(\delta)}\right)_{t\ge 0}$
.
Lemma 2.1. Under
 $({\bf A1})$
and
 $({\bf A3})$
,
 \begin{equation}p^{(\delta)}(j\delta ,t,x,y)\le \dfrac{\Lambda_3\exp\bigl(-\frac{|y-x|^2}{\kappa_0(t-j\delta)}\bigr)}{(2\pi\breve{\lambda}_0(t-j\delta))^{d/2}},\quad x,y\in\mathbb{R}^d,\ t> j\delta ,\ \delta \in(0,1),\end{equation}
where
 \begin{equation}\kappa_0\colon= 4(1+24d)\hat\lambda_0,\quad \Lambda_3\colon= \Lambda_2\exp\biggl(\frac{\|b\|_\infty^2}{2\hat\lambda_0}\biggr)\biggl(\dfrac{\kappa_0}{2\breve{\lambda}_0}\biggr)^{d/2}.\end{equation}
Proof. For fixed
 $t>0$
there is an integer
 $k\ge 0$
such that
 $[k\delta ,(k+1)\delta)$
. By a direct calculation, it follows from (1.2) and (1.3) that
 \begin{equation}p^{(\delta)}(k\delta ,t,x,y)\le\dfrac{\exp\left(-\frac{\left|y-x-b(x)\left(t-k\delta\right)\right|^2}{2\hat\lambda_0\left(t-k\delta\right)}\right)}{(2\pi\breve{\lambda}_0)(t-k\delta)^{d/2}}\le\exp\biggl(\frac{\|b\|_\infty^2}{2\hat\lambda_0}\biggr)\dfrac{\exp\left(-\frac{|y-x|^2}{4\hat\lambda_0(t-k\delta)}\right)}{(2\pi\breve{\lambda}_0(t-k\delta))^{d/2}},\end{equation}
where in the second inequality we used the basic inequality
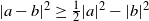 $|a-b|^2\ge \frac{1}{2}|a|^2-|b|^2$
,
 $a,b\in\mathbb{R}^d$
. Next, by invoking Lemma A.2 below, we have
 \begin{equation}p^{(\delta)}(j\delta,j'\delta,x,x')\le\dfrac{\Lambda_2\exp\bigl(-\frac{|x'-x|^2}{\kappa_0(j'\delta-j\delta)}\bigr)}{(2\pi\breve{\lambda}_0(j'\delta-j\delta))^{d/2}},\quad j'>j,~x,x'\in\mathbb R^d,\end{equation}
where
 $\Lambda_2,\kappa_0$
were given in (2.2) and (2.4),respectively. Subsequently, (2.3) follows immediately by taking advantage of the Chapman–Kolmogorov equation
 \begin{equation*}p^{(\delta)}(j\delta ,t,x,y)=\int_{\mathbb{R}^d}p^{(\delta)}(j\delta ,\lfloor t/\delta \rfloor\delta ,x,u)p^{(\delta)}(\lfloor t/\delta \rfloor\delta ,t,u,y)\,{\text{d}} u,\end{equation*}
and the fact that
 \begin{equation*}\int_{\mathbb{R}^d}\dfrac{\exp\left(-\frac{\left| u-x\right|^2}{\kappa_0(k\delta -j\delta)}\right)}{(2\pi\breve{\lambda}_0(k\delta -j\delta))^{d/2}}\dfrac{\exp\left(-\frac{|y-u|^2}{4\hat\lambda_0(t-k\delta)}\right)}{(2\pi\breve{\lambda}_0(t-k\delta))^{d/2}}\,{\text{d}}u\le\biggl(\dfrac{\kappa_0}{2\breve{\lambda}_0}\biggr)^{d/2} \dfrac{\exp\left(-\frac{|y-x|^2}{\kappa_0\left(t-j\right)}\right)}{(2 \pi\breve{\lambda}_0(t-j\delta))^{d/2}},\quad k>j.\end{equation*}
Lemma 2.2. Under
 $({\bf A1})$
–
 $({\bf A3})$
, for any
 $T>0$
, there exists a constant
 $C>0 $
such that
 \begin{equation}\int_0^T\mathbb{E}\left|b\left(X^{(\delta)}_t\right)-b\left(X^{(\delta)}_{t_\delta }\right)\right|^\gamma\,{\text{d}} t\leq C\delta ^{1\wedge{({\alpha_\gamma}/{2})}}, \end{equation}
where
 $\alpha>0$
was introduced in
 $({\bf A2})$
.
Proof. Observe that
 \begin{align*}\int_0^T\mathbb{E}\left|b\left(X^{(\delta)}_t\right)-b\left(X^{(\delta)}_{t_\delta }\right)\right|^\gamma\,{\text{d}}t&=\int_0^\delta \mathbb{E}\left|b\left(X^{(\delta)}_t\right)-b\left(X^{(\delta)}_0\right)\right|^\gamma\,{\text{d}}t\\&\quad\, +\sum_{k=1}^{\lfloor T/\delta \rfloor}\int_{k\delta }^{T\wedge(k+1)\delta }\mathbb{E}\left|b\left(X^{(\delta)}_t\right)-b\left(X^{(\delta)}_{k\delta }\right)\right|^\gamma\,{\text{d}}t.\end{align*}
By
 $\|b\|_\infty<\infty$
due to (A1), it follows that
 \begin{equation}\int_0^\delta \mathbb{E}\left|b\left(X^{(\delta)}_t\right)-b\left(X^{(\delta)}_0\right)\right|^\gamma\,{\text{d}} t\le2^\gamma\|b\|_\infty^\gamma\delta .\end{equation}
For
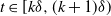 $t\in[k\delta ,(k+1)\delta)$
, by taking the mutual independence between
 $X^{(\delta)}_{k\delta }$
and
 $W_t-W_{k\delta }$
into account and employing Lemma 2.1, we derive that
 \begin{align} &\mathbb{E}\left|b\left(X^{(\delta)}_t\right)-b\left(X^{(\delta)}_{k\delta }\right)\right|^\gamma \notag \\[3pt] &\quad =\mathbb E\left|b\left(X^{(\delta)}_{k\delta }+b\left(X^{(\delta)}_{k\delta }\right)(t-k\delta)+\sigma\left(X^{(\delta)}_{k\delta }\right)\left(W_t-W_{k\delta }\right)\right)-b\left(X^{(\delta)}_{k\delta }\right)\right|^\gamma \notag \\[3pt] &\quad =\int_{\mathbb{R}^d}\int_{\mathbb{R}^d}|b(y+z)-b(y)|^\gamma p^{(\delta)}(0,k\delta ,x,y) \notag \\[3pt] &\quad\quad\, \times\dfrac{\exp\bigl({-\frac{1}{2}(t-k\delta)^{-1}}\langle (\sigma^*\sigma)^{-1}(y)(z-b(y)(t-k\delta)),z-b(y)(t-k\delta)\rangle \bigr)}{\sqrt {(2\pi)^d\mbox{det}((t-k\delta)(\sigma\sigma^*)(y))}}\,{\text{d}} y\,{\text{d}} z \notag \\[3pt] &\quad \le \dfrac{C_1}{(k\delta (t-k\delta))^{d/2}} \int_{\mathbb{R}^d}\int_{\mathbb{R}^d}|b(y+z)-b(y)|^\gamma\exp\biggl(-\frac{|z|^2}{4\hat\lambda_0(t-k\delta)}\biggr) \exp\biggl({-\frac{|x-y|^2}{\kappa_0k\delta }}\biggr)\,{\text{d}} y\,{\text{d}} z\end{align}
for some constant
 $C_1>0$
, where
 $\kappa_0$
was given in (2.4). With the aid of the fact that
 \begin{equation}\sup_{x\ge 0}\left(x^\gamma\text{{e}}^{-\beta x^2}\right)=\biggl(\dfrac{\gamma}{2\text{{e}}\beta}\biggr)^{{{\gamma}/{2}}},\quad \gamma,\beta>0,\end{equation}
we infer from (A2) and (2.9) that
 \begin{align*}\mathbb{E}\left|b\left(X^{(\delta)}_t\right)-b\left(X^{(\delta)}_{k\delta }\right)\right|^2&\le\dfrac{ C_2\phi_\gamma(\kappa_0k\delta)}{(t-k\delta)^{d/2}}\int_{\mathbb{R}^d}|z|^{\alpha_\gamma}\exp\biggl({-\frac{|z|^2}{4\hat\lambda_0(t-k\delta)}}\biggr)\,{\text{d}}z\\&\le\dfrac{ C_3\phi_\gamma(\kappa_0k\delta)\delta ^{{{\alpha_\gamma}/{2}}}}{ (t-k\delta)^{d/2}}\int_{\mathbb{R}^d}\exp\biggl({-\frac{|z|^2}{8\hat\lambda_0(t-k\delta)}}\biggr)\,{\text{d}} z\\&\le C_4\phi_\gamma(\kappa_0k\delta)\delta ^{{{\alpha_\gamma}/{2}}}\end{align*}
for some constants
 $C_2,C_3,C_4>0$
. Hence we arrive at
 \begin{equation}\sum_{k=1}^{\lfloor T/\delta \rfloor}\int_{k\delta }^{T\wedge(k+1)\delta }\mathbb{E}\left|b\left(X^{(\delta)}_t\right)-b\left(X^{(\delta)}_{k\delta }\right)\right|^\gamma\,{\text{d}}t\le C_4\delta ^{{{\alpha_\gamma}/{2}}}\int_\delta ^T\phi_\gamma(\kappa_0\lfloor t/\delta \rfloor\delta)\,{\text{d}} t.\end{equation}
Observe that
 \begin{align*}\int_\delta ^T\phi_\gamma(\kappa_0\lfloor t/\delta \rfloor\delta)\,{\text{d}} t&=\sum_{i=1}^{\lfloor T/\delta \rfloor}\int_{(i-1)\delta }^{((1+i)\delta)\wedge T-\delta }\phi_\gamma(\kappa_0i\delta)\,{\text{d}} t\\&\le \sum_{i=1}^{\lfloor T/\delta \rfloor}\int_{(i-1)\delta }^{i\delta }\phi_\gamma(\kappa_0i\delta)\,{\text{d}} t\\&\le \sum_{i=1}^{\lfloor T/\delta \rfloor}\int_{(i-1)\delta }^{i\delta }\phi_\gamma(\kappa_0 t)\,{\text{d}} t\\&\le \dfrac{1}{\kappa_0}\int_0^{\kappa_0T}\phi_\gamma( t)\,{\text{d}} t,\end{align*}
where in the second inequality we used the fact that
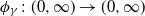 $\phi_\gamma\colon (0,\infty)\rightarrow(0,\infty)$
is decreasing. Hence (2.7) holds true by combining (2.8) with (2.11) and by utilizing
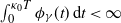 $\int_0^{\kappa_0T}\phi_\gamma(t)\,{\text{d}} t<\infty$
for arbitrary
 $T>0$
.
For any
 $p,q\ge 1$
and
 $0\le S\le T$
, let
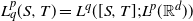 $L^p_q(S,T)=L^q([S,T];L^p(\mathbb{R}^d))$
be the family of all Borel-measurable functions
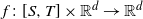 $f\colon [S,T]\times\mathbb{R}^d\rightarrow\mathbb{R}^d$
endowed with the norm
 \begin{equation*}\|f\|_{L^p_q(S,T)}\colon= \biggl(\int_S^T\biggl(\int_{\mathbb{R}^d}|f_t(x)|^p\,{\text{d}}x\biggr)^{{{q}/{p}}}\,{\text{d}} t\biggr)^{{{1}/{q}}}<\infty.\end{equation*}
For simplicity we shall write
 $L^p_q(T)$
in place of
 $L^p_q(0,T)$
. In contrast to (1.1), in (1.6) we have written the drift term as
 $b(X_{t_\delta }^{(\delta)})$
instead of
 $b(X_t^{(\delta)})$
so that the classical Krylov estimate (see e.g. [Reference Gyöngy and Martinez4], [Reference Huang and Wang9], [Reference Krylov and Röckner14], [Reference Xie and Zhang30], and [Reference Zhang32]) is not directly applicable. However, the following lemma shows that
 $(X_t^{(\delta)})_{t\ge 0}$
still satisfies the Khasminskii estimate by employing a Gaussian heat kernel estimate, although the Krylov estimate for
 $(X_{t_\delta }^{(\delta)})_{t\ge 0}$
is invalid, as Remark 2.1 below describes.
Lemma 2.3. Assume
 $({\bf A1})$
and
 $({\bf A3})$
. Then, for
 $f\in L^p_q(T)$
with
 $(p,q)\in\mathscr{K}_1$
and
 $T>0$
, the Khasminskii-type estimate
 \begin{equation}\mathbb E\exp\biggl(\lambda\int_0^T\left|f_t\left(X^{(\delta)}_t\right)\right| \,{\text{d}} t\biggr)\le 2^{1+ T\left(2\lambda\alpha_0\|f\|_{ L^p_q(T)}\right)^{\gamma_0}},\quad \lambda>0{,}\end{equation}
holds, where
 \begin{align} \alpha_0 \colon= \dfrac{(1-1/p)^{\frac{d}{2}(1-1/p)}}{(\breve{\lambda}_0(2\pi)^{{{1}/{p}}})^{{{d}/{2}}}}\Bigl\{\hat\lambda_0^{\frac{d}{2}(1-1/p)}+\Lambda_3 (\gamma_0(1-1/q))^{{{(q-1)}/{q}}}(\kappa_0/2)^{\frac{d}{2}(1-1/p)}\Bigr\}.\end{align}
Proof. For
 $0\le s\le t\le T$
, note that
 \begin{align*}&\mathbb E\biggl(\int_s^t\Big|f_r\Big(X_r^{(\delta)}\Big)\Big|\,{\text{d}}r\Bigm|\mathscr F_s\biggr)\\&\quad =\mathbb E\biggl(\int_s^{t\wedge(s_\delta +\delta)}\left|f_r\left(X_r^{(\delta)}\right)\right|\,{\text{d}}r\Bigm|\mathscr F_s\biggr)+\mathbb E\biggl(\int_{t\wedge(s_\delta +\delta)}^t\left|f_r\left(X_r^{(\delta)}\right)\right|\,{\text{d}} r\Bigm|\mathscr F_s\biggr)\\&\quad =\!:\, I_1(s,t)+I_2(s,t).\end{align*}
Since
 \begin{equation*}X_r^{(\delta)}=X_{s_\delta }^{(\delta)}+b\left(X_{s_\delta }^{(\delta)}\right)(r-s_\delta)+\sigma\left(X_{s_\delta }^{(\delta)}\right)(W_s-W_{s_\delta })+\sigma\left(X_{s_\delta }^{(\delta)}\right)(W_r-W_s),\quad r\in[s,s_\delta +\delta),\end{equation*}
we derive from (1.2) and Hölder’s inequality that
 \begin{align}I_1(s,t) & =\int_s^{t\wedge(s_\delta +\delta)}\int_{\mathbb{R}^d}f_r(y_{x,w}+z)\notag \\[3pt]&\quad\times\dfrac{\exp\bigl({-\frac{1}{2}(r-s)^{-1}}\langle(\sigma\sigma^*)^{-1}(x)(z-y_{x,w}),z-y_{x,w}\rangle \bigr)}{\sqrt {(2\pi(r-s))^d\mbox{det}((\sigma\sigma^*)(x))}}\,{\text{d}}z\bigg|_{x=X_{s_\delta }^{(\delta)}}^{w=W_s-W_{s_\delta }}\,{\text{d}} r \notag \\[3pt]&\le\|f\|_{L_q^p(T)}\biggl(\int_s^{t\wedge(s_\delta +\delta)}\biggl(\dfrac{1}{\sqrt {(2\pi(r-s))^d\mbox{det}((\sigma\sigma^*)(x))}} \notag \\[3pt]&\quad\times\biggl(\int_{\mathbb{R}^d}\exp\biggl(\!{-}\dfrac{p}{2(p-1)(r-s)}\langle(\sigma\sigma^*)^{-1}(x)z,z\rangle \biggr)\,{\text{d}}z\biggr)^{{{(p-1)}/{p}}}\biggr)^{{{q}/{(q-1)}}}\,{\text{d}}r\biggr)^{{{(q-1)}/{q}}}\bigg|_{x=X_{s_\delta }^{(\delta)}} \notag \\[3pt]&\le (2\pi)^{-{{d}/{(2p)}}}((p-1)/p)^{\frac{d}{2}(1-{{1}/{p}})}(\hat\lambda_0^{1-{{1}/{p}}}/\breve{\lambda}_0)^{{{d}/{2}}}(t-s)^{{{1}/{\gamma_0}}}\|f\|_{L_q^p(T)},\end{align}
where
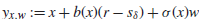 $y_{x,w}\colon= x+b(x)(r-s_\delta)+\sigma(x)w$
,
 $x\in\mathbb{R}^d$
,
 $w\in\mathbb{R}^m$
. For
 $r\ge k\delta $
, let
 $X_{k\delta ,r}^{(\delta),x}$
be the EM scheme determined by (1.6) with
 $X_{k\delta ,k\delta }^{(\delta),x}=x$
. From the tower property of conditional expectation, we have
 \begin{align*}I_2(s,t)&\le \int_{ s_\delta +\delta }^t\mathbb E\left(\left|f_r\left(X_r^{(\delta)}\right)\right|\mathscr F_s\right)\,{\text{d}} r\\[3pt]&=\int_{s_\delta +\delta }^t\mathbb E\Bigl(\mathbb E\left(\left|f_r\left(X_r^{(\delta)}\right)\right|\left|\mathscr F_{s_\delta +s}\right)\right|\mathscr F_s\Bigr)\,{\text{d}}r\\[3pt]&=\int_{ s_\delta +\delta }^t\mathbb E\Bigl(\mathbb E\left|f_r\left(X_{s_\delta +\delta ,r}^{(\delta),x}\right)\right|\left|_{x=X_{s_\delta +\delta }^{(\delta)}}\right|\mathscr F_s\Bigr)\,{\text{d}} r.\end{align*}
In terms of Lemma 2.1, along with Hölder’s inequality, we obtain
 \begin{align*} &\mathbb E\left|f_r\left(X_{s_\delta +\delta ,r}^{(\delta),x}\right)\right|\\ &\quad\le \dfrac{\Lambda_3}{(2\pi\breve{\lambda}_0(r-s_\delta -\delta))^{d/2}}\int_{\mathbb{R}^d}|f_r(y)| \exp\biggl({-\frac{|x-y|^2}{\kappa_0(r-s_\delta -\delta)}}\biggr)\,{\text{d}} y\\ &\quad \le\dfrac{\Lambda_3}{((2\pi)^{{{1}/{p}}}\breve{\lambda}_0)^{d/2}} \biggl(\dfrac{\kappa_0(p-1)}{2p}\biggr)^{\frac{d}{2}(1-1/p)} (r-s_\delta -\delta)^{-{{d}/{(2p)}}}{\|f_r\|_{L^p (\mathbb{R}^d)}} \end{align*}
where
 \[ {\|f_r\|_{L^p (\mathbb{R}^d)}= \biggl(\int_{\mathbb{R}^d}|f_r(y)|^p\,{\text{d}} y\biggr)^{{{1}/{p}}}.} \]
By Hölder’s inequality this yields
 \begin{align}I_2(s,t)&\le\dfrac{\Lambda_3}{((2\pi)^{{{1}/{p}}}\breve{\lambda}_0)^{d/2}}\biggl(\dfrac{\kappa_0(p-1)}{2p}\biggr)^{\frac{d}{2}(1-1/p)}\int_{ s_\delta +\delta }^t(r-s_\delta -\delta)^{-{{d}/{(2p)}}}{\|f_r\|_{L^p (\mathbb{R}^d)}}\notag \\&=\dfrac{\Lambda_3 (\gamma_0(1-1/q) )^{{{(q-1)}/{q}}}}{((2\pi)^{{{1}/{p}}}\breve{\lambda}_0)^{d/2}}\biggl(\dfrac{\kappa_0}{2}(1-1/p)\biggr)^{\frac{d}{2}(1-1/p)}(t-s)^{{{1}/{\gamma_0}}}\|f\|_{L_q^p(T)}.\end{align}
 \begin{equation}\mathbb E\biggl(\int_s^t\left|f_r\left(X_r^{(\delta)}\right)\right|\,{\text{d}} r\Bigm|\mathscr F_s\biggr)\le\alpha_0\,\|f\|_{L_q^p(T)} (t-s)^{{{1}/{\gamma_0}}},\quad 0\le s\le t\le T,\end{equation}
in which
 $\alpha_0>0$
was introduced in (2.13). For each
 $k\ge 1$
, applying (2.16) inductively gives
 \begin{align}&\mathbb E\biggl(\biggl(\int_s^t\left|f_r\left(X^{(\delta)}_r\right)\right| \,{\text{d}} r\biggr)^k\Bigm|\mathscr F_s\biggr)\notag \\&\quad =k! \mathbb E\biggl(\int_{\triangle_{k-1}(s,t)}\left|f_{r_1}\left(X^{(\delta)}_{r_1}\right)\right|\cdots\left|f_{r_{k-1}}\left(X^{(\delta)}_{r_{k-1}}\right)\right|\,{\text{d}} r_1\cdots\,{\text{d}} r_{k-1}\notag \\&\quad\quad\, \times\mathbb E\biggl(\int_{r_{k-1}}^t\left|f_k\left(X^{(\delta)}_{r_k}\right)\right|\,{\text{d}}r_k\Bigm|\mathscr F_{r_{k-1}}\biggr)\Bigm|\mathscr F_s\biggr) \notag \\&\quad \le \alpha_0k! (t-s)^{{{1}/{\gamma_0}}} \|f\|_{L^p_q(T)} \notag \\&\quad\quad\, \times\mathbb E\biggl(\biggl(\int_{\triangle_{k-1}(s,t)}\left|f_{r_1}\left(X^{(\delta)}_{r_1}\right)\right|\cdots\left|f_{r_{k-1}}\left(X^{(\delta)}_{r_{k-1}}\right)\right|\,{\text{d}} r_1\cdots\,{\text{d}} r_{k-1}\biggr)\Bigm|\mathscr F_s\biggr) \notag \\&\quad \le\cdots\le k!\big(\alpha_0 (t-s)^{{{1}/{\gamma_0}}}\|f\|_{ L^p_q(T)}\big)^k,\quad 0\le s\le t\le T,\end{align}
where
 \begin{equation*}\triangle_k(s,t)\colon= \{(r_1,\cdots,r_{k})\in\mathbb{R}^{k}\colon s\le r_1\le\cdots\le r_{k}\le t\}.\end{equation*}
Taking
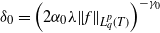 $\delta _0=\left(2\alpha_0\lambda\|f\|_{ L^p_q(T)}\right)^{-\gamma_0}$
, we obviously have
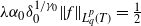 $ \lambda \alpha_0\delta _0^{{{1}/{\gamma_0}}}\|f\|_{ L^p_q(T)}=\frac{1}{2}$
. With this and (2.17) in hand, we derive that
 \begin{equation}\mathbb E\biggl(\exp\biggl(\lambda\int_{(i-1)\delta _0}^{i\delta _0\wedge T} \left|f_t\left(X^{(\delta)}_t\right)\right| \,{\text{d}}t\biggr)\Bigm|\mathscr F_{(i-1)\delta _0}\biggr)\le\sum_{k=0}^\infty\dfrac{1}{2^k}=2,\quad i\ge 1,\end{equation}
which further implies inductively that
 \begin{align}\mathbb E\exp\biggl(\lambda\int_0^T\left|f_t\left(X^{(\delta)}_t\right)\right| \,{\text{d}} t\biggr)&=\mathbb E\biggl(\exp\biggl(\lambda\sum_{i=1}^{\lfloor T/\delta _0\rfloor}\int_{(i-1)\delta _0}^{ i\delta _0 }\left|f_t\left(X^{(\delta)}_t\right)\right| \,{\text{d}}t\biggr) \notag \\&\quad\,\times \mathbb E\biggl(\exp\biggl(\lambda\int_{\lfloor T/\delta _0\rfloor\delta _0}^{T }\left|f_t\left(X^{(\delta)}_t\right)\right| \,{\text{d}}t\biggr)\Bigm|\mathscr F_{\lfloor T/\delta _0\rfloor\delta _0}\biggr)\biggr) \notag \\&\le2\,\mathbb E\exp\biggl(\lambda\sum_{i=1}^{\lfloor T/\delta _0\rfloor}\int_{(i-1)\delta _0}^{ i\delta _0 }\left|f_t\left(X^{(\delta)}_t\right)\right| \,{\text{d}}t\biggr)\notag \\&\le\cdots\le 2^{1+T/\delta _0 }.\end{align}
Therefore (2.12) is now available by recalling
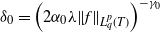 $\delta _0=\left(2\alpha_0\lambda\|f\|_{ L^p_q(T)}\right)^{-\gamma_0}$
.
The following lemma is concerned with Khasminskii’s estimate for the solution process
 $(X_t)_{t\ge 0}$
, which is more or less standard; see e.g. [Reference Gyöngy and Martinez4], [Reference Huang and Wang9], [Reference Krylov and Röckner14], [Reference Xie and Zhang30], and [Reference Zhang32]. Here we state the Khasminskii estimate and provide a sketch of its proof merely for the sake of an explicit upper bound.
Lemma 2.4. Assume
 $({\bf A1})$
and
 $({\bf A3})$
. Then, for
 $f\in L^p_q(T)$
with
 $(p,q)\in\mathscr{K}_1$
,
 $\lambda>0$
, and
 $T>0$
,
 \begin{equation}\mathbb E\exp\biggl(\lambda\int_0^T|f_t(X_t)| \,{\text{d}} t\biggr)\le 2^{1+ T \left(2\lambda\hat\alpha_0\|f\|_{ L^p_q(T)}\right)^{\gamma_0}},\end{equation}
where
 \begin{equation} \begin{aligned}\hat \alpha_0 & \colon= (2\pi)^{-{{d}/{(2p)}}}\hat\beta_T(8(p-1)/p)^{\frac{d}{2}(1-{{1}/{p}})}\left(\hat\lambda_0^{1-{{1}/{p}}}/\breve{\lambda}_0\right)^{{{d}/{2}}},\\\hat\beta_T&\colon= \exp\biggl({\frac{\|b\|_\infty^2T}{2\hat\lambda_0}}\biggr)\sum_{i=0}^\infty\dfrac{ \beta_T^i}{\Gamma(1+{{i}/{2}})},\end{aligned}\end{equation}
with
 $\beta_T$
being given in (A.2)below.
Proof. By (A.1) below, it follows from Hölder’s inequality and theMarkov property that
 \begin{align}\mathbb E\biggl(\int_s^t|f_r(X_r)|\,{\text{d}}r\Bigm|\mathscr F_s\biggr)&=\int_s^t \mathbb E|f_r(X_r^{s,x})| \,{\text{d}} r\big|_{x=X_s}\notag \\&\le\hat\beta_T \int_s^t\int_{\mathbb{R}^d}|f_r(y)|\dfrac{\exp\bigl({-\frac{|y-x|^2}{16\hat\lambda_0(r-s)}}\bigr)}{(2\pi\breve{\lambda}_0(r-s))^{d/2}}\,{\text{d}} y\,{\text{d}}r\bigg|_{x=X_s} \notag \\&\le\hat \alpha_0(t-s)^{1-{{d}/{(2p)}} -{{1}/{q}}}\|f\|_{L_q^p(T)},\end{align}
where
 $(X^{s,x}_t)_{t\ge s}$
stands for the solution to (1.1) with the initial value
 $X_s^{s,x}=x$
, and
 $\hat\beta_T,\hat \alpha_0>0$
were introduced in (2.21). Then (2.20) follows immediately by utilizing (2.22) and by following the argument to derive (2.19).
Remark 2.1. In (2.16), Krylov’s estimate for
 $\left(X_t^{(\delta)}\right)_{t\ge 0}$
instead of
 $\left(X_{t_\delta }^{(\delta)}\right)_{t\ge 0}$
is available, whereas the Krylov estimate associated with
 $\left(X_{t_\delta }^{(\delta)}\right)_{t\ge 0}$
no longer holds true. Indeed, if we take
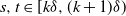 $s,t\in[k\delta ,(k+1)\delta)$
for some integer
 $k\ge 1$
, we obviously have
 \begin{equation}\mathbb E\biggl(\int_s^t\left|f_{r_\delta }\left(X_{r_\delta }^{(\delta)}\right)\right|\,{\text{d}} r\Bigm|\mathscr F_s\biggr)=\left|f_{k\delta }\left(X_{k\delta }^{(\delta)}\right)\right|(t-s), \quad f\in L^p_q(T),\ (p,q)\in\mathscr{K}_1 ,\end{equation}
which is a random variable. Hence it is impossible to control the quantity on the left-hand side of (2.23) by
 $\|f\|_{L^p_q(T)}$
up to a constant; see also [Reference Shao26] for more details.
Before we go further, we introduce some additional notation. For
 $p\ge 1$
and
 $m\ge 0$
, let
 $H^m_p$
be the usual Sobolev space on
 $\mathbb{R}^d$
with the norm
 \begin{equation*}\|f\|_{H_p^m}\colon= \sum_{k=0}^m\|\nabla^mf\|_{L^p},\end{equation*}
where
 $\nabla^m$
denotes the mth-order gradient operator. For
 $q\ge 1$
and
 $0\le S\le T$
, let
 \[\mathbb{H}_p^{m,q}(S,T)=L^q\left([S,T];H_p^m\right)\]
and let
 $\mathscr{H}_p^{m,q}(S,T)$
be the collection of all functions
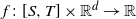 $f\colon [S,T]\times\mathbb{R}^d\rightarrow\mathbb{R}$
such that
 $f\in\mathbb{H}_p^{m,q}(S,T)$
and
 $\partial_t f\in L^p_q(S,T)$
. For a locally integrable function
 $h\colon \mathbb{R}^d\rightarrow\mathbb{R}$
, the Hardy–Littlewood maximal operator
 $\mathscr{M}h$
is defined as
 \begin{equation*}(\mathscr{M}h)(x)=\sup_{r>0}\dfrac{1}{|B_r(x)|}\int_{B_r(x)}h(y)\,{\text{d}}y,\quad x\in\mathbb{R}^d,\end{equation*}
where
 $B_r(x) $
is the ball with the radius r centered at the point x and
 $|B_r(x)|$
denotes the d-dimensional Lebesgue measure of
 $B_r(x)$
.
To make the content self-contained, we recall the Hardy–Littlewood maximal theorem, which is stated as follows.
Lemma 2.5. For any
 $f \in W^{1,1}_{\text{loc}}(\mathbb{R}^d)$
, there exists a constant
 $C>0$
such that
 \begin{equation}|f(x)-f(y)|\le C|x-y|\{(\mathscr{M}|\nabla f|)(x)+(\mathscr{M}|\nabla f|)(y)\},\quad \textit{a.e.}\ \text{x,y}\in\mathbb{R}^d.\end{equation}
For any
 $f\in L^p(\mathbb{R}^d)$
,
 $p>1$
, there exists a constant
 $C_p$
, independent of d, such that
 \begin{equation}\|\mathscr{M}f\|_{L^p}\le C_p\|f\|_{L^p}.\end{equation}
Remark 2.2. For the detailed proof of (2.24), please refer to the counterpart of [Reference Zhang33, Lemma 3.5]. Comparing with [Reference Zhang33, Lemma 3.5], we have replaced the local maximum function by the global one due to the monotonicity of the local maximum function. On the other hand, the inequality in (2.25) is called the Hardy–Littlewood maximal inequality, which can be consulted in [Reference Stein28, Theorem 1, page 5]. Combining (2.24) with (2.25), it is clear that for
 $f\in H^1_p$
, the right-hand side of (2.24) is finite for a.e.
 $x,y\in\mathbb{R}^d$
.
Now we are in a position to complete the proof of Theorem 1.1.
Proof of Theorem 1.1. For any
 $\lambda >0$
, consider the following PDE for
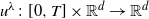 $u^\lambda\colon [0,T]\times\mathbb{R}^d\rightarrow\mathbb{R}^d$
:
 \begin{equation} \partial_tu^\lambda+\dfrac{1}{2}\sum_{i,j=1}^{d}{\langle\sigma\sigma^{\ast}e_{i},e_{j}\rangle}\nabla_{e_{i}}\nabla_{e_{j}}u^\lambda+b+\nabla_{b}u^\lambda=\lambda u^\lambda,\end{equation}
where
 $\{e_j\}_{j=1}^d$
stipulates the orthogonal basis of
 $\mathbb{R}^d$
and
 $\left(\nabla_bu^\lambda\right)(x)$
(resp.
 $\left(\nabla_{e_{j}}u^\lambda\right)(x)$
) means the directional derivative of
 $u^\lambda$
at the point x along the direction b(x) (resp.
 $e_j$
). According to [Reference Xie and Zhang30, Lemma 4.3], (2.26) has a unique solution
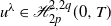 $u^{\lambda}\in \mathscr{H}_{2p}^{2,2q}(0,T)$
for the pair
 $ (p,q)\in\mathscr{K}_1$
due to
 $p>{{d}/{2}}$
satisfying
 \begin{equation} (1\vee\lambda)^{\frac{1}{2}(1-{{d}/{(2p)}}-{{1}/{q}})} \|\nabla u^\lambda\|_{T,\infty} +\|\nabla^2 u^\lambda\|_{L^{2p}_{2q}(T)}\leq c_1\||b|^2\|_{L^{p}}\end{equation}
for some constant
 $c_1>0$
independent of
 $\lambda$
, where
 \[\|\nabla u^\lambda\|_{T,\infty}\colon= \sup_{0\le t\le T,x\in\mathbb{R}^d}\|\nabla u_t^\lambda(x)\|_{\text{HS}}.\]
With the help of (2.27), there is a constant
 $\lambda_0\ge 1$
such that
 \begin{equation} \|\nabla u^\lambda\|_{T,\infty}\le\dfrac{1}{2},\quad \lambda\ge \lambda_0.\end{equation}
For
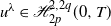 $u^\lambda\in{\mathscr{H}_{2p}^{2,2q}(0,T)}$
, there exists a sequence
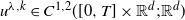 $u^{\lambda,k}\in C^{1,2}([0,T]\times\mathbb{R}^d;\mathbb{R}^d)$
such that
 \begin{equation*}\lim_{k\rightarrow\infty}\|u^{\lambda,k}-u^\lambda\|_{{\mathscr{H}_{2p}^{2,2q}(0,T)}}=0, \end{equation*}
where
 \begin{equation*}\|u\|_{{\mathscr{H}_{2p}^{2,2q}(0,T)}}\colon= \|\partial_\cdot u\|_{L^{2p}_{2q}(0,T)}+\| u\|_{\mathbb{H}_{2p}^{2,2q}(0,T)}.\end{equation*}
Henceforth, we can apply Itô’s formula directly to
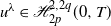 $u^\lambda\in{\mathscr{H}_{2p}^{2,2q}(0,T)}$
by adopting a standard approximation approach; for more details see e.g. the arguments of [Reference Xie and Zhang30, Theorem 2.1] and [Reference Zhang32, Lemma 4.3]. Set
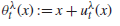 $\theta^\lambda_t(x)\colon= x+u^\lambda_t(x)$
,
 $x\in\mathbb{R}^d$
, and
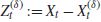 $Z_t^{(\delta)}\colon= X_t-X^{(\delta)}_t$
. By Itô’s formula, we obtain from (2.26) that
 \begin{align}{\text{d}}\theta^\lambda_t(X_t)&= \lambda u^\lambda(X_t)\,{\text{d}} t+\nabla\theta^\lambda_t(X_t)\sigma(X_t)\,{\text{d}} W_t \notag \\{\text{d}}\theta^\lambda_t(X^{(\delta)}_t)&=\biggl\{\lambda u^\lambda\left(X^{(\delta)}_t\right) +\nabla\theta^\lambda_t\left(X^{(\delta)}_t\right)\left( b\left(X^{(\delta)}_{t_\delta }\right)-b\left(X^{(\delta)}_t\right)\right)+\dfrac{1}{2}\sum_{i,j=1}^d\langle ((\sigma\sigma^*)\left(X_{t_\delta }^{(\delta)}\right)\notag \\&\quad\, -(\sigma\sigma^*)\left(X_t^{(\delta)}\right))e_i,e_j\rangle \nabla_{e_i}\nabla_{e_j}u_t^\lambda\left(X_t^{\delta }\right)\biggr\}\,{\text{d}} t + \nabla\theta^\lambda_t\left(X^{(\delta)}_t\right)\sigma\left(X^{(\delta)}_{t_\delta }\right)\,{\text{d}} W_t.\end{align}
Let
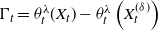 $\Gamma_t= \theta^\lambda_t(X_t)-\theta^\lambda_t\left(X^{(\delta)}_t\right)$
,
 $t\ge 0$
. From (2.28), it is easy to see that
 \begin{equation} \dfrac{1}{2}\left|Z_t^{(\delta)}\right|\le |\Gamma_t | \le \dfrac{3}{2}\left|Z_t^{(\delta)}\right|. \end{equation}
Hence, by Itô’s formula, we derive from (2.29) that for
 $\gamma\ge 2$
in (A2),
 \begin{align} & \left|Z_t^{(\delta)}\right|^\gamma \le 2^{\gamma}\gamma\lambda\int_0^t |\Gamma(s)|^{\gamma-2}\langle \Gamma(s),u^\lambda(X_s)-u^\lambda(X^{(\delta)}_s)\rangle \,{\text{d}}s \notag \\&\quad\, +2^{\gamma}\gamma\int_0^t |\Gamma(s)|^{\gamma-2}\langle \Gamma(s),\nabla\theta^\lambda_s\left(X^{(\delta)}_t\right)\left(b\left(X^{(\delta)}_s\right)-b\left(X^{(\delta)}_{s_\delta }\right)\right) \rangle \,{\text{d}} s \notag \\&\quad\, +2^{\gamma-1}\gamma\sum_{i,j=1}^d\int_0^t |\Gamma(s)|^{\gamma-2} \langle ((\sigma\sigma^*)\left(X_{s_\delta }^{(\delta)}\right)-(\sigma\sigma^*)\left(X_s^{(\delta)}\right))e_i,e_j\rangle \langle \Gamma(s),\nabla_{e_i}\nabla_{e_j}u_s^\lambda\left(X_s^{\delta }\right)\rangle \,{\text{d}} s \notag \\&\quad\, + 2^{\gamma-1}\gamma(\gamma-1)\int_0^t |\Gamma(s)|^{\gamma-2}\|\nabla\theta^{\lambda}_s(X_s)\sigma(X_s)-\nabla\theta^{\lambda}_s\left(X^{(\delta)}_s\right)\sigma\left(X^{(\delta)}_{s_\delta }\right)\|^2_{\text{HS}}\,{\text{d}} s+{\text{d}} M_t \notag \\& =\!:\, I_{1,\delta }(t)+I_{2,\delta }(t)+I_{3,\delta }(t)+I_{4,\delta }(t)+M_t,\end{align}
where
 \begin{equation*}M_t\colon=2^\gamma\gamma \int_0^t|\Gamma(s)|^{\gamma-2}\langle \Gamma(s),\left(\left(\nabla\theta^\lambda_s\sigma\right)(X_s)-\nabla\theta^\lambda_s\left(X^{(\delta)}_s\right)\sigma\left(X_{s_\delta }^{(\delta)}\right)\right)\,{\text{d}}W_s\rangle .\end{equation*}
By means of (2.28) and (2.30), we have
 \begin{equation}I_{1,\delta }(t)\le 3^{\gamma-1}\gamma\lambda\int_0^t\left|Z_s^{(\delta)}\right|^{\gamma}\,{\text{d}} s.\end{equation}
Also, by virtue of (2.28), as well as (2.30), we find that there exists a constant
 $c_2>0$
such that
 \begin{equation}I_{2,\delta }(t)\le c_2\biggl\{\int_0^t\left|Z_s^{(\delta)}\right|^\gamma\,{\text{d}}s+\int_0^t\left|b\left(X^{(\delta)}_s\right)-b\left(X^{(\delta)}_{s_\delta }\right)\right|^\gamma\,{\text{d}} s\biggr\}.\end{equation}
Owing to (1.3) and (1.5), we have
 \begin{align*}\|(\sigma\sigma^*)(x)-(\sigma\sigma^*)(y)\|_{\text{HS}}&\le(\|\sigma(x)\|_{\text{op}}+\|\sigma(y)\|_{\text{op}})\| \sigma(x)- \sigma (y)\|_{\text{HS}}\\&\le 2\,L_0\sqrt {\hat\lambda_0d}\,|x-y|,\quad x,y\in\mathbb{R}^d.\end{align*}
Combining (2.30) and Young’s inequality, this leads to
 \begin{align}I_{3,\delta }(t)&\le c_3\int_0^t \left| X_s^{(\delta)}- X_{s_\delta }^{(\delta)}\right|\cdot\left|Z_s^{(\delta)}\right|^{\gamma-1}\cdot\| \nabla^2 u_s^\lambda(X_s^{\delta })\|_{\text{HS}}\,{\text{d}} s \notag \\&\le \dfrac{c_3}{\gamma}\int_0^t\bigl\{(\gamma-1)\left|Z_s^{(\delta)}\right|^\gamma\| \nabla^2 u_s^\lambda\left(X_s^{\delta }\right)\|_{\text{HS}}^{{{\gamma}/{(\gamma-1)}}}+ \left| X_s^{(\delta)}- X_{s_\delta }^{(\delta)} \right|^\gamma\bigr\}\,{\text{d}} s \notag \\&\le \dfrac{c_3}{2}\int_0^t\left\{ \left|Z_s^{(\delta)}\right|^\gamma \left(\gamma\| \nabla^2 u_s^\lambda\left(X_s^{\delta }\right)\|_{\text{HS}}^2+\gamma-2\right)+ \left| X_s^{(\delta)}- X_{s_\delta }^{(\delta)}\right|^\gamma\right\}\,{\text{d}} s\end{align}
for some constant
 $c_3>0$
. Furthermore, thanks to (1.2), (1.5), (2.24), (2.28), and (2.30), we derive from Hölder’s inequality that
 \begin{align}I_{4,\delta }(t)&\le 2^{\gamma+1}\gamma(\gamma-1)\int_0^t |\Gamma(s)|^{\gamma-2}\bigl\{\|\sigma(X_s)-\sigma\left(X^{(\delta)}_{s_\delta }\right)\|^2_{\text{HS}}\notag \\&\quad\, +\|(\nabla u^{\lambda}_s(X_s)-\nabla u^{\lambda}_s\left(X^{(\delta)}_s\right))\sigma(X_s)\|^2_{\text{HS}}\notag \\&\quad\, +\|\nabla u^{\lambda}_s\left(X^{(\delta)}_s\right)(\sigma(X_s)-\sigma\left(X^{(\delta)}_{s_\delta }\right)\|^2_{\text{HS}} \bigr\}\,{\text{d}} s \notag \\&\le c_4\int_0^t |\Gamma(s)|^{\gamma-2}\bigl\{\|\sigma(X_s)-\sigma\left(X^{(\delta)}_{s_\delta }\right)\|^2_{\text{HS}} +\| \nabla u^{\lambda}_s(X_s)-\nabla u^{\lambda}_s\left(X^{(\delta)}_s\right) \|^2_{\text{HS}} \bigr\}\,{\text{d}} s \notag \\&\le c_5 \int_0^t|\Gamma(s)|^{\gamma-2}|Z_s^{(\delta)}|^2\left\{\left(\mathscr{M}\|\nabla^2u^{\lambda}_s\|_{\text{HS}}^2\right)(X_s)+\left(\mathscr{M}\|\nabla^2u^{\lambda}_s\|_{\text{HS}}^2\right)\left(X^{(\delta)}_s\right)\right\} \,{\text{d}} s \notag \\&\quad\, +c_5\int_0^t|\Gamma(s)|^{\gamma-2}\bigl\{\left| Z_s^{(\delta)} \right|^2+\left| X_s^{(\delta)}- X_{s_\delta }^{(\delta)} \right|^2\bigr\}\,{\text{d}} s \notag \\&\le c_6 \int_0^t |Z_s^{(\delta)}|^\gamma\left\{\left(\mathscr{M}\|\nabla^2u^{\lambda}_s\|_{\text{HS}}^2\right)(X_s)+\left(\mathscr{M}\|\nabla^2u^{\lambda}_s\|_{\text{HS}}^2\right)\left(X^{(\delta)}_s\right)\right\} \,{\text{d}} s \notag \\&\quad\, +c_6\int_0^t \left\{\left| Z_s^{(\delta)} \right|^\gamma+ \left| X_s^{(\delta)}- X_{s_\delta }^{(\delta)} \right|^\gamma \right\}\,{\text{d}} s\end{align}
for some constants
 $c_4,c_5,c_6>0$
. As a result, plugging (2.32)–(2.35) into (2.31) gives
 \begin{equation*}\left|Z_t^{(\delta)}\right|^\gamma\le\int_0^t\left|Z_s^{(\delta)}\right|^\gamma\,{\text{d}}A_s+\int_0^t\bigl\{c_2\left|b\left(X^{(\delta)}_s\right)-b\left(X^{(\delta)}_{s_\delta }\right)\right|^\gamma+(c_3/2+c_6)\left|X_s^{(\delta)}- X_{s_\delta }^{(\delta)}\right|^\gamma\bigr\}\,{\text{d}} s+M_t,\end{equation*}
in which, for some constant
 $\hat c_1>0$
,
 \begin{equation*}A_t\colon= \hat c_1\int_0^t\left\{1+\left(\mathscr{M} \|\nabla^2u^{\lambda}_s\|_{\text{HS}}^2\right)(X_s)+\left(\mathscr{M}\|\nabla^2u^{\lambda}_s\|_{\text{HS}}^2\right)\left(X^{(\delta)}_s\right)+ \|\nabla^2u_s^{\lambda}\|^2_{\text{HS}}\left(X_s^{\delta }\right)\right\}\,{\text{d}} s,\quad t\ge 0.\end{equation*}
Consequently, by the stochastic Gronwall inequality (see e.g. [Reference Xie and Zhang30, Lemma 3.8]), we deduce that for
 $0<\kappa'<\kappa<1$
 \begin{align*}\bigl(\mathbb E \|Z^{(\delta)}\|^{\kappa'\gamma}_{t,\infty} \bigr)^{1/\kappa'}&\le\biggl(\dfrac{\kappa}{\kappa-\kappa'}\biggr)^{1/\kappa'}\left(\mathbb E\,\text{{e}}^{\kappa A_t/(1-\kappa)}\right)^{(1-\kappa)/\kappa}\\&\quad\,\times\int_0^t\bigl\{c_2\mathbb E\left|b\left(X^{(\delta)}_s\right)-b\left(X^{(\delta)}_{s_\delta }\right)\right|^\gamma+(c_3/2+ c_6)\,\mathbb E\left|X_s^{(\delta)}- X_{s_\delta }^{(\delta)} \right|^\gamma\bigr\}\,{\text{d}} s,\end{align*}
where
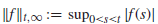 $\|f\|_{t,\infty}\colon= \sup_{0\le s\le t}|f(s)|$
for a continuous function
 $f\colon \mathbb{R}_+\rightarrow\mathbb{R}^d$
. The estimate above, together with Lemma 2.2 and the fact that
 \begin{equation*}\sup_{0\le t\le T}\mathbb E\big| X_t^{(\delta)}- X_{t_\delta }^{(\delta)}\big|^\gamma\le \hat c_2\delta ^{{{\gamma}/{2}}}\end{equation*}
for some constant
 $\hat c_2>0$
, leads to
 \begin{equation}\left(\mathbb E \|Z^{(\delta)}\|^{\kappa'\gamma}_{t,\infty} \right)^{1/\kappa'}\le \hat c_3\left(\mathbb E\,\text{{e}}^{\kappa A_t/(1-\kappa)}\right)^{{{1}/{\kappa}}-1 }\left(\delta ^{{{\gamma}/{2}}}+\delta ^{ {{\alpha_\gamma}/{2}} }\right)\end{equation}
for some constant
 $\hat c_3>0$
. By Hölder’s inequality, we deduce for some constant
 $\hat c_4>0$
that
 \begin{align*}\mathbb E\exp\biggl({\frac{\kappa A_t}{1-\kappa}}\biggr)&\le\exp\biggl({\frac{\kappa\, \hat c_1t}{1-\kappa}}\biggr)\biggl(\mathbb E\exp\biggl(\hat c_4 \int_0^t\bigl(\mathscr{M}\|\nabla^2u^{\lambda}_s\|^2_{\text{HS}}\bigr)(X_s)\,{\text{d}} s\biggr)\biggr)^{1/2}\\&\quad\,\times\biggl(\mathbb E\exp\biggl(\hat c_4\int_0^t\bigl(\mathscr{M}\|\nabla^2u^{\lambda}_s\|^2_{\text{HS}}\bigr) \left(X^{(\delta)}_s\right)\,{\text{d}}s\biggr)\biggr)^{1/4}\\&\quad\,\times\biggl(\mathbb E\exp\biggl(\hat c_4\int_0^t \|\nabla^2u_s^{\lambda}\|^2_{\text{HS}}\left(X_s^{\delta }\right)\,{\text{d}} s\biggr)\biggr)^{1/4}.\end{align*}
In addition to (2.12), (2.20), (2.25) as well as (2.27), this implies that
 \begin{align}\mathbb E\exp\biggl({\frac{\kappa A_t}{1-\kappa}}\biggr)&\le \exp\Bigl(\hat c_5\Bigl(1+\bigl\|\|\nabla^2u^{\lambda}\|^2_{\text{HS}}\bigr\|_{ L^{p}_{q}(T)}^{\gamma_0}+\|\mathscr{M}\|\nabla^2u^{\lambda}\|^2_{\text{HS}}\|_{ L^{p}_{q}(T)}^{\gamma_0}\Bigr)\Bigr) \notag \\&\le\exp\Bigl(\hat c_6\Bigl(1+\|\nabla^2u^{\lambda} \|_{L^{2p}_{2q}(T)}^{2\gamma_0}\Bigr)\Bigr) \notag \\&\le\exp \bigl(\hat c_7\bigl(1+\||b|^2\|_{ L^{p}}^{\gamma_0} \bigr)\bigr)\end{align}
for someconstants
 $\hat c_5,\hat c_6,\hat c_7>0$
. Substituting (2.37) back into (2.36), we find constants
 $\hat c_8,\hat c_9>0$
such that
 \begin{equation*} \mathbb E \|Z^{(\delta)}\|^{\kappa'\gamma}_{t,\infty} \le \hat c_8\exp\bigl(\hat c_9(1+\||b|^2\|_{ L^{p}}^{\gamma_0} )\bigr)\bigl(\delta ^{{{\gamma}/{2}}}+\delta ^{ {{\alpha_\gamma}/{2}} }\bigr)^{\kappa'}\end{equation*}
so that we have
 \begin{equation*} \mathbb E \|Z^{(\delta)}\|^{\beta}_{t,\infty} \le \hat c_8\exp\bigl(\hat c_9(1+\||b|^2\|_{ L^{p}}^{\gamma_0} )\bigr)\bigl(\delta ^{{{\beta}/{2}}}+\delta ^{ {{\alpha_\gamma\beta}/{2\gamma}} }\bigr),\quad \beta\in(0,\gamma).\end{equation*}
We therefore complete the proof.
3. Proof of Theorem 1.2
In this section we aim to complete the proof of Theorem 1.2 by carrying out a truncation approach; see e.g. [Reference Bao, Huang and Yuan1] and [Reference Ngo and Taguchi23] for further details.
Let
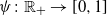 $\psi\colon \mathbb{R}_+\rightarrow[0,1]$
be a smooth function such that
 \[\psi(r)=1, r\in[0,1],\quad \psi(r)\equiv0, r\ge 2.\]
For each integer
 $k\ge 1$
, let
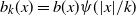 $b_k(x)=b(x)\psi(|x|/k)$
,
 $x\in\mathbb{R}^d$
, be the truncation function associated with the drift b. A direct calculation shows that
 \begin{equation}\|b_k\|_\infty\le\|b\|_\infty\quad \mbox{ and}\quad \||b_k|^2\|_{L^p}\le\biggl(\dfrac{2^d\pi^{{{d}/{2}}}}{\Gamma({{d}/{2}}+1)}\biggr)^{1/p}k^{{{d}/{p}}}\|b\|_\infty^2.\end{equation}
Consider the following truncated SDE corresponding to (1.1):
 \begin{equation}{\text{d}} X_t^{k}=b_k\left(X_t^{k}\right)\,{\text{d}} t+\sigma\left(X_t^k\right)\,{\text{d}} W_t,\quad t\ge 0, X_0^{k}=X_0.\end{equation}
The EM scheme associated with (3.2) is given by
 \begin{equation*}{\text{d}} X_t^{k,(\delta)}=b_k\left(X_{t_\delta }^{k,(\delta)}\right)\,{\text{d}}t+\sigma\left(X_{t_\delta }^{k,(\delta)}\right)\,{\text{d}} W_t,\quad t\ge 0, X_0^{k,(\delta)}=X_0^{(k)}.\end{equation*}
Observe that for
 $\beta\in(0,\gamma)$
 \begin{align}\mathbb E \|X -X^{(\delta)} \|^\beta_{T,\infty} &\le3^{0\vee(\beta-1)} \bigl\{\mathbb E\|X-X^{k}\|^2_{T,\infty}+\mathbb E\|X^{(\delta)}-X^{k,(\delta)}\|^2_{T,\infty} +\mathbb E\|X_{t}^k-X^{k,(\delta)}\|^2_{T,\infty} \bigr\}\notag \\&=\!:\, 3^{0\vee(\beta-1)} \{I_1+I_2+I_3\},\end{align}
where, for a map
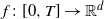 $f\colon [0,T]\rightarrow\mathbb{R}^d$
, we set
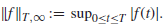 $\|f\|_{T,\infty}\colon= \sup_{0\le t\le T}|f(t)|$
. Via Hölder’s inequality and the fact that
 \[\{X_t\neq X_t^{k},0\le t\le T\}\subseteq\{\|X \|_{T,\infty}\ge k\},\]
it follows that
 \begin{equation*}I_1=\mathbb E( \|X-X^{k}\|^\beta_{T,\infty}{\bf1}_{\{ \|X \|_{T,\infty}\ge k\}})\le\left(\mathbb E \|X-X^{k}\|_{T,\infty}^{2\beta} \right)^{1/2}(\mathbb P(\|X\|_{T,\infty}\ge k))^{1/2}.\end{equation*}
Since
 \begin{equation*}\|X \|_{T,\infty}\le |x|+\|b\|_\infty T+ |M|_{T,\infty},\end{equation*}
in which
 \[M_t\colon= \int_0^t\sigma(X_s)\,{\text{d}} W_s,\quad t\ge 0,\]
with the quadratic variation
 $\langle M\rangle _T\le d\hat\lambda_0 T$
, we derive from [Reference Shigekawa27, Proposition 6.8, page 147] that
 \begin{align} \mathbb P(\|X \|_{T,\infty}\ge k)&\le\mathbb P( \|M \|_{T,\infty}\ge k-|x|-\|b\|_\infty T,\langle M\rangle _T\le d\hat\lambda_0 T)\notag \\&\le 2\,d\exp\biggl(-\dfrac{(k-|x|-\|b\|_\infty T)^2}{4d^2\hat\lambda_0T}\biggr)\notag \\&\le 2\,d\exp\biggl(\dfrac{(|x|+\|b\|_\infty T)^2}{4d^2\hat\lambda_0T}\biggr)\exp\biggl({-\frac{k^2}{8d^2\hat\lambda_0T}}\biggr),\end{align}
where in the last display we used the inequality
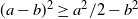 $(a-b)^2\ge a^2/2-b^2$
,
 $a,b\in\mathbb{R}$
. Thus (3.4), together with
 \begin{equation*}\mathbb E \|X\|_{T,\infty}^{2\beta}+\mathbb E \| X^{k}\|_{T,\infty}^{2\beta}\le C_{1}\end{equation*}
for some constant
 $C_{1}$
, yields
 \begin{equation}I_1\le C_2\exp\biggl(\dfrac{(|x|+\|b\|_\infty T)^2}{8d^2\hat\lambda_0T}\biggr)\exp\biggl({-\frac{k^2}{16d^2\hat\lambda_0T}}\biggr)\end{equation}
for some constant
 $C_2>0$
. Following a similar procedure, we also derive that
 \begin{equation}I_2\le C_3\exp\biggl(\dfrac{(|x|+\|b\|_\infty T)^2}{8d^2\hat\lambda_0T}\biggr)\exp\biggl({-\frac{k^2}{16d^2\hat\lambda_0T}}\biggr)\end{equation}
for some constant
 $C_3>0$
. Moreover, for
 $(p,q)\in \mathscr{K}_2$
, according to Theorem 1.1, there exist constants
 $C_4,C_5>0$
such that
 \begin{equation*}\mathbb E\|X^k-X^{k,(\delta)}\|^2_{T,\infty}\le C_4 \text{{e}}^{C_5\||b_k|^2\|_{L^{p}}^{\gamma_0} }\bigl(\delta ^{{{\beta}/{2}}}+\delta ^{ {{\alpha_\gamma\beta}/{(2\gamma)}} }\bigr).\end{equation*}
This, together with (3.1), implies that
 \begin{equation}\mathbb E\|X^k-X^{k,(\delta)}\|^2_{T,\infty}\le C_4 \text{{e}}^{C_6\|b\|_\infty^{2\gamma_0}k^{{{d\gamma_0}/{p}}} } \bigl(\delta ^{{{\beta}/{2}}}+\delta ^{ {{\alpha_\gamma\beta}/{(2\gamma)}} }\bigr)\end{equation}
for some constant
 $C_6>0$
. As a consequence, from (3.5), (3.6), and (3.7), we arrive at
 \begin{equation*}\mathbb E\|X -X^{(\delta)} \|^2_{T,\infty}\le C_8\biggl\{\exp\biggl({-\frac{k^2}{16d^2\hat\lambda_0T}}\biggr)+\text{{e}}^{C_7 k^{{{d\gamma_0}/{p}}} }\delta ^{\frac{\beta}{2}(1\wedge{{\alpha_\gamma}/{\gamma}})}\biggr\}\end{equation*}
for some constants
 $C_7,C_8>0$
. Thereby, the desired assertion (1.8) follows by taking
 \begin{equation*}k=\biggl(-8\beta d^2\hat\lambda_0T\biggl(1\wedge\dfrac{\alpha_\gamma}{\gamma}\biggr)\log\delta \biggr)^{{{1}/{2}}}.\end{equation*}
4. Illustrative examples
In this section we give examples to demonstrate that the assumption imposed on the drift term holds true.
Example 4.1. Let
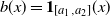 $b(x)={\bf1}_{[a_1,a_2]}(x)$
,
 $x\in\mathbb{R}$
, for some constants
 $a_1<a_2$
. Evidently b is not continuous at all but
 $b^2\in L^p$
for any
 $p\ge 1$
. Observe that
 \begin{equation*}\lim_{\varepsilon\downarrow0}\dfrac{-\varepsilon(b(a_1-\varepsilon)-b(a_1))}{\varepsilon^2}=\lim_{\varepsilon\downarrow0}\dfrac{1}{\varepsilon}=\infty\end{equation*}
so that b does not obey the one-sided Lipschitz condition. Next we aim to show that b given above satisfies (A2). By a direct calculation, for any
 $s>0$
,
 $\gamma\ge 2$
, and
 $y\in\mathbb{R}$
,
 \begin{align*}\int_{-\infty}^\infty|b(x+y+z)-b(x+y)|^\kappa\text{{e}}^{-{{x^2}/{s}}}\,{\text{d}} x&\le\int_{-\infty}^\infty|b(x+z)-b(x)|^\kappa \,{\text{d}}x\\&=\int_{a_1-z}^{a_2-z}{\bf1}_{[a_1,a_2]^c}(x) \,{\text{d}}x+\int_{a_1}^{a_2}{\bf1}_{[a_1-z,a_2-z]^c}(x) \,{\text{d}} x\\&=\!:\, I_1(z)+I_2(z).\end{align*}
If
 $z\ge 0$
, then
 \begin{equation*}I_1(z)=\int_{a_1-z}^{(a_2-z)\wedge a_1} \,{\text{d}} x\le |z|\quad \mbox{ and }\quad I_2(z)=\int^{a_2}_{(a_2-z)\vee a_1} \,{\text{d}} x\le |z|.\end{equation*}
On the other hand, for
 $z<0$
, we have
 \begin{equation*}I_1(z)=\int_{(a_1-z)\vee a_2}^{a_2-z} \,{\text{d}} x\le |z|\quad \mbox{ and }\quad I_2(z)=\int^{a_2\wedge(a_1-z)}_{ a_1} \,{\text{d}} x\le |z|.\end{equation*}
So (A2) holds true with
 $\alpha=1$
and
 $\phi(s)=s^{-{{1}/{2}}}$
,
 $s>0$
.
Example 4.2. For
 $\theta>0$
and
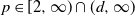 $p\in[2,\infty)\cap(d,\infty)$
, if the Gagliardo seminorm is finite, that is,
 \begin{equation*}[b]_{W^{\theta,p}}\colon= \biggl(\int_{\mathbb{R}^d\times\mathbb{R}^d}\dfrac{|b(x)-b(y)|^p}{|x-y|^{d+p\theta}}\,{\text{d}}x\,{\text{d}} y\biggr)^{{{1}/{p}}}<\infty,\end{equation*}
then
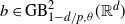 $b\in \text{GB}^2_{1-{{d}/{p}},\theta}(\mathbb{R}^d)$
. Indeed, by Hölder’s inequality and (2.10), it follows that
 \begin{align} &\dfrac{1}{(rs)^{d/2}}\int_{\mathbb{R}^d\times\mathbb{R}^d}|b(x)-b(y)|^2\exp\biggl({-\frac{|x-z|^2}{s}}\biggr)\exp\biggl({-\frac{|y-x|^2}{r}}\biggr)\,{\text{d}}y\,{\text{d}} x \notag \\&\quad =\dfrac{1}{(rs)^{d/2}}\int_{\mathbb{R}^d\times\mathbb{R}^d}\dfrac{|b(x)-b(y)|^2}{|x-y|^{{{2d}/{p}}+2\theta}}\exp\biggl({-\frac{|x-z|^2}{s}}\biggr)\exp\biggl({-\frac{|y-x|^2}{r}}\biggr)|x-y|^{{{2d}/{p}}+2\theta}\,{\text{d}}y\,{\text{d}}x \notag \\&\quad \le C_1 \dfrac{[b]_{W^{\theta,p}}^{{{2}/{p}}}}{(rs)^{d/2}}\biggl(\int_{\mathbb{R}^d\times\mathbb{R}^d}\exp\biggl({-\frac{p|x-z|^2}{(p-2)s}}\biggr) \exp\biggl({-\frac{p|x-y|^2}{(p-2)r}}\biggr)|x-y|^{\frac{2(d+p\theta)}{p-2} }\,{\text{d}} y\,{\text{d}} x\biggr)^{{{(p-2)}/{p}}} \notag \\&\quad \le C_2[b]_{W^{\theta,p}}^{{{2}/{p}}}\dfrac{r^{{{d}/{p}}+\theta}}{(rs)^{d/2}}\biggl(\int_{\mathbb{R}^d\times\mathbb{R}^d}\exp\biggl({-\frac{p|x-z|^2}{(p-2)s}}\biggr) \exp\biggl({-\frac{p|x-y|^2}{2(p-2)r}}\biggr) \,{\text{d}} y\,{\text{d}}x\biggr)^{{{(p-2)}/{p}}} \notag \\&\quad \le C_3[b]_{W^{\theta,p}}^{{{2}/{p}}}\biggl(\dfrac{p-2}{p}\biggr)^{{{(d(p-2))}/{p}}}s^{-{{d}/{p}}}r^\theta,\quad r,s>0, z\in\mathbb{R}^d,\ p>2\end{align}
for some constants
 $C_1,C_2,C_3>0$
. On the other hand, if
 $d=1$
and
 $p=2$
, we deduce from (4.1) that
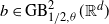 $b\in \text{GB}^2_{1/2,\theta}(\mathbb{R}^d)$
due to
 $\lim_{x\rightarrow0}x^x=1$
.
Example 4.3. For
 $0<a<b<\infty$
,
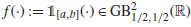 $f({\cdot})\colon= \unicode{x1d7d9}_{[a,b]}({\cdot})\in\text{GB}^2_{{{1}/{2}},{{1}/{2}}}(\mathbb{R})$
, whereas
 $f\notin W^{{{1}/{2}},2}(\mathbb{R})$
. In fact it is easy to see that
 \begin{equation*}f\in\cap_{0\le\theta<{{1}/{2}}}W^{\theta,2},\quad \lim_{\theta\uparrow{{1}/{2}}}[f]_{W^{\theta,2}}=\infty,\end{equation*}
which yields
 $f\notin W^{{{1}/{2}},2}(\mathbb{R})$
. On the other hand, since
 \begin{align*}\dfrac{1}{(rs)^{d/2}}\int_{\mathbb{R}^2}|f(x)-f(y)|^2\exp\biggl({-\frac{|x-z|^2}{s}}\biggr)\exp\biggl({-\frac{|y-x|^2}{r}}\biggr)\,{\text{d}}y\,{\text{d}} x\le Cs^{-{{1}/{2}}}r^{{{1}/{2}}}, \\ r,s>0,\ z\in\mathbb{R}\end{align*}
for some constant
 $C>0$
, we arrive at
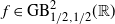 $f \in\text{GB}^2_{{{1}/{2}},{{1}/{2}}}(\mathbb{R})$
.
Appendix A
The next lemma provides explicit estimates of the parameters concerning a Gaussian-type estimate of transition density for the diffusion process
 $(X_t)_{t\ge 0}$
solving (1.1).
Lemma A.1. Under
 $\|b\|_\infty<\infty$
and
 $({\bf A3})$
, the transition density p of
 $(X_t)_{t\ge s}$
satisfies
 \begin{equation}p(s,t,x,x')\le\exp\biggl({\frac{\|b\|_\infty^2T}{2\hat\lambda_0}}\biggr)\sum_{i=0}^\infty\dfrac{\beta_T^i}{\Gamma(1+{{i}/{2}})}\,p_0(t-s,x,x'),\quad 0\le s< t\le T,x,x'\in\mathbb{R}^d,\end{equation}
where
 $\Gamma({\cdot})$
is the gamma function and
 \begin{gather}\beta_T \colon= 2^{3d+1}\biggl(\dfrac{\hat\lambda_0}{\breve{\lambda}_0}\biggr)^{d+1}(\pi T)^{{{1}/{2}}}\left\{ \dfrac{\|b\|_\infty}{\sqrt {\hat{\lambda}_0}}+L_0 \left(d+2\sqrt d\right) \right\}\exp\biggl({\frac{\|b\|_\infty^2T}{4\hat\lambda_0}}\biggr),\notag \\p_0(t,x,x') \colon= \dfrac{\exp\left({-\frac{|x-x'|^2}{16\hat\lambda_0t}}\right)}{(2\pi\breve{\lambda}_0t)^{d/2}}.\end{gather}
Proof. The proof of Lemma A.1 is based on the parametrix method [Reference Konakov and Mammen13, Reference Lemaire and Menozzi15]. To complete the proof of Lemma A.1, it suffices to refine the argument of [Reference Konakov and Mammen13, Lemma 3.2]; for further details see also [Reference Lemaire and Menozzi15, pages 1660–1662]. Under
 $\|b\|_\infty<\infty$
and
 $({\bf A3})$
,
 $X_t$
admits a smooth transition density p(s,t,x,y) at the point y, given
 $X_s=x$
, such that
 \begin{equation}\begin{aligned}\partial_tp(s,t,x,y)&=L^*p(s,t,x,y),&\ & p(s,t,x,\cdot)=\delta _x({\cdot}),\quad t\downarrow s,\\\partial_sp(s,t,x,y)&=-Lp(s,t,x,y), &\ & p(s,t,\cdot,y)=\delta _y({\cdot}),\quad s\uparrow t,\end{aligned}\end{equation}
where L is the infinitesimal generator of (1.1) and
 $L^*$
is its adjoint operator. For
 $t>s$
and
 $x,x'\in\mathbb{R}^d$
, let
 $ \tilde X^{s,x,x'}_t $
solve the frozen SDE
 \begin{equation}{\text{d}} \tilde X_t^{s,x,x'}=b(x')\,{\text{d}} t+\sigma(x')\,{\text{d}} W_t, \quad t>s, \quad \tilde X_s^{s,x,x'}=x\in\mathbb{R}^d ,\end{equation}
and let
 $\tilde p^{x'}(s,t,x,x')$
stand for its transition density at x’, given
 $\tilde X^{s,x,x'}_s=x$
. Evidently
 $\tilde p^{x'}$
admits the explicit form
 \begin{equation*}\tilde p^{x'}(s,t,x,x')=\dfrac{\exp\bigl({-\frac{1}{2(t-s)}\langle (\sigma\sigma^*)^{-1}(x')(x'-x-b(x')(t-s)),x'-x-b(x')(t-s)\rangle }\bigr)}{\sqrt {(2\pi(t-s))^d\mbox{det}((\sigma\sigma^*)(x'))}}.\end{equation*}
A direct calculation yields
 \begin{equation*}\partial_s\tilde p^{x'}(s,t,x,x')=-\tilde L^{x'}\tilde p^{x'}(s,t,x,x'),\quad t>s,\quad \tilde p^{x'}(s,t,\cdot,x')\rightarrow\delta _{x'}({\cdot}),\quad s\uparrow t,\end{equation*}
where
 $\tilde L^{x'}$
is the infinitesimal generator of (A.4). By (A.3) and (A.4), we derive from [Reference Konakov and Mammen13, (3.8)] that
 \begin{equation}p(s,t,x,x')=\tilde p^{x'}(s,t,x,x')+\int_s^t\int_{\mathbb{R}^d}p(s,u,x,z)H(u,t,z,x')\,{\text{d}} z\,{\text{d}} u,\end{equation}
where
 \begin{align} H(s,t,x, x')& \colon= \left(L-\tilde L^{x'}\right)\tilde p^{x'}(s,t,x,x')\notag \\ &=\langle b(x)-b(x'),\nabla \tilde p^{x'}(s,t,x,x')\rangle +\dfrac{1}{2}\langle (\sigma\sigma^*)(x)-(\sigma\sigma^*)(x'),\nabla^2 \tilde p^{x'}(s,t,x,x')\rangle _{\text{HS}}.\end{align}
In (A.5), iterating for p(s,u,x,z) gives
 \begin{equation}p(s,t,x,x')=\sum_{i=0}^\infty\left(\tilde p^{x'}\otimes H^{(i)}\right)(s,t,x,x'),\end{equation}
where
 $\tilde p\otimes H^{(0)}\colon= \tilde p$
and
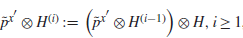 $\tilde p^{x'}\otimes H^{(i)}\colon= \left(\tilde p^{x'}\otimes H^{(i-1)}\right)\otimes H,i\ge 1$
, with
 \begin{equation*}(f\otimes g)(s,t,x,x')\colon= \int_s^t\int_{\mathbb{R}^d}f(s,u,x,z)g(u,t,z,y)\,{\text{d}}u\,{\text{d}} z.\end{equation*}
If we can claim that
 \begin{equation}|\tilde p\otimes H^{(i)}|(s,t,x,x')\le\dfrac{\exp\bigl({\frac{\|b\|_\infty^2T}{2\hat\lambda_0}}\bigl)\beta_T^i}{\Gamma(1+{{i}/{2}})}\,p_0(t-s,x,x'),\end{equation}
in which
 $\beta_T,p_0$
were introduced in (A.2), then (A.1) follows from (A.7) and (A.8). Below it suffices to show that (A.8) holds true. By means of (2.10) and
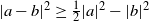 $|a-b|^2\ge\frac{1}{2}|a|^2-|b|^2$
,
 $a,b\in\mathbb{R}^d$
, it follows from (1.2) and
 $\|b\|_\infty<\infty$
that
 \begin{align}|\nabla\tilde p|(s,t,x,x')&\le\dfrac{ \,\sqrt {\hat\lambda_0}\exp\bigl({\frac{\|b\|_\infty^2T}{4\hat\lambda_0}}\bigr)}{\breve{\lambda}_0\sqrt {t-s}} p_0(t-s,x,x'),\notag \\ \|\nabla^2\tilde p\|_{\text{HS}}(s,t,x,x')&\le\dfrac{ (\sqrt d+{{4}/{\text{{e}}}})\exp\bigl({\frac{\|b\|_\infty^2T}{4\hat\lambda_0}}\bigr)}{\breve{\lambda}_0(t-s)}\dfrac{\exp\bigl({-\frac{|x'-x|^2}{8\hat\lambda_0(t-s)}}\bigr)}{(2\pi\breve{\lambda}_0(t-s))^{d/2}}.\end{align}
Thus, combining (2.10) with (A.9), together with
 $\|b\|_\infty<\infty$
and (1.3), enables us to obtain
 \begin{equation}|H|(s,t,x,x') \le \dfrac{ 2\hat\lambda_0 \left\{ \|b\|_\infty/\sqrt {\hat\lambda_0}+L_0 \left(d+2\sqrt d\right)\right\}\exp\left({\frac{\|b\|_\infty^2T}{4\hat\lambda_0}}\right)}{\breve{\lambda}_0\sqrt {t-s}}\,p_0(t-s,x,x').\end{equation}
By
 \[\int_s^t(t-u)^{-{{1}/{2}}}(u-s)^\alpha\,{\text{d}}u=(t-s)^{\alpha+{{1}/{2}}}B\biggl(1+\alpha,\frac12\biggr),\quad t>s,\ \alpha>-1,\]
we have
 \begin{equation*}\Lambda_i(s,t)\colon= \int_s^t\cdots \int_s^{u_{i-1}}(t-u_1)^{-{{1}/{2}}} \cdots(u_{i-1}-u_i)^{-{{1}/{2}}}\,{\text{d}} u_i\cdots\,{\text{d}} u_1=\dfrac{(\pi(t-s))^{{{i}/{2}}}}{\Gamma(1+{{i}/{2}})},\quad i\ge 1.\end{equation*}
Hence, taking advantage of
 $\|b\|_\infty<\infty$
, (1.2), and (A.10), as well as
 \begin{equation*}\int_{\mathbb{R}^d}p_0(u-s,x,z) p_0(t-u,y,z) \,{\text{d}}z=\biggl(\dfrac{8\hat\lambda_0}{\breve{\lambda}_0}\biggr)^d p_0(t-s,x,x'),\quad s<u<t ,\end{equation*}
yields (A.8).
For
 $x,x'\in\mathbb{R}^d$
and
 $j\ge 0, $
let
 $ (\tilde X^{(\delta),j,x,x'}_{i\delta })_{i\ge j}$
solve the following frozen EM scheme associated with (1.1):
 \begin{equation*}\tilde X^{(\delta),j,x,x'}_{(i+1)\delta }=\tilde X^{(\delta),j,x,x'}_{i\delta }+b(x')\delta +\sigma(x')(W_{(i+1)\delta }-W_{i\delta }),\quad i\ge j,\quad \tilde X_{j\delta }^{(\delta),j,x,x'}=x.\end{equation*}
Write
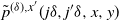 $\tilde p^{(\delta),x'}(j\delta ,j'\delta ,x,y)$
by the transition density of
 $ \tilde X^{(\delta),j,x,x'}_{j'\delta }$
at the point y, given
 ${ \tilde X^{(\delta),j,x,x'}_{j\delta }=x}$
.
The following lemma reveals explicit upper bounds of coefficients with regard to the Gaussian bound of the discrete-time EM scheme.
Lemma A.2. Under
 $\|b\|_\infty<\infty$
and
 $({\bf A3})$
, for any
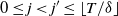 $0\le j<j'\le \lfloor T/\delta \rfloor$
,
 \begin{equation}p^{(\delta)}(j\delta ,j'\delta ,x,x')\le\exp\biggl({\frac{\|b\|_\infty T}{2\hat\lambda_0}}\biggr)\sum_{k=0}^{\infty}\dfrac{(\sqrt {\pi T}\hat C_T((1+24d)\hat\lambda_0/\breve{\lambda}_0)^d)^k}{\Gamma(1+{{k}/{2}})}\dfrac{\text{{e}}\bigl({-\frac{|x'-x|^2}{4(1+24d)\hat\lambda_0(j'-j)\delta }}\bigr)}{(2\pi\breve{\lambda}_0(j'-j)\delta)^{d/2}}.\end{equation}
Proof. To obtain (A.11), we refine the proof of [Reference Lemaire and Menozzi15, Lemma 4.1]. For
 $\psi\in C^2(\mathbb{R}^d;\mathbb{R})$
and
 $j\ge 0$
, set
 \begin{align*}\bigl(\mathscr{L}_{j\delta }^{ (\delta) }\psi\bigr)(x) & \colon=\delta ^{-1}\bigl\{\mathbb E\bigl(\psi\bigl(X_{(j+1)\delta }^{(\delta)}\bigr) \mid X_{j\delta }^{(\delta)}=x\bigr)-\psi(x) \bigr\},\\\bigl(\hat{\mathscr{L}}_{j\delta }^{ (\delta) }\psi\bigr)(x) & \colon= \delta ^{-1}\bigl\{\mathbb E\psi\bigl(\tilde X^{(\delta),j,x,x'}_{(j+1)\delta }\bigr) -\psi(x)\bigr\} ,\end{align*}
and
 \begin{equation*}H^{(\delta)}(j\delta ,j'\delta ,x,x')\colon= \bigl(\mathscr{L}_{j\delta }^{ (\delta)}-\hat{\mathscr{L}}_{j\delta }^{ (\delta) }\bigr)\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x,x'),\quad j'\ge j+1.\end{equation*}
In what follows, let
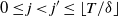 $0\le j<j'\le\lfloor T/\delta \rfloor$
. According to [Reference Konakov and Mammen13, Lemma 3.6], we have
 \begin{equation}p^{(\delta)}(j\delta ,j'\delta ,x,x')=\sum_{k=0}^{j'-j}(\tilde p^{(\delta),x'}\otimes_\delta H^{(\delta),(k)})(j\delta ,j'\delta ,x,x'),\end{equation}
where
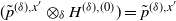 $(\tilde p^{(\delta),x'}\otimes_\delta H^{(\delta),(0)})=\tilde p^{(\delta),x'}$
,
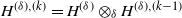 $H^{(\delta),(k)} =H^{(\delta)}\otimes_\delta H^{(\delta),(k-1)}$
, with
 $\otimes_\delta $
being the convolution-type binary operation defined by
 \begin{equation*}(f\otimes_\delta g)(j\delta ,j'\delta ,x,x')=\delta \sum_{k=j}^{j'-1}\int_{\mathbb{R}^d}f(j\delta ,k\delta ,x,u)g(k\delta ,j'\delta ,u,x')\,{\text{d}}u.\end{equation*}
If the assertion
 \begin{equation}H^{(\delta)}(j\delta ,j'\delta ,x,x')\le \dfrac{\hat C_T}{\sqrt {(j'-j)\delta }}\dfrac{\exp\left({-\frac{| x'-x|^2}{4(1+24d)\hat\lambda_0\left(j'-j\right)\delta }}\right)}{(2\pi\breve{\lambda}_0(j'-j)\delta)^{d/2}}\end{equation}
holds true, where
 $\hat C_T$
was given in (2.1), then (A.11) follows due to (A.12) by an induction argument. So, in order to complete the proof of Lemma A.2, it remains to verify (A.13). First of all, we show (A.13) for
 $j'=j+1$
. By the definition of
 $H^{(\delta)}$
, observe from (1.2) that
 \begin{align*} & |H^{(\delta)}|(j\delta ,(j+1)\delta ,x,x')\\ &\quad =\dfrac{1}{\delta }\left|p^{(\delta)}-\tilde p^{(\delta),x'}\right|\left(j\delta ,(j+1)\delta ,x,x'\right) \\ &\quad \le\dfrac{1}{\delta (2\pi\breve{\lambda}_0\delta)^{d/2}}\biggl\{\biggl|\exp\biggl({-\frac{1}{2\delta }\left|\left(\sigma\sigma^*\right)^{-{{1}/{2}}}(x)\left(x'-x-b(x)\delta\right)\right|^2}\biggr)\\ &\quad\quad\, -\exp\biggl({-\frac{1}{2\delta }\left|\left(\sigma\sigma^*\right)^{-{{1}/{2}}}(x)\left(x'-x-b(x')\delta\right)\right|^2}\biggr)\biggr|\\ &\quad\quad\, +\biggl|\exp\biggl({-\frac{1}{2\delta }\langle (\sigma\sigma^*)^{-1}(x)(x'-x-b(x')\delta),x'-x-b(x')\delta \rangle }\biggr)\\ &\quad\quad\, -\exp\biggl({-\frac{1}{2\delta }\langle (\sigma\sigma^*)^{-1}(x')(x'-x-b(x')\delta),x'-x-b(x')\delta \rangle }\biggr)\biggr|\\ &\quad\quad\, +\dfrac{1}{2\breve{\lambda}_0^d}\exp\biggl({-\frac{1}{2\delta }\left|\left(\sigma\sigma^*\right)^{-{{1}/{2}}}(x')\left(x'-x-b(x')\delta\right)\right|^2}\biggr) |\mbox{det}((\sigma\sigma^*)(x'))- \mbox{det}((\sigma\sigma^*)(x))| \biggr\}\\ &\quad =\!:\, \dfrac{1}{\delta (2\pi\breve{\lambda}_0\delta)^{d/2}}\{\Lambda_1+\Lambda_2+\Lambda_3\}.\end{align*}
Next we aim to estimate
 $\Lambda_1,\Lambda_2,\Lambda_3$
one by one. By
 $\|b\|_\infty<\infty$
, (1.2), and (2.10), it follows from the first fundamental theorem of calculus that
 \begin{equation} |\Lambda_1| \le2\sqrt {\delta /\breve{\lambda}_0}\|b\|_\infty \,\exp\biggl({\frac{\|b\|_\infty^2\delta }{\hat\lambda_0}}\biggr)\,\exp\biggl({-\frac{|x-x'|^2}{8\hat\lambda_0\delta }}\biggr).\end{equation}
 \begin{equation*}\|(\sigma\sigma^*)^{-1}(x)-(\sigma\sigma^*)^{-1}(x')\|_{\text{HS}} \le2\breve{\lambda}_0^{-2}\sqrt {d\hat \lambda_0}L_0|x-x'|.\end{equation*}
By invoking
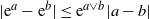 $|\text{{e}}^a-\text{{e}}^b|\le\text{{e}}^{a\vee b} |a-b|$
,
 $a,b\in\mathbb{R}$
, and utilizing
 $\|b\|_\infty<\infty$
, (1.2), and (2.10), this yields
 \begin{equation} |\Lambda_2|\le4\sqrt {d\delta }L_0(\hat\lambda_0/\breve{\lambda}_0)^{2}\,\exp\biggl({\frac{\|b\|_\infty^2\delta }{4\hat\lambda_0}}\biggr)\,\exp\biggl({-\frac{|x-x'|^2}{16\hat\lambda_0\delta }}\biggr).\end{equation}
Also, making use of
 $\|b\|_\infty<\infty$
, (1.2) and (2.10), in addition to
 \begin{equation*}|\mbox{det}((\sigma\sigma^*)(x))-\det((\sigma\sigma^*)(x'))| \le 2d^{{{d}/{2}}+1}d! \hat\lambda_0^{d-{{1}/{2}}} L_0|x-x'|,\end{equation*}
due to (1.2) and (1.3), we arrive at
 \begin{equation}|\Lambda_3|\le \sqrt 2d^{{{d}/{2}}+1}d! (\hat\lambda_0/\breve{\lambda}_0)^{d}L_0\sqrt {\delta } \,\exp\biggl({ \frac{\|b\|_\infty^2\delta }{2\hat\lambda_0}}\biggr) \,\exp\biggl({-\frac{|x'-x|^2}{8\hat\lambda_0\delta }}\biggr).\end{equation}
We therefore conclude that (A.13) holds with
 $j'=j+1$
by taking (A.14)–(A.16) into account. Below, we are going to show that (A.13) is still available for
 $j'>j+1$
. According to the definition of
 $H^{(\delta)}$
,
 \begin{align*} &H^{(\delta)}(j\delta ,j'\delta ,x,x')\\&=\dfrac{1}{\delta (2\pi)^{m/2}}\biggl\{ \int_{\mathbb{R}^m} \text{{e}}^{-{{|z|^2}/{2}}} \bigl\{\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x+\Gamma_z(x),x')-\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x,x')\bigr\}\,{\text{d}}z\\&\quad\, - \int_{\mathbb{R}^m}\text{{e}}^{-{{|z|^2}/{2}}}\bigl\{\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x+\Gamma_z(x'),x')-\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x,x') \bigr\}\,{\text{d}} z \biggr\},\end{align*}
where
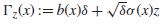 $\Gamma_z(x)\colon= b(x)\delta +\sqrt \delta \sigma(x)z$
,
 $x\in\mathbb{R}^d$
,
 $z\in\mathbb{R}^m$
. By Taylor’s expansion, we also have
 \begin{align*} &H^{(\delta)}(j\delta ,j'\delta ,x,x')\\ &\quad =\dfrac{1}{\delta (2\pi)^{m/2}}\biggl\{\int_{\mathbb{R}^m} \text{{e}}^{-{{|z|^2}/{2}}} \langle \nabla\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x,x'),\Gamma_z(x)-\Gamma_z(x')\rangle \,{\text{d}} z\\&\quad\quad\, + \int_{\mathbb{R}^m}\text{{e}}^{-{{|z|^2}/{2}}} \left\langle \nabla^2\tilde p^{(\delta),x'}\left((j+1)\delta ,j'\delta ,x,x'\right),\left(\Gamma_z\Gamma^*_z\right)(x)-\left(\Gamma_z\Gamma^*_z\right)(x')\right\rangle _{\text{HS}}\,{\text{d}} z\biggr\} \\&\quad\quad\, +\dfrac{1}{2\delta (2\pi)^{m/2}}\int_{\mathbb{R}^m}\int_0^1(1-\theta)^2\text{{e}}^{-{{|z|^2}/{2}}}\bigl\{\nabla_{\Gamma_z(x)}^3\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x+\theta\Gamma_z(x),x')\\&\quad\quad\, -\nabla_{\Gamma_z(x')}^3\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x+\theta\Gamma_z(x'),x')\bigr\} \,{\text{d}}\theta\,{\text{d}} z\\&\quad =\!:\, \Pi_1+\Pi_2+\Pi_3,\end{align*}
where
 $\nabla^i$
means the ith-order gradient operator. Employing
 \begin{align*}\int_{\mathbb{R}^m}\text{{e}}^{-{{|z|^2}/{2}}}\,\text{trace}(A\sigma(x)zz^*\sigma(x)\,{\text{d}}z & =\int_{\mathbb{R}^m}\text{{e}}^{-{{|z|^2}/{2}}}z^*\sigma^*(x)A\sigma(x)z\,{\text{d}}z\\&=(2\pi)^{m/2}\,\text{trace}(\sigma^*(x)A\sigma(x))\end{align*}
for a symmetric
 $d\times d$
-matrix and
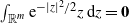 $\int_{\mathbb{R}^m}\text{{e}}^{-{{|z|^2}/{2}}}z\,{\text{d}} z={\bf0}$
gives
 \begin{equation*}\Pi_1+\Pi_2=H((j+1)\delta ,j'\delta ,x,x')+\dfrac{\delta }{2}\left\langle \nabla^2\tilde p^{(\delta),x'}\left((j+1)\delta ,j'\delta ,x,x'\right),(bb^*)(x)-\left(bb^*\right)(x')\right\rangle _{\text{HS}},\end{equation*}
where H was defined as in (A.6) with
 $p^{x'} $
replaced by
 $\tilde p^{(\delta),x'}$
. Equations (A.9) and (A.10) enable us to obtain
 \begin{align}&|\Pi_1|+|\Pi_2| \notag \\&\quad \le\dfrac{2^{{{(d+1)}/{2}}}\exp\bigl({\frac{\|b\|_\infty^2T}{4\hat\lambda_0}}\bigr)}{\breve{\lambda}_0}\Bigl\{ 2\sqrt {\hat\lambda_0} \|b\|_\infty+ (\|b\|_\infty^2+2\hat\lambda_0L_0\sqrt d)(\sqrt d+2) \Bigr\}\dfrac{p_0((j'-j)\delta ,x,x')}{\sqrt {(j'-j)\delta }}.\end{align}
Note that
 $\Pi_3$
can be reformulated as
 \begin{align*}\Pi_3&=\dfrac{1}{2\delta (2\pi)^{m/2}}\int_{\mathbb{R}^m}\int_0^1(1-\theta)^2\text{{e}}^{-{{|z|^2}/{2}}}\bigl\{\nabla_{\Gamma_z(x)}^3\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x+\theta\Gamma_z(x'),x')\\&\quad\, -\nabla_{\Gamma_z(x')}^3\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x+\theta\Gamma_z(x'),x')\bigr\} \,{\text{d}}\theta\,{\text{d}}z\\&\quad\, +\dfrac{1}{2\delta (2\pi)^{m/2}}\int_{\mathbb{R}^m}\int_0^1(1-\theta)^2\text{{e}}^{-{{|z|^2}/{2}}}\bigl\{\nabla_{\Gamma_z(x)}^3\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x+\theta\Gamma_z(x),x')\\&\quad\, -\nabla_{\Gamma_z(x)}^3\tilde p^{(\delta),x'}((j+1)\delta ,j'\delta ,x+\theta\Gamma_z(x'),x')\bigr\} \,{\text{d}}\theta\,{\text{d}} z\\& =\!:\, \Pi_{31}+\Pi_{32}.\end{align*}
By means of (1.2), (1.3) and (2.10), it follows that
 \begin{align}|\Pi_{31}|&\le \dfrac{2^{m+{{(d+21)}/{2}}}(L_0+2\|b\|_\infty)(\|b\|_\infty^2 +d\hat\lambda_0)(1+\sqrt {2(1+4d)\hat\lambda_0})\exp\bigl({\frac{3\|b\|_\infty^2T}{8d\hat\lambda_0}}\bigr)}{\breve{\lambda}_0^{{{3}/{2}}}((j'-j)\delta)^{{{1}/{2}}}}\notag \\ &\quad\,\times\dfrac{\exp\bigl({-\frac{|x'-x |^2}{8(1+4d)\hat\lambda_0(j'-j)\delta }}\bigr)}{(2\pi\breve{\lambda}_0(j'-j)\delta)^{d/2}},\end{align}
Also, by exploiting (1.2), and (2.10), we infer from Taylor expansion that
 \begin{align}|\Pi_{32}|&\le\dfrac{2^{m+{{(d+23)}/{2}}}(L_0+2\|b\|_\infty)\left(\|b\|_\infty^3+\left(d\hat\lambda_0\right)^{{{3}/{2}}}\right)\left(1+\sqrt {2(1+24d)\hat\lambda_0}\right)\exp\left({\frac{(6\|b\|_\infty^2+\|b\|_\infty)T}{24d\hat\lambda_0}}\right)}{\breve{\lambda}_0^2((j'-j)\delta)^{{{1}/{2}}}}\notag \\ &\quad\, \times\dfrac{\exp\left({-\frac{| x'-x|^2}{4(1+24d)\hat\lambda_0(j'-j)\delta }}\right)}{(2\pi\breve{\lambda}_0(j'-j)\delta)^{d/2}}.\end{align}
Consequently, (A.13) follows from (A.17), (A.18), and (A.19).
Acknowledgements
We are indebted to the referees for their valuable comments which have greatly improved our earlier version.
Funding information
This paper is supported in part by National Natural Science Foundation of China (grants 11771326, 11801406, 11831014, 11901604, 12071340). The third author is also supported by the Emerging Interdisciplinary Project disciplinary funding of CUFE.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


