



1. Evolution systems and comparison of Markov processes
Stochastic ordering and comparison results for Markov processes are basic problems in probability theory. They have a long history and are motivated by a number of applications in a variety of fields (see [Reference Cox, Fleischmann and Greven4], [Reference Criens5], [Reference Criens6], [Reference Daduna and Szekli7], [Reference Krasin and Melnikov14], [Reference Massey15], [Reference Rüschendorf16], [Reference Rüschendorf and Wolf17], and [Reference Rüschendorf, Schnurr and Wolf18]). Various approaches ranging from analytic to coupling methods have been developed to this end, sometimes in the context of specific models or specific applications. The most general comparison results so far have been obtained based on the theory of evolution systems on Banach spaces (see [Reference Rüschendorf, Schnurr and Wolf18]).
The transition operators  $T_{s,t}$,
 $s\le t$, of a Markov process X with values in a metric space S are an evolution system on the space of measurable bounded real-valued functions
 $\mathcal{L}_b(S)$. Since the transition operators are defined by conditional expectations, it is also possible to consider them on function spaces other than
 $\mathcal{L}_b(S)$. In order to stay within the framework of evolution systems, we consider the transition operators on Banach spaces. We also assume that the Banach spaces are spaces of integrable functions, in the sense that they are integrable with respect to all conditional laws. Generally, a family of bounded linear operators
 $(T_{s,t})_{s \le t}$ from a Banach space
 $\mathbb{B}$ to
 $\mathbb{B}$ is called an evolution system if, for all
 $0 \le s \le t \le u$, it satisfies
(1)
 $T_{s,s} = \textrm{id}$,
(2)
$T_{s,u} = T_{s,t} T_{t,u}$.


An evolution system is called strongly continuous if, for all  $f \in \mathbb{B}$, the
 $\mathbb{B}$-valued function
 $(s,t) \mapsto T_{s,t\,}f$ is continuous. If the evolution system is time-homogeneous, i.e. it only depends on the duration
 $t-s$, then
 $(T_t)_{t \ge 0}$ defined by
 $T_t f \coloneqq T_{0,t\,} f$ is a semigroup. An evolution system
 $(T_{s,t})_{s \le t}$ is called a Feller evolution system if it is strongly continuous and maps
 $C_0(S)$ into itself. If the evolution system maps
 $C_b(S)$ into itself, we call it a
 $C_b$-Feller evolution system. Further, if the transition operators of a Markov process X are a (
 $C_b$)-Feller evolution system, X is called a (
 $C_b$)-Feller process.
Right generators of evolution systems  $(T_{s,t})$ on a Banach space
 $\mathbb{B}$ are defined by
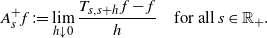 \begin{equation*}A_s^+f \coloneqq \lim_{h \downarrow 0} \dfrac{T_{s,s+h\,}f - f}{h} \quad \text{for all}\ s \in \mathbb{R}_+.\end{equation*}
This operator is defined on its domain  $\mathcal{D}(A^+_s)$, i.e. for all
 $f \in \mathbb{B}$ for which the limit exists in norm. Analogously we define the left generators on the domain
 $\mathcal{D}(A^-_s)$ by
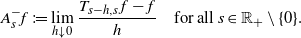 \begin{equation*}A_s^-f \coloneqq \lim_{h \downarrow 0} \dfrac{T_{s-h,s\,}f - f}{h} \quad \text{for all}\ s \in \mathbb{R}_+ \setminus \{0\}.\end{equation*}
If we weaken the limit in the definitions of the left and right generators to a pointwise limit, then the corresponding operators are called extended pointwise right and left generators (see [Reference Gulisashvili and van Casteren9]). The generators of an evolution system on a Banach space  $\mathbb{B}$ are linear operators on
 $\mathbb{B}$. In general the right generator and left generator do not coincide. In [Reference Böttcher1] an explicit example for a Markov process is given whose right and left generators do not coincide. There also, a condition is given to imply equality for the left and right generators.
Evolution systems arise as solutions of homogeneous evolution problems. Let  $(T_{s,t})_{s \le t \le T}$ be an evolution system on some Banach space
 $\mathbb{B}$. For
 $0 < t$ we set
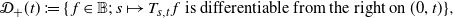 \begin{equation}\mathcal{D}_+(t) \coloneqq \{\, f \in \mathbb{B} ;\ s \mapsto T_{s,t\,}f \ \text{is differentiable from the right on (0, \textit{t})}\},\end{equation}
and
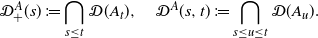 \begin{equation*}\mathcal{D}_+^A(s) \coloneqq \bigcap_{s \le t} \mathcal{D}(A_t), \quad \mathcal{D}^A(s,t) \coloneqq \bigcap_{s \le u \le t} \mathcal{D}(A_u).\end{equation*}
The following theorem restates basic connections of evolution systems to their right generators from [Reference Gulisashvili and van Casteren9] and states some corresponding representation results.
Theorem 1.1. Let  $(T_{s,t})_{s \le t \le T}$ be an evolution system on a Banach space
 $\mathbb{B}$ with right generators
 $(A^+_t)_{t \in [0,T)}$. Then the following assertions hold true.
(a) If
$(T_{s,t})_{s\le t \le T}$ is strongly continuous, then for fixed t the function $u\colon s \mapsto T_{s,t\,}f$ with $f \in \mathcal{D}_+(t)$ is a solution to the following final value problem on (0, t):
(1.2)
\begin{equation}\left\{\begin{aligned}\dfrac{\partial^+}{\partial s} u(s) &= -A^+_s u(s),\\[3pt]\lim_{s \uparrow t} u(s) &= f.\end{aligned}\right.\end{equation}
(b) For
$f \in \mathcal{D}_+^{A^+}(s)$, for some fixed $0 < s < T$, and for any $s < t < T$, the forward equation holds:
\begin{equation*} \dfrac{\partial^+}{\partial t} T_{s,t\,}f = T_{s,t}A^+_tf.\end{equation*}
(c) (Representation results) Let
$(T_{s,t})_{s\le t \le T}$ be strongly continuous and $f \in \mathcal{D}_+(t)$. Further, assume that the right derivative $({{{\partial^+}}/{{\partial u}}}) T_{u,t\,}f$ is integrable on [s,t]. Then the following integral representation of the evolution system holds true:
If
\begin{equation*}T_{s,t\,}f - f = \int_s^t A^+_u T_{u,t\,} f \,{\textrm{d}} u.\end{equation*}
$f \in \mathcal{D}^{A^+}(s,t)$, and the right derivative $({{{\partial^+}}/{{\partial u}}})T_{s,u\,}f$ is integrable on [s,t], then
(1.3)
\begin{equation}T_{s,t\,}f - f = \int_s^t T_{s,u}A^+_uf \,{\textrm{d}} u.\end{equation}


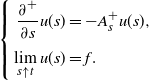


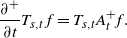


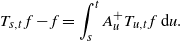


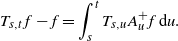
A similar integral representation also holds true for  $f \in \mathcal{D}^{A^-}(s,t)$ using the left derivative instead of the right derivative.
Theorem 1.2. Let  $(T_{s,t})_{s \le t \le T}$ be an evolution system on a Banach space
 $\mathbb{B}$ with left generators
 $(A^-_t)_{t \in (0,T]}$, and define
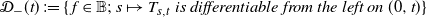 \begin{equation*}\mathcal{D}_-(t) \coloneqq \{\,f \in \mathbb{B};\ s \mapsto T_{s,t}\ \textit{is differentiable from the left on}\ (0,\textit{t})\}\end{equation*}
and
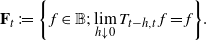 \begin{equation*}\textbf{F}_t \coloneqq \biggl\{\,f \in \mathbb{B}; \lim_{h \downarrow 0} T_{t-h,t\,}f = f \biggr\}.\end{equation*}
Then the following assertions hold.
(a) For
$0 < t < T$ and $f \in \mathcal{D}_-(t) \cap \textbf{F}_t$, the function $u\colon s \mapsto T_{s,t\,}f$ is a solution to the backward equation on (0, t):
\begin{equation*}\left\{\begin{aligned}\dfrac{\partial^-}{\partial s} u(s) &= -A^-_s u(s),\\[3pt]\lim_{s \uparrow t} u(s) &= f.\end{aligned}\right.\end{equation*}
(b) If
$(T_{s,t})_{s\le t \le T}$ is strongly continuous in s, $f \in \mathcal{D}_-(t)$, and the left derivative $({{{\partial^-}}/{{\partial s}}}) T_{s,t\,}f$ is integrable on [s,t], then the following integral representation of the evolution system holds:
\begin{equation*}T_{s,t\,}f - f = \int_s^t A^-_u T_{u,t\,} f \,{\textrm{d}} u.\end{equation*}

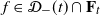

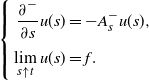


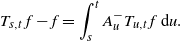
For further extensions and properties of the notion of left (right) generators, see [Reference Böttcher1], [Reference van Casteren2], and [Reference Köpfer13].
A basic result in the theory of evolution systems is the following integral representation for solutions to an inhomogeneous evolution problem (see [Reference Rüschendorf, Schnurr and Wolf18]). For fixed  $s,t \in \mathbb{R}_+$, let
 $(A_r)_{s \le r \le t}$ be a family of linear operators on a Banach space
 $\mathbb{B}$, and let
 $G \colon [s,t] \to \mathbb{B}$. A function
 $u\colon [s,t] \to \mathbb{B}$, right differentiable on (s, t) and such that
 $u(r) \in \mathcal{D}(A_r)$ for all
 $s \le r < t$, is called a solution to the inhomogeneous right evolution problem with boundary condition
 $f \in \mathbb{B}$ if
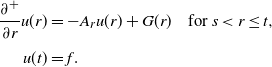 \begin{align*}\dfrac{\partial^+}{\partial r} u(r) &= -A_r u(r) + G(r)\quad \text{for}\ s<r\le t,\\[3pt] u(t) &= f.\end{align*}
If, moreover, u is continuous on [s, t], it is called a classical solution to the inhomogeneous right evolution problem.
On the other hand, for  $u\colon [s,t] \to \mathbb{B}$, left differentiable on (s, t) such that
 $u \in \mathcal{D}^{A}(s,t)$, u is a solution to the inhomogeneous left evolution problem with boundary condition
 $f \in \mathbb{B}$ if
 \begin{align*}\dfrac{\partial^-}{\partial r} u(r) &= -A_r u(r) + G(r)\quad \text{for}\ s
< r \le t,\\*u(t) &= f.\end{align*}
If u is continuous it is called a classical solution.
The representation result is as follows.
Theorem 1.3. Let  $(T_{s,t})_{s \le t}$ be a strongly continuous evolution system on a Banach space
 $\mathbb{B}$ with right generators
 $(A^+_t)_{t \ge 0}$. For fixed
 $t \in \mathbb{R}_+$, let
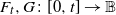 $F_t,G \colon [0,t] \to \mathbb{B}$ be such that
(a) the function
$r \mapsto T_{s,r}G(r)$ is integrable on fixed [s, t],(b)
$F_t$ solves the inhomogeneous right evolution problem for the operators $(A^+_s)_{s \le t}$,
\begin{equation*}\dfrac{\partial^+}{\partial r} F_t(r) = -A^+_r F_t(r) + G(r).\end{equation*}


Then the following representation holds:
 \begin{equation*}F_t(s) = T_{s,t}F_t(t) - \int_s^t T_{s,r} G(r) \,{\textrm{d}} r.\end{equation*}
The same representation result also holds true for the inhomogeneous left evolution problem for left generators of a strongly continuous evolution system (see [Reference Köpfer13]). The representation result is the basic tool for the general comparison theorem for Markov processes by means of evolution systems in [Reference Rüschendorf, Schnurr and Wolf18], stating an ordering result of Markov processes with respect to function classes  $\mathcal{F}$. Therefore, let X and Y be Markov processes with corresponding transition operators
 $T^X$ and
 $T^Y$. Under some regularity conditions this result states that a propagation of order property for X, i.e.
 $f \in \mathcal{F}$, implies
 $T^X_{s,t\,}f \in \mathcal{F}$, and comparison of generators implies the stochastic ordering condition
 $X_t \le_{\mathcal{F}} Y_t$,
 $t \ge 0$.
The following is a modification of this result holding true for single functions f. Note that for this case where  $\mathcal{F} = \{\,f \}$, the propagation of order property does not make sense. We let
 $\mathcal{D}_+^X(t)$ and
 $\mathcal{D}_+^Y(t)$ denote the sets from (1.1) corresponding to the particular transition operators.
Theorem 1.4. Assume that  $(T^X_{s,t})_{s \le t}$ and
 $(T^Y_{s,t})_{s \le t}$ are strongly continuous evolution systems on a Banach space
 $\mathbb{B}$ and let
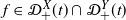 $f \in \mathcal{D}_+^X(t) \cap \mathcal{D}_+^Y(t)$. If, for fixed
 $t \in \mathbb{R}_+$, it holds that, for all
 $s \le t$,
(a)
$T^X_{s,t\,}f \in \mathcal{D}(A_s^{Y+})$,(b)
$r \mapsto T^Y_{s,r}(A^{X+}_r - A^{Y+}_r) T^X_{s,r}f$ is integrable on [s, t],(c)
$A^{X+}_s T^X_{s,t\,}f \le A^{Y+}_s T^X_{s,t\,}f$ a.s.,
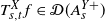
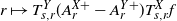
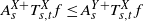
then
 \begin{equation*}T^X_{s,t\,} f \le T^Y_{s,t\,} f \quad a.s.\ for\ all\ s \le t.\end{equation*}
Proof. Set 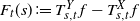 $F_t(s) \coloneqq T^Y_{s,t\,}f - T^X_{s,t\,}f$. Then, by (1.2),
 $F_t$ satisfies the equation
 \begin{equation*}\dfrac{\partial^+}{\partial s} F_t(s) = - A^{Y+}_s T^Y_{s,t\,}f + A^{X+}_s T^X_{s,t\,}f,\end{equation*}
with boundary condition  $F_t(t) = 0$. This equation can be written as
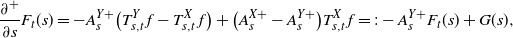 \begin{equation}\dfrac{\partial^+}{\partial s} F_t(s) = - A^{Y+}_s \big(T^Y_{s,t\,}f - T^X_{s,t\,}f\big) + \big(A^{X+}_s - A^{Y+}_s\big) T^X_{s,t\,}f =: - A^{Y+}_s F_t(s) + G(s),\end{equation}
where 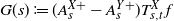 $G(s)\coloneqq (A^{X+}_s - A^{Y+}_s) T^X_{s,t\,}f$. The terms in the equation are well-defined by Theorem 1.1 and assumption (a). Hence
 $F_t$ solves an inhomogeneous right evolution problem.
From the strong continuity of the evolution systems we deduce that  $F_t$ is continuous in s. Hence
 $F_t$ is a classical solution to the inhomogeneous right evolution problem (1.4).
We show that  $F_t$ is non-negative; then the assertion follows. To see this we apply the integral representation in Theorem 1.3 to
 $F_t$, to obtain
 \begin{equation*}F_t(s) = T^Y_{s,t\,} F_t(t) - \int_s^t T^Y_{s,r} G(r) \,{\textrm{d}} r = \int_s^t T^Y_{s,r} (-G(r)) \,{\textrm{d}} r.\end{equation*}
From assumption (c) it follows that  $-G(r) \ge 0$ a.s. and hence the assertion follows from the fact that the transition operators of Markov processes are positivity-preserving operators.
A similar comparison result also holds for left generators (see [Reference Köpfer13]).
2. The martingale comparison method for Markov processes
For the comparison of a semimartingale X to a Markovian semimartingale Y, Gushchin and Mordecki [Reference Gushchin and Mordecki10] introduced the martingale comparison method. The basic step of this approach is to establish that the linking process
 \begin{equation*}\big(T^X_{s,t\,}f(Y_s)\big)_{0 \le s \le t}\end{equation*}
is a submartingale for fixed t. Note that 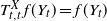 $T^X_{t,t\,}f(Y_t) = f(Y_t)$ and
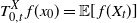 $T^X_{0,t\,}f(x_0) = \mathbb{E}[\,f(X_t)]$, assuming that
 $X_0 = x_0 = Y_0$. Thus
 $(T^X_{s,t\,}f(Y_s))$ gives a link between the processes X and Y. From the submartingale property of the linking process, as a direct consequence, the following comparison result is obtained:
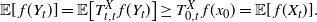 \begin{equation}\mathbb{E}[\,f(Y_t)] = \mathbb{E}\big[T^X_{t,t\,}f(Y_t)\big] \ge T^X_{0,t\,}f(x_0) = \mathbb{E}[\,f(X_t)].\end{equation}
If 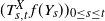 $(T^X_{s,t\,}f(Y_s))_{0 \le s \le t}$ is a supermartingale, the reverse inequality holds. The proof of the submartingale property is essentially based on Itô’s formula and on a version of Kolmogorov’s backwards equation for Markovian semimartingales. In this paper we transfer this martingale comparison approach to the comparison of general Markov processes. As main tool we make essential use of the characterization of Markov processes by the martingale problem. We transfer this classical result (see e.g. [Reference Ethier and Kurtz8, Chapter 4, Proposition 1.7]) to the frame of Markov processes with transition operators defined on a Banach space
 $\mathbb{B}$ of integrable functions; for a detailed exposition see [Reference Köpfer13].
Theorem 2.1. Let  $(X_t)_{t \in [0,T]}$ be a Markov process with strongly continuous transition operators
 $(T_{s,t\,})_{s \le t \le T}$ on some Banach space
 $\mathbb{B}$ and corresponding right generators
 $(A^+_t)_{t \in [0,T)}$. If for
 $f \in \mathcal{D}^{A+}_+(0)$ the right derivative
 $({{{\partial^+}}/{{\partial t}}}) T_{s,t\,}f$ is integrable on [0,T), then the process
 $(M_t)_{t \in [0,T]}$ defined by
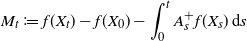 \begin{equation*}M_t \coloneqq f(X_t) - f(X_0) - \int_0^t A^+_s f(X_s) \,{\textrm{d}} s\end{equation*}
is a martingale with respect to its natural filtration 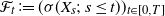 $\mathcal{F}_t \coloneqq (\sigma(X_s;\ s \le t))_{t \in [0,T]}$.
Proof. The integrability is clear since the Banach space is assumed to consist of integrable functions and the right generator  $(A^+_t)_{t \in [0,T)}$ maps the Banach space into itself. Let
 $0 \le s \le t$. Then, by the Markov property and equation (1.3), we have
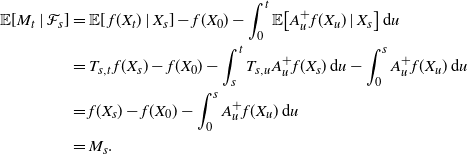 \begin{align*}\mathbb{E}[M_t \mid \mathcal{F}_s] &= \mathbb{E}[\,f(X_t)\mid X_s] - f(X_0) - \int_0^t \mathbb{E}\big[A^+_u f(X_u)\mid X_s\big] \,{\textrm{d}} u \\*&= T_{s,t\,}f(X_s) - f(X_0) - \int_s^t T_{s,u} A^+_u f(X_s)\,{\textrm{d}} u - \int_0^s A^+_u f(X_u) \,{\textrm{d}} u\\&= f(X_s) - f(X_0) - \int_0^s A^+_u f(X_u) \,{\textrm{d}} u\\*&= M_s.\end{align*}
This shows the assertion.
Remark 2.1. The integrability condition on  $({{{\partial^+}}/{{\partial t}}}) T_{s,t\,}f$ can be replaced by the assumption that
 $T_{s,.}f$ is absolutely continuous on [0, T); see [Reference Hewitt and Stromberg11, Example 18.41]. This also holds true for Theorems 1.4, 2.2, 2.3, and 2.4.
A similar martingale property also holds for the left generators. We will also make use of the martingale property for space–time functions f(t, x). To that end we state the following definition, a variant of the definition in [Reference van Casteren2] for general Banach spaces. The family of operators  $(A^+_t)_{t \in [0,T)}$ is here regarded as single operator
 $A^+$ on a space consisting of space–time functions
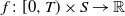 $f\colon [0,T) \times S \to \mathbb{R}$. Therefore it is important that the Banach space
 $\mathbb{B}$ on which each
 $A^+_t$ is defined can be extended reasonably to functions of the space–time process
 $\bar{\mathbb{B}}$, like
 $L^p(\mathbb{R}^d)$,
 $\mathcal{L}_b(\mathbb{R}^d)$ and the smooth functions vanishing at infinity
 $C_0^\infty(\mathbb{R}^d)$. Then a function f is in
 $\mathcal{D}(A^+)$ if, for all
 $t \in [0,T]$, it holds that
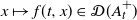 $x \mapsto f(t,x) \in \mathcal{D}(A^+_t)$ and if
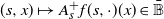 $(s,x) \mapsto A^+_s f(s,\cdot)(x) \in \bar{\mathbb{B}}$. We let
 $\mathcal{D}_+(A^+)$ denote the set of functions
 $f \in \mathcal{D}(A^+)$ which are right differentiable in the time variable.
 $\mathcal{D}_-(A^+)$ is defined analogously for the left derivatives.
Definition 2.1. A family of operators  $(A^+_t)_{t \in [0,T)}$ on some Banach space
 $\mathbb{B}$ is said to be a right generator of a Markov process X if, for all
 $f \in \mathcal{D}_+(A^+)$, for all
 $x \in S$, and for all
 $s \le t$, it holds that
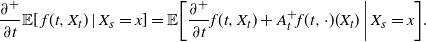 \begin{equation*}\dfrac{\partial^+}{\partial t} \mathbb{E} [\,f(t,X_t)\mid X_s = x ] = \mathbb{E} \biggl[ \dfrac{\partial^+}{\partial t} f(t,X_t) + A^+_t f(t,\cdot)(X_t) \biggm| X_s = x \biggr].\end{equation*}
A family of operators  $(A^-_t)_{t \ge 0}$ on
 $\mathbb{B}$ is said to be a left generator of X if we replace the right derivatives above by left derivatives.
We remark that the extended pointwise right and left generators  $(A^+_t)$ and
 $(A^-_t)$ of strongly continuous transition operators are also right and left generators in the sense of Definition 2.1 (see [Reference Köpfer13]).
With the help of this definition we can formulate the martingale property for the space–time process.
Theorem 2.2. Let  $(A^+_t)_{t \in [0,T)}$ be the right generator of a Markov process X in the sense of Definition 2.1. Then, for every
 $f \in \mathcal{D}_+(A^+)$ such that
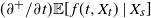 $({{{\partial^+}}/{{\partial t}}}) \mathbb{E}[\,f(t,X_t)\mid X_s]$ is integrable on [0,T), we find that
 \begin{equation*}M_t \coloneqq f(t,X_t) - f(0,X_0) - \int_0^t \biggl(\dfrac{\partial^+}{\partial s} + A^+_s\biggr)\, f(s,X_s) \,{\textrm{d}} s\end{equation*}
is a martingale with respect to the natural filtration  $(\mathcal{F}_t)_{t \in [0,T]}$.
Proof. Again the integrability is clear and the martingale property can be shown easily:
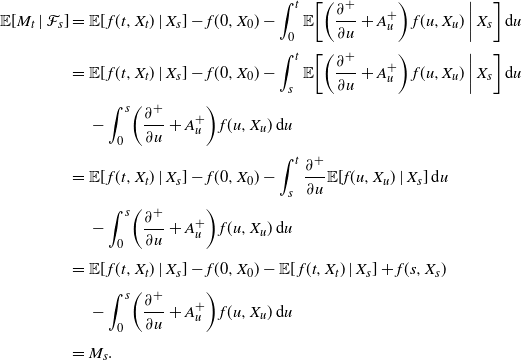 \begin{align*}\mathbb{E}[M_t\mid \mathcal{F}_s] &= \mathbb{E}[\,f(t,X_t)\mid X_s] - f(0,X_0) - \int_0^t\mathbb{E}\biggl[ \biggl(\dfrac{\partial^+}{\partial u} + A^+_u\biggr)\, f(u,X_u) \biggm|X_s \biggr] \,{\textrm{d}} u\\[3pt]
&= \mathbb{E}[\,f(t,X_t)\mid X_s] - f(0,X_0) - \int_s^t\mathbb{E}\biggl[ \biggl(\dfrac{\partial^+}{\partial u} + A^+_u\biggr)\, f(u,X_u)\biggm| X_s \biggr] \,{\textrm{d}} u\\[3pt]
&\quad\, - \int_0^s \biggl(\dfrac{\partial^+}{\partial u} + A^+_u\biggr)\, f(u,X_u) \,{\textrm{d}} u\\[3pt]
&= \mathbb{E}[\,f(t,X_t)\mid X_s] - f(0,X_0) - \int_s^t \dfrac{\partial^+}{\partial u} \mathbb{E} [ f(u,X_u)\mid X_s ] \,{\textrm{d}} u\\[3pt]
&\quad\, - \int_0^s \biggl(\dfrac{\partial^+}{\partial u} + A^+_u\biggr)\, f(u,X_u) \,{\textrm{d}} u\\[3pt]
&= \mathbb{E}[\,f(t,X_t)\mid X_s] - f(0,X_0) - \mathbb{E}[\,f(t,X_t)\mid X_s] + f(s,X_s)\\[3pt]
&\quad\, - \int_0^s \biggl(\dfrac{\partial^+}{\partial u} + A^+_u\biggr)\, f(u,X_u) \,{\textrm{d}} u\\[3pt]
&= M_s.\end{align*}
This completes the proof.
(a) In [Reference van Casteren2] a similar result is given under the assumption that the function f is continuously differentiable in the time variable.
(b) The proof of Theorem 2.2 can also be adapted for the extended pointwise right and left generators of the transition operators of X. Thus Theorem 2.1 also holds for the extended pointwise right and left generators.
The connection of Markov processes to martingales allows the introduction of further extensions of generators. Therefore we give some definitions which are motivated by Theorem 2.1. They are variants of definitions from [Reference Çinlar, Jacod, Protter and Sharpe3] for time-inhomogeneous Markov processes.
Definition 2.2. Let  $(A_t)_{t \ge 0}$ be a family of operators on a Banach space with domains
 $(\mathcal{D}(A_t))_{t \ge 0}$. It is called the extended generator of a Markov process X if
 $\mathcal{D}_+^A(0)$ consists of measurable functions
 $f\colon S \to \mathbb{R}$ such that, for all
 $t \ge 0$,
 \begin{equation*}f(X_t) - f(X_0) - \int_0^t A_sf(X_s) \,{\textrm{d}} s\end{equation*}
is well-defined and a local martingale.
Note that it makes no sense to distinguish between left and right generators since here the interpretation as partial semi-differential of the underlying evolution system is not taken. Also, a restriction to Banach spaces as domains is not necessary.
The same definition can be given for the space–time process. Recall that the Banach space under consideration has to be extendable to the space–time process.
Definition 2.3. Let  $(A^+_t)_{t \ge 0}$ be a family of operators on a Banach space with domains
 $(\mathcal{D}(A^+_t))_{t \ge 0}$. It is called the extended right generator of the space–time process (id, X) if
 $\mathcal{D}_+(A^+)$ consists of measurable functions
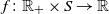 $f\colon \mathbb{R}_+ \times S \to \mathbb{R}$ such that, for all
 $t \ge 0$,
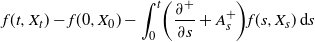 \begin{equation*}f(t,X_t) - f(0,X_0) - \int_0^t \biggl(\dfrac{\partial^+}{\partial s} + A^+_s \biggr)f(s,X_s) \,{\textrm{d}} s\end{equation*}
is well-defined and a local martingale.
If the derivatives above are replaced by left derivatives, we call the corresponding family of operators extended left generators.
The extended generators can be expanded to integrals other than the Lebesgue integral. This is particularly interesting, for example, if we consider general Markovian semimartingales with fixed jump times.
Definition 2.4. Let  $F \in \mathscr{V}^+$ be predictable. A family of operators
 $(A_t)_{t \ge 0}$,
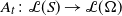 $A_t\colon \mathcal{L}(S) \to \mathcal{L}(\Omega)$ is called the F-random generator of a Markov process X if
 $\mathcal{D}_+^A(0)$ consists of functions
 $f\colon \mathbb{R}^d \to \mathbb{R}$ for which
 $(A_tf)_{t \ge 0}$ is an optional process such that
 $Af \cdot F \in \mathscr{V}$ is predictable, and
 \begin{equation*}f(X_t) - f(X_0) - \int_0^t A_sf \,{\textrm{d}} F_s\end{equation*}
is well-defined and a local martingale.
Based on the martingale problem, we obtain a transfer of the martingale comparison method to the comparison of general Markov processes. In the following theorem we consider the transition operators  $T^X_{s,t\,}$ for fixed t and
 $f \in \mathbb{B}$ as a function
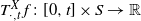 $T^X_{\cdot,t\,}f\colon [0,t] \times S \to \mathbb{R}$. Hence we can insert the space–time process and obtain the connection to the martingale problem from Theorem 2.2. Note that we use generators in the sense of Definition 2.1. For processes X, Y we denote their (right) generators
 $A^{X+}$ and
 $A^{Y+}$. The following comparison result by the martingale method uses similar conditions as the comparison result Theorem 1.4 by the evolution approach.
Theorem 2.3. (Comparison by the martingale comparison method.) Let  $(T^X_{s,t})_{s \le t}$ and
 $(T^Y_{s,t})_{s \le t}$ be strongly continuous with right generators
 $(A^{X+}_s)_{s \ge 0}$ and
 $(A^{Y+}_s)_{s \ge 0}$. For
 $f \in \mathbb{B}$ and fixed
 $t \in \mathbb{R}_+$, assume that for all
 $s \le t$ the following holds:
(a)
$T^X_{\cdot,t\,}f \in \mathcal{D}_+\big(A^{X+}\big) \cap \mathcal{D}_+\big(A^{Y+}\big)$,(b)
$({{{\partial^+}}/{{\partial u}}})\mathbb{E}[T_{u,t\,}^Xf(X_u)\mid X_s]$ and $({{{\partial^+}}/{{\partial u}}})\mathbb{E}[T_{u,t\,}^Xf(Y_u)|Y_s]$ are integrable on [0, t],(c)
$\textrm{supp}\big(\mathbb{P}^{Y_s}\big) \subset \textrm{supp}\big(\mathbb{P}^{X_s}\big)$,(d)
$A^{X+}_s T^X_{s,t\,} f \le A^{Y+}_s T^X_{s,t\,} f$ a.s.
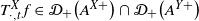
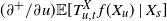
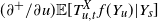
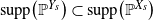
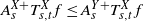
Then
 \begin{equation*}\mathbb{E}\big[\,f(Y_t)\big] \ge \mathbb{E}[\,f(X_t)].\end{equation*}
Proof. For the proof of the assertion, we establish that  $(T^X_{s,t}(Y_s))$ is a submartingale. By construction
 $(T_{s,t\,}^Xf(X_s))_{s \le t}$ is a martingale; this follows by the Markov property. For
 $u \le s$ we have
 \begin{align*}\mathbb{E}[T_{s,t\,}^Xf(X_s)\mid \mathcal{F}_u] &= \mathbb{E}[\mathbb{E}[\,f(X_t)\mid X_s]\mid \mathcal{F}_u]\\[3pt]&= \mathbb{E}[\mathbb{E}[\,f(X_t) \mid \mathcal{F}_s]\mid \mathcal{F}_u]\\[3pt]&= \mathbb{E}[\,f(X_t)\mid \mathcal{F}_u]\\[3pt]&= T_{u,t\,}^Xf(X_u).\end{align*}
On the other hand, by assumption (b) and Theorem 2.2,
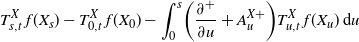 \begin{equation*}T_{s,t\,}^Xf(X_s) - T_{0,t\,}^Xf(X_0) - \int_0^s \biggl( \dfrac{\partial^+}{\partial u} + A^{X+}_u \biggr) T_{u,t\,}^Xf(X_u) \,{\textrm{d}} u\end{equation*}
is a martingale as well. It follows that the integral process
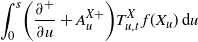 \begin{equation*}\int_0^s \biggl( \dfrac{\partial^+}{\partial u} + A^{X+}_u \biggr) T_{u,t\,}^Xf(X_u) \,{\textrm{d}} u\end{equation*}
is also a martingale starting at zero. Since it is an integral with respect to the Lebesgue measure, it is of finite variation and continuous. By [Reference Jacod and Shiryaev12, Corollary I.3.16] it follows that it is zero  $\lambda \times \mathbb{P}$ almost surely:
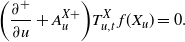 \begin{equation*}\biggl( \dfrac{\partial^+}{\partial u} + A^{X+}_u \biggr) T_{u,t\,}^Xf(X_u) = 0.\end{equation*}
Hence, for all  $x \in \textrm{supp}(\mathbb{P}^{X_u})$ except on a set of time points u of Lebesgue measure zero, we obtain
 \begin{equation*}\biggl( \dfrac{\partial^+}{\partial u} + A^{X+}_u \biggr) T_{u,t\,}^Xf(x) = 0.\end{equation*}
By assumption (c), this implies that
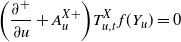 \begin{equation}\biggl( \dfrac{\partial^+}{\partial u} + A^{X+}_u \biggr) T_{u,t\,}^Xf(Y_u) = 0\end{equation}
 $\lambda \times \mathbb{P}$ almost surely. Therefore, by assumptions (a), (b) and Theorem 2.2 applied to
 $T_{s,t\,}^Xf$, we find that
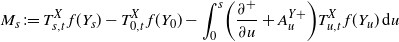 \begin{equation*}M_s \coloneqq T_{s,t\,}^Xf(Y_s) - T_{0,t\,}^Xf(Y_0) - \int_0^s \biggl( \dfrac{\partial^+}{\partial u} + A^{Y+}_u \biggr) T_{u,t\,}^Xf(Y_u) \,{\textrm{d}} u\end{equation*}
is a martingale. Combining this with (2.2) implies that
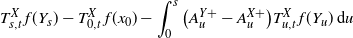 \begin{equation*}T_{s,t\,}^Xf(Y_s) - T_{0,t\,}^Xf(x_0) - \int_0^s \big( A^{Y+}_u - A^{X+}_u \big) T_{u,t\,}^Xf(Y_u) \,{\textrm{d}} u\end{equation*}
is a martingale. By assumption (d) the integral is non-negative, and it follows that  $\big(T_{s,t\,}^Xf(Y_s)\big)_{s \le t}$ has the representation
 \begin{equation*}T_{s,t\,}^Xf(Y_s) = T_{0,t\,}^Xf(x_0) + M_s + \int_0^s \big( A^{Y+}_u - A^{X+}_u \big) T_{u,t\,}^Xf(Y_u) \,{\textrm{d}} u.\end{equation*}
This is a submartingale since the integral is non-negative. The assertion then follows by inequality (2.1).
Remark 2.3. From the proof of Theorem 2.3 it follows in a similar way that the inverse inequality, 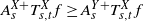 $A^{X+}_s T^X_{s,t\,}f \ge A^{Y+}_s T^X_{s,t\,}f$, implies that
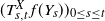 $(T^X_{s,t\,}f(Y_s))_{0 \le s \le t}$ is a supermartingale and hence the expectations are ordered the other way around, i.e.
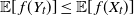 $\mathbb{E}[\,f(Y_t)] \le \mathbb{E}[\,f(X_t)]$.
Since we also have an analogous martingale property for left generators, we can transfer Theorem 2.3 to left generators.
Theorem 2.4. Let  $(T^X_{s,t})_{s \le t}$ and
 $(T^Y_{s,t})_{s \le t}$ be strongly continuous and
 $f \in \mathbb{B}$. For fixed
 $t \in \mathbb{R}_+$, assume that for all
 $s \le t$ we have
(a)
$T^X_{\cdot,t\,}f \in \mathcal{D}_-(A^{Y-}) \cap \mathcal{D}_-(A^{Y-})$,(b)
$({{{\partial^-}}/{{\partial u}}})\mathbb{E}[T_{u,t\,}^Xf(X_u)\mid X_s]$ and $({{{\partial^-}}/{{\partial u}}})\mathbb{E}[T_{u,t\,}^Xf(Y_u)|Y_s]$ are integrable on [0, t],(c)
$\textrm{supp}(\mathbb{P}^{Y_s}) \subset \textrm{supp}(\mathbb{P}^{X_s})$,(d)
$A^{X-}_s T^X_{s,t\,} f \le A^{Y-}_s T^X_{s,t\,} f$ a.s.
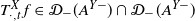
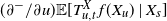
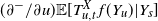
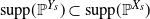
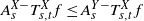
Then
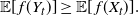 \begin{equation*}\mathbb{E}[\,f(Y_t)] \ge \mathbb{E}[\,f(X_t)].\end{equation*}
Proof. The proof is similar to the proof of Theorem 2.3.
The extended generators and the random generators are defined by a local martingale property. Since the results above rely on the martingale property, we are able to obtain similar results for the extended generators and the random generators. The main difference now is that we only have a local martingale property and we are not restricted to Banach spaces.
Let  $(A^{X+}_t)_{t \ge 0}$ and
 $(A^{Y+}_t)_{t \ge 0}$ be the extended right generators for X and Y; see Definition 2.3. Let
 $f\colon S \to \mathbb{R}$ be a function such that
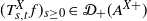 $(T^X_{s,t\,}f)_{s \ge 0} \in \mathcal{D}_+(A^{X+})$. By the martingale property of
 $(T^X_{s,t\,}f(X_s))_{s \ge 0}$, we obtain that,
 $\lambda \times \mathbb{P}$ almost surely,
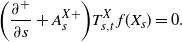 \begin{equation}\biggl(\dfrac{\partial^+}{\partial s} + A^{X+}_s \biggr) T^X_{s,t\,}f(X_s) = 0.\end{equation}
We then can undertake the same steps as in the proof of Theorem 2.3, which yields a local submartingale property for  $(T^X_{s,t\,}f(Y_s))_{s \ge 0}$. So we only need to specify the particular assumptions and make sure that
 $(T^X_{s,t\,}f(Y_s))_{s \ge 0}$ is a proper submartingale. Therefore we use the class (DL), which makes a local (sub-) martingale a proper martingale. A stochastic process X is of class (DL) if all
 $t \ge 0$,
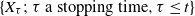 $\{X_\tau ;\ \tau\ \text{a stopping time}, \tau \le t\}$ is uniformly integrable. Note that we use the extended right generator in the next theorem.
Theorem 2.5. Let  $f\colon S \to \mathbb{R}$ be such that, for fixed t and all
 $s \le t$,
(a)
$T^X_{\cdot,t\,}f \in \mathcal{D}_+(A^{X+}) \cap \mathcal{D}_+(A^{Y+})$,(b)
$\textrm{supp}(\mathbb{P}^{Y_s}) \subset \textrm{supp}(\mathbb{P}^{X_s})$,(c)
$(T^X_{s,t\,}f(Y_s)^-)_{s \ge 0}$ is of class (DL),(d)
$A^{X+}_s T^X_{s,t\,} f \le A^{Y+}_s T^X_{s,t\,} f$ a.s.
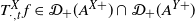
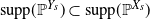
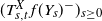
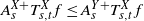
Then
 \begin{equation*}\mathbb{E}[\,f(Y_t)] \ge \mathbb{E}[\,f(X_t)].\end{equation*}
Proof. The proof is similar to the proof of Theorem 2.3. As mentioned above, we have  $\lambda \times \mathbb{P}$ almost surely
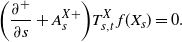 \begin{equation*}\biggl(\dfrac{\partial^+}{\partial s} + A^{X+}_s \biggr) T^X_{s,t\,}f(X_s) = 0.\end{equation*}
By assumption (b) we obtain that
 \begin{equation*}\biggl(\dfrac{\partial^+}{\partial s} + A^{X+}_s \biggr) T^X_{s,t\,}f(Y_s) = 0\end{equation*}
 $\lambda \times \mathbb{P}$ almost surely as well. On the other hand, by the definition of the extended generator,
 \begin{equation*}T^X_{s,t\,}f(Y_s) - T^X_{0,t\,}f(x_0) - \int_0^s \biggl( \dfrac{\partial^+}{\partial u} + A^{Y+}_u \biggr) T^X_{u,t\,}f(Y_u) \,{\textrm{d}} u\end{equation*}
is a local martingale. Combining with (2.3),
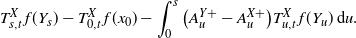 \begin{equation*}T^X_{s,t\,}f(Y_s) - T^X_{0,t\,}f(x_0) - \int_0^s \big(A^{Y+}_u - A^{X+}_u \big) T^X_{u,t\,}f(Y_u) \,{\textrm{d}} u.\end{equation*}
The integral is non-negative by assumption (d) and hence 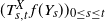 $(T^X_{s,t\,}f(Y_s))_{0 \le s \le t}$ is a local submartingale. By assumption (c) it is a proper submartingale. The assertion now follows as in Theorem 2.3.
An analogous result also holds in the case of extended left generators.
Finally, if we consider random generators instead of extended generators, we get a similar comparison result. Here we have the advantage that no partial derivative appears in Definition 2.4. This means that we can proceed more directly.
Theorem 2.6. Let  $F \in \mathscr{V}^+$ be predictable. Assume that X and Y possess F-random generators
 $(A^X_t)_{t \ge 0}$ and
 $(A^Y_t)_{t \ge 0}$. Further, for
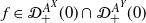 $f \in \mathcal{D}_+^{A^X}(0) \cap \mathcal{D}_+^{A^Y}(0)$, let
(a)
$X_0 \sim Y_0$,(b)
$(f(X_t)- f(Y_t))_{t \ge 0}$ be of class (DL),(c)
$A^X_s f \ge A^Y_s f$ a.s.

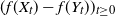

Then we obtain
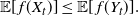 \begin{equation*}\mathbb{E}[\,f(X_t)] \le \mathbb{E}[\,f(Y_t)].\end{equation*}
Proof. Since  $(A^X_t)_{t \ge 0}$ and
 $(A^Y_t)_{t \ge 0}$ are F-random generators, we have by Definition 2.4 that
 \begin{equation*}f(X_t) - f(X_0) - \int_0^t A^X_s f \,{\textrm{d}} F_s\end{equation*}
and
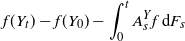 \begin{equation*}f(Y_t) - f(Y_0) - \int_0^t A^Y_s f \,{\textrm{d}} F_s\end{equation*}
are local martingales. It follows that
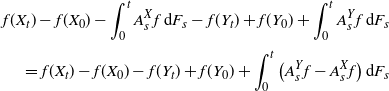 \begin{align*}f(X_t) - f(X_0) - \int_0^t A^X_s f \,{\textrm{d}} F_s - f(Y_t) + f(Y_0) + \int_0^t A^Y_s f \,{\textrm{d}} F_s\\[3pt] = f(X_t) - f(X_0) - f(Y_t) + f(Y_0) + \int_0^t \big(A^Y_sf - A^X_sf\big) \,{\textrm{d}} F_s\end{align*}
is a local martingale as well. The integral is non-negative, and it follows that 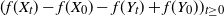 $(f(X_t) - f(X_0) - f(Y_t) + f(Y_0))_{t \ge 0}$ is a local supermartingale and thus by assumption (b) a supermartingale. In consequence we have that
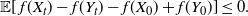 \begin{equation*}\mathbb{E}[\,f(X_t) - f(Y_t) - f(X_0) + f(Y_0)] \le 0.\end{equation*}
The assertion follows by assumption (a).
2.1. Discussion and comparison of regularity conditions
The martingale comparison method as developed in this paper gives an alternative approach to the comparison of two Markov processes. The regularity conditions of this approach are comparable but different from the conditions assumed for the evolution approach. The main achievements and corresponding assumptions in this paper are as follows.
(1) We extend the evolution approach to the comparison of the expectation of single functions f and thus without using the propagation of order condition.
(2) The martingale approach allows comparison results for random generators too, as occurring, for example, in the case of Markovian semimartingales with fixed jump times, which do not fit with the conditions of the evolution approach.
(3) In the case where the evolution approach and the martingale approach both apply, the regularity conditions are similar but (slightly) different. The evolution approach result (Theorem 1.4) makes use of the integrability condition
(I)
$T^Y_{s,u}(A^{X+}_u - A^{Y+}_u) T^X_{s,u\,}f$ is integrable over $u \in [s,t]$,
(II)
$({{{\partial^+}}/{{\partial u}}}) \mathbb{E}[T^X_{u,t\,}f(X_u)\mid X_s]$ and $({{{\partial^+}}/{{\partial u}}}) \mathbb{E}[T^X_{u,t\,}f(Y_u)|Y_s]$ are integrable on [s, t].
$T^X_{s,u} A^{X+}_u T^X_{u,t\,}f$ and $T^Y_{s,u} A^{X+}_u T^X_{u,t\,}f$.
Under the propagation of order condition as in previous literature, for a class of functions
$\mathcal{F}$ this amounts to
(II) ′
$T^X_{s,u} A^{X+}_u f$ and $T^Y_{s,u} A^{X+}_u f$ are integrable for $f \in \mathcal{F}$.
In comparison, condition (I) together with additionally postulating integrability of both terms separately results in
(I) ′
$T^Y_{s,u} A^{X+}_u f$ and $T^Y_{s,u} A^{Y+}_u f$ are integrable for $f \in \mathcal{F}$.
(4) In Theorem 2.6 we give a reasonable and easily verifiable integrability condition not directly involving the generators of the processes. There is no corresponding result available for the evolution approach.
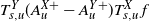

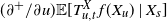
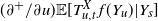


Acknowledgement
An LGFG grant from the state Baden-Württemberg is gratefully acknowledged.


