



1. Introduction
For the price process of a risky asset driven by geometric Brownian motion (GBM), Merton [Reference Merton22, Reference Merton23] pioneered the study of the consumption and portfolio problem with unconstrained investment strategy in a continuous-time setting. Since then, the optimal consumption–portfolio or optimal investment–consumption problem has been studied extensively by many authors. Among them, Jonathan and Ingersoll [Reference Jonathan and Ingersoll16] studied the problem for a class of intertemporally dependent utility functions; Akian et al. [Reference Akian, Menaldi and Sulem2] considered the optimal problem for an investor with proportional transaction costs and Framstad et al. [Reference Framstad, Øksendal and Sulem10] discussed a similar problem in a jump-diffusion market, which then was extended by Ma et al. [Reference Ma, Siu and Zhu21]; Koo [Reference Koo18] studied the problem with liquidity constraint and uninsurable income risk; Wachter [Reference Wachter31] solved the optimal problem under mean-reverting returns; Karatzas and Žitković [Reference Karatzas and Žitković17] considered the problem in a constrained incomplete semi-martingale market by convex duality; Chacko and Viceira [Reference Chacko and Viceira4] examined the problem with constant expected return and stochastic volatility in incomplete markets; Schied [Reference Schied28] discussed robust optimal control for the problem under model uncertainty and Cheridito and Hu [Reference Cheridito and Hu5] investigated the problem in a possibly incomplete market with general stochastic constraints. Other examples can be found in the literature [Reference Collin-Dufresne, Daniel and Sağlam6, Reference Framstad, Øksendal and Sulem11, Reference Kronborg and Steffensen19, Reference Perera26, Reference Shen and Wei29].
In real financial markets, empirical studies often show the invalidity of the GBM model due to various defects including sudden big changes in stock price or a random market environment which switches among a finite number of states and hence a more sophisticated tool for modelling stock prices is needed. To tackle jumps in stock price, Merton [Reference Merton24] extended the GBM model to a jump-diffusion model for option pricing. Under this model, Aase [Reference Aase1] studied the optimal portfolio–consumption problem on a finite-time horizon; Framstad et al. [Reference Framstad, Øksendal and Sulem10] considered the problem on an infinite-time horizon in the presence of proportional transaction costs with constant relative risk aversion utility; Ruan et al. [Reference Ruan, Zhu and Huang27] investigated the optimal problem with habit formulation in an incomplete market using the maximum principle; Guambe and Kufakunesu [Reference Guambe and Kufakunesu14] extended the work of Shen and Wei [Reference Shen and Wei29] to a geometric Itô–Lévy jump process [Reference Cont and Tankov7], and solved the problem by combining the Hamilton–Jacobi–Bellman (HJB) equation [Reference Yong and Zhou32] and a backward stochastic differential equation (SDE); Nguyen [Reference Nguyen25] examined the problem with downside risk constraint. Apart from the diffusion and jump-diffusion models, there are some other models to describe financial markets in the literature. For regime-switching models, Sotomayor and Cadenillas [Reference Sotomayor and Cadenillas30] considered the investment–consumption problem in a financial market modelled by an observable finite-state continuous-time Markov chain; Liu [Reference Liu20] investigated this problem with proportional transaction costs; Gassiat et al. [Reference Gassiat, Gozzi and Pham12] examined the optimal problem in an illiquid financial market, where the investor can trade a stock only at the discrete arrival times of a Cox process [Reference Cont and Tankov7] with intensity depending on the market regime and Hu and Wang [Reference Hu and Wang15] studied the problem with liability and a maximum value-at-risk constraint.
In this paper, we investigate a finite-time-horizon problem of optimal portfolio and consumption for a jump-diffusion process in a Markovian regime switching economy, in which the market modes are divided into a finite number of regimes and all the key parameters change according to the change in the market mode. Suppose that the financial market consists of one risk-free asset and n risky assets, where the price processes are described by a jump-diffusion model. Under the criterion of maximizing the expected discounted total utility of consumption, we study the problem for the general objective function using two different approaches, namely the dynamic programming principle and the stochastic maximum principle. Specifically, a verification theorem under the dynamic programming principle as well as sufficient conditions for optimality under the stochastic maximum principle are proved. The results show that the optimal strategies derived by both methods are the same. In the case of a power utility function [Reference Guambe and Kufakunesu14], under the constraints of no-short-selling and nonnegative consumption, we investigate the existence and uniqueness of the optimal solution and obtain closed-form expressions for the optimal strategy and the value function. Moreover, in order to illustrate the effects of jumps on the optimal results, we carry out some comparisons between the results for the risk model with and that without jumps. We conclude that if the finance market is in good shape, investors are willing to invest more into the risky asset so that the amount of consumption is reduced; whereas if the financial market is bad, investors prefer investing less into the risky asset; when the economic situation (good or bad) is not clear, further statistical properties of the jump amplitude are needed on the comparison of the optimal results. Finally, we demonstrate that our optimal results in some special cases are consistent with those in the literature.
The main contribution of the present paper is fourfold. First, we add jumps in the price processes of the risky assets. This kind of model is more reasonable for a real financial market, since the information often comes as a surprise, which usually leads to a jump in the price of a stock. Meanwhile, we consider the Markov regime switching in various market parameters which can better reflect the random nature of the underlying market environment than those with constant coefficients. It generalizes the model of a risky asset from geometric Brownian motion to Markov regime switching jump-diffusion processes, which makes the analysis more complicated. Secondly, this paper considers the constraints of no-short-selling and nonnegative consumption and extends the interval of the optimal portfolio solution from
 $(0,1)$
in Framstad et al. [Reference Framstad, Øksendal and Sulem9] or Guambe and Kufakunesu [Reference Guambe and Kufakunesu14] to
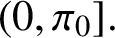 $(0,\pi _0].$
We also prove the existence and uniqueness of the optimal strategy for the jump-diffusion model, and closed-form expressions of the optimal strategy and the value function are derived. In addition, we present the verification theorem and prove it in detail for the jump-diffusion process with regime switching. Thirdly, we provide Example 4.5 to illustrate the optimal results of Proposition 4.2. It shows clearly what the optimal portfolio strategy would be in different cases by analysing the monotonicity and concavity of some function. Lastly, but not least, we carry out some detailed comparisons between the optimal results for the jump-diffusion risk model and the pure diffusion model in Section 5 and give some economic interpretations in Remark 5.2.
The rest of the paper is organized as follows. In Section 2, the models and problem are formulated. In Section 3, some optimal results for the jump-diffusion process with regime switching are obtained. Section 4 analyses the existence and uniqueness of the optimal solution, and derives closed-form expressions for the optimal strategy and value function under the power utility. Section 5 gives some comparisons between the optimal results for the jump-diffusion model and the pure diffusion model, while Section 6 presents the optimal results in some special cases. We conclude the paper in Section 7.
2. Model and problem formulation
We consider a continuous-time and right-continuous Markov chain
 $\{\alpha (t)\mid t\in [0,T]\}$
on a complete filtered probability space
 $(\Omega , \mathcal {F},\mathcal {F}(t),\mathbb {P})$
, where
 $\mathcal {F}(t)$
is generated by the information up to time t. The Markov chain
 $\alpha (t)$
is assumed to take values in a finite state space
 $\mathcal {M}=\{e_1,e_2,\ldots ,e_l\}$
, where
 $e_i\in \mathbb {R}^l$
and the jth component of
 $e_i$
is the Kronecker delta
 $\delta _{ij}.$
It is also assumed that the chain is homogeneous and has a generator
 $Q=(q_{ij})_{l\times l},$
in which
 $\sum \nolimits _{j=1}^lq_{ij}=0$
for any
 $ e_i\in \mathcal {M},$
and
 $q_{ij}>0$
if
 $i\neq j.$
Suppose that a financial market consists of a risk-free asset (bond) and n risky assets (stocks). Assume that risky assets can be traded continuously over
 $[0,T]$
and that there are no transaction costs and taxes in trading. The risk-free asset’s price process
 $S_0(t)$
is given by
 $$ \begin{align*} dS_0(t)=r(t, \alpha(t))S_0(t)\,dt, \quad t\in[0, T], \end{align*} $$
where
 $r(t, e_i) (>0)$
representing the risk-free interest rate at state
 $e_i$
is a bounded and deterministic function on
 $[0,T]$
. For
 $k=1,2,\ldots ,n,$
the price process of the kth risky asset denoted by
 $S_k(t)$
is described by the following stochastic differential equation:
 $$ \begin{align} \begin{cases} dS_k(t)=S_k(t-)\bigg[b_k(t, \alpha(t-))\,dt+\displaystyle\sum\limits_{j=1}^{N}\sigma_{kj}(t, \alpha(t-))\,dW_j(t)\\ \qquad \qquad+\displaystyle\sum\limits_{j=1}^{M}\displaystyle\int_{\mathbb{R}_0}\eta_{kj}(t, z, \alpha(t-))N_{\alpha}^j(dt, dz)\bigg],\\ S_k(0)=S_{k0}, \end{cases} \end{align} $$
where the symbol “
 $t-$
” stands for the time before a jump occurring;
 $S_{k0}$
is the deterministic initial price;
 $b_k(t, \cdot )$
and
 $\sigma _{kj}(t, \cdot )$
represent the appreciation rate and volatility coefficient, respectively;
 $\eta _{kj}(t, z, \cdot )\,(>-1)$
is the jump amplitude with
 $\mathbb {R}_0=\mathbb {R}\setminus \{0\}$
;
 $b_k(t, \cdot )$
,
 $\sigma _{kj}(t, \cdot )$
,
 $\eta _{kj}(t, z, \cdot )$
are continuous and bounded;
 $W(t)=(W_1(t),W_2(t),\ldots ,W_N(t))^\top $
is an N-dimensional standard Brownian motion, where the superscript
 $\text {``}^{\top }\text {''}$
denotes the transpose of a matrix or vector and
 $N_{\alpha }(dt, dz)=(N_{\alpha }^1(dt, dz),\ldots , N_{\alpha }^M(dt, dz))^\top $
is an M-dimensional Poisson random measure with compensated Poisson random measures defined as
 $$ \begin{align*}\begin{array}{@{}ll} \tilde{N}_{\alpha}^j(dt, dz)=N_{\alpha}^j(dt, dz)-\nu_{\alpha}^j(dz)\,dt,\quad j=1, 2,\ldots, M. \end{array}\end{align*} $$
The diffusion component in equation (2.1) characterizes the normal fluctuation in a stock’s price, due to gradual changes in economic conditions or arrivals of new information which causes marginal changes in the stock’s price. The jump component describes sudden changes in a stock’s price, due to arrivals of important new information which has large effects on the stock’s price. It is well known from the SDE theory that a unique solution exists for the SDE (2.1).
Assumption 2.1 Throughout the paper, we make the following assumptions.
-
(A1)
 $N_{\alpha }^j(dt, dz),\, j=1,2,\ldots ,M,$
and
$W_j(t),\, j=1,2,\ldots ,N,$
are independent of each other.
-
(A2) The expected return of the risky asset is larger than the risk-free interest rate and hence, for any state
$e_i\in \mathcal {M},$
we assume that
$b_k(t, e_i)+\sum \nolimits _{j=1}^{M}\int _{\mathbb {R}_0}\eta _{kj}(t, z, e_i)\nu _{e_i}^j(dz)>r(t, e_i).$


Let
 $\pi _k(t)$
be the proportion of an investor’s wealth invested into the kth risky asset at time t and
 $\pi (t)=(\pi _1(t), \pi _2(t), \ldots , \pi _n(t))^\top , ~t\in [0,T],$
be the investor’s portfolio strategy. The remaining proportion of the investor’s wealth invested in the risk-free asset is then given by
 $1-\sum \nolimits _{k=1}^n \pi _k(t).$
Assume that the investor consumes wealth with nonnegative rate
 $c(t)$
at time t. Denote
 $u(t)=(\pi (t),c(t)).$
Given a consumption process c and a portfolio process
 $\pi $
, the wealth process
 $X(t)=X^u(t)$
of the investor evolves as
 $$ \begin{align} dX(t)&=\sum_{k=1}^n\dfrac{\pi_k(t)X(t)}{S_k(t-)}\,dS_k(t)+\frac{\big(1-\sum_{k=1}^n\pi_k(t)\big)X(t)}{S_0(t)}\,dS_0(t) -c(t)\,dt \nonumber \\ &=\bigg[\bigg\{r(t, \alpha(t-))+\sum_{k=1}^n\pi_k(t)\{b_k(t,\alpha(t-))-r(t, \alpha(t-))\}\bigg\}X(t) -c(t)\bigg]\,dt \nonumber \\ &\quad+\sum_{k=1}^n\pi_k(t)X(t)\sum_{j=1}^{N}\sigma_{kj}(t, \alpha(t-))\,dW_j(t) \nonumber\\ &\quad +\sum_{k=1}^n\pi_k(t)X(t)\sum_{j=1}^{M}\int_{\mathbb{R}_0}\eta_{kj}(t, z, \alpha(t-))N_{\alpha}^j(dt, dz). \end{align} $$
Setting
 $$ \begin{align*} \begin{cases} B(t,\alpha(t-))=(b_1(t,\alpha(t-))-r(t, \alpha(t-)),\ldots,b_n(t,\alpha(t-))-r(t, \alpha(t-)))^\top,\\ \sigma(t,\alpha(t-))=(\sigma_{kj}(t, \alpha(t-)))_{n\times N},\\ \eta(t,z,\alpha(t-))=(\eta_{kj}(t, z, \alpha(t-)))_{n\times M}, \end{cases} \end{align*} $$
we can rewrite the wealth equation (2.2) as
 $$ \begin{align} dX(t)&=[\{r(t, \alpha(t-))+\pi^\top(t)B(t,\alpha(t-))\}X(t)-c(t)]\,dt \nonumber\\ &\quad+\pi^\top(t)X(t)\sigma(t,\alpha(t-))\,dW(t) +\int_{\mathbb{R}_0}\pi^\top(t)X(t)\eta(t,z,\alpha(t-))N_{\alpha}(dt, dz). \end{align} $$
In the rest of the paper, we write
 $r(t,\alpha (t-))$
,
 $B(t,\alpha (t-))$
,
 $\sigma (t,\alpha (t-))$
and
 $\eta (t,z,\alpha (t-))$
as r, B,
 $\sigma $
and
 $\eta $
, respectively, for notational convenience.
Definition 2.2 A portfolio–consumption strategy
 $u(\cdot )=(\pi (\cdot ),c(\cdot )) $
is said to be admissible if
 $u(\cdot )$
satisfies the following conditions:
-
(i)
$u(t)=(\pi (t),c(t)) $
is an
$\mathcal {F}(t)$
-predictable process; -
(ii)
$\pi _i(t)\geq 0$
for
$i=1,2,\ldots ,n$
and
$c(t)\geq 0$
; -
(iii)
$$ \begin{align*}\begin{array}{@{}ll} E\bigg[\!\!\displaystyle\int_0^T\bigg\{\displaystyle\int_{\mathbb{R}_0}\pi^\top(t)X(t)\eta(t,z,\alpha(t-))\eta^\top(t,z,\alpha(t-))\pi(t)X(t)\nu_{\alpha}(dz)\\ \qquad+\pi^\top(t)X(t)\sigma(t,\alpha(t-))\sigma^\top(t,\alpha(t-))\pi(t)X(t)\bigg\}\,dt\bigg]<\infty; \end{array}\end{align*} $$
-
(iv) the SDE (2.3) for
$X(t)$
has a unique solution.


The set of all admissible strategies is denoted by
 $\mathcal {U}$
.
For a real-valued continuous and concave function g (with respect to
 $\pi $
and c) and a concave function h (with respect to x), we define the reward function
 $J(t,x,u(\cdot ),e_i)$
for a finite-time horizon
 $[0,T]$
by
 $$ \begin{align} J(t,x,u(\cdot),e_i) =E_{t,x,e_i}\bigg[\displaystyle\int_t^Te^{-\gamma s}g(s,X(s),u(s),\alpha(s))\,ds+e^{-\gamma T}h(X(T), \alpha(T))\bigg], \end{align} $$
where
 $E_{t,x,e_i}[\cdot ]=E[\cdot \mid X(t)=x, \alpha (t)=e_i],$
which leads to the value function
 $$ \begin{align} \begin{array}{@{}ll} V(t,x,e_i)=\displaystyle\mathop{\mathrm{sup}}_{u(\cdot)\in\mathcal{U}}J(t,x,u(\cdot),e_i). \end{array} \end{align} $$
Without the nonnegativity constraints on the portfolio strategy
 $\pi $
and the consumption rate c, we denote the corresponding admissible set by
 $\mathcal {\tilde {U}}.$
It is obvious that
 $\mathcal {U}\mathcal {\subseteq \tilde {U}}.$
In the next section, we will focus on the corresponding optimization problem with
 $\mathcal {\tilde {U}}$
, that is,
 $$ \begin{align} \begin{array}{@{}ll} V(t,x,e_i)=\mathop{\mathrm{sup}}\limits_{u(\cdot)\in\mathcal{\tilde{U}}}J(t,x,u(\cdot),e_i), \end{array} \end{align} $$
where
 $J(t,x,u(\cdot ),e_i)$
is defined in (2.4) and
 $X(t)$
satisfies the SDE (2.3). We will return to the problem (2.5) with power utility in Section 4.
3. Some results for the optimization problem
In this section, we aim at investigating the problem (2.6) by two kinds of methods, namely, the dynamic programming principle and the stochastic maximum principle.
3.1. Dynamic programming principle
For any
 $e_i\in \mathcal {M}$
, let
 $C^{1,2}([0,T]\times \mathbb {R})$
denote the space of
 $\varphi (t,x,e_i)$
such that
 $\varphi (t,x,e_i)$
and its derivatives
 $\varphi _t(t,x,e_i)$
,
 $\varphi _x(t,x,e_i)$
,
 $\varphi _{xx}(t,x,e_i)$
are continuous on
 $[0,T]\times \mathbb {R}$
. For any function
 $\varphi (t,x,e_i)\in C^{1,2}([0,T]\times \mathbb {R})$
, the usual infinitesimal generator
 $\mathcal {A}^{u}$
under u for the jump-diffusion process (2.3) is given by
 $$ \begin{align*} \mathcal{A}^{u}\varphi(t,x,e_i)&=\varphi_t(t,x,e_i)+(rx+\pi^\top Bx-c)\varphi_x(t,x,e_i) +\dfrac{1}{2}\pi^\top x\sigma\sigma^\top\pi x\varphi_{xx}(t,x,e_i)\\ &\quad+\sum\limits_{j=1}^{l}q_{ij}\varphi(t,x,e_j) +\sum\limits_{j=1}^{M}\int_{\mathbb{R}_0}[\varphi(t,x+\pi^\top x\eta^{(j)},e_i)-\varphi(t,x,e_i)]\nu_{e_i}^j(dz), \end{align*} $$
where
 $\eta ^{(j)}$
denotes the jth column of the matrix
 $\eta $
.
According to standard stochastic control theory (see the book by Fleming and Soner [Reference Fleming and Soner8]), one can show that the HJB equation associated with the problem (2.6) is
 $$ \begin{align} \begin{cases} \begin{aligned} &\mathop{\mathrm{sup}}\limits_{u}\{\mathcal{A}^{u}V(t,x,e_i)+e^{-\gamma t}g(t,x,u,e_i)\}=0,\\ &V(T,x,e_i)=e^{-\gamma T}h(x,e_i). \end{aligned} \end{cases} \end{align} $$
The following theorem shows a connection between the solution to the HJB equation (3.1) and the optimal strategy as well as the value function.
Theorem 3.1 (Verification theorem).
Assume that
 $W(t,x,e_i)\in C^{1,2}$
is a solution to the HJB equation (3.1) with
 $W_x(t,x,e_i)>0, W_{xx}(t,x,e_i)<0$
and
 $u^*=(\pi ^*, c^*)$
satisfying
 $$ \begin{align*}\begin{array}{@{}ll} u^*=\arg\mathop{\mathrm{sup}}\limits_{u}\{\mathcal{A}^{u}W(t,x,e_i)+e^{-\gamma t}g(t,x,u,e_i)\}. \end{array}\end{align*} $$
Then the value function
 $V(t,x,e_i)$
coincides with
 $W(t,x,e_i)$
, that is,
 $$ \begin{align*}W(t,x,e_i)=V(t,x,e_i).\end{align*} $$
Furthermore,
 $u^*$
is an optimal strategy for the problem (2.6).
Proof. The HJB equation (3.1) that is satisfied by
 $W(t,x,e_i)$
can be rewritten as
 $$ \begin{align*}\begin{array}{@{}ll} \begin{aligned} W_t(t,x,e_i)+\mathop{\mathrm{sup}}\limits_{u}\bigg\{\psi(\pi,c)+\displaystyle\sum\limits_{j=1}^{l}q_{ij}W(t,x,e_j)\bigg\}=0 \end{aligned} \end{array}\end{align*} $$
with the boundary condition
 $W(T,X(T),\alpha (T))=e^{-\gamma T}h(X(T),\alpha (T)),$
where
 $$ \begin{align*} \psi(\pi,c)&=(rx+{\pi}^\top Bx-c)W_x(t,x,e_i)+\dfrac{1}{2}{\pi}^\top x\sigma\sigma^\top{\pi} xW_{xx}(t,x,e_i)\\ &\quad+\sum\limits_{j=1}^{M}\int_{\mathbb{R}_0}[W(t,x+{\pi}^\top x\eta^{(j)},e_i)-W(t,x,e_i)]\nu_{e_i}^j(dz) +e^{-\gamma t}g(t,x,u,e_i). \end{align*} $$
For any
 $s\in [t, T],$
applying Itô’s formula [Reference Fleming and Soner8] to the function
 $W(s, X(s), \alpha (s))$
yields
 $$ \begin{align} dW(s, X(s), \alpha(s)) &=\dfrac{1}{2}\pi^\top X(s-)\sigma(s,\alpha(s-))\sigma^\top(s,\alpha(s-))\pi X(s-)W_{xx}\nonumber \\ &\quad+\bigg[W_s+\{r(s,\alpha(s-))X(s-)+\pi^\top X(s-)B(s,\alpha(s-))-c(s)\}W_x \nonumber\\ &\quad+\sum\limits_{j=1}^{M}\int_{\mathbb{R}_0}\{W(s,X(s-)+\pi^\top X(s-)\eta^{(j)},\alpha(s))\nonumber\\ &\quad-W(s,X(s-),\alpha(s-))\}\nu_{\alpha}^j(dz) \nonumber\\ &\quad+\sum\limits_{j=1}^{l}\{W(s,X(s-),e_j)-W(s,X(s-),\alpha(s-))\}q_{\alpha(s-)j}\bigg]\,ds+dM(t), \end{align} $$
where
 $$ \begin{align*} M(t)=&\int_0^t\pi^\top(s)X(s)\sigma(s,\alpha(t-))W_x(s, X(s), \alpha(s-))\,dW(s)\\ &+\sum\limits_{j=1}^{M}\int_0^t\int_{\mathbb{R}_0}\{W(s,X(s-)+\pi^\top(s) X(s-)\eta^{(j)},\alpha(s))\\ &-W(s,X(s-),\alpha(s-))\}\tilde{N}_{\alpha}^j(ds,dz)\\ &+\sum\limits_{j=1}^{l}\int_0^t\{W(s,X(s-),e_j)-W(s,X(s-),\alpha(s-))\}\,d\tilde{\Phi}_j(s). \end{align*} $$
Here
 $\tilde {\Phi }_j(s),j=1,2,\ldots ,l$
is an
 $(\mathcal {F},\mathbb {P})$
martingale (see the paper by Zhang et al. [Reference Zhang, Elliott and Siu33] for more details). Then
 $M(t)$
is a local martingale. Since
 $b_k(t, \cdot )$
,
 $\sigma _{kj}(t, \cdot )$
,
 $\eta _{kj}(t, z, \cdot )$
are continuous and bounded by the parameter hypothesis and
 $u(\cdot )=(\pi (\cdot ),c(\cdot ))$
is an admissible strategy, the first and second terms are square-integrable. Moreover, the third term is also square-integrable due to the assumption
 $W(t,x,e_i)\in C^{1,2}.$
Thus,
 $M(t)$
is a martingale.
Adding
 $\int _t^Te^{-\gamma s}g(s,X(s),u(s),\alpha (s))\,ds$
and taking expectation in equation (3.2),
 $$ \begin{align*} E_{t,x,e_i}\bigg[&W(T, X(T), \alpha(T))+\int_t^Te^{-\gamma s}g(s,X(s),u(s),\alpha(s))\,ds\bigg] \\ &=W(t,x,e_i) +E_{t,x,e_i}\bigg[\int_t^T\{\mathcal{A}^uW(s, X(s), \alpha(s))+e^{-\gamma s}g(s,X(s),u(s),\alpha(s))\}\,ds\bigg]. \end{align*} $$
From (3.1),
 $$ \begin{align*} \mathcal{A}^uW(s, X(s), \alpha(s))+e^{-\gamma s}g(s,X(s),u(s),\alpha(s))\leq0, \end{align*} $$
where equality holds when
 $u=u^*.$
By the definition of the objective function (2.4) and the terminal condition
 $W(T, X(T), \alpha (T))=e^{-\gamma T}h(X(T), \alpha (T))$
,
 $$ \begin{align} J(t,x,u,e_i)\leq W(t,x,e_i), \end{align} $$
where the equality in (3.3) will hold when
 $u=u^*.$
Therefore,
 $V(t,x,e_i)\leq W(t,x,e_i).$
On the other hand,
 $$ \begin{align*}W(t,x,e_i)=J(t,x,u^*,e_i)\leq V(t,x,e_i).\end{align*} $$
As a result,
 $W(t,x,e_i)=V(t,x,e_i),$
that is, the solution
 $W(t,x,e_i)$
to (3.1) is the value function and
 $u^*$
is an optimal strategy. This completes the proof.
Furthermore, the following theorem shows that under some condition, the optimal result for the problem (2.6) is the solution to a system of partial differential equations.
Theorem 3.2. For the portfolio–consumption problem (2.6), if the inequality
 $$ \begin{align} e^{-\gamma t}&g_{cc}(t,x,u,e_i)\bigg[x\sigma\sigma^\top xV_{xx}(t,x,e_i) +e^{-\gamma t}g_{\pi\pi}(t,x,u,e_i) \nonumber \\ &+\sum\limits_{j=1}^{M}\displaystyle\int_{\mathbb{R}_0}V_{xx}(t,x+{\pi}^\top x\eta^{(j)},e_i)x^2\eta^{(j)}{\eta^{(j)}}^T\nu_{e_i}^j(dz)\bigg] -e^{-2\gamma t}g_{c\pi}^2(t,x,u,e_i)>0 \end{align} $$
holds, then the optimal strategy
 $(\pi ^*,c^*)$
is the solution to the following equations:
 $$ \begin{align} \begin{cases} BxV_x(t,x,e_i)+\sigma\sigma^\top\pi x^2V_{xx}(t,x,e_i)+e^{-\gamma t}g_{\pi}(t,x,u,e_i)\\ \quad+\displaystyle\sum\limits_{j=1}^{M}\displaystyle\int_{\mathbb{R}_0}V_x(t,x+{\pi}^\top x\eta^{(j)},e_i)x\eta^{(j)}\nu_{e_i}^j(dz)=0,\\ e^{-\gamma t}g_{c}(t,x,u,e_i)-V_{x}(t,x,e_i)=0. \end{cases} \end{align} $$
Proof. Differentiating
 $\psi (\pi ,c)$
with respect to
 $\pi $
and
 $c,$
respectively, yields
 $$ \begin{align*} \begin{cases} \dfrac{\partial\psi}{\partial c}=-V_x(t,x,e_i)+e^{-\gamma t}g_c(t,x,u,e_i),\\[2mm] \dfrac{\partial\psi}{\partial \pi}= BxV_x(t,x,e_i)+x\sigma\sigma^\top{\pi} xV_{xx}(t,x,e_i)+e^{-\gamma t}g_{\pi}(t,x,u,e_i)\\ \quad\quad\ \ +\displaystyle\sum\limits_{j=1}^{M}\displaystyle\int_{\mathbb{R}_0}V_x(t,x+{\pi}^\top x\eta^{(j)},e_i)x\eta^{(j)}\nu_{e_i}^j(dz),\\ \dfrac{\partial^2\psi}{\partial c^2}=e^{-\gamma t}g_{cc}(t,x,u,e_i),\\[2mm] \dfrac{\partial^2\psi}{\partial \pi^2}=x\sigma\sigma^\top xV_{xx}(t,x,e_i)+e^{-\gamma t}g_{\pi\pi}(t,x,u,e_i)\\ \quad\quad\quad+\displaystyle\sum\limits_{j=1}^{M}\displaystyle\int_{\mathbb{R}_0}V_{xx}(t,x+{\pi}^\top x\eta^{(j)},e_i)x^2\eta^{(j)}{\eta^{(j)}}^\top\nu_{e_i}^j(dz),\\ \dfrac{\partial^2\psi}{\partial c\partial\pi}=\dfrac{\partial^2\psi}{\partial\pi\partial c}=e^{-\gamma t}g_{c\pi}(t,x,u,e_i). \end{cases} \end{align*} $$
Since g is a concave function with respect to
 $\pi $
and c and the Hessian matrix
 $$ \begin{align*}H=\left(\begin{array}{@{}ll} \dfrac{\partial^2\psi}{\partial c^2}\quad \dfrac{\partial^2\psi}{\partial c\partial\pi}\\[8pt] \dfrac{\partial^2\psi}{\partial\pi\partial c}\quad \dfrac{\partial^2\psi}{\partial \pi^2} \end{array}\!\!\right)\end{align*} $$
is a negative-definite matrix because of inequality (3.4), the maximizer
 $u^*=(\pi ^*,c^*)$
to the HJB equation (3.1) satisfies equation (3.5).
3.2. Stochastic maximum principle
In this subsection, we discuss the problem (2.6) using the approach of the stochastic maximum principle. Define the Hamiltonian function
 $H: [0,T]\times \mathbb {R}\times U\times \mathcal {M}\times \mathbb {R}\times \mathbb {R}^N\times \mathbb {R}^M\longrightarrow \mathbb {R}$
by
 $$ \begin{align*} H(t,x,u,e_i,p,\varphi,\psi) &=-e^{-\gamma t}g(t,x,u,e_i)+\bigg[\bigg\{r+\pi^\top\bigg(B+\int_{\mathbb{R}_0}\eta \nu_{e_i}(dz)\bigg)\bigg\}x-c\bigg]p(t)\\ &\quad+\sum\limits_{k=1}^n\sum\limits_{j=1}^N\pi_kx\sigma_{kj}\varphi_j(t) +\sum\limits_{k=1}^n\sum\limits_{j=1}^M\displaystyle\int_{\mathbb{R}_0}\pi_kx\eta_{kj}\psi_j(t,z)\nu^j_{e_i}(dz). \end{align*} $$
Assume that the Hamiltonian function H is differentiable with respect to x.
The adjoint equation corresponding to u and
 $X(t)$
for the unknown adapted processes
 $p(t), \varphi (t)$
and
 $\psi (t,\cdot ),$
where
 $p(t)\in \mathbb {R}, \varphi (t)\in \mathbb {R}^N$
and
 $\psi (t,\cdot )\in \mathbb {R}^M,$
is given by the following SDE:
 $$ \begin{align} \begin{cases} \begin{aligned} dp(t)=&\bigg\{e^{-\gamma t}g_x(t,X(t-),u,\alpha(t-))-\bigg[r+\pi^\top\bigg(B+\int_{\mathbb{R}_0}\eta \nu_{\alpha(t-)}(dz)\bigg)\bigg]p(t-)\\ &-\displaystyle\sum\limits_{k=1}^n \displaystyle\sum\limits_{j=1}^N\pi_k\sigma_{kj}\varphi_j(t) - \displaystyle\sum\limits_{k=1}^n \displaystyle\sum\limits_{j=1}^M\displaystyle\int_{\mathbb{R}_0}\pi_k\eta_{kj}\psi_j(t,z)\nu^j_{\alpha(t-)}(dz)\bigg\}\,dt\\ &+\displaystyle\sum\limits_{j=1}^N\varphi_j(t)\,dW_j(t)+ \displaystyle\sum\limits_{j=1}^M\displaystyle\int_{\mathbb{R}_0}\psi_j(t,z)\tilde{N}^j_{\alpha}(dt,dz),\\ p(T)=&-e^{-\gamma t}h_x(X(T),\alpha(T)). \end{aligned} \end{cases} \end{align} $$
For the existence and uniqueness of the solution to the SDE (3.6) with jumps, interested readers are referred to Zhang et al. [Reference Zhang, Elliott and Siu33].
The next theorem develops a sufficient stochastic maximum principle for the optimal problem.
Theorem 3.3 (Sufficient conditions for optimality).
Let
 $u^*\in \mathcal {\tilde {U}}$
with the corresponding solution
 $X^*=X^{u^*}$
. Suppose that there exists an adapted solution
 $(\hat {p}(t),\hat {\varphi }(t),\hat {\psi }(t,\cdot ))$
to the corresponding adjoint equation (3.6) such that for all
 $u(\cdot )\in \mathcal {\tilde {U}}$
,
 $$ \begin{align*}\begin{array}{@{}ll} E\bigg[\displaystyle\int_0^T(X^*(t)-X(t))^2\bigg(\hat{\varphi}^\top(t)\hat{\varphi}(t) +\displaystyle\int_{\mathbb{R}_0}\hat{\psi}^\top(t,z) \mbox{ {Diag}}(\nu_\alpha(dz))\hat{\psi}(t,z)\bigg)\,dt\bigg]<\infty \end{array}\end{align*} $$
and
 $$ \begin{align*} &E\bigg[\displaystyle\int_0^T\hat{p}(t)^2\bigg({\pi^*(t)}^\top X^*(t-)\sigma\sigma^\top\pi^*(t)X^*(t-)\\ &\quad+\displaystyle\int_{\mathbb{R}_0}{\pi^*(t)}^\top X^*(t-)\eta \mbox{ {Diag}}(\nu_\alpha(dz))\eta^\top\pi^*(t)X^*(t-)\bigg)\,dt\bigg]<\infty. \end{align*} $$
Assume further that the following three conditions hold:
-
(i) for almost all
$t\in [0,T],$
$$ \begin{align*} & H(t,X^*(t-),u^*(t),\alpha(t-),\hat{p}(t-),\hat{\varphi}(t),\hat{\psi}(t,\cdot))\\ & \quad=\inf\limits_{u}H(t,X^*(t-),u(t),\alpha(t-),\hat{p}(t-),\hat{\varphi}(t),\hat{\psi}(t,\cdot)); \end{align*} $$
-
(ii) for each fixed pair
$(t,e_i)\in [0,T]\times \mathcal {M}$
, exists and is a convex function with respect to x;
$$ \begin{align*}\hat{H}(x)=\inf\limits_{u}H(t,x,u,e_i,\hat{p}(t-),\hat{\varphi}(t),\hat{\psi}(t,\cdot))\end{align*} $$
-
(iii)
$h(x, e_i)$
is a concave function with respect to x for each
$e_i\in \mathcal {M}.$


Then
 $u^*$
is an optimal strategy for the problem (2.6) and
 $X^*$
is the corresponding controlled state process.
Proof. Define
 $\tilde {J}(t,x,u(\cdot ),e_i)$
and
 $\tilde {V}(t,x,e_i)$
by
 $$ \begin{align*} \tilde{J}(t,x,u(\cdot),e_i)&=-J(t,x,u(\cdot),e_i)\\ &=E_{t,x,e_i}\bigg[\displaystyle\int_t^T-e^{-\gamma s}g(s,X(s),u(s),\alpha(s))\,ds-e^{-\gamma T}h(X(T), \alpha(T))\bigg],\\ \tilde{V}(t,x,e_i)&=-V(t,x,e_i), \end{align*} $$
respectively. Then the problem (2.6) is equivalent to the following problem:
 $$ \begin{align} \tilde{V}(t,x,e_i)=\inf\limits_{u(\cdot)\in\mathcal{\tilde{U}}}\tilde{J}(t,x,u(\cdot),e_i) \end{align} $$
with
 $X(t)$
satisfying the SDE (2.3).
For the problem (3.7) with the Hamiltonian function
 $H(t,x,u,e_i,p,\varphi ,\psi )$
and the adjoint equation (3.6), one can follow the proof of Theorem 3.1 in Zhang et al. [Reference Zhang, Elliott and Siu33] to obtain the optimal strategy
 $u^*$
for the problem (2.6). This completes the proof.
The next theorem presents the results derived by the method of the stochastic maximum principle for the problem (2.6).
Theorem 3.4. For the portfolio–consumption problem (2.6), the optimal strategy
 $(\pi ^*, c^*)$
is the solution to the following equations:
 $$ \begin{align} \begin{cases} e^{-\gamma t}g_{\pi}(t,x,u,e_i)+BxV_x(t,x,e_i)+\sigma\sigma^\top\pi x^2V_{xx}(t,x,e_i) \\ \quad{} +\displaystyle\sum\limits_{j=1}^M\displaystyle\int_{\mathbb{R}_0}V_{x}(t,x+\pi^\top x\eta^{(j)},e_i)x\eta^{(j)}\nu^j_{e_i}(dz)=0,\\ e^{-\gamma t}g_c(t,x,u,e_i)-V_x(t,x,e_i)=0. \end{cases} \end{align} $$
Proof. For the problem (3.7) with the adjoint equation (3.6), we mimic the proof of Theorem 4.2 in Zhang et al. [Reference Zhang, Elliott and Siu33] to obtain the optimal results. Note that
 $$ \begin{align} \begin{cases} \hat{p}(t)=\tilde{V}_x(t,x,e_i)=-V_x(t,x,e_i),\\ \hat{\varphi}_j(t)=\tilde{V}_{xx}(t,x,e_i)\displaystyle\sum\limits_{k=1}^n\pi_kx\sigma_{kj}=-V_{xx}(t,x,e_i)\displaystyle\sum\limits_{k=1}^n\pi_kx\sigma_{kj},\\ \hat{\psi}_j(t,z)=\tilde{V}_x(t,x+\displaystyle\sum\limits_{k=1}^n\pi_kx\eta_{kj},e_i)-\tilde{V}_x(t,x,e_i)\\ \qquad \quad=V_x(t,x,e_i)-V_x(t,x+\displaystyle\sum\limits_{k=1}^n\pi_kx\eta_{kj},e_i). \end{cases} \end{align} $$
Since
 $H(t,x,u,e_i,\hat {p}(t),\hat {\varphi }(t),\hat {\psi }(t,\cdot ))$
is linear in
 $\pi $
and c, the coefficients of
 $\pi $
and c should vanish at optimality, that is,
 $$ \begin{align} \begin{cases} -e^{-\gamma t}g_{\pi}(t,x,u,e_i)+\bigg[B+\displaystyle\int_{\mathbb{R}_0}\eta \nu_{e_i}(dz)\bigg]x\hat{p}(t) \\ \quad {} + {} x\sigma\hat{\varphi}(t) +\displaystyle\sum\limits_{j=1}^M\displaystyle\int_{\mathbb{R}_0}x\eta^{(j)}\hat{\psi}_j(t,z)\nu^j_{e_i}(dz)=0,\\ -e^{-\gamma t}g_c(t,x,u,e_i)-\hat{p}(t)=0. \end{cases} \end{align} $$
Substituting
 $(\hat {p}(t),\hat {\varphi }(t),\hat {\psi }(t,z))$
of (3.9) into (3.10), we obtain the equation (3.8).
Remark 3.5 For the portfolio–consumption problem (2.6), by the techniques of the dynamic programming principle and the stochastic maximum principle, we obtain the same results for the general objective function, that is, the optimal strategy without nonnegative constraints is the solution to a system of partial differential equations. In the next section, we shall focus on the optimization problem with a power utility function and derive closed-form expressions for the optimal strategy and the value function.
4. Optimal results under power utility
In this section, we work on the problem (2.6) in which the utility function of the investor is of power type, that is,
 $$ \begin{align} \begin{cases} g(t,x,\pi,c,e_i)=\dfrac{c^\delta}{\delta},\\[-1mm] h(x,e_i)=\dfrac{x^\delta}{\delta}, \end{cases} \end{align} $$
with
 $ 0<\delta <1.$
For illustration purposes, we consider the case with
 $n=N=M=1$
. The derivations of the optimal strategy and the value function are based on the HJB equation. From (4.1) and based on the terminal condition of the value function, we try to fit a solution of the form
 $$ \begin{align} V(t,x,e_i)=e^{-\gamma t}k^{1-\delta}(t,e_i)\dfrac{x^\delta}{\delta}, \end{align} $$
where
 $k(t,e_i)$
is a suitable function such that (4.2) is a solution to the HJB equation (3.1). The boundary condition
 $V(T,x,e_i)=e^{-\gamma T} x^\delta / \delta $
implies that
 $k(T,e_i)=1$
. Then the original HJB equation (3.1) can be rewritten as
 $$ \begin{align} \begin{cases} \dfrac{x^\delta}{\delta}[(1-\delta)k_t(t,e_i)-\gamma k(t,e_i)]+rk(t,e_i)x^{\delta}+\mathop{\mathrm{sup}}\limits_{c}\psi(c)\\ \quad +\mathop{\mathrm{sup}}\limits_{\pi}[k(t,e_i)x^{\delta}\phi(\pi)] +\displaystyle \sum\limits_{j=1}^{l}q_{ij}k^{1-\delta}(t,e_j)k^\delta(t,e_i)\dfrac{x^\delta}{\delta}=0,\\ k(T,e_i)=1, \end{cases} \end{align} $$
where
 $k_t$
represents the partial derivative of the function k with respect to t and
 $$ \begin{align*}\left\{\begin{array}{@{}ll} \psi(c)=\dfrac{c^\delta}{\delta}k^\delta(t,e_i)-k(t,e_i)cx^{\delta-1},\\ \phi(\pi)=\pi (b-r)+\dfrac{1}{2}(\delta-1)\sigma^2\pi^2 +\dfrac{1}{\delta}\displaystyle\int_{\mathbb{R}_0}((1+\pi\eta)^\delta-1)\nu_{e_i}(dz). \end{array}\right.\end{align*} $$
Recalling Theorem 3.2, we find that the inequality
 $$ \begin{align} \begin{array}{@{}ll} (\delta-1)^2e^{-2\gamma t}k^{1-\delta}(t,e_i)x^\delta\bigg[\sigma^2+\displaystyle\int_{\mathbb{R}_0}(1+\pi\eta)^{\delta-2}\eta^2\nu_{e_i}(dz)\bigg]>0 \end{array} \end{align} $$
holds and, thus, the maximizer of the problem (2.6) without constraints is the solution to the following equations:
 $$ \begin{align} \begin{cases} e^{-\gamma t}\psi'(c)=0,\\[.2cm] e^{-\gamma t}k^{1-\delta}(t,e_i) \phi'(\pi)=0, \end{cases} \end{align} $$
where
 $\psi '$
(
 $\phi '$
) represents the first derivative of
 $\psi $
(
 $\phi $
). From (4.5),
 $$ \begin{align} c^*=k^{-1}(t,e_i)x, \end{align} $$
which is the maximizer of
 $\psi (c)$
.
We see later in Proposition 4.6 that
 $k(t,e_i)$
is positive for any state
 $e_i$
. Hence, if
 $X^*(t)\geq 0$
holds, then
 $c^*(t)=k^{-1}(t,e_i)X^*(t)$
is the optimal consumption strategy. Before investigating the optimal portfolio strategy, we need the following result.
Lemma 4.1. Assume that the consumption process
 $c(t)$
is given by the equation (4.6). For any
 $s\in [0,T],$
if
 $1+\pi \eta (u,\cdot ,\alpha (u))\geq 0$
holds for any
 $u\in [0,s]$
, then
 $X(s)\geq 0$
.
Proof. Inserting
 $c(t)=k^{-1}(t,e_i)X(t)$
back into (2.3) yields
 $$ \begin{align*}\begin{array}{@{}ll} dX(t)=X(t)\bigg\{[r+ (b-r)\pi-k^{-1}(t,\alpha(t-))]\,dt+\sigma\pi\,dW(t)+\displaystyle\int_{\mathbb{R}_0}\eta\pi N_{\alpha}(dt, dz)\bigg\}. \end{array}\end{align*} $$
Applying Itô’s formula to
 $\ln X(t)$
and integrating on both sides from
 $0$
to s for
 $s\in [0,T],$
 $$ \begin{align*}\begin{array}{@{}ll} \begin{aligned} X(s)&=x\prod\limits_{k=1}^{N(s)}(1+\pi\eta(\tau_k,Z_{\tau_k},\alpha(\tau_k)))\\ &\quad \times\exp\bigg\{\int_0^s\bigg[r+ (b-r)\pi-\frac{1}{2}\sigma^2\pi^2-k^{-1}(u,\alpha(u-))\bigg]\,du+\int_0^s\sigma\pi\, dW(u)\bigg\}, \end{aligned} \end{array}\end{align*} $$
where
 $N(s)$
is the Poisson counting process (see the papers by Cont and Tankov and Framstad et al. [Reference Cont and Tankov7, Reference Framstad, Øksendal and Sulem9] for details) up to time
 $s.$
Since the exponent of the exponential function is positive, we have
 $X(s)\geq 0$
if
 $1+\pi \eta (u,\cdot ,\alpha (u))\geq 0$
for any
 $u\in [0,s].$
This completes the proof.
Define
 $$ \begin{align*}\begin{array}{@{}ll} \bar{M}=-\text{ess~inf} ~\eta(t,\cdot,\alpha(t))=-{\mathrm{sup}}\{m\mid \mathbb{P}(\{z \mid \eta(t,z,\alpha(t))<m\})=0\}, \end{array}\end{align*} $$
where the symbol “
 $\text {ess~inf}$
” is the essential infimum. Let
 $\pi _0=1/\bar {M}$
for
 $\bar {M}>0$
and
 $\pi _0=+\infty $
for
 $\bar {M}\leq 0.$
It is easy to see that
 $\pi _0 \geq 1$
. Then, for
 $\pi \in (\pi _0,+\infty ),$
it is possible that
 $1+\pi \eta (t,\cdot ,\alpha (t))\geq 0$
or
 $1+\pi \eta (t,\cdot ,\alpha (t))<0.$
If
 $1+\pi \eta (t,\cdot ,\alpha (t))<0,$
then it follows from Lemma 4.1 that the nonnegativity of
 $X(t)$
cannot be guaranteed and hence the consumption process
 $c(t)$
could be negative due to equation (4.6), which is meaningless and impractical. Thus, in the following context, we shall consider the optimal portfolio strategy in the interval
 $[0,\pi _0]$
, which guarantees that
 $X(t)\geq 0.$
The following proposition gives the result of the optimal portfolio strategy.
Proposition 4.2. Suppose that Assumption
2.1
holds. Then the function
 $\phi (\pi )$
reaches its maximum value at
 $\pi ^*,$
where:
-
(i)
$\pi ^*$
is the unique positive solution to the equation (4.7)if
$$ \begin{align} b-r+(\delta-1)\sigma^2\pi+\displaystyle\int_{\mathbb{R}_0}(1+\pi\eta)^{\delta-1}\eta\nu_{e_i}(dz)=0 \end{align} $$
$\phi '(\pi _0)<0;$
-
(ii)
$\pi ^*=\pi _0$
if
$\phi '(\pi _0)\geq 0$
.


Proof. Obviously, according to the function
 $\phi (\pi ),$
 $$ \begin{align*}\left\{\begin{array}{@{}ll} \phi'(\pi)= b-r+(\delta-1)\sigma^2\pi+\displaystyle\int_{\mathbb{R}_0}(1+\pi\eta)^{\delta-1}\eta\nu_{e_i}(dz),\\ \phi''(\pi)= (\delta-1)\bigg[\sigma^2+\displaystyle\int_{\mathbb{R}_0}(1+\pi\eta)^{\delta-2}\eta^2\nu_{e_i}(dz)\bigg]. \end{array}\right.\end{align*} $$
For the jump-diffusion risk model, the jump item in
 $\phi (\pi )$
is a power function with respect to
 $\pi $
and
 $\eta (t,\cdot ,\alpha (t))$
is a random jump size with values in
 $(-1,+\infty )$
. Therefore, it is not easy to obtain an explicit expression for the optimal portfolio strategy simply using
 $\phi '(\pi )$
.
By the definition of
 $\pi _0,$
we know that
 $1+\pi \eta (t,\cdot ,\alpha (t))\geq 0$
and
 $\phi ''(\pi )<0$
for
 $\pi \in [0,\pi _0].$
Hence,
 $\phi (\pi )$
is continuous and concave in
 $[0,\pi _0].$
Also, following from Assumption 2.1, we have
 $\phi '(0)>0$
. Thus, we claim that if
 $$ \begin{align} \phi'(\pi_0)= b-r+(\delta-1)\sigma^2\pi_0+\displaystyle\int_{\mathbb{R}_0}(1+\pi_0\eta)^{\delta-1}\eta\nu_{e_i}(dz)<0 \end{align} $$
holds, according to the zero theorem [Reference Gille and Hornbostel13], there exists a unique solution
 $\pi ^*\in (0,\pi _0)$
such that
 $\phi '(\pi ^*)=0,$
which is the maximum point of
 $\phi (\pi ),$
and thus
 $\pi ^*$
is the optimal portfolio strategy. If
 $\phi '(\pi _0)\geq 0,$
that is,
 $\phi (\pi )$
increases in
 $[0,\pi _0],$
then
 $\pi _0$
is the maximizer of
 $\phi (\pi )$
and hence it is the optimal portfolio strategy.
Remark 4.3 If the jump size of the risky asset is nonnegative, that is,
 $\eta (t,\cdot ,\alpha (t))\geq ~0$
, we have
 $\pi _0=+\infty $
and
 $$ \begin{align*}\phi'(+\infty)= \lim\limits_{\pi\rightarrow +\infty}\phi'(\pi)=-\infty,\end{align*} $$
so that the condition (4.8) is satisfied. Therefore, the optimal portfolio strategy is the unique positive solution to the equation (4.7) in this case.
Remark 4.4 Note that
 $\pi _0=1/\bar {M}\geq 1.$
For the condition (4.8), which is similar to the condition
 $\phi '(1)<0$
in Framstad et al. [Reference Framstad, Øksendal and Sulem9] or Guambe and Kufakunesu [Reference Guambe and Kufakunesu14], we extend the interval of the optimal solution from
 $(0,1)$
to
 $(0,\pi _0].$
The following example illustrates the result in Proposition 4.2.
Example 4.5 Assume that the jump size of the risky asset is negative, that is,
 $-1<\eta (t,\cdot ,\alpha (t))<0.$
Set
 $\delta = q/p \in (0,1)$
with two positive integers p and q such that
 $p>q$
and
 $q/p$
is irreducible. Suppose that both p and q are odd numbers. In this case,
 $p-q$
and
 $3p-q$
are even numbers and
 $2p-q$
is an odd number, so that
 $(1+\pi \eta (t,\cdot ,\alpha (t)))^{\delta -1}\geq 0$
and
 $(1+\pi \eta (t,\cdot ,\alpha (t)))^{\delta -3}\geq 0$
for
 $\pi \in [0,+\infty ).$
Denote
 $$ \begin{align*}\varphi(\pi)=\sigma^2+\displaystyle\int_{\mathbb{R}_0}(1+\pi\eta)^{\delta-2}\eta^2\nu_{e_i}(dz)\end{align*} $$
with
 $$ \begin{align*}\left\{\begin{array}{@{}ll} \varphi(0)=\sigma^2+\displaystyle\int_{\mathbb{R}_0}\eta^2\nu_{e_i}(dz),\\ \varphi(+\infty)=\lim\limits_{\pi\rightarrow +\infty}\varphi(\pi)=\sigma^2,\\ \varphi'(\pi)=(\delta-2)\displaystyle\int_{\mathbb{R}_0}(1+\pi\eta)^{\delta-3}\eta^3\nu_{e_i}(dz)>0. \end{array}\right.\end{align*} $$
Thus, there exists a breaking point
 $\tilde {\pi }\in (0,+\infty )$
satisfying
 $$ \begin{align*}\varphi(\tilde{\pi}-)=\lim\limits_{\pi\rightarrow \tilde{\pi}-}\varphi(\pi)=+\infty\end{align*} $$
and
 $$ \begin{align*}\varphi(\tilde{\pi}+)=\lim\limits_{\pi\rightarrow \tilde{\pi}+}\varphi(\pi)=-\infty,\end{align*} $$
where
 $\varphi (\tilde {\pi }-)$
and
 $\varphi (\tilde {\pi }+)$
express the left limit and the right limit for the function
 $\varphi (\cdot )$
at
 $\tilde {\pi }$
, respectively. Then there is a
 $\tilde {\pi }_1>\tilde {\pi }$
such that
 $\varphi (\tilde {\pi }_1)=0.$
Define
 $$ \begin{align*}\left\{\begin{array}{@{}ll} \tilde{\pi}_0=\inf\{\tilde{\pi}>0\mid\varphi(\tilde{\pi}-)=+\infty,~ \varphi(\tilde{\pi}+)=-\infty\},\\ \pi_1=\inf\{\tilde{\pi}_1>\tilde{\pi}_0\mid\varphi(\tilde{\pi}_1)=0\},\\ \pi_{\infty}=\inf\{\pi>\pi_1\mid\varphi(\pi-)=+\infty\} \end{array}\right.\end{align*} $$
and put
 $\pi _{\infty }=+\infty $
if there does not exist
 $\pi>\pi _1$
such that
 $\varphi (\pi -)=+\infty .$
Obviously, we have
 $\tilde {\pi }_0\geq \pi _0.$
Moreover, it is easy to see that
 $\phi (0)=0, \phi '(0)>0$
and
 $$ \begin{align*}\left\{\begin{array}{@{}ll} \phi'(+\infty)= \lim\limits_{\pi\rightarrow +\infty}\phi'(\pi)=-\infty,\\ \phi''(\pi)= (\delta-1)\varphi(\pi),\\[3mm] \phi'''(\pi)=(\delta-1)\varphi'(\pi)<0. \end{array}\right.\end{align*} $$
Then, for
 $\pi \in [0,\tilde {\pi }_0), \phi ''(\pi )$
decreases and
 $\phi ''(\pi )<0,$
which in turn imply that
 $\phi '(\pi )$
is decreasing. On the other hand, for
 $\pi \in (\tilde {\pi }_0,\pi _\infty ), \phi (\pi )$
is convex in
 $(\tilde {\pi }_0,\pi _1)$
and concave in
 $(\pi _1,\pi _\infty ).$
Define
 $\Theta =\{\pi \geq 0:\varphi (\pi )>0\}.$
Then we have
 $[0,\tilde {\pi }_0)\cup (\pi _1,\pi _\infty )\subseteq \Theta $
. Note that the condition (4.4) holds for
 $\pi \in \Theta $
and
 $\phi (\pi )$
is concave in
 $\Theta .$
If
 $\phi '(\pi _1)\leq 0,$
then
 $\phi '(\tilde {\pi }_0+)=\lim \nolimits _{\pi \rightarrow \tilde {\pi }_0+}\phi '(\pi )<0$
and
 $\phi (\pi )$
decreases in
 $(\tilde {\pi }_0,\pi _\infty ).$
So, there exists a unique
 $\pi _1^*\in (0,\tilde {\pi }_0)$
such that
 $\phi '(\pi _1^*)=0$
and
 $\pi _1^*$
is the maximizer of
 $\phi (\pi ).$
Hence, the optimal portfolio strategy in this case is
 $\pi ^*=\min \{\pi _1^*,\pi _0\}$
and the trajectory of the function
 $\phi (\pi )$
is shown in Figure 1.
 $\phi '(\pi _1)\leq 0$
.

If
 $\phi '(\pi _1)>0,$
then we have
 $\phi '(\tilde {\pi }_0+)\geq 0$
or
 $\phi '(\tilde {\pi }_0+)<0.$
For
 $\phi '(\tilde {\pi }_0+)\geq 0,$
there exists
 $\pi _1^*>\pi _1$
such that
 $\phi (\pi )$
is increasing in
 $[0,\pi _1^*)$
and decreasing in
 $(\pi _1^*,\pi _\infty ).$
Hence,
 $\pi _1^*$
is the unique point such that
 $\phi '(\pi _1^*)=0,$
which maximizes
 $\phi (\pi ).$
However,
 $\pi _1^*\notin [0,\pi _0].$
Thus, the optimal portfolio strategy is
 $\pi ^*=\pi _0$
in this case and the trajectory of the function
 $\phi (\pi )$
is presented in Figure 2(a). For
 $\phi '(\tilde {\pi }_0+)<0, \phi (\pi )$
increases first and then decreases in
 $\pi \in (0,\tilde {\pi }_0-)$
. Moreover, there are two points
 $\pi _1^*, \pi _2^*\in (0,\pi _\infty )$
such that
 $\phi '(\pi _1^*)=0$
and
 $\phi '(\pi _2^*)=0.$
Note that
 $\pi _2^*\notin [0,\pi _0].$
Thus, the optimal portfolio strategy is
 $\pi ^*=\min \{\pi _1^*,\pi _0\}$
and the trajectory of the function
 $\phi (\pi )$
in this case is presented in Figure 2(b).
 $\phi '(\pi _1)>0$
.

With (4.6) and Proposition 4.2, by computing
 $c^*$
and
 $\pi ^*$
and putting them back into (4.3),
 $$ \begin{align} \begin{cases} k_t(t,e_i)+\dfrac{k(t,e_i)}{1-\delta}\bigg\{-\gamma+\delta(r+\pi^*(b-r)) +\dfrac{1}{2}\sigma^2 \delta(\delta-1){\pi^*}^2\\ ~~+\displaystyle\int_{\mathbb{R}_0}[(1+\pi^*\eta)^\delta-1]\nu_{e_i}(dz)\bigg\} + \dfrac{1}{1-\delta}\displaystyle\sum\limits_{j=1}^{l}q_{ij}k^{1-\delta}(t,e_j)k^\delta(t,e_i)+1=0,\\ k(T,e_i)=1. \end{cases} \end{align} $$
Proposition 4.6. The equation (4.9) admits a unique positive solution.
Proof. Note that the equation (4.9) can be rewritten as
 $$ \begin{align} \begin{cases} \dfrac{dk(t,e_i)}{dt}+M_{ii}k(t,e_i)+\displaystyle\sum_{j\neq i}M_{ij}k^{1-\delta}(t,e_j)k^{\delta}(t,e_i)+C=0,\\ k(T,e_i)=1, \end{cases} \end{align} $$
where
 $$ \begin{align*}\left\{\begin{array}{@{}ll} \begin{aligned} M_{ii}&=\frac{1}{1-\delta}\bigg\{-\gamma+\delta(r+\pi^*(b-r))+\frac{1}{2}\delta(\delta-1)\sigma^2{\pi^*}^2 \\[2pt] &\quad +\displaystyle\int_{\mathbb{R}_0} [(1+{\pi^*}\eta)^\delta-1]\nu_{e_i}(dz)+q_{ii}\bigg\},\\[2pt] M_{ij}&=\frac{1}{1-\delta}q_{ij}\quad (j\neq i),\\ C&=1. \end{aligned} \end{array}\right.\end{align*} $$
We first prove the existence and uniqueness of
 $k(t,e_i)$
to the equation (4.10). Denote
 $\bar {k}(t,e_i)=k^{1-\delta }(t,e_i)$
and
 $$ \begin{align*}\left\{\!\!\!\!\!\begin{array}{@{}ll} &\bar{M}_{ii}=(1-\delta)M_{ii},\\ &\bar{M}_{ij}=(1-\delta)M_{ij} \quad (j\neq i), \\ &\bar{C}=(1-\delta)C. \end{array}\right.\end{align*} $$
Then (4.10) can be rewritten as
 $$ \begin{align} \frac{d\bar{k}(t,e_i)}{dt}+\bar{M}_{ii}\bar{k}(t,e_i)+\sum_{j\neq i}\bar{M}_{ij}\bar{k}(t,e_j)+\bar{C}\bar{k}^{-\delta/(1-\delta)}(t,e_i)=0. \end{align} $$
This equation satisfies the Lipschitz condition, since all of the parameters are continuous and bounded and
 $\pi ^*\in (0,\pi _0]$
. Applying Lemma A.1 in the Appendix of Cajueiro and Yoneyama [Reference Cajueiro and Yoneyama3], one can conclude that the equation (4.11) has a unique solution and that there exists a unique solution to the equation (4.10).
We next prove that the solution
 $k(t,e_i)$
to (4.10) is positive. Setting
 $\tau =T-t$
in (4.10) yields
 $dt=-d\tau .$
Let
 $\tilde {k}(\tau ,e_i)=k(T-\tau ,e_i)=k(t,e_i).$
Then equation (4.10) can be expressed as
 $$ \begin{align} \begin{cases} \dfrac{d\tilde{k}(\tau,e_i)}{d\tau}=M_{ii}\tilde{k}(\tau,e_i)+\displaystyle\sum_{j\neq i}M_{ij}\tilde{k}^{1-\delta}(\tau,e_j)\tilde{k}^{\delta}(\tau,e_i)+C,\\ \tilde{k}(0,e_i)=1, \end{cases} \end{align} $$
in which
 $M_{ij}\geq 0$
for
 $j\neq i$
and C is a positive constant. Note that the equation (4.12) is the same as (A.3) in Lemma A.2 of Cajueiro and Yoneyama [Reference Cajueiro and Yoneyama3]. Therefore, one can show that the equation (4.12) has a positive solution and hence the equation (4.10) also has a positive solution.
As a result, the uniqueness and positivity of (4.10) imply that the equation (4.9) has a unique positive solution.
Finally, Propositions 4.2 and 4.6 together with equation (4.6) give the following result for the optimal problem with constraints, the problem (2.5).
Theorem 4.7. For the portfolio–consumption problem (2.5), the optimal strategy is attained at
 $u^*=(\pi ^*, c^*),$
where
 $\pi ^*$
and
 $c^*$
are given by Proposition
4.2
and equation (4.6), respectively. Moreover, the value function has the form
 $$ \begin{align*} V(t,x,e_i)=e^{-\gamma t}k^{1-\delta}(t,e_i)\frac{x^\delta}{\delta}, \end{align*} $$
where
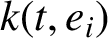 $k(t,e_i)$
is the unique positive solution to the equation (4.9).
5. Comparison of optimal results
In this section, we carry out some comparison between the optimal results for the jump-diffusion risk model and the pure diffusion model.
Assume that the financial market has only one state, that is,
 $l=1$
. Let
 $\pi ^*, c^*$
and
 $V(t,x)$
be the optimal results in the jump-diffusion market with
 $\nu \neq 0.$
Let
 $ \bar {\pi }^*, \bar {c}^*$
and
 $\bar {V}(t,x)$
be the corresponding optimal solutions when there are no jumps, that is,
 $\nu =0.$
Recall
 $\phi (\pi )$
defined in Proposition 4.2. Similarly, we define
 $$ \begin{align*}\begin{array}{@{}ll} \bar{\phi}(\pi)= \pi (b(t)-r(t)) +\frac{1}{2} \sigma^2\pi^2 (\delta-1) \end{array}\end{align*} $$
in the case of no jumps. Then we have
 $\phi (0)=\bar {\phi }(0)=0$
. In addition, we can rewrite the equation (4.9) as
 $$ \begin{align} \begin{cases} k_t(t)+\dfrac{\Gamma(t)}{1-\delta} k(t)+1=0,\\[.2cm] k(T)=1, \end{cases} \end{align} $$
where
 $\Gamma (t)=-\gamma +\delta r(t)+\delta \phi (\pi ^*).$
Solving the equation (5.1) by using the variation of constants method yields
 $$ \begin{align} k(t)=\exp\bigg\{\int_t^T\frac{\Gamma(s)}{1-\delta}\,ds\bigg\}+\int_t^T\exp\bigg\{\int_t^s\frac{\Gamma(\tau)}{1-\delta}d\tau\bigg\}\,ds. \end{align} $$
It follows from (5.2) that the function
 $k(t)$
increases as
 $\Gamma (t)$
increases. In order to make comparison of the optimal results more explicitly, we need to discuss the following three cases.
Case I
 $\eta (t,\cdot )\geq 0$
.
In this case,
 $\phi (\pi )$
is concave and the inequality
 $\phi '(\pi )\geq \bar {\phi }'(\pi )$
holds for all
 $\pi \in (0,+\infty ),$
which implies that
 $\bar {\phi }'(\pi ^*)\leq \phi '(\pi ^*)=0.$
Since
 $\bar {\phi }(\pi )$
is concave and
 $\bar {\pi }^*$
is the maximum point with
 $\bar {\phi }'(\bar {\pi }^*)=0$
, we conclude that
 $\bar {\pi }^*\leq \pi ^*.$
Moreover, we have
 $\phi (\pi ^*)\geq \phi (\bar {\pi }^*)\geq \bar {\phi }(\bar {\pi }^*)$
and thus
 $$ \begin{align*}\Gamma(t)\geq\bar{\Gamma}(t)=-\gamma+\delta r(t)+\delta\bar{\phi}(\bar{\pi}^*).\end{align*} $$
In other words, the value of
 $k(t)$
in the jump case is no less than that in the case without jumps. Therefore, we have
 $V(t,x)\geq \bar {V}(t,x)$
and
 $c^*\leq \bar {c}^*.$
Case II
 $-1<\eta (t,\cdot )<0$
.
In this case, we know that
 $\phi (\pi )$
is concave and
 $\phi '(\pi )<\bar {\phi }'(\pi )$
in
 $[0,\pi _0].$
If
 $\bar {\pi }^*\in [0,\pi _0],$
we have
 $\phi '(\bar {\pi }^*)<\bar {\phi }'(\bar {\pi }^*)=0$
. So, we obtain
 $\bar {\pi }^*>\pi ^*$
and
 $\phi (\pi ^*)<\bar {\phi }(\bar {\pi }^*),$
which in turn yield
 $\Gamma (t)<\bar {\Gamma }(t).$
As a result, we get
 $V(t,x)<\bar {V}(t,x)$
and
 $c^*>\bar {c}^*.$
On the other hand, if
 $\bar {\pi }^*>\pi _0,$
it is obvious that
 $\bar {\pi }^*>\pi ^*$
and
 $\phi (\pi ^*)<\bar {\phi }(\bar {\pi }^*)$
, so that we obtain the same result, that is,
 $V(t,x)<\bar {V}(t,x)$
and
 $c^*>\bar {c}^*.$
Case III General
 $\eta (t,\cdot ),$
that is,
 $\eta (t,\cdot )> -1$
.
Put
 $$ \begin{align*}\tilde{\Phi}(\pi)=E[(1+\pi\eta)^{\delta-1}\eta]=\displaystyle\int_{\mathbb{R}_0}(1+\pi\eta)^{\delta-1}\eta\nu(dz).\end{align*} $$
For any
 $\pi \in [0,\pi _0],$
we have
 $\tilde {\Phi }(\pi _0)\leq \tilde {\Phi }(\pi )\leq E[\eta ].$
-
(a) If
$\phi '(\pi _0)<0$
holds, the optimal strategy
$\pi ^*\in (0,\pi _0)$
satisfies
$\phi '(\pi ^*)=0.$
-
(i) If
$E[\eta ]<0,$
that is, the average jump size of the risky asset is negative, the financial market is bad, so we have
$\tilde {\Phi }(\pi )<0,$
from which we conclude that
$\phi '(\pi )<\bar {\phi }'(\pi )$
. Therefore,
$\bar {\pi }^*>\pi ^*$
and
$\phi (\pi ^*)<\bar {\phi }(\bar {\pi }^*)$
, which lead to the two inequalities shown in Case II, that is,
$V(t,x)<\bar {V}(t,x)$
and
$c^*>\bar {c}^*.$
-
(ii) If
$\tilde {\Phi }(\pi _0)>0$
, which implies that
$\tilde {\Phi }(\pi )>0,$
then
$\phi '(\pi )>\bar {\phi }'(\pi ).$
Along the same lines, one can show that the two inequalities in this case are the same as those in Case I, that is,
$V(t,x)\geq \bar {V}(t,x)$
and
$c^*\leq \bar {c}^*.$
-
(iii) If
$E[\eta ]\geq 0$
and
$\tilde {\Phi }(\pi _0)\leq 0,$
it is hard to decide the sign of
$\tilde {\Phi }(\pi )$
and hence we cannot tell which one of
$\bar {\pi }^*$
and
$\pi ^*$
(
$\phi (\pi ^*)$
and
$\bar {\phi }\,(\bar {\pi }^*)$
) is larger. Hence, the relationship between
$c^*$
and
$\bar {c}^*$
and that of
$V(t,x)$
and
$\bar {V}(t,x)$
cannot be determined.
-
-
(b) If
$\phi '(\pi _0)\geq 0,$
the optimal strategy
$\pi ^*=\pi _0.$
-
(i) If
$E[\eta ]<0,$
similar to Case III(a)(i), one can obtain the result in Case II. -
(ii) If
$\tilde {\Phi }(\pi _0)>0,$
one can obtain
$\phi '(\pi )>\bar {\phi }'(\pi )$
and
$\phi '(\bar {\pi }^*)>\bar {\phi }'(\bar {\pi }^*)=0$
. Unfortunately, we still do not know whether
$\pi _0$
is larger than
$\bar {\pi }^*$
or vice versa, since
$\phi '(\pi _0)\geq 0,$
and
$\phi (\pi _0)$
may be greater or less than
$\bar {\phi }(\bar {\pi }^*)$
. -
(iii) If
$E[\eta ]\geq 0$
and
$\tilde {\Phi }(\pi _0)\leq 0,$
However, we cannot judge which one of
$$ \begin{align*} \phi'(\pi_0)&= b-r+(\delta-1)\sigma^2\pi_0+\displaystyle\int_{\mathbb{R}_0}(1+\pi_0\eta)^{\delta-1}\eta\nu(dz)\geq0\\ &\Rightarrow~ b-r+(\delta-1)\sigma^2\pi_0\geq0=b-r+(\delta-1)\sigma^2\bar{\pi}^*\\ &\Rightarrow~ \pi_0\leq\bar{\pi}^*. \end{align*} $$
$\phi (\pi _0)$
and
$\bar {\phi }(\bar {\pi }^*)$
is larger. Therefore, we cannot determine the relationship between
$c^*$
and
$\bar {c}^*$
and that of
$V(t,x)$
and
$\bar {V}(t,x)$
.
-


The following theorem summarizes the results of the comparison.
Theorem 5.1. Under Assumption 2.1 , the relationship between the jump-diffusion model and the pure diffusion model for the portfolio–consumption problem (2.5) is stated as follows.
-
(I) For
$\eta (t,\cdot )\geq 0,$
(5.3)
$$ \begin{align} \begin{cases} \pi^*\geq\bar{\pi}^*,\\ c^*\leq\bar{c}^*,\\ V(t,x)\geq\bar{V}(t,x). \end{cases} \end{align} $$
-
(II) For
$-1<\eta (t,\cdot )<0,$
(5.4)
$$ \begin{align} \begin{cases} \pi^*<\bar{\pi}^*,\\ c^*>\bar{c}^*,\\ V(t,x)<\bar{V}(t,x). \end{cases} \end{align} $$
-
(III) For general
$\eta (t,\cdot ),$
that is,
$\eta (t,\cdot )> -1,$
we have the following results:-
(i) if
$E[\eta ]<0,$
then (5.4) holds; -
(ii) if
$\phi '(\pi _0)<0$
and
$\tilde {\Phi }(\pi _0)>0$
, then (5.3) holds; -
(iii) if
$\phi '(\pi _0)\geq 0$
,
$E[\eta ]\geq 0$
and
$\tilde {\Phi }(\pi _0)\leq 0,$
then we can only conclude that
$\pi ^*=\pi _0\leq \bar {\pi }^*;$
-
(iv) if
$(\phi '(\pi _0)<0$
,
$E[\eta ]\geq 0$
,
$\tilde {\Phi }(\pi _0)\leq 0)$
or
$(\phi '(\pi _0)\geq 0$
and
$\tilde {\Phi }(\pi _0)>0),$
then no conclusion can be drawn.
-


Remark 5.2 The interpretation of Theorem 5.1 is as follows. If
 $\eta (t,\cdot )\geq 0,$
the financial market is in good shape and hence the jumps are positive. As a result, investors are willing to invest more into the risky asset, so that the amount of consumption is reduced. On the other hand,
 $\eta (t,\cdot )<0$
implies that the financial market is bad. In this case, investors prefer investing less into the risky asset. As for the general case, it is not clear that investors want to invest less or more into the risky asset in the jump-diffusion market. Further statistical properties of
 $\eta (t,\cdot )$
are needed in order to make a conclusion on the comparison of the optimal results.
Remark 5.3 In this section, we present some comparison results to illustrate the effects of the jump on the optimal results under the single-regime case, that is,
 $l=1$
. If multiple regimes are considered, the corresponding equation (5.1) will be
 $$ \begin{align*} \left\{\begin{array}{@{}ll} k_t(t,e_i)+\dfrac{\Gamma(t)}{1-\delta}k(t,e_i)+ \dfrac{1}{1-\delta}\displaystyle\sum\limits_{j=1}^{l}q_{ij}k^{1-\delta}(t,e_j)k^\delta(t,e_i)+1=0,\\ k(T,e_i)=1,~~i=1,2,\ldots,l. \end{array} \right. \end{align*} $$
For this case, although Proposition 4.6 guarantees its existence and uniqueness, it is very hard to obtain its explicit expression and not easy to analyse its properties as well, for example, the monotonicity with respect to
 $\Gamma (t)$
. As a result, it is difficult and even impossible to make comparisons for the optimal results. Thus, in order to obtain some comparative results, we only discuss the case with a single state.
6. Some special cases
In this section, we present some special cases of our model and compare the optimal results with those in the literature.
Example 6.1 (without jumps)
Suppose that the risky asset’s price process is simply modulated by a geometric Brownian motion. Write
 $b(t,\alpha (t))=b(\alpha (t))$
,
 $r(t,\alpha (t))=r(\alpha (t))$
and
 $\sigma (t,\alpha (t))=\sigma (\alpha (t)).$
Then the optimal strategy in Theorem 4.7 has the form
 $$ \begin{align*}(\pi^*,c^*)=\bigg(\dfrac{b(e_i)-r(e_i)}{(1-\delta)\sigma^2(e_i)},k^{-1}(t,e_i)x\bigg)\end{align*} $$
and the value function is given by
 $$ \begin{align*}V(t,x,e_i)=e^{-\gamma t}k^{1-\delta}(t,e_i)\frac{x^\delta}{\delta},\end{align*} $$
where
 $k(t,e_i)$
satisfies the following system:
 $$ \begin{align} \begin{cases} k_t(t,e_i)+\dfrac{1}{1-\delta}\bigg[-\gamma+\delta r(e_i) + \dfrac{\delta(b(e_i)-r(e_i))^2}{2(1-\delta)\sigma^2(e_i)}\bigg]k(t,e_i) \\ \qquad \qquad +\dfrac{1}{1-\delta}\displaystyle\sum\limits_{j=1}^{l}q_{ij}k^{1-\delta}(t,e_j)k^\delta(t,e_i)+1=0,\\ k(T,e_i)=1. \end{cases} \end{align} $$
These optimal results are the same as those shown by Cajueiro and Yoneyama [Reference Cajueiro and Yoneyama3, Theorem 5.1].
Example 6.2 (without regime switching)
Consider the case that Markov regime switching does not come into play, that is, the number of the market states is only one
 $(l = 1)$
, and that all the parameters
 $r(t), b(t), \sigma (t), \eta (t)$
are constants. Let
 $T\rightarrow +\infty $
and
 $k(t,e_i)=\tilde {k}.$
By putting
 $\tilde {k}$
into (4.9) and solving the corresponding equation, the optimal consumption strategy given in Theorem 4.7 becomes
 $$ \begin{align*}c^*=(C\delta)^{1/(\delta-1)}x,\end{align*} $$
where
 $$ \begin{align*}C=\frac{1}{\delta}\bigg(\frac{1-\delta}{\lambda}\bigg)^{1-\delta}\end{align*} $$
with
 $$ \begin{align*}\lambda=\gamma-\delta [r+{\pi^*}(b-r)]+\frac{1}{2}{\pi^*}^2\sigma^2 \delta(1-\delta)-\int_{\mathbb{R}_0} [(1+{\pi^*}\eta)^\delta-1]\nu(dz).\end{align*} $$
Also, under the condition that
 $\phi '(\pi _0)<0$
, the optimal portfolio strategy
 $\pi ^*$
is the unique positive solution to the following equation:
 $$ \begin{align*}b-r+{\pi}\sigma^2(\delta-1)+\displaystyle\int_{\mathbb{R}_0}(1+{\pi}\eta)^{\delta-1}\eta\nu(dz)=0.\end{align*} $$
Moreover, the value function is given by
 $$ \begin{align*}V(t,x)=Cx^\delta.\end{align*} $$
With
 $\pi _0=1,$
these results are in line with those by Framstad et al. [Reference Framstad, Øksendal and Sulem9].
Example 6.3 (without jumps and regime switching)
In this example, we assume that there are no jumps and no regime switching, and that the parameters
 $r(\alpha (t)), b(\alpha (t)), \sigma (\alpha (t))$
are constants. Then one can solve the equation (6.1) and obtain
 $$ \begin{align*}k(t)=e^{A(T-t)}+\frac{1}{A}e^{A(T-t)}-\frac{1}{A}\end{align*} $$
with
 $$ \begin{align*}A=\frac{1}{1-\delta}\bigg[-\gamma+\delta r+\frac{\delta(b-r)^2}{2(1-\delta)\sigma^2}\bigg].\end{align*} $$
If the following condition holds:
 $$ \begin{align*}\gamma>\delta r+\frac{\delta(b-r)^2}{2(1-\delta)\sigma^2},\end{align*} $$
then
 $A<0.$
When
 $T\rightarrow +\infty ,$
we have
 $k(t)\rightarrow - A^{-1}$
. Therefore, we obtain the optimal strategy
 $$ \begin{align*}\begin{array}{@{}ll} (\pi^*,c^*)= \bigg(\dfrac{b-r}{(1-\delta)\sigma^2},(\delta v)^{1/(\delta-1)}x\bigg) \end{array}\end{align*} $$
and the value function
 $V(x)=vx^\delta ,$
where
 $$ \begin{align*}v=\frac{1}{\delta(1-\delta)^{\delta-1}}\bigg(\gamma-\delta r-\frac{\delta(b-r)^2}{2(1-\delta)\sigma^2}\bigg)^{\delta-1}.\end{align*} $$
These results are consistent with the optimal results by Merton [Reference Merton23].
7. Conclusion
We investigated a portfolio and consumption problem in a finite-time horizon for an investor involving n risky securities, in which the risk model is governed by a jump-diffusion process with Markov regime switching. Under the criterion of maximizing the expected discounted total utility of consumption, we first investigated some results for the general objective function by the methods of the dynamic programming principle and the stochastic maximum principle and obtained the same results that the optimal strategy without constraint is the solution to a system of partial differential equations. Then, for the special case of the power utility, the existence and uniqueness of the optimal results were proved and closed-form expressions of the optimal strategy and value function were derived. In addition, we gave a comparison for the corresponding optimal results between the cases with and without jumps when the regime switching is ignored. We found that when the financial market is good, the investor will invest more into the risky asset in the jump-diffusion market than that in the pure diffusion market; however, when the financial market is bad, we obtained the opposite conclusion; as for the market being uncertain, whether the investor invests more into the risky asset or not in the jump-diffusion market strongly depends on the number and frequency of the jumps.
It is worth noting that we adopted the power utility to make the problem tractable. One of the potential research topics in the future is to extend our results to the case of other utilities. However, even in the case of power utility, the analysis and calculation are very complicated. It is also meaningful to extend our model to some other cases such as involving transaction cost and tax or covering borrowing constraints, which seem to be more challenging.
Acknowledgements
We would like to thank the anonymous reviewers and the Editor for their constructive comments and suggestions. We also thank the supporting agencies for this work: Z. Liang was supported by the National Natural Science Foundation of China (Grant Nos. 12071224 and 11771079), C. Zhang was supported by the Natural Science Fund for Colleges and Universities in Jiangsu Province (Grant No. 20KJB110018) and K. C. Yuen was supported by a grant from the Research Grants Council of the Hong Kong Special Administrative Region, China (Project No. HKU17306220).



