



1. Introduction
Optimal stopping problems determine the time to terminate a process so as to maximize expected rewards. Such problems have attracted a great deal of attention since they have wide applications in the areas of finance, economics, and statistics, such as the entry decision of a firm into a new market, pricing for American options, and the Wald test, which determines the optimal sampling size for a sequential experiment. One of the most frequently used results given in the literature is that of El Karoui [Reference El Karoui5]: the optimal stopping time exists when the reward process (of class
 $\mathcal{D}$
) is required to be upper semicontinuous. We refer to Karatzas and Shreve [Reference Karatzas and Shreve6] and Peskir and Shiryaev [Reference Peskir and Shiryaev11] and the references therein.
The optimal stopping problem only allows us to choose one time to exercise and get the related reward. If we have more than one time to exercise, how do we maximize the summation of the expected reward? This kind of problem is called the optimal multiple stopping problem. Carmona and Touzi [Reference Carmona and Touzi4] first established a rigorous mathematical analysis of the optimal multiple stopping in the continuous time case. The value function of the optimal
 $\ell$
-stopping problem coincides with the value function of an optimal single stopping problem after
 $\ell$
-times iteration. The optimal stopping strategy can also be constructed using the auxiliary optimal single stopping problems. The reward process in [Reference Carmona and Touzi4] is required to be continuous. One of the applications of the optimal multiple stopping problem is the pricing for the swing options, which usually comes from the energy market. Roughly speaking, a swing option is a type of contract utilized by investors in energy markets. This contract portrays the least and most energy an option holder can buy each day and each month, and how frequently during the month the option holder can change the daily quantity of energy purchased. Swing options are usually utilized for the purchase of oil, natural gas, and power.
The consumption of energy is influenced by many occasional elements, such as sudden weather changes, breakdown in power plants, financial crises, etc. When we encounter a high temperature variation or a strong storm, there will be a peak in power consumption. Due to the fact that energy storage is almost impossible in the case of electricity, the price will increase drastically, which have a significant impact in the financial market. For example, during the European summer heatwave in 2003, the spot prices on the Dutch APX rose by over 3000
 $\%$
between 10 and 11 August (from 19.18 €/MWh to 660.34 €/MWh). The electricity price can be characterized by a time-changed process driven by a Brownian motion and a compound Poisson process (see [Reference Borovkova and Schmeck2]). Therefore it is meaningful to study the optimal multiple stopping problem with irregular reward processes both in theoretical analysis and practical applications. Bouzguenda Zeghal and Mnif [Reference Bouzguenda Zeghal and Mnif3] generalized this problem to the context of a Lévy market. In [Reference Ben Latifa, Bonnans and Mnif1], the reward process is assumed to have right continuous path and to be left continuous along stopping times in expectation, i.e. the same assumptions as in [Reference El Karoui5] for the optimal single stopping problem. However, the results in [Reference Ben Latifa, Bonnans and Mnif1] and [Reference Bouzguenda Zeghal and Mnif3] cannot be applied to the market with electricity prices given in [Reference Borovkova and Schmeck2].
The optimal single and multiple stopping problem can also be well-defined when the reward is given by a set of random variables indexed by stopping times satisfying some compatibility properties, but not a progressively measurable process. Kobylanski et al. [Reference Kobylanski, Quenez and Rouy-Mironescu8] studied both the optimal single and multiple stopping problems under this framework. They constructed the optimal single (resp. multiple) stopping times when the reward family is continuous in expectation along stopping times (resp. uniformly continuous in expectation along stopping times). They also considered perpetual swing options. Kobylanski and Quenez [Reference Kobylanski and Quenez7] then extended the single stopping problem to the case when the reward family is upper semicontinuous in expectation along stopping times, with the help of the strict value function. Recently, Li [Reference Li10] investigated the optimal multiple stopping problem under the so-called filtration-consistent nonlinear expectations, which can be applied to the pricing for swing options under model uncertainty. The above results can naturally be applied to the case of reward processes.
In the present paper, we aim to investigate the optimal multiple stopping problem with finite terminal time induced by reward families under weaker regularity conditions. As a standard method for the
 $\ell$
-stopping problem, the value function corresponds to that for the single stopping problem with a new reward family, where the new reward family is the value function of an
 $(\ell-1)$
-stopping problem. In order to apply the results for the single stopping problem, we need to study the regularity of the value function of the optimal single stopping problem defined by an induction procedure, which is the main difficulty in this paper. Using some technical results from probability theory, we show that the value function preserves the regularity property proposed for the reward family (see Lemma 3.2). Therefore, applying the results in [Reference Kobylanski and Quenez7], we can construct the optimal stopping times for the auxiliary single stopping problems, which finally gives the optimal multiple stopping time. We also obtain the corresponding construction for the optimal multiple stopping problem when the reward is given by a progressively measurable process. Compared with the results in [Reference Ben Latifa, Bonnans and Mnif1], [Reference Bouzguenda Zeghal and Mnif3], and [Reference Carmona and Touzi4], our reward can be given by a family of random variables and it can be assumed to be right upper semicontinuous and left upper semicontinuous along stopping times in expectation, which makes our results applicable to broader situations, such as the pricing for swing options in the financial market with electricity prices given by [Reference Borovkova and Schmeck2].
The paper is organized as follows. We first recall some basic notions and results on optimal stopping problems in Section 2. In Section 3 we study the optimal multiple stopping problem when the reward is given by an admissible family of random variables which is upper semicontinuous in expectation along stopping times. The case that the reward is given by a progressively measurable process is investigated in Section 4.
2. Preliminaries
In this section we first recall some basic notions and results on optimal stopping problems without aggregation. More details can be found in [Reference Kobylanski and Quenez7] and [Reference Kobylanski, Quenez and Rouy-Mironescu8]. Let
 $(\Omega,\mathcal{F},\mathbb{P})$
be a Radon measure space, which is equipped with a filtration
 $\mathbb{F}=\{\mathcal{F}_t\}_{t\in[0,T]}$
satisfying the usual conditions of right continuity and completeness. Throughout this paper, we fix a terminal time T. Let
 $\mathcal{S}_{0,T}$
be the set of
 $\mathbb{F}$
-stopping times taking values between 0 and T, and for any
 $\sigma,\sigma'\in \mathcal{S}_{0,T}$
with
 $\sigma\leq \sigma'$
, set
 $\mathcal{S}_{\sigma,\sigma'}=\{\tau\in \mathcal{S}_{0,T}\colon \sigma\leq \tau\leq \sigma'\}$
. For simplicity, we always omit the subscript T.
Remark 2.1. The reason why we consider a Random measure space is that we need the fact that
 $\mathbb{P}$
is a compact measure and Lusin’s theorem to prove our technical result (see Lemma 3.2). Typically, if
 $\Omega$
is a Polish space and
 $\mathcal{F}$
is the
 $\sigma$
-algebra of Borel sets, then
 $(\Omega,\mathcal{F},\mathbb{P})$
is a Radon measure space. For example, let
 $\Omega=C_0^d([0,\infty))$
be the space of all continuous,
 $\mathbb{R}^d$
-valued functions
 $\omega$
on
 $[0,\infty)$
with
 $\omega_0=0$
, equipped with the distance
 \begin{align*} d(\omega^1,\omega^2)=\sum_{n=1}^{\infty}\dfrac{1}{2^n}\max_{0\leq t\leq n}\bigl(|\omega^1_t-\omega^2_t|\wedge 1\bigr).\end{align*}
Let
 $\mathcal{F}$
be the Borel
 $\sigma$
-algebra and let
 $\mathbb{P}$
be the Wiener measure. Then
 $(\Omega,\mathcal{F},\mathbb{P})$
is a Radon measure space.
Given a set of random variables indexed by stopping times written as
 $\{X(\tau),\tau\in\mathcal{S}_0\}$
, the basic requirement of this family is to be admissible, defined as follows.
Definition 2.1. The family
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
is called admissible if it satisfies the following.
-
(1) For all
 $\tau\in\mathcal{S}_0$
,
$X(\tau)$
is an
$\mathcal{F}_{\tau}$
-measurable, non-negative random variable.
-
(2) For all
$\tau,\tau'\in\mathcal{S}_0$
,
$X(\tau)=X(\tau')$
a.s. on
$\{\tau=\tau'\}$
.


Remark 2.2. (i) Let
 $\{Y_t\}_{t\in[0,T]}$
be a positive, progressively measurable process. For any
 $\tau\in \mathcal{S}_0$
, set
 $X(\tau)\,:\!=\, Y_{\tau}$
. Then the family
 $\{X(\tau),\tau\in\mathcal{S}_0\}$
is admissible. The assumptions on admissible family can be seen as the requirement for adaptedness and compatibility, respectively. In fact, the definition of admissible family coincides with the notion of
 $T_0$
-system introduced in [Reference El Karoui5].
(ii) Let
 $T=1$
and
 $(\Omega,\mathcal{F},\mathbb{P})=([0,1],\mathcal{L},\lambda)$
, where
 $\mathcal{L}$
denotes the
 $\sigma$
-algebra of Lebesgue sets in [0,Reference Ben Latifa, Bonnans and Mnif1] and
 $\lambda$
denotes the Lebesgue measure. Let
 $\mathcal{L}_0\subset \mathcal{L}$
be the
 $\sigma$
-algebra such that
 $\lambda(B)=0$
or 1 for any
 $B\in\mathcal{L}_0$
. For each
 $t\in[0,1]$
, set
 $\mathcal{F}_t=\mathcal{L}_0$
and
 $\mathbb{F}=\{\mathcal{F}_t\}_{t\in[0,1]}$
. Define the set A by
 $A=\{(t,\omega)\in[0,1]\times[0,1]\colon t=\omega\in[0,1/2]\}$
and the function
 $I^A$
by
 \begin{align*}I^A_t(\omega)=\begin{cases}1, & t=\omega\in[0,1/2],\\0, &\text{otherwise}.\end{cases}\end{align*}
We claim that for any
 $\mathbb{F}$
-stopping time
 $\tau$
,
 $I^A_\tau$
is
 $\mathcal{F}_\tau$
-measurable. It suffices to prove that for any
 $a\in\mathbb{R}$
and any
 $t\in[0,1]$
, we have
 \begin{align*}\{I^A_\tau\geq a\}\cap \{\tau\leq t\}\in \mathcal{F}_t=\mathcal{L}_0,\end{align*}
which is equivalent to the following equation
 \begin{equation}\lambda(\{I^A_\tau\geq a\}\cap \{\tau\leq t\})=0\ \text{or 1.}\end{equation}
Clearly (2.1) holds true for any
 $a\leq 0$
and
 $a> 1$
. By the definition of
 $\mathbb{F}$
, for any stopping time
 $\tau$
, there exists a constant
 $t_\tau\in[0,1]$
and a set
 $B_\tau\in \mathcal{L}_0$
with
 $\lambda(B_\tau)=1$
, such that
 $\tau(\omega)=t_\tau$
for any
 $\omega\in B_\tau$
. Then we consider the following two cases.
Case 1.
 $t\in [0,t_\tau)$
. In this case, we have
 $\lambda(\{\tau\leq t\})=0$
.
Case 2.
 $t\in [t_\tau,1]$
. In this case, for any
 $a\in(0,1]$
, we have
 \begin{align*}\{I^A_\tau(\omega)\geq a\}&=\{\tau(\omega)=\omega\in[0,1/2]\}\\&=(\{t_\tau=\omega\in [0,1/2]\}\cap B_\tau)\cup (\{\tau(\omega)=\omega\in [0,1/2]\}\cap B^c_\tau).\end{align*}
It follows that
 $\lambda(\{I^A_\tau(\omega)\geq a\})=0$
.
Then we conclude that in the above two cases, (2.1) still holds. Hence, for any
 $\mathbb{F}$
-stopping time
 $\tau$
,
 $I^A_\tau\in \mathcal{F}_\tau$
. However, it is worth pointing out that Example 1.38 of [Reference Scheutzow12] indicates that the process
 $I^A$
is not progressively measurable.
Let
 $\{X(\tau),\tau\in\mathcal{S}_0\}$
be a given admissible family, which can be regarded as the reward. The value function at time
 $S\in \mathcal{S}_0$
is defined by
 \begin{equation}v(S)\,:\!=\, \operatorname{ess\,sup}_{\tau\in \mathcal{S}_S}\mathbb{E}_S[X(\tau)],\end{equation}
where
 $\mathbb{E}_S[\cdot]$
is the conditional expectation taken under
 $\mathbb{P}$
with respect to
 $\mathcal{F}_S$
. The following result indicates that the value function family is admissible.
Proposition 2.1. ([Reference Kobylanski and Quenez7, Reference Kobylanski, Quenez and Rouy-Mironescu8].) The family
 $\{v(S),S\in\mathcal{S}_0\}$
defined by (2.2) is admissible.
Definition 2.2. An admissible family
 $\{X(\tau),\tau\in\mathcal{S}_0\}$
is said to be a supermartingale family (resp. a martingale family) if, for any
 $\tau,\sigma\in \mathcal{S}_0$
with
 $\tau\leq \sigma$
a.s., we have
 \begin{align*}\mathbb{E}_\tau[X(\sigma)]\leq X(\tau)\ \text{a.s.}\quad (\text{resp.}\ \mathbb{E}_\tau[X(\sigma)]= X(\tau)\ \text{a.s.}).\end{align*}
Proposition 2.2. ([Reference Kobylanski and Quenez7, Reference Kobylanski, Quenez and Rouy-Mironescu8].) The family
 $\{v(S),S\in\mathcal{S}_0\}$
is a supermartingale family. Furthermore, it is characterized as the Snell envelope family associated with
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
, that is, the smallest supermartingale family which is greater than or equal to
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
.
The following proposition, known as the optimality criterion, provides a characterization of optimal stopping times for the value function v(S).
Proposition 2.3. ([Reference Kobylanski and Quenez7, Reference Kobylanski, Quenez and Rouy-Mironescu8].) Let
 $S\in\mathcal{S}_0$
and let
 $\theta^*\in\mathcal{S}_S$
be such that
 $\mathbb{E}[X(\theta^*)]<\infty$
. The following statements are equivalent.
-
(1)
$\theta^*$
is S-optimal for v(S), that is,
\begin{align*}v(S)=\mathbb{E}_S[X(\theta^*)] \quad {a.s.}\end{align*}
-
(2) The following equalities hold:
$v(\theta^*)=X(\theta^*)$
a.s. and
$\mathbb{E}[v(S)]=\mathbb{E}[v(\theta^*)]$
. -
(3) The following equality holds:
$\mathbb{E}[v(S)]=\mathbb{E}[X(\theta^*)]$
.


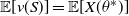
Remark 2.3. Note that since the value function is a supermartingale family, the equality
 $\mathbb{E}[v(S)]=\mathbb{E}[v(\theta^*)]$
is equivalent to the fact that the family
 $\{v(\theta),\theta\in \mathcal{S}_{S,\theta^*}\}$
is a martingale family, which can also be written as
 $\{v((\theta\vee S)\wedge \theta^*),\theta\in\mathcal{S}_0\}$
is a martingale family.
Note that none of the above results need any regularity assumptions on the reward family
 $\{X(\tau),\tau\in\mathcal{S}_0\}$
. However, in order to construct the optimal stopping time for the value function defined by (2.2), we need to propose the following condition on the admissible family
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
.
Definition 2.3. An admissible family
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
is said to be right (resp. left) upper semicontinuous in expectation along stopping times (RUSCE (resp. LUSCE)) if, for all
 $\tau\in \mathcal{S}_0$
and for all sequence of stopping times
 $\{\tau^n\}$
such that
 $\tau^n\downarrow \tau$
(resp.
 $\tau^n\uparrow \tau$
),
 \begin{align*}\mathbb{E}[X(\tau)]\geq \limsup_{n\rightarrow \infty} \mathbb{E}[X(\tau^n)].\end{align*}
An admissible family
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
is said to be upper semicontinuous in expectation along stopping times (USCE) if it is RUSCE and LUSCE.
Proposition 2.4. ([Reference Kobylanski and Quenez7].) If an admissible family
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
is right (resp. left) USCE, then, for each
 $S\in\mathcal{S}_0$
and each
 $A\in \mathcal{F}_S$
,
 $\{X(\tau)I_A, \tau\in\mathcal{S}_S\}$
is right (resp. left) USCE.
Now, we give the existence result of an optimal stopping time and the regularity of the value function family.
Theorem 2.1. ([Reference Kobylanski and Quenez7].) Suppose the reward family
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
is such that
 $v(0)<\infty$
and is USCE. Let
 $S\in\mathcal{S}_0$
. The stopping time
 $\theta^*(S)$
defined by
 \begin{align*}\theta^*(S)\,:\!=\, \operatorname{ess\, inf} \{\theta\in\mathcal{S}_S\colon v(\theta)=X(\theta) \ {a.s.}\}\end{align*}
is the minimal optimal stopping time for v(S). Further, the admissible family
 $\{v(S),S\in \mathcal{S}_0\}$
is USCE.
The optimal stopping time
 $\theta^*(S)$
can also be constructed by using hitting times of processes if the reward is given by some progressively measurable process. This formulation (see (2.3) below) gives an efficient method to compute an optimal stopping time by numerical methods since it is defined pathwise (see also line 7 of Section 4 in [Reference Kobylanski, Quenez and Rouy-Mironescu8]).
Proposition 2.5 ([Reference Kobylanski and Quenez7].) Let
 $\{X_t,t\in[0,T]\}$
be a right upper semicontinuous (i.e. for almost every
 $\omega$
, the function
 $t\rightarrow X_t(\omega)$
is right upper semicontinuous) progressively measurable process of class
 $\mathcal{D}$
. Suppose that the associated family
 $\{X_\tau,\tau\in \mathcal{S}_0\}$
is LUSCE. Then there exists an adapted process
 $\{v_t,t\in[0,T]\}$
aggregating the value function family
 $\{v(S),S\in\mathcal{S}_0\}$
, that is, for all
 $S\in\mathcal{S}_0$
,
 $v_S=v(S)$
a.s. Moreover, for all
 $S\in \mathcal{S}_0$
, the stopping time
 $\tau^*(S)$
defined by
 \begin{align}\tau^*(S)\,:\!=\, \inf\{t\geq S\colon v_t=X_t\}\end{align}
is the minimal optimal stopping time for v(S).
3. Optimal multiple stopping with reward family
Consider the holder of a swing option who can exercise it
 $\ell$
times. Let
 $\delta>0$
be the refracting period which separates two successive exercises. This requirement will exclude the trivial case that the holder exercises her
 $\ell$
-times rights simultaneously. When she exercises at stopping time
 $\tau$
, she will get the reward
 $X(\tau)$
. For
 $\ell\geq 2$
, let
 $\mathcal{S}_\tau(\ell,\delta)$
be the collection of all vectors of stopping times
 $\tau^{(\ell)}=(\tau_1,\ldots,\tau_\ell)$
satisfying
 \begin{align*} \tau_1\geq \tau, \tau_i-\tau_{i-1}\geq \delta \text{ on } \{\tau_{i-1}+\delta\leq T\},\quad \tau_i=T_+ \text{ on } \{\tau_{i-1}+\delta >T\}\quad \text{for all $ i=2, \ldots,\ell$.} \end{align*}
For any
 $\mathbb{F}$
-stopping time
 $\sigma$
and any family of random variables
 $\{\xi(\tau),\tau\in \mathcal{S}_0\}$
, we set
 $\xi(\sigma) I_{\{\sigma>T\}}=0$
. The value of the swing option at time
 $\tau$
is defined by
 \begin{equation}Z^{(\ell)}(\tau)\,:\!=\, \operatorname{ess\,sup}_{\tau^{(\ell)}\in \mathcal{S}_\tau(\ell,\delta)} \mathbb{E}_\tau\Biggl[\sum_{i=1}^\ell X(\tau_i)\Biggr].\end{equation}
The objective includes the following two aspects: (i) computing the value function
 $Z^{(\ell)}(\tau)$
as explicitly as possible, and (ii) finding the optimal multiple stopping time
 $(\tau^*_1,\ldots,\tau^*_\ell)\in \mathcal{S}_\tau(\ell,\delta)$
at which the supremum in (3.1) is attained. Motivated by [Reference Ben Latifa, Bonnans and Mnif1] and [Reference Carmona and Touzi4], we consider the following auxiliary optimal single stopping problems inductively:
 \begin{equation}Y^{(0)}\equiv 0\quad \text{and}\quad Y^{(i)}(\tau)=\operatorname{ess\,sup}_{\sigma\in\mathcal{S}_\tau}\mathbb{E}_\tau[X^{(i)}(\sigma)], \quad i=1,\ldots,\ell,\end{equation}
where the ith exercise reward family
 $X^{(i)}$
is given by
 \begin{equation}X^{(i)}(\tau)=\begin{cases} X(\tau)+ \mathbb{E}_\tau[Y^{(i-1)}(\tau+\delta)], & 0\leq \tau\leq T-\delta,\\X(\tau), &T-\delta < \tau\leq T.\end{cases}\end{equation}
In the rest of this paper, C will always be a positive constant, which may vary from line to line.
Remark 3.1. (i) Recalling the convention that
 $\xi(\sigma) I_{\{\sigma>T\}}=0$
for any family
 $\{\xi(\tau),\tau\in \mathcal{S}_0\}$
, we can write
 $X^{(i)}(\tau)=X(\tau)+ \mathbb{E}_\tau[Y^{(i-1)}(\tau+\delta)]$
for any
 $\tau\in \mathcal{S}_0$
.
(ii) We provide the motivation for the auxiliary optimal single stopping problems. Consider the multiple stopping problem in the discrete-time case. Suppose that
 $T,\delta,\ell$
are positive integers such that
 $(\ell-1)\delta\leq T$
. For any fixed
 $i=0,\ldots,T$
, let
 $\mathcal{S}^d_i(\ell,\delta)$
be the collection of all vectors of integer-valued stopping times
 $\tau^{(\ell)}=(\tau_1,\ldots,\tau_\ell)$
satisfying
 \begin{align*} \tau_1\geq i, \tau_j-\tau_{j-1}\geq \delta\quad \text{for all $ j=2, \ldots,\ell$.} \end{align*}
Further, we define
 $\mathcal{S}^d_i\,:\!=\, \mathcal{S}^d_i(1,\delta)$
. The value function of the optimal multiple stopping problem is given by
 \begin{align*}Z^{(\ell)}_d(i)=\operatorname{ess\,sup}_{\tau^{(\ell)}\in \mathcal{S}^d_i(\ell,\delta)} \mathbb{E}_i\Biggl[\sum_{j=1}^\ell X(\tau_j)\Biggr].\end{align*}
By Lemma 3.1 of [Reference Li9], the value function can be obtained recursively. More precisely, for any
 $j=2,\ldots,\ell$
, we have
 $Z^{(j)}_d(T)=X(T)$
and
 \begin{equation}Z^{(j)}_d(i)=\max\bigl\{ X(i)+\mathbb{E}_i\bigl[Z^{(j-1)}_d(i+\delta)\bigr],\mathbb{E}_i\bigl[Z^{(j)}_d(i+1)\bigr]\bigr\}, \quad i=0,\ldots, T-1,\end{equation}
and
 $Z^{(1)}_d$
is the value function of the optimal single stopping problem with reward
 $\{X(i)\}_{i=0}^T$
. Motivated by (3.4),
 $Z^{(j)}_d$
can be seen as the value function of the optimal single stopping problem with reward
 $\bigl\{X(i)+\mathbb{E}_i\bigl[Z^{(j-1)}_d(i+\delta)\bigr]\bigr\}_{i=0}^T$
.
Therefore, set
 \begin{align*}Y^{(0)}_d\equiv 0\quad \text{and}\quad Y^{(j)}_d(i)=\operatorname{ess\,sup}_{\sigma\in\mathcal{S}^d_i}\mathbb{E}_i[X^{(j)}(\sigma)],\quad j=1,\ldots,\ell,\end{align*}
where
 $X^{(j)}$
is given by
 \begin{align*}X^{(j)}(i)=\begin{cases} X(i)+ \mathbb{E}_i[Y^{(j-1)}(i+\delta)], & 0\leq i\leq T-\delta,\\X(i), &T-\delta < i\leq T.\end{cases}\end{align*}
It is obvious that
 $Z^{(1)}_d\equiv Y^{(1)}_d$
. By induction, we have
 $Z^{(j)}_d\equiv Y^{(j)}_d$
,
 $j=2,\ldots,\ell$
. That is, the value function of the optimal multiple stopping problem coincides with that for some optimal single stopping problem with a new reward family.
Lemma 3.1. Suppose that
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
is admissible. Then, for any
 $1\leq i\leq \ell$
, the families
 $\{Y^{(i)}(\tau),\tau\in \mathcal{S}_0\}$
,
 $\{X^{(i)}(\tau),\tau\in \mathcal{S}_0\}$
are admissible.
Proof. By Proposition 2.1, it is sufficient to prove that the family
 $\{X^{(i)}(\tau),\tau\in \mathcal{S}_0\}$
is admissible,
 $1\leq i\leq \ell$
. This fact is obvious when
 $i=1$
. We assume that
 $\{X^{(k)}(\tau),\tau\in \mathcal{S}_0\}$
are admissible for
 $1\leq k\leq i-1$
with
 $i\geq 2$
. It is clear that
 $X^{(i)}(\tau)$
is non-negative and
 $\mathcal{F}_\tau$
-measurable. Further, applying Proposition 2.1, the family
 $\{Y^{(i-1)}(\tau),\tau\in \mathcal{S}_0\}$
is admissible. For any
 $\tau,\sigma\in \mathcal{S}_0$
, on the set
 $A=\{\tau=\sigma\}$
, noting that
 $A\in \mathcal{F}_\tau\cap \mathcal{F}_\sigma$
, we have
 \begin{align*} \mathbb{E}_\tau[Y^{(i-1)}(\tau+\delta)]I_A&=\mathbb{E}_\tau[Y^{(i-1)}(\tau+\delta)I_A]\\ &=\mathbb{E}_\tau[Y^{(i-1)}(\sigma+\delta)I_A]\\ &=\mathbb{E}_\tau[Y^{(i-1)}(\sigma+\delta)]I_A\\ &=\mathbb{E}_\sigma[Y^{(i-1)}(\sigma+\delta)]I_A.\end{align*}
Hence the family
 $\{X^{(i)}(\tau),\tau\in\mathcal{S}_0\}$
is admissible.
In order to construct the optimal stopping time for the auxiliary problem (3.2), we assume that the family
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
satisfies the following condition:
-
(H1) The admissible family
$\{X(\tau),\tau\in\mathcal{S}_0\}$
is USCE and there exists some
$p>1$
such that
$\sup_{\tau\in\mathcal{S}_0}\mathbb{E}[|X(\tau)|^p]<\infty$
.


As we will see later, the optimal multiple stopping times are constructed by the optimal stopping times for the auxiliary single stopping problems. The existence of optimal stopping times for the single stopping problems needs some regularity property of the admissible family
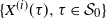 $\{X^{(i)}(\tau),\tau\in \mathcal{S}_0\}$
. More precisely, the admissible family
 $\{X^{(i)}(\tau),\tau\in \mathcal{S}_0\}$
should be USCE (see Theorem 2.1). The following lemma shows that the iterated reward processes
 $X^{(i)}$
,
 $i=2, \ldots,\ell$
inherit conditions proposed on the reward family
 $\{X(\tau),\tau\in\mathcal{S}_0\}$
.
Lemma 3.2. Under assumption (H1), for any
 $i=1,\ldots,\ell$
, the families
 $\{X^{(i)}(\tau),\tau\in\mathcal{S}_0\}$
,
 $\{Y^{(i)}(\tau),\tau\in \mathcal{S}_0\}$
satisfy
 $\sup_{\tau\in\mathcal{S}_0}\mathbb{E}[|X^{(i)}(\tau)|^p]<\infty$
,
 $\sup_{\tau\in\mathcal{S}_0}\mathbb{E}[|Y^{(i)}(\tau)|^p]<\infty$
. Furthermore, the family
 $\{X^{(i)}(\tau),\tau\in\mathcal{S}_0\}$
is USCE.
Proof.
Step 1. We first prove that the properties hold when
 $i=1$
. Since
 $X^{(1)}=X$
, the properties of
 $\{X^{(1)}(\tau),\tau\in\mathcal{S}_0\}$
are obvious. By Theorem 2.1, for any stopping time
 $\tau$
, there exists a stopping time
 $\tau^*(\tau)$
such that
 $Y^{(1)}(\tau)=\mathbb{E}_\tau[X(\tau^*(\tau))]$
. It follows that
 \begin{align*}\mathbb{E}[|Y^{(1)}(\tau)|^p]&=\mathbb{E}[|\mathbb{E}_\tau[X(\tau^*(\tau))]|^p]\\&\leq \mathbb{E}[\mathbb{E}_\tau[|X(\tau^*(\tau))|^p]]\\&=\mathbb{E}[|X(\tau^*(\tau))|^p]\\&\leq \sup_{\tau\in \mathcal{S}_0}\mathbb{E}[|X(\tau)|^p]\\&<\infty.\end{align*}
Now suppose that the properties hold for the families
 $\{X^{(k)}(\tau),\tau\in\mathcal{S}_0\}$
,
 $\{Y^{(k)}(\tau),\tau\in \mathcal{S}_0\}$
for
 $1\leq k\leq i-1$
with some
 $i\geq 2$
.
Step 2. We then show that
 $\{X^{(i)}(\tau),\tau\in\mathcal{S}_0\}$
is USCE. Set
 $Y^{(i-1)}(\sigma)=0$
on the set
 $\{\sigma> T\}$
. Note that for any
 $\tau\in \mathcal{S}_0$
we have
 \begin{equation*}\mathbb{E}[X^{(i)}(\tau)]=\mathbb{E}[X(\tau)]+\mathbb{E}[Y^{(i-1)}(\tau+\delta)].\end{equation*}
It suffices to show that the family
 $\{Y^{(i-1)}(\tau+\delta),\tau\in \mathcal{S}_{0}\}$
is USCE. We first prove the left upper semicontinuity. Let
 $\{\tau^n\}$
be a set of stopping times such that
 $\tau^n\uparrow \tau$
; we aim to show that
 \begin{align*}\limsup_{n\rightarrow \infty}\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)]\leq \mathbb{E}[Y^{(i-1)}(\tau+\delta)].\end{align*}
For any
 $\varepsilon \in (0,1)$
, there exists an
 $\mathcal{F}_\tau$
-measurable compact set B such that
 $\mathbb{P}(B^c)\leq {{\varepsilon}/{2}}$
. By Lusin’s theorem, there exists some
 $\mathcal{F}_\tau$
-measurable open sets
 $\{O_n\}_{n=0}^\infty$
with
 $\mathbb{P}(O_n)\leq {{\varepsilon}/{2^{n+2}}}$
, such that the restrictions of
 $\tau_n$
to
 $O^c_n$
and of
 $\tau$
to
 $O^c_0$
are continuous. Set
 \begin{align*}O=\biggl(\bigcup_{n=0}^\infty O_n\biggr)\bigcup B^c.\end{align*}
It is easy to check that
 $\mathbb{P}(O)\leq \varepsilon$
. Since
 $\{\tau^n\}$
is increasing in n, it converges uniformly on
 $O^c$
by Dini’s theorem. Hence, on the set
 $\{\tau+\delta>T\}\cap O^c$
, there exists an integer N independent of
 $\omega$
, such that for any
 $n\geq N$
,
 $\tau^n+\delta>T$
and on the set
 $\{\tau+\delta\leq T\}$
, we have
 $\{\tau^n+\delta\leq T\}$
for any n. Now, for
 $n\geq N$
, recalling that
 $Y^{(i-1)}(\sigma)=0$
on the set
 $\{\sigma> T\}$
, it is easy to check that
 \begin{equation}\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)]=\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)I_{\{\tau+\delta\leq T\}}]+\mathbb{E}[Y^{(i-1)}(\tau^n+\delta) I_{\{\tau+\delta> T\}}I_{O}].\end{equation}
For any n, a simple calculation implies that
 \begin{align}|\mathbb{E}[Y^{(i-1)}(\tau^n+\delta) I_{\{\tau+\delta> T\}}I_{O}]|&\leq (\mathbb{E}[|Y^{(i-1)}(\tau^n+\delta)|^p])^{1/p} (\mathbb{P}(O))^{1/q} \notag \\&\leq \Bigl(\sup_{\sigma\in \mathcal{S}_0}\mathbb{E}[|Y^{(i-1)}(\sigma)|^p]\Bigr)^{1/p} \varepsilon^{1/q},\end{align}
where
 $q=p/(p-1)$
. Recalling that
 $\{X^{(i-1)}(\tau),\tau\in\mathcal{S}_0\}$
is USCE, by Theorem 2.1, the family
 $\{Y^{(i-1)}(\tau),\tau\in \mathcal{S}_0\}$
is USCE. It is easy to check that
 $\{\tau+\delta\leq T\}\in \mathcal{F}_\tau$
and
 $\tau^n+\delta\geq \tau$
for n large enough. By Proposition 2.4 and applying (3.5) and (3.6), we have
 \begin{align*}\limsup_{n\rightarrow \infty}\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)]&\leq \limsup_{n\rightarrow \infty}\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)I_{\{\tau+\delta\leq T\}}]+ C\varepsilon^{1/q}\\&\leq \mathbb{E}[Y^{(i-1)}(\tau+\delta)I_{\{\tau+\delta\leq T\}}]+C\varepsilon^{1/q}\\&=\mathbb{E}[Y^{(i-1)}(\tau+\delta)]+C\varepsilon^{1/q},\end{align*}
where
 $C=(\sup_{\sigma\in \mathcal{S}_0}\mathbb{E}[|Y^{(i-1)}(\sigma)|^p])^{1/p}$
. Letting
 $\varepsilon$
approach 0, we get the desired result.
Now we prove the right upper semicontinuity of the family
 $\{Y^{(i-1)}(\tau+\delta),\tau\in \mathcal{S}_{0}\}$
. Let
 $\{\tau^n\}$
be a set of stopping times such that
 $\tau^n\downarrow \tau$
. On the set
 $\{\tau+\delta>T\}$
, for any n, we have
 $\{\tau^n+\delta> T\}$
. Hence, on the set
 $\{\tau+\delta> T\}$
,
 $Y^{(i-1)}(\tau^n+\delta)=Y^{(i-1)}(\tau+\delta)(=0)$
. It follows that
 \begin{equation}\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)]= \mathbb{E}[Y^{(i-1)}(\tau^n+\delta)I_{\{\tau+\delta\leq T\}}]+\mathbb{E}[Y^{(i-1)}(\tau+\delta) I_{\{\tau+\delta>T\}}].\end{equation}
We define
 \begin{align*}\widetilde{\tau}^n=\tau^n I_{\{\tau^n+\delta\leq T\}}+(T-\delta) I_{\{\tau^n+\delta>T\}}=\min\{\tau^n,T-\delta\}.\end{align*}
It is easy to check that
 $\widetilde{\tau}^n$
is non-increasing in n,
 $\widetilde{\tau}^n\geq \tau\wedge (T-\delta)$
and
 $\widetilde{\tau}^n\downarrow \widetilde{\tau}$
, where
 $\widetilde{\tau}=\tau I_{\{\tau+\delta\leq T\}}+(T-\delta)I_{\{\tau+\delta>T\}}$
. Noting that
 $Y^{(i-1)}$
is non-negative and
 $\{\tau^n+\delta\leq T\}\subset \{\tau+\delta\leq T\}$
, we have
 \begin{align*}&\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)I_{\{\tau+\delta\leq T\}}]\\&\quad =\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)I_{\{\tau^n+\delta\leq T\}}]+\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)I_{\{\tau+\delta\leq T<\tau^n+\delta\}}]\\&\quad \leq \mathbb{E}[Y^{(i-1)}(\widetilde{\tau}^n+\delta)I_{\{\tau^n+\delta\leq T\}}]+\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)I_{\{\tau^n-\tau>0\}}]\\&\quad \leq \mathbb{E}[Y^{(i-1)}(\widetilde{\tau}^n+\delta)I_{\{\tau+\delta\leq T\}}]+C(\mathbb{P}(\{\tau^n-\tau>0\}))^{1/q},\end{align*}
where
 $C=(\sup_{\sigma\in \mathcal{S}_0}\mathbb{E}[|Y^{(i-1)}(\sigma)|^p])^{1/p}$
and
 $1/p+1/q=1$
. It follows that
 \begin{align}\limsup_{n\rightarrow\infty}\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)I_{\{\tau+\delta\leq T\}}]&\leq \limsup_{n\rightarrow\infty}\mathbb{E}[Y^{(i-1)}(\widetilde{\tau}^n+\delta)I_{\{\tau+\delta\leq T\}}]\notag \\&\leq \mathbb{E}[Y^{(i-1)}(\widetilde{\tau}+\delta)I_{\{\tau+\delta\leq T\}}]\notag \\&= \mathbb{E}[Y^{(i-1)}(\tau+\delta)I_{\{\tau+\delta\leq T\}}],\end{align}
where we have used the dominated convergence theorem in the first inequality and Proposition 2.4 in the second inequality. Combining (3.7) and (3.8) yields
 \begin{align*}\limsup_{n\rightarrow\infty}\mathbb{E}[Y^{(i-1)}(\tau^n+\delta)]\leq \mathbb{E}[Y^{(i-1)}(\tau+\delta)],\end{align*}
which is the desired result.
Step 3. It remains to prove that
 $\sup_{\tau\in\mathcal{S}_0}\mathbb{E}[|X^{(i)}(\tau)|^p]<\infty$
and
 $\sup_{\tau\in\mathcal{S}_0}\mathbb{E}[|Y^{(i)}(\tau)|^p]<\infty$
. A simple calculation implies that
 \begin{align*}\mathbb{E}[|X^{(i)}(\tau)|^p]&\leq C\{\mathbb{E}[|X(\tau)|^p]+\mathbb{E}[|\mathbb{E}_\tau[Y^{(i-1)}(\tau+\delta)]|^p]\}\\&\leq C\{\mathbb{E}[|X(\tau)|^p]+\mathbb{E}[|Y^{(i-1)}(\tau+\delta)|^p]\}.\end{align*}
It follows that
 $\sup_{\tau\in\mathcal{S}_0}\mathbb{E}[|X^{(i)}(\tau)|^p]<\infty$
. Since the admissible family
 $\{X^{(i)}(\tau),\tau\in\mathcal{S}_0\}$
is USCE with
 $\sup_{\tau\in\mathcal{S}_0}\mathbb{E}[|X^{(i)}(\tau)|^p]<\infty$
, by Theorem 2.1, for each
 $\tau\in \mathcal{S}_0$
, there exists an optimal stopping time
 $\tau^*$
, i.e.
 $Y^{(i)}(\tau)=\mathbb{E}_\tau[X^{(i)}(\tau^*)]$
. By an analysis similar to that of the proof of Step 1, we have
 \begin{align*}\sup_{\tau\in\mathcal{S}_0}\mathbb{E}[|Y^{(i)}(\tau)|^p]\leq \sup_{\tau\in\mathcal{S}_0}\mathbb{E}[|X^{(i)}(\tau)|^p]<\infty.\end{align*}
The proof is complete.
In the following we aim to construct the optimal multiple stopping times for the problem (3.1). Recall the double stopping problem in Remark 3.1. It is easy to check that the optimal double stopping times should be
 $(\tau^*_1(S),\tau^*_2(S))$
, where
 \begin{align*}\tau_1^*(S)&=\operatorname{ess\,inf}\{\tau\in \mathcal{S}_S\colon Z^{(2)}(\tau)=X^{(2)}(\tau)\},\\\tau_2^*(S)&=\operatorname{ess\,inf}\{\tau\in \mathcal{S}_{\tau^*_1(S)+\delta}\colon Z^{(1)}(\tau)=X(\tau)\}.\end{align*}
Motivated by this construction (or the construction in [Reference Carmona and Touzi4] and [Reference Kobylanski, Quenez and Rouy-Mironescu8]), for the general case, given
 $\tau\in \mathcal{S}_0$
, we set
 \begin{align*}\tau^*_1(\tau)=\operatorname{ess\,inf}\{\sigma\in \mathcal{S}_\tau\colon X^{(\ell)}(\sigma)=Y^{(\ell)}(\sigma)\}.\end{align*}
For
 $2\leq i\leq \ell$
, we define
 \begin{align*}\tau^*_i(\tau)&=\operatorname{ess\,inf}\{\sigma\in \mathcal{S}_{\tau^*_{i-1}(\tau)+\delta}\colon X^{(\ell-i+1)}(\sigma)=Y^{(\ell-i+1)}(\sigma)\}I_{\{\delta+\tau^*_{i-1}(\tau)\leq T\}} + (T_+) I_{\{\delta+\tau^*_{i-1}(\tau)>T\}}.\end{align*}
It is easy to check that
 $\vec{\tau}^*(\tau)=(\tau^*_1(\tau),\ldots,\tau^*_\ell(\tau))\in \mathcal{S}_\tau(\ell,\delta)$
. Actually, we claim that
 $\vec{\tau}^*(\tau)$
is the optimal multiple stopping time for the problem (3.1). In order to prove this assertion, we first show that
 $\tau^*_i$
is optimal for the auxiliary single stopping problem (3.2).
Theorem 3.1. Under assumption (H1), for each
 $\tau\in\mathcal{S}_0$
, there exists an optimal stopping time for
 $Y^{(\ell-i+1)}(\tau)$
,
 $1\leq i\leq \ell$
. Moreover,
 $\tau^*_i(\tau)$
is the minimal optimal stopping time for
 $Y^{(\ell-i+1)}(\tau^*_{i-1}(\tau)+\delta)$
(by convention
 $\tau^*_0(\tau)+\delta=\tau$
), and the family
 \begin{align*}\{Y^{(\ell-i+1)}(\sigma\wedge \tau^*_i(\tau))\colon \tau^*_{i-1}(\tau)+\delta\leq \sigma\leq T\}\end{align*}
is a martingale family.
Theorem 3.2. Let assumption (H1) hold. Then, for each
 $\tau\in\mathcal{S}_0$
, we have
 \begin{align*}Z^{(\ell)}(\tau)=Y^{(\ell)}(\tau)=\mathbb{E}_\tau\Biggl[\sum_{i=1}^\ell X(\tau^*_i(\tau))\Biggr],\end{align*}
which implies that
 $\vec{\tau}^*(\tau)$
is the optimal multiple stopping time.
Proof. The proof is similar to those for Theorem 2.1 of [Reference Carmona and Touzi4] and Theorem 4.10 of [Reference Ben Latifa, Bonnans and Mnif1]. For the readers’ convenience, we give a short proof here. For any
 $\vec{\tau}=(\tau_1,\ldots,\tau_\ell)\in \mathcal{S}_\tau(\ell,\delta)$
, we first note that for any
 $1\leq i\leq \ell$
,
 \begin{equation}\mathbb{E}_\tau\Biggl[\sum_{j=1}^\ell X(\tau_j)\Biggr]\leq \mathbb{E}_\tau\Biggl[X^{(i)}(\bar{\tau}_i)+\sum_{j=i+1}^\ell X(\bar{\tau}_j)\Biggr],\end{equation}
where
 $\bar{\tau}_i\,:\!=\, \tau_{\ell-i+1}$
and
 $\sum_{j=\ell+1}^\ell X(\bar{\tau}_j)\,:\!=\, 0$
. The proof of (3.9) is postponed (to the end of this proof). Now, choosing
 $i=\ell$
, by Theorem 3.1, we have
 \begin{align}\mathbb{E}_\tau\Biggl[\sum_{j=1}^\ell X(\tau_j)\Biggr]&\leq \mathbb{E}_\tau[X^{(\ell)}(\bar{\tau}_\ell)]\notag \\&\leq Y^{(\ell)}(\tau)=\mathbb{E}_\tau[X^{(\ell)}(\tau^*_1(\tau))]\notag \\&=\mathbb{E}_\tau[X(\tau^*_1(\tau))+\mathbb{E}_{\tau^*_1(\tau)}[Y^{(\ell-1)}(\tau^*_1(\tau)+\delta)]]\notag \\&=\mathbb{E}_\tau[X(\tau^*_1(\tau))]+\mathbb{E}_{\tau}[Y^{(\ell-1)}(\tau^*_1(\tau)+\delta)].\end{align}
By Theorem 3.1 and (3.3), it is easy to check that for any
 $1\leq i\leq \ell-1$
,
 \begin{equation}\mathbb{E}_\tau[Y^{(\ell-i)}(\tau^*_{i}(\tau)+\delta)]=\mathbb{E}_\tau[X^{(\ell-i)}(\tau^*_{i+1}(\tau))]=\mathbb{E}_\tau[X(\tau^*_{i+1}(\tau))+Y^{(\ell-i-1)}(\tau^*_{i+1}(\tau)+\delta)].\end{equation}
Using (3.10), (3.11), and by a recursive method, we have
 \begin{align*}\mathbb{E}_\tau\Biggl[\sum_{j=1}^\ell X(\tau_j)\Biggr]\leq Y^{(\ell)}(\tau)\leq \mathbb{E}_\tau\Biggl[\sum_{j=1}^\ell X(\tau^*_j(\tau))\Biggr]\leq Z^{(\ell)}(\tau).\end{align*}
Since
 $\vec{\tau}=(\tau_1,\ldots,\tau_\ell)\in \mathcal{S}_\tau(\ell,\delta)$
is chosen arbitrarily, taking the essential supremum over all
 $\vec{\tau}$
in
 $\mathcal{S}_\tau(\ell,\delta)$
, we get the desired result.
It remains to prove that (3.9) holds by an induction method. Clearly this inequality holds when
 $i=1$
. Suppose that (3.9) is true for
 $1\leq k\leq i-1$
, with
 $2\leq i\leq \ell$
. Since we have
 \begin{equation}\mathbb{E}_\tau\Biggl[\sum_{j=1}^\ell X(\tau_j)\Biggr]=\mathbb{E}_\tau\Biggl[\sum_{j=1}^{i-1} X(\bar{\tau}_j)+\sum_{j=i}^\ell X(\bar{\tau}_j)\Biggr],\end{equation}
it suffices to prove that
 \begin{align*}\mathbb{E}_\tau\Biggl[\sum_{j=1}^{i-1} X(\bar{\tau}_j)\Biggr]\leq \mathbb{E}_\tau[X^{(i)}(\bar{\tau}_{i})-X(\bar{\tau}_{i})].\end{align*}
Recalling that (3.9) holds for
 $1\leq k\leq i-1$
and noting that (3.12), we have
 \begin{align*}\mathbb{E}_\tau\Biggl[\sum_{j=1}^{i-1} X(\bar{\tau}_j)\Biggr]\leq \mathbb{E}_\tau[X^{(i-1)}(\bar{\tau}_{i-1})].\end{align*}
Therefore, we only need to show that
 \begin{equation}\mathbb{E}_\tau[X^{(i-1)}(\bar{\tau}_{i-1})]\leq \mathbb{E}_\tau[X^{(i)}(\bar{\tau}_{i})-X(\bar{\tau}_{i})].\end{equation}
For the case
 $T-\delta< \bar{\tau}_{i}\leq T$
, we have
 $X^{(i)}(\bar{\tau}_{i})=X(\bar{\tau}_{i})$
and
 $\bar{\tau}_{i-1}=\tau_{\ell-i+2}\geq \tau_{\ell-i+1}+\delta=\bar{\tau}_{i}+\delta>T$
. It follows that
 \begin{align*}\mathbb{E}_\tau[X^{(i-1)}(\bar{\tau}_{i-1})]=0= \mathbb{E}_\tau[X^{(i)}(\bar{\tau}_{i})-X(\bar{\tau}_{i})].\end{align*}
For the case
 $0\leq \bar{\tau}_{i}\leq T-\delta$
, noting that
 $\bar{\tau}_{i-1}=\tau_{\ell-i+2}\geq \tau_{\ell-i+1}+\delta=\bar{\tau}_{i}+\delta\geq \tau$
, we have
 \begin{align*}\mathbb{E}_\tau[X^{(i-1)}(\bar{\tau}_{i-1})]=\mathbb{E}_\tau[\mathbb{E}_{\bar{\tau}_{i}+\delta}[X^{(i-1)}(\bar{\tau}_{i-1})]]\leq \mathbb{E}_\tau[Y^{(i-1)}(\bar{\tau}_{i}+\delta)]= \mathbb{E}_\tau[X^{(i)}(\bar{\tau}_{i})-X(\bar{\tau}_{i})].\end{align*}
Hence (3.13) holds true. The proof is complete.
4. Optimal multiple stopping with reward process
In this section we consider optimal multiple stopping problems for the particular case where the reward is given by a progressively measurable process
 $\{X_t,t\in[0,T]\}$
. Applying the results obtained in the previous section, we construct the optimal multiple stopping times in terms of first hitting times under the following assumption:
-
(H2) X is a non-negative, progressively measurable process with right upper semicontinuous path (RUSC) a.s. For some
$p>1$
,
$\mathbb{E}[\bar{X}^p]<\infty$
, where
$\bar{X}=\sup_{t\in[0,T]}X_t$
. Furthermore, X is left upper semicontinuous in expectation along stopping times (LUSCE), that is, for any
$\{\tau_n\}_{n\in \mathbb{N}}\subset \mathcal{S}_0$
with
$\tau_n\uparrow \tau$
, we have
\begin{align*}\limsup_{n\rightarrow \infty}\mathbb{E}[X_{\tau_n}]\leq \mathbb{E}[X_\tau].\end{align*}


Remark 4.1. Under assumption (H2), the associated family
 $\{X(\tau),\tau\in\mathcal{S}_0\}$
satisfies (H1), where
 $X(\tau)\,:\!=\, X_\tau$
.
Set
 $X_t=0$
,
 $t>T$
, and consider the following value function of the optimal multiple stopping problem associated with the reward process X,
 \begin{equation*} Z^{(\ell)}_0\,:\!=\, \sup_{\tau^{(\ell)}\in \mathcal{S}_0(\ell,\delta)} \mathbb{E}\Biggl[\sum_{i=1}^\ell X_{\tau_i}\Biggr],\end{equation*}
and the auxiliary optimal single stopping problems,
 \begin{equation}Y^{(0)}\equiv 0 \quad \text{and}\quad Y^{(i)}_t=\operatorname{ess\,sup}_{\sigma\in\mathcal{S}_t}\mathbb{E}_t[X^{(i)}_\sigma], \quad i=1,\ldots,\ell,\end{equation}
where the ith exercise reward process
 $X^{(i)}$
is given by
 \begin{equation}X_t^{(i)}=\begin{cases} X_t+ \mathbb{E}_t[Y^{(i-1)}_{t+\delta}], & t\in[0,T-\delta],\\X_t, &t\in(T-\delta,T].\end{cases}\end{equation}
We will show that the value
 $Z^{(\ell)}_0$
coincides with
 $Y^{(\ell)}_0$
and the optimal multiple stopping time exists under assumption (H2). In fact these results are obtained in [Reference Carmona and Touzi4] when the reward process X is continuous and in [Reference Ben Latifa, Bonnans and Mnif1] when X is right continuous and left continuous in expectation along stopping times (LCE for short), that is, for any
 $\{\tau_n\}_{n\in \mathbb{N}}\subset \mathcal{S}$
with
 $\tau_n\uparrow \tau$
, we have
 \begin{align*}\lim_{n\rightarrow \infty}\mathbb{E}[X_{\tau_n}]= \mathbb{E}[X_\tau].\end{align*}
We first list some properties which do not essentially depend on the regularity of the reward process.
Lemma 4.1. Under assumption (H2), we have for all
 $i=1,\ldots,\ell$
,
 \begin{align*}\mathbb{E}[(\bar{X}^{(i)})^p]<\infty,\quad {where}\ \bar{X}^{(i)}=\sup_{t\in[0,T]}X^{(i)}_t\end{align*}
and p is the same as in (H2).
Proof. The proof is similar to those for Lemma 2.1 of [Reference Carmona and Touzi4] and Lemma 4.2 of [Reference Ben Latifa, Bonnans and Mnif1]. For the readers’ convenience, we give a short proof here. We proceed by induction. For
 $i=1$
, the result is obvious since
 $X^{(1)}=X$
. Let us assume that
 $\mathbb{E}[(\bar{X}^{(i-1)})^p]<\infty$
for some
 $2\leq i\leq \ell$
. We shall prove that
 $\mathbb{E}[|\bar{X}^{(i)}|^p]<\infty$
. For any
 $\tau\in \mathcal{S}_0$
and
 $t\in[0,T]$
, it is easy to check that
 \begin{align*}\mathbb{E}_t[X^{(i-1)}_\tau]\leq \mathbb{E}_t[\bar{X}^{(i-1)}].\end{align*}
Since
 $\tau$
is chosen arbitrarily, we have
 $Y^{(i-1)}_t\leq \mathbb{E}_t[\bar{X}^{(i-1)}]$
. The martingale inequality yields
 \begin{align*}\mathbb{E}\Bigl[\sup_{t\in[0,T]}|Y^{(i-1)}_t|^p\Bigr]&\leq \mathbb{E}\Bigl[\sup_{t\in[0,T]}|\mathbb{E}_t[\bar{X}^{(i-1)}] |^p\Bigr]\\&\leq \mathbb{E}\Bigl[\sup_{t\in[0,T]}\mathbb{E}_t[|\bar{X}^{(i-1)}|^p] \Bigr]\\&\leq \biggl(\dfrac{p}{p-1}\biggr)^p\mathbb{E}[|\bar{X}^{(i-1)}|^p]\\&<\infty.\end{align*}
A simple calculation indicates that
 \begin{align*}\mathbb{E}[|\bar{X}^{(i)}|^p]& \leq C\Bigl\{\mathbb{E}[|\bar{X}|^p]+\mathbb{E}\Bigl[\sup_{t\in[0,T]}|\mathbb{E}_t[Y^{(i-1)}_{t+\delta}]|^p\Bigr]\Bigr\}\\&\leq C\Bigl\{\mathbb{E}[|\bar{X}|^p]+\mathbb{E}\Bigl[\sup_{t\in[0,T]}\mathbb{E}_t\Bigl[\sup_{s\in[0,T]}|Y^{(i-1)}_{s}|^p\Bigr]\Bigr]\Bigr\}\\&\leq C\Bigl\{\mathbb{E}[|\bar{X}|^p]+\mathbb{E}\Bigl[\sup_{t\in[0,T]}|Y^{(i-1)}_{t}|^p\Bigr]\Bigr\}\\&<\infty,\end{align*}
where C is a constant depending only on p. The proof is complete.
In the following, we aim to show that
 $X^{(i)}$
possesses all the properties of X, especially the regularity property, which makes it possible to represent the optimal stopping time for
 $Y^{(i)}$
as the first hitting time using Proposition 2.5. Before establishing this result, we first list some results about the single stopping problem when the reward is given by a progressively measurable process (see [Reference Kobylanski and Quenez7]).
Let
 $\{X_t,t\in[0,T]\}$
be a non-negative progressively measurable process. Set
 $\phi(\tau)\,:\!=\, X_\tau$
, for any
 $\tau\in \mathcal{S}_0$
. Then the family
 $\{\phi(\tau),\tau\in\mathcal{S}_0\}$
is admissible. Let
 $v_\phi$
be the value function associated with the family
 $\{\phi(\tau),\tau\in\mathcal{S}_0\}$
. Suppose that
 $v_\phi(0)<\infty$
. Then, by Proposition B.1 of [Reference Kobylanski and Quenez7], there exists a progressively measurable process
 $\{v_t,t\in[0,T]\}$
aggregating the value function family
 $\{v_\phi(\tau),\tau\in\mathcal{S}_0\}$
, i.e.
 $v_\phi(S)=v_S$
for all
 $S\in\mathcal{S}_0$
. Further, the process
 $\{v_t,t\in[0,T]\}$
is a strong supermartingale and there exists a right limited and left limited version of
 $\{v_t,t\in[0,T]\}$
, still denoted by
 $\{v_t,t\in[0,T]\}$
(see P23 in [Reference Kobylanski and Quenez7]).
Further, we assume additionally that
 $\{X_t,t\in[0,T]\}$
is of class
 $\mathcal{D}$
and the family
 $\{X_\tau,\tau\in\mathcal{S}_0\}$
is RUSCE. Then
 $\{v_t,t\in[0,T]\}$
is a strong supermartingale of class
 $\mathcal{D}$
. Furthermore, by Proposition 2.26 of [Reference El Karoui5] (see also P25 in [Reference Kobylanski and Quenez7]), there exists a uniformly integrable RCLL martingale M, a predictable right continuous non-decreasing process A with
 $A_0=0$
and
 $\mathbb{E}[A_T]<\infty$
and an adapted non-decreasing process C, which is purely discontinuous with
 $C_0=0$
and
 $\mathbb{E}[C_T]<\infty$
, such that
 \begin{align*}v_t=M_t-A_t-C_{t-}, \quad t\in[0,T].\end{align*}
Moreover, the above decomposition is unique. With this decomposition, it is easy to check that
 $\{v_t,t\in[0,T]\}$
is RUSC.
To summarize, we have the following lemma.
Lemma 4.2. Suppose that the non-negative, progressively measurable process
 $\{X_t,t\in[0,T]\}$
is of class
 $\mathcal{D}$
and RUSCE. Then
 $\{v_t,t\in[0,T]\}$
is a strong supermartingale of class
 $\mathcal{D}$
and is RUSC, where, for any
 $t\in[0,T]$
,
 \begin{align*}v_t=\operatorname{ess\,sup}_{\tau\in \mathcal{S}_t}\mathbb{E}_t[X_\tau].\end{align*}
Now, we may prove that
 $X^{(i)}$
inherits all the properties of X.
Lemma 4.3. Under assumption (H2), for all
 $i=1,\ldots,\ell$
, the process
 $X^{(i)}$
also satisfies (H2), that is, it is non-negative, progressively measurable, RUSC, and LUSCE.
Proof. It is clear that the process
 $X^{(i)}$
is non-negative and progressively measurable. We prove by induction that
 $X^{(i)}$
is RUSC and LUSCE. For
 $i=1$
, we are done since
 $X^{(1)}=X$
. Now assume that
 $X^{(i-1)}$
is RUSC and LUSCE for
 $i=2,\ldots, \ell$
. Let us first prove that
 $X^{(i)}$
is RUSC. By the definition of
 $X^{(i)}$
(see (4.2) and note that it is clear that
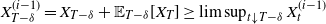 $X^{(i-1)}_{T-\delta}=X_{T-\delta}+\mathbb{E}_{T-\delta}[X_T]\geq \limsup_{t\downarrow T-\delta} X^{(i-1)}_t$
), it suffices to prove that
 $\{\mathbb{E}_t[Y^{(i-1)}_{t+\delta}]\}$
is RUSC on
 $[0,T-\delta)$
. First, by Lemma 4.2,
 $Y^{(i-1)}$
is an RUSC strong supermartingale. For any
 $t_n\downarrow t$
as n goes to infinity, there exists some N such that for
 $n\geq N$
,
 $t_n\leq t+\delta$
. Then we have
 \begin{align*}&\limsup_{n\rightarrow \infty}\bigl(\mathbb{E}_{t_n}\bigl[Y^{(i-1)}_{t_n+\delta}\bigr]-\mathbb{E}_t\bigl[Y^{(i-1)}_{t+\delta}\bigr]\bigr)\\&\quad \leq \limsup_{n\rightarrow \infty}\bigl(\mathbb{E}_{t_n}\bigl[Y^{(i-1)}_{t_n+\delta}\bigr]-\mathbb{E}_{t_n}\bigl[Y^{(i-1)}_{t+\delta}\bigr]\bigr)+\limsup_{n\rightarrow \infty}\bigl(\mathbb{E}_{t_n}\bigl[Y^{(i-1)}_{t+\delta}\bigr]-\mathbb{E}_{t}\bigl[Y^{(i-1)}_{t+\delta}\bigr]\bigr)\\&\quad =\limsup_{n\rightarrow \infty}\bigl(\mathbb{E}_{t_n}\bigl[\mathbb{E}_{t+\delta}\bigl[Y^{(i-1)}_{t_n+\delta}\bigr]\bigr]-\mathbb{E}_{t_n}\bigl[Y^{(i-1)}_{t+\delta}\bigr]\bigr)\leq 0,\end{align*}
where we have used the fact that
 $Y^{(i-1)}$
is a supermartingale in the last inequality. Therefore
 $\bigl\{\mathbb{E}_t\bigl[Y^{(i-1)}_{t+\delta}\bigr]\bigr\}$
is RUSC on
 $[0,T-\delta)$
. Recalling that we assume
 $X^{(i-1)}$
is RUSC and LUSCE, it follows that the family
 $\bigl\{X^{(i-1)}_\tau,\tau\in\mathcal{S}_0\bigr\}$
is USCE. Then the LUSCE property of
 $X^{(i)}$
is obtained from Lemma 3.2. The proof is complete.
Remark 4.2. In order to show that
 $\{X^{(i)}_t,t \in [0,T]\}$
is progressively measurable, it suffices to prove that
 $\{\mathbb{E}_t[\eta_{t+\delta}]\}_{t\in[0,T-\delta]}$
is progressively measurable for any
 $\eta \in M_p$
, where
 $p\geq 1$
and
 \begin{align*}M_p=\biggl\{\eta\colon \eta \ \text{is progressively measurable and}\ \mathbb{E}\biggl[\int_0^T |\eta_t|^p\,{\mathrm{d}} t\biggr]<\infty\biggr\}.\end{align*}
In fact, if
 $\eta$
is a simple process, it is clear that
 $\{\mathbb{E}_t[\eta_{t+\delta}]\}_{t\in[0,T-\delta]}$
is progressively measurable. For the general case, let
 $\{\eta^n\}_{n\in \mathbb{N}}$
be a sequence of simple process such that
 \begin{align*}\lim_{n\rightarrow \infty}\mathbb{E}\biggl[\int_0^T|\eta^n_t-\eta_t|^p \,{\mathrm{d}} t\biggr]=0.\end{align*}
It is easy to check that for any
 $n\in\mathbb{N}$
,
 $\{\mathbb{E}_t[\eta^n_{t+\delta}]\}_{t\in[0,T-\delta]}$
is progressively measurable and
 \begin{align*}\lim_{n\rightarrow \infty}\mathbb{E}\biggl[\int_0^{T-\delta}|\mathbb{E}_t[\eta^n_{t+\delta}]-\mathbb{E}_t[\eta_{t+\delta}]|^p \,{\mathrm{d}} t\biggr]\leq \lim_{n\rightarrow \infty}\mathbb{E}\biggl[\int_0^{T-\delta}|\eta^n_t-\eta_t|^p \,{\mathrm{d}} t\biggr]=0.\end{align*}
It follows that
 $\{\mathbb{E}_t[\eta_{t+\delta}]\}_{t\in[0,T-\delta]}$
is progressively measurable.
Building upon Proposition 2.5, Lemma 4.1, and Lemma 4.3, we may construct the optimal stopping time for the auxiliary optimal stopping problems (4.1).
Theorem 4.1. Under assumption (H2), for each
 $\tau\in \mathcal{S}_0$
, there exists an optimal stopping time for
 $Y^{(\ell-i+1)}_\tau$
,
 $i=1,\ldots,\ell$
. Moreover,
 $\tau^*_i$
is the minimal optimal stopping time for
 $Y^{(\ell-i+1)}_{\tau^*_{i-1}+\delta}$
(with convention
 $\tau^*_0+\delta=0$
), where
 \begin{align*}\tau^*_1=\inf\bigl\{t\geq 0\colon Y^{(\ell)}_t=X^{(\ell)}_t\bigr\}\end{align*}
and for
 $2\leq i\leq \ell$
,
 \begin{align*}\tau^*_i=\inf\bigl\{t\geq \tau^*_{i-1}+\delta\colon Y^{(\ell-i+1)}_t=X^{(\ell-i+1)}_t\bigr\} I_{\{\tau^*_{i-1}+\delta\leq T\}}+T_+ I_{\{\tau^*_{i-1}+\delta>T\}}.\end{align*}
Further,
 $(\tau^*_1,\ldots,\tau^*_\ell)\in \mathcal{S}_0(\ell,\delta)$
and the process
 $\bigl\{Y^{(\ell-i+1)}_{t\wedge \tau^*_i}, \tau^*_{i-1}+\delta\leq t\leq T\bigr\}$
is a martingale.
Now we can state the final result in this section, which indicates that when the reward is given by a progressively measurable process satisfying some weak regularity conditions, the optimal multiple stopping times can be interpreted by the first hitting times.
Theorem 4.2. Under assumption (H2), we have
 \begin{align*}Z^{(\ell)}_0=Y^{(\ell)}_0=\mathbb{E}\Biggl[\sum_{i=1}^\ell X_{\tau^*_i}\Biggr],\end{align*}
where
 $(\tau^*_1,\ldots,\tau^*_\ell)$
is defined in Theorem 4.1. That is,
 $(\tau^*_1,\ldots,\tau^*_\ell)$
is the optimal exercise strategy for the optimal multiple stopping problem.
Proof. The proof is similar to that for Theorem 3.2, so we omit it.
Remark 4.3. Note that the optimal multiple stopping times in Theorem 3.2 are represented as the essential infimum over a set of stopping times. It cannot be used directly to prove Theorem 4.2 since the optimal multiple stopping times here are interpreted as first hitting times. However, these two representation of optimal multiple stopping times are equal if the reward process X satisfies (H2) (i.e. satisfies the conditions in Proposition 2.5). In fact it is easy to check that the reward family
 $\{X(\tau),\tau\in \mathcal{S}_0\}$
satisfies the conditions in Theorem 2.1. Note that the optimal stopping times given in Theorem 2.1 and Proposition 2.5 are both minimal optimal stopping times for the same value function. Applying Theorem 3.1, Lemma 4.3, and Theorem 4.1, we may conclude that
 $\tau^*_i=\tau^*_i(0)$
.
Acknowledgements
The author thanks the anonymous referee for their helpful comments and suggestions which have contributed greatly to the present version.
Funding information
I acknowledge financial support by the Natural Science Foundation of Shandong Province (no. ZR2022QA022), the Natural Science Foundation of Shandong Province for Excellent Young Scientists Fund Program (Overseas) (no. 2023HWYQ-049), the National Natural Science Foundation of China (no. 12301178), the Fundamental Research Funds for the Central Universities and the Qilu Young Scholars Program of Shandong University.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


