


1. Introduction
Friedrich Hayek's work is associated with his critique of central planning and with his advocacy of a classical liberal institutional structure. Hayek's economic arguments against central planning rest on an epistemic foundation: market prices are necessary knowledge dissemination devices in an economy where knowledge is dispersed among its constituent individuals and where the cognitive limitations of each individual are severe (Hayek, Reference Hayek1937, Reference Hayek1945, Reference Hayek1952). His case for a classical liberal institutional order rests on the assumption that universal, stable, and simple rules facilitate the coordination of individual plans in an uncertain and open-ended world (Hayek, Reference Hayek1979).
Austrian economists tend to define socialism as coterminous with central planning; their rejection of socialism rests on this definition in conjunction with theories that focus on entrepreneurship and open-ended change. But this is not the only way to define socialism. In the Marxian tradition, it is common to define socialism as the absence of ‘capitalist exploitation' of workers. Socialism may then be defined as the abolition of wage contracts and the resulting entitlement of workers to the ‘full value’ of their labor.
It is this labor-centered definition of socialism that enables Theodore Burczak (Reference Burczak2006) to claim that a socialist system is possible that preserves the knowledge-generating properties of the market process. Burczak offers a vision that attempts to combine decentralized market competition with the socialist traits of worker-managed firms and comprehensive redistribution of wealth.
In the following section, I provide a brief summary of Hayekian arguments for a society that is organized according to classical liberal principles. The third section provides a general outline of Burczak's (ibid.) vision of Hayekian market socialism. In the fourth and fifth section, I discuss the two main socialist planks of Burczak's institutional order – redistribution and worker cooperatives – from an economic point of view. There are two main conclusions. The first is that some forms of redistribution may aid the dissemination of local knowledge. The second conclusion is that prohibition of wage contracts is likely to lead to less economic knowledge being disseminated and some individual preferences not being provided for. The final section assesses the value of Burczak's contribution.
All assessments require normative criteria that are either explicit or implicit. The criterion of this paper is Hayekian: it uses pattern predictions of institutional performance defined as the systemic capacity to promote the growth of economic knowledge. Such knowledge growth arises from an entrepreneurial process involving profit-seeking or utility-seeking individuals, which results in a more complex economy over time. The underlying value judgment is that an increase in the set of production or consumption opportunities that is available to a randomly selected individual is a desirable consequence of any proposed institutional change.
The economics of both Hayek and Burczak does not rest on unrealistic assumptions of perfect information or knowledge; knowledge – like preferences – is both subjective and heterogeneous. The economic theory that undergirds this paper conforms to this Hayekian tradition, although it differs from Burczak (Reference Burczak2006) in three ways. First, entrepreneurs are uncertainty-bearing factor owners as well as residual claimants (Knight, Reference Knight1921; Foss et al. Reference Foss, Foss, Klein and Klein2007). Second, the subjectivity of expectations implies that capital markets do not have any intrinsic tendency toward equilibrium (Lachmann, Reference Lachmann1976). Third, non-parametric uncertainty increases with extensions of the time horizon (Keynes, [1937]Reference Keynes and Moggridge1973), although institutional stability makes market prices more accurate than random ‘noise’ (Koppl, Reference Koppl2002) for future-oriented action with short or intermediate time horizons.
2. Hayekian social theory and classical liberalism
Hayek (Reference Hayek1945) puts dispersed knowledge and widespread ignorance as the most important feature to consider in the choice of whether to use markets or governments. Knowledge is dispersed because each individual embodies unique local knowledge that reflects her cognition, social networks, and spatiotemporal location.
In an economy with indirect exchange, the process of parallel and sequential exchanges creates market prices. Such prices disseminate signals about perceived relative resource scarcities to other individuals and firms. Market prices thereby convey distilled information about perceptions of overall scarcity among a multitude of market participants.
Hayek (Reference Hayek1952) explains that the cognitive limitations of each individual make it impossible for any central planner to collect all the relevant economic data. This is due to the limits of individual information-processing to structures that are less complex than an individual human mind: ‘the capacity of any explaining agent must be limited to objects possessing a degree of complexity lower than its own’ (Hayek Reference Hayek1952: 185). It is therefore impossible for a small group of planners to know when resources should be reallocated to new production processes or new consumer goods or services, since that would imply that they have access to the preferences, ideas, skills, and whims of all potential entrepreneurs within their planning domain. They would also need to be able to know how all these new bits of individual knowledge will be received – and ultimately demanded – by the rest of the population.
One of the main features of the market order that explain its success at meeting the diverse objectives of millions of people is that it is structured yet pursues no overriding objective of its own. Hayek (Reference Hayek1960; 1979) therefore claims that the market is a spontaneous order: abstract procedural rules structure a discovery process that brings the local knowledge of order participants into greater mutual coherence over time. For markets, the feedback signal is the set of money prices, which distils and reflects the perceptions of all those who have an impact on demand and supply conditions, however small the individual impact.
While Hayek generalized his ideas about spontaneous orders to other fields such as the legal system, he treated the state as akin to an instrumental organization. But this is a mistake for democracies, since the character of the rules and feedback show that democracies are also spontaneous orders (diZerega, Reference diZerega1989). The rules include freedom of speech and periodic elections, and the order-specific feedback consists of vote tallies. While both markets and democracies constitute spontaneous orders, they exhibit systematic structural differences: democratic choices are more bundled, aggregated, and egalitarian than market choices (Andersson, Reference Andersson2008a).
The systemic economic justification for democratic over market priority-sorting is that it might improve upon situations where it is more difficult for some people than for others to disseminate their local knowledge through entrepreneurial action, since access to credit tends to depend on an individual's accumulated wealth. Unlike in markets, all included individuals are weighted equally in democratic decision-making, whether in democratic states or cooperative firms. This is the foundation of Burczak's (Reference Burczak2006) arguments for a decentralized version of market socialism in Socialism after Hayek.
3. The Burczakian challenge
Burczak has fully integrated the Hayekian critique of central planning into his proposal for what he believes to be a workable version of market socialism. Unlike the ‘market socialist’ proposals of an earlier era (e.g. Lange and Taylor, Reference Lange and Taylor1948), Burczakian market socialism involves real rather than simulated markets. Burczak (Reference Burczak2006) is therefore able to engage Austrians to an extent that is unusual for socialists (Horwitz, Reference Horwitz2007; Storr, Reference Storr2007).
Burczak's critique of classical liberalism focuses on the detrimental systemic effects of credit rationing. He criticizes the asset neutrality assumption of Israel Kirzner's (Reference Kirzner1973) theory of entrepreneurship, which Kirzner views as an extension of Hayekian insights into how market processes bring about a dissemination of knowledge:
According to Kirzner, in a market economy that places no statutory limits on the economic activities in which an individual may participate . . . every person has in principle the same opportunity of acting on an entrepreneurial insight as any other. Specifically, ownership of wealth provides no entrepreneurial advantage: a poor person who notices an opportunity for entrepreneurial gain is in principle no less able to seize this opportunity than is a wealthy person. Kirzner's conclusion reinforces Hayek's notion that a market economy improves the life chances of any person chosen at random. Kirzner reaches this conclusion because he believes that credit markets in a free economy do not systematically discriminate among types of borrowers. This belief has been called into question by credit rationing models demonstrating that asset-poor individuals who are not able to provide collateral to lenders will be unable to obtain credit, no matter the interest rate they pay. (Burczak, Reference Burczak2006: 67–68).
Burczak's critique of Kirzner's theory reflects Bowles and Gintis (Reference Bowles and Gintis1986): lenders have a rational fear of moral hazard and adverse selection in an environment with imperfect information about credit risks. Burczak's reliance on this model is however inconsistent with his own ‘postmodern’ theoretical foundations, since moral hazard and adverse selection arguments lose much of their force if separated from assumptions of narrow self-interest and rational expectations. But Burczak's conclusions hold even without these assumptions.
One arrives at the same conclusion by noting that the pursuit of profits is based on expected revenues and costs, which are unavoidably uncertain (Hodgson, Reference Hodgson1999). This in turn implies that evolutionary selection principles are imperfect. Moreover, they tend to be influenced by institutions such as norms and habits of interpretation. The consequence is that lenders may treat two equally loss-making firms differently: the goodwill of creditors does not only depend on the balance sheet, it must depend on their subjective expectations and may also reflect cultural prejudices that favor certain categories of borrowers. In many societies, it has been common among banks and other lenders to engage in systematic positive or negative discrimination of groups, often on the basis of factors – for example race or accent – that may be irrelevant to firm performance.
An individual's access to resources that she can transform into forward-looking entrepreneurial ventures reflects some combination of her savings, her access to loans, and her ability to persuade others to pool their resources with hers. What this implies is that poor people – whether in terms of wealth or entrepreneurially useful connections to others – have fewer entrepreneurial opportunities than the rich. It has the further systemic implication that many people with useful local knowledge cannot disseminate that knowledge because they do not have sufficient resources to influence market prices.Footnote 1
Burczak's critique of Kirzner's theory is suggestive of some of the deeper problems associated with Kirzner's view that entrepreneurs are alert discoverers of pre-existing price discrepancies, which allows him to separate the entrepreneurial from the capitalist function. This separation is only possible if we abstract from transaction costs, which reflect individuals' imperfect knowledge. Not even pure arbitrage is possible to profit from for an individual with neither tangible nor intangible resource ownership: an entrepreneur who notices a discrepancy in the price of an identical good in two locations (net of transport costs) may need to learn the transaction technology and institutions of the relevant markets. This means that a real-world entrepreneur requires human resources and not just costless entrepreneurial alertness. Kirzner skirts this problem by assuming ‘free entry’, which points to the excessive ‘thinness’ that Kirznerian theory shares with otherwise dissimilar models of perfect competition.
An additional problem is that the notion of ‘entrepreneurial discovery’ is unsuited to processes that involve an open-ended, uncertain future. Kirzner attempts to generalize his theory from arbitrage to speculation and innovation. The introduction of a time component complicates matters, however. O'Driscoll and Rizzo ([1985]Reference O'Driscoll and Rizzo1996) draw attention to the ‘Newtonian time’ of reversible mathematical models and the ‘real time’ of irreversible economic processes. In ‘real time’, knowledge must change (Lachmann, Reference Lachmann1986). Consumption causes individual consumers to learn new attributes of consumer goods, which may lead them to revise their preferences. Production experiences cause workers to learn or forget skills, which changes the availability of human resources. Sometimes they discover new ways of combining ideas, which has the potential of changing the available technology. It is thus misleading to claim that entrepreneurs discover future prices.
As a consequence, Kirzner's theory has two major flaws as regards its applicability to real-world conditions. The first is its assumption of asset neutrality, which Burczak discusses at length. This forms the basis for his proposal of lump-sum wealth redistribution. It is to this topic we turn next. The second flaw in Kirzner's theory is that it assumes that the future is out there somewhere, to be discovered by alert but passive entrepreneurs. But speculators and innovators have to deal with the structural uncertainty of the future, which implies that real-world entrepreneurs deal with this by making judgments and earning the profits or suffering the losses that correspond to the residual claims that are not accounted for as contractual compensations to factor owners. Burczak does not address this second flaw, which has implications for the second plank of his socialist proposal: the prohibition of wage labor and a resultant market of worker-owned cooperatives. We shall turn to the problems associated with wage labor prohibitions after discussing government-mandated redistribution.
4. Redistribution
The distribution of property rights has historical roots. All tangible resources – including capital and consumer goods – are ultimately derived from combinations of labor and land (Schumpeter, Reference Schumpeter1934). While labor sticks to people in a free-market economy, land in the form of natural resources does not attach in any inevitable way to people. Land ownership reflects a historical path-dependent process of acquisition through some mixture of homesteading, might-makes-right force, market exchange and government redistribution. In some societies, this has resulted in extremely skewed distributions of property rights over land.
While it is conceivable that a redistribution of land and accumulated capital goods could equalize the initial resource access of a population, it is inevitable that an entrepreneurial process that relies on profit-and-loss signals will generate new material inequalities over time. Andersson (Reference Andersson2008b: 77) proposes a two-fold pattern prediction regarding the knowledge-disseminating properties of markets.
On the one hand, one should expect the total amount of local knowledge that price signals disseminate to increase with decreasing differences in initial resource access among market participants, other things being equal. On the other hand, more local knowledge can be expected to be disseminated if all market participants receive undistorted profit-and-loss signals that result from decentralized and voluntary market exchanges. There is thus an unavoidable tension between the desirability of equal entrepreneurial opportunities and unequal entrepreneurial rewards, exacerbated by the absence of any self-evident distinction between starting point and market process.
Our unavoidable lack of detailed knowledge about the systemic effects of various redistributive policies implies that it is impossible to optimize the mixture of egalitarian redistribution and undistorted market processes so as to achieve the greatest aggregate dissemination of local economic knowledge. Burczak's (Reference Burczak2006: 133) endorsement of a specific redistributive Stakeholder Grant of $100,000 that all United States citizens receive on their eighteenth birthday is a rare lapse into the sort of constructivism that he is otherwise adept at avoiding.
Apart from its constructivism, there are two other reasons why Burczak's Stakeholder Grant is unlikely to offer much promise. First, democracies are associated with structural incentives that favor redistribution from large groups with small individual losses to small groups with large individual gains (Olson, Reference Olson1965). Democracies must therefore overcome the tendency to favor the interests of the well-organized over other groups. The second reason involves Virgil Storr's (Reference Storr2007: 314–15) questions: ‘How does the government in the stakeholder society know that the size of the transfer is large enough to turn citizens into stakeholders? What is the feedback mechanism at work here?’ Election results provide questionable feedback about the knowledge dissemination efficacy of state-organized redistribution.
The choice of the United States as a potential stakeholder society is also unfortunate because of the size of that jurisdiction. The size problem is associated with the ‘feedback mechanism’ of a higher-level spontaneous order of inter-jurisdictional competition. This feedback is more complex than profits (the market order) or vote tallies (a single democracy). To the extent that human and material resources are able to relocate, there will be an inter-jurisdictional spontaneous order with net flows of people and capital goods as the relevant feedback. But the feedback signal is not only aided by an absence of barriers to investment or migration. It is also aided by jurisdictional decentralization. High relocation costs enfeeble the feedback in large jurisdictions such as the United States, especially when involving the movement of people. On the other hand, decentralization makes the redistribution of mobile assets such as wages or profits more difficult. Therefore, small-area governments face greater incentives than large-area ones to adopt institutions that are attractive to factor owners (Jones, Reference Jones1981) as well as incentives to tax immobile rather than mobile resources (Foldvary, Reference Foldvary2002).
The problems associated with detailed policy proposals such as Burczak's stakeholder grant should not be construed as implying that the ‘Hayekian liberal with Burczakian glasses’ cannot suggest anything at all. First, the overall analysis suggests an important role for market prices and predictable property rights. It also suggests some rich-to-poor redistribution in situations with highly skewed distributions of wealth. Second, different forms of redistribution differ in the degree to which they dilute the knowledge-disseminating property of market prices.
A one-off redistribution of land, for example, does not affect such knowledge dissemination. Instead, it replaces one array of individual opportunity sets with a new one, which results in market prices and opportunity costs that are possibly very different, while preserving the knowledge content of the subsequent market process. Of course, the possibility of future redistribution of land may inhibit entrepreneurial ventures, especially if market participants expect such redistribution to be a possible but uncertain outcome of discretionary decision-making rather than subject to credible long-run rules that are not easily altered (cf. Koppl, Reference Koppl2002).
Knowledge losses are an inevitable consequence of redistribution if we were to assume a pre-determined future. But if we take structural uncertainty seriously, our interpretation of entrepreneurship directed toward the distant future must change. To paraphrase Keynes ([1937]Reference Keynes and Moggridge1973: 113), it would have been impossible in 1937 to know anything about the position of wealth owners in 1970.
If Keynes (ibid.) is right – and the dismal performance of long-term economic forecasts would seem to support his view of uncertainty – then the ability to speculate with a time horizon of 50 or 100 years does not disseminate superior knowledge about market conditions after the relevant time period has elapsed. Moreover, this would imply that the institution of freehold ownership of immovable property is not indispensible from a knowledge dissemination perspective. Certain redistributive policies may thus disperse entrepreneurial opportunities without diluting the knowledge dissemination properties of market prices. An example could be staggered 50-year or 100-year leaseholds where an equal share (1/50 or 1/100) of all lots expire and are redistributed as new tradable leaseholds each year.
But this would seem to be the only exception. All redistributions of current income flows and short-term capital gains are afflicted with adverse knowledge and incentive effects, although some such policies reduce the market dissemination of local knowledge more than others. A simple redistribution of income from high-income to low-income individuals is less subversive of knowledge dissemination than the transformation of income tax revenues into school vouchers, while vouchers are less subversive than a policy that allocates students to schools according to inflexible catchment areas. The more closely a government directs the allocation of resources, the less individual citizens will be capable of signaling their local knowledge through market exchanges.
A workable mix of laissez-faire market processes and redistribution that enhances entrepreneurial opportunities is impossible to pinpoint and should be expected to vary according to local conditions. The spatiotemporal specificity of institutional performance reflects a variety of factors such as land ownership structures, intellectual property right regimes, and the prevalence of both philanthropic giving and rent-seeking behavior. Policy-making is a trial-and-error process which benefits from experimentation and pluralism.
5. Worker-managed firms
Burczak's brand of socialism hinges on the Marxian notion of wage labor as wasteful and degrading exploitation. His explicit arguments in favor of prohibiting wage labor derive from David Ellerman's (Reference Ellerman1992) labor theory of property. That theory is a socialist natural rights theory, which like its libertarian counterparts (e.g. Nozick, Reference Nozick1974) implies the problematic requirement – in a world with more than one conception of natural rights – that one accept certain principles as self-evident. Burczak (Reference Burczak2006: 113) argues that ‘people should be held legally responsible for the results of their actions, [which] is readily accepted in the case of a crime, no matter what kind of contract the criminals have agreed on’. From a consequentialist perspective, this ignores the institutional specificity of what counts as a ‘crime’.
David Prychitko (Reference Prychitko1998) draws attention to another problem with Ellerman's theory if one accepts Austrian notions of entrepreneurial profit: if the worker is entitled to the full product of her labor, this should extend to the profits that arise because of her entrepreneurial actions. But if this is the case, the difference between market socialism and capitalism may become nominal rather than substantive, as long as we allow relational contracts between self-managed one-person firms that sell their services to the highest bidder.
There is however still a need to consider Burczak's other arguments, since it is clear that he intends market socialism to be construed as one that primarily consists of multi-person – rather than one-person – worker-managed firms. First, Burczak (Reference Burczak2006: 118) believes that an economy of labor-managed firms will not run afoul of any Hayekian knowledge problems. More importantly, he suggests that an economy without wage laborers will be less wasteful than a conventional capitalist economy:
Hayek's idea of the importance of tacit, local knowledge in the production process suggests . . . efficiency-promoting benefits of labor-appropriating firms. There is reason to think that the labor-appropriating firm will give more workers incentive to report their subjective perceptions of economic opportunity – such as more efficient technologies, since they share in the profits these technologies might allow. Insofar as capitalist firms often do not provide incentives to all employees to notice and report improvements in a firm's technology, the labor-appropriating firm may be more innovative than the capitalist firm. (Burczak, Reference Burczak2006: 119)
Burczak's ability to reach this sort of conclusion rests both on a misunderstanding of risk as it is presented in one of Kirzner's examples and on an implicit acceptance of Kirzner's disregard of the uncertainty-bearing role of entrepreneurs, which is quite different from problems associated with the asset neutrality assumption. Burczak illustrates his reasoning by using one of Kirzner's (Reference Kirzner1989) examples:
Kirzner seems to suggest that workers who do not employ their entrepreneurial facilities to direct a productive enterprise prefer to take fewer risks than those who do. He asks us to imagine two men, Jones and Smith, who each own no resources but who both believe that cab driving is a rewarding economic activity. Kirzner contrasts the case of Jones, who borrows money to rent a taxicab to become an independent cab driver, with the case of Smith, who rents his labor time to an owner of a fleet of taxicabs. Both the independent contractor Jones and the wage-laborer Smith act entrepreneurially when deciding to work in the taxi-driving industry. . . The only difference between Jones and Smith appears to be that [only] Jones is willing to take the risk of running his own firm. (Burczak, Reference Burczak2006: 71–2)
The reason that Jones and Smith are both ‘entrepreneurs’ in Kirzner's theory is that they have both presumably earned pure profits from the difference between the returns in the taxi industry and the returns in Jones's and Smith's second most remunerative known employment of their labor, respectively (i.e. their opportunity costs). Burczak draws the following conclusion:
There are two problems with Kirzner's analysis and conclusion. First, in this example, the amount of risk incurred by Smith and Jones is not very different, contrary to Kirzner's claim. Since Jones borrowed the money to finance the purchase of his cab, if the cab business is not profitable, all he runs the risk of losing is the labor time he devoted to the enterprise. The lending bank or capitalist bears all the risk if Jones does not generate enough revenue to pay back his loan. This is the same exact loss to which Smith is exposed. If the fleet owner Brown goes out of business and is unable to pay Smith his wage, Smith will have lost perhaps the same amount of labor time as Jones. However, if the cab business proves to be extremely successful, Jones will gain entrepreneurial profit, while Smith will recover no more than his contracted wage. What then, prohibits Smith from starting his own cab-driving business? For that matter, if Kirzner is right that factor owners are all making the same kind of entrepreneurial judgments, why would anyone ever choose to work for someone else if credit is easily accessible to all? (Burczak, Reference Burczak2006: 72)
But Kirzner's implication is correct in this instance: the choice between being an independent cab driver and an employee may reflect relative risk aversion as it is usually interpreted. For the sake of argument, let us assume that business failure is associated with a monetary return of $0. Let us further assume that the potential monthly profit of Jones is $1,000 while Smith's monthly wage is $100. If the expected monetary return, E(R), is p 1R 1 + p 2R 2, where p is probability and R is return, then it is possible that Jones and Smith both perceive their alternatives in the following way:
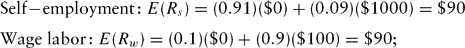
which would imply equal expected returns for a risk-neutral individual. Thus, if Smith decides to become a wage laborer rather than a self-employed cab driver (assuming that credit is readily available), it would imply that Smith ranks the ex ante utility associated with the wage labor alternative (Uw) as superior to the expected utility of being an independent cab driver (Us). In this case, the inequality Uw > Us implies that Smith is risk-averse, while Jones' self-employment choice implies risk-loving behavior. Although the assumption that Jones and Smith have an identical set of expectations is unrealistic, the example shows that it is possible and not at all unrealistic to choose wage labor over self-employment, even if credit were available on equal terms to all potential borrowers.
But risk is itself an unhelpful notion when dealing with entrepreneurial decisions. Following Knight (Reference Knight1921), the usual treatment of risk is as a known probability distribution associated with a set of unequally valued outcomes. This is not the situation that an entrepreneur faces, since she has to make her decision in the face of a structurally uncertain future, where the set of potential outcomes is open-ended. There is thus no way in which an entrepreneur can maximize her expected utility in a way that an outside observer such as an economist can analyze. It is thus possible for both Jones and Smith to be equally risk-averse, the difference being that Jones is convinced that he will succeed – which implies a high payoff with no ‘risk’ – whereas Smith is more pessimistic about his entrepreneurial fortunes.
Regardless of whether we think in terms of risk or uncertainty, it becomes clear that real losses would accompany the loss of the wage labor option, which implies an economy that is less responsive to the subjective preferences of individuals. What then would be the position of the individual worker in an economy with asset-owning entrepreneurs?
First, the individual worker, as the original owner of her own labor, decides whether to be self-employed or to be an employee under the direction of others. The original owner of individual labor – in the sense of being the one who has ultimate control over the variability in the value of her labor – is therefore always the worker, and she is therefore an entrepreneur when deciding how to deploy her own labor. When an employee decides to work as an employee for a fixed income, she delegates judgment to the firm's owners, just as owners delegate firm-specific judgment when they hire managers. The employee pays an implicit price for the contractually guaranteed compensation: the potential profits that arise from the marginal variability in output value that is due to her efforts. The economic function of the firm with fixed-income employees is to take on a temporary insurance function. An individual may decide to become an employee rather than a self-employed worker because of insufficient access to resources, but this is not the only possible reason. It could also be caused by uncertainty aversion (the fear of the unknown rather than a measurable risk) or a lack of confidence in her own entrepreneurial judgment.
The owners of a firm that employs wage labor will remain employers only if they expect their undiluted judgment about resource use to cause revenues in excess of their opportunity costs, which includes the cost of monitoring employees. If this were not so, they would prefer that the employees claim part of the variation (profits or losses) in the firm's capital value, transforming the workers into part-owners and part-entrepreneurs. A common example is a manager who is partly compensated through stock ownership, which tends to reduce the value of the fixed salary to take into account expected profits from capital gains and dividends. The original owners will resort to shared ownership with workers if they expect the benefits of the additional motivation among workers, the lower monitoring costs, and the greater influence of the workers' local knowledge to exceed the additional costs of persuading co-owners and negotiating joint entrepreneurial judgments.
Burczak's ‘labor-managed market’ is therefore less flexible than a market that permits both capitalist and cooperative firms. This will induce systemic knowledge losses if there is a positive correlation between entrepreneurial self-appraisement and entrepreneurial performance. A positive correlation does not mean that entrepreneurial employers are always right. Burczakian socialism would imply knowledge losses as long as the entrepreneurial judgments of self-selected entrepreneurs are only slightly better than the entrepreneurial judgments of self-selected employees. And even if entrepreneurial success is entirely random, enforced worker cooperatives would imply that some uncertainty-averse individuals would be worse off than with more flexible contracting. But both the division of knowledge and the institutional bounds of human ignorance make it likely that those who specialize in entrepreneurial profit-seeking tend to have better-than-average knowledge regarding the prospects of their self-selected industry. The future is uncertain, but not shapeless.
While the Hayekian liberal would be well advised to carefully consider Burczak's argument in favor of opportunity-enhancing redistributive policies, there is little in his proposed prohibition of wage labor that makes sense if one does not accept the evils of wage labor as self-evident. Worker cooperatives are not necessarily inferior to capitalist firms, but there is a trade-off that should be familiar to anyone who has ever chosen a less remunerative salaried position over the higher but more uncertain payoffs associated with entrepreneurial start-ups. Some people do choose the security of being a management professor over the possibly greater incomes of a freelance management consultant. More pointedly, some specialists work better when temporarily isolated from the ups and downs of market evaluations, while others thrive when relentlessly pursuing profits.
6. What can liberals learn from Burczak?
It is ironic that it takes a socialist coming from a Marxian tradition to appreciate how market processes promote the growth of knowledge. The step should be smaller for non-Marxists who justify policy interventions by referring to individual preferences rather than class interests. That many economists have still not learned the Hayekian lesson reflects the enduring influence of abstract economic models that assume away the dispersion of knowledge and the subjectivity of interpretation. Burczak's book provides the ideal antidote to the pretense of knowledge among those who favor supposedly welfare-promoting social engineering. Burczak's key insight is that markets are necessary even if the aim is the elimination of ‘capitalist exploitation’.
But there is also a lesson for Hayekian classical liberals: markets are not neutral devices that serve all interests equally. While markets are indispensable for the division of knowledge, they do not always generate rewards that reflect unbiased social benefits. Burczak's analysis of credit rationing provides classical liberals with an understanding that redistribution is not always akin to ‘leaking buckets’, even though many government programs may indeed amount to sector-specific central planning or redistribution from the masses to well-organized interest groups. Classical liberals would benefit from being as observant of market pathologies as they are of the democratic pathologies associated with rent-seeking and voter ignorance.
While Burczak provides a stimulating analysis that raises several interesting questions, there is no need for liberals to take on board Marxian notions that prohibit delegating responsibilities from workers to owner-entrepreneurs. Liberalism – especially in its Hayekian formulation – is rooted in individualism, subjectivism, and pluralism. This lies behind the appreciation of unplanned spontaneous orders. Liberals could do worse than heed diZerega's (Reference diZerega2008) advice: the open-minded development of Hayekian social theory. A future assessment of milestones in such development will surely include Socialism after Hayek as a seminal normative contribution.


