



1. Introduction
A correlated random walk (CRW) is a sequence of partial sums of random variables whose increments form a Markov chain. Thus, it is a natural generalization of the standard random walk. The CRW is also a special case of a Markov random walk (see, for example, [Reference Fuh4, Reference Grama, Lauvergnat and Page7]). As was noticed in [Reference Gut and Stadtmüller11], a symmetric CRW with increments
 $\{1,-1\}$
can also be viewed as a special case of an elephant random walk when the elephant only remembers the very last step. In this paper we investigate a one-dimensional CRW; a d-dimensional CRW is called a Gillis–Domb–Fisher correlated random walk [Reference Chen and Renshaw2, Reference Gillis6].
CRWs have numerous applications in statistical physics, finance, ecology, and other areas of research. Here are just a few examples. In [Reference Allaart1], a CRW is employed to maximize the expected return of a commodity seller. In [Reference Gardner, McClintock, Converse and Hostetter5], it is used to model short-term directional persistence in animal movements. Applications to quantum walks in connection with quantum computing are used as motivation in [Reference Konno13]. Our interest in random walks with delays (that is, with
 $\{1,0,-1\}$
increments) is prompted by applications to sequential detection in sensor networks with communication constraints [Reference Guerriero, Pozdnyakov, Glaz and Willett8]. In this work, we consider a scenario where a sensor takes a measurement and, due to battery limitations, proceeds as follows: if the measurement is too high, above a certain threshold, it sends a 1 to the fusion center; if it is too low, it sends a
 $-1$
. When the measurement is within an acceptable range, the sensor does nothing, which is interpreted as a passive response, or 0.
The gambler’s ruin problem for CRWs was first investigated in [Reference Mohan16] with the help of first-step analysis. The case of a two-state k-order Markov chain was studied in [Reference Mukherjea and Steele17] by the difference equations method. However, as they noted, handling a large number of difference equations is difficult even for small k. A numerical method (via n-step transition probabilities) for finding the ruin probabilities and the expected duration of the game is given by [Reference Lal and Bhat14]. The gambler’s ruin problem with delays for the independent increment case was solved in [Reference Gut10] with the help of martingales.
The paper proceeds as follows. In Section 2 we describe a game that is used as an illustration of a Markovian gambler’s ruin problem with delays. In Section 3 we derive closed-form expressions for both the ruin probabilities and the expected time until ruin for the correlated random walk with increments
 $\{1, -1\}$
. Section 4 includes closed-form expressions for the ruin probabilities and the expected time until ruin for symmetric CRWs with delays, and a martingale treatment of the general case. Section 5 provides a solution for the gambler’s ruin problem in the case of the two arbitrary pattern game. In the final section we briefly discuss some open questions.
2. A two-pattern problem
Let us introduce a simple game that naturally leads us to the gambler’s ruin problem for correlated random walks with delays. This game will be used to demonstrate the flexibility and limitations of our methodology. The complete solution to this gambler’s ruin problem will be provided in Section 5, along with a solution for the general case.
A casino flips a fair coin. A gambler gets $1 if they see HH (including overlapping occurrences, i.e. for HHH they will get $2). They lose a dollar if it is TH. Here are some facts that we know about this game:
-
• The expected number of occurrences of HH and TH in n trials is
 $(n-1)/4$
for both patterns.
-
• The expected waiting time until the first HH is 6.
-
• The expected waiting time until the first TH is 4.
-
• The expected waiting time until the first occurrence of either pattern is 3.
-
• The probability that HH will occur before TH is 0.25.

The first statement is a trivial fact that we can get by taking the expectation of a sum of appropriate indicators. The other statements are more interesting. There is a long list of articles on this topic, the occurrence of patterns. An approach based on generating functions can be found in [Reference Feller3]. In a private communication, Donald Knuth indicated to us that the key observation – that the expected waiting time until the first occurrence of a pattern depends on self-overlapping of the pattern with itself – was first made in [Reference Solov’ev18]. A combinatorial method was developed in [Reference Guibas and Odlyzko9]. More relevant to our approach is a nice martingale technique introduced in [Reference Li15].
Now, let us ask a different question. Let A, B be positive integers. What is the probability of getting to $A before reaching -$B? This is a variation of the famous gambler’s ruin problem for random walks to be found in classical texts such as [Reference Feller3]. However, here we have two important differences from the standard setup: the payments are not independent, and the payments take three values (1, 0, and
 $-1$
).
We must acknowledge that there is an element of luck in the sequence of payments in this particular game forming a Markov chain with three states
 $\{1,0,-1\}$
. Usually, this is not the case. We can easily verify that if we play the same game with HH and TT, the payments do not form a Markov chain. However, as we demonstrate later, finding the ruin probability for a game with two arbitrary patterns is closely related to the gambler’s ruin problem for the CRW.
3. Correlated random walk
Consider a two-state Markov chain
 $\{X_n\}_{n\geq 1}$
with state set
 $\{1, -1\}$
, transition matrix
 \begin{align*}\begin{pmatrix} p &\quad 1-p \\ 1-q &\quad q \\\end{pmatrix},\end{align*}
and initial distribution
 $(p_0, 1-p_0)$
, where
 $0<p,q<1$
and
 $0\leq p_0\leq 1$
. In what follows, we assume that the initial distribution is always a stationary one, i.e. in this case,
 $p_0=(1-q)/(2-p-q)$
. This assumption helps to eliminate the extra variable,
 $p_0$
, in our formulas. But all our derivations can be easily adjusted to an arbitrary initial distribution.
Let
 $S_n=X_1+\cdots +X_n$
,
 $n\geq 1$
, denote a correlated random walk, and let
 ${\mathcal{F}}_n=\sigma(X_1, \dots, X_n)$
be the
 $\sigma$
-field generated by
 $\{X_n\}_{n\geq 1}$
. For any integers
 $A,B>0$
, let us consider the stopping time (with respect to to the filtration
 $\{{\mathcal{F}}_n\}_{n\geq 1}$
),
 $\tau=\inf\{k\colon S_k=A \mbox{ or }S_k=-B\}$
. One important technical observation is that
 ${\mathbb{E}}(\tau)<\infty$
. This is a well-known fact, so we will skip the proof. Then the ruin probabilities are
 $\alpha={\mathbb{P}}(S_\tau=A)$
and
 $\beta={\mathbb{P}}(S_\tau=-B)$
.
When
 $p=1-q$
,
 $\{X_n\}_{n\geq 1}$
are independent and identically distributed (i.i.d.) random variables. The gambler’s ruin problem can be solved with the help of various techniques. The most popular ones are first-step analysis and the martingale approach. A review of both methods can be found in [Reference Steele19]. In particular, the following martingales are useful. For a symmetric random walk
 $\big(p=q=\frac12\big)$
, they are
 $S_n$
and
 $S_n^2-n$
. For asymmetric random walks, they are
 $(q/p)^{S_n}$
and
 $S_n-(p-q)n$
. Then, by a standard application of the optional stopping theorem (OST) we can show that, for example in the symmetric case,
 $\alpha=B/(A+B)$
and
 ${\mathbb{E}}(\tau)=AB$
.
The general Markovian case was first treated in [Reference Mohan16] with the help of first-step analysis. To the best of our knowledge, nobody has used a martingale approach to address the gambler’s ruin problem for correlated random walks. So, our first task is to re-derive the formulas from [Reference Mohan16] with the help of the OST. For that, we need to construct an additive martingale (similar to
 $S_n-(p-q)n$
in the i.i.d. case).
The starting point is a formula for the conditional expectation
 ${\mathbb{E}}(X_n\mid{\mathcal{F}}_{n-1})$
. Observe first that
 \begin{align*} {\mathbb{E}}(X_n\mid{\mathcal{F}}_{n-1}) & = {\mathbb{E}}(X_n\mid X_{n-1}=1)\mathbf{1}_{X_{n-1}=1} + {\mathbb{E}}(X_n\mid X_{n-1}=-1)\mathbf{1}_{X_{n-1}=-1} \\ & = [1\cdot p+(\!-1)\cdot(1-p)]\frac{X_{n-1}+1}{2} + [1\cdot (1-q)+(\!-1)\cdot q]\frac{1-X_{n-1}}{2} \\ & = (p+q-1)X_{n-1}+(p-q).\end{align*}
Next, if we define
 $Y_1=X_1$
and
 $Y_n=X_n-(p+q-1)X_{n-1}-(p-q)$
for
 $n\geq 2$
, then
 \begin{align} M_n = Y_1 + \cdots + Y_n & = (2-p-q)S_{n-1} + X_n - (p-q)(n-1) \nonumber \\ & = (2-p-q)S_{n} + (p+q-1)X_n - (p-q)(n-1) \end{align}
is a martingale with respect to the filtration
 $\{{\mathcal{F}}_n\}_{n\geq 1}$
as a sum of martingale differences.
3.1. Ruin probability for symmetric CRWs
If
 $p=q$
, then
 $M_n=(2-2p)S_n+(2p-1)X_n$
. The OST immediately gives us that
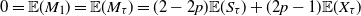 $0={\mathbb{E}}(M_1)={\mathbb{E}} (M_\tau)=(2-2p){\mathbb{E}}(S_\tau)+(2p-1){\mathbb{E}}(X_\tau)$
. Since
 $X_{\tau}=1$
on the set
 $\{S_{\tau}=A\}$
, and
 $X_{\tau}=-1$
on
 $\{S_{\tau}=-B\}$
, we have
 $0=(2-2p)(\alpha A-\beta B)+ (2p-1)(\alpha-\beta)$
. Since we also have
 $\alpha+\beta=1$
, we immediately get
 \begin{equation} \alpha=\frac{B-1+{1}/{(2-2p)}}{A+B-2+{1}/({1-p})}.\end{equation}
Note that we have intuitive answers for special cases:
-
• if
$A=B$
(symmetry), then
$\alpha=\frac12$
, -
• if
$p=1/2$
(i.i.d.), then
$\alpha=B/(A+B)$
, -
• if
$p\to 1$
, then
$\alpha\to 1/2$
(everything is decided by the first flip), -
• if
$B\to\infty$
, then
$\alpha\to 1$
.


As previously mentioned, adjusting to an arbitrary initial distribution
 $(\pi_1,1-\pi_1)$
is straightforward. The only change is the value of
 ${\mathbb{E}}(M_1)$
. In this case,
 ${\mathbb{E}}(M_1)=2\pi_1-1$
. Consequently, we have
 \begin{equation} \alpha=\frac{B-1+{\pi_1}/({1-p})}{A+B+({2p-1})/({1-p})}.\end{equation}
3.2. Expected waiting time until ruin for symmetric CRWs
The i.i.d. case tells us that we should try to find a quadratic martingale. This suggests the candidate
 $M_n=S_n^2+aS_nX_n-bn$
. If it is possible to find such values of a and b so
 $M_n$
forms a martingale, then the OST gives us
 \begin{align*}(1+a)-b={\mathbb{E}}(M_1)={\mathbb{E}}(M_\tau)=A^2\alpha+B^2\beta+a(A\alpha+B\beta)-b{\mathbb{E}}(\tau).\end{align*}
Since we already know
 $\alpha$
and
 $\beta$
, we have a formula for the expected waiting time:
 \begin{equation} {\mathbb{E}}(\tau)=\frac{1}{b}[b-(1+a)+A^2\alpha+B^2\beta+a(A\alpha+B\beta)].\end{equation}
Now, using
 ${\mathbb{E}}(X_n\mid{\mathcal{F}}_{n-1})=(2p-1)X_{n-1}$
and
 $X_n^2=1$
we get
 \begin{align*} {\mathbb{E}}(M_n\mid{\mathcal{F}}_{n-1}) & = {\mathbb{E}}(S_n^2+aS_nX_n-bn\mid{\mathcal{F}}_{n-1}) \\ & = {\mathbb{E}}((S_{n-1}+X_n)^2+a(S_{n-1}+X_n)X_n-bn\mid{\mathcal{F}}_{n-1}) \\ & = S_{n-1}^2 + [2(2p-1)+a(2p-1)]S_{n-1}X_{n-1} + [1+a-bn].\end{align*}
Therefore, to make it a martingale we need a and b to satisfy the following system of equations:
 \begin{align*}\left\{ \begin{array}{l} 2(2p-1) + a(2p-1) = a, \\ 1 + a - bn = -b(n-1). \end{array}\right.\end{align*}
This gives us
 $a=(2p-1)/(1-p)$
and
 $b=p/(1-p)$
. Plugging these values into (4), after some algebra we obtain
 \begin{equation} {\mathbb{E}}(\tau) = AB\frac{1-p}{p}+(A+B)\frac{2p-1}{2p}.\end{equation}
Here are some special cases:
-
• If
$p=\frac12$
(i.i.d.), then
${\mathbb{E}}(\tau)=AB$
. -
• If
$p=1$
, then
${\mathbb{E}}(\tau)=(A+B)/2$
(going straight to A or
$-B$
depending on the initial value
$X_1$
). -
• If
$A=B$
, then
${\mathbb{E}}(\tau)=A^2({1-p})/{p} + A({2p-1})/{p}$
.


3.3. Ruin probability for asymmetric CRWs
The i.i.d. case together with our first martingale construction suggests an exponential martingale
 $M_n=\lambda^{S_n+aX_n}$
, where
 $\lambda>0$
and
 $a\in \mathbb{R}$
. Again, let us assume first that we are successful in finding
 $\lambda>0$
and a that make
 $M_n$
a martingale. Then, in addition to
 $\alpha+\beta=1$
, the OST gives another linear equation:
 \begin{equation} {\mathbb{E}}(M_1)={\mathbb{E}}(M_\tau)=\lambda^{A+a}\alpha+\lambda^{-B-a}\beta.\end{equation}
So, let us figure out these
 $\lambda$
and a. First, we have
 \begin{align*} {\mathbb{E}}(M_n\mid{\mathcal{F}}_{n-1}) & = {\mathbb{E}}(\lambda^{S_{n-1}+(1+a)X_n+ aX_{n-1}-aX_{n-1}}\mid{\mathcal{F}}_{n-1}) \\ & = M_{n-1}{\mathbb{E}}(\lambda^{(1+a)X_n-aX_{n-1}}\mid{\mathcal{F}}_{n-1}).\end{align*}
Can we make the conditional expectation in the last expression equal to 1? Yes. As before,
 \begin{align*} {\mathbb{E}}(\lambda^{(1+a)X_n-aX_{n-1}}\mid{\mathcal{F}}_{n-1}) & = \big[p\lambda^{(1+a)-a}+(1-p)\lambda^{-(1+a)-a}\big]\frac{X_{n-1}+1}{2} \\ & \quad + \big[(1-q)\lambda^{(1+a)+a}+q\lambda^{-(1+a)+a}\big]\frac{1-X_{n-1}}{2} \\ & = \big[p\lambda +(1-p)\lambda^{-1-2a}-(1-q)\lambda^{1+2a}-q\lambda^{-1}\big]\frac{X_{n-1}}{2} \\ & \quad + \big[p\lambda +(1-p)\lambda^{-1-2a}+(1-q)\lambda^{1+2a}+q\lambda^{-1}\big]\frac{1}{2}.\end{align*}
Next, equating the first coefficient to 0 and the second one to 2, we get the following non-linear system of equations for
 $\lambda$
and a:
 \begin{align*}\left\{ \begin{array}{l} p\lambda+(1-p)\lambda^{-1-2a}=1, \\ (1-q)\lambda^{1+2a}+q\lambda^{-1}=1. \end{array}\right.\end{align*}
Because of the i.i.d. martingale
 $(q/p)^{S_n}$
, it is natural to try
 $\lambda=q/p$
. And it works:
 $\lambda=q/p$
and
 \begin{align*}a=\frac{1}{2}\bigg[\log_{q/p}\frac{1-p}{1-q}-1\bigg]\end{align*}
is a solution. Note that a itself is not really a part of (6), it enters as
 \begin{align*}\left(\frac{q}{p}\right)^a=\sqrt{\frac{(1-p)p}{(1-q)q}},\end{align*}
since our Markov chain starts from the stationary distribution
 \begin{align*}{\mathbb{E}}(M_1)=&\left(\frac{q}{p}\right)^{1+a}\frac{1-q}{2-p-q}+\left(\frac{q}{p}\right)^{-1-a}\frac{1-p}{2-p-q} =\frac{\sqrt{(1-q)(1-p)}}{2-p-q}\left[\sqrt{\frac{q}{p}}+\sqrt{\frac{p}{q}}\right].\end{align*}
Finally, plugging it into (6) and solving with respect to
 $\alpha$
gives
 \begin{equation*} \alpha = \left[\sqrt{\frac{q}{p}}+\sqrt{\frac{p}{q}}\right]\frac{({q}/{p})^{-B}\sqrt{({(1-q)q})/({(1-p)p})} - {\sqrt{(1-q)(1-p)}}/({2-p-q})} {({q}/{p})^{-B}\sqrt{({(1-q)q})/({(1-p)p})} - ({q}/{p})^{A}\sqrt{({(1-p)p})/({(1-q)q})}}.\end{equation*}
If
 $p=1-q$
,
 $p\neq \frac12$
, then this equation simplifies to a well-known expression for the asymmetric i.i.d. case (see, for example, [Reference Steele19]):
 \begin{align*}\alpha=\frac{({q}/{p})^{-B}-1}{({q}/{p})^{-B}-({q}/{p})^{A}}.\end{align*}
3.4. Expected waiting time until ruin for asymmetric CRWs
Everything is ready now. Applying the OST to the martingale (1), we have, for
 ${\mathbb{E}}(\tau)$
,
 \begin{align*}{\mathbb{E}}(M_1)={\mathbb{E}}(M_\tau)=(2-p-q)(A\alpha-B\beta)+(p+q-1)(\alpha-\beta)-(p-q)({\mathbb{E}}(\tau)-1).\end{align*}
Since we already know
 $\alpha$
(and
 $\beta=1-\alpha$
) and
 ${\mathbb{E}}(M_1)={\mathbb{E}}(X_1)=(p-q)/(2-p-q)$
, the formula for
 ${\mathbb{E}}(\tau)$
immediately follows:
 \begin{align*}{\mathbb{E}}(\tau)=\frac{2-p-q}{p-q}(A\alpha-B\beta)+\frac{p+q-1}{p-q}(\alpha-\beta)+\frac{1-p-q}{2-p-q}.\end{align*}
4. Correlated random walk with delays
As we mentioned in the introduction, accounting for the Markovian dependence is not enough to solve our two-pattern problem. The payments are quite often equal to 0. Random walks associated with such random variables are called random walks with delays. The gambler’s ruin problem with delays for the i.i.d. case can be solved using standard martingale techniques and the OST [Reference Gut10]. Here we extend these results to CRWs with delays. We start with a symmetric CRW, which can be viewed as a natural generalization of the i.i.d. symmetric random walk with delays.
4.1. Ruin probability for symmetric CRWs with delays
Consider a three-state Markov chain
 $\{X_n\}_{n\geq 1}$
with state set
 $\{1, 0, -1\}$
and transition matrix
 \begin{align*}\begin{pmatrix} p &\quad r &\quad 1-p-r \\ (1-q)/2 &\quad q &\quad (1-q)/2\\ 1-p-r &\quad r &\quad p \\\end{pmatrix},\end{align*}
where
 $0\leq p,q,r<1$
and
 $0\leq p+r\leq 1$
. We assume that the initial distribution is stationary, i.e. it is given by
 \begin{align*}\left(\frac{1-q}{2(1+r-q)},\frac{r}{(1+r-q)},\frac{1-q}{2(1+r-q)}\right).\end{align*}
We will keep the same notation for random walks, ruin probabilities, filtration, and stopping time. We call this random walk symmetric because states 1 and
 $-1$
enter into the picture in a symmetric way – they are interchangeable. More specifically, for states 1 and
 $-1$
, the probabilities of staying in the same state and the probabilities of switching to state 0 are the same. Additionally, the probabilities of switching from 0 to 1 and
 $-1$
are equal, too.
As before, the first step is to figure out the conditional expectation
 ${\mathbb{E}}(X_{n}\mid{\mathcal{F}}_{n-1})$
. We will use a technique similar to the one employed in the previous section. But note that in this case,
 $X_n^2$
is still a random variable, and the expressions for indicators of events
 $\{X_n=k\}$
,
 $k=1,0,-1$
, now depend on both
 $X_n$
and
 $X_n^2$
. More specifically,
 $\mathbf{1}_{X_n=1} =(X_n^2+X_n)/2$
,
 $\mathbf{1}_{X_n=0} =1-X_n^2$
, and
 $\mathbf{1}_{X_n=-1} =(X_n^2-X_n)/2$
. As a consequence, we get
 \begin{align*} {\mathbb{E}}(X_n\mid{\mathcal{F}}_{n-1}) & = {\mathbb{E}}(X_n\mid X_{n-1}=1)\mathbf{1}_{X_{n-1}=1} + {\mathbb{E}}(X_n\mid X_{n-1}=0)\mathbf{1}_{X_{n-1}=0} \\ & \quad + {\mathbb{E}}(X_n\mid X_{n-1}=-1)\mathbf{1}_{X_{n-1}=-1} \\ & = [p-(1-p-r)](X_{n-1}^2+X_{n-1})/2 + [(1-q)/2-(1-q)/2](1-X_{n-1}^2) \\ & \quad + [(1-p-r)-p](X_{n-1}^2-X_{n-1})/2 = (2p+r-1)X_{n-1}.\end{align*}
Note that because of the symmetry of the transition matrix,
 $X_{n-1}^2$
is not a part of the formula.
So, a natural candidate for another useful martingale is
 $M_n=S_n+aX_n=S_{n-1}+(a+1)X_n$
. Using the expression for the conditional expectation, we immediately get that
 $(a+1)(2p+r-1)=a$
, or
 \begin{align*}a=\frac{2p+r-1}{2-2p-r}.\end{align*}
Let us make two observations about the martingale. First, q is not a part of the formula, because in the symmetric case the delays do not affect the ruin probabilities. Second, note that because of
 $p+r\leq1$
and
 $r<1$
, we have
 $2-2p-r>0$
, so no division by zero. The rest is standard. The OST gives us
 \begin{align*}0={\mathbb{E}}(M_1)={\mathbb{E}}(M_\tau)= A\alpha-B\beta+\frac{2p+r-1}{2-2p-r}(\alpha-\beta).\end{align*}
Together with
 $\alpha+\beta=1$
, this leads us to
 \begin{equation*} \alpha=\frac{B-1+{1}/({2-2p-r})}{A+B-2+{2}/({2-2p-r})}.\end{equation*}
As a check, let us take a look at some special cases:
-
• If
$r=0$
(the state 0 is ignored), then we have (2). -
• If
$2p+r=1$
or
$p=1-p-r$
(almost the i.i.d. case because of an additional symmetry), then
$S_n$
itself a martingale, and
$\alpha=B/(A+B)$
. -
• If
$A=B$
(symmetry), then
$\alpha=\frac12$
.


In fact, because the delays do not really affect the ruin probabilities, the gambler’s ruin problem for a symmetric CRW with delays is equivalent to the gambler’s ruin problem for a two-state symmetric CRW with a probability of staying in a state of
 $p+r/2$
.
4.2. Expected waiting time until ruin for symmetric CRWs with delays
Finding
 ${\mathbb{E}}(\tau)$
is more challenging, because the delays play a significant role. At this point, we have some experience in building useful martingales, and this experience suggests the following candidate:
 $M_n=S_n^2+aS_nX_n+bX_n^2-cn$
. If we are successful in finding the right constants a, b, and c, the OST immediately gives us a formula for the expected waiting time until ruin:
 \begin{equation} {\mathbb{E}}(\tau)=\frac{1}{c}\big[A^2\alpha+B^2\beta+a(A\alpha+B\beta)+b-{\mathbb{E}}(M_1)\big].\end{equation}
So, the first step is to figure out the conditional expectation
 ${\mathbb{E}}(X_n^2\mid{\mathcal{F}}_n)$
. Using the expressions for indicators, we have
 \begin{align*} {\mathbb{E}}(X_n^2\mid{\mathcal{F}}_{n-1}) & = [1-r](X_{n-1}^2+X_{n-1})/2 + [1-q](1-X_{n-1}^2) + [1-r](X_{n-1}^2+X_{n-1})/2 \\ & = (1-q) + (q-r)X_{n-1}^2.\end{align*}
Next, we get that
 \begin{align*} {\mathbb{E}}(M_n\mid{\mathcal{F}}_{n-1}) & = {\mathbb{E}}((S_{n-1}+X_n)^2+a(S_{n-1}+X_n)X_n+bX_n^2-cn\mid{\mathcal{F}}_{n-1}) \\ & = {\mathbb{E}}(S_{n-1}^2+2S_{n-1}X_n+X_n^2 +aS_{n-1}X_n+aX_n^2+bX_n^2-cn\mid{\mathcal{F}}_{n-1}) \\ & = S_{n-1}^2+(2+a)(2p+r-1)S_{n-1}X_{n-1} +(1+a+b)(q-r)X_{n-1}^2 \\ & \quad +(1+a+b)(1-q)-cn.\end{align*}
To make it a martingale, a, b, and c have to satisfy the following linear system:
 \begin{align*}\left\{ \begin{array}{l} (2+a)(2p+r-1)=a, \\ (1+a+b)(q-r)=b, \\ (1+a+b)(1-q)=c. \end{array}\right.\end{align*}
That leads us to
 \begin{align*}a=\frac{2(2p+r-1)}{2-2p-r}, \quad\quad b=\frac{(q-r)(2p+r)}{(1+r-q)(2-2p-r)}, \quad\quad c=\frac{(1-q)(2p+r)}{(1+r-q)(2-2p-r)}.\end{align*}
Note that because of the restrictions on p, q, and r, there is no division by zero. The last step is to calculate
 ${\mathbb{E}}(M_1)$
. Since we start from the stationary distribution,
 ${\mathbb{E}}(X_1^2)=(1-q)/(1+r-q)$
, and, as a result, we get
 \begin{equation*} {\mathbb{E}}(M_1) ={\mathbb{E}}(S_{1}^2+aS_{1}X_1+bX_1^2-c) ={\mathbb{E}}(X_{1}^2+aX_{1}X_1+bX_1^2-c) =(1+a+b)\frac{1-q}{1+r-q}-c.\end{equation*}
Finally, (7) leads us to
 \begin{align*} {\mathbb{E}}(\tau)=AB\frac{(1+r-q)(2-2p-r)}{(1-q)(2p+r)} +(A+B)\frac{(2p+r-1)(1+r-q)}{(1-q)(2p+r)}+\frac{(q-r)r}{(1-q)(1+r-q)}.\end{align*}
As always, let us consider special cases:
-
• If
$r=0$
(the state 0 is ignored), then q will be canceled out and we get (5). -
• If
$2p+r=1$
or
$p=1-p-r$
(balanced switches between 1 and
$-1$
), then
\begin{align*}{\mathbb{E}}(\tau)=AB\frac{1+r-q}{1-q}+\frac{(q-r)r}{(1-q)(1+r-q)}.\end{align*}
-
• If
$2p+r=1$
and
$r=q$
(the i.i.d. symmetric random walk with delays), then
${\mathbb{E}}(\tau)=AB/(1-q)$
, a formula from [Reference Gut10].


4.3. Ruin probability for general CRWs with delays
Finding closed-form formulas in a general case might be a challenging task – the transition matrix has six free parameters. However, it is possible to develop a method that will work, at least numerically, for almost any Markov chain.
In this section
 $\{X_n\}_{n\geq 1}$
is a three-state Markov chain with state set
 $\{1, 0, -1\}$
and transition matrix
 \begin{align*}\begin{pmatrix} p &\quad p_0 &\quad 1-p-p_0 \\ r_1 &\quad r &\quad 1-r-r_1\\ 1-q-q_0 &\quad q_0 &\quad q \\\end{pmatrix},\end{align*}
where
 $0\leq p,p_0,q,q_0,r,r_1\leq 1$
and
 $0\leq p+p_0,r+r_1,q+q_0\leq 1$
. We will drop here the assumption that the initial distribution is stationary. The initial distribution is given by
 $(\pi_1,\pi_0,1-\pi_0-\pi_1)$
, where
 $0\leq\pi_1,\pi_0\leq 1$
and
 $0\leq \pi_1+\pi_0\leq 1$
. We will employ the same notation for random walks, ruin probabilities, filtration, and stopping time.
The candidate for a martingale in the general case, as before, takes an exponential form,
 $M_n=\lambda^{S_n+aX_n^2+bX_n}$
. If we can find
 $\lambda>0$
,
 $\lambda\neq 1$
, a, and b that make
 $M_n$
a martingale, then the OST gives us
 ${\mathbb{E}} (M_1)={\mathbb{E}} (M_\tau)=\lambda^{A+a+b}\alpha+\lambda^{-B+a-b}(1-\alpha)$
. Therefore, we have
 \begin{equation} \alpha=\frac{{\mathbb{E}}(M_1)-\lambda^{-B+a-b}}{\lambda^{A+a+b}-\lambda^{-B+a-b}}.\end{equation}
So, let us try to find such
 $\lambda$
, a, and b. First, note that
 \begin{align*} {\mathbb{E}}(M_n\mid{\mathcal{F}}_{n-1}) & = {\mathbb{E}}\big[\lambda^{S_{n-1}+aX_{n-1}^2+bX_{n-1}+a(X_n^2-X_{n-1}^2)+(b+1)X_n-bX_{n-1}}\mid{\mathcal{F}}_{n-1}\big] \\ & = M_{n-1}{\mathbb{E}}\big[\lambda^{a(X_n^2-X_{n-1}^2)+(b+1)X_n-bX_{n-1}}\mid{\mathcal{F}}_{n-1}\big].\end{align*}
Thus, we need
 $\lambda$
, a, and b that make the conditional expectation of
 $Y_n=\lambda^{a(X_n^2-X_{n-1}^2)+(b+1)X_n-bX_{n-1}}$
equal to 1. Now, our usual tricks lead us to
 \begin{align*} {\mathbb{E}}(Y_n\mid{\mathcal{F}}_{n-1}) & = {\mathbb{E}}(Y_n\mid X_{n-1}=1)\mathbf{1}_{X_{n-1}=1} + {\mathbb{E}}(Y_n\mid X_{n-1}=-1)\mathbf{1}_{X_{n-1}=-1} \\ & \quad + {\mathbb{E}}(Y_n\mid X_{n-1}=0)\mathbf{1}_{X_{n-1}=0} \\ & = {\mathbb{E}}(Y_n\mid X_{n-1}=1)\frac{X_{n-1}^2+X_{n-1}}{2} + {\mathbb{E}}(Y_n\mid X_{n-1}=-1)\frac{X_{n-1}^2-X_{n-1}}{2} \\ & \quad + {\mathbb{E}}(Y_n\mid X_{n-1}=0)(1-X_{n-1}^2) \\ & = \big[{\mathbb{E}}(Y_n\mid X_{n-1}=1) + {\mathbb{E}}(Y_n\mid X_{n-1}=-1) - 2{\mathbb{E}}(Y_n\mid X_{n-1}=0)\big]\frac{X_{n-1}^2}{2} \\ & \quad + \big[{\mathbb{E}}(Y_n\mid X_{n-1}=1) - {\mathbb{E}}(Y_n\mid X_{n-1}=-1)\big]\frac{X_{n-1}}{2} + [{\mathbb{E}}(Y_n\mid X_{n-1}=0)].\end{align*}
Taking into account that
 \begin{align*} {\mathbb{E}}(Y_n\mid X_{n-1}=1) & = p\lambda+p_0\lambda^{-a-b}+(1-p-p_0)\lambda^{-2b-1}, \\ {\mathbb{E}}(Y_n\mid X_{n-1}=0) & = r_1\lambda^{a+b+1}+r+(1-r-r_1)\lambda^{a-b-1}, \\ {\mathbb{E}}(Y_n\mid X_{n-1}=-1) & = (1-q-q_0)\lambda^{2b+1}+q_0\lambda^{-a+b}+q\lambda^{-1},\end{align*}
we finally get the following system of non-linear equations
 \begin{equation}\left\{ \begin{array}{l} p\lambda+p_0\lambda^{-a-b}+(1-p-p_0)\lambda^{-2b-1} = 1, \\[3pt] r_1\lambda^{a+b+1}+r+(1-r-r_1)\lambda^{a-b-1} = 1, \\ [3pt] (1-q-q_0)\lambda^{2b+1}+q_0\lambda^{-a+b}+q\lambda^{-1} = 1. \end{array}\right.\end{equation}
Example 1. Consider a three-state Markov chain with state set
 $\{1, 0, -1\}$
, transition matrix
 \begin{align*} \begin{pmatrix} 1/2 &\quad 1/4 &\quad 1/4 \\ 1/3 &\quad 1/3 &\quad 1/3\\ 1/8 &\quad 1/8 &\quad 3/4 \\ \end{pmatrix}, \end{align*}
and the initial distribution (0,1,0). Then we can show that
 $\lambda=13/10$
,
 $a=-\log_{13/10}\sqrt{81/65}$
, and
 $b=\log_{13/10}\sqrt{20/13}$
solve system (9). Also in this case
 ${\mathbb{E}} (M_1)=1$
. Plugging these values into (8), we get
 \begin{align*} \alpha=\frac{(18/13)(13/10)^B-1}{(20/13)(13/10)^{A+B}-1}. \end{align*}
As a simple check, set
 $A=B=1$
, then obviously
 $\alpha=0.5$
. The formula gives the same answer.
One practical recommendation is to do a re-parametrization, and use
 $x=\lambda$
,
 $y=\lambda^a$
, and
 $z=\lambda^b$
instead of the original
 $\lambda$
, a, and b. Then Mathematica easily finds solutions of the system.
This method might not work for some Markov chains, if their transition probability matrix exhibits a certain symmetry. Recall that in the i.i.d. case,
 $(q/p)^{S_n}$
is useless if
 $p=q$
. In fact, our two-pattern problem is a case of this nature.
4.4. Expected waiting time until ruin for general CRWs with delays
Using the same technique as before we can show that
 ${\mathbb{E}}(X_n\mid{\mathcal{F}}_{n-1})=l_2X_{n-1}^2+l_1X_{n-1}+1_0$
, where
 $l_2=p-q+(p_0-q_0)/2+1-r-2r_1$
,
 $l_1=p+q+(p_0+q_0)/2-1$
, and
 $l_0=2r_1+r-1$
, and that
 ${\mathbb{E}}(X_n^2\mid{\mathcal{F}}_{n-1})=k_2X_{n-1}^2+k_1X_{n-1}+k_0$
, where
 $k_2=r-(p_0+q_0)/2$
,
 $k_1=(q_0-p_0)/2$
, and
 $k_0=1-r$
. Remember that for the asymmetric i.i.d. case a simple martingale
 $S_n-cn$
works. Therefore, it makes sense to try a linear martingale
 $M_n=S_n+aX_n^2+bX_n-cn$
. Using our expressions for
 ${\mathbb{E}}(X_n\mid{\mathcal{F}}_{n-1})$
and
 ${\mathbb{E}}(X_n^2\mid{\mathcal{F}}_{n-1})$
we can show that if a, b, and c satisfy
 \begin{equation} \left\{ \begin{array}{l} ak_2 + (1+b)l_2 = a, \\ [3pt] ak_1 + (1+b)l_1 = b, \\[3pt] ak_0 + (1+b)l_0 = c, \\ \end{array} \right.\end{equation}
then
 $M_n$
is a martingale. Moreover, if
 $c\neq 0$
, then we get a formula for the expected time until ruin:
 \begin{align*}{\mathbb{E}}(\tau)=\frac{1}{c}\big[(A+a+b)\alpha+(\!-B+a-b)(1-\alpha)-{\mathbb{E}}(M_1)\big],\end{align*}
where
 ${\mathbb{E}}(M_1)=\pi_1(1+a+b)+(1-\pi_1-\pi_0)(\!-1+a-b)-c$
. If we consider the Markov chain in Example 1, then our method will lead to the martingale
 \begin{align*}M_n=S_n-\frac{2}{5}X_n^2+\frac{37}{45}X_n+\frac{4}{15}n.\end{align*}
5. Gambler’s ruin probability for the two-pattern game
In this section, we first provide a complete solution of the HH vs TH gambler’s ruin problem. Then, we describe a martingale method that can be used to find the ruin probabilities for an arbitrary two-pattern game. Finally, we will use the method to re-derive the ruin probability for the HH vs TH game.
5.1. HH vs TH gambler’s ruin problem
Let
 $\{\xi_n\}_{n\geq 1}$
be a sequence of independent Bernoulli random variables with a probability of success
 $\frac12$
. Then for
 $n\geq 2$
our payments are given by
 \begin{align*}X_n=\left\{\begin{array}{cl} 1&\,\, \mbox{ if } \xi_{n-1}=1, \xi_n=1, \\ 0&\,\, \mbox{ if } \xi_n=0, \\ -1&\,\, \mbox{ if } \xi_{n-1}=0, \xi_n=1. \end{array}\right.\end{align*}
In the general case of two patterns of length 2 (for instance, HH and TT), the associated sequence of payments typically does not form a Markov chain. But for HH and TH,
 $\{X_n\}_{n\geq 2}$
is a first-order Markov chain with the transition matrix
 \begin{align*}\begin{pmatrix} 1/2 &\quad 1/2 &\quad 0 \\ 0 &\quad 1/2 &\quad 1/2\\1/2 &\quad 1/2 &\quad 0 \\\end{pmatrix},\end{align*}
and the initial distribution
 $\big(\frac14, \frac12, \frac14\big)$
. This Markov chain is not symmetric in the sense of Section 4.1, but it does have a very special structure. As a result, we can easily verify that for this transition matrix there is no solution of system (9) such that
 $\lambda\neq 1$
.
However, we can construct a linear martingale. Note that here
 $S_n=X_2+\cdots+X_n$
. Since
 ${\mathbb{E}}(X_n\mid{\mathcal{F}}_{n-1})=X_{n-1}^2-\frac{1}{2}$
and
 ${\mathbb{E}}(X_n^2\mid{\mathcal{F}}_{n-1})=\frac{1}{2}$
, using our approach (or by solving the linear system (10)) we can verify that
 $M_n=S_n+X_n^2$
,
 $n\geq 2$
, is a martingale. Applying the OST to this martingale gives us
 \begin{align*}\alpha=\frac{B-1/2}{A+B}.\end{align*}
A simple check in this case is that when
 $A=B=1$
, the formula gives
 $\frac14$
. This makes sense, because the only way to get to 1 is to have HH right away.
Since the linear martingale does not contain an n term, it cannot be used to compute
 ${\mathbb{E}}(\tau)$
. But then we can try to find a quadratic martingale similar to the one used for the symmetric CRW with delays. Indeed, we can show that
 $M_n=S_n^2+2S_nX_n^2+2X_n^2-n/2$
is a martingale. Applying the OST to this martingale gives us
 ${\mathbb{E}}(\tau)=2AB+B-A+1$
.
5.2. Gambler’s ruin probability for an arbitrary two-pattern game
As previously mentioned, for an arbitrary two-pattern game the sequence of payments typically is not a Markov chain. For example, suppose that we play this game with HH and TT. As before, let
 $\{X_n\}_{n\geq 2}$
be the sequence of payments, where we get 1 for HH,
 $-1$
for TT, and 0 otherwise. Then, for any
 $n\geq 2$
, we have
 \begin{align*}{\mathbb{P}}(X_{2n+1}=1\mid X_{2n}=0,X_{2n-1}=0, \dots, X_3=0,X_2=1)=\frac{1}{2},\end{align*}
but
 ${\mathbb{P}}(X_{2n+1}=1\mid X_{2n}=0,X_{2n-1}=0, \dots, X_3=0,X_2=-1)=0$
.
However, we can still find the ruin probability using a CRW. For the rest of the section, let
 $\{\xi_n\}_{n\geq 1}$
be an i.i.d. sequence of letters from a finite alphabet. A sequence of letters is called a pattern. A pattern that has no letters is called a void pattern. Consider two patterns,
 $P=a_1a_2\dots a_k$
and
 $Q=b_1b_2\dots b_m$
, where
 $k,m\geq 1$
. Assume that P and Q are not connected subsequences of each other. Our game is the same as before: we get $1 for every (overlapping) occurrence of P and we lose a dollar if we see Q.
Let
 $\{X_n\}_{n\geq 1}$
be the sequence of only 1 or
 $-1$
payments (i.e. 0s are ignored). Then
 $\{X_n\}_{n\geq 1}$
is a two-state Markov chain whose initial distribution and transition probabilities can be computed with the help of the theory developed for the occurrence of patterns. More specifically, let
 \begin{equation*} P^*=\left\{ \begin{array}{ll} a_2\dots a_k, & k\geq 2, \\ \mbox{void pattern}, &\, k=1; \end{array} \right. \qquad Q^*=\left\{ \begin{array}{ll} b_2\dots b_m, & m\geq 2, \\ \mbox{void pattern}, &\, m=1. \end{array} \right.\end{equation*}
Then the initial probability is
 $\pi_1={\mathbb{P}}$
(pattern P will occur before Q in
 $\{\xi_n\}_{n\geq 1}$
). The transition probability of going from state 1 to state 1 is given by
 \begin{align*}p={\mathbb{P}}(\mbox{pattern ${P}$ will occur before ${Q}$ in $\{\xi_n\}_{n\geq 1}$ given that it starts from $P^*$}),\end{align*}
and the transition probability of going from state
 $-1$
to state
 $-1$
is given by
 \begin{align*}q={\mathbb{P}}(\mbox{pattern ${Q}$ will occur before ${P}$ in $\{\xi_n\}_{n\geq 1}$ given that it starts from $Q^*$}).\end{align*}
All three probabilities can be found using, for example, [Reference Li15, Theorem 3.1]. To find each probability, we need to solve a linear system with three equations. Then, we simply apply the appropriate formula from Section 3.
To close the loop, let us apply this method to the HH vs TH game. As we mentioned in Section 2, in this case
 $\pi_1=0.25$
. Additionally, here
 $P^*=Q^*=H$
, and
 $p=q=\frac12$
. This means that the non-zero payments in the HH vs TH game form a sequence of independent symmetric random variables, primarily because the coin is fair. Plugging these values into (3) leads us again to
 \begin{align*}\alpha=\frac{B-1/2}{A+B}.\end{align*}
6. Concluding remarks
The expected time until the gambler’s ruin in a game with two arbitrary patterns remains an open question. The method based on the occurrence of patterns ignores zero payments, making it unclear how it can be applied to this problem. Additionally, our technique relies on the fact that indicators of events like
 $X_n=1$
can be expressed in terms of
 $X_n$
. Consequently, it is likely unsuitable for Markov chains with more than three states. The distribution of the waiting time until ruin for CRWs with delays is an open question as well. Finally, the gambler’s ruin problem for elephant walks is also unresolved. A comprehensive review of the results on elephant random walks can be found in [Reference Gut and Stadtmüller12].
Acknowledgements
The author is grateful to the referees for their helpful comments.
Funding information
There are no funding bodies to thank relating to the creation of this article.
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


