

1 Introduction
At present, many defined benefit (DB) pension plans around the world are underfunded. The poor performance of global stock markets, aging populations, staggering economic growth, and low interest rate has all contributed to shortages in assets relative to liabilities. As a consequence, the question of who should absorb these shocks is once again at the forefront of the policy and academic debate. Risk solidarity is often understood to imply that the elderly are protected against a sudden loss of pension capital Teulings and de Vries, Reference Teulings and de Vries2006). The young, by contrast, are able to absorb more risk as they can adjust savings and labor supply decisions going forward (Bodie et al., Reference Bodie, Merton and Samuelson1992) and in return pay a lower average pension premium.Footnote 1
However, several pension plans are currently reducing (or plan to reduce) the level of pension benefits, suggesting that the elderly absorb part of the recent negative shocks after all. At the same time some other plans increase their premiums and leave the level of pension payments relatively unaffected. To illustrate this point, Figure 1 displays the current funding ratio alongside the planned reduction in pension benefits.Footnote 2 Despite the negative relationship between the funding ratio and the planned reduction, there is significant heterogeneity across pension plans. This suggests that there may be differences across pension funds in the ex ante amount of risk taking and the ex post amount of risk sharing that is applied.
(colour online) Funding ratios and planned reduction in pension benefits. Source: http://www.pensioenfederatie.nl/Document/Pers/Lijst%20Pensioenfederatie%2021-02-12.pdf.

In 2007, many pension plans were holding close to a 60–40 mix in stocks and bonds, leading to the underfunded status of many plans in 2012.Footnote 3 As retirees are generally advised to reduce their holdings in risky investments, these older plan participants may not have chosen such a risky portfolio themselves. The question is therefore why they should absorb (part of) the negative shocks, and perhaps more importantly, whether it was known ex ante that this was the risk sharing across generations that would be applied ex post.
This naturally puts pressure on collective pension plans as participants call for more freedom to choose the amount of risk they would like to take. In this paper, we explore the possibility of introducing individual portfolio choice within collective pension schemes. We first analyze the main advantages of collective pension schemes. We then ask the question how one can think of introducing choice elements while preserving the benefits of collective pension schemes. Our main argument throughout the paper is the need for increased transparency in the trading of risks and risk sharing between plan participants and pension plans.
In thinking about our proposal, we take the lessons from behavioral economics seriously. There is abundant evidence that households may not be sufficiently literate to take optimal savings (Beshears et al., Reference Beshears, Choi, Laibson, Madrian and Sakong2011), investment (Calvet et al., Reference Calvet, Campbell and Sodini2007), and insurance decisions (Koijen et al., Reference Koijen, Van Nieuwerburgh and Yogo2012) when given too much freedom to choose. Complexity and choice-overload might therefore render participants unable and perhaps even unwilling to actively choose. Therefore, we intend to introduce limited choice along the dimensions that we think are important. We will distinguish three types of decisions: the savings decision, the investment decision, and the risk-sharing decision.
First, we take mandatory participation in pension schemes as given, and therefore propose to limit the choices in the savings decision that household face. One could surely argue in favor of more flexible savings rates, within reasonable limits, or allow the pension contributions to adjust in response to temporary idiosyncratic shocks. Motivated by the permanent income hypothesis, most economists would argue in favor of such flexibility.
Second, we think it has advantages to allow households to have flexibility in their investment decision and particularly in the level of investment risk they would like to take. We do argue that this decision should only be introduced within reasonable bounds set by the regulator. We propose that households can choose from a set of diversified balanced index funds, with different weights in stocks and bonds.
Third, and related to the previous point, households should have some choices in their risk-sharing decision, that is, the amount of long-term guarantees they purchase. One of the main benefits of collective pension schemes is to offer intergenerational contracts (i.e., guarantees) that are currently not offered (or not offered at competitive prices) in financial markets. We provide examples of such (long-term) guarantees below. However, the flip-side of this argument is that other (younger) participants should be willing to write those guarantees. As a first step, we argue that it needs to be transparent what the guarantees are that each generation buys or sells to one another. Since the market for guarantees has to clear within the collective pension scheme, we can determine the price of the guarantees. We show in this paper that, in the current system, the price of guarantees is determined within each fund and therefore crucially depends on, for instance, the age composition of each fund. This means that by making it transparent what the guarantees are that are purchased and sold within different collective pension schemes, we will observe a wide variety of prices for the same contract. This will naturally lead to a debate about why different pension plans offer the same guarantee at different prices. The opaqueness of the current system masks those differences in prices. Since we need prices to allow households to decide how many guarantees they want, we need to resolve this issue.
Our suggestion is to clear the market for standardized guarantees across pension funds at a national exchange. This exchange achieves two things. First, there is a single price for the same guarantee across different pension plans. Second, as we show theoretically in this paper, such exchanges are welfare improving and hence provide the maximum benefit offered by collective pension schemes.
Once a national exchange is present, the next question that arises is why it is not possible to allow other investors to offer those guarantees to the older plan participants instead of young plan participants. For instance, other countries that age less rapidly or that want to obtain exposure to Dutch inflation for the purpose of diversification, may be able to offer the guarantees at even lower prices than offered by the young. This provides even cheaper guarantees for older households. We discuss the pros and cons of this new system and provide a model example to illustrate the welfare benefits the Pension Guarantee Exchanges (PGEs) can offer.
One important advantage worth highlighting is that the risk-sharing agreement we propose is between different, existing generations participating in the pension scheme. This differs from the current risk-sharing agreement in which the young plan participants provide guarantees to older participants in return for the (implicit) promise that these guarantees are offered to them as well by future generations. We argue that such an implicit agreement may be unattractive for several reasons. First, it is non-trivial to make the guarantees transparent and compute their fair value. In particular, the implicit guarantee with future generations is a challenge, as future generations do not participate in the negotiations. Our risk-sharing agreement between participating generations avoids this problem. Second, guarantees with future generations rely on (implicit) assumptions about population growth, industry dynamics, labor market conditions over planning periods as long as several decades. Our proposal avoids this uncertainty and only depends on the current distribution of young versus old generations.
In line with the literature on bounded rationality in terms of investment and savings decisions, the successful implementation of PGEs will require the education of pension plan participants on the need and value of providing the guarantees and a methodology is needed to help individuals assess their equity exposure when holding the PGE equity derivative. In addition, individual's ability to buy and sell guarantees should be bounded, so that irrationally excessive or low risk taking does not enter the market.
The paper proceeds as follows. In Section 2, we discuss the important tradeoffs between DB and defined contribution (DC) plans that have been discussed in the literature, and conclude that the main advantages of DB plans are: (1) low implementation costs and (2) intergenerational risk sharing. We argue that it is possible to introduce individual portfolio choice to participants by having them choose from a set of balanced index funds (i.e., more flexibility in their investment decision) together with a quantity of long-term guarantees (i.e., more flexibility in their risk-sharing decision. To achieve this flexibility, we propose a market for intergenerational risk sharing, which we discuss in Section 3. We provide a theoretical illustration of the upsides of PGEs in Section 5 and conclude in Section 4.
2 Collective pension agreements and individual choice
To assess the benefits of collective pension agreements, we start with an individual DC plan, in which every agent saves for his or her own retirement. We assess what advantages or disadvantages such a plan has relative to a collective DB pension plan.
Within a DC plan, the optimal savings and investment behavior of each agent is dependent on his age, income process, and risk preferences. By entering into a collective pension agreement, the flexibility to invest based on these individual parameters is lost. Furthermore, collective DB pension schemes can induce agency problems that naturally arise within large institutional investors and that may distort optimal diversification, see for instance Sharpe (Reference Sharpe1981), Binsbergen and Brandt (2007) and Binsbergen et al. (Reference Binsbergen, Brandt and Koijen2008) . Hence, a natural question to ask is why not moving to a DC system?
The biggest downside of DC plans is that agents may save too little, withdraw too much from their savings account too early, and make portfolio choices that are undiversified. We argue that these are serious concerns. However, even with a DC scheme, we can impose a minimal savings rate, a maximum withdrawal rate, and a restricted set of investment options that only includes globally diversified portfolios. Hence, a ‘constrained DC’ can address all of the main concerns that are often brought up in this discussion. Such a constrained DC can easily allow for age and income differentiation and, to a certain degree, differentiation by risk aversion.
Another often-heard argument against introducing choice in term of risk taking (and DC plans), is that households are not holding stocks, despite their high average returns.Footnote 4 We argue that pension plans can confront households with a trade-off between expected benefits and the riskiness of the investment portfolios. After all, the main reason why collective pension schemes take large positions in equities is to increase the average return, which in turn lowers the expected pension premium or increases the expected pension benefit. Hence, we think that households can be given a restricted choice set of risk taking alongside the implications for pension benefits and premiums that may depend on age. As mentioned before, alongside each of these investment choices, the pension fund indicates the premium and expected pension benefits to ensure that the household realizes that a reduction in investment risk comes with an increase in the expected pension premium or a reduction in expected pension benefits.
Another concern with respect to individual risk choice (and DC) is that households start timing the market in ways that may not be optimal. For instance, in response to the stock market decline in 2008, households may have a tendency to shift to the safest option offered to them. This may be sub-optimal given the recent insights of the empirical asset pricing literature that shows that risk premia vary over time (Campbell and Shiller, Reference Campbell and Shiller1988; Cochrane, Reference Cochrane1991; Binsbergen and Koijen, Reference Binsbergen and Koijen2010). During bad economic times, expected returns tend to rise and the investment opportunities for long-horizon investors may in fact improve (Campbell and Viceira, Reference Campbell and Viceira1999). If households move out of risky investments in those episodes, then this ‘wrong’ timing behavior may have a negative impact on their long-term performance and may in extreme cases even contribute to the volatility of asset markets. For instance, following the stock market decline in 2008, households would have lost out on the recovery in global asset markets in 2009. To mitigate the impact of such unwanted timing behavior, we suggest that the way households can move their money only once a year and by limited amounts.Footnote 5
Arguably the most important upside of a collective DB pension fund is that it can enhance risk sharing in incomplete markets.Footnote 6 The four important risk categories that participants face are inflation risk, income risk, asset market risk, and longevity risk. Within pension funds, these risks are traded between generations. In this paper, we argue that the way risks are currently traded within pension plans is not always transparent. Also, it is not obvious why it would be optimal to share these risks only with the participants within a single pension fund, as opposed to the participants from other funds. If two pension funds have a drastically different age distribution, then the amount and price of the guarantees that are exchanged between generations is likely to be very different. Setting up a market that trades guarantees makes this explicit. We call this a PGE and allow pension funds to share these risks with each other.
3 Advantages of PGEs
An individual DC system allows for high individual flexibility, but does not offer intergenerational guarantees. Currently, collective DB systems offer guarantees but in a rather in transparent fashion. Introducing a market for guarantees overcomes these issues and has the following advantages.
1. PGEs allow participants to share risk not just with the participants in their own plan, but also with participants of other plans. This enhanced risk sharing across all pension plans (and potentially even with other (international) parties) is welfare improving as it offers more instruments to accomplish consumption smoothing over the life cycle.
2. PGEs enhance the transparency of the pension system because it reveals the market price of intergenerational risk sharing. Opaque systems with frequent policy changes introduce regulatory uncertainty. This induces uncertainty averse agents to want to exit the pension system.
3. PGEs can help accommodate different risk sharing preferences of individual plan participants. Several important long-term risks for retirees are not easily traded on financial markets. Participants can currently only share these risks through their pension plans. However, because pension plans make choices for the average participant, the amount of risk sharing the plan implements may not be optimal for individual participants.
4 Other considerations regarding PGEs
In the previous section, we mentioned several advantages of PGEs. In this section, we present some additional considerations regarding PGEs. We discuss successively positive externalities of PGEs, the institutional aspects of organizing a PGE publicly or privately and the consequences of a lack in supply or demand for guarantees.
4.1 Positive externalities of PGEs
A potentially less obvious, but important additional advantage of PGEs is that the widely recognized benefits of collective pension schemes can be easily extended to self-employed households. Such positive externalities are not offered by collective pension schemes, which a consequence discourages people to become self-employed. Along the same lines, we can allow self-employed households to allocate capital to the global index fund, thereby offering the benefits of diversification to a larger group of households. Leveling the pension playing field encourages entrepreneurship and may therefore spur growth and innovation in the Netherlands.
4.2 Public or private PGEs
Introducing a market for PGEs may be controversial to some. After the financial crisis, there may be concerns about the functioning of a potentially illiquid financial market. There may also be serious political economy problems when, e.g., legislators or lobbying organizations would try to influence pricing on these markets. That said, a key observation to make in this context is that these markets (with all their political problems) already exist and that it happens to be the case that they are segmented and opaque across pension funds.
One important concern is the way prices at PGEs are determined and whether to allow other parties, such as insurance companies, hedge funds, and foreign pension funds, to participate on PGEs. Let us first spell out the main objectives. First, the prices on PGEs should reflect the current or recent demand and supply curves of participants. Second, as it is too complicated to ask for full demand and supply schedules, the mechanism needs to be simple and transparent. Third, we believe that the market should be well-regulated to prevent price manipulation. The government can only regulate the rules of the game, but should not take positions in this market itself. This is to prevent prices from being distorted by politically motivated interventions.
Moreover, the regulation may mandate an independent review, perhaps annually, by a team of professionals, including economists, actuaries, and investment professionals among others of the price mechanism to assure that it is operating in a just, fair, equitable, rational, and transparent manner. This group can also be involved in setting the boundaries for the amount of guarantees the young need to provide to the older generations.
A final concern with bringing in other market participants is that they may default on the guarantees they offer. There are various ways to mitigate such concerns. First, as with many financial contracts, one can require that the guarantor posts margins on a frequent basis so that the losses are minimized.Footnote 7 The regulator can impose restrictions on the types of institutions that can offer guarantees or the fraction of guarantees that have to be cleared internally versus the fraction that can be sold to parties outside of the Dutch pension schemes.
4.3 Lack of demand or supply
What if there is no demand or no supply of guarantees at what is believed to be a ‘reasonable’ price. For example, what if the young also want to buy guarantees and are unwilling to sell them. Could this lead to unreasonable prices? In many ways, posing this question reveals the main motivation for this paper. If young people are unwilling to offer guarantees, then why are pension funds offering these guarantees for them to old people at an unknown price, in an unknown quantity? Similarly, old people currently believe they own guarantees (hence the term ‘defined’ benefits), but how hard these guarantees are in terms of their price and quantity is unknown.
One potential mechanism is the following. We randomly divide the population in 52 groups (corresponding to 52 trading weeks), which can be done on birth days (scaled for seasonal effects). Each household trades once a year, and depending on age, has a default supply or demand for guarantees. This is similar for the minimum pension contribution or the maximum level of investment risk a household can take. At a higher (lower) price, the household can buy (supply) additional guarantees. Households then decide how much additional guarantees to buy or supply. We clear the market as so far as possible. Any mismatch in demand and supply is offered to third parties, such as insurance companies. If they want to hold the excess demand or supply of guarantees, the market clears. If not, the excess demand or supply is canceled and all positions of households that asked (or offered) the additional guarantees are canceled. As we observed the demand and supply at the different prices, we can update our best estimate of the demand and supply curves, which form the input for the trade the next week (recall that there are 52 groups). In this way, prices always reflect the recent demand curves and third parties are only allowed to absorb excess demand or supply, which prevents them from squeezing the market.
Alternatively, we can impose the same level of paternalism as is currently in place; the young may well be forced to offer guarantees to the old participants. The main motivation for such a policy may be that households are unable to take such complicated decisions themselves, implying that the design of defaults is important. However, it is optimal from a welfare perspective to offer such guarantees all at the same price across funds to optimally share the risk across participants. Ultimately, these decisions are left to society and depend on the preferences of the government designing the system.
5 The welfare gains of PGEs: an illustration
In this section, we provide a simple of examples to illustrate the potential benefits of PGEs. In the Appendix, we develop a formal model, but we describe the main economic insights here with a series of graphs.
Collective pension schemes offer a variety of guarantees associated with asset market risk, inflation risk, and longevity risk. For instance, in collective DB plans, the pension plan implicitly offers long-term put options such that in case of market downturns, the retirement benefit is not as much affected. Another guarantee is that pension benefits may be indexed with inflation, thereby offering a valuable long-term risk-free asset that is otherwise not available to households (Campbell and Viceira, Reference Campbell and Viceira2001).
In our example, we focus on the benefit of introducing a risk-free asset.Footnote 8 Old households have a demand for risk-free assets to finance their consumption during retirement. Young households, by contrast, receive labor income that allows them to finance consumption. As such, they can adjust their consumption-savings behavior in the future more easily and they can even adjust their labor supply decision if necessary. This naturally generates a market for risk-free assets within collective pension schemes; young participants write guarantees to old households.
In our model, we first determine the demand and supply of risk-free assets given a certain price. We then clear the market within a pension fund to arrive at the equilibrium price of risk-free assets within each pension fund. This is the most favorable interpretation of a collective pension fund: The risk sharing within the pension fund is optimal prior to the introductions of PGEs.
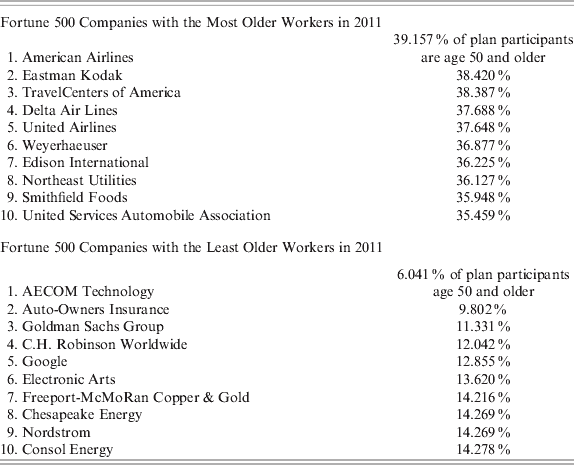
We consider two pension funds. The pension funds may differ in the age distribution of their participants. The age distribution across industries and firms may differ widely, as illustrated for instance in Table 1. The table presents the fraction of participants older than 50 for Fortune 500 companies, implying that they are all large corporations in the USA. The heterogeneity in terms of the age distribution is quite remarkable. The companies with oldest labor force have about 35–40% of their participants that are older than 50. For the companies with the youngest labor force, this is only 6–14%.
Fraction of plan participants older than 50 for Fortune 500 companies
Our main point is that if we share risk within the pension funds of these companies, or across industries in the Netherlands, the risk sharing may be sub-optimal. For instance, in case of Google, with only 12.9% of workers older than age 50, a large group of young people can offer the guarantees and the price will be low as a result. As the interest rate is the inverse of the price of a risk-free asset, the interest rate that the old people earn on their guarantees is high. By contrast, American Airlines, for which 39.2% of their participants are older than 50, fewer young people offer the same guarantees. The price they will ask in equilibrium is higher, and hence the interest the old plan participants of American Airlines earn is lower. Such differences in prices across funds driven by heterogeneity in the age distribution are sub-optimal.
This effect is illustrated in Figure 2. The solid line illustrates the equilibrium interest rate in the isolated pension fund if we vary the fraction of young employees between 10 and 90%. We also consider the combined pension fund. In case of the combined pension fund, we introduce the PGE that sets a single price for the guarantees. The second pension fund with which the first pension fund can share risk has a 50–50% distribution of young and old workers. We assume that both pension funds have the same funding positions to highlight the main economic forces at work. As risk sharing is more optimal in this case, the slope of the interest rate curve is flatter.
(colour online) The interest on guarantees for a fund in isolation and in the presence of a PGE.
In Figure 3, we illustrate the value, as measured by the certainty equivalent, of the first pension fund in isolation as we vary the age distribution of the pension fund. The certainty equivalent of the old is increasing in the fraction of young plan participants and vice versa for the certainty equivalent of the old plan participants. The intuition is that the old plan participants can trade with many young plan participants if the share of young plan participants is high. As a result, the price of guarantees is lower and the rate of return of the old is higher. The opposite is true for the young plan participants. For that reason, the benefits of varying the age distribution move in opposite directions for young and old plan participants. Furthermore, unless the age distribution of the first pension fund is 50–50% as well, the prices of the very same guarantee differ across funds. Such differences are obviously hard to explain to plan participants and in fact result in welfare losses as well, as we show below.
(colour online) The certainty equivalents of a fund in isolation.
We now introduce the PGE allows for risk sharing across pension funds. The certainty equivalents are compared in Figure 4. If the fraction of young plan participants is low in the first pension fund, it is better for the old plan participants to merge with the second pension fund and for the young to stay in isolation. The intuition is the same as before.
(colour online) The certainty equivalents of a fund in isolation and in the presence of a PGE.
This result begs the question whether PGEs are in fact welfare improving. We show that they are. The welfare gains are presented in Figure 5 from merging both pension funds. Only if the first fund also has a 50–50% distribution, there are no gains from PGEs. This is obvious as the prices in both funds for the same guarantee are identical. However, imagine again that the fraction of young plan participants is low in the first fund. We show in Figure 4 that the young would prefer to stay in isolation, whereas the old benefit from PGEs. As the fraction of young plan participants is low, it is welfare enhancing to share risk across both pension funds. The welfare gains are larger the more heterogeneity there is in terms of the age distributions, for instance, if the plan participants of Google in our earlier example were to share risk with the plan participants of American Airlines.
(colour online) Welfare benefits of a PGE.
6 Conclusion
In this proposal, we discuss how to introduce individual risk choices in collective pension schemes. The main benefits we identify of collective pension schemes, which has been argued in earlier work as well, are that collective plans have scale advantages to diversify investments and that collective plans can create markets that are otherwise non-existent. To facilitate individual choice, we argue in favor of PGE, where intergenerational guarantees are traded.
PGEs improve risk-sharing across pension funds, offer transparent pricing of guarantees, and thereby make it possible to introduce the freedom to individually choose the level of guarantees depending on age, income, and risk preferences. The welfare-enhancing characteristics of PGEs are typically present as the age compensation of pension funds is diverse. The welfare gains are larger the more heterogeneity there is in terms of the age distributions.
Appendix Motivating theory
We consider a simple model where there are two groups of agents per pension fund. The first group, ‘young agents,’ has preferences of the form:
 $$E\left[ {{{\lpar C_{Y} \plus Y\rpar ^{\setnum{1} \minus {\rm \gamma }} } \over {1 \minus {\rm \gamma }}}} \right].$$
Young agents receive labor income Y. The second group, ‘old agents,’ has preferences of the form:
 $$E\left[ {{{C_{O}^{\setnum{1} \minus {\rm \gamma }} } \over {1 \minus {\rm \gamma }}}} \right].$$
Young agents own WY and old agents WO. There is a single risky asset with a return R∊RL,RH, where P(R=RL)=π.Footnote 9 Initially, this return is given exogenously. Without further contracts, the market is incomplete, as there are two states of the world and only one asset.
Without pension plans, there is no risk free asset that would facilitate a guaranteed fixed pension. The role of pension plans is to complete this market. The payoff of the contract equals 1. The price of the contract is determined in equilibrium and equals B.
There are two pension funds, indexed by j=1, 2. Funds differ by the age distribution of their workers. The fraction of young workers equals λj. The main role of the pension fund is to facilitate binding risk-sharing agreements across generations.
We introduce a stochastic discount factor of the form:
 $$\left[ {\matrix{ 1 \cr B \cr} } \right] \equals \left[ {\matrix{ {\pi R_{L} } \tab {\lpar 1 \minus \pi \rpar R_{H} } \cr \pi \tab {1 \minus \pi } \cr} } \right]\left[ {\matrix{ {M_{L} } \cr {M_{H} } \cr} } \right].$$
The Lagrangian of the young agents is given by:
 $${{\lpar C_{Y} \plus Y\rpar ^{\setnum{1} \minus {\rm \gamma }} } \over {1 \minus {\rm \gamma }}} \minus {\rm \rmLambda }_{Y} \lpar MC_{Y} \minus W_{Y} \rpar \comma $$
which we optimize over CY. This leads to the FOC:
 $$C_{Y} \equals \lpar {\rm \rmLambda }_{Y} M\rpar ^{ \minus {\textstyle{\setnum{1} \over {\rm \gamma }}}} \minus Y.$$
For the old, we have:
 $$C_{O} \equals \lpar {\rm \rmLambda }_{O} M\rpar ^{ \minus {\textstyle{\setnum{1} \over {\rm \gamma }}}} .$$
The LMPs satisfy:
 $$\eqalign{ \tab {\rm \rmLambda }_{Y} \equals \left[ {{{W_{Y} \plus BY} \over {\pi M_{L}^{\setnum{1} \minus {\setnum{1} \over {\rm \gamma }}} \plus \lpar 1 \minus \pi \rpar M_{H}^{\setnum{1} \minus {\setnum{1} \over {\rm \gamma }}} }}} \right]^{ \minus {\rm \gamma }} \comma \cr \tab {\rm \rmLambda }_{O} \equals \left[ {{{W_{O} } \over {\pi M_{L}^{\setnum{1} \minus {\setnum{1} \over {\rm \gamma }}} \plus \lpar 1 \minus \pi \rpar M_{H}^{\setnum{1} \minus {\setnum{1} \over {\rm \gamma }}} }}} \right]^{ \minus {\rm \gamma }} . \cr} $$
This implies:
 $${\rm \rmLambda }_{O} \equals {{W_{O}^{\rm \gamma } } \over {\lpar W_{Y} \plus BY\rpar ^{\rm \gamma } }}{\rm \rmLambda }_{Y} .$$
The demand for bonds follows from:
 $$\eqalign{ \tab \lpar W_{Y} \minus N_{Y} B\rpar R \plus N_{Y} \equals W_{Y} R \plus \lpar 1 \minus BR\rpar N_{Y} \equals C_{Y} \comma \cr \tab \lpar W_{O} \minus N_{O} B\rpar R \plus N_{O} \equals W_{O} R \plus \lpar 1 \minus BR\rpar N_{O} \equals C_{O} . \cr} $$
The equilibrium condition for bonds is:
 $$\lambda _{j} N_{Y} \plus \lpar 1 \minus \lambda _{j} \rpar N_{O} \equals 0.$$
Using the budget constraints, we can write this as:
 $$\lambda _{j} {{C_{Y} \minus W_{Y} R} \over {1 \minus BR}} \plus \lpar 1 \minus \lambda _{j} \rpar {{C_{O} \minus W_{O} R} \over {1 \minus BR}} \equals 0\comma $$
that is,
 $$\lambda _{j} \left( \lpar {\rm \rmLambda }_{Y} M\rpar ^{ \minus {\textstyle{\setnum{1} \over {\rm \gamma }}}} \minus Y \minus W_{Y} R \right) \plus \lpar 1 \minus \lambda _{j} \rpar \left( \lpar {\rm \rmLambda }_{O} M\rpar ^{ \minus {\textstyle{\setnum{1} \over {\rm \gamma }}}} \minus W_{O} R\right) \equals 0\comma $$
which we solve for B. In case of two pension funds, we have
 $$\lambda _{\setnum{1}} N_{Y} \plus \lpar 1 \minus \lambda _{\setnum{1}} \rpar N_{O} \plus \lambda _{\setnum{2}} N_{Y} \plus \lpar 1 \minus \lambda _{\setnum{2}} \rpar N_{O} \equals 0\comma $$
where we assume that the wealth of the young and the old are identical across both funds. This condition simplifies to
 $$\lpar \lambda _{\setnum{1}} \plus \lambda _{\setnum{2}} \rpar \left( \lpar {\rm \rmLambda }_{Y} M\rpar ^{ \minus {\textstyle{\setnum{1} \over {\rm \gamma }}}} \minus Y \minus W_{Y} R\right ) \plus \lpar 2 \minus \lambda _{\setnum{1}} \minus \lambda _{\setnum{2}} \rpar \left( \lpar {\rm \rmLambda }_{O} M\rpar ^{ \minus {\textstyle{\setnum{1} \over {\rm \gamma }}}} \minus W_{O} R\right ) \equals 0.$$
With equilibrium bond price in hand, we can compute the certainty equivalents:
 $$\eqalign{ \tab W_{Y\comma j}^{CE} \equals E\left[ \lpar C_{Y\comma j} \plus Y\rpar ^{\setnum{1} \minus {\rm \gamma }} \right] ^{{\textstyle{\setnum{1} \over {\setnum{1} \minus {\rm \gamma }}}}} \comma \cr \tab W_{O\comma j}^{CE} \equals E\left[ \lpar C_{O\comma j} \rpar ^{\setnum{1} \minus {\rm \gamma }} \right] ^{{\textstyle{\setnum{1} \over {\setnum{1} \minus {\rm \gamma }}}}} \comma \cr} $$
which we can aggregate:
 $$CE^{Total} \equals \lambda _{\setnum{1}} W_{Y\comma \setnum{1}}^{CE} \plus \lambda _{\setnum{2}} W_{Y\comma \setnum{2}}^{CE} \plus \lpar 1 \minus \lambda _{\setnum{1}} \rpar W_{O\comma \setnum{1}}^{CE} \plus \lpar 1 \minus \lambda _{\setnum{2}} \rpar W_{Y\comma \setnum{2}}^{CE} .$$
A fully dynamic, OLG version of this model is in progress, so stay tuned.