

Introduction
Why and when does the state change its foreign policy? How do we account for foreign policy change? Despite the importance of foreign policy change, which can (re)shape the nature of a given state's international relations vis-à-vis other states and international systems, explanations of foreign policy change have received only sporadic attention in foreign policy analysis literature. The conventional wisdom in International Relations is that inertia is the default setting for governments. Thus, continuity in policy is interrupted only occasionally, and then only by major crises such as failed policies and political instability. This way of treating foreign policy change has been subject to two types of criticism. First, the sources of foreign policy change are so banal in the matrix of success and failure that they result in a flurry of ad hoc explanations. Second, the field of foreign policy analysis has not provided a clear understanding of the mechanism(s) through which foreign policy change occurs.
Against this backdrop, I offer in this article a reformulated framework designed to capture both motivational and processual aspects of foreign policy change. I develop the framework by critically examining and synthesising two recent systematic explorations of foreign policy change: one within the tradition of rationalism (broadly defined) – David Welch's Painful Choice: A Theory of Foreign Policy Change Footnote 1 – and the other within constructivism – Jeffrey Legro's Rethinking the World: Great Power Strategies and International Order.Footnote 2 In this article, I contend that a fuller account of foreign policy change can be achieved by combining and expanding on the two works for their respective shortcomings. The former (Welch's work) paid scant attention to the process of foreign policy change by focusing disproportionately on the motivational aspect of foreign policy change. Furthermore, I point out below the indeterminacy of Welch's use of prospect theory in analysing the gain/loss metrics for foreign policy change. The latter (Legro's work), dubbed the ‘synthetic’ approachFootnote 3 to foreign policy change, leaves out the motivational aspect while offering a general mechanism (or process) of foreign policy change. I show that this relative neglect of analysing the motivational aspect leaves Legro's ‘synthetic’ approach somewhat ambiguous in terms of the causal relationships between relative power, domestic interests, and collective ideas. By not fully accounting for the motivational aspect of foreign policy change, Legro (perhaps unwittingly) tends to take state interest as given and to focus on explicating how means to given interests are formulated in the fashion of change and continuity. Ironically, his constructivism seems to work within the boundary of rationalism because he does not provide an analytical account of the formation of national goals. Given these respective shortcomings in the two works, a reformulated alternative framework calls for a combination of the motivational and processual aspects of foreign policy change.
In what follows, I develop a reformulated approach to foreign policy change that covers both the motivational and processual aspects of foreign policy change. The key to the reformulated synthesis is to identify the common denominators of the two works and address their common problems briefly discussed earlier. In the vein of the constructivist theorisation of International Relations that does not take state interests as given, the crux of a reformulated approach is the incorporation of an analysis of state interest formation in the framework of foreign policy change. Central to this is the role of crisis-defining ideas in shaping the state's interests that travel through policy change process. In this way, a reformulated framework is able to encompass both the motivational and processual levels of analysis. The emphasis on crisis-defining ideas relates to the general recognition from previous research on foreign policy change that dramatic foreign policy changes normally occur under conditions of crisis-induced uncertainty. For the motivational analysis, I link the role of crisis-defining ideas to threat perception to sharpen prospect theory. As discussed in detail below, prospect theory, as it currently stands, is not specific enough about how loss framing inducing actors' risk acceptance for foreign policy change emerges. I show that one way to address this important issue is to examine the influence of threat perception on the development of loss framing, the hallmark of prospect theory.
I illustrate this reformulated synthesis with an example of Japan's policy shift toward East Asian financial regionalism.Footnote 4 In the wake of the Asian financial crisis (AFC) of 1997–1998, Japan made an important shift in its foreign economic policy in the way in which it approached regional institution building for East Asian monetary and financial cooperation.Footnote 5 Prior to the AFC, Japan endorsed ‘open regionalism’ to trade, investment, and monetary cooperation in the loosely institutionalised APEC (Asia-Pacific Economic Cooperation). By contrast, Japan has been the leading advocate of ‘exclusionary’ institution-building efforts in the region's monetary and financial affairs since the late 1990s. By ‘exclusionary’, it is meant that Japan has not included the US in these processes. Japan proposed and helped to materialise two major exclusionary institution-building measures for East Asia's monetary/financial cooperation: the Chiang Mai Initiative (2000) and the multilateralisation of the CMI potentially for the Asian Monetary Fund in future (2007). In addition, in December 2002, Japan proposed the idea of the Asian Bond Market Initiative (ABMI), which is aimed at developing regional financial markets that could issue local bonds denominated in local currencies. Finally, Japan established the ‘Kobe Study Group’ for the monetary integration process in East Asia in 2002. Following up on this establishment, Japan played a pivotal role in having the ASEAN Plus Three agree to study the feasibility of developing the Asian Currency Unit (ACU), which is modelled after the European Common Currency (ECU), in 2006. The US has not been included in any of these regional initiatives.
The rest of this article proceeds as follows. Section II presents a critical examination of Welch's and Legro's works with an eye toward a reformulated synthesis. Section III offers a reformulated framework for foreign policy change. Section IV illustrates the framework with an example of Japan's policy shift toward exclusionary financial regionalism. Section V provides a summary and suggests some avenues for future research.
Loss-aversion versus synthetic approach
Drawing on organisational theory, cognitive and motivational psychology, and prospect theory, Welch proposes three hypotheses (not necessarily mutually exclusive of each other) that aim to capture the likely conditions for foreign policy change in the sense of punctuated equilibrium. Hypothesis 1, which is based on organisational theory, states that ‘foreign policy change should be less frequent in highly bureaucratic states with democratic regime than in less bureaucratic states with autocratic regime.’ This has to do with the number of actors involved in foreign policymaking; a highly bureaucratic state under a democratic regime tends to involve more actors with competing (and often interlocking organisational) interests in the process of formulating foreign policy, which contributes to a higher threshold for policy change. Hypothesis 2, which is based on cognitive and motivational psychology, predicts that ‘foreign policy change will be most likely when policy fails either repeatedly or catastrophically, or when leaders become convinced that it will imminently do so.’ The experience and anticipation of a catastrophic failure of existing policies can lead leaders to alter their cognitive and motivational inertia. Finally, Welch offers Hypothesis 3 on the basis of prospect theory: ‘leaders are more likely to pay the inherent costs of foreign policy change to avoid losses than to realize gains of equivalent magnitude’.Footnote 6
Although these three hypotheses together constitute Welch's general model of foreign policy change, the third hypothesis is central to his analysis. Welch himself comments on the basis of his empirical findings that ‘Hypothesis 3 is the most interesting and the most important’ because of its explanatory power for both ‘the expectation of inertia and an explanation for sudden departure’.Footnote 7 By exploring Hypothesis 3 both theoretically and empirically, Welch offers ‘a loss-aversion’ model as a mechanism for explaining dramatic foreign policy changes. The model, which is based on prospect theory that individuals are more sensitive to losses and consider them to be more painful than gains are pleasurable, is parsimonious. In his words, ‘foreign policy is most likely to change dramatically when leaders expect the status quo to generate continued painful losses. States will not alter their behavior simply to try to realize some gain’.Footnote 8 In addition, prospect theory suggests that individuals assess the alternatives presented to them not by assessing the net assets the particular option could bring them (utility maximisation in rationalism), but by comparing the outcome of a choice with their reference point defining what they consider to be an acceptable outcome.Footnote 9 As such, when applied to foreign policy change, (dramatic) foreign policy changes are most likely to occur when leaders (or decision-makers) are faced with painful losses or costs with existing policies and when other available alternatives appear to be acceptable. This is his generalisable model of foreign policy change across time and space. Welch claims that ‘significant foreign policy changes should be rare and, when states change their behavior dramatically, they will do so for what are formally (if not substantively) similar reasons’.Footnote 10
If applied to Japan's foreign economic policy change, the key question would be what types of losses triggered Japanese leaders to pursue exclusionary institution building for the region's monetary/financial cooperation. In terms of the sensitivity to losses in Hypothesis 2, Welch further suggests that democratic and highly bureaucratic states are less sensitive to small prospects of loss or gain than are autocratic or relatively non-bureaucratic states.Footnote 11 Given that Japan is a democratic and highly bureaucratic state, Japan's policy change should come from the anticipated (or realised) ‘large (or high) loss’ if the status quo were to continue.
The problem with Welch's ‘loss-aversion model’ is that the model does not elaborate enough on what the reference point is. Welch claims that this is an acceptable state of affairs or what individuals or states want to achieve.Footnote 12 Decision-makers would then compare this reference point to the status quo and determine whether the status quo brings them losses or gains. Despite the centrality of the concept of the reference point in his analysis of foreign policy change, Welch does not shed light on the question of how a reference point is defined, formulated, and projected with respect to the status quo.Footnote 13
Is the reference point to be only materially defined? What would be the precise threshold demarcating a large loss from a small loss? How about the cases in which losses are to be traded off?Footnote 14 When applied to Japan's policy shift, for example, Japan might have to pursue exclusionary institution building for the region's monetary/financial cooperation at the expense of its strategic alliance with the US. In the strict gain/loss metrics, Japanese leaders would have to compare the different losses resulting from different policy options. Again, this example points to the need for a further examination of the issue of the reference point.
Lebow's critique of prospect theory strikes a note of the importance of defining a reference point that incorporates the study of actors' motives.Footnote 15 He divides human motives into three categories, that is, appetite (material interests), security (fear), and spirit (honour and self-esteem), and argues that each motive invites different metrics of gains and losses. When security/fear is involved, it is often difficult to separate gains from losses, which is the core of prospect theory, because security is relational; another's gain can be understood as your loss and vice versa.Footnote 16 Furthermore, Lebow posits and demonstrates through his empirical studies that when actors are motivated by spirit/honour, they tend to accept risks with respect to either gains or losses. According to Lebow, even appetite/material interests can complicate gains from losses if they are framed relationally.Footnote 17
With this nuanced notion of gains and losses, Lebow calls for the reformulation of prospect theory by claiming that ‘willingness to run risks varies as a function of motive. They not only determine how actors frame the meaning of gain and loss but the possibility of distinguishing between them, which is so essential to prospect theory’.Footnote 18 He urges that ‘prospect theory needs to be reformulated to take into account of the motives of actors’.Footnote 19
For example, Welch's own case study of Canada's three attempts to have a free trade agreement with the US provides support for the insufficiency of prospect theory, absent an analysis of motives (or state preferences) that can help define a reference point: In 1911, Canada tried for gains. The 1948 attempt came about by their fear of losses. Finally, Canada tried and succeeded in 1988 with a mixture of realising gains and avoiding losses.Footnote 20
Relatedly (and perhaps more fundamentally), Welch's current model is silent on how decision-makers frame the status quo or the current situation through an act of interpretation and evaluation. Given that the calculations of gains and losses are based on a specific reference point associated with decision-makers' interpretation and evaluation of the current situation with respect to the future, a theoretical apparatus of decision-makers' framing of an issue in terms of what constitutes the current situation should be incorporated into the model. After all, framing is the ground on which both the notion of the reference point and the evaluation of gains and losses are established.Footnote 21 Each foreign policy emerges from the interaction between states and the understanding (and misunderstandings) that underlies the ‘moves’ they made in response to one another's actions. As such, the key to framing lie in, among others, the meaning that one state gives to another's action, including ‘its nature, motives, interests, probable actions, attitudes, and role in any given political context’.Footnote 22 Once the current situation is framed in a certain way over others, the very framing entails ‘who and what “we” are, who and what “our enemies” are, in what ways “we” are threatened by them, and how “we” might best deal with those threats’.Footnote 23 In essence, without an analysis of framing, the key proposition from prospect theory that individuals are prone to risks under the condition of a loss would become an oxymoron and be unable to reasonably predict the specific content of foreign policy change.
Legro offers a constructivist account of foreign policy change. He explores a mechanism through which major foreign policy changes can occur by focusing on the role of collectively-held ideas in facilitating such changes. In a nutshell, Legro claims that foreign policy change results from a change in collectively-held (group or national) ideas in the interaction with strategic environments and domestic political processes. Shocks to old thinking (typically a war or economic calamity) make possible the reorientation of foreign policy, and it is at these historical ‘pivot points’, when the nation's interests are not clear and leaders are forced to debate the future, that ideas and beliefs matter. Legro states that ‘New foreign policy ideas are shaped by preexisting dominant ideas and their relationship to experienced events, sometimes reinforcing the continuity of concepts and infrequently leading to their radical change’.Footnote 24
Building on the previous one-stage model of foreign policy change (old thinking → shock → new thinking), he suggests a more nuanced, specified two-stage model that goes through the collapse of old thinking and the consolidation of new thinking, which eventually shapes a new foreign policy. The three key terms are ideas, events, and experienced outcomes. Foreign policy change occurs ‘to the degree to which the expectations of particular dominant ideas are defied by events (“shocks”), negative consequences result, and some socially viable alternative exists’.Footnote 25 In other words, the effects of shocks such as wars, revolutions, and economic crises depend on the interaction between pre-existing and new ideas that intersubjectively define the events as a ‘success’ or ‘failure’ in a given society.
This is where other factors such as the relative power between states (influence of power) and domestic politics come into play in ‘the politics of ideas’ for Legro's ‘synthetic approach’. The relative power wielded from abroad, for example, can have a considerable effect on the process of consolidating new foreign policy ideas (that is, the influence of the US on the foreign policy of Germany and Japan after World War II). When it comes to domestic politics, motivated interest groups and social movements play a crucial role in spreading replacement ideas and helping them to gain social salience. As such, Legro's synthetic approach clearly recognises the role of relative power and domestic interests in influencing the (un)making of national ideas but still prioritises the role of ideas because ‘such influence (influence of power and domestic interests) typically depends on interaction with prior ideas (and mix of ideas, events, and consequences)’.Footnote 26
In this way, Legro puts forward his version of a general model of foreign policy change. He states that ‘The way that states believe their interests are best pursued can vary significantly, but the processes [two-stage model] that govern when change or continuity occurs in those ideas seems to reveal many similarities’.Footnote 27 As such, Legro's general model offers the general mechanisms (processes) of foreign policy change, which is in contrast with Welch's general model focusing on the motivational aspect of foreign policy change.
This leaves Legro's ‘synthetic’ approach somewhat ambiguous with respect to the causal relationships between relative power, domestic interests, and collective ideas. In other words, such relationships are not always clear, although Legro makes a compelling case that strategic beliefs cannot be reduced to a strategic circumstance throughout his empirical case studies. Legro himself is not so clear about this relationship: ‘in this book I examine beliefs about effective means for achieving interests or how states think about achieving their ends’.Footnote 28 This indicates that he treats state interests as given (whatever they are, or survival) and focuses on explicating how means to given interests are formulated in the fashion of change and continuity. Ironically, then, his constructivism seems to work within the boundary of rationalism because he does not provide an account of the formation of national goals.Footnote 29
For example, Legro is successful in demonstrating the combinatorial effects of relative power, domestic politics, and dominant ideas on Japan's policy change from a policy of seclusion to an open-door policy in the late nineteenth century. The role of ideas here is, however, only secondary to external pressures (the power asymmetry between Japan and outside forces and domestic political battles) as an intervening variable.Footnote 30 Instead of foreign policy changes resulting from changes in collectively-held ideas from the interaction between strategic environments and domestic political processes (as Legro claims his model to be), the causal relationship seems to work the other way around. This leads Legro's model yet to address his question within his general process framework: ‘how ideas interact with other factors in specific ways to cause outcomes?’
Japan's pursuit of exclusionary institution building for the region's monetary/financial cooperation clearly illustrates the weakness of Legro's approach. In a nutshell, the AFC was the fundamental impetus behind the shift in the Japanese government's views and policies toward a regional financial structure. Prior to the AFC, Japan's Ministry of Finance (MOF) showed little interest in activities involving regional financial cooperation, particularly those excluding the US. The AFC was a shock to Japan in two important ways. First, the US attributed the cause of the crisis to Asia's crony capitalism while contributing nothing to the crisis management. This dealt a blow to Japan's reputation, not least because Japan had long argued that Asian states' economic success came from their adoption of the so-called Japanese model of state-led economic development.Footnote 31 Second, Japan realised that East Asia did not have any financial institutional mechanism that could prevent another financial crisis, let alone an effective management system independent of the US and the IMF.
In Legro's model, the AFC was a watershed moment that sharply demarcated Japan's ideas about exclusionary institution building for the region's monetary/financial cooperation. Japan's old idea of internationalism collapsed and was replaced by the new idea of financial regionalism. However, this whole process of collapse and consolidation took place in the context of Japan's (more precisely the MOF's) interpretation of the nature of the US response to the crisis during the AFC, not in the context of any change in immediate material incentives, domestic politics, and relative power (vis-à-vis the US, for example), which is discussed in detail later. Therefore, this example suggests how the absence of an analysis of state interest formation may prevent a fuller account of the nature and development of major foreign policy changes.
Synthesis and reformulation
What would then be a better and fuller way of explaining foreign policy change? One way to do this is to combine Welch's and Legro's accounts of foreign policy change so that we can cover both the motivational and processual aspects of foreign policy change. In what follows, I present a reformulated approach to foreign policy change by building on the two works examined above. The key to this reformulation is to identify the common denominators of the two works and address their common problems discussed earlier; notably, the reformulation incorporates an analysis of state interest formation (in relation to framing) into the model of foreign policy change. The reformulated synthesis emphasises the role of crisis-defining ideas in shaping the state interest under uncertainty. Along the way, I also suggest a way to sharpen prospect theory's ambiguity in the development of loss framing that induces actors' risk acceptance for foreign policy change. I do so by shedding light on the linkage between crisis-defining ideas and threat perception.
A good starting point for the reformulated synthesis is the recognition from both works that dramatic foreign policy changes typically occur under conditions of crisis-led (or policy failure-led) uncertainty and that both works do not offer a definitive analysis of state interest formation leading to the indeterminacy of the timing and content of foreign policy change. Following Widmaier, Blyth, and Seabrooke, crises are defined here as ‘events which agents intersubjectively interpret as necessitating change’.Footnote 32 As such, what is needed for the reformulation is an analytical framework that can help explicate state interest formation from shared meanings and the interpretation of events (a crisis, for example) on the part of actors geared toward policy change. Exogenous shocks and crises must be interpreted, perceived, and understood in a particular way.Footnote 33 An actor acts based on such an interpretation of the event, not on ‘its materially telegraphed interests’.Footnote 34 In moments of uncertainty, ‘crisis-defining ideas not only tell agents “what has gone wrong” but also “what is to be done”’.Footnote 35 By constructing a crisis or policy failure in a certain way, crisis-defining ideas enable/constrain actors in a position of institutional authority to engage in defining, diagnosing, and explaining the crisis as an event that calls for a particular course of action.
Bourdieu's discussion on habitus is relevant here for a crisis-driven mechanism of foreign policy change.Footnote 36Habitus consists of doxa, orthodoxy, and heterodoxy, whose interplay facilitates social change. Doxa, which refers to a set of dominant social meanings and values in a given issue area that appears to be legitimate and natural (not socially or politically constructed), falls apart in the face of ‘objective crises’, which typically arise from external shocks or events. The crises call into question the naturalness of the doxa, which in turn engenders orthodoxy (a set of attempts by some groups in society to interpret the crises not contradictory to the existing doxa in defending its function and legitimacy) and heterodoxy (a set of attempts by some groups in society to interpret the crises to delegitimise and denaturalise the doxa so that it can be overturned). The very emergence of orthodoxy and heterodoxy carves out a space for the possibility of change. As such, the interpretation of an event (or giving meaning to an event) is logically prior to as well as integral to the construction of what actors want (or Welch's conception of gains and losses). There would be little direct and unmediated response to external shocks or crises.
This emphasis on the interpretation based on crisis-defining ideas does not suggest that the resulting interests are ideational. There is no a priori assumption here about the nature of emergent interests. For example, Johnston claims that Ming's hard realipolik approach to Mongol (or Ming's realpolitik strategic culture) derived from, as socially learned behaviour, Ming leaders' interpretation and perception of strategic environments facing China in particular periods of time, not from anarchical structural conditions.Footnote 37 Rousseau also discusses the importance of belief systems that shape realpolitik preferences.Footnote 38 In the analysis of economic interests, Abdelal demonstrates how post-Soviet states' conception of national identity vis-à-vis Russia and West Europe led some states to re-establish their trade relations with Russia while driving others to cut theirs.Footnote 39 In a similar vein, Herrera explores the emergence and development of economic interests per se.Footnote 40 Herrera demonstrates how a certain motivational disposition is developed through the act of processing information in which schemas play a central role. The act of schema-based interpretation helps shape certain economic rationality in greater or lesser regional sovereignty.
Given the fact that not all crises result in policy change, a further specification is needed for the types of crisis-led state interests that are most likely to induce major foreign policy changes. Here the insight from prospect theory is useful: actors are risk averse when making gains and are more willing to accept risks when avoiding losses. As such, the likelihood of foreign policy change increases when the resulting state interest from a crisis-defining idea is framed as a loss.Footnote 41 As discussed in detail earlier, however, prospect theory is ambiguous in the development of loss framing in terms of its sources (that is, material interests, self-esteem, and fear) and across issue areas (that is, security and economic affairs). This ambiguity calls for a conceptual apparatus that can help specify the distinctive analytical path(s) through which loss framing can emerge.
I suggest that one way to address this ambiguity is to link crisis-defining ideas to threat perception. In other words, this requires an analysis of the influence of threat perception on the development of loss framing. The logic is simple. For example, once a state defines another state's policy as a threat, the state has to respond to it. A threat normally calls for defence, not offense. The implication of defence is that the state's response is likely to be formulated in the loss framing. The key to this analytical linkage is to show how threat is constructed by crisis-defining ideas, which increases the probability of risk acceptance for foreign policy change.
Indeed, the linkage between ideas and threat perception is not new in the field of International Relations. Unlike Waltz,Footnote 42 who views threat as a function of the power asymmetry (defined as material capability), Walt puts forward his balance of threat theory, which incorporates an ideational factor (aggressive intention) into the development of threat perception.Footnote 43 States balance against threat, not power. Threat perception, not pure power distribution, leads states to choose among balancing, bandwagoning, and neutrality when faced with a rising power. Copenhagen School's concept of securitisation is relevant here.Footnote 44 A threat is socially and politically constructed through securitisation discourses. There is no such a thing as an inherent and naturally given threat. In constructivist theorisation, Wendt theoretically and conceptually develops the claim that threat perception is a function of shared identity.Footnote 45 Rousseau empirically corroborates the importance of shared identity as a key conditioning variable in the emergence and development of threat perception, which leads to either a realist policy choice (that is, the pursuit of relative gains) or a liberal one (that is, the pursuit of absolute gains).Footnote 46 As a domestic determinant, Johnston analyses China's strategic culture and makes the case that a threat is a product of domestic beliefs around a given state's strategic circumstances.Footnote 47
What unites these cognitive models analytically is their shared emphasis on microprocess of social learning by key decision-makers. As Sohn aptly maps out in his explanation of China’ shift from passive to active support for East Asian financial cooperation, social learning on the part of decision-makers, which is to update beliefs and behaviours based on interaction with other states and assessment of their past policies via cognitive dissonance, feedback effects, and persuasion, foregrounds threat perception by guiding them to frame other states' policy in aggressive or hostile intentions.Footnote 48 Social learning, which cognitively filters new information (that is, other states' new policy choice) through decision-makers' prior social relationships with other states and the identities and interests formed from these, importantly shapes the function of amity and enmity in Bayesian updating fashion. The same policy from other states can be interpreted as threat or non-threat depending on whether it comes from an ally or an adversary. Social learning is a critical source of how to determine the meaning of other states' action in a myriad ways of perceiving it.Footnote 49
Two experimental studies are illustrative in this microprocess of social learning that influences threat perception. Rousseau reports on lab experiments involving subjects interpreting the cause of a fictitious attack on an American naval destroyer.Footnote 50 The attack was interpreted as an accident driven by situational factors (that is, a storm) when the subjects were informed that the suspected attacker was Britain. In sharp contrast, the subjects understood the same attack as a purposeful act when the suspected attacker was identified as Iran. Similarly, Alker reports that in an iterated PD game, the meaning of defection changes from ‘an act of aggression’ to ‘mistake’ once the interaction of two players becomes locked into ‘a joint commitment to a pattern of peaceful coexistence’.Footnote 51 Social learning, then, is a crucial property of any emergent threat perception by helping define the present and the future in terms of the past.
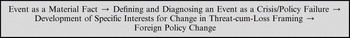
In sum, the above analysis suggests a reformulated causal path through which foreign policy change occurs. This framework can be represented as follows.
Reformulated version of foreign policy change.

This way of reformulation can address the abovementioned analytical shortcomings in Welch's and Legro's works. Because this reformulated framework offers a way to identify the source and content of state interests through an analysis of the role of crisis-defining ideas in defining and diagnosing crises linked to threat perception, it can better address the ambiguity associated with the reference point. The suggested causal path, which fleshes out the independent role of ideas in linking external events to the process of state interest formation, can also help Legro's synthetic model to respond effectively to the under-explored question of ‘how ideas interact with other factors in specific ways to cause outcomes’. In this way, the reformulation can better capture the dynamics of foreign policy change both theoretically and empirically. The micro-level causal process built in the reformulation also avoids the charge of tautology that has been associated with some presentations of ideational approaches that derive intentions from policy outcome (post-hoc reasoning).
In what follows, I illustrate the effectiveness of the reformulated analytical framework with an example of Japan's promotion of East Asian financial regionalism in the aftermath of the AFC. Because of limited space, the following discussion is illustrative, not demonstrative.
Illustration
The AFC was a watershed moment that induced a major shift in the Japanese government's views and policies toward a regional financial structure.Footnote 52 Prior to the AFC, the Japanese government (that is, the MOF, which is in charge of Japan's external financial relations) was not an enthusiastic proponent of activities involving regional financial cooperation, particularly those excluding the US from the regional institutional arrangement. Since Japan rose to global economic prominence by the 1980s, the MOF's policy focus was on increasing Japan's influence on the two key IFIs, the IMF and the World BankFootnote 53 and on achieving a stable yen-dollar exchange rate, with the possibility of yen internationalisation.Footnote 54
These primary policy goals remained largely the same until the breakup of the AFC. Japan's non-commitment to the development of a regional financial structure was conspicuous because of the size of Japan's economic interest and clout in the region. Since the 1985 Plaza Accord and the resulting appreciation of the Japanese yen against the US dollar, many Japanese companies shifted their manufacturing base from Japan to Southeast Asia to establish new export platforms. This shift in Japan's manufacturing base not only required large foreign direct investment but also massive bank lending from Japan. This resulted in the virtual dominance of Japan in the function of regional economies. According to Hatch and Yamamura, Japan ‘embraced’ Asia.Footnote 55 Despite the enormous economic influence in the region and the chronically unstable exchange rate, Japan's reluctance to shape a formal regional economic structure without the US resulted at least partly from US pressure (or Japan's abhorrence of alienating and angering its long-time post-war ally, the US). Japan's lukewarm attitude and subsequent decision not to join the then Malaysian Prime Minister Mahathir bin Mohamad's proposal to form the East Asian Economic Grouping exemplified this dilemma.Footnote 56
The AFC shook Japan's patterned response to the development of a regional institution and helped to reimagine a regional alternative to the US-centred global financial arrangement. During the Thai crisis, Japan (led by the MOF) proposed to create the Asian Monetary Fund (AMF) at the annual meeting of the World Bank and the IMF in Hong Kong on 21 September 1997 while excluding the US from membership. The goal of the AMF was to create a $100 billion fund for the quick disbursement of funds to crisis-affected countries that, from the MOF's point of view, otherwise would have been forced to accept the IMF's unnecessary and intrusive structural reform conditionalities.Footnote 57 After the AMF was rejected by the US, Europe, the IMF, and China, the idea of added liquidity and the quick disbursement of funds in response to the AFC was taken up by the Manila Framework (under the auspices of the IMF) in November 1997.
Despite the initial failure, Japan's idea and effort aimed at creating a regional emergency funding mechanism did not die easily. Japan revived it first through the ‘New Miyazawa Initiative’ in 1998. Although bilateral in nature, the $30 billion initiative tried to meet financial needs for economic recovery and reform in crisis-affected East Asian countries without IMF-style conditionalities. In announcing and implementing the initiative, the MOF stated that the bilateral arrangement would be a stepping stone to a multilateral framework in the future, such as the AMF.Footnote 58 Japan furthered this effort in the context of APT by taking the lead in establishing and developing the Chiang Mai Initiative (CMI).Footnote 59 Since its establishment in May 2000, the CMI has developed into the core of East Asia's regional emergency liquidity mechanism.
Since its establishment in 2000, the CMI has intensified regional monetary cooperation with added policy goals.Footnote 60 The CMI was first conceptualised at the APT Summit in 1999 when the Asian finance ministers agreed to enhance ‘self-help and support mechanisms in East Asia’.Footnote 61 Subsequently, the CMI arranged a network of bilateral swap arrangements among the central banks of APT countries to provide a ‘balance of payment support’ and ‘short term liquidity support’. Thus, the CMI was initially envisioned as the first-order defensive mechanism that can provide foreign exchange liquidity support. As Amyx acutely notes, what is of importance is the latter (‘short term liquidity support’), which emerged from Asia's financial crisis experiences. Unlike the ‘balance of payment support’, which is linked to the recipient country's macroeconomic policy and allows the IMF to play a role through its conditionality principles on loan amounts, ‘short term liquidity support’ injects liquidity into the recipient country where capital would exit rapidly without the country's particular macroeconomic mismanagement. Thus, this provision would not require any IMF intervention.Footnote 62
Another major step was taken on 6 May 2005. The APT further strengthened the CMI at the ADB annual conference in Istanbul, clearly stating that it would be a ‘step toward multilateralization […] a de facto Asian Monetary Fund may eventually be created’.Footnote 63 The Istanbul Initiative doubled the size of currency swaps under the CMI from $36.5 billion to $72 billion; increased the amount of emergency liquidity available without IMF conditions from 10 per cent to 20 per cent; and made bilateral swaps into two-way swaps, aiming to make them multilateral in future.Footnote 64 Japan led this initiative with China's support.Footnote 65 Perhaps not surprisingly, Haruhiko Kuroda, the new ADB president, who was among those proposing the creation of the AMF in 1997, spearheaded the Istanbul Initiative. In April 2005, Kuroda created the Office for Regional Economic Integration within the ADB to facilitate regional monetary cooperation and appointed Masahiro Kawai, another proponent of the AMF, as its head.
On the heels of the Istanbul meeting, East Asian states' efforts to multilateralise the CMI began in earnest. From May 2006, APT countries started to work on the details by agreeing to discuss various key issues such as the total size of the fund, the form of funding, the legal modality, procedures and voting shares, and the proportion of the contribution that each state would make.Footnote 66 On 5 May 2007 in Kyoto, Japan, APT finance ministers, led by Japan, historically and unanimously agreed to launch a multilateral currency swap scheme. This scheme was to materialise by multilateralising the CMI. At the Kyoto meeting, the finance ministers were not hesitant to state that the envisioned multilateral institution would be an ‘Asian version of the IMF’, which was first proposed by Japan in 1997. Furthermore, on 3 May 2009, APT concretised the multilateral currency swap scheme by agreeing to its size: $120 billion. China and Japan would contribute $38.4 billion each, and Korea, $19.4 billion. The rest of the fund would come from ASEAN countries. Accordingly, voting shares were also finalised. China, Japan, and ASEAN countries would have 28.4 per cent each, and Korea, 14.8 per cent. The form of funding would be self-reserved reserve pooling. For its legal modality, a legally binding, single contractual agreement was decided upon. What remains for a fully loaded multilateral institution are lending conditionalities for the release of funds and the finalisation of the surveillance mechanism, for which discussions are currently under way.
Japan's shift toward East Asian financial regionalism has not been limited to developing a framework (the CMI/AMF) for preventing and managing future financial crises. Japan has actively pursued the development of a regional financial market arguably for regional financial stability and independence in the wake of the AFC.Footnote 67 In December 2002, Japan officially put forward the Asian Bond Market Initiative (ABMI). The ABMI proposal aimed to reduce the region's reliance on foreign capital for financial stability by developing local (or regional) bond markets that could issue local bonds denominated in local currencies. The lack of a deep local financial market forced the region (or East Asian countries) to depend unnecessarily heavily on external financial markets as the source of investment and funding. Absent a deep local financial market, the region was not able to tap into its large surplus of savings; the region's surplus of savings flowed out of the region to external (Western) financial markets. Then, the invested savings returned by way of loans to East Asian borrowers now interest rates attached. Simply put, East Asia ended up borrowing its own money. This not only made little economic sense but also kept the region asymmetrically dependent on external financial markets.Footnote 68
In addition, the regional dependence created interrelated problems, resulting in region-wide chronic financial instability, namely the double mismatch. A double mismatch occurred as East Asian countries obtained short-term loans denominated in the dollar from external financial markets and invested in long-term assets denominated in local currencies. The outcome was that assets and liabilities were mismatched in terms of both the maturity and the settlement currency. This double mismatch thus exposed East Asia to more risks and higher costs of borrowing, making the region highly vulnerable to movements in the value of the dollar. Following up on the 2002 proposal, Japan led APT's announcement of the ‘New ABMI Roadmap’ at the APT Finance Ministers' Meeting in Madrid in 2008. The ‘New ABMI Roadmap’ included the development of a facility to increase the demand for local currency-denominated bonds, the improvement of the regulatory framework (a regional bond-rating system and an information dissemination mechanism), and the enhancement of infrastructure for local bond markets (credit guarantee and investment mechanisms and settlement coordination).
Finally, Japan, through APT, has been a strong proponent of the creation of the Asian Monetary Union (AMU) to effectively manage currency volatility for intra-regional and interregional trade and investment. This area is indeed the least developed component of East Asian financial regionalism with a longer-term time horizon. In 2002, Japan launched the ‘Kobe Research Group’ and put together economists and policymakers in the region to conduct a joint study of the European monetary integration process with an eye on the applicability of the process to East Asia. The first report from the Kobe Research Group came out in July 2002 and recommended the launching of a single currency in 2030. Another visible initiative of Japan's leadership on this score has been the idea of the Asian Currency Unit (ACU), which has been modelled after the European Currency Unit (ECU), the region's currency unit (the unit of currency exchange based on the weighted average of a basket of currencies) before the euro was launched. The idea of the ACU first came from the ADB's Office of Regional Economic Integration under the leadership of its then director Kawai and ADB president Kuroda.Footnote 69 The idea was later picked up by APT, which agreed in 2006 to study the feasibility of the ACU.
In sum, Japan's shift to East Asian financial regionalism has been clear after the AFC. Japan has been proactive and showed leadership for all of the three components of East Asian financial regionalism by providing important initiatives, ideas, and policy and monetary support. As with the CMI, Japan did not include the US in the discussion on the ABMI as well as on the AMU (ACU). In doing so, Japan has exercised the boundary marking of the region in financial and monetary affairs.
Analysis
The above illustration suggests the importance of the AFC for Japan's policies toward an exclusionary arrangement for the region's monetary/financial cooperation in East Asia. However, existing explanations differ on how the AFC (or an external shock) has shaped Japan's post-crisis policy choice. Previous research has identified three factors that contributed to Japan's policy change.
First, Japan felt the lack of alternatives to the IMF as a crisis management framework. At the time of the crisis, the regional institutions in East Asia, such as ASEAN and the APEC, were informal and loosely structured and lacked appropriate mechanisms for binding commitments, making them unable to adequately manage crises.Footnote 70 Second is Japan's awareness of the region's structural dependence on extra-regional sources of finance for crisis prevention and effective management. The Japanese government came to believe that, unless there were some regional financial mechanisms for liquidity within East Asia, the region would very likely face similar financial crises without much recourse.Footnote 71 Finally, Japan's shift to regionalism has been closely linked to its aspiration for regional leadership in the context of its growing rivalry with China.Footnote 72
Although suggestive, none of these explanations adequately addresses the question of why Japan has excluded the US from being part of the post-crisis institution-building process for the region's monetary/financial cooperation. For example, if additional money for crisis management and its rivalry with China are all on the table, Japan may be eager to include its closest post-war ally, the US, in the regional scheme for a source of additional funding as well as for hedging against China's influence.
As such, an alternative approach is needed that can determine how Japan's perception (particularly MOF officials) and interpretation of the AFC have shaped Japan's decision to ‘go regional’ in the sense of developing regional financial schemes that have excluded the US. In short, Japan's dramatic policy change cannot be separated from its interpretation of the causes and consequences of the AFC in relation to the ways in which the US (or the US-led IMF) addressed the AFC. This interpretation in turn has shaped Japan's threat perception, inducing Japan to take a defensive approach with respect to US-led globalisation.
Since the early stage of the AFC, there was a fairly strong disagreement over the causes of the AFC between Japan (and East Asian states) and the US and the IMF. Japan's MOF insisted that the AFC was a temporary liquidity problem, not a solvency crisis. This insistence was based on the MOF's assessment of the sound macroeconomic fundamentals of the crisis-affected countries. The US and the IMF refuted Japan's interpretation and claimed that the AFC was nothing more than a manifestation of the fundamental problem embedded in the Asian model of capitalism (‘crony capitalism’). Subsequently, the US-cum-the IMF pushed through a wide range of economic reforms aimed at forcing Asian state-led capitalism to be more in line with the putative global standard of neoliberal capitalism, going well beyond the usual IMF austerity measures.Footnote 73 From the viewpoint of Japan's MOF, the US and the IMF were interested mainly in advancing their own prerogatives, not in helping those economies afflicted by the crisis.Footnote 74 Eisuke Sakakibara, the then vice minister of the MOF who was known to be the architect of Japan's AMF proposal in 1997 and to have led Japan's shift to regionalism after the AFC, commented on the IMF bailout:
But the initial mistakes committed by the IMF in late 1997 and early 1998 were very crucial – they tightened the monetary policy, which was not necessary, and imposed very rigid and sometimes unrealistic structural reforms in a somewhat unreasonable manner. It was too hasty. Structural reforms in Asia may have been necessary, but it should not have been imposed from outside without internal preparations for the change…These are not the appropriate functions of the IMF. The IMF needs to concentrate on macro policies and liquidity issues rather than on structural problems […] It was not the function of the IMF to impose those reforms on the countries in crisis.Footnote 75
To Japan's MOF, the AFC was an event that helped it to develop an ‘image of the region in adversity besieged by outsiders “ganging up” in their attempts to exploit the difficulties that East Asian governments faced’.Footnote 76 As Higgott aptly notes in his discussion of ‘the politics of resentment’,Footnote 77 ‘Most East Asians [including Japan] feel that they were both let down and put upon by the West’.Footnote 78 From the viewpoint of Japanese policymakers, the root cause of the AFC was in fact the premature financial liberalisation of crisis-affected Asian states under pressure from the US and IMF. Furthermore, even after a decade since the AFC, the fear and resentment with respect to the ‘Washington Consensus’ has served as glue for Japanese and East Asian leaders to come together to push exclusionary financial regionalism.Footnote 79 In this regard, Chey captures the anti-American mood within Japanese policy circles since the AFC that helped to form ‘the volition to reduce US influence in East Asia’.Footnote 80 Sakakibara argued in an international conference on globalisation that ‘if East Asia does not want to be divided and ruled as in the colonial days and in the more recent past [the AFC], we need to form some types of regional cooperation of our own’.Footnote 81 Indeed, Japan's then Prime Minister Keizo Obuchi officially used the concept of ‘East Asia’ as opposed to ‘Asia Pacific’ for the first time in Japan's history when emphasising regional economic cooperation in his speech at the APT summit in Hanoi in December 1998.Footnote 82
As such, Japan's shift to regionalism, which takes risks by excluding the US from the region's institution building for monetary/financial cooperation, derives from its conception of the anticipated loss in the absence of a regional defensive alternative. As Hayashi puts it, ‘Considering these factors [Japan's as well as East Asian states’ resentment toward the nature of the US-led IMF operation during the AFC], there is no wonder that the East Asian countries [including Japan] became increasingly discontented with the Washington Consensus, which reinforced their belief that self-help was the only alternative’.Footnote 83 Self-help has become a buzzword connoting ‘never again [under the IMF rule]’ in post-AFC East Asia and reinvigorated efforts to find regional financial solutions.Footnote 84 Hamanaka reports on a series of interviews with the MOF officials that exclusion of the US was undoubtedly the main reason why Japan supported ASEAN plus Three financial cooperation after the AFC.Footnote 85 To the MOF, any regional cooperation including the US is not meaningful, because inclusion of the US makes regional cooperation merely redundant to the ongoing global financial system ‘owned by the US’.
Japan's shift to regionalism is defensive in its character because Japanese policymakers had first-hand experience and lived through the meanings, discourses, and policy behaviour of US-led neoliberal globalisation during the AFC. Pascha, for example, interprets Japan's shift to regionalism as a loss-induced defensive move. Pascha argues that Japan's main goal of constructing East Asian financial regionalism has been to protect East Asia from financial risks, not to proactively boost its regional influence vis-à-vis the US.Footnote 86 Similarly, Grimes observes that Japan's shift to regionalism can be best seen as ‘a defensive measure against US influence and globalization as greater threats to national autonomy […] Broadly speaking, the East Asian states [including Japan] have been driven by a motivation to reduce vulnerability to global finance rather than to maximize market efficiency’.Footnote 87 The defensive nature is evident in the MOF's explanation for the necessity of the New Miyazawa Initiative, which would be a cornerstone of subsequent developments of Japan's financial regionalism. The MOF emphasised that the Initiative had a longer-term goal to develop and strengthen Asian financial institutions being able to stem negative effects of global finance.Footnote 88 To Japanese policymakers, the CMI was intended to create a regional self-help mechanism for crisis management; bond market initiatives (the ABMI), to address the double mismatch and reduce the role of dollar-based markets for intermediation for regional financial autonomy (the reduction of regional vulnerability to external financial markets);Footnote 89 and currency initiatives (the ACU), to lead to a regional currency basket to reduce the role of the dollar in managing currency volatility.Footnote 90 In this regard, a MOF official made the following statement:
When our [Japan's] AMF proposal of 1997 merged into the Manila Framework in December 1998, many [foreign observers] thought that Japan lost its interest in the AMF. But our view was that it would be an important first step toward an AMF, which indeed started to develop in the form of the Chiang Mai Initiative […] After all, it was East Asian states' premature financial liberalization under pressure from the US and the IMF and their [the US and the IMF] mismanagement of the AFC that led us to seek a regional solution to the negative effects of globalization […] the US and the IMF do not know much about how Asian economies work. Asian matters should be discussed among Asians.Footnote 91
In the process of developing and projecting Japan's exclusionary financial regionalism, the MOF's successful construction of the US-led IMF operation during the AFC as a neoliberal project effectively worked to win over several levels of domestic opposition. First, it helped to tone down some pro-IMF officials within the MOF who were concerned about negative political implications of exclusion of the US for Japan's position in the IFIs.Footnote 92 The legitimacy of the idea of developing defensive measures for Japan and East Asia against negative effects of global finance overshadowed such a concern.Footnote 93 Second, it elicited a substantial shift in the Ministry of Foreign Affairs' (MOFA) stance regarding regional financial cooperation. In the early stage of Japan's financial regionalism, the MOFA, which tends to define Japan's national interests in terms of the country's relationship with the US, opposed Japan's shift to regionalism that excluded the US. The MOFA, however, changed its stance later on in the face of the MOF's firm resolution and the legitimacy attached to the MOF's idea of regional financial cooperation.Footnote 94 In fact, the MOFA's shift in its stance was quite substantial to the extent that its view came to closely follow that of the MOF. The 2000 Blue Book,Footnote 95 for example, emphasises ‘the important lessons learned from the crisis [AFC]’ and the MOFA's full commitment to strengthening and implementing regional financial cooperation agreements from ASEAN plus Three.Footnote 96
Lastly, the impact of the AFC and the MOF's threat perception were also felt in Japan's private sector's stance. Initially, the reaction from Japanese financial institutions to Japan's pursuit of exclusionary financial regionalism was at best lukewarm. It was partly because they did not know what Japan's shift to financial regionalism was all about, having had only limited consultation with the MOF about it.Footnote 97 Some quarter of private sector even expressed the concern that Japan's initiatives, such as the AMF, might increase Japan's financial burden as the lender of last resort as well as create a psychology of dependence on the part of East Asian states.Footnote 98 In this context, Japan's then Prime Minister Obuchi dispatched the Okuda Mission (the Mission for the Revitalisation of the Asian Economies) to six East Asian states (South Korea, Vietnam, Thailand, Malaysia, Indonesia, and the Philippines), headed by Hiroshi Okuda (the then Chairman of the Japan Federation of Employers' Association) along with other leading business leaders and prominent academics. The mission was set out to examine the issues and needs of East Asian economies in light of the AFC and to identify the role that Japan should play in leading a more stable and robust economic development of East Asia. The final report from the mission, which was written in consultation with high ranking officials of such ministries as the MOF and the MOFA who participated in the mission as observers, called for Japan's more rigorous and proactive regional institutional building efforts, among others, for financial crisis prevention, regional bond market development, and currency stabilisation.Footnote 99 These issues coincide with the three components of Japan's financial regionalism, as discussed earlier.Footnote 100
As illustrated above, Japan's policy change process has gone through a cycle of observation, interpretation, and resultant policy choice, which the reformulated version of foreign policy change posits (see Figure 1, earlier). There has been no unambiguous structural determinant leading to Japan's policy choice and no calculation of gains and losses prior to the interpretative moment. This serves as a useful reminder that far from unmediated structural/material determinants, foreign policy change starts when the meanings, discourses, and systems of knowledge of an event are lived, experienced, and transformed on the part of decision-makers of a given state.
Conclusion
This article makes a theoretical suggestion that we should combine Welch's and Legro's accounts of foreign policy change so that we could have a fuller range of analytical methods that can captures both the motivational and processual aspects of foreign policy change. Furthermore, based on the discussion on the weaknesses of both works, this study proposes a reformulated synthetic analytical framework combining the two works. The framework emphasises the role the interpretation of the crisis/policy failure plays in constructing the timing and content of foreign policy change. The study also suggests a way to sharpen prospect theory by providing a better understanding of how loss framing that can induce actors' risk acceptance for foreign policy change emerges. Central to this is the analytical link between threat perception (emanating from a particular crisis-defining idea) and the development of loss framing. I have illustrated the value added of this reformulated version with Japan's shift to regional institution building for monetary/financial cooperation in the post-AFC period.
For future theoretical development, this combinatorial analytical framework should further clarify the domestic and international conditions under which crisis-defining ideas could have substantial, long-lasting effects instead of just creating opportunities for ‘reform talk’. For example, closer analytical attention should be paid to the process of the domestic contestation of foreign policy change in issue areas in which the distribution of the decision-making authority is less concentrated. In terms of Japan's policy toward financial regionalism in East Asia, the MOF is by far the dominant force with its expertise and jurisdiction over international finance and development issues in Japan vis-à-vis, for example, the MOFA. In addition, as FriedenFootnote 101 and KirshnerFootnote 102 note, a state's decision-making process on monetary and finance issues tends to involve a fairly limited number of strategic actors within the government. This is mainly due to the technicality/complexity of issues as well as the dispersed nature of gains and losses that monetary and financial policies pose. The insight is evident in the limited involvement of Japanese banks and large businesses in the making of Japan's shift to regionalism.Footnote 103
However, this may not be the case for other issue areas such as trade, in which distributional politics among domestic actors can be more pronounced in the development of a crisis. For such cases, a richer and fuller account could be constructed by detailing the process of domestic political struggles associated with the competing interpretations of the crisis and the resultant interests of the state: who gets to speak and define authoritatively the meaning of the crisis, thus imparting the meaning to political outcomes? In this regard, future research should also examine the possibility of a coalition between concerned domestic actors and international actors for crisis definition and policy change. Hypothetically, Japan's banks and large manufacturing firms could have aligned with the US and the IMF in their neoliberal interpretation of the AFC (‘crony capitalism’). Then this shared interpretation could have pressured the Japanese government to endorse a neoliberal reform of crisis-affected countries, not a defensive policy pursuing regional institution building. According to Abdelal, Blyth, and Parson, the relations of ‘qui bono?’ (who benefits?), ‘qui termino?’ (who defines?), and ‘qui dicto?’ (who speaks?) in times of crisis are subject to change depending on the specific context of the crisis and the nature of its issue areas.Footnote 104 Thus, the exercise of hypothesis formation, testing, revising, and reformulating should enrich the current debate on the questions of when and how foreign policy change comes about.