




No CrossRef data available.
THE DIFFUSION LIMIT OF A TVP-GQARCH-M(1,1) MODEL
Published online by Cambridge University Press: 05 March 2004
Abstract
This paper presents results on the issue of weak convergence of a TVP-GQARCH-M(1,1) process. These suggest that the weak limit of this endogenous volatility model is an exogenous (stochastic) volatility continuous time process. Under the appropriate assumptions, we derive the invariant distributions at which the process converges in various cases. They reveal an approximate distributional relation between the GARCH or the asymmetric GQARCH variance processes and the continuous time Ornstein–Uhlenbeck models with respect to appropriate nonnegative Levy processes.I am grateful to Ritsa Panagiotou, Phyllis Alexander, Antonis Demos, Bruce Hansen, Nicholas Magginas, Nour Meddahi, Enrique Sentana, Paolo Zaffaroni, two anonymous referees, and the seminar participants at the Department of International and European Economic Studies for their valuable comments.
Information
- Type
- Research Article
- Information
- Copyright
- © 2004 Cambridge University Press
1. INTRODUCTION
Discrete time stochastic processes that pose particular structures in their conditional moments have been extensively used to model the statistical stylized facts of financial time series. Well-known examples of the aforementioned practice are nested in the formalization of AGARCH (augmented generalized autoregressive conditional heteroskedasticity) models (see Duan, 1997). The latter consists of a plethora of dynamic structures posed on transformations of the conditional variance of the process. These have rapidly emerged since the introduction of the first ARCH model of Engle (1982) and its generalization (GARCH) by Bollerslev (1986).1
Conditionally heteroskedastic is any sequence with ∥Var(xt+m /σ{xi}i=−∞t) − Var(xt+m)∥p > 0, where ∥·∥p denotes the Lp norm (see, e.g., Davidson, 1994, Ch. 14).
Despite the popularity of these models, there are still obscure points concerning their mathematical properties. A characteristic example is the lack of knowledge of the exact unconditional distribution of the conditional variance and therefore of the level process. This stems from the fact that usually these models prescribe a very complex mixture of the conditional distributions, results in several shortcomings. Examples range from the unavailability of the full information (pseudo) likelihood function needed in estimation purposes to the inability of generally deriving fractional moments, or truncated versions of nonexisting moments, of the conditional variance.
One way to circumvent this is to approximate (in an appropriate sense) the underlying process by another process whose properties are more easily inferable. More specifically, by exploiting the theory of weak convergence, one can derive the (diffusion) limit of the conditionally heteroskedastic processes, as the time interval becomes infinitesimal, hoping to be able to access the density of the limiting process. The literature covering this approach—which as a matter of fact is already exhaustive—was initiated by Nelson (1990), who provides a general theoretical framework and specific examples for the weak limits of the GARCH-M and the E-GARCH-M models. Because of this first effort, several other papers have arisen, most notably those by Corradi (2000), who shows how a degenerate or a nondegenerate diffusion limit can be obtained; Drost and Werker (1996), concerning the diffusion limits of weak GARCH process; and Duan (1997), who inter alia derives the system of stochastic differential equations in which a unified version of GARCH processes—an extension to the formulation of Hentschel (1995)—converge.
The main common result arising from the aforementioned literature is that in the limit the endogeneity of volatility is not retained. This means that all the endogenous (GARCH type) volatility models weakly converge to continuous time stochastic volatility processes. Conditional variance endogeneity is information that is lost upon the application of the functional central limit theorems. Naturally, it is not restored even when the latter are approximated by standard discretization schemes except for degenerate cases (Corradi, 2000).
An important member of the collection of these processes that cannot be nested in the aforementioned works remains unexplored as far as weak convergence theory is concerned. It is the quadratic GARCH (GQARCH) model of Sentana (1995), whose weak limit concerns the present paper.
The quadratic GARCH model was introduced in an attempt to capture the dynamically asymmetric nature of the empirical finite sample distributions of the stock market returns,2
The aforementioned asymmetry is exhibited through the significant and negative sample autocorrelation of the process and its squares at different epochs (i.e., ρ(yt2, yt+k) < 0 for k > 0). Part of this correlation is theoretically attributed to the so-called leverage effect.
The paper is organized as follows. In the next section the discrete time model, its approximating sequence of models, and its diffusion limit are presented in Theorem 1. The approximating invariant probability density for the conditional variance is derived in Theorem 2, in the cases of the quadratic and the conditionally asymmetric GARCH parametrization. The analogous probability density for the level process itself is also derived in the latter case. The last section contains the conclusion and the statement of some possible extensions of the procedure. All proofs are included in the Appendix.
2. THE TVP-GQARCH(1,1) DIFFUSION LIMIT
2.1. The Discrete Time Model
Let us now consider the following TVP-GQARCH-M(1,1) model:


Equation (1) specifies the dynamics of the conditional mean of the process yt (or equivalently of the process rt = Δyt). A transformation of the conditional variance process (i.e., ht in the power of μ, a parameter that takes values in the nonextended real line) enters the mean specification, whereas the parameter of htμ is defined as a standard AR(1) process with mean δ (hence the abbreviation TVP [time varying parameter]). This allows us to obtain a range of behaviors for the TVP, nested in this parameterization, through restrictions on vector Φ = (δ, φ, φu)′. Thus, we can obtain the usual GQARCH(1,1) process by letting Φ = 0′, or constancy of the parameter for Φ = (δ,0,0)′, etc.
Equation (2) describes the dynamics of the conditional variance process. The asymmetry parameter γ can be of either sign (it is obvious that for γ = 0 the model collapses to the standard GARCH(1,1) model). For γ < 0, ht is augmented when zt−1 is negative, something that corresponds to the aforementioned empirical observation of the dynamic asymmetry phenomenon for the financial returns, partially attributed to the leverage effect. The conditional variance process remains positive and nondegenerate if the matrix

is positive definite, whereas the weak (second-order) stationarity condition for the same process is simply a + β < 1 (Sentana, 1995).
3No extra positivity constraints are needed when conditional variance is parameterized as ht =

. Then we have that ω = ω* + aγ*2 and γ = 2aγ*.
Weak convergence can be established through the imposition of relevant asymptotic order conditions on the truncated first and second conditional moments of the sequence of processes. It is evident from the preceding discussion that the underlying moments need not exist.
Relation (4) defines the distributional assumption for the state variable processes of the model, i.e., zt,ut, without explicitly prescribing a particular distribution (yet, as we shall see, the existence of higher moments for at least zt will be needed). It also describes their temporal and mutual independence. It is evident though, that the mild semiparametric assumption imposed results in more flexible dynamic structures than those derived by Nelson (1990). The terms D1 and D2 are two probability distributions that do not necessarily coincide.5
It is perhaps useful to note that results concerning the statistical (local) identification of TVP-GARCH-M models can be found in Demos (2000).
Finally, (5) specifies the filtration of the discrete time system, i.e., (It)t=0,1,…. It is composed of the corresponding paths of the state variables. By definition the conditional variance process and also the TVP are adapted to (It−1).
2.2. The Main Result
Remember that in this section we are interested in the pointwise convergence of the finite-dimensional distributions of a sequence of discrete time stochastic processes to the analogues of a system of Itô's diffusions living in C([0,∞), Rd). This convergence is by construction associated with a finite time span.
For the model described in equations (1)–(4) a sequence of stochastic models as n augments (s diminishes) is given by


Also let rks(n) = Δyks(n). The weak convergence results are summarized in the following theorem.
THEOREM 1. Under the assumption that E(zt4) < ∞, as n → ∞ (s → 0), for

, γs = γ, δs = δ, φs = φs + 1, φus = φu, and θ ∈ R, the system described by equations (6)–(8) converges weakly to the following system of stochastic differential equations:


and

where σ3 and σ4 are, respectively, the skewness and kurtosis of zt, W1t,W2t,W3t are three independent Wiener processes,

is a probability measure on (R3, B(R3)), and ∞ is a 3 × 1 vector of infinities. Also |·| denotes the supremum norm of a d-dimensional vector.
First, the ht and δt processes are adapted to the

continuous time filtrations, respectively. These are defined as
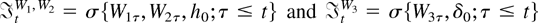
. Notice that yt is by construction adapted to

. For

to satisfy the usual conditions, it is necessary to endow

with the P-null sets of
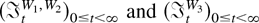
A filtration

is said to satisfy the usual conditions if it is right continuous and

contains the P − null sets of

.
The latter is needed for weak solutions of (9)–(11) to be definable. Note that in our asymptotic context we are not interested in the existence of strong (pathwise) unique solutions for the diffusions established earlier. Therefore, global Lipschitz conditions on the drift and diffusion functions are irrelevant. Weaker conditions that guarantee weak (appropriate distributional) existence and uniqueness—i.e., that the system admits weak solutions (see, e.g., Stroock and Varadhan, 1979)—are reviewed in Nelson (1990).
Second, because of the aggregation effect (Drost and Werker, 1996), we cannot interpret hk(n) for n > 1 and the limit ht as conditional variance processes but only can interpret them as processes whose moments are “close” to those of the original variance process. However, if we commence our analysis from the continuous time framework, it is clear that the system in (9)–(11) specifies the dynamics of a continuous time stochastic volatility model. This process is stochastically driven by the three state variables W1t,W2t, and W3t. Dynamic asymmetry is induced via the QARCH parameter γ and/or σ3. Nonnullity of these parameters results in the contemporaneous correlation between the mean and the variance process through the W1t state variable.
The main result of this section coincides with the overall result of this literature. An endogenous volatility model in a continuous time framework cannot be obtained as the weak limit of a discrete time endogenous volatility process.
The process consisting of the solution of the Langevin-type equation (11) is identified as a mean reverting Ornstein–Uhlenbeck process. It is also simple to verify that when μ = 1, φ = 0, φu = 0, zt ∼ N(0,1) and therefore σ3 = 0, σ4 = 3 the system reduces to

whereas for γ = 0 the system reduces to the well-known result of Nelson (1990) and Duan (1997).
Also, it is trivial to verify the validity of the results of Nelson (1990) and Corradi (2000) concerning the Euler discretization of the system in (9)–(11). In the case of a degenerate volatility diffusion (i.e., when a = γ = 0), and because of the fact that (dyt)2 = ht dt, the Euler approximation conveys a symmetric GARCH structure identical to the one in equation (22) of Corradi (2000). When the volatility diffusion is nondegenerate (i.e., when a and/or γ ≠ 0), the approximation consists of a discrete time stochastic volatility model, which determines dynamic asymmetry in the same way as the continuous time model does.
Finally, let us briefly discuss the issue of statistical identification of the system in (9)–(11). It is clear that the simultaneous presence of the parameters a, σ3, and σ4 in (10) results in nonidentifiability of the underlying statistical model. Therefore, our semiparametric framework is only useful when analyzing the properties of this process. When it comes to estimation and inference this framework has to be strengthened.7
Even in this case estimation and inference in a continuous time model with two latent variables ht and δt is at least a computationally demanding task.
2.3. Convergence of Invariant Distributions
In this section we are interested in the convergence of the stationary distributions (when they exist) of the GQARCH process. Note that the convergence of finite-dimensional distributions established previously guarantees the former (along with assumptions concerning convergence in distribution at time 0) only in the case when t (i.e., ks) remains fixed as s ↓ 0. When t is allowed to go to infinity, Theorem 1 does not guarantee the desired result. As Nelson (1990) points out, tightness of the underlying sequence of processes is also needed. Conditions that ensure it can be found in Kushner (1983).
Following Nelson (1990), we use the Fokker–Planck (the second Kolmogorov, or “forward”) equation (Skorohod, 1996; Karatzas and Shreeve, 1991) to obtain the invariant distribution of (10).
The results are stated within the following theorem in two parts. This will demonstrate that the two different methods of specification of the dynamic asymmetry (i.e., the asymmetric conditional or the QARCH parameterization) will naturally result in distinct processes. The symbol

denotes convergence in distribution of random variables.
THEOREM 2. A. For the process defined in equation (10), under the additional assumption of σ3 = 0 and γ ≠ 0, l ≠ 0, 2θ/l > −1 we have that

Also if 2ω/(2θ + l)h0 [bsim ] F(4ω/γ2, 4θ/l + 2) then for all t ≥ 0

where F(·,·) denotes the F distribution and l = (a/2)2(σ4 − 1). For the sequence hks(n) if in addition, (i)
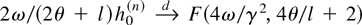
and (ii) the sequence {ωs, as, βs, γs}s↓0 is as defined in Theorem 1, then for fixed ks as s ↓ 0

Finally, if (ii) holds and (iii) there is a d > 0 : E [sup((h0(n))d)] < ∞, then as ks → ∞ as s ↓ 0
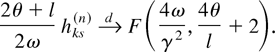
B. For the process defined in equation (10), under the assumption of γ = 0 and 2ω/l > 0, 2θ/l > −1, we have that

whereas for φ = φu = 0, μ = 1, for the process

we have that

Also, if h0 [bsim ] RΓ(2θ/l + 1, 2ω/l) then for all t ≥ 0

and

Here T(·,·,·,·) denotes the skewed Student's t-distribution and RΓ(·,·) denotes the reciprocal (inverted) gamma distribution. Also for the sequence hks(n) if in addition, (i)′
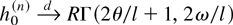
and (ii) hold, then for fixed ks as s ↓ 0


Finally, if (i)′, (ii), and (iii) hold then as ks → ∞ as s ↓ 0

In the additional case where δ = 0, we are able to prove the following corollary.
COROLLARY 1. When δ = 0

Also if 2ω/(2θ + l)h0 [bsim ] RΓ(2θ/l + 1, 2ω/l) then for all t ≥ 0

Here tν is the Student's t-distribution with ν degrees of freedom. Also under (i)′, (ii), and for fixed ks as s ↓ 0


if (i)′, (ii), and (iii) hold then as ks → ∞ as s ↓ 0

The result in part A of Theorem 2 indicates that when dynamic asymmetry is induced via the parameter γ, a linear transformation of the conditional variance converges in distribution to a random variable following an F-distribution. This is a new result. The asymmetry parameter clearly affects the tails of the distribution of the volatility and therefore of the whole process.
It is straightforward that 2ω/(2θ + l)ht−1 [bsim ] F(4θ/l + 2, 4ω/γ2). Therefore, if γ → 0, we have that 2ω/(2θ + l)ht−1 [bsim ] F(4θ/l + 2, 4ω/γ2) → G(2θ/l + 1, 2θ/l + 1) where G(·,·) denotes the gamma distribution. Finally, it is clear that ht [bsim ] RΓ(2θ/l + 1, 2ω/l), which is in accordance with the results in part B. Clearly when additionally σ4 = 3, Nelson's result is upheld.
Part B of Theorem 2 explores the situation when dynamic asymmetry is induced only via an asymmetric conditional. In this case conditional variance converges to a reciprocal (inverted) gamma distribution.8
The abbreviation RΓ(·,·) is preferred to the IG(·,·), because the latter might be confused with the inverse Gaussian distribution (see Barndorff-Nielsen and Shephard, 2001).
Both the previous results hold even for θ < 0 (within a bounded interval). This is in accordance with the strict stationarity property of the GARCH(1,1) model, even in neighborhoods of the parameter space where second-order stationarity is lost.
The reciprocal gamma distribution belongs to the family of the generalized inverse Gaussian distributions (abbreviated as GIG(·,·,·)). Specifically we have that

. The latter is infinitely divisible. Hence the continuous time volatility process (10) is equal in distribution to an Ornstein–Uhlenbeck process with respect to an appropriate Levy process (the background driving levy process [BDLP]), as the results of Barndorff-Nielsen and Shephard (2000) indicate. Moreover, the Ornstein–Uhlenbeck type of drift of (10) ensures that the correlation function of (the continuous time) ht is the same as that of the latter Ornstein–Uhlenbeck–Levy type process.
Part B of Theorem 2 also deduces the invariant distribution of the standardized continuous time process rt* when the mean parameter process δt is constant. This is a skewed Student's t-distribution, which is a special case of the generalized hyperbolic distribution (abbreviated as GH(·,·,·,·,·)). More specifically, we have that

. Note that the mean parameter

is controlling for the marginal asymmetry. In a theory of finance context, δ is associated with the price of risk, which is positive under risk aversion. Therefore this model cannot accommodate is negative skewness, which frequently present in samples of financial excess returns.
The generalized hyperbolic family is also infinitely divisible. From the results of Barndorff-Nielsen (1997) we have that

, which in turn is for δ = 0 a

, where q(·) is as in Theorem 2. This distribution could be useful for filtering purposes.
Corollary 1 shows that Theorem 2 nests the analogous results of Nelson (1990).
3. CONCLUSION
This paper presents results on the issue of weak convergence of a TVP-GQARCH-M(1,1) process. This type of convergence allows us to obtain approximate information on noninferable characteristics of the process. Our results confirm the general findings of the relevant literature. These suggest that the weak limits of the endogenous volatility models are exogenous (stochastic) volatility continuous time processes.
Under the appropriate assumptions, we present the invariant distributions at which the process converges in various cases. These suggest an approximate distributional relation between the GARCH or the asymmetric GQARCH conditional variance processes and the continuous time Ornstein–Uhlenbeck models with respect to appropriate nonnegative Levy processes.
Furthermore, as a result of the Ornstein–Uhlenbeck type of drift of the diffusions at which the former variance precesses converge, their correlation function also converges to that of the aforementioned Ornstein–Uhlenbeck–Levy processes. A closer examination of the common characteristics of these two distinct modeling methodologies could be the subject of further research.
Finally, our results suggest that the discrete time GQARCH process can be used for the estimation of the continuous time process to which it converges weakly. More specifically, the discrete time endogenous volatility process can be considered as a natural auxiliary model for the estimation of the parameters of the continuous time diffusion system, in the framework of the indirect inference principle (see, e.g., Gourieroux, Monfort, and Renault, 1993). Note here that the more efficient choice of the Euler discretization as an auxiliary model is undermined by the stochastic volatility structure of the latter, and therefore its burdensome likelihood-based estimation.
APPENDIX
Proof of Theorem 1. To establish the distributional limit of the process described in (6)–(8) we will rely on the verification of Assumption 5 in Nelson (1990). We first assume that the density D1 possesses finite moments up to the fourth order. Then (4) would imply for the sequence that zks(n) [bsim ] D1(0, s), uks(n) [bsim ] D2(0, s), σ3 = E((zks(n))3)/[E((zks(n))2)]3/2, and σ4 = E((zks(n))4)/[E((zks(n))2)]2 (i.e., σ3 and σ4 denote the unconditional skewness and kurtosis, respectively, that are naturally independent of s). Following the derivation of Nelson (1990) we will establish the drift b(xt, t) and diffusion σ(xt, t) of a system of the form
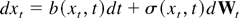
where

and W1t, W2t, W3t are three independent standard Wiener processes. To establish b(xt, t) and a(xt, t) = σ(xt, t)σT(xt, t) we consider the following limits (for

:

where

and therefore

whereas

. It is also trivial to verify that

Tedious algebra shows that the Kolmogorov condition concerning the continuity of the limiting process is verified because
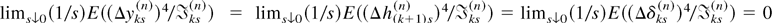
. Therefore we have established that

A Cholecky decomposition of a(xt, t) gives that
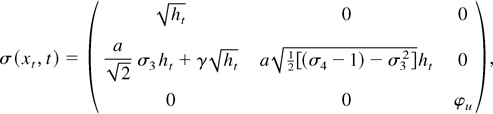
leading therefore to (9)–(11). Note that although the preceding factorization is not unique, it leads to probability measures with identical distributions. Now for the aforementioned system to be the desired limit process we also need to establish its weak (distributional) existence and uniqueness (Stroock and Varadhan, 1979, Ch. 6). Weak uniqueness concerning the processes in (9)–(11) is proved along the lines of Nelson (1990). The term ht is transformed into Vt = ln(ht) and after the application of Itô's lemma, Condition B in Nelson (1990, Appendix A) is easily checked. Existence is verified by the analogous nonexplosion condition of Nelson (1990). █
Proof of Theorem 2. First, we concentrate on equation (10). Our purpose is to derive the stationary distribution for the solution of the aforementioned equation. This can be written as

and then we can use the Fokker–Planck (second Kolmogorov) equation (see, e.g., Karatzas and Shreeve, 1991; Skorohod, 1996), which states that the transition probability p(t, x) of a diffusion of the form dx = b(t, x)dt + σ(t, x)dWt—where a(t, x) is a n-dimensional vector function, b(t, x) is a n × k matrix function, and Wt is a k-dimensional Wiener process—is given by

which for the stationary distribution p*(x) = limt→∞(∂p(x, t)/∂t) = 0 becomes

Let us denote by l = (a/2)2(σ4 − 1).
Part A. Suppose first that σ3 = 0. Then

We have that

The first integral is given by (2.154) in Gradshteyn et al. (1994), whereas the second is solved via the substitution u = (lh + γ2).
Therefore p*(h) = c(h(2ω/γ2)−1/(lh + γ2)(2ω/γ2)+(2θ/l)+1). We have that

with

for 0 < (2θ/l) + 1, l ≠ 0 from (3.241.4) and (8.384.1) in Gradshteyn et al. (where B(·,·) is the beta function). Therefore p*(h) = [(γ2)(2θ/l)+1l2ω/γ2/B(2ω/γ2,(2θ/l) + 1)][h(2ω/γ2)−1/ (lh + γ2)(2ω/γ2)+(2θ/l)+1].
Using the transformation u = [(2θ + l)/2ω]h and Theorem 8.12 in Davidson (1994) we obtain (14). Expression (15) follows immediately.
Part B. Now let us consider the case of σ3 ≠ 0 but γ = 0. The Fokker–Planck equation becomes
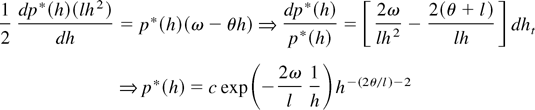
with

and therefore
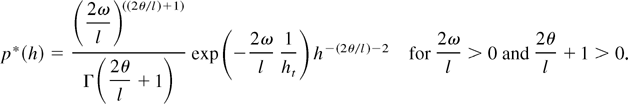
and (18) is proved.
Expression (19) follows from Barndorff-Nielsen and Shephard (2001, paragraph 2.3.1) if we consider (for δt = δ and μ = 1 and
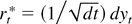
the previous result and the fact that

. Notice that we have that

where
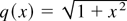
, ν(x) = xνKν(x), and Kν(·) is the modified Bessel function. Expressions (20) and (21) follow immediately.
Now for both Part A and B of the underlying theorem (16), (22), and (23) follow directly from Theorem 1, the fact that ks is fixed, and conditions (i)′ and (ii)′ and also from (15), (20), and (21), respectively. This is due to the fact that Theorem 1 applies for finite t (see Ethier and Kurtz, 1986, Nelson, 1990). All of this ensures convergence of marginals. Therefore

, and the result follows from the continuous mapping theorem. When ks → ∞ (17) and (24) follow from Nelson (1990) and Kushner (1983) if we can prove that the discrete time sequence hks(n) is tight. Tightness for hks(n) is proved along the lines of Nelson (1990). █
Proof of Corollary 1. Expressions (25), (26), and (27) follow from Theorem 2 if we consider the limδ→0 p(r*) and note that

where [bsim ] now denotes asymptotic equivalence. Then (28) follows from the fact that

is independent and identically distributed (i.i.d.), standard normal and independent of hks(n) ∀s exactly as in Nelson (1990), relation (2.45). Finally, (29) follows from the tightness of

, which is ensured from the fact that

is i.i.d., standard normal and independent of hks(n), exactly as in Nelson (1990), relation (2.47). █
References
REFERENCES
Barndorff-Nielsen, O.E.
(1997)
Normal inverse Gaussian distributions and stochastic volatility
modelling.
Scandinavian Journal of Statistics
24,
1–13.Google Scholar
Barndorff-Nielsen, O.E. &
N. Shephard
(2001)
Non-Gaussian based models and some of their uses in financial
econometrics.
Journal of the Royal Statistical Society, Series B
63,
167–241.Google Scholar
Barndorff-Nielsen, O.E. &
N. Shephard
(2001)
Modelling by Levy processes for financial econometrics. In
O.E. Barndorff-Nielsen,
T. Mikosch, &
S. Resnick (eds.),
Levy Processes-Theory and Applications, pp.
283–318.
Birkhauser.
Bollerslev, T.
(1986)
Generalized autoregressive conditional heteroskedasticity.
Journal of Econometrics
31,
307–327.Google Scholar
Corradi, V.
(2000)
Reconsidering the continuous time limit of the GARCH(1,1) process.
Journal of Econometrics
96,
145–153.Google Scholar
Davidson, J.
(1994)
Stochastic Limit Theory: Advanced Texts in Econometrics.
Oxford University Press.
Demos, A.
(2000)
The Autocorrelation Function of Conditionally Heteroskedastic in
Mean Models.
Discussion paper 2000-07,
Department of International and European Economic Studies, Athens
University of Economics and Business.
Drost, F.C. &
T.E. Nijman
(1993)
Temporal aggregation of GARCH processes.
Econometrica
61,
909–1027.Google Scholar
Drost, F.C. &
B.J.M. Werker
(1996)
Closing the GARCH gap: Continuous time GARCH modelling.
Journal of Econometrics
74,
31–57.Google Scholar
Duan, J.-C.
(1997)
Augmented GARCH(p,q) process and its diffusion
limit.
Journal of Econometrics
79,
97–127.Google Scholar
Engle, R.F.
(1982)
Autoregressive conditional heteroskedasticity with estimates of the
variance of United Kingdom inflation.
Econometrica
50,
987–1007.Google Scholar
Ethier, S.N. &
T.G. Kurtz
(1986)
Markov Processes: Characterization and Convergence.
Wiley.
Gourieroux, C.,
A. Monfort, &
E. Renault
(1993)
Indirect inference.
Journal of Applied Econometrics
8,
85–118.CrossRefGoogle Scholar
Gradshteyn, I.S. &
I.M. Ryznik
(1994)
Table of Integrals, Series, and Products,
5th ed.
Academic Press.
Hentschel, L.
(1995)
All in the family: Nesting Symmetric and Asymmetric GARCH models.
Journal of Financial Economics
39,
71–104.Google Scholar
Karatzas, I. &
E.S. Shreeve
(1991)
Brownian Motion and Stochastic Calculus,
2nd ed.
Springer-Verlag.
Kushner, H.J.
(1983)
Approximation and Weak Convergence Methods for Random Processes
with Applications to Stochastic Systems Theory.
MIT Press.
Nelson, D.
(1990)
ARCH models as diffusion approximations.
Journal of Econometrics
45,
97–127.Google Scholar
Skorohod, A.V.
(1996)
Lectures on the Theory of Stochastic Processes.
Trans-Atlantic Publications.
Stroock, D.W. &
S.R.S. Varadhan
(1979)
Multidimensional Diffusion Processes.
(corrected second printing, 1997)
Springer-Verlag.
 You have
Access
- 3
- Cited by