1. Introduction
A non-life insurance company holds at time
 $t=0$
an initial capital
 $u =X(0)\geq0$
, collects premiums at a rate
 $p(x)>0$
depending on the current level of the capital
 $X(t)=x$
, and pays compensation from time to time (when a claim is filed). The aggregated size of claims up to time
 $t>0$
is modeled by a compound Poisson process
 $(L(t),\, t\geq0)$
. That is, the number of claims is governed by a homogeneous Poisson process of intensity
 $\beta$
independent of the claims, which, in turn, form a sequence
 $U_1,U_2,\ldots$
of indedependent, identically distributed (i.i.d.) non-negative random variables with cumulative distribution function
 $B(\!\cdot\!)$
. The net worth of the insurance company is then given by a continuous-time stochastic process
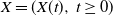 $X = (X(t),\,t \ge 0)$
, with
 \begin{equation}X(t) = u+\int_0^{t}p(X(s))\,\mathrm{d}s-\sum_{k=1}^{N(t)}U_k=u+\int_0^{t}p(X(s))\,\mathrm{d}s-L(t),\quad t \ge 0.\end{equation}
Examples of this level-dependent premium rate include the insurance company downgrading the premium rate from
 $p_1$
to
 $p_2$
when the reserves reach a certain threshold, or incorporating a constant interest force,
 $p(x)=p+ix$
. In this paper a more general risk model is considered. The surplus (1) is perturbed by a Brownian motion
 $\{W(t) , \, t\geq0\}$
, multiplied by a diffusion parameter
 ${\sigma}$
, to account for the fluctuations around the premium rate. This diffusion parameter may also depend on X(t). Further, we let the accumulated liability L(t) be governed by a pure-jump, non-decreasing Lévy process, starting from
 $L(0) = 0$
. The financial reserves of the insurance company evolve according to the following dynamics:
 \begin{equation}\mathrm{d}X(t)= p(X(t))\,\mathrm{d}t+\sigma(X(t))\,\mathrm{d}W(t)-\mathrm{d}L(t),\quad X(0) = u.\end{equation}
In risk theory, one of the main challenges is the evaluation of ruin probabilities. The probability of ultimate ruin is the probability that the reserves ever drop below zero:
 \begin{equation}\psi(u) := {\mathbb P}\Bigl(\inf_{t \ge 0}X(t) \le 0\Bigr).\end{equation}
We stress dependence of
 $\psi$
on the initial capital u. The probability of ruin by time T is defined as
 \begin{equation}\psi(u, T) := {\mathbb P}\Bigl(\inf_{0 \le t \le T}X(t) \le 0\Bigr).\end{equation}
We often refer to
 $\psi(u)$
and
 $\psi(u,T)$
as infinite- and finite-time horizon ruin probability, respectively. For a comprehensive overview on risk theory and ruin probabilities, see the book [Reference Asmussen and Albrecher3].
We study the rate of exponential convergence of the finite-time horizon ruin probability toward its infinite-time counterpart. The goal of this paper is to provide an explicit estimate for this rate: to find constants
 $C, k > 0$
such that
 \begin{equation}0 \le \psi(u) - \psi(u, T) \le C\,{\mathrm{e}}^{-kT}\quad \text{for all}\ T, u \ge 0.\end{equation}
This is achieved via a duality argument. For the original model (1), define the storage process
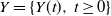 $Y=\{Y(t), \, t\geq0\}$
as follows:
 \begin{equation}Y(t)=L(t)-\int_{0}^{t}p(Y(s))\,{\mathrm{d}} s.\end{equation}
We assume that
 $p(\,y) = 0$
for
 $y < 0$
. This makes zero a reflecting barrier. This is essentially a time-reversed version of the risk model (1), reflected at 0. For the general model (2) perturbed by Brownian motion, the dual process is a reflected jump-diffusion on the positive half-line. As
 $t \to \infty$
, Y(t) weakly converges to some distribution
 $Y(\infty)$
. The crucial observation is as follows: for
 $T > 0$
and
 $u \ge 0$
,
 \begin{equation*}{\mathbb P}(Y(T) \ge u) = \psi(u, T),\quad {\mathbb P}(Y(\infty) \ge u) = \psi(u).\end{equation*}
This is a particular case of Siegmund duality; see Siegmund [Reference Siegmund32]. This method was first employed in [Reference Lévy17] for the similar duality between absorbed and reflected Brownian motion. It has become a standard tool in risk theory since the seminal paper of Prabhu [Reference Prabhu25]; see also [Reference Asmussen and Albrecher3, Chapter III, Section 2]. Problem (5) therefore reduces to the study of the convergence of Y(t) toward
 $Y(\infty)$
as
 $t \to \infty$
:
 \begin{equation*}0 \le \mathbb{P}(Y(\infty)>u) - {\mathbb P}(Y(T) \ge u) \le C\,{\mathrm{e}}^{-kT}.\end{equation*}
In this paper, in Lemma 6, we state and prove Siegmund duality between the process (1) and a certain reflected diffusion with additional Lévy term. We believe this is a contribution to the theory of Siegmund duality. There exist many similar Siegmund duality results [Reference Jansen and Kurt11, Reference Kolokoltsev15, Reference Kolokoltsev and Lee16, Reference Sigman and Ryan33], but we could not find exactly the one we need, so we have proved it ourselves.
A stochastically ordered real-valued Markov process
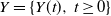 $Y = \{Y(t), \, t\geq0\}$
is such that, for all
 $y_1 \ge y_2$
, we can couple two copies
 $Y_1(t)$
and
 $Y_2(t)$
of Y(t) starting from
 $Y_1(0) = y_1$
and
 $Y_2(0) = y_2$
, in such a way that
 $Y_1(t) \ge Y_2(t)$
a.s. for all
 $t \ge 0$
. A Lyapunov function for a Markov process with generator
 $\mathcal L$
is, roughly speaking, a function
 $V \ge 1$
such that
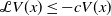 $\mathcal L V(x) \le -cV(x)$
for some constant
 $c > 0$
, for all x outside a compact set. Then we can combine this coupling method with a Lyapunov function to get a simple, explicit, and in some cases, sharp estimate for the rate k. This method was first applied by Lund and Tweedie [Reference Lund and Tweedie18] for discrete-time Markov chains and by Lund, Meyn, and Tweedie [Reference Lund, Meyn and Tweedie19] for continuous-time Markov processes. A direct application of their results yields the rate of convergence for the storage process defined in (6) and the level-dependent compound Poisson risk model (1). However, the dual model associated to the risk process (2) is a more general process since it is a reflected jump-diffusion on the positive half-line.
The same method as in [Reference Lund, Meyn and Tweedie19] has been refined in a recent paper by Sarantsev [Reference Sarantsev29] and applied to reflected jump-diffusions on the half-line. The jump part is not a general Lévy process but rather a state-dependent compound Poisson process, which makes a.s. finitely many jumps in finite time. In a recent paper [Reference Ichiba and Sarantsev10], it was applied to Walsh diffusions (processes which move along the rays emanating from the origin in
 ${\mathbb{R}}^d$
as one-dimensional diffusions; as they hit the origin, they choose a new ray randomly). Without attempting to give an exhaustive survey, let us mention the classic papers [Reference Down, Meyn and Tweedie7], [Reference Meyn and Tweedie20], and [Reference Meyn and Tweedie21], which use Lyapunov functions (without stochastic ordering) to prove the very existence of exponential long-term convergence, and a related paper by Sarantsev [Reference Sarantsev30]. However, estimation of the rate k is more difficult. Some partial results in this direction are provided in [Reference Bakry, Cattiaux and Guillin5], [Reference Davies6], [Reference Meyn and Tweedie22], [Reference Roberts and Rosenthal26], [Reference Roberts and Tweedie27], and Reference Roberts and Tweedie28].
In this paper we combine these two methods – Lyapunov functions and stochastic ordering – to find the rate of convergence of the process Y, which is dual to the original process X from (2). This process Y, as noted above, is a reflected jump-diffusion on the half-line. We apply the method developed in [Reference Lund, Meyn and Tweedie19] and [Reference Sarantsev29]. In the general case, it can have infinitely many jumps during finite time, or it can have no diffusion component, as in the level-dependent compound Poisson risk model from (1). Therefore we need to adjust the argument from [Reference Sarantsev29]. Our method only applies in the case of light-tailed claim size. Asmussen and Teugels [Reference Asmussen and Teugels4] studied the convergence of ruin probabilities in the compound Poisson risk model with sub-exponentially distributed claim size. It is shown that the convergence takes place at a sub-exponential rate.
The paper is organized as follows. In Section 2 we define assumptions on p,
 $\sigma$
, and the Lévy process L. We also introduce the concept of Siegmund duality to reduce the problem to convergence rate of a reflected jump-diffusion to its stationary distribution. Our main results are stated in Section 3: Theorem 2 and Corollary 1 provide an estimate for the exponential rate of convergence. Section 4 gives examples of calculations of the rate k. The proof of Theorem 2 is carried out in Section 5. Proofs of some technical lemmas are postponed to the Appendix.
2. Definitions and Siegmund duality
First, let us impose assumptions on our model (2). Recall that the wealth of the insurance company is modeled by the right-continuous process with left limits
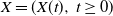 $X = (X(t),\, t \ge 0)$
, governed by the integral equation
 \begin{align}X(t) = u + \int_0^tp(X(s))\,{\mathrm{d}} s + \int_0^t{\sigma}(X(s))\,{\mathrm{d}} W(s) - L(t)\end{align}
or, equivalently, by the stochastic differential equation (SDE) with initial condition
 $X(0) = u$
, given by (2). We say that X is driven by the Brownian motion W and Lévy process L. A function
 $f \colon {\mathbb{R}} \to {\mathbb{R}}$
, or
 $f \colon {\mathbb{R}}_+ \to {\mathbb{R}}$
, is Lipschitz-continuous (or simply Lipschitz) if there exists a constant K such that
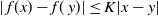 $|\,f(x) - f(\,y)| \le K|x-y|$
for all x, y.
Assumption 1. The function
 $p \colon {\mathbb{R}}_+ \to {\mathbb{R}}$
is Lipschitz. The function
 ${\sigma} \colon {\mathbb{R}}_+ \to {\mathbb{R}}_{+}$
is bounded, and continuously differentiable with Lipschitz-continuous derivative
 ${\sigma}'$
.
Assumption 2. The process L is a pure-jump subordinator, that is, a Lévy process (stationary independent increments) with
 $L(0) = 0$
, and with a.s. non-decreasing trajectories, which are right-continuous with left limits. The process W is a standard Brownian motion, independent of L.
Assumption 1 is not too restrictive as it allows us to consider classical risk process such as (a) the compound Poisson risk process when
 $p(x)=p$
and
 $\sigma(x)=0$
, or (b) the compound Poisson risk process under constant interest force when
 $p(x)=p+ix$
and
 $\sigma(x)=0$
. However, the regime-switching premium rate when the surplus hits some target is not covered. Assumption 2 allows the study of the compound Poisson risk process perturbed by a diffusion when
 $p(x)=p$
and
 $\sigma(x)=\sigma$
, extensively discussed in the paper by Dufresne and Gerber [Reference Dufresne and Gerber8], as well as the Lévy-driven risk processes defined for example by Furrer [Reference Furrer9] or Morales and Schoutens [Reference Morales and Schoutens24]. It is known from the standard theory (see e.g. [Reference Karatzas and Shreve13, Section 6.2]) that the Lévy measure of this process is a measure
 $\mu$
on
 ${\mathbb{R}}_+$
which satisfies
 \begin{equation}\int_0^{\infty}(1\wedge x)\,\mu({\mathrm{d}} x) < \infty.\end{equation}
Therefore, for all
 $c > 0$
we have
 \begin{equation*}\mu[c, \infty) < \infty\quad \text{and}\quad \int_0^cx\,\mu(\mathrm{d}x) < \infty.\end{equation*}
When
 $\mu(\mathbb R_+) = \infty$
, there are infinitely many jumps on any finite-time interval. If
 $\mu(\mathbb R_+) < \infty$
and thus the Lévy measure is finite, then there are finitely many jumps in a finite-time interval, and we simply have a compound Poisson process: times between jumps form i.i.d. exponential random variables with rates
 $\mu(\mathbb R_+)$
, and the displacement during each jump is distributed according to the normalized measure
 $[\mu(\mathbb R_+)]^{-1}\mu(\!\cdot\!)$
. From Assumption 2, we have
 \begin{equation}{\mathbb E} \,{\mathrm{e}}^{-\lambda L(t)} = \exp (t\kappa(-\lambda)) \quad \text{for every}\ t, \lambda \ge 0,\end{equation}
where
 $\kappa(\lambda)$
is the Lévy exponent:
 \begin{equation*} \kappa(\lambda) := \int_0^{\infty} [{\mathrm{e}}^{\lambda x} - 1] \mu({\mathrm{d}} x),\quad \lambda \in {\mathbb{R}}.\end{equation*}
As shown in [Reference Appelbaum1, Theorem 3.3.15], applied to the case
 $b = 0$
and
 $X(t) \equiv t$
(in the notation of that book), under Assumption 2, L is a Feller-continuous strong Markov process, with generator
 \begin{equation}\mathcal N f(x) = \int_0^{\infty} [\,f(x+y) - f(x)]\,\mu({\mathrm{d}} y)\end{equation}
for
 $f \in C^{\infty}({\mathbb{R}})$
with a compact support. We impose an additional assumption.
Assumption 3. The measure
 $\mu$
has finite exponential moment: for some
 $\lambda_0 > 0$
,
 \begin{equation}\int_1^{\infty}\,{\mathrm{e}}^{\lambda_0 x}\,\mu({\mathrm{d}} x) < \infty.\end{equation}
Remark 1. The existence of exponential moments on the jump size distribution prevents us from considering heavy-tailed claim size distribution; see [Reference Sato31, Chapter 5]. This case is treated in the work of Asmussen and Teugels [Reference Asmussen and Teugels4] or Sato [Reference Sato31].
Under Assumption 3, we can combine (8) and (11) to get
 \begin{equation*}\kappa(\lambda) < \infty \quad \text{for}\ \lambda \in [0, \lambda_0).\end{equation*}
Proofs of the following technical lemmas are postponed to the Appendix.
Lemma 1. Under Assumption 3, we can extend the formula (10) for functions
 $f \in C^{\infty}({\mathbb{R}})$
which satisfy
 \begin{equation}C_f := \sup_{x \ge 0}\,{\mathrm{e}}^{-\lambda x}|\,f(x)| < \infty\quad {for\ some}\ {\lambda} \in (0, {\lambda}_0).\end{equation}
Lemma 2. Under Assumptions 2 and 3, the following quantity is finite:
 \begin{equation}m(\mu) := \int_0^{\infty}x\,\mu({\mathrm{d}} x) < \infty.\end{equation}
Example 1. If
 $\{L(t),\, t \ge 0\}$
is a compound Poisson process with jump intensity
 $\beta$
and distribution B for each jump, then the Lévy measure is given by
 $\mu(\!\cdot\!) = \beta B(\!\cdot\!)$
.
The following lemma can be proved by a classic argument, a version of which can be found in any textbook on stochastic analysis; see for example [Reference Karatzas and Shreve13, Section 5.2] or [Reference Sato31, Chapter 6]. For the sake of completeness, we give the proof in the Appendix.
Lemma 3. Under Assumptions 1 and 2, for every initial condition
 $X(0) = u$
there exists (in the strong sense, i.e. on a given probability space) a pathwise unique version of (2), driven by the given Brownian motion W and Lévy process L. This is a Markov process, with generator
 \begin{equation}{\mathcal L} f(x) := p(x)f'(x) + \dfrac12{\sigma}^2(x)f''(x) + \int_0^{\infty}[\,f(x-y) - f(x)]\,\mu({\mathrm{d}} y)\end{equation}
for
 $f \in C^2({\mathbb{R}})$
with a compact support. Under Assumption 3, this expression (14) is also valid for functions
 $f \in C^2({\mathbb{R}})$
satisfying (12) with
 $f(-x)$
instead of f(x).
Define the ruin probability in finite- and infinite-time horizons as in (4) and (3). We are interested in finding an estimate of the form
 \begin{equation*}0 \le \psi(u) - \psi(u, T) \le C\,{\mathrm{e}}^{-kT},\quad u, T \ge 0,\end{equation*}
for some constants
 $C,\,k > 0$
. Recall the concept of Siegmund duality.
Definition 1. Two Markov processes
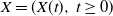 $X = (X(t),\, t \ge 0)$
and
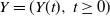 $Y = (Y(t),\, t \ge 0)$
on
 ${\mathbb{R}}_+$
are called Siegmund dual if, for all
 $t, x, y \ge 0$
,
 \begin{equation*}{\mathbb P}_x(X(t) \ge y) = {\mathbb P}_y(Y(t) \le x).\end{equation*}
Here, the indices x and y refer to initial conditions
 $X(0) = x$
and
 $Y(0) = y$
.
Siegmund duality allows us to reduce the ruin problem to a convergence problem of a reflected jump-diffusion
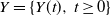 $Y=\{Y(t), \, t\geq0\}$
toward stationarity. There is a vast literature on Siegmund duality and a more general concept of functional duality of stochastic processes, both in discrete and continuous time. The earliest example of Siegmund duality was [Reference Lévy17, page 210]: absorbed and reflected Brownian motions on
 ${\mathbb{R}}_+$
are Siegmund dual. In a more general case, duality between absorbed and reflected processes was noted in [Reference Siegmund32]. Siegmund duality was studied for diffusions, jump-diffusions, and their absorbed and reflected versions, in [Reference Kolokoltsev15], [Reference Kolokoltsev and Lee16], [Reference Sigman and Ryan33], and for continuous-time discrete-space Markov chains in [Reference Zhao37]. The paper [Reference Sturm and Swart34] deals with Siegmund duality for general partially ordered spaces. See also survey [Reference Jansen and Kurt11] and references therein.
Take some functions
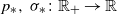 $p_{\ast},\, \sigma_{\ast} \colon \mathbb{R}_+\to\mathbb{R}$
.
Definition 2. Consider an
 ${\mathbb{R}}_+$
-valued process
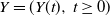 $Y = (Y(t),\, t \ge 0)$
with right-continuous trajectories with left limits, which satisfies the following SDE:
 \begin{equation}Y(t) = Y(0) + \int_0^tp_{\ast}(Y(s))\,{\mathrm{d}} s + \int_0^t\sigma_{\ast}(Y(s))\,{\mathrm{d}} W(s) + L(t) + R(t),\end{equation}
where
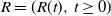 $R = (R(t),\, t \ge 0)$
is a non-decreasing right-continuous process with left limits, which starts from
 $R(0) = 0$
and can increase only when
 $Y(t) = 0$
. Then the process Y is called a reflected jump-diffusion on the half-line, with drift coefficient
 $p_{\ast}$
, diffusion coefficient
 ${\sigma}_{\ast}$
, and driving jump process
L with Lévy measure
 $\mu$
.
The following result is the counterpart of Lemma 3 for the process
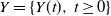 $Y=\{Y(t), \, t\geq0\}$
.
Lemma 4. If
 $p_{\ast}$
and
 ${\sigma}_{\ast}$
are Lipschitz, then for every initial condition
 $Y(0) = y$
, there exists in the strong sense a pathwise unique version of (15). This is a Markov process with generator
 ${\mathcal A}$
, such that, for
 $f \in C^2({\mathbb{R}}_+)$
with compact support and
 $f'(0) = 0$
,
 \begin{equation}{\mathcal A} f(x) = p_{\ast}(x)f'(x) + \dfrac12{\sigma}_{\ast}^{2}(x)f''(x) + \int_0^{\infty} [\,f(x +y) - f(x)]\,\mu({\mathrm{d}} y).\end{equation}
The proof, which is similar to that of Lemma 3, is provided in the Appendix. It was shown in [Reference Siegmund32] that a Markov process on
 ${\mathbb{R}}_+$
has a (Siegmund) dual process if and only if it is stochastically ordered.
Theorem 1. A Markov process X, corresponding to a transition semigroup
 $(P^t)_{t\geq0}$
, is stochastically ordered if and only if one of the following two conditions holds.
(a) The semigroup
 $(P^t)_{t \ge 0}$
maps bounded non-decreasing functions into bounded non-decreasing functions; that is, for every bounded non-decreasing
$f \colon {\mathbb{R}}_+ \to {\mathbb{R}}$
and every
$t \ge 0$
, the function
$P^tf$
is also bounded and non-decreasing.
(b) For every
$t \ge 0,\, c \ge 0$
, the function
$x \mapsto {\mathbb P}_x(X(t) \ge c)$
is non-decreasing in x.


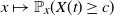
This equivalence follows from [Reference Kamae, Krengel and Brien12]. Now, consider the process (2), stopped at hitting 0. The following result is known in the literature. A proof is provided in the Appendix for the sake of completeness.
Lemma 5. The process (2) is stochastically ordered.
Our main convergence theorem relies on the following result. We have not found this exact result in the literature. A proof is given in the Appendix.
Lemma 6. Under Assumptions 1 and 2, the Siegmund dual process for the jump-diffusion (2), absorbed at zero, is the reflected jump-diffusion on
 ${\mathbb{R}}_+$
from (15), starting at
 $Y(0)=0$
, with drift and diffusion coefficients
 \begin{equation*}p_{\ast}(x) = -p(x) + {\sigma}(x){\sigma}'(x),\quad {\sigma}_{\ast}(x) = {\sigma}(x).\end{equation*}
We summarize this section as follows. We have shown that under Assumptions 1, 2, and 3, the wealth process is a stochastically ordered Markov process that admits as a Siegmund dual process a Markov process defined as a reflected jump-diffusion process. Therefore the rate of convergence for ruin probabilities coincides with that of the dual process
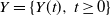 $Y=\{Y(t), \, t\geq0\}$
, associated to the risk process
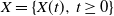 $X=\{X(t), \, t\geq0\}$
, toward stationarity.
3. Main results
A common method for proving an exponential rate of convergence toward the stationary distribution is to construct a Lyapunov function.
Definition 3. Let
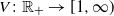 $V\colon \mathbb{R}_+\to[1,\infty)$
be a continuous function and assume there exists
 $b,k,z>0$
such that
 \begin{equation*} {\mathcal A} V(x)\leq-kV(x)+b{1}_{[0,z]}(x),\quad x\in\mathbb{R}_+.\end{equation*}
Then V is called a Lyapunov function.
We shall build a Lyapunov function for the Markov process Y in the form
 $V_{\lambda}(x)={\mathrm{e}}^{\lambda x}$
for
 $\lambda>0$
. This choice appears to be suitable to tackle the rate of convergence problem for the reflected jump-diffusion process as the generator acts on it in a simple way. Under Assumption 3, consider the function
 \begin{equation*}\phi({\lambda}, x) := p_*(x){\lambda} + \dfrac12{\sigma}^2(x){\lambda}^2 + \kappa({\lambda}),\quad {\lambda} \in[0,\lambda_0),\ x \in {\mathbb{R}}{.}\end{equation*}
For a signed measure
 $\nu$
on
 $\mathbb{R}_+$
and a function
 $f\colon \mathbb{R}_+\to\mathbb{R}$
, we let
 $(\nu, f)=\int f\mathrm{d}\nu$
. Further, for a function
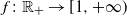 $f\colon \mathbb{R}_+\to [1,+\infty)$
, define the norm
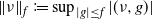 ${\lVert{\nu}\rVert}_f:= \sup_{|g| \le f}|(\nu,g)|$
. If
 $f\equiv1$
, then
 ${\lVert{\cdot}\rVert}_f$
is the total variation norm. Define
 \begin{equation*} \Phi(\lambda)=\inf_{x \ge 0}({-}\phi({\lambda}, x)) = -\sup_{x \ge 0}\phi({\lambda}, x).\end{equation*}
Theorem 2. Under Assumptions 1, 2, and 3, suppose
 \begin{equation}\Phi(\lambda) > 0\quad {for\ some}\ {\lambda} \in (0, {\lambda}_0).\end{equation}
Then there exists a unique stationary distribution
 $\pi$
for the reflected jump-diffusion Y. Take a
 ${\lambda} \in (0, {\lambda}_0)$
such that
 $k = \Phi(\lambda) > 0$
. This stationary distribution satisfies
 $(\pi, V_{{\lambda}})< \infty$
. The transition function
 $Q^t(x, \cdot)$
of the process Y satisfies
 \begin{equation*} {\lVert{Q^t(x, \cdot) - \pi(\!\cdot\!)}\rVert}_{V_\lambda} \le [V_{\lambda}(x) + (\pi,V_{\lambda})]\,{\mathrm{e}}^{-kt}.\end{equation*}
The proof of Theorem 2 is postponed to Section 5. The central result of this paper is a corollary of Theorem 2, a direct consequence of the duality link established between the processes X and Y.
Corollary 1. Under Assumptions 1, 2, and 3, and condition (17),
 \begin{equation}0 \le \psi(u) - \psi(u, T) \le [1 + (\pi, V_{{\lambda}})]\,{\mathrm{e}}^{-kT},\quad u, T \ge 0.\end{equation}
Proof. By virtue of Siegmund duality,
 \begin{equation} \psi(u) - \psi(u, T)={\mathbb P}(Y(\infty) \ge u) - {\mathbb P}(Y(T) \ge u),\end{equation}
where
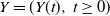 $Y=(Y(t) , \,t\geq0)$
is a reflected jump-diffusion on
 $\mathbb{R}_{+}$
, starting at
 $Y(0)=0$
, and
 $Y(\infty)$
is a random variable distributed as
 $\pi$
. We may rewrite (19) as
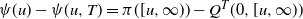 $\psi(u) - \psi(u, T)=\pi([u,\infty)) - Q^{T}(0,[u,\infty))$
. Then the inequality (18) follows immediately from the application of Theorem 2.
In the space-homogeneous case
 $p(x) \equiv p$
and
 ${\sigma}(x) \equiv {\sigma}$
, the quantity
 $\phi({\lambda}, x)$
is independent of x, and condition (17) means that there exists a
 ${\lambda} > 0$
such that
 $\phi({\lambda}) < 0$
. Then
 $p_{\ast} = p$
and
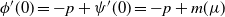 $\phi'(0) = -p + \psi'(0) = -p + m(\mu)$
. It is easy to show that
 $\phi(\!\cdot\!)$
is a convex function with
 $\phi(0) = 0$
. Therefore condition (17) holds if and only if
 $\phi'(0) < 0$
or, equivalently,
 \begin{equation*} p > m(\mu).\end{equation*}
4. Explicit rate of exponential convergence calculation
In this section we study the rate k of exponential convergence depending on the parameters of the risk model. In the examples we assume a constant premium rate that satisfies the net benefit condition with
 \begin{equation*}p=(1+\eta)\cdot\mathbb{E}[L(1)],\quad \eta>0,\end{equation*}
and a constant diffusion parameter
 $\sigma$
around the premium rate. Under these settings and for finite measure
 $\nu$
(when L is the compound Poisson process), the rate of exponential convergence derived in this work has been shown to be optimal in a certain sense; see [Reference Sarantsev29, Section 6]. However, we absolutely do not claim that for general (non-constant) premium rate p and diffusion parameter
 $\sigma$
, this exponential rate is optimal. Let us remark that the concept of optimal rate of convergence could be understood in various ways; at the very least, it depends on the distance used.
4.1. Compound Poisson risk model perturbed by a diffusion
In this subsection the risk process
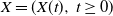 $X=(X(t), \, t\geq0)$
is defined as
 \begin{equation*}X(t)=u+pt+\sigma W(t)-\sum_{k=1}^{N(t)}U_k,\end{equation*}
where
 $u\geq0$
denotes the initial capital and p corresponds to the premium rate. The process
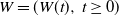 $W=(W(t), \, t\geq0)$
is a standard Brownian motion allowing us to capture the volatility around the premium rate encapsulated in the parameter
 $\sigma>0$
. The process
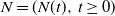 $N=(N(t), \, t\geq0)$
is a homogeneous Poisson process with intensity
 $\beta>0$
, independent of the claims
 $U_1,U_2,\ldots$
i.i.d. with distribution function B. The premium rate satisfies the net benefit condition:
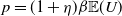 $p=(1+\eta)\beta\mathbb{E}(U)$
, where
 $\eta>0$
is safety loading.
We can study the rate of exponential convergence of ruin probabilities; specifically, how it depends on the parameters of the model: (a) the diffusion coefficient
 $\sigma$
in front of the perturbation term; (b) the safety loading
 $\eta$
; (c) the shape of the claim size distribution. The function
 $\phi({\lambda}, x)$
for this risk process is given by
 \begin{equation*}\phi({\lambda}, x) = -p{\lambda} + \dfrac12{\sigma}^2{\lambda}^2 + \beta [\widehat{B}(\lambda)-1 ],\quad {\lambda} \ge 0,\ x \in {\mathbb{R}},\end{equation*}
where
 $\widehat{B}(\lambda)=\mathbb{E}({\mathrm{e}}^{\lambda U})$
denotes the moment generating function (MGF) of the claim amount distribution. As the expression of
 $\phi({\lambda}, x)$
does not in fact depend on x, then
 \begin{equation*}\inf_{x \ge 0}({-}\phi({\lambda}, x))=\Phi(\lambda)= p{\lambda} - \dfrac12{\sigma}^2{\lambda}^2 - \beta [\widehat{B}(\lambda)-1],\quad {\lambda} \ge 0,\ x \in {\mathbb{R}}.\end{equation*}
Based on Corollary 18, we define the rate of exponential convergence by
 \begin{equation*}k=\max\{\Phi(\Lambda)\mid {\lambda}\geq0 \,;\; \widehat{B}(\lambda)<\infty\}.\end{equation*}
The function
 $\lambda\mapsto \Phi(\lambda)$
is strictly concave as
 \begin{equation*}\Phi''(\lambda)=-\sigma^{2}-\beta\widehat{B}''(\lambda)<0\quad \text{for all ${\lambda}\in\{{\lambda}\geq0;\; \widehat{B}(\lambda)<\infty\}$}.\end{equation*}
It follows that
 \begin{equation*} {\lambda}_{\ast}:= \underset{\{{\lambda}\geq0;\; \widehat{B}(\lambda)<\infty\}}{\text{argmax}}\,\Phi(\lambda)\end{equation*}
is a solution of the equation
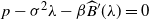 $p-\sigma^{2}{\lambda}-\beta\widehat{B}'(\lambda)=0$
under the constraint
 \begin{equation*} {\lambda}^{\ast}\in\{\lambda\geq0;\; \widehat{B}(\lambda)<\infty\}. \end{equation*}
The rate of exponential convergence is then given by
 \begin{equation*}k=\Phi({\lambda}_{\ast})=p{\lambda}_{\ast} - \dfrac12{\sigma}^2{\lambda}_{\ast}^2 - \beta [\widehat{B}({\lambda}_{\ast})-1].\end{equation*}
In this example, we compare the rate of convergence k for three claim size distributions: the gamma distribution
 $\text{Gamma}(\alpha, \delta)$
with probability density function
 \begin{equation*}p(x;\,\; \alpha, \beta) = \dfrac{\delta^{\alpha}}{\Gamma(\alpha)}x^{\alpha-1}\,{\mathrm{e}}^{-\delta x}\quad \text{for}\ x>0.\end{equation*}
Define the exponential distribution
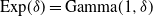 $\text{Exp}(\delta) = \text{Gamma}(1, \delta)$
, and the mixture of exponential distributions
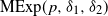 $\text{MExp}(\kern1pt p,\delta_1,\delta_2)$
with associated probability density function
 \begin{equation*}p(x;\,\; p,\delta_1,\delta_2) = p\delta_1\,{\mathrm{e}}^{-\delta_1 x}+(1-p)\delta_2\,{\mathrm{e}}^{-\delta_2 x},\quad x > 0.\end{equation*}
Let the claim size be distributed as
 $\text{Gamma}(2,1)$
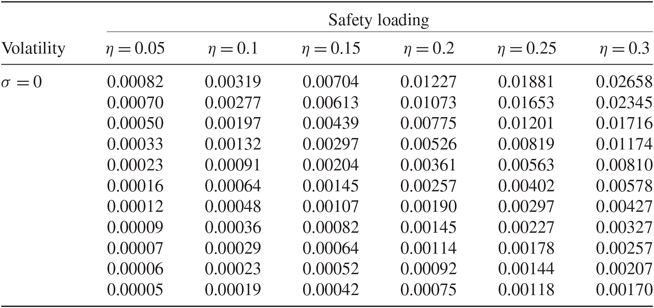
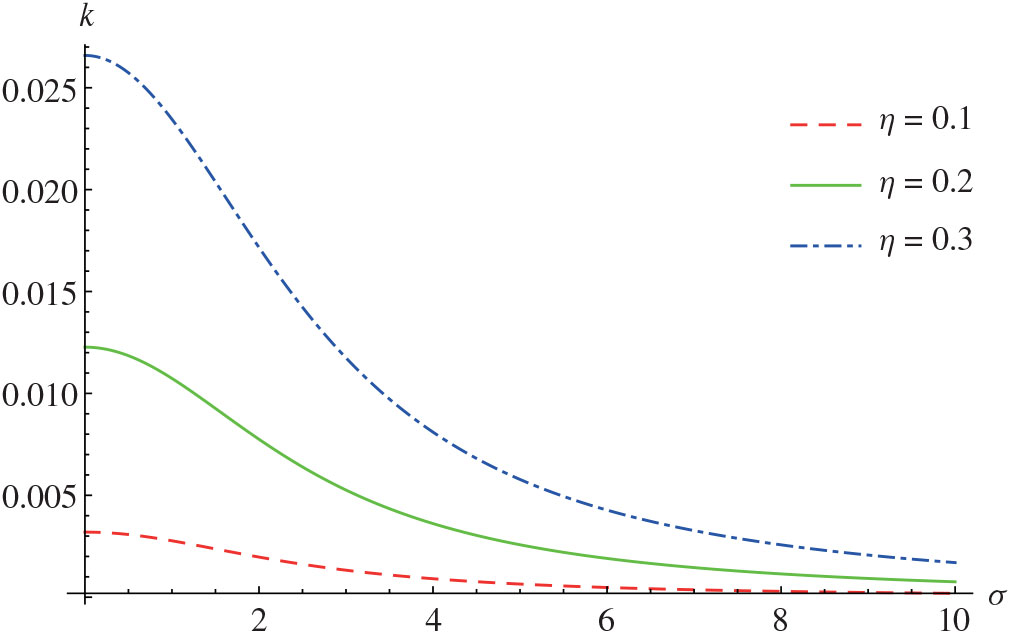
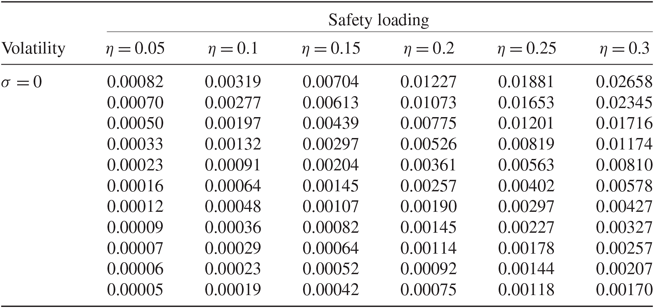
. Table 1 gives the rate of exponential convergence for various combinations of values for the safety loading and the volatility. For a given value of the safety loading, the rate of convergences decreases when the volatility increases. Conversely, for a given volatility level, the rate of convergence increases with the safety loading. The first row of Table 1 contains the rates of convergence when
 $\sigma=0$
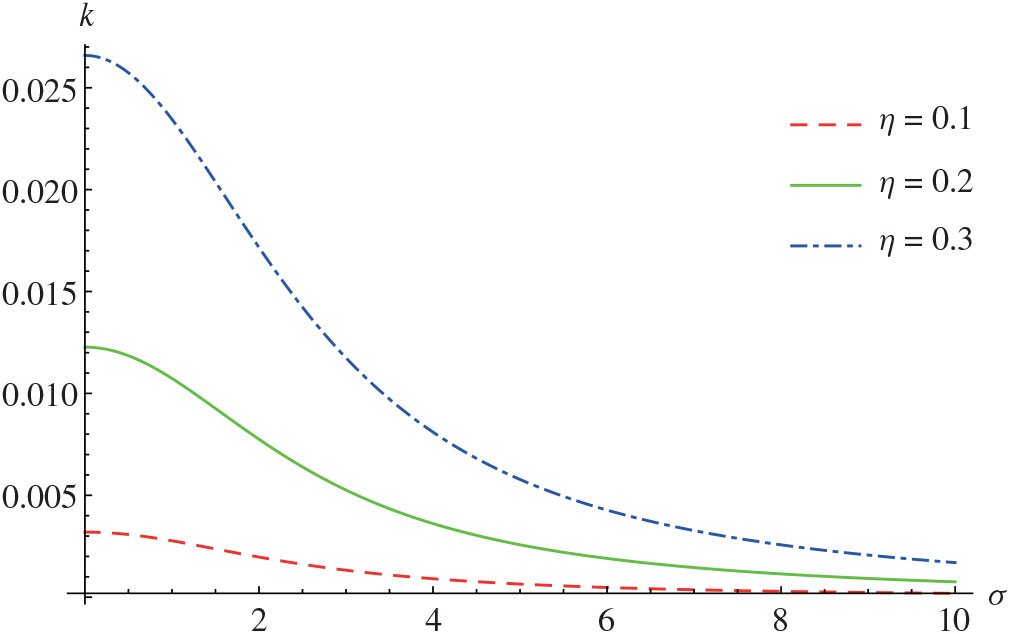
, associated to the compound Poisson risk model. Figure 1 displays the rates of exponential convergence depending on the volatility level for different values of the safety loading:
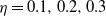 $\eta=0.1,0.2,0.3$
.
Rate of exponential convergence in the compound Poisson risk model perturbed by a diffusion, with Gamma(2,1) claim size
Rate of exponential convergence in the compound Poisson risk model perturbed by a diffusion depending on the volatility, for
 $\eta=0.1,0.2,0.3$
.
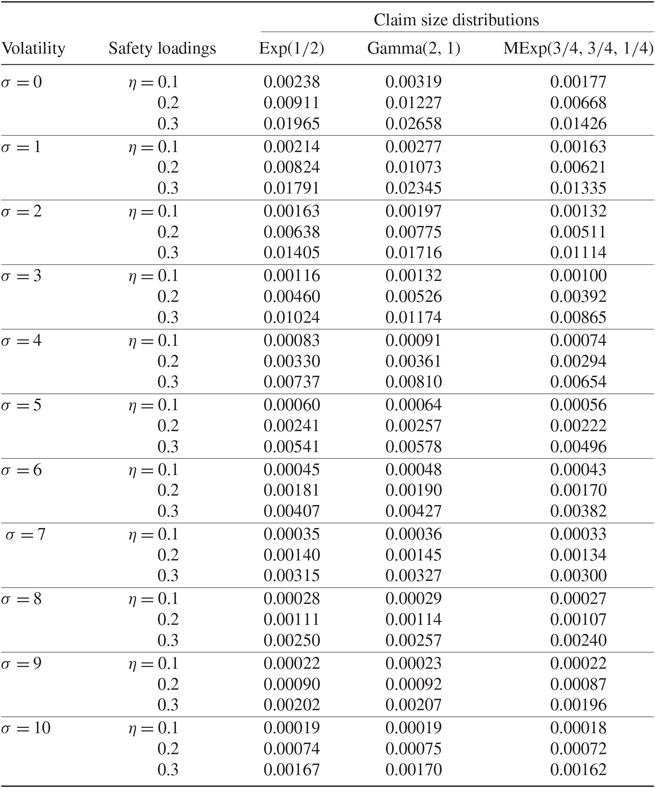
Rate of exponential convergence in the compound Poisson risk model perturbed by a diffusion for different claim size distribution
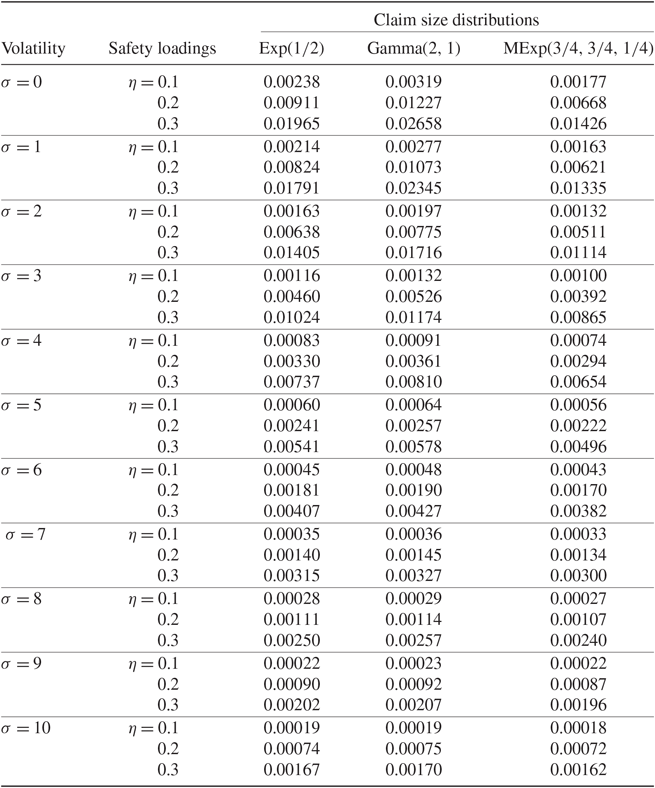
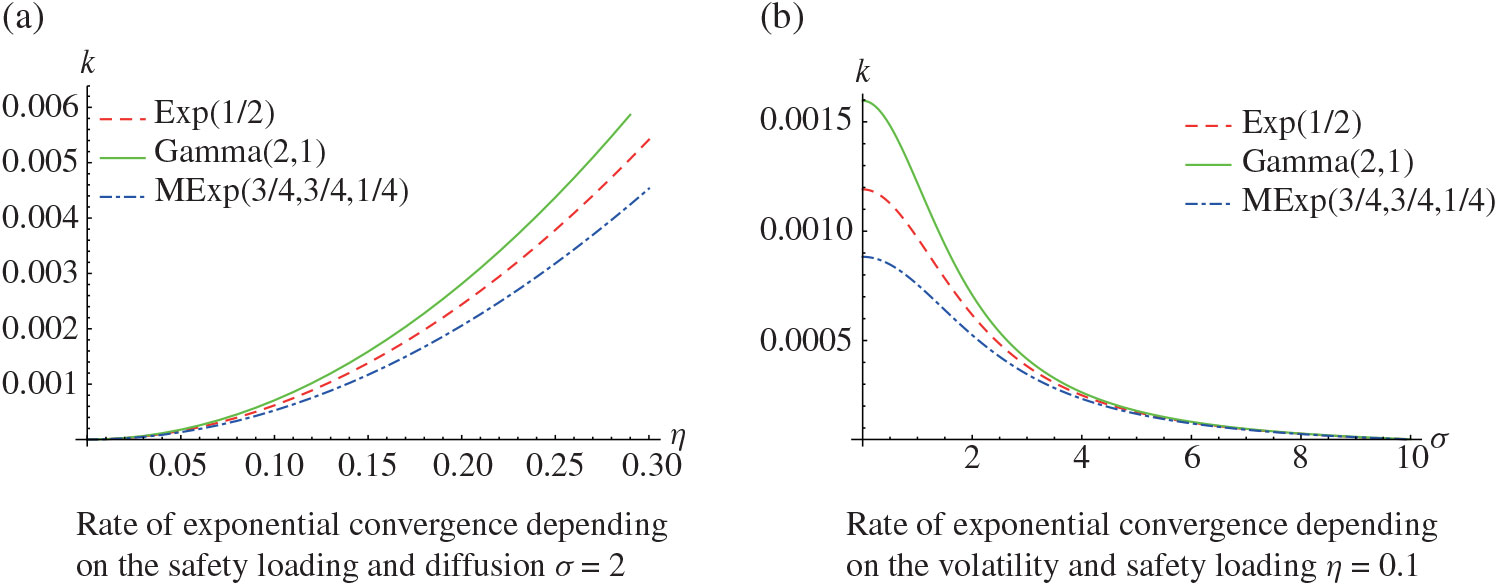
Rate of exponential convergence in the compound Poisson risk model perturbed by a diffusion for different claim size distributions.
Remark 2. Consider the compound Poisson risk model perturbed by a diffusion under constant interest force
 $i>0$
by assuming that
 $p(x)=p+ix$
; the function
 $\phi({\lambda},x)$
then becomes
 \begin{equation*}\phi({\lambda}, x) = -(\kern1pt p+ix){\lambda} + \dfrac12{\sigma}^2{\lambda}^2 + \beta [\widehat{B}(\lambda)-1],\quad {\lambda} \ge 0,\ x \in {\mathbb{R}}.\end{equation*}
Although the function
 $\phi({\lambda},x)$
depends on x, it is easily seen that
 \begin{equation*}\inf_{x \ge 0}({-}\phi({\lambda}, x))=\Phi(\lambda)= p{\lambda} - \dfrac12{\sigma}^2{\lambda}^2 - \beta [\widehat{B}(\lambda)-1],\quad {\lambda} \ge 0,\ x \in {\mathbb{R}}.\end{equation*}
The maximization problem is the same as for the compound Poisson risk model perturbed by a diffusion and will lead to the same rate of convergence.
Let us turn to the study of rate of convergence for different claim size distributions. We assume the claims are exponentially distributed
 $\text{Exp}(1/2)$
, or gamma-distributed
 $\text{Gamma}(2,1)$
, or a mixture of exponentially distributed
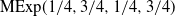 $\text{MExp}(1/4,3/4,1/4,3/4)$
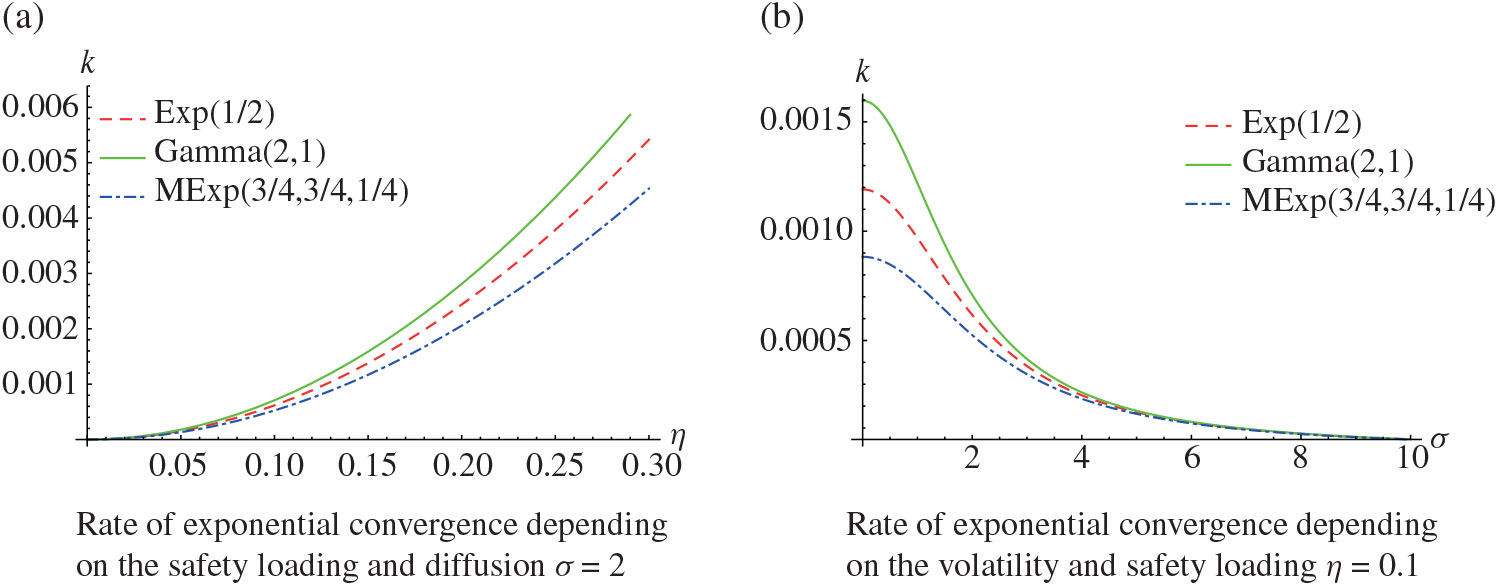
. The mean associated with claim size distributions is the same but the variance differs:
 \begin{equation*}\text{Var}[\text{Gamma}(2,1)]<\text{Var}[ \text{Exp}(1/2)]<\text{Var}[ \text{MExp}(3/4,3/4,1/4)].\end{equation*}
Table 2 contains the values of the rate of exponential convergence over the three claim size distributions. The fastest convergence occurs in the gamma case. The slowest convergence occurs in the exponential-mixture case. Figure 2 displays the evolution of the rate of exponential convergence depending on the safety loading and the diffusion parameter for the different assumptions on the claim size. In the wake of this numerical study, we may conclude that the speed of convergence depends on the variance of the process. Increasing the variance via the claim size distribution or the diffusion component makes convergence slower.
4.2. Lévy-driven risk process
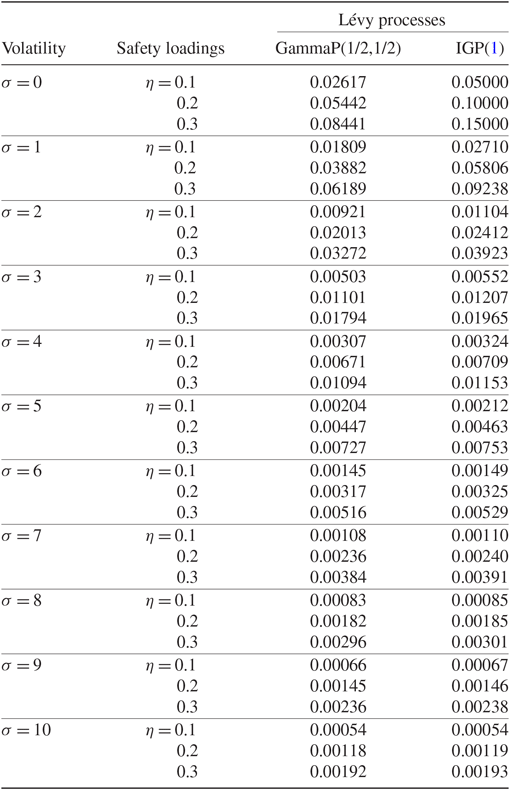
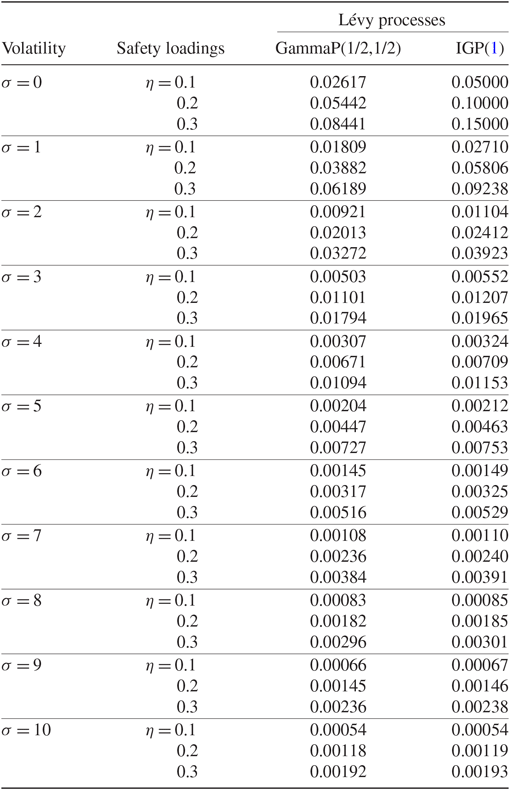
In this subsection we compare the rate of exponential convergence of the ruin probabilities when the liability of the insurance company is modeled by a gamma process and an inverse Gaussian Lévy process. The Lévy measure of a gamma process,
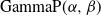 $\text{GammaP}(\alpha,\beta)$
, is given by
 \begin{equation*} \mu(\mathrm{d}x)=\dfrac{\alpha \,{\mathrm{e}}^{-\beta x}}{x}\quad \text{for }x>0,\end{equation*}
where
 $\alpha,\,\beta>0$
. Its Lévy exponent is
 \begin{equation*} \kappa(\lambda)=\alpha\ln\biggl(\dfrac{\beta}{\beta-{\lambda}}\biggr)\quad \text{for }{\lambda}\in[0,\beta).\end{equation*}
Note that in this case an explicit expression for finite-time and infinite-time ruin probabilities can be found in [Reference Meyn and Tweedie22]. The function
 $\Phi(\!\cdot\!)$
is strictly concave as
 \begin{equation*}\Phi''(\lambda)=-\sigma^{2}-\dfrac{\alpha}{(\beta-\lambda)^2}<0.\end{equation*}
It follows that
 ${\lambda}_{\ast}$
is the solution of the equation
 \begin{equation*}p-\sigma^{2}{\lambda}-\dfrac{\alpha}{\beta-\lambda}=0.\end{equation*}
The rate of exponential convergence is then given by
 \begin{equation*}k=\Phi({\lambda}_{\ast})=p{\lambda}_{\ast} - \dfrac12{\sigma}^2{\lambda}_{\ast}^2 - \alpha\ln\biggl(\dfrac{\beta}{\beta-{\lambda}_\ast}\biggr).\end{equation*}
The Lévy measure of the inverse Gaussian Lévy process,
 $\text{IGP}(\gamma)$
, is defined as
 \begin{equation*} \mu(\mathrm{d}x)=\dfrac{1}{\sqrt{2\pi}x^{3/2}}\,{\mathrm{e}}^{-x\gamma^{2}/2}\quad \text{for }x>0 {,}\end{equation*}
where
 $\gamma>0$
. Its Lévy exponent is
 \begin{equation*} \kappa(\lambda)=\gamma-\sqrt{\gamma^{2}-2{\lambda}}\quad \text{for }{\lambda}\in[0,\gamma^{2}/2).\end{equation*}
The function
 $\Phi$
is strictly concave as
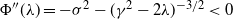 $\Phi''(\lambda)=-\sigma^{2}-(\gamma^{2}-2\lambda)^{-3/2}<0$
. It follows that
 ${\lambda}_{\ast}$
is the solution of the equation
 \begin{equation*}p-\sigma^{2}{\lambda}-\dfrac{1}{\sqrt{\gamma^{2}-2\lambda}}=0{.}\end{equation*}
The rate of exponential convergence is then given by
 \begin{equation*}k=\Phi({\lambda}_{\ast})=p{\lambda}_{\ast} - \dfrac12{\sigma}^2{\lambda}_{\ast}^2 - \gamma+\sqrt{\gamma^2-2{\lambda}_\ast}.\end{equation*}
We set
 $\gamma=1$
,
 $\alpha=1/2$
,
 $\beta=1/2$
, to match the first moment of the liabilities in both risk models at time
 $t=1$
. The premium rate is then given by
 \begin{equation*} p=(1+\eta)\mathbb{E}(L(1))=(1+\eta)\dfrac{\alpha}{\beta}=(1+\eta)\dfrac{1}{\gamma}.\end{equation*}
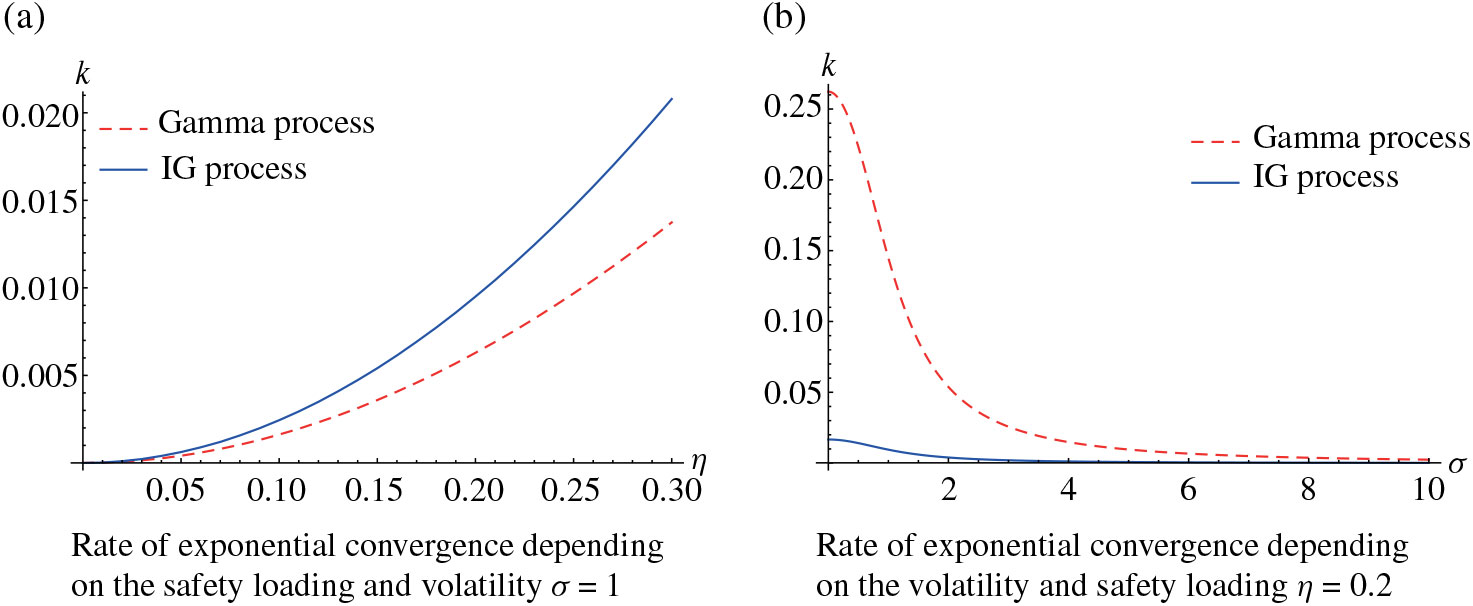
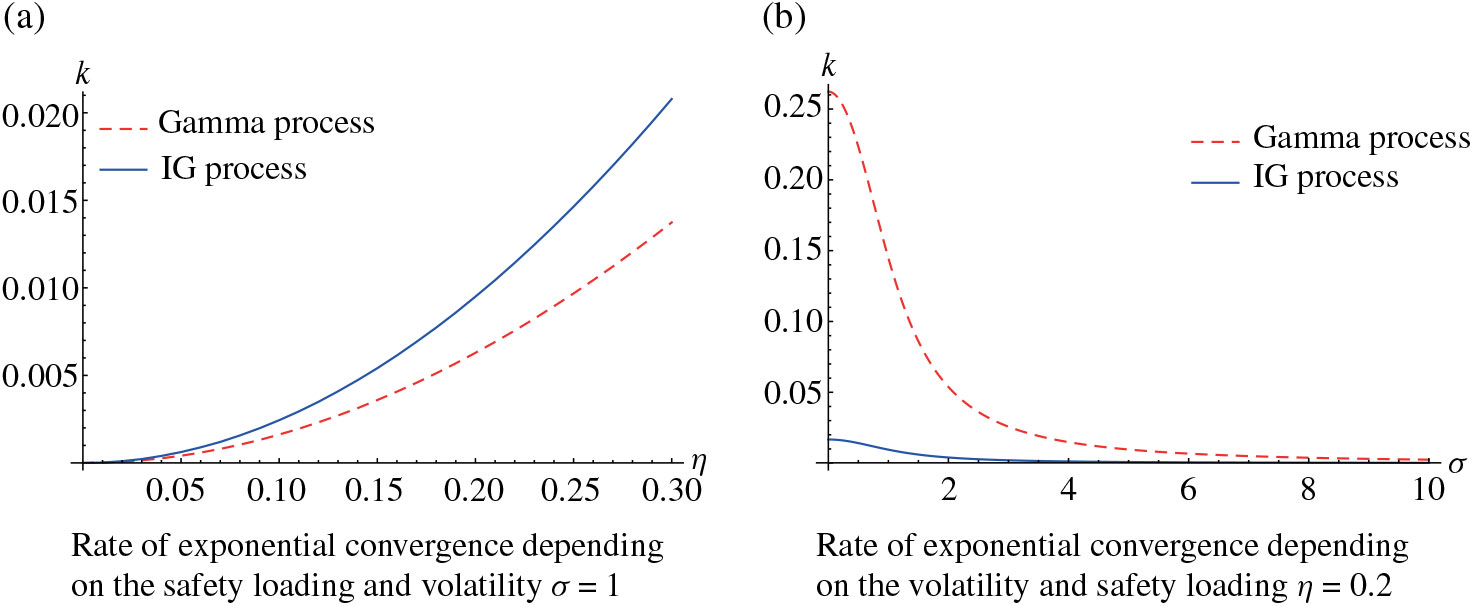
Table 3 shows the value of the exponential rate of convergence when the liability of the insurance company is governed by a gamma process or an inverse Gaussian Lévy process depending on the safety loading and the volatility of the diffusion. Figure 3(a) displays the rates of exponential convergence for the considered Lévy-driven risk models. We observe that the impact of the volatility and the safety loading on the convergence rate remains the same as in the compound Poisson case. The rate of exponential convergence is noticeably greater when the liability of the insurance company follows an inverse Gaussian Lévy process.
Rate of exponential convergence in Lévy-driven risk models
5. Proof of Theorem 2
If Y were a reflected jump-diffusion with a.s. finitely many jumps in finite time, and with positive diffusion coefficient, then we could directly apply [Reference Sarantsev29, Theorem 4.1, Theorem 4.3], and complete the proof of Theorem 2. We can have: (a)
 ${\sigma}(x) = 0$
for some x; (b) infinite Lévy measure
 $\mu$
.
In the proof of [Reference Sarantsev29, Theorem 3.2], we used the following property: for all
 $t > 0$
,
 $x \in {\mathbb{R}}_+$
, and
 $A \subseteq {\mathbb{R}}_+$
of positive Lebesgue measure, we have
 $Q^t(x, A) > 0$
. This property might not hold for the case
 ${\sigma}(x) = 0$
for some
 $x \in {\mathbb{R}}_+$
. We bypass this difficulty by approximating the reflected jump-diffusion Y by a ‘regular’ reflected jump-diffusion, where
 ${\sigma}(x) > 0$
for
 $x \in {\mathbb{R}}_+$
, and the Lévy measure is finite.
Rate of exponential convergence for Lévy-driven risk processes.
For an
 ${\varepsilon} > 0$
, let
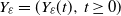 $Y_{{\varepsilon}} = (Y_{{\varepsilon}}(t),\, t \ge 0)$
be the reflected jump-diffusion on
 ${\mathbb{R}}_+$
, with drift coefficient
 $p_*$
, diffusion coefficient
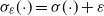 ${\sigma}_{{\varepsilon}}(\!\cdot\!) = {\sigma}(\!\cdot\!) + {\varepsilon}$
, and jump measure
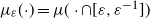 $\mu_{{\varepsilon}}(\!\cdot\!) = \mu(\cdot\cap[{\varepsilon}, {\varepsilon}^{-1}])$
. Note that this is a reflected jump-diffusion with positive diffusion coefficient
 ${\sigma}_{{\varepsilon}}(\,y) > 0$
for all
 $y \in {\mathbb{R}}_+$
, and with finite Lévy measure
 $\mu_{{\varepsilon}}({\mathbb{R}}_+) < \infty$
. Therefore we can apply the results of [Reference Sarantsev29] to this process. For
 $x \in {\mathbb{R}}_+$
, let
 \begin{equation*}\phi_{{\varepsilon}}(x, {\lambda}) := p_{\ast}(x){\lambda} + \dfrac12{\sigma}^2_{{\varepsilon}}(x){\lambda}^2 + \int_{{\varepsilon}}^{{\varepsilon}^{-1}} ({\mathrm{e}}^{{\lambda} y} - 1)\,\mu_{{\varepsilon}}({\mathrm{d}} y).\end{equation*}
For every
 $x \ge 0$
, we have
 \begin{equation}\phi(x, {\lambda}) -\phi_{{\varepsilon}}(x, {\lambda}) = -\Big[{\varepsilon}{\sigma}_{{\varepsilon}}(x) + \dfrac12{\varepsilon}^2\Big]{\lambda}^2 + \biggl(\int_0^{{\varepsilon}} + \int_{{\varepsilon}^{-1}}^{\infty}\biggr) ({\mathrm{e}}^{{\lambda} y} - 1 )\,\mu({\mathrm{d}} y).\end{equation}
Recall also that
 \begin{equation}\int_0^{\infty} ({\mathrm{e}}^{{\lambda} y} - 1 )\,\mu({\mathrm{d}} y) < \infty.\end{equation}
Combining (20) with (21) and the boundedness of
 ${\sigma}$
from Assumption 1, we have
 \begin{equation}\sup_{x \ge 0} |\phi_{{\varepsilon}}(x, {\lambda}) - \phi(x, {\lambda})| \to 0,\quad {\varepsilon} \downarrow 0.\end{equation}
By our assumptions,
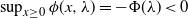 $\sup_{x \ge 0}\phi(x, {\lambda}) = -\Phi({\lambda}) < 0$
. From (22),
 \begin{equation*}-\sup_{x \ge 0}\phi_{{\varepsilon}}(x, {\lambda}) =: \Phi_{{\varepsilon}}({\lambda}) \to \Phi({\lambda}).\end{equation*}
Thus we conclude that there exists an
 ${\varepsilon}_0 > 0$
such that for
 ${\varepsilon} \in [0,{\varepsilon}_0]$
,
 $\Phi_{{\varepsilon}}({\lambda}) > 0$
. Apply [Reference Sarantsev29, Theorem 4.3] to prove the statement of Theorem 2 for the process
 $Y_{{\varepsilon}}$
. For consistency of notation, let
 $Y_0 := Y$
. There exists a unique stationary distribution
 $\pi_{{\varepsilon}}$
for
 $Y_{{\varepsilon}}$
, which satisfies
 $(\pi_{{\varepsilon}}, V_{{\lambda}}) < \infty$
; its transition kernel
 $Q_{{\varepsilon}}^t(x, \cdot)$
satisfies
 \begin{equation}{\lVert{Q_{{\varepsilon}}^t(x, \cdot) - \pi_{{\varepsilon}}(\!\cdot\!)}\rVert}_{V_{{\lambda}}} \le [V_{{\lambda}}(x) + (\pi_{{\varepsilon}}, V_{{\lambda}})]\,{\mathrm{e}}^{-\Phi_{{\varepsilon}}({\lambda})t}.\end{equation}
We would like to take the limit
 ${\varepsilon} \downarrow 0$
in (23). To this end, let us introduce some new notation. Take a smooth non-decreasing
 $C^{\infty}$
function
 $\theta \colon {\mathbb{R}}_+ \to {\mathbb{R}}_+$
with
 \begin{equation*}\theta(x) =\begin{cases}0 & x \le s_-,\\x & x \ge s_+,\end{cases} \quad \theta(x) \le x,\end{equation*}
for some fixed
 $s_+ > s_- > 0$
. The function
 $\theta$
is Lipschitz on
 ${\mathbb{R}}_+$
: there exists a constant
 $C(\theta) > 0$
such that
 \begin{equation}|\theta(s_1) - \theta(s_2)| \le C(\theta)|s_1 - s_2|\quad \text{for all}\ s_1, s_2 \in {\mathbb{R}}_+.\end{equation}
Next, define
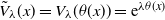 $\tilde{V}_{{\lambda}}(x) = V_{{\lambda}}(\theta(x)) = {\mathrm{e}}^{{\lambda}\theta(x)}$
. The process
 $Y_{{\varepsilon}}$
has the generator
 ${\mathcal L}_{{\varepsilon}}$
:
 \begin{equation*}{\mathcal L}_{{\varepsilon}}f(x) = p_{\ast}(x)f'(x) + \dfrac12{\sigma}_{{\varepsilon}}^2(x)f''(x) + \int_{{\varepsilon}}^{{\varepsilon}^{-1}}[\,f(x+y) - f(x)]\,\mu({\mathrm{d}} y)\end{equation*}
for
 $f \in C^2({\mathbb{R}}_+)$
with
 $f'(0) = 0$
. Repeating calculations from [Reference Sarantsev29, Theorem 3.2] with minor changes, we get
 \begin{equation}\begin{split}{\mathcal L}_{{\varepsilon}}\tilde{V}_{{\lambda}}(x) & \le -\Phi_{{\varepsilon}}({\lambda})\tilde{V}_{{\lambda}}(x) + c_{{\varepsilon}}1_{[0, s_+]}(x),\quad x \in {\mathbb{R}}_+,\\c_{{\varepsilon}} & := \max_{x\in[0, s_+]} [{\mathcal L}_{{\varepsilon}}\tilde{V}_{{\lambda}}(x) + \phi_{{\varepsilon}}({\lambda},x)\tilde{V}_{{\lambda}}(x)].\end{split}\end{equation}
Lemma 7.
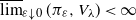 $\varlimsup_{{\varepsilon} \downarrow 0}(\pi_{{\varepsilon}}, V_{{\lambda}}) < \infty$
.
Proof. The functions
 $V_{{\lambda}}$
and
 $\tilde{V}_{{\lambda}}(x)$
are of the same order, in the sense that
 \begin{equation}0 < \inf_{x \ge 0}\dfrac{\tilde{V}_{{\lambda}}(x)}{V_{{\lambda}}(x)} \le \sup_{x \ge 0}\dfrac{\tilde{V}_{{\lambda}}(x)}{V_{{\lambda}}(x)} < \infty.\end{equation}
Therefore it suffices to show that
 \begin{equation}\varlimsup_{{\varepsilon} \downarrow 0}(\pi_{{\varepsilon}}, \tilde{V}_{{\lambda}}) < \infty.\end{equation}
Apply the measure
 $\pi_{{\varepsilon}}$
to both sides of the inequality (25). This probability measure is stationary and thus the left-hand side of (25) becomes
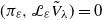 $(\pi_{{\varepsilon}}, {\mathcal L}_{{\varepsilon}}\tilde{V}_{{\lambda}}) = 0$
. Therefore
 \begin{equation*}-\Phi_{{\varepsilon}}({\lambda})(\pi_{{\varepsilon}}, \tilde{V}_{{\lambda}}) + c_{{\varepsilon}}(\pi_{{\varepsilon}}, 1_{[0, s_+]}) \ge 0.\end{equation*}
From
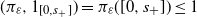 $(\pi_{{\varepsilon}}, 1_{[0, s_+]}) = \pi_{{\varepsilon}}([0, s_+]) \le 1$
, we get
 \begin{equation}(\pi_{{\varepsilon}}, \tilde{V}_{{\lambda}}) \le \dfrac{c_{{\varepsilon}}}{\Phi_{{\varepsilon}}({\lambda})}.\end{equation}
By (28), to show (27), it suffices to show that
 $\varlimsup_{{\varepsilon}\downarrow 0}c_{{\varepsilon}} < \infty$
. This, in turn, would follow from (25) and the relation
 \begin{equation}{\mathcal L}_{{\varepsilon}}\tilde{V}_{{\lambda}}(x) \to {\mathcal L}\tilde{V}_{{\lambda}}(x)\ \text{uniformly on}\ [0, s_+].\end{equation}
We can express the difference of generators as
 \begin{equation} {\mathcal L}_{{\varepsilon}} \tilde{V}_{\lambda}(x) - {\mathcal L}\tilde{V}_{\lambda}(x) = \dfrac12 ({\sigma}_{{\varepsilon}}^2(x) - {\sigma}^2(x) )f''(x) - \biggl(\int_0^{{\varepsilon}}+\int_{{\varepsilon}^{-1}}^{\infty}\biggr)\bigl[\tilde{V}_{{\lambda}}(x+y) - \tilde{V}_{{\lambda}}(x)\bigr]\,\mu({\mathrm{d}} y).\end{equation}
The first term on the right-hand side of (30) is equal to
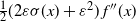 $\frac12(2{\varepsilon}{\sigma}(x) + {\varepsilon}^2)\,f''(x)$
. Since
 ${\sigma}$
is bounded, this term converges to 0 as
 ${\varepsilon} \downarrow 0$
uniformly on
 $[0, s_+]$
. It suffices to prove that the second term converges to zero as well. For all
 $x, y \ge 0$
, using (24), we have
 \begin{align}0 &\le \tilde{V}_{{\lambda}}(x + y) - \tilde{V}_{{\lambda}}(x) \notag \\& = {\mathrm{e}}^{{\lambda}\theta(x+y)} - {\mathrm{e}}^{{\lambda}\theta(x)} \notag \\& = {\mathrm{e}}^{{\lambda}\theta(x)} [{\mathrm{e}}^{{\lambda}(\theta(x+y) - \theta(x))} - 1] \notag \\& \le \tilde{V}_{{\lambda}}(x) [{\mathrm{e}}^{{\lambda} C(\theta)y} - 1].\end{align}
Changing the parameter
 $s_-$
and letting
 $s_- \downarrow 0$
, we have
 $\theta(x) \to x$
uniformly on
 ${\mathbb{R}}_+$
. Therefore we can make the Lipschitz constant
 $C(\theta)$
as close to 1 as necessary. Also, note that for
 ${\lambda}'$
in some neighborhood of
 ${\lambda}$
, we have
 \begin{equation}\int_0^{\infty} ({\mathrm{e}}^{{\lambda}'x} - 1)\,\mu({\mathrm{d}} x) < \infty.\end{equation}
Combining (31) and (32), using that
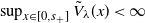 $\sup_{x \in [0, s_+]}\tilde{V}_{{\lambda}}(x) < \infty$
, and taking
 $C(\theta)$
close enough to 1, we complete the proof that the second term on the right-hand side of (30) tends to 0 as
 ${\varepsilon} \downarrow 0$
. This completes the proof of (29), and with it that of Lemma 7.
Now, we state a fundamental lemma, and complete the proof of Theorem 2 assuming that this lemma is proved. The proof is postponed to the Appendix.
Lemma 8. Take a version
 $\tilde{Y}_{{\varepsilon}}$
of the reflected jump-diffusion
 $Y_{{\varepsilon}}$
, starting from
 $y_{{\varepsilon}} \ge 0$
, for
 ${\varepsilon} \ge 0$
. If
 $y_{{\varepsilon}} \to y_0$
, then we can couple
 $\tilde{Y}_{{\varepsilon}}$
and
 $\tilde{Y}_0$
so that, for every
 $T \ge 0$
,
 \begin{equation*}\lim_{{\varepsilon} \downarrow 0}{\mathbb E}\sup_{0 \le t \le T} |\tilde{Y}_{{\varepsilon}}(t) - \tilde{Y}_{0}(t)|^2 = 0.\end{equation*}
Lemma 9. The reflected jump-diffusion
 $Y_0$
has a stationary distribution
 $\pi_0$
.
Proof. Since
 $V_{{\lambda}}(\infty) = \infty$
, Lemma 7 implies tightness of the family
 $(\pi_{{\varepsilon}})_{{\varepsilon} \in (0, {\varepsilon}_0]}$
of probability measures. Now take a stationary version
 $\overline{Y}_{{\varepsilon}}$
of the reflected jump-diffusion
 $Y_{{\varepsilon}}$
: for every
 $t \ge 0$
, let
 $\overline{Y}_{{\varepsilon}}(t) \sim \pi_{{\varepsilon}}$
. Take a sequence
 $({\varepsilon}_n)_{n \ge 1}$
such that
 ${\varepsilon}_n \downarrow 0$
as
 $n \to \infty$
, and
 $\pi_{{\varepsilon}_n} {\Rightarrow} \pi_0$
(where
 ${\Rightarrow}$
stands for weak convergence) for some probability measure
 $\pi_0$
on
 ${\mathbb{R}}_+$
. It follows from Lemma 8 that, for every
 $t \ge 0$
, we have
 $\overline{Y}_{{\varepsilon}_n}(t) {\Rightarrow} \overline{Y}_0(t)$
as
 $n \to \infty$
, where
 $\overline{Y}_0$
is a stationary version of the reflected jump-diffusion
 $Y_0$
, that is,
 $\overline{Y}_0(t) \sim \pi_0$
for every
 $t \ge 0$
.
Next, take a measurable function
 $g \colon {\mathbb{R}}_+ \to {\mathbb{R}}$
such that
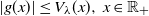 $|g(x)| \le V_{{\lambda}}(x),\, x \in {\mathbb{R}}_+$
.
Lemma 10.
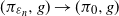 $(\pi_{{\varepsilon}_n}, g) \to (\pi_0, g)$
as
 $n \to \infty$
.
Proof. The function
 $\Phi$
is a supremum of a family of functions
 $-\phi(\cdot, x)$
, which are continuous in
 ${\lambda}$
. Thus
 $\Phi$
is lower semicontinuous, and the set
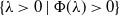 $\{{\lambda} > 0\mid \Phi({\lambda}) > 0\}$
is open. Apply Lemma 7 to some
 ${\lambda}' > {\lambda}$
(which exists by the observation above). Then we get
 \begin{equation*}\varlimsup_{{\varepsilon} \downarrow 0}(\pi_{{\varepsilon}_n}, V_{{\lambda}'}) < \infty.\end{equation*}
Note also that
 \begin{equation*}|g(x)|^{{\lambda}'/{\lambda}} \le [V_{{\lambda}}(x)]^{{\lambda}'/{\lambda}} = V_{{\lambda}'}(x)\quad\text{for all $x \ge 0$.}\end{equation*}
Therefore the family
 $(\pi_{{\varepsilon}}g^{-1})_{{\varepsilon} \in (0, {\varepsilon}_0]}$
of probability distributions is uniformly integrable. Uniform integrability plus a.s. convergence imply convergence of expected values. Thus we complete the proof of Lemma 10.
For all
 ${\varepsilon} \ge 0$
, take a copy
 $Y^{{\varepsilon}}$
of
 $Y_{{\varepsilon}}$
starting from the same initial point
 $x \in {\mathbb{R}}_+$
.
Lemma 11. For every
 $t \ge 0$
, we have
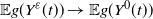 ${\mathbb E} g(Y^{{\varepsilon}}(t)) \to {\mathbb E} g(Y^0(t))$
as
 ${\varepsilon} \downarrow 0$
.
Proof. Following calculations in the proof of [Reference Sarantsev29, Theorem 3.2], we get
 \begin{equation}{\mathbb E} \tilde{V}_{{\lambda}}(Y^{{\varepsilon}}(t)) - \tilde{V}_{{\lambda}}(x) \le \int_0^t\bigl[-\Phi_{{\varepsilon}}({\lambda})\tilde{V}_{{\lambda}}(Y^{{\varepsilon}}(s)) + c_{{\varepsilon}}1_{[0, s_+]}(s)\bigr]\,{\mathrm{d}} s \le c_{{\varepsilon}}t.\end{equation}
Therefore, from (33) we have
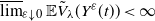 $\varlimsup_{{\varepsilon}\downarrow 0}{\mathbb E} \tilde{V}_{{\lambda}}(Y^{{\varepsilon}}(t)) < \infty$
. Because of (26), this holds for
 $V_{{\lambda}}$
in place of
 $\tilde{V}_{{\lambda}}$
. This is also true for
 ${\lambda}' > {\lambda}$
slightly larger than
 ${\lambda}$
. Applying the same uniform integrability argument as in the proof of Lemma 10, we complete the proof of Lemma 11.
Finally, let us complete the proof of Theorem 2. From (23), we have
 \begin{equation}|{\mathbb E} g(Y^{{\varepsilon}}(t)) - (\pi_{{\varepsilon}}, g)| \le [V_{{\lambda}}(x) + (\pi_{{\varepsilon}}, V_{{\lambda}})]\,{\mathrm{e}}^{-\Phi_{{\varepsilon}}({\lambda})t}.\end{equation}
Taking
 ${\varepsilon} = {\varepsilon}_n$
and letting
 $n \to \infty$
in (34), we use Lemma 10 and 11 to conclude that
 \begin{equation*} |{\mathbb E} g(Y^{0}(t)) - (\pi_{0}, g)| \le [V_{{\lambda}}(x) + (\pi_{0}, V_{{\lambda}})]\,{\mathrm{e}}^{-\Phi({\lambda})t}.\end{equation*}
Take the supremum over all functions
 $g \colon {\mathbb{R}}_+ \to {\mathbb{R}}$
which satisfy
 $|g(x)| \le V_{{\lambda}}(x)$
for all
 $x \in {\mathbb{R}}_+$
, and complete the proof of Theorem 2 for Lipschitz
 $p_*$
.
6. Concluding remarks
We showed that the convergence of ruin probabilities in a rather broad class of risk processes is achieved exponentially fast. This rate is easy to compute (at least in the examples considered in Section 4), and happens to be sharp when the premium rate and its variability are independent of the current wealth of the insurance company.
A natural question concerns the practical implication of having access to the value of the rate of exponential convergence, and in particular whether this leads to an numerical approximation of the finite-time ruin probability. This issue has been discussed by Asmussen [Reference Asmussen2]: the answer was negative. For constant premium rate and diffusion parameter, one may approximate the actual gap between the ruin probabilities using numerical integration techniques based on the paper by Michna, Palmowski, and Pistorius [Reference Michna, Palmowski and Pistorius23].
Another direction is to relax the condition on the tail of the claim size. It is of practical interest to let the claim size distribution be heavy-tailed. An extension of the early work of Asmussen and Teugels [Reference Asmussen and Teugels4] could be envisaged. For example, in the work of Tang [Reference Tang35], a compound Poisson risk model under constant interest force with sub-exponentially distributed claim size is considered. When comparing the asymptotics provided by Tang [Reference Tang35, (2.5), (3.2)], it seems that exponential convergence holds for large initial reserves.
Appendix
Proof of Lemma 1
As a preliminary step, we claim that
 \begin{equation}\mathbb E\exp\biggl[\lambda_0\sup_{0 \le s \le t}L(s)\biggr] = \mathbb E[{\mathrm{e}}^{\lambda_0 L(t)}] < \infty.\end{equation}
This follows from plugging
 $\lambda := -\lambda_0$
into (9) and from monotonicity of L. Turning to the proof of the main statement, we first claim that, for all functions
 $f \in C^{\infty}(\mathbb R)$
which satisfy (11), the function
 $\mathcal Nf$
is well-defined, and satisfies, for some constant
 $D_f$
,
 \begin{equation}|\mathcal Nf(x)| \le D_f\,{\mathrm{e}}^{\lambda_0x},\quad x \ge 0{.}\end{equation}
Indeed, for
 $y \in [0, 1]$
and
 $x \ge 0$
,
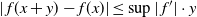 $|\,f(x+y) - f(x)| \le \sup|\,f'|\cdot y$
. Thus
 \begin{equation}\int_0^1(\,f(x+y) - f(x))\,\mathrm{d}\mu(\,y) \le \sup|\,f'|\cdot\int_0^{1}y\,\mathrm{d}\mu(\,y) < \infty.\end{equation}
But for
 $y \ge 1$
we have
 \begin{align}\biggl|\int_1^{\infty}[\,f(x+y) - f(x)]\,\mu(\mathrm{d} y)\biggr| &\le f(x)\mu[1, \infty) + C_f\,{\mathrm{e}}^{\lambda_0x}\int_1^{\infty}\,{\mathrm{e}}^{\lambda_0y}\,\mu(\mathrm{d} y) \notag \\ & \le C_f\,{\mathrm{e}}^{\lambda_0x}\biggl[\mu[1, \infty) + \int_1^{\infty}\,{\mathrm{e}}^{\lambda_0y}\,\mu(\mathrm{d} y)\biggr].\end{align}
Combining (37) and (38), we get (36) for
 \begin{equation*}D_f := C_f\biggl[\mu[1, \infty) + \int_1^{\infty}\,{\mathrm{e}}^{\lambda_0y}\,\mu(\mathrm{d} y)\biggr] + \sup|\,f'|\cdot\int_0^{1}y\,\mathrm{d}\mu(\,y).\end{equation*}
Combining (35) with (36), we get
 \begin{equation}\mathbb{E} |\,f(L(t))| < \infty,\quad \sup_{0 \le s \le t}\mathbb E |(\mathcal N f)(L(s))| < \infty,\quad t > 0.\end{equation}
By the standard stopping argument, the following process is a local martingale:
 \begin{equation}f(L(t)) - f(L(0)) - \int_0^t(\mathcal Nf)(L(s))\,\mathrm{d}s,\quad t \ge 0.\end{equation}
Using (39) we obtain that the process (40) is an actual martingale. Taking expectation (if
 $x := L(0)$
is a constant), we get
 \begin{equation*}\mathbb E[\,f(L(t))] - f(x) - \int_0^t\mathbb E[(\mathcal Nf)(L(s))]\,\mathrm{d}s = 0.\end{equation*}
Dividing by t and letting
 $t \downarrow 0$
, we get
 \begin{equation*}\lim_{t \downarrow 0}\dfrac1t(\mathbb E[\,f(L(t))] - f(x)) = (\mathcal Nf)(x).\end{equation*}\vskip-28pt\hfill\qed
Proof of Lemma 2
From Assumption 3 it follows that
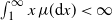 $\int_1^{\infty}x\,\mu({\mathrm{d}} x) < \infty$
, and from (8) we get
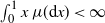 $\int_0^1x\,\mu({\mathrm{d}} x) < \infty$
. Condition (13) then immediately follows from these two observations.
Proof of Lemma 3
The proof is very similar to the classic existence and uniqueness theorem for an SDE, which can be found in any stochastic analysis textbook, via Picard iterations or a fixed-point theorem. For the sake for completeness, we provide the complete proof.
Take every filtered probability space with two independent processes: a Brownian motion W and a Lévy process L. Fix time horizon
 $T > 0$
and consider the space
 $\mathcal E_T$
of all right-continuous adapted processes
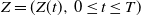 $Z = (Z(t),\, 0 \le t \le T)$
with left limits and
 \begin{equation}{\lVert{Z}\rVert}_{2, T}^2 := {\mathbb E}\sup_{0 \le t \le T}Z^2(t) < \infty.\end{equation}
This is a Banach space with norm
 ${\lVert{\cdot}\rVert}_{2, T}$
. Let us introduce a mapping
 $\mathcal P \colon \mathcal E_T \to \mathcal E_T$
:
 \begin{equation*}\mathcal P(Z)(t) = u + \int_0^tp_{\ast}(Z(s))\,{\mathrm{d}} s + \int_0^t{\sigma}(Z(s))\,{\mathrm{d}} W(s) - L(t),\quad 0 \le t \le T.\end{equation*}
Any solution to the stochastic integral equation (7) is a fixed point for this mapping
 $\mathcal P$
. It is straightforward to show, using Lipschitz properties of
 $p_{\ast}$
and
 ${\sigma}$
, that these mappings indeed map
 $\mathcal E_T$
into
 $\mathcal E_T$
. Assume
 $C(\kern1pt p_{\ast})$
and
 $C({\sigma})$
are Lipschitz constants for functions
 $p_{\ast}$
and
 ${\sigma}$
respectively.
Lemma 12. For
 $\mathcal Z, \mathcal Z' \in \mathcal E_T$
, the following Lipschitz property holds:
 \begin{equation}{\lVert{\mathcal R(\mathcal Z) - \mathcal R(\mathcal Z')}\rVert}_{2, T} \le C_T{\lVert{\mathcal Z - \mathcal Z'}\rVert}_{2, T}, \quad C_T := C(\kern1pt p_\ast)T + 2C({\sigma})T^{1/2}.\end{equation}
Proof. For
 $t \in [0, T]$
, we can represent the difference
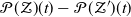 $\mathcal P(\mathcal Z)(t) - \mathcal P(\mathcal Z')(t)$
as
 \begin{equation}\int_0^t [\kern1pt p_\ast(\mathcal Z(s)) - p_\ast(\mathcal Z'(s))]\,{\mathrm{d}} s + \int_0^t [{\sigma}(\mathcal Z(s)) - {\sigma}(\mathcal Z'(s))]\,{\mathrm{d}} W(s) =: I(t) + M(t).\end{equation}
Apply the norm
 $\lVert{\cdot}\rVert_{T, 2}$
to (43):
 \begin{equation}{\lVert{\mathcal P(\mathcal Z)(t) - \mathcal P(\mathcal Z')(t)}\rVert}_{2, T} \le{\lVert{I(t)}\rVert}_{2, T} + {\lVert{M(t)}\rVert}_{2, T}.\end{equation}
The norm
 ${\lVert{I(t)}\rVert}_{2, T}$
is estimated using the Lipschitz property of
 $\sigma$
:
 \begin{align} {\lVert{I(t)}\rVert}_{2, T}^2 &= {\mathbb E}\sup_{0 \le t \le T}I^2(t)\notag \\ & \le {\mathbb E}\sup_{0 \le t \le T}\biggl(\int_0^tC(\kern1pt p_\ast)[\mathcal Z(s) - \mathcal Z'(s)]\,{\mathrm{d}} s\biggr)^2 \notag \\ & \le T^2C^2(\kern1pt p_\ast)\cdot {\mathbb E}\sup_{0 \le s \le T}[\mathcal Z(s) - \mathcal Z'(s)]^2 \notag \\ & = T^2C^2(\kern1pt p_\ast){\lVert\mathcal Z - \mathcal Z'\rVert}^2_{2, T}.\end{align}
Finally, the norm
 ${\lVert{M}\rVert}_{2, T}$
can be estimated using the martingale inequalities:
 \begin{align} {\lVert{M}\rVert}_{2, T}^2 & = {\mathbb E}\sup_{0 \le t \le T}M^2(t) \notag \\ & \le 4{\mathbb E} M^2(T)= 4\int_0^T[{\sigma}(\mathcal Z(s)) - {\sigma}(\mathcal Z'(s))]^2\,{\mathrm{d}} s \notag \\& \le4C^2({\sigma})T\cdot{\mathbb E}\sup_{0 \le t \le T}{(\mathcal Z(t) - \mathcal Z'(t))}^2 \notag \\& = 4C^2({\sigma})T{\lVert{\mathcal Z - \mathcal Z'}\rVert}^2_{2, T}.\end{align}
Combining (44), (45), and (46), we complete the proof of (42).
For small enough T, the constant
 $C_T$
from (57) is strictly less than 1. Assume this is the case until the end of the proof. Then the mapping
 $\mathcal R$
is contractive. Therefore it has a unique fixed point, which can be obtained by successive approximations:
 \begin{equation*}\mathcal Y = \lim_{n \to \infty}\mathcal R^n(\mathcal Z)\quad \text{for every}\ \mathcal Z \in \mathcal E_T.\end{equation*}
This completes the proof of Lemma 3 for small enough T. Thus we can prove strong existence and pathwise uniqueness on the time interval [0, T], and then on [T, 2T], [2T, 3T], etc. The formula for the generator in (14) then follows from a straightforward application of Itô’s formula.
Proof of Lemma 4
This is similar to the proof of Lemma 4, but we have a Skorokhod mapping
 $\mathcal S$
:
 \begin{equation*}\mathcal S(Z)(t) = Z(t) + \sup_{0 \le s \le t}(Z(s))_-,\quad 0 \le t \le T,\end{equation*}
where
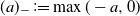 $(a)_{-}:=\max(-a, 0)$
for any
 $a\in\mathbb{R}$
. Thus any solution to the stochastic integral equation (15) defining the reflected process is a fixed-point mapping of
 $\mathcal S\circ\mathcal R$
in the space
 $\mathcal E_T$
from (41). But this mapping
 $\mathcal S$
is 1-Lipschitz (see [Reference Whitt36]), and thus for small T the mapping
 $\mathcal S\circ\mathcal R$
is contractive. Therefore the fixed point exists and is unique by the classic theorem. Similarly to the proof of Lemma 12, the formula for the generator in (16) follows by Itô’s formula.
Proof of Lemma 5
Consider two copies
 $X_1$
and
 $X_2$
of this process, starting from
 $X_1(0) = x_1$
and
 $X_2(0) = x_2$
, where
 $x_1 > x_2 \ge 0$
. Let us couple them: that is, we create their copies on a common probability space, using the same driving Brownian motion W and Lévy process L. We can do this by Lemma 3. Next, we aim to prove that
 $X_1(t) \ge X_2(t)$
for all
 $t \ge 0$
simultaneously, with probability 1. This would automatically imply that
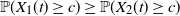 ${\mathbb P}(X_1(t) \ge c) \ge {\mathbb P}(X_2(t) \ge c)$
for all
 $t, c \ge 0$
, which is property (b) of Theorem 1.
Assume there exists a
 $t > 0$
such that
 $X_1(t) < X_2(t)$
. Let
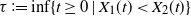 $\tau := \inf\{t \ge 0\mid X_1(t) < X_2(t)\}$
. By right-continuity of
 $X_1$
and
 $X_2$
, we must have
 $X_1(\tau) \le X_2(\tau)$
. But we cannot have
 $X_1(\tau) = X_2(\tau)$
, because then by the strong Markov property we would have
 $X_1(t) = X_2(t)$
for all
 $t \ge \tau$
(recall that
 $\tau$
is a stopping time). Therefore
 \begin{equation}X_1(\tau) < X_2(\tau),\quad \text{but}\ X_1(\tau-) \ge X_2(\tau-).\end{equation}
Thus
 $\tau$
is a jump time for both
 $X_1$
and
 $X_2$
, that is, for the Lévy process L. The displacement during the jump must be the same for
 $X_1$
and
 $X_2$
:
 \begin{equation}X_1(\tau) - X_1(\tau-) = -[L(\tau) - L(\tau-)] = X_2(\tau) - X_2(\tau-).\end{equation}
The contradiction between (47) and (48) completes the proof of Lemma 5.
Proof of Lemma 6
We can adapt the proof of [33, Proposition 4.3] to the case with jumps. We also point the reader to the construction in [11, Example 4.1], used to establish the duality between an absorbed and a reflected random walk. In the notation of [33, Proposition 4.3], we change the following: L is a two-sided Lévy process, that is,
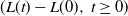 $(L(t) \,{-}\, L(0),\, t \ge 0)$
and
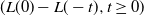 $(L(0)\,{-}\,L(-t), t \ge 0)$
are i.i.d. Lévy processes;
 $(B_r,\, r \ge 0)$
a two-sided Brownian motion, and
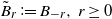 $\tilde{B}_r := B_{-r},\, r \ge 0$
; and we define the reflected process as
 \begin{equation}\begin{split}Y_s[\kern1pt y] & = y + \int_0^sp_*(V_r[y])\,\mathrm{d}r + \int_0^s\alpha(V_r[y])\,\mathrm{d}B_r + L(s),\quad s, y \ge 0, \\V_t[y] & = Y_t[y] + \sup_{0 \le s \le t}(Y_s[y])_-.\end{split}\end{equation}
We have other notation from [Reference Jansen and Kurt11]:
 \begin{equation}\begin{split}X_s^{(-t)}[\kern1pt y] &= y + \int_{-s}^tp_*(X_r[y])\,\mathrm{d}r + \int_0^s\alpha(X_r[y])\,\mathrm{d}B_r + L(s) - L(-t),\quad s, y \ge 0,\\W_t[x] &= x + \int_0^tp(W_s[x])\,\mathrm{d}s + \int_0^t\alpha(W_s[x])\,\mathrm{d}\tilde{B}_s - L(t),\quad t, x \ge 0.\end{split}\end{equation}
In that paper, the authors denote the driving Brownian motion inside the Itô integral by B, not W. In (50), the process W stands for the risk process, which we denote here by X. The process Y defined in the system (49) is the reflected jump-diffusion, which we also denote by Y. The first equation in (50) defines the non-reflected version of the process Y, starting from time
 $-t$
.
The proof can be adapted mutatis mutandis, with the following corrections. We use right-continuous versions with left limits instead of left-continuous versions. (We refer the reader to [33, page 431, Example 1].) The statement at the top of [33, page 438] that for every trajectory of B and L, and every
 $T > 0$
, there exists an
 $x' > 0$
such that
 $W_r(x') > 0$
for all
 $r \in [0, T]$
. In [Reference Sigman and Ryan33], this follows from the continuity of
 $X_s[y]$
in s. Now we no longer have this property. But in our case, this follows from the following comparison. Let
 $L(T) = x''$
. Take a copy of
 $\tilde{W}_t[x']$
without jumps, which we start from x’:
 \begin{equation*}\tilde{W}_t[x'] = x + \int_0^tp(\tilde{W}_s[x'])\,\mathrm{d}s + \int_0^t\alpha(\tilde{W}_s[x'])\,\mathrm{d}B_s.\end{equation*}
Take an
 $x' > 0$
such that
 $\tilde{W}_t[x'] > 0$
for all
 $t \in [0, T]$
. Then the copy of
 $W_t[x' + x'']$
starting from
 $x' + x''$
is estimated from below by
 $\tilde{W}_t[x']$
. This follows from the standard comparison arguments. Thus
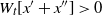 $W_t[x' + x''] > 0$
for all
 $t \in [0, T]$
.
Proof of Lemma 8
This is similar to the proof of Lemma 4, but we have to add a few details. Let us take a probability space with independent Brownian motion W and Lévy process L, and let
 $L_{{\varepsilon}}$
be a subordinator process with Lévy measure
 $\mu_{{\varepsilon}}$
, obtained from L by eliminating all jumps of size less than
 ${\varepsilon}$
and greater than
 ${\varepsilon}^{-1}$
. For consistency of notation, let
 $L_0 := 0$
. For every
 ${\varepsilon} \ge 0$
, we can represent
 \begin{equation}\tilde{Y}_{{\varepsilon}}(t) = y_{{\varepsilon}} + \int_0^tp_{\ast}(\tilde{Y}_{{\varepsilon}}(s))\,{\mathrm{d}} s + \int_0^t{\sigma}_{{\varepsilon}}(\tilde{Y}_{{\varepsilon}}(s))\,{\mathrm{d}} W(s) + L_{{\varepsilon}}(t) + N_{{\varepsilon}}(t),\quad t \ge 0.\end{equation}
Here,
 $N_{{\varepsilon}}$
is a non-decreasing right-continuous process with left limits, with
 $N_{{\varepsilon}}(0) = 0$
, which can increase only when
 $\tilde{Y}_{{\varepsilon}} = 0$
. We can rewrite (51) as
 \begin{equation}\tilde{Y}_{{\varepsilon}}(t) = \mathcal X_{{\varepsilon}}(t) + \int_0^tp_{\ast}(\tilde{Y}_{{\varepsilon}}(s))\,{\mathrm{d}} s + \int_0^t{\sigma}(\tilde{Y}_{{\varepsilon}}(s))\,{\mathrm{d}} W(s) + N_{{\varepsilon}}(t),\quad t \ge 0.\end{equation}
Here, we introduce a new piece of notation:
 \begin{equation}\mathcal X_{{\varepsilon}}(t) = y_{{\varepsilon}} + L_{{\varepsilon}}(t) + {\varepsilon} W(t),\quad t \ge 0.\end{equation}
The process
 $L(\!\cdot\!) - L_{{\varepsilon}}(\!\cdot\!)$
is non-decreasing. By Assumption 3 as
 ${\varepsilon} \downarrow 0$
, for every
 $T > 0$
,
 \begin{equation}{\mathbb E}\sup_{0 \le t \le T}|L(t) - L_{{\varepsilon}}(t)|^2 = {\mathbb E}(L(T) - L_{{\varepsilon}}(T))^2 = T\biggl(\int_0^{{\varepsilon}} + \int_{{\varepsilon}^{-1}}^{\infty}\biggr)\,x^2\,\mu({\mathrm{d}} x) \to 0.\end{equation}
 \begin{equation}{\mathbb E}\sup_{0 \le t \le T}|\mathcal X_0(t) - \mathcal X_{{\varepsilon}}(t)|^2 \to 0,\quad {\varepsilon} \downarrow 0.\end{equation}
Fix time horizon
 $T > 0$
, and consider the space
 $\mathcal E_T$
as above. Fix an
 $\mathcal X \in \mathcal E_T$
. Let us introduce a mapping
 $\mathcal P_{\mathcal X}$
:
 \begin{equation*}\mathcal P_{\mathcal X}(Z)(t) = \mathcal X(t) + \int_0^tp_{\ast}(Z(s))\,{\mathrm{d}} s + \int_0^t{\sigma}(Z(s))\,{\mathrm{d}} W(s),\quad 0 \le t \le T.\end{equation*}
For any
 $\mathcal X \in \mathcal E_T$
, let
 $\mathcal R_{\mathcal X} := \mathcal S\circ\mathcal P_{\mathcal X}$
. Then we can represent (52) as
 \begin{equation}Y_{{\varepsilon}} = (\mathcal S \circ \mathcal P_{\mathcal X_{{\varepsilon}}}(Y_{{\varepsilon}})) = \mathcal R_{\mathcal X_{{\varepsilon}}}(Y_{{\varepsilon}}).\end{equation}
As before, these mappings indeed map
 $\mathcal E_T$
into
 $\mathcal E_T$
. Similarly to the proof of Lemma 12, we can prove the following result.
Lemma 13. For
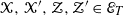 $\mathcal X, \mathcal X', \mathcal Z, \mathcal Z' \in \mathcal E_T$
, the following holds with constant
 $C_T$
from (42):
 \begin{equation}{\lVert{\mathcal R_{\mathcal X}(\mathcal Z) - \mathcal R_{\mathcal X'}(\mathcal Z')}\rVert}_{2, T} \le C_T{\lVert{\mathcal Z - \mathcal Z'}\rVert}_{2, T} + {\lVert{\mathcal X - \mathcal X'}\rVert}_{2, T}.\end{equation}
Proof. Since
 $\mathcal S$
is 1-Lipschitz, it suffices to show (57) for
 $\mathcal P_{\mathcal X}$
instead of
 $\mathcal R_{\mathcal X}$
. We can express the difference between
 $\mathcal P_{\mathcal X}(\mathcal Z)$
and
 $\mathcal P_{\mathcal X'}(\mathcal Z')$
as follows. For
 $t \in [0, T]$
,
 \begin{align}& \mathcal P_{\mathcal X} (\mathcal Z)(t) - \mathcal P_{\mathcal X'}(\mathcal Z')(t) \notag \\&\qquad = \mathcal X(t) - \mathcal X'(t) + \int_0^t [\kern1pt p_\ast(\mathcal Z(s)) - p_\ast(\mathcal Z'(s))]\,{\mathrm{d}} s + \int_0^t [{\sigma}(\mathcal Z(s)) - {\sigma}(\mathcal Z'(s))]\,{\mathrm{d}} W(s).\end{align}
Let I and M denote the second and third terms on the right-hand side of (58):
 \begin{equation}{\lVert{\mathcal P_{\mathcal X}(\mathcal Z)(t) - \mathcal P_{\mathcal X'}(\mathcal Z')(t)}\rVert}_{2, T} \le {\lVert{\mathcal X - \mathcal X'}\rVert}_{2, T} + {\lVert{I}\rVert}_{2, T} + {\lVert{M}\rVert}_{2, T}.\end{equation}
The last two terms on the right-hand side of (59) are estimated as in (45) and (46).
As before, for small enough T, the constant
 $C_T$
from (42) is strictly less than 1. Assume this is the case until the end of the proof. Then for every
 $\mathcal X \in \mathcal E_T$
, the mapping
 $\mathcal R_{\mathcal X}$
is contractive. Therefore it has a unique fixed point, which can be obtained by successive approximations:
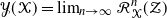 $\mathcal Y(\mathcal X) = \lim_{n \to \infty}\mathcal R_{\mathcal X}^n(\mathcal Z)$
. In particular, the equation (56) has a unique solution, which is obtained by successive approximations:
 \begin{equation*}Y_{{\varepsilon}} = \lim_{n \to \infty}\mathcal R^n_{\mathcal X_{{\varepsilon}}}(\mathcal Z).\end{equation*}
We can take
 $\mathcal Z = 0$
as the initial condition, or any other element in
 $\mathcal E_T$
. Applying the mappings in Lemma 13 once again, we have
 \begin{equation*}{\lVert{\mathcal R^2_{\mathcal X}(\mathcal Z) - \mathcal R^2_{\mathcal X'}(\mathcal Z')}\rVert}_{2, T} \le C_T^2{\lVert{\mathcal Z - \mathcal Z'}\rVert} + (1+ C_T)\lVert{\mathcal X - \mathcal X'}\rVert.\end{equation*}
By induction over
 $n = 1, 2, \ldots$
we obtain, with
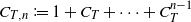 $C_{T, n} := 1 + C_T + \cdots + C_T^{n-1}$
,
 \begin{equation}{\lVert{\mathcal R^n_{\mathcal X}(\mathcal Z) - \mathcal R^n_{\mathcal X'}(\mathcal Z')}\rVert}_{2, T} \le C_T^n{\lVert{\mathcal Z - \mathcal Z'}\rVert}_{2, T} + C_{T, n}{\lVert{\mathcal X - \mathcal X'}\rVert}_{2, T}.\end{equation}
Let
 $n \to \infty$
in (60). If
 $C_T < 1$
, then
 \begin{equation}{\lVert{\mathcal Y(\mathcal X) - \mathcal Y(\mathcal X')}\rVert}_{2, T} \le \dfrac1{1 - C_T}{\lVert{\mathcal X - \mathcal X'}\rVert}_{2, T}.\end{equation}
Letting
 $\mathcal X := \mathcal X_0$
,
 $\mathcal X' := \mathcal X_{{\varepsilon}}$
in (61), and using (55), we complete the proof of Lemma 8.
Acknowledgements
Pierre-Olivier Goffard was partially funded by a Center of Actuarial Excellence Education Grant given to the University of California, Santa Barbara, from the Society of Actuaries. Andrey Sarantsev was supported in part by the NSF grant DMS 1409434 (with Jean-Pierre Fouque as a Principal Investigator) during this work. We are also grateful to two referees whose comments and constructive criticism led to significant improvements to this manuscript.