1 Introduction
A convertible bond (CB) is a very popular fixed-income corporate debt security. During the life of a CB, the holder has a right but not an obligation to convert the bond into a predetermined number of shares in the issuing company, or to hold the bond till expiration to receive coupons and the principal prescribed in the purchase agreement.
In a report that appeared in Reuters on 17 February 2021, Murugaboopathy [Reference Murugaboopathy13] stated that global companies were raising vast amounts of money through CBs in 2021, as soaring stock markets lifted demand for these bonds which gave investors the option to change into equity shares at a later date. In particular, Refinitiv data [15] showed that companies had issued $19.7 billion worth of CBs in the first 7 weeks of 2021, the biggest in 3 years for comparable periods. Further in the report, it was stated that ‘while U.S. bond yields are rising, interest rates generally are still at historically low levels, so it makes sense for many corporations to take advantage of this to raise capital for future uses’. Companies raised a record $190 billion through CBs in 2020, compared with $126 billion in 2019, the data showed.
In a similar report from an article from the Australian Financial Review on 25 March 2021, Shapiro [Reference Shapiro16] stated that in Australia, the CB market had been booming as more companies were opting for this form of financing. It stated that troubled travel stocks, including Webjet and Flight Centre in Australia and Carnival offshore, raised funds in this form to avoid hefty dilution when their share prices were down, while other companies such as Afterpay and Xero had also taken advantage of low interest rates and elevated share prices to raise cheap capital. They reported that zero coupons were in fact quite common of late, with Twitter, Airbnb, Dropbox, Beyond Meat and Ford all having issued zero-coupon bonds with conversion prices of between 40% and 70% above the share price within the past 6 weeks (of the article date).
Given the popularity of these CBs, finding accurate prices quickly for their values is an important problem. The theoretical framework for their pricing dates back to Ingersoll [Reference Ingersoll8] and Brennan and Schwartz [Reference Brennan and Schwartz4], who used the contingent claims approach. Brennan and Schwartz [Reference Brennan and Schwartz4] originally used the firm value as the underlying variable, and later, in 1980, they [Reference Brennan and Schwartz5] extended their analysis to include stochastic interest rates, but found that the effect of the stochastic term structure was negligible. However, models based on firm value are not easy to use in practice as they rely on parameters that are difficult to estimate. McConnell and Schwartz [Reference McConnell and Schwartz11] modified the approach, and instead of using the firm value as the underlying variable, used the stock price in a single-factor pricing model for a zero-coupon CB. The advantage of course is that the stock price is readily available in real markets.
An important feature of CBs is that the holder can choose to convert at anytime during the life of the bond. They can be referred to as ‘American-style’ because of the similarity with American options. Since McConnell and Schwartz [Reference McConnell and Schwartz11], there has been a large amount of research interest in the pricing of American-style vanilla CBs under the stock-value-based Black–Scholes (BS) [Reference Black and Scholes3] framework.
Almost all of this earlier work led to a numerical rather than an analytical solution of the underlying equations for the value of a CB. These include numerical approaches such as the binomial tree method [Reference Chambers and Lu6], Monte Carlo simulations [Reference Ammann, Kind and Wilde2, Reference Lvov, Yigitsbasioglu and El Bachir9] and the finite-difference method [Reference Tavella and Randall18]. However, numerical methods can be inefficient and very time-consuming, which may make their applications difficult in practice where fast accurate answers are needed. For this reason, a number of authors have focused on finding analytical solutions. Nyborg [Reference Nyborg14] presented a closed-form solution for CBs but with conversion only allowed at maturity (these are called European-style CBs). However, CBs are mostly American-style and unfortunately the pricing of American-style financial derivatives is usually a very challenging problem as they can be exercised at any time before the maturity date. Thus, for an American-style CB, the buyer has an additional right to convert the bond into stocks earlier during the life of the contract, which leads to a free boundary separating the region where it is optimal to hold the bond, from the region where it is optimal to convert it. This means that the optimal conversion price should be determined together with the bond price in the solution procedure. The unknown domain of the solution resulting from this additional right makes the pricing problem highly nonlinear and very difficult to solve.
In 2006, Zhu [Reference Zhu20] presented an analytical solution in the form of a Taylor series expansion for the American-style vanilla CB, using the homotopy analysis method (HAM). However, this series solution still requires a number of numerical integrations to be performed with complicated integrands and is very time-consuming. In a similar-style solution utilizing the HAM, Chan and Zhu [Reference Chan and Zhu7] then derived a solution for the price of a CB under the regime-switching model. In a different approach, Zhu and Zhang [Reference Zhu and Zhang21] used the semi-analytical integral equation method to formulate an integral equation representation for vanilla CB prices so that its value is written as the sum of a straight bond plus an option plus an extra premium associated with the holder’s early conversion right.
It should be noted (see, for example, Wilmott [Reference Wilmott19]) that there exist some CBs with more complicated structures such as a callability or a putability or a default feature. These options embedded in a CB can greatly affect the value of the bond.
In this paper, we price CBs without callability and putability features but with conversion being of the typical American-style. As we are interested in shorter-term CBs we assume constant interest rates (although, as stated earlier, some authors such as Brennan and Schwartz [Reference Brennan and Schwartz5] have found that the inclusion of stochastic interest rates has negligible effect on prices). This means that we can derive prices for coupon-bearing CBs simply from the zero-coupon bond prices. As such we will focus on deriving fast and accurate prices for the American-style zero CB. As most current analytic and pseudo-analytic approximations do not generate fast solutions and in fact are fairly slow, this is an important place to start. It is also sensible to start with a simpler model when introducing a new approach to a series solution in an already difficult problem with a free boundary. Our method also could in future be extended to higher-factor models.
Medvedev and Scaillet [Reference Medvedev and Scaillet12] proposed a new analytical approximation method that ‘is both computationally tractable and general enough to be successfully applied to a three factor diffusion model without jumps’. The main idea behind their approach is to substitute the optimal exercise rule with a simple suboptimal exercise rule to exercise the option as soon as its moneyness (measured in standard deviations) reaches some specific level. The American option price is given as an asymptotic series with respect to time to maturity. However, a major shortcoming of the method is that to determine the coefficients of their asymptotic series, one needs to solve complicated recursive systems. This is a problem as investors require fast answers.
In the following section of this paper, we provide a short summary of the main ideas used by Medvedev and Scaillet [Reference Medvedev and Scaillet12] to price American options. Then in Section 3 we adapt their method to find analytic approximations for CBs and provide the formulae for the coefficients of the series so that the method can be used without the need to solve any complicated recursive system, leading to faster results. In Section 4 we compare the performance of the model with those obtained using the Crank–Nicolson numerical scheme (see, for example, [Reference Wilmott19]). Generally, a good analytic approximation scheme for a free boundary problem yields either accurate prices for the financial product or accurate answers for the optimal exercise/conversion price. The formula in this paper though yields excellent and fast results for both the CB and the optimal conversion price. A short conclusion follows in Section 5.
2 The mathematical model
We begin by outlining the mathematical model used by Medvedev and Scaillet [Reference Medvedev and Scaillet12] to price American put options. The authors assume that the stock price S follows the usual risk-neutral lognormal process, that is,
 $$ \begin{align*} dS/S= (r-q)\, dt + \sigma \, dQ, \end{align*} $$
where
 $r, q$
and
 $\sigma $
are the constant risk-free rate, dividend yield and volatility, respectively, and Q is the Wiener process under a risk-neutral measure (see, for example, [Reference Wilmott19]). Then, if we denote the optimal exercise boundary (OEB) by
 $S_f(T-t)$
, it is well known that in the continuation region,
 $ S_f(T-t) \leq S < \infty $
, the value of the American put option
 $P(S,t)$
with exercise price X and expiry T satisfies the BS equation
 $$ \begin{align*} P_t+ \frac{\sigma^2S^2 }{2} P_{SS} + (r-q) SP_S-rP=0, \end{align*} $$
subject to
 $$ \begin{align*} & P(S,T) = \max(X-S,0),\nonumber \\ &\lim_{S\to \infty} P(S,t)= 0,\nonumber \end{align*} $$
and at
 $S_f(T-t)<X$
,
 $$ \begin{align} &P(S_f(T-t),t)= X-S_f(T-t),\nonumber \\ &P_S(S_f(T-t),t)=-1. \end{align} $$
Medvedev and Scaillet replace the smooth-pasting condition (2.1a) by an explicit exercise rule, and assume that the OEB has the form
 $$ \begin{align} S_f(T-t)=Xe^{-y\sigma\sqrt{T-t}}, \end{align} $$
where y is a decision variable determining the suboptimal rule. They make the change of variables
 $\theta = {(\ln (X/S))/ \sigma \sqrt {\tau }}$
and
 $\tau =T-t$
so that the problem becomes
 $$ \begin{align} \theta P_{\theta} +P_{\theta \theta} + \frac{1}{\sigma}[\sigma^2+2(q-r)]P_{\theta} \sqrt{\tau} -2 (P_{\tau}+rP)\tau=0, \end{align} $$
to be solved subject to
 $$ \begin{align} &P(-\infty,\tau)=0, \nonumber \\ &P(y,\tau)=X(1-e^{-\sigma y \sqrt{\tau}}). \end{align} $$
They assume the following asymptotic form near maturity (
 $\tau =0$
):
 $$ \begin{align} P(\theta, \tau)=\sum_{n=1}^{\infty} P_n(\theta) \tau^{n/2}. \end{align} $$
Substituting (2.5) into the partial differential equation (PDE) (2.3), the coefficients
 $P_n(\theta )$
can be determined from the recursive relationship
 $$ \begin{align} \theta (P_n)_{\theta} +(P_n)_{\theta \theta} + \frac{1}{ \sigma}[\sigma^2+2(q-r)](P_{n-1})_{\theta} -2rP_{n-2}-nP_n=0, \end{align} $$
with
 $P_0=P_{-1}=0$
. The authors provide the general solution for
 $(P_n)(\theta )$
as
 $$ \begin{align*} P_n(\theta)=C_n[p_n^0(\theta)\Phi(\theta)+q_n^0(\theta)\phi(\theta)]+[p_n^1(\theta)\Phi(\theta)+q_n^1(\theta)\phi(\theta)], \end{align*} $$
where
 $\Phi (\theta )$
and
 $\phi (\theta )$
are the cumulative distribution function and probability density function, respectively, of the standard normal distribution and
 $$ \begin{align*} \begin{array}{ll} p_n^0(\theta)=\theta^n + c_{n-2}\theta^{n-2}+\cdots+c_m\theta^m, &m=\text{mod}\,(n,2), \\[2pt] p_n^1(\theta)=a_{n-2}\theta^{n-2}+\cdots+a_m\theta^m, &m=\text{mod}\,(n-2,2),\\[2pt] q_n^0(\theta)=\theta^{n-1} + k_{n-3}\theta^{n-3}+\cdots+k_m\theta^m, &m=\text{mod}\,(n-1,2),\\[2pt] q_n^1(\theta)=b_{n-3}\theta^{n-3}+\cdots+b_m\theta^m, &m=\text{mod}\,(n-3,2). \end{array} \end{align*} $$
To determine the constants
 $c_i, a_i, k_i$
and
 $b_i$
, substitutions into (2.6) are required which then lead to solving a recursive system. The coefficients
 $C_i$
are found using (2.4). Then to find the put option price, they solve the optimization problem
 $$ \begin{align*} P(\theta,\tau) \approx \max_{y\ge\theta} P(\theta,\tau;y), \end{align*} $$
which determines the optimal exercise policy under the form (2.2). Hence, to find the American put option price necessitates solving complicated recursive systems which are time-consuming and computationally intensive, especially for the higher-order series expansions. In the following section we adapt their solution method to provide a series solution for the price of CBs in a form where the coefficients are exactly solved in terms of known mathematical functions.
3 An improved representation of the solution
In this section, we present the main result of the paper, whereby we give the series representation for the CB price, which depends on coefficients for which explicit formulae are given.
Theorem 3.1. An approximation to the zero-coupon American-style CB price with face value Z, and which can be converted to n shares (each with value S) before maturity T, is
 $$ \begin{align} V(x,\tau) = \max _{y\ge{x/ \sigma\sqrt{\tau}}}V(x,\tau;y) = V(x,\tau;\hat y), \end{align} $$
where
 $x= \ln ( {nS/ Z})$
,
 $ \tau =T-t$
and
 $$ \begin{align} V(x,\tau;y)=\left\{\begin{array}{@{}l@{}l} Z \bigg[e^{-r\tau} & + \ e^{-q\tau} e^{Ax+ B\tau}e^{-x^2/( 2\sigma^2\tau)}\displaystyle\sum_{i=1}^\infty -D_i\tau^{i/2}U\bigg(\displaystyle \frac{1+i}{2},\frac{1}{2},\frac{x^2}{2\sigma^2\tau} \bigg) \bigg] \\[10pt] & \qquad \qquad \text{for}\ x \le 0, \ \text{that is,}\ 0 \le S \le \displaystyle \frac{Z}{n} , \\[10pt] Z\Bigg[ e^{-r\tau} & +\ e^{-q\tau} e^{Ax+ B\tau}e^{-x^2/ (2\sigma^2\tau)}\displaystyle\sum_{i=1}^\infty \tau^{i/2} D_i \left\{ \displaystyle \frac{-2\sqrt{\pi}}{\Gamma(1+{i/2})}M\bigg(\displaystyle\frac{1+i}{2}, \frac{1}{2}, \frac{x^2}{2\sigma^2\tau} \bigg ) \right. \\[14pt] & +\left.\left. U\bigg(\displaystyle \frac{1+i}{2}, \frac{1}{2}, \frac{x^2}{2\sigma^2\tau} \bigg ) \right\} \right ] \\[10pt] & \qquad \qquad \text{for}\ 0 \le x \le \ln\bigg(\displaystyle\frac{n S_c(\tau)}{Z}\bigg), \ \text{that is,} \ \frac{Z}{n}\le S<S_c(\tau), \end{array} \right. \end{align} $$
with
 $$ \begin{align*} A= \frac{-r+q+{\sigma^2 / 2}}{ \sigma^2},\quad B= - \frac{(2q-2r-\sigma^2)^2 }{ \ 8\sigma^2}, \end{align*} $$
and M and U represent, respectively, the Kummer-M and Kummer-U functions; also known as confluent hypergeometric functions (see Abramowitz and Stegun [Reference Abramowitz and Stegun1]).
The coefficients
 $D_i$
are given by
 $$ \begin{align*} \displaystyle D_i={(\gamma_i-\epsilon_i)\bigg/ \bigg[e^{-y^2/2}\bigg \{ U\bigg(\frac{1+i}{2}, \frac{1}{ 2},\frac{y^2}{ 2}\bigg)- \frac{2\sqrt{\pi}}{\Gamma(1+{i/ 2})}M\bigg( \frac{1+i}{ 2},\frac{1}{2},\frac{y^2}{2}\bigg)\bigg\}\bigg]}, \end{align*} $$
where
 $$ \begin{align} \epsilon_i=\sum_{j=0}^i \alpha'_j\beta_{i-j} \quad \mathrm{and } \quad \gamma_i=\sum_{j=0}^i \alpha_j(\beta')_{i-j}, \end{align} $$
with
 $$ \begin{align} \alpha_n= \left\{ \begin{array}{@{}ll} 0 & n=1,3,5,\ldots , \\ \dfrac{(q-B)^{n/2}}{(n/2)!} & n=0,2,4,\ldots , \\ \end{array} \right. \end{align} $$
 $$ \begin{align} \alpha'_n= \left\{ \begin{array}{@{}ll} 0 & n=1,3,5,\ldots , \\ \dfrac{(q-B-r)^{n/2}}{(n/2)!} & n=0,2,4, \ldots , \\ \end{array} \right. \end{align} $$
 $$ \begin{align} \beta_m= \frac{(-Ay\sigma)^m}{ m!}, \quad m=0,1,2,3,\ldots , \end{align} $$
and
 $$ \begin{align} \beta'_m= \frac{((1-A)y\sigma)^m}{ m!}, \quad m=0,1,2,3,\ldots . \end{align} $$
The optimal conversion price (OCP) is given by
 $$ \begin{align*} S_c(\tau)=\frac{Z}{ n} e^{y\sigma \sqrt{\tau}}, \end{align*} $$
where an approximation
 $\hat \theta $
for the true early exercise level of moneyness is given by
 $$ \begin{align} \hat \theta(\tau)= \mathrm{min}_{\theta={x/ \sigma\sqrt{\tau}}} \{\theta\ge 0\mid \hat y(\theta,\tau)=\theta\}, \end{align} $$
and where
 $\hat y$
is implicitly defined in (3.1), or explicitly as
 $\mathrm {argmax} _{y\ge {x/ \sigma \sqrt {\tau }}}V(x,\tau ;y)$
. Note that in (3.4) the minimum value is taken with
 $\theta $
varying, or more specifically x varying and
 $\tau $
and
 $\sigma $
fixed.
Proof. The value of a zero-coupon CB,
 $V(S,t),$
with face value Z in which the bond can be converted to n shares at any time before maturity time T satisfies the following problem in the continuation region
 $0\le S<S_c(T-t)$
:
 $$ \begin{align} V_t+ \frac{\sigma^2S^2 }{ 2} V_{SS} + (r-q) SV_S-rV=0, \end{align} $$
subject to
 $$ \begin{align} &\phantom{\hspace{-25pt}}V(S,T) = \max(nS,Z), \end{align} $$
 $$ \begin{align} &\phantom{\hspace{-40pt}}V(0,t)=Ze^{-r(T-t)}, \end{align} $$
 $$ \begin{align} &\!V(S_c(T-t),t)=nS_c(T-t), \end{align} $$
 $$ \begin{align} &\phantom{\hspace{-35pt}}V_S(S_c(T-t),t)=n. \end{align} $$
First, we simplify the problem by letting
 $\displaystyle V'(S',t)= V(ZS',t)/Z$
, and substitute this into the above problem. For convenience, we can then drop the primes so that we solve the same equation but with conditions
 $$ \begin{align*} &V(S,T) = \max(nS,1), \\ &V(0,t)=e^{-r(T-t)}, \\ &V(S_c(T-t),t)=nS_c(T-t), \\ &V_S(S_c(T-t),t)=n, \end{align*} $$
where the new
 $S_c(T-t)$
refers to
 $S_c(T-t)/Z$
in terms of the original true OCP.
Now letting
 $\tau =T-t$
and
 $W(S,\tau )=V(S,t)-e^{-r\tau }$
, our problem in
 $0\le S < S_c(\tau )$
becomes
 $$ \begin{align} W_{\tau}=\frac{\sigma^2S^2 }{ 2} W_{SS} + (r-q) SW_S-rW, \end{align} $$
subject to
 $$ \begin{align} & \phantom{\hspace{-8pt}}W(S,0) = \max(nS-1,0), \end{align} $$
 $$ \begin{align} &\phantom{\hspace{-44pt}}W(0,\tau)=0,\qquad \end{align} $$
 $$ \begin{align} &W(S_c(\tau),\tau)=nS_c(\tau)-e^{-r\tau}, \\ &W_S(S_c(\tau),\tau)=n.\notag \end{align} $$
As when
 $\tau =0$
we must have
 $S_c=1/n$
, it is worthwhile to split the continuation domain into the two regions
 $0\le S<1/n$
and
 $1/n \le S < S_c(\tau )$
. Hence, in the continuation region of the CB,
 $W(S,\tau )$
satisfies equation (3.7) which in
 $1/n \le S < S_c(\tau )$
needs to be solved, subject to
 $$ \begin{align*} W(S_c(\tau),\tau)=nS_c(\tau)-e^{-r\tau} \end{align*} $$
and in
 $0\le S<1/n$
, subject to
 $ W(0,\tau )= 0$
.
Note. As indicated in (3.2), we will be deriving a solution of the form
 $$ \begin{align} V(\theta, \tau)=Z\bigg[ e^{-r\tau}+ g(\theta,\tau) \sum_{n=1}^{\infty} f_n(\theta) \tau^{n/2}\bigg],\end{align} $$
where
 $\theta = {x/ \sigma \sqrt {\tau }},\ x=\ln ({nS/ Z} )$
. With
 $\theta $
fixed, when
 $\tau =0$
,
 $g(\theta ,0) = \exp (-{\theta ^2 / 2})$
and
 $S=Z/n$
. Hence,
 $\max (nS,Z)=Z$
is implied by the form (3.9) and as such (3.6a) and so (3.8a) will be satisfied.
We also impose continuity of the value of the bond and its derivative across
 $S=1/n$
, that is,
 $$ \begin{align*} \lim_{S \to {1/ n}^-}W&= \lim_{S \to {1/ n}^+}W, \\ \lim_{S \to {1/ n}^-}W_S&= \lim_{S \to {1/ n}^+}W_S. \end{align*} $$
Note that for an exact, classical solution to the second-order PDE (3.7), we also require continuity of the second derivative
 $W_{SS}$
across
 $S={1/ n}$
, but this will be shown to follow automatically.
Making the substitutions
 $$ \begin{align*}S= \frac{1}{ n}e^{x}, \quad W(S,\tau)=e^{-q\tau}Y(x,\tau),\end{align*} $$
PDE (3.7) becomes
 $$ \begin{align} Y_{\tau} = \frac{\sigma^2}{ 2} Y_{xx} -\bigg[\frac{\sigma^2}{ 2} +(q-r)\bigg]Y_{x} -(r-q)Y. \end{align} $$
We solve (3.10) on
 $(-\infty , 0)$
, subject to
 $\lim _{x\to -\infty } Y=0 $
, and on
 $[0,y\sigma \sqrt {\tau })$
, subject to
 $Y(y\sigma \sqrt {\tau },\tau )=e^{q\tau }(e^{y\sigma \sqrt {\tau }}-e^{-r\tau }).$
The continuity conditions become
 $$ \begin{align*} \lim_{x \to 0^-} Y &= \lim_{x \to 0^+} Y, \\ \lim_{x \to 0^-} Y_x &= \lim_{x \to 0^+} Y_x. \end{align*} $$
Now letting
 $Y=u(x,\tau )\exp (Ax+B\tau ) $
, where
 $$ \begin{align*}A= - \frac{(r-q-{\sigma^2/ 2})}{ \sigma^2} \quad \text{and} \quad B= \frac{\sigma^2A^2}{ 2} - A\bigg(q-r+\frac{\sigma^2}{ 2}\bigg) - (r-q),\end{align*} $$
reduces (3.10) to the classical heat equation
 $$ \begin{align*} u_{\tau} = \frac{\sigma^2}{ 2} u_{xx}. \end{align*} $$
Finally, we let
 $\theta = {x/ \sigma \sqrt {\tau }}$
, to get
 $$ \begin{align} 2\tau u_{\tau}=u_{\theta\theta} + \theta u_{\theta}, \end{align} $$
to be solved on
 $-\infty <\theta <0$
, subject to
 $u(-\infty ,\tau )=0$
, and on
 $0\le \theta <y$
, subject to
 $$ \begin{align*} u(y,\tau)= e^{-Ay\sigma\sqrt{\tau}-B\tau} e^{q\tau} (e^{y\sigma\sqrt{\tau}}-e^{-r\tau}), \end{align*} $$
with continuity conditions
 $$ \begin{align*} \lim_{\theta \to 0^-}u &= \lim_{\theta \to 0^+}u, \\ \lim_{\theta \to 0^-}u_{\theta} &= \lim_{\theta \to 0^+}u_{\theta}. \end{align*} $$
Equation (3.11) admits separable solutions of the form
 $$ \begin{align} u(\theta,\tau)=e^{-\theta^2 / 2} \sum_{i=1}^{\infty} \tau^{i/ 2}\bigg [ C_i M\bigg(\frac{1+i}{ 2},\frac{1}{2},\frac{\theta^2}{ 2}\bigg )+D_i U\bigg(\frac{1+i}{ 2},\frac{1}{ 2}, \frac{\theta^2}{ 2}\bigg ) \bigg], \end{align} $$
where M and U are the Kummer-M and Kummer-U functions, respectively [Reference Abramowitz and Stegun1]. The separation constant used in (3.12) is
 $\lambda _i={i/ 2}$
where i is a positive integer, as power series in square root time have been found to be adequate in solving other free boundary problems involving linear diffusion equations (see, for example, Tao [Reference Tao17]). Equation (3.12) describes solutions valid for
 $0\le \theta <y$
for some nonzero constants
 $C_i, \ D_i$
to be determined, while for
 $\theta <0$
, consideration of the initial condition implies solutions of the form
 $$ \begin{align*}u(\theta,\tau)=e^{-\theta^2/ 2} \sum_{i=1}^{\infty} \tau^{i/ 2} F_i U\bigg(\frac{1+i}{ 2},\frac{1}{ 2},\frac{\theta^2}{ 2}\bigg ),\end{align*} $$
for constants
 $F_i$
to be determined.
Determining the solution coefficients. In order to satisfy the limit conditions at
 $\theta =0$
(or equivalently, the x conditions across
 $x=0$
), we require
 $$ \begin{align} F_i&=\frac{\Gamma(1+{i/ 2})}{ \sqrt{\pi}}C_i + D_i, \\ F_i&= -D_i, \nonumber \end{align} $$
so that we set
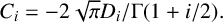 $ C_i={-2\sqrt {\pi }D_{i}/ \Gamma (1+{i/ 2})}.$
Note that for continuity at
 $x=0$
of the second derivatives, we require
 $$ \begin{align*}\frac{\sqrt{\pi} }{ \Gamma(1+{i/ 2})} iF_i = iC_i + \frac{\sqrt{\pi} }{ \Gamma(1+{i/ 2})} iD_i,\end{align*} $$
but this follows automatically from (3.13). Hence, derivatives of u of all orders are continuous at
 $x=0$
.
Hence, we have
 $$ \begin{align*} u(\theta,\tau)= \begin{cases} e^{-\theta^2/2}\displaystyle\sum_{i=1}^\infty -D_i\tau^{i/2}U\bigg(\frac{1+i}{ 2},\frac{1}{ 2},\frac{\theta^2}{ 2} \bigg ) \quad \text{for } \theta < 0, \\[12pt] e^{-\theta^2/2}\displaystyle\sum_{i=1}^\infty \tau^{i/2} D_i \bigg[\frac{-2\sqrt{\pi}}{ \Gamma(1+{i/ 2})}M\bigg(\frac{1+i}{ 2},\frac{1}{ 2},\frac{\theta^2}{ 2} \bigg )+ \displaystyle U\bigg(\frac{1+i}{ 2},\frac{1}{ 2},\frac{\theta^2}{ 2} \bigg )\bigg ] \\[6pt] \qquad \qquad \qquad \qquad \text{for } 0 \le \theta <y. \end{cases} \end{align*} $$
To find the constants
 $D_i$
, we apply the boundary condition at
 $\theta =y \ (>0)$
. The boundary condition there can be written in series form as
 $$ \begin{align*} u(y,\tau) = \sum_{i=0}^{\infty} (\gamma_i-\epsilon_i)\tau^{i/2}, \end{align*} $$
where
 $\epsilon _i$
and
 $\psi _i$
are defined in (3.3a)–(3.3e). Hence,
 $$ \begin{align*} \displaystyle D_i={(\gamma_i-\epsilon_i)\bigg/ \bigg[e^{-y^2/2}\bigg\{ U\bigg( \frac{1+i}{2},\frac{1}{2},\frac{y^2}{2}\bigg)-\frac{2\sqrt{\pi}}{ \Gamma(1+{i/ 2})}M\bigg(\frac{1+i}{2},\frac{1}{2},\frac{y^2}{2}\bigg)\bigg\}\bigg ]}. \end{align*} $$
Undoing the change of variables made in the proof yields the solution (3.2).
The condition for the early exercise (3.4) is based on knowing that with
 $\theta ={x/ \sigma \sqrt {\tau }}$
, if
 $\theta =\hat y(\theta ,\tau ),$
then the bond should be converted. This completes the proof of the theorem.□
4 Some comparisons with numerical solutions
In this section, we examine the performance of the formula in Theorem 3.1 for pricing near- and short-term CBs with that obtained numerically using (3.5) and (3.6a)–(3.6d). The solution method is designed for CBs with a short time to maturity, for example up to 1 year, as it is based on a short-term maturity expansion. However, we will also show that the method can still yield quite accurate results for longer-term CBs with 2–3 years to maturity. The numerical method we used was the Crank–Nicolson method with successive over-relaxation which is accurate to
 $O(dt^2,dS^2)$
(see Wilmott [Reference Wilmott19]) where
 $dt$
and
 $dS$
are the increments in time and asset price, respectively.
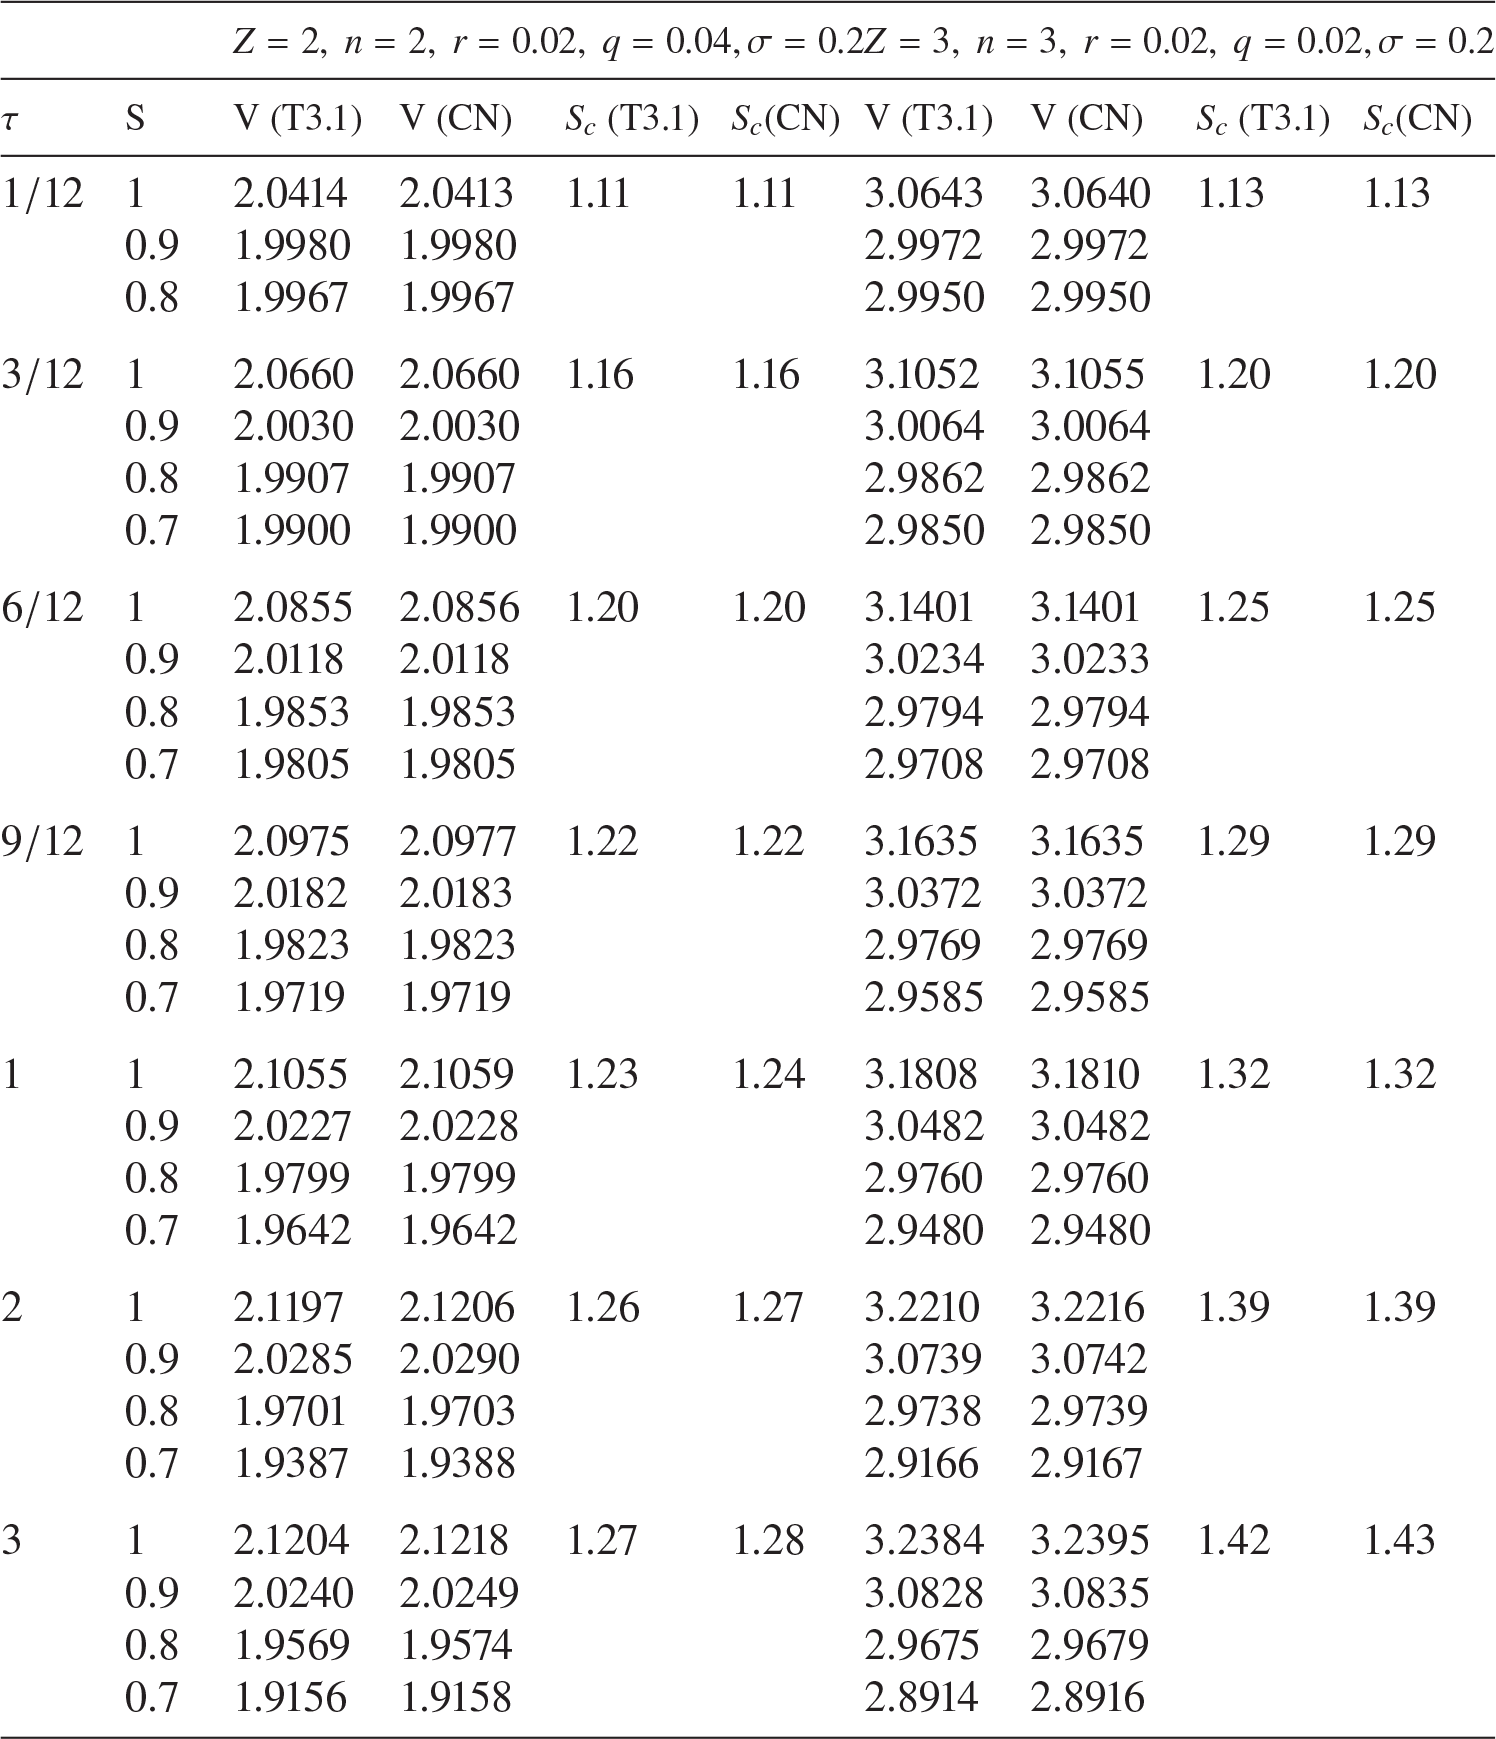
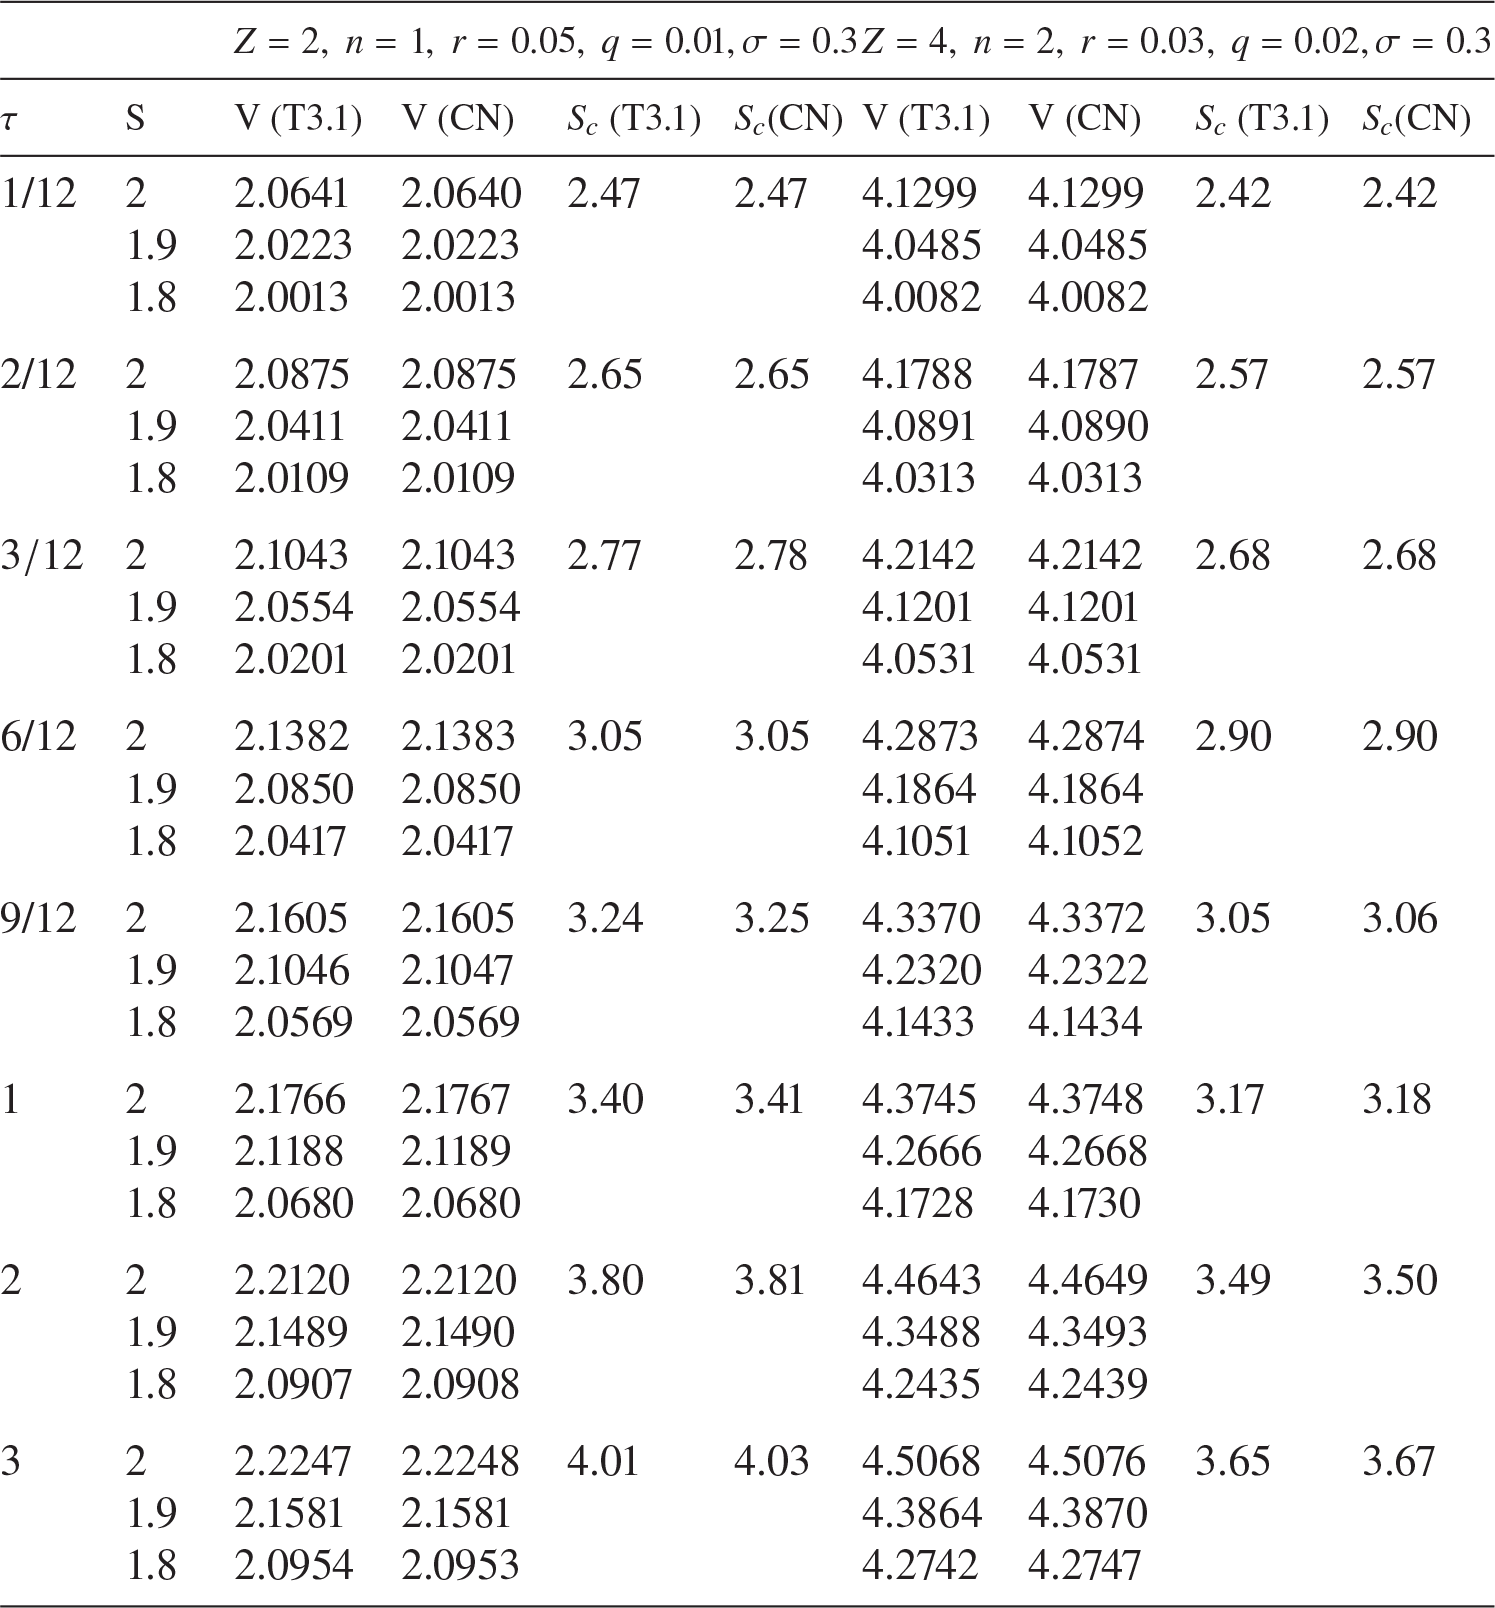
In Tables 1 and 2 (with
 $\sigma =0.2$
and
 $\sigma =0.3$
, respectively) we use a variety of other parameter values for
 $Z, n, r, q$
and S and give CB prices, V, and OCPs,
 $S_c$
, using maturity times from 1 month to 3 years. As can be seen in Tables 1 and 2, the CB price solutions agree remarkably well with relative errors for CBs with maturities under 1 year being less than
 $10^{-4}$
with mostly 5 significant figure accuracy, while there is still 3 or 4 significant figure accuracy for CBs with 3 years left to maturity.
Comparison of CB prices, V, and OCPs,
 $S_c$
, using Theorem 3.1 (T3.1) and the Crank–Nicolson numerical method (CN) with
 $\sigma = 0.2$
.

Comparison of CB prices, V, and OCPs,
 $S_c$
, using Theorem 3.1 (T3.1) and the Crank–Nicolson numerical method (CN) with
 $\sigma = 0.3$
.

Remarkably, the OCPs also agree extremely well in all cases including for the CBs with 3 years to maturity. Hence, the solution as described in Theorem 3.1 has shown to be remarkably accurate not only for the CB values but also for the OCPs.
As a further test, we adapted the classical Medvedev and Scaillet [Reference Medvedev and Scaillet12] method which prices American put options to price CBs, and compared the computational times of that method with that of the proposed solution in this paper. (Adapting the classical Medvedev and Scaillet [Reference Medvedev and Scaillet12] method involved making the change of variable
 $S=(1/n)e^{\theta \sigma \sqrt {\tau }}$
in (3.7) and boundary conditions (3.8a)–(3.8c). The transformed PDE is similar to that of equation (11) in Medvedev and Scaillet’s paper [Reference Medvedev and Scaillet12] with a negative sign in front of the third term. The new boundary condition is
 $W(y,\tau )=e^{y\sigma \sqrt {\tau }}-e^{-r\tau }.$
) Using the computer algebra package Maple [10] on a Dell x64 PC, Intel Core i7 processor, 16 GB RAM, CPU 3.6 GHz, we found that, using
 $n=5$
terms in the series expansions for CBs, the new method proposed in this paper took just over half a second (0.526 seconds) in real time or 0.328 seconds of CPU time, to yield the CB price. In comparison the classical method of Medvedev and Scaillet, which involves solving recursive systems, generally took over 6 times longer (3.202 seconds real time and 2.266 seconds of CPU time). Meanwhile, the numerical Crank–Nicolson method could take between 25 and 300 seconds depending on the time to maturity, or between 86 and 1000 seconds of CPU time. Given that fast and accurate answers are critical in practice, this is an important development in the area of CB pricing.
5 Conclusion
Given the popularity of CBs in recent years, it is not surprising that the issue of accurate and fast pricing of such bonds is so important. In this paper, we have provided an adaptation of the analytical approximation for American options by Medvedev and Scaillet [Reference Medvedev and Scaillet12] in order to price CBs. We have also made the new representation more efficient by providing formulae for the coefficients in the series solution in terms of well-known mathematical functions. This means that solutions of all orders can be found extremely quickly. We have also demonstrated that the solution yields very accurate results not just for the CB price but also for the optimal conversion price. It should be noted again that even though the solution in this paper yields accurate answers for CBs with maturities up to 3 years, it is designed for CBs with short maturity dates and so it seems reasonable to hold the interest rate, r, constant. It is also a sensible strategy in mathematical modelling to start with a simpler model when developing a new approach to a solution. However, this method can potentially be easily extended to multi-factor models with stochastic interest rates. New transformations, dependent on the coefficients in the interest rate model, need to be determined that would allow for separation of variables, in order to derive formulae for the functions in (3.9) as
 $f_n(\hat \theta , \eta )$
and
 $g(\hat \theta , \eta )$
where
 $\hat \theta $
and
 $ \eta $
are functions of
 $x, r$
and
 $\tau $
. This will be the subject of our future work.