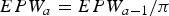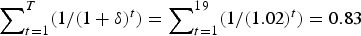1 Introduction
Aging populations are a challenge for retirement security and pension funds. The steep rise of expected years in retirement across industrialized countries (OECD, 2015) involves the necessity to delay employment exit and retirement. Policies that aim at postponed retirement usually restrict access to public pensions by raising the normal retirement age and imposing benefit reductions in case of early retirement.Footnote 1 While such a financial incentive can induce people to stay in gainful employment for further years, a key issue is that retirement choices require pension knowledge based on the complex information. Learning more about the perception and understanding of financial incentives is crucial to implement retirement policies successfully.
The current state of the literature is that financial incentives are a fairly reasonable way to influence the timing of retirement.Footnote 2 The quasi-experimental literature does not coincide in all details but by and large, there is widespread agreement that people respond to retirement incentives. However, recent studies have stressed that misinformed individuals do respond to perceived (but incorrect) pension information (Chan and Stevens, Reference Chan and Stevens2008) and that the reaction to financial incentives not only depends on their size but also on their perception (Liebman and Luttmer, Reference Liebman and Luttmer2015). One further remarkable result is that the stepwise introduction of information letters on individual expected pension payments, the annual US Social Security Statements, has increased pension knowledge but had no effect on actual retirement behavior (Mastrobuoni, Reference Mastrobuoni2011). Whether there is no reason to change retirement choices because workers already behave optimally or whether the information contained in the pension statement is not sufficient to improve their retirement decisions remains an open question.
In this paper, we aim to contribute to the resolution of this puzzle. For this purpose, we establish an ideal experiment where participants (N: 318) are asked to make choices about their retirement age. Subjects are randomly assigned to different schemes of financial incentives and information provision. Variation in financial incentives is induced by confronting subjects with two alternative payoff structures of pension benefits.Footnote 3 Variation in pension knowledge is obtained by facing subjects with two different information regimes: while all subjects know their pension annuity, only some are informed about the forward-looking expected pension wealth (EPW hereafter). We test how strong people respond to the financial incentive and whether they respond differently once the present value of pension benefits (the EPW) makes the financial consequences of a given retirement age more salient. In contrast to only knowing the annuity, we investigate whether retirement choices differ if people can draw on explicit information about the present value of their EPW. This piece of information is not included in typical pension information letters that are sent out to future retirees in many countries.Footnote 4
The controlled environment of the laboratory allows us to test ceteris paribus conditions on information provision and the resulting differences in the functioning of financial incentives. Some parameters are difficult to control outside the laboratory and since valid data on the interaction between financial incentives and information are not available it would not be possible to resolve the puzzle raised above without this type of experimental test. To make the experimental situation as realistic as possible, the design is couched into the institutional setting of the German public pension system.Footnote 5 Moreover, a considerable share of participants is sampled from older workers in close distance to retirement. Our experimental design builds on the one by Fatas et al. (Reference Fatas, Lacomba and Lagos2007), who test retirement decisions in an experimental framework. While they test how the distribution of benefits over time (lump-sum vs. annuity)Footnote 6 affects retirement outcomes, we extend this approach by investigating the combined effect of financial incentives and information provision on retirement timing. To the best of our knowledge, this experimental test of retirement decisions is a novel one.
The results indicate that, in line with previous quasi-experimental estimates for Germany (e.g. Hanel, Reference Hanel2010; Giesecke, Reference Giesecke2017), individuals delay their retirement choices considerably in response to financial incentives. Strikingly, individuals react less to these incentives if they are not informed about the EPW and only know their pension annuity. This piece of evidence is important in resolving the puzzle of why typical information letters on expected pension payments do not affect actual retirement behavior. Inducing a stronger response in retirement choices requires information on a forward-looking measure of pension benefits, making the financial consequences of retirement choices become more salient to the decision maker. Importantly, this can improve the effectiveness of financial incentives in policies that aim at raising the retirement age.
Our paper also adds to the literature on financial decision-making abilities and financial literacy (see Lusardi and Mitchell, Reference Lusardi and Mitchell2014, for a recent review). Many studies have shown a positive link between financial literacy and retirement planning or wealth accumulation (Ameriks et al., Reference Ameriks, Caplin and Leahy2003; Lusardi and Mitchell, Reference Lusardi and Mitchell2007; Bucher-Koenen and Lusardi, Reference Bucher-Koenen and Lusardi2011; van Rooij et al., Reference van Rooij, Lusardi and Alessie2012). It has also been made clear that people have time-inconsistent preferences concerning their payout of retirement savings (lump-sum vs. annuity, see Schreiber and Weber, Reference Schreiber and Weber2016) and that they do have difficulties in valuing annuities (Brown et al., Reference Brown, Kapteyn, Luttmer and Mitchell2017). Based on this literature and our concern of whether people are able to calculate forward-looking incentive measures from future earnings and pension benefits, we shed more light on how retirement decisions depend on grasping basic actuarial principles. In this paper, we examine the ability to understand the concept of the EPW and to calculate it with all relevant information at hand. If financial literacy is high, we find that – especially older workers – are more likely to maximize benefits. Retirement planning is enhanced once people understand the patterns that determine their pension wealth as a function of the retirement age.
This paper is organized as follows. Section 2 provides the experimental design, the variation of treatment parameters, and hypotheses to be tested. Section 3 describes details on the experimental procedures and the recruitment process of older workers. Section 4 outlines the results and Section 5 concludes.
2 Experimental design
Our experimental design aims to elicit preferences for the retirement age under alternating schemes of financial incentives and information treatments. The experiment is framed as an individual retirement decision of late-career working individuals who repeatedly decide whether to retire immediately or to continue working.Footnote 7 The design implicitly allows for the presence of labor (and income) although we do not explicitly model it. This involves the assumption that participating subjects are indifferent between a marginal change in the utility from labor income and disutility from labor.Footnote 8
2.1 Retirement decisions in the laboratory
The point of departure is at age 58. Participating subjects are asked whether to work or to retire in the following year. Subjects who decide to retire will receive pension benefits as an annuity starting at age 59. The annuity is a function of the retirement age and is paid for the remaining lifetime. The actual lifetime of each subject is determined by a random process based on recent mortality tables covering the entire German population (Federal Statistical Office, 2012). Survival probabilities are averaged for men and women and participants are explicitly informed about them in the instructions (see Table H.3.2.1, Appendix H). Retirement is defined as an absorbing state and thus no further work is possible after retirement. Subjects who decide to continue working one additional year and survive the respective year will face the same work-retirement decision again in the following year. The repeated decision situation implies that they have grown older by 1 year (now: age 59), having to decide again whether to work at that age or to retire instead.
The decision situation recurs as long as the subject keeps working and neither retires nor dies. However, decisions are restricted to a maximum of 12 decisions in the age window 58–69. At age 69, participants can decide for the last time whether they want to retire immediately or to continue working given that they have not retired before and are still alive. If they chose to continue working in this last period, they mandatorily retire at age 70. Subjects who decide to continue working but do not survive at that time do not receive any pension benefits.Footnote 9 The decision situation yields a zero payoff in this case.Footnote 10 We consider these observations as right-censored since the choice of the retirement age remains unobserved.
Subjects are informed about their survival status after each period. Once subjects have retired, an additional survival year yields one further year of pension benefits. After subjects have actively decided upon work and retirement over 12 periods, they passively receive information concerning their survival status and benefit payments. The experiment ends after all subjects have died.Footnote 11
2.2 The baseline treatment: declining EPW
The payoff structure of the baseline treatment is characterized by an EPW that declines over age. The EPW is defined as the sum of all future pension benefits as a function of the retirement age, calculated as the product of the pension annuity times the life expectancy at the current age. The baseline payoff structure is illustrated graphically in Figure 1 (dashed line) and with corresponding numerical values in the left panel of Table 1 (BASELINE). A subject who decides to retire at age 58 will receive a pension annuity of 11,047.59 token (laboratory units) which translates into an EPW of 272,655 token (24.68 × 11,047.59 = 272,655).Footnote 12, Footnote 13 After reaching a peak value at age 60, the EPW monotonically declines (from 280,785 to 190,934 token). This payoff structure is illustrated graphically in Figure 1 (dashed line).
Pension Benefits as a Function of the Retirement Age. (a) Pension Annuity (b) Expected Pension Wealth (EPW).

Payoff structure at age 58

LE, life expectancy.
Note: The reference person is assumed to retire at age 65 (factor = 1), having contributed at the average earnings level for 40 years, evaluated at the current (2014) annuity value of 28 Euros/earnings point (40 × 1 × 28 × 12 = 13,440 Euro). The reference person is indicated by bold values.
Subjects who survive the 58th living year and decide not to retire face a new decision situation as summarized in the left panel of Table 2 (BASELINE). Now, at age 59, all values of the EPW are updated conditional on having survived one additional year.Footnote 14 As long as individuals keep working and do not retire the EPW is updated conditional on having survived at each subsequent age.Footnote 15
Payoff structure at age 59

LE, life expectancy.
Note: The reference person is assumed to retire at age 65 (factor = 1), having contributed at the average earnings level for 40 years, evaluated at the current (2014) annuity value of 28 Euros/earnings point (40 × 1 × 28 × 12 = 13,440 Euro). The reference person is indicated by bold values.
2.3 Intervention I: financial incentives
To investigate how financial incentives affect retirement decisions we contrast the baseline treatment to an alternative payoff structure which is characterized by a constant EPW. Comparing with the baseline treatment, these payoffs differ by an adjustment factor which is a 3% reduction rate for every year of retirement previous to the normal retirement age of 65 (i.e. ‘early retirement’) and a 5% premium for every year of retirement after age 65. This type of actuarial adjustment essentially relates to real benefit adjustments in the German public pension system.Footnote 16 According to the right panel of Table 1, subjects who decide to retire immediately (in the first round of the experiment) receive an annual pension of 8,727.60 token. After age 60, the EPW remains constant over age at 238,667 token. In contrast to the baseline treatment, this payoff structure is actuarially neutral.
The question is whether individuals tend to work longer and retire later under constant EPW (adjustment factor > = <1) in contrast to the baseline payoffs with declining EPW (adjustment factor = 1). The adjustment factor is the only parameter that is varied between the two payoff structures, holding everything else constant. This implies that we only alternate the slope of the EPW as a function of the retirement age. The fundamental difference between the two payoff structures is apparent from Figure 1. At the reference age of 65, the two payoff profiles intersect because they generate an identical pension annuity of 13,440 Euros per year. The baseline treatment (declining EPW, dashed line) produces a higher EPW at each retirement age below the intersection and a lower one above the intersection. Thus, retirement at early ages (58–64) is financially more attractive in the baseline treatment. However, at higher ages (66–70) retirement is financially more attractive when facing the payoff structure involving a constant EPW.
Under both schemes of financial incentives the EPW increases between age 58 and 60 and then declines (Factor = 1) or remains constant (Factor > = <1). The purpose of this pattern is to isolate retirement decisions from risk attitudes.Footnote 17 It enables us to distinguish strongly risk-averse subjects who retire as early as possible (corner solution at age 58) from expected payoff maximizers who retire at age 60 (peak value/unique maximum: declining EPW) or between age 60 and 70 (non-unique maximum under constant EPW). Aside from this detail, our design reflects the long-standing German retirement window with old age pensions available early at age 60 or 63 and a normal retirement age that is currently shifted from 65 to 67.
2.3.1 Relevance of the financial incentive
The magnitude of the adjustment rate (3% reduction; 5% premium) is a relevant intervention when comparing with its real counterpart from the field. The reason for making the financial incentive within our experiment very similar to benefit adjustments in the German pension system is that these adjustments have been shown to induce a considerable shift of the retirement age.Footnote 18 Quasi-experimental estimates of the average delay of retirement in response to benefit adjustments range between 14 months (Hanel, Reference Hanel2010, using administrative data) and 13.2 months (Giesecke, Reference Giesecke2017, using survey data). Adopting the adjustment rates from the field not only ensures the relevance of the intervention but also enables us to relate our results to these estimates.
We also aim at making the retirement framing in the laboratory as realistic as possible. Since all experiments are conducted in Germany, the experimental design is anchored to the German public pension system.Footnote 19 Implementing financial incentives that are a close fit to the real pension insurance helps to improve the perception of the retirement framing in the laboratory on average and facilitates putting the intervention into the institutional context.
2.4 Intervention II: information on the EPW
The major contribution of this paper is to show how the functioning of financial incentives differs across information treatments. Learning more about this source of heterogeneity is important because the perception of financial incentives may depend on whether the decision maker is informed about the expected present value of pension wealth (EPW). We aim to test whether this type of information influences the choice of the retirement age.
For this purpose, we distinguish three levels of information provision. First, the BASIC treatment provides subjects only with annual pension benefits (as a function of the retirement age), remaining life expectation (in years) according to each retirement age and conditional survival probabilities. Based on this information, subjects have all relevant information at hand to calculate the EPW from the perspective of any age. To make a decision based on the EPW, however, they must be capable to understand the concept and to calculate it.
Second, subjects in the INFO treatment receive similar information as in the BASIC treatment but are additionally endowed with numerical values of the EPW and a short explanation of how it is calculated (underlined paragraph in the instructions). Providing this key information makes the payoff structure of the two systems transparent. Subjects who are not able to calculate the EPW by themselves can use this information for the choice of their retirement age.
Finally, we introduce an INFO PLUS treatment. Subjects receive similar information as in the INFO treatment but are additionally endowed with an explanation of the economic meaning of the EPW. In this treatment, the instructions include an explicit verbal statement on how the payoff structure evolves over age to further facilitate the comprehension also for those subjects who have difficulties to grasp the payoff structure in terms of numbers. Since retirement outcomes do not significantly differ between INFO and INFO PLUS treatments, these are uniformly summarized as INFO treatments in the subsequent presentation of results.
2.5 Sensitivity analysis
2.5.1 Subject pool
While university students are easy to recruit (existing subject pool and standardized recruitment process), conducting the experiment on older workers substantially improves the external validity of our results. The experiment is framed as a work-retirement trade-off which is realistically faced by a group of actively employed persons who are, per definition, in close distance to retirement. 25% of our total observations are obtained from actively employed older workers of age 45–58. These workers have obtained a substantial amount of work experience and are likely to have made some retirement considerations. We thus test for differential retirement behavior of this group compared with students.
2.5.2 Decision structure
So far, we have outlined a sequential decision structure where people move from one period to another and repeatedly evaluate their retirement decision. This is an extension of the approach taken by Fatas et al. (Reference Fatas, Lacomba and Lagos2007), who test one-stage retirement decisions in the laboratory. To provide an anchor point to this study, we also compare one-stage decisions to sequential ones. This allows to investigate behavioral differences under two framings of an otherwise identical decision.
One-stage treatments differ only to the extent that they involve a modified decision structure, asking subjects to decide upon their retirement age only once and for all. They are offered a menu of retirement ages from 58 to 70 from which to choose. Aside from the (ex ante) one-stage choice, everything else (annuities, life expectancy etc.) remain unchanged with subjects facing the same payoff structure under a given scheme of financial incentives. Thus, the underlying decision problem is identical under both one-stage and sequential decisions.
2.6 Treatment overview
In total, the experiment consists of 14 treatments as summarized in Table 3. The treatment variables split into financial incentives (declining vs. constant EPW), information provision (BASIC vs. INFO) and the interaction of the two. To ensure the functioning of the experimental setting, in each treatment only one parameter is varied while holding everything else constant. All subjects are randomly assigned to treatments.
Treatment overview

DEC, declining EPW; CON, constant EPW; SEQ, sequential decisions; ONE, one-stage decisions.
2.7 Hypotheses
We test two central hypotheses that each divide into two sub-hypotheses. Hypotheses 1a and 1b are based on the theoretical expectation that individuals make retirement decisions using forward-looking measures (see e.g., Burtless, Reference Burtless1986; Krueger and Meyer, Reference Krueger and Meyer2002) and that financial incentives influence retirement choices, the latter being the principal finding of the quasi-experimental literature (as summarized in the introduction). Based on this expectation, hypotheses 1 and 2 are formulated in a way that presumes identical outcomes under two different schemes of information provision:
Hypothesis 1a
Consider basic information (BASIC): In contrast to the baseline treatment (declining EPW) individuals choose a higher retirement age, on average, when confronted to the constant EPW.
Hypothesis 1b
Consider further information (INFO/INFO PLUS): In contrast to the baseline treatment (declining EPW) individuals choose a higher retirement age, on average, when confronted to the constant EPW.
The general assumption is that individuals make retirement decisions under complete information about their retirement benefits and are able to calculate their retirement incentives. However, if the information is incomplete and gaining knowledge on the computation of retirement incentives is costly, then retirement outcomes may differ by information and pension knowledge. Since recent studies have raised concerns about the ability to calculate forward-looking incentive measures (Mastrobuoni, Reference Mastrobuoni2011) and to value annuities (Brown et al., Reference Brown, Kapteyn, Luttmer and Mitchell2017) we also test whether retirement decision making differs across information treatments within a given payoff structure. Hypotheses 2a and 2b presume that information on the EPW do not influence retirement decisions:
Hypothesis 2a
Under declining EPW (baseline), retirement timing does not differ, on average, across information treatments (BASIC vs. INFO).
Hypothesis 2b
Under constant EPW, retirement timing does not differ, on average, across information treatments (BASIC vs. INFO).
3 Experimental procedures
A total of 318 subjects participated in the computer-based experiment using z-tree (Fischbacher, Reference Fischbacher2007). The experimental sessions were conducted between December 2014 and February 2016 at the Essener Labor für experimentelle Wirtschaftsforschung (elfe).Footnote 20
3.1 Subject pool and recruitment process
The pool of participants splits into 239 students (bachelor and master level) from the University of Duisburg-Essen and 79 older workers (age 45–58) in active employment.Footnote 21 We used the standard electronic recruitment procedures via ORSEE (Greiner, Reference Greiner, Kremer and Macho2004) to collect the subject pool of university students.
To recruit older workers, we sent invitation emails to about 3,350 employees with workplaces nearby the laboratory (in the region of Essen, Germany). This included about 350 non-scientific staff members at the University of Duisburg-EssenFootnote 22 and 3,000 public administration workers in the cities of Essen, Gelsenkirchen, Bottrop and Oberhausen.Footnote 23 We only sent messages to professional email accounts (available on the institutions’ homepages) to ensure that people are actively employed.
The invitation email very generally stated the purpose to recruit older workers for participation in a scientific study on retirement behavior. The message also stated that participants could earn money depending on their individual decision making throughout the experimental procedure. We made clear that our research is of public interest only, has no commercial background and is conducted on behalf of the German Science Foundation (DFG). We finally asked recipients who fulfill all participation criteria (age 45–58, German-speaking, in active employment) to respond if they are interested in participation.
We collected responses and then made appointments for the experiment. To raise the participation rate we offered appointments very flexibly, leaving us with about three participants per session on average. A few days in advance of each arranged appointment we sent an information email to participants, including a reminder and all relevant details (day, time, location plan). The effective participation rate was 2.4% (79/3,350).
While not representative for the German population (see Table B2, Appendix B, for socio-economic details), the subject pool of older workers has useful properties for the experiment. First of all, it encompasses a group of older workers in close distance to retirement. In contrast to the typical student subject, they are likely to have made some retirement planning. Second, these people are only contacted if they have an active email account in one of the mentioned institutions and are thus actively employed by definition. And finally, respondents do have a basic level of computer literacy which ensures that they are able to go through the computer-based procedure.
3.2 Sequence of events
All treatments include the same sequence of events, splitting into six subsequent steps (Figure 2). Participants first read the instructionsFootnote 24 while having the opportunity to pose clarifying questions (part 1). To ensure that everybody understands the instructions and the general proceeding, participants have to answer four control questions (part 2). The actual decision part is the core of the experiment (part 3), including the treatments summarized in Table 3.
Sequence of Events.

The retirement decision part is followed by three incentivized math questions (part 4) to test the ability of calculating the EPW. From the results of these questions, we construct a financial literacy score (0 = low financial literacy; 3 = high financial literacy) that is used to further analyze the understanding of actuarial considerations underlying the decision problem (see Appendix E). The score yields information on whether people are at least able to make payoff maximizing decisions although they may have other preferences.
In part 5 we conduct a test to elicit risk preferences as proposed by Holt and Laury (Reference Holt and Laury2002). Participants are offered ten paired lotteries as summarized in Table A1 (Appendix A). The corresponding choices have real monetary consequences and are thus incentive compatible. We map these choices into a measure of risk attitudes on a scale from 0 (very risk-averse) to 10 (very risk-loving). We use this measure to control for risk attitudes in subsequent regressions.Footnote 25
The final step is a questionnaire on socio-economic questions (part 6). Among students, we asked for age, sex, number of siblings, final school grade (German Abitur), field of studies, number of semesters studied and whether at least one parent is already retired. Among older workers, the questionnaire comprised age, sex, number of children, marital status, education, employment, employment of spouse and household net income. All subjects, both students and older workers, were asked to report their ex-post satisfaction with the experienced retirement system (0–10), their risk attitude (0–10) and health status (0–10). The two subject pools are summarized according to these variables in Table B1 (students) and 8 (older workers) in Appendix B.
The instructions were handed out to the subjects before the beginning of the experiment without mentioning the existence of the second part. At the end of the experiment, subjects were privately paid with an exchange rate of 15,000 units (students) and 10,000 units (older workers) of laboratory token = 1 EUR (around USD 1.12 at that time). The experiment took less than 90 min and the average payoff among students was 18.8 EUR (around 21.1 USD), ranging between a minimum of 1.6 EUR and a maximum of 32.4 EUR. The average payoff among older workers was 28.1 EUR (about 31.5 USD), ranging between a minimum of 1.5 EUR and a maximum of 43.9 EUR. The expected payoffs are real average hourly wages that intend to reflect opportunity costs and are thus 50% higher for older workers. To further ensure a functioning incentive structure, we did not pay a lump-sum amount/show-up fee. Payoffs depended only on retirement decisions, the number of correct answers on math questions, paired lottery choices of the risk-aversion test, and luck concerning the number of survival periods.
4 Results
The main results outlined in Sections 4.1 and 4.2 are based on 223 total observations from sequential decisions. Those parts of the analysis that look at retirement decisions alone, i.e. tests and graphs, exclude 19 right-censoredFootnote 26 observations and leave us with a total of 204 observations.
4.1 Financial incentives and information provision
Treatment comparisons show a significant difference in retirement timing of 2.4 years between the two schemes of financial incentives but only if people are informed about the EPW (Table 4, column 1 and 2). A payoff structure that makes early retirement less attractive (constant EPW) induces a large delay of the retirement age in comparison with the baseline treatment (declining EPW). In light of this result, which is strongly in line with the quasi-experimental retirement literature, we do not reject hypothesis 1b. However, we do reject 1a because the measured difference is small and insignificant in the BASIC information treatment.
Differences in retirement decisions: non-parametric and parametric tests

Source: Own calculations based on experimental data.
Note: z-statistic: non-parametric Wilcoxon rank-sum test. t-statistic: two-sample t-test on differences in means. 19 censored observations are excluded from the sample.
A graphical summary of the main resultFootnote 27 in Figure 3 illustrates how retirement choices differ between the two payoff structures in BASIC treatments (panel a) and in INFO treatments (panel b). Under declining EPW (solid line: red), retirement is characterized by a remarkable peak at age 60 with only few retirement entries after age 65. Under constant EPW (dashed line: blue) retirement choices are rather evenly distributed across the age window 58–70 and are more pronounced at higher ages.
Differences in Retirement Decisions: Graphical Evidence. (a) BASIC (N:79) (b) INFO (N:125).

Despite some similarities of the principal patterns across information treatments, the amount of available information induces substantial differences in retirement decision making. Comparing the two panels in Figure 3 makes clear that not only the peak at age 60 (declining EPW) is more pronounced in INFO treatments. It also suggests that the shift of retirement entries towards higher ages (constant EPW) is larger once people are informed about the EPW.
Ordinary least squares (OLS) estimates of the treatment effect, conditional on a range of additional variables, are in line with previous tests and graphical evidence (Table 5).Footnote 28 Our preferred estimate of the treatment effect is a retirement delay of 1.9 years among those who face a constant EPW relative to the baseline and are explicitly informed about it (interaction term, specification 6). This estimate is robust against the subject pool, risk preferences, health status, gender, age (a measure of distance to retirement), and financial literacy.
Financial incentives, information provision, and retirement decisions

Source: Own calculations based on experimental data.
Note: Reported values are coefficients from OLS regressions. *p<0.10, **p<0.05, ***p<0.01. Censored observations are either excluded from the sample (specification 3) or controlled for.
4.2 The role of available information
Two things are important when looking at differential retirement outcomes across information treatments (BASIC vs. INFO) while holding the payoff structure constant. First, a measurable difference in retirement outcomes only occurs for subjects who face a declining EPW but not for those under constant EPW (Table 4, column 3 and 4). Second, the measured difference under declining EPW is mostly driven by the peak value at age 60. This is evident from Figure 4 (left panel), showing that this unique payoff maximizing retirement age is chosen by 46% of subjects in the INFO treatment while only 26% make this choice in the BASIC treatment. We thus reject hypothesis 2a, meaning that people are significantly more likely to chose the payoff-maximizing peak value under declining EPW once they are explicitly informed about the EPW (t-statistic: 2.09). Under constant EPW, we do not find such differences across information treatments and thus hypothesis 2b is not rejected. The latter finding is rather unsurprising since, under constant EPW, retirement should be evenly distributed across age in both BASIC and INFO treatments.
The Role of Available Information: Graphical Evidence. (a) Declining Expected Pension Wealth (EPW) (N:102) (b) Constant EPW (N:102).

Strikingly, subjects recognize payoff patterns differently depending on whether explicit information on the EPW is available or not. They tend to move towards a benefit maximizing retirement age once they become aware of the payoff structure. What we can learn is that informing people about an economically meaningful forward-looking measure can make financial incentives more effective. Policies that aim at raising the retirement age by making early retirement financially less attractive (e.g. by benefit reductions) would exhibit a higher responsiveness if less people only react to their own perceived but incorrect pension incentives (a phenomenon first noted by Chan and Stevens, Reference Chan and Stevens2008).
4.3 Sensitivity analysis
We now examine the sensitivity of the main results against two sources of heterogeneity outlined in Section 2.5 (all results in Appendix C). First, the subject pool includes university students (mean age: 23.8) who have not started their working career while older workers (mean age: 51.6) have much more work experience and are in closer distance to retirement. We therefore analyze retirement decisions separately for the two groups. Second, we alternate the decision structure among students, testing for differences between the baseline design (sequential decisions) and one-stage decisions. These checks shed more light on effect heterogeneity and show how the relationship between financial incentives and retirement behavior is linked to financial literacy and risk preferences.
4.3.1 Subject pools: students vs. older workers
Investigating the two subject pools in more detail reveals that older workers are adversely selected in terms of financial literacy. When taking this type of selection into account, tests of retirement decisions within separate subject pools yield results that are consistent to the previous overall findings for both groups.
In the student sub-sample, these tests document a significant retirement delay of 2.6 years in the INFO treatment which does not resemble for those in the BASIC treatments, showing only a small and insignificant difference (Table C1). Corresponding OLS estimates (Table C2) report the treatment effect conditional on further variables such as family background (N siblings, parental retirement status) and education (final school grade, the field of studies, N semesters) which are available for students only. The estimated difference between the two payoff schemes ranges between 2.2 and 2.6 years within the INFO treatments and is insignificant within the BASIC treatments.
The same holds for older workers in close distance to retirement. These participants also choose to retire at higher ages on average when facing a constant EPW, but as for students, the response is limited to those who are explicitly informed about the EPW (Table C1, column 3 and 4). Since joint estimation including financial incentives, information, and the interaction is not feasible due to the small sample (total N:79), we further stratify the estimation sample by information treatments. As for students and in line with previous results, OLS estimates document a retirement delay between 1.9 and 2.3 years (Table C3) in the INFO treatments and no significant difference in the BASIC treatments (Table C4). The estimated treatment effect in the INFO treatments is robust against adding variables on family background (specification 6), education (7), and employment (8) but the analysis is limited to the extent that the sample size is rather small (N = 40) with only a few degrees of freedom which is apparent in specification (9) and (10).
The smaller and less precisely estimated difference among older workers is not only due to the small number of observations but also because older workers are adversely selected in terms of financial literacy. This can be shown by taking a closer look at the financial literacy score (0–3), constructed from three incentivized math problems of computing the EPW.Footnote 29 It reveals that the mean of correct answers is 2.1 among students but only 1.5 among older workers (see Table B1 and B2, Appendix B) Further evidence on this point is provided in Table E1, showing a significant difference in the share of three (out of three) correct answers among students (74%) and older workers (50%). Using a narrow definition of financially literate older workers, namely only those with three correct answers, reveals a large and significant difference in retirement timing for declining vs. constant EPW of 3.3 years (Table C1, column 4, squared brackets). Taking this type of selection into account is important since grasping the concept of the EPW and the ability of its calculation is influential for the outcomes of our experiment.
4.3.2 One-stage decision structure
The difference in retirement timing between the two payoff schemes is large (about 4 years) and significant when participants face one-stage decisions, irrespective of information provision (Table C5). Once again, these results are consistent to those documented from OLS estimates (Table C6). The indication is, first, a larger response to financial incentives compared with sequential decisions and second, that information provision (INFO vs. BASIC) does not considerably change retirement outcomes under one-stage decisions. This result is surprising to the extent that knowing the EPW is essential to maximize benefits, thus challenging the previous findings of smaller (or even zero) effects in BASIC treatments. As shown in the following, the finding is driven by risk-taking behavior.
To explain the result, we first test for differences between BASIC treatments under sequential vs. one-stage decisions (students only). Remarkably, the differential response is induced by a significant difference between treatments with constant EPW (difference: 3.6 years, p-value (rank-sum): 0.000) while treatments with declining EPW do not significantly differ (difference: 0.4 years, p-value (rank-sum): 0.553).
Since the risk attitude is a parameter that may jointly vary with the decision structure, we test for differential risk preferences under treatments with sequential vs. one-stage decision structure. The results of this exercise (Table C7) show that subjects are more prone to take risks in their retirement decision making once facing one-stage decisions.Footnote 30 They state themselves to be more risk-loving under one-stage decisions (left panel) while this is not the case for overall risk preferences from paired lottery choices (right panel).Footnote 31
Given that the underlying decision problem is identical in both sequential and one-stage decisions, the higher willingness to take risks in one-stage decisions is a relevant explanation for the larger response to financial incentives. Under one-stage decisions, subjects make different choices under different payoff structures even if they are poorly informed (BASIC). Some subjects do have an intuitive idea of the payoff structure once the underlying patterns are sufficiently clear (peak value at age 60 under declining EPW, Figures 1 and 3). Once these patterns are not clear, as for the constant EPW, they tend to make more risky choices under one-stage decisions and choose higher retirement ages on average.
This data-driven explanation is consistent with theoretical predictions and experimental evidence on risk taking behavior. Experimental studies show that individuals are more risk averse the higher the frequency by which returns from assets are evaluated over time. The result holds when conducting experiments with students (Gneezy and Potters, Reference Gneezy and Potters1997) and is even stronger for professional traders (Haigh and List, Reference Haigh and List2005). The idea is put into a theoretical context by Dillenberger (Reference Dillenberger2010) who assumes the value of a lottery to directly depend on how uncertainty is resolved over time.Footnote 32 In summary, this literature advances on decision making under uncertainty and concludes that people are more risk averse when they perceive that risk is resolved over time compared with a one-shot resolution of uncertainty.
In our setting, the predictions from these models would be that individuals who evaluate the outcome EPW less frequent (one-stage decisions) will be less risk averse compared with those who reevaluate their decision more frequently (sequential decisions). This prediction is exactly what we find in our experimental data where people make riskier choices once facing the one-stage decision structure in comparison with the recurring sequential decision.
5 Conclusions
We provide experimental evidence on the effect of financial incentives on retirement decisions under different schemes of information provision. We show that making the financial consequences of retirement decisions more salient in terms of a forward-looking measure of pension benefits does have a considerable impact on the functioning of financial incentives and corresponding retirement choices. Previous research has shown that retirement behavior is not influenced if people are only informed about the recurrent payment (annuity) of pension benefits that corresponds to a specific retirement age (Mastrobuoni, Reference Mastrobuoni2011). Whether the ‘no reaction’ is due to the fact that people already behave optimally or if the type of information is not sufficient to improve retirement behavior is an open question and this paper contributes to resolve this puzzle.
Relative to the baseline scenario our intervention is a 3% benefit reduction for each year of retirement previous to the normal retirement age and a 5% premium thereafter, thus making early retirement financially less attractive. Our preferred estimate of the difference between two payoff structures is a retirement delay of 1.9 years, conditional on risk attitude, health status, gender, distance to retirement (age), and financial literacy. What this means is that the average contribution years of the typical German retiree (35.1 years in 2014 German Federal Pension Insurance, 2015, p. 131) would be extended by more than 5%. By and large, these experimental results are in line with quasi-experimental estimates for Germany (e.g. Hanel, Reference Hanel2010; Giesecke, Reference Giesecke2017). However, the relationship only holds for those who are explicitly informed about the expected pension wealth while the effects are small and largely insignificant once people only know their annuity. These results are robust across subject pools, documenting consistent behaviors of student subjects and older workers in close distance to retirement.
There are a few caveats regarding the external validity of the results since our data are obtained from a laboratory experiment. First, the sample (N: 318) is small when compared with quasi-experimental estimates derived from large data sets. However, randomization within the experimental framework should ensure unbiased estimates even in a relatively small sample. Second, the choice of the subject pool matters for generalizing results at the population level. 75% of our participants are sampled from university students which save financial resources and facilitates the recruitment process. While this procedure does not yield the most appropriate sample to study retirement decisions, the results obtained from students are strongly consistent with those obtained from another sub-sample of older workers (25% of the sample) in close distance to retirement. A final concern of generalizing the results from the laboratory to the real world is that the rewards paid in the experiment are only 1/10,000 of the value of the real decision for older workers. This small share is nevertheless an appropriate payoff regarding the time spent in the laboratory (90 min), yielding an average reward of 28 Euros among older workers.
Interestingly, if no information on the expected pension wealth as a forward-looking measure for pension wealth is available then revealed retirement choices bunch at age 60, 63, 65 and 67. The corresponding spikes, most notable when facing the constant EPW (see Figure 3), are commonly known retirement ages in the universe of the German public pension system.Footnote 33 Studies on the US social security system have drawn different conclusions about the role of social norms in retirement decision making. While Lumsdaine et al. (Reference Lumsdaine, Stock, Wise and Wise1996) conclude that social norms are an important explanation why so many people retire at specific ages, in contrast, Asch et al. (Reference Asch, Haider and Zissimopoulos2005) argue that social norms seem not to play a role in retirement timing. The striking result from our experiment is that both can be true, depending on whether people know what they do. People who are poorly informed about actuarial considerations of the retirement decision tend to make choices that are anchored to perceived reference points. These are usually set out by long-standing social security rules that establish what people consider to be a good age to retire, especially if they do not foresee the financial consequences.
We conclude that the financial consequences of retirement choices become more salient once the decision maker is informed about a forward-looking measure of pension benefits. Typical information letters, for example, the US Social Security statements or similar ones in Germany, only include information on expected annuities and these seem not to influence retirement behavior.Footnote 34 How to influence retirement behavior and how to delay job exits are relevant questions at times of aging societies. Probably the most important implication of this study is that programs aiming to raise the retirement age are more effective once the perception and understanding of financial incentives are improved.
Supplementary material
The supplementary material for this article can be found at https://doi.org/10.1017/S1474747217000439.
Appendix A – Risk Aversion Test
In this test, subjects are asked to choose between lottery A and B across ten different settings. Throughout these settings, the payoffs remain constant within lotteries but the probability of the high payoff (initially small, prob = 1/10) increases across decisions while the probability of the low payoff (initially high, prob = 9/10) decreases. The difference between the two payoffs is larger in lottery B. For example, subjects who choose lottery B in the first decision are very risk-loving while only very risk-averse subjects choose lottery B in the second last decision. Risk-neutral individuals choose lottery A in the first four decisions and switch to lottery B thereafter. This is so because lottery A yields the higher expected payoff throughout decision 1–4 while lottery B yields the higher expected payoff throughout decision 5–10 (see the last column of Table A1).
Ten paired lottery choices

Appendix B – Descriptive Statistics
Descriptive statistics: students

Descriptive statistics: older workers

Appendix C – Sensitivity Analysis: Results
Further testing: retirement decisions by the subject pool

Students sub-sample: regression analysis

Students sub-sample: regression analysis

Older workers’ sub-sample: regression analysis (BASIC)

Further testing: one-stage retirement decisions (Students only)

One-stage decision sub-sample: regression analysis (Students only)

Decision structure and risk preferences: constant EPW/BASIC (Students only)

Appendix D – Detailed Results: Graphical Evidence
D.1 Histograms: students
Retirement Decisions across Information Treatments: Declining EPW. (a) Full Sample (N: 239) (b) Declining EPW (N: 119). (c) Declining EPW: BASIC (N: 48) (d) Declining EPW: INFO (N: 71).

Retirement Decisions across Information Treatments: Constant EPW. (a) Full Sample (N: 239) (b) Constant EPW (N: 120). (c) Constant EPW: BASIC (N: 48) (d) Constant EPW: INFO (N: 72).

D.2 Histograms: older workers
Retirement Decisions across Information Treatments: Declining EPW. (a) Full Sample (N: 79) (b) Declining EPW (N: 39). (c) Declining EPW: BASIC (N: 19) (d) Declining EPW: INFO (N: 20).

Retirement Decisions across Information Treatments: Constant EPW. (a) Full Sample (N: 79) (b) Constant EPW (N: 40). (c) Constant EPW: BASIC (N: 20) (d) Constant EPW: INFO (N: 20).

Appendix E – Financial Literacy Score (0–3)
After their retirement decision, subjects are asked to solve three math problems related to the computation of the EPW. The financial literacy score used in parts of the analysis is based on the number of correct answers (=0 if none of the answers is correct; … ; =3 if all three answers are correct). If a correct answer is provided within 120 s, they earn 1.00 EUR (students) and 1.50 EUR (older workers) for each question. If no correct answer is provided within 120 s, the payoff is zero. All three questions involve calculating the EPW from different perspectives:
1. You are 58 years old. What is the exact amount of your EPW (in experimental token) if you retire immediately? Hint: The EPW equals the sum of all future pension benefits for the average remaining living years, given that you have reached the specific age (here: 58).
2. You are 61 years old. What is the exact amount of your EPW (in experimental token) if you retire immediately?
3. You are 58 years old. What is the exact amount of your EPW (in experimental token) if you plan to retire at age 61?
Financial literacy score (0–3)