



1. Introduction
In this paper we shall focus on the following fast–slow McKean–Vlasov equations driven by Brownian motion (Bm) and fractional Brownian motion (fBm):
 \begin{equation}\begin{cases} {\mathrm{d}} X_{t}^{\epsilon} =f(X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}),Y_{t}^{\epsilon})\,{\mathrm{d}} t+\sigma_\omega(X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}))\,{\mathrm{d}} W^1_t+\sigma_H(\mathscr{L}(X_{t}^{\epsilon}))\,{\mathrm{d}} B^H_t,\\ {\mathrm{d}} Y_{t}^{\epsilon} =\dfrac{1}{\epsilon}g (X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}),Y_{t}^{\epsilon})\,{\mathrm{d}} t+\dfrac{1}{\sqrt{\epsilon}}B (X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}),Y_{t}^{\epsilon})\,{\mathrm{d}} W^2_t\end{cases}\end{equation}
for
 $t>0$
with
 $X_{0}^{\epsilon}=x_0\in \mathbb R^{d}$
,
 $Y_{0}^{\epsilon}=y_0\in \mathbb R^{d}$
. The small positive parameter
 $\epsilon\in(0,1)$
represents the time scales between the processes
 $X_{t}^{\epsilon}$
and
 $Y_{t}^{\epsilon}$
. With this time scale, the process
 $X_{t}^{\epsilon}$
is referred to as the slow system and
 $Y_{t}^{\epsilon}$
as the fast system. The maps
 $f, g\colon \mathbb R^{d}\times \mathscr{P}_2\times \mathbb R^{d}\rightarrow \mathbb R^{d}$
,
 $\sigma_\omega\colon \mathbb R^{d}\times \mathscr{P}_2\rightarrow \mathbb R^{d\times r}$
,
 $B\colon \mathbb R^{d}\times \mathscr{P}_2\times \mathbb R^{d}\rightarrow \mathbb R^{d\times r}$
,
 $\sigma_H\colon \mathscr{P}_2\rightarrow \mathbb R^{d\times m}$
are continuous. The
 $W_t^1$
and
 $W_t^2$
are r-dimensional independent Wiener processes, and
 $B^H_t$
is m-dimensional fBm with Hurst parameter
 $H\in(\tfrac{1}{2},1)$
. The integral
 $\int\cdot {\mathrm{d}} W$
should be interpreted as an Itô stochastic integral and the integral
 $\int\cdot {\mathrm{d}} B^H$
as a generalized Riemann–Stieltjes integral [Reference Nualart and Răşcanu14, Reference Zähle23].
Fractional Brownian motion [Reference Mishura13] with Hurst parameter
 $H\in (0,1)$
is defined on a probability space
 $(\Omega, {\mathscr F}, \mathbb P)$
as a continuous, centered Gaussian process
 $B^H=\{B_t^H,t\geq 0\}$
with the covariance function
 \begin{equation*} R_{H}(t,s) = E\bigl[B^{H}(t)B^{H}(s)\bigr] = \dfrac{1}{2}\bigl(|t|^{2H}+|s|^{2H}-|t-s|^{2H}\bigr),\quad s,t\in \mathbb R.\end{equation*}
The fBm is a standard Bm when
 $H=\tfrac{1}{2}$
. The integral for Brownian motion is the standard Itô integral, but for
 $H \neq \tfrac{1}{2}$
it is neither a semimartingale nor a Markov process. Hence the Itô integral theory for the construction of stochastic integrals with respect to fBm is invalid. For
 $H\in(\tfrac{1}{2},1)$
, it exhibits a property of long-range dependence, which makes it a popular model for long-range dependence in the natural sciences, finance, etc. In addition, Brownian motion as a model is inappropriate because of lack of memory, and fractional Brownian motion with
 $H\in(\tfrac{1}{2},1)$
is too smooth. Fortunately, pathwise Riemann–Stieltjes stochastic integrals can be defined using the Young integral [Reference Young22] in this case. For these reasons, in this paper we focus on stochastic differential equations driven by mixed fractional Brownian motion with Hurst parameter
 $H\in(\tfrac{1}{2},1)$
.
On the other hand, a distribution-dependent stochastic differential equation (SDE) is an equation in which the coefficients rely on the distribution of the solution. Its solution is frequently referred to as a nonlinear diffusion process whose transition function depends on both the current state and the distribution of the process. This type of SDE, also known as a McKean–Vlasov or mean-field SDE, has garnered significant attention in recent years, with its origin traced back to McKean [Reference McKean12]. It is widely acknowledged that distribution-dependent SDEs currently play a crucial role in chaos theory (see, for instance, McKean [Reference McKean11], Sznitman [Reference Sznitman17], and references therein). Wang [Reference Wang19] explored the existence, uniqueness, and distributional properties of the strong solution to the McKean–Vlasov SDE for the Landau-type equation under the Lipschitz condition on the distribution-dependent coefficients. Ding and Qiao [Reference Ding and Qiao2] examined a type of weak solution of the McKean–Vlasov SDE with a non-Lipschitz condition via an Euler–Maruyama approximation. Bauer and Meyer-Brandis [Reference Bauer and Meyer-Brandis1] considered the results regarding the existence and uniqueness of solutions to the McKean–Vlasov SDE in an infinite-dimensional Hilbert space setting, involving irregular drift and additive fractional noise. Fan et al. [Reference Fan, Huang, Suo and Yuan3] demonstrated the well-posedness of distribution-dependent SDEs driven by fBm with Hurst parameter
 $H\in(\tfrac{1}{2}, 1)$
, and subsequently established a general result on the Bismut formula for the Lions derivative using Malliavin calculus. Galeati [Reference Galeati, Harang and Mayorcas5] proved stability results, as well as some novel auxiliary results, concerning the regularity of the law of solutions for distribution-dependent SDEs with irregular, possibly distributional drift, driven by an additive fractional Brownian motion with Hurst parameter
 $H \in(0, 1)$
.
The research on averaging principles within stochastic systems can be traced back to the work of Khasminskii [Reference Khasminskii7]. This work offers an efficacious approach for the qualitative analysis of complex multi-scale systems. The core concept is that the fast process can be regarded as noise and possesses an invariant measure. Utilizing this invariant measure, the slow process converges to a limit that is an average with respect to the stationary measure of the fast process. Freidlin and Wentzell [Reference Freidlin and Wentzell4] furnished an illuminating review and discussion regarding the averaging principle. Thompson et al. [Reference Thompson, Kuske and Monahan18] examined nonlinear fast–slow SDEs, where the fast process is driven by additive
 $\alpha$
-stable noise and the slow process has linear dependence on the fast process. Xu et al. [Reference Xu, Liu and Miao20] addressed the averaging principle for two-time-scale SDEs under non-Lipschitz conditions, thereby extending the existing outcomes from the Lipschitz to the non-Lipschitz scenario. Xu et al. [Reference Xu, Pei and Guo21] explored the stochastic averaging of slow–fast SDEs driven by mixed fractional Brownian motion (fBm) with the Hurst parameter
 $H\in(\tfrac{1}{2},1)$
. Hairer and Li [Reference Hairer and Li6] considered the averaging principle of the fast–slow system, where the fast system is driven by fBm, and proved that the convergence to the averaged solution takes place in probability, which is highly reliant on the stochastic sewing lemma. Shen et al. [Reference Shen, Xiang and Wu16] studied the solutions of distribution-dependent SDEs driven simultaneously by fBm and Bm, which can be approximated by the solutions of the associated averaged distribution-dependent SDEs in the sense of mean-square convergence.
However, as far as we know, there is no result on the averaging principle for fast–slow McKean–Vlasov SDEs with mixed fBm. For numerical purposes, however, studying only the strong convergence of the slow system to the corresponding averaged equation with Lipschitz conditions is not enough, since in addition one needs to know the strong averaging principle with a non-Lipschitz condition. Hence the main purpose of our paper is to establish the averaging principle for fast–slow McKean–Vlasov SDEs of mixed fBm with the Hurst parameter
 $H\in(\tfrac{1}{2},1)$
using the non-Lipschitz condition in the sense of mean-square convergence.
A concise overview of the paper is presented as follows. In Section 2 we succinctly introduce the preliminary concepts necessary for the subsequent discussion, and demonstrate the existence and uniqueness theorem of the solution to fast–slow McKean–Vlasov equations driven by Brownian motion (Bm) and fBm (1) within the non-Lipschitz condition framework. In Section 3 we develop and validate the auxiliary estimates required for the proof. Section 4 focuses on presenting the exponential ergodicity of the frozen equation and certain characteristics of the coefficient of the averaged equation. Finally, in Section 5, we principally establish the central theorem of this paper, which pertains to a stochastic averaging principle for fast–slow McKean–Vlasov SDEs driven by mixed fractional Brownian motion under non-Lipschitz conditions. In other words, the slow SDE converges to the associated averaged equation in the sense of mean-square convergence.
Throughout the remainder of this paper, the letter C will represent a positive constant, with its precise value subject to change upon each occurrence.
2. Preliminaries
In this section we furnish a succinct exposition of the fundamental preliminaries requisite for the ensuing discourse. Additionally, we describe the existence and uniqueness theorem pertaining to the solution of the fast–slow McKean–Vlasov equations driven by Bm and fBm (1) under non-Lipschitz conditions.
Let
 $|\cdot|$
be the Euclidean vector norm, let
 $\langle\cdot,\cdot\rangle$
be the Euclidean inner product, and let
 $\|\cdot\|$
be the matrix norm or the operator norm. Then
 $\mathscr{P}_2$
is defined by
 \begin{equation*}\mathscr{P}_2(\mathbb R^{d})\,:\!=\, \biggl\{\mu\in\mathscr{P}\colon \mu(|\cdot|^2)\,:\!=\, \int_{\mathbb R^{d}}|x|^2\mu({\mathrm{d}} x)<\infty\biggr\},\end{equation*}
where
 $\mathscr{P}$
is the set of all probability measures on
 $(\mathbb R^{d},\mathscr{B}(\mathbb R^{d}))$
, which is a Polish space under the
 $L^2$
-Wasserstein distance
 \begin{equation*}{\mathbb W}_2(\mu_1,\mu_2)\,:\!=\, \inf_{\pi\in\mathscr {C}(\mu_1,\mu_2)}\biggl(\int_{\mathbb R^{d}\times\mathbb R^{d}}|x-y|^2\pi({\mathrm{d}} x,{\mathrm{d}} y)\biggr)^{{{1}/{2}}},\quad \mu_1,\mu_2\in\mathscr{P}_2(\mathbb R^{d}),\end{equation*}
where
 $\mathscr {C}(\mu_1,\mu_2) $
is the set of probability measures on
 $ \mathbb R^{d}\times \mathbb R^{d}$
with marginals
 $\mu_1$
and
 $\mu_2$
. That is, for any
 $x\in \mathbb R^{d}$
, the Dirac measure
 $\delta_x \in \mathscr{P}_2$
, and if
 $\mu_1 = \mathscr {L}(X)$
,
 $\mu_2 = \mathscr {L} (Y)$
are the corresponding distributions of random variables X and Y respectively, then
 \begin{equation*}({\mathbb W}_2(\mu_1,\mu_2))^2\leq \int_{\mathbb R^{d}\times\mathbb R^{d}}|x-y|^2\mathscr {L}(X,Y)({\mathrm{d}} x,{\mathrm{d}} y)=E|X-Y|^2,\end{equation*}
in which
 $\mathscr {L}(X,Y)$
represents the joint distribution of the random pair(X,Y) [Reference Shen, Xiang and Wu16]. Next we introduce an inequality to prove our results.
Lemma 1. (Bihari’s inequality [Reference Mao10, Reference Shen, Xiang and Wu16].) Let
 $T > 0$
, and
 $c > 0$
. Let
 $\psi\colon \mathbb R_+\rightarrow \mathbb R_+$
be a continuous non-decreasing function such that
 $\psi(t) > 0$
for all
 $t > 0$
. Let
 $u(\!\cdot\!)$
be a Borel-measurable bounded non-negative function on
 $[0,T]$
, and let
 $v(\!\cdot\!)$
be a non-negative integrable function on
 $[0,T]$
. If
 \begin{equation*}u(t)\leq c+\int_0^tv(s)\psi(u(s))\,{\mathrm{d}} s\end{equation*}
holds for all
 $t\in[0, T]$
, then
 \begin{equation*}u(t)\leq G^{-1}\biggl(G(c) +\int_0^tv(s)\,{\mathrm{d}} s\biggr)\end{equation*}
holds for all
 $t\in[0, T]$
, and
 \begin{equation*}G(c) +\int_0^tv(s)\,{\mathrm{d}} s\in \operatorname{Dom}\!(G^{-1}),\end{equation*}
where
 \begin{equation*}G(r)=\int_1^r\dfrac{1}{\psi(s)}\,{\mathrm{d}} s\end{equation*}
on
 $r>0$
,
 $G^{-1}$
is the inverse function of G.
In the following sections we present a series of assumptions that underpin this work.
(A1) There exists a constant K such that for any
 $t\in [0,T]$
, x,
 $x_1$
,
 $x_2$
, y,
 $y_1$
,
 $y_2\in \mathbb R^{d}$
,
 $\mu$
,
 $\nu\in \mathscr{P}_2(\mathbb R^{d})$
,
 \begin{align*}|f (x_1,\mu,y_1) -f (x_2,\nu,y_2) |^2\leq K\Psi\bigl(|x_1-x_2|^2+|y_1-y_2|^2+{\mathbb W}^2_2(\mu,\nu)\bigr),\\\|\sigma_\omega (x_1,\mu) -\sigma_\omega (x_2,\nu) \|^2+\|\sigma_H (\mu) -\sigma_H (\nu) \|^2\leq K\Psi\bigl(|x_1-x_2|^2+{\mathbb W}^2_2(\mu,\nu)\bigr),\\|g (x_1,\mu,y_1) -g (x_2,\nu,y_2) |^2\leq K\Psi\bigl(|x_1-x_2|^2+|y_1-y_2|^2+{\mathbb W}^2_2(\mu,\nu)\bigr),\\\|B (x_1,\mu,y_1) -B (x_2,\nu,y_2) \|^2\leq K\Psi\bigl(|x_1-x_2|^2+|y_1-y_2|^2+{\mathbb W}^2_2(\mu,\nu)\bigr),\end{align*}
where
 $\Psi\colon \mathbb R_+\rightarrow \mathbb R_+$
is a continuous and non-decreasing concave function with
 $\Psi(0)=0$
,
 $\Psi(x) > 0$
for all
 $x > 0$
such that
 \[\int_{0^+}\frac{1}{\Psi(x)}{\mathrm{d}} x=+\infty.\]
Remark 1. When
 $\Psi(x)=Kx,x\geq 0$
, we observed that the Lipschitz condition is a special case of our proposed condition.
(A2) There is a positive constant
 $K_1$
such that
 \begin{equation*}|f (0,\delta_0,0) |^2+|g (0,\delta_0,0) |^2+\|\sigma_\omega (0,\delta_0) \|^2+\|\sigma_H (\delta_0) \|^2+\|B (0,\delta_0,0) \|^2\leq K_1.\end{equation*}
(A3) There is a positive constant
 $\beta_1$
such that
 \begin{equation*}2yg (x,\mu,y) +\|B (x,\mu,y) \|^2\leq -\beta_1|y|^2+C|x|^2+C\mu(|\cdot|^2).\end{equation*}
(A4) There is a positive constant
 $\beta_2$
such that
 \begin{align*}&2\langle y_1-y_2,g (x_1,\mu,y_1) -g (x_2,\nu,y_2) \rangle+\|B (x_1,\mu,y_1) -B (x_2,\nu,y_2) \|^2\\&\quad \leq -\beta_2|y_1-y_2|^2+K\Psi\bigl(|x_1-x_2|^2+{\mathbb W}^2_2(\mu,\nu)\bigr).\end{align*}
Remark 2. Assumptions (A1) and (A2) can be used to estimate
 $|f (x,\mu,y) |^2$
,
 $\|\sigma_\omega (x,\mu)) \|^2$
and
 $\|\sigma_H (\mu) \|^2$
:
 \begin{align*}&|f (x,\mu,y) |^2+\|\sigma_\omega (x,\mu) \|^2+\|\sigma_H (\mu) \|^2 \\&\quad \leq 2|f (x,\mu,y) -f (0,\delta_0,0) |^2+ 2|f (0,\delta_0,0) |^2+2\|\sigma_H (\delta_0) \|^2\\&\quad\quad +2\|\sigma_\omega (x,\mu) -\sigma_\omega(0,\delta_0)\|^2+2\|\sigma_\omega(0,\delta_0)\|^2+2\|\sigma_H (\mu) -\sigma_H (\delta_0) \|^2\\&\quad \leq2K\Psi \bigl(|x|^2+|y|^2+\mathbb{W}^2_2 (\mu,\delta_0) \bigr) +2K\Psi \bigl(|x|^2+\mathbb {W}^2_2 (\mu,\delta_0) \bigr) +2K\Psi\bigl({\mathbb W}^2_2 (\mu,\delta_0) \bigr) + 6K_1.\end{align*}
In this subsection our focus will be on establishing the existence and uniqueness theorem concerning the solution of the fast–slow McKean–Vlasov equations driven by Bm and fBm (1). The next definition [Reference Shen, Xiang and Wu16] pertains to the existence and uniqueness of the solution for the fast–slow system denoted by (1).
Definition 1. An
 $\mathbb R^{d}\times\mathbb R^{d}$
-valued stochastic process
 $ (X^\epsilon_t,Y^\epsilon_t) _{t\in[0,T]}$
is called a unique solution of (1) if
 $X\in L^P,P\geq 2$
and satisfies the following.
-
(i)
 \begin{equation*}\left\{ \begin{aligned} X_{t}^{\epsilon} &=x_0+\int_0^tf (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon})\,{\mathrm{d}} s+\int_0^t\sigma_\omega (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}))\,{\mathrm{d}} W^1_s \\& \quad+\int_0^t\sigma_H (\mathscr{L}(X_{s}^{\epsilon}))\,{\mathrm{d}} B^H_s,\\ Y_{t}^{\epsilon}& =y_0+\dfrac{1}{\epsilon}\int_0^tg (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon})\,{\mathrm{d}} s+\dfrac{1}{\sqrt{\epsilon}}\int_0^tB (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon})\,{\mathrm{d}} W^2_s.\end{aligned}\right.\end{equation*}
-
(ii) If
$Z^\epsilon= (Z_t^\epsilon) _{t\in[0,T]}$
is another solution with
$Z_0= (x_0,y_0) ^{\top}$
, then
\begin{equation*}P ( (X^\epsilon_t,Y^\epsilon_t) =Z^\epsilon(t)\ \text{for all} \ 0\leq t\leq T) =1.\end{equation*}


The following theorem will establish the existence and uniqueness of the solution for the fast–slow McKean–Vlasov equations driven by Bm and fBm as denoted in (1), under non-Lipschitz conditions. This result can be derived by employing the findings of Shen et al. as cited in [Reference Shen, Xiang and Wu16].
Theorem 1. Suppose that assumptions (A1) and (A2) hold. For each
 $\epsilon>0$
and initial values
 $x_0,y_0\in\mathbb R^{d}$
, equation (1) has a unique solution
 $ (X^\epsilon_t,Y^\epsilon_t) _{t\in[0,T]}$
in the sense of Definition 1.
Proof. We set
 \begin{align*}Z_t^\epsilon&\,:\!=\, (X^\epsilon_t,Y^\epsilon_t) ^{\top},\tilde{f} (x,\tilde{\mu},y) \,:\!=\, \biggl(f (x,\mu,y) ,\dfrac{1}{\epsilon}g(x,\mu,y)\biggr)^{\top},\\W_t&\,:\!=\, (W_t^1,W_t^2) ^{\top},B^H_t\,:\!=\, (B^H_t,0) ^{\top},\\\tilde{\sigma}^\epsilon_\omega(x,\tilde{\mu},y)&\,:\!=\, \begin{pmatrix}\sigma_\omega(x,\mu) & 0 \\0 & \frac{1}{\sqrt{\epsilon}}B(x,\mu,y)\\\end{pmatrix}_{2d \times 2r},\quad\tilde{\sigma}^\epsilon_H(\tilde{\mu})\,:\!=\, \left(\begin{array}{l@{\quad}l}\sigma_H(\mu) & 0 \\ 0 & 0\end{array}\right)_{2d \times 2m},\end{align*}
where
 $t\geq0$
,
 $x\in\mathbb R^d$
,
 $y\in\mathbb R^d$
,
 $\tilde{\mu}\in \mathscr{P}_2(\mathbb R^{2d})$
with its marginal distribution
 $\mu$
on
 $\mathbb R^d$
. Then equation (1) can be rewritten as
 \begin{equation*}{\mathrm{d}} Z_t^\epsilon=\tilde{f} (Z_t^\epsilon,\mathscr{L} (Z_t^\epsilon) )\,{\mathrm{d}} t+\tilde{\sigma}^\epsilon_\omega (Z_t^\epsilon,\mathscr{L} (Z_t^\epsilon) )\,{\mathrm{d}} W_t+\tilde{\sigma}^\epsilon_H(\mathscr{L} (Z_t^\epsilon) )\,{\mathrm{d}} B^H_t\end{equation*}
with
 $Z^\epsilon_0= (x_0,y_0) ^{\top}$
. In fact, for
 $T>0$
, and
 $z_i=(x_i,y_i)^{\top}\in \mathbb R^{2d}$
,
 $\tilde{\mu_i}\in \mathscr{P}_2(\mathbb R^{2d})$
with its marginal distribution
 $\mu_i$
on
 $\mathbb R^d$
,
 $i=1,2$
,
 $t\in[0,T]$
,
 \begin{align*}&|\tilde{f} (z_1,\tilde{\mu}_1) -\tilde{f} (z_2,\tilde{\mu}_2) |^2+\|\tilde{\sigma}_\omega (z_1,\tilde{\mu}_1) -\tilde{\sigma}_\omega (z_2,\tilde{\mu}_2) \|^2+\|\tilde{\sigma}_H (\tilde{\mu}_1) -\tilde{\sigma}_H (\tilde{\mu}_2) \|^2 \\&\quad =|f (x_1,\mu_1,y_1) -f (x_2,\mu_2,y_2) |^2+\dfrac{1}{\epsilon^2}|g (x_1,\mu_1,y_1) -g (x_2,\mu_2,y_2) |^2\\&\quad\quad +\|\sigma_H (\mu_1) -\sigma_H (\mu_2) \|^2\\ &\quad\quad +\dfrac{1}{\epsilon}\|B (x_1,\mu_1,y_1) -B (x_2,\mu_2,y_2) \|^2+\|\sigma_\omega (x_1,\mu_1) -\sigma_\omega (x_2,\mu_2) \|^2\\&\quad \leq\biggl(2+\dfrac{1}{\epsilon^2}+\dfrac{1}{\epsilon}\biggr)K\Psi\bigl(|x_1-x_2|^2+|y_1-y_2|^2+{\mathbb W}^2_2(\mu,\nu)\bigr)\\&\quad =\biggl(2+\dfrac{1}{\epsilon^2}+\dfrac{1}{\epsilon}\biggr)K\Psi\bigl(|z_1-z_2|^2+{\mathbb W}^2_2(\mu,\nu)\bigr).\end{align*}
Further,
 \begin{align*}&|\tilde{f} (0,\tilde{\delta}_0) |^2+\|\tilde{\sigma}_\omega (0,\tilde{\delta}_0) \|^2+\|\tilde{\sigma}_H (\tilde{\delta}_0) \|^2\\&\quad =|f (0,\delta_0,0) |^2+\dfrac{1}{\epsilon^2}|g (0,\delta_0,0) |^2+\|\sigma_\omega (0,\delta_0) \|^2+\|\sigma_H (\delta_0) \|^2+\dfrac{1}{\epsilon} \|B (0,\delta_0,0) \| ^2\\&\quad \leq\biggl(1+\dfrac{1}{\epsilon^2}+\dfrac{1}{\epsilon}\biggr)K_1.\end{align*}
Hence, by Theorem 3.6 in [Reference Shen, Xiang and Wu16], equation (1) has a unique solution
 $ (X^\epsilon_t,Y^\epsilon_t) _{t\in[0,T]}$
in the sense of Definition 1.
3. Some a priori estimates
In this section we formulate and subsequently prove the auxiliary estimates that are essential for the proof. At the outset of this section we initiate by demonstrating certain uniform bounds in the sense of the mean square of the solution
 $ (X^\epsilon_t,Y^\epsilon_t) _{t\in[0,T]}$
to equation (1).
Lemma 2. For any
 $T>0$
, there exists a constant
 $C_T>0$
such that
 \begin{align*}\textrm{sup}_{0<\epsilon<1} \mathbb{E}\textrm{sup}_{0\leq s\leq t} |X^\epsilon_s| ^2 & \leq C_T (1+|x_0|^2+|y_0|^2) ,\\\textrm{sup}_{0<\epsilon<1}\textrm{sup}_{0\leq s\leq t}\mathbb{E} |Y^\epsilon_s| ^2 & \leq C_T (1+|x_0|^2+|y_0|^2) .\end{align*}
Proof. By Itô’s formula, we have
 \begin{equation*}\dfrac{{\mathrm{d}}\mathbb{E} |Y^\epsilon_t| ^2}{{\mathrm{d}} t} = \dfrac{2}{\epsilon}\mathbb{E}\langle Y^\epsilon_t,g (X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}),Y_{t}^{\epsilon}) \rangle +\dfrac{1}{\epsilon}\mathbb{E} \|B (X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}),Y_{t}^{\epsilon}) \| ^2.\end{equation*}
By (A3), we obtain
 \begin{align*}&2\langle Y^\epsilon_t,g (X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}),Y_{t}^{\epsilon}) \rangle + \|B (X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}),Y_{t}^{\epsilon}) \| ^2\\&\quad \leq -{\beta_1} |Y_{t}^{\epsilon}| ^2+C|X_{t}^{\epsilon}|^2+C\mathscr{L}(X_{t}^{\epsilon})(|\cdot|^2).\end{align*}
Note that
 $\mathscr{L}(X_{t}^{\epsilon})(|\cdot|^2)=\mathbb{E}|X_{t}^{\epsilon}|^2$
. Thus we get
 \begin{equation*}\dfrac{{\mathrm{d}}\mathbb{E} |Y^\epsilon_t| ^2}{{\mathrm{d}} t}\leq -\dfrac{\beta_1}{\epsilon}\mathbb{E} |Y^\epsilon_t| ^2+\dfrac{C}{\epsilon}\mathbb{E}|X_{t}^{\epsilon}|^2.\end{equation*}
The Gronwall inequality implies
 \begin{align*}\mathbb{E} |Y^\epsilon_t| ^2&\leq |y_0|^2+\dfrac{C}{\epsilon}\int_0^t \exp\biggl({-\frac{\beta_1}{\epsilon}(t-s)}\biggr)\mathbb{E}|X_{s}^{\epsilon}|^2\,{\mathrm{d}} s\leq |y_0|^2+C\mathbb{E} \bigl(\textrm{sup}_{0\leq s\leq t}|X_{s}^{\epsilon}|^2\bigr) .\end{align*}
Following the elementary inequality
 \begin{equation*} |a+b+c+d| ^2\leq 4 (|a|^2+|b|^2+|c|^2+|d|^2) ,\end{equation*}
we have
 \begin{align*} \mathbb{E} (\textrm{sup}_{0\leq s\leq t} |X_{s}^{\epsilon}| ^2 ) &\leq4|x_0|^2+4\mathbb{E}\biggl(\textrm{sup}_{0\leq s\leq t}\biggl|\int_0^sf\bigl(X_{r}^{\epsilon},\mathscr{L}(X_{r}^{\epsilon}),Y_{r}^{\epsilon}\bigr)\,{\mathrm{d}} r\biggr|^2\biggr)\\&\quad +4\mathbb{E}\biggl(\textrm{sup}_{0\leq s\leq t}\biggl|\int_0^s\sigma_\omega (X_{r}^{\epsilon},\mathscr{L}(X_{r}^{\epsilon}))\,{\mathrm{d}} W^1_r\biggr|^2\biggr)\\&\quad +4\mathbb{E}\biggl(\textrm{sup}_{0\leq s\leq t}\biggl|\int_0^s\sigma_H (\mathscr{L}(X_{r}^{\epsilon}))\,{\mathrm{d}} B^H_r\biggr|^2\biggr)\\&=\!:\,4|x_0|^2+4I_1(t)+4I_2(t)+4I_3(t).\end{align*}
For the term
 $I_1(t)$
, by the Hölder inequality, (A1), (A2), Remark 2, and the Jensen inequality, we obtain
 \begin{align}I_1(t)&= \mathbb{E}\biggl(\textrm{sup}_{0\leq s\leq t}\biggl|\int_0^sf (X_{r}^{\epsilon},\mathscr{L}(X_{r}^{\epsilon}),Y_{r}^{\epsilon})\,{\mathrm{d}} r\biggr|^2\biggr)\nonumber\\&\leq t\int_0^t \mathbb{E} |f (X_{r}^{\epsilon},\mathscr{L}(X_{r}^{\epsilon}),Y_{r}^{\epsilon}) | ^2\,{\mathrm{d}} r\nonumber\\&\leq 2t\int_0^t K \mathbb{E}\Psi ( |X_{r}^{\epsilon}| ^2+ |Y_{r}^{\epsilon}| ^2+{\mathbb W}^2_2 (\mathscr{L}(X_{r}^{\epsilon}),\delta_0) )\,{\mathrm{d}} r+ 2t^2K_1\nonumber\\&\leq 2t\int_0^t K\Psi (2 \mathbb{E} |X_{r}^{\epsilon}| ^2+ \mathbb{E} |Y_{r}^{\epsilon}| ^2)\,{\mathrm{d}} r+2t^2K_1.\end{align}
Note that
 ${\mathbb W}^2_2 (\mathscr{L}(X_{r}^{\epsilon}),\delta_0) = \mathbb{E} |X_{r}^{\epsilon}-\delta_0| ^2\leq \mathbb{E} |X_{r}^{\epsilon}| ^2$
.
For the term
 $I_2(t)$
, it follows from the Burkhölder–Davis–Gundy inequality, (A1), (A2), Remark 2, and the Jensen inequality that
 \begin{align*} I_2(t)&= \mathbb{E}\biggl(\textrm{sup}_{0\leq s\leq t}\biggl|\int_0^s\sigma_\omega (X_{r}^{\epsilon},\mathscr{L}(X_{r}^{\epsilon}))\,{\mathrm{d}} W^1_r\biggr|^2\biggr)\nonumber\\&\leq 4\int_0^t \mathbb{E} \|\sigma_\omega (X_{r}^{\epsilon},\mathscr{L}(X_{r}^{\epsilon})) \| ^2{\mathrm{d}} r\nonumber\\&\leq 8\int_0^t K \mathbb{E}\Psi ( |X_{r}^{\epsilon}| ^2+{\mathbb W}^2_2 (\mathscr{L}(X_{r}^{\epsilon}),\delta_0) )\,{\mathrm{d}} r+ 8tK_1\nonumber\\&\leq 8\int_0^t K\Psi (2 \mathbb{E} |X_{r}^{\epsilon}| ^2)\,{\mathrm{d}} r+8tK_1.\end{align*}
For the term
 $I_3(t)$
, it follows from [Reference Fan, Huang, Suo and Yuan3, (3.5)], (A1), (A2), Remark 2, and the Jensen inequality that
 \begin{align}I_3(t)&= \mathbb{E}\biggl(\textrm{sup}_{0\leq s\leq t}\biggl|\int_0^s\sigma_H (\mathscr{L}(X_{r}^{\epsilon}))\,{\mathrm{d}} B^H_r\biggr|^2\biggr)\nonumber\\&\leq C_{\lambda,H}t^{2H-1}\int_0^t \|\sigma_H (\mathscr{L}(X_{r}^{\epsilon})) \| ^2\,{\mathrm{d}} r\nonumber\\&\leq 2C_{\lambda,H}t^{2H-1}\int_0^t K \mathbb{E}\Psi ({\mathbb W}^2_2 (\mathscr{L}(X_{r}^{\epsilon}),\delta_0) )\,{\mathrm{d}} r+ 2C_{\lambda,H}t^{2H-1}tK_1\nonumber\\&\leq 2C_{\lambda,H}t^{2H-1}\int_0^t K\Psi ( \mathbb{E} |X_{r}^{\epsilon}| ^2)\,{\mathrm{d}} r+2C_{\lambda,H}t^{2H}K_1,\end{align}
where
 $C_{\lambda,H}$
only depends on H, by choosing suitable
 $1-H<\lambda<\tfrac{1}{2}$
. Thus (2)–(3) yield
 \begin{align*} \mathbb{E}\bigl(\textrm{sup}_{0\leq s\leq t} |X_{s}^{\epsilon}| ^2 \bigr) &\leq 4|x_0|^2+4\biggl(2C_{\lambda,H}t^{2H-1}\int_0^t K\Psi ( \mathbb{E} |X_{r}^{\epsilon}| ^2)\,{\mathrm{d}} r+2C_{\lambda,H}t^{2H}K_1\biggr)\\&\quad +8t^2K_1+4\biggl(8\int_0^t K\Psi (2 \mathbb{E} |X_{r}^{\epsilon}| ^2)\,{\mathrm{d}} r+8tK_1\biggr)\\&\quad +8t\int_0^t K\Psi (2 \mathbb{E} |X_{r}^{\epsilon}| ^2+ \mathbb{E} |Y_{r}^{\epsilon}| ^2)\,{\mathrm{d}} r\\&\leq 4|x_0|^2+C_{T,H,K}\int_0^t \Psi (2 \mathbb{E} |X_{r}^{\epsilon}| ^2+\mathbb{E} |Y_{r}^{\epsilon}| ^2)\,{\mathrm{d}} r+C_{T,H,K_1}.\end{align*}
It follows from the Hahn–Banach theorem that there must exist a positive number a such that
 $\Psi(x)\leq a(1+x)$
. Hence, by the estimate of
 $\mathbb{E} |Y_{t}^{\epsilon}| ^2$
, we get
 \begin{align*}\mathbb{E} \bigl(\textrm{sup}_{0\leq s\leq t} |X_{s}^{\epsilon}| ^2 \bigr) &\leq 4|x_0|^2+C_{T,H,K}\int_0^t a (1+2\mathbb{E} |X_{r}^{\epsilon}| ^2+\mathbb{E} |Y_{r}^{\epsilon}| ^2)\,{\mathrm{d}} r+C_{T,H,K_1}\\&\leq C (1+|x_0|^2+|y_0|^2) +C_{a,T,H,K}\int_0^t \bigl(3\mathbb{E} \bigl(\textrm{sup}_{0\leq u\leq r} |X_{u}^{\epsilon}| ^2\bigr) \bigr)\,{\mathrm{d}} r.\end{align*}
Then, by the Gronwall inequality, we obtain
 \begin{equation*}\mathbb{E} \bigl(\textrm{sup}_{0\leq s\leq t} |X_{s}^{\epsilon}| ^2 \bigr) \leq C_T (1+|x_0|^2+|y_0|^2) .\end{equation*}
This yields
 \begin{equation*}\textrm{sup}_{0\leq s\leq t}\mathbb{E} |Y^\epsilon_s| ^2\leq |y_0|^2+C\textrm{sup}_{0\leq s\leq t}\mathbb{E} \bigl(\textrm{sup}_{0\leq u\leq s}|X_{u}^{\epsilon}|^2\bigr) \leq C_T (1+|x_0|^2+|y_0|^2).\end{equation*}
Lemma 3. For any
 $T>0$
,
 $0\leq t\leq t+h\leq T$
, there exists a constant
 $C_T>0$
such that
 \begin{equation*}\mathbb{E} |X_{t+h}^{\epsilon}-X_{t}^{\epsilon}| ^2\leq C_T (h+h^2+h^{2H}) .\end{equation*}
Proof. From Theorem 1, we get
 \begin{align*} X_{t+h}^{\epsilon}- X_{t}^{\epsilon} &= \int_t^{t+h}f (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon})\,{\mathrm{d}} s+\int_t^{t+h}\sigma_\omega (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}))\,{\mathrm{d}} W^1_s\\&\quad +\int_t^{t+h}\sigma_H (\mathscr{L}(X_{s}^{\epsilon}))\,{\mathrm{d}} B^H_s .\end{align*}
Then, by the Hölder inequality, the Burkhölder–Davis–Gundy inequality, (A1), (A2), Remark 2, the Jensen inequality, and Lemma 2, we have
 \begin{align*} \mathbb{E} |X_{t+h}^{\epsilon}- X_{t}^{\epsilon}| ^2 &\leq 3\mathbb{E}\biggl|\int_t^{t+h}f (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon})\,{\mathrm{d}} s\biggr|^2\\&\quad +3\mathbb{E}\biggl|\int_t^{t+h}\sigma_\omega (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}))\,{\mathrm{d}} W^1_s\biggr|^2\\&\quad +3\mathbb{E}\biggl|\int_t^{t+h}\sigma_H (\mathscr{L}(X_{s}^{\epsilon}))\,{\mathrm{d}} B^H_s\biggr|^2\\ &\leq 3h\int_t^{t+h}\mathbb{E} |f (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon}) | ^2\,{\mathrm{d}} s\\&\quad +3\int_t^{t+h}\mathbb{E} \|\sigma_\omega (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon})) \| ^2\,{\mathrm{d}} s\\&\quad +3C_{\lambda,H}h^{2H-1} \int_t^{t+h}\mathbb{E} \|\sigma_H (\mathscr{L}(X_{s}^{\epsilon})) \| ^2\,{\mathrm{d}} s\\ &\leq 6hK\int_t^{t+h}\mathbb{E}\Psi ( |X_{s}^{\epsilon}| ^2+ |Y_{s}^{\epsilon}| ^2+{\mathbb W}^2_2 (\mathscr{L}(X_{s}^{\epsilon}),\delta_0) )\,{\mathrm{d}} s+6h^2K_1 \\&\quad +6K\int_t^{t+h}\mathbb{E}\Psi ( |X_{s}^{\epsilon}| ^2+{\mathbb W}^2_2 (\mathscr{L}(X_{s}^{\epsilon}),\delta_0) )\,{\mathrm{d}} s +6hK_1\\&\quad +6C_{\lambda,H}h^{2H-1} \int_t^{t+h}\mathbb{E}\Psi ({\mathbb W}^2_2 (\mathscr{L}(X_{s}^{\epsilon}),\delta_0) )\,{\mathrm{d}} s+6C_{\lambda,H}h^{2H}\\ &\leq 6hK\int_t^{t+h}\Psi (2\mathbb{E} |X_{s}^{\epsilon}| ^2+\mathbb{E} |Y_{s}^{\epsilon}| ^2)\,{\mathrm{d}} s +6hK_1\\&\quad +6C_{\lambda,H}h^{2H-1}\int_t^{t+h}\Psi (\mathbb{E} |X_{s}^{\epsilon}| ^2)\,{\mathrm{d}} s\\&\quad +6C_{\lambda,H}h^{2H}+6h^2K_1+6K\int_t^{t+h}\Psi ( \mathbb{E} |X_{s}^{\epsilon}| ^2)\,{\mathrm{d}} s\\&\leq C_T (h+h^2+h^{2H}).\end{align*}
We then present some auxiliary processes and conclusions that will be utilized in the subsequent proof. Additionally, we define the following auxiliary processes, which are modifications of the fast–slow equation (1). Let [x] represent the largest integer less than or equal to x. Partitioning [0,T] into subintervals of the same length
 $\delta$
, we construct for
 $t\in[k\delta,\min\!((k+ 1)\delta),T) ]$
,
 $k\geq0$
,
 \begin{equation*}{\mathrm{d}} \hat{Y}_t^\epsilon=\dfrac{1}{\epsilon}g \bigl({X}_{k\delta}^\epsilon,\mathscr{L}\bigl(X_{k\delta}^{\epsilon}\bigr),\hat{Y}_t^\epsilon\bigr)\,{\mathrm{d}} t+\dfrac{1}{\sqrt{\epsilon}}B \bigl({X}_{k\delta}^\epsilon,\mathscr{L}\bigl(X_{k\delta}^{\epsilon}\bigr),\hat{Y}_t^\epsilon\bigr)\,{\mathrm{d}} W^2_t,\quad \hat{Y}_{k\delta}^\epsilon=Y_{k\delta}^\epsilon.\end{equation*}
We also define
 \begin{align*}\hat{X}_t^\epsilon&= x_0+\int_{0}^{t}f \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr)\,{\mathrm{d}} s+\int_{0}^{t}\sigma_\omega (X_s^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) )\,{\mathrm{d}} W^1_s\\&\quad +\int_{0}^{t}\sigma_H (\mathscr{L} (X_{s}^{\epsilon}) )\,{\mathrm{d}} B^H_s.\end{align*}
Via an argument similar to the proof of Lemma 2, we obtain the following lemma.
Lemma 4. For any
 $T>0$
, there exists a constant
 $C_T>0$
such that
 \begin{equation*}\textrm{sup}_{0<\epsilon<1}\textrm{sup}_{0\leq s\leq t}\mathbb{E} |\hat{Y}^\epsilon_s| ^2\leq C_T (1+|x_0|^2+|y_0|^2) .\end{equation*}
Subsequently we will prove the relationship between the fast–slow equation (1) and its modified process.
Lemma 5. For any
 $T>0$
, there exists a constant
 $C_T>0$
such that
 \begin{equation*}\textrm{sup}_{0<\epsilon<1}\mathbb{E} |{Y}^\epsilon_t-\hat{Y}^\epsilon_t| ^2\leq C_T (1+|x_0|^2+|y_0|^2)\Psi (\delta+\delta^2+\delta^{2H}) .\end{equation*}
Proof. It is easy to see that
 \begin{align*}Y_{t}^{\epsilon}-\hat{Y}^\epsilon_t &=\dfrac{1}{\epsilon}\int_0^t\bigl[g (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon}) -g \bigl({X}_{k\delta}^\epsilon,\mathscr{L}\bigl(X_{k\delta}^{\epsilon}\bigr),\hat{Y}_s^\epsilon\bigr) \bigr]\,{\mathrm{d}} s\\&\quad +\dfrac{1}{\sqrt{\epsilon}}\int_0^t\bigl[B (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon}) -B \bigl({X}_{k\delta}^\epsilon,\mathscr{L}\bigl(X_{k\delta}^{\epsilon}\bigr),\hat{Y}_s^\epsilon\bigr) \bigr]\,{\mathrm{d}} W^2_s.\end{align*}
By Itô’s formula, (A4), and Lemma 3, we obtain
 \begin{align*}\dfrac{{\mathrm{d}} \mathbb{E} |Y_{t}^{\epsilon}-\hat{Y}^\epsilon_t| ^2}{{\mathrm{d}} t}& =\dfrac{2}{\epsilon}\mathbb{E}\bigl\langle Y_{t}^{\epsilon}-\hat{Y}^\epsilon_t,g (X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}),Y_{t}^{\epsilon}) -g \bigl({X}_{k\delta}^\epsilon,\mathscr{L}\bigl(X_{k\delta}^{\epsilon}\bigr),\hat{Y}_t^\epsilon\bigr) \bigr\rangle\\&\quad +\dfrac{1}{\epsilon}E \bigl\|B (X_{t}^{\epsilon},\mathscr{L}(X_{t}^{\epsilon}),Y_{t}^{\epsilon}) -B \bigl({X}_{k\delta}^\epsilon,\mathscr{L}\bigl(X_{k\delta}^{\epsilon}\bigr),\hat{Y}_t^\epsilon\bigr) \bigr\| ^2\\& \leq-\beta_2\mathbb{E} |Y_{t}^{\epsilon}-\hat{Y}^\epsilon_t| ^2+K\Psi \bigl(\mathbb{E} |X_{t}^{\epsilon}-{X}_{k\delta}^\epsilon| ^2+{\mathbb W}^2_2 \bigl(\mathscr{L}(X_{t}^{\epsilon}),\mathscr{L}\bigl(X_{k\delta}^{\epsilon}\bigr)\bigr) \bigr) \\&\leq-\dfrac{\beta_2}{\epsilon}\mathbb{E} |Y_{t}^{\epsilon}-\hat{Y}^\epsilon_t| ^2+\dfrac{K}{\epsilon}\Psi \bigl(2\mathbb{E} |X_{t}^{\epsilon}-{X}_{k\delta}^\epsilon| ^2\bigr) \\& \leq -\dfrac{\beta_2}{\epsilon}\mathbb{E} |Y_{t}^{\epsilon}-\hat{Y}^\epsilon_t| ^2+\dfrac{K}{\epsilon}\Psi (2\delta+2\delta^2+2\delta^{2H}) .\end{align*}
Finally, the Gronwall inequality yields
 \begin{equation*}\textrm{sup}_{0<\epsilon<1}\mathbb{E} |{Y}^\epsilon_t-\hat{Y}^\epsilon_t| ^2\leq C_T (1+|x_0|^2+|y_0|^2)\Psi (\delta+\delta^2+\delta^{2H}).\end{equation*}
Lemma 6. For any
 $T>0$
, there exists a constant
 $C_T>0$
such that
 \begin{equation*}\textrm{sup}_{0<\epsilon<1}\mathbb{E} |{X}^\epsilon_t-\hat{X}^\epsilon_t| ^2\leq C_T (1+|x_0|^2+|y_0|^2)\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) .\end{equation*}
Proof. Note that
 \begin{equation*}{X}^\epsilon_t-\hat{X}^\epsilon_t=\int_0^{t}\bigl[f (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon}) -f \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) \bigr]\,{\mathrm{d}} s.\end{equation*}
By the Hölder inequality, (A1), and the Jensen inequality, we get
 \begin{align*}\mathbb{E} |{X}^\epsilon_t-\hat{X}^\epsilon_t| ^2& =\mathbb{E}\biggl|\int_0^{t}\bigl[f (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon}) -f \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) \bigr]\,{\mathrm{d}} s\biggr|^2\\& \leq t\int_0^{t}\mathbb{E} |f (X_{s}^{\epsilon},\mathscr{L}(X_{s}^{\epsilon}),Y_{s}^{\epsilon}) -f \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) | ^2\,{\mathrm{d}} s\\& \leq t\int_0^{t}K\mathbb{E}\Psi \bigl( |X_{s}^{\epsilon}-X_{[s/\delta]\delta}^{\epsilon}| ^2+ |Y_{s}^{\epsilon}-\hat{Y}_s^\epsilon| ^2+{\mathbb W}^2_2 \bigl(\mathscr{L}(X_{s}^{\epsilon}),\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) \bigr) \bigr)\,{\mathrm{d}} s\\& \leq t\int_0^{t}K\Psi \bigl(2\mathbb{E} |X_{s}^{\epsilon}-X_{[s/\delta]\delta}^{\epsilon}| ^2+\mathbb{E} |Y_{s}^{\epsilon}-\hat{Y}_s^\epsilon| ^2\bigr)\,{\mathrm{d}} s.\end{align*}
 \begin{align*}\mathbb{E} |{X}^\epsilon_t-\hat{X}^\epsilon_t| ^2& \leq t^2K\Psi (2C_T (\delta+\delta^2+\delta^{2H}) +C_T (1+|x_0|^2+|y_0|^2)\Psi (\delta+\delta^2+\delta^{2H}) ) \\& \leq C_T (1+|x_0|^2+|y_0|^2)\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) .\end{align*}
The proof is complete.
4. The frozen equation and the averaged equation
In this section we present an exponential ergodicity of the frozen equation, along with certain properties of the coefficient for the averaged equation.
We first introduce the frozen equation, for fixed
 $t\geq0$
,
 $x\in \mathbb R^{d}$
,
 $\mu\in \mathscr{P}_2(\mathbb R^{d})$
,
 \begin{equation}{\mathrm{d}} Y_{t}^{x,\mu} =g (x,\mu,Y_{t}^{x,\mu})\,{\mathrm{d}} t+B (x,\mu,Y_{t}^{x,\mu})\,{\mathrm{d}} \tilde{W}^2_t,Y_{0}^{x}=y_0\in \mathbb R^{d},\end{equation}
where
 $\tilde{W}^2_t\in\mathbb R^{d}$
is a standard Wiener process.
We next prove the exponential ergodicity of the frozen equation. Let
 $Y_t^{x,\mu,y_1}$
be the solution of system (4) with initial value
 $Y^x_0 = y_1$
. In order to show the exponential ergodicity, we need to add a assumption.
(A1ʹ) There exists a constant K such that for any
 $t\in [0,T]$
,
 $x, x_1, x_2, y, y_1, y_2\in \mathbb R^{d}$
,
 $\mu, \nu\in \mathscr{P}_2(\mathbb R^{d})$
,
 \begin{equation*} |f (x_1,\mu,y_1) -f (x_2,\nu,y_2) | ^2 \leq K\Psi (|x_1-x_2|^2+{\mathbb W}^2_2(\mu,\nu)) +K|y_1-y_2|^2.\end{equation*}
Remark 3. Even this condition is weaker than the Lipschitz condition. If
 $\Psi(x) = x$
, assumption (A1ʹ) also implies the Lipschitz condition.
Lemma 7. For any
 $t\in [0,T]$
, x,
 $y_0$
,
 $y\in \mathbb R^{d}$
,
 $\mu\in \mathscr{P}_2(\mathbb R^{d})$
,
 \begin{equation*} |\mathbb{E}f (x,\mu,Y_{t}^{x,\mu,y_0}) -\bar{f}(x,\mu)| \leq C (1 + |x|^2+ |y_0| ^2+\mu(|\cdot|^2)) \,{\mathrm{e}}^{-\beta_2t}.\end{equation*}
Proof. For any
 $t\in [0,T]$
, x,
 $y_1$
,
 $y_2\in \mathbb R^{d}$
,
 $\mu\in \mathscr{P}_2(\mathbb R^{d})$
, it follows from the Itô formula and (A4) that
 \begin{align*}& \dfrac{{\mathrm{d}}\mathbb{E} |Y_{t}^{x,\mu,y_1}-Y_{t}^{x,\mu,y_2}| ^2}{{\mathrm{d}} t}\\&\quad = 2\mathbb{E}\langle Y_{t}^{x,\mu,y_1}-Y_{t}^{x,\mu,y_2},g (x,\mu ,y_1) -g (x,\mu,y_2) \rangle+\mathbb{E} \|B (x,\mu ,y_1) -B (x,\mu ,y_2) \| ^2\\&\quad \leq -\beta_2\mathbb{E} |Y_{t}^{x,\mu,y_1}-Y_{t}^{x,\mu,y_2}| ^2.\end{align*}
By the Gronwall inequality, we have
 \begin{equation}\mathbb{E} |Y_{t}^{x,\mu,y_1}-Y_{t}^{x,\mu,y_2}| ^2\leq|y_1-y_2|\,{\mathrm{e}}^{-\beta_2t}.\end{equation}
On the other hand, by [Reference Liu and Röckner9], it is easy to show that there exists a unique invariant measure
 $\nu^{x,\mu}$
associated to
 $P_t^{x,\mu}$
, where
 $P_t^{x,\mu}$
is the transition semigroup of
 $Y_{t}^{x,\mu}$
, which satisfies
 \begin{equation}\int_{\mathbb R^{d}}|y|^2\nu^{x,\mu}({\mathrm{d}} y)\leq C (1 + |x|^2+\mu(|\cdot|^2)) .\end{equation}
By the definition of an invariant measure, (A1ʹ), (5), and (6), we get
 \begin{align*}& |\mathbb{E}f (x,\mu,Y_{t}^{x,\mu,y_0}) -\bar{f}(x,\mu)| \\&\quad = |\mathbb{E}f (x,\mu,Y_{t}^{x,\mu,y_0}) -\int_{\mathbb R^{d}}{f}(x,\mu,y)\nu^{x,\mu}({\mathrm{d}} y)| ^2\\&\quad \leq \biggl|\int_{\mathbb R^{d}}\bigl[\mathbb{E}f (x,\mu,Y_{t}^{x,\mu,y_0}) -\mathbb{E}{f} (x,\mu,Y_{t}^{x,\mu,y}) \bigr]\nu^{x,\mu}({\mathrm{d}} y)\biggr| ^2\\&\quad \leq C\int_{\mathbb R^{d}}\mathbb{E} |f (x,\mu,Y_{t}^{x,\mu,y_0}) -{f} (x,\mu,Y_{t}^{x,\mu,y}) | ^2\nu^{x,\mu}({\mathrm{d}} y)\\&\quad \leq CK\int_{\mathbb R^{d}}\Psi (\mathbb{E} |Y_{t}^{x,\mu,y_0}-Y_{t}^{x,\mu,y}| ^2) \nu^{x,\mu}({\mathrm{d}} y)\\&\quad \leq CK\int_{\mathbb R^{d}} (|y_0-y|^2{\mathrm{e}}^{-\beta_2t}) \nu^{x,\mu}({\mathrm{d}} y)\\&\quad \leq CK{\mathrm{e}}^{-\beta_2t}\int_{\mathbb R^{d}}|y_0-y|^2\nu^{x,\mu}({\mathrm{d}} y)\\&\quad \leq C (1 + |x|^2+ |y_0| ^2+\mu(|\cdot|^2)) \,{\mathrm{e}}^{-\beta_2t}.\end{align*}
Define the averaged system as follows:
 \begin{equation}{\mathrm{d}} Z_{t} =\bar{f} (Z_{t},\mathscr{L}(Z_{t}))\,{\mathrm{d}} t+\sigma_\omega (Z_{t},\mathscr{L}(Z_{t}))\,{\mathrm{d}} W^1_t+\sigma_H (\mathscr{L}(Z_{t}))\,{\mathrm{d}} B^H_t,\quad Z_{0}=x_0\in \mathbb R^{d},\end{equation}
where
 \begin{equation*}\bar{f} (x,\mu) =\int_{\mathbb R^{d}}{f}(x,\mu,y)\nu^{x,\mu}({\mathrm{d}} y),\end{equation*}
and
 $\nu^{x,\mu}$
is the unique invariant measure of (4).
We next show that the function
 $\bar{f}$
is non-Lipschitz continuous and linear growth.
Lemma 8. There exists a constant K such that for any
 $t\in [0,T]$
,
 $x_1$
,
 $x_2\in \mathbb R^{d}$
,
 $\mu_1$
,
 $\mu_2\in \mathscr{P}_2(\mathbb R^{d})$
,
 \begin{equation*} |\bar{f} (x_1,\mu) -\bar{f} (x_2,\nu) | ^2 \leq C\Psi_1 \bigl(|x_1-x_2|^2+{\mathbb W}^2_2(\mu_1,\mu_2)\bigr) ,\end{equation*}
where
 $\Psi_1=\Psi(x+\Psi(x))\colon \mathbb R_+\rightarrow \mathbb R_+$
is a continuous and non-decreasing concave function with
 $\Psi_1(0)=0$
,
 $\Psi_1(x) > 0$
for all
 $x > 0$
such that
 \[\int_{0^+}\frac{1}{\Psi_1(x)}{\mathrm{d}} x=+\infty.\]
There is a positive constant
 $K_1$
such that
 \begin{equation*} |\bar{f} (0,\delta_0) | ^2\leq K_1.\end{equation*}
Proof. By assumption (A1) and the Jensen inequality, we obtain
 \begin{align} |\bar{f} (x_1,\mu_1) -\bar{f} (x_2,\mu_2) | ^2 & = \biggl|\int_{\mathbb R^{d}}{f}(x_1,\mu_1,y)\nu^{x_1,\mu_1}({\mathrm{d}} y)-\int_{\mathbb R^{d}}{f}(x_2,\mu_2,y)\nu^{x_2,\mu_2}({\mathrm{d}} y)\biggr|^2\nonumber\\&= \lim_{t\rightarrow\infty} |\mathbb{E}{f} (x_1,\mu_1,Y_{t}^{x_1,\mu_1,y}) -\mathbb{E}{f} (x_2,\mu_2,Y_{t}^{x_2,\mu_2,y}) | ^2\nonumber\\& \leq \lim_{t\rightarrow\infty}\mathbb{E} |{f} (x_1,\mu_1,Y_{t}^{x_1,\mu_1,y}) -{f} (x_2,\mu_2,Y_{t}^{x_2,\mu_2,y}) | ^2\nonumber\\& \leq \lim_{t\rightarrow\infty}K\Psi \bigl(|x_1-x_2|^2+\mathbb{E}|Y_{t}^{x_1,\mu_1,y}-Y_{t}^{x_2,\mu_2,y}|^2+{\mathbb W}^2_2(\mu_1,\mu_2)\bigr) \nonumber\\& = K\Psi \bigl(|x_1-x_2|^2+\lim_{t\rightarrow\infty}\mathbb{E}|Y_{t}^{x_1,\mu_1,y}-Y_{t}^{x_2,\mu_2,y}|^2+{\mathbb W}^2_2(\mu_1,\mu_2)\bigr) .\end{align}
On the other hand, by the Itô formula, (A4), and the definition of
 $Y_t^{x,\mu,y}$
, we have
 \begin{align*} \dfrac{{\mathrm{d}}\mathbb{E} |Y_{t}^{x_1,\mu_1,y}-Y_{t}^{x_2,\mu_2,y}| ^2}{{\mathrm{d}} t} & =2\mathbb{E}\langle Y_{t}^{x_1,\mu_1,y}-Y_{t}^{x_2,\mu_2,y},g (x_1,\mu_1 ,Y_{t}^{x_1,\mu_1,y}) -g (x_2,\mu_2,Y_{t}^{x_2,\mu_2,y}) \rangle\\&\quad +\mathbb{E} \|B (x_1,\mu_1,Y_{t}^{x_1,\mu_1,y}) -B (x_2,\mu_2 ,Y_{t}^{x_2,\mu_2,y}) \| ^2\\& \leq -\beta_2\mathbb{E} |Y_{t}^{x_1,\mu_1,y}-Y_{t}^{x_2,\mu_2,y}| ^2+K\Psi \bigl(|x_1-x_2|^2+{\mathbb W}^2_2(\mu_1,\mu_2)\bigr) .\end{align*}
Hence, the Gronwall inequality yields
 \begin{equation*}\mathbb{E} |Y_{t}^{x_1,\mu_1,y}-Y_{t}^{x_2,\mu_2,y}| ^2\leq {\mathrm{e}}^{-\beta_2 t}|y_1-y_2|^2+CK\Psi \bigl(|x_1-x_2|^2+{\mathbb W}^2_2(\mu_1,\mu_2)\bigr) .\end{equation*}
This and (8) yield
 \begin{align*} |\bar{f} (x_1,\mu_1) -\bar{f} (x_2,\mu_2) | ^2 & \leq C\Psi \bigl(|x_1-x_2|^2+{\mathbb W}^2_2(\mu_1,\mu_2)+\Psi \bigl(|x_1-x_2|^2+{\mathbb W}^2_2(\mu_1,\mu_2)\bigr) \bigr) \\& \,:\!=\, C\Psi_1 \bigl(|x_1-x_2|^2+{\mathbb W}^2_2(\mu_1,\mu_2)\bigr) .\end{align*}
Because of the properties of
 $\Psi$
, the
 $\Psi_1=\Psi(x+\Psi(x))\colon \mathbb R_+\rightarrow \mathbb R_+$
is a continuous and non-decreasing concave function with
 $\Psi_1(0)=0$
,
 $\Psi_1(x) > 0$
for all
 $x > 0$
such that
 \[\int_{0^+}\frac{1}{\Psi_1(x)}{\mathrm{d}} x=+\infty.\]
Furthermore, by (A1) it is easy to derive that
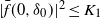 $ |\bar{f} (0,\delta_0) | ^2\leq K_1$
, which completes the proof.
Finally, by an argument similar to the proof of Theorem 1, it is easy to obtain the existence and uniqueness results for the averaged equation (7). We omit the proof here.
Lemma 9. Suppose that assumptions (A1) and (A2) hold. For each
 $\epsilon>0$
and initial values
 $x_0\in\mathbb R^{d}$
, system (7) has a unique solution
 $Z_t$
.
5. Averaging principle
In this section we will establish the main theorem in this paper: a stochastic averaging principle for fast–slow McKean–Vlasov SDEs driven by mixed fractional Brownian motion under non-Lipschitz conditions.
Theorem 2. Suppose (A1)–(A4) and (A1ʹ) are satisfied. The following averaging principle holds:
 \begin{equation*}\lim_{\epsilon\rightarrow0}\mathbb{E}|X^\epsilon_t-Z_t|^2=0.\end{equation*}
Proof. We will divide the proof into two steps.
Step 1. Note that
 \begin{align*}\hat{X}_t^\epsilon-Z_t&= \int_{0}^{t}[\sigma_\omega(X_s^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) )-\sigma_\omega(Z_{s},\mathscr{L}(Z_{s}))]\,{\mathrm{d}} W^1_s\\&\quad +\int_{0}^{t}[\sigma_H (\mathscr{L} (X_{s}^{\epsilon}) ) -\sigma_H (\mathscr{L}(Z_{s})) ]\,{\mathrm{d}} B^H_s\\&\quad +\int_{0}^{t}\bigl[f \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} (Z_{s},\mathscr{L}(Z_{s})) \bigr]\,{\mathrm{d}} s\\&=\int_{0}^{t}[\sigma_\omega(X_s^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) )-\sigma_\omega(Z_{s},\mathscr{L}(Z_{s}))]\,{\mathrm{d}} W^1_s\\&\quad +\int_{0}^{t}[\sigma_H (\mathscr{L} (X_{s}^{\epsilon}) ) -\sigma_H (\mathscr{L}(Z_{s})) ]\,{\mathrm{d}} B^H_s\\&\quad +\int_{0}^{t}\bigl[f \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) \bigr) \bigr]\,{\mathrm{d}} s\\&\quad +\int_{0}^{t}\bigl[\bar{f} \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) \bigr) -\bar{f} (X_{s}^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) ) \bigr]\,{\mathrm{d}} s\\&\quad +\int_{0}^{t}[\bar{f} (X_{s}^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) ) -\bar{f} (Z_{t},\mathscr{L}(Z_{s})) ]\,{\mathrm{d}} s.\end{align*}
Then, by the Cauchy–Schwarz inequality, we have
 \begin{align*}\mathbb{E} |\hat{X}_t^\epsilon-Z_t| ^2&\leq 5\mathbb{E}\biggl|\int_{0}^{t}[\sigma_\omega(X_s^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) )-\sigma_\omega(Z_{s},\mathscr{L}(Z_{s}))]\,{\mathrm{d}} W^1_s\biggr|^2\\&\quad +5\mathbb{E}\biggl|\int_{0}^{t}[\sigma_H (\mathscr{L} (X_{s}^{\epsilon}) ) -\sigma_H (\mathscr{L}(Z_{s})) ]\,{\mathrm{d}} B^H_s\biggr|^2\\&\quad +5\mathbb{E}\biggl|\int_{0}^{t}\bigl[f \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) \bigr) \bigr]\,{\mathrm{d}} s\biggr|^2\\&\quad +5\mathbb{E}\biggl|\int_{0}^{t}\bigl[\bar{f} \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) \bigr) -\bar{f} (X_{s}^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) ) \bigr]\,{\mathrm{d}} s\biggr|^2\\&\quad +5\mathbb{E}\biggl|\int_{0}^{t}[\bar{f} (X_{s}^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) ) -\bar{f} (Z_{s},\mathscr{L}(Z_{s})) ]\,{\mathrm{d}} s\biggr|^2\,:\!=\, \sum^{5}_{i=1}5I_i(t).\end{align*}
In view of the Hölder inequality and Lemmas 8 and 3, we get
 \begin{align*}I_4(t)&= \mathbb{E}\biggl|\int_{0}^{t} \bigl[\bar{f} \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) \bigr) -\bar{f} (X_{s}^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) ) \bigr]\,{\mathrm{d}} s\biggr|^2\\&\leq t\int_{0}^{t}\mathbb{E} \bigl|\bar{f} \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) \bigr) -\bar{f} (X_{s}^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) ) \bigr| ^2\,{\mathrm{d}} s\\&\leq tC\int_{0}^{t}\mathbb{E}\Psi_1 \bigl( \bigl|X_{[s/\delta]\delta}^{\epsilon}-X_{s}^{\epsilon}\bigr| ^2+{\mathbb W}^2_2 \bigl(\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) ,\mathscr{L} (X_{s}^{\epsilon}) \bigr) \bigr) \,{\mathrm{d}} s\\&\leq tC\int_{0}^{t}\Psi_1 \bigl(2\mathbb{E} \bigl|X_{[s/\delta]\delta}^{\epsilon}-X_{s}^{\epsilon}\bigr| ^2\bigr)\,{\mathrm{d}} s\\&\leq C\Psi_1 (\delta+\delta^2+\delta^{2H}) .\end{align*}
By the Hölder inequality, and Lemmas 8 and 6, we have
 \begin{align*}I_5(t)&= \mathbb{E}\biggl|\int_{0}^{t}[\bar{f} (X_{s}^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) ) -\bar{f} (Z_{s},\mathscr{L}(Z_{s})) ]\,{\mathrm{d}} s\biggr|^2\\&\leq t\int_{0}^{t}\mathbb{E} |\bar{f} (X_{s}^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) ) -\bar{f} (Z_{s},\mathscr{L}(Z_{s})) | ^2\,{\mathrm{d}} s\\&\leq \int_{0}^{t}2t\mathbb{E} |\bar{f} (X_{s}^{\epsilon},\mathscr{L} ({X}_{s}^{\epsilon}) ) -\bar{f} (\hat{X}_{s}^{\epsilon},\mathscr{L} (\hat{X}_{s}^{\epsilon}) ) | ^2\,{\mathrm{d}} s\\&\quad +\int_{0}^{t}2t\mathbb{E} |\bar{f} (\hat{X}_{s}^{\epsilon},\mathscr{L} (\hat{X}_{s}^{\epsilon}) ) -\bar{f} (Z_{s},\mathscr{L}(Z_{s})) | ^2\,{\mathrm{d}} s\\&\leq C\int_{0}^{t}\Psi_1 (2\mathbb{E} |X_{s}^{\epsilon}-\hat{X}_{s}^{\epsilon}| ^2)\,{\mathrm{d}} s+C\int_{0}^{t}\Psi_1 (2\mathbb{E} |\hat{X}_{s}^{\epsilon}-Z_{s}| ^2)\,{\mathrm{d}} s\\&\leq C\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) +C\int_{0}^{t}\Psi_1 (2\mathbb{E} |\hat{X}_{s}^{\epsilon}-Z_{s}| ^2)\,{\mathrm{d}} s.\end{align*}
By the moment inequality and Lemmas 8 and 6, we get
 \begin{align*}I_1(t)&= \mathbb{E}\biggl|\int_{0}^{t}[\sigma_\omega(X_s^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) )-\sigma_\omega(Z_{s},\mathscr{L}(Z_{s}))]\,{\mathrm{d}} W^1_s\biggr|^2\\&\leq \int_{0}^{t}\mathbb{E} \|\sigma_\omega(X_s^{\epsilon},\mathscr{L} (X_{s}^{\epsilon}) )-\sigma_\omega(Z_{s},\mathscr{L}(Z_{s}))\| ^2\,{\mathrm{d}} s\\&\leq \int_{0}^{t}2\mathbb{E} \|\sigma_\omega (X_{s}^{\epsilon},\mathscr{L} ({X}_{s}^{\epsilon}) ) -\sigma_\omega (\hat{X}_{s}^{\epsilon},\mathscr{L} (\hat{X}_{s}^{\epsilon}) ) \| ^2\,{\mathrm{d}} s\\&\quad +\int_{0}^{t}2\mathbb{E} \|\sigma_\omega (\hat{X}_{s}^{\epsilon},\mathscr{L} (\hat{X}_{s}^{\epsilon}) ) -\sigma_\omega (Z_{s},\mathscr{L}(Z_{s})) \| ^2\,{\mathrm{d}} s\\&\leq C\int_{0}^{t}\Psi_1 (2\mathbb{E} |X_{s}^{\epsilon}-\hat{X}_{s}^{\epsilon}| ^2)\,{\mathrm{d}} s+C\int_{0}^{t}\Psi_1 (2\mathbb{E} |\hat{X}_{s}^{\epsilon}-Z_{s}| ^2)\,{\mathrm{d}} s\\&\leq C\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) +C\int_{0}^{t}\Psi_1 (2\mathbb{E} |\hat{X}_{s}^{\epsilon}-Z_{s}| ^2)\,{\mathrm{d}} s.\end{align*}
From [Reference Fan, Huang, Suo and Yuan3, (3.5)] and Lemmas 8 and 6, we obtain
 \begin{align*}I_2(t)&= \mathbb{E}\biggl|\int_{0}^{t}[\sigma_H (\mathscr{L} (X_{s}^{\epsilon}) ) -\sigma_H (\mathscr{L}(Z_{s})) ]\,{\mathrm{d}} B^H_s\biggr|^2\\&\leq t^{2H-1}\int_{0}^{t}\mathbb{E} \|\sigma_H(\mathscr{L} (X_{s}^{\epsilon}) )-\sigma_H(\mathscr{L}(Z_{s}))\| ^2\,{\mathrm{d}} s\\&\leq \int_{0}^{t}2t^{2H-1}\mathbb{E} \|\sigma_H (\mathscr{L} ({X}_{s}^{\epsilon}) ) -\sigma_H (\mathscr{L} (\hat{X}_{s}^{\epsilon}) ) \| ^2\,{\mathrm{d}} s\\&\quad +\int_{0}^{t}2t^{2H-1}\mathbb{E} \|\sigma_H (\mathscr{L} (\hat{X}_{s}^{\epsilon}) ) -\sigma_H (\mathscr{L}(Z_{s})) \| ^2\,{\mathrm{d}} s\\&\leq C\int_{0}^{t}\Psi_1 (\mathbb{E} |X_{s}^{\epsilon}-\hat{X}_{s}^{\epsilon}| ^2)\,{\mathrm{d}} s+C\int_{0}^{t}\Psi_1 (\mathbb{E} |\hat{X}_{s}^{\epsilon}-Z_{s}| ^2)\,{\mathrm{d}} s\\&\leq C\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) +C\int_{0}^{t}\Psi_1 (\mathbb{E} |\hat{X}_{s}^{\epsilon}-Z_{s}| ^2)\,{\mathrm{d}} s.\end{align*}
For
 $I_3(t)$
, we obtain
 \begin{align*}I_3(t)&= \mathbb{E}\biggl|\int_{0}^{t}\bigl[f \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} \bigl(X_{[s/\delta]\delta}^{\epsilon},\mathscr{L} \bigl(X_{[s/\delta]\delta}^{\epsilon}\bigr) \bigr) \bigr]\,{\mathrm{d}} s\biggr|^2\\&\leq 2\mathbb{E} \Biggl|\sum^{[t/\delta]-1}_{k=0}\int_{k\delta}^{(k+1)\delta}f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \,{\mathrm{d}} s\Biggr| ^2 \\&\quad +2\mathbb{E}\biggl|\int_{t(\delta)}^{t}\bigl[f \bigl(X_{t(\delta)}^{\epsilon},\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} \bigl(X_{t(\delta)}^{\epsilon},\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) \bigr) \bigr]\,{\mathrm{d}} s\biggr|^2\\& \,:\!=\, I_{31}(t)+I_{32}(t).\end{align*}
By the Hölder inequality, (A1), (A2), and Lemma 2, we get
 \begin{align*}I_{32}(t)&= 2\mathbb{E}\biggl|\int_{t(\delta)}^{t}f \bigl(X_{t(\delta)}^{\epsilon},\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} \bigl(X_{t(\delta)}^{\epsilon},\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) \bigr) \,{\mathrm{d}} s\biggr|^2\\&\leq 2t\int_{t(\delta)}^{t}\mathbb{E} \bigl|f \bigl(X_{t(\delta)}^{\epsilon},\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} \bigl(X_{t(\delta)}^{\epsilon},\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) \bigr) \bigr| ^2\,{\mathrm{d}} s\\&\leq 8\delta\int_{t(\delta)}^{t}\mathbb{E} \bigl|f \bigl(X_{t(\delta)}^{\epsilon},\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -f(0,\delta_0,0)\bigr| ^2\,{\mathrm{d}} s\\&\quad +8\delta\int_{t(\delta)}^{t}\mathbb{E} \bigl|\bar{f} \bigl(X_{t(\delta)}^{\epsilon},\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) \bigr) -\bar{f}(0,\delta_0)\bigr| ^2\,{\mathrm{d}} s\\&\quad +8\delta\int_{t(\delta)}^{t}\mathbb{E} |f(0,\delta_0,0)| ^2\,{\mathrm{d}} s+8\delta\int_{t(\delta)}^{t} |\bar{f}(0,\delta_0)| ^2\,{\mathrm{d}} s\\&\leq C\delta\int_{t(\delta)}^{t}\mathbb{E}\Psi \bigl( \bigl|X_{t(\delta)}^{\epsilon}\bigr| ^2+ |\hat{Y}_s^\epsilon| ^2+{\mathbb W}^2_2 \bigl(\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) ,\delta_0\bigr) \bigr) \,{\mathrm{d}} s+C\delta^2\\&\quad +C\delta\int_{t(\delta)}^{t}\mathbb{E}\Psi_1 \bigl( \bigl|X_{t(\delta)}^{\epsilon}\bigr| ^2+{\mathbb W}^2_2 \bigl(\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) ,\delta_0\bigr) \bigr) \,{\mathrm{d}} s\\&\leq C\delta\int_{t(\delta)}^{t}\Psi \bigl(2 \mathbb{E} \bigl|X_{t(\delta)}^{\epsilon}\bigr| ^2+\mathbb{E} |\hat{Y}_s^\epsilon| ^2\bigr) \,{\mathrm{d}} s+C\delta^2+C\delta\int_{t(\delta)}^{t}\Psi_1 \bigl(2\mathbb{E} |X_{t(\delta)}^{\epsilon}\bigr| ^2\bigr) \,{\mathrm{d}} s\\&\leq C\delta^2.\end{align*}
Note that
 \begin{align*}I_{31}(t)&= 2\mathbb{E}\biggl|\sum^{[t/\delta]-1}_{k=0}\int_{k\delta}^{(k+1)\delta}f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \,{\mathrm{d}} s\biggr|^2\\&\leq 2\dfrac{t}{\delta}\sum^{[t/\delta]-1}_{k=0}\mathbb{E}\biggl|\int_{k\delta}^{(k+1)\delta}f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \,{\mathrm{d}} s\biggr|^2\\&\,:\!=\, 2\dfrac{t}{\delta}\sum^{[t/\delta]-1}_{k=0}A^k.\end{align*}
Further,
 \begin{align*}A^k&= \mathbb{E}\biggl|\int_{k\delta}^{(k+1)\delta}f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_s^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \,{\mathrm{d}} s\biggr|^2\\&= \mathbb{E}\biggl|\int_{0}^{\delta}f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_{s+k\delta}^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \,{\mathrm{d}} s\biggr|^2\\&= 2\int_{0}^{\delta}\int_s^{\delta}\mathbb{E}\bigl\{\bigl[f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_{s+k\delta}^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \bigr]\\&\quad \times \mathbb{E}_{s+k\delta}\bigl[f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_{\tau+k\delta}^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \bigr] \bigr\}{\mathrm{d}} \tau \,{\mathrm{d}} s\\&\leq 2\int_{0}^{\delta}\int_s^{\delta}\bigl\{\mathbb{E}\bigl[f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_{s+k\delta}^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \bigr]^2\bigr\}^{{{1}/{2}}}\\&\quad \times \bigl\{\mathbb{E}\bigl[\mathbb{E}_{s+k\delta}\bigl[f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_{\tau+k\delta}^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \bigr] \bigr]^2\bigr\}^{{{1}/{2}}}{\mathrm{d}} \tau \,{\mathrm{d}} s.\end{align*}
By (A1), (A2), and Lemmas 8, 2, and 4, we have
 \begin{align}&\mathbb{E}\bigl[f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_{s+k\delta}^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \bigr]^2\nonumber\\&\quad \leq4\mathbb{E} \bigl|f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_{s+k\delta}^\epsilon\bigr) -f (0,\delta_0,0) \bigr| ^2+4 |f (0,\delta_0,0) | ^2\nonumber\\&\quad\quad +4\mathbb{E} \bigl|\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) -\bar{f} (0,\delta_0) \bigr| ^2+4 |\bar{f} (0,\delta_0) | ^2\nonumber\\&\quad \leq \mathbb{E}\Psi \bigl( |X_{k\delta}^{\epsilon}| ^2+ \bigl|\hat{Y}_{s+k\delta}^\epsilon\bigr| ^2+{\mathbb W}^2_2 \bigl(\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) ,\delta_0\bigr) \bigr) \nonumber\\&\quad\quad +\mathbb{E}\Psi_1 \bigl( |X_{t(\delta)}^{\epsilon}| ^2+{\mathbb W}^2_2 \bigl(\mathscr{L} \bigl(X_{t(\delta)}^{\epsilon}\bigr) ,\delta_0\bigr) \bigr)\nonumber\\&\quad \leq\Psi \bigl(2 \mathbb{E} |X_{t(\delta)}^{\epsilon}| ^2+\mathbb{E} |\hat{Y}_{k\delta+s}^\epsilon| ^2\bigr) + \Psi_1 (2\mathbb{E} |X_{t(\delta)}^{\epsilon}| ^2) \nonumber\\&\quad \leq C.\end{align}
The exponential ergodicity of the frozen equation yields
 \begin{equation}\bigl\{\mathbb{E}\bigl[\mathbb{E}_{s+k\delta}\bigl[f \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) ,\hat{Y}_{\tau+k\delta}^\epsilon\bigr) -\bar{f} \bigl(X_{k\delta}^{\epsilon},\mathscr{L} \bigl(X_{k\delta}^{\epsilon}\bigr) \bigr) \bigr] \bigr]^2\bigr\}^{{{1}/{2}}}\leq C\exp\biggl({-\frac{\beta_2(\tau-s)}{2\epsilon}}\biggr).\end{equation}
Combining (9) and (10), we get
 \begin{equation*}A^k\leq C\int_0^\delta\int_s^\delta \exp\biggl({-\frac{\beta_2(\tau-s)}{2\epsilon}}\biggr)\,{\mathrm{d}} \tau \,{\mathrm{d}} s\leq C (\epsilon\delta+\epsilon^2) .\end{equation*}
Thus
 \begin{equation*}I_{31}(t)\leq2\dfrac{t}{\delta}\sum^{[t/\delta]-1}_{k=0}A^k\leq C\biggl(\dfrac{\epsilon}{\delta}+\dfrac{\epsilon^2}{\delta^2}\biggr).\end{equation*}
Finally, we obtain
 \begin{align*} \mathbb{E}|\hat{X}_t^\epsilon-Z_t|^2&\leq 5C\Psi_1 (\delta+\delta^2+\delta^{2H}) +5C\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) \\&\quad +5C\int_{0}^{t}\Psi_1 (2\mathbb{E}|\hat{X}_{s}^{\epsilon}-Z_{s}|^2)\,{\mathrm{d}} s+5C\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) \\&\quad +5C\int_{0}^{t}\Psi_1 (2\mathbb{E}|\hat{X}_{s}^{\epsilon}-Z_{s}|^2)\,{\mathrm{d}} s+5C\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) \\&\quad +5C\int_{0}^{t}\Psi_1 (\mathbb{E}|\hat{X}_{s}^{\epsilon}-Z_{s}|^2)\,{\mathrm{d}} s+C\delta^2+5C\biggl(\dfrac{\epsilon}{\delta}+\dfrac{\epsilon^2}{\delta^2}\biggr)\\&\leq C\Psi_1 (\delta+\delta^2+\delta^{2H}) +\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) +C\delta^2\\&\quad +C\biggl(\dfrac{\epsilon}{\delta}+\dfrac{\epsilon^2}{\delta^2}\biggr)+C\int_{0}^{t}\Psi_1 (\mathbb{E}|\hat{X}_{s}^{\epsilon}-Z_{s}|^2)\,{\mathrm{d}} s+C\int_{0}^{t}\Psi_1 (2\mathbb{E}|\hat{X}_{s}^{\epsilon}-Z_{s}|^2)\,{\mathrm{d}} s\\&\leq C\Psi_1 (\delta+\delta^2+\delta^{2H}) +\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) +C\delta^2\\&\quad +C\biggl(\dfrac{\epsilon}{\delta}+\dfrac{\epsilon^2}{\delta^2}\biggr)+C\int_{0}^{t}\Psi_2 (p\mathbb{E}|\hat{X}_{s}^{\epsilon}-Z_{s}|^2)\,{\mathrm{d}} s,\end{align*}
where the
 $\Psi_2=\Psi_1(x)+\Psi_1(2x)\colon \mathbb R_+\rightarrow \mathbb R_+$
is a continuous and non-decreasing concave function with
 $\Psi_2(0)=0$
,
 $\Psi_2(x) > 0$
for all
 $x > 0$
such that
 \[\int_{0^+}\frac{1}{\Psi_2(x)}{\mathrm{d}} x=+\infty.\]
Step 2. By Lemma 6 and Step 1, it is easy to see that
 \begin{align*}\mathbb{E} |{X}_t^\epsilon-Z_t| ^2 & \leq 2\mathbb{E} |{X}_t^\epsilon-\hat{X}_t^\epsilon| ^2+2\mathbb{E} |\hat{X}_t^\epsilon-Z_t| ^2\\& \leq C_T (1+|x_0|^2+|y_0|^2)\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) +C\Psi_1 (\delta+\delta^2+\delta^{2H}) \\&\quad +\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) +C\delta^2+C\biggl(\dfrac{\epsilon}{\delta}+\dfrac{\epsilon^2}{\delta^2}\biggr)\\&\quad +C\int_{0}^{t}\Psi_2 (p\mathbb{E} |\hat{X}_{s}^{\epsilon}-Z_{s}| ^2)\,{\mathrm{d}} s.\end{align*}
Hence the Bihari inequality yields
 \begin{align*}\mathbb{E} |{X}_t^\epsilon-Z_t| ^2 & \leq G^{-1}\biggl(G\biggl(C_T (1+|x_0|^2+|y_0|^2)\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) \\&\quad +C\Psi_1 (\delta+\delta^2+\delta^{2H}) +\Psi_1 (\Psi (\delta+\delta^2+\delta^{2H}+\Psi (\delta+\delta^2+\delta^{2H}) ) ) +C\delta^2\\&\quad +C\biggl(\dfrac{\epsilon}{\delta}+\dfrac{\epsilon^2}{\delta^2}\biggr)\biggr)+Ct\biggr)\\&\,:\!=\, G^{-1} (G(F(\delta,\epsilon))+Ct)\end{align*}
for all
 $t\in[0,T]$
, where
 $F(\delta,\epsilon)\in \operatorname{Dom}\!(G^{-1})$
,
 $G^{-1}$
is the inverse function of G and
 \begin{equation*}G(r)=\int_1^r\dfrac{1}{\Psi_2(s)}\,{\mathrm{d}} s.\end{equation*}
Hence, taking
 $\delta=\sqrt{\epsilon}$
, the definition of
 $\Psi_2$
implies
 $\lim_{\epsilon\rightarrow 0^+}G(F(\delta,\epsilon))=-\infty$
. Finally, we can conclude that
 \begin{equation*}\lim_{\epsilon\rightarrow0}\mathbb{E}|X^\epsilon_t-Z_t|^2=0.\end{equation*}
Funding information
We would like to thank the support provided by NSFs of China (12301172), the PhD Research Startup Fund for Anhui Jianzhu University (2022QDZ19), the Research of the Department of Education for Anhui Province (2023AH050191,2024AH050265), and the Innovation Team of Operation Research and Combinatorial Optimization of Anhui Province (2023AH010020).
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.



