The literature on monetary policy highlights the role of monetary institutions in stabilizing private-sector inflation expectations. Central bank independence (CBI), inflation targeting (IT), and fixed exchange rates (pegs) are widely viewed as institutions that have the capacity to mitigate private-sector concerns that policymakers will exploit them after they have locked in their price, wage, and investment decisions. While other empirical research explores the institutional correlates of inflation and its variability—yielding mixed results—we use firm-level data in our study to directly assess the impact of monetary anchors on private-sector inflation concerns. We find evidence that pegs mitigate firm owners' concerns with inflation, but that domestic anchors such as IT and CBI are uncorrelated with our micro-indicators of inflation expectations.
Considerable research has investigated the use of IT, CBI, and pegs as institutions that establish monetary policy credibility. Whereas these anchors are expected, theoretically, to yield improvements in credibility, the empirical record is surprisingly weak, especially with respect to CBI.Footnote 1 The problem may be that the relationship between anchoring institutions and private-sector expectations has largely been skipped over in existing analyses, leaving a gap between the theory of inflation and empirical work. While some researchers use market-based proxies for inflation expectations, such as bond yields,Footnote 2 we exploit survey data to assess directly the relationship between monetary anchors and individual inflation perceptions.
Our micro-level approach provides a more proximate test of institutional theories of monetary credibility than work employing cross-country inflation regressions. It may also shed light on the empirical inconsistencies found in these country-level analyses. If certain monetary institutions are inherently more credible than others, then not only inflation but also private-sector inflation expectations should differ systematically across countries that differ in their institutions. If CBI reduces inflation, then firm owners in countries with more independent central banks should perceive their governments' promises of low inflation to be more credible. Likewise, if inflation targets and exchange-rate pegs anchor inflation outlooks, we should expect to find that business managers in countries with such regimes perceive policymakers to be more credible than managers in countries that lack these anchoring institutions. Examining the impact of institutions at the individual level is necessary because the structure of incentives provided by a country's institutions must work through private actors to have aggregate effects.
Improvements in cross-national surveys of firm managers allow us to analyze the connection between monetary institutions and individual perceptions. We draw upon the World Bank's World Business Environment Survey (WBES) for our firm-level data. In 1999, the WBES was administered to more than 10,000 firms in eighty-one countries. The stated purpose of the survey was to identify the features of a country's investment climate that matter most for productivity and growth, from the perspective of private-sector actors. The WBES assessed the institutional and policy environment for private enterprise using a common survey instrument, administered to a representative sample of firms in each country. This standardized approach allows us to draw consistent, cross-national inferences about the micro-level effects on monetary institutions.
This article is organized as follows. In the next section, we describe our research design and contrast it with existing work on monetary institutions. The second section presents our dependent variable from the WBES, and we assess its validity. The third section presents our measures of monetary institutions, and we provide preliminary evidence on how these regimes relate to private-sector inflation expectations. The fourth section contains our empirical models and findings. The final section concludes with a discussion of the implications of our study.
Monetary Anchors: Theory and Evidence
The widely accepted Barro-Gordon model of inflation examines the costs and benefits of surprise inflation in a game between a monetary authority and a representative private-sector actor.Footnote 3 After the monetary authority has announced its policy and the private-sector actor has taken actions that rely on that policy, the authority has an incentive to raise output above its full employment level through surprise inflation. In rational-expectations equilibrium, where inflation is predicted correctly by the private actor, output remains at its full employment level, but inflation and the volatility of inflation is higher than it would have been had the monetary authority been able to pre-commit.
This model of inflation has generated much research on institutional design. The challenge has been to design a monetary institution that credibly commits policy to an announced path but allows the policymaker some flexibility to adjust to shocks. Three institutions dominate the literature:
1. Central Bank Independence. Rogoff recommends delegating monetary policy to an independent and conservative central banker. To ensure greater flexibility, Lohmann proposes a partially independent central bank that accommodates political pressures only when extreme shocks hit the economy.Footnote 4 Walsh advocates optimal contracts that penalize central bank governors by loss of compensation for breaking promises without sufficient evidence of cause.Footnote 5
2. Exchange-Rate Pegging. Flood and Isard, and Canavan and Tommasi, show that pegging the exchange rate to a stable foreign currency provides a credible commitment to low inflation.Footnote 6 If it is fully supported by monetary policy, an unchanged peg will tend to produce the same rate of inflation as in the country of the currency peg. Pegging is also easy to implement and provides an observable commitment to monetary policy.Footnote 7 Yet pegging comes at a cost since it can eliminate the flexibility needed to use monetary policy to stabilize the domestic economy. Hence, the Flood and Isard model pegged regimes with “escape clauses.”Footnote 8
3. Inflation Targeting. Bernanke and Mishkin propose a numerical target for inflation whereby the inflation forecast over some horizon becomes the intermediate target of policy.Footnote 9 IT also requires central bank transparency and accountability to compensate for the greater operational flexibility that inflation targeting offers. Short-term deviations from the forecast target are possible and do not necessarily translate into losses in credibility.
A large body of macro-level empirical work is built on the Barro-Gordon framework but it is remarkable how limited the evidence is that CBI and IT bring lower inflation in practice. While some studies find that CBI correlates with lower average inflation,Footnote 10 others find little evidence of this in wider samples.Footnote 11 Overall, the empirical record for CBI is quite weak, as noted in various reviews.Footnote 12
The evidence on IT is also inconclusive. While studies such as Ammer and Freeman, and Mishkin and Posen, found that average inflation fell under IT,Footnote 13 Cecchetti and Ehrmann did not find similar benefits.Footnote 14 Ball and Sheridan find no evidence that inflation targeters performed better than nontargeters,Footnote 15 but Mishkin and Schmidt-Hebbel challenge their results.Footnote 16
By contrast, the correlation between pegging and lower inflation is found in many studies. Mahadeva and Sterne report that thirty-nine of seventy episodes of stable inflation came under exchange-rate pegs; among developing countries, all fourteen episodes of stable inflation occurred through pegging.Footnote 17 Calvo and Vegh show that developing countries that pegged were successful in stabilizing inflation, and Giavazzi and Pagano find that membership in the European Monetary System brought significant credibility gains to inflation-prone countries.Footnote 18 More generally, Ghosh, Gulde, and Wolf study a large sample of advanced and developing countries and find that inflation averaged 9 percent under pegs, 30 percent under intermediate regimes, and 59 percent under floating regimes.Footnote 19 Tavlas, Dellas, and Stockman conclude that “pegged exchange-rate systems tend to be associated with lower inflation rates.”Footnote 20
In summary, the country-level empirical record suggests that nations with a history of high inflation improved their monetary credibility and stabilized inflation by pegging. However, in the country-level data, there is little consistency in the evidence that IT or CBI is associated with improved inflation performance.
To pursue the matter further, we use a research design—illustrated in Figure 1—that provides a more direct test of the relationship between monetary anchors and inflation. Unlike existing work that regresses cross-country inflation on monetary anchors, we evaluate the effect of anchoring institutions at the micro level, using firm owners' perceptions of inflation as our dependent variable. According to the theory of inflation, monetary institutions do not directly affect inflation and inflation variability; rather, institutions influence individual perceptions (and behaviors) which, in aggregate, influence inflation outcomes. Private-actor agency lies between institutions and aggregate outcomes. Our design uncovers this relationship by estimating the impact of monetary anchors on individual inflation perceptions.
Causal pathway in the rational-expectations theory of inflation
Notes: Our approach (inside the oval) directly estimates the impact of institutions on inflation expectations. By contrast, cross-counry inflation regresssions (dashed line) skip over the micro-level steps.

Private-Sector Inflation Perceptions
In this section, we operationalize inflation perceptions and analyze the validity of our measures. Our data come from the WBES, an eighty-one-country firm-level survey conducted in 1999 by the World Bank.Footnote 21 At least 100 firms were interviewed in each country, with an overall total of 10,090 firms in the sample. The survey has a number of questions on the business environment in which firms operate, including assessments of inflation. The data set also includes information on firm ownership (foreign, government), firm size, sales performance, sector of operation (manufacturing, services, agriculture), and export orientation, which we tap as control variables.
According to theory, the inflation expectations of price and wage setters are a crucial factor in the inflation process. But data on the price expectations of business firms—the price setters in the first instance—as well as information on nominal wage expectations is scarce. The most widely used surveys ask household consumers, as opposed to firms or labor representatives, about their inflation expectations.Footnote 22 The University of Michigan's “Survey of Consumer Attitudes and Behavior” has tracked the inflation expectations of U.S. households for more then fifty years by asking consumers to predict the change in prices over the next year. Since consumers do not set prices or wages, these surveys do not measure the forecasts of the individuals that matter in models of inflation. The Livingston “Survey of Professional Forecasters,” conducted quarterly by the Federal Reserve Bank of Philadelphia, comes closer to measuring the expectations of price-setting firms, since respondents come largely from the business world. But, like the Michigan consumer survey, data are limited to the United States.
In work similar to our own, Crowe, and Levin, Natalucci, and Piger employ cross-country inflation forecasts from Consensus Forecasts—a firm that pools and averages the forecasts of professional economists from around the world—to examine the effectiveness of inflation targeting.Footnote 23 An advantage of the WBES over Consensus Forecasts is that it is a survey of firm owners and managers, so that people with the capacity to set prices form the pool of respondents. An obvious shortcoming is that the WBES does not explicitly ask business owners to provide a forecast of inflation. However, we show that the following WBES query on inflation makes a reasonably good proxy for the theoretical construct of “inflation expectations.” We label our indicator inflation concern, and construct it from firm owners' response to the following WBES query: “Please judge on a four point scale how problematic inflation is for the operation and growth of your business.” Answers vary between 1 (no obstacle), 2 (minor obstacle), 3 (moderate obstacle), and 4 (major obstacle).
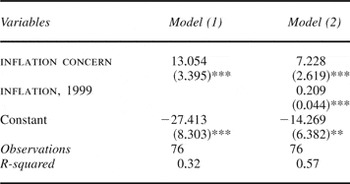
Clearly, respondents are not asked to provide an explicit inflation forecast. However, they are asked to give an assessment of the impact that inflation has on the performance of their firms, which may include perceptions of future inflation. In Table 1, we assess whether our variable, inflation concern, approximates the concept of “inflation expectations” by testing to see how accurately it predicts actual future inflation.Footnote 24 Not only do we examine whether our survey measures contain a forward-looking component, but we also assess whether they contain additional information about subsequently realized inflation beyond what is already contained in the past history of actual inflation rates. Model 1 is an ordinary least squares (OLS) regression of one-year ahead (that is, 2001) realized consumer price index (CPI) inflation rates on country averages of inflation concern (from late 1999 and early 2000). The estimate is positive and highly significant and accounts for about a third of the variance in realized future inflation. As inflation tends to be persistent, Model 2 controls for the rate of inflation at about the time of the survey (1999). The positive and significant estimate for inflation concerns in Model 2 indicates that there is forecasting information in these survey responses above and beyond actual inflation in 1999. On this evidence, we feel the WBES indicator of businesses' inflation concerns of is a reasonable proxy for “inflation expectations.”
inflation concern as a proxy for “inflation expectations”

Notes: The dependant variable is CPI inflation in 2001, the year after the WBES survey was completed. inflation, 1999 = CPI inflation in 1999, the year the survey began. inflation concern = the country average of firm owner responses to the WBES inquiry about inflation.
* significant at 10%;
** significant at 5%;
*** significant at 1%.
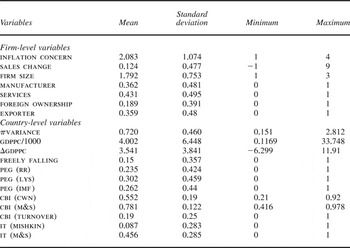
In Table 1, inflation concerns has a mean of 2.8 and a standard deviation of 1.07. Overall, 34 percent of all firms in the sample report that inflation is a major obstacle to the operation and growth of their businesses. Another 26 percent see inflation as a moderate obstacle, while 23 percent of firms view inflation as minor obstacle, and 16 percent view inflation as no obstacle at all.
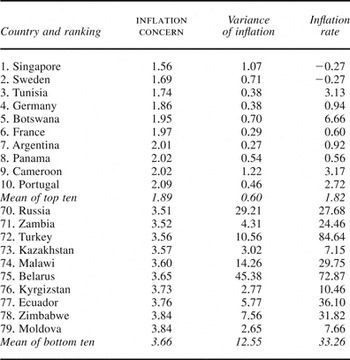
Table 2 assesses the face validity of inflation concerns by showing that the measured concern with inflation not only varies across firms within a country but that it also varies across countries in intuitive ways. The table lists the country average of inflation concerns for the top and bottom ten countries in the sample, along with information on inflation and the volatility of inflation in these countries. With few exceptions, the lists are intuitively appealing: in the ten countries where firms reported the least concern with inflation, inflation volatility (as measured by the standard deviation of month-to-month inflation over calendar year 1998), averaged just 0.60. The inflation rate (measured as the annual percentage change in CPI for 1998) in these countries was also very low, averaging just 1.8 percent. By contrast, in the ten countries where firms reported the most concern with inflation, inflation volatility was very high, with a standard deviation of 12.55, and actual inflation averaged 33.3 percent.
Face validity of inflation concern

Notes: inflation concern = the country average of firm-owner responses to the WBES inquiry about inflation. Variance of Inflation = the standard deviation over calendar year 1998 of month-on-month inflation rates, based on the consumer price index (CPI) basket. Inflation rate = the annual percentage change in CPI for 1998.
Monetary Anchors and Inflation Perceptions
Monetary institutions such as pegs, CBI, and IT have been suggested to stabilize inflation expectations. Our goal is to examine whether these institutions actually do help anchor private-sector inflation concerns. In this section, we describe our measures of monetary institutions and provide some preliminary comparisons of firm-owner inflation perceptions across these regimes.
To assess how firms' inflation concerns are conditioned by the country's exchange-rate regime, we need to classify countries by exchange-rate regime. We employ two classifications of de facto exchange-rate regimes: Levy-Yeyati and Sturzenegger, and Reinhart and Rogoff.Footnote 25 Although the methods differ, both classifications attempt to capture the actual behavior of the exchange rate. Levy-Yeyati and Sturzenegger categorize regimes according to observed changes in the nominal exchange rate, the volatility of these changes, and the volatility of international reserves. Reinhart and Rogoff exploit the conditional probability of the exchange rate staying within a given range over a rolling five-year window, and they use information about parallel (dual market) exchange rates in determining whether a regime continues from one year to the next. We collapse Reinhart and Rogoff's classification into a dichotomous variable (0 = not peg, 1 = peg), take values for 1999, and label this variable peg (rr).Footnote 26 We do the same with the Levy-Yeyati and Sturzenegger classification and label it peg (lys). We also include a de jure measure of exchange-rate regime on the grounds that an announced regime that differs from a de facto regime may be less credible to private-sector actors. The variable peg (imf) is the regime the government reports to the IMF. We take values from 1999 and construct a 2-way indicator (0 = not peg, 1 = peg).
To test the effects of CBI on inflation expectations, we use three alternative measures. For de jure CBI, as written into countries' laws and legal systems, we use the Polillo and Guillén update of the Cukierman, Webb, and Neyapti index.Footnote 27 Our variable, cbi (cwn), is the 1999 value of the Polillo and Guillén index for countries in our sample. Our second de jure measure is from Mahadeva and Sterne.Footnote 28 Unlike the cbi (cwn) index, which academic experts coded on the basis of a reading of central banking statutes, Mahadeva and Sterne's index is constructed from a 1998 survey administered directly to central bankers. The survey was designed along the lines of Cukierman's de jure approach and was administered through the Bank of England.Footnote 29 The composite index is a weighted average of central banker responses to questions about (1) their statutory obligation to focus on price stability, (2) target independence, (3) their instrument independence, (4) the finance of government deficits, (5) and the term of office of the governor. We label the index cbi (m&s) and obtain values for fifty-one of eighty-one countries in our sample. We are aware that this measure is open to the criticism that the responses of central bankers may be particularly biased.
Our third measure of CBI, the central bank turnover rate, is a rather poor de facto indicator based on work by Cukierman.Footnote 30 This indicator relies on the assumption that governors who resist political pressure will be replaced; high turnover is interpreted as indicating political interference in the conduct of monetary policy. Of course, low turnover need not indicate independence since a governor that is pliant to political pressure would not need to be replaced. Our variable, cbi (turnover), is the turnover rate of central bank governors for the five years between 1995 and 1999, taken from Ghosh, Gulde, and Wolf.Footnote 31
Inflation targeting is another regime that can help constrain inflation expectations. Mishkin's definition has five elements: (1) an announced, numerical, medium-term inflation target, (2) price stability as a primary goal of monetary policy, (3) an information-inclusive strategy in which many variables are used for deciding the setting of policy instruments, (4) high transparency of the monetary policy strategy through communication with the private sector about the plans, objectives, and decisions of the monetary authorities, and (5) accountability of the central bank for attaining its inflation objectives.Footnote 32
We draw on two sources for data on IT regimes. The first is the Mishkin and Schmidt-Hebbel classification of countries that met the above criteria prior to the WBES survey.Footnote 33 We use a binary indicator for the variable, it (mishkin): 1, if an inflation target regime was in place prior to 1999; 0 otherwise. In our sample, Canada, Chile, the Czech Republic, Mexico, Poland, Sweden, and the United Kingdom had IT regimes prior to 1999 (we exclude Spain because it adopted the Euro in January 1999).
Our second IT indicator comes from Mahadeva and Sterne who constructed an index from the responses of central bankers to a 1998 survey.Footnote 34 This index measures the degree to which a country's central bank focused on IT and is constructed as the equally weighted average of numerical responses to four questions: (1) Is your regime described as inflation targeting? (2) Do you publish a specific target/monitoring range now? (3) In practice, how highly do you rank this objective? (4) Does inflation prevail when there are policy conflicts? The variable, it (m&s), ranges from 0 for a country that does not focus on targeting inflation at all, to 1, for a central bank whose focus is entirely on IT.
We thus have multiple indicators of each monetary institution, as well as a mix of de jure and de facto indicators. Summary statistics are in Table 3. Having described our data, we provide preliminary comparisons of firms' concerns about inflation across these monetary commitment regimes. Figure 2 illustrates how the exchange-rate regime relates to firms' inflation concerns, using our three different regime indicators. Firm responses range from 1, indicating that inflation is “no obstacle,” to 4, which means inflation is perceived as a “major obstacle.” Regardless of the measure we use—rr, lys, or imf—these distributions reveal that firms operating in pegged regimes are consistently less concerned about inflation than firms in floats or intermediate regimes.
Summary statistics

Firms' concern with inflation by exchange-rate regime

Figure 3 explores the link between inflation concerns and CBI and IT. We grouped firm responses by domestic anchoring arrangement, with the bars on the left indicating “high CBI” (above the mean) or the presence of IT, and the bars on the right indicating “low CBI” (below the mean) or the absence of IT. These distributions do not convey a clear relationship between these domestic anchors and inflation concerns. While Mahadeva and Sterne's measure of CBI and the “turnover” indicator both suggest that CBI reduces inflation concerns (recall that higher turnover of central bankers suggests less independence), the Cukierman, Webb, and Neyapti distributions suggest that firms in high-CBI countries are more concerned about inflation than firms in low-CBI settings. The IT indicators also yield conflicting results. When IT is proxied by the Mishkin indicator, there is prima facie support for the claim that inflation targets reduce price concerns. But when Mahadeva and Sterne's measure is used, firms perversely report more concern with inflation under IT.
Firms' concern with inflation by CBI and IT

This preliminary evidence suggests that pegging relates negatively to private-sector inflation perceptions but that CBI and IT do not have a consistent effect. To further assess the evidence and control for other factors that might contribute to these differences, we move to regression analysis.
Model and Results
Survey responses may reflect other firm- or country-level characteristics besides monetary institutions. For firm-level controls, we use the responses to five other WBES questions: sales change, firm size, sector of operation, foreign ownership, and export orientation. Firms that experience sales increases may be more successful and therefore less likely to view inflation as a problem. Our variable, sales change, is the percent change in firm sales over the previous three years. Larger firms may be more established and therefore less likely to find inflation a problem. Our measure, firm size, is an ordered response where 1 = small (5 to 50 employees), 2 = medium (51 to 500 employees), and 3 = large (more than 500 employees). Since a currency peg has a direct effect on the prices of traded goods, firms in this sector may perceive price stability even when unaware of the anchoring institution. To ensure that we are testing the inference that pegging stabilizes inflation expectations directly rather than through its effect on the price of traded goods, we include controls for firms operating in the traded goods sector. We use binary (0, 1) measures for manufacturer and for exporter, where 1 indicates that a firm manufactures products or exports some portion of its output.Footnote 35 Similarly, foreign-owned firms might be more diversified internationally and therefore less subject to price shocks in the home market. But foreign ownership may also be more likely under a currency peg. To control for this, we include a binary variable, foreign-owned, which indicates that some share of a firm is owned by foreign nationals.
We include several country-level variables in our models to control for national factors that may correlate with monetary institutions. Firms in less developed countries may have more concern with inflation, so we control for per capita gross domestic product (GDP) in 1999 (gdppc). Firms in countries with lower rates of economic growth may be more concerned with inflation so we control for growth performance with the change in GDP per capita between 1998 and 1999 (Δgdppc). We control for the variability of inflation because unstable prices might affect the types of monetary institutions a nation adopts, as well as individuals' perceptions of inflation. For instance, price volatility could positively influence worries about inflation while at the same time increasing the likelihood that a government fixes the exchange rate, grants greater autonomy to the central bank, or adopts IT. Leaving inflation out of the model would thus bias the effects of monetary institutions on private-sector inflation expectations. Our measure, “πvariance,” is the log of 1 + the standard deviation of inflation (monthly change in the consumer price index) from 1996 to 1998, the three-year period before the survey was administered.Footnote 36
Lastly, we control for survivor bias, which would arise if we excluded failed fixed exchange-rate regimes because they no longer existed at the time of the survey.Footnote 37 Since our goal is to assess the relationship between pegging and firm-owner inflation concerns, our results would be biased upward if we examined only successful currency pegs that survived through the period of observation. We control for survivor bias with the variable freely falling from Reinhart and Rogoff.Footnote 38freely falling is a dichotomous variable that takes the value of 1 if a country experienced either a currency crisis followed by a transition to a floating regime, or an inflation rate above 40 percent per annum.
We run ordered probit models with robust standard errors clustered by country to estimate the following equation:

where the subscripts stand for firm i in country j. The dependent variable is inflation expectations, the response of firm i in country j. We use ordered responses from the WBES as the dependent variable, inflation concern. Our variable of interest is anchor, which represents one of three monetary institutions designed to commit policy credibly to low inflation: peg, cbi, and it. The vectors firm and economy are the firm- and country-level controls described above.
Table 4 presents results of regressing our indicator of firms' inflation expectations, inflation concern, on the type of exchange-rate regime and a set of control variables. Model 1 estimates the effects controlling for firm-level characteristics. Model 2 adds country-level controls. Intuitively, higher inflation volatility increases the likelihood that a firm will perceive inflation to be a problem while the level of economic development and recent economic growth both significantly reduce businesses' concern about inflation. The estimate for freely falling—our control for survivor bias—is positive and highly significant, indicating that firm owners were more concerned with inflation in countries that recently suffered the collapse of a peg.Footnote 39
inflation concern and pegged exchange rates

Notes: Ordered probit regressions where the dependent variable, inflation concern, is the firm-owner response to the WBES inquiry about inflation. The shaded region indicates alternate measures of peg, our variable of interest. Robust standard errors, clustered by country, in parentheses.
* significant at 10%;
** significant at 5%;
*** significant at 1%.
Models 3 to 5 introduce our three measures of exchange-rate regime: rr, lys, and imf. Each is coded 1 = peg, 0 = not peg, so negative estimates indicate that pegging reduces concerns about inflation. The estimates for each indictor are negative and statistically significant: firms operating in fixed exchange-rate environments report fewer problems with inflation than do firms operating under floats and intermediate regimes.
Model 6 controls for CBI and IT to show that the effect of pegging is robust to the inclusion of these domestic anchors. Indeed, pegs have a significant effect even where the other two mechanisms do not. We ran this model with alternative measure of de jure and de facto IT and CBI and, in every case (not reported), the results are similar to those reported in Model 6: pegging remains negative and significant.
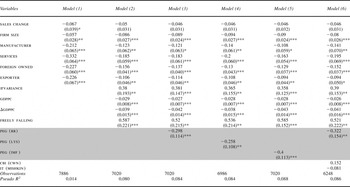
Table 5 explores the relationship between firms' inflation concerns and domestic anchors in more depth. In Models 1 to 3, we introduce our three indicators of CBI to the baseline model of firm- and country-level controls. Although cbi (cwn) and cbi (m&s) are negative, as expected, the estimates are not significant. cbi (turnover) has the wrong sign (since higher turnover of central bank officials is taken to suggest political manipulation), but the estimate is not significant. Models 4 and 5 introduce the proxies for IT regimes: it (mishkin) and it (m&s). Both indicators have the wrong sign—IT is associated with greater concerns with inflation—and the it (m&s) estimate is significant in this direction.
inflation concern and CBI and IT

Notes: Ordered probit regressions where the dependent variable, inflation concern, is the firm-owner response to the WBES inquiry about inflation. Robust standard errors, clustered by country, in parentheses. The shaded region contains our variables of interest: alternate measures of cbi and IT, and their interactions with polity.
* significant at 10%;
** significant at 5%;
*** significant at 1%.
The perverse effect of IT on firms' inflation concerns is surprising. To pursue the matter further, we ran Models 4 and 5 with a control for central bank “transparency.” If IT requires transparency to compensate for its relatively high level of discretion, our thought was that we should control for transparency to obtain more predictable results on the IT variables.Footnote 40 Inclusion of this control (not reported) does not change our results. We also interacted IT with transparency but obtained insignificant results on the interaction. It may be that inflation targeting is an endogenous variable, such that countries that had greater long-run problems with inflation in the past were more likely to have selected IT as a focus for central bank policy. As a crude test for endogeneity, we substituted a longer five-year (1994–98) lag of πvariance for our three-year measure but our results are unchanged.
Some scholars argue that relatively opaque anchors such as CBI and IT require a certain level of domestic political development to operate effectively, which suggests an interactive effect between political institutions and these domestic anchors. Broz and Keefer, and Stasavage test arguments about the institutional preconditions for controlling inflation with CBI.Footnote 41 In Models 6 and 7, we explore such interactions. Model 6 uses the Polity IV measure of democratic institutional development as a constitutive term in an interaction with cbi (cwn). The estimated effect of the interaction is zero and insignificant. Model 7 runs an interaction of polity and it (mishkin) and here, for the first time, we obtain a negative (and nearly significant) estimate for IT. We experimented with other interactions using various measures of political institutions—executive constraints, checks and balances, civil liberties, as well as alternative indicators of IT and CBI—but failed to obtain consistent results.
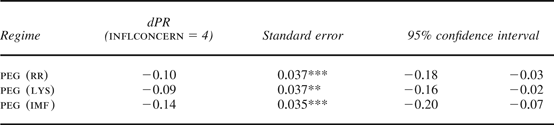
To this point, we have not discussed the substantive meaning of our estimates. In Table 6, we simulated the change in the predicted probability of observing a “4 = major problem” response as we move peg from a float/intermediate regime to a fixed regime (from 0 to 1), holding other variables in Table 5, Models 3 to 5, at their means. The effects of pegging are substantively important. The probability that a firm will report inflation to be a “major obstacle” decreases by 10 percentage points as the currency regime moves from an rr float to an rr peg. A move from an lys float to an lys peg reduces the likelihood of this response by 9 percentage points, and firm owners are 14 percentage points less likely to report that inflation is a major obstacle under a de jure (IMF) peg.
Substantive impact of pegging the exchange rate on inflation concern
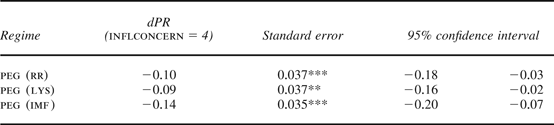
Notes: The table reports the change in the predicted probability of observing a “4 = major problem” response as peg is moved from float to fixed (from 0 to 1), holding other variables (in Models 3 to 5 from Table 5) at their means. The simulation was run with Clarify from Tomz, Wittenberg, and King Reference Tomz, Wittenberg and King1998.
Conclusion
We have examined micro-level evidence to see if monetary institutions influence the perceptions of price-setting business owners in the manner stipulated in theory. We found that exchange-rate pegging is negatively related to business owners' concerns about inflation while CBI and IT are not.
Our micro-level findings parallel the results of country-level studies, where the association between pegging and inflation is generally consistent and robust: currency pegs are associated with lower and more stable inflation. By contrast, debate persists over whether CBI and IT improve inflation performance. In principle, all three monetary anchors should yield improvements in private-sector credibility. But pegging has three characteristics that give it a “credibility” advantage over IT and CBI. First, pegs are transparent. Choosing the exchange rate as the nominal anchor has the advantage of being a more easily observable commitment than either CBI or IT.Footnote 42 When a government adopts policies that are inconsistent with its promised exchange-rate target, the effects will be almost instantaneously reflected in the foreign exchange markets. By contrast, CBI and IT lack the inherent transparency of pegs and must be made more transparent by legislation or proclamation. Even then, it is difficult for the private sector to evaluate the filtered and potentially biased information provided by the central bank. While information on the credibility of a peg is continuously available in the foreign exchange markets, no analogous market exists to continuously evaluate the credibility of the commitment to CBI or IT. Instead, the best information available is produced by academic specialists who construct relatively crude, subjective indicators on an infrequent basis. The problem of observing the true nature of these institutions is so crucial that it informs nearly all academic analyses. It is also the reason why we have better measures of currency regimes than CBI and IT in our data.
A second advantage of a currency peg is that it is an act of international, as opposed to domestic, delegation. By ceding monetary authority to a reputable foreign central bank over which it has no influence, the pegging country makes a costly commitment that may resolve the “McCallum Fallacy.” In an important paper, McCallum observes that it is a fallacy to think that domestic delegation schemes such as CBI and IT can resolve the time-inconsistency problem.Footnote 43 These arrangements merely “relocate” the source of the problem domestically to the legislation establishing the institution. The government must therefore enforce the enabling legislation before the institution will be taken seriously by the private sector. The fallacy arises because the government that needs to delegate to improve its credibility in the first place will have no incentive to enforce the arrangement once it is in place (for example, fire the central banker that gives in to pressures to inflate the economy or reduce the pay of a central banker that misses an inflation target). In fact, if a domestic delegation regime is effective in changing private-sector expectations, then that would be the ideal time to revoke the regime, according to the logic of the Barro-Gordon game, since policymakers can do better if they are perceived as committed to price stability.
A third factor that bolsters the credibility of pegging is that it is more costly to employ than domestic anchors. Not only does pegging require governments to sacrifice domestic monetary policy as a tool of macroeconomic management, it can also leave countries exposed to speculative currency attacks. In the spirit of signaling models, the costliness of adopting a peg could be what makes pegging so credible. The knowledge that costly trade-offs exist lends credibility to the commitment since it would not be optimal to incur the costs of pegging unless the commitment to price stability is unusually strong.Footnote 44 Furthermore, the private sector may understand that a government that is not fully committed to a peg faces a strong possibility of dismissal. Pegs that are not fully supported by monetary and fiscal discipline tend to end badly, in devaluations, for which politicians are held accountable. Devaluations are highly visible events that have been found to severely damage governments' approval ratings, increase the likelihood that the finance minister will lose his job, and raise the odds the government will fall.Footnote 45 Pegging thus brings a costly personal punishment to the policymaker or political party that breaks the commitment to price stability.
Yet domestic anchors are advocated by policymakers and the international financial institutions as alternatives to pegging on the very grounds that they can reduce these costs, with little loss of credibility. The greater flexibility of IT and CBI means that monetary policy can be used for domestic stabilization purposes. In addition, the threat of a costly devaluation becomes moot since currency crises are not possible under floats. Unfortunately, there appears to be a trade-off: our results suggest that greater flexibility and the absence of a devaluation threat come at the expense of credibility.
Our findings have both analytical and practical implications. In the spirit of academic work that examines the trade-offs between external and domestic monetary institutions,Footnote 46 we provide the first micro-level evidence on the relative effectiveness of the alternatives. For policy advocates of domestic anchoring schemes, our results suggest a reason why many countries still prefer foreign currency pegs despite the serious trade-offs: they work.