1. Introduction
A fundamental feature of real-valued Lévy processes is the independence of the pre-supremum process and of the post-supremum increments of the process, before an independent exponential random time, together with the associated spatio-temporal Wiener–Hopf factorization at the maximum. Through the Lamperti transform for positive self-similar Markov processes (pssMp), this splitting at the maximum of the underlying Lévy process carries over, in particular, to a conditional, given the value of the overall maximum and the multiplicative jump at the maximum, independence of the time at which the ultimate supremum of the associated pssMp is reached and the time from then until its absorption at zero. Moreover, in the spectrally negative case, roughly speaking, the ‘temporal conditional Wiener–Hopf factors’ corresponding to this independence statement can be made explicit. We now proceed to look at this in precise detail.
Notation 1.1. Throughout we will write  $\mathbb{Q}[W]$ for
 $\mathbb{E}_\mathbb{Q}[W]$,
 $\mathbb{Q}[W;\, A]$ for
 $\mathbb{E}_\mathbb{Q}[W\mathds{1}_A]$ and
 $\mathbb{Q}[W\mid \mathcal{H}]$ for
 $\mathbb{E}_\mathbb{Q}[W\mid \mathcal{H}]$. More generally the integral
 $\int f \,\text{d} \mu$ will be written
 $\mu[f]$, etc. For
 $\sigma$-fields
 $\mathcal A$ and
 $\mathcal B$,
 $\mathcal A/\mathcal B$ will denote the set of
 $\mathcal A/\mathcal B$-measurable maps;
 $\mathcal{B}_A$ is the Borel (under the standard topology)
 $\sigma$-field on A.
Let  $X=(X_t)_{t\in [0,\infty)}$ be a spectrally negative Lévy process (snLp) under the probabilities
 $(\mathbb{P}_x)_{x\in \mathbb{R}}$. This means that X is a càdlàg, real-valued process, with stationary independent increments (under
 $\mathbb{P}_x$ for all
 $x\in \mathbb{R}$, of course), with no positive jumps and non-monotone paths, which, under
 $\mathbb{P}_0$, a.s. vanishes at zero; furthermore, for each
 $x \in \mathbb{R}$, the law of X under
 $\mathbb{P}_x$ is that of
 $x+X$ under
 $\mathbb{P}_0$. We refer to [Reference Bertoin3], [Reference Kyprianou14], [Reference Sato21], and [Reference Doney8] for the general background on (the fluctuation theory of) Lévy processes and to [Reference Bertoin3, Chapter VII], [Reference Kyprianou14, Chapter 8], [Reference Doney8, Chapter 9], and [Reference Sato21, Section 9.46] for snLp in particular. Further, let
 $\textsf{e}$ be an exponentially distributed random time with rate
 $p\in [0,\infty)$ (
 $\textsf{e}=\infty$ a.s. when
 $p=0$) independent of X. We set
 $\mathbb{P}\coloneqq \mathbb{P}_0$, assume each
 $\mathbb{P}_x$,
 $x\in\mathbb{R}$, is complete, and we let
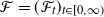 $\mathcal F=(\mathcal F_t)_{t\in [0,\infty)}$ denote the usual augmentation (in the sense of the theory of Markov processes [Reference Getoor and Blumenthal9, Section I.5]) of the smallest filtration with respect to which X is adapted and
 $\textsf{e}$ is a stopping time. When ‘a.s.’ appears below with no further qualification, it will mean ‘a.s.-
 $\mathbb{P}_x$ for all
 $x\in \mathbb{R}$’. Also, fix an
 $\alpha\in (0,\infty)$.
Associated to X,  $\textsf{e}$, and
 $\alpha$, via the Lamperti transformation [Reference Lamperti15] (see also [Reference Kyprianou14, Theorem 13.1]), is a positive
 $\alpha^{-1}$-self-similar Markov process
 $Y=(Y_s)_{s\in [0,\infty)}$, where we understand ‘positive’ to mean that Y is non-negative with 0 an absorbing state. We make this formal.
Let  $\mathbb D$ be the space of real-valued càdlàg paths on
 $[0,\infty)$, endowed with the sigma-field
 $\mathcal D$ and canonical filtration
 $(\mathcal D_t)_{t\in [0,\infty)}$ of evaluation maps, shifts
 $(\theta_t)_{t\in [0,\infty)}$, coordinate process
 $\xi=(\xi_t)_{t\in[0,\infty)}$. For
 $\omega\in \mathbb{D}$, set
 \begin{align*}\text{I}_t(\omega) & \coloneqq \int_0^{t }\,\text{e}^{\alpha \xi_u(\omega)} \,\text{d} u,\quad t\in [0,\infty]{,}\\[2pt] \varphi_s(\omega) & \coloneqq \inf\{t\in [0,\infty)\colon \text{I}_t(\omega)>s\},\quad s\in [0,\infty){,} \end{align*}
and, for a further  $l\in [0,\infty]$,
 \[\mathcal{L}^l(\omega)=(\mathcal{L}^l(\omega)_s)_{s\in [0,\infty)},\quad \mathcal{L}^{l}(\omega)_s\coloneqq \begin{cases}\text{e}^{ \xi_{\varphi_s(\omega)}(\omega)} & \text{for }s\in [0,\text{I}_l(\omega)){,}\\[2pt] 0 & \text{for }s\in [\text{I}_l(\omega),\infty)\end{cases}\]
(of course, for  $v\in [0,\infty)$,
 $\xi_v(\omega)$ is just
 $\omega(v)$ above). Then
 $Y=\mathcal{L}^{\textsf{e}}(X)$.
We will write  $I_t\coloneqq \text{I}_t(X)$,
 $t\in [0,\infty]$, and
 $\phi_s\coloneqq \varphi_s(X)$,
 $s\in [0,\infty)$, for short. Also, define the filtration
 $\mathcal G=(\mathcal G_s)_{s\in [0,\infty)}$ by
 $\mathcal G_s\coloneqq \mathcal F_{\phi_s}$ for
 $s\in [0,\infty)$,
 $T_0\coloneqq \inf\{t\in (0,\infty)\colon Y_t=0\}=I_\textsf{e}=\int_0^\textsf{e} \,\text{e}^{\alpha X_u} \,\text{d} u$, and for convenience set
 $\mathbb{Q}_y\coloneqq \mathbb{P}_{\log y}$ for
 $y\in (0,\infty)$ (naturally
 $\mathbb{Q}\coloneqq \mathbb{Q}_1$). Note that
 $\mathcal G$, just like
 $\mathcal F$, is right-continuous [Reference Kallenberg12, Lemma 6.3].
The assumptions on X and  $\textsf{e}$ entail that for any
 $\mathcal F$-stopping time S, on
 $\{S<\textsf{e}\}$,
 $\mathcal F_S$ is independent of
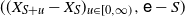 $((X_{S+u}-X_S)_{u\in [0,\infty)},\textsf{e}-S)$, which has (assuming the probability of
 $\{S<\textsf{e}\}$ is strictly positive) the distribution of
 $(X,\textsf{e})$ under
 $\mathbb{P}$. In consequence Y is Markov with lifetime
 $T_0$, cemetery state 0, in the filtration
 $\mathcal G$, under the probabilities
 $(\mathbb{Q}_y)_{y\in (0,\infty)}$; clearly it is
 $\mathcal G$-adapted and
 $T_0$ is a
 $\mathcal G$-stopping time. Moreover, for any
 $h\in \mathcal{B}_\mathbb{R}/\mathcal{B}_{[0,\infty]}$,
 $y\in (0,\infty)$,
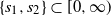 $\{s_1,s_2\}\subset [0,\infty)$, we have a.s.-
 $\mathbb{Q}_y$
 \[ \mathbb{Q}_y[h(Y_{s_1+s_2})\mathds{1}_{\{s_1+s_2<T_0\}}\mid \mathcal G_{s_1}]=\mathbb{Q}_{Y_{s_1}}[h(Y_{s_2});\, s_2<T_0]\mathds{1}_{\{s_1<T_0\}}{,} \]
and then, for any  $s\in [0,\infty)$ and
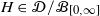 $H\in \mathcal D/\mathcal{B}_{[0,\infty]}$,
 \[ \mathbb{Q}_y[H(\theta_s(Y))\mid \mathcal G_s]=\mathbb{Q}_{Y_s}[H(Y)]\quad\text{a.s.-$\mathbb{Q}_y$ on $\{s<T_0\}$}. \]
Further, Y respects the  $1/\alpha$-self similarity property: for each
 $c\in (0,\infty)$ and
 $y\in (0,\infty)$, the law of
 $(cY_{sc^{-\alpha}})_{s\in [0,\infty)}$ under
 $\mathbb{Q}_y$ is that of Y under
 $\mathbb{Q}_{cy}$.
Conversely [Reference Kyprianou14, Theorem 13.1], any sufficiently regular positive  $1/ \alpha$-self-similar Markov process with no positive jumps and non-monotone paths is
 $\mathcal{L}^R(Z)$ for some snLp Z and exponential random time R independent of Z, possibly only once we have enlarged the probability space by an independent factor.
We refer to [Reference Kyprianou14, Chapter 13] for a further account of the properties of pssMp, to [Reference Chaumont, Kyprianou, Pardo and Rivero7] for their general fluctuation theory, and to [Reference Kyprianou14, Chapter 13.7] for those/that of the spectrally negative type in particular.
Next, let  $\overline{Y}=(\overline{Y}_s)_{s\in [0,\infty]}$ (resp.
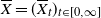 $\overline{X}=(\overline{X}_t)_{t\in [0,\infty]}$) denote the running supremum process of Y (resp. X), and define
 \[L\coloneqq \sup\{s\in [0,\infty)\colon \overline{Y}_s=Y_s\}\quad \text{and}\quad G\coloneqq \sup\{t\in [0,\textsf{e})\colon \overline{X}_t=X_t\}.\]
Throughout we make the following assumption (but see Remark 1.1 for extensions when this assumption is dropped).
Assumption 1.1. When  $p=0$, then X drifts to
 $-\infty$.
This assumption is equivalent to the following being a.s. finite quantities:
•
 $\overline{Y}_\infty=\overline{Y}_L=\text{e}^{\overline{X}_G}=\text{e}^{\overline{X}_\textsf{e}}$, the overall supremum of Y,
•
$L=I_G=\int_0^G\,\text{e}^{\alpha X_u} \,\text{d} u$, the last time Y is at its running supremum, and•
$T_0$, the absorption time of Y.
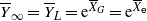


Indeed the following trichotomy is well known: a.s. Y never reaches zero and its overall supremum is infinite, hits zero continuously, or hits zero by a jump, respectively, as X does not drift to  $-\infty$ and
 $p=0$, X drifts to
 $-\infty$ and
 $p=0$, or
 $p>0$.
By the independence statement of the Wiener–Hopf factorization for X (see Section 2.2 below) we have the following.
(I) The pair
$(L,\overline{Y}_\infty)$ is independent of
which is the size of the multiplicative jump at L for Y on
\[J\coloneqq \dfrac{Y_L}{\overline{Y}_\infty}\mathds{1}_{\{L<T_0\}}+\mathds{1}_{\{L=T_0\}}\overset{\text{a.s.}}{=}\text{e}^{X_G-\overline{X}_\textsf{e}},\]
$\{L<T_0\}$ and 1 otherwise (note that J is only not a.s. equal to 1, when 0 is irregular for $({-}\infty,0)$ for the process X, which is equivalent to X being of finite variation).
-
(II) Conditionally on
$\overline{Y}_\infty$ and J (or just $\overline{Y}_\infty$), L is independent of
which is the time that elapses from Y reaching its overall supremum and until absorption at zero.
\[T_0-L=\int_G^\textsf{e} \,\text{e}^{\alpha X_u} \,\text{d} u=\text{e}^{\alpha \overline{X}_G}\,\text{e}^{\alpha(X_G-\overline{X}_G)}\int_G^\textsf{e} \,\text{e}^{\alpha (X_u-X_G)} \,\text{d} u,\]


As indicated briefly at the start, this may be interpreted as a kind of conditional Wiener–Hopf factorization at the maximum of  $T_0$, and in this paper we explicitly provide the associated ‘conditional Wiener–Hopf factors’. That is to say, we compute, in tractable detail, for
 $y\in (0,\infty)$,
 $\beta\in [0,\infty)$, the conditional Laplace transforms (i)
 $\mathbb{Q}_y[\text{e}^{-\beta L}\mid \overline{Y}_\infty]$ (Proposition 4.1) and (ii)
 $\mathbb{Q}_y [\text{e}^{-\beta (T_0-L)}\mid \overline{Y}_\infty,J]$ (Proposition 4.3). Specifically, these Laplace transforms are given as algebraic expressions involving certain power series, whose coefficients are expressed directly in terms of the Laplace exponent of X. In addition, (iii) the law of J can be identified (Proposition 4.2). This then yields an explicit conditional, given
 $\overline{Y}_\infty$ and J, factorization of
 $T_0$ at the maximum (see Theorem 4.1, our main result), and, because the law of
 $\overline{Y}_\infty$ is also known (see Section 2.1 below), it characterizes the joint quadruple law of
 $(L,\overline{Y}_\infty,J,T_0-L)$.
Question 1.1. Can a suitable tractable conditional factorization/joint law be obtained if one adds into the mix  $Y_{T_0-}/(J\overline{Y}_\infty)$, the multiplicative jump at absorption relative to the position at the maximum? This is left open.
Remark 1.1. It is worth noticing that, on account of the correspondences between the quantities pertaining to X and Y in the Lamperti transform,
 \[ T_0=I_\textsf{e}\overset{\text{a.s.}}{=}\inf \biggl\{s\in [0,\infty)\colon \int_0^s Y_v^{-\alpha} \,\text{d} v\geq \textsf{e}\biggr\}\]
(where  $0^{-\alpha}\coloneqq \infty$). Further, let
 $\lambda\in (0,\infty)$ and let
 $e_\lambda$ be an exponentially distributed random time of rate
 $\lambda$, independent of the pair
 $(X,\textsf{e})$. Drop Assumption 1.1 for a moment and consider, ceteris paribus, splitting at the maximum for Y before the time
 $I_{e_\lambda}$, which is to say at the maximum before the time
 \[I_{e_\lambda}\land I_\textsf{e}=I_{e_\lambda\land \textsf{e}}\overset{\text{a.s.}}{=}\inf\biggl\{s\in [0,\infty)\colon \int_0^s Y_v^{-\alpha} \,\text{d} v\geq e_\lambda\land \textsf{e}\biggr\}{,} \]
instead of splitting at the overall maximum. Then we see that this splitting at the maximum before the time  $I_{e_\lambda}$ in fact reduces immediately to our base case of splitting at the overall maximum subject to Assumption 1.1 – at least as far as the distributions of all of the quantities ‘in sight’ are concerned. Indeed,
 $\textsf{e}\land e_\lambda$ being an exponential random time of rate
 $p+\lambda$, one need only replace p with
 $p+\lambda$ throughout. Thus nothing would be gained in the way of generality if we were to consider (also) splitting at the maximum for Y before the time
 $I_{e_\lambda}$.
Literature-wise we note that a different kind of Wiener–Hopf type factorization of the exponential functional of Lévy processes – namely, in distribution, into a product of independent random variables, themselves exponential functionals in turn – is considered in [Reference Pardo, Patie and Savov16] (Corollary 2.1 therein addresses specifically the spectrally negative case). There does not seem to be any (immediate) connection to our results, which correspond rather to writing the exponential functional as a sum,  $I_\textsf{e}=L+(T_0-L)$, of conditionally independent random variables.
The organization of the remainder of this paper is as follows. Section 2 recalls the relevant fluctuation theory of snLp and introduces further necessary notation in parallel. Then in Section 3 we develop the Laplace transform of the absorption time of Y on the event that Y does not go above a given level, which is a key result for the investigations of Section 4, in which we finally present the laws of quantities at the maximum as stated in (i)–(iii) above. Section 5 concludes with some remarks, in particular on (possible) applications.
2. Preliminaries and further notation concerning the snLp X
This section lays the groundwork. In order to gather only the notation required for the understanding of the results (not the arguments), the reader may restrict their attention to Section 2.1 (items (i) and (ii)) and Section 2.5 (they will also need to consult Definitions 3.1 and 4.1 below).
2.1 Some basic fluctuation theory facts
The following is standard. We provide some specific references for the reader’s benefit.
(i) Let  $\psi$ be the Laplace exponent of X,
 $\psi(\lambda)\coloneqq \log \mathbb{P}[\text{e}^{\lambda X_1}]$ for
 $\lambda\in [0,\infty)$. It has the representation
 \begin{equation}\psi(\lambda)=\dfrac{\sigma^2}{2}\lambda^2+\mu\lambda+\int(\text{e}^{\lambda y}-\mathds{1}_{[-1,0)}(y)\lambda y-1)\nu(\text{d} y),\quad \lambda\in [0,\infty),\end{equation}
for some (unique)  $\mu\in \mathbb{R}$,
 $\sigma^2\in [0,\infty)$, and measure
 $\nu$ on
 $\mathcal{B}_\mathbb{R}$, supported by
 $({-}\infty,0)$, and satisfying
 $\int (1\land y^2 )\nu(\text{d} y)<\infty$. When X has paths of finite variation, equivalently
 $\sigma^2=0$ and
 $\int (1\land \vert y\vert)\nu(\text{d} y)<\infty$, we set
 $\textsf d\coloneqq \mu+\int_{[-1,0)}\vert y\vert\nu(\text{d} y)$; in this case we must have
 $\textsf d\in (0,\infty)$ and
 $\nu$ non-zero. Differentiating under the integral sign in (2.1),
 $\psi$ is seen to be strictly convex, continuous, with
 $\lim_\infty\psi=\infty$, and indeed with
 $\lim_\infty \psi'=\infty$ provided X has paths of infinite variation.
We also let  $\Phi$ be the right-continuous inverse of
 $\psi$,
 $\Phi(q)\coloneqq \inf\{\lambda\in [0,\infty)\colon \psi(\lambda)>q\}$ for
 $q\in [0,\infty)$, so that
 $\Phi(0)$ is the largest zero of
 $\psi$. Recall that X drifts to
 $\infty$, oscillates, or drifts to
 $-\infty$, respectively, as
 $\psi'(0+\!)>0$,
 $\psi'(0+\!)=0$, or
 $\psi'(0+\!)<0$ (the latter being equivalent to
 $\Phi(0)>0$).
Remark 2.1. Assumption 1.1 means that  $\Phi(p)>0$. (Recall that p is the rate of the exponentially distributed random time
 $\textsf{e}$, which features in the Lamperti transform:
 $Y=\mathcal{L}^\textsf{e}(X)$.)
(ii) For real  $x\leq a$,
 $q\in [0,\infty)$, we have the classical identity [Reference Kyprianou14, equation (3.15)]
 \begin{equation}\mathbb{P}_x\big[\text{e}^{-q\tau_a^+};\, \tau_a^+<\infty\big]=\text{e}^{-\Phi(q)(a-x)},\end{equation}
where  $\tau_a^+\coloneqq \inf\{t\in (0,\infty)\colon X_t>a\}$. Equation (2.2) causes
 $\overline{X}_\textsf{e}-X_0$ to have the exponential distribution of rate
 $\Phi(p)$.
(iii) Associated to the solution (2.2) of the first passage upwards problem is the family, in  $\lambda\in[0,\infty)$, of exponential
 $\mathcal F$-martingales,
 $\mathcal{E}^\lambda=(\mathcal{E}^\lambda_t)_{t\in [0,\infty)}$,
 \begin{equation} \mathcal{E}^\lambda_t\coloneqq \text{e}^{\lambda(X_t-X_0)-\psi(\lambda)t},\quad t\in[0,\infty).\end{equation}
(iv) Regarding the position of X at first passage upwards, we have the following resolvent identity [Reference Kuznetsov, Kyprianou and Rivero13, Theorem 2.7(ii)]. For real  $x\leq a$,
 $q\in [0,\infty)$, and
 $f\in \mathcal{B}_{\mathbb{R}}/\mathcal{B}_{[0,\infty]}$,
 \begin{equation}\int_0^\infty \,\text{e}^{-q t}\mathbb{P}_x[f(X_t);\, t<\tau_a^+] \,\text{d} t = \int_{ -\infty}^a f(y)\big(\text{e}^{-\Phi(q)(a-x)}W^{(q)}(a-y) - W^{(q)}(x-y) \big) \,\text{d} y,\end{equation}
where, for  $q\in [0,\infty)$,
 $W^{(q)}\colon \mathbb{R}\to [0,\infty)$ is the q-scale function of X, characterized by being continuous on
 $[0,\infty)$, vanishing on
 $({-}\infty,0)$, and having Laplace transform
 \begin{equation}\int_0^\infty \,\text{e}^{-\theta x}W^{(q)}(x) \,\text{d} x=\dfrac{1}{\psi(\theta)-q},\quad \theta\in (\Phi(q),\infty).\end{equation}
The reader is referred to [Reference Kuznetsov, Kyprianou and Rivero13] for further background on scale functions of snLp. As usual we set  $W^{(0)}=\!:\,W$, and recall that
 $W(0)>0$ or
 $W(0)=0$, respectively, as X has paths of finite or infinite variation [Reference Kuznetsov, Kyprianou and Rivero13, Lemma 3.1].
2.2 Wiener–Hopf factorization
The following falls under the umbrella of the Wiener–Hopf factorization.
(i) Because X is regular upwards [Reference Kyprianou14, page 232], the process  $(X_t;\, t\in [0,G))$ is independent of the process
 $(X_{G+t}-X_{G-};\, t\in [0,\textsf{e}-G))$ [Reference Bertoin3, Lemma VI.6(ii)], and [Reference Bertoin3, comment following Lemma VI.6(ii)]
 $X_{G-}=X_G$ a.s. if and only if X is regular downwards, that is, if and only if X has paths of infinite variation [Reference Kyprianou14, page 232]. In particular, the Wiener–Hopf factors
 $(G,\overline{X}_\textsf{e})$ and
 $(\textsf{e}-G,\overline{X}_\textsf{e}-X_\textsf{e})$ are independent. When
 $p>0$, then their Laplace transforms are given, for
 $\{\gamma,\delta\}\subset [0,\infty)$, by [Reference Kyprianou14, Theorem 6.15(ii)]
 \[\mathbb{P}\big[\text{e}^{-\gamma G-\delta \overline{X}_\textsf{e}}\big]=\dfrac{\kappa(p,0)}{\kappa(p+\gamma,\delta)}\quad\text{and}\quad\mathbb{P}\big[\text{e}^{-\gamma (\textsf{e}-G)+\delta (X_\textsf{e}-\overline{X}_\textsf{e})}\big]=\dfrac{\hat{\kappa}(p,0)}{\hat{\kappa}(p+\gamma,\delta)},\]
where  $\kappa$ and
 $\hat{\kappa}$ are the Laplace exponents of the increasing and decreasing ladder heights processes, respectively. The latter are themselves in turn expressed explicitly as [Reference Kyprianou14, Section 6.5.2]
 \[\kappa(\gamma,\delta)=\Phi(\gamma)+\delta\quad \text{and}\quad \hat{\kappa}(\gamma,\delta)=\dfrac{\gamma-\psi(\delta)}{\Phi(\gamma)-\delta},\quad\{\gamma,\delta\}\subset [0,\infty) \]
(the expression for  $\hat{\kappa}$ being understood in the limiting sense when
 $\Phi(\gamma)=\delta$).
(ii) We have
 \[ \mathbb{P}(\overline{X}_\textsf{e}=X_\textsf{e})=\lim_{\beta\to\infty}\mathbb{P} \big[\text{e}^{\beta(X_\textsf{e}-\overline{X}_\textsf{e})}\big]=\lim_{\beta\to\infty}\dfrac{p(\Phi(p)-\beta)}{\Phi(p)(p-\psi(\beta))}, \]
so that
 \begin{equation} \mathbb{P}(\overline{X}_\textsf{e} = X_\textsf{e}) = \begin{cases} \dfrac{p}{\Phi(p)\textsf d}& \text{if \textit{X} has paths of finite variation,} \\ \\[-9pt] 0 & \text{if \textit{X} has paths of infinite variation.} \end{cases}\end{equation}
For convenience we shall understand  $\textsf d=\infty$, and (hence)
 ${{p}/{(\Phi(p)\textsf d)}}=0$, when X has paths of infinite variation. Note also that
 ${{p}/{(\Phi(p)\textsf d)}}<1$.
2.3 Excursions from the maximum
We gather here some facts concerning the Itô point process of excursions [Reference Blumenthal5, Reference Itô11] from the maximum of X. For what follows, as well as the general references given in the Introduction, the reader may also consult [Reference Greenwood and Pitman10], [Reference Rogers20], and [Reference Avram, Kyprianou and Pistorius1, passim].
(i) Under  $\mathbb{P}$ the running supremum
 $\overline{X}$ serves as a continuous local time for X at the maximum. Its right-continuous inverse is the process of first passage times
 $\tau^+=(\tau_a^+\!)_{a\in [0,\infty)}$. The time axis
 $[0,\infty)$ is partitioned
 $\mathbb{P}$-a.s. into
 \[\textsf M\coloneqq \overline{\{t\in [0,\infty)\colon \overline{X}_t=X_t\}}\allowbreak =\{t\in [0,\infty)\colon \overline{X}_t=X_t\text{ or }\overline{X}_{t}=X_{t-}\},\]
the closure of the random set of times when X is at its running supremum, and the open intervals  $(\tau_{a-}^+,\tau_a^+\!)$,
 $a\in \textsf D\coloneqq \{b\in (0,\infty)\colon \tau_{b-}^+<\tau_b^+\}$; the visiting set
 $\textsf M$ has
 $\mathbb{P}$-a.s. no isolated points.
(ii) The process  $\varepsilon=(\varepsilon_a)_{a\in (0,\infty)}$, defined for
 $a\in (0,\infty)$ by
 \[\varepsilon_a(u)\coloneqq \begin{cases} X_{(\tau_{a-}^++u)\land \tau_a^+}-X_{\tau_{a-}^+-} & \text{if $a\in \textsf D$,}\\ \\[-9pt] \Delta & \text{otherwise,}\end{cases}\]
for  $u\in [0,\infty)$ (of course
 $X_{\tau_{a-}^+-}=a$ off the event
 $\{X_0\ne 0\}$, which is
 $\mathbb{P}$-negligible), where
 $\Delta\notin \mathbb D$ is a cemetery state, is, under
 $\mathbb{P}$, a Poisson point process (Ppp) with values in
 $(\mathbb D,\mathcal D)$, in the filtration
 $\mathcal F_{\tau^+}=(\mathcal F_{\tau^+_a})_{a\in [0,\infty)}$, absorbed on first entry into a path
 $\omega\in \mathbb D$ for which
 $\zeta(\omega)=\infty$, where
 $\zeta(\omega)\coloneqq \inf\{t\in (0, \infty)\colon \omega(t)\geq 0\}$, and whose characteristic measure we will denote by
 $\textsf{n}$ (so the intensity measure of
 $\varepsilon$ is
 $\textsf{l}\times \textsf{n}$, where
 $\textsf{l}$ is Lebesgue measure on
 $\mathcal{B}_{(0,\infty)}$). Note that
 $\textsf{n}$ is carried by the set
 $\{\zeta>0\}$ and also by
 $\{\xi_0<0\}$ (resp.
 $\{\xi_0=0\}$) when X has paths of finite (resp. infinite) variation. Besides,
 $\mathbb{P}$-a.s., for all
 $a\in \textsf D$,
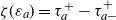 $\zeta(\varepsilon_a)=\tau_{a}^+-\tau_{a-}^+$.
(iii) We have
 \[\mathbb{P} \biggl[\sum_{a\in \textsf D}Z_{a}(\varepsilon_a)\biggr]=\mathbb{P}\biggl[\int_0^{\overline{X}_\infty}\int Z_a(\omega)\textsf{n}(\text{d}\omega) \,\text{d} a\biggr]\]
by the compensation formula for Ppp, whenever 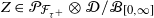 $Z\in \mathcal P_{\mathcal F_{\tau^+}}\otimes \mathcal D/\mathcal{B}_{[0,\infty]}$, with
 $ \mathcal P_{\mathcal F_{\tau^+}}$ the
 $\mathcal F_{\tau^+}$-predictable
 $\sigma$-field. In this regard note that if
 $R\in \mathcal P_\mathcal F\otimes \mathcal D/\mathcal{B}_{[0,\infty]}$, where
 $\mathcal P_\mathcal F$ is now the
 $\mathcal F$-predictable
 $\sigma$-field, then
 $(R_{\tau_{a-}^+})_{a\in (0,\infty)}\in \mathcal P_{\mathcal F_{\tau^+}}\otimes \mathcal D/\mathcal{B}_{[0,\infty]}$.
(iv) The measure  $\textsf{n}$ has the following Markov property: for all
 $t\in [0,\infty)$,
 \[\textsf{n}[G\cdot H\circ \theta_t;\, t<\zeta]=\textsf{n}[G\mathbb{P}_{\xi_t}[H];\, t<\zeta],\quad G\in \mathcal D_t/\mathcal{B}_{[0,\infty]},H\in \mathcal D/\mathcal{B}_{[0,\infty]}.\]
(v) If X has paths of infinite variation (equivalently, X is regular downwards) the result of [Reference Chaumont and Doney6, Corollary 1] applied to  $-X$ (in conjunction with [Reference Chaumont and Doney6, equations (2.5) and (2.8)] therein, (2.2), and the fact that in this case
 $\textsf{n}[1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}]=\Phi(p)$: see Remark 4.1), implies that for all
 $t\in (0,\infty)$ and then all
 $F\in \mathcal D_t/\mathcal{B}_{\mathbb{R}}$ bounded and continuous in the Skorokhod topology on
 $\mathbb D$,
 \begin{equation}\textsf{n}[F;\, t<\zeta]=\textsf{k}\lim_{x\uparrow 0}\dfrac{\mathbb{P}_x[F;\, t<\tau_0^+]}{\textsf{g}(x)},\end{equation}
where
 \[\textsf{g}(x)\coloneqq \lim_{q\downarrow 0}\dfrac{1-\text{e}^{\Phi(q)x}}{\Phi(q)}=\begin{cases}\dfrac{1-\text{e}^{\Phi(0)x}}{\Phi(0)} & \Phi(0)>0{,}\\\\[-9pt] -x & \Phi(0)=0{,}\end{cases}\quad x\in ({-}\infty,0),\]
and with  $\textsf{k}\in (0,\infty)$ depending on the characteristics of X only.
(vi) We have the following representation of the scale function W [Reference Kuznetsov, Kyprianou and Rivero13, equation (31)]:
 \begin{equation}\dfrac{W(x)}{W(a)}=\exp\biggl\{-\int_x^a\textsf{n}({-}\underline{\xi}_{\zeta}>y) \,\text{d} y\biggr\},\quad 0\leq x
< a,\end{equation}
where  $\underline{\xi}=(\underline{\xi}_t)_{t\in [0,\infty]}$ is the running infimum process of
 $\xi$.
2.4 Point process of jumps
Under  $\mathbb{P}$ the process
 $\Delta X=(\Delta X_t)_{t\in (0,\infty)}$ of the jumps of X is a Ppp in the filtration
 $\mathcal F$ with values in
 $(\mathbb{R}\backslash \{0\},\mathcal{B}_{\mathbb{R}\backslash \{0\}})$ and 0 as cemetery state, whose characteristic measure is the restriction to
 $\mathcal{B}_{\mathbb{R}\backslash \{0\}}$ of
 $\nu$. In this case the compensation formula for Ppp states that
 \[\mathbb{P}\biggl[\sum_{t\in\textsf J}Z_{t}(\Delta X_t)\biggr]=\mathbb{P}\biggl[\int_0^\infty \int Z_t(x)\textsf{n}( \text{d} x) \,\text{d} t\biggr]\quad\text{for $Z\in \mathcal P_\mathcal F\otimes \mathcal{B}_{\mathbb{R}\backslash \{0\}}/\mathcal{B}_{[0,\infty]}$,}\]
where  $\textsf J\coloneqq \{t\in (0,\infty)\colon \Delta X_t\ne 0\}$ is the set of jump times of X. See for instance [Reference Bertoin3, Theorem I.1].
2.5 Patie’s scale functions
Assuming  $\Phi(p)\notin \alpha\mathbb{N}$, we set
 \[\mathcal{J}^{p,\alpha}(y)\coloneqq \sum_{k=0}^{\infty}\textsf{a}^{p,\alpha}_ky^k,\quad y\in [0,\infty),\quad \text{where }\textsf{a}^{p,\alpha}_k\coloneqq \biggl(\prod_{l=1}^k(\psi(l\alpha)-p)\biggr)^{-1},\quad k\in \mathbb{N}_0\]
(the condition on  $\Phi(p)$ ensures all the
 $\textsf{a}^{p,\alpha}_k$ are well-defined), and, whether or not
 $\Phi(p)\notin \alpha\mathbb{N}$,
 \[\mathcal{I}^{p,\alpha}(y)\coloneqq \sum_{k=0}^{\infty}\textsf{b}^{p,\alpha}_k y^k,\quad y\in [0,\infty),\quad \text{where }\textsf{b}^{p,\alpha}_k\coloneqq \biggl(\prod_{l=1}^k(\psi(\Phi(p)+l\alpha)-p)\biggr)^{-1},\quad k\in \mathbb{N}_0,\]
with (as usual) the empty product being interpreted as  $=1$. These power series converge absolutely, indeed
 \[ \lim_{k\to\infty}\dfrac{\textsf{a}^{p,\alpha}_{k+1}}{\textsf{a}^{p,\alpha}_k}=\lim_{k\to\infty}\dfrac{\textsf{b}^{p,\alpha}_{k+1}}{\textsf{b}^{p,\alpha}_k}=0, \]
and the coefficients  $\textsf{a}^{p,\alpha}_k$ are ultimately of the same sign (even all strictly positive when
 $\Phi(p)<\alpha$). Finally
 \begin{equation}\mathbb{P}_x \big[\text{e}^{-\gamma I_{\tau_a^+}};\, \tau_a^+<\textsf{e}\big]=\dfrac{\text{e}^{\Phi(p)x}\mathcal{I}^{p,\alpha}(\gamma\text{e}^{\alpha x})}{\text{e}^{\Phi(p)a}\mathcal{I}^{p,\alpha}(\gamma\text{e}^{\alpha a})},\quad x\leq a,\gamma\in[0,\infty){.}\end{equation}
In other words
 \begin{equation}\mathbb{Q}_y\big[\text{e}^{-\gamma T_d^+};\, T_d^+<\infty\big]=\biggl(\dfrac{y}{d}\biggr)^{\Phi(p)}\dfrac{\mathcal{I}^{p,\alpha}(\gamma y^\alpha)}{\mathcal{I}^{p,\alpha}(\gamma d^\alpha)},\quad 0<y\leq d,\gamma\in[0,\infty),\end{equation}
where
 \[T_d^+\coloneqq \inf\{s\in(0,\infty)\colon Y_s>d\}\quad \text{for $d\in (0,\infty)$.}\]
See [Reference Patie17, Theorem 2.1] (or [Reference Kyprianou14, Section 13.7], [Reference Vidmar22, Example 6]).
Remark 2.2. Note that  $\psi-p$ is the Laplace exponent of the snLp X killed (and sent to
 $-\infty$) at time
 $\textsf{e}$, while
 $\psi(\Phi(p)+\cdot)-p$ is the Laplace exponent of X under the Esscher transform corresponding to the exponential martingale
 $\mathcal{E}^{\Phi(p)}$. In this sense
 $\mathcal{J}^{p,\alpha}$ and
 $\mathcal{I}^{p,\alpha}$ may both be viewed as being just two special instances of the same underlying power series that is in general associated to the Laplace exponent of a possibly killed snLp and an index
 $\alpha$.
3. Laplace transform of the absorption time of Y (on the event that Y does not go above a given level)
The next proposition is the key to the main result of this section, but it is also interesting in its own right.
Proposition 3.1. Assume  $\Phi(p)\notin \alpha\mathbb{N}$. Let
 $\beta\in [0,\infty)$ and set
 \begin{align*}M_t & \coloneqq \text{e}^{-\beta I_{t\land \textsf{e}}}\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha X_{t}}\mathds{1}_{\{t<\textsf{e}\}}),\quad t\in [0,\infty){,}\\[3pt] N_s & \coloneqq \text{e}^{-\beta (s\land T_0)}\mathcal{J}^{p,\alpha}(\beta Y_s^\alpha),\quad s\in [0,\infty).\end{align*}
(i) For each
$y\in (0,\infty)$, under $\mathbb{Q}_y$, N is a martingale in the filtration $\mathcal{G}$.-
(ii) For each
$c\in \mathbb{R}$ and $x\in \mathbb{R}$, under $\mathbb{P}_x$, $M^{\tau_c^+}$ is a martingale in the filtration $\mathcal F$. (Here $M^{\tau_c^+}$ is the process M stopped at $\tau_c^+$.)


The proof of Proposition 3.1 follows presently on page 11. Before that, however, we would like to make some associated remarks, put the proposition into context, and, moreover, we would like to state Corollary 3.1, which gives the main result of this section, namely the Laplace transform of the absorption time of Y (on the event that Y does not go above a given level). As mentioned in the Introduction, the latter will in turn be used to compute the temporal ‘conditional Wiener–Hopf factors’ in the next section.
Remark 3.1. We have the following parallel statements to (i) and (ii) of Proposition 3.1. Let  $\gamma\in [0,\infty)$.
(I) The process
$(\text{e}^{-\gamma s}Y_s^{\Phi(p)} \mathcal{I}^{p,\alpha}(\gamma Y_s^\alpha)\mathds{1}_{\{s<T_0\}})_{s\in [0,\infty)}$ stopped at $T_d^+$ is a martingale in $\mathcal G$ with terminal value $d^{\Phi(p)}\mathcal{I}^{p,\alpha}(\gamma d^\alpha)\,\text{e}^{-\gamma T_d^+}\mathds{1}_{\{T_d^+<T_0\}}$, this being true under $\mathbb{Q}_y$ for all $d\in (0,\infty)$ and $y\in (0,d]$.-
(II) The process
$(\text{e}^{-\gamma I_t}\,\text{e}^{\Phi(p)X_t}\mathcal{I}^{p,\alpha}(\gamma\text{e}^{\alpha X_t})\mathds{1}_{\{t<\textsf{e}\}})_{t\in [0,\infty)}$ stopped at $\tau_a^+$ is a martingale in $\mathcal F$ with terminal value $\text{e}^{\Phi(p)a}\mathcal{I}^{p,\alpha}(\gamma\text{e}^{\alpha a})\,\text{e}^{-\gamma I_{\tau_a^+}}\mathds{1}_{\{\tau_a^+<\textsf{e}\}}$, this being true under $\mathbb{P}_x$ for all $a\in \mathbb{R}$ and $x\in ({-}\infty,a]$.


Indeed (I) is a direct consequence of (2.10) and the Markov property of Y in  $\mathcal G$, whereas it is perhaps easiest to get (II) by optional sampling on the martingale from (I) via the time change
 $I=(I_t)_{t\in [0,\infty)}$ (in an analogous manner, as we will see in the first paragraph of the proof of Proposition 3.1).
Remark 3.2. In the case  $p=0=\Phi(0)$ (
 $T_0=\infty$ a.s.), when
 $\mathcal{J}^{p,\alpha}=\mathcal{I}^{p,\alpha}$, the martingale claim on N of Proposition 3.1 can be found in [Reference Kyprianou14, Theorem 13.9]. The case
 $\Phi(0)>0=p$ is inspired by [Reference Patie17, equation (2.4)]. Indeed the latter result implies that if, further, Rivero’s condition [Reference Rivero19, Theorem 2]
 $\Phi(0)\in (0,\alpha)$ is met (guaranteeing that Y admits a self-similar recurrent extension that leaves 0 continuously), then for some
 $b\in (0,\infty)$, the process
 $M-bO$, where
 $O\coloneqq (\text{e}^{\Phi(0) X_t}\mathcal{I}^{0,\alpha}(\beta \,\text{e}^{\alpha X_t}))_{t\in [0,\infty)}$, is an (even bounded non-negative) martingale in
 $\mathcal F$. Combined with (II) of Remark 3.1, Proposition 3.1 (ii) follows (apply optional stopping and the fact that martingales form a linear space). The general case can be handled by the same techniques as are used in the proof of [Reference Kyprianou14, Theorem 13.9], but the details are quite delicate, so we provide an explicit proof below. More generally, Proposition 3.1 is related to the computation of the positive entire moments of (spectrally negative) pssMp, for which see [Reference Bertoin and Yor4] and more recently [Reference Barczy and Döring2]. We mention also the paper [Reference Patie18], which provides some analytical representations of the density of the absorption time
 $T_0$.
Corollary 3.1. For  $\beta\in [0,\infty)$ and for real
 $x\leq c$,
 $0<y\leq d$,
 \begin{equation}\mathbb{P}_x \big[\text{e}^{-\beta I_\textsf{e}};\, \tau_c^+\geq \textsf{e}\big]=\mathcal{M}^{p,\alpha}_\beta(\text{e}^x,\,\text{e}^c),\quad i.e.\quad \mathbb{Q}_y\big[\text{e}^{-\beta T_0};\, T_d^+=\infty\big]=\mathcal{M}^{p,\alpha}_\beta(y,d).\end{equation}
Definition 3.1. For  $\beta\in [0,\infty)$, we set
 \begin{equation*}\mathcal{M}^{p,\alpha}_\beta(y,d)\coloneqq \mathcal{J}^{p,\alpha}(\beta y^\alpha)-\biggl(\dfrac{y}{d}\biggr)^{\Phi(p)}\dfrac{\mathcal{I}^{p,\alpha}(\beta y^\alpha)}{\mathcal{I}^{p,\alpha}(\beta d^\alpha)}\mathcal{J}^{p,\alpha}(\beta d^\alpha),\quad \{y,d\}\subset (0,\infty),y\leq d,\end{equation*}
where the expression must be understood in the limiting sense (as  $\alpha\to \Phi(p)/m$), when
 $\Phi(p)=\alpha m$ for some
 $m\in \mathbb{N}$. It will be seen in the proof of Corollary 3.1 that this limit exists a priori, and it will be identified analytically in Remark 3.3.
Some further remarks concerning the above corollary and definition follow.
Remark 3.3. Suppose  $\Phi(p)=m\alpha$ for an
 $m\in \mathbb{N}$. Then, for
 \[ \alpha'\in \biggl(\dfrac{\Phi(p)}{m+1},\dfrac{\Phi(p)}{m-1}\biggr)\bigg\backslash \biggl\{\dfrac{\Phi(p)}{m}\biggr\}, \]
provisionally setting
 \[ \widetilde{\textsf{b}^{p,\alpha'}_k}\coloneqq \biggl(\prod_{l=1}^k(\psi(m\alpha'+l\alpha')-p)\biggr)^{-1}\quad \text{for $k\in \mathbb{N}_0$,} \]
we may write
 \begin{align*} & \mathcal{M}^{p,\alpha'}_\beta(y,d)\\[2pt] &\quad =\sum_{k=0}^{m-1} \textsf{a}^{p,\alpha'}_k(\beta y^{\alpha'}\!)^k-\biggl(\dfrac{y}{d}\biggr)^{\Phi(p)}\dfrac{\mathcal{I}^{p,\alpha'}(\beta y^{\alpha'}\!)}{\mathcal{I}^{p,\alpha'}(\beta d^{\alpha'}\!)}\sum_{k=0}^{m-1} \textsf{a}^{p,\alpha'}_k(\beta d^{\alpha'}\!)^k\\[2pt] &\quad\quad\, +\textsf{a}^{p,\alpha'}_{m-1}\beta^m\dfrac{y^{m\alpha'}\sum_{k=0}^\infty \widetilde{\textsf{b}^{p,\alpha'}_k}(\beta y^{\alpha'}\!)^k- ({{y}/{d}})^{\Phi(p)}\tfrac{\mathcal{I}^{p,\alpha'}(\beta y^{\alpha'}\!)}{\mathcal{I}^{p,\alpha'}(\beta d^{\alpha'}\!)}d^{m\alpha'}\sum_{k=0}^\infty \widetilde{\textsf{b}^{p,\alpha'}_k}(\beta d^{\alpha'}\!)^k}{\psi(m\alpha')-p}\\[2pt] &\quad \xrightarrow{\alpha'\to {{\Phi(p)}/{m}}}\sum_{k=0}^{m-1} \textsf{a}^{p,\alpha}_k(\beta y^{\alpha})^k-\biggl(\dfrac{y}{d}\biggr)^{\Phi(p)}\dfrac{\mathcal{I}^{p,\alpha}(\beta y^{\alpha})}{\mathcal{I}^{p,\alpha}(\beta d^{\alpha})}\sum_{k=0}^{m-1} \textsf{a}^{p,\alpha}_k(\beta d^{\alpha})^k\\[2pt] &\quad\quad\, +\dfrac{\textsf{a}^{p,\alpha}_{m-1}(\beta y^\alpha)^m}{\psi'(\Phi(p))}\biggl[\ln\biggl(\dfrac{y}{d}\biggr)\mathcal{I}^{p,\alpha}(\beta y^{\alpha})-\mathcal{K}^{p,\alpha}(\beta y^\alpha)+\dfrac{\mathcal{I}^{p,\alpha}(\beta y^\alpha)}{\mathcal{I}^{p,\alpha}(\beta d^\alpha)}\mathcal{K}^{p,\alpha}(\beta d^{\alpha})\biggr]\\[2pt] &\quad=\mathcal{M}^{p,\alpha}_\beta(y,d),\end{align*}
where
 \[\mathcal{K}^{p,\alpha}(z)\coloneqq \sum_{k=1}^\infty \textsf{c}^{p,\alpha}_kz^k,\quad z\in (0,\infty), \quad\text{with }\textsf{c}^{p,\alpha}_k\coloneqq \textsf{b}^{p,\alpha}_k\sum_{l=1}^k\dfrac{\psi'(\Phi(p)+l\alpha)}{\psi(\Phi(p)+l\alpha)},\quad k\in \mathbb{N}\]
(it is easy to check that  $\psi'/\psi$ is bounded on
 $[c,\infty)$ for any
 $c\in (\Phi(0),\infty)$).
Remark 3.4. It is clear from the definition of  $\mathcal{J}^{p,\alpha}$ and
 $\mathcal{I}^{p,\alpha}$ (resp. and from Remark 3.3) in the case when
 $\Phi(p)\notin \alpha\mathbb{N}$ (resp. when
 $\Phi(p)\in \alpha\mathbb{N}$) that
 $\mathcal{M}^{p,\alpha}_\cdot(\cdot,\cdot)$ is jointly continuous. This also follows in any case from (3.1): by quasi-left-continuity and regularity of 0 for
 $(0,\infty)$ of the process X, and from the distribution of
 $\overline{X}_\textsf{e}$ not having any finite atoms, one concludes that for each
 $c\in \mathbb{R}$, a.s.
 \[\bigcap_{d\in ({-}\infty,c)}\{\tau_d^+< \textsf{e}\}=\{\tau_c^+< \textsf{e}\}=\bigcup_{d\in (c,\infty)}\{\tau_d^+
< \textsf{e}\},\]
so that bounded convergence applies in (3.1) (once we have passed from  $\mathbb{P}_x$ to
 $\mathbb{P}$ via spatial homogeneity of X). Furthermore, the relation
 $0\leq \mathcal{M}^{p,\alpha}_\beta(y,d)\leq 1-({{y}/{d}})^{\Phi(p)}$ also follows directly from (3.1) (via (2.2)).
Remark 3.5. Provisionally, let  $f(\beta)\coloneqq \mathbb{P}[\text{e}^{-\beta I_\textsf{e}}]$ for
 $\beta\in [0,\infty)$. Assume
 $\Phi(p)\notin \alpha\mathbb{N}$. Then, by (3.1) and (2.9), for all real
 $x\leq c$,
 \begin{align*} f(\beta \,\text{e}^{\alpha x}) & =\mathbb{P}_x[\text{e}^{-\beta I_{\tau_c^+}};\, \tau_c^+<\textsf{e}]\mathbb{P}_c[\text{e}^{-\beta I_\textsf{e}}]+\mathbb{P}_x[\text{e}^{-\beta I_\textsf{e}};\, \tau_c^+\geq \textsf{e}]\\[3pt] &=\dfrac{\text{e}^{\Phi(p)x}\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha x})}{\text{e}^{\Phi(p)c}\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha c})}f(\beta \,\text{e}^{\alpha c})+\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha x})-\dfrac{\text{e}^{\Phi(p)x}\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha x})}{\text{e}^{\Phi(p)c}\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha c})}\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha c}),\end{align*}
that is,
 \[\dfrac{f(\beta \,\text{e}^{\alpha x})-\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha x})}{(\beta \,\text{e}^{\alpha x})^{{{\Phi(p)}/{\alpha}}}\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha x})}=\dfrac{f(\beta \,\text{e}^{\alpha c})-\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha c})}{(\beta \,\text{e}^{\alpha c})^{{{\Phi(p)}/{\alpha}}}\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha c})}.\]
It follows that, for some  $C^{p,\alpha}\in \mathbb{R}$ (the
 $C^{p,\alpha}$ of course also depends on the characteristic of X; we make explicit only the dependence on
 $\alpha$ and p), and then all
 $x\in \mathbb{R}$,
 $\beta \in [0,\infty)$, we have
 \begin{equation}\mathbb{P}_x[\text{e}^{-\beta I_\textsf{e}}]=f(\beta \,\text{e}^{\alpha x})=\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha x})-C^{p,\alpha} (\beta \,\text{e}^{\alpha x})^{{{\Phi(p)}/{\alpha}}}\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha x}).\end{equation}
Since, by bounded convergence, for  $\beta>0$,
 $\lim_{x\to\infty}\mathbb{P}_x[\text{e}^{-\beta I_\textsf{e}}]=0$, one can identify
 $C^{p,\alpha}$ as the unique real number, necessarily not zero (indeed strictly positive or strictly negative depending on whether the coefficients
 $\textsf{a}^{p,\alpha}_n$ are ultimately all strictly positive or strictly negative), for which
 \[\lim_{y\to\infty}(\mathcal{J}^{p,\alpha}(y)- C^{p,\alpha} y^{{{\Phi(p)}/{\alpha}}}\mathcal{I}^{p,\alpha}(y))=0.\]
Again, when  $\Phi(p)=\alpha m$ for some
 $m\in \mathbb{N}$, then (3.2) still holds, provided the right-hand side is understood in the limiting sense as
 $\alpha\to \Phi(p)/m$. This generalizes the result of [Reference Patie17, equation (2.4)] to the case when
 $p>0$ or else
 $\Phi(0)\in [\alpha,\infty)$.
Proofs of Proposition 3.1 and Corollary 3.1. Suppose (i) of Proposition 3.1 has been established. For each  $c\in \mathbb{R}$,
 $M^{\tau_c^+}$ is
 $N^{T_{\text{e}^c}^+}$, time-changed by
 $I=(I_t)_{t\in [0,\infty)}$. By optional stopping
 $N^{T_{\text{e}^c}^+}$ is an a.s. bounded martingale in
 $\mathcal G$. I is a family of finite
 $\mathcal G$-stopping times. Thus, by optional sampling on
 $N^{T_{\text{e}^c}^+}$, the martingale property of
 $M^{\tau_c^+}$ follows (note that
 $\mathcal F_t\subset \mathcal G_{I_t}$ for all
 $t\in [0,\infty)$), which is (ii) of Proposition 3.1. Assuming
 $\Phi(p)\notin \alpha\mathbb{N}$, Corollary 3.1 then holds yet again by optional sampling, this time on the martingale
 $M^{\tau_c^+}$: for real
 $x\leq c$,
 $\beta\in[0,\infty)$, we have
 \[\mathbb{P}_x [\text{e}^{-\beta I_{\tau_c^+}}\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha c});\, \tau_c^+<\textsf{e}]+\mathbb{P}_x[\text{e}^{-\beta I_\textsf{e}};\, \tau_c^+\geq \textsf{e}]=\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha x}),\]
followed by an application of (2.9). The case  $\Phi(p)\in \alpha\mathbb{N}$ is obtained by taking limits.
So it remains to argue Proposition 3.1 (i). Let  $s\in[0,\infty)$,
 $y\in (0,\infty)$, and
 $n\in \mathbb{N}$.
Recall first from (2.10) that for  $\gamma\in (0,\infty)$ and
 $d\in [y,\infty)$,
 \[\mathbb{Q}_y[\text{e}^{-\gamma T_d^+};\, T_d^+<\infty]=\biggl(\dfrac{y}{d}\biggr)^{\Phi(p)}\dfrac{\mathcal{I}^{p,\alpha}(\gamma y^\alpha)}{\mathcal{I}^{p,\alpha}(\gamma d^\alpha)}.\]
But
 \[\mathbb{Q}_y[\text{e}^{-\gamma T_d^+};\, T_d^+<\infty]=\int_0^\infty \gamma\text{e}^{-\gamma s}\mathbb{Q}_y(\overline{Y}_s> \text{d}) \,\text{d} s.\]
Hence, for  $k\in (0,\infty)$, using
 $\mathbb{Q}_y[\overline{Y}_s^k]=k\int_0^\infty m^{k-1}\mathbb{Q}_y(\overline{Y}_s>m) \,\text{d} m$ and Tonelli’s theorem,
 \begin{equation}\int_0^\infty \gamma\text{e}^{-\gamma s}\mathbb{Q}_y[\overline{Y}_s^k] \,\text{d} s=y^k+k\int_y^\infty m^{k-1}\biggl(\dfrac{y}{m}\biggr)^{\Phi(p)}\dfrac{\mathcal{I}^{p,\alpha}(\gamma y^\alpha)}{\mathcal{I}^{p,\alpha}(\gamma m^\alpha)} \,\text{d} m<\infty\end{equation}
(the finiteness is clear from the definition of  $\mathcal{I}^{p,\alpha}$). We conclude that
 $\mathbb{Q}_y[\overline{Y}_s^n]<\infty$. (Incidentally, formula (3.3) gives the positive moments of
 $\overline{Y}$ sampled at an independent exponential random time of rate
 $\gamma$; it is even trivially valid for
 $k=0$.)
Next we have, for  $t\in [0,\infty)$,
 \[\mathbb{Q}_y[Y_{s\land I_t}^{\alpha n}]=\mathbb{P}_{\log y}[\text{e}^{\alpha nX_{\phi_s\land t}};\, \phi_s\land t<\textsf{e}]=\mathbb{Q}_y[\text{e}^{\alpha nX_{\phi_s\land t}-p(\phi_s\land t)}],\]
because  $\textsf{e}$ is independent of X; note that
 $\phi_{s\land I_t}=\phi_s\land t$. Furthermore, we have (because
 $\phi$ is the right inverse of I, which is, by the fundamental theorem of calculus, differentiable from the right and differentiable at every continuity point of X)
 \[\dfrac{\text{d}^+\phi_v}{ \text{d} v}=\text{e}^{-\alpha X_{\phi_v}},\quad v\in [0,I_\infty),\]
where  $d^+$ signifies that the right-derivative is intended, with the understanding that it can be replaced by the ordinary derivative at every
 $v\in [0,I_\infty)$ for which
 $\phi_v$ is a continuity point of X (and hence for Lebesgue-almost every (indeed all except countably many)
 $v\in [0,I_\infty)$). Then, with analogous provisos,
 \[\dfrac{\text{d}^+}{ \text{d} v}\,\text{e}^{(\psi(\alpha n)-p)\phi_v}=\text{e}^{(\psi(\alpha n)-p)\phi_v}(\psi(\alpha n)-p)\,\text{e}^{-\alpha X_{\phi_v}},\quad v\in [0,I_\infty),\]
so that
 \[\text{e}^{(\psi(\alpha n)-p)\phi_v}=1+(\psi(\alpha n)-p)\int_0^v\,\text{e}^{(\psi(\alpha n)-p)\phi_w-\alpha X_{\phi_w}} \,\text{d} w,\quad v\in [0,I_\infty)\]
(the function  $[0,\infty)\ni u\mapsto X_u$ is locally bounded away from
 $-\infty$, hence
 $[0,I_\infty)\ni v\mapsto \phi_v$ is locally Lipschitz and thus absolutely continuous; accordingly the fundamental theorem of calculus applies). Then
 \[\text{e}^{(\psi(\alpha n)-p)\phi_{s\land I_t}}=1+(\psi(\alpha n)-p)\int_0^s\,\text{e}^{(\psi(\alpha n)-p)\phi_v-\alpha X_{\phi_v}} \mathds{1}_{[0,t)}(\phi_v)\,\text{d} v.\]
Now multiply both sides by  $\text{e}^{\alpha n (X_{\phi_{s\land I_t}}-\log y)-\psi(\alpha n)\phi_{s\land I_t}}$ and take the
 $\mathbb{Q}_y$-expectation. By Tonelli’s theorem, by optional sampling on the exponential martingale
 $\mathcal{E}^{\alpha n}$ (2.3) at the bounded
 $\mathcal F$-stopping times
 $\phi_s\land t$ and
 $\phi_v\land t$, and by the independence of X from
 $\textsf{e}$, it follows that
 \begin{align*} \mathbb{Q}_y[Y_{s\land I_t}^{\alpha n}] & =y^{\alpha n}+(\psi(\alpha n)-p)\int_0^s\mathbb{Q}_y[\text{e}^{\alpha(n-1)X_{\phi_{v}}-p\phi_v};\, v<I_t] \,\text{d} v\\* & =y^{\alpha n}+(\psi(\alpha n)-p)\int_0^s\mathbb{Q}_y[Y_{v}^{\alpha (n-1)};\, v<I_t,\phi_v<\textsf{e}] \,\text{d} v. \end{align*}
Let  $t\to \infty$. By dominated convergence on the left-hand side and monotone convergence on the right-hand side, and because Y is constant on
 $[I_\textsf{e},\infty)\supset [I_\infty,\infty)$ and a.s. continuous at
 $I_\infty$ when
 $p=0$, we obtain
 \begin{equation}\mathbb{Q}_y[Y_{s}^{\alpha n}]=y^{\alpha n}+(\psi(\alpha n)-p)\int_0^s\mathbb{Q}_y[Y_{v}^{\alpha (n-1)};\, v<T_0] \,\text{d} v.\end{equation}
It is now proved by induction that
 \[\mathbb{Q}_y[Y_s^{\alpha n}]\leq \sum_{k=0}^n\dfrac{\vert \textsf{a}^{p,\alpha}_{n-k}\vert }{\vert \textsf{a}^{p,\alpha}_n\vert }y^{\alpha(n-k)}\dfrac{s^k}{k!}\]
(with equality when  $T_0=\infty$ a.s., i.e.
 $\Phi(0)= 0=p$, in which case all the
 $\textsf{a}^{p,\alpha}_l$ are positive). Then
 \begin{align*} \mathbb{Q}_y[\text{e}^{-\beta s}\vert \mathcal{J}^{p,\alpha}(\beta Y_s^\alpha)\vert ] & \leq \text{e}^{-\beta s}\sum_{n=0}^\infty \vert \textsf{a}^{p,\alpha}_n\vert \beta^n\mathbb{Q}_y[Y_s^{\alpha n}]\\* &\leq \text{e}^{-\beta s}\sum_{n=0}^\infty \vert \textsf{a}^{p,\alpha}_n\vert \beta^n\sum_{k=0}^n\dfrac{\vert \textsf{a}^{p,\alpha}_{n-k}\vert }{\vert \textsf{a}^{p,\alpha}_n\vert}y^{\alpha(n-k)}\dfrac{s^k}{k!}\\ & =\text{e}^{-\beta s}\sum_{k=0}^\infty\dfrac{(\beta s)^k}{k!}\sum_{n=k}^\infty\vert \textsf{a}^{p,\alpha}_{n-k}\vert (\beta y^\alpha)^{n-k}\\* &= \sum_{n=0}^\infty\vert \textsf{a}^{p,\alpha}_{n}\vert (\beta y^\alpha)^{n}<\infty.\end{align*}
Moreover, in the above display, when  $\Phi(0)=0=p$, the two occurrences of
 $\leq$ are actually equalities and the whole expression is equal to
 $\mathcal{J}^{p,\alpha}(\beta y^\alpha)$ (use Tonelli’s theorem to note that the first inequality is in fact an equality).
We conclude that
 \begin{equation}\sup_{v\in [0,\infty)}\mathbb{Q}_y[\text{e}^{-\beta v}\vert \mathcal{J}^{p,\alpha}(\beta Y_v^\alpha)\vert ]<\infty\end{equation}
(and 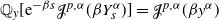 $\mathbb{Q}_y[\text{e}^{-\beta s} \mathcal{J}^{p,\alpha}(\beta Y_s^\alpha)]=\mathcal{J}^{p,\alpha}(\beta y^\alpha)$ when
 $\Phi(0)=0=p$). In the case when
 $\Phi(0)=0=p$ (
 $T_0=\infty$ a.s.), it is now already standard to argue that N is a martingale in
 $\mathcal G$, but to handle the general scenario we have to do a little more work.
Specifically, we show that
 \begin{equation}\mathbb{Q}_y[\text{e}^{-\beta(s\land T_0)}\mathcal{J}^{p,\alpha}(\beta Y_{s}^\alpha)]=\mathcal{J}^{p,\alpha}(\beta y^\alpha).\end{equation}
By self-similarity we may assume  $y=1$. We then obtain
 \[f(s)\coloneqq \mathbb{Q}[\text{e}^{-\beta(s\land T_0)}\mathcal{J}^{p,\alpha}(\beta Y_{s}^\alpha)]=\mathbb{Q}[\text{e}^{-\beta T_0};\, T_0\leq s]+ \text{e}^{-\beta s}\sum_{n=0}^\infty \textsf{a}^{p,\alpha}_n\beta^n\mathbb{Q}[Y_s^{\alpha n};\, s<T_0]\]
by linearity and Tonelli’s theorem, recalling that all the  $\textsf{a}^{p,\alpha}_n$ are ultimately of the same sign. Therefore
 \begin{align*} f(s)& =\mathbb{Q}[\text{e}^{-\beta (s\land T_0)}]+\text{e}^{-\beta s}\sum_{n=1}^\infty \textsf{a}^{p,\alpha}_n\beta^n\mathbb{Q}[Y_s^{\alpha n}],\\*& = \mathbb{Q}[\text{e}^{-\beta (s\land T_0)}]+\text{e}^{-\beta s}\sum_{n=1}^\infty \textsf{a}^{p,\alpha}_n\beta^n\biggl(1+(\psi(\alpha n)-p)\int_0^s\mathbb{Q}_y[Y_{v}^{\alpha (n-1)};\, v<T_0] \,\text{d} v\biggr)\\& =\mathbb{Q}[\text{e}^{-\beta (s\land T_0)}]+\text{e}^{-\beta s}(\mathcal{J}^{p,\alpha}(\beta )-1)+\text{e}^{-\beta s}\beta \int_0^s\sum_{n=0}^\infty \textsf{a}^{p,\alpha}_n\beta^n\mathbb{Q}[Y_v^{\alpha n};\, v<T_0] \,\text{d} v\\& =\mathbb{Q}[\text{e}^{-\beta (s\land T_0)}]+\text{e}^{-\beta s}(\mathcal{J}^{p,\alpha}(\beta )-1)+\text{e}^{-\beta s}\beta\int_0^s\,\text{e}^{\beta v}(f(v)-\mathbb{Q}[\text{e}^{-\beta T_0};\, T_0\leq v]) \,\text{d} v\\& =\mathbb{Q}[\text{e}^{-\beta (s\land T_0)}]+\text{e}^{-\beta s}(\mathcal{J}^{p,\alpha}(\beta )-1)+\text{e}^{-\beta s}\beta\int_0^s\,\text{e}^{\beta v}f(v) \,\text{d} v-\mathbb{Q}[\text{e}^{-\beta T_0}-\text{e}^{-\beta s};\, s\geq T_0]\\*& =\mathcal{J}^{p,\alpha}(\beta)\,\text{e}^{-\beta s}+\beta \,\text{e}^{-\beta s}\int_0^s\,\text{e}^{\beta v}f(v) \,\text{d} v,\end{align*}
where the second equality follows from (3.4), while the interchange of the integral and summation in the third equality is again justified by the fact that all the  $\textsf{a}^{p,\alpha}_l$ are ultimately of the same sign.
We now have the integral equation
 \[f(s)=\mathcal{J}^{p,\alpha}(\beta)\,\text{e}^{-\beta s}+\beta \,\text{e}^{-\beta s}\int_0^s\,\text{e}^{\beta v}f(v) \,\text{d} v\quad\text{for\, $f\colon [0,\infty)\to[0,\infty)$.} \]
But f is locally bounded because of (3.5), hence continuous by bounded convergence, hence continuously differentiable by the fundamental theorem of calculus. Differentiating, we obtain  $f'=0$ and thus
 $f(s)=f(0)=\mathcal{J}^{p,\alpha}(\beta)$, as was to be shown.
With (3.6) having been established, showing that N is a martingale in  $\mathcal G$ is an exercise in applying the Markov property of Y on
 $[0,T_0)$: for
 $\{s_1,s_2\}\subset [0,\infty)$,
 \begin{align*} & \mathbb{Q}_y[\text{e}^{-\beta((s_1+s_2)\land T_0)}\mathcal{J}^{p,\alpha}(\beta Y_{s_1+s_2}^\alpha)\mid \mathcal G_{s_1}]\\[3pt] &\quad =\mathds{1}_{\{s_1<T_0\}}\,\text{e}^{-\beta s_1}\mathbb{Q}_{Y_{s_1}}[\text{e}^{-\beta (s_2\land T_0)}\mathcal{J}^{p,\alpha}(\beta Y_{s_2}^\alpha)]+\mathds{1}_{\{s_1\geq T_0\}}\,\text{e}^{-\beta T_0}\\[3pt] &\quad =\text{e}^{-\beta(s_1\land T_0)}\mathcal{J}^{p,\alpha}(\beta Y_{s_1}^\alpha)\quad{\text{a.s.-$\mathbb{Q}_y$,}} \end{align*}
where we used (3.6) in the last equality.□
4. Laws of quantities at the maximum
In this section the laws of the quantities at the maximum are developed as stated in the Introduction. The section culminates on page 21 with Theorem 4.1, which gives a panorama of all the results in the context of the ‘conditional’ Wiener–Hopf factorization.
4.1 Laplace transform of L given $\overline{Y}_\infty$

Proposition 4.1. Let  $\gamma\in [0,\infty)$. For
 $x\in \mathbb{R}$, a.s.-
 $\mathbb{P}_x$,
 \[\mathbb{P}_x\biggl[\exp\biggl\{-\gamma\int_0^G\,\text{e}^{\alpha X_u} \,\text{d} u\biggr\}\mid \overline{X}_\textsf{e}\biggr]=\dfrac{\mathcal{I}^{p,\alpha}(\gamma\text{e}^{\alpha x})}{\mathcal{I}^{p,\alpha}(\gamma\text{e}^{\alpha \overline{X}_\textsf{e}})}.\]
In other words, for  $y\in (0,\infty)$, a.s.-
 $\mathbb{Q}_y$,
 \[\mathbb{Q}_y[\text{e}^{-\gamma L}\mid \overline{Y}_\infty]=\dfrac{\mathcal{I}^{p,\alpha}(\gamma y^\alpha)}{\mathcal{I}^{p,\alpha}(\gamma {\overline{Y}_\infty}^\alpha)}.\]
Remark 4.1 In the proof we will, en passant, establish the identity
 \[ \textsf{n}[1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}]=\Phi(p)-\dfrac{p}{\textsf d} \]
(recall that we interpret  $\textsf d=\infty$, hence
 ${{p}/{\textsf d}}=0$, when X has paths of infinite variation).
Proof. Without loss of generality we work under  $\mathbb{P}$: for
 $x\in \mathbb{R}$, the law of
 $(L,\overline{X}_\textsf{e})$ under
 $\mathbb{P}_x$ is that of
 $(\text{e}^{\alpha x}L,x+\overline{X}_\textsf{e})$ under
 $\mathbb{P}$. Then we are to determine, for
 $f\in \mathcal{B}_\mathbb{R}/\mathcal{B}_{[0,\infty]}$,
 \begin{align*} \mathcal A & \coloneqq \mathbb{P}\biggl[\exp\biggl\{-\gamma \int_0^G \,\text{e}^{\alpha X_u} \,\text{d} u\biggr\}f(\overline{X}_\textsf{e})\biggr]\\*
& =\mathbb{P} \biggl[\sum_{a\in \textsf D}\exp\biggl\{-\gamma \int_0^{\tau_{a-}^+} \,\text{e}^{\alpha X_u} \,\text{d} u\biggr\}f\big(\overline{X}_{\tau_{a-}^+}\big)\mathds{1}_{\{\tau_{a-}^+<\textsf{e}\leq \tau_a^+\}}\biggr]\\*
&\quad\, +\mathbb{P}\biggl[\exp\biggl\{-\gamma \int_0^G \,\text{e}^{\alpha X_u}\,\text{d} u\biggr\}f(\overline{X}_G);\, \overline{X}_\textsf{e}=X_\textsf{e}\biggr]. \end{align*}
Here the second term only appears when  $p>0$. From the Wiener–Hopf factorization, the event
 $\{\overline{X}_\textsf{e}=X_\textsf{e}\}$ is independent of the process X on the time interval [0,G), and (2.6)
 $\mathbb{P}(\overline{X}_\textsf{e}=X_\textsf{e})={{p}/{(\Phi(p) \textsf d)}}$. In consequence
 \begin{align*} \mathcal A\biggl(1-\dfrac{p}{\Phi(p)\textsf d}\biggr) & = \mathbb{P} \biggl[\sum_{a\in \textsf D}\exp\biggl\{-p \tau_{a-}^+-\gamma \int_0^{\tau_{a-}^+} \,\text{e}^{\alpha X_u} \,\text{d} u\biggr\}f\big(\overline{X}_{\tau_{a-}^+}\big) \big(1-\text{e}^{-p(\tau_a^+-\tau_{a-}^+\!)}\mathds{1}_{\{\tau_a^+<\infty\}}\big)\biggr]\\*
&=\mathbb{P} \biggl[\sum_{a\in \textsf D}\exp\biggl\{-p \tau_{a-}^+-\gamma \int_0^{\tau_{a-}^+} \,\text{e}^{\alpha X_u} \,\text{d} u\biggr\}f\big(\overline{X}_{\tau_{a-}^+}\big)\big(1-\text{e}^{-p\zeta(\varepsilon_a)}\mathds{1}_{\{\zeta(\varepsilon_a)<\infty\}}\big)\biggr]. \end{align*}
Now, by the absence of positive jumps,  $f(\overline{X}_{\tau_{a-}^+})=a$ for all
 $a\in (0,\infty)$ a.s.-
 $\mathbb{P}$. The compensation formula for
 $\varepsilon$ then entails that
 \begin{align*} \mathcal A\biggl(1-\dfrac{p}{\Phi(p)\textsf d}\biggr) &=\mathbb{P}\biggl[\int_0^{\overline{X}_\infty} \,\text{e}^{-p\tau_{a-}^+-\gamma\int_0^{\tau_{a-}^+}\text{e}^{\alpha X_u} \,\text{d} u}f(a) \,\text{d} a\biggr]\textsf{n}[1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}]\\*&=\textsf{n}[1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}]\mathbb{P}\biggl[\int_0^{\overline{X}_\infty} \,\text{e}^{-p\tau_a^+-\gamma\int_0^{\tau_{a}^+}\,\text{e}^{\alpha X_u} \,\text{d} u}f(a) \,\text{d} a\biggr]\\* & =\textsf{n}[1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}]\int_0^{\infty} \mathbb{P} \big[\text{e}^{-\gamma\int_0^{\tau_{a}^+}\,\text{e}^{\alpha X_u} \,\text{d} u};\, \tau_{a}^+<\textsf{e}\big]f(a) \,\text{d} a, \end{align*}
where the penultimate equality follows from the fact that  $\tau^+$ has at most countably many jump times, the set of which therefore has zero Lebesgue measure. Using (2.9) this can be expressed as
 \[\mathcal A\biggl(1-\dfrac{p}{\Phi(p)\textsf d}\biggr)=\textsf{n}[1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}]\int_0^{\infty}\dfrac{\mathcal{I}^{p,\alpha}(\gamma)}{\mathcal{I}^{p,\alpha}(\gamma\text{e}^{\alpha a})}f(a)\,\text{e}^{-\Phi(p)a} \,\text{d} a.\]
Taking  $\gamma=0$ and
 $f=1$ and plugging back in concludes the proof, since, under
 $\mathbb{P}$, the law of
 $\overline{X}_\textsf{e}$ is exponential of rate
 $\Phi(p)$. □
4.2 Law of J
Proposition 4.2. Assume X has paths of finite variation. For  $h\in \mathcal{B}_{({-}\infty,0]}/\mathcal{B}_{[0,\infty]}$,
 \[\mathbb{P}[h(X_G-\overline{X}_\textsf{e})]=\dfrac{1}{\Phi(p)\textsf d}\biggl[ph(0)+\int h(z)(1-\text{e}^{\Phi(p)z})\nu(\text{d} z)\biggr].\]
In other words, for  $g\in \mathcal{B}_{(0,1]}/\mathcal{B}_{[0,\infty]}$,
 \begin{equation}\mathbb{Q}[g(J)]=\dfrac{1}{\Phi(p)\textsf d}\biggl[pg(1)+\int g(\text{e}^z)(1-\text{e}^{\Phi(p)z})\nu(\text{d} z)\biggr].\end{equation}
Remark 4.2. Of course any  $\mathbb{P}_x$ (resp.
 $\mathbb{Q}_y$) may replace
 $\mathbb{P}$ (resp.
 $\mathbb{Q}$) in the above. In the proof we will see that
 $\nu/\textsf d$ is the law of
 $\xi_0$ under
 $\textsf{n}$ (which is otherwise a known fact [Reference Rogers20]; we include the (short) argument for completeness).
Proof. Let  $f\in \mathcal{B}_\mathbb{R}/\mathcal{B}_{[0,\infty]}$. By the compensation formulas for
 $\varepsilon$ and
 $\Delta X$, for any (arbitrary)
 $q\in (0,\infty)$, we have
 \begin{align*} q \textsf{n}[f(\xi_0)]\Phi(q)^{-1} & =q\mathbb{P}\biggl[\sum_{a\in \textsf D}\,\text{e}^{-q\tau_{a-}^+}f(\varepsilon_a(0))\biggr]\\[2pt]
& =q\mathbb{P}\biggl[\sum_{t\in \textsf J}\,\text{e}^{-q t}\mathds{1}_{\{\overline{X}_{t-}=X_{t-}\}}f(\Delta X_t)\biggr]\\[2pt]
&=\mathbb{P}\biggl[\int_0^\infty \mathds{1}_{\{\overline{X}_{t-}=X_{t-}\}}q \,\text{e}^{-q t} \,\text{d} t\biggr]\nu[\kern1.5ptf]\\[2pt]
&=\mathbb{P}\biggl[\int_0^\infty \mathds{1}_{\{\overline{X}_{t}=X_{t}\}}q \,\text{e}^{-q t} \,\text{d} t\biggr]\nu[\kern1.5ptf]\\[2pt]
&=\dfrac{q}{\Phi(q) \textsf d}\nu[\kern1.5ptf]. \end{align*}
Let h be bounded. As in the proof of Proposition 4.1, we compute
 \begin{align*} \mathbb{P}[h(X_G-\overline{X}_\textsf{e})]&=\mathbb{P} \biggl[\sum_{a\in \textsf D}h(\varepsilon_a(0))\mathds{1}_{\{\tau_{a-}^+<\textsf{e}\leq \tau_a^+\}}\biggr]+h(0)\mathbb{P}(\overline{X}_\textsf{e}=X_\textsf{e})\\[2pt] &=\mathbb{P}\biggl[\sum_{a\in \textsf D}\,\text{e}^{-p\tau_{a-}^+}h(\varepsilon_a(0))(1-\text{e}^{-p\zeta(\varepsilon_a)}\mathds{1}_{\{\zeta(\varepsilon_a)<\infty\}})\biggr]+h(0)\dfrac{p}{\Phi(p)\textsf d}\\[2pt] &=\mathbb{P}\biggl[\int_0^{\overline{X}_a}\,\text{e}^{-p\tau_{a-}^+} \,\text{d} a\biggr]\textsf{n} [h(\xi_0)(1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}})]+h(0)\dfrac{p}{\Phi(p)\textsf d}\\[2pt] &=\Phi(p)^{-1}\lim_{t\downarrow 0}\textsf{n}[h(\xi_0)(1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}});\, t<\zeta]+h(0)\dfrac{p}{\Phi(p)\textsf d}\\[2pt] &=\Phi(p)^{-1}\lim_{t\downarrow 0}\textsf{n}[h(\xi_0)\,\text{e}^{-pt}(1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}})\circ \theta_t;\, t<\zeta]+h(0)\dfrac{p}{\Phi(p)\textsf d}\\[2pt] &=\Phi(p)^{-1}\lim_{t\downarrow 0}\textsf{n}[h(\xi_0)\mathbb{P}_{\xi_t}[1-\text{e}^{-p\tau_0^+}\mathds{1}_{\{\tau_0^+<\infty\}})];\, t<\zeta]+h(0)\dfrac{p}{\Phi(p)\textsf d}\\[2pt] &=\Phi(p)^{-1}\lim_{t\downarrow 0}\textsf{n}[h(\xi_0)(1-\text{e}^{\Phi(p)\xi_t});\, t<\zeta]+h(0)\dfrac{p}{\Phi(p)\textsf d}\\[2pt] &=\Phi(p)^{-1}\textsf{n}[h(\xi_0)(1-\text{e}^{\Phi(p)\xi_0})]+h(0)\dfrac{p}{\Phi(p)\textsf d}{.} \end{align*}
Here the fifth equality follows by dominated convergence since
 \[(1-\text{e}^{-pt})\mathds{1}_{\{t<\zeta\}}\leq 1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}\quad\text{and}\quad\textsf{n}[1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}]<\infty{,}\]
the antepenultimate equality is by the Markov property of  $\textsf{n}$, and the final equality is by dominated convergence since
 \[(1-\text{e}^{\Phi(p)\xi_t})\mathds{1}_{\{t<\zeta\}}\leq (1-\text{e}^{\Phi(p)\underline{\xi}_{\zeta}})\]
and
 \[\textsf{n}[1-\text{e}^{\Phi(p)\underline{\xi}_{\zeta}}]=\int_0^\infty \Phi(p)\,\text{e}^{-\Phi(p)a}\textsf{n}\Big({-}\underline{\xi}_{\zeta}>a\Big) \,\text{d} a,\]
which quantity is finite when X has paths of finite variation, as follows from (2.8) and the fact that in this case  $W(0)>0$. By the first part of this proof the claims follow. □
4.3 Laplace transform of $T_0-L$ given $\overline{Y}_\infty$ and J


The following definition will allow us to state our next result more succinctly. Recall the notation of Section 2.5.
Definition 4.1. For  $\beta\in[0,\infty)$ and
 $ y\in (0,\infty)$, set
 \[\mathcal{N}^{p,\alpha}_\beta(y)\coloneqq \mathcal{J}^{p,\alpha}(\beta y^\alpha)+\dfrac{\alpha}{\Phi(p)}\biggl[\dfrac{\mathcal{J}^{p,\alpha}(\beta y^\alpha)}{\mathcal{I}^{p,\alpha}(\beta y^\alpha)}\sum_{k=1}^\infty k\textsf{b}^{p,\alpha}_k(\beta y^\alpha)^k-\sum_{k=1}^\infty k\textsf{a}^{p,\alpha}_k(\beta y^\alpha)^k\biggr],\]
where the expression must be understood in the limiting sense (as  $\alpha\to \Phi(p)/m$), when
 $\Phi(p)=\alpha m$ for some
 $m\in \mathbb{N}$: the limit is seen to exist and identified in Remark 4.3 to follow.
Remark 4.3. Suppose  $\Phi(p)=m\alpha$ for an
 $m\in \mathbb{N}$. Then, for
 \[ \alpha'\in \biggl(\dfrac{\Phi(p)}{m+1},\dfrac{\Phi(p)}{m-1}\biggr)\bigg\backslash \biggl\{\dfrac{\Phi(p)}{m}\biggr\}, \]
provisionally setting
 \[ \widetilde{\textsf{b}^{p,\alpha'}_k}\coloneqq \biggl(\prod_{l=1}^k(\psi(m\alpha'+l\alpha')-p)\biggr)^{-1}\quad {\text{for $k\in \mathbb{N}_0$,}} \]
we may write
 \begin{align*} & \mathcal{N}^{p,\alpha'}_\beta(y)\\[2pt] &\quad =\sum_{k=0}^{m-1}\textsf{a}^{p,\alpha'}_k (\beta y^{\alpha'}\!)^k+\dfrac{\alpha'}{\Phi(p)}\biggl[\dfrac{\sum_{k=0}^{m-1}\textsf{a}^{p,\alpha'}_k (\beta y^{\alpha'}\!)^k}{\mathcal{I}^{p,\alpha}(\beta y^{\alpha'}\!)}\sum_{k=1}^\infty k\textsf{b}^{p,\alpha'}_k(\beta y^{\alpha'}\!)^k - \sum_{k=1}^{m-1}k\textsf{a}^{p,\alpha'}_k(\beta y^{\alpha'}\!)^k\biggr] \\* &\quad\quad\, + \dfrac{\textsf{a}^{p,\alpha'}_{m-1}(\beta y^{\alpha'}\!)^m}{\psi(\alpha' m)-p} \biggl[ \sum_{k=0}^\infty \widetilde{\textsf{b}^{p,\alpha'}_k} (\beta y^{\alpha'}\!)^k +\dfrac{\alpha'}{\Phi(p)} \\* &\quad \quad\, \times \biggl(\dfrac{\sum_{k=0}^\infty \widetilde{\textsf{b}^{p,\alpha'}_k} (\beta y^{\alpha'}\!)^k}{\mathcal{I}^{p,\alpha}(\beta y^{\alpha'}\!)} \sum_{k=1}^\infty k\textsf{b}^{p,\alpha'}_k (\beta y^{\alpha'}\!)^k- \sum_{k=0}^\infty \widetilde{\textsf{b}^{p,\alpha'}_k} (\beta y^{\alpha'}\!)^k(k+m) \biggr) \biggr]\\&\quad \xrightarrow{\alpha'\to \alpha}\sum_{k=0}^{m-1}\textsf{a}^{p,\alpha}_k (\beta y^{\alpha})^k+\dfrac{\alpha}{\Phi(p)}\biggl[\dfrac{\sum_{k=0}^{m-1}\textsf{a}^{p,\alpha}_k (\beta y^{\alpha})^k}{\mathcal{I}^{p,\alpha}(\beta y^{\alpha})}\sum_{k=1}^\infty k\textsf{b}^{p,\alpha}_k(\beta y^{\alpha})^k-\sum_{k=1}^{m-1}k\textsf{a}^{p,\alpha}_k(\beta y^{\alpha})^k\biggr]\\ &\quad\quad\, +\dfrac{\textsf{a}^{p,\alpha}_{m-1}(\beta y)^{\alpha m}}{\psi'(\Phi(p))\Phi(p)}\biggl[\alpha\biggl(1-\dfrac{\sum_{k=1}^\infty k \textsf{b}^{p,\alpha}_k(\beta y^\alpha)^k}{\mathcal{I}^{p,\alpha}(\beta y^\alpha)}\biggr)\sum_{k=1}^\infty\textsf{c}^{p,\alpha}_k(\beta y^\alpha)^k-\mathcal{I}^{p,\alpha}(\beta y^\alpha)\biggr]\\* &\quad=\mathcal{N}^{p,\alpha}_\beta(y) \end{align*}
(recall the  $\textsf{c}^{p,\alpha}_k$ from Remark 3.3).
Proposition 4.3. Let  $\beta\in [0,\infty)$.
(i) If X has finite variation, then for all
$x\in \mathbb{R}$, a.s.-$\mathbb{P}_x$,
In other words, for all
\begin{equation*}\mathbb{P}_x [ \text{e}^{-\beta\int_G^\textsf{e} \,\text{e}^{\alpha X_u} \,\text{d} u}\mid \overline{X}_\textsf{e},X_G] = \dfrac{\mathcal{M}^{p,\alpha}_\beta( \text{e}^{ X_G}, \text{e}^{ \overline{X}_\textsf{e}})}{1-\text{e}^{\Phi(p)(X_G-\overline{X}_\textsf{e})}}\mathds{1}_{({-}\infty,0)} (X_G-\overline{X}_\textsf{e})+\mathds{1}_{\{0\}} (X_G-\overline{X}_\textsf{e}){.}\end{equation*}
$y\in (0,\infty)$, a.s.-$\mathbb{Q}_y$,
\begin{equation*}\mathbb{Q}_y[ \text{e}^{-\beta(T_0-L)}\mid \overline{Y}_\infty,J]=\dfrac{\mathcal{M}^{p,\alpha}_\beta(\overline{Y}_\infty J,\overline{Y}_\infty)}{1-J^{\Phi(p)}}\mathds{1}_{(0,1)}(J)+\mathds{1}_{\{1\}}(J).\end{equation*}
-
(ii) If X has infinite variation, then for all
$x\in \mathbb{R}$, a.s.-$\mathbb{P}_x$,
In other words, for all
\begin{equation*}\mathbb{P}_x[ \text{e}^{-\beta\int_G^\textsf{e} \,\text{e}^{\alpha X_u} \,\text{d} u}\mid \overline{X}_\textsf{e}]=\mathcal{N}^{p,\alpha}_\beta(\text{e}^{\overline{X}_\textsf{e}}){.}\end{equation*}
$y\in (0,\infty)$, a.s.-$\mathbb{Q}_y$,
\begin{equation*}\mathbb{Q}_y[ \text{e}^{-\beta(T_0-L)}\mid \overline{Y}_\infty]=\mathcal{N}^{p,\alpha}_\beta(\overline{Y}_\infty).\end{equation*}


Remark 4.4. Recall that  $\overline{X}_\textsf{e}=X_G$, i.e.
 $J=1$, a.s. when X has paths of infinite variation.
Remark 4.5. In the course of the proof we establish, en passant, that the  $\textsf{k}$ from (2.7) is equal to 1.
Proof. Again we may work without loss of generality under  $\mathbb{P}$. Let f and h be bounded functions from
 $\mathcal{B}_{\mathbb{R}}/\mathcal{B}_{[0,\infty)}$. We compute
 \begin{align*} & \mathbb{P}[\text{e}^{-\beta\int_G^\textsf{e} \,\text{e}^{\alpha X_u} \,\text{d} u}h(X_G-\overline{X}_\textsf{e})f(\overline{X}_\textsf{e})]\\* &\quad =\mathbb{P} \biggl[ \sum_{a\in \textsf D}\exp \biggl\{-\beta \,\text{e}^{\alpha \overline{X}_{\tau_{a-}^+}} \int_0^{\textsf{e}-\tau_{a-}^+} \,\text{e}^{\alpha \varepsilon_a(u)} \,\text{d} u\biggr\} h(\varepsilon_a(0))f(\overline{X}_{\tau_{a-}^+})\mathds{1}_{\{\tau_{a-}^+
< \textsf{e}\leq \tau_a^+\}} \biggr] \\* &\quad\quad\, +\mathbb{P} [h(0)f(\overline{X}_\textsf{e});\, \overline{X}_\textsf{e}=X_\textsf{e}]\\ &\quad =\mathbb{P}\biggl[\sum_{a\in \textsf D}\,\text{e}^{-p\tau_{a-}^+}\exp\biggl\{-\beta \,\text{e}^{\alpha \overline{X}_{\tau_{a-}^+}}\int_0^{\textsf{e}} \,\text{e}^{\alpha \varepsilon_a(u)} \,\text{d} u\biggr\}h(\varepsilon_a(0))f(a)\mathds{1}_{\{\textsf{e}\leq \zeta(\varepsilon_a)\}}\biggr]\\* &\quad\quad\, +h(0)\mathbb{P}[f(\overline{X}_\textsf{e})]\mathbb{P}(\overline{X}_\textsf{e}=X_\textsf{e})\\ &\quad =\int_0^\infty \,\text{e}^{-\Phi(p)a}f(a)\int \textsf{n}[\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_u}h(\xi_0);\, u\leq \zeta]\,\text{Exp}_p(\text{d} u)\,\text{d} a \\* &\quad\quad\, +h(0)\int_0^\infty\Phi(p) \,\text{e}^{-\Phi(p)a}f(a) \,\text{d} a \dfrac{p}{\Phi(p)\textsf d}.\end{align*}
Here the second term in the second line (and subsequent lines) appears only if  $p>0$, the penultimate equality is by the memoryless property of the exponential distribution and because X is independent of
 $\textsf{e}$, and
 $\text{Exp}_p$ is the exponential law of rate p on
 $\mathcal{B}_{(0,\infty]}$. Thus it remains to determine, for
 $a\in [0,\infty)$,
 \begin{align*} \mathfrak{O} & \coloneqq \int \textsf{n}[\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_u}h(\xi_0);\, u\leq \zeta]\,\text{Exp}_p(\text{d} u) \\*
&= \lim_{t\downarrow 0}\int \textsf{n}[\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_u}h(\xi_0);\, t \lt u\leq \zeta] \,\text{Exp}_p(\text{d} u)\\*
& =\lim_{t\downarrow 0}\int_{(t,\infty]} \textsf{n}[\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_t}h(\xi_0)(\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_{u-t}}\mathds{1}_{\{\zeta\geq u-t\}})\circ\theta_t;\, t<\zeta]\,\text{Exp}_p(\text{d} u)\\& =\lim_{t\downarrow 0}\int_{(t,\infty]} \textsf{n}[h(\xi_0)(\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_{u-t}}\mathds{1}_{\{\zeta\geq u-t\}})\circ\theta_t;\, t<\zeta]\,\text{Exp}_p(\text{d} u)\\& =\lim_{t\downarrow 0}\int_{(t,\infty]} \textsf{n}[h(\xi_0)(\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_{u-t}}\mathds{1}_{\{\zeta\geq u-t\}})\circ\theta_t;\, t<\zeta]\,\text{e}^{pt}\,\text{Exp}_p(\text{d} u)\\& =\lim_{t\downarrow 0}\int \textsf{n}[h(\xi_0)(\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_{v}}\mathds{1}_{\{\zeta\geq v\}})\circ\theta_t;\, t<\zeta]\,\text{Exp}_p( \text{d} v)\\& =\lim_{t\downarrow 0}\int \textsf{n} [h(\xi_0)\mathbb{P}_{\xi_t}[\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_v};\, \tau_0^+\geq v];\, t<\zeta]\,\text{Exp}_p( \text{d} v)\\& =\lim_{t\downarrow 0} \textsf{n} [h(\xi_0)\mathbb{P}_{\xi_t}[\text{e}^{-\beta \,\text{e}^{\alpha a}\text{I}_\textsf{e}};\, \tau_0^+\geq \textsf{e}];\, t<\zeta]\\*&=\lim_{t\downarrow 0}\textsf{n} [h(\xi_0)\mathcal{M}^{p,\alpha}_\beta( \text{e}^{a+\xi_t}, \text{e}^{ a});\, t<\zeta]{.} \end{align*}
Here the second line follows by monotone convergence, the fourth line is obtained by dominated convergence, since  $\textsf{n}(\zeta\geq u)<\infty$ for each
 $u\in (0,\infty]$ and moreover
 $\textsf{n}[1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}]<\infty$, and we used (3.1) in the last equality.
Suppose first that X is of finite variation. We know already from the proof of Proposition 4.2 that  $\textsf{n}[1-\text{e}^{\Phi(p)\underline{\xi}_{\zeta}}]<\infty$. Since, for
 $t\in (0,\infty)$,
 \[ \mathcal{M}^{p,\alpha}_\beta(\text{e}^{a+\xi_t},\text{e}^{ a})\leq 1-\text{e}^{\Phi(p)\xi_t}\leq 1-\text{e}^{\Phi(p)\underline{\xi}_{\zeta}}\quad \text{on $\{t<\zeta\}$,} \]
it follows by dominated convergence that
 \[\mathfrak{O}=\textsf{n}[h(\xi_0)\mathcal{M}^{p,\alpha}_\beta( \text{e}^{a+\xi_0}, \text{e}^{ a})].\]
Hence, using the fact that under  $\mathbb{P}$ the random variable
 ${\overline{X}_\textsf{e}}$ is exponential of rate
 $\Phi(p)$, Proposition 4.2, Remark 4.2, and the independence of
 $\overline{X}_\textsf{e}$ from
 $X_G-\overline{X}_\textsf{e}$, it follows that
 \begin{align*} &\mathbb{P}[\text{e}^{-\beta\int_G^\infty \,\text{e}^{\alpha X_u} \,\text{d} u}h(X_G-\overline{X}_\textsf{e})f(\overline{X}_\infty)]\\[3pt] &\quad =\mathbb{P}\biggl[f(\overline{X}_\infty)h(X_G-\overline{X}_\infty)\biggl(\dfrac{\mathcal{M}^{p,\alpha}_\beta( \text{e}^{ X_G}, \text{e}^{ \overline{X}_\textsf{e}})}{1-\text{e}^{\Phi(p)(X_G-\overline{X}_\textsf{e})}}\mathds{1}_{({-}\infty,0)}(X_G-\overline{X}_\textsf{e})+\mathds{1}_{\{0\}}(X_G-\overline{X}_\textsf{e})\biggr)\biggr]\end{align*}
and (i) is proved.
Now let X be of infinite variation; take  $h=1$. Because the coordinate projection
 $(\mathbb D\ni \xi\mapsto \xi_t)$ is continuous in the Skorokhod topology at all paths for which
 $t\in (0,\infty)$ is a continuity point, and in particular (by the Markov property of
 $\textsf{n}$ and since X has no fixed points of discontinuity a.s.)
 $\textsf{n}$-a.e., it follows from (2.7) that
 \[\mathfrak{O}=\textsf{k}\lim_{t\downarrow 0}\lim_{x\uparrow 0} \dfrac{\mathbb{P}_x[\mathcal{M}^{p,\alpha}_\beta( \text{e}^{a+X_t}, \text{e}^{ a});\, t<\tau_0^+]}{\textsf{g}(x)}.\]
Hence the expression inside the limit  $\lim_{t\downarrow 0}$, say r(t), is bounded by
 $\textsf{n}[1-\text{e}^{-p\zeta}\mathds{1}_{\{\zeta<\infty\}}]\,\text{e}^{pt}$, and the limit
 $\lim_{t\downarrow 0}r(t)$ exists a priori. Then
 \[\lim_{q\to\infty}\int_0^\infty \,\text{e}^{-q t}q r(t) \,\text{d} t=\lim_{q\to\infty}\dfrac{q}{q-p}\int_0^\infty \,\text{e}^{-(q-p) t}(q-p) \,\text{e}^{-pt}r(t) \,\text{d} t=r(0+\!),\]
and since  $\lim_{x\downarrow 0}{{\textsf{g}(x)}/{({-}x)}}=1$, we obtain
 \[\mathfrak{O}=\textsf{k} \lim_{q \to\infty}\int_0^\infty q \,\text{e}^{-q t}\lim_{x\uparrow 0} \dfrac{\mathbb{P}_x[\mathcal{M}^{p,\alpha}_\beta( \text{e}^{a+X_t}, \text{e}^{ a});\, t<\tau_0^+]}{-x} \,\text{d} t.\]
Moreover, for all  $t\in (0,\infty)$,
 \[\mathcal{M}^{p,\alpha}_\beta( \text{e}^{a+X_t}, \text{e}^{ a})\leq 1-\text{e}^{\Phi(p)X_t}\quad \text{on $\{t<\tau_0^+\}$,}\]
and since
 \begin{align*}\mathbb{P}_x[1-\text{e}^{\Phi(p)X_t};\, t<\tau_0^+] = \mathbb{P}_x[(1-\text{e}^{-p(\tau_0^+-t)}\mathds{1}_{\{\tau_0^+<\infty\}});\, t<\tau_0^+] \leq \mathbb{P}_x(\textsf{e}\leq \tau_0^+\!)=1-\text{e}^{\Phi(p)x},\end{align*}
dominated convergence yields
 \begin{align} \mathfrak{O}& =\textsf{k} \lim_{q \to\infty}\lim_{x\uparrow 0} \dfrac{\int_0^\infty q \,\text{e}^{-q t}\mathbb{P}_x [\mathcal{M}^{p,\alpha}_\beta( \text{e}^{a+X_t}, \text{e}^{ a});\, t<\tau_0^+] \,\text{d} t}{-x} \notag \\[3pt] &=\textsf{k} \lim_{q \to\infty}q \lim_{x\downarrow 0}\int_{0}^\infty\mathcal{M}^{p,\alpha}_\beta( \text{e}^{a-y}, \text{e}^{ a})\dfrac{\text{e}^{-\Phi(q)x}W^{(q)}(y)-W^{(q)}(y-x)}{x} \,\text{d} y,\end{align}
by (2.4).
Next, as the integral of a resolvent density, for all  $q\in(0,\infty)$ and all
 $x\in (0,\infty)$, we have that
 \[\int_{0}^\infty \,\text{e}^{-\Phi(q)x}W^{(q)}(y)-W^{(q)}(y-x) \,\text{d} y\]
is finite. At the same time we know from (2.5) that
 \begin{equation}(\psi(\lambda)-q)\int_0^\infty \,\text{e}^{-\lambda y}(\text{e}^{-\Phi(q)x}W^{(q)}(y)-W^{(q)}(y-x)) \,\text{d} y=\text{e}^{-\Phi(q)x}-\text{e}^{-\lambda x}\end{equation}
at least for  $\lambda\in (\Phi(q),\infty)$. But by the theorems of Cauchy, Morera, and Fubini, the left-hand side and clearly the right-hand side are analytic, or can be extended to analytic functions in
 $\lambda\in \{z\in \mathbb{C}\colon \Re z>0\}$. Hence, by the principle of permanence for analytic function, the equality (4.3) prevails for
 $\lambda\in (0,\infty)$. Taking limits, by monotone convergence and continuity, we conclude that
 \[\int_0^\infty \,\text{e}^{-\lambda y}(\text{e}^{-\Phi(q)x}W^{(q)}(y)-W^{(q)}(y-x)) \,\text{d} y=\dfrac{\text{e}^{-\Phi(q)x}-\text{e}^{-\lambda x}}{\psi(\lambda)-q}\]
for all  $\lambda\in [0,\infty)$, provided the right-hand side is interpreted in the limiting sense at
 $\lambda=\Phi(q)$.
Consequently, integrating term by term (via linearity and monotone or dominated convergence) in (4.2), we obtain, assuming  $\Phi(p)\notin\alpha\mathbb{N}$,
 \begin{align*} \mathfrak{O} & = \textsf{k} \lim_{q \to\infty}^{*} q \lim_{x\downarrow 0} \, x^{-1}\biggl( \sum_{k=0}^\infty \textsf{a}^{p,\alpha}_k (\beta \,\text{e}^{\alpha a})^k \,\dfrac{\text{e}^{-\Phi(q)x} -\text{e}^{-\alpha k x}}{\psi(\alpha k)-q} \\* &\quad\, - \dfrac{\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}{\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha a})} \sum_{k=0}^\infty \textsf{b}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a}) ^k\, \dfrac{\text{e}^{-\Phi(q)x} -\text{e}^{-(\Phi(p)+k\alpha) x}}{\psi(\Phi(p)+k\alpha)-q}\biggr), \end{align*}
where  $\overset{*}{\lim}$ indicates that we take the limit along a sequence
 $(q_k)_{k\in \mathbb{N}_0}$ that uniformly (we use this for convenience later on when arguing dominated convergence) avoids the grid
 $\psi(\alpha\mathbb{N}_0\cup (\Phi(p)+\alpha\mathbb{N}_0))$.
Then, by dominated convergence (recall the elementary estimate  $1-\text{e}^{-u}\leq u$,
 $u\in [0,\infty)$),
 \begin{align*} \mathfrak{O} & =\textsf{k} \lim_{q \to\infty}^{*}q \biggl[\sum_{k=0}^\infty \textsf{a}^{p,\alpha}_k (\beta \,\text{e}^{\alpha a})^k\dfrac{\alpha k-\Phi(q)}{\psi(\alpha k)-q}-\dfrac{\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}{\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}\sum_{k=0}^\infty \textsf{b}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a}) ^k\dfrac{\Phi(p)+k\alpha-\Phi(q)}{\psi(\Phi(p)+k\alpha)-q}\biggr]\\*
& =\textsf{k} \lim_{q \to\infty}^*q\biggl[\sum_{k=0}^\infty \textsf{a}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\biggl(\dfrac{\alpha k-\Phi(q)}{\psi(\alpha k)-q}-\dfrac{\Phi(q)}{q}\biggr)\\*
&\quad\, -\dfrac{\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}{\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}\sum_{k=0}^\infty \textsf{b}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\biggl(\dfrac{\Phi(p)+\alpha k-\Phi(q)}{\psi(\Phi(p)+k\alpha)-q}-\dfrac{\Phi(q)}{q}\biggr)\bigg]\\
&=\textsf{k} \lim_{q \to\infty}^{*}\biggl[\sum_{k=0}^\infty \textsf{a}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\dfrac{q\alpha k}{\psi(\alpha k)-q}-\dfrac{\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}{\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}\sum_{k=0}^\infty \textsf{b}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\dfrac{q(\Phi(p)+\alpha k)}{\psi(\Phi(p)+k\alpha)-q}\biggr]\\&\quad\, +\textsf{k} \lim_{q \to\infty}^{*}\sum_{k=0}^\infty \textsf{a}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\biggl(\dfrac{(\alpha k-\Phi(q))\psi(\alpha k)}{\psi(\alpha k)-q}-\dfrac{\alpha k\psi(\alpha k)}{\psi(\alpha k)-q}\biggr)\\* &\quad\, -\textsf{k}\dfrac{\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}{\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha a})} \lim_{q \to\infty}^{*} \sum_{k=0}^\infty \textsf{b}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k \\* &\quad\, \times \biggl(\dfrac{(\alpha k+\Phi(p)-\Phi(q))\psi(\alpha k+\Phi(p))}{\psi(\alpha k+\Phi(p))-q}-\dfrac{(\alpha k+\Phi(p))\psi(\alpha k+\Phi(p))}{\psi(\alpha k+\Phi(p))-q} \biggr)\\&=\textsf{k} \lim_{q \to\infty}^{*}\biggl[\sum_{k=0}^\infty \textsf{a}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\dfrac{q\alpha k}{\psi(\alpha k)-q}-\dfrac{\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}{\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}\sum_{k=0}^\infty \textsf{b}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\dfrac{q(\Phi(p)+\alpha k)}{\psi(\Phi(p)+k\alpha)-q}\biggr]\\&=\textsf{k} \lim_{q \to\infty}^{*}\sum_{k=0}^\infty \textsf{a}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\biggl(\dfrac{q\alpha k}{\psi(\alpha k)-q}+\alpha k-\alpha k\biggr)\\* &\quad\, -\textsf{k} \dfrac{\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}{\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}\lim_{q \to\infty}^{*}\sum_{k=0}^\infty \textsf{b}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\\* &\quad\, \times \biggl(\dfrac{q(\Phi(p)+\alpha k)}{\psi(\Phi(p)+k\alpha)-q}+\Phi(p)+\alpha k-(\Phi(p)+\alpha k)\biggr)\\* &=\textsf{k}\biggl[\dfrac{\mathcal{J}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}{\mathcal{I}^{p,\alpha}(\beta \,\text{e}^{\alpha a})}\sum_{k=0}^\infty \textsf{b}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k(\Phi(p)+\alpha k)-\sum_{k=1}^\infty \textsf{a}^{p,\alpha}_k(\beta \,\text{e}^{\alpha a})^k\alpha k\biggr], \end{align*}
where the antepenultimate equality is by dominated convergence, noting that
 \[ \dfrac{z-w}{\psi(z)-\psi(w)} \]
is bounded in  $z\ne w$,
 $\{z,w\}\subset [\Phi(p),\infty)$ by the strict convexity of
 $\psi$, and that
 \[ \lim_{q\to\infty}\dfrac{\Phi(q)}{q}=0 \]
because  $\lim_\infty\psi'= \infty$. The last equality is again by dominated convergence. Plugging in
 $f=1$,
 $\beta=0$, we identify
 $\textsf{k}=1$. The case
 $\Phi(p)\in \alpha\mathbb{N}$ follows by taking limits. □
4.4 Conditional temporal splitting at the maximum
Combining our results, we arrive at the following (recall the notation of Definitions 3.1 and 4.1).
Theorem 4.1. Let  $\beta\in [0,\infty)$.
(1) Let X be of finite variation. Then the random variables L and
$T_0-L$ are independent given $\overline{Y}_\infty$ and J (and also just given $\overline{Y}_\infty$), which in turn are independent. Moreover, the law of J is given by (4.1), and for all $y\in \mathbb{R}$, we have the conditional factorization
where the two factors either side of
\[ \mathbb{Q}_y[\text{e}^{-\beta T_0}\mid \overline{Y}_\infty,J]=\dfrac{\mathcal{I}^{p,\alpha}(\beta y^\alpha)}{\mathcal{I}^{p,\alpha}(\beta {\overline{Y}_\infty}^\alpha)}\times \biggl[\dfrac{\mathcal{M}^{p,\alpha}_\beta(\overline{Y}_\infty J,\overline{Y}_\infty)}{1-J^{\Phi(p)}}\mathds{1}_{(0,1)}(J)+\mathds{1}_{\{1\}}(J)\biggr]\quad {a.s.\text{-$\mathbb{Q}_y$,}} \]
$\times$ correspond to the conditional expectations
respectively.
\[ \mathbb{Q}_y[\text{e}^{-\beta L}\mid \overline{Y}_\infty]\overset{\text{a.s.-$\mathbb{Q}_y$}}{=}\mathbb{Q}_y[\text{e}^{-\beta L}\mid \overline{Y}_\infty,J] \quad {and}\quad \mathbb{Q}_y[\text{e}^{-\beta (T_0-L)}\mid \overline{Y}_\infty,J], \]
-
(2) Let X be of infinite variation. Then
$J=1$ a.s., the random variables L and $T_0-L$ are independent given $\overline{Y}_\infty$, and for all $y\in \mathbb{R}$, we have the conditional factorization
where the two factors either side of
\[ \mathbb{Q}_y[\text{e}^{-\beta T_0}\mid \overline{Y}_\infty]=\dfrac{\mathcal{I}^{p,\alpha}(\beta y^\alpha)}{\mathcal{I}^{p,\alpha}(\beta {\overline{Y}_\infty}^\alpha)}\times\mathcal{N}^{p,\alpha}_\beta(\overline{Y}_\infty)\quad {a.s.\text{-$\mathbb{Q}_y$,}} \]
$\times$ correspond to the conditional expectations
respectively.
\[ \mathbb{Q}_y[\text{e}^{-\beta L}\mid \overline{Y}_\infty] \quad {and}\quad \mathbb{Q}_y[\text{e}^{-\beta (T_0-L)}\mid \overline{Y}_\infty], \]


In either case the law of  $\log(\overline{Y}_\infty/Y_0)$ is exponential of rate
 $\Phi(p)$.
Proof. Items (1) and (2) follow from Propositions 4.2, 4.1, and 4.3, and from the comments concerning the (conditional) independences in  $(L,\overline{Y}_\infty,J,T_0-L)$ made in the Introduction (as a consequence of the independence statement of the Wiener–Hopf factorization for X). The final statement is simply a consequence of
 $\log(\overline{Y}_\infty/Y_0)=\overline{X}_\textsf{e}-X_0$. □
Remark 4.6. It is clear from their defining representation as power series in Section 2.5, that the functions  $\mathcal{I}^{p,\alpha}$ and
 $\mathcal{J}^{p,\alpha}$ as well as their first derivatives will be given in terms of generalized hypergeometric functions whenever
 $\psi$ is rational. Recalling Definitions 3.1 and 4.1, these are then, in turn, trivially combined into
 $\mathcal{M}^{p,\alpha}_\beta$ and
 $\mathcal{N}^{p,\alpha}_\beta$, except in ‘degenerate’ cases corresponding to
 $\Phi(p)\in \alpha\mathbb{N}$, when another limit intervenes. See [Reference Kuznetsov, Kyprianou and Rivero13, Section 5.4] for X with jumps of rational transform (which is equivalent to
 $\psi$ being rational); one such process is illustrated in Figure 1. In special cases the hypergeometric functions may themselves be expressed in terms of more elementary functions.
The function  $(0,1)\ni j\mapsto {{\mathcal{M}^{p,\alpha}_\beta(j,1)}/{(1-j^{\Phi(p)}})}$ for
 $\alpha=2$,
 $p=1$, and
 $\psi(\lambda)=\lambda-{{\lambda}/{(\lambda+1)}}$,
 $\lambda\in [0,\infty)$, corresponding to X being the difference of a unit drift and of a homogeneous Poisson process of unit intensity.

Example 4.1. Let us take an instance of the situation described in the above remark:  $\psi(\lambda)={{\lambda^2}/{2}}-{{\lambda}/{2}}$ for
 $\lambda\in [0,\infty)$,
 $\alpha=2$, and
 $p=0$. It is well known that it corresponds to Y being Brownian motion stopped on hitting zero. Note that
 $\Phi(p)=\Phi(0)=1\notin 2\mathbb{N}=\alpha\mathbb{N}$. For this example – admittedly the simplest one could think of – the expressions for the functions are compact enough to warrant an explicit presentation. For
 $y\in (0,\infty)$ and
 $\beta\in [0,\infty)$ we indeed obtain
 \[\mathcal{J}^{p,\alpha}(y)=\cosh(\sqrt{2y}),\quad \mathcal{I}^{p,\alpha}(y)=\dfrac{\sinh(\sqrt{2y})}{\sqrt{2y}},\quad \text{and}\quad\mathcal{N}^{p,\alpha}_\beta(y)=\dfrac{\sqrt{2\beta} y}{\sinh(\sqrt{2\beta} y)}{,}\]
and therefore
 \[\mathbb{Q}_y[\text{e}^{-\beta T_0}\mid \overline{Y}_\infty]=\dfrac{\overline{Y}_\infty}{y}\dfrac{\sinh(y\sqrt{2\beta} )}{\sinh(\overline{Y}_\infty\sqrt{2\beta} )}\times \dfrac{\overline{Y}_\infty\sqrt{2\beta}}{\sinh(\overline{Y}_\infty\sqrt{2\beta} )}\quad \text{a.s.-$\mathbb{Q}_y$,}\]
where the two factors either side of  $\times$ correspond to the conditional expectations
 $\mathbb{Q}_y[\text{e}^{-\beta L}\mid \overline{Y}_\infty]$ and
 $\mathbb{Q}_y[\text{e}^{-\beta (T_0-L)}\mid \overline{Y}_\infty]$, respectively. As a check, using that
 $\log(\overline{Y}_\infty/Y_0)$ is exponential of rate
 $\Phi(p)$, we compute the
 $\mathbb{Q}_y$ integral of the right-hand side of the above identity to get
 $\text{e}^{-\sqrt{2\beta} y}$, which is the well-known Laplace transform of
 $\mathbb{Q}_y[\text{e}^{-\beta T_0}]$ (as it should be). Incidentally, it means that the constant
 $C^{p,\alpha}$ in Remark 3.5 is equal to
 $\sqrt{2}$ in this case.
5. Concluding remarks/applications
We conclude with some indications of applications and of a possible further avenue of research (besides Question 1.1, which we pointed out in the Introduction).
5.1 Expected discounted payoff of a ‘regret’ lookback option
One immediate application of the above that springs to mind is computation of the expected discounted payoff (under the ‘physical’ measure) of a lookback option on the stock of a company that one views as eventually going bankrupt, and whose price is modeled by the process Y. The idea is that one holds equity in the company until termination, say for dividends, but at the same time one wants an option to provide some hedge against not selling the stock sooner (or indeed at its maximum). It is a ‘buy-and-hold’ strategy recognizing that the company will eventually terminate.
Specifically, we may imagine that the stock price is given by the process Y under the ‘physical’ measure  $\mathbb{Q}_y$ for an initial price
 $y\in (0,\infty)$. Assumption 1.1 then means that eventually the price will hit zero a.s., either abruptly, say as a result of some one-off adverse event, when
 $p>0$, or continuously, say as a result of gradually deteriorating business conditions, when
 $p=0$. At the same time we have an option written on the stock that will pay some (non-decreasing) function
 $f\colon (0,\infty)\to [0,\infty)$ of the overall maximum
 $\overline{Y}_\infty$ at termination
 $T_0$, thus providing some measure of compensation for the ‘regret’ of not having sold the stock optimally.
Assuming a constant risk-free force of interest  $r\in [0,\infty)$, then the expected discounted payoff of such an option is simply
 \[\mathbb{Q}_y[\text{e}^{-rT_0}f(\overline{Y}_\infty)]=\mathbb{Q}_y[f(\overline{Y}_\infty)\mathbb{Q}_y[\text{e}^{-r L}\mid \overline{Y}_\infty]\mathbb{Q}_y[\text{e}^{-r(T_0-L)}\mid \overline{Y}_\infty,J]],\]
which may easily be expressed using the results of Theorem 4.1 in terms of (at most) a two-dimensional integral. Such an expectation provides some information on the ‘value’ of the option for the investor, though of course it does not correspond to a risk-neutral valuation thereof.
5.2 Properties of the joint law of $(L,\overline{Y}_\infty,J,T_0-L)$

It is immediate from the definition of  $\mathcal{I}^{p,\alpha}$ and from Proposition 4.1 (but not obvious a priori) that, for given
 $\beta\in[0,\infty)$,
 $y\in (0,\infty)$, the conditional Laplace transform
 \[ \mathbb{Q}_y[\text{e}^{-\beta L}\mid \overline{Y}_\infty]\overset{\text{a.s.-$\mathbb{Q}_y$}}{=}\dfrac{\mathcal{I}^{p,\alpha}(\beta y^\alpha)}{\mathcal{I}^{p,\alpha}(\beta{\overline{Y}_\infty}^\alpha)} \]
is decreasing as a function of  $\overline{Y}_\infty$. On the other hand it is clear from Definition 4.1 that
 $\mathcal{N}^{p,\alpha}_\beta(y)$ depends on
 $\beta$ and y only through
 $\beta y^\alpha$. Hence it follows from Proposition 4.3 (ii) that
 \[ \mathbb{Q}_y[\text{e}^{-\beta (T_0-L)}\mid \overline{Y}_\infty]\overset{\text{a.s.-$\mathbb{Q}_y$}}{=}\mathcal{N}^{p,\alpha}_\beta\big(\beta {\overline{Y}_\infty}^\alpha\big) \]
is decreasing as a function of  $\overline{Y}_\infty$ when X has paths of infinite variation. In the opposite case, it follows similarly from Definition 3.1, Corollary 3.1 and from Proposition 4.3 (i) that
 \[ \mathbb{Q}_y[\text{e}^{-\beta (T_0-L)}\mid \overline{Y}_\infty,J]\overset{\text{a.s.-$\mathbb{Q}_y$}}{=}\dfrac{\mathcal{M}^{p,\alpha}_\beta(\overline{Y}_\infty J,\overline{Y}_\infty)}{1-J^{\Phi(p)}}\mathds{1}_{(0,1)}(J)+\mathds{1}_{\{1\}}(J) \]
is also decreasing in  $\overline{Y}_\infty$. However, its dependence on J is non-trivial; see Figure 1.
More generally one would be interested in the following question.
Question 5.1. What properties of the joint law of  $(L,\overline{Y}_\infty,J,T_0-L)$ can be deduced based on the results of Theorem 4.1 (or otherwise)?
We have given a flavor of this in the above, but do not pursue the problem any further here.
Acknowledgements
Financial support from the Slovenian Research Agency is acknowledged (research program P1-0222). The author is grateful to an anonymous referee whose comments and suggestions helped to improve the presentation as well as the content of this paper.