



1. Introduction
We consider a class of exotic options known as life-contingent options. The name comes from the fact that such options first arose in the context of insurance, in which they are contingent on the lifetime of the holder. That is, the exercise time is at the time of the holder’s death. Such options are also known in the literature as equity-linked death benefits, or guaranteed minimum death benefits (GMDB). These are options that give a general payoff at the exercise time that is a function of the underlying asset’s price. But unlike the European and American options, the exercise time is neither fixed nor under the holder’s control. Instead, it is contingent on the time of occurrence of an event of interest. In our case, we assume the event to be independent of the asset price.
A typical GMDB may have the payoff form
 $\max(X_\tau^1,G)$
, where
 $X_\tau^1$
is the time-
 $\tau$
price of the underlying, G is the guarantee amount, and
 $\tau$
is a stopping time (time until death). Because
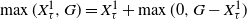 $\max(X_\tau^1,G)=X_\tau^1+\max(0,G-X_\tau^1)$
, the payoff of this GMDB is the sum of the underlying price and a life-contingent put option with strike price G and exercise time
 $\tau$
. Thus, the problem of hedging this GMDB is equivalent to the problem of hedging the life-contingent put option.
There has been considerable work on the valuation problem for life-contingent options. For instance, [Reference Gerber, Shiu and Yang3] determines the expected payoff of life-contingent options within the framework of the geometric Brownian motion model by using a discounted density approach. There, the random exercise time is modelled by a linear combination of exponentially distributed random variables independent of the underlying price processes. Closed-form expressions for the expected payoff are obtained for various types of payoffs, including European-type options, which give the holder the right to buy (respectively sell) a unit of underlying at the expiry date; as well as digital, lookback, and barrier options. The results are extended to a jump-diffusion model of stock prices in [Reference Gerber, Shiu and Yang4]. An underlying asset price model with jumps is also considered in [Reference Zhang, Yong and Yu13], where valuation formulae for a class of payoff functions are obtained under the assumption that the risky asset price follows a geometric Lévy process, and the pricing method is implemented numerically via spline function methods. Meanwhile, the valuation problem for life-contingent options in a discrete-time model is considered by [Reference Gerber, Shiu and Yang5], which uses the technique of geometric stopping of a random walk to derive closed-form expressions for the expected payoff of European, barrier, and lookback life-contingent options.
On the other hand, the hedging problem for life-contingent options, an equally important topic in financial literature, has been far less frequently studied compared to the problem of valuation. The hedging problem is considered in [Reference Kelani and Quittard-Pinon6] in incomplete markets with an independence assumption for the mortality risk and market risk, giving a concise formula for the optimal hedging ratio under the framework of local risk minimisation. In this framework, the portfolio is not required to be self-financing, but its value process is a martingale. The objective is to hedge the option while minimising the variance of the cumulative cost process of the portfolio. The hedging problem is considered in [Reference Wang, Shen, Qian and Yang9] in a more intricate market model where the risky asset price follows a Hawkes jump-diffusion process, which is a jump process with self-exciting jumps, obtaining explicit expressions for locally risk-minimising strategies for unit-linked life insurance contracts.
Another hedging framework that is widely used in incomplete markets is that of quantile hedging. In this framework, one attempts to find a self-financing portfolio that successfully hedges the option with maximal probability, given constraints on the initial value of the portfolio. This framework is explored in [Reference Wang10]. Under various assumptions, quantile hedges are derived for life-contingent options, referred to in the paper as guaranteed minimum death benefits. Meanwhile, [Reference Eyraud-Loisel and Royer-Carenz2] considered hedging problems for an insider trader. They studied the hedging problem for American-style options and modelled it with backward stochastic differential equations with random terminal time. However, strong additional conditions were included in the setup. In particular, the portfolio holder is assumed to have access to additional information not included in the asset filtration, and their portfolio is allowed to consist of an additional asset other than the two included in the standard market model.
In this paper, we consider the hedging problem for life-contingent options. Since the exercise time for life-contingent options is itself random, this presents a novel difficulty in constructing a hedge process, or a replicating portfolio. In [Reference Gerber, Shiu and Yang3–Reference Gerber, Shiu and Yang5,Reference Zhang, Yong and Yu13], the expected payoff of the life-contingent option at the exercise time is derived. However, they do not explore the hedging problem for this type of option. In [Reference Kelani and Quittard-Pinon6,Reference Wang10], the hedging problem is studied. The frameworks investigated are, respectively, the local risk minimisation framework and the quantile hedging framework. This leaves the problem of super-replication unanswered. In [Reference Eyraud-Loisel and Royer-Carenz2], the existence of a super-replication portfolio is obtained, but the authors make crucial additions to the scenario—in particular the existence of an additional asset, and additional datum in the filtration, the so-called insider information. Thus, the question of super-hedging for the life-contingent option—in the classical setting of a portfolio consisting only of market assets, and adapted to the market filtration—remains unanswered.
As such, we are interested in the case where the additional devices in [Reference Eyraud-Loisel and Royer-Carenz2] are not provided. We explore the super-replication problem for life-contingent options. Given that the market is incomplete, exact replication will rarely be possible, thus we examine the possibility of super-replication instead, that is, a portfolio that almost surely pays off more than or equal to the option payoff at the exercise time. First, we derive the minimal price of a super-replicating portfolio for the life-contingent option. We then show that there exists a minimal hedge for the life-contingent option, given only access to the asset price process as information, and consisting of only the two assets in the market. Next, we give a characterisation of when replication of the life-contingent option is possible, and finally derive an explicit expression for a super-replicating portfolio in a simple case.
The rest of this paper is organised as follows. Section 2 introduces the model settings and our notation. Section 3 presents the existence of a minimal super-replication portfolio and gives an explicit super-replicating hedge for a simple life-contingent option. Section 4 presents necessary and sufficient conditions under which a replication portfolio exists. In Section 5, we summarise our findings and present potential directions for further research. Finally, in the Appendix, we collect some technical proofs.
2. The setup
We first introduce the setup for the problem. Let
 $(\Omega, \mathcal F, \mathbb{F}, \mathbb{P})$
be a filtered probability space satisfying the usual conditions. The probability measure
 $\mathbb{P}$
is referred to as the physical measure. We consider the processes
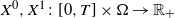 $X^0, X^1\colon [0, T] \times \Omega \to \mathbb R_+$
, known as the bond and stock prices respectively, satisfying the stochastic differential equations (SDE)
 \begin{align} \mathrm{d} X^0_t & = rX^0_t \, \mathrm{d} t, \nonumber \\[5pt] \mathrm{d} X^1_t & = X^1_t (\mu\, \mathrm{d} t + \sigma \, \mathrm{d} W_t), \end{align}
with
 $X^0_0 = 1$
,
 $X^1_0 = x_0$
almost surely (a.s.) for some
 $x_0 \in \mathbb R_+$
, and
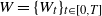 $W=\{W_t\}_{t\in[0,T]}$
a standard Brownian motion with T denoting a fixed and finite time horizon. Here,
 $r, \mu, \sigma \in \mathbb R$
are positive constants, respectively known as the risk-free interest rate, expected return rate, and volatility of the stock. The filtration
 $\mathbb{F} = \{\mathcal F_t\}_{t \geq 0}$
is the natural filtration generated by the Brownian motion W. We assume that
 $\mathbb F$
satisfies the usual conditions, that is, it is right continuous and contains all
 $\mathbb P$
-null sets.
To describe the randomness of the exercise time of life-contingent options, we let
 $\tau$
be an a.s. finite random variable independent of
 $\mathcal F$
taking finitely many values
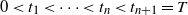 $0 < t_1 < \dots < t_n < t_{n+1} = T$
, representing the possible exercise and expiry times. We interpret the times
 $t_1 \dots t_n$
as being the possible occurrence times of the event of interest (e.g. the death of the policy holder) at which time the option may be exercised. On the other hand, if
 $\tau = t_{n+1} = T$
, we interpret it as the option having expired before the event of interest occurs. We denote by
 $\mathcal G$
the natural filtration of the process
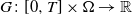 $G\colon[0, T]\times \Omega \to \mathbb R$
given by
 $G(t, \cdot) = \textbf{1}_{\{\tau \leq t\}}$
. By construction,
 $\tau$
is then a bounded stopping time of
 $\mathcal G$
.
We now introduce some key definitions.
Definition 2.1. (T-year life-contingent option.) Let T be the fixed expiration date of the life-contingent option, and
 $0\leq \tau \leq T$
be the stopping time of an event of interest. The payoff of a life-contingent option is an
 $(\mathcal F_T \vee \mathcal G_{\tau})$
-measurable random variable, where
 $\mathcal G_\tau$
denotes the
 $\sigma$
-algebra of the stopping time
 $\tau$
, and
 $\mathcal F_T \vee \mathcal G_{\tau}$
denotes the
 $\sigma$
-algebra generated by
 $\mathcal F_T$
and
 $\mathcal G_\tau$
. The time-
 $\tau$
payoff of the life-contingent option is of the form
 \begin{align*}f_\tau \;:\!=\; \textbf{1}_{\{\tau < T\}} b(X^1_\tau) + \textbf{1}_{\{\tau = T\}} c(X^1_T),\end{align*}
where
 $X^1$
is the underlying price process satisfying (2.1) and
 $\tau$
is the random exercise time.
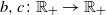 $b,c\colon \mathbb R_+ \to \mathbb R_+$
are bounded Borel-measurable functions called the death benefit payoff and compensation payoff, respectively.
Thus, the policy pays death benefit
 $b(X^1_\tau)$
if the policy holder dies at time
 $\tau$
but before time
 $T = t_{n+1}$
, and otherwise the compensation payoff is
 $c(X^1_T)$
at time T.
Definition 2.2. (Self-financing portfolio.) A self-financing portfolio is a pair of processes
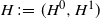 $H \;:\!=\; (H^0, H^1)$
with values in
 $\mathbb R^2$
that is adapted to the filtration
 $\mathbb F$
, and satisfies the following conditions:
-
(C1) The portfolio must be self-financing, i.e.
 $X^0_t\,\mathrm{d} H^0_t + X^1_t\,\mathrm{d} H^1_t = 0$
a.s.
-
(C2) The portfolio must have a nonnegative value at all times:
$X^0_t H^0_t + X^1_t H^1_t \geq 0$
a.s. for all
$t \in [0, T]$
.
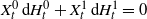
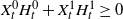

We denote by
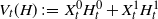 $V_t (H) \;:\!=\; X^0_t H^0_t + X^1_t H^1_t$
the value process of the portfolio H at time t, and
 $V_0 (H)$
the initial investment of the portfolio. The set of self-financing portfolios is denoted by
 $\textit{SF}$
.
Remark 2.1. Note that the initial values
 $H^0_0, H^1_0$
may be freely chosen, so long as the nonnegativity condition (C2) in Definition 2.2 is satisfied.
Definition 2.3. (Super-replication portfolio.) A super-replication portfolio for the lifetime-contingent option f is a self-financing portfolio whose associated value process V satisfies
 $V_\tau \geq f_\tau$
almost surely. More precisely, a super-replication portfolio is an element of the set
 $\mathcal S(f, \tau)$
defined by
 \begin{align*}\mathcal S(f_,\tau) \;:\!=\; \{H\mid H\in\textit{SF};\; X^0_\tau H^0_\tau + X^1_\tau H^1_\tau \geq f_\tau\ \mathrm{a.s.}\}.\end{align*}
Definition 2.4. (Minimal super-replication price.) We define the minimal super-replication price
 $\pi_0(f)$
for the life-contingent option
 $(f,\tau)$
to be the infimal value of a super-replication portfolio for
 $(f, \tau)$
, i.e.
 \begin{align*}\pi_0(f) \;:\!=\; \mathrm{inf}\{V_0 (H) \mid H = (H^0, H^1) \in \mathcal S(f, \tau)\},\end{align*}
where
 $V_0(H)$
is the initial investment for the portfolio H.
Definition 2.5. (Minimal super-replication portfolio.) A minimal super-replication portfolio for
 $(f,\tau)$
, if it exists, is a super-replication portfolio whose initial value equals the minimal hedging price
 $\pi_0 (f)$
.
Recall that the market involving the two assets
 $X^0$
and
 $X^1$
is complete. This implies that there exists a unique equivalent martingale measure
 $\mathbb Q$
, which is a probability measure equivalent to
 $\mathbb P$
such that the discounted asset prices are martingales.
3. Existence of a minimal super-replication portfolio
We are now ready to state the first main theorem of the paper.
Theorem 3.1. Let b, c, f, and
 $\tau$
be as in the setup in Section 2. There exists a minimal hedge for the life-contingent option
 $(f,\tau)$
whose associated initial investment
 $\pi_0$
is
 \begin{equation} \pi_0 = D_0 \dots D_{n} (U), \end{equation}
where the random variable U is defined by
 \begin{align*} U \;:\!=\; \begin{cases} c(X^1_T) & \textit{if }\; \mathbb P(\tau = T) \neq 0, \\[5pt] 0 & \textit{if }\; \mathbb P(\tau = T) = 0, \\[5pt] \end{cases} \end{align*}
and the operators
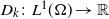 $D_k\colon L^1(\Omega) \to \mathbb R$
are defined as follows. For any random variable
 $Y \in L^1(\Omega)$
,
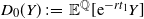 $D_0 (Y) \;:\!=\; \mathbb E^{\mathbb Q} [\mathrm{e}^{-rt_1} Y]$
; for
 $1 \leq k \leq n$
,
 \begin{align*}D_{k}(Y) \;:\!=\; \max\big(b(X^1_{t_{k}}),\mathbb E^{\mathbb Q}\big[\mathrm{e}^{-r(t_{k+1}-t_{k})}Y\mid\mathcal F_{t_{k}}\big]\big).\end{align*}
Here,
 $\mathbb E^{\mathbb Q}$
denotes the expectation under the probability measure
 $\mathbb Q$
, and we recall that
 $t_1, \dots, t_{n+1}$
are the possible exercise or expiry times of the option.
Remark 3.1. The operators
 $D_k$
above correspond to a discretised version of the Snell envelope in the theory of optimal stopping. See, for instance, [Reference Zhang12, Chapter 6] for more details.
For the proof of Theorem 3.1, we will need the following lemma on independence of filtrations, as well as a standard result from the theory of option pricing.
Lemma 3.1. Let
 $\mathbb H = \{\mathcal H_t\}$
and
 $\mathbb K = \{\mathcal K_t\}$
be two independent filtrations under the probability measure
 $\mathbb P$
. If
 $\mathbb Q$
is another probability measure such that
 $\mathrm{d}\mathbb Q = Z \, \mathrm{d}\mathbb P$
for some
 $\mathcal H_\infty$
-measurable random variable Z, then
 $\mathbb H$
and
 $\mathbb K$
remain independent under
 $\mathbb Q$
.
Proof. Let
 $H \in \mathcal H_t$
and
 $K \in K_r$
for some
 $t, r \geq 0$
. Then
 \begin{align*} \mathbb Q(H \cap K) & = \mathbb E^{\mathbb Q}[\textbf{1}_H\textbf{1}_K] = \mathbb E^{\mathbb P}[Z\textbf{1}_H\textbf{1}_K] \\[5pt] & = \mathbb E^{\mathbb P}[Z\textbf{1}_H]\mathbb E^{\mathbb P}[\textbf{1}_K] \\[5pt] & = \mathbb E^{\mathbb P}[Z\textbf{1}_H]\mathbb E^{\mathbb P}[\textbf{1}_K]\mathbb E^{\mathbb P}[Z] \\[5pt] & = \mathbb E^{\mathbb P}[Z\textbf{1}_H]\mathbb E^{\mathbb P}[Z\textbf{1}_K] = \mathbb E^{\mathbb Q}[\textbf{1}_H]\mathbb E^{\mathbb Q}[\textbf{1}_K] = \mathbb Q(H)\mathbb Q(K), \end{align*}
where the equality on the third line is valid because
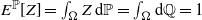 $E^{\mathbb P}[Z] = \int_{\Omega}Z\,\mathrm{d}\mathbb P = \int_{\Omega}\mathrm{d}\mathbb Q = 1$
.
We now recall a key result in the theory of option pricing, which can be found in references such as [Reference Elliott and Kopp1, Theorem 7.5.10, p. 190]: given a geometric Brownian motion market model with two assets, the minimal initial investment for a hedge of a European option with payoff
 $h_T$
is
 $\mathbb E^{\mathbb Q}[\mathrm{e}^{-rT}h_T]$
, where
 $\mathbb Q$
denotes an equivalent martingale measure and T is the exercise time. Stated more precisely, the form of this result we will need is as follows.
Proposition 3.1. Let W be a standard Brownian motion on a filtered probability space. Suppose
 $X^0$
and
 $X^1$
are solutions to the SDE
 \begin{align} \mathrm{d} X^0_t & = rX^0_t\,\mathrm{d} t , \end{align}
 \begin{align} \mathrm{d} X^1_t & = X^1_t(\mu\,\mathrm{d} t + \sigma\,\mathrm{d} W_t) \end{align}
for
 $t \in [q, s]$
with initial conditions
 $X^0_q = x_0$
and
 $X^1_q = x_1$
for some
 $x_0, x_1 \in \mathbb R_{+}$
. Let
 $f_s$
be an
 $\mathcal F_s$
-measurable random variable. Suppose
 $(Z^0, Z^1)$
is a super-replication portfolio consisting of
 $X^0$
and
 $X^1$
on [q, s]. Then
 \begin{align*}Z_q^0 X_q^0 + Z_q^1 X_q^1\geq\mathbb E^{\mathbb Q}[\mathrm{e}^{r(q-s)}f_s\mid\mathcal F_q]\ \mathrm{a.s.},\end{align*}
where
 $\mathbb Q$
is a probability measure equivalent to
 $\mathbb P$
under which the discounted process
 $\mathrm{e}^{-r(t-q)}X_t^1$
is a martingale on [q, s] with respect to the filtration
 $\mathbb F$
. Further, there exists a self-financing portfolio
 $H = (H^0, H^1)$
with
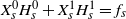 $X^0_s H^0_s + X^1_s H^1_s = f_s$
a.s., in which case
 \begin{align*}X^0_q H^0_q + X^1_q H^1_q = \mathbb E^{\mathbb Q}[\mathrm{e}^{r(q-s)}f_s\mid\mathcal F_q].\end{align*}
As a first step to proving Theorem 3.1, we obtain a lower bound on the value of any
 $(f, \tau)$
hedge at the times
 $t_1, \dots, t_{n+1}$
. For convenience, we write
 $t_0 = 0$
.
Proposition 3.2. Let b, c, f, and
 $\tau$
be as in the setup in Section 2, and suppose
 $H\in S(f,\tau)$
. Then the associated value process V must satisfy
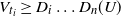 $V_{t_i} \geq D_{i}\ldots D_{n}(U)$
for each
 $0 \leq i \leq n$
a.s., where the random variables U and the operators
 $D_i$
are defined as in Theorem 3.1. If
 $\mathbb P(\tau = T) \neq 0$
, V must further satisfy
 $V_T \geq c(X^1_T)$
a.s.
Proof. Let V(H) be the value process of a hedging portfolio
 $H = (H^0, H^1)$
. Assuming first that
 $\mathbb P(\tau = T) \neq 0$
, we will show that
 $V_T (H) \geq c(X^1_T)$
a.s. Indeed, assume otherwise; then the event
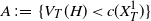 $A \;:\!=\; \{V_T (H) < c(X^1_T)\}$
has nonzero probability. Since the two variables involved in the defining inequality are
 $\mathcal F_T$
-measurable, A is
 $\mathcal F_T$
-measurable.
But then, since
 $\tau$
is independent of the filtration generated by the Brownian motion, we have that
 $A \cap \{\tau = T\}$
has nonzero probability as well. Thus
 $V_\tau < c(X_\tau)$
with nonzero probability, contradicting the definition of a hedge.
By exactly the same reasoning, we conclude that
 \begin{equation} V_{t_i}(H) \geq b(X^1_{t_i}) \ \mathrm{a.s}, \end{equation}
for each
 $1 \leq i \leq n$
.
It remains to show the inequalities
 \begin{equation} V_{t_i} (H) \geq D_{i} \ldots D_{n} (U)\; \mathrm{ a.s}, \end{equation}
for each
 $0 \leq i \leq n$
. We treat the cases
 $1 \leq i \leq n$
and
 $i = 0$
separately. For the former, we take a dynamic programming approach and induct backwards on i.
For the base case, we must show that
 \begin{equation} V_{t_{n}} (H) \geq D_{n} (U)\; \mathrm{ a.s.} \end{equation}
We first note that by the Markov property of Itô SDEs, conditional on
 $\mathcal F_{t_{n}}$
, we find that
 $X^0, X^1$
, and the portfolio
 $H^0, H^1$
restricted to
 $[t_{n}, T]$
satisfy the hypotheses of Proposition 3.1.
Indeed,
 $X^0$
and
 $X^1$
satisfy the SDEs (3.2) and (3.3) on the interval
 $[t_n, T]$
, and, from above,
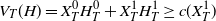 $V_T (H) = X^0_T H^0_T + X^1_T H^1_T \geq c(X^1_T)$
a.s. Thus
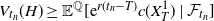 $V_{t_{n}}(H)\geq\mathbb E^{\mathbb Q}[\mathrm{e}^{r(t_n-T)}c(X^1_T)\mid\mathcal F_{t_{n}}]$
. Combining this with the fact that
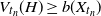 $V_{t_{n}}(H)\geq b(X_{t_{n}})$
from (3.4), we conclude the inequality (3.6) as desired.
For the induction step, let
 $2 \leq k \leq n$
, and assume that
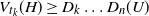 $V_{t_k} (H) \geq D_{k} \dots D_{n} (U)$
a.s. We must show that
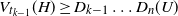 $V_{t_{k-1}}(H) \geq D_{k-1} \dots D_{n} (U)$
a.s. However, conditional on
 $\mathcal F_{t_{k-1}}$
, we again find that
 $X^0, X^1$
, and the portfolio
 $H^0, H^1$
restricted to
 $[t_{k-1}, t_k]$
, satisfy the hypotheses of Proposition 3.1. Indeed, we again check that
 $X^0$
and
 $X^1$
satisfy the SDEs (3.2) and (3.3) on the interval
 $[t_{k-1}, t_k]$
and, by the induction hypothesis,
 \begin{align*}V_{t_k}(H) = X^0_{t_{k}}H^0_{t_{k}} + X^1_{t_{k}}H^1_{t_{k}} \geq D_{k} \dots D_{n} (U), \mathrm{ a.s.}\end{align*}
Together with (3.4), we deduce that
 \begin{equation*} V_{t_{k-1}}(H) \geq \mathrm{max}\big(b(X^1_{t_{k-1}}),\mathbb E^{\mathbb Q} \big[\mathrm{e}^{r(t_{k-1}-t_{k})}D_{k}\dots D_{n}(U)\mid\mathcal F_{t_{k-1}}\big]\big) = D_{k-1} \dots D_{n} (U)\; \mathrm{ a.s}, \end{equation*}
which proves the case
 $1 \leq i \leq n$
in (3.5) as required. Finally, one more application of Proposition 3.2 proves the case
 $i = 0$
in (3.5).
In the case where
 $\mathbb P(\tau = T) = 0$
, we note that by similar considerations to earlier, we still have the inequality
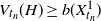 $V_{t_n}(H) \geq b(X^1_{t_n})$
a.s., whence the rest of the proof proceeds verbatim.
Now we set out to construct a minimal hedge. Before we do so, we need the following generalities on regular conditional probabilities. The definitions below are largely based on [Reference Leao, Fragoso and Ruffino7].
Definition 3.1. (Transition probability.) Let
 $(\Omega, \mathcal F, P)$
be a probability space and
 $(E,\mathcal E)$
a measurable space. A transition probability from E to
 $\Omega$
is a function
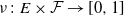 $\nu\colon E \times \mathcal F \to [0, 1]$
which satisfies the following conditions:
-
(i)
$\nu(x, \cdot)$
is a probability measure on
$(\Omega, \mathcal F)$
for all
$x \in E$
; -
(ii)
$\nu(\cdot, A)$
is an
$\mathcal E$
-measurable function on E for all
$A \in \mathcal F$
.


Definition 3.2. (Regular conditional probability.) Let
 $T \colon \Omega \to E$
be a measurable function. A regular conditional probability with respect to T is a transition probability
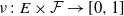 $\nu \colon E \times \mathcal F \to [0, 1]$
from
 $(E,\mathcal E)$
to
 $(\Omega,\mathcal F)$
such that
 \begin{align*}\mathbb P[A \cap T^{-1} (B)] = \int_B \nu(x, A)\,T_*\mathbb P(\mathrm{d} x)\end{align*}
for all
 $x \in E$
,
 $A \in \mathcal F$
, and
 $B \in \mathcal E$
, where
 $T_* \mathbb P$
denotes the image measure of
 $\mathbb P$
under T.
Definition 3.3. (Sub-
 $\sigma$
-algebra regular conditional probability.) Let
 $\mathcal H$
be a sub-
 $\sigma$
-algebra of
 $\mathcal F$
. A sub-
 $\sigma$
-algebra regular conditional probability (with respect to
 $\mathcal H$
) is a regular conditional probability with respect to the identity map
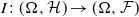 $I \colon (\Omega, \mathcal H) \to (\Omega, \mathcal F)$
.
The following is [Reference Yong and Zhou11, Proposition 1.9], and gives sufficient conditions for regular conditional probabilities to exist. We then state a proposition which ensures that regular conditional probabilities exist in our setting.
Proposition 3.3. Let
 $(\Omega, \mathcal F, \mathbb P)$
be a Radon probability space, and
 $\mathcal H$
a sub-
 $\sigma$
-algebra of
 $\mathcal F$
. Then there exists a regular conditional probability with respect to
 $\mathcal H$
.
We shall need the following technical proposition, whose proof we relegate to the Appendix.
Proposition 3.4. The market model
 $(\Omega, \mathcal F, \mathbb P)$
in the setup in Section 2 can be taken to be a Radon probability space.
We are now ready to construct our minimal hedge and, in doing so, prove Theorem 3.1.
Proof of Theorem 3.1. Denote by
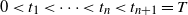 $0 < t_1 < \dots < t_n < t_{n+1} = T$
the values of
 $\tau$
that occur with nonzero probability, with the exception of
 $\mathbb P(\tau = t_{n+1})$
which is permitted to possibly be 0. In the notation introduced in the statement of the theorem, write, for convenience,
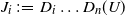 $J_i \;:\!=\; D_{i} \dots D_{n} (U)$
for
 $1 \leq i \leq n$
.
We define our hedging process H on
 $[0, t_1]$
by
 $H^0 = Y^0$
,
 $H^1 = Y^1$
, where
 $Y^0, Y^1$
are defined as follows. By Proposition 3.2, given
 $X^0, X^1$
as in the setup, there exists an
 $\mathbb F$
-adapted solution
 $(Y^0, Y^1, V)$
to the following system (FBSDE 1) of forward–backward stochastic differential equations,
 \begin{align} \mathrm{d} X^0_t & = rX^0_t \, \mathrm{d} t, \end{align}
 \begin{align} \mathrm{d} X^1_t & = X^1_t(\mu\,\mathrm{d} t + \sigma\,\mathrm{d} W_t), \end{align}
 \begin{align} \mathrm{d} V_t & = Y^0_t\,\mathrm{d} X^0_t + Y^1_t\,\mathrm{d} X^1_t, \end{align}
 \begin{align} 0 & = X^0_t\,\mathrm{d} Y^0_t + X^1_t\,\mathrm{d} Y^1_t \end{align}
for
 $t \in [0, t_1]$
under
 $\mathbb P$
with initial conditions
 $X_0^0 = 1$
,
 $X_0^1 = x$
, and terminal condition
 $V_{t_1} = J_1$
almost surely.
Suppose now inductively our processes
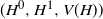 $(H^0, H^1, V(H))$
have already been defined on
 $[0,t_{i}]$
for some
 $1 \leq i \leq n$
and satisfy (3.7)–(3.10), and further that
 $V_{t_k} (H) \geq J_k$
for each
 $1 \leq k \leq i$
. Consider the regular conditional probability
 $\xi$
of
 $\mathbb P$
given
 $\mathcal F_{t_i}$
.
Now fix
 $x \in \mathbb R_+$
and
 $\omega \in \Omega$
such that
 $X^1_{t_i} (\omega) = x$
, and consider the system (FBSDE 2)
 \begin{align*} \mathrm{d} X^0_t & = r X^0_t \, \mathrm{d} t, \\[5pt] \mathrm{d} X^1_t & = X^1_t(\mu\,\mathrm{d} t + \sigma\,\mathrm{d} W_t), \\[5pt] \mathrm{d} R_t & = Z^0_t\,\mathrm{d} X^0_t + Z^1_t\,\mathrm{d} X^1_t, \\[5pt] 0 & = X^0_t\,\mathrm{d} Z^0_t + X^1_t\,\mathrm{d} Z^1_t \end{align*}
for
 $t \in [t_i, t_{i+1}]$
under the probability measure
 $\xi(\omega, \cdot)$
with initial conditions
 $X_{t_i}^0 = \mathrm{e}^{rt_i}$
,
 $X_{t_i}^1 = x$
, and terminal condition
 $R_{t_{i + 1}} = J_{i+1}$
,
 $\xi(\omega, \cdot)$
-a.s. Note that
 $\xi(\omega, \cdot)$
is supported on the event
 $\{X^1_{t_i} = x\}$
, since
 $X^1_{t_i}$
is
 $\mathcal F_{t_i}$
-measurable, and
 $X^1_{t_i} (\omega) = x$
.
By Proposition 3.1, for each such
 $\omega \in \Omega$
there exists a
 $\xi(\omega,\cdot)$
-a.s. well-defined solution
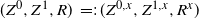 $(Z^0,Z^1,R) \;=\!:\; (Z^{0,x},Z^{1,x},R^x)$
to (FBSDE 2). We define our process for
 $t \in (t_i, t_{i+1}]$
by
 \begin{align*} H^0_t & = Z^{0, x}_t + \mathrm{e}^{-rt_i}(V_{t_i} (H) - Z^{0, x}_{t_i} X^0_{t_i} - Z^{1, x}_{t_i} X^1_{t_i}), \\[5pt] H_t^1 & = Z_t^{1, x}, \\[5pt] V_t(H) & = \mathrm{e}^{-rt_i}(V_{t_i} (H) - Z^{0, x}_{t_i} X^0_{t_i} - Z^{1, x}_{t_i} X^1_{t_i}) X_{t}^0 + Z_t^{0, x} X_t^0 + Z_t^{1, x} X_t^1 = H^0_t X^0_t + H^1_t X^1_t \end{align*}
on the event
 $\{X^1_{t_i} = x\}$
. This defines
 $(H^0, H^1, V)$
 $\mathbb P$
-a.s. up to
 $[0,t_{i+1}]$
.
Indeed, denoting by E the set on which
 $(H^0, H^1, V)$
is well defined up to
 $[0,t_{i+1})$
, we have
 \begin{align*}\mathbb P(E) = \int_{\Omega}\xi(\omega,E)\,\mathbb P(\mathrm{d}\omega) = \int_{\Omega}1\,\mathbb P(\mathrm{d}\omega) = 1.\end{align*}
We now show that
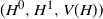 $(H^0, H^1, V(H))$
satisfies the system (FBSDE 1) on
 $[0, t_{n+1}]$
under
 $\mathbb P$
with initial conditions
 $X_0^0 = 1$
,
 $X_0^1 = x$
, and terminal condition
 $V_{t_{i + 1}}(H) \geq J_{i+1}$
, almost surely. That (3.7) and (3.8) are satisfied has already been established a priori in the construction of the market model. For
 $t\in[t_i,t_{i+1}]$
, (3.9) is satisfied. Indeed, writing
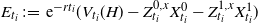 $E_{t_i} \;:\!=\; \mathrm{e}^{-rt_i}(V_{t_i} (H) - Z^{0, x}_{t_i} X^0_{t_i} - Z^{1, x}_{t_i} X^1_{t_i})$
, we get
 \begin{align*} \mathrm{d} V_t(H) & = E_{t_i}\,\mathrm{d} X^0_t + \mathrm{d} Z_t^{0, x}X^0_t + \mathrm{d} Z_t^{1, x}X^1_t + Z_t^{0, x}\,\mathrm{d} X^0_t + Z_t^{1, x}\,\mathrm{d} X^1_t \\[5pt] & = E_{t_i}\,\mathrm{d} X^0_t + Z_t^{0, x}\,\mathrm{d} X^0_t + Z_t^{1, x}\,\mathrm{d} X^1_t \\[5pt] & = H_t^0\,\mathrm{d} X^0_t + H_t^1\,\mathrm{d} X^1_t. \end{align*}
But we may also compute, for
 $s \in [0, t_i]$
and
 $t \in [t_i, t_{i+1}]$
,
 \begin{align*} V_t (H) - V_s(H) & = (V_t (H) - V_{t_i} (H)) + (V_{t_i} (H) - V_s (H)) \\[5pt] & = \int_{t_i}^t H^0_r\,\mathrm{d} X^0_r + \int_{t_i}^{t}H^1_r\,\mathrm{d} X^1_r + \int_{s}^{t_i}H^0_r\,\mathrm{d} X^0_r + \int_s^{t_i}H^1_r\,\mathrm{d} X^1_r \\[5pt] & = \int_{s}^t H^0_r\,\mathrm{d} X^0_r + \int_{s}^t H^1_r\,\mathrm{d} X^1_r, \end{align*}
which shows that (3.9) holds on
 $[0, t_{i+1}]$
. Finally, we check the self-financing condition (3.10). Recall that we have assumed inductively that (3.10) holds on
 $[0, t_i]$
. Thus we need only check that (3.10) is satisfied for times s, t in the interval
 $[0, t_{i+1}]$
, with
 $s < t$
, and
 $t \in (t_i, t_{i+1}]$
.
Assume first that
 $s \leq t_{i}$
. Then we have
 \begin{align*} \int_s^t X^0_r\,\mathrm{d} H^0_r + \int_s^t X^1_r\,\mathrm{d} H^1_r & = \int_{[s, t_i)}X^0_r\,\mathrm{d} H^0_r + \int_{[s, t_i)}X^1_r\,\mathrm{d} H^1_r + \int_{(t_i, t]}X^0_r\,\mathrm{d} H^0_r + \int_{(t_i, t]}X^1_r\,\mathrm{d} H^1_r \\[5pt] & \quad + X^0_{t_i}(H^{0+}_{t_i} - H^{0}_{t_i}) + X^1_{t_i}(H^{1+}_{t_i} - H^{1}_{t_i}). \end{align*}
The first two terms are 0 by the induction hypothesis. We claim that the third and fourth terms are also 0. Indeed, on
 $[t_i, t_{i+1})$
, we have
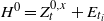 $H^0 = Z_t^{0, x} + E_{t_i}$
and
 $H^1 = Z_t^{1, x}$
, so that for,
 $t \in [t_i, t_{i+1})$
,
 $\mathrm{d} H^0_t = \mathrm{d} Z_t^{0, x}$
and
 $\mathrm{d} H^1_t = \mathrm{d} Z_t^{1, x}$
, and thus, by (FBSDE 2),
 \begin{equation*} \int_{(t_i, t]}X^0_r\,\mathrm{d} H^0_r + \int_{(t_i, t]}X^1_r\,\mathrm{d} H^1_r = \int_{(t_i, t]}X^0_r\,\mathrm{d} Z^0_r + \int_{(t_i, t]}X^1_r\,\mathrm{d} Z^1_r = 0. \end{equation*}
Now, for the last two terms, we note that
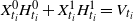 $X^0_{t_i} H^{0}_{t_i} + X^1_{t_i}H_{t_i}^{1} = V_{t_i}$
a.s., so
 \begin{align*} \int_s^t X^0_r\,\mathrm{d} H^0_r + \int_s^t X^1_r\,\mathrm{d} H^1_r & = X^0_{t_i}H^{0+}_r + X^1_{t_i}H^{1+}_r - V_{t_i} (H) \\[5pt] & = X^0_{t_i}\bigg[Z_{t_i}^{0,x}+\frac{1}{X^0_{t_i}}(V_{t_i}(H)-Z_{t_i}^{0,x}X^0_{t_i}-Z^{1,x}_{t_i}X^1_{t_i})\bigg] + X^1_{t_i}Z_{t_i}^{1, x} - V_{t_i}(H) \\[5pt] & = X^0_{t_i}Z^{0,x} + V_{t_i}(H) - X^0_{t_i}Z^{0,x}_{t_i} - X^1_{t_i}Z^{1,x}_{t_i} + X^1_{t_i}Z_{t_i}^{1,x} - V_{t_i}(H) = 0. \end{align*}
Next, assume
 $s \in (t_i, t_{i+1}]$
. Then we simply have
 \begin{equation*} \int_s^t X^0_r\,\mathrm{d} H^0_r + \int_s^t X^1_r\,\mathrm{d} H^1_r = \int_s^t X^0_r\,\mathrm{d} Z^0_r + \int_s^t X^1_r\,\mathrm{d} Z^1_r = 0. \end{equation*}
Thus,
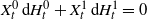 $X^0_t\,\mathrm{d} H^0_t + X^1_t\,\mathrm{d} H^1_t = 0$
for
 $t \in [0, t_{i+1}]$
, and so the self-financing condition (3.10) is verified.
It remains to check that the terminal condition
 $V_{t_{i + 1}} \geq J_{i+1}$
holds almost surely. But, by construction,
 $V_{t_{i + 1}} \geq J_{i+1}$
,
 $\mu(\omega, \cdot)$
-a.s. for each
 $\omega$
, so we have, denoting by F the event
 $\{V_{t_{i + 1}} \geq J_{i+1}\}$
,
 \begin{align*}\mathbb P(F) = \int_{\Omega}\xi(\omega,F)\,\mathbb P_{|\mathcal F_{t_i}}(\mathrm{d}\omega) = \int_{\Omega}1\,\mathbb P_{|\mathcal F_{t_i}}(\mathrm{d}\omega) = 1,\end{align*}
where
 $\mathbb P_{|\mathcal F_{t_i}}$
denotes the pushforward measure
 $I_*\mathbb P$
of
 $\mathbb P$
under the identity map
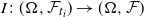 $I\colon (\Omega, \mathcal F_{t_i}) \to (\Omega, \mathcal F)$
. Hence, we conclude that the FBSDE holds on the interval
 $[0, t_{i+1}]$
. Inductively, we obtain a solution
 $(V, H^0, H^1)$
on the whole interval [0, T].
To see that this is a minimal hedge, we note that non-negativity holds since on each interval
 $[t_i, t_{i+1}]$
the value process is the sum of the two non-negative portfolios
 $(Z^0, Z^1)$
and
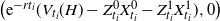 $\big(\mathrm{e}^{-rt_i}(V_{t_i}(H) - Z^0_{t_i}X^0_{t_i} - Z^1_{t_i}X^1_{t_i}), 0\big)$
, where the non-negativity of the second portfolio follows from the fact that
 $V_{t_i} (H) \geq J_{t_i}$
. Further, the hedging property holds since
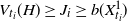 $V_{t_i} (H) \geq J_i \geq b(X^1_{t_i})$
for all i, so
 $V_{\tau} (H) \geq b(X_{\tau})$
almost surely. And finally, since
 $V_{t_1} = J_1$
, the initial investment
 $V_0$
is
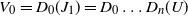 $V_0 = D_0(J_1) = D_0 \dots D_{n}(U)$
. So the hedge achieves the infimal hedging price, and is thus a minimal hedge.
Next, we derive an explicit expression for the minimal super-replicating hedge and hedging price associated to a particular life-contingent option. Due to the iterated conditional expectations in (3.1), it is in general difficult or impossible to obtain closed-form solutions for the super-replication price and minimal hedge. However, we are able to do so here for a very simple case.
Proposition 3.5. Let the market model be as in Section 2. Consider a life-contingent option
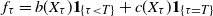 $f_\tau = b(X_\tau)\textbf{1}_{\{\tau < T\}} + c(X_\tau)\textbf{1}_{\{\tau = T\}}$
with only two exercise times
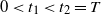 $0 < t_1 < t_2 = T$
, where we assume
 $\mathbb P(\tau = t_i) \neq 0$
for each
 $i = 1, 2$
. We suppose that the payoffs b, c are given by
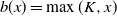 $b(x) = \max(K, x)$
and
 $c(x) = x$
respectively, where
 $K > 0$
is a strike price. We note that
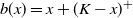 $b(x) = x + (K - x)^+$
, i.e. it is the combination of a long position in the stock and a put option on the stock. Then the minimal initial investment for a super-replicating portfolio,
 $\pi_0$
, is given by
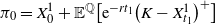 $\pi_0 = X^1_0 + \mathbb E^{\mathbb Q}\big[\mathrm{e}^{-r t_1}\big(K - X^1_{t_1}\big)^+\big]$
, where we recall that
 $\mathbb Q$
is an equivalent probability measure under which the discounted asset prices are martingales.
A minimal super-replicating hedge
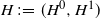 $H \;:\!=\; (H^0, H^1)$
is given by
 \begin{align*} H^0_t & \;:\!=\; \begin{cases} K\mathrm{e}^{-rt_1}\bigg(1 - \Phi\bigg(\dfrac{\log({X^1_t}/{K}) + (t_1 - t)(r - ({\sigma^2}/{2}))} {\sigma\sqrt{t_1 - t}}\bigg)\bigg) & \textit{for }\; 0 \leq t \leq t_1, \\[5pt] \mathrm{e}^{-rt_1}\big(K - X^1_{t_1}\big)^+ & \textit{for }\; t_1 < t \leq T, \\[5pt] \end{cases} \\[5pt] H^1_t & \;:\!=\; \begin{cases} \Phi\bigg(\dfrac{\log({X^1_t}/{K}) + (t_1 - t)(r + ({\sigma^2}/{2}))} {\sigma\sqrt{t_1 - t}}\bigg) & \textit{for }\; 0 \leq t \leq t_1, \\[5pt] 1 & \textit{for }\; t_1 < t \leq T, \\[5pt] \end{cases} \end{align*}
where
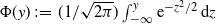 $\Phi(y) \;:\!=\; ({1}/{\sqrt{2 \pi}})\int_{-\infty}^y\mathrm{e}^{-{z^2}/{2}}\,\mathrm{d} z$
denotes the cumulative distribution function of the standard normal random variable.
Proof. Recall the notation
 \begin{align*}D_0(Y) \;:\!=\; \mathbb E^{\mathbb Q}[\mathrm{e}^{-rt_1}Y], \qquad D_{k}(Y) \;:\!=\; \max\big(b(X^1_{t_{k}}),\mathbb E^{\mathbb Q} \big[\mathrm{e}^{-r(t_{k+1} - t_{k})}Y\mid\mathcal F_{t_{k}}\big]\big)\end{align*}
for any random variable Y. By Theorem 3.1, the minimal super-replication price
 $\pi_0$
is then given by
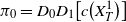 $\pi_0 = D_0 D_1\big[c\big(X^1_T\big)\big]$
. First, note that
 \begin{align*} D_{1}\big[c\big(X^1_T\big)\big] = D_1\big[X^1_T\big] & = \max\big(b\big(X^1_{t_{1}}\big),\mathbb E^{\mathbb Q}\big[\mathrm{e}^{-r(T - t_1)}X^1_T\mid\mathcal F_{t_{1}}\big]\big) \\[5pt] & = \max\big(b\big(X^1_{t_{1}}\big), X^1_{t_1}\big) \\[5pt] & = \max\big(\max\big(K, X^1_{t_1}\big), X^1_{t_1}\big) = \max\big(K , X^1_{t_1}\big) , \end{align*}
where on the second line we have used the martingale property of the discounted stock price under
 $\mathbb Q$
. To compute
 $\pi_0$
, we have
 \begin{align*} \pi_0 = D_0D_{1}\big[c\big(X^1_T\big)\big] & = D_0\big[\max\big(K , X^1_{t_1}\big)\big] \\[5pt] & = E^{\mathbb Q}\big[\mathrm{e}^{-rt_1}\max\big(K, X^1_{t_1}\big)\big] \\[5pt] & = E^{\mathbb Q}\big[\mathrm{e}^{-rt_1}X^1_{t_1} + \mathrm{e}^{-rt_1}\big(K - X^1_{t_1}\big)^+\big] \\[5pt] & = X^1_0 + E^{\mathbb Q}\big[\mathrm{e}^{-rt_1}\big(K - X^1_{t_1}\big)^+\big], \end{align*}
where again in the third line we have used the martingale property of the discounted stock price. Note that the minimal super-replication portfolio can be viewed as a combination of a long position in the underlying and a long position of an European put option with exercise time
 $t_1$
.
Next, we derive the expression for the hedge. First, we show that the given portfolio
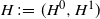 $H \;:\!=\;(H^0, H^1)$
is well defined, i.e. it satisfies assumptions (C1) and (C2) in Definition 2.2. To this end, consider a European put option on the underlying with exercise time
 $t_1$
and strike price K, with corresponding payoff
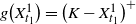 $g\big(X^1_{t_1}\big) = \big(K - X^1_{t_1}\big)^+$
. By standard results (see [Reference Elliott and Kopp1, Theorem 7.6.2]), a replicating portfolio
 $R \;:\!=\; (R^0, R^1)$
of the European put option with exercise time
 $t_1$
for
 $t \in [0, t_1]$
is given by
 \begin{align*} R^0_t & \;:\!=\; K\mathrm{e}^{-rt_1}\bigg(1 - \Phi\bigg(\frac{\log({X^1_t}/{K}) + (t_1 - t)(r - ({\sigma^2}/{2}))} {\sigma\sqrt{t_1 -t}}\bigg)\bigg), \\[5pt] R^1_t & \;:\!=\; \Phi\bigg(\frac{\log({X^1_t}/{K}) + (t_1 - t)(r + ({\sigma^2}/{2}))} {\sigma\sqrt{t_1 - t}}\bigg) - 1. \end{align*}
Noting this, we may write our portfolio H as
 \begin{align*} H^0_t & \;:\!=\; \begin{cases} R^0_t + J^0_t & \mathrm{for }\; 0 \leq t \leq t_1, \\[5pt] \mathrm{e}^{-rt_1}\big(K - X^1_{t_1}\big)^+ & \mathrm{for }\; t_1 < t \leq T, \\[5pt] \end{cases} \\[5pt] H^1_t & \;:\!=\; \begin{cases} R^1_t + J^1_t & \mathrm{for }\; 0 \leq t \leq t_1, \\[5pt] 1 & \mathrm{for }\; t_1 < t \leq T, \\[5pt] \end{cases} \end{align*}
where
 $J^0_t = 0$
,
 $J^1_t = 1$
. Now we check that assumption (C2) holds. Indeed, H is clearly non-negative on
 $(t_1, T]$
, since the holdings in both the riskless and underlying assets are non-negative, while on
 $(0, t_1)$
it is the sum of the two non-negative portfolios R and
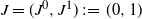 $J = (J^0, J^1) \;:\!=\; (0, 1)$
.
Next, we check the self-financing condition (C1). On
 $(0, t_1]$
, it is the sum of the two self-financing portfolios R and J, and thus is self-financing on this interval. On the other hand, on the interval
 $(t_1, T]$
,
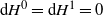 $\mathrm{d} H^0 = \mathrm{d} H^1 = 0$
, and thus we need only check the self-financing condition for times s, t with
 $s < t_1 < t$
. To this end, we compute
 \begin{align*} \int_s^t X^0_t\,\mathrm{d} H^0_t + \int_s^t X^1_t\,\mathrm{d} H^1_t & = \int_s^{t_1}X^0_t\,\mathrm{d} H^0_t + \int_s^{t_1}X^1_t\,\mathrm{d} H^1_t + X^0_{t_1}\big(H^{0+}_{t_1} - H^0_{t_1}\big) + X^1_{t_1}\big(H^{1+}_{t_1} - H^1_{t_1}\big) \\[5pt] & = X^0_{t_1}\big(H^{0+}_{t_1} - H^0_{t_1}\big) + X^1_{t_1}\big(H^{1+}_{t_1} - H^1_{t_1}\big) \\[5pt] & = X^0_{t_1}H^{0+}_{t_1} + X^1_{t_1}H^{1+}_{t_1} - V_{t_1}(H) \\[5pt] & = \mathrm{e}^{rt_1}\big(\mathrm{e}^{-rt_1}\big(K - X^1_{t_1}\big)^+\big) + X^1_{t_1} - \big[\big(K - X^1_{t_1}\big)^+ + X^1_{t_1}\big] = 0, \end{align*}
where we have written
 $H^{0+}_{t_1}$
to denote
 $\lim_{t \to t_1^+} H^0_t$
, and likewise for
 $H^{1+}_{t_1}$
.
Thus, the portfolio H is a self-financing portfolio. Now we check that it is indeed a super-replicating portfolio for the contingent option. It is sufficient to check that
 $V_{t_i}(H) \geq f_{t_i}$
a.s. for
 $i = 1, 2$
. But for
 $i = 1$
, we see that
 \begin{equation*} V_{t_1}(H) = V_{t_1}(R) + V_{t_i}(J) = \big(K - X^1_{t_1}\big)^+ + X^1_{t_1} = \max\big(K, X^1_{t_1}\big) = f_{t_1}, \end{equation*}
while for
 $i = 2$
, i.e. at time
 $t_2 = T$
, we have
 \begin{equation*} V_{T}(H) = X^1_{T} + X^0_T\mathrm{e}^{-rt_1}\big(K - X^1_{T}\big)^+ \geq X^1_{T} = f_T. \end{equation*}
This shows that the portfolio is super-replicating, as desired. Finally, we check that H is a minimal super-replicating portfolio. It is sufficient to check that H achieves the minimal super-replication price, which by Theorem 3.1 we know is
 \begin{align*}\pi_0 \;:\!=\; X^1_0 + \mathbb E^{\mathbb Q}\big[\mathrm{e}^{-r t_1}\big(K - X^1_{t_1}\big)^+\big].\end{align*}
But, by writing
 \begin{equation*} V_0(H) = V_0(J) + V_0(R) = X^1_0 + \mathbb E^{\mathbb Q}\big[\mathrm{e}^{-r t_1}\big(K - X^1_{t_1}\big)^+\big] = \pi_0, \end{equation*}
we verify this immediately. This concludes the proof.
4. Existence of a replicating portfolio
Given that a super-replication trading strategy exists, a natural question to ask is: when is this super-replication portfolio a replicating portfolio? That is, the payoff of the portfolio is exactly the same as the option payoff at the exercise time. To make the above precise, we record here a few initial definitions.
Definition 4.1. (Replicating portfolio.) A replicating portfolio for the life-contingent option
 $(f, \tau)$
is a self-financing portfolio
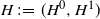 $H \;:\!=\; (H^0, H^1)$
with associated value process V such that
 $V_\tau(H) = f_\tau$
almost surely.
Definition 4.2. (Universally replicable.) We say that the life-contingent option f is universally replicable if, for all stopping times
 $\tau$
independent of the process taking finitely many values, there exists a replicating portfolio for
 $(f, \tau)$
.
Now we state the main theorem of this section.
Theorem 4.1. The life-contingent option is universally replicable if and only if the discounted option price process
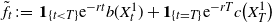 $\tilde f_t \;:\!=\; \textbf{1}_{\{t < T\}}\mathrm{e}^{-rt}b(X^1_t) + \textbf{1}_{\{t = T\}}\mathrm{e}^{-rT}c\big(X^1_T\big)$
is an
 $\mathcal F_t$
-martingale on (0, T] under the equivalent martingale measure
 $\mathbb Q$
.
Proof. Suppose first that the discounted option price process
 $\tilde f_t$
is a martingale. Consider the Black–Scholes replicating portfolio H for the simple European claim with payoff
 $f_T$
at time T given by Proposition 3.1. By [Reference Elliott and Kopp1, Lemma 7.5.9], the discounted value process
 $\tilde V$
of the replicating portfolio satisfies
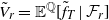 $\tilde V_r = \mathbb E^{\mathbb Q}[\tilde f_T\mid\mathcal F_r]$
for
 $r \in [0, T]$
. Hence,
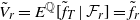 $\tilde V_r = E^{\mathbb Q} [\tilde f_T\mid \mathcal F_r] = \tilde f_r$
almost surely for each
 $r \in [0, t]$
, where in the last equality we have applied the martingale property of
 $\tilde f$
. Thus, the undiscounted values also satisfy
 $V_r = f_r$
a.s. We hence conclude that for any given stopping time
 $\tau$
,
 $V_\tau = f_\tau$
a.s., i.e. H is a replicating portfolio for the life-contingent option with terminal time
 $\tau$
, as desired.
For the other direction, suppose the life-contingent option is universally replicable, and let
 $s, t \in [0, T]$
,
 $s < t$
, be arbitrary times. We want to show that
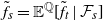 $\tilde f_s = \mathbb E^{\mathbb Q}[\tilde f_t\mid \mathcal F_s]$
almost surely. To this end, let
 $\tau$
be a stopping time independent of the asset filtration taking value s or t with probability
 $\frac{1}{2}$
each. Since the life-contingent option is universally replicable, there exists a replicating portfolio H associated with this
 $\tau$
. By the same argument as in the proof of Proposition 3.2, we must have that the value process V of H satisfies
 $V_t = f_t$
a.s., and
 $V_s = f_s$
a.s.
From the equality
 $V_t = f_t$
a.s., we deduce that H is a replicating portfolio for the simple European-style claim with payoff
 $f_t$
at time t. By [Reference Pascucci8, Theorem 7.13], the replicating portfolio for such a payoff is unique, and hence the equality in Proposition 3.1 holds, i.e.
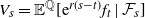 $V_s = \mathbb E^{\mathbb Q}[\mathrm{e}^{r(s-t)}f_t\mid\mathcal F_s]$
. Since
 $V_s = f_s$
a.s., we have
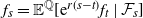 $f_s = \mathbb E^{\mathbb Q}[\mathrm{e}^{r(s-t)}f_t\mid\mathcal F_s]$
, and rearranging the equality leads to the desired result
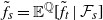 $\tilde f_s = \mathbb E^{\mathbb Q}[\tilde f_t\mid\mathcal F_s]$
a.s.
5. Conclusion
We have investigated the super-replication problem for life-contingent options. We proved the existence of a minimal super-replication portfolio, and found necessary and sufficient conditions for the existence of a replication portfolio.
There are several potential directions for future research. It would be of interest to extend the analysis to include stopping times that do not take a discrete set of values, but rather have continuous support. It may also be of interest to investigate life-contingent options whose payoffs are functions of the entire path of the asset process. In this case, the option payoff process would be non-Markovian, presenting a novel difficulty in the analysis. An extension of the work to life-contingent options depending on multiple risky assets also seems to be a fruitful line of research. In addition to market models with multiple risky assets, other extensions of the market model, such as including the possibility of jumps in the asset prices, might also be considered. Finally, we could extend the analysis to exercise times that are not independent of the risky asset, but depend on it crucially. For example, in a Lévy market with jumps, we could take the exercise time to be the first time a large jump in stock prices is made.
Appendix A. Proof of Proposition 3.4
Proof. Let
 $(C, \mathcal B(C))$
denote the Wiener space of continuous functions
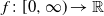 $f\colon [0, \infty) \to \mathbb R$
with
 $f(0) = 0$
. Consider also
 $(\mathbb R, \mathcal B(\mathbb R))$
, the space of real numbers with its usual Borel sigma-algebra. Further, let
 $\mathbb P_0$
denote the Wiener measure on C, i.e. the law of a standard Brownian motion. Let
 $\mathbb P_1$
be an arbitrary probability measure on
 $\mathbb R$
supported on finitely many values in (0, T], to be interpreted as the law of the stopping time
 $\tau$
.
Now let
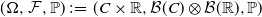 $(\Omega,\mathcal F,\mathbb P) \;:\!=\; (C \times \mathbb R,\mathcal B(C) \otimes \mathcal B(\mathbb R),\mathbb P)$
, where
 $\mathbb P \;:\!=\; \mathbb P_0 \times \mathbb P_1$
. Then the probability space supports a Brownian motion W and a stopping time
 $\tau$
independent of each other. Indeed, we may set
 $W(\omega, r) = \omega$
and
 $\tau(\omega, r) = r$
. By construction, W is a Brownian motion,
 $\tau$
is a stopping time with prescribed law
 $\mathbb P_1$
, and since
 $\mathbb P$
is a product measure, W and
 $\tau$
are independent of each other.
Finally, we note that
 $\Omega$
, being the product of Radon probability spaces, is itself a Radon probability space. This concludes the proof.
Acknowledgements
The authors would like to thank the referees and the handling editor for their many helpful comments and suggestions.
Funding information
H. Yang’s research was partially supported by a grant from Xi’an Jiaotong-Liverpool University (grant number RDF-23-01-006).
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


