




No CrossRef data available.
MONOTONICITY AND CONVEXITY OF SOME FUNCTIONS ASSOCIATED WITH DENUMERABLE MARKOV CHAINS AND THEIR APPLICATIONS TO QUEUING SYSTEMS
Published online by Cambridge University Press: 12 December 2005
Abstract
Motivated by various applications in queuing theory, this article is devoted to the monotonicity and convexity of some functions associated with discrete-time or continuous-time denumerable Markov chains. For the discrete-time case, conditions for the monotonicity and convexity of the functions are obtained by using the properties of stochastic dominance and monotone matrix. For the continuous-time case, by using the uniformization technique, similar results are obtained. As an application, the results are applied to analyze the monotonicity and convexity of functions associated with the queue length of some queuing systems.
Information
- Type
- Research Article
- Information
- Probability in the Engineering and Informational Sciences , Volume 20 , Issue 1 , January 2006 , pp. 67 - 86
- Copyright
- © 2006 Cambridge University Press
1. INTRODUCTION
In queuing analysis, the queue length of customers is an important performance measure. Quite often, we are interested in the information on the queue length as a function of time. For instance, we may like to know how the mean queue length changes as a function of time or under what conditions the mean queue length is a monotone, convex, or concave function of time. For many queuing models, the queue length process can be described by a Markov chain. Thus, the study of the queuing process for those queuing models is equivalent to the study of a Markov chain with a finite or countable (denumerable infinitely) state space (i.e., a denumerable Markov chain) (see Kemeny, Snell, and Knapp [11]). The objective of this article is to study the monotonicity, convexity, or concavity of some functions associated with denumerable Markov chains.
There have been a large number of articles and some books in the literature dealing with the monotonicity of stochastic processes. For instance, Doorn [4] discussed the stochastic monotonicity of birth-and-death processes and Stoyan [21] studied the stochastic monotonicity of Markov processes with applications in queuing theory. By using some partial orderings defined on a set of matrices, He [7] studied the monotonicity of the corresponding rate matrix R for the Markov chain of the GI/M/1 type (see Neuts [16]). Lindvall [13] discussed the problem of the monotonicity and convexity of birth-and-death processes by using the coupling method. Shanthikumar and Yao [20] studied the strong stochastic convexity of parameterized random variables.
In queuing theory, there have been a number of articles in the literature dealing with the monotonicity and convexity of the mean waiting time or the throughput of queuing systems. For example, Dyer and Proll [5] showed that the mean waiting time in the M/M/c queue is strictly decreasing and convex in c (the number of servers in the system). Weber [23] extended that result to the GI/G/c queue. Shanthikumar and Yao [19] showed that the throughput in the M/M/c/K queue is increasing and concave in arrival rate. Shanthikumar and Yao [20] established the strong stochastic convexity for the mean waiting time of the GI/G/1 queue. Wang [22] showed that the actual waiting time of the nth customer in the GI/G/1 queue is stochastically increasing and concave in n in the sense of the usual stochastically larger order.
For many queuing systems, the queue length process can be characterized by a discrete-time or continuous-time denumerable Markov chain. For example, the queue length process in the M/M/c queue can be characterized by a birth-and-death process. The queue length process in the M/G/1 or GI/M/c queue can be described by a Markov chain embedded at the departure epochs or at the arrival epochs (see Cohen [2] or Hsu [8]), respectively. Unlike the waiting time process, the study of the monotonicity and convexity of the queue length process is limited. Lindvall [13] showed the monotonicity and convexity of the mean queue length for the M/M/c queue under certain conditions. In this article the monotonicity and convexity of some functions associated with Markov chains are investigated. Some general conditions for the monotonicity or convexity are found. Based on these results, conditions for some functions associated with the queue length of some queuing systems are found to be monotonic, convex, or concave in time.
For convenience, the results of this article are shown only for Markov chains with a countable state space, although all results hold for Markov chains with a finite state space. That explains why the word “denumerable” is used in the title of this article.
The rest of the article is organized as follows. In Section 2 we provide the definitions of stochastic dominance and monotone matrix. Some general conditions for functions associated with Markov chains to be monotone, convex, or concave are given in Section 3. By using the uniformization technique (see Dijk [3], Gross and Miller [6], or Medhi [14]), the results are extended to the case of continuous-time Markov chains. In Section 4 the results obtained in Section 3 are applied to a number of queuing systems such as the M/M/c, M/G/1, and GI/M/c queues. Conditions for some functions of the queue length to be monotone, convex, or concave are found. Some comments on future research are provided in Section 5.
Throughout this article, we use Z+ to denote the set of nonnegative integers and R+ for the set of nonnegative real numbers. We use x(i) to denote the ith component of a vector x and ai,j to denote the (i,j)-th entry of a matrix A. Let 〈x,y〉 denote the inner product of two vectors x and y (i.e.,

). The terms “increasing” and “decreasing” mean “nondecreasing” and “nonincreasing,” respectively.
2. STOCHASTIC DOMINANCE AND MONOTONE MATRIX
Let λ = (λ(0),λ(1),…) and μ = (μ(0),μ(1),…) be two probability distributions defined on Z+, and let P be a stochastic matrix.
Definition 2.1: We say that λ dominates μ, denoted by λ ≥d μ (or, equivalently, μ ≤d λ), if

Note that stochastic dominance of measures is similar to the stochastically larger order of probability distributions (see Ross [17], Shaked and Shanthikumar [18], or Stoyan [21]). An equivalent way to define λ ≥d μ is that

holds for all increasing (decreasing) functions f(·) defined on Z+, where f(·) has a vector representation f = (f(0),f(1),…).
Definition 2.2: Let pi = (pi,0,pi,1,···) denote the ith row of a stochastic matrix P, i ≥ 0. The matrix P is called monotone if pi ≤d pi+1 for i ≥ 0, or, equivalently, for i ≥ 0,

A monotone matrix has the following useful properties.
Proposition 2.1: Assume that a stochastic matrix P = (pi,j)i,j≥0 is monotone and that λ and μ are two probability distributions defined on Z+.
(i) If λ ≥d μ, then

(ii) If λ ≥d μ and function f(·) defined on Z+ is increasing (decreasing), then

Proof: It is easy to see that to prove (i), we only need to show λP ≥d μP. If λ ≥d μ, let λ′ = λP and μ′ = μP. Then

. Similarly, we have

. Thus, λ′ and μ′ are also probability distributions defined on Z+. Let

. In view of the monotonicity of the matrix P, we know that ξi(k) is decreasing in i for all k ≥ 0. Hence, for k ≥ 0,

Thus, λP ≥d μP.
Part (ii) can be shown by part (i) and Eq. (2). █
Remark 2.1: In Definition 2.2, it is possible to define the monotonicity of P as pi ≥d pi+1 for i ≥ 0. Nonetheless, such a definition does not lead to results such as part (i) in Proposition 2.1. In fact, if λ ≥d μ, then λP ≤d μP under the new definition. Thus, it is more difficult to compare {λPn, n ≥ 0} and {μPn, n ≥ 0}. Therefore, we will not explore such monotonicity of P in this article.
Remark 2.2: Stochastic dominance and a monotone matrix are related to Markov chain theory in the following manner. Suppose that the stochastic matrix P is monotone; then the discrete dominance theory (see Lindvall [13, p.134]) ensures the existence of Markov chains
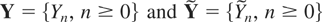
governed by P such that, almost surely,

if the initial distributions λ of Y and μ of

satisfy λ ≥d μ.
3. MONOTONICITY AND CONVEXITY
In this section, we investigate the monotonicity and convexity of some functions associated with Markov chains for both the discrete-time and continuous-time cases. Note that all Markov chains considered in Sections 3–5 have a countable state space. In addition, we assume that Markov chains are irreducible and aperiodic in the discrete-time case and are irreducible in the continuous-time case.
3.1. The Discrete-Time Markov Chain Case
Consider a discrete-time Markov chain Y = {Yn, n ≥ 0}. Let P = (pi,j) be the transition probability matrix of Y.
Let λ be the initial probability distribution of the Markov chain Y. Let Eλ(·) be the expectation of Y when the initial distribution of Y is λ. Define

for function f(·) defined on Z+. Let hf = (hf(0),hf(1),···). Then Eq. (6) can be rewritten as hfT = PfT − fT, where T denotes the transpose of the vector. It is readily seen that hf(i) is the mean drift of the Markov chain Y with respect to function f(·) at the state i. Thus, we call hf the mean-drift function of Y with respect to f(·).
For the Markov chain Y with transition matrix P, it is well known that P{Yn = i} = (λPn)(i), i ≥ 0. Thus, we have Eλ [f(Yn)] = 〈λPn,f〉. In this article we study the monotonicity and convexity of the function Eλ [f(Yn)] for the Markov chain Y with an initial distribution λ. The objective is to find conditions under which the function Eλ [f(Yn)] is increasing, decreasing, convex, or concave in n. For the continuous-time Markov chain {X(t),t ≥ 0}, we want to find conditions under which the function Eλ [f(X(t))] is increasing, decreasing, convex, or concave in t. The relationship between the functions Eλ [f(X(t))] and Eλ [f(Yn)] is given in Section 3.2.
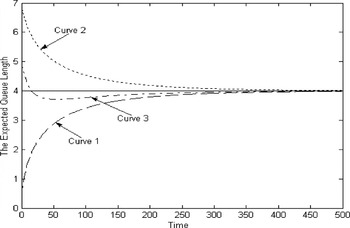
For example, consider an M/M/1 queue (see Section 4.1). The queue length process X = {X(t), t ≥ 0} is a birth-and-death process. The mean queue length Eλ [X(t)] at time t is depicted in Figure 1 for different initial distributions λ. Figure 1 shows that the function Eλ [X(t)] can be monotone, convex, or concave if the initial distribution λ is chosen properly (curves 1 and 2). Figure 1 also shows that, in general, the function Eλ [X(t)] may not be monotone, convex, or concave (curve 3). Thus, some conditions must be imposed on λ to ensure desired properties on Eλ [X(t)].

The mean queue length curves for an M/M/1 queue with ρ = 0.8.
In general, to ensure monotonicity, convexity, or concavity on the function Eλ [f(Yn)], certain conditions must be imposed on the transition matrix P, the initial distribution λ, and the function f(·). The conditions considered in this article are closely related to the stochastic dominance of measures. Formally, we state the conditions as follows:

The following theorem shows the monotonicity, convexity, and concavity of the function Eλ [f(Yn)] under the above conditions. The theorem also explains why the above conditions are utilized in this article.
Theorem 3.1: Consider an irreducible and aperiodic discrete-time Markov chain Y with transition matrix P. Let λ be the initial distribution of Y. Function f(·) is defined on Z+. We assume that Eλ [f(Yn)] is finite for n ≥ 0.
(i) If Conditions I and II in Eq. (7) hold and the function f(·) is increasing, then the function Eλ [f(Yn)] is increasing in n. If Conditions I and II in Eq. (7) hold and the function f(·) is decreasing, then the function Eλ [f(Yn)] is decreasing in n.
(ii) If Conditions I and II′ in Eq. (7) hold and the function f(·) is increasing, then the function Eλ [f(Yn)] is decreasing in n. If Conditions I and II′ in Eq. (7) hold and the function f(·) is decreasing, then the function Eλ [f(Yn)] is increasing in n.
(iii) If Conditions I, II, and III in Eq. (7) hold, then the function Eλ [f(Yn)] is concave in n. If Conditions I, II, and III′ in Eq. (7) hold, then the function Eλ [f(Yn)] is convex in n.
(iv) If Conditions I, II′, and III in Eq. (7) hold, then the function Eλ [f(Yn)] is convex in n. If Conditions I, II′, and III′ in Eq. (7) hold, then the function Eλ [f(Yn)] is concave in n.
Proof: We only give a proof of (iii). Others can be proved similarly. Since λ and P satisfy Conditions I and II in Eq. (7), by Proposition 2.1 we have λPn+1 ≥d λPn for all n ≥ 0. In view of the monotonicity of the mean-drift function hf, we obtain 〈λPn+1,hf〉 ≤ 〈λPn,hf〉. Hence, 〈λPn+2,f〉 + 〈λPn,f〉 ≤ 2〈λPn+1,f〉; that is, Eλ [f(Yn)] is concave in n. █
Remark 3.1: Assume that f(·) defined on Z+ is increasing. f(·) satisfies Condition III in Eq. (7) if and only if the function Δf is excessive (see Çinlar [1, p.204]), where the function Δf is defined by Δf(i + 1) = f(i + 1) − f(i),i ≥ 0.
In general, it is not straightforward to check the conditions required in Theorem 3.1. Nonetheless, for some interesting special cases, these conditions can be checked (see Sections 4 and 5 for examples). We also point out that, in Theorem 3.1, the Markov chain Y does not have to be recurrent. Thus, in later sections, we do not require the Markov chains to be recurrent or the queueing models to be stable, unless stated otherwise.
Although the Markov chain Y in Theorem 3.1 is not required to be positive recurrent, some of the conditions in Eq. (7) have a close relationship with the positive recurrence of Y. For instance, if Y is positive recurrent, then Condition II implies λ ≤d π, where π is the steady state distribution of Y. If the mean-drift function hf is negative and decreasing, then the Markov chain Y is positive recurrent by Foster's criterion (see Cohen [2]). Such relationships are useful when we choose the initial distribution λ for our examples in Sections 4.
3.2. The Continuous-Time Markov Chain Case
Based on the above results for discrete-time Markov chains, we can obtain similar results for continuous-time Markov chains by using the uniformization technique.
Let X = {X(t), t ∈ R+} be a homogeneous and continuous-time Markov chain. Let Q = (qi,j) be the infinitesimal generator of X. Then Markov process X is said to be uniformizable if

If the Markov chain X is uniformizable, then for any ν ≥ supi≥0(−qi,i), we define

where I is the identity matrix. Note that P defined by Eq. (8) is a stochastic matrix. We have (Medhi [14])

To study functions associated with X, we make use of a Markov chain with transition matrix P given in Eq. (8). We denote the Markov chain as Y. Assume that X and Y have the same initial distribution λ. Let

Suppose that the function g(λ,t) in Eq. (10) has derivative of order 2. Then by Eqs. (8) and (9), we can establish the following relationships between X and Y:

where Eλ [f(Yn)] is defined for the Markov chain Y.
Equation (11) indicates that to study functions associated with X, it is sufficient to study functions associated with Y. More specifically, by Eq. (11), we know that the convexity of the function Eλ [f(Yn)] implies the convexity of the function Eλ [f(X(t))]. Similarly, the monotonicity of the function Eλ [f(Yn)] implies the monotonicity of the function Eλ [f(X(t))]. Counterparts of conditions in Eq. (7) are given as follows:

We state the monotonicity, convexity, and concavity of the function Eλ [f(X(t))] in the following theorem; it can be proved by combining Theorem 3.1 and Eq. (11). We omit its proof.
Theorem 3.2: Consider a continuous-time Markov chain X with infinitesimal generator Q. Suppose that X is uniformizable, and let ν ≥ supi(−qi,i). We assume that Markov chain Y with transition matrix P given by Eq. (8) is irreducible and aperiodic. Suppose that X and Y have the same initial distribution λ. We assume that Eλ [f(X(t))] is finite for t ≥ 0.
(i) If Conditions Icont and IIcont in Eq. (12) hold and if the function f(·) defined on Z+ is increasing, then the function Eλ [f(X(t))] is increasing in t. If Conditions Icont and IIcont in Eq. (12) hold and if the function f(·) defined on Z+ is decreasing, then the function Eλ [f(X(t))] is decreasing in t.
(ii) If Conditions Icont and IIcont′ in Eq. (12) hold and if the function f(·) defined on Z+ is increasing, then the function Eλ [f(X(t))] is decreasing in t. If Conditions Icont and IIcont′ in Eq. (12) hold and if the function f(·) defined on Z+ is decreasing, then the function Eλ [f(X(t))] is increasing in t.
(iii) If Conditions Icont, IIcont, and IIIcont in Eq. (12) hold, then the function Eλ [f(X(t))] is concave in t. If Conditions Icont, IIcont, and IIIcont′ in Eq. (12) hold, then the function Eλ [f(X(t))] is convex in t.
(iv) If Conditions Icont, IIcont′, and IIIcont in Eq. (12) hold, then the function Eλ [f(X(t))] is convex in t. If Conditions Icont, IIcont′, and IIIcont′ in Eq. (12) hold, then the function Eλ [f(X(t))] is concave in t.
4. APPLICATIONS TO QUEUING SYSTEMS
In this section, we show how the monotonicity and convexity can help us gain insight into the queue length processes of a number of queuing systems.
4.1. The M/M/1 Queue
Consider an M/M/1 queue with an infinite number of waiting rooms, a first-in–first-served service discipline, arrival rate α, and service rate β (see Cohen [2]). We assume that α > 0 and β > 0. Let X(t) represent the number of customers in the system at time t. It is well known that the queue length process X = {X(t), t ∈ R+} is a continuous-time Markov chain with an infinitesimal generator

The Markov chain X with generator Q given by Eq. (13) is a special continuous-time Markov chain. The Markov chain X is irreducible and its discrete counterpart P defined by Eq. (8) is irreducible and aperiodic if α > 0 and β > 0. Let ν ≥ α + β and define ρ = α/β. Conditions in Eq. (12) can be simplified to the following:

Note that for Conditions M/M/1(III) and M/M/1(III′), we assume that Δf(0) = 0, where Δf is a function defined in Remark 3.1.
To interpret the above conditions probabilistically, we use the following generalized likelihood ratio order defined for nonnegative measures. For two measures λ and μ, we say λ ≤lr μ if λ(i + 1)μ(i) ≤ λ(i)μ(i + 1) for i ≥ 0. For more about the likelihood ratio order for random variables, see Shaked and Shanthikumar [18]. Let

. If the queuing system is stable (i.e., ρ < 1),

can be normalized to a probability measure π = (1 − ρ, (1 − ρ)ρ, (1 − ρ)ρ2,…), which is the steady state distribution of X. If

can be normalized to a probability measure π−1 = (ρ − 1)(1/ρ, 1/ρ2, 1/ρ3,…).
Proposition 4.1: Condition M/M/1(I) in Eq. (14) is satisfied for all ν ≥ α + β. Condition M/M/1(II) in Eq. (14) holds if and only if

. Condition M/M/1(II′) in Eq. (14) holds if and only if

. Condition M/M/1(III) in Eq. (14) holds if and only if

, where the function Δ2f is defined by Δ2f(i + 1) = Δf(i + 1) − Δf(i) for i ≥ 0. Condition M/M/1(III′) in Eq. (14) holds if and only if

.
Proof: It is clear that the first conclusion holds. The second and third conclusions hold by the definition of the generalized likelihood ratio order defined earlier. The last two conclusions are true since, by Eq. (14), ρΔ2f(i + 2) ≤ (≥)Δ2f(i + 1) for i ≥ 0. █
Using Proposition 4.1, it is easy to check the conditions for the monotonicity and convexity of the function Eλ [f(X(t))]. For Condition M/M/1(II) or M/M/1(II′) in Eq. (14), we consider the following initial distributions:

By Proposition 4.1, it can be verified that

satisfies Condition M/M/1(II) in Eq. (14) for all
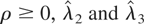
satisfy Condition M/M/1(II) if

satisfy Condition M/M/1(II) if

satisfy Condition M/M/1(II′) in Eq. (14) if

satisfy neither Condition M/M/1(II) nor Condition M/M/1(II′).
For Condition M/M/1(III) in Eq. (14), we consider the function f(i) = ik, i ≥ 0, where k = 1,2,…. By Proposition 4.1, if k = 1, Condition M/M/1(III) in Eq. (14) holds for all ρ > 0; if k = 2, Condition M/M/1(III) in Eq. (14) holds for

and Condition M/M/1(III′) in Eq. (14) holds for ρ ≥ 1; if k = 3, Condition M/M/1(III) in Eq. (14) holds for

, Condition M/M/1(III′) in Eq. (14) holds for ρ ≥ 1; and if k = 4, Condition M/M/1(III) in Eq. (14) holds if

and Condition M/M/1(III′) in Eq. (14) holds for ρ ≥ 1. Details for cases with k > 4 are omitted.
For the above initial distributions and function f(·), the monotonicity, convexity, and concavity of the function Eλ [f(X(t))] can be obtained immediately from Theorem 3.2. Details are as follows:
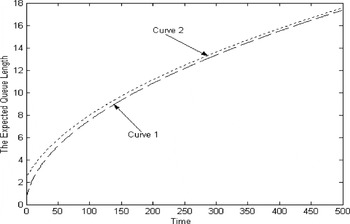
Case 1. Suppose that f(i) = i, i ≥ 0. The mean queue length

is increasing and concave in t. In addition, if ρ ≥ 1, then

is increasing and concave in t. Figure 2 depicts the two functions

for ρ = 1 (curves 1 and 2); we can get similar curves for ρ = 1.05, and ρ = 1.35. Note that the queues are unstable for ρ = 1, 1.05, and 1.35.

The mean queue length curves for an M/M/1 queue with ρ = 1.
Case 2. Suppose that f(i) = i, i ≥ 0, and ρ < 1. Then the mean queue length

is equal to a constant ρ/(1 − ρ);

is decreasing and convex in t. Since

does not satisfy Condition M/M/1(II) or Condition M/M/1(II)′ in Eq. (14),

does not have the monotonicity and convexity (curve 3 in Fig. 1).
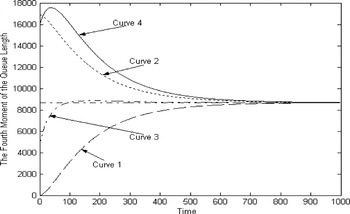
Case 3. Suppose that

.

satisfies Condition M/M/1(II) and

satisfies Condition M/M/1(II′). The function f(·) does not satisfy Condition M/M/1(III),
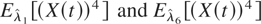
do not have the monotonicity and convexity (curves 1 and 2 in Fig. 3). However, if

, then

is increasing and concave and

is decreasing and convex.

The fourth moment of queue length curves for an M/M/1 queue with ρ = 0.8.
Remark 4.1: We point out that similar results can be obtained for the M/M/c(c ≥ 1) queue with an infinite number of waiting rooms, a first-in–first-out served discipline, and c parallel servers. The only necessary change in Proposition 4.1 is that the vector

is changed to

Details are omitted.
4.2. The M/G/1 Queue
Consider an M/G/1 queue where customers arrive according to a Poisson process with parameter α (α > 0) and the service times are independent and identically distributed (i.i.d.) random variables and follow a general distribution G(·). We further assume that the mean and second moment of service times exist; the mean and variance of service times are denoted by E [S] and Var[S] = E [S2] − (E [S])2, respectively. Assume that service times are independent of the interarrival times and customers are served according to the order of their arrival (see Cohen [2]). Let Yn denote the number of customers left in the system right after the nth customer departs from the system. Then Y = {Yn, n ≥ 0} is a discrete-time Markov chain, for which the transition probability matrix P is given by
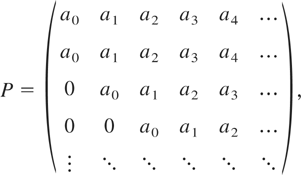
where

for k ≥ 0. It is easy to see that the Markov chain Y is aperiodic and irreducible if α > 0. Let

. For the M/G/1 queue, conditions in Eq. (7) can be further simplified to the following:

First, it is clear that the matrix P is always monotone; that is, Condition M/G/1(I) in Eq. (18) always holds for the M/G/1 queue. Second, by routine calculations, it is easy to verify that λ = (1,0,0,…) and λ = (a02/(1 − a1),a0(1 − a0)/(1 − a1),(1 − a0 − a1)/(1 − a1),0,…) satisfy Condition M/G/1(II) in Eq. (18). It can also be verified that λ = (0,0,0,π0,π1,π2,…) satisfies Condition M/G/1(II′) in Eq. (18), where π = (π0,π1,π2,…) is the steady state distribution of the Markov chain Y if ρ < 1. Third, it can be shown that Condition M/G/1(III) in Eq. (18) always holds for f(i) = i, since the mean-drift function hf is given by (ρ,ρ − 1,ρ − 1,…). Condition M/G/1(III) in Eq. (18) holds for f(i) = i2 if ρ ≤ 1 and for f(i) = i3 if 2ρ + ρ2(1 + Var[S]) ≤ 2.
For the queuing system, the mean queue length Eλ [Yn] (i.e., f(i) = i) is increasing and concave in n if λ = (1,0,0,…) or λ = (a02/(1 − a1),a0(1 − a0)/(1 − a1), (1 − a0 − a1)/(1 − a1),0,…). For λ = (0,0,0,π0,π1,π2,…), if the queuing system is stable, the mean queue length Eλ [Yn] is decreasing and convex in n. Furthermore, for higher moments of the queue length, Eλ [Yn2] (i.e., f(i) = i2) is increasing and concave in n if λ = (1,0,0,…) or λ = (a02/(1 − a1),a0(1 − a0)/(1 − a1), (1 − a0 − a1)/(1 − a1),0,…) and ρ ≤ 1 and Eλ [Yn3] (i.e., f(i) = i3) is increasing and concave in n if λ = (1,0,0,…) or λ = (a02/(1 − a1),a0(1 − a0)/(1 − a1),(1 − a0 − a1)/(1 − a1),0,…) and 2ρ + ρ2(1 + Var[S]) ≤ 2.
Remark 4.2: Note that for f(i) = i2, the condition for the mean-drift function hf to be decreasing is ρ ≤ 1 for the M/G/1 case. For the M/M/1 case, that condition is

. The reason is that we only consider the queue length at departure epochs for the M/G/1 case, whereas the queue length at an arbitrary time is considered for the M/M/1 case.
Remark 4.3: Condition III′ in Eq. (7) does not hold for f(i) = ik,k ≥ 1, in the M/G/1 queue, since f(0) ≥ f(1) is not satisfied in this case.
4.3. The GI/M/1 Queue
Consider a GI/M/1 queue. Assume that the interarrival times are i.i.d. random variables, where the common distribution is A(·) and the mean interarrival time equals

. The service times are independent exponential random variables with parameter β (β > 0). Assume that service times are independent of interarrival times and that customers are served according to their order of arrival (see Cohen [2]). Let Yn denote the number of customers seen by the nth customer at its arrival epoch. Then {Yn, n ≥ 0} is a discrete-time Markov chain with a transition probability matrix P given by

where
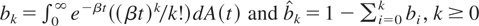
. It is easy to verify that the Markov chain Y is irreducible and aperiodic if β > 0. Conditions in Eq. (7) can be simplified as follows:

Similar to the M/G/1 queue, Condition GI/M/1(I) in Eq. (20) always holds for the GI/M/1 queue. For the initial distribution λ, it can be verified that λ = (1,0,0,…),

satisfy Condition GI/M/1(II) in Eq. (20), where r is the unique root of the equation s = A*(β − βs) that is inside the circle

. The vector λ = (0,0,1 − r,(1 − r)r,(1 − r)r2,…) satisfies Condition GI/M/1(II′) in Eq. (20). For Condition GI/M/1(III) in Eq. (20), it always holds for f(i) = i. For f(i) = i2, Condition GI/M/1(III) in Eq. (20) holds if 3b0 + b1 ≤ 1. For f(i) = i3, Condition GI/M/1(III) in Eq. (20) holds if 7b0 + b1 < 1 and 19b0 + 7b1 + b2 ≤ 7.
For the queue length at arrival epochs, it is easy to see that Eλ [Yn] is increasing and concave if λ = (1,0,0,…),

For those λ, Eλ [Yn2] is increasing and concave if 3b0 + b1 ≤ 1 and Eλ [Yn3] is increasing and concave if bi,i ≥ 0, satisfy 7b0 + b1 < 1 and 19b0 + 7b1 + b2 ≤ 7. Eλ [Yn] is decreasing and convex if λ = (0,0,1 − r,(1 − r)r,(1 − r)r2,…).
The results of the monotonicity and convexity of functions associated with queue length for the GI/M/1 queue can be generalized to the GI/M/c(c ≥ 1) queue in a straightforward manner, although formulas can be much more involved.
Remark 4.4: Condition III′ in Eq. (7) does not hold for f(i) = i in the GI/M/1 queue since b0 + b1 ≤ 1 always holds; that is, Condition GI/M/1(III) in Eq. (20) always holds for k = 0.
4.4. A Queuing System with Batch Service
Consider a single-server processor sharing queuing system in which the the interarrival times are i.i.d. random variables, where the common distribution is A(·). Let τn denote the arrival epoch of the nth customer, let Q(t) be the number of customers in the system at time t, and let Yn ≡ Q(τn−) denote the number of customers seen by the nth customer at its arrival epoch. We assume that if Yn = i, the arrival of the next customer causes all customers to leave the system (so that the queue becomes empty) with probability σi (0 < σi < 1),i = 0,1,…. We call such a customer a negative customer. Thus, the queuing system becomes empty if a service is completed or a negative customer arrives. The service times are i.i.d. exponential random variables with parameter β (β > 0). Assume that service times are independent of interarrival times. Then {Yn, n ≥ 0} is a discrete-time Markov chain. The transition probability matrix P of Y = {Yn, n ≥ 0} is given by

where

. The Markov chain Y is aperiodic and irreducible. Conditions in Eq. (7) can be further simplified as follows:

Thus, Condition Batch(I) in Eq. (22) holds if and only if the sequence {θi, i ≥ 0} is increasing in i. For Condition Batch(II) in Eq. (22), it holds if λ(i + 1) ≤ λ(i)θi, for all i ≥ 0. By the definition of the generalized likelihood ratio order defined in Section 4.1, Condition Batch(II) in Eq. (22) holds if λ ≤lr μ, where μ = (μ(0),μ(1),…) is a measure defined on

. The measure μ can be normalized to a probability measure by taking

. Similarly, Condition Batch(II′) in Eq. (22) holds if λ ≥lr μ. The following measures also satisfy Condition Batch(II) in Eq. (22): λ = (1,0,0,…) and

For Condition Batch(III) in Eq. (22), it is satisfied for f(i) = i if

it is satisfied for f(i) = i2 if

and it is satisfied for f(i) = i3 if

Similarly, we can get the corresponding conditions under which Condition Batch(III′) in Eq. (22) holds.
Then Eλ [Yn] is increasing and concave if

{θi} is increasing in i, and Eq. (23) holds. Eλ [Yn2] is increasing and concave if

{θi} is increasing in i, and Eq. (24) holds. Eλ [Yn3] is increasing and concave if

{θi} is increasing in i, and Eq. (25) holds.
In the literature the Markov chain with transition matrix given by Eq. (21) was called a backward recurrent time chain (see Meyn and Tweedie [15, p.64]).
5. CONCLUDING REMARKS AND FUTURE RESEARCH
In this article, we studied the monotonicity and convexity of some functions associated with denumerable Markov chains. For the discrete-time case, we obtained conditions for the monotonicity, convexity, and concavity. By using the uniformization technique, similar results were obtained for the continuous-time case.
It is interesting to identify explicit conditions for Markov chains with a general transition matrix, since the expressions of the conditions described in Eq. (7) cannot be checked easily for applications in this case. In what follows, we provide an example to illustrate that it is possible to find explicit conditions under which the functions associated with a Markov chain have monotonicity and convexity, where its transition matrix has a different form compared with those discussed in Section 4.
Consider a Markov chain Y = {Yn, n ≥ 0} with a countable state space Z+ and a transition probability matrix P given by

where 0 < p ≤ 1, p = 1 − p, e = (1,1,1,…)T, and μ = (μ(0),μ(1),μ(2),…) is a probability distribution defined on Z+, and e is a column vector whose elements all equal one. The process Y with transition matrix given by Eq. (26) is called the discrete autoregressive process of order 1 (DAR(1)) (see Hwang, Choi, and Kim [9] or Hwang and Sohraby [10]).
By routine calculations, it can be verified that Condition I in Eq. (7) holds for all p and μ. For other conditions, we have the following:
Condition II in Eq. (7) holds if and only if μ ≥d λ.
Condition II′ in Eq. (7) holds if and only if λ ≥d μ.
Condition III in Eq. (7) holds if and only if the function f(·) defined on Z+ is increasing.
Condition III′ in Eq. (7) holds if and only if the function f(·) defined on Z+ is decreasing.
By Theorem 3.1, we have the following:
(i) If μ ≥d λ and the function f(·) defined on Z+ is increasing, then the function Eλ [f(Yn)] is increasing and concave in n.
(ii) If μ ≥d λ and the function f(·) defined on Z+ is decreasing, then the function Eλ [f(Yn)] is decreasing and convex in n.
(iii) If λ ≥d μ and the function f(·) defined on Z+ is increasing, then the function Eλ [f(Yn)] is decreasing and convex in n.
(iv) If λ ≥d μ and the function f(·) defined on Z+ is decreasing, then the function Eλ [f(Yn)] is increasing and concave in n.
Future research is in the monotonicity and convexity of some functions associated with parallel queuing systems with correlated arrival processes to different queues described by Li and Xu [12]; the main difficulty in analyzing those systems is that the presence of correlation makes the explicit computation of the joint performance measure either intractable or computationally intensive.
References
REFERENCES
Çinlar, E.
(1975).
Introduction to stochastic processes.
Englewood Cliffs, NJ:
Prentice Hall.
Cohen, J.W.
(1982).
The single server queue, rev. ed.
Amsterdam:
North-Holland.
Dijk, N.M.V.
(1990).
On a simple proof of uniformization for continuous and
discrete-state continuous-time Markov chains.
Advances in Applied Probability
22:
749–750.Google Scholar
Doorn, E.V.
(1980).
Stochastic monotonicity and queueing applications of
birth–death processes.
New York:
Springer-Verlag.
Dyer, M.E. &
Proll, L.G.
(1977).
On the validity of marginal analysis for allocating servers in
M/M/c queues.
Management Sciences
23:
1019–1022.Google Scholar
Gross, D. &
Miller, D.R.
(1984).
The randomization technique as a modeling tool and solution
procedure for transient Markov processes.
Operations Research
32:
343–361.Google Scholar
He, Q.M.
(1999).
Partial orders and the matrix R in matrix analytic methods.
SIAM Journal of Matrix Analysis and Its Applications
20:
871–885.Google Scholar
Hsu, G.H.
(1985).
Stochastic service systems.
Beijing:
Science Press.
Hwang, G.U.,
Choi, B.D., &
Kim, J.K.
(2002).
The waiting time analysis of a discrete-time queue with arrivals as
a discrete autoregreessive process of order 1.
Journal of Applied Probability
39:
619–629.Google Scholar
Hwang, G.U. &
Sohraby, K.
(2003).
On the exact analysis of a discrete-time queueing system with
autoregressive inputs.
Queueing Systems
43:
29–41.Google Scholar
Kemeny, J.G.,
Snell, J.L., &
Knapp, A.W.
(1976).
Denumerable Markov chains.
New York:
Springer-Verlag.
Li, H.J. &
Xu, S.H.
(2000).
On the dependence structure and bounds of correlated parallel queues
and their applications to synchronized stochastic systems.
Journal of Applied Probability
37:
1020–1043.Google Scholar
Lindvall, T.
(1992).
Lecture on the coupling method.
New York:
Wiley.
Medhi, J.
(1991).
Stochastic models in queueing theory.
London:
Academic Press.
Meyn, S.P. &
Tweedie, R.L.
(1993).
Markov chains and stochastic stability.
New York:
Springer-Verlag.
Neuts, M.F.
(1981).
Matrix-geometric solutions in stochastic models: An algorithmic
approach.
Baltimore:
The Johns Hopkins University Press.
Ross, S.M.
(1983).
Stochastic processes.
New York:
Wiley.
Shaked, M. &
Shanthikumar, J.G.
(1994).
Stochastic orders and their applications.
New York:
Academic Press.
Shanthikumar, J.G. &
Yao, D.D.
(1991).
Multiclass queueing systems: Polymatroidal structure and optimal
scheduling control.
Operations Research
40:
293–299.Google Scholar
Shanthikumar, J.G. &
Yao, D.D.
(1992).
Strong stochastic convexity: Closure properties and
applications.
Journal of Applied Probability
28:
131–145.Google Scholar
Stoyan, D.
(1983).
Comparison methods for queues and other stochastic models.
New York:
Wiley.
Wang, C.L.
(1999).
On the transient delays of M/G/1
queues.
Journal of Applied Probability
36:
882–893.Google Scholar
Weber, R.R.
(1980).
On the marginal benefit of adding servers to G/GI/m
queues.
Management Sciences
26:
946–951.Google Scholar
The mean queue length curves for an M/M/1 queue with ρ = 0.8.
The mean queue length curves for an M/M/1 queue with ρ = 1.
The fourth moment of queue length curves for an M/M/1 queue with ρ = 0.8.
 You have
Access
- 1
- Cited by