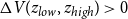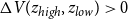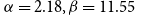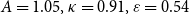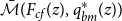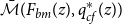1. Introduction
In the U.S., the measured markups (i.e., the difference between price and marginal cost as a percentage of the cost) have been increasing since the early 1980s (Barkai, Reference Barkai2020; de Loecker et al. Reference de Loecker, Eeckhout and Unger2020). The recent literature has investigated the impact of increasing markups on other aggregate variables, such as industrial concentration and labor share. However, there is no consensus on what forces have driven the increase in markups over the past four decades (Grossman & Oberfield, Reference Grossman and Oberfield2022). Our paper thus examines and quantitatively evaluates one such force: the relaxation of antitrust policies and the ensuing surging M&A activities since the 1980s. Over time, M&As have become an increasingly important strategy for firms to gain a competitive edge, acquire new technology and skills, or expand to new markets.
We first measure the firm-level markups of Compustat firms using the method proposed by de Loecker and Warzynski (Reference de Loecker and Warzynski2012) and de Loecker et al. (Reference de Loecker, Eeckhout and Unger2020), and construct an aggregate-level markup using the cost-weighted average. As strong evidence for rising market power, the measured aggregate markup has increased from 13.93% in 1981–1985 to 23.68% in 2013–2017. On the other hand, obtaining competitive advantage is typically both a reason for and a consequence of M&As. Since the Reagan administration took office in the early 1980s, antitrust policy implementation has been drastically relaxed in the U.S. (Mueller, Reference Mueller1984; Philippon, Reference Philippon2019), allowing for a surge in M&A activities. Using the Compustat public firms database along with the Thompson Financial SDC Platinum M&As database, we find that the aggregate M&A rate, defined as the ratio of M&As to the number of Compustat firms in our merged sample, increases from 11.52% in 1981–1985 to 19.11% in 2013–2017.
We then build a dynamic general equilibrium model with heterogeneous firms, endogenous markups, and an M&A market, to analyze the economic consequences of increasing M&A activities. Our model builds on the M&A market setup proposed by David (Reference David2021) under a heterogeneous firm dynamics framework. M&A is characterized by a two-sided search and matching process. Firms endogenously decide their search intensities bearing search costs. M&As are assumed to improve the acquirer’s post-merger productivity, and the magnitude of the increase depends on the pre-merger productivity of both parties to capture the technological or managerial complementarity between the acquiring firm and the target. Potential acquirer and target firms jointly decide whether to consummate the M&A deal, as they split the surplus through Nash bargaining.
We extend the model of David (Reference David2021) that assumes a competitive goods market to one that features endogenous and heterogeneous market power by introducing a Kimball aggregator. Larger firms face lower elasticity of demand, hence optimally charging a higher markup. M&As raise the acquirers’ productivity and sizes, and consequently, their post-merger markups. Given that an individual firm’s monopoly power is affected by the ease of finding M&A opponents and consummating deals, the proposed model allows us to study the impact of different antitrust policy regimes on the evolution of the aggregate markup and the markup distribution.
To quantitatively evaluate the impact of M&As on the aggregate markup, we discipline the benchmark model parameters with moments from the 1981–1985 U.S. economy. In particular, parameters are calibrated such that the model-generated increase in post-merger markups at the firm level matches the data counterpart. The equilibrium properties of the quantified model match stylized facts documented in the literature. For example, large (and productive) firms search more intensively as acquirers, and raise their bar for synergistic targets, which is consistent with empirical findings in Andrade et al. (Reference Andrade, Mitchell and Stafford2001 and Rhodes-Kropf and Robinson (Reference Rhodes-Kropf and Robinson2008). Then, we vary the value of search costs to target the 2013–2017 U.S. M&A rate, as in the model, search costs can reflect the strictness of antitrust policies. The counterfactual exercise generates a 5.80 percentage points increase in the economy’s aggregate markup, while that in the data is 9.75 percentage points. That gives the main conclusion of our paper: changes in the M&A market account for
 $59.45\%$
of the observed rise in the aggregate markup.
As mentioned earlier, the paper is most closely related to David (Reference David2021) among the literature studying the aggregate implications of M&As. Beyond that, Xu (Reference Xu2017) studies how M&As contribute to economic growth under an endogenous growth framework, while Fons-Rosen et al. (Reference Fons-Rosen, Roldan-Blanco and Schmitz2024) examines the impact of M&As on the innovation incentives of both incumbent firms and startups. However, neither paper studies the evolution of markups as we do. A large number of studies empirically investigate the impact of M&As on acquirers’ performance, typically using stock returns as a measurement for merger gains (Andrade et al. Reference Andrade, Mitchell and Stafford2001; Bhagata et al. Reference Bhagata, Dongb, Hirshleiferc and Noahd2005). Our paper focuses on the market power dimension.
The paper is also related to the recent literature (Grullon et al. Reference Grullon, Larkin and Michaely2019; Barkai, Reference Barkai2020; de Loecker et al. Reference de Loecker, Eeckhout and Unger2020) that documents rising market powers in the U.S. since the 1980s. Philippon (Reference Philippon2019) systematically collects evidence on rising concentration and market powers and declining investment in the U.S. and argues that they indicate a (inefficiently) decreasing domestic competition rather than a rise of (efficient) superstar firms over the past few decades, especially after 2000. He points to the weakening of merger reviews and the decline in entry associated with the rise of entry regulations as the main drivers. In particular, the author concludes that “What is undeniable, however, is that mergers have been allowed to proceed at an unprecedented pace, which has significantly contributed to a rise in the concentration in the U.S.”. Our research contributes to the literature by quantitatively evaluating the impact of a more active M&A market, triggered by the relaxation of antitrust policies, on the rise in aggregate markup.
The rest of the paper is organized as follows. In Section 2, we present the evolution of markups and M&A activities, and show a positive correlation between M&As and changes in firm-level markups. The dynamic general equilibrium model is proposed in Section 3. Section 4 presents quantification and quantitative evaluations of the model. Concluding remarks are provided in Section 5.
2. Motivational facts
This section provides the main motivation facts. We first document that the measured markups — the difference between price and marginal cost as a percentage of the cost — have been rising since the early 1980s, among Compustat public firms.Footnote 1 We provide the aggregate as well as distributional comparisons of markups in the 1980s and the 2010s, and then present the facts on surging M&A activities, from the same period.
Rising markups
The rise in markups in the U.S. is documented by various studies in the literature (Barkai, Reference Barkai2020; de Loecker et al. Reference de Loecker, Eeckhout and Unger2020). We measure markup using the method proposed by De Loecker and Warzynski (Reference de Loecker and Warzynski2012).Footnote 2 The measurement is based on the following observation: at the firm level, the ratio of price to marginal cost equals the ratio of the output elasticity to an input without significant adjustment cost, to the cost share of this input.Footnote 3 The input cost share can be directly calculated from firms’ balance sheets, while the elasticity is estimated by using a control function approach following the productivity estimation literature (Olley and Pakes, Reference Olley and Pakes1996; Levinsohn and Petrin, Reference Levinsohn and Petrin2003).Footnote 4
The aggregate markup and changes in markup distribution.
Note: This figure shows the time series of the aggregate markup, defined as the cross-firm weighted average with weights equal to the cost of goods sold, among public firms (Panel (a)), and change in the markup distribution restricting to values between 0% and the 95th percentile (Panel(b)). Data source: Compustat.

There are a total of 341,540
 $firm \times year$
valid observations from 1951–2020 in Compustat.Footnote
5
The aggregate markup is calculated as a cost-weighted average
 \begin{equation*} \bar {\mathcal{M}}_t = \sum _i \omega _{i,t} \times \mathcal{M}_{i,t}, \end{equation*}
where
 $\mathcal{M}_{i,t}$
is firm
 $i$
’s measured markup at year
 $t$
, and the weight
 $\omega _{i,t}$
equals to its cost of goods sold.Footnote
6
Panel (a) of Figure 1 presents the evolution of aggregate markup in our data period. Variations considered, the aggregate markup in the early 1980s is at about the same level as in the 1950s. However, over the following three to four decades, the measured aggregate markup has increased sharply from around 14% to close to 24% in the 2010s.
Panel (b) of Figure 1 presents the distribution of estimated markups among Compustat public firms in 1983 v.s. that in 2015. The markup distributions for both years are characterized by a fat upper tail but also demonstrate clear differences. In particular, the 2015 distribution has more firms with markups on the upper tail, while the 1983 distribution featured significantly more firms with low-to-medium markups. Consistent with what’s documented in the literature, the rise in aggregate markup is mainly driven by the fattening upper tail of the distribution.
Another widely used measurement of markup and market power is the Lerner index, which relies less on assumptions about the production function. Like German and Philippon (Reference German and Philippon2017) and Grullon et al. (Reference Grullon, Larkin and Michaely2019), we measure firm-level Lerner index as operating income after depreciation divided by sales using Compustat data, then aggregate them using sales as weight.Footnote 7 Figure A.1 in the appendix plots the aggregate Lerner index from 1951 to 2020. Consistent with the evolution of aggregate markup in Figure 1, the Lerner index was relatively stable until the 1980s and shows a clear rising trend after that.
Surging M&As
Since the Reagan administration took office in the early 1980s, the antitrust policy implementation in the U.S. has been drastically relaxed. More lenient antitrust policies are reflected by a surge in M&A activities. We combine the Compustat public firms database and the Thompson Financial SDC Platinum M&As database, and construct a Compustat-SDC merged sample using the CUSIP identifier recorded in both databases.Footnote 8 A Compustat firm in a year is labeled as an acquirer if it has acquired at least one other firm in the SDC database, and as a target if it was acquired by other firms in that year.
Table 1 shows the ratio of M&As to the number of Compustat firms in our merged sample, which we dub the aggregate “M&A rate,” in 1981–1985 and 2013–2017.Footnote 9 The M&A rate has seen a significant rise over the decades—an increase of 7.59 percentage points in levels and of about 66% in relative terms.Footnote 10
Aggregate M&A rate among compustat firms

Note: The aggregate M&A rate is the ratio of total M&As to total number of Compustat firms. Data source: The merged Compustat-SDC sample.
Obtaining competitive advantage is typically both a reason for and a consequence of M&A transactions. Using our Compustat-SDC merged sample, we empirically establish a correlation between M&As and changes in a firm’s markup. Formally, we run the following firm-year regression
 \begin{equation} \Delta \ln (1+\mathcal{M}_{i,j,t+1}) = \delta _0 + \underbrace {0.0174^{***}}_{(s.e.\;0.0028)} \times MA_{i,j,t}+\mathcal{M}_{i,j,t}+D_t+D_j+ \nu _{i,j,t}. \end{equation}
The term
 $\mathcal{M}_{i,j,t}$
is the markup of firm
 $i$
in industry
 $j$
in year
 $t$
, and
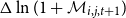 $\Delta \ln (1+\mathcal{M}_{i,j,t+1})$
is the change in the logarithmic ratio of price to marginal cost from year
 $t$
to
 $t+1$
.
 $MA_{i,j,t}$
is an indicator variable and equals to
 $1$
for firm
 $i$
if it has acquired at least one other firm in year
 $t$
. The year and 2-digit industry dummies,
 $D_t$
and
 $D_j$
, are added to account for any time trend or industrial heterogeneity. The estimated coefficient for
 $MA_{i,j,t}$
,
 $0.0174$
, is significant at the 1% level. That is, the acquiring firm’s price-to-marginal cost ratio increases after the M&A transaction, by a magnitude of 1.74% in relative terms. That is, for an average firm with a markup of 14%, M&A increases its markup to about 15.98%. As firms’ merger decisions are endogenous, the correlation pattern shown in equation (1) is not causal. Later, we use the correlation implied by equation (1) as a target moment to discipline parameters in the model with endogenous merger decisions of firms, such that the model-generated post-merger increase in the markups of acquirers matches that in the data.
3. The model
We now present the modeling framework to evaluate the impact of M&As on the aggregate markup. A firm is characterized by its productivity, which determines the firm’s optimal size. Firms of different sizes face different elasticities of demand, allowing for an endogenous markup distribution. Firms find potential targets to acquire on a market featuring two-sided search and matching. Successfully matched pairs jointly decide whether to consummate an M&A deal, through a Nash bargaining of the surplus. To capture the technological and managerial complementarity between acquirers and targets, we allow acquiring firms to increase their productivity by merging worthy opponents.
3.1 Production
Time is continuous and denoted by
 $t$
. The economy consists of two sectors—an intermediate goods sector where each single firm monopolizes in producing an intermediate variety, and a final good sector where firms produce competitively by aggregating over intermediate varieties. We start with the competitive final good sector.
Final good
The final good is produced competitively by aggregating over intermediate varieties according to the following aggregator
 \begin{equation} \int _{\Omega _t} \sigma \left ( \frac {y_t(\omega )}{Y_t} \right ) d\omega = 1, \end{equation}
where
 $Y_t$
and
 $y_t(\omega )$
denote the quantity of the final good and intermediate variety
 $\omega$
at time
 $t$
, respectively.
 $\Omega _t$
is the set of varieties available at time
 $t$
, whose size
 $M_t$
is determined endogenously by the number of incumbent intermediate firms. Following Kimball (Reference Kimball1995), the function
 $\sigma (q)$
is assumed to be strictly increasing, strictly concave, and satisfy
 $\sigma (1)=1$
.
Use the final good as the numeraire and denote by
 $p_t(\omega )$
the price of an intermediate variety
 $\omega$
. Competitive final good producers optimally choose the quantity of intermediate varieties to maximize profit, that is
 \begin{equation*} \max _{y_t(\omega )}\quad Y_t-\int _{\Omega _t} p_t(\omega )y_t(\omega )d\omega , \end{equation*}
subject to the production technology specified in equation (2). The maximization problem gives the demand function facing the producer of variety
 $\omega$
as
 \begin{equation} p_t(\omega ) = \sigma ' \left ( \frac {y_t(\omega )}{Y_t} \right ) D_t, \end{equation}
where
 $D_t$
is a common term facing all intermediate producers, defined as
 \begin{equation*} D_t \equiv \left ( \int _{\Omega _t} \sigma '\left (\frac {y_t(\omega )}{Y_t}\right )\frac {y_t(\omega )}{Y_t} d\omega \right )^{-1}. \end{equation*}
One useful property of this demand function is that, depending on the functional form of
 $\sigma (q)$
, the elasticity of demand facing the producer of an intermediate variety can vary across its relative size
 $q \equiv y/Y$
. This property allows the model to generate an endogenous markup distribution among intermediate firms.
For the
 $\sigma (q)$
function, we follow Klenow and Willis (Reference Klenow and Willis2016) and Edmond et al. (Reference Edmond, Midrigan and Xu2023) to choose the following specification
 \begin{equation*} \sigma (q) = 1 + (\beta -1)\exp \left (\frac {1}{\alpha }\right ) \alpha ^{\frac {\beta - \alpha }{\alpha }} \left [ \Gamma \left (\frac {\beta }{\alpha },\frac {1}{\alpha }\right ) - \Gamma \left (\frac {\beta }{\alpha },\frac {q^{\frac {\alpha }{\beta }}}{\alpha } \right ) \right ], \end{equation*}
where
 $\alpha \gt 0$
,
 $\beta \gt 1$
, and
 $\beta \gt \alpha$
.
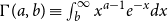 $\Gamma (a,b) \equiv \int _b^\infty x^{a-1} e^{-x} dx$
is the upper incomplete Gamma function.
Using this specification, the term
 $\sigma '(q)$
in the intermediate goods demand function can be written as
 \begin{equation} \sigma '(q)=\frac {\beta -1}{\beta }\exp \left (\frac {1-q^{\frac {\alpha }{\beta }}}{\alpha }\right ), \end{equation}
which is a decreasing function of the relative size
 $q$
. Consequently, larger firms face smaller demand elasticity and charge a higher markup.
Intermediate goods
Each intermediate variety is produced monopolistically by a single firm. An intermediate firm with productivity
 $z \gt 0$
uses labor as the sole input and has access to the following linear production technology
 \begin{equation} y_t = z \ell _t. \end{equation}
The intermediate monopolist optimally chooses the quantity and price of its product, and the amount of labor to employ, to maximize profit
 \begin{equation*} \pi _t(z) \equiv \max _{p_t,y_t,\ell _t} \; p_t y_t - W_t \ell _t, \end{equation*}
subject to the demand function and production technology specified in equations (3) and (5).
 $W_t$
is the competitive wage rate at time
 $t$
.
Drop the time subscript
 $t$
and substitute away price and labor, we can rewrite the intermediate firm’s profit maximization problem as
 \begin{equation*} \pi (z) = \max _{q}\quad \left [ \sigma '(q)q - \frac {w}{z} q \right ] D Y, \end{equation*}
where
 $w \equiv W/D$
represents the “effective wage rate.” With our specification of
 $\sigma '(q)$
in equation (4), the optimality condition yields
 \begin{equation} \frac {\beta -1}{\beta }\exp \left (\frac {1-q^{\frac {\alpha }{\beta }}}{\alpha }\right ) \left ( \frac {\beta -q^{\frac {\alpha }{\beta }}}{\beta } \right ) = \frac {w}{z}. \end{equation}
From the first-order condition, one can solve for the equilibrium relative size
 $q^*$
as a function of the productivity
 $z$
, and the markup satisfies
 \begin{equation} \mathcal{M} \equiv \frac {p}{MC}-1 = \frac {{q^*}^\frac {\alpha }{\beta }}{\beta - {q^*}^\frac {\alpha }{\beta }}. \end{equation}
As
 $\alpha , \beta \gt 0$
, equation (7) indicates a positive correlation between firm sizes and markups.
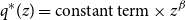
Understanding the correlation between productivity and markups requires further analysis of the equilibrium relative size function
 $q^*(z)$
. The following proposition shows important properties of the function.
Proposition 1.
The equilibrium relative size
 $q^*(z)$
is strictly increasing in
 $z$
, and “convex-concave.” That is, there exist
 $0\lt \underline {z}_q \leq \bar {z}_q$
to such that,
 $q^*(z)$
is strictly convex on
 $(0,\underline {z}_q)$
and strictly concave on
 $(\bar {z}_q,\infty )$
. Furthermore,
 $q^*(z)$
is bounded above by a constant
 $\beta ^{\frac {\beta }{\alpha }}$
.
Proposition1 states that firms with higher productivity have larger market shares. Since the markup is an increasing function of market share, more productive firms also charge a higher markup.
The following proposition summarizes the convexity of the profit function. Proofs for both propositions can be found in Appendix B.
Proposition 2.
The intermediate firm’s profit
 $\pi (z)$
is strictly increasing in
 $z$
, and “convex-concave.” That is, there exist
 $0\lt \underline {z}_\pi \leq \bar {z}_\pi$
such that,
 $\pi (z)$
is strictly convex in
 $(0,\underline {z}_\pi )$
and strictly concave in
 $(\bar {z}_\pi ,\infty )$
.
3.2 The M&A Market
In the previous layout of the model, productivity determines a firm’s market share, as well as the markup it charges. To single out the effect of M&As on markups, we assume that productivity changes only through M&As, and stays constant otherwise.
Following the setup in David (Reference David2021), which builds on the canonical framework of Shimer and Smith (Reference Shimer and Smith2000), M&As are introduced to the economy as a process of search and matching, and bargaining over the surplus. Firms search on both sides of the market simultaneously.Footnote 11 Once met, the pair of potential acquirer and target jointly decide whether to consummate the deal, through a Nash bargaining over the surplus. In a backward order, we start by introducing the merger technology and bargaining.
Merger technology
Individual firms use M&As to gain a competitive edge, acquire new technology and skills, or expand to a new market. In our model, though, the synergy between firms is characterized by the following merger technology: upon a successful matching with a potential target firm of productivity
 $z_T$
, an acquirer firm with pre-merger productivity
 $z_A$
can expect post-merger productivity of
 \begin{equation} z_M = A z_A^\kappa z_T^\varepsilon , \end{equation}
given that the M&A is consummated. If not, both parties leave with their productivity unaffected. We further assume that
 $A \gt 1$
,
 $\kappa + \varepsilon \gt 1$
, and
 $\kappa \gt \varepsilon \gt 0$
.Footnote
12
The merger technology captures productivity improvement from technological or managerial complementarity between firms. In the Cobb-Douglas form that we use, parameter
 $A$
represents a general scale of synergy, that is, improvement regardless of pre-merger productivity. Parameters
 $\kappa$
and
 $\varepsilon$
govern the elasticity with respect to the acquirer’s and the target’s pre-merger performance, respectively.
 $\kappa \gt \varepsilon$
implies that the post-merger productivity relies more heavily on the productivity of acquirers. David (Reference David2021) gives an excellent discussion on how this assumption makes it more likely for large firms to acquire small ones,Footnote
13
which is consistent with empirical findings in Andrade et al. (Reference Andrade, Mitchell and Stafford2001) and Rhodes-Kropf and Robinson (Reference Rhodes-Kropf and Robinson2008).
Let
 $V(z)$
denote the value of an intermediate firm of productivity
 $z$
. Since an M&A changes the acquirer’s post-merger productivity, the associated change of value is given by
 \begin{equation*} \Delta V(z_A, z_T) \equiv V(z_M) - V(z_A) - V(z_T), \end{equation*}
where
 $z_M$
is specified in equation (8). Naturally, we assume that an M&A will be consummated if and only if
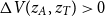 $\Delta V(z_A, z_T) \gt 0$
, that is, with a positive surplus.
Bargaining
The surplus from the M&A, if any, is split between the acquirer and the target through Nash bargaining. Let
 $\gamma \in (0,1)$
represent the bargaining power of the acquirer. In a consummated M&A transaction, the acquiring firm pays the target
 \begin{equation} P(z_A, z_T) = V(z_T) + (1-\gamma ) \times \Delta V(z_A, z_T), \end{equation}
and continues with post-merger productivity
 $z_M$
, while the target firm exits the economy.Footnote
14
For the purpose of this paper, we omit possible contractual constraints and assume that an acquirer can always commit to paying such
 $P(z_A, z_T)$
, either by a lump-sum transfer or through a long-term contract.
We further define
 $G_A$
and
 $G_T$
as the gain from matching as an acquirer and a target, respectively. It follows that
 \begin{equation*} \begin{aligned} &G_A(z_A, z_T) = \max \Big \{ \gamma \times \Delta V(z_A, z_T) \, , \, 0 \Big \};\\ &G_T(z_A, z_T) = \max \Big \{ (1 - \gamma ) \times \Delta V(z_A, z_T) \, , \, 0 \Big \}. \end{aligned} \end{equation*}
These two terms will prove useful when we write down the intermediate firm’s value function.
Search and matching technology
Next, we explain how firms meet on the M&A market through a two-sided search and matching process. A firm can search on both sides of the market simultaneously with separate search intensities. In particular, denote
 $\mu _A$
and
 $\mu _T$
as its search intensities on the acquirer and the target side, respectively. Search is costly, to maintain a search intensity of
 $\mu _i$
, the firm must pay a cost of
 \begin{equation} C(\mu _i) = \frac {B}{\phi } {\mu _i}^\phi ,\quad i=A,T, \end{equation}
where
 $B\gt 0$
and
 $\phi \gt 1$
.
In equilibrium, the search intensities of a firm depend on its current productivity level. We denote the optimal choices
 $\mu _A(z)$
and
 $\mu _T(z)$
, and assume a matching technology characterized by the following matching rateFootnote
15
 \begin{equation*} \min \left \{ \int \mu _A(z) dF(z) , \int \mu _T(z) dF(z) \right \}, \end{equation*}
where
 $F(z)$
denotes the endogenous productivity distribution of firms.
This matching technology implies that if the two sides of the market are not equally populated, the short side will determine the number of matches, while the long side is rationed. Correspondingly, the market tightnesses on the acquirer and the target side are given by
 \begin{equation*} \theta _A = \min \left \{\frac {\int \mu _T(z)dF(z)}{\int \mu _A(z) dF(z)},1 \right \};\quad \theta _T = \min \left \{\frac {\int \mu _A(z)dF(z)}{\int \mu _T(z)dF(z)},1 \right \}. \end{equation*}
We assume undirected (or random) search, so the rates at which a type
 $z_A$
acquirer meets a type
 $z_T$
target, and vice versa, are given by
 \begin{equation*} \underbrace {\mu _A(z_A)}_{\text{search intensity}} \times \underbrace {\theta _A}_{\text{market tightness}} \times \underbrace {\frac {\mu _T(z_T)dF(z_T)}{\int \mu _T(z)dF(z)}}_{\text{conditional probability}};\quad \mu _T(z_T) \times \theta _T \times \frac {\mu _A(z_A) dF(z_A)}{\int \mu _A(z)dF(z)}. \end{equation*}
In the end, the rate at which M&As are consummated in the economy, i.e., the aggregate M&A rate, can be written as
 \begin{equation*} \int \int \mu _A(z_A) \theta _A \frac {\mu _T(z_T)}{\int \mu _T(z)dF(z)} \times \unicode {x1D7D9}\Big \{\Delta V(z_A,z_T)\gt 0 \Big \} dF(z_T) dF(z_A), \end{equation*}
where
 $\unicode {x1D7D9}\{\cdot \}$
is the standard index function. That is, potential M&A parties meet each other through undirected search and matching, then consummate the deal if and only if such a transaction incurs a positive change of value, or, surplus.
3.3 Equilibrium
Next, we present the value function, the evolution of productivity distribution, and the definition of a stationary equilibrium of the economy.
Value function
Assume a time discount rate of
 $\rho \gt 0$
and all incumbent firms exit at an exogenous rate
 $\eta \gt 0$
. The value of an intermediate firm with productivity
 $z$
can be written as
 \begin{equation} \begin{aligned} (\rho + \eta ) V(z) = \pi (z) & + \max _{\mu _A} \left \{\mu _A\theta _A\mathbb{E}_{z_T}[G_A(z, z_T)] - C(\mu _A)\right \}\\ & + \max _{\mu _T} \left \{\mu _T\theta _T\mathbb{E}_{z_A}[G_T(z_A, z)] - C(\mu _T)\right \}, \end{aligned} \end{equation}
i.e., the flow value of the firm equals the instantaneous profit
 $\pi (z)$
, plus the expected net gains from searching in the M&A market. With the search cost specified in equation (10), the optimal search intensities are given by
 \begin{equation} \mu _A(z) = \left \{\frac {\theta _A\mathbb{E}_{z_T}[G_A(z, z_T)]}{B}\right \}^{\frac {1}{\phi -1}}; \quad \mu _T(z) = \left \{\frac {\theta _T\mathbb{E}_{z_A}[G_T(z_A, z)]}{B}\right \}^{\frac {1}{\phi -1}}. \end{equation}
Entry, exit, and equilibrium
Incumbent firms exit the economy either by being merged, or being hit by an exogenous shock at rate
 $\eta$
. On the other hand, a firm enters the economy by paying an entry cost
 $c_E \gt 0$
upfront, then draws initial productivity from an exogenous distribution
 $H(z)$
. We assume that
 $H(z)$
follows a Pareto distribution with shape parameter
 $\xi \gt 1$
. Free entry implies that the expected value of entrants equals the cost, i.e.,
 \begin{equation} \int V(z) dH(z) = c_E. \end{equation}
Let
 $M_E$
denote the total mass of new entrants, and
 $M$
is that of incumbent firms.Footnote
16
The distribution of firm productivity,
 $F(z)$
, evolves according to the following Kolmogorov forward equation
 \begin{equation*} \begin{aligned} \dot {dF}(z) &= \underbrace {\int \mu _A(z_A)\theta _A\frac {\mu _T\left (z_T^{-1}(z,z_A)\right )}{\int \mu _T(z)dF(z)} \unicode {x1D7D9}\left \{\Delta V\left (z_A,z_T^{-1}(z,z_A)\right )\gt 0\right \} dF\left (z_T^{-1}(z,z_A)\right ) dF(z_A)}_{\text{inflow through M&As}}\\ &-\underbrace {dF(z) \times \mu _A(z)\theta _A\left [\int \frac {\mu _T(z_T)}{\int \mu _T(z)dF(z)}\unicode {x1D7D9}\left \{\Delta V(z, z_T)\gt 0\right \} dF(z_T)\right ]}_{\text{outflow through merging}}\\ &-\underbrace {dF(z) \times \mu _T(z)\theta _T\left [\int \frac {\mu _A(z_A)}{\int \mu _A(z)dF(z)}\unicode {x1D7D9} \left \{\Delta V(z_A, z)\gt 0\right \} dF(z_A)\right ]}_{\text{outflow through being merged}}\\ &-\underbrace {dF(z) \times \eta }_{\text{outflow through exogenous exit}} + \underbrace {dH(z) \times \frac {M_E}{M}}_{\text{inflow through entry}}. \end{aligned} \end{equation*}
In the equation above, we define
 \begin{equation*} z_T^{-1}(z,z_A) \equiv \left (\frac {z}{A z_A^\kappa }\right )^\frac {1}{\varepsilon }. \end{equation*}
That is, for an acquirer firm of productivity
 $z_A$
, a target of productivity
 $z_T^{-1}(z,z_A)$
is needed to make the post-merger productivity right at level
 $z$
.
This law of motion decomposes changes at the density of any state
 $z$
into five possible channels: firms previously of lower productivity might acquire others and obtain post-merger productivity of
 $z$
; firms originally with productivity
 $z$
might acquire others and arrive at a new (and higher) productivity level; firms originally with productivity
 $z$
might be acquired by others and exit the economy; firms originally with productivity
 $z$
might be hit by the exogenous exit shock; and entrants might draw an initial productivity of
 $z$
. In a stationary equilibrium, the distribution at each state must remain constant. That gives the stationary conditions
 \begin{equation*} \dot {dF}(z) = 0, \quad \forall z. \end{equation*}
To close the model, we assume that the economy admits a representative household who owns all firms. It is endowed with 1 unit of labor and supplies it inelastically. The household consumes all its income every period, as saving is not allowed. Formally, the equilibrium in our model is defined as follows:
Definition 1.
A
S
tationary
E
quilibrium of the economy consists of: aggregate variables of the economy,
 $\left \{Y, C, W, M, M_E, F(z), \theta _A, \theta _T \right \}$
; firm’s policy function and profit from the static profit maximization problem,
 $\left \{ q^*(z), \pi (z) \right \}$
; and firm’s policy functions and value function in the M&A market,
 $\left \{\mu _A(z), \mu _T(z), \unicode {x1D7D9}\left \{\Delta V\gt 0\right \}, V(z)\right \}$
, so that:
-
1. Policy functions solve their corresponding optimization problems;
-
2. The goods and labor markets clear;
-
3. The free entry condition is met;
-
4. The evolution of firm productivity distribution is consistent with the stationary conditions.
4. Quantitative analysis
In this section, we first calibrate the model’s benchmark parameters to the 1981–1985 U.S. economy, using moments from our Compustat-SDC merged sample. Then we evaluate the impact of surging M&A activities on the aggregate markup through a counterfactual exercise, in which we reduce firms’ search costs to the 2013–2017 level. We also show that the quantified model successfully replicates several stylized patterns in the U.S. M&A market.
4.1 Calibration Strategy
We calibrate the model’s benchmark economy with our Compustat-SDC merged sample in 1981–1985, that is, when the surge of M&As and the rise of markups began to happen. We start with those that can be externally calibrated, directly inferred, or taken from the literature.
We follow the literature and normalize the lower bound of firm productivity to
 $z_{min} = 1$
.Footnote
17
Moreover, we set the time discount rate
 $\rho$
to match an annual interest rate of 5%. For the exogenous exit rate,
 $\eta$
, we use the average exit rate of 7.17% calculated from the Compustat database. We assume a 50–50 split of surplus between the acquirer and target in their Nash bargaining, which is close to the estimate in David (Reference David2021). Table 2 summarizes the values of all externally calibrated parameters and their sources.
Externally calibrated parameters

Note: See detailed explanations of the parameter values in the main text.
The rest of the parameters are calibrated internally. We jointly estimate all remaining 9 parameters to minimize the total sum of distances between model-generated and data moments
 \begin{equation*} \sum _i \Bigg | \frac {\text{model}(i)-\text{data}(i)}{\text{data}(i)} \Bigg | \times 100\%. \end{equation*}
In particular, we pick 9 moments that are standard to the literature. While these parameters are jointly estimated, some moments are particularly informative about the corresponding parameters. Next, we briefly outline the logic.
The first subset of parameters regards the aggregate economy. Our specification of the Kimball aggregator contains two parameters,
 $\alpha$
and
 $\beta$
. In the theoretical layout, we showed that
 $\beta$
affects the aggregate markup level, while
 $\alpha$
governs how fast markups rise with firms’ relative sizes. Correspondingly, we use the economy’s cost-weighted aggregate markup (
 $\bar {\mathcal{M}}$
) to discipline
 $\beta$
, and the difference in markup levels between firms of the
 $90^{th}$
and
 $50^{th}$
size percentiles (
 $\Delta \mathcal{M}$
) to discipline
 $\alpha$
.Footnote
18
The former moment amounts 13.93%, while the latter is 8.60% in the 1981–1985 sample period.
For the entry cost, Hopenhayn (Reference Hopenhayn1992) discussed how it affects firms of different sizes differently. In our model, it affects the equilibrium wage rate, thereby influencing the firm size distribution. In particular, we pick the size ratio between firms of the
 $90^{th}$
and
 $50^{th}$
percentiles (
 $s_{F_{90}/F_{50}}$
), 24.10, to discipline
 $c_E$
. We use that ratio among entrants (
 $s_{H_{90}/H_{50}}$
), 18.05, to discipline the shape parameter
 $\xi$
of entrant firms’ productivity distribution
 $H(z)$
.Footnote
19
Next, we turn to parameters in the search cost function. For the scale parameter,
 $B$
, we use the aggregate M&A rate (
 $\overline {MA}$
), defined as the number of consummated M&As divided by that of Compustat firms. We use the ratio of acquirer rates between firms at the
 $90^{th}$
and
 $50^{th}$
size percentiles (
 $Acq_{F_{90}/F_{50}}$
) to discipline the curvature parameter,
 $\phi$
.Footnote
20
These two moments are 11.52% and 1.92, respectively, in the 1981–1985 sample period.
The last 3 parameters,
 $A$
,
 $\kappa$
and
 $\varepsilon$
, are from the merger technology. Parameter
 $A$
represents the general scale of M&A synergy. The higher
 $A$
is, the faster a firm’s productivity improves through the lens of M&As, as well as its size and markup. Consequently, we use the average increase in ln(1+markup) for post-merger firms (
 $\Delta \mathcal{M}_{MA}$
), as estimated empirically by regression equation (1), to discipline the parameter.Footnote
21
As for the elasticity on pre-merger productivity, David (Reference David2021) gives an excellent explanation on how they determine the size of acquirers and targets in consummated M&A transactions. We thus use the size ratio between median acquirers and median firms (
 $s_{A_{50}/F_{50}}$
), and the median size ratio between matched acquirer-target pairs in consummated M&A transactions (
 $s_{(A/T)_{50}}$
), to discipline these two parameters. The value of the former is 4.30, while that of the latter is 4.43 in the 1981–1985 sample period. Table 3 summarizes the parameters and their corresponding target moments.
Parameters calibrated by minimum distance

Note: See detailed explanations of target moments in the main text.
4.2 Model Fit
As explained in the calibration strategy, we have in total 9 parameters jointly estimated by minimum distance. We start by checking their values and the model fit on targeted moments.
Targeted moments
Table 4 presents estimation results and model fit, showing that the benchmark model replicates targeted moments well. The total sum of data-model distances is about 10 percentage points, or an average distance of 1.14 percentage points per moment. We further illustrate the identification of the model parameters in Appendix C.2.
Benchmark parameters and moments

Note: Detailed information on each moment can be found in Section 4.1. All numbers are rounded to two decimal places for better presentation.
The estimate of
 $\beta$
is close to what’s reported in Edmond et al. (Reference Edmond, Midrigan and Xu2023), while our estimate of
 $\alpha$
is higher,Footnote
22
which implies a steeper increase in markup when a firm’s productivity and size increase. We then run a regression of ln(1+markup) on ln(size) in both the quantified model and the Compustat-SDC merged sample. The obtained coefficient in the model is 0.016, which is reasonably close to the value of 0.019 estimated from the data.Footnote
23
The estimated entry cost
 $c_E$
is about a third of the average firm value, and the share of total output used in paying the entry cost is 8.42% in the stationary equilibrium. The value of
 $\xi$
indicates a skewed productivity distribution. Note that, as discussed in Proposition1, firm productivity does not translate proportionally into size. To compare the model-generated size distribution with data,Footnote
24
we further estimate a Pareto shape coefficient by regressing the logarithmic frequency on the logarithmic size, and find a slope of –1.79, or a Pareto shape coefficient of 0.79, which is close to the value of 1 found in the literature (Axtell, Reference Axtell2001).Footnote
25
Our estimate of the search costs implies an aggregate matching rate of around 18% on the M&A market. About two-thirds of the matched pairs eventually consummate the deal, while the rest willingly forgo the opportunity as their matches generate no surplus. In the model, firms of different sizes choose search intensities endogenously, thus bearing different search costs. On average, search costs take around 7% of the firm’s profit.
Though using different target moments, our estimates of the merger technology parameters are close to David (Reference David2021).Footnote
26
The value of
 $A$
implies that in general, merged firms enjoy a productivity improvement of 3%, regardless of pre-merger performance. Estimates of
 $\kappa$
and
 $\varepsilon$
confirm that post-merger productivity relies more on the productivity of acquirers. As a consequence, larger firms search more intensively, especially as acquirers, a point that is shown by rows 1 & 2 in the following Table 5.Footnote
27
Search intensities and rates across firm sizes

Note: The percentiles are ranked in terms of firm size.
 $\mu _A$
and
 $\mu _T$
denote search intensities,
 $\theta _A$
and
 $\theta _T$
denote market tightness.
 $Acq$
and
 $Tag$
denote the rates of becoming acquirers and targets, respectively. All numbers are rounded for better presentation.
Simulated M&A transactions.
Note: The vertical (horizontal) axis represents the productivity of the acquirer (target). Each dot represents a consummated M&A from the simulation, and the solid line is the OLS fit.

On the other hand, the conditional probabilities of finding a synergistic opponent are hump-shaped on both the acquirer’s and the target’s side, peaking at different percentiles (rows 3 & 4). In the end, it is firms that are large but still have the potential to grow that are more likely to be acquirers, and those that are relatively small become targets. Another important feature of merging firms is positive sorting. As size (and productivity) grows, an acquiring firm will raise its bar for the targets it is willing to merge with, and vice versa. We simulate 1 million matches on the M&A market and scatter those that are eventually consummated in Figure 2. The simulation shows a clear and positive correlation between the sizes (and productivity) of the acquirer and the target. These numerical properties of the quantified model are consistent with empirical findings in the literature (Andrade et al. Reference Andrade, Mitchell and Stafford2001; Rhodes-Kropf and Robinson, Reference Rhodes-Kropf and Robinson2008; David, Reference David2021).
Next, we turn to the situation in which firms’ search cost on the M&A market is reduced to the 2013–2017 level, to see how much rise in aggregate markup the quantified model can generate.
4.3 Surging M&As and the Aggregate Markup
As reported in Table 1, the aggregate M&A rate has increased from 11.52% for 1981–1985 to 19.11% for the 2013–2017 period in our Compustat-SDC merged sample. Equation (12) shows that a decrease in
 $B$
raises the search intensities so as the aggregate M&A rate, and can be used as a proxy for more lenient antitrust policies which fail to keep M&A activities at bay.Footnote
28
To examine the impact of surging M&A activities on the aggregate markup, we study a counterfactual economy where the scale parameter of the search cost function,
 $B$
, is recalibrated to match the M&A rate in 2013–2017, while all other parameters are kept at their benchmark values. Table 6 summarizes the results.Footnote
29
Surging M&As and the aggregate markup

Note: The explanation power is calculated as the model-generated change in the aggregate markup divided by that in the data. All numbers are rounded to two decimal places for better presentation.
Compared to the benchmark, the counterfactual economy features lower search costs, and consequently, higher search intensities and aggregate M&A rate.Footnote
30
The aggregate markup in the model increases by 5.80 percentage points, which explains about 60% of the observed change in the data. In the model, the (cost-weighted) aggregate markup
 $\bar {\mathcal{M}}$
can be written as
 \begin{equation*} \bar {\mathcal{M}}\big (F(z),q^*(z)\big ) = \int \frac {{q^*(z)}^\frac {\alpha }{\beta }}{\beta - {q^*(z)}^\frac {\alpha }{\beta }} \, \frac {\left [q^*(z)/z\right ]dF(z)}{\int \left [q^*(z)/z\right ]dF(z)}. \end{equation*}
Hence, changes in the aggregate markup can be attributed to two channels: (i) changes in the productivity distribution
 $F(z)$
; and (ii) changes in the map between productivity and firm size, as characterized by the
 $q^*(z)$
function.Footnote
31
A further decomposition exercise shows that channel (i) contributes 99.21% to the change in the aggregate markup, i.e., the rise in aggregate markup is mainly driven by a fattening productivity distribution.Footnote
32
Next, we examine the distributional impact of surging M&A activities. In particular, we look at changes in the markup distribution of firms. We first record the markup levels of different percentiles of the 1981–1985 distribution, then calculate the fraction of firms with a markup greater than those levels in the 2013–2017 distribution. For the
 $X^{th}$
percentile markup level in the 1981-1985 distribution, that more than
 $(100-X)\%$
of firms in 2013–2017 have markups greater than it indicates a fattening distribution.
Table 7 presents the comparison, our model produces changes in the markup distribution at various percentiles that are comparable to the data. Moreover, the fattening of markup distribution mainly happens around the upper percentiles, a pattern consistent with empirical findings both in De Loecker et al. (Reference de Loecker, Eeckhout and Unger2020 and that documented in panel (b) of Figure 1.
Changes in cost-weighted markup distribution

Note: The comparison is based on the cost-weighted markup distribution. We restrict to non-negative markups for all firms and all years in the data.
Overall, our quantified model suggests that surging M&A activities can cause the aggregate markup to rise. And the fattening of the markup distribution can be largely explained by the fattening of firms’ productivity distribution.Footnote 33
5. Conclusion
This paper evaluates the impact of M&As on the evolution of aggregate markup under a dynamic general equilibrium framework. We construct a model featuring heterogeneous firms, endogenous markups, and an M&A market characterized by search, matching, and Nash bargaining. We calibrate the benchmark economy to empirical moments from a Compustat-SDC merged sample in the 1981–1985 period, and then, to evaluate the impact of more lenient antitrust policies, counterfactually reduce the search costs on the M&A market to match the aggregate M&A rate in the 2013–2017 period. The counterfactual economy successfully generates a fattening markup distribution, and a 5.80 percentage points increase in the aggregate markup, which accounts for around 60% of the change observed in the U.S. economy from the 1980s to the 2010s.
Our model incorporates both the efficiency-enhancing and markup-raising effects of M&A activities. However, both effects are characterized by a single parameter — productivity. One needs to disentangle these two factors, to give a reliable implication on welfare, which we view beyond the scope of this paper. The model can be extended by including other productivity-enhancing activities such as innovation (Fons-Rosen et al. Reference Fons-Rosen, Roldan-Blanco and Schmitz2024). The aggregate impact of more lenient M&A policies could be strengthened or weakened, depending on whether self-innovation complements or substitutes M&As at the firm level. The paper also abstracts from reasons for lenient antitrust policies. International trade and globalization could be one driver. A globalized economy might encourage more domestic M&As, as firms strategically merge with domestic competitors to be better positioned in the international market. We leave these interesting questions to future research.
Acknowledgements
We are grateful to Michele Boldrin, Francisco Buera, Rodolfo Manuelli, and Yongseok Shin for their helpful comments and suggestions.
Supplementary material
The supplementary material for this article can be found at https://doi.org/10.1017/S1365100525100199