


Private pension provision is in transition, moving from employer-sponsored defined benefit (DB) pension plans towards individual defined contribution (DC) pension plans (Investment Company Institute (2017)). Many workers regard this trend as undesirable (Rhee and Boivie (Reference Rhee and Boivie2015)). Indeed, a DC plan focuses primarily on accumulating retirement wealth rather than providing a stable lifelong income stream. Recently, Bovenberg and Nijman (Reference Bovenberg and Nijman2015) propose a new pension contract called a Personal Pension with Risk sharing (PPR). A PPR unbundles the three main functions of variable annuity contracts: insurance, investment and withdrawal.Footnote 1 In particular, a PPR organizes the insurance function collectively and individualizes the investment and withdrawal functions.Footnote 2, Footnote 3
While the work by Bovenberg and Nijman (Reference Bovenberg and Nijman2015) is descriptive in nature, this paper formalizes the decumulation period of a PPR. We define the pension contract in terms of various parameters such as the investment policy and the median growth rate of the benefit payout. We show how the budget condition implies several relationships between the contract parameters. The budget condition does, however, not uniquely identify all parameters. As a consequence, individuals must specify some parameters exogenously. They can specify the parameters according to (at least) two alternative approaches: the investment approach and the consumption approach. We explore these two approaches in detail and show how they differ from each other.
In the investment approach, individuals specify, in each period, how to invest their accumulated retirement wealth and how much to withdraw. The value of the investment account at the start of the decumulation period (e.g., accumulated retirement wealth at the age of retirement) is also given exogenously. Many pension providers adopt the investment approach in practice. For example, when an individual purchases a variable annuity from a provider, the payout policy is (usually) a function of the adopted investment policy and the so-called Assumed Interest Rate (AIR). In particular, the investment policy and the AIR together determine the median growth rate of the benefit payout. Indeed, if a pension provider adopts a more conservative investment policy and leaves the AIR unaffected, then the benefit payout will, in expectation, grow at a slower rate. Changes in not only the investment policy but also the expected return on investments affect the median growth rate of the benefit payout.
In the consumption approach, individuals specify the entire retirement consumption stream exogenously.Footnote 4 More specifically, individuals define the desired median growth rate and the volatility of the benefit payout. They also specify the benefit payout at the start of the decumulation period exogenously. The initial value of the investment account, the investment policy and the withdrawal policy follow endogenously from these objectives. Individuals thus adopt the principle of liability-driven investment. In fact, the investment policy consists of two endogenous components: a speculative component and a hedging component. This decomposition of the investment policy is familiar from the literature on optimal consumption and portfolio choice under a stochastic investment opportunity set (see, e.g., Brennan and Xia (Reference Brennan and Xia2002), Wachter (Reference Wachter2002), Chacko and Viceira (Reference Chacko and Viceira2005), and Liu (Reference Liu2007)). The speculative portfolio allows individuals to take advantage of risk premia, while the hedging portfolio hedges changes in the investment opportunity set that affect the costs of future benefit payouts (Merton (Reference Merton1971)).Footnote 5 The hedging portfolio thus enables individuals to achieve a stable median payout stream in retirement.
Standard variable annuities fully reflect a speculative shock into the current benefit payout; that is, the current benefit payout responds one-to-one to an unexpected change in the value of the speculative portfolio (see, e.g., Chai et al. (Reference Chai, Horneff, Maurer and Mitchell2011) and Maurer et al. (Reference Maurer, Mitchell, Rogalla and Kartashov2013)).Footnote 6 As a result, in a standard variable annuity, a speculative shock does not affect the AIR. A PPR, in contrast, allows a speculative shock to affect the AIR so as to reduce the year-on-year volatility of retirement consumption. This so-called smoothing of speculative shocks is optimal in the presence of internal habit formation and loss aversion (see, e.g., Fuhrer (Reference Fuhrer2000), Pagel (Reference Pagel2017), and Van Bilsen et al. (Reference Van Bilsen, Laeven and Nijman2017)).Footnote 7 As the individual ages and the duration of his pension liabilities declines, the AIR becomes less effective in absorbing speculative shocks. Accordingly, in order to prevent an extreme year-on-year volatility of retirement consumption at higher ages, the individual must reduce the riskiness of his investment portfolio over the course of his life.
1. Modelling the decumulation period of a PPR
1.1 Financial market
This section describes the financial market. Our specification of the financial market is closely related to Liu (Reference Liu2007). The only difference between his specification and ours is that he does not assume a complete financial market, whereas we do. Denote by X t an N-dimensional vector of state variables. This vector characterizes the asset prices in the financial market. The vector of state variables could include the short-term real interest rate, the realized rate of inflation, or predictors of stock returns. We assume that X t satisfies the following dynamic equation:
 $${\rm d}X_t = \mu ^X\left ( {X_t} \right ) {\rm d}t + \Sigma ^X\left ( {X_t} \right ) {\rm d}Z_t,$$
where the drift term μ X(X t) and the diffusion matrix ΣX(X t) are an N-by-1 vector function and an N-by-N matrix function of X t, respectively, and Z t is an N-dimensional standard Brownian motion.
We consider a financial market consisting of N risky assets and one (locally) risk-free asset. The vector of risky asset prices P t = (P 1t, …, P Nt) and the risk-free asset price P 0t satisfy, respectively, the following dynamic equations:Footnote 8
 $${\rm d}P_t = \mu (X_t)P_t{\rm d}t + \Sigma (X_t)P_t{\rm d}Z_t,$$
 $${\rm d}P_{0t} = R^f\,(X_t)P_{0t}{\rm d}t.$$
The drift term μ(X t), the diffusion matrix Σ(X t) and the risk-free interest rate R f(X t) are functions of X t. In what follows, we write  $\mu ^X(X_t) = \mu _t^X, \Sigma ^X(X_t) = \Sigma _t^X, \mu (X_t) = \mu _t,\Sigma (X_t) = \Sigma _t$ and
 $R^f(X_t) = R_t^f $.
1.2 Survival probabilities
To protect individuals against the risk of outliving their accumulated retirement wealth, a PPR distributes the accumulated retirement wealth of someone who dies among the surviving individuals of the same age. Hence, a PPR pools individual longevity risk. We assume that the risk-sharing pool is sufficiently large so that the law of large numbers applies. Furthermore, we abstract away from macro longevity risk.
Denote by y the date of birth of an individual, by xr the age at which individuals retire, and by x max the maximum age individuals can reach. If the date of birth y falls between time t − xr and time t − x max and the individual has survived up to time t, then this individual receives a pension payment at time t. We denote the probability that an individual aged x = t − y will survive to age x + h by
 $$_h p_x = \exp \left\{ {-\int\limits_0^h {\theta_{x + v}} {\rm d}v} \right\}$$
Here, θ x+v represents the force of mortality (i.e., hazard rate) at age x + v.
1.3 Budget condition
The value of the individual's investment account should match the value of the individual's pension liabilities in every state of nature and at any date. Indeed, in a PPR, an individual finances its pension liabilities by its own investment account. Let W t,y and V t,y denote, respectively, the value of the investment account and the value of the pension liabilities at time t of an individual born at time y. Mathematically, budget balance implies that for each t ∈ [y + x r, y + x max]
 $$W_{t,y}{\rm} = {\rm} V_{t,y}$$
The budget condition (5) states that the (balance sheet) funding ratio W t,y/V t,y is equal to unity in every state of nature and at any date. It follows from (5) that dlog W t,y = dlog V t,y. We explore the dynamics of log W t,y and log V t,y in Sections 1.4 and 1.5, respectively. Section 1.6 derives several relationships between the contract parameters that follow from the budget condition (5).
1.4 Dynamics of the value of the investment account
The value of the investment account of a surviving individual satisfies the following dynamic equation:
 $${\rm d}W_{t,y} = \left ( {\theta_{t-y} + R_t^f + \omega_{t,y}^{\rm \top} \left \lsqb {\mu_t-R_t^f} \right \rsqb } \right ) W_{t,y}{\rm d}t + \omega _{t,y}^{\rm \top} \Sigma _tW_{t,y}{\rm d}Z_t-B_{t,y}{\rm d}t.$$
Here, ω t,y and B t,y represent, respectively, the vector of portfolio weights and the (annualized) benefit payout at time t of an individual born at time y.Footnote 9 We can view θ t−y as the biometric rate of return.Footnote 10 Indeed, because the accumulated retirement wealth of someone who dies goes to the surviving individuals (and not to its heirs), surviving individuals earn an additional return. The symbol ‘ ${\rm \top} $’ denotes the transpose sign.
Application of Itô’s lemma to log W t,y yields
 $$d\log W_{t,y} = \left ( {\theta_{t-y} + \mu_{t,y}^W -c_{t,y}} \right ) {\rm d}t + \omega _{t,y}^{\rm \top} \Sigma _t{\rm d}Z_t,$$
where  $\mu _{t,y}^W $ and c t,y denote, respectively, the (geometric) expected financial return on accumulated retirement wealth and the withdrawal rate at time t of a person born at time y:Footnote 11
 $$\mu _{t,y}^W = R_t^f + \omega _{t,y}^{\rm \top} \left ( {\mu_t-R_t^f} \right ) -\displaystyle{1 \over 2}\omega _{t,y}^{\rm \top} \Sigma _t\Sigma _t^{\rm \top} \omega _{t,y},$$
 $$c_{t,y} = \displaystyle{{B_{t,y}} \over {W_{t,y}}}.$$
The withdrawal rate (9) controls the speed at which accumulated retirement wealth W t,y = V t,y is depleted. In fact, it models how the individual's accumulated retirement wealth is allocated between his current payout and his future payouts.
1.5 Dynamics of the value of the pension liabilities
1.5.1 A factorization
Let C t,y denote the conversion factor at time t of an individual born at time y. This factor is implicitly defined as follows:
 $$C_{t,y}B_{t,y} = W_{t,y}=V_{t,y.}$$
It follows from (10) that
 $${\rm d}\log V_{t,y} = {\rm d}\log C_{t,y} + {\rm d}\log B_{t,y}.$$
Hence, to derive the dynamics of the log value of the individual's pension liabilities V t,y, we first need to derive the dynamics of the log conversion factor C t,y and the dynamics of the log benefit payout logB t,y. Sections 1.5.2 and 1.5.3 explore the dynamics of log C t,y and log B t,y, respectively.
1.5.2 Dynamics of the log conversion factor
Denote by  $V_{t,y,h}^{} $ the value of the future benefit payout B t+h,y We can write the conversion factor C t,y as follows:
 $$C_{t,y} = \displaystyle{{V_{t,y}} \over {B_{t,y}}} = \int\limits_0^{x_{\max} -(t-y)} {\displaystyle{{V_{t,y,h}} \over {B_{t,y}}}} {\rm d}h = \int\limits_0^{x_{\max} -(t-y)} {C_{t,y,h}} {\rm d}h,$$
where C t,y,h = V t,y,h/B t,y.
Let δ t,y,h denote individual y’s discount rate (or AIR) at time t for a benefit payout occurring at time t + h. This discount rate is implicitly defined as follows:
 $$C_{t,y,h} =\; _h p_{t-y}\exp \lcub {- \delta_{t,y,h} h} \rcub .$$
The discount rate models the speed at which an individual withdraws his accumulated retirement wealth. We allow the discount rate to depend on future expected financial rates of return and past speculative shocks.Footnote 12 Hence, we can divide δ t,y,h into two parts:
 $$\delta _{t,y,h} = \delta _{t,y,h}^u + \delta _{t,y,h}^c. $$
Here,  $\delta _{t,y,h}^u $ models how the discount rate depends on future expected financial rates of returns. The individual's elasticity of intertemporal substitution determines the extent to which
 $\delta _{t,y,h}^u $ responds to a change in the investment opportunity set. In the special case where the individual has unit elasticity of intertemporal substitution, the discount rate
 $\delta _{t,y,h}^u $ is insensitive to changes in the investment opportunity set. The term
 $\delta _{t,y,h}^c $ models how the discount rate depends on past speculative shocks. By increasing (decreasing)
 $\delta _{t,y,h}^c $ following a negative (positive) speculative shock, the individual (partially) absorbs a shock into the future growth rates of the benefit payout. We call
 $\delta _{t,y,h}^u $ and
 $\delta _{t,y,h}^c $ the unconditional and the conditional part of
 $\delta _{t,y,h}^{} $, respectively. Henceforth, we refer to
 $\delta _{t,y,h}^u $ as the unconditional discount rate. We note that at the start of the decumulation period, the unconditional discount rate coincides with the actual discount rate (i.e.,
 $\delta _{y + x_r,y,h}^u = \delta _{y + x_r,y,h}$ for all h).
Using (13) and (14), we can write  $C_{t,y,h}^{} $ as follows:
 $$C_{t,y,h}^{} = A_{t,y,h}^{} F_{t,y,h},$$
where
 $$A_{t,y,h}{\rm} =\; _hp_{t-y}\exp \lcub {-\delta_{t,y,h}^u h} \rcub ,$$
 $$F_{t,y,h} = \exp \lcub {-\delta_{t,y,h}^c h} \rcub .$$
In what follows, we refer to  $A_{t,y,h}^{} $ and
 $F_{t,y,h}^{} $ as the horizon-dependent annuity factor and the horizon-dependent funding ratio, respectively.
It follows from Itô’s lemma, (12) and (15) that
 $$\eqalign{{\rm d}\log C_{t,y} = &\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} {\rm d}\log C_{t,y,h}{\rm d}h-c_{t,y}{\rm d}t \cr &\;+ \displaystyle{1 \over 2}\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} {\rm d}\left [ {\log C_{t,y,h},\log C_{t,y,h}} \right ] {\rm d}h \cr &\;-\displaystyle{1 \over 2}\int\limits_0^{x_{\max} -(t-y)} {\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,u}}} \alpha _{t,y,v}{\rm d}\left [ {\log C_{t,y,u},\log C_{t,y,v}} \right ] {\rm d}u{\rm d}v,} $$
and
 $${\rm d}\log C_{t,y,h} = {\rm d}\log A_{t,y,h} + {\rm d}\log F_{t,y,h}.$$
Here, α t,y,h = C t,y,h/C t,y and [log C t,y,u, log C t,y,v] denotes the quadratic covariation between log C t,y,u and log C t,y,v. We now derive the dynamics of  $\log A_{t,y,h}^{} $ and
 $\log F_{t,y,h}^{} $, respectively.
Dynamics of the Log Horizon-Dependent Annuity Factor. To derive the dynamics of the log horizon-dependent annuity factor  $\log A_{t,y,h}^{} $, we assume that the unconditional discount rate
 $\delta _{t,y,h}^u $ depends on the vector of state variables X t. By Itô’s lemma, the log horizon-dependent annuity factor
 $\log A_{t,y,h} = \log _hp_{t-y}-\delta _{t,y,h}^u h$ (see also (16) for the definition of
 $A_{t,y,h}^{} $) satisfies the following dynamic equation:
 $$\eqalign{{\rm d}\log A_{t,y,h} =\; &\theta _{t-y}{\rm d}t + \displaystyle{{\partial \left ( {\delta_{t,y,h}^u h} \right ) } \over {\partial h}}{\rm d}t-D_{t,y,h}^{\rm \top} \mu _t^X {\rm d}t \cr &\;-\displaystyle{1 \over 2}{\rm Tr}\left[ {{\left ( {\Sigma_t^X} \right ) }^{\rm \top} H_{t,y,h}\Sigma_t^X} \right] {\rm d}t-D_{t,y,h}^{\rm \top} \Sigma _t^X {\rm d}Z_t.} $$
Here,  $D_{t,y,h} = \nabla _X\left ( {\delta_{t,y,h}^u h} \right ) $ and
 $H_{t,y,h} = H_X\left ( {\delta_{t,y,h}^u h} \right ) $ are the gradient and the Hessian matrix of
 $\delta _{t,y,h}^u h$ with respect to X t, respectively, and Tr denotes the trace operator. The first term on the right-hand side of (20) denotes the change in the (log) survival probability. This term is positive. Indeed, the probability of surviving to age t + h − y increases as time proceeds. The second term represents the unwinding of the discount rate. Finally, the last three terms model how the underlying state variables affect the log horizon-dependent annuity factor.
Dynamics of the Log Horizon-Dependent Funding Ratio. Equation (20) shows that the (aggregate) annuity factor  $A_{t,y} = \int_0^{x_{\max} -(t-y)} {A_{t,y,h}} {\rm d}h$ is typically stochastic. The hedging portfolio aims at hedging stochastic variations in the annuity factor. If the hedging portfolio does not coincide with the actual portfolio, then there is a speculative risk. The individual can absorb a speculative shock in either the current benefit payout B t,y or the future growth rates of the benefit payout or a combination of both.
Denote by  $\omega _{t,y}^S $ the N-dimensional vector of speculative portfolio weights at time t of an individual born at time y. The speculative shock at time t is thus given by
 $\left ( {\omega_{t,y}^S} \right ) ^{\rm \top} \Sigma _t{\rm d}Z_t$. The individual translates a fraction q t,y,h of a current speculative shock into the future benefit payout B t+h,y. That is, the exposure of log V t,y,h to a current speculative shock equals q t,y,h. We assume that q t,y,h (which we call the smoothing coefficient) weakly increases with the horizon h so that a current speculative shock does not yield a smaller impact on a benefit payout in the distant future than on a benefit payout in the near future. To absorb the entire speculative shock into the current payout and the future growth rates of the payout, we must have that
 $$\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} q_{t,y,h}{\rm d}h = 1.$$
The exposure of the log horizon-dependent conversion factor log C t,y,h = log V t,y,h − log V t,y,0 to a current speculative shock equals q t,y,h − q t,y,0. Hence, the horizon-dependent funding ratio (which models how the conversion factor depends on past speculative shocks) is given byFootnote 13
 $$F_{t,y,h} = \exp \left\{ {\int\limits_{y + x_r}^t {\left ( {q_{s,y,t + h-s}-q_{s,y,t-s}} \right ) } {\left ( {\omega_{s,y}^S} \right ) }^{\rm \top} \Sigma_s{\rm d}Z_s} \right\}.$$
By comparing (17) with (22), we arrive at
 $$\delta _{t,y,h}^c h{\rm} = -\int\limits_{y + x_r}^t {\left ( {q_{s,y,t + h-s}-q_{s,y,t-s}} \right ) } \left ( {\omega_{s,y}^S} \right ) ^{\rm \top} \Sigma _s{\rm d}Z_s = -\log F_{t,y,h}.$$
Equation (23) shows how past speculative shocks affect the discount rate. In the case of no horizon differentiation in risk exposures (i.e., q t,y,h is equal to unity for every h), past speculative shocks do not affect the conversion factor C t,y. Indeed, in the absence of horizon differentiation in risk exposures, the individual fully translates a speculative shock into the current benefit payout. The conditional part of the discount rate, i.e.,  $\delta _{t,y,h}^c $, is thus the consequence of the gradual adjustment of the current benefit payout to a speculative shock. The log horizon-dependent funding ratio obeys the following equation (this follows from (22)):
 $${\rm d}\log F_{t,y,h}=\left(q_{t,y,h}-q_{t,y,0}\right)\left(\omega_{t,y}^{S}\right)^{\rm \top} \Sigma _t{\rm d}Z_t -\int\limits_{y+x_r}^{t}{\rm d}q_{s,y,t-s}\left(\omega_{s,y}^{S}\right)^{\rm \top}\Sigma _s{\rm d}Z_s.$$
The first term on the right-hand side of (24) represents the impact of a current speculative shock on the horizon-dependent funding ratio. The second term denotes past speculative shocks that are absorbed into the current benefit payout so that they are no longer included in the horizon-dependent funding ratio.
Also, Guillén et al. (Reference Guillén, Jørgensen and Nielsen2006) and Maurer et al. (Reference Maurer, Mitchell, Rogalla and Siegelin2016) consider a pension product in which a speculative shock has less impact on the current benefit payout than on the future benefit payouts.Footnote 14 Their pension product works as follows. In the case of a positive investment return, only a fraction of the positive return will be added to the benefit payout. The insurer retains the remainder of the return. In the case of a negative investment return, only a fraction of the negative return will be subtracted from the benefit payout. The insurer confers the additional benefit payout. A potential drawback of this shock absorbing mechanism is that the pension provider runs the risk of ending up with a negative reserve. Our specification, in contrast, implies individual buffers so that investment shocks do not cause transfers between individuals and the provider.
1.5.3 Dynamics of the log benefit payout
We specify the benefit payout at time t + h of an individual born at time y as follows:
 $$B_{t + h,y} = B_{y + x_r,y}\exp \left\{ {\int\limits_{y + x_r}^{t + h} {\gamma_{s,y}^u} {\rm d}s + \int\limits_{y + x_r}^{t + h} {{\left ( {\Sigma_{s,y,t + h-s}^B} \right ) }^{\rm \top}} {\rm d}Z_s} \right\}.$$
Here,  $\gamma _{t,y}^u $ denotes the unconditional median growth rate of the benefit payout at time t of an individual born at time y and
 $\Sigma _{t,y,h}^B $ models the exposure of the future benefit payout log B t+h,y to a current Brownian shock dZ t. We require that
 $\Sigma _{t,y,h}^B $ weakly increases with the horizon h so that a current Brownian shock does not yield a smaller impact on a benefit payout in the distant future than on a benefit payout in the near future.
It follows from (25) that
 $$B_{t + h,y} = B_{t,y}F_{t,y,h}\exp \left\{ {\int\limits_t^{t + h} {\gamma_{s,y}^u} {\rm d}s + \int\limits_t^{t + h} {{\left ( {\Sigma_{s,y,t + h-s}^B} \right ) }^{\rm \top}} {\rm d}Z_s} \right\},$$
where
 $$F_{t,y,h} = \exp \left\{ {\int\limits_{y + x_r}^t {{\left ( {\Sigma_{s,y,t + h-s}^B -\Sigma_{s,y,t-s}^B} \right ) }^{\rm \top}} {\rm d}Z_s} \right\}.$$
Comparison of (27) with (22) yields
 $$\Sigma _{t,y,h}^B = q_{t,y,h}\Sigma _t^{\rm \top} \omega _{t,y}^S. $$
Equation (28) expresses how the vector of speculative portfolio weights  $\omega _{t,y}^S $ and the smoothing coefficient q t,y,h together determine the vector of payout exposures
 $\Sigma _{t,y,h}^B $.
The log benefit payout log B t,y evolves according to (this follows from (25)):
 $${\rm d}\log B_{t,y}{\rm} = \gamma _{t,y}^u {\rm d}t + \int\limits_{y + x_r}^t {\rm d} \left ( {\Sigma_{s,y,t-s}^B} \right ) ^{\rm \top} {\rm d}Z_s + \left ( {\Sigma_{t,y,0}^B} \right ) ^{\rm \top} {\rm d}Z_t = \gamma _{t,y}{\rm d}t + \left ( {\Sigma_{t,y,0}^B} \right ) ^{\rm \top} {\rm d}Z_t.$$
Here, γ t,y denotes the actual median growth rate of the current benefit payout. This rate depends on current expected financial rates of return (i.e., if expected returns change, the individual may want to reallocate consumption over time) and past Brownian shocks. Hence, we can divide γ t,y into two parts:
 $$\gamma _{t,y} = \gamma _{t,y}^u + \gamma _{t,y}^c, $$
where
 $$\gamma _{t,y}^c = \int\limits_{y + x_r}^t {\rm d} \left ( {\Sigma_{s,y,t-s}^B} \right ) ^{\rm \top} {\rm d}Z_s.$$
We refer to  $\gamma _{t,y}^{\;c} $ as the conditional part of γ t,y. Equation (31) represents past Brownian shocks that affect the median growth rate of the current benefit payout.
1.6 Relationships between the contract parameters
The previous sections have modelled the decumulation period of a PPR in terms of seven parameters. The first column of Table 1 lists these parameters. This section derives several relationships between the contract parameters that follow from the budget condition (5). We can write this condition as follows (use dlog V t,y = dlog C t,y + dlog B t,y):
 $${\rm d}\log W_{t,y} = {\rm d}\log C_{t,y} + {\rm d}\log B_{t,y}.$$
Investment approach versus consumption approach. The second (third) column of this table summarizes the exogenous and endogenous parameters of the investment (consumption) approach

Appendix A.1 shows that (32) is equivalent to:
 $$\mu _{t,y}^W {\rm d}t + \omega _{t,y}^{\rm \top} \Sigma _t{\rm d}Z_t = \left ( {\mu_{t,y}^C + \gamma_{t,y}} \right ) {\rm d}t + \left \lsqb {{\left ( {\omega_{t,y}^S} \right ) }^{\rm \top} \Sigma_t-\hat{D}_{t,y}^{\rm \top} \Sigma_t^X} \right \rsqb {\rm d}Z_t.$$
Here,  $\hat{D}_{t,y} = \int_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} D_{t,y,h}{\rm d}h$ models the sensitivity of the conversion factor with respect to the underlying state variables and
 $\mu _{t,y}^C $ is the expected financial rate of return on the conversion factor; see Appendix A.1 for the expression of
 $\mu _{t,y}^C $.
Using (5) and (33), we find the following system of equations:Footnote 15
 $$W_{y + x_r,y} = C_{y + x_r,y}\;{\rm} B_{y + x_r,y},$$
 $$\gamma _{t,y} = \mu _{t,y}^W -\mu _{t,y}^C, $$
 $$\omega _{t,y} = \omega _{t,y}^S -\left ( {\Sigma_t^X \Sigma_t^{-1}} \right ) ^{\rm \top} \hat{D}_{t,y}.$$
Individuals can use this system of equations to determine the contract parameters. Condition (or relationship) (35) shows that the median growth rate of the current benefit payout γ t,y equals the difference between the expected financial rate of return on accumulated retirement wealth  $\mu _{t,y}^W $ and the expected financial rate of return on the conversion factor
 $\mu _{t,y}^C $. Condition (36) shows that the vector of portfolio weights ω t,y is equal to the sum of the vector of speculative portfolio weights
 $\omega _{t,y}^S $ and the vector of hedge portfolio weights
 $\omega _{t,y}^H = -\left ( {\Sigma_t^X \Sigma_t^{-1}} \right ) ^{\rm \top} \hat{D}_{t,y}$. We also have a condition for every horizon h (see also (28)):
 $$\Sigma _{t,y,h}^B = q_{t,y,h}\Sigma _t^{\rm \top} \omega _{t,y}^S. $$
Conditions (34)–(37) do not uniquely identify all contract parameters. Individuals must thus specify some parameters exogenously. They can specify the parameters according to (at least) two alternative approaches: the investment approach and the consumption approach. In the investment approach individuals specify the initial value of the investment account, the unconditional discount rate (as a function of t and h), the vector of portfolio weights (as a function of t) and the smoothing coefficient (as a function of t and h) exogenously; see also the second column of Table 1. In the consumption approach individuals specify the benefit payout at the start of the decumulation period, the unconditional median growth rate of the current benefit payout (as a function of t) and the vector of payout exposures (as a function of t and h) exogenously; see also the third column of Table 1. The next sections explore these two approaches in more detail and show how they differ from each other.
2. Investment approach
This section explores the investment approach which is commonly adopted by pension providers. In this approach the benefit payout at the start of the decumulation period, the unconditional median growth rate of the current benefit payout and the vector of payout exposures are endogenously determined; see also the second column of Table 1. Section 2.1 specifies the vector of state variables and its dynamics. Section 2.2 considers the investment approach, with the restriction that the smoothing coefficient q t,y,h is equal to unity for all h. Hence, past speculative shocks do not affect the discount rate. We relax this restriction in Section 2.3.
2.1 State variables
For the sake of simplicity, we characterize asset prices by three state variables: the inflation rate π t, the real interest rate r t, and the stock price S t. Hence, X t = (π t, r t, S t). Following Brennan and Xia (Reference Brennan and Xia2002), the inflation rate and the real interest rate follow Ornstein–Uhlenbeck processes and the stock price follows a geometric Brownian motion. The drift term  $\mu _t^X $ and the diffusion coefficient
 $\Sigma _t^X $ are thus specified as follows:Footnote 16
 $$\mu _t^X = \left( {\matrix{ {\eta \left ( {\bar{\pi} -\pi_t} \right ) } \cr {\kappa \left ( {\bar{r}-r_t} \right ) } \cr {S_tR_t^f + S_t\lambda_S\sigma_S} \cr}} \right),\Sigma _t^X = \left( {\matrix{ {\sigma_\pi} & 0 & 0 \cr 0 & {\sigma_r} & 0 \cr 0 & 0 & {S_t\sigma_S} \cr}} \right).$$
Here, η > 0 and κ > 0 are mean reversion coefficients,  $\bar{\pi} $ and
 $\bar{r}$ denote long-term means, λ S is the equity risk premium per unit of risk, and σ π > 0, σ r > 0 and σ S > 0 correspond to diffusion coefficients.Footnote 17
The individual invests his retirement wealth in three risky assets: two nominal zero-coupon bonds with times to maturity h 1 and h 2, and a stock. We find the following expressions for the expected excess return  $\mu_t - R_t^f $ and the diffusion matrix Σt (see Appendix A.2):
 $$\mu_t - R_t^f = \left( {\matrix{ {-\lambda_\pi \sigma_\pi K_{h_1}-\lambda_r\sigma_rL_{h_1}} \cr {-\lambda_\pi \sigma_\pi K_{h_2}-\lambda_r\sigma_rL_{h_2}} \cr {\lambda_S\sigma_S} \cr}} \right),\Sigma _t = \left( {\matrix{ {-\sigma_\pi K_{h_1}} & {-\sigma_rL_{h_1}} & 0 \cr {-\sigma_\pi K_{h_2}} & {-\sigma_rL_{h_2}} & 0 \cr 0 & 0 & {\sigma_S} \cr}} \right).$$
Here, λ = (λ π, λ r, λ S) is the vector of market prices of risk,  $K_{h_1} = (1-e^{-\eta h_1})/\eta $ and
 $L_{h_1} = (1-e^{-\kappa h_1})/\kappa $. Table 2 reports the parameter values that we use in our numerical illustrations.
Parameter values. This table reports the parameter values that we use in our numerical illustrations

2.2 No Smoothing of speculative shocks
Figure 1 illustrates the investment approach, with the following two restrictions. First, the smoothing coefficient q t,y,h is equal to unity for all h. Second, the (unconditional) discount rate is constant (i.e.,  $\delta _{t,y,h}^u = \delta ^u = \delta $ for all t and h). The latter restriction implies that the vector of hedge portfolio weights is equal to zero:
 $$\omega _{t,y}^H = 0.$$
Illustration of the Investment Approach: A Special Case. The figure illustrates the investment approach, with the restriction that the smoothing coefficient q t,y,h is equal to unity for all h and the (unconditional) discount rate is constant. The left-hand side of the figure shows the exogenous parameters of the contract. These exogenous parameters determine the parameters of the contract on the right-hand side of the figure.

The benefit payout at the start of the decumulation period, the (unconditional) median growth rate of the current benefit payout and the vector of payout exposures follow from (34), (35) and (37), respectively. We findFootnote 18
 $$B_{y + x_r,y} = \displaystyle{{W_{y + x_r,y}} \over {C_{y + x_r,y}}},$$
 $$\gamma _{t,y}^u {\rm} = \mu _{t,y}^W -\delta ^u,$$
 $$\Sigma _{t,y,h}^B {\rm} = \Sigma _{t,y}^B = \Sigma _t^{\rm \top} \omega _{t,y}^S. $$
Equation (42) shows that the expected rate of return on accumulated retirement wealth  $\mu _{t,y}^W = R_t^f + \omega _{t,y}^{\rm \top} \left ( {\mu_t-R_t^f} \right ) -1/2\omega _{t,y}^{\rm \top} \Sigma _t\Sigma _t^{\rm \top} \omega _{t,y}$ and the (unconditional) discount rate δ u together determine the (unconditional) median growth rate of the current benefit payout
 $\gamma _{t,y}^u $. As a result, the median growth rate of the current benefit payout is not constant but rather depends on the inflation rate and the real interest rate.Footnote 19 To obtain a constant median growth rate, the individual must determine the discount rate endogenously. Section 3 derives the discount rate under the assumption that the individual specifies the median growth rate of the current benefit payout exogenously. We will see that the discount rate then depends on the current inflation rate, the current real interest rate and the horizon. In fact, the discount rate has an endogenous term structure.
2.3 Smoothing of speculative shocks
This section assumes that the individual now adjusts the conversion factor following a speculative shock; in other words, the smoothing coefficient q t,y,h increases with the investment horizon h. As a direct consequence, the conditional part of the discount rate, i.e.,  $\delta _{t,y,h}^c $, differs from zero (see (23)). We still assume that the unconditional discount rate is constant (i.e.,
 $\delta _{t,y,h}^u = \delta ^u$ for all t and h). The unconditional median growth rate of the current benefit payout, i.e.,
 $\gamma _{t,y}^u $ is given by (42). However, equation (43) no longer applies. The exposure of the future log benefit payout log B t+h,y to a current Brownian shock is now given by
 $$\Sigma _{t,y,h}^B = q_{t,y,h}\Sigma _t^{\rm \top} \omega _{t,y}^S. $$
It follows from (21) that q t,y,0 increases and converges to one when the individual becomes older because his remaining life expectancy declines and the value weights of the shorter horizons α t,y,h increase. Hence, under the condition that the vector of speculative portfolio weights  $\omega _{t,y}^S $ does not change over time, the vector of payout exposures
 $\Sigma _{t,y,0}^B $ becomes larger as the individual ages (see (44)). Intuitively, a relatively old individual with a short remaining life expectancy can no longer smooth the investment results over a long remaining lifetime. Hence, the year-on-year volatility of retirement consumption increases as the individual ages. To arrive at a constant year-on-year volatility of retirement consumption, the individual must determine the investment policy endogenously. Section 3.2.2 below derives an endogenous investment policy such that the year-on-year volatility of retirement consumption is constant.
3. Consumption approach
This section explores the consumption approach. We consider the same setting as in Section 2.1. In the consumption approach, individuals specify the entire retirement consumption stream exogenously. Section 3.1 examines the DB approach in which retirement consumption is constant in either nominal or real terms. Section 3.2 extends the DB approach to stochastic benefit payouts.
3.1 DB approach
In the DB approach individuals specify the benefit payout at the start of the decumulation period and the rate at which the benefit payout grows over time. The benefit payout either grows with the inflation rate (inflation-linked annuity) or does not grow at all (nominal annuity). This section derives, in line with the principle of liability-driven investment, the (unconditional) forward discount rate and the vector of portfolio weights endogenously from the liabilities of the contract. Figure 2 illustrates the DB approach.
Illustration of the DB Approach. The figure illustrates the DB approach. The left-hand side of the figure shows the exogenous parameters of the contract. These exogenous parameters determine the parameters of the contract on the right-hand side of the figure.

The DB approach specifies the (unconditional) growth rate of the current benefit payout as follows:
 $$\gamma _{t,y}^u = g_{0} + g_{1}\cdot \pi _t,$$
where g 1 ∈ {0, 1}. If g 1 equals zero (unity), retirement consumption is constant in nominal (real) terms.
Let  ${\check \delta}_{t,y,v}^u $ denote individual y’s (unconditional) forward discount rate at time t for horizon v. The (unconditional) forward discount rate is implicitly defined as follows:
 $$\delta _{t,y,h}^u = \displaystyle{1 \over h} \int\limits_0^h {\check \delta}^u_{t,y,v}{\rm d}v. $$
We find that the forward discount rate  ${\check \delta}_{t,y,v}^u $ is specified as follows (see Appendix A.3):
 $${\check \delta}_{t,y,v}^u = { {\opf E}}_t [(1-g_1)\pi _{t + v} + r_{t + v}]-g_{0}-D_{1v}\sigma _\pi \left( {\lambda_\pi + \displaystyle{1 \over 2}D_{1v}\sigma_\pi} \right)-D_{2v}\sigma _r\left( {\lambda_r + \displaystyle{1 \over 2}D_{2v}\sigma_r} \right),$$
where D 1v = (1 − g 1)1/η(1 − e −ηv), D 2v = (1/κ)(1 − e −κv) and  ${\opf E}_t[(1-g_1)\pi _{t + v} + r_{t + v}] = (1-g_1)\,\,[\pi _t + (1-e^{-\eta v})(\bar{\pi }-\pi _t)] + r_t + (1-e^{-\kappa v})(\bar{r}-r_t).$
We observe that the coefficients g 0 and g 1, which model the median growth rate of the current benefit payout, determine the forward discount rate (47). Intuitively, the higher the median growth rate of the current benefit payout is, the higher the costs of future benefit payouts are and the lower the forward discount rate will be.
Mean reversion in the state variables also affects the forward discount rate and is captured by the term 𝔼t[(1 − g 1)π t+v + r t+v]. Indeed, if the current inflation rate and the current real interest rate exceed their long-term means (i.e., $\pi _t \gt \bar{\pi} $ and
 $r_t \gt \bar{r}$), then returns are expected to decline over time (i.e., 𝔼t[(1 − g 1)π t+v + r t+v] decreases with v), and hence it may be relatively more expensive to finance long-term benefit payouts than to finance short-term benefit payouts depending on the size of the second term, i.e., − D 1vσ π(λ π + (1/2)D 1vσ π) − D 2vσ r(λ r + (1/2)D 2vσ r).
The latter term reflects the expected excess return on the underlying hedging portfolio and typically increases with the horizon. Indeed, larger horizons are more exposed to inflation risk and real interest rate risk and thus benefit from higher risk premia (i.e., D 1v and D 2v increase with v and λ π, λ r < 0). Hence, the later the payout date is, the larger the second term will be. The discount rate thus exhibits an endogenous term structure, which depends both on current state variables (i.e., current inflation rate and the current real interest rate) and the horizon. In particular, the term structure is upward sloping unless the current inflation rate and the current real interest rate are substantially above their long-term means.
3.1.1 Guaranteed nominal benefit payouts
The individual receives guaranteed flat nominal benefit payouts if g 0 = g 1 = 0. We find the following expression for the (unconditional) forward discount rate (substitute g 0 = g 1 = 0 into (47)):
 $${\check \delta}_{t,y,v}^u = R_{t,v},$$
where R t,v denotes the nominal forward interest rate:
 $$R_{t,v} = { {\opf E}}_t[\pi _{t + v} + r_{t + v}]-D_{1v}\sigma _\pi \left( {\lambda_\pi + \displaystyle{1 \over 2}D_{1v}\sigma_\pi} \right)-D_{2v}\sigma _r\left( {\lambda_r + \displaystyle{1 \over 2}D_{2v}\sigma_r} \right).$$
Figure 3 illustrates the forward discount rate  ${\check \delta}_{t,y,v}^u $ for various values of the current inflation rate π t and the current real interest rate r t as a function of the horizon v. The solid line shows the case in which the current inflation rate and the current real interest rate are equal to their long-term means (i.e.,
 ${\rm {\opf E}}_t[\pi _{t + v}] = \bar{\pi} $ and
 ${\rm {\opf E}}_t[r_{t + v}] = \bar{r}$ for all v). As shown by Figure 3, the solid line is not horizontal, but rather rises with the investment horizon v. Indeed, the longer the investment horizon, the more a nominal benefit payout is exposed to inflation risk and real interest rate risk, and hence the larger the nominal interest rate risk premium
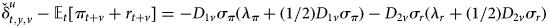 ${\check \delta}_{t,y,v}^u -{\rm {\opf E}}_t[\pi _{t + v} + r_{t + v}] = -D_{1v}\sigma _\pi (\lambda _\pi + (1/2)D_{1v}\sigma _\pi )-D_{2v}\sigma _r(\lambda _r + (1/2)D_{2v}\sigma _r)$.Footnote 20
Illustration of the Nominal Forward Interest Rate. The figure illustrates the nominal forward interest rate for various values of the current inflation rate π t and the current real interest rate r t as a function of the horizon v. The benchmark parameter values are given in Table 2.

The dash-dotted and the dashed line show the case in which the current inflation rate and the current real interest rate deviate from their long-term means. If the current inflation rate and the current real interest rate exceed their long-term means, then the term 𝔼t[π t+v + r t+v] in (49) decreases with the investment horizon v. Indeed, in a situation where returns are expected to decline over time, it may be relatively more expensive to finance long-term benefit payouts than to finance short-term benefit payouts if the mean-reversion term 𝔼t[π t+v + r t+v] dominates the risk premium term − D 1vσ π(λ π + (1/2)D 1vσ π) − D 2vσ r(λ r + (1/2)D 2vσ r)
The inflation sensitivity and the real interest rate sensitivity of the value of the pension liabilities are, respectively, given by
 $$\hat{D}_{1t,y} = \int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} D_{1h}{\rm d}h = \int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} (1-e^{-\eta h}){\rm d}h/\eta, $$
 $$\hat{D}_{2t,y} = \int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} D_{2h}{\rm d}h = \int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} (1-e^{-\kappa h}){\rm d}h/\kappa. $$
Pension providers can replicate the pension contract by investing in a portfolio of nominal bonds with inflation sensitivity  $\hat{D}_{1t,y}$ and real interest rate sensitivity
 $\hat{D}_{2t,y}$; that is, the portfolio weights ω 1t,y and ω 2t,y solve the following system of equations:
 $$\hat{D}_{1t,y}{\rm} = \omega _{1t,y}K_{h_1} + \omega _{2t,y}K_{h_2},$$
 $$\hat{D}_{2t,y}{\rm} = \omega _{1t,y}L_{h_1} + \omega _{2t,y}L_{h_2}.$$
Equations (52) and (53) show that the portfolio weights ω 1t,y and ω 2t,y are not constant (as is usually the case under the investment approach), but rather depend on the inflation sensitivity and the real interest rate sensitivity of the value of the liabilities. In particular, the larger the inflation sensitivity and the real interest rate sensitivity of the value of the liabilities, the greater the extent to which the value of the bond portfolio responds to a change in the inflation rate and the real interest rate.
3.1.2 Guaranteed inflation-linked benefit payouts
The individual receives guaranteed flat inflation-linked benefit payouts if  $g_{_0} {\rm } = {\rm } 0$ and g 1 = 1. We find the following expression for the (unconditional) forward discount rate (substitute g 0 = 0 and g 1 = 1 into (47)):
 $${\check \delta}_{t,y,v}^u = r_{t,v},$$
where r t,v denotes the real forward interest rate:
 $$r_{t,v} = { {\opf E}}_t[r_{t + v}]-D_{2v}\sigma _r\left( {\lambda_r + \displaystyle{1 \over 2}D_{2v}\sigma_r} \right).$$
Figure 4 illustrates the forward discount rate  ${\check \delta}_{t,y,v}^u $ for various values of the current real interest rate r t as a function of the horizon v. The solid line shows the case in which the current real interest rate is equal to its long-term mean. This line increases with the investment horizon v. Indeed, the longer the investment horizon, the more an inflation-linked benefit payout is exposed to real interest rate risk, and hence the larger the real interest rate risk premium
 ${\check \delta}_{t,y,v}^u -{\opf E}_t[r_{t + v}] = -D_{2v}\sigma _r(\lambda _r +&InLnBrk; (1/2)D_{2v}\sigma _r)$. Also here, the slope of the term structure depends on the risk premium term, which is typically upward sloping, and the mean-reversion term, which may be both upward and downward sloping depending on how the current short-term real interest rate compares with its long-term mean.
Illustration of the Real Forward Interest Rate. The figure illustrates the real forward interest rate for various values of the current real interest rate r t as a function of the horizon v. The benchmark parameter values are given in Table 2.

The real interest rate sensitivity of the value of the pension liabilities is given by
 $$\hat{D}_{2t,y} = \int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} D_{2h}{\rm d}h = \int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} (1-e^{-\kappa h}){\rm d}h/\kappa. $$
Budget balance requires the pension provider to invest in an investment portfolio that is insensitive to changes in the inflation rate and, furthermore, has the same real interest rate sensitivity as the value of the liabilities, i.e.,
 $$0 = \omega _{1t,y}K_{h_1} + \omega _{2t,y}K_{h_2},$$
 $$\hat{D}_{2t,y} = \omega _{1t,y}L_{h_1} + \omega _{2t,y}L_{h_2}.$$
The investment portfolio is thus continuously rebalanced over time.
3.2 Defined Ambition (DA) Approach
The DA approach generalizes the DB approach to stochastic benefit payouts. In the DA approach individuals specify the benefit payout at the start of the decumulation period, the unconditional median growth rate of the current benefit payout and the vector of payout exposures. As in the DB approach, the unconditional forward discount rate and the vector of portfolio weights follow endogenously from the liabilities of the contract. The DA approach generalizes the DB approach in two directions.
First, the unconditional median growth rate of the current benefit payout (45) may depend on the real interest rate r t, i.e.,
 $$\gamma _{t,y}^u = g_0 + g_1\cdot \pi _t + g_2\cdot r_t,$$
where the coefficients g 0, g 1 and g 2 are given exogenously.Footnote 21 In fact, the coefficient g 2 models the preference for intertemporal substitution (i.e., the extent to which the drawdown policy changes in response to a real interest rate shock). We note that if g 1 ∈ {0, 1} and g 2 = 0, (59) reduces to (45).
Second, the individual is allowed to take the speculative risk (i.e.,  $\Sigma _{t,y,h}^B \ne 0$). Section 3.2.1 assumes that the exposure of a future benefit payout to a current Brownian shock does not depend on the investment horizon h; that is,
 $\Sigma _{t,y,h}^B = \Sigma _{t,y}^B $. Figure 5 illustrates this case. Section 3.2.2 considers the DA approach with gradual adjustment of the current benefit payout to a current Brownian shock; that is,
 $\Sigma _{t,y,h}^B $ increases with the horizon h. This case is illustrated by Figure 6.
Illustration of the DA Approach: Direct Adjustment of the Current Benefit Payout. The figure illustrates the DA approach with direct adjustment of the current benefit payout. The left-hand side of the figure shows the exogenous parameters of the contract. These exogenous parameters determine the parameters of the contract on the right-hand side of the figure.

Illustration of the DA Approach: Gradual Adjustment of the Current Benefit Payout. The figure illustrates the DA approach with gradual adjustment of the current benefit payout. The left-hand side of the figure shows the exogenous parameters of the contract. These exogenous parameters determine the parameters of the contract on the right-hand side of the figure.

3.2.1 Direct adjustment of the current benefit payout
We find that the forward discount rate  ${\check \delta}_{t,y,v}^u $ is given by (see Appendix A.3):
 $$\eqalign {{\check \delta}_{t,y,v}^u & = {\opf E}_t[(1-g_1)\pi _{t + v} + (1-g_2)r_{t + v}]-g_0-D_{1v}\sigma _\pi \left( {\lambda_\pi + \displaystyle{1 \over 2}D_{1v}\sigma_\pi} \right) \cr & \quad- D_{2v}\sigma _r\left( {\lambda_r + \displaystyle{1 \over 2}D_{2v}\sigma_r} \right) + \left ( {\omega_{t,y}^S} \right ) ^{\rm \top} \left[ {\left ( {\mu_t-R_t^f} \right ) -\displaystyle{1 \over 2}\Sigma_t{(\Sigma_t)}^{\rm \top} \omega_{t,y}^S} \right] \cr & \quad+ \left ( {\omega_{t,y}^S} \right ) ^{\rm \top} \Sigma _t\left ( {D_v^{\rm \top} \Sigma_t^X} \right ) ^{\rm \top},} $$
where the vector of (efficient) speculative portfolio weights  $\omega _{t,y}^S $ follows from the vector of payout exposures
 $\Sigma _{t,y}^B $:
 $$\omega _{t,y}^S = \left ( {\Sigma_t^{-1}} \right ) ^{\rm \top} \Sigma _{t,y}^B. $$
Comparing (60) with (47), we observe that the forward discount rate  ${\check \delta}_{t,y,v}^u $ now includes two additional terms. The first additional term
 $$\left ( {\omega_{t,y}^S} \right ) ^{\rm \top} \left[ {\left ( {\mu_t-R_t^f} \right ) -\displaystyle{1 \over 2}\Sigma_t{(\Sigma_t)}^{\rm \top} \omega_{t,y}^S} \right] = \left ( {\Sigma_{t,y}^B} \right ) ^{\rm \top} \left[ {\Sigma_t^{-1} \left ( {\mu_t-R_t^f} \right ) -\displaystyle{1 \over 2}\Sigma_{t,y}^B} \right]$$
is due to taking the speculative risk. By taking the speculative risk, pension providers are able to offer an adequate expected payout stream at an affordable price.
The last additional term in (60)
 $$\left ( {\omega_{t,y}^S} \right ) ^{\rm \top} \Sigma _t\left ( {D_v^{\rm \top} \Sigma_t^X} \right ) ^{\rm \top} = -\sigma _\pi ^2 \left ( {\omega_{1t,y}^S K_{h_1} + \omega_{2t,y}^S K_{h_2}} \right ) D_{1v}-\sigma _r^2 \left ( {\omega_{1t,y}^S L_{h_1} + \omega_{2t,y}^S L_{h_2}} \right ) D_{2v}$$
is due to the interaction between the speculative portfolio and the hedging portfolio. Appendix A.4 shows that  $\omega _{1t,y}^S $ and
 $\omega _{2t,y}^S $ are positive if the individual invests efficiently. Hence, the longer the investment horizon is, the larger D 1v and D 2v are and thus the more negative the interaction term
 $\left ( {\omega_{t,y}^S} \right ) ^{\rm \top} \Sigma _t\left ( {D_v^{\rm \top} \Sigma_t^X} \right ) ^{\rm \top} $ becomes. Intuitively, long investment horizons benefit less from speculative risk premia because lower interest rates raising the value of the speculative portfolio go together with a higher value of the liabilities. This applies especially to longer horizons for which the value of the liabilities is relatively more sensitive to interest rates. Figure 7 illustrates the forward discount rate (60) (panel (a)) and the interaction term (panel (b)) as a function of the horizon v. This figure assumes that the current inflation rate and the current real interest rate equal their long-term means.
Illustration of the Forward Discount Rate. Panel (a) illustrates the forward discount rate in the presence of speculative risk. We assume that  $\pi _t = \bar{\pi} = 2\%, \;r_t = \bar{r} = 1\% $g 0 = g 1 = g 2 = 0,
 $\Sigma _{1t,y}^B = \lambda _\pi /5,\;\Sigma _{2t,y}^B =&InLnBrk; \lambda _r/5$ and
 $\Sigma _{3t,y}^B = \lambda _S/5$ Panel (b) illustrates the reduction in the forward discount rate (in %-points) as a result of the interaction between the hedging portfolio and the speculative portfolio. The benchmark parameter values are given in Table 2.

The inflation sensitivity and the real interest rate sensitivity of the value of the pension liabilities are, respectively, given by
 $$\hat{D}_{1t,y} = (1-g_1)\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} (1-e^{-\eta h}){\rm d}h/\eta, $$
 $$\hat{D}_{2t,y} = (1-g_2)\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} (1-e^{-\kappa h}){\rm d}h/\kappa. $$
To replicate the benefit payouts of the contract, the pension provider should choose a hedging portfolio with the same sensitivities.
3.2.2 Gradual adjustment of the current benefit payout
We find that the forward discount rate  ${\check \delta} _{t,y,v}^u $ is given by (see Appendix A.3):
 $$\eqalign{{\check \delta} _{t,y,v}^u =\; &{ {\opf E}}_t[(1-g_1)\pi _{t + v} + (1-g_2)r_{t + v}]-g_0-D_{1v}\sigma _\pi \left( {\lambda_\pi + \displaystyle{1 \over 2}D_{1v}\sigma_\pi} \right) \cr &-D_{2v}\sigma _r\left( {\lambda r + \displaystyle{1 \over 2}D_{2v}\sigma_r} \right) + q_{t,y,v}\left ( {\omega_{t,y}^S} \right ) ^{\rm \top} \left[ {\left ( {\mu_t-R_t^f} \right ) -\displaystyle{1 \over 2}q_{t,y,v}\Sigma_t\Sigma_t^{\rm \top} \omega_{t,y}^S} \right] \cr &+ q_{t,y,v}\left ( {\omega_{t,y}^S} \right ) ^{\rm \top} \Sigma _t\left ( {D_v^{\rm \top} \Sigma_t^X} \right ) ^{\rm \top},} $$
where the vector of speculative weights is given by
 $${\hat \Sigma} _{t,y}^B = \int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} \Sigma _{t,y,h}^B {\rm d}h.$$
with
 $${\hat \Sigma} _{t,y}^B = \int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} \Sigma _{t,y,h}^B {\rm d}h.$$
Equations (67) and (68) show that the individual implements a life-cycle investment strategy if the vector of payout exposures  $\Sigma _{t,y,h}^B $ – which is exogenously given – increases with the horizon h. Indeed, when the remaining life expectancy declines, the value weights α t,y,h of the shorter horizons become larger. As a result,
 ${\hat \Sigma} _{t,y}^B $ decreases as the individual ages. Hence, the vector of speculative portfolio weights
 $\omega _{t,y}^S $ is also a decreasing function of age.
Equation (66) shows that gradual adjustment of the current benefit payout to speculative shocks (i.e., q t,y,v increases with v) is another reason why the forward discount rate  ${\check \delta} _{t,y,v}^u $ depends on the horizon v. Indeed, the further into the future a benefit payout occurs, the larger the exposure of the benefit payout to a current speculative shock is, and hence the higher the discount rate will be.
We note that gradual adjustment of the current benefit payout also impacts the interaction term  $q_{t,y,v}\left ( {\omega_{t,y}^S} \right ) ^{\rm \top} \Sigma _t\left ( {D_v^{\rm \top} \Sigma_t^X} \right ) ^{\rm \top} $. This term causes the term structure to become less upward sloping. Hence, although gradual adjustment causes the forward discount rate to increase more rapidly with the horizon, the interaction term somewhat mitigates the increase in the slope of the term structure of the forward discount rates.
We illustrate the forward discount rate (66) in Figure 8. This figure assumes that the current inflation rate and the current real interest rate equal their long-term means. Moreover, the vector of payout exposures is given by  $\Sigma _{t,y,v}^B = (1-e^{-0.2v})(\lambda _\pi /5,\lambda _r/5,\lambda _S/5)$. Hence, it takes 3 1/2 years before 50% of the Brownian shocks λ π/5dZ 1t, λ r/5dZ 2t, and λ S/5dZ 3t are reflected in the current benefit payout.
Illustration of the Forward Discount Rate. The figure illustrates the forward discount rate in the case of smoothing of speculative shocks. We assume that  $\pi _t = \bar{\pi} = 2\%, \;r_t = \bar{r} = 1\% $, g 0 = g 1 = g 2 = 0,
 $\Sigma _{1t,y,v}^B = \left ( {1-e^{-0.2v}} \right ) \lambda _\pi /5,\;\Sigma _{2t,y,v}^B = \left ( {1-e^{-0.2v}} \right ) \lambda _r/5$ and
 $\Sigma _{3t,y,v}^B = \left ( {1-e^{-0.2v}} \right ) \lambda _S/5$. The benchmark parameter values are given in Table 2. We also illustrate the case in which the individual does not smooth speculative shocks, i.e.,
 $\Sigma _{1t,y}^B = \lambda _\pi /5,\;\Sigma _{2t,y}^B = \lambda _r/5$ and
 $\Sigma _{3t,y}^B = \lambda _S/5$. Hence, the exposure of a future benefit payout to a current Brownian shock is always strictly smaller in the case of smoothing than in the case of no smoothing.

4. Concluding remarks
This paper has explored how to model the decumulation period of a PPR. We have derived a system of restrictions on the contract parameters. These restrictions do not uniquely identify all parameters. As a result, individuals must specify some parameters exogenously. They can specify the parameters according to (at least) two alternative approaches: the investment approach and the consumption approach. In the investment approach, individuals specify the speed of decumulation and the investment policy exogenously. We have shown how these exogenous parameters determine the median growth rate and the volatility of retirement consumption. The consumption approach, in contrast, specifies the entire retirement consumption stream exogenously. We have shown how to derive the discount rate and the investment policy given a particular exogenous consumption profile.
If the median retirement consumption is assumed flat in real terms and benefit payouts respond gradually to a current speculative shock, then the discount rate depends on the investment horizon because of four reasons.Footnote 22 First, mean reversion in the state variables affects the discount rate. Indeed, if the real interest rate exceeds its long-term mean, then returns are expected to decline, and hence long-term benefit payouts benefit less from the current high real interest rate than short-term benefit payouts. Second, the degree of real interest rate exposure varies across horizons. Typically, longer horizons are more exposed to real interest rate risk than shorter horizons and thus benefit from a higher real interest rate risk premium. Hence, the discount rate for a short horizon is lower than the discount rate for a long horizon unless the current real interest rate is substantially above its long-term mean. Third, if the individual invests efficiently, then the hedging portfolio and the speculative portfolio are positively correlated with each other. In particular, longer horizons benefit less from speculative risk premia because lower interest rates raising the value of the speculative portfolio go together with a larger value of the liabilities. Fourth, since a speculative shock is smoothed, such a shock has a larger impact on benefit payouts in the far future than on benefit payouts in the near future. With a larger risk premium for longer horizons, the discount rate increases with the horizon.
Acknowledgements
We are very grateful to Bas Werker for his helpful comments and suggestions.
Conflicts of interest
None.
Appendix
A.1 Derivation of (A1.33)
The log horizon-dependent conversion factor  $\log C_{t,y,h}^{} $ satisfies the following dynamic equation (the second equality follows from (A1.20) and (A1.24)):
 $$\eqalign{{\rm d}\log C_{t,y,h}^{} = \;&{\rm d}\log A_{t,y,h} + {\rm d}\log F_{t,y,h} \cr =\; &\theta _{t-y}{\rm d}t + \displaystyle{{\partial \left ( {\delta_{t,y,h}^u h} \right ) } \over {\partial h}}{\rm d}t-\int_{y + x_r}^t {\rm d} q_{s,y,t-s}\left ( {\omega_{s,y}^S} \right ) ^{\rm \top} \Sigma _s{\rm d}Z_s \cr &\quad \left( {D_{t,y,h}^{\rm \top} \mu_t^X + \displaystyle{1 \over 2}{\rm Tr} \left [ {{\left ( {\Sigma_t^X} \right ) }^{\rm \top} H_{t,y,h}\Sigma_t^X} \right ] } \right){\rm d}t \cr &+ \;\left ( {\left [ {q_{t,y,h}-q_{t,y,0}} \right ] {\left ( {\omega_{t,y}^S} \right ) }^{\rm \top} \Sigma_t-D_{t,y,h}^{\rm \top} \Sigma_t^X} \right ) {\rm d}Z_t.} $$
The dynamic equation of the log conversion factor log C t,y is given by (this follows from (A1.12), (A1.21) and (A1.69))
 $${\rm d}\log C_{t,y} = \left ( {\theta_{t-y} + \mu_{t,y}^C} \right ) {\rm d}t + \left ( {\left [ {1-q_{t,y,0}} \right ] {\left ( {\omega_{t,y}^S} \right ) }^{\rm \top} \Sigma_t-\hat{D}_{t,y}^{\rm \top} \Sigma_t^X} \right ) {\rm d}Z_t-c_{t,y}{\rm d}t,$$
where  $\mu _{t,y}^C {\rm d}t$ is defined as follows:
 $$\eqalign{\mu _{t,y}^C {\rm d}t = &-\theta _{t-y}{\rm d}t + \int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} { {\opf E}}_t[{\rm d}\log C_{t,y,h}]{\rm d}h \cr &+\; \displaystyle{1 \over 2}\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} {\rm d}[\log C_{t,y,h},\log C_{t,y,h}]{\rm d}h \cr &-\;\displaystyle{1 \over 2}\int\limits_0^{x_{\max} -(t-y)} {\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,u}}} \alpha _{t,y,v}{\rm d}[\log C_{t,y,u},\log C_{t,y,v}]{\rm d}u{\rm d}v.} $$
Here, d[log C t,y,u, log C t,y,v] is given by
 $$\eqalign{{\rm d}[\log C_{t,y,u},\log C_{t,y,v}] = \;&\left ( {\left[q_{t,y,u}-q_{t,y,0}\right]{\left ( {\omega_{t,y}^S} \right ) }^{\rm \top} \Sigma_t-D_{y,u}^{\rm \top} \Sigma_t^X} \right ) \cr &\times\; \left ( {\left [ {q_{t,y,v}-q_{t,y,0}} \right ] {\left ( {\omega_{t,y}^S} \right ) }^{\rm \top} \Sigma_t-D_{y,v}^{\rm \top} \Sigma_t^X} \right ) ^{\rm \top} {\rm d}t.} $$
Substitution of (A1.7), (A1.70) and (A1.29) into (A1.32) yields (A1.33).
A.2 Derivation of (A2.39)
We start by deriving the analytical solution to the stochastic differential equation (SDE) for the Ornstein–Uhlenbeck process. After applying Itô’s lemma to the function  $f(t,\pi _t) = e^{\eta t}(\pi _t-\bar{\pi} )$, we find
 $$\eqalign{{\rm d}f\,(t,\pi _t){\rm} = \;&\eta e^{\eta t}(\pi _t-\bar{\pi} ){\rm d}t + e^{\eta t}{\rm d}\pi _t \cr = \;&\eta e^{\eta t}(\pi _t-\bar{\pi} ){\rm d}t-e^{\eta t}\eta (\pi _t-\bar{\pi} ){\rm d}t + e^{\eta t}\sigma _\pi {\rm d}Z_{1t} = \sigma _\pi e_{\rm d}^{\eta t} Z_{1t}} $$
The solution of (A2.73) is given by
 $$f\,(t,\pi _{t + v}) = f\,(t,\pi _t) + \sigma _\pi \int\limits_t^{t + v} {e^{\eta u}} {\rm d}Z_{1u}.$$
The inflation rate at time t + v > t is given by (the first and third equality follow from the definition of f (t, π t), and the second equality follows from (A2.74))
 $$\eqalign{\pi _{t + v} =\; &\bar{\pi} + e^{-\eta (t + v)}f\,(t,\pi _{t + v}) = \bar{\pi} + e^{-\eta (t + v)}f\,(t,\pi _t) + \sigma _\pi \int\limits_t^{t + v} {e^{-\eta (t + v-u)}} {\rm d}Z_{1u} \cr =\; &\bar{\pi} + e^{-\eta v}(\pi _t-\bar{\pi} ) + \sigma _\pi \int\limits_0^v {e^{-\eta (v-u)}} {\rm d}Z_{1(t + u)} \cr =\; &\pi _t + (1-e^{-\eta v})(\bar{\pi} -\pi _t) + \sigma _\pi \int\limits_0^v {e^{-\eta (v-u)}} {\rm d}Z_{1(t + u)}.} $$
In a similar fashion, we find
 $$r_{t + v} = r_t + (1-e^{-\kappa v})(\bar{r}-r_t) + \sigma _r\int\limits_0^v {e^{-\kappa (v-u)}} {\rm d}Z_{2(t + u)}.$$
The (conditional) expectation of the inflation rate 𝔼t[π t+v] and the (conditional) expectation of the real interest rate 𝔼t[r t+v] are given by
 $${ {\opf E}}_t[\pi _{t + v}] = \pi _t + \eta (\bar{\pi} -\pi _t)K_v,$$
 $${ {\opf E}}_t[r_{t + v}]{\rm} = r_t + \kappa (\bar{r}-r_t)L_v.$$
The aggregate inflation rate  $\bar{\pi} _{t,h} = \int_0^h {\pi _{t + v}} {\rm d}v$ and the aggregate real interest rate
 $\bar{r}_{t,h} = \int_0^h {r_{t + v}} {\rm d}v$ play a key role in determining the yield to maturity. We find (the first equality follows from substituting (A2.75) to eliminate π t+v)
 $$\eqalign{{\bar{\pi}} _{t,h} = &\int\limits_0^h {\pi _{t + v}} {\rm d}v \cr = &\int\limits_0^h {(\pi _t + (\bar{\pi} -\pi _t)(1-e^{-\eta v}))} {\rm d}v + \sigma _\pi \int\limits_0^h {\int\limits_0^v {e^{-\eta (v-u)}} {\rm d}Z_{1(t + u)}{\rm d}v} \cr = &\int\limits_0^h {(\pi _t + (\bar{\pi} -\pi _t)(1-e^{-\eta v}))} {\rm d}v + \sigma _\pi \int\limits_0^h {\int\limits_v^h {e^{-\eta (h-u)}}} {\rm d}u{\rm d}Z_{1(t + v)} \cr = &\int\limits_0^h {(\pi _t + (\bar{\pi} -\pi _t)\eta K_v)} {\rm d}v + \displaystyle{{\sigma _\pi} \over \eta} \int\limits_0^h {(1-e^{-\eta (h-v)})} {\rm d}Z_{1(t + v)} \cr = &\int\limits_0^h {{ {\opf E}}_t} [\pi _{t + v}]{\rm d}v + \sigma _\pi \int\limits_0^h {K_{h-v}} {\rm d}Z_{1(t + v)}.} $$
In a similar fashion, we find that the aggregate real interest rate  $\bar{r}_{t,h}$ is given by
 $$\bar{r}_{t,h} = \int\limits_0^h {r_{t + v}} {\rm d}v = \int\limits_0^h {{ {\opf E}}_t} [r_{t + v}]{\rm d}v + \sigma _r\int\limits_0^h {L_{h-v}} {\rm d}Z_{2(t + v)}.$$
The pricing kernel is given by (see, e.g., Brennan and Xia (Reference Brennan and Xia2002)):
 $$\xi _t = \exp \left\{ {-\int\limits_0^t {\left( {\pi_s + r_s + \displaystyle{1 \over 2}\lambda^{\rm \top} \lambda {\rm d}s-\lambda^{\rm \top} Z_t} \right)}} \right\}.$$
Here, λ = (λ π, λ r, λ S) represents the vector of market prices of risk. Denote by P 1t the price of a bond with time to maturity h 1. We can determine P 1t as follows:
 $$P_{1t} = { {\opf E}}_t\left[ {\displaystyle{{\xi_{t + h_1}} \over {\xi_t}}} \right], = { {\opf E}}_t\left[ {\exp \left\{ {-\int\limits_0^{h_1} {\left( {\pi_{t + v} + r_{t + v} + \displaystyle{1 \over 2}\lambda^{\rm \top} \lambda {\rm d}v-\lambda \left ( {Z_{t + h_1}-Z_t} \right ) } \right)}} \right\}} \right].$$
Substituting (A2.79) and (A2.80) into the pricing formula (A2.82) to eliminate  $\int_0^h {\pi _{t + v}} {\rm d}v$ and
 $\int_0^h {r_{t + v}} {\rm d}v$, we arrive at
 $$ \eqalign{P_{1t} =\; &\exp \left\{ {-\int\limits_0^{h_1} {\left( {{\rm {\opf E}}_t\left[ {\pi _{t + v} + r_{t + v}} \right] + \displaystyle{1 \over 2}\lambda ^{\rm \top }\lambda {\rm d}v} \right)} } \right\}{\rm {\opf E}}_t\left[ {\exp \left\{ {-\int\limits_0^{h_1} {\lambda _S} {\rm d}Z_{3(t + v)}} \right\}} \right. \cr &\left. {\exp \left\{ {\int\limits_0^{h_1} {\left( {-\lambda _\pi -\sigma _\pi K_{h_1-v}} \right){\rm d}Z_{1(t + v)} + } \int\limits_0^{h_1} {\left( {-\lambda _r-\sigma _rL_{h_1-v}} \right)} {\rm d}Z_{2(t + v)}} \right\}} \right] \cr & \exp \left \{ -\int\limits_0^{h_1} \left({{{\opf E}}_t\left[ {\pi _{t + v} + r_{t + v}} \right]-\lambda _\pi \sigma _\pi K_v-\lambda _r\sigma _rL_v} -\displaystyle{1 \over 2} {\left( {\sigma _\pi K_v} \right)}^2 - {\displaystyle{1 \over 2}{\left( {\sigma _rL_v} \right)}^2} \right) {\rm d}v \right \} \cr & = \exp \left\{ {-\int\limits_0^{h_1} {R_{t,v}} {\rm d}v} \right\}.} $$
The instantaneous nominal forward interest rate R t,v is defined as follows:
 $$R_{t,v} = { {\opf E}}_t\lsqb {\pi_{t + v} + r_{t + v}} \rsqb -\lambda _\pi \sigma _\pi K_v-\lambda _r\sigma _rL_v-\displaystyle{1 \over 2}\lpar {\sigma_\pi K_v} \rpar ^2-\displaystyle{1 \over 2}\lpar {\sigma_rL_v} \rpar ^2.$$
The log bond price is given by (this follows from (A2.77), (A2.78), (A2.83) and (A2.84))
 $$\eqalign{\log P_{1t} = &-\int\limits_0^{h_1} {\lpar {-\pi_t + \eta \lpar {\bar{\pi} -\pi_t} \rpar K_v + r_t + \kappa \lpar {\bar{r}-r_t} \rpar L_v-\lambda_\pi \sigma_\pi K_v} } \cr &\;-\lambda _r\sigma _rL_v-\displaystyle{1 \over 2}\lpar {\sigma_\pi K_v} \rpar ^2-\displaystyle{1 \over 2}\lpar {\sigma_rL_v} \rpar ^2\rpar {\rm d}v.} $$
Solving the integral (A2.85), we arrive atFootnote 23
 $$\eqalign{\log P_{1t} = &-\pi _th_1-\left( {\bar{\pi} -\pi_t} \right ) \left( {h_1-K_{h_1}} \right ) -r_th_1-\left( {\bar{r}-r_t} \right ) \left( {h_1-L_{h_1}} \right ) \cr &+\; \displaystyle{{\lambda _\pi \sigma _\pi} \over \eta} \left( {h_1-K_{h_1}} \right ) + \displaystyle{{\lambda _r\sigma _r} \over \kappa} \left( {h_1-L_{h_1}} \right ) \cr &+\; \displaystyle{1 \over 2}\left( {\displaystyle{{\sigma_\pi} \over \eta}} \right)^2\left( {h_1-2K_{h_1} + \displaystyle{1 \over 2}K_{2h_1}} \right) + \displaystyle{1 \over 2}\left( {\displaystyle{{\sigma_r} \over \kappa}} \right)^2\left( {h_1-2L_{h_1} + \displaystyle{1 \over 2}L_{2h_1}} \right) \cr &\;= -\pi _tK_{h_1}-r_tL_{h_1}-M_{h_1}.} $$
Here, the horizon-dependent constant  $M_{h_1}$ is defined as follows:
 $$\eqalign{M_{h_1} = \;&\left( {\bar{\pi} -\displaystyle{{\lambda_\pi \sigma_\pi} \over \eta} -\displaystyle{1 \over 2}{\left[ {\displaystyle{{\sigma_\pi} \over \eta}} \right]}^2} \right)\left ( {h_1-K_{h_1}} \right ) + \displaystyle{1 \over {4\eta}} \left ( {\sigma_\pi K_{h_1}} \right ) ^2 \cr &+ \left( {\bar{r}-\displaystyle{{\lambda_r\sigma_r} \over \kappa} -\displaystyle{1 \over 2}{\left[ {\displaystyle{{\sigma_r} \over \kappa}} \right]}^2} \right)\left ( {h_1-L_{h_1}} \right ) + \displaystyle{1 \over {4\kappa}} \left ( {\sigma_rL_{h_1}} \right ) ^2.} $$
To calculate how the value of the bond with a fixed maturity date t + h 1 develops as time proceeds (i.e., t + h 1 is fixed but t changes), we apply Itô’s lemma to
 $$P_{1t} = \exp \lcub {-\pi_tK_{h_1}-r_tL_{h_1}-M_{h_1}} \rcub .$$
We find
 $$\eqalign{\displaystyle{{{\rm d}P_{1t}} \over {P_{1t}}} =\; &(R_{t,h_1}-\eta \left ( {\bar{\pi} -\pi_t} \right ) K_{h_1}-\kappa \left ( {\bar{r}-r_t} \right ) L_{h_1} + \displaystyle{1 \over 2}\left ( {\sigma_\pi K_{h_1}} \right ) ^2 + \displaystyle{1 \over 2}\left ( {\sigma_rL_{h_1}} \right ) ^2){\rm d}t \cr &\quad \sigma _\pi K_{h_1}{\rm d}Z_{1t}-\sigma _rL_{h_1}{\rm d}Z_{2t} \cr =\; &\left ( {r_t + \pi_t-\lambda_\pi \sigma_\pi K_{h_1}-\lambda_r\sigma_rL_{h_1}} \right ) {\rm d}t-\sigma _\pi K_{h_1}{\rm d}Z_{1t}-\sigma _rL_{h_1}{\rm d}Z_{2t}.} $$
A.3 Derivation of (A3.47), (A3.60) and (A.66)
We show that the following specification of the (unconditional) forward discount rate yields budget balance:
 $${\check \delta} _{t,y,v}^u = d_{0v} + d_{1v}\cdot \pi _t + d_{2v}\cdot r_t.$$
Budget balance implies that (see also (A3.35))
 $$\gamma _{t,y}{\rm d}t = \mu _{t,y}^W {\rm d}t-\mu _{t,y}^C {\rm d}t.$$
Substituting (A3.59) and (A3.31) into (A3.91), we arrive at
 $$\left ( {g_0 + g_1\cdot \pi_t + g_2\cdot r_t} \right ) {\rm d}t + \int\limits_{y + x_r}^t {\rm d} \left ( {\Sigma_{s,y,t-s}^B} \right ) ^{\rm \top} {\rm d}Z_s = \mu _{t,y}^W {\rm d}t-\mu _{t,y}^C {\rm d}t.$$
The vector of portfolio weights depends on  $\hat{D}_{t,y} = \int_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} D_{t,y,h}{\rm d}h$ and is given by
 $$\omega _{t,y} = \omega _{t,y}^H + \omega _{t,y}^S = -\left ( {\Sigma_t^X \Sigma_t^{-1}} \right ) ^{\rm \top} \hat{D}_{t,y} + \left ( {\Sigma_t^{-1}} \right ) ^{\rm \top} {\hat \Sigma} _{t,y}^B. $$
Here,  $D_{t,y,h} = \nabla _X\left ( {\delta_{t,y,h}h} \right ) = \left( {\int_0^h {d_{1v}} {\rm d}v,\int_0^h {d_{2v}} {\rm d}v,0} \right) = \left ( {D_{1h},D_{2h},D_{3h}} \right ) = D_h$ models the sensitivity of the discount rate with respect to the underlying state variables.
Substitution of (A3.93) into (A3.8) yields
 $$\eqalign {\mu _{t,y}^W {\rm d}t & = \left({\pi _t + r_t + } {\left[ {{\left( {{\hat \Sigma }_{t,y}^B } \right)}^{\rm \top }-{\hat D}_{t,y}^{\rm \top } \Sigma _t^X } \right]} {\Sigma _t^{-1} \left( {\mu _t-R_t^f } \right)}\right. \cr &\quad \left.{-\displaystyle{1 \over 2}{\left( {\hat{\Sigma }_{t,y}^B } \right)}^{\rm \top }\hat{\Sigma }_{t,y}^B -} {\displaystyle{1 \over 2}\hat{D}_{t,y}^{\rm \top } \Sigma _t^X {\left( {\Sigma _t^X } \right)}^{\rm \top }{\hat{D}}_{t,y} + \hat{D}_{t,y}^{\rm \top } \Sigma _t^X \hat{\Sigma }_{t,y}^B }\right){\rm d}t.}$$
Substituting (A3.90) and the expression for  $\mu _t^X $ (see (A3.38)) into (A3.71), we arrive at
 $$\eqalign{\mu _{t,y}^C {\rm d}t = &\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} d_{0h}{\rm d}h{\rm d}t + \pi _t\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} d_{1h}{\rm d}h{\rm d}t \cr &+\; r_t\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} d_{2h}{\rm d}h{\rm d}t-\hat{D}_{1t,y}^{\rm \top} \eta \left ( {\bar{\pi} -\pi_t} \right ) {\rm d}t-\hat{D}_{2t,y}^{\rm \top} \kappa \left ( {\bar{r}-r_t} \right ) {\rm d}t \cr &\;-\int\limits_{y + x_r}^t {{\rm d}q_{s,y,t-s}} \left ( {\omega_{s,y}^S} \right ) ^{\rm \top} \Sigma _s{\rm d}Z_s + \displaystyle{1 \over 2}\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} {\rm d}\left [ {\log C_{t,y,h},\log C_{t,y,h}} \right ] {\rm d}h \cr &\;-\displaystyle{1 \over 2}\int\limits_0^{x_{\max} -(t-y)} {\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,u}}} \alpha _{t,y,v}{\rm d}\left [ {\log C_{t,y,u},\log C_{t,y,v}} \right ] {\rm d}u{\rm d}v.} $$
It follows from substituting (A3.94) and (A3.95) into (A3.92) that d 1h and d 2h must satisfy the following two conditions:
 $$d_{2h} = 1-g_2 + \kappa D_{2h}.$$
 $$d_{2h} = 1-g_2 + \kappa D_{2h}.$$
Solving these two equations, we find d 1v = (1 − g 1)e −ηv and d 2v = (1 − g 2)e −κv.
The coefficient d 0h must satisfy
 $$\eqalign{\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} d_{0h}{\rm d}h{\rm d}t = &-g_0{\rm d}t + \left [ {{\left ( {{\hat \Sigma}_{t,y}^B} \right ) }^{\rm \top} -\hat{D}_{t,y}^{\rm \top} \Sigma_t^X} \right ] \Sigma _t^{-1} \left ( {\mu_t-R_t^f} \right ) {\rm d}t \cr &-\displaystyle{1 \over 2}\left ( {{\hat \Sigma}_{t,y}^B} \right ) ^{\rm \top} {\hat \Sigma} _{t,y}^B {\rm d}t-\displaystyle{1 \over 2}\hat{D}_{t,y}^{\rm \top} \Sigma _t^X \left ( {\Sigma_t^X} \right ) ^{\rm \top} {\hat{D}}_{t,y}{\rm d}t + \hat{D}_{t,y}^{\rm \top} \Sigma _t^X {\hat \Sigma} _{t,y}^B {\rm d}t \cr &+ \hat{D}_{1t,y}^{\rm \top} \eta \bar{\pi} {\rm d}t + \hat{D}_{2t,y}^{\rm \top} \kappa \bar{r}{\rm d}t \cr &-\displaystyle{1 \over 2}\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,h}} {\rm d}\left [ {\log C_{t,y,h},\log C_{t,y,h}} \right ] {\rm d}h \cr &+ \displaystyle{1 \over 2}\int\limits_0^{x_{\max} -(t-y)} {\int\limits_0^{x_{\max} -(t-y)} {\alpha _{t,y,u}}} \alpha _{t,y,v}{\rm d}\left [ {\log C_{t,y,u},\log C_{t,y,v}} \right ] {\rm d}u{\rm d}v.} $$
We note that
 $$\int\limits_{y + x_r}^t {\rm d} \left ( {\Sigma_{s,y,t-s}^B} \right ) ^{\rm \top} {\rm d}Z_s = \int\limits_{y + x_r}^t {\rm d} q_{s,y,t-s}\left ( {\omega_{s,y}^S} \right ) ^{\rm \top} \Sigma _s{\rm d}Z_s.$$
Straightforward computations yield (A3.66). Equations (A3.47) and (A3.60) emerge as a special case of (A3.66).
A.4 Derivation of the Efficient Speculative Investment Portfolio
This appendix derives the efficient speculative investment portfolio. In particular, we show that  $\Sigma _1^B =&InLnBrk; -\sigma _\pi \left ( {\omega_{1t,y}^S K_{h_1} + \omega_{2t,y}^S K_{h_2}} \right ) $ and
 $\Sigma _2^B = -\sigma _r\left ( {\omega_{1t,y}^S L_{h_1} + \omega_{2t,y}^S L_{h_2}} \right ) $ are (typically) negative. The individual aims to minimize the variance of the change in the log benefit payout, i.e.,
 ${\rm {\open V}}$t[dlog B t,y], subject to a given expected excess return on the speculative portfolio c ≥ 0. Hence, the individual's optimization problem is given by
 $$\eqalign{& \mathop {\left ( {\Sigma_1^B} \right ) }\limits_{\Sigma _1^B, \Sigma _2^B, \Sigma {_3^B} ^{\min}} ^2 +\; \left ( {\Sigma_2^B} \right ) ^2 +\; \left ( {\Sigma_3^B} \right ) ^3 \cr & {\rm s}{\rm. t}{\rm.} \quad \Sigma _1^B \lambda _\pi + \Sigma _2^B \lambda _r + \Sigma _3^B \lambda _S = c.} $$
The Lagrangian  ${\rm {\cal L}}$ is given by
 $${\rm {\cal L}} = \left ( {\Sigma_1^B} \right ) ^2 +\; \left ( {\Sigma_2^B} \right ) ^2 +\; \left ( {\Sigma_3^B} \right ) ^3 +\; y\left ( {c-\Sigma_1^B \lambda_\pi +\; \Sigma_2^B \lambda_r + \Sigma_3^B \lambda_S} \right ) .$$
Here, y ≥ 0 denotes the Lagrange multiplier.
The first-order optimality conditions are given by
 $$2\Sigma _1^{B{^\ast}} = y\lambda _\pi, $$
 $$2\Sigma _2^{B{^\ast}} = y\lambda _r,$$
 $$2\Sigma _3^{B{^\ast}} {\rm} = y\lambda _S.$$
It follows from (A4.102)–(A4.104) that  $\Sigma _1^{B*} \propto \lambda _\pi, \Sigma _2^{B*} \propto \lambda _r$ and
 $\Sigma _S^{B*} \propto \lambda _S$. Since λ r and λ π are typically negative, it follows that
 $\Sigma _1^{B*} $ and
 $\Sigma _2^{B*} $ are also typically negative.
Optimal Benefit Policy
This appendix derives the optimal benefit policy with and without pooling of mortality risk. We assume the same economy as in Section 2.1. Denote by x D the age at which the individual dies. In case mortality risk is pooled, we can determine the optimal benefit policy by assuming x D is known in advance. Hence, we have the following maximization problem:
 $$\eqalign{& \max _{B_{t,y}:x_r + y \le t \le x_D + y}^{} \int\limits_{x_r + y}^{x_D + y} {e^{-\rho \left ( {t-x_r-y} \right ) }} { {\opf E}}_{x_r + y}\left[ {\displaystyle{1 \over {1-\gamma}} {\left( {\displaystyle{{B_{t,y}} \over {\Pi_t}}} \right)}^{1-\gamma}} \right]{\rm d}t \cr & {\rm s}{\rm. t}{\rm.}\; { {\opf E}}_{x_r + y}\left[ {\int\limits_{x_r + y}^{x_D + y} {\displaystyle{{\xi_t} \over {\xi_{x_r + y}}}} B_{t,y}{\rm d}t} \right] \le W_{x_r + y}.} $$
Here, ξ t represents the nominal pricing kernel (or stochastic discount factor) at time t (see (A4.81) for an explicit analytical expression of ξ t),  $\Pi _t = \exp \left\{ {\int_0^t {\pi_s} {\rm d}s} \right\}$ corresponds to the consumer price index at time t, γ stands for the coefficient of relative risk aversion, and ρ denotes the rate of time preference.
Maximizing (A4.105), we arrive at
 $$B_{t,y}^{^\ast} = \Pi _t\left( {e^{\rho \left ( {t-x_r-y} \right ) }y\Pi_t\displaystyle{{\xi_t} \over {\xi_{x_r + y}}}} \right)^{-\displaystyle{1 \over \gamma}}, $$
where y > 0 denotes the Lagrange multiplier.
Substituting (A4.81) into (A4.106), we find
 $$\eqalign {B_{t,y}^{\ast} & = B_{x_r + y,y}^{\ast} \exp \left\{{\int\limits_{x_r + y}^t {\pi _s} {\rm d}s-\displaystyle{{\rho -(1/2)\lambda ^{\rm \top }\lambda } \over \gamma }\left( {t-x_r-y} \right)}\right. \cr &\quad\, \left. + {\displaystyle{1 \over \gamma }\int\limits_{x_r + y}^t {r_s} {\rm d}s + \displaystyle{{\lambda _\pi } \over \gamma }\int\limits_{x_r + y}^t {\rm d} Z_{1s} + \displaystyle{{\lambda _r} \over \gamma }\int\limits_{x_r + y}^t {\rm d} Z_{2s} + \displaystyle{{\lambda _S} \over \gamma }\int\limits_{x_r + y}^t {\rm d} Z_{3s}}\right\}.}$$
Hence, the optimal g 0, g 1 and g 2 are given by
 $$g_0 = \displaystyle{{(1/2)\lambda ^{\rm \top} \lambda -\rho} \over \gamma}, $$
 $$g_1{\rm} = {\rm} 1,$$
 $$g_2{\rm} = \displaystyle{1 \over \gamma}. $$
We now consider the case where mortality risk is not pooled. We have the following maximization problem in case the individual does not have bequest motives:
 $$\eqalign {&\mathop {\max }\limits_{B_{t,y}:x_r + y \le t \le x_{\max } + y} {\int\limits_{x_r + y}^{x_{\max } + y} {e^{-\rho (t-x_r-y)}{\rm {\opf E}}_{x_r + y}} } \big[{{\open 1} _{1t \lt x_D + y}\big]{\rm {\opf E}}_{x_r + y}\left[\displaystyle{1 \over {1-\gamma }}{\left( {\displaystyle{{B_{t,y}} \over {\Pi _t}}} \right)}^{1-\gamma }} \right]{\rm d}t }\cr & {\rm s}{\rm .t} {\rm .} \, {\rm {\opf E}}_{x_r + y}\left[ {\int\limits_{x_r + y}^{x_{\max } + y} {\displaystyle{{\xi _t} \over {\xi _{x_r + y}}}} B_{t,y}{\rm d}t} \right] \le W_{x_r + y}.}$$
Assuming independence between the age of death and financial returns, we can write (A4.111) as follows:
 $${\rm s}{\rm. t}{\rm.} \;{ {\opf E}}_{x_r + y}\left[ {\int\limits_{x_r + y}^{x_{\max} + y} {\displaystyle{{\xi_t} \over {\xi_{x_r + y}}}} B_{t,y}^{} {\rm d}t} \right] \le W_{x_r + y}.$$
Note that  $ {\opf E}_{x_r + y} \lsqb {{\open 1} t \lt x_D + y} \rsqb $ represents the probability that an individual aged x r at time x r + y will survive at least t − y − x r years, i.e.,
 $${ {\opf E}}_{x_r + y}\left \lsqb {{\open 1} t \lt x_D + y} \right \rsqb = _{t-y-x_r}p_{x_r}. $$
Problem (A4.112) is thus equivalent to:
 $$\eqalign{& \max _{B_{t,y}:x_r + y \le t \le x_{\max} + y}\int\limits_{x_r + y}^{x_{\max} + y} {e_{}^{-\rho \left ( {t-x_r-y} \right ) }} _{t-y-x_r}p_{x_r}{ {\opf E}}_{x_r + y}\left[ {\displaystyle{1 \over {1-\gamma}} {\left( {\displaystyle{{B_{t,y}} \over {\Pi_t}}} \right)}^{1-\gamma}} \right]{\rm d}t \cr & {\rm s}{\rm. t}{\rm.} \;{ {\opf E}}_{x_r + y}\left[ {\int\limits_{x_r + y}^{x_{\max} + y} {\displaystyle{{\xi_t} \over {\xi_{x_r + y}}}} B_{t,y}{\rm d}t} \right] \le W_{x_r + y}.} $$
Maximizing (A4.114), we arrive at
 $$B_{t,y}^{^\ast} = \Pi _t\left( {\displaystyle{{e^{\rho \left ( {t-x_r-y} \right ) }} \over {t-y-x_rp_{x_r}}}y\Pi_t\displaystyle{{\xi_t} \over {\xi_{x_r + y}}}} \right)^{-\displaystyle{1 \over \gamma}}, $$
where y > 0 denotes the Lagrange multiplier.
Note that the following holds (see also (A4.4)):
 $$_{t-y-x_r} p_{x_r} = \exp \left\{ {-\int\limits_0^{t-y-x_r} {\theta_{x_r + v}} {\rm d}v} \right\}$$
Substituting (A4.81) into (A4.115) and using (A4.116), we find
 $$\eqalign{B_{t,y}^{\ast} & = B_{x_r + y,y}^{\ast} \exp \left\{{\int\limits_{x_r + y}^t {\pi _s} {\rm d}s-\displaystyle{{\rho -(1/2)\lambda ^{\rm \top }\lambda } \over \gamma }\left( {t-x_r-y} \right)}\right. \cr & \left. { \quad\;+ \displaystyle{1 \over \gamma }\int\limits_{x_r + y}^t {\left( {r_s-\theta _{s-y}} \right)} {\rm d}s + \displaystyle{{\lambda _\pi } \over \gamma }\int\limits_{x_r + y}^t {\rm d} Z_{1s} + \displaystyle{{\lambda _r} \over \gamma }\int\limits_{x_r + y}^t {\rm d} Z_{2s} + \displaystyle{{\lambda _S} \over \gamma }\int\limits_{x_r + t}^t {\rm d} Z_{3s}} \right\}.}$$
In case of no pooling of mortality risk, the optimal median growth rate of the benefit payout is thus given by:
 $$\gamma _{t,y}^u = \pi _t + \displaystyle{1 \over \gamma} \cdot \left( {r_t + \displaystyle{1 \over 2}\lambda^{\rm \top} \lambda -\rho -\theta_{t-y}} \right).$$
Compared to the case where mortality risk is pooled, the biometric rate of return θ t−y reduces the effective median growth rate of the current benefit payout.



