




No CrossRef data available.
UNIFORM ESTIMATES FOR THE TAIL PROBABILITY OF MAXIMA OVER FINITE HORIZONS WITH SUBEXPONENTIAL TAILS
Published online by Cambridge University Press: 22 January 2004
Abstract
Let F be the common distribution function of the increments of a random walk {Sn, n ≥ 0} with S0 = 0 and a negative drift and let {N(t), t ≥ 0} be a general counting process, independent of {Sn, n ≥ 0}. This article investigates the tail probability, denoted by ψ(x; t), of the maximum of SN(v) over a finite horizon 0 ≤ v ≤ t. When F is strongly subexponential, some asymptotics for ψ(x; t) are derived as x → ∞. The merit is that all of the obtained asymptotics are uniform for t in a finite or infinite time interval.
Information
- Type
- Research Article
- Information
- Probability in the Engineering and Informational Sciences , Volume 18 , Issue 1 , January 2004 , pp. 71 - 86
- Copyright
- © 2004 Cambridge University Press
1. INTRODUCTION
Let F be the common distribution function (d.f.) of the increments of a random walk {Sn, n ≥ 0} with S0 = 0. This distribution function always satisfies F(x) = 1 − F(x) > 0 for all x. We assume hereafter that F has a finite mean −μ < 0; hence, the random walk Sn drifts to −∞ and the ultimate maximum of the random walk is finite almost surely. Random walks with heavy-tailed increments and negative drifts have been extensively investigated in the literature; see, for example, Feller [9], Asmussen [1,2], Embrechts, Klüppelberg, and Mikosch [7], and Rolski, Schmidli, Schmidt, and Teugels [21] for some background and important applications, see also a recent study by Denisov, Foss, and Korshunov [6] on an extreme case where the mean of the increment is not finite.
Veraverbeke [23] and Embrechts and Veraverbeke [8] investigated the asymptotic behavior of the tail probability of the ultimate maximum. Under the assumption that the d.f. F∞ defined by (2.4) is subexponential, they provided a celebrated asymptotic relation that

Hereafter, any limit relationship is for x → ∞ unless otherwise stated; the symbol ∼ means that the quotient of the left-hand side and right-hand side of the corresponding relationship tends to one in the indicated limiting sense. Relation (1.1) has been universally accepted as one of the most fundamental results in risk theory and some related fields. Korshunov [17] proved that the subexponentiality of F∞ is also necessary for (1.1).
Throughout, let {N(t), t ≥ 0} be a counting process, namely a nonnegative, nondecreasing, and integer-valued stochastic process, which is independent of the random walk {Sn, n ≥ 0} and satisfies

for any t > 0. We write S(t) = SN(t) for t ≥ 0. In this article, we are interested in the tail probability of the maxima of the random sum S(t) over a finite time horizon. For this purpose, we introduce a bivariate function

and write

Since for any fixed x ≥ 0 the function ψ(x; t) is nondecreasing in t, the limit in (1.3) is well defined. Clearly, if λ(t) → ∞ as t → ∞, then (1.1) implies that the relation

holds under the same assumptions.
According to Ng, Tang, Yan, and Yang [20], we propose an actuarial explanation for the functions ψ(x; t) and ψ(x;∞). Rather than counting the number of claims, we count the number of customers buying insurance. The customer arrival process is assumed to be the counting process N(t), t ≥ 0. After the kth customer has bought an insurance contract, k ≥ 1, the insurance company will bear a risk from this policyholder within a fixed term. Suppose that the amount of all incurred claims due to the kth policyholder is Zk and that Zk, k ≥ 1, are independent and identically distributed (i.i.d.) nonnegative random variables (r.v.'s) with finite mean. The premium paid for each policy is

, where the positive constant δ can be interpreted as the safety loading. Clearly, the insurance company's total net risk due to the kth policyholder is

Assuming that the interest rate is zero, the total claim amount accumulated in the period (0, t] can be written as

and the surplus of the company accumulated in the period (0, t] can be written as

where x denotes the initial capital of the company. Thus, ψ(x; t) and ψ(x;∞) defined by (1.2) and (1.3) represent the ruin probability within finite time t and the ultimate ruin probability, respectively.
In this article, we will investigate the asymptotic behavior of the tail probability ψ(x; t) and aim at asymptotic relations which are uniform for t in a finite or infinite time interval. As generally acknowledged by those experienced mathematicians, the uniformity often significantly merits the theoretical value of the asymptotic relations obtained. We remark that it is also crucial for many application problems; see Klüppelberg and Mikosch [14] and Embrechts et al. [7, Chap.8] for related discussions.
Under the assumption that the d.f. F of the increments is strongly subexponential, applying Theorem 1 of Kaas and Tang [12], we can easily obtain that

holds for any fixed t > 0; see also Foss and Zachary [10] for a similar result in a more general framework. In this article, we prove in Theorem 3.1 below that the asymptotic property in (1.6) is uniform for t in any finite interval [t1, t2] for 0 < t1 ≤ t2 < ∞; that is,

We remark that if λ(t) → ∞ as t → ∞, then the local uniformity of (1.6) cannot be extended to any infinite time interval. Based on some analysis, we intuitively believe that the asymptotic relation (1.6) will lose its accuracy when λ(t) gets large.
A significant large deviation result by Korshunov [18] makes it possible to derive an asymptotic relation for ψ(x; t) such that it is uniform for t in an infinite interval. We prove in Theorem 4.1 below that the uniformity for t ∈ [t1,∞) can be achieved by the asymptotic relation

that is,

This is the main contribution of the present article. In doing so, we only additionally assume that the counting process {N(t), t ≥ 0} satisfies the law of large numbers. A closely related work in the literature is Klüppelberg and Mikosch [14], who successfully established a precise large deviation result for the random sum (1.5) as

with γ > 0 arbitrarily fixed; see also the review article by Mikosch and Nagaev [19]. Clearly, the uniformity in (1.9) is more general than that in (1.10).
For the sake of completeness, we further consider the uniformity of the asymptotic relation (1.8) for t ∈ (0,∞). We examine this uniformity for two special cases where N(t) are the Cox and renewal processes, respectively.
The outline of this article is as follows. Section 2 lists some preliminaries about heavy-tailed distributions; Section 3 proves that the asymptotic relation (1.6) is uniform for t in any finite interval [t1, t2] for 0 < t1 ≤ t2 < ∞; Section 4 proves that the asymptotic relation (1.8) holds uniformly for t ∈ [t1,∞) for any t1 > 0; Section 5 complements the study by considering the uniformity for t ∈ (0,∞).
2. HEAVY-TAILED DISTRIBUTIONS
Like many recent researchers in the fields of applied probability and risk theory, we restrict our interest to the case of heavy-tailed d.f.'s. The most important class of heavy-tailed distributions is the subexponential class, denoted as

. By definition, a d.f. F concentrated on [0,∞) belongs to the class

if and only if

where F*2 denotes the convolution of F. More generally, a d.f. F concentrated on (−∞,∞) is still said to be subexponential if the d.f.

is subexponential, where and throughout

denotes the indicator function of a set A. It is well known that if

, then

for any fixed real number l; see Chistyakov [5], or Embrechts et al. [7, Lemma1.3.5]. Relation (2.2) characterizes another famous class of heavy-tailed distributions, denoted as

. We easily check that for a d.f.

, there exists a positive function lF(x) → ∞ such that

A nice review on heavy-tailed distributions with applications to insurance and finance is the book by Embrechts et al. [7].
Recently, Korshunov [18] introduced another class of subexponential d.f.'s. For a subexponential d.f. F with

, let

Clearly, for any u ∈ [0,∞] , Fu defines a standard d.f. concentrated on [0,∞). According to the terminology of Korshunov [18], we say that the d.f. F is strongly subexponential, denoted as

, if the relation

holds uniformly for u ∈ [1,∞] . From the discussions in Korshunov [18], we see that the class

almost coincides with the class of subexponential distributions with finite m =

. Specifically, the class

contains the Pareto type (with parameter α > 1), the log-normal, and the Weibull distributions. It was also pointed out recently by Denisov, Foss, and Korshunov [6, Lemma9] that another useful subexponential class

, which was introduced by Klüppelberg [13] and is characterized by the property

is a subclass of the class

. To the best of our knowledge, whether or not this inclusion

is strict remains unsolved.
We repeat here the result of Korshunov [18] for our quotation later:
Lemma 2.1: If the d.f. F of the increments of the random walk is strongly subexponential and has a finite mean −μ < 0, then it holds uniformly for n ≥ 1 that

Some intimately related results can be found in Borovkov and Borovkov [4].
3. ESTIMATE 1: t ∈ [t1,t2] FOR 0 < t1 ≤ t2 < ∞
Recall that {Sn, n ≥ 0} denotes a random walk with S0 = 0 and a negative drift; that is, {Sn − Sn−1, n ≥ 1} is a sequence of i.i.d. r.v.'s with common d.f. F and finite mean −μ < 0. Let N(t) be a nonnegative, nondecreasing, and integer-valued stochastic process, independent of the random walk {Sn, n ≥ 0} and satisfying

In the sequel, for two positive infinitesimals A(x) and B(x), we write A(x) [gsim ] B(x) if lim inf A(x)/B(x) ≥ 1 and write A(x) [lsim ] B(x) if lim sup A(x)/B(x) ≤ 1. Clearly, A(x) ∼ B(x) if and only if both A(x) [gsim ] B(x) and A(x) [lsim ] B(x).
The first result of this article is as follows:
Theorem 3.1: If

, then for any 0 < t1 ≤ t2 < ∞, it holds uniformly for t ∈ [t1, t2] that

We formulate the proof of Theorem 3.1 into a series of lemmas below, which have their own merits.
Lemma 3.1: If

, then uniformly for 0 < t < ∞, the relation
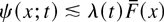
holds; that is,

Proof: Since (2.5) holds uniformly for n ≥ 1, we have uniformly for t ∈ (0,∞) that

This ends the proof of Lemma 3.1. █
Lemma 3.2: If F

, then for any 0 < t1 ≤ t2 < ∞, the relation

holds uniformly for t ∈ [t1, t2], where the uniformity is understood in a similar way as in Lemma 3.1.
Proof: Applying Lemma 1 of Korshunov [18] and recalling (2.3), in terms of the function lF(x) in (2.3) we derive that, uniformly for t ∈ (0,∞),

In view that N(t), hence λ(t), is nondecreasing, we have

Substituting this into the right-hand side of (3.5), we obtain that

holds uniformly for t1 ≤ t ≤ t2. This ends the proof of Lemma 3.2. █
Lemma 3.3: If

, then for any 0 < t2 < ∞, the relation

holds uniformly for t ∈ (0, t2].
Proof: Trivially, the inequality

holds for all 0 < t, x < ∞. On the other hand, recalling (2.2), we have, uniformly for t ∈ (0, t2] ,

This ends the proof of Lemma 3.3. █
4. ESTIMATE 2: t ∈ [t1,∞) FOR 0 < t1 < ∞
This section is devoted to the uniform estimate for the probability ψ(x; t) for large t.
Theorem 4.1: If the conditions
1.

2. N(t)/λ(t) →p 1 as t → ∞
hold simultaneously, then for any t1 > 0, it holds uniformly for t ∈ [t1,∞) that

Proof: We bear in mind that all the asymptotic relations in the proof below hold uniformly for t ∈ [t1,∞). The proof starts from the asymptotic relation (3.3):
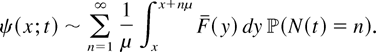
For arbitrarily fixed 0 < δ < 1, applying the techniques developed by Klüppelberg and Mikosch [14], we divide the series on the right-hand side into three parts as follows:

Now, we treat the three terms respectively. Clearly,

As for I3, we have

Then, we handle I2:

Combining all these bounds together yields that

By the assumption N(t)/λ(t) →p 1 as t → ∞, we know that

Furthermore, from Lemma 3.1 in Ng, Tang, Yan, and Yang [20], we also have

Thus, for any ε > 0, there exists some large t* = t*(ε, δ) > t1 such that for all t > t*,

Substituting (4.5) into (4.4) yields

It follows that

where, in the last step, we applied (4.6) and Theorem 3.1. By the arbitrariness of ε and δ, we conclude that

Next, we turn to derive the lower bound for ψ(x; t). Using the same approach as applied in (4.3), we obtain the corresponding lower bound for I2 that

The assumption N(t)/λ(t) →p 1 as t → ∞ implies that there exists some large t* = t*(ε, δ) > t1 such that for all t > t*,

Substituting (4.9) into (4.8) and recalling (4.2) and Theorem 3.1, we obtain

The arbitrariness of ε and δ gives that

Finally, we conclude from (4.7) and (4.10) that

This ends the proof of Theorem 4.1. █
5. ESTIMATE 3: t ∈ (0,∞)
5.1. General Case
Now, we derive some uniform estimates for the tail probability ψ(x; t) over the time interval (0,∞). By virtue of Theorem 4.1, this amounts to considering the uniformity for t ∈ (0,1] . We assume that

Substituting (5.1) into the right-hand side of (3.5), going along the same line as the proof of Lemma 3.2, we obtain that

holds uniformly for 0 < t ≤ 1. Combining this with Lemmas 3.1 and 3.3 leads to the following lemma:
Lemma 5.1: If the conditions
1.

2. N(t) satisfies (5.1)
hold simultaneously, then (3.1) holds uniformly for t ∈ (0,1].
From Theorem 4.1 and Lemma 5.1, we immediately obtain the following theorem.
Theorem 5.1: If the conditions
1.

2. N(t)/λ(t) →p 1 as t → ∞
3. N(t) satisfies (5.1)
hold simultaneously, then it holds uniformly for t ∈ (0,∞) that

5.2. Cox Case
Now, we seek some concrete examples such that assumption (5.1) is fulfilled. Let N1(t), t ≥ 0, be a homogeneous Poisson process with unit intensity and let Λ(t), t ≥ 0, be another process independent of N1(t) with the following properties:
1. Λ(0) = 0
2.

for any t ≥ 0
3. The trajectories of Λ(t) do not decrease and are right-continuous.
We say that a doubly stochastic process N(t) that is defined as the composition of N1(·) and Λ(·),

is a Cox process. Clearly, it holds for any t > 0 that
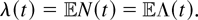
For overviews on Cox processes as well as their applications to actuarial and financial mathematics, we refer to Grandell [11] and Björk and Grandell [3]. Recent discussions on Cox processes can be found, for example, in Korolev [15,16].
Lemma 5.2 shows that (5.1) can be satisfied by some Cox processes.
Lemma 5.2: Let N(t) be a Cox process with stochastic intensity Λ(t) satisfying

Then, N(t) satisfies assumption (5.1).
Proof: By the definition of Cox process, we derive

For arbitrarily fixed M > 0, we continue the derivation as follows:

By assumption (5.4), we know that the right-hand side of the above vanishes as M → ∞. Therefore, (5.1) is fulfilled. This ends the proof of Lemma 5.2. █
Based on Lemma 5.2, the following result is an immediate consequence of Theorem 5.1.
Corollary 5.1: Let N(t) be a Cox process with stochastic intensity Λ(t) satisfying (5.4). If the conditions
1.

2.

as t → ∞
hold simultaneously, then (5.2) holds uniformly for t ∈ (0,∞).
Proof: By Lemma 5.2, assumption (5.4) implies assumption (5.1). Furthermore, by Lemma 2 in Korolev [16], we see that as t → ∞,

implies N(t)/λ(t) →p 1. Hence, Theorem 5.1 gives the result in Corollary 5.1. █
We remark that N(t) in Corollary 5.1 can be specified as any homogeneous or inhomogeneous Poisson process.
5.3. Renewal Case
The second case we consider is the renewal process N(t) defined by

where {Yk, k ≥ 1} is a sequence of i.i.d. and nonnegative r.v.'s and max φ = 0 by convention. In order that λ(t) > 0 for any t > 0, we assume

Lemma 5.3: Consider the renewal process N(t) defined in (5.5). If Y1 satisfies assumption (5.6), then N(t) satisfies assumption (5.1).
Proof: By condition (5.6), there exists some integer m0 ≥ 1 such that

holds. We write

Clearly, 0 < p0(t) ≤ p0(1) < 1 for each 0 < t ≤ 1. Hence, for any n ≥ 1, we derive that

This proves that assumption (5.1) holds. █
By the well-known renewal theory, we know that if the r.v. Y1 in (5.5) has a finite mean 1/λ > 0, then

see, for example, Feller [9, Chap. XI]. Based on (5.7) and Lemma 5.3, the following result is another immediate consequence of Theorem 5.1.
Corollary 5.2: Let N(t) be a renewal process defined by (5.5). If the conditions
1.

2. Y1 satisfies (5.6) and has a finite mean 1/λ
hold simultaneously, then (5.2) holds uniformly for t ∈ (0,∞). Furthermore, for any positive function f (x) → ∞, it holds uniformly for t ≥ f (x) that

that is,

Acknowledgments
The author would like to thank Professor Rob Kaas for his helpful discussions. This work was supported by the Dutch Organization for Scientific Research (project no. NWO 42511013).
References
REFERENCES
Asmussen, S.
(1987).
Applied probability and queues.
Chichester:
Wiley.
Björk, T. &
Grandell, J.
(1988).
Exponential inequalities for ruin probabilities in the Cox case.
Scandanavian Actuarial Journal
1–2:
77–111.Google Scholar
Borovkov, A.A. &
Borovkov, K.A.
(2002).
On probabilities of large deviations for random walks. I. Regularly
varying distribution tails.
Theory of Probability and Its Applications
46(2):
193–213.Google Scholar
Chistyakov, V.P.
(1964).
A theorem on sums of independent positive random variables and its
applications to branching random processes.
Theory of Probability and Its Applications
9:
710–718.Google Scholar
Denisov, D.,
Foss, S. &
Korshunov, D.
(2003).
Tail asymptotics for the supremum of a random walk when the mean
is not finite.
Queueing Systems Theory and Applications,
to appear.
Embrechts, P.,
Klüppelberg, C., &
Mikosch, T.
(1997).
Modelling extremal events for insurance and finance.
Berlin:
Springer-Verlag.CrossRef
Embrechts, P. &
Veraverbeke, N.
(1982).
Estimates for the probability of ruin with special emphasis on the
possibility of large claims.
Insurance Mathematics and Economics
1(1):
55–72.Google Scholar
Feller, W.
(1971).
An introduction to probability theory and its
applications.
Vol. 2, 2nd ed.
New York:
Wiley.
Foss, S. &
Zachary, S.
(2003).
The maximum on a random time interval of a random walk with
long-tailed increments and negative drift.
Annals of Applied Probability
13(1):
37–53.Google Scholar
Grandell, J.
(1976).
Doubly stochastic Poisson processes, Lecture Notes in Mathematics Vol. 529,
Berlin:
Springer-Verlag.CrossRef
Kaas, R. &
Tang, Q.
(2003).
Note on the tail behavior of random walk maxima with heavy tails
and negative drift.
North American Actuarial Journal
7(3):
57–61.Google Scholar
Klüppelberg, C.
(1988).
Subexponential distributions and integrated tails.
Journal of Applied Probability
25(1):
132–141.Google Scholar
Klüppelberg, C. &
Mikosch, T.
(1997).
Large deviations of heavy-tailed random sums with applications in
insurance and finance.
Journal of Applied Probability
34(2):
293–308.Google Scholar
Korolev, V.Y.
(1999).
On the convergence of distributions of generalized Cox processes to
stable laws.
Theory of Probability and Its Applications
43(4):
644–650.Google Scholar
Korolev, V.Y.
(2001).
Asymptotic properties of the extrema of generalized Cox processes
and their application to some problems in financial mathematics.
Theory of Probability and Its Applications
45(1):
136–147.Google Scholar
Korshunov, D.A.
(1997).
On distribution tail of the maximum of a random walk.
Stochastic Processes and Their Applications
72(1):
97–103.Google Scholar
Korshunov, D.A.
(2002).
Large-deviation probabilities for maxima of sums of independent
random variables with negative mean and subexponential
distribution.
Theory of Probability and Its Applications
46(2):
355–366.Google Scholar
Mikosch, T. &
Nagaev, A.V.
(1998).
Large deviations of heavy-tailed sums with applications in
insurance.
Extremes
1(1):
81–110.Google Scholar
Ng, K.W.,
Tang, Q.H.,
Yan, J.A., &
Yang, H.
(2003).
Precise large deviations for the prospective-loss process.
Journal of Applied Probability
40(2):
391–400.Google Scholar
Rolski, T.,
Schmidli, H.,
Schmidt, V., &
Teugels, J.
(1999).
Stochastic processes for insurance and finance.
Chichester:
Wiley.
Tang, Q.,
Su, C.,
Jiang, T., &
Zhang, J.S.
(2001).
Large deviations for heavy-tailed random sums in compound renewal
model.
Statistics and Probability Letters
52(1):
91–100.Google Scholar
Veraverbeke, N.
(1977).
Asymptotic behaviour of Wiener–Hopf factors of a random walk.
Stochastic Processes and Their Applications
5(1):
27–37.Google Scholar
 You have
Access
- 20
- Cited by