Do interstate obligations affect state behavior? Scholars have established numerous channels through which international institutions may have effects. Agreements solve collective action problems, create reputation costs of noncompliance, or provide focal points for domestic interest group mobilization.Footnote 1 An institution's existence may alter state incentives, strategies, or preferences over time, or commit a country to lock in future reforms or continue existing, desirable behaviors.Footnote 2 Institutions may, alternatively, codify existing preferences, norms, or power dynamics that would be expressed with or without the institution's existence.Footnote 3 A central premise that underlies much of this work is the assumption that agreements are credible—that state commitments matter and, in the short run, states will largely abide by their international obligations, albeit imperfectly and for various reasons. Distributional effects reflect underlying state power and determine whether an agreement can be reached and the shape of agreement.Footnote 4 State membership is a basic criterion for an organization to be considered an “international institution,”Footnote 5 and obligations are typically among state members, such as the World Trade Organization (WTO) or the International Monetary Fund (IMF).
Distinct from state obligations toward other states, regular meetings and cooperative agreements among state regulatory bodies are an increasingly common form of global governance. Regulatory network organizations—regularized, international collaboration of national regulators—have emerged as the primary fora for international cooperation within important issue areas such as international financial regulation.Footnote 6 Prominent financial regulatory networks include the Basel Committee on Banking Supervision (BCBS)—whose members include forty-five central banks and bank supervisors representing twenty-six countries, Hong Kong, and the European Union (EU)—and the International Organization of Securities Commissions (IOSCO)—whose members include 123 securities regulators representing more than 110 states.Footnote 7 Because international financial regulatory cooperation occurs among regulators, not states, resulting agreements are nonbinding within international law. Although members agree to implement regulatory network outcomes—such as best practices and standards—within their home countries, regulatory networks often have weak monitoring and no institutional enforcement provisions. Should scholars treat regulatory network organizations and their agreements in similar ways as formal, interstate, legally binding obligations? This article inductively concludes that credible global governance arrangements can and do occur outside of binding, international legal commitments.
Examination of an archetypal financial regulatory network agreement that increases regulatory stringency compared with the status quo, the BCBS's 2010 Basel III agreement on minimum bank capital regulations, pushes forward two open debates about the nature of regulatory networks. First, do investors view regulatory network agreements as credible? That is, at the time of international agreement, do investors believe that these commitments can and will be implemented at the national level? Some international legal scholars argue that regulatory network commitments are credible, functional equivalents to binding state commitments and facilitate international cooperation for which binding agreements might be blocked by domestic politics.Footnote 8 Other scholars argue that regulatory networks have weak formal characteristics—nonbinding international legal standing and weak monitoring—such that members and their home states face high barriers to implement resulting cooperative agreements.Footnote 9 Second, does increased regulatory stringency help or hurt regulated firms? Scholars alternatively argue that the 1988 precedent agreement, Basel I, created either global public goods (that is, greater financial stability associated with higher regulations) at the expense of regulated banks or private goods to US-regulated banks at the expense of foreign-regulated banks (because non-US banks incurred higher adjustment costs to comply than did US-regulated banks).Footnote 10 This article adjudicates among the competing claims of each debate.
To measure credibility and distributional effects, an event study research design isolates stock price movements of regulated firms attributable to Basel III. Regulated firms’ stock returns reflect equity investors’ aggregate perceptions of the impact of Basel III on regulated firm profitability and are thus a good measure of the perceived impact of an international regulatory network agreement. Between September 2009 and December 2010, the BCBS negotiated Basel III during five closed meetings. Following each meeting, the BCBS made a public press release that summarized negotiated outcomes and provided new, public information upon which investors might trade. Each day's press release is an event of interest. On each announcement day, for each US-regulated firm (large, US-headquartered banks), the difference between the firm's expected and observed stock return—the abnormal stock return—can be attributed to Basel III press release information.
The main quantity of interest is the average abnormal stock return, or Average Announcement Effect, across US-regulated firms on each event day. If the Average Announcement Effect substantially differs from 0, this is evidence that the international agreement is seen to be credible—that is, investors believe the agreement will be implemented at the national level and affect regulated firms. The direction of any deviation informs distributional effects; observed stock returns lower than expected indicate a perception that regulated firms’ profitability would be hurt, while greater-than-expected stock returns indicate a boost in perceived profitability attributable to the new information. To further inform distributional effects, I compare the magnitude and direction of US-regulated firm returns with two sets of foreign-headquartered banks that will also have to comply with Basel III.
A crucial modeling decision is how to arrive at each firm's expected stock return on the day of each event—that is, the stock return that is expected in the absence of an announcement. As unobserved counterfactuals, these values must be estimated from observed data. I use a variable selection method, a Lasso estimator, to select specific, unaffected firms to estimate a convincing counterfactual. For each regulated firm for each event, the Lasso estimator considers the full set of (nonfinancial) firms that should be unaffected by the Basel III announcements and the stock returns of the regulated firm in the immediate period prior to each press release. The Lasso estimator identifies a small subset among 2,884 unaffected firms and beta estimates such that the fitted value of these nonfinancial firm returns best approximates the regulated firm prior to the announcement. Then, on an announcement day, the selected nonfinancial firms’ observed stock returns are used to estimate the counterfactual—the regulated firm's expected stock return—for each regulated firm for each announcement. The Lasso variable selection method that identifies a set of specific, unaffected firms improves upon estimates from a traditional event study approach that uses an aggregate market index (such as the S&P 500) as a single regressor that yields correlated, predicted returns for all regulated firms for a given announcement.
Stock return patterns provide evidence that US stock market investors viewed Basel III to be credible. On each announcement day, regulated firms’ stock returns systematically differed from expectations. Although the direction of effects is not uniform across events, the initial reaction and net effect across all five events are negative, providing evidence consistent with the interpretation that regulations hurt regulated firms. Early events (the two 2009 announcements) are associated with US bank stock returns that are systematically lower than expected by an average of 1.43 percent and 0.41 percent, respectively, representing more than $9 billion and $2 billion in foregone equity value. On these days, investors either sold regulated bank stocks or did not buy as readily as expected. Foreign-regulated banks experienced similar declines as US-regulated firms—additional evidence that US banks did not benefit relative to foreign competitors.
The article contributes to existing literature in three ways. First, the theoretical framework places regulatory networks within existing typologies of international cooperation. Regulatory networks are most distinct from formal international institutions because members are not states, such that commitments are all nonbinding within international law. Second, the empirical results establish the importance of regulatory networks as international cooperation. Basel III, an important regulatory network agreement, was perceived by investors to be credible upon agreement at the international level and prior to domestic implementation. Finally, the article illustrates how, when conditions enable event study analysis, this method can precisely measure policy impact and is especially helpful to analyze policies with ambiguous a priori distributional effects.Footnote 11
Regulatory Networks as International Organizations
A type of transgovernmentalism, regulatory networks—regular meetings among state agencies that perform similar tasks—have become a common form of international financial regulatory cooperation.Footnote 12 The defining feature of regulatory networks is that members are substate actors rather than states, from which it directly follows that these organizations do not bind states within international law. Thus, these agreements are considered to be soft law or informal arrangements and distinct from hard law.Footnote 13
Two sets of scholarly debates surround the credibility and distributional effects of financial regulatory networks. One debate lies in whether or not regulatory networks should be viewed as effective, credible forms of international institutional governance. That is, do investors view international financial regulatory network agreements, at the time of agreement, as likely to be implemented into national regulations? A second debate lies in the nature of regulatory agreements’ underlying distributional effects. Increased national regulatory stringency could plausibly help or hurt regulated firms, a general insight for which it is empirically difficult to arrive at an answer.
Regulatory Network Credibility
International legal scholars, sensitive to the legal status of organizational outputs, debate about financial regulatory networks’ degrees of credibility. An affirmative functionalist perspective views the rise and proliferation of regulatory networks as evidence that demand exists for such governance structures. Slaughter argues that transgovernmental networks are flexible, efficient, and accountable; the nonbinding legal nature of agreements that arise among these groups facilitates governments’ willingness to delegate to international bodies.Footnote 14 She argues that, as globalization increases, negative cross-border externalities increase potential gains from international coordination, and yet states’ desires to delegate formal authority to international organizations decreases.Footnote 15 Thus, informal agreements enable de facto cooperation, resulting in net welfare gains. Within international institutions scholarship, scholars identify how publicly stated commitments among countries—whether formal or informal—may increase reputation costs of noncompliance and affect state behavior.Footnote 16
Other scholars alternatively conclude that regulatory network agreements will have limited effects because of these agreements’ formal institutional design characteristics—specifically, that such agreements lack international legal standing and contain weak enforcement mechanisms.Footnote 17 Theoretically, states will have incentives to defect from cooperative arrangements within issue areas marked by high distributional effects and without monitoring and enforcement.Footnote 18 Cheating may be rampant or agreement may be shallow.Footnote 19 Alternatively, the agreement might allow for mock compliance, whereby a country commits to compliance in name, but implements the agreement, in practice, to cater to vested interests within regulated industries.Footnote 20 In all conceptions, international agreement may not imply meaningful policies and outcomes. The nonbinding legal nature of regulatory network agreements render the agreement incredible at the international level.
This article's focus on regulatory network credibility at the time of international agreement complements existing studies of domestic implementation of regulatory network agreements. Bach and Newman establish that international institutional membership in IOSCO, distinct from bilateral US ties, is associated with faster adoption of insider trading legislation and prosecutions and how the EU embedded international regulatory agreements into EU law, leading to the hardening of soft law.Footnote 21 These studies importantly establish that regulatory network outputs diffuse to the domestic level, while this article establishes that regulatory networks may have real effects prior to domestic implementation.
Regulatory Network Distributional Effects
A second scholarly debate concerns the distributional effects of financial regulatory network agreements. What motivates increased regulatory stringency cooperation through financial regulatory networks? Scholars interpret the 1988 Basel I agreement among BCBS members to coordinate bank capital minimums as, alternatively, the provision of global public goods and as private goods for US-regulated banks.Footnote 22 Each perspective assumes the agreement will be credibly implemented within BCBS member countries but holds a different expectation about the direction of the agreement's distributional effects for regulated firms.
One argument is that an agreement that increases regulatory stringency marks the provision of global public goods. This public goods perspective is that international agreements increase financial stability and, simultaneously, maintain competitive advantage across countries.Footnote 23 Regulators desire both financial stability and domestic bank competitiveness, yet when a regulator unilaterally decides on a level of national regulatory stringency, he faces a tradeoff between these two objectives, known as the “regulator's dilemma.”Footnote 24 Higher (lower) regulatory stringency increases (decreases) financial stability, but hinders (helps) competitiveness of regulated firms. However, simultaneous, coordinated regulatory increases across different countries alleviate each individual country's regulator's dilemma. Financial stability increases while competitiveness is maintained. The increase in financial stability is a global public good. Private, regulated firms may incur adjustment and ongoing compliance costs associated with increased regulatory stringency and greater financial stability.
A contrasting, private goods perspective is that higher regulatory stringency increases the competitiveness of firms in states that already maintain high regulatory stringency.Footnote 25 International agreements require member countries with low regulatory stringency to increase minimum regulatory levels, while member countries with higher regulatory stringency at the time of the agreement face lower adjustment costs to comply. In this way, banks in states with high regulatory stringency just prior to the agreement will enjoy private, competitive gains compared with banks in states with relatively low stringency. For example, prior to Basel I, Japanese regulators required Japanese banks to maintain extremely low capital minimums, while US regulators, following the Latin American debt crisis, required US banks to increase minimum capital levels.Footnote 26 To implement Basel I would require both US and Japanese firms to maintain higher minimums than the status quo, but US banks faced lower adjustment costs and were thought to benefit vis-à-vis Japanese competitors.Footnote 27
These perspectives anticipate opposite distributional effects, with US banks hurt if the public goods perspective prevails and helped (in an absolute or relative way) if private goods dominate. In sum, the direction of any effect will help adjudicate between these perspectives. Analysis of Basel III, an international regulatory network agreement that increased bank regulatory stringency in the aftermath of the 2008 global financial crisis, offers a unique opportunity to empirically adjudicate among equally plausible theoretical possibilities.
Basel III
Basel III, an archetypal regulatory network agreement that unambiguously increased the stringency of bank regulatory capital minimums by narrowing the definition of regulatory capital and increasing required minimum levels of high-quality capital that regulated banks must hold, was negotiated during five meetings between September 2009 and December 2010. The agreement contained public, detailed commitments among regulators such that Basel III is a best-case scenario where a regulatory network agreement may be viewed as credible at the international level. What follows is a brief history of precedent agreements Basel I (agreed on in 1988) and Basel II (agreed on in 2004), and a discussion of Basel III negotiations within the post-2008 financial crisis context. Of particular importance is the unexpected nature of the initial BCBS announcement to negotiate Basel III in September 2009.
The BCBS and Bank Regulatory Capital Agreements, 1973–2007
The BCBS was established in 1973 and rule-based member commitments were first codified in 1988's International Convergence of Capital Measurement and Capital Standards report (also known as the Basel Accord, or, Basel I).Footnote 28 Regulatory capital is a bank's buffer against unexpected losses.Footnote 29 The capital ratio—regulatory capital as a percentage of risk-weighted assets—quantifies a bank's regulatory capital level at any time. Basel I stipulated that internationally active banks should maintain a minimum of 4 percent high-quality (Tier I), and 8 percent total capital as a percentage of risk-weighted assets. BCBS members committed to, and implemented, the terms of Basel I within their home countries within the agreed-on timeline.Footnote 30
During the 1990s and 2000s, Basel I was revised several times, including a significant revision finalized in 2004, the International Convergence of Capital Measurement and Capital Standards: A Revised Framework (commonly called Basel II).Footnote 31 Basel II maintained the 8 percent capital adequacy minimum in name, but allowed each regulated firm to select among three approaches to define asset risk-weights.Footnote 32 Basel I's approach—BCBS-defined asset risk-weight classes—became known as the Standard Approach under Basel II; two additional options allowed banks to use internal firm models to determine asset risk-weights and calculate their firms’ regulatory capital positions at any given time. In practice, large banks used the new options and often held lower levels of capital than would have been required under Basel I or Basel II's Standard Approach.Footnote 33 Basel II was much more technically complex than Basel I. A simple measure to illustrate this is that the Basel II text ran 251 pages compared with Basel I's twenty-six pages of rules framework.Footnote 34 In contrast to Basel I, countries implemented Basel II with variable timeliness. BCBS countries agreed to implement Basel II by 2006 but it was implemented early by the EU (in October 2005, through a Capital Adequacy Directive) and late by the US (November 2007).Footnote 35
Beyond Basel I, II, and III, quarterly BCBS meetings included discussion of a range of ongoing bank regulatory issues. Upon the onset of the 2007 Global Financial Crisis, Basel I and Basel II capital adequacy regulations were the most formal agreement outputs among BCBS members, meaning that these were specific rules that members promised to domestically implement.
The 2008 Global Financial Crisis and Basel III, 2008–2010
The period following the peak of financial institutional failures in September 2008 was one of reform. The direction and content of reform emerged through evolving discussions among academics, practitioners, and policy-makers at both national and international levels.Footnote 36 Beginning in November 2008, rather than meet as a Group of Seven (G7), heads of government began to meet as a Group of Twenty (G20), and French and UK heads of state publicly sought a “new Bretton Woods.”Footnote 37 G20 guidance directed high-level, post-crisis initiatives of the Financial Stability Board (FSB), the IMF, and the BCBS, among others.Footnote 38 Nationally, within the United States, significant domestic financial reform—the Dodd-Frank Act—was proposed in December 2009 and signed into law on 21 July 2010.
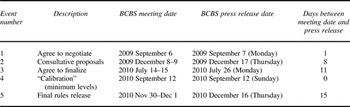
Table 1 outlines the timing of five BCBS meetings that made up the Basel III international agreement negotiations. A BCBS press release followed each meeting—with all meetings conducted within closed sessions—and summarized key outcomes.
Basel III negotiations occurred within five BCBS meetings between September 2009 and December 2010

Notes: Press releases that provided public information about Basel III negotiations were made at various times following each BCBS meeting, ranging from the same day (Event 4) to more than two weeks between meeting and press release (Event 5), increasing likelihood that investors cannot anticipate press release timing.
Source: BCBS press releases, available at <http://www.bis.org/list/press_releases/index.htm>.
The September 2009 press release announced a thorough revision of Basel II, a Basel III, would be negotiated. BCBS members agreed in principle to update capital standards, and offered broad direction of reforms. Minimum capital quantities and quality would increase compared with the status quo and a leverage ratio and liquidity ratio would be introduced.Footnote 39 Basel III would mark a clear increase in regulatory stringency. The Financial Times, London edition, reported on 8 September 2009 that “Regulators have agreed [on] tough rules for banks … that would force many institutions in Europe to raise tens of billions of euros in capital in coming months.”Footnote 40 Although investors expected some form of new regulations, the timing of the announcement and the significant degree of reform came as a surprise.
The December 2009 BCBS meeting press release was accompanied by two Basel III consultative proposals (draft documents) made available for public comment.Footnote 41 The media reported on draft content, “the description of what will count as tier 1 capital and how the leverage ratio will be calculated was stricter than some analysts had expected.”Footnote 42 At the same time, newspaper reports commented that the implementation timeline was longer than expected.Footnote 43
A BCBS press release on 26 July 2010 occurred in the wake of media reports that bankers were trying to weaken Basel III proposals. The Financial Times reported on 28 July that “the principles outlined late on Monday by the Basel Committee on Banking Supervision contained far-reaching concessions [by regulators toward industry preferences for weaker regulations].”Footnote 44 The BCBS press release announced general agreement to move forward with negotiations, and included some intended modifications from the consultative proposals regarding certain specific capital definitions.Footnote 45
Finally, September and December 2010 BCBS press releases, respectively, provided regulatory details of capital minimum levels and confirmed the shape of rules. The 12 September press release, called “Calibration,” revealed required minimum capital levels.Footnote 46 The Wall Street Journal’s front page the next day read, “Banks Get New Restraints—Historic Refashioning of Rules,”Footnote 47 while the front page of the Financial Times explained, “global banking regulators on Sunday sealed a deal to in effect triple the size of the capital reserves that the world's banks must hold against losses.”Footnote 48 Regulatory stringency would unambiguously increase compared with pre-Basel III levels. At the same time, reports indicated regulated banks welcomed both certainty about the regulations and the long, nine-year implementation timeline. The 17 December BCBS press release confirmed regulatory details and the implementation timeline without significant changes from previous proposals.Footnote 49
Thus, Basel III clearly increased minimum levels of required capital compared with Basel I and Basel II.Footnote 50 For a bank to increase its capital ratio it must increase capital (the ratio's numerator) or decrease risk-weighted assets (the ratio's denominator), typically by issuing new stock shares, changing asset mixes, or selling assets. Each option is expensive because new equity issues dilute existing stock shares’ values, and selling assets or substantially changing asset mixes takes time. For this reason, higher minimum required levels of capital are associated with adjustment and ongoing opportunity costs for regulated banks.Footnote 51
Finally, from the start of Basel III negotiations, it was assumed that European and Japanese banks would face higher adjustment costs than US banks would. Media coverage of the initial Basel III announcement in September 2009 immediately identified European banks, especially French and German banks, as being hurt because of these countries’ firms' existing reliance on hybrid securities (combinations of debt and shareholder's equity) that were considered to be regulatory capital under Basel II but not under Basel III's more narrow definition.Footnote 52 Japanese media reported throughout late 2009 and 2010 that Basel III's narrow capital definition would require Japanese banks to raise capital.Footnote 53 In contrast, no reports singled out US banks as those that would incur especially high adjustment costs relative to other countries. Together, if any country's banks would benefit from relative competitive advantage, it would be US banks at the expense of European and Japanese banks. Thus, during the post-2008 worldwide reform period, Basel III was introduced in a surprise manner in September 2009 and marked a clear increase in regulatory stringency.
Empirical Analysis
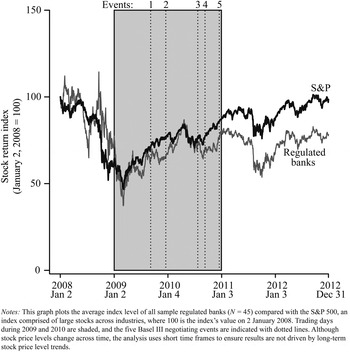
Because international institutions are endogenous to member selection into institutions, and international agreements are endogenous to member negotiations, it is a general challenge to isolate and measure direct effects of international institutions and international agreements.Footnote 54 This challenge is heightened during periods such as post-2008 when multiple regulatory and legal reforms occur in quick succession. Figure 1 shows that US-regulated banks, on average, underperformed the total stock market between 2008 and the end of 2012.Footnote 55 Within an event study research design, this article analyzes firm stock returns at precise times to measure how investors react to new information about Basel III negotiations. Such a focused, localized analysis isolates effects attributable to the regulation of interest (Basel III) while controlling for other reforms that advance during 2009 and 2010.
Regulated bank and stock market indices, 2 January 2008 to 31 December 2012

Basel III provides a unique opportunity to apply a standard event study research design to inform the two debates of interest—the credibility and distributional effects of regulatory networks and their agreements. To calculate the counterfactual within this design, I utilize a variable selection (Lasso) method that improves on in-sample and out-of-sample fit compared with standard event study estimators. I analyze US-headquartered, regulated firms as well as two sets of foreign-headquartered, regulated firms. Results provide evidence that investors do perceive regulations to be credible, more consistent with the functionalist perspective regarding regulatory network credibility and less consistent with institutional design perspectives. The Basel III agreement was globally perceived to hurt regulated firm profits rather than to benefit US firms at the expense of foreign competitors. This is more consistent with a global public goods perspective and less consistent with a private goods perspective.
Event Study Methodology and Basel III
Event studies analyze effects attributable to new information. For this study, five information events are the five BCBS press releases that report on the shape and cadence of Basel III negotiations. Stock returns of banks that will have to comply with the regulation—that is, regulated firms—measure effects of the press release information.
Press releases as new information
BCBS press releases are surprises in both release dates and content. Table 1 shows that BCBS press release timing ranges from being announced on the same day as the BCBS meeting (for example, Event 4) to being announced more than two weeks after the meeting (for example, Event 5). Between any two events, newspaper coverage provides no indication that the BCBS provided interim or informal information about the negotiation's progress.
The BCBS is an extremely opaque negotiating body and indications suggest that BCBS press release content is unknown to the public or to private interests prior to formal announcements.Footnote 56 Meeting minutes are never publicly released, and the organization maintains closed archives.Footnote 57 Although the public may know BCBS meeting dates, newspaper coverage never reports meeting outcomes prior to press releases, increasing confidence that press releases reflect new public information.Footnote 58 Interview evidence suggests that, during 2009 and 2010, the BCBS maintained especially formal and distant relations with private interests.Footnote 59
Finally, BCBS meeting outcomes cannot be known with certainty prior to each meeting because BCBS members actively negotiate within meetings. In a rare description of BCBS meeting proceedings, Sheila Bair, the chairwoman of the US Federal Deposit Insurance Corporation (FDIC) during the Basel III negotiation period, documents a fragmented US negotiating position just days prior to certain BCBS meetings about Basel III.Footnote 60 If the US position was unclear prior to meetings, it is reasonable that the collective outcome of a negotiation involving forty-five agencies was also unforeseeable. No negotiation updates occur between BCBS meetings. Overall, BCBS press releases about Basel III negotiations represent new public information upon which investors may trade.
Stock returns as outcome variable
Stock prices adjust to public news almost immediately, and this analysis uses stock returns to proxy for investors’ perceptions about an international agreement's credibility and distributional effects. Considering only the immediate period following each announcement isolates reaction to the expected effects of the international agreement. Stock returns offer a costly, observable measure of investors’ changing perceptions of a firm's value within investors’ portfolios.Footnote 61 New information that changes investor perception of a stock's value will cause investors to act, with the change reflected in the stock price and occurring on the day that new information is available. Firms regulated by the agreement are those that should be affected by investor actions.
Stock returns are a commonly used outcome variable and appropriate for this study. Stock returns, the percentage change in each stock's price today compared with yesterday, provide normalized measures of stock price changes across firms. For example, on the first trading day of 2009, Wells Fargo's 1.76 percent stock return reflected a $0.56 per share stock price increase ($29.48 to $30.00). This stock return is approximately equal to Bank of America's 1.78 percent stock return, reflecting a $0.25 per share increase ($14.08 to $14.33). The analysis uses stock returns that account for dividends and stock splits.Footnote 62
The trading day on which an event occurs is the day when any estimated effect is most attributable to investors’ reactions to Basel III news.Footnote 63 For the two BCBS press releases that occur on nontrading days (for example, Event 1 on US's Labor Day holiday and Event 4 on a Sunday), adjustment is expected on the first trading day following the press release.Footnote 64
US-regulated firms
If credible, Basel III should affect firms that will have to comply with its content. Regulated firms are identifiable and cannot opt into or out of being regulated.Footnote 65 Large US banks, which had to comply with Basel I and Basel II, were certain to be regulated by Basel III. For this reason, main results include the largest available sample of publicly traded, US-headquartered banks with more than $10 billion in consolidated assets in 2009.Footnote 66 This leaves a sample of forty-five firms, detailed in online appendix Table A. Nonfinancial firms are those that should not be directly affected by Basel III and will be used as the set of potential control firms; 2,884 nonfinancial firms publicly traded on US stock exchanges have full stock return data to include in this group.Footnote 67 For each event, for each regulated firm of interest, a subset of nonfinancial firms will be used to create a counterfactual stock return on the event day.
Hypotheses
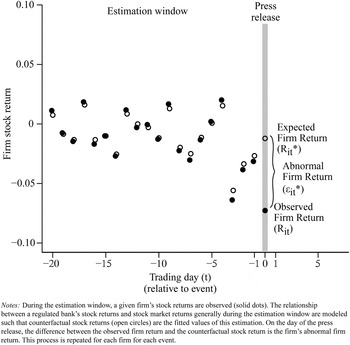
Illustrated in Figure 2, for each firm for each event, I measure the difference between each regulated firm's observed stock return compared with its counterfactual stock return. The difference is the estimated effect of the announcement for the firm, called the Abnormal Firm Return. The average effect across all firms on an event day is the average effect of the press release (Average Announcement Effect).Footnote 68 Average Announcement Effect is estimated for each of the five BCBS press release announcements between September 2009 and December 2010, and each firm's cumulative abnormal return across the five events is averaged to arrive at a net effect.
Calculating firm abnormal return, illustrative example

Associated with the credibility debate is the following question: Do investors perceive that international agreement implies domestic implementation and firm effects? If the Basel III agreement is viewed to be credible and to have significant effects, consistent with the functionalist perspective, despite its nonbinding nature, investors should react to negotiation news.
H1a
Credibility, functionalist perspective: Days of BCBS press releases will be associated with Average Announcement Effects that differ from 0.
Alternatively, consistent with the institutional design perspective, if the Basel III agreement is not viewed as credible—either because the agreement is shallow or because it is unlikely that regulatory network members will implement the agreement domestically—then new information about Basel III negotiations should not lead investors to buy or sell regulated firm stocks and we will not observe abnormal returns.
H1b
Credibility, institutional design perspective: Days of BCBS press releases will be associated with Average Announcement Effects that do not statistically differ from 0.
Scholars debate the nature of distributional effects associated with increased regulatory stringency: should US-regulated firms—that may incur lower adjustment costs than foreign-headquartered rivals—be hurt by regulations, consistent with a global public goods approach, or be helped by regulations, consistent with a private goods approach? If abnormal returns are negative, investors perceive US-regulated firms to be hurt by the regulations, consistent with the public goods argument.
H2a
Global public goods distributional effects: Days of BCBS press releases will be associated with Average Announcement Effects less than 0.
In contrast, positive abnormal returns imply that US-regulated firms are helped by regulations in an absolute way, consistent with a private goods argument. If US-regulated firms have negative abnormal returns but benefit in a relative manner to foreign rivals, this might be consistent with a private goods argument in a relative manner. I consider both possibilities.
H2b(i)
Private goods absolute distributional effects: Days of BCBS press releases will be associated with Average Announcement Effects greater than 0.
H2b(ii)
Private goods relative distributional effects: Days of BCBS press releases will be associated with Average Announcement Effects significantly higher than foreign rivals.
To evaluate H2b(ii), I compare abnormal returns of US-regulated firms with two sets of foreign-headquartered, regulated firms.
Interpretation
To interpret empirical findings, I focus on results from Event 1, and the net effect across all five events. Although Basel III marks an increase in regulatory stringency, each of the five press releases provides new information that supplements existing information and accumulated investor expectations. For example, investor reactions to new information contained in the Event 2 press release is the marginal reaction to Event 2's information compared with expectations set by Event 1. Similarly, Event 3 stock return movement measures the marginal effect of new information compared with expectations set from Event 1 and Event 2 information, and so on.
Knowing that Basel III increased stringency compared with the status quo leads to reasonably clear interpretations of abnormal returns associated with the initial announcement of Basel III negotiations (Event 1, the September 2009 press release) and the net effect across all five events. Ideally, it would be possible to determine investors’ expectations of the stringency of Basel III at a moment just prior to a press release, and to compare that with the actual stringency update contained within the press release. In this way, those press releases that are most different from investors’ expectations would be where one should see the greatest effect. However, a measure of Basel III investor expectations does not exist.Footnote 69 Although second-best, that Basel III increased regulatory stringency, and that the initial announcement was a surprise, allows us to focus on Event 1. Further, the net effect across all five press releases informs how the effect accumulates across press release days. Media reports supplement our understanding and inform the plausibility of results across events.
Counterfactual Estimation and Model
All estimations follow from the set-up illustrated in Figure 2. On an event day, each regulated firm's stock return is observed and compared with its unobserved, expected stock return on that day. To calculate the expected return, event studies analyze the typical pattern between the regulated firm's stock returns and some other, unaffected asset just prior to the event. On the event day, the unaffected asset's price is observed and the fitted value—using the pre-event relationship between the regulated firm and the unaffected firm—is the expected return.
Formally, the following estimation is conducted for each of the five events listed in Table 1. Let i represent each regulated bank (i = 1, 2, …, 45) and t be a trading day relative to the event (t = –∞, …, –1, 0, 1, …,∞), with the event occurring on day t = 0. Each regulated bank's stock return is observed on each trading day and denoted R it . Thus, the event day and relative trading days’ counts are common to all firms, but returns are distinct.
For each regulated bank, I observe the end-of-day stock return on the event day (R
i0), and decompose this return into expected firm return (
 $R_{i0}^* $
) and an error term (
 $\varepsilon _{i0}^* $
), which is the abnormal firm return, to obtain the following:
 $$\underbrace {R_{i0}} _{{\rm Observed}\,\,{\rm Firm}\,\,{\rm Return}} = \underbrace {R_{i0}^*} _{{\rm Expected}\,\,{\rm Firm}\,\,{\rm Return}} + \underbrace {\varepsilon _{i0}^*} _{{\rm Abnormal \ Firm}\,\,{\rm Return}}\comma$$
where Expected Firm Return is the estimated stock return for the regulated firm in the absence of an announcement. Abnormal Firm Return is the difference between Observed Firm Return and Expected Firm Return and is visually illustrated for one firm for one event in the gray panel in Figure 2. The calculation is repeated for each regulated firm for each event. The overall quantity of interest for each event is the average Abnormal Firm Return across all regulated firms on event day, and denoted the Average Announcement Effect (P).
 $$\underbrace P_{{\rm Average \ Announcement \ Effcet}} = \underbrace {\displaystyle{1 \over N}\sum\limits_{i = 1}^N {\varepsilon _{i0}^*}} _{{\rm Average \ Abnormal \ Firm \ Return}} $$
Specific to this analysis, there are forty-five US-headquartered, regulated firms that trade on major US stock exchanges (N = 45).
Calculation of the unobserved, counterfactual Expected Firm Return on an event day is a crucial part of analysis. Event studies regress a regulated firm's stock returns on unaffected firms’ stock returns for the period prior to the event such that, in the absence of an event, this correlation should provide a reasonable measure of the expected stock return of the regulated firm. Within this standard, conceptual design, I use a variable selection method, a Lasso estimator, to identify specific firms that together create a custom market index for each firm for each event. Although the Lasso regression differs from the traditional approach that uses an aggregate stock market index, both the Lasso regression and the traditional approach use data prior to the event to identify a relationship between each regulated firm and a measure of the stock market. Both approaches assume that data observed prior to the (unanticipated) event capture the relationship between an individual stock and the stock market generally, and that, on the event day, the relationship observed prior to the event can be used to calculate a counterfactual stock return for the regulated firm.
To calculate Expected Firm Return, an estimation window is defined as the period of trading days prior to the event that captures a general relationship between a regulated bank and unregulated, nonfinancial stocks. Formally, the estimation window [a, b] is the set of trading days a < b < 0 prior to the event (t = 0). The estimation window is of length l = b – a + 1. For instance, the main event window specification ([–20, –1]) uses a twenty-day estimation window (l = 20) that includes the twenty trading days immediately prior to the event.
Traditional approach: Stock market index
Traditional event studies often model each regulated firm's stock returns over the estimation window as a function of one stock market index, such as the S&P 500 (the weighted-average stock returns of 500 large companies) or an equally weighted index (the simple average of all publicly traded firm stock returns).Footnote 70 The traditional approach applies a simple linear regression to the estimation window data. The dependent variable is the regulated firm's stock return each day during the estimation window, and the explanatory variable is the stock market index return each day. Formally, define M t as the stock market index return on a given trading day. For each regulated firm, for the set of all trading days within the estimation window, a ≤ t ≤ b, the following model is fit: R it = α i + β i Mt + ε i. The stock market index provides a single, daily measure of performance to fit all regulated firms. Because the daily index reflects an average over many firms’ stock returns, it poorly fits different regulated banks’ individual stock returns (R it ). Further, each stock market index may include some regulated firms themselves within the aggregate index measure, resulting in inconsistencies. Regulated firms of interest include large firms, such as Bank of America (Forbes’ 11th largest firm in 2009), Citigroup (12th largest), JPMorgan Chase (16th largest), and Wells Fargo (41st largest).Footnote 71 Because regulated firm stocks are likely to affect general stock market indices (which are supposed to act as a control group), this is a serious concern for this analysis.
Variable selection model: Custom firm index via Lasso estimator
I use a variable selection model, called a Lasso estimator, to identify a subset of nonfinancial firms for each event whose weighted-average stock returns over the estimation window are most similar to each regulated firm of interest. Using patterns in the estimation window data, the Lasso estimator selects a subset of nonfinancial firms that create a custom market index for each regulated firm. This approach better fits estimation window data, creating precise estimations and the ability to test for model sensitivity across estimation windows.
The variable selection method utilizes individual stock returns of unregulated firms over an estimation window. Nonfinancial firms should not be affected by the Basel III regulations and thus the set of all nonfinancial firms compose the control group. Formally, let j denote a publicly traded, nonfinancial firm (j = 1, 2, …, 2,884), where j ≠ i. The observed stock return of each nonfinancial firm on trading day t is denoted R jt .
This model also uses a simple regression, but one with a Lasso constraint and with individual firm returns as possible regressors. The dependent variable is the regulated firm's stock return each day during the estimation window (R
jt
), and N
j
explanatory variables are the stock returns of each unregulated firm. Because there are many more possible regressors (N
j
= 2,884) than observations during the event window, the Lasso estimator imposes a constraint such that most weights are constrained to 0; only regressors that best approximate the regulated firm's returns over the estimation window have nonzero weights. Formally, the estimation window data are fit by the following model:
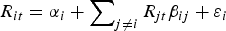 $R_{it} = \alpha _i + \sum\nolimits_{j \ne i} {R_{jt}} \beta _{ij} + \varepsilon _i $
subject to the constraint
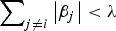 $\sum\nolimits_{j \ne i} {\left\vert {\beta _j} \right\vert} \lt \lambda $
.Footnote
72
Thus, the series of
 $\widehat{{\beta _{ij}}} $
over the set of j control firms is the weight given to each nonfinancial control firm j to fit regulated bank i’s stock returns over the estimation window. Most
 $\widehat{{\beta _{ij}}} $
equal 0.Footnote
73
Thus, only a few nonfinancial firms emerge as regressors for each regulated firm and they are specifically selected based on the regulated bank's own stock returns over the estimation window. When estimation windows change, selected regressors change accordingly. Table B in the online appendix shows variation for the largest US banks (for example, Wells Fargo, JPMorgan Chase, Bank of America, and Citigroup), illustrating that even the most similar banks have largely different regressors across firms and events.
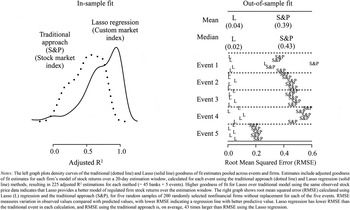
Figure 3 shows that the Lasso estimation method has significantly higher goodness of fit and better predictive power than the traditional stock market index approach, indicating that Lasso provides more precise counterfactuals than the traditional approach. The left graph of Figure 3 plots density of goodness of fit (that is, adjusted R 2) under each estimation strategy for a twenty-day estimation window.Footnote 74 The interquartile range of the full set of adjusted R 2 values using the Lasso estimator is between 0.58 (first quartile adjusted R 2) and 0.95 (third quartile adjusted R 2). This range is smaller, and has a higher fit, than the full set of adjusted R 2 using the traditional approach (which is between 0.29 [first quartile] and 0.67 [third quartile]). The Lasso regression fits observed data during the estimation window better than the traditional approach does. The right graph of Figure 3 shows that the better goodness of fit of sample data translates into better predictive values outside of the estimation window. I calculate the root mean square error (RMSE) for random samples of nonfinancial firms using both the Lasso method and the traditional approach. RMSE measures variation in observed values compared with predicted values, with lower RMSE indicating a regression line with better predictive value. Lasso regression has lower RMSE than the traditional event in each calculation, and RMSE using the traditional approach is, on average, forty-three times larger than RMSE using the Lasso regression.Footnote 75 High goodness of fit and better predictive power using the Lasso estimator lowers estimation noise and leads to higher confidence in estimates than under the traditional method.
Comparing in-sample (historic) and out-of-sample (predictive) fit across estimation methods

To estimate uncertainty around Average Announcement Effect, I compute 95 percent confidence intervals by following a modified bootstrap method specific to the Lasso estimator.Footnote 76
Estimation Specifications
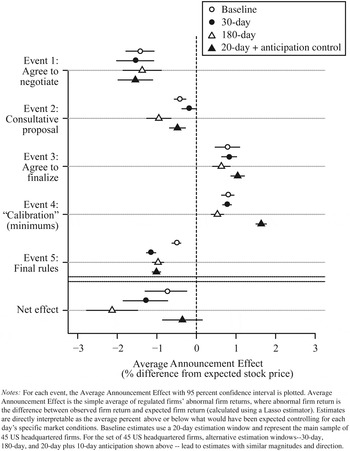
The base specification uses an estimation window made up of the twenty trading days just prior to each event ([–20, –1]). The results from these models indicate whether stock returns on an event day differ from stock return patterns just prior to press releases. Three additional estimation window specifications—a thirty-day estimation window immediately prior to each event ([–30, –1]), a long, 180-day estimation window ([–180, –1]), and a final, additional specification uses a twenty-day estimation window but controls for the possibility of anticipation effects by ending the estimation window ten trading days prior to each press release ([–30, –11])—ensure that results do not change across different estimation window lengths.Footnote 77
Given a relatively small baseline sample of forty-five firms, two tests ensure that the Average Announcement Effect's signs and statistical significance are not driven by outliers. First, a jackknife procedure drops each firm individually and recalculates Average Announcement Effect and the 95 percent confidence interval to ensure results are not driven by any one firm.Footnote 78 Second, after estimating Abnormal Firm Returns for all regulated firms for an event, I regress Abnormal Firm Returns on Observed Firm Return and use Cook's Distance to identify any influential points. The set of regulated firms whose returns are identified as influential points are simultaneously dropped and the Average Announcement Effect is recalculated with remaining firms. Results are not sensitive to either test.
To inform the distributional effects of the agreement, I compare US-regulated firm returns with two sets of foreign banks—Japanese-regulated banks that trade on the Tokyo Stock Exchange (n = 88) and foreign-headquartered banks that trade on major US stock exchanges (n = 12).Footnote 79 As discussed earlier, Japanese- and European-headquartered banks expected to face the highest adjustment costs to comply with Basel III. To compare US-headquartered, regulated firm results with foreign-headquartered competitors provides greater insight into the distributional effects of regulations.
Finally, to establish the validity of the method as a whole, I run a placebo test randomly selecting samples of unregulated firms and estimating Average Announcement Effect for these firms that should not be affected by Basel III regulations. Among nonfinancial firms, I expect Average Announcement Effect to be statistically indistinguishable from 0.Footnote 80 Specifically, of the 2,884 nonfinancial firms, I take 100 random samples of 200 nonfinancial firms without replacement and treat each as if it were a regulated bank. I estimate the Average Announcement Effect using a twenty-day estimation window.
Results
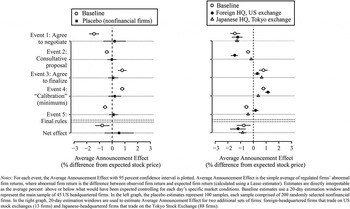
Figure 4 displays Average Announcement Effects for each of the five events of interest, and the net effect across those five events. The left graph of Figure 4 plots the base specification (shown with white circles)—US-headquartered firms using a twenty-day estimation window immediately prior to each event—and the placebo test results (shown with black squares). The twenty-day estimation window results indicate stock returns statistically differ from 0, evidence in support of H1a that investors systematically traded these stocks on announcement days. The largest estimated effect is Event 1, where observed stock returns were lower than expected stock returns by 1.43 percent on average (that is, an Average Announcement Effect of –1.43 percent). This is the equivalent of $783 million foregone equity for Citigroup shareholders and $2.1 billion foregone equity for Bank of America shareholders.Footnote 81 Event 2 (consultative paper release) and Event 5 (final rules release) also resulted in negative and statistically significant stock returns, but with smaller magnitudes (Average Announcement Effects of –0.41 percent and –0.51 percent, respectively). Event 3 and Event 4 are associated with firm stock returns greater than expected by 0.78 percent and 0.79 percent, respectively. Results imply that stock returns do deviate on days of press releases. Each event's effect measures the marginal change in expectations from just prior to the announcement to just after the press release. It is thus appropriate that reaction to the initial announcement is largest, and that the direction and magnitude of estimated effects of Events 2 through 5 plausibly reflect the qualitative media reports discussed earlier. While the direction of deviations vary, the net effect is negative and statistically significant, averaging –0.77 percent.
Average Announcement Effect on event days, base specification and placebo (left) and base specification and foreign-headquartered firms (right)

Placebo point estimates and 95 percent confidence intervals—represented by black squares in the left graph of Figure 4—do not statistically differ from 0. This increases confidence that the method is measuring a bank-specific effect rather than a general market effect. It establishes that the statistical method is able to produce a null result.
Although the left graph of Figure 4 provides initial evidence that Basel III negotiations hurt regulated firms, to more fully consider Basel III's distributional effects (to evaluate H2b(i) and H2b(ii)), the right graph of Figure 4 shows estimated effects for the base specification of US-headquartered firms (shown with white circles) compared with two sets of foreign firms—foreign-headquartered banks (from countries with BCBS member agencies) that trade on US stock exchanges (black circles) and Japanese-headquartered banks that trade on the Tokyo Stock Exchange (white triangles). Japan was expected to endure especially high adjustment costs and thus Japanese-regulated firms should be the most affected. Empirically, however, the right graph of Figure 4 displays remarkable similarity, in both direction and magnitude, between US-regulated firms and the two sets of foreign firms. If anything, Japanese-regulated banks seemed to enjoy slightly better outcomes than did US banks in Event 1 and as a net effect across events. Thus, there is little evidence in support of H2b(ii) that US-regulated firm returns are relatively higher than foreign firms’ returns. Overall, there is little support for either absolute or relative private goods perspective, and empirical analysis provides evidence in support of H2(a), that Basel III was perceived to hurt US-regulated firms as it provided global public goods.
As a robustness check, Figure 5 shows that results for US-regulated firm models are consistent when using alternative estimation window lengths—twenty-day base specification (white circles), thirty-day (black circles), 180-day (white triangles) and twenty-day plus a ten-day anticipation control (black triangles). When using a ten-day anticipation control, the net effect across firms is not statistically significant, though this results from a large positive Average Announcement Effect on Event 4. Event 1 remains negative and statistically significant, consistent with previous findings.
Average Announcement Effect on event days, base specification, and alternative estimation windows

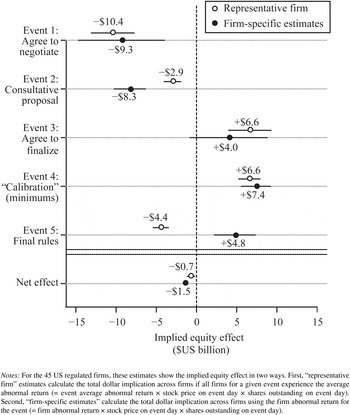
What is the magnitude of these effects? Figure 6 displays the implied total effect on baseline firms' equity values, calculated in two ways—by the average estimated firm effect applied to all firms (representative firm estimates are white circles), and by the firm-specific estimates (firm-specific estimates are black circles). Estimates are the sum total among all forty-five firms. On Event 1—the day that Basel III was announced—regulated firms’ shareholder equity was $9.3 to $10.4 billion lower than was expected in the absence of the announcement. Across all five events, the net effect is smaller, with foregone shareholder value between $700 million and $1.5 billion, on average. Because Basel III was negotiated during a period where new financial regulations were being discussed at national and international levels, this localized measure plausibly isolates the marginal effect of Basel III negotiations, distinct from other reforms.Footnote 82
Implied equity effect on event days

Overall, results provide consistent evidence that investors viewed Basel III to be a credible agreement that imposed costs on regulated firms (evidence in support of H1a and H2a). Returning to the two theoretical debates, there exists empirical evidence in favor of the functionalist perspective of credible regulatory network agreements (H1a) and less evidence to support the institutional design perspective (H1b). Related to distributional effects, there is little evidence that Basel III acted as private goods for US-regulated firms in either a relative or absolute manner (that is, little evidence in support of H2b(i) and H2b(ii)) and there is evidence that US-regulated firms incurred a negative net effect that was as great or larger than foreign-regulated firms, more consistent with Basel III acting as a global public good (H2a). It is striking to find evidence that, following the height of crisis, when investors expected more stringent regulations, investors perceived actual regulations to be even more stringent than expected.
Conclusion
Basel III negotiations provide an opportunity to observe and measure effects of a financial regulatory network output that increases stringency compared with the status quo. Basel III is a most-likely financial regulatory network agreement to result in effects because its content is detailed and public, and because it supplants some of the most legalized existing arrangements (that is, Basel I and Basel II). Despite being a most-likely case, Basel III is simultaneously nonbinding within international law and lacks enforcement mechanisms, such that some scholars doubt that an arrangement such as Basel III should have real effects on national policies and regulated firms. If cooperation in a strong case had yielded no effect, scholars would conclude that these organizations are largely symbolic. Yet, this article establishes that investors did perceive Basel III to be credible at the international agreement's establishment, and to affect firms subject to Basel III in a negative manner. This finding for an important case of cooperation—although it does not imply that all regulatory network outputs have effects or that all outputs will harm regulated firms—points us toward fruitful, future research areas.
First, this article holds direct implications for institutional design literature.Footnote 83 State membership—often a criterion for an organization to be considered an international institution—is not a necessary condition for an international organization's outputs to lead to anticipated national policies and subsequent distributional effects. Depending on a researcher's purpose, excluding informal institutions from the full population of international governance organizations may create biased results.
Second, the specific source of credibility to which investors react remains an open question. For Basel III, three possible sources include historical precedent, hegemonic leadership, and/or technocratic member identity. Historical precedents (Basel I and Basel II) that established an existing “Basel” brand since 1988 may have been necessary for Basel III to be seen as credible; if so, it supports the basic insight that institutions are easier to continue than to create.Footnote 84 Second, the reputation of regulatory agency members, or the fact that they are from leading financial centers—the United States, the United Kingdom, and European Union—may have significantly bolstered credibility.Footnote 85 Finally, that regulatory agencies are (relatively) independent technocrats perhaps led outputs to be credible.Footnote 86 Although it may be a combination of these items that matters for credibility rather than any individual characteristic, distinguishing among them creates a set of possibilities for future inquiry. To unpack these theoretically distinct sources of credibility requires a research design that analyzes across-time or across-output variation of institutional characteristics. An opportunity to do so may arise with the establishment of BRICS-led financial organizations—such as the New Development Bank (NDB) and Asian Infrastructure Investment Bank (AIIB)—because the emerging population of financial governance organizations will display variation on all three dimensions.
Third, cursory comparison of Basel I and Basel III illustrates distinct ways in which international organizations may constrain private, special interests. Both agreements narrowed regulatory differences across jurisdictions and increased regulatory stringency compared with the status quo. It is fairly straightforward that these international agreements may limit regulated special interest leverage over national level regulatory outcomes. Yet, Basel I may be seen as addressing across-country preference heterogeneity and constraining special interests in a few BCBS regulators’ home countries; in contrast, Basel III could be interpreted as BCBS member regulators (with relatively homogeneous preferences for high regulations) using the agreement to tie their hands at the international level in preparation for parallel negotiations between each and every BCBS member and domestic interests. Initial evidence for this is the dissatisfaction of even the largest US banks with Basel III, with Jamie Dimon, the chief executive officer of JPMorgan, calling the agreement “anti-American.”Footnote 87 It is generally important to identify and understand different types of special interest constraint. That financial regulatory networks may act to constrain special interests is an important contrasting perspective to existing literature that emphasizes how international organizations are easily captured by strong financial industry special interests.Footnote 88
Finally, this article illustrates how ambiguous policy effects, even during periods of multiple, simultaneous policy reforms, may be measured through well-defined identification strategies (such as the event study used here, or a regression discontinuity design) and/or through isolating and measuring a third-party, exogenous action (such as, in the context of this paper, stock returns). Opportunities to apply such designs are limited by external factors (such as the availability of new information for event studies or the implementation of a policy for regression discontinuity) to find and analyze even small-N effects acts as a valuable supplement to broader trend analyses (for example, time-series cross-section). This approach will inform questions within policy areas where distributional effects are a priori uncertain (as they are in banking regulation). Again, while limited to certain instances, these are compelling ways to identify policy effects.
This article confirms the significance of an increasingly utilized form of international governance: financial regulatory networks. While this is a small subset of the full population of international governance organizations it is an example of an informal institution with a moderate-and increasing-level of legalization. To prioritize the study of formal organizations dismisses such important subsets of international governance organizations whose policy outputs market actors care about and respond to. Future scholarship should continue to better understand the nature of individual institutions, along with collective political interactions, within this dynamic environment.
Supplementary Material
Supplementary material for this article is available at https://doi.org/10.1017/S0020818316000291.