

No other national jurisdiction endows its corporations with as many of the rights of citizens as the United States.Footnote 1 This cannot be attributed to pro-corporate sentiment on the part of the American public or even of their elected representatives. Rather, throughout American history, it has been the federal courts that, time and again—from Dartmouth College v. Woodward to Citizens United v. Federal Election Commission—have extended constitutional protection to corporations against the efforts of state and national legislatures to reform or restrain them.Footnote 2
On its face, this is quite surprising. A few national constitutions do discuss the rights of corporations—for example, Germany’s Basic Law, in Article 19. However, the US Constitution makes no mention of corporations or corporate rights. Indeed, the framers were so concerned about the possibility of privileged monopolies squeezing out ordinary citizens that they did not endow Congress with the traditional right of Parliament to charter corporations, let alone expressly extend constitutional rights to corporations (Berle 1964, 87).Footnote 3 Nor did the drafters of the Fourteenth Amendment intend to include corporations among the “persons” granted the rights of due process and equal protection of the laws, the protestations of Senator Roscoe Conkling to the contrary notwithstanding.Footnote 4 Absent textual mention of corporate rights, the extension of constitutional rights to corporations rests, doctrinally, on the drawing of a connection between corporations and natural persons of sufficient intimacy to impute to the former the constitutional rights of the latter. This is true not only in the United States but in any national jurisdiction with a constitution that is silent on the question of the rights of corporations. My critique of this practice focuses on the United States because it has been the lead country in extending constitutional rights to corporations. However, the critique applies to all jurisdictions that make no mention of business corporations in their fundamental law, and even applies to the few that do, as an argument against inferring any rights beyond those expressly mentioned.
That corporations are “legal persons,” in the sense of having the right to own property, make contract, and sue and be sued in court as a unitary entity, or “person,” has never been in question. This is what I refer to as the corporation’s “contractual individuality” (or “contractual personhood”), and it has been a defining feature of the corporation from its Roman origins (Williston 1888). But being a contracting individual, with rights under the law of property and contract, is very different from being a “constitutional individual,” with constitutional rights such as those in the Bill of Rights.Footnote 5 For example, a foreign government can, within United States jurisdiction, be a contracting individual, but only in a few legal areas can it claim the protections of a constitutional individual. This is where having a connection with natural persons—or more strongly, with citizens or citizenship—becomes essential.
Only two ways of drawing this connection have ever suggested themselves (Millon Reference Millon1990). First, the corporation can be construed as a mere association of natural persons. The rights of the corporation, it is then claimed, are simply the rights of these persons, which may include constitutional rights. Elaboration of this metaphor produces what I call the “association” theory of the corporation.Footnote 6 Second, the corporation can be construed as itself a kind of natural person. That is, the corporation can be treated, not merely as a contracting individual in the eyes of the law (which no one disputes), but as an independent entity with interests, ends, and knowledge of its own and thus deserving of at least some of the constitutional rights of natural persons. Elaboration of this metaphor produces the “real entity” theory of the corporation. Both of these theories gained currency toward the end of the 19th century, and the Court began extending constitutional rights to corporations shortly thereafter.Footnote 7
In evaluating whether corporations deserve constitutional rights, analysis necessarily turns to the arguments developed by corporate lawyers and professors in support of these theories, rather than to the arguments of the US Supreme Court. This is not just a requirement of charity, in that the former advance the more developed, better-defended claims about the nature of the connection between corporate entities and natural persons. It is because, remarkably, the Court has never offered a sustained argument as to why corporations merit constitutional rights. Santa Clara County v. Southern Pacific Railroad Co. (118 U.S. 394), which serves as the lead case, expressly avoided the constitutional issue—a point emphasized by Chief Justice Waite in his opening remarks, by Justice Harlan in the majority opinion, and by a disappointed Justice Field in a concurring opinion in a companion case.Footnote 8 Nonetheless, two years later, Field began citing Santa Clara as if it had decided the issue (Missouri Pacific Railway Company v. Mackey, 127 U.S. 205, 210 [1888]). He was eventually joined in this practice by Harlan, then by Brewer, until it became institutionalized on the Court as a whole.Footnote 9 In other words, strictly speaking, the question has never been decided but merely presumed decided. To this day, in place of argumentation, the Court either offers a flawed chain of precedent back to Santa Clara, which never addressed the question, or drops loose metaphors of corporations being “persons” or “associations of persons,” which conjure up theories elaborated by others.
Justice Kennedy’s majority opinion in Citizens United (130 S.Ct. at 876, 904, 906–7, 925, 928) is a case in point, using mixed metaphors that conjure up both theories, despite their inconsistency. The “association” theory lurks behind Kennedy’s contention that a corporation is an “association of citizens” and thus deserves the speech rights of its citizen members. The “real entity” theory lurks behind his contention that the corporation deserves to have its “voice” protected because it is not reducible to its members, but has opinions of its own that can add to the marketplace of ideas (906–7). In other words, the majority concludes that corporations deserve free speech rights both because they are, and because they are not, reducible to their members.
The currency of these theories, within business schools, law schools, and on the Court, rests on long-standing and widespread misapprehensions of the nature of the corporate form. This misapprehension of the corporate form is not surprising. Corporations are legally complex. What is more, it is only for a little over a decade that, thanks to some pioneering corporate law scholarship, we have had a full and clear view of their legal attributes and the indispensable role of government in providing these attributes.Footnote 10
In light of this scholarship, it becomes clear that the association theory and real entity theory are mistaken. The arguments that can be drawn from this scholarship return us to the original theory of the corporation, which in its main points was undisputed for centuries, but which has been out of favor since the end of the 19th century. This is the “grant” theory (or “concession” theory), which holds that the corporation receives its existence and its rights in grant from government. In contrast to the association theory, the grant theory maintains that the corporation is an entity distinct from its members (with property, contracts, and liabilities entirely separate from the property, contracts, and liabilities of its members). In contrast to the real entity theory, the grant theory maintains that this distinct entity is “artificial,” not “real.” That is, it is a wholly abstract legal construct, with rights and responsibilities conferred by legal fiat. As classically formulated by John Marshall, in Dartmouth College (17 U.S. at 518), “A corporation is an artificial being, invisible, intangible, and existing only in contemplation of law. Being the mere creature of law, it possesses only those properties which the charter of its creation confers upon it.”
In the grant theory view, corporations may assert contractual rights against government (e.g., suing government for breach of contract), since contractual rights are part of what they are granted by their charters. However, neither states (which, in the United States, issue almost all corporate charters) nor the federal government has the power to grant constitutional rights, whether by charter or statute. Constitutional rights come from the Constitution. Because the Constitution does not expressly grant rights to corporations, and because corporations cannot be reduced to the citizens or classes of persons to whom it does expressly grant rights (i.e., because it is neither an association of natural persons nor itself a natural, or “real,” person), it makes no sense, on the grant theory view, to impute constitutional rights to corporations. Put simply, corporations, having been constituted by government and having received their rights from government, cannot turn around and claim constitutional rights against government, as if, like the People, they preexisted government and had reserved rights against it (US Constitution, Tenth Amendment).
It was presumably the grant theory perspective that Justice Sotomayor was contemplating when she noted, in the reargument of Citizens United (September 9, 2009, transcript p. 33, lines 20–24), that “there could be an argument made that was the Court’s error to start with … that the Court imbued a creature of State law with human characteristics.” This article, which is an exercise in normative legal theory, shows how strong this argument is when fleshed out with the insights of recent corporate law scholarship. While the practical implications of denying constitutional rights to corporations may seem dramatic, they need not be. Many of their key property rights are sufficiently protected by the common law, and any of the additional rights they currently enjoy could be enacted by statute, after consideration on the merits. But they should not have constitutional status.
This article first addresses the question of constitutional rights for business corporations, since they are the most legally complex corporate type. Section I lays out the defining legal attributes of the business corporation and shows how each contributes to the corporation’s economic success. Section II shows why only government can provide these attributes. Sections III, IV, and V evaluate the association, real entity, and grant theories in light of this corporate dependence on government. Section VI addresses the simpler if less certain case of nonprofits and is followed by a conclusion.
I. The Attributes and Advantages of the Corporate Form of Business
A general partnership may fairly be described as an association of individuals. The property of the partnership is the partners’ personal property, the contracts of the partnership are their contracts, and the liabilities of the partnership are their liabilities. None of this holds for the corporation, which has property, contracts, and liabilities wholly separate from its shareholders. It is not a glorified partnership. The present section describes the legal attributes that effect this separation in the corporation. The succeeding section explains why these attributes cannot be secured through private contract but must be provided by government through legal fiat. The conclusion toward which these sections drive is that the corporation is not an association of individuals but is an abstract right- and property-holding entity ordained by the government for the use of individuals. Being legally separate, its rights are not those of its shareholders, and the rights of its shareholders do not “pass through” to it. Further, being dependent on government for this separateness, it does not have an existence independent from or prior to government that would justify its holding constitutional rights against government as a “real entity.”
Limited Liability. The most famous defining attribute of the business corporation is the privilege of limited liability, which protects investors from corporate debt.Footnote 11 In protecting investors from business debt, it lowers investor risk, thus attracting passive investors, large and small. This both increases the quantity of capital that can be raised and lowers its cost.
Asset Lock-in. In truth, limited liability, despite all the attention it receives, is the least important of the Big Three corporate privileges from a business perspective. Corporations have succeeded without it, because financing can also be obtained from banks and bondholders, which generally prefer shareholders to be liable. Indeed, limited liability did not become a fully standard feature of incorporation until after 1900 (Horwitz Reference Horwitz1992, 94). A more important privilege is what I call asset lock-in. In a general partnership, a partner has license to withdraw her share of assets at any time, possibly forcing liquidation of the partnership. In a corporation, however, investments are permanent. An investor may recoup the monetary value of her investment if she can find another investor to take her place—that is, to buy her stock. But the assets that the corporation purchases with her initial investment are “locked in,” becoming corporate property. On the one hand, this increases the corporation’s creditworthiness, as lenders need not fear expropriation by withdrawing investors. On the other hand, it increases firm productivity. This is because it allows the corporation to specialize its assets to the production process, rather than keep them in more liquid form out of fear that investor withdrawal will force a sell-off (Blair Reference Blair2003). Furthermore, and for the same reason, it allows the corporation to specialize its workers to these specialized assets (Rajan and Zingales Reference Rajan1998). And of course, the specialization of capital and labor is the classic route to increased productivity (Smith 1776/Reference Smith1976, bk. I, chap. 1).
Entity Shielding. Equally important is the privilege that Henry Hansmann and Reiner Kraakman have named strong entity shielding (Hansmann, Kraakman, and Squire Reference Hansmann2006). It may be thought of as the inverse of limited liability. Whereas the latter shields the investor from the debts of the corporation, entity shielding shields the corporation from the debts of its investors. General partnerships do not enjoy this privilege. If partner Jones racks up debts at the casino that his personal assets will not cover, the casino can go after partnership assets, possibly dissolving the partnership. In contrast, if stockholder Martinez racks up these debts, the casino may take his stock, but it cannot levy against the assets of the corporation itself. This further increases the corporation’s creditworthiness. Creditors of the corporation need not worry that their due will be seized by the personal creditors of insolvent investors.
The magic that these three privileges work when working together is to combine strong capital-raising capability with strong liquidation protection. This is otherwise an elusive combination. A sole proprietorship certainly has liquidation protection from outside investors, since there are no outside investors. But that also means it has restricted capital-raising capability. A partnership has improved capital-raising capability, since it can raise capital from its multiple partners. But the ability of partners to withdraw their contributions leaves it with poor liquidation protection.
In contrast, the privileges of limited liability, asset lock-in, and entity shielding allow the corporation to have both. The combination of asset lock-in and entity shielding, as we have seen, protects the corporation from asset liquidation, whether by investors or their personal creditors. And it increases the creditworthiness of the corporation and thus its capital-raising capability.
It might seem, however, that the privilege of asset lock-in, while appealing to creditors, would actually lessen the attractiveness of the corporation to investors, since their investments become locked in. Thus, the capital-raising capability that a corporation gains from creditors would be cancelled out by its loss of investors. However, the corporate form generates compensating advantages for the investor that more than offset this downside.
First, the combination of asset lock-in and entity shielding increases the attraction of the corporation to investors for the same reason it does to creditors, which is that they need not worry about their own investments being put at risk by insolvent fellow-investors—something they very much have to worry about if in a partnership. Even more, the corporation compensates for the irrevocability of investments by issuing tradable shares. This allows investors to withdraw the value of their investments, by selling their shares, while leaving the assets of the corporation untouched. And significantly, tradable shares are themselves made possible by the combined privileges of limited liability and entity shielding. This is for two reasons. First, without these privileges, shares would make their way into the hands of financially weak investors, who would be willing to pay a premium for them because of the possibility of using corporate assets as collateral. Initial investors would never tolerate this, and trade in shares would be barred (Hansmann et al. Reference Hansmann2006, 1350). With these privileges in place, however, the financial condition of investors is irrelevant to the value of the firm and thus not a concern of existing investors, so tradability can go forward. Second, without these two privileges, it would be next to impossible to calculate the value of a share, since its value would depend on the financial condition, not only of the firm, but of every investor, which is a constantly moving target. For example, without limited liability, a wealthy investor would see a corporation with other wealthy investors as lower risk (and thus more valuable) than one with the same number of middle-class investors, who have fewer assets for creditors to levy against should the firm fold. Similarly, without entity shielding, an investor would rate the shares of a firm higher or lower depending on the solvency of the other investors, whose personal creditors might levy against firm assets. Calculating the value of shares under these conditions, especially given our privacy laws, would simply be a guessing game, which would hamper tradability. What is more, a potential investor would be saddled with enormous costs in monitoring the constantly changing stable of other investors to ensure the soundness of her own investment. This is just what partners have to do. Reduced monitoring costs is thus another reason these privileges increase the appeal of corporations to investors. In sum, the corporate form reduces the investor’s monitoring costs and, with tradable shares, largely preserves his liquidity, making corporations just as attractive for the investor as for the creditor.
A simple way of characterizing the work performed by the privileges of asset lock-in, entity shielding, and limited liability is that they completely disentangle corporate assets and liabilities from investor assets and liabilities. They are what make the corporation a separate contracting individual with the right to “own property, make contracts, and sue and be sued” as if it were a natural individual. Which is to say, they are what make the corporation a corporation. Without these, its property and liabilities would be legally reducible to its investors, making it a partnership.
This disentanglement of assets and liabilities shows why it is a complete misnomer to speak of shareholders as the “owners” of the corporation. The corporation owns corporate property. Shareholders do not. What a shareholder owns is a share. It is a good purchased from the corporation—a good that provides some unusual rights, such as the (nominal) right to vote on directors and the privilege of receiving dividends if management decides to offer them. But in owning it, a shareholder does not own a “piece” of the company, any more than the owner of a Buick owns a piece of General Motors. The purchaser of a share in a public offering hands over money to the company for keeps. This is the meaning of asset lock-in and entity shielding. To get any of it back, the shareholder has to find someone else to buy the share, as is true of any other good they have purchased.
Owning a share is thus nothing like owning corporate assets. Neither individually nor as a body do shareholders have the right to use corporate assets, restrict others’ use of them, lend them out, borrow on them, or sell them. They cannot even claim the profits from the use or sale of corporate assets, as they would if they were truly the “residual claimants” of corporate property, since dividends are provided at management discretion (Greenfield Reference Greenfield2006, 43–47). What is more, if shareholders were true owners, then, at the dissolution of the corporation, all corporate assets and liabilities would devolve onto them, and it would be their responsibility to discharge company debts to corporate creditors. But in actuality, corporate creditors are paid first, with shareholders receiving what is left over, as heirs, not owners (Wood v. Dummer, 30 F. Cas. 435 [C.D. Me. 1824] [No. 17944]).
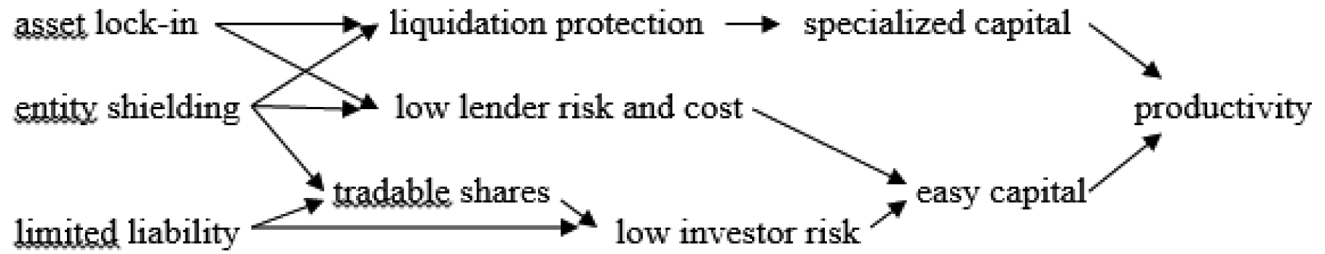
That corporate property is owned by the corporation is the key to its being a contracting individual, as it is this property that bonds its contracts. This property ownership brings great business benefits to the corporation. It provides it with strong liquidation protection (neither investors nor their creditors can force liquidation of firm assets), which increases its productivity (by enabling asset and labor specialization) and lowers its cost of capital (by lowering the risk and monitoring costs of its creditors and investors). Limited liability then drops the cost of capital even more, by lowering investor risk (both directly, and by combining with entity shielding to make shares tradable).
The economic benefits provided by these legal attributes may be diagrammed as follows, providing us with the essentials of an economic theory of the corporation (fig. 1). This combination of attributes makes the corporate form (or one of the new quasi-corporate forms such as the Limited Liability Company) the business form of choice in any industry requiring large amounts of specialized capital.
An economic theory of the corporation
II. Dependence of the Corporate Form of Business on Government
I have denominated these legal attributes “privileges,” but is it correct to say that these corporate attributes can only be provided by government? Today, asset lock-in, entity shielding, and limited liability are provided by each state as part of a default package of legal privileges that come with incorporation. But could an association of natural individuals secure them for itself through a series of bilateral contracts? If it could (Alchian and Demsetz Reference Alchian1972; Posner Reference Posner1976), then the business corporation would be reducible to individuals in association. And if these individuals are citizens, then it could be argued that the corporation bears their citizenship rights. However, the contractual view is mistaken.
Limited Liability. Limited liability is conventionally seen as the key corporate privilege (Easterbrook and Fischel Reference Easterbrook1985). The contractual view acquires credence because of the fact that it is possible to secure partial limited liability through bilateral contracting. This may be done by having every corporate contract include a rider specifying that, in case of the corporation’s default, the corporate creditor will not levy against the personal assets of the corporation’s shareholders. This is not just a theoretical possibility. In early 19th-century England—where the Lords Justice, acting as Regents, had made the corporate form largely unavailable after the South Sea bubble—this became a not infrequent practice, gradually, if grudgingly, condoned by the English courts (Harris Reference Harris1994, 624; Anderson and Tollison Reference Anderson and Tollison1996, 114; Hansmann and Kraakman Reference Hansmann2000, 429–30).
However, this means of limiting liability only goes so far. Importantly, such contracting cannot limit investor liability for corporate torts, since the harmed parties would not in general have been party to the contract. Only the legal fiat of government can grant tort protection to investors (Hansmann and Kraakman Reference Hansmann2000, 431). With the rise of product liability and environmental liability, this is a significant privilege.
Asset Lock-in. Like limited liability, asset lock-in can also be partially secured through bilateral contracting. Investors simply contract with one another not to withdraw assets for a fixed term. This is, in fact, a common arrangement among partners in a partnership, who through this secure for their firm some of the advantages of asset lock-in (Blair Reference Blair2003, 410). However, corporations enjoy asset lock-in on a permanent basis, whereas courts have viewed contractual arrangements among partners that restrict asset withdrawal beyond a handful of years as inconsistent with the rights of private property, and have been unwilling to honor them (Hansmann and Kraakman Reference Hansmann2000, 412). This is no substitute in industries that require long-term dedication of specialized capital—including almost all manufacturing and resource extraction industries, for example. So again, private contracting is only partially successful in securing the corporate privilege.
Entity Shielding. The biggest stumbling block for the contractual view is the privilege of entity shielding. The failure of contractualists to come to terms with this privilege is understandable, given that it is only in the past ten years that the privilege has been properly isolated and analyzed. But it is arguably the linchpin privilege, combining with each of the others to secure their economic benefits. If it cannot be contracted for, then corporations simply cannot be reduced to the contracts of private parties.
The device that would have to be used to secure entity shielding through contract is clear. Every investor would have to write a contract with every one of her personal creditors specifying that, in case of nonpayment, the creditor could not levy against corporate assets. These creditors would include the banks that might hold her mortgage or car loan, the utility companies and communication and entertainment companies that service her home, and every vender with whom she purchases on credit, from grocery stores to online venders.
The most obvious strike against this ever happening is the high negotiation costs involved. But there is an even bigger, less obvious, strike against it. It would be against the interest of every investor to write these contracts. Without the contracts, the investor’s credit would be markedly improved, as the assets of those corporations in which the investor owns stock would back her loans. Signing the contracts would reduce her credit, as she would only have her personal assets to back any loan. Given this adverse incentive to signing, establishing entity shielding contractually would require every investor to monitor the content of the contracts of every other investor, which would be neither feasible nor legal. In conclusion, between the contracting costs and moral hazard involved, securing entity shielding through bilateral contracts is out of the question, and there are no historical examples of it. Entity shielding is a privilege that must be provided by government or not at all (Hansmann and Kraakman Reference Hansmann2000, 406–22).
In sum, of these three legal privileges, limited liability and asset lock-in can be partially secured with the creative use of contracts, but cannot be fully secured. What is more, entity shielding cannot be secured at all. All of the constitutive attributes of the business corporation can only be provided in full on the authority of government.
It should be emphasized that this argument about the dependence of the corporation on government differs from standard “legal realist” arguments and has different constitutional implications. A legal realist would point out that all businesses, whether proprietorships, partnerships, or corporations, are to some degree dependent upon government, in that the common law rules of property, contract, and liability by which they operate do not exist in the “state of nature” but are provided and upheld by government. But I am talking about a different order of dependence. The property, contracts, and liabilities of proprietorships and general partnerships are the property, contracts, and liabilities of natural persons. Whatever the specific rules of property and contract by which they operate, this remains the case, for that is what it is to be a proprietorship or partnership—they are legally identified with natural persons. Therefore, the rights of proprietorships and general partnerships can be said to be those of natural persons. And since natural persons are not dependent on government for their existence, they—and through them their businesses—can claim to have rights prior to government that may be held against it.
This is not true of corporate persons. A business corporation, as a contracting individual, only exists because of the rules of asset and liability partitioning just discussed. Without them, one is back with a general partnership. These rules are applied to a firm when it is granted a government charter, and with this act, government creates the contracting, property-owning individual that is the corporation.
In sum, legal realist arguments show that the terms on which economic entities relate to one another is dependent on government. That may have consequences for the right of legislatures to revise these rules (which was the legal realists’ objective), but it has no bearing on whether these economic entities are in principle entitled to constitutional rights. The arguments above show that the business corporation itself is dependent on government. That has constitutional implications. Being a creature of government, it can neither claim to be a mere association of private persons, not can it claim to preexist government and hold reserved rights against it. That is the crux of the argument being developed here.Footnote 12
The conclusions of Section II allow us to evaluate the three theories of the corporation. I begin with the association theory, which was the first to argue that corporations merit constitutional rights. Then I evaluate the real entity theory, which appeared to offer a yet stronger grounding for corporate constitutional rights. Finally, I turn to the grant theory, mapping its original strength, its subsequent decline, and its renewed force in light of contemporary scholarship on the corporation’s legal privileges.
III. Evaluating the Association Theory
The association theory argues that a corporation is reducible to its members, generally with the additional claim that it is formed, rather like a partnership, through voluntary association. As put by Victor Morawetz (Reference Morawetz1882, 2), a prominent corporate lawyer, in one of the earliest legal treatises advancing the theory, corporations “are formed by the voluntary association of their members. … Although a corporation is frequently spoken of as a person or unit … the existence of a corporation as an entity, independently of its members, is a fiction; and … the rights and duties of an incorporated association are in reality the rights and duties of the persons who compose it, and not of an imaginary being.”
In light of the analysis above, we see immediately the shortcomings of this theory. First, shareholder agreements are not sufficient to establish a corporation, as our analysis of entity shielding has shown. Second, because a corporation’s property, credit, and liability are wholly separate from that of its investors, the corporation is a legal entity independent of its members. Even if a corporation bought back all of its outstanding stock (eliminating its shareholders) and if all employees, managers, and board members resigned, the corporation would still exist, because it would still own property and be party to outstanding contracts (and would either be taken over by the state or wound up by the courts). The corporate entity brings people into association, but it is not itself the association.Footnote 13 Third, the rights of the corporation are not at all the rights of its members. As one contemporary of Morawetz cautioned, “The main value of a corporate charter arises from the fact that powers and privileges are thereby acquired which individuals do not possess. It is this that makes the difference between a business corporation and a partnership. In the former there is no individual liability. … There is no death … It is not policy therefore for a corporation to break down its own independent existence by burying its original character in the common place privileges of the individual. … Any mingling of corporate existence with the existence of the shareholders will weaken corporate rights.”Footnote 14
In sum, the corporation (unlike a general partnership) cannot be identified with its members. Its rights are different than those of its members and, because it has a separate legal existence from them, it does not share in their rights. Rather, the rights of a corporation come from its charter. And charter rights do not include constitutional rights.
An Association of Shareholder Property?
There is a more limited version of the association theory, however, that construes the corporation as an association of property rather than of people. Whether or not the corporate entity is reducible to natural persons, the argument runs, corporate assets and funds are. They are the property of shareholders, who “own” the corporation. This is the prevalent view in law school classrooms and the business press, and it seems to be the view of the Court as well (Citizens United 2010, 908). If true, then it does not matter that the entity holding the funds is not reducible to its members. If corporate funds are the funds of shareholders, then these funds should have the same protections—under common law, statute, and the Constitution—as the private property of the shareholders, since these funds are the private property of shareholders.
This seems, in fact, to have been the ground on which constitutional rights were first expressly extended to corporations. In his circuit court opinion in San Mateo v. Southern Pacific Railroad Co. (13 F. 22 [1882], the companion case to Santa Clara), Justice Field provided the most extended defense—indeed the only extended defense—of constitutional rights for corporations ever offered by a federal judge. “So far as their property is concerned,” Field argued, corporations no less than natural persons enjoy Fourteenth Amendment due process protection and equal protection of the laws. “It would be a most singular result if a constitutional provision intended for the protection of every person against partial and discriminating legislation by the states, should cease to exert such protection the moment the person becomes a member of a corporation. We cannot accept such a conclusion.” This, he continued, “is because the property of a corporation is in fact the property of the corporators” (747). Field continued to invoke this property version of the association theory as justification for Fourteenth Amendment rights for corporations in a string of cases subsequent to Santa Clara, beginning with Pembina Consolidated Silver Mining & Milling Company v. Pennsylvania (1888). It was also invoked by justice Brewer in Gulf, Colorado and Santa Fe Railway Co. v. Ellis (an equal protection case), and it seems to be the version of the association theory invoked by justice Brown in Hale v. Henkel.Footnote 15
It was in anticipation of this argument that I emphasized above the fallacy of treating shareholders as the owners of the corporation. From the beginning, the defining attribute of a corporation has been its right, granted by charter, to own property, make contracts, and sue and be sued as an individual. Asset lock-in and entity shielding are the privileges that make good on this right. Corporations thus receive protection of their property at common law as do natural persons. But if the corporate entity owns corporate property, then shareholders cannot own it also. The property rights of shareholders protect their shares. They do not extend to corporate property. Therefore, the property rights of corporations are only as extensive as what the common law, or federal statute, provides. They do not get the additional constitutional protections of their property afforded to natural person. These cannot come by state (or federal) charter.
The property version of the association theory went into remission after the New Deal Court ended use of the Fourteenth Amendment as a bar to economic regulation. But once the Court, in Buckley v. Valeo (424 U.S. 1 [1976]), equated monetary expenditures with speech, new vistas were opened for the property theory through the First Amendment. Citizens United represents the culmination of this development. Assuming shareholders to be the owners of corporate funds, Kennedy complains that “wealthy individuals and unincorporated associations can spend unlimited amounts on independent expenditures,” while “associations of citizens … that have taken on the corporate form” are prevented (Citizens United, 130 S.Ct. at 108).
But again, corporate funds are not the personal funds of shareholders or anyone else. They are corporate property. Shareholders who want to spend in elections can and should sell some of their shares and use the proceeds for this purpose. This preserves their constitutional rights in full. But unlike their shares, which they actually own, the funds of the corporation are simply not theirs, and therefore their right to spend unlimited personal funds on political speech does not extend to corporate funds.
That shareholders do not own corporate funds is also why management, whose prerogative it is to spend corporate funds, does not properly have a constitutional right to spend corporate funds for political purposes on behalf of shareholders. To say otherwise is to say that, even though shareholders have absolutely no other property rights over corporate property and funds—cannot use it, lend it out, borrow on it, or sell or spend it—and have none of the legal liabilities that come with such control rights, we will nonetheless attribute to them a right to spend corporate property without limit in elections and furthermore will posit that, through some unexplained commutative principle, management gets to exercise this right for them, even if without any process of authorization and against their will.
In short, just as the corporation, as a separate, government-constituted legal entity, cannot be construed as an association, so the property of the corporation cannot be construed as the property of its “associating members” (shareholders). Therefore, corporate management should not be able to claim for the corporation or its property the constitutional rights of its shareholders.
The central problems with the association theory may now be summarized:
-
1. The corporate form cannot be created through a series of bilateral contracts but only through government’s legal fiats. The corporation thus cannot be construed as a voluntary association of individuals and cannot, in legal logic, claim the constitutional rights of these individuals.
-
2. Corporate property is owned by the corporation, not the shareholders. Therefore, the property rights of shareholders do not apply to the corporation. The corporation has property rights at common law, via its charter, but this does not include constitutional-level protections.
-
3. If the rights of a corporation are derived from its members, why does a corporation receive rights that natural persons do not have? What is more, if rights pass through to a corporation from its members, why do corporations not enjoy all constitutional rights, including the right to personal privacy, or to vote?
IV. Evaluating the Real Entity Theory
As already noted, the association theory did come with one downside for corporate advocates, which is that, in justifying the extension of constitutional rights to corporations by identifying corporate rights with the rights of their members as natural persons, it jeopardized corporate rights not enjoyed by unincorporated natural persons, such as limited liability. The real entity theory was promoted in the 1890s to remove corporations from the horns of this dilemma. Like the grant theory, the real entity theory posits that the corporation is an entity distinct from its members—a “legal person” with rights of its own (such as limited liability). Like the association theory, the real entity theory posits that this corporate entity arises independent of the state and is therefore fully private. Taken together, this would mean that corporations are “private persons” and thus capable of holding constitutional rights against government through the Fourteenth Amendment.
The appeal of such a theory for corporate management is clear enough.Footnote 16 But on its face, the claim that a corporation is a real entity akin to a flesh-and-blood person is bizarre. For the sophisticate, however, two factors lent the theory an air of plausibility.
First, as noted at the outset of this essay, the term “legal person” is deeply ambiguous. It traditionally referenced what I have been calling a “contracting individual,” with rights under the law of property and contract. This is very different from being a “constitutional individual,” with constitutional rights such as those in the Bill of Rights. Nonetheless, since a constitutional individual is also a kind of legal person, it becomes all too easy to imagine that the corporation, as a legal person (meaning a contracting individual) deserves to have the rights of a legal person (meaning a constitutional individual).Footnote 17
But to give the real entity theory a proper grounding, something more was needed than a linguistic sleight of hand. Corporate advocates had to come up with an argument that corporations were legally separate from their members and also independent of the state—nonartificial, “natural” and thus “real.” It was at this point that corporate advocates drew on a new and learned multivolume history of associations and corporations by the great German scholar Otto von Gierke, which was read and elaborated upon by the great English scholar Frederick Maitland, and the American scholar Ernest Freund, among others (Gierke Reference Gierke1868/1913; Freund Reference Freund1897; Maitland Reference Maitland2003). The thrust of this work, which was simultaneously antistatist and anti-individualist, was to show that medieval corporations, such as towns, universities, and guilds, were not the handiwork of the state but were sui generis groups with organic lives of their own independent of the state and irreducible to the individuals composing them.Footnote 18 “Our German Fellowship is no fiction, no symbol, no piece of the State’s machinery, no collective name for individuals, but a living organism and a real person, with body and members and a will of its own. Itself can will, itself can act; it wills and acts by the men who are its organs as a man wills and acts by brain, mouth and hand” (quoted in Maitland Reference Maitland and von Gierke1900, xxvi). American scholars such as Arthur Machen of the University of Chicago Law School applied these conclusions to their own work on the business corporation. “In these days it has become fashionable to inveigh against the doctrine that a corporation is an entity, as a mere technicality and a relic of the Middle Ages, but nothing could be further from the truth. A corporation is an entity—not imaginary or fictitious, but real, not artificial but natural” (quoted in Horwitz Reference Horwitz1992, 103).
These scholars made two mistakes, however. One was to infer the nature of the modern business corporation from the nature of the medieval corporation. Many medieval corporations, such as towns, did in fact form independent of the crown and only later were required by the crown to obtain a charter (Mumford Reference Mumford1961).Footnote 19 But this is not so for business corporations. Being investment vehicles, business corporations rely upon government granted privileges such as asset lock-in and entity shielding and cannot form without this government intervention. Business corporations are inherently “artificial” entities. This was not obvious to historians of a century ago, but it should be obvious in light of recent corporate law scholarship.
A yet more fundamental mistake was to conflate the corporation with the group personality that, on hypothesis, emerges from its members. This sociological phenomenon, if real, could arise in any group (as Gierke would agree), not just in a corporation. So if a group personality is the source of rights, it is unclear why corporate groups receive one set of rights and other groups (families, partnerships, government agencies) receive other sets of rights. What is more, the members of any given corporation may change—indeed, they may all resign—without affecting the rights and obligations of the corporate entity. This shows that the group personality has nothing to do with grounding these rights. The only position consistent with these facts is that corporate rights attach, not to the natural persons affiliated with the corporation, or to group personality that emerges from them, but to the abstract legal entity, “invisible, intangible, and existing only in contemplation of law,” and that these rights are attached to it by the corporate charter.
The entity theory thus rose on the back of three errors: (1) a conflation of contracting individuals with constitutional individuals; (2) a conflation of medieval corporations with modern business corporations; and (3) a conflation of the group personality with the rights-bearing corporate entity.
The degree of influence of the entity theory on the Supreme Court is a matter of dispute.Footnote 20 But that it has had at least some purchase is evidenced by Citizens United, where the majority presumes something like the real entity theory when it argues that the corporation is a speaker with opinions that add to the diversity of democratic debate.
However, the real entity theory is especially sterile when invoked as a support for something like corporate electioneering. This is because, to legally spend money in elections, one must be more than a person. One must be a citizen (Federal Campaign Election Act of 1971, Pub.L. 92–225, 86 Stat. 3, 2 U.S.C. § 431 [1972]). Citing the Court’s Bellotti opinion (First National Bank of Boston v. Bellotti, 435 U.S. 765, 777–83 [1978]), Kennedy creates the impression that the identity of the speaker does not matter, as it is the rights of the listeners that are infringed when speech is prohibited. But this is a false impression, as evidenced by the Court’s post—Citizens United summary affirmation in Bluman v. FEC (2012) of a district court’s dismissal of a Canadian’s claim of a right to make campaign contributions and expenditures in American elections. The identity of the speaker does matter to the Court, at least in that the speaker must be a citizen. So even were the corporation a “real entity” with a distinctive viewpoint (which it is not), it still would have no right under US law (or so far as I know, the law of any nation) to electioneer, because, having been neither biologically born nor naturalized, it would be no more a citizen than a foreign national. Therefore, the billions of Exxon Mobil should have no more right to be spent in American elections than the billions of a Russian oligarch or Saudi prince, however distinctive the political views of each, because each lacks citizenship.
V. Evaluating the Grant Theory
The grant theory was the theory of the business corporation on through the Civil War. There are several reasons for the self-evidence of this theory in the early history of the business corporation. First, before the era of general incorporation laws, the grant of a charter had a strong performative dimension. Incorporation involved negotiations between would-be incorporators and the sovereign (whether Crown or legislature), which, if successful, resulted in the grant, by special enactment, of a charter, wherein was specified the rights being conveyed (Maier Reference Maier1993, 54–56). Under such a procedure, the “grantedness” of corporate rights was obvious.
Second, the rights conveyed often included, beyond those discussed above, clear delegations of sovereignty. The English East India Company and Dutch East India Company, the world’s first two publicly traded limited liability business corporations, enjoyed monopolies over trade, and a right to mint coin, imprison lawbreakers, establish colonies, declare war, and negotiate treaties (Robins Reference Robins2006; Ames Reference Ames2008, 102–3). Even in early 19th-century America, corporate rights generally included a monopoly and might additionally include the exemption of incorporators from taxes or even military service (Maier Reference Maier1993, 67). These were hardly normal business rights; they were clear exceptional grants—delegations of sovereignty for undertaking activities that the government supported but did not have the desire or capacity to undertake itself.
Third, the early business corporations were founded in the Age of Absolutism, during which official ideology accorded all rights to the sovereign, with all liberties understood as privileges carved out of this overarching sovereignty (Franklin Reference Franklin2009). Under this theory, whatever rights were acquired by a corporation would naturally have been understood as privileges in grant.
These three circumstances underscored the grantedness of corporate existence and rights, which made the idea of corporations having constitutional rights against government a nonstarter. But over the ensuing centuries, political and business transformations weakened the hold of the grant theory on the legal mind. The absolutist theory of sovereignty was the first to go. Over the course of the English Civil War, the Glorious Revolution, and especially the American Independence movement and the French Revolution, theories of natural rights were articulated that turned the theory of sovereignty on its head, suggesting that the rights of government were a grant from the governed rather than the other way around (Tuck Reference Tuck1982). Meanwhile, corporate privileges were being whittled down to the core elements discussed in Section II, with corporate monopoly in particular coming under lethal assault from Jacksonian Democrats (Maier Reference Maier1993, 76). Finally, as part of this same Jacksonian assault on monopoly and privilege, states passed general laws of incorporation that extended the right of incorporation to all, provided that incorporators paid the requisite fee and abided by specified business practices (76).
Combined, these transformations could convey the impression that incorporation and the rights that come with it are a part of normal, “natural” business rights, rather than government privileges. This impression was exploited by corporate lawyers seeking to overthrow the grant theory and replace it with one of the above theories more supportive of corporate rights against government regulation.
As the discussion above shows, however, this impression is false. Corporate existence is a government privilege, effected through means of the more specific legal privileges of asset lock-in, entity shielding, and limited liability. It is immaterial whether these privileges are granted through special legislative enactment, as they once were, or through a licensing process under a general law of incorporation, as now. Either way, corporations are brought into being by legal fiats that override the rules by which proprietors and partners operate. However much the modern practice of incorporation may look like a private act, the legal privileges granted to corporations belie this appearance and instead show us that corporations, at their very foundation, blur the line between public and private.Footnote 21
The surprising implication is that the grant theory of the corporation—old-fashioned though it may be—is seen to rest on a firm foundation once the legal attributes of the corporation are properly identified and analyzed. Corporations do not emerge naturally from the property and contract law of market economies. Rather, government constitutes them by issuing charters that override on their behalf the normal rights of private property and duties of liability—for example, by barring investors from withdrawing their capital contribution, while relieving investors of their liability to corporate creditors. Again, these are not mere “advantages” grafted on to a preexisting, contractually constituted corporation. They are what create the corporate form of business, and they are grants of government.
A straightforward implication of this argument and of the grant theory that it supports is that corporations should not be able to claim constitutional rights against government. A corporation comes into being through a grant of rights from government, via a charter. Constitutional rights never have been, and never could be, among the rights granted them by charter, because constitutional rights cannot be conveyed by charter (or statute). They must be grounded in the constitution. Under constitutions such as that of the United States which do not speak of corporations or corporate rights, but only of natural persons and citizens, the case for corporate constitutional rights must rest on the reduction of corporations to either natural persons or citizens (or, for a more limited range of constitutional rights, the reduction of corporate property to the property of persons or citizens), whose rights pass to the corporation. But as the above critiques of the association theory and real entity theory show, this reduction cannot be made. Contra the association theory, associations of private persons cannot fully generate for themselves, through bilateral contracting, the corporate form with its legal attributes of asset-lock-in, entity shielding, and limited liability; nor does a corporation cease to exist if all natural persons associated with it sell out or resign. Therefore, corporations cannot be construed as associations of persons. Furthermore, their property, contracts, and liabilities are wholly separate from those of their shareholders or other natural persons, so their property cannot be reduced to the property of natural persons. Corporations are wholly abstract, property-owning entities that can only be constituted by government. And for this same reason—their being abstract entities constituted by government—corporations also cannot be construed as “real entities” akin to natural persons, nor can they be construed as members of a People that preexists government and holds reserved rights against it. And they certainly cannot be construed as citizens, being neither natural born nor naturalized.Footnote 22 Corporations thus only have what rights their chartering government grants them, and these do not and cannot include constitutional rights.
VI. Nonprofit Corporations and Constitutional Rights
The case of nonprofit corporations is far simpler to analyze, although more difficult to judge. On the one hand, nonprofits do not have investors. Therefore, they have no need for limited liability, nor for asset lock-in, nor for entity shielding. In this respect, nonprofits ask less of government in the way of overriding the normal rules of property and liability. However, nonprofits are no less able to own property, make contracts, and sue and be sued as unitary entities, and to establish internal governance, and these are all things granted through legal fiat. For example, there is no set of contracts that a group of individuals can sign with one another that would induce the courts to recognize a collection of their property as an independent unity, able to bond contracts and appear in court in its own name.Footnote 23 This is a baseline privilege that government grants to all corporations, even before one considers the special privileges (limited liability, asset lock-in, and entity shielding) that a business corporation must receive to remain a contracting individual (owing property and contracting in its own name) despite having multiple investors.
For-profit and nonprofit corporations are different enough that a constitutional distinction might be drawn. However, I believe the debt of nonprofits to government fiat remains substantial enough that nonprofits should not be able to claim constitutional rights. They are not “real entities,” since their capacity to own property comes in grant. And because they do not have shareholders, it is even more obvious that they cannot be construed as associations of shareholders, and that their property cannot be construed as the property of natural persons or citizens. Indeed, the implausibility of construing nonprofits as associations strengthens the case that for-profits are not associations, since for-profits merely tack on an investment mechanism to the nonprofit form, which historically preceded it. As an add-on, investors do not suddenly become the corporation, or become the owners of the corporation. The grant theory remains the correct theory for nonprofits, and therefore nonprofits should not be able to claim constitutional rights either.
VII. Conclusion
Over the past century and a half, three distinct theories of the corporation have informed arguments over corporate constitutional rights, each differently construing how corporations relate to natural individuals and government. Analysis of the legal attributes of the corporation allows us to evaluate all three.
The association theory denies that the corporation has any essential relationship to government. Instead, it sees the corporation as constituted by its members through normal, if complicated, bilateral contracting. Being reducible to its members, the corporation therefore deserves the same legal rights as its members, including constitutional rights. But as analysis of the legal attributes of the corporation shows, its existence as a property-owning, contracting individual cannot be reduced to contracts among its members. Neither can its property be reduced to the property of its members. Therefore, it cannot in sound logic acquire constitutional rights from its members.
The real entity theory agrees with the association theory that the corporation owes nothing to government. And it agrees with the grant theory that the corporation is distinct from its members. That is, it denies that the corporation is constituted either by government or reducible to natural individuals. The corporation is a “real entity” separate from each. The theory’s denial of a constitutive relationship between the corporation and individual citizens would seem to put in jeopardy the use of this theory for the justification of corporate constitutional rights. However, in the case of the United States, the Fourteenth Amendment’s fateful use of the word “person” rather than “citizen” created a back door by which the real entity theory could claim that a corporation, as a “private individual,” is a person within the meaning of the amendment, and thus a proper object of the amendment and all the rights incorporated through it.Footnote 24 However, analysis shows that the claim of corporate independence from government is erroneous. Let it be granted that the interaction of corporate employees or shareholders generates a group personality that is irreducible to these interacting members and independent of government; such a personality is not to be confused with the corporation as a legal entity and is thus irrelevant to the question of its rights at law. As a rights-bearing, property-owning entity, the corporation depends on government for its very existence. It is an artificial entity, not a “real” entity, nor a person within the meaning of the Fourteenth Amendment, nor a citizen. Therefore, a corporation cannot rightly invoke constitutional passages referencing the rights of persons or citizens to claim constitutional protection for itself as if it were itself a constitutional person or citizen.
Finally, the grant theory holds that government relates to the corporation as creator to creature. This is not to say that natural individuals are not required to animate the abstract legal body. But the corporation is conceived as a rights-bearing, property-owning, legal entity separate from its members, with all its rights coming in grant from the government (by charter or legislation). Analysis of the constituting privileges of asset lock-in and entity shielding confirms the grant theory view. The consequences of this for constitutional rights are entirely negative. If government is the source of corporate rights, then these cannot include constitutional rights, since constitutional rights cannot be granted by government legislation or charter. They can only be granted through a constitutional process. Furthermore, if government is the source of corporate rights, and indeed of corporate existence, it makes no sense for a corporation subsequently to claim constitutional rights for itself against government as if it were a natural person or association of persons. That is, the grant theory being right, the association and real entity theories must be wrong. And if government is the source of corporate existence, there is certainly no room for a Tenth Amendment interpretation that corporations preexist government and have reserved rights against it. Therefore, the only possible source for corporate constitutional rights is express mention of such rights in the text of a constitution.
Translated into American constitutional practice, this means (1) that corporations should never have received due process and equal rights protection for their property under the federal Constitution. The impact of this may have been minimal, however, because of the possibility of claiming due process and equal protection rights at common law, which turn-of-the-century federal judges may have been willing to expand even to substantive due process proportions.Footnote 25 Regardless, the “substantive” interpretation of these protections was overturned during the New Deal. It also means, however, that (2) corporations should not have protection under the Bill of Rights. The impact of this denial would be more substantial. It would exclude corporations from such things as the Fourth Amendment protection against unannounced inspections for regulatory compliance, which hampers, for example, the enforcement of OSHA regulations (Marshall v. Barlow’s Inc., 436 U.S. 307 [1978]). It would also exclude their speech from First Amendment protection, which would curtail both corporate advertising rights and corporate political influence.Footnote 26 Of course, any of these rights might be granted to corporations through statute. But whether or not this is done should be a matter of policy. It should not be a matter of constitutional adjudication.
Again, this is not to say that a corporation should not hold any rights against government. All corporations are chartered as contracting individuals with the right to own property, make contracts, and sue in court, and this has long included a corporation’s right, for example, to sue government if a government makes and breaks a contract with it. But these are rights under contract law. In contrast, constitutional rights cannot be granted by ordinary legislation or charter. They require the following of a prescribed constitutional process to amend the constitution. Yet ironically, in the United States, the decisions of the Court over the past 120 years, and its disposition today, may make a constitutional amendment necessary to assert this fact as applied to corporations.Footnote 27 One might hope that other nations will avoid the need for such extreme measures by avoiding the fallacious interpretative traditions that lead there.