



1. Introduction
Stochastic orders of variability have proved to be very useful in statistics, actuarial science, risk management, and operations research, among others. Various types of stochastic orders and associated properties can be found in [Reference Müller and Stoyan13] and [Reference Shaked and Shanthikumar16]. The most important and common orders are the (increasing) convex order, the usual dispersive order, and the right spread order (also called the excess wealth order). Belzunce, Hu, and Khaledi [Reference Belzunce, Hu and Khaledi5] introduced and studied a family of dispersion-type variability orders, among which are the usual dispersive order and the right spread order.
In the literature of statistics, the inter-quantile difference is a popular measure to quantify statistical dispersion of a random variable (see e.g. [Reference David7]). The usual dispersive order was introduced in [Reference Bickel and Lehmann6] in terms of inter-quantile differences of random variables. Recently, Bellini, Fadina, Wang, and Wei [Reference Bellini, Fadina, Wang and Wei2] studied parametric measures of variability induced by risk measures, expected shortfall (ES) and the expectiles, namely the inter-ES difference and the inter-ex difference. The inter-ES difference was also mentioned in [Reference Wang, Wei and Willmot17]. The purpose of this short note is to introduce and characterize two notions of dispersion-type variability orders, namely ES-dispersive order and ex-dispersive order, which are defined in terms of the inter-ES difference and the inter-ex difference. Such a study gives us some insight into the properties of the dilation order and parametric measures of variability induced by risk measures.
The rest of this short note is organized as follows. The definitions of three notions of dispersion-type variability orders induced by differences of the value-at-risk, ES, and the expectiles are presented in Section 2 with some basic properties. In Sections 3 and 4 we characterize the ES-dispersive order and the ex-dispersive order in terms of the dilation order, respectively, and prove that they are all equivalent. In Section 5 we conclude this paper with remarks on the definition of the ex-dispersive order.
Throughout, let
 $L^q$
denote the set of all risk variables in a probability space
 $(\Omega, \mathcal{A}, \mathbb{P})$
with finite q-moment, where
 $q\in [0, \infty)$
. For a distribution function F, the inverse of F is taken to be the left continuous version of it defined by
 \begin{equation*} F^{-1}(p)= \inf\{x\,:\, F(x)\ge p\}, \quad p\in (0,1),\end{equation*}
with
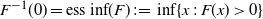 $F^{-1}(0)=\mathrm{ess\, inf}(F)\,:\!=\, \inf\{x\,:\, F(x)>0\}$
and
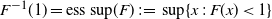 $F^{-1}(1)=\mathrm{ess\, sup}(F)\,:\!=\, \sup\{x\,:\, F(x)<1\}$
.
2. Definitions and basic properties
2.1. Three popular risk measures
The following three parametric families of risk measures are very popular in risk management (see e.g. [Reference Bellini and Di Bernardino1], [Reference Bellini, Klar, Müller and Rosazza Gianin4], and [Reference Emmer, Kratz and Tasche9]).
-
(i) The value-at-risk (VaR) of X at probability level p: for
 $p\in (0,1)$
,
\begin{equation*} \mathrm{VaR}_p(X)= F^{-1}_X(p),\quad X\in L^0. \end{equation*}
-
(ii) The expected shortfall (ES) of X at probability level p: for
$p\in (0,1)$
, The left-ES of X at probability level p: for
\begin{equation*} \mathrm{ES}_p(X)= \dfrac {1}{1-p} \int^1_p F^{-1}(u) \,{\mathrm{d}} u,\quad X\in L^1. \end{equation*}
$p\in (0,1)$
,
\begin{equation*} \mathrm{ES}^-_p(X)\,:\!=\, - \mathrm{ES}_{1-p}({-}X) = \dfrac {1}{p} \int^p_0 F^{-1}(u) \,{\mathrm{d}} u,\quad X\in L^1. \end{equation*}
-
(iii) The expectile of X at probability level p: for
$p\in (0,1)$
, The left-expectile of X at probability level p: for
\begin{equation*} \mathrm{ex}_p(X)= \min\{x\in\mathbb{R}\,:\, p\, \mathbb{E} [(X-x)_+] \le (1-p) \mathbb{E} [(X-x)_-]\}, \quad X\in L^1. \end{equation*}
$p\in (0,1)$
, where the last equality follows from Proposition 7 in [Reference Bellini, Klar, Müller and Rosazza Gianin4].
\begin{equation*} \mathrm{ex}^-_p(X)\,:\!=\, - \mathrm{ex}_{1-p}({-}X) = \mathrm{ex}_p(X),\quad X\in L^1, \end{equation*}


2.2. Dispersion-type variability orders
Definition 2.1. ([Reference Bickel and Lehmann6].) For
 $X, Y\in L^0$
, X is said to be smaller than Y in the dispersive order, denoted by
 $X\le_{\mathrm{disp}} Y$
, if
 \begin{equation*} \mathrm{VaR}_\beta(X) - \mathrm{VaR}_\alpha(X) \le \mathrm{VaR}_\beta(Y) - \mathrm{VaR}_\alpha(Y)\quad \text{for all $ 0<\alpha<\beta<1$.} \end{equation*}
This dispersive order is defined in terms of quantile or value-at-risk, so we call it the quantile-dispersive order, and denote it by
 $X\le_{\operatorname{Q-disp}} Y$
. For
 $0<\alpha<\beta<1$
,
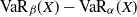 $\mathrm{VaR}_\beta(X) - \mathrm{VaR}_\alpha(X)$
is called the inter-quantile difference of a risk variable X.
Definition 2.2. For
 $X, Y\in L^1$
, X is said to be smaller than Y in the ES-dispersive order, denoted by
 $X\le_{\operatorname{ES-disp}} Y$
, if
 \begin{equation*} \mathrm{ES}_\beta(X) -\mathrm{ES}_\alpha^-(X) \le \mathrm{ES}_\beta(Y) -\mathrm{ES}_\alpha^-(Y)\quad \text{for all $ 0<\alpha<\beta<1$.} \end{equation*}
Definition 2.3. For
 $X, Y\in L^1$
, X is said to be smaller than Y in the ex-dispersive order, denoted by
 $X\le_{\operatorname{ex-disp}} Y$
, if
 \begin{equation} \mathrm{ex}_\beta(X) -\mathrm{ex}_\alpha(X) \le \mathrm{ex}_\beta(Y)- \mathrm{ex}_\alpha(Y)\quad \text{for all $ 0<\alpha\le \frac {1}{2}\le \beta<1$.}\end{equation}
For
 $0<\alpha<\beta<1$
,
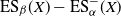 $\mathrm{ES}_\beta(X) -\mathrm{ES}_\alpha^-(X)$
is called the inter-ES difference, and
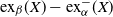 $\mathrm{ex}_\beta(X) -\mathrm{ex}^-_\alpha(X)$
is called the inter-expectile difference. Both can be used to measure the variability of X. Bellini et al. [Reference Bellini, Fadina, Wang and Wei2] introduced and investigated properties of three parametric measures of variability defined by the inter-quantile difference, inter-ES difference, and inter-expectile difference with
 $\alpha=1-\beta$
and parameter
 $\beta\in [1/2,1]$
. The ex-dispersive order was also independently introduced in [Reference Eberl and Klar8], and called the weak expectile dispersive order.
A remark (Remark 5.2) is given in Section 5 to explain why the restriction ‘
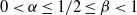 $0<\alpha\le 1/2\le \beta<1$
’ in (2.1) should not be replaced by ‘
 $0<\alpha\le \beta<1$
’.
2.3. Basic properties
Since
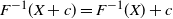 $F^{-1}(X+c)=F^{-1}(X)+c$
,
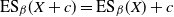 $\mathrm{ES}_\beta(X+c)= \mathrm{ES}_\beta(X)+c$
,
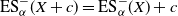 $\mathrm{ES}_\alpha^-(X+c)=\mathrm{ES}_\alpha^-(X)+c$
, and
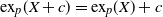 $\mathrm{ex}_p(X+c)= \mathrm{ex}_p(X)+c$
for any
 $X\in\mathcal{X}$
and
 $c\in\mathbb{R}$
, it follows that the order
 $\le_{*\hbox{-}\textrm{disp}}$
is location-independent, that is,
 \begin{equation*} X \le_{\text{$\ast$-disp}} Y \Longleftrightarrow X +c\le_{\text{$\ast$-disp}} Y\quad \text{for all $ c\in\mathbb{R}$,}\end{equation*}
where
 $\ast=$
Q, ES, and ex.
It is easy to see that if
 $X\le_{\operatorname{Q-disp}} Y$
, then
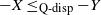 $-X\le_{\operatorname{Q-disp}} -Y$
. Note that, for any
 $X\in L^1$
and
 $\beta\in (0,1)$
,
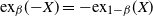 $\mathrm{ex}_\beta({-}X) = -\mathrm{ex}_{1-\beta}(X)$
for any
 $X\in L^1$
and
 $\beta\in (0,1)$
(see Proposition 7 in [Reference Bellini, Klar, Müller and Rosazza Gianin4]) and
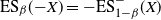 $\mathrm{ES}_\beta({-}X) = -\mathrm{ES}^-_{1-\beta}(X)$
. Therefore we have
 \begin{equation*} X\le_{\text{$\ast$-disp}} Y \Longleftrightarrow -X\le_{\text{$\ast$-disp}} -Y,\end{equation*}
where
 $\ast=$
Q, ES, and ex.
We list some basic properties of the quantile-dispersive order as follows.
-
Q1. If
$X\le_{\operatorname{Q-disp}} Y$
and
$X, Y\in L^2$
, then
$\mathrm{Var}(X)\le \mathrm{Var}(Y)$
. -
Q2. ([Reference Saunders14, Reference Shaked and Shanthikumar16]) X satisfies
$X \le_{\operatorname{Q-disp}} X+Y$
for any
$Y\in L^0$
independent of X if and only if X is
$\mathrm{PF}_2$
, that is, X has a log-concave density or probability mass function. -
Q3. ([Reference Hickey11, Reference Shaked and Shanthikumar16]) If
$X\le_{\operatorname{Q-disp}} Y$
, and if Z is
$\mathrm{PF}_2$
and independent of X and Y, then
$X+Z\le_{\operatorname{Q-disp}} Y+Z$
.


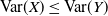
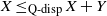


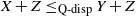
3. ES-dispersive order
Recall that for two risk variables
 $X, Y\in L^1$
, X is said to be smaller than Y in the convex order, denoted by
 $X\le_{\mathrm{cx}} Y$
, if
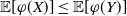 $\mathbb{E} [\varphi(X)]\le \mathbb{E} [\varphi(Y)]$
for all convex functions
 $\varphi$
such that the expectations exist. X is said to be smaller than Y in the dilation order, denoted by
 $X\le_{\mathrm{dil}} Y$
, if
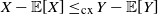 $X-\mathbb{E} [X]\le_{\mathrm{cx}} Y-\mathbb{E} [Y]$
; see [Reference Fagiuoli, Pellerey and Shaked10] and [Reference Shaked and Shanthikumar16] for properties of the convex order and definitions of other stochastic orders. Obviously, if
 $X\le_{\mathrm{cx}} Y$
, then
 $\mathbb{E} [X] =\mathbb{E} [Y]$
.
Proposition 3.1. For
 $X, Y\in L^1$
,
 \begin{equation*} X \le_{\operatorname{ES-disp}} Y \Longleftrightarrow X \le_{\mathrm{dil}} Y.\end{equation*}
Proof. Since both the order
 $\le_{\operatorname{ES-disp}}$
and the order
 $\le_{\mathrm{dil}}$
are location-independent, without loss of generality assume that
 $\mathbb{E} [X]=\mathbb{E} [Y]$
. Note that for any
 $ 0<\alpha<\beta<1$
,
 \begin{align*} \mathrm{ES}_\beta(X) -\mathrm{ES}_\alpha^-(X) &= \dfrac {1}{1-\beta} \int^1_{\beta} F^{-1}(u) \,{\mathrm{d}} u - \dfrac {1}{\alpha} \biggl(\mathbb{E} [X] -\int^1_\alpha F^{-1}(u) \,{\mathrm{d}} u \biggr)\\ &= \dfrac {1}{1-\beta} \int^1_{\beta} F^{-1}(u) \,{\mathrm{d}} u + \dfrac {1}{\alpha} \int^1_\alpha F^{-1}(u) \,{\mathrm{d}} u -\dfrac {1}{\alpha} \mathbb{E} [X].\end{align*}
Thus
 $X \le_{\operatorname{ES-disp}} Y$
if and only if, for any
 $ 0<\alpha<\beta<1$
,
 \begin{align} \dfrac {1}{1-\beta} \int^1_{\beta} F^{-1}(u) \,{\mathrm{d}} u + \dfrac {1}{\alpha} \int^1_\alpha F^{-1}(u) \,{\mathrm{d}} u \le \dfrac {1}{1-\beta} \int^1_{\beta} G^{-1}(u) \,{\mathrm{d}} u + \dfrac {1}{\alpha} \int^1_\alpha G^{-1}(u) \,{\mathrm{d}} u .\end{align}
On the other hand, from Theorems 4.A.3 and 4.A.35 in [Reference Shaked and Shanthikumar16], it follows that
 $X \le_{\mathrm{dil}} Y$
is equivalent to
 \begin{equation} \int^1_p F^{-1}(u) \,{\mathrm{d}} u \le \int^1_p G^{-1}(u) \,{\mathrm{d}} u\quad \text{for all $ p\in (0,1)$.}\end{equation}
Obviously (3.2) implies (3.1). On the other hand, for any
 $p\in (0,1)$
, letting
 $\beta \downarrow p$
and
 $\alpha\uparrow p$
in (3.1) yields that
 \begin{equation*} \biggl(\dfrac {1}{1-p}+\dfrac {1}{p}\biggr) \int^1_p F^{-1}(u) \,{\mathrm{d}} u \le \biggl(\dfrac {1}{1-p}+\dfrac {1}{p}\biggr) \int^1_p G^{-1}(u) \,{\mathrm{d}} u.\end{equation*}
This means that (3.1) implies (3.2). Therefore the desired result follows.
By Proposition 3.1 and exploiting the properties of the dilation order, we conclude the following.
-
ES1. If
$X\le_{\operatorname{ES-disp}} Y$
and
$X, Y\in L^2$
, then
$\mathrm{Var}(X)\le \mathrm{Var}(Y)$
. -
ES2. For any
$X, Z\in L^1$
such that X is independent of Z, we always have
$X\le_{\operatorname{ES-disp}} X+Z$
. -
ES3. If
$ X \le_{\operatorname{ES-disp}} Y$
and Z is independent of X and Y, then
$ X+Z \le_{\operatorname{ES-disp}} Y+Z$
. In particular, if
$X_i\le_{\operatorname{ES-disp}} Y_i$
for
$i=1, 2$
,
$X_1$
is independent of
$X_2$
, and
$Y_1$
is independent of
$Y_2$
, then
\begin{equation*} X_1+X_2 \le_{\operatorname{ES-disp}} Y_1+Y_2. \end{equation*}


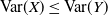

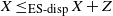

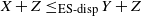


4. ex-dispersive order
Expectiles are related to the so-called Omega ratio, which is a popular measure of investment performance and was introduced in [Reference Shadwick and Keating15]. The Omega ratio of
 $X\in L^1$
is defined by
 \begin{equation*} \Omega_X(t)=\dfrac {\mathbb{E} [(X-t)_+]}{ \mathbb{E} [(X-t)_-]}, \end{equation*}
i.e. the ratio of the upside of X to the downside. Some basic properties of the Omega ratio of X are as follows (see [Reference Bellini, Klar and Müller3] and [Reference Klar and Müller12]). For
 $X\in L^1$
, denote
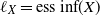 $\ell_X=\mathrm{ess\, inf}(X)$
and
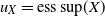 $u_X=\mathrm{ess\, sup}(X)$
. Then the function
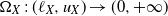 $\Omega_X\,:\, (\ell_X, u_X)\to (0, +\infty)$
is strictly decreasing, positive, and continuous with
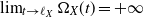 $\lim_{t\to \ell_X} \Omega_X(t)=+\infty$
,
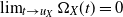 $\lim_{t\to u_X}\Omega_X(t)=0$
, and
 $\Omega_X(\mathbb{E} [X])=1$
. Also,
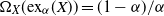 $\Omega_X(\mathrm{ex}_\alpha(X))=(1-\alpha)/\alpha$
for
 $\alpha\in (0,1)$
. Thus
 \begin{equation} \mathrm{ex}_\alpha(X) =\Omega_X^{-1}\biggl(\dfrac {1-\alpha}{\alpha}\biggr).\end{equation}
Lemma 4.1. For
 $X, Y\in L^1$
,
 $X \le_{\operatorname{ex-disp}} Y$
if and only if
 \begin{equation} \Omega_X^{-1}(p)-\Omega_Y^{-1}(p) \le \mathbb{E} [X]-\mathbb{E} [Y] \le \Omega_X^{-1}\biggl(\dfrac {1}{p}\biggr)-\Omega_Y^{-1}\biggl(\dfrac {1}{p}\biggr)\quad \textit{for all}\ p\in (0,1).\end{equation}
Proof. In view of (4.1),
 $X \le_{\operatorname{ex-disp}} Y$
is equivalent to
 \begin{equation*} \Omega_X^{-1}\biggl(\dfrac {1-\beta}{\beta}\biggr)-\Omega_X^{-1}\biggl(\dfrac {1-\alpha}{\alpha}\biggr) \le \Omega_Y^{-1}\biggl(\dfrac {1-\beta}{\beta}\biggr)-\Omega_Y^{-1}\biggl(\dfrac {1-\alpha}{\alpha}\biggr)\end{equation*}
or equivalently
 \begin{equation} \Omega_X^{-1}\biggl(\dfrac {1-\beta}{\beta}\biggr)- \Omega_Y^{-1}\biggl(\dfrac {1-\beta}{\beta}\biggr) \le \Omega_X^{-1}\biggl(\dfrac {1-\alpha}{\alpha}\biggr) -\Omega_Y^{-1}\biggl(\dfrac {1-\alpha}{\alpha}\biggr)\end{equation}
whenever
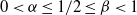 $0< \alpha\le 1/2\le \beta<1$
. Since
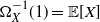 $\Omega_X^{-1}(1)=\mathbb{E} [X]$
,
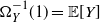 $\Omega_Y^{-1}(1)=\mathbb{E} [Y]$
, and
 $\Omega_X^{-1}$
and
 $\Omega_Y^{-1}$
are continuous, for
 $\beta\in [1/2,1)$
, letting
 $\alpha \uparrow 1/2$
in (4.3), we have
 \begin{equation*} \Omega_X^{-1}\biggl(\dfrac {1-\beta}{\beta}\biggr)- \Omega_Y^{-1}\biggl(\dfrac {1-\beta}{\beta}\biggr) \le \Omega_X^{-1} (1) -\Omega_Y^{-1} (1) = \mathbb{E} [X] -\mathbb{E} [Y]\end{equation*}
for
 $\beta\in [1/2, 1)$
. Similarly, letting
 $\beta \downarrow 1/2$
in (4.3), we have
 \begin{equation*} \mathbb{E} [X] -\mathbb{E} [Y] =\Omega_X^{-1} (1) -\Omega_Y^{-1} (1 ) \le \Omega_X^{-1}\biggl(\dfrac {1-\alpha}{\alpha}\biggr)-\Omega_Y^{-1}\biggl(\dfrac {1-\alpha}{\alpha}\biggr)\end{equation*}
for
 $\alpha\in (0, 1/2]$
. Therefore (4.2) is equivalent to (4.3). This completes the proof of the lemma.
Proposition 4.1. For
 $X, Y\in L^1$
,
 \begin{equation*} X \le_{\operatorname{ex-disp}} Y \Longleftrightarrow X \le_{\mathrm{dil}} Y.\end{equation*}
Proof. Since both the order
 $\le_{\operatorname{ex-disp}}$
and the order
 $\le_{\mathrm{dil}}$
are location-independent, without loss of generality assume that
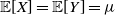 $\mathbb{E} [X]=\mathbb{E} [Y]=\mu$
. Then (4.2) reduces to
 \begin{equation*} \Omega_X^{-1}(p)-\Omega_Y^{-1}(p) \le 0 \le \Omega_X^{-1}\biggl(\dfrac {1}{p}\biggr)-\Omega_Y^{-1}\biggl(\dfrac {1}{p}\biggr)\quad \text{for all $ p\in (0,1)$,}\end{equation*}
or equivalently
 \begin{equation} \Omega_X^{-1} (p) \le \Omega_Y^{-1}(p),\quad \Omega_X^{-1}\biggl(\dfrac {1}{p}\biggr) \ge \Omega_Y^{-1}\biggl(\dfrac {1}{p}\biggr)\quad \text{for all $ p\in (0,1)$.}\end{equation}
Since
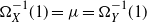 $\Omega_X^{-1}(1)=\mu=\Omega_Y^{-1}(1)$
, it follows that (4.4) is equivalent to
 \begin{equation} \Omega_X(t) \le \Omega_Y(t)<1\quad \text{for all $ t>\mu$,}\end{equation}
and
 \begin{equation} \Omega_X(t) \ge \Omega_Y(t)>1\quad \text{for all $ t<\mu$.}\end{equation}
Let
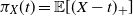 $\pi_X(t)=\mathbb{E} [(X-t)_+]$
and
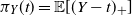 $\pi_Y(t)=\mathbb{E} [(Y-t)_+]$
denote the stop-loss transforms of X and Y, respectively. Then
 $X\le_{\mathrm{dil}} Y$
if and only if
 $\pi_X(t)\le \pi_Y(t)$
for all
 $t\in\mathbb{R}$
(see [Reference Shaked and Shanthikumar16, Theorem 3.A.1]). On the other hand, observe that
 \begin{equation} \Omega_X(t) = \dfrac {\pi_X(t)}{t-\mathbb{E} [X] + \pi_X(t)},\quad t\in\mathbb{R},\end{equation}
and hence
 \begin{equation*} \pi_X(t) =\dfrac {\Omega_X(t) (t-\mathbb{E} [X])}{1-\Omega_X(t)}, \quad t\ne \mathbb{E} X.\end{equation*}
Therefore both (4.5) and (4.6) hold if and only if
 $\pi_X(t)\le \pi_Y(t)$
for all
 $t\in\mathbb{R}$
. Thus the desired result of the proposition follows.
It should be pointed out that Proposition 4.1 was also proved in [Reference Eberl and Klar8] via a different method. Properties ES1, ES2, and ES3 in Section 3 also hold for the ex-dispersive order.
5. Remarks
From Theorem 3.B.16 in [Reference Shaked and Shanthikumar16], it follows that if
 $X \le_{\operatorname{Q-disp}} Y$
for
 $X, Y\in L^1$
, then
 $X\le_{\mathrm{dil}} Y$
. Thus we can summarize the relationships among the Q-dispersive, ES-dispersive, ex-dispersive, and dilation orders in the following diagram:
 \begin{align*}\begin{array}{c@{\quad}c@{\quad}c@{\quad}c@{\quad}c}X\le_{\operatorname{Q-disp}} Y\! & \!\Longrightarrow\!\! & \!\! X\le_{\mathrm{dil}} Y\!\! & \!\!\Longleftrightarrow & \! X \le_{\operatorname{ES-disp}} Y\\ & & \Updownarrow & & \\ & & X \le_{\operatorname{ex-disp}} Y & &\end{array}\end{align*}
In practice, the inter-quantile, inter-ES, and inter-ex differences are used to measure variability of different random variables or real data. The characterization results in this paper suggest that instead of comparing the performance of the parametric measures based on the inter-ES and the inter-ex differences, we only need to test whether the dilation ordering exists between two different (empirical) distributions.
Remark 5.1. If
 $\mathbb{E} [X]=\mathbb{E} [Y]$
, then
 $X \le_{\operatorname{ex-disp}} Y$
if and only if
 \begin{equation*} \begin{aligned}&\text{$\mathrm{ex}_\alpha(X)\ge \mathrm{ex}_\alpha(Y)$ for each $\alpha\in (0,1/2)$,} \\ &\text{$\mathrm{ex}_\alpha(X)\le \mathrm{ex}_\alpha(Y)$ for each $\alpha\in (1/2,1)$.} \end{aligned}\end{equation*}
This means that a necessary and sufficient condition for the ex-dispersive order is the convex ordering of both the left deviation from the mean and the right deviation from the mean. Bellini, Klar, and Müller [Reference Bellini, Klar and Müller3] introduced the expectile order on random variables on
 $L^1$
, defined by
 $X\le_{\mathrm{e}} Y$
if
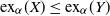 $\mathrm{ex}_\alpha(X)\le \mathrm{ex}_\alpha(Y)$
for each
 $\alpha\in (0,1)$
. In the equal mean case, it is pointed out in Corollary 13 of [Reference Bellini, Klar and Müller3] that a necessary and sufficient condition for the expectile order is the concave ordering of the left deviation from the mean and the convex ordering of the right deviation from the mean.
Remark 5.2. In general, for
 $X_1, X_2\sim L^1$
,
 $X_1\le_{\mathrm{dil}} X_2$
does not imply
 \begin{equation} \mathrm{ex}_\beta(X_1) -\mathrm{ex}_\alpha(X_1) \le \mathrm{ex}_\beta(X_2)- \mathrm{ex}_\alpha(X_2)\quad \text{for all $ 0<\alpha\le \beta<1$.}\end{equation}
This is why we impose the restriction ‘
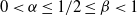 $0<\alpha\le 1/2\le\beta<1$
’ in Definition 2.3.
To see (5.2), let
 $X_i\sim F_i$
with
 $F_i$
belonging to the family of Lomax or Pareto type II distribution, given by
 \begin{equation*} F_i(t)\,:\!=\, F(t;\, \alpha_i, \lambda_i)=1-\biggl(1+\dfrac {t}{\lambda_i}\biggr)^{-\alpha_i}, \quad t\ge 0,\end{equation*}
where
 $\lambda_i>0$
and
 $\alpha_i>1$
for
 $i=1,2$
. It is known from [Reference Bellini, Klar and Müller3] that
 $F_1\le_{\mathrm{cx}} F_2$
and
 $F_1\ne F_2$
if and only if
 \begin{equation} \alpha_1>\alpha_2>1,\quad \dfrac {\alpha_1-1}{\alpha_2-1} =\dfrac {\lambda_1}{\lambda_2},\end{equation}
and that
 \begin{equation} F_1\le_{\mathrm{st}} [\!\le_{\mathrm{hr}}]\ F_2\ \ \Longleftrightarrow\ \ \alpha_1 \ge \alpha_2>0,\ \ \dfrac {\alpha_1}{\alpha_2} \ge \dfrac {\lambda_1}{\lambda_2}.\end{equation}
Also, the stop-loss transform of
 $F_i$
is given by
 \begin{equation*} \pi_i(t)=\dfrac {\lambda_i}{\alpha_i-1} \biggl(1+\dfrac {t}{\lambda_i}\biggr)^{1-\alpha_i}= \dfrac {\lambda_i}{\alpha_i-1} {\overline{F}}(t;\,\alpha_i-1,\lambda_i),\quad t\ge 0.\end{equation*}
Now assume that (5.2) holds. Then
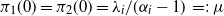 $\pi_1(0)=\pi_2(0)=\lambda_i/(\alpha_i-1)\,=\!:\, \mu$
, and
 $\pi_1(t)<\pi_2(t)$
for
 $t>0$
, where the last inequality follows from (5.3) and the fact that the hazard rate function
 $h_1(t)$
of
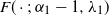 $F(\cdot;\, \alpha_1-1,\lambda_1)$
is larger than the hazard rate function
 $h_2(t)$
of
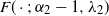 $F(\cdot;\, \alpha_2-1,\lambda_2)$
for
 $t>0$
. Thus, from (4.7), it follows that
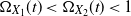 $\Omega_{X_1}(t)<\Omega_{X_2}(t)<1$
for
 $t>\mu$
, and
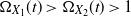 $\Omega_{X_1}(t)>\Omega_{X_2}(t)>1$
for
 $t\in (0, \mu)$
. By exploiting (4.1), this in turn implies that
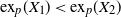 $\mathrm{ex}_p(X_1)< \mathrm{ex}_p(X_2)$
for
 $p\in (1/2, 1)$
, and
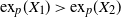 $\mathrm{ex}_p(X_1)> \mathrm{ex}_p(X_2)$
for
 $p\in (0, 1/2)$
. Since
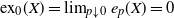 $\mathrm{ex}_0(X)=\lim_{p\downarrow 0} e_p(X)=0$
and
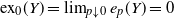 $\mathrm{ex}_0(Y)=\lim_{p\downarrow 0} e_p(Y)=0$
, we conclude that the strict inequality in (5.1) holds for
 $\beta\in (1/2,1)$
and
 $\alpha$
small enough, while the strict inverse inequality in (5.1) holds for
 $\beta\in (0, 1/2)$
and
 $\alpha$
small enough.
Another interpretation of (5.1) for
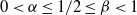 $0<\alpha\le 1/2\le\beta<1$
when
 $X_1\le_{\mathrm{cx}} X_2$
is as follows. It is known that the expectile
 $\mathrm{ex}_p({\cdot})$
is consistent with the convex order for
 $p\in [1/2,1)$
, and is consistent with the concave order when
 $p\in (0,1/2]$
(see e.g. [Reference Bellini, Klar and Müller3]). Recall that X is smaller than Y in the concave order if and only if Y is smaller than X in the convex order. As a consequence, differences of the form
 $\mathrm{ex}_\beta({\cdot}) - \mathrm{ex}_\alpha({\cdot})$
are consistent with the convex order only when
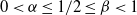 $0<\alpha\le 1/2\le \beta<1$
. This interpretation also applies to Proposition 4.1.
Example 5.1 (Location-scale families.) Let X and Y be two random variables with respective distribution functions F and G from the same location-scale family, namely
 \begin{equation*} F(x)= H\biggl(\dfrac {x-\mu_X}{\sigma_X}\biggr), \quad G(x)= H\biggl(\dfrac {x-\mu_Y}{\sigma_Y}\biggr),\end{equation*}
where
 $\sigma_X>0$
,
 $\sigma_Y>0$
, and H is the distribution function of a risk variable
 $Z\in L^1$
. A necessary and sufficient condition for
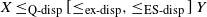 $X \le_{\operatorname{Q-disp}} [\!\le_{\operatorname{ex-disp}}, \le_{\operatorname{ES-disp}}]\,Y$
is
 $\sigma_X\le \sigma_Y$
, since
 \begin{align*} \mathrm{VaR}_\beta(X) -\mathrm{VaR}_\alpha(X)& =\sigma_X [ \mathrm{VaR}_\beta(Z) -\mathrm{VaR}_\alpha(Z)],\\ \mathrm{ex}_\beta(X) -\mathrm{ex}_\alpha(X))& =\sigma_X [ \mathrm{ex}_\beta(Z) -\mathrm{ex}_\alpha(Z)],\\ \mathrm{ES}_\beta(X) -\mathrm{ES}_\alpha(X))& =\sigma_X [ \mathrm{ES}_\beta(Z) -\mathrm{ES}_\alpha(Z)]\end{align*}
for
 $0<\alpha<\beta<1$
. In particular, let H denote the standard uniform, exponential, or normal distribution functions, respectively. Then we have
 \begin{align*} U(a_1, b_1)\le_{\operatorname{Q-disp}} [\!\le_{\operatorname{ex-disp}},\le_{\operatorname{ES-disp}}\!]\, U(a_2, b_2) &\Longleftrightarrow b_1-a_1\le b_2-a_2,\\ \mathrm{Exp}(\lambda_1) \le_{\operatorname{Q-disp}} [\!\le_{\operatorname{ex-disp}},\le_{\operatorname{ES-disp}}\!]\, \mathrm{Exp}(\lambda_2) & \Longleftrightarrow \lambda_1\ge \lambda_2>0,\\ N(\mu_1, \sigma_1^2)\le_{\operatorname{Q-disp}} [\!\le_{\operatorname{ex-disp}},\le_{\operatorname{ES-disp}}\!]\, N(\mu_2, \sigma_2^2)& \Longleftrightarrow \sigma_1^2\le \sigma_2^2.\end{align*}
Acknowledgements
We thank the two anonymous reviewers for their constructive and helpful comments. In particular, we thank one of the reviewers for pointing out [Reference Eberl and Klar8] to us.
Funding information
T. Hu was supported by the NNSF of China (no. 71871208) and by the Anhui Center for Applied Mathematics. W. Zhuang was supported by the NNSF of China (no. 71971204).
Competing interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


