


Despite the severe aftermath of the crises of the 1870s, banking activity within Latin American countries picked up with renewed strength in the 1880s as a financial transformation took place that was led by the dynamism of national banks. Previously only a half-dozen nations in this vast region had experienced the first stages of a banking revolution, but by the end of the nineteenth century a growing number of financial firms – large and small – emerged in the more dynamic economic zones of Mexico, Central America, the Caribbean and throughout most of South America.Footnote 1 But perhaps the most striking feature in the 1880s was the consolidation of large banks that created networks of branches. These enterprises surpassed earlier firms in size as well as in their greater capacity to provide credit. Their broader geographical reach was the result of the establishment of numerous offices and agencies in capital cities as well as in regional centers, where the big banks were determined to force entry in order to capture clients and business of diverse types. Regardless of whether these entities were founded as private, public or mixed companies, they generally became the largest financial organizations in nations such as Argentina, Brazil, Chile, Colombia, Mexico and Uruguay, but also in Bolivia, Haiti, Santo Domingo and Costa Rica, during the last decades of the centuryFootnote 2 (see Table 6.1).
Banco do Brasil (1851–1893)Footnote a
Banco Nacional de Chile (1865–1893)Footnote b
Banco Nacional del Perú (1872–1880)
Banco Nacional (Argentina) (1872–1890)Footnote c
Banco Nacional de Colombia (1880–1894)
Banco Nacional de México (1884–2026)
Banco de la Unión de Costa Rica (1877–1890)Footnote d
Banco Nacional de Guatemala (1874–1876)
Banque Nationale d’Haití (1880–1911)
Banco Nacional de Uruguay (1887–1891)
Banco Nacional de Paraguay (1883–1890)
Banco Nacional de Santo Domingo (1889–1914)
Banco de Venezuela (1890–2026)
* In this table we include banks in Latin America that identified themselves as national banks (the majority being privately owned) toward the end of the nineteenth century – with the right to issue banknotes and generally maintaining close relationships with the respective governments.
a The Banco do Brasil merged with other banks in 1893 and then closed its doors in 1900, reopening in 1906, and it continues to operate today as the largest commercial bank in Brazil.
b The Banco Nacional de Chile merged with two other banks in 1893 and formed Banco de Chile, which has been one of the largest in the country since then and until the present day.
c After the bankruptcy of the Banco Nacional de Argentina in 1890, the Banco de la Nación Argentina was created in 1891, reactivating many of the old branches of its predecessor; today, the Banco de la Nación Argentina remains the largest bank in Argentina.
d The Banco de la Unión de Costa Rica changed its name to the Banco de Costa Rica in 1890 and has continued to operate to the present day.
The birth and trajectories of the largest national banks took place at a series of historical crossroads that were characterized by the modernization of state administrations, in parallel to the launching of important development projects throughout Latin America precisely at a time when national identities began to strengthen. Gradual economic integration, the reform of monetary regimes and the shaping of financial systems went hand in hand. While each of these trends involved specific arenas of political and economic negotiation, all were part and parcel of the process of nation-building. Each of the so-called national banks emerged in a particular context and assumed specific tasks, but practically all contributed to the extension of credit for both public and private sectors, while they also facilitated the gradual integration of payments systems, prompted the use of banknotes and provided financial services to governments. In some cases a given bank would be awarded a monopoly of the issue of banknotes but, often enough, plurality of issue remained common. In any case, it should be emphasized that while the large banks maintained close relations to the state, they were not central banks, since the latter did not begin to be established in Latin America until the mid 1920s.Footnote 3
The creation of national banks in many countries of the hemisphere during the last quarter of the nineteenth century raises several major questions, beginning with the issue of why there should have been such enthusiasm for the promotion of this type of financial enterprise based on official concessions that offered numerous privileges.Footnote 4 A first hypothesis concerns the interests of political and economic elites who wished to profit from taking control of the growing financial requirements of governments that were experiencing political changes in the process of consolidation of nation-states. The 1880s marked the zenith of a number of strong political and military leaders in most of Latin America, figures who had the capacity to submit regional elites and integrate them into nominally liberal political projects, although espoused by authoritarian regimes. Forceful personalities such as General Julio Roca, who was president of Argentina in the years 1880–1886, or General Porfirio Diaz in Mexico, long-time autocratic ruler of Mexico from 1876 to 1910, stood out. But so did the conservative, centralist politician Rafael Nuñez in Colombia (1880–1886), and the popular but highly controversial President José Manuel Balmaceda in Chile (1886–1891), to mention only a few of the various architects of a new political order in Latin America that was characterized by parliamentary and constitutional regimes that were clearly conservative and oligarchic, but at the same time modernizing and increasingly capitalist.
The push for authoritarian modernization was reflected in the famous motto “order and progress,” the leitmotif of economic policy adopted by the most stable and solid government of the Latin American region, the imperial government of Brazil. The force of political centralism was clearly reflected in the 1880s by the transformation of many capitals in Latin America into thriving European-style metropoles. Ambitious urban development projects in Rio de Janeiro, Buenos Aires, Mexico and other cities unfolded, shaping what was termed as the belle époque. Public works, the design of large avenues and parks, the construction of new buildings for government ministries and legislatures, national libraries, national museums and national archives, new installations for professional armies and navies, schools, scientific institutes and lavishly designed railway stations reflected confidence in progress and nationalism, both fundamental values of the time.
The promotion of national banks was near the top of the list of economic priorities adopted by most of the powerful autocrats who headed parliamentary regimes bent on the modernization of their administrations as well as their societies and economies. Latin American elites looked to Europe for new models of governance as they were cognizant of the fact that the consolidation of national administrations in Europe had gone hand in hand with the establishment of large banks in close relation to states.Footnote 5 The pioneering roles of the Bank of Sweden (1668) and the Bank of England (1694) were clearly influential, being among the oldest in the world. But Latin American elites, especially leading merchants and private bankers, were also aware of the prestige of institutions such as the Banque de France (1800) and the Oesterreichische Nationalbank of Austria (1818). Equally important were examples of large banks established after 1850 in other European nations.Footnote 6 A significant example was the foundation of the Banque Nationale de Belgique (1850), which eventually became a central bank, but actually began as a firm dedicated to commercial banking operations. More imposing was the Reichsbank of Germany, created in 1875 as a consequence of the union of the German states and the launching of the first Reich by Bismark. Similarly, news spread of the transformation of the Bank of Spain into the dominant institution within the Spanish financial system as a result of the political crisis of 1874, which inaugurated a long-lasting conservative regime.Footnote 7
Latin American professional and economic elites interested in financial reform were becoming aware of innovations in monetary and banking legislation in Europe but also in the United States. Frequent reference was made in the press and journals of Argentina, Brazil and Mexico to the multiple national banks of the United States, although these were relatively small entities and operated within a very different institutional framework from that of the great national banks of European states. Not surprisingly, the concrete experiments of the Latin American elites with banks reveal distinctive circumstances in the manner in which they proposed the design of the institutional frameworks of their emerging banking systems and regimes, as well to put in place the operational structure of the principal entities.
In short, the creation of national banks from the 1870s in Latin America represented a significant innovation within the gradual process of capitalist development and state modernization. Some were public banks but most were privately owned. Practically all had privileges of banknote issues, and several were charged with the management of government accounts as well as the negotiation and service of public debts. Nonetheless, they were hard put to fulfill the role of lender of last resort, since they were not central banks. As commercial banks, they attracted numerous private clients who opened deposit accounts and took loans, yet they also frequently operated as investment firms and, in some cases, carried on a significant mortgage business. In general, the national banks played an important role in expanding monetary circulation through the introduction and increasingly widespread use of banknotes, as well as by the extension of their credit facilities, stimulating the gradual integration of financial markets in various countries. Their activities were part of a process of economic growth generated primarily by agricultural and mining exports, accompanied by urban and railway expansion. Nonetheless, the new national banks were not necessarily well prepared to confront local financial crises, nor the sequence of booms and busts that were characteristic of the spread of capitalism almost everywhere. In fact, a good number of the larger banking enterprises that came of age in Latin America during the 1880s would face enormous stress as a result of extensive financial and debt crises in the 1890s and, in some cases, collapsed.
In most historical studies the establishment of a large bank with close ties to governments has often been attributed to the special benefits granted by a given state to such an enterprise, almost always closely controlled by financial and political elites.Footnote 8 Yet the study of these banking enterprises makes it evident that there is a need for additional studies on the debates and policies that led to the genesis of the new financial institutions and enterprises. This is a field that has only recently been broached in Latin American political and economic historiography and should prove to be a fertile arena of future research not only by economic historians but by political scientists and sociologists interested in analyzing the complex dynamics that connect politics, economics and finance.
National Banks and Government: A Two-way Relationship
The emergence of increasingly complex banking systems in Latin America in the late nineteenth century cannot be understood without thoroughly examining the relationship between the government and one or two major banks that occupied a most influential place within the respective financial regime of most nations in this era. The preeminent role of such banks was largely the result of the charters granted them by the respective government as a result of complex negotiations between political and financial elites who bargained hard for privileges regarding the issue of bank notes as well as the management of fiscal and public debt accounts. We follow here the interpretations of Calomiris and Haber in their path-breaking work Fragile by Design.Footnote 9
The banks closest to the government inevitably benefited from public business, but politicians also frequently gained much from the access to credit for their own private business. In addition, it should be borne in mind that there generally did not exist strict regulations or methods of supervision of banks at this time, although some early banking laws provided guidelines. The individual charters were firm-specific and thus largely dependent on bank managers and directors to maintain observance of relatively limited sets of operating rules. The influence exerted over the largest banking enterprises by political leaders and/or lobbies in most Latin American nations was a common feature of the age, and opportunities to obtain large profits through nontransparent business transactions and insider lending by both financiers and politicians proved inexorable. Financial public and private affairs were mixed and symbiotic.
The larger banks generally extracted considerable benefits from their privileged positions as government financial agents, as managers of government fiscal accounts and as agents for negotiation and service of domestic and/or foreign public debts. The privileges granted to banking firms with regards to the issue of banknotes provided economic power since this allowed them to control a large share of the currency in circulation. In the following pages, we detail the relative proportions of issue of banknotes by the various larger banks in the case of Argentina, Brazil, Chile and Mexico. Their preponderance in this realm reflected not only the fact that the national banks exercised key functions in public finance, but also their role as leading commercial banks.
At the same time, it is important to ask whether the quite concentrated banking structures that emerged in many Latin American countries during the late nineteenth century were economically beneficial in the long run. The issue of the interlocking nature of financial and political elites is raised by Calomiris and Haber in their innovative work, which reviews the comparative historical banking experiences in five countries – Great Britain, the United States, Canada, Mexico and Brazil.Footnote 10 They highlight the relationship between entrepreneurs and politicians, the design of bank contracts and the institutional framework that served as the foundation of banks, the banking system and economic performance over time. The main argument advanced by the authors is that in the long run, democratic regimes tend to produce more stable banking systems and, furthermore, are likely to better fulfill the credit demand requirements of the local economy. In contrast, they argue that authoritarian political regimes tend to foster the establishment of oligopolistic banking systems and shallow credit markets, which impose restrictions on credit supply, giving priority to the interest of powerful coalitions of politicians and economic elites, inducing inequality in political, economic and social terms.
Following this argument, it would be natural to expect that toward the end of the nineteenth century most of the Latin American countries would have followed similar paths, including predominance of banking enterprises and institutions linked to authoritarian government and dominant oligarchies, albeit within parliamentary regimes. The hypotheses advanced by Haber and Calomiris can prove useful to explore the dynamics of both Latin American political power and banking structures yet need specific validation. In this sense, we believe that a comparative approach requires much empirical research to reach more specific conclusions. National case studies reveal significant nuances in the relationships between policy and banking, with substantial variations, depending on both political and economic circumstance.Footnote 11
It is also possible to argue that beyond politics and elite power struggles, organizational theory also indicates that the establishment of national banks was linked to state modernization. The spread of branch banking helped improve government fiscal and financial administration, contributing to the introduction of reforms in tax-collection systems as well as the possibility to make payments more efficiently throughout the respective national territory, besides allowing for the adoption of new accounting methods that permitted a more detailed tracking of budgets and public debts. In this sense, the creation of national banks with numerous branches represented institutional innovations in fiscal management with generally positive effects on the administration and management of state finances. This was also related to the expansion of banking networks that were put in place quickly, as can be seen in the case of the Banco Nacional de Argentina, which set up more than twenty branches in different provinces between 1872 and 1885. In the case of Mexico the process was slower, but even so it may be noted that the establishment of the Banco Nacional de México in the nation’s capital 1884 also impelled the expansion of branches in six of the most economically important cities in the country as well as offices and agencies in many other urban centers.
The creation of large modern banks provided diverse administrative and financial benefits for governments. For example, public accounting methods utilized by the different ministries of finance improved substantially as public officials became familiar with the accounting methods used by the banks, allowing greater precision, punctuality and centralization in the collection and disbursement of public income and expenditures. Improvements in the management and analysis of information on fiscal and financial revenues enabled treasury ministers to better evaluate overall trends in public finances and their relationships with the economy.Footnote 12 Governments also were now able to obtain short- and medium-term domestic credit more reliably and at more reasonable interest rates. In some cases, the improvement of collection and administration of fiscal income went hand in hand with a better management of domestic debt, resulting in lower interest rates and reducing dependency on private speculators (agiotistas), commercial houses or large individual lenders.Footnote 13 This fact suggests that the institutional and operational frameworks of the largest banks in Latin America of this era were shaped in part by the fiscal and financial needs of the national administrations but that the process was reciprocal, since the creation of the banks simultaneously contributed to facilitating state reforms.
The creation of enterprises such as the Banco do Brasil, the Banco Nacional de Argentina, the Banco Nacional de Chile or the Banco Nacional de México, among other large banking firms, propelled a downward trend in information and money costs for the respective governments, as well as for private enterprise. It should be noted, however, that the relations between large banks and governments took somewhat different paths. For instance, the Banco do Brasil (1853) and the Banco Nacional de México (1884) were private firms that managed financial operations both for the private sector and for governments. In contrast, the Banco Nacional de Argentina (1872) was more of a public bank, insofar as the government participated in its capital structure since its foundation but, even so, commercial operations with private clients were also a prominent feature of its activities. Evidently, the national banks exhibited distinct political and entrepreneurial components, as well as different institutional frameworks. Their study can illustrate the complex relations between early capitalist development and administrative modernization, exhibiting numerous parallels and contrasts, as well as successes and failures.
The Large Banks, Capitalists and Financial Development in the Late Nineteenth Century
The new banking enterprises initially prospered as a result of the expansion of financial markets within Latin America in the late nineteenth century. Stock markets experienced a golden age in several countries during the late 1880s, and allowed for the establishment and growth of numerous joint-stock companies. As joint-stock companies, the banks sold their stock on local markets, mainly to the wealthiest members of society. In this sense, it can be argued that a high degree of banking concentration in the ownership of the privileged institutions contributed to the disproportionate economic strength acquired by certain sectors of the financial, mercantile and landowning elites in Latin America during the late nineteenth century.
The performance of the banks improved as a result of the marked increase in the financial information provided by the local commercial newspapers during the 1880s. The burgeoning economic press included regular information on the trends of both international and domestic financial markets including stock market quotations, interest rates and information on public debts, as well as commercial, agricultural, mining and manufacturing data, allowing for more accurate diagnoses of business cycles. In Brazil the Almanak Laemmert, Administrativo, Mercantil e Industrial do Río de Janeiro (1844–1901) continued to be a fundamental source of business news but was enhanced substantially from the 1870s as a result of new transatlantic telegraph connections, which also benfitted other leading newspapers in the Brazilian capital, such as the Jornal do Comercio (1827–2016) and The Rio News (1874–1901). This was also the case in Chile, where El Mercurio (1827–1900) and El Ferrocarril (1855–1910) also modernized during the latter part of the century and provided increasing quantities of commercial and financial information. In Argentina, up-to-date news on international trade and finance was published by The Buenos Aires Standard and River Plate News (1861–1959), but also by newspapers like La Nación and others. In Mexico, La Semana Mercantil and El Economista became the most important sources of economic information from the 1880s. These innovations in access to financial data and analysis substantially reduced the information costs related to the price of money (present and future), creating new opportunities and incentives for private economic agents – and especially banks – with regard to decisions on credits, loans and investments.
Apart from the role of national banks as de facto government banks, these enterprises were also profitable for the groups that controlled them, from an entrepreneurial perspective. The commercial banks offered new financial capabilities that surpassed those of traditional merchant bankers that operated domestically. The new entities contributed to the adoption of technical and organizational innovations that far exceeded the capabilities of private or family firms of bankers. Other features of the establishment of large joint-stock banks included the departmental organization, which separated functions more clearly, including the management of deposits, savings accounts, credit and loans as well as reserves. In addition, the national banks were especially effective in spreading the use of fractional reserve money issue (bank bills), an innovation that some authors consider a revolution in financial markets, although it should be underlined that the banks were used mainly by economic elites and state administrations. The banknotes contributed to the creation of new forms of money and their circulation, whether as a consequence of the issuance of bank notes or from the discount facilities that expanded as deposits increased, increasing sources of credit and giving rise to broader circles of clients.
The establishment of large banks with numerous branches ran parallel to a series of entrepreneurial, technological and institutional reforms in the fields of communications and transport, advancing rapidly in the larger Latin American nations during the last quarter of the nineteenth century. The development of branch banking systems in the last quarter of the century almost always accompanied the introduction of telegraph networks and railroad lines, as was common in the United States.Footnote 14 Bank offices or agencies were frequently set up in those towns or cities where there were railway stations, as can be seen in the cases of Argentina, Brazil, Chile or Mexico. In short, the new financial and communications technologies fostered the gradual integration of regional markets and also directly influenced the integration of fiscal and military administrations.
The strategic roles played by railroads, telegraphs and banks in the strengthening of Latin American governments may be highlighted by focusing on reciprocal relationships. For instance, military administrations were able to better confront regional insurrections as a result of the building of railways since they facilitated the logistics involved in the movement of soldiers and officers as well as transport of weapons and, in parallel form, the new banks helped the transfer/payment of salaries, thereby increasing loyalty and efficiency. It was not surprising, therefore, that from the 1880s there was a reduction in provincial rebellions that had been frequent in previous decades, often provoked by the battles for fiscal and financial resources by discontented regional groups of politicians and military officials, a key feature and cause of political instability in the early nineteenth century.
Reciprocally, after the 1880s, greater military and political stability reinforced financial modernization. The new bank networks contributed to the growth of credit and financial markets and also propitiated the economic integration of regional markets. This argument runs somewhat counter to the traditional focus of much economic history in Latin America that argues that governments were the main initiators and protagonists of economic development in the belle époque, for instance, by promoting foreign investments or public works or establishing new regulatory frameworks for enterprise. On the other hand, it can also be argued that banking enterprises and other companies, such as the railroads, played a decisive role in driving forward what were the increasingly modern states, economies and societies in the region.
Generally speaking, the larger domestic banks took over at least a part of the management of the rapidly growing domestic and external debts and helped to improve debt service performance, carrying out payments on a more regular basis in gold. What is more, the national banks proved to be key instruments for obtaining the long-term finance required by urban development projects, port modernization or the building of state railways, all involving large disbursements of cash as well as the acquisition of capital goods and equipment from abroad. The banks collaborated with financial ministers in negotiating large loans with European bankers, who eagerly promoted the sale of external gold bonds of Argentina, Brazil, Chile, Mexico and many other Latin American states on the capital markets of London, Paris, Berlin, Brussels and Amsterdam.Footnote 15
The formidable inflows during the 1880s of portfolio capital into the Latin American markets and state treasuries marked a high point in the early globalization of investment and debt instruments, but major economic challenges were not absent in this era, especially in regard to international economic trends. Among the most formidable was the need to deal with the contradictory impact of the considerable volume of foreign capital that arrived on an unprecedented scale as a result of foreign direct investments, as well as inflows of funds from government debt sold abroad. These surges could generate acute challenges for banks and governments particularly at times of local or international financial crises that spurred inverse flows of capital flight.
The national banks were heavily involved in the financial euphoria that, often as not, led to extraordinary corruption as a result of insider lending and speculation in real estate markets. Much of the financial frenzy was stimulated by the mortgage business of the larger banks, as well by outright gambling in the local stock exchanges. The booms continued until the outbreak of financial crises in the early 1890s that battered the economies of Argentina, Uruguay and Brazil with extreme severity, but did not spare smaller countries.Footnote 16 Inevitably, many banks collapsed and financial recovery proved slow and uneven, a fact that reflected the fragility of capitalist development in Latin America in this era.
In order to unravel aspects of the complex relationships between states, economies and national banks during this age it is necessary to provide some concrete historical examples that can stimulate new questions and research, particularly from a comparative perspective.Footnote 17 Such an approach requires examination of some of the principal similarities as well as differences between the size and structure of the main banks in different countries. This is the purpose of the remainder of this chapter. We pay special attention to the specific cases of Brazil, Chile and Argentina, using the rich comparative data found in official reports published during the 1880s, as well as a range of complementary primary and secondary sources.Footnote 18 In the closing section we also direct attention to the creation of a powerful national bank in Mexico in the 1880s and its impressive trajectory.
The Banking System of Brazil in the Last Quarter of the Nineteenth Century
In some Latin American countries, the idea of a national bank had already led to the establishment of important institutions before the last quarter of the nineteenth century. In Brazil, the birth of banking had proved somewhat more precocious than in other nations of the region. We may recall that the Banco do Brasil was refounded in 1853 and was already in the process of becoming a kind of national bank from an early date. As Thiago Gambi has argued, this enterprise was a major power in Brazilian banking since the mid 1850s and would continue to be so for a long time.Footnote 19 On the basis of research carried out by the pioneering financial historian María Barbara Levy, it is possible to observe the trajectory of the Banco do Brasil within the banking market of the capital Rio de Janeiro between 1854 and 1888 in regard to deposit banking (see Figure 6.1). Initially, it appears that other banks attracted more clients but in the last quarter of the century the preeminence of the Banco do Brasil became ever more notable, despite the fact that other banking enterprises emerged in both the capital and in São Paulo.
Share of the Banco do Brasil in total Rio de Janeiro banking deposits, 1854–1888 (contos de réis).

Figure 6.1 Long Description
It includes two separate data series: Total deposits in the entire Brazilian banking system (plotted with a thick black line and filled circular markers). Deposits specifically in the Banco do Brasil (plotted with a thinner dark gray line and filled circular markers). Both data series are represented in contos de réis.
The Banco do Brasil, however, was not a public bank, but rather owned by the principal merchants and financiers of Rio, as well as by important sectors of the coffee plantation owners. Its ties to the government had been severely weakened during the Paraguayan War, when the Ministry of Finance rescinded the bank’s right to issue banknotes, which then became a monopoly of the state Treasury that simply issued convertible paper money. Nonetheless, after 1879 relations between the government and the Banco do Brazil improved. The latter collaborated increasingly with the Ministry of Finance and opened an account for the Treasury with credits for large sums. Reciprocally, the government now began to deposit all surplus at the bank, as did the principal customs offices. Simultaneously, the bank began to operate as an agent for the state in negotiating loans on European markets, several of them used to improve the value of the Brazilian milreís, facilitating the exchange operations of the imperial government of Brazil. These were key functions carried out by the bank, which still had a small staff of barely forty-seven functionaries at its head office as of 1880. Despite the small size of this financial enterprise, it played a crucial role in the economy.Footnote 20
After the end of the war with Paraguay in 1870, there still circulated a large volume of banknotes that had been issued in previous decades and remained crucial to the payments systems in Brazil. From 1880 the government gradually adopted more flexible policies to allow for a small increase of monetary circulation, but until 1887 only three banks, the Banco do Brasil and two mortgage banks, circulated banknotes widely in financial markets, a fact that clearly gave these entities special advantages (see Figure 6.2). Nonetheless, it should be mentioned that there also existed an additional fifteen commercial banks in Rio de Janeiro, and several more in cities such as Bahía and São Paulo. These entities carried on a brisk business based on the discount of commercial paper on a short-term basis, using the rising volume of such trade bills to sustain credit operations, at the same as they invested some of their capital in a variety of investments. But those same banks faced limits to their expansion because of the lack of capacity to issue banknotes.Footnote 21
Share of total banknote issues in Brazil, 1887.

Figure 6.2 Long Description
The chart consists of two circular diagrams joined by a thin diagonal line, showing a comparison of the share of total banknotes issued in Brazil since 1887. The large circular diagram on the left shows that Banco do Brasil held 62 percent of the banknotes issued, while the smaller circular diagram on the right breaks down the Other category into Banco Hipotecario de São Paulo with 19 percent and Banco Hipotecario Brasileiro with 18 percent of the banknotes issued.
It should be noted that while the monetary and banking system in Brazil had a basically conservative and oligopolistic character, it was bound to be modified as a result of the major socioeconomic developments taking place in the 1880s.Footnote 22 These changes were driven most forcefully by the rapid expansion of coffee production and exports in the provinces of São Paulo and Minas Gerais, which became the new locomotives of the Brazilian economy, replacing the declining coffee plantations of the great Paraíba Valley, proximate to Rio de Janeiro. As a result, the emerging mercantile and coffee oligarchies of São Paulo and Minas Gerais began to challenge the elites of Rio and pressed for financial reforms. But there was another equally important process that was taking place: namely, the burgeoning of a series of movements in favor of the abolition of slavery. In fact, manumission proved inevitable as a result of the aging of the slave population and the virtual end of the internal slave trade that had transferred tens of thousands of slaves from the old sugar plantations in the northeast to the coffee plantations of central-southern Brazil during several decades.
Despite the growing force of abolition, the Banco do Brasil itself remained heavily engaged in mortgages of old plantations, using slaves as collateral until the year 1884. According to William Summerhill, in 1880 this large bank held mortgages on 346 plantations (fazendas) in the classic coffee districts of the province of Rio de Janeiro, the collateral of which included nearly 19,000 slaves.Footnote 23 The Banco do Brasil was, therefore, overloaded with mortgages on large but declining rural properties. It also held dozens of mortgages in the more dynamic provinces of São Paulo and Minas Gerais, but these were also confronted with acute problems, as slaves began to be freed. Nonetheless, this powerful bank continued to benefit from a large volume of deposits provided by the mercantile and professional classes of the capital at Rio, since they continued to be loyal to an entity that was a close ally of the imperial government. The abundance of deposits allowed the bank to carry on an important discount business for commercial and early industrial firms, for some railways, as well as for agricultural companies.Footnote 24 Nonetheless, the Banco do Brasil was a rather staid organization that some foreign observers considered inefficient.
Rivals to the Banco do Brasil began to appear in the late 1880s and soon built special relations with the government. One of the first was the Banco Internacional do Brazil, founded in 1886 in Rio de Janeiro by the influential entrepreneur Viscount Francisco Figueiredo, who soon came to be a key partner of European banks in the negotiation of foreign investments as well as public debts of Brazil.Footnote 25 Figueiredo was a leading coffee export merchant, president of a major waterworks company in Rio and director of important railroad enterprises, such as the Estrada de Ferro Dom Pedro II. He is remembered as a promoter of the abolition of slavery but also as a monarchist. In the last years of the Empire, Figueiredo helped to ratify important financial reforms that allowed for the concession of short-term bank loans to the government as well as the reduction of the external debt service, in good measure as a result of his close relations with leading Paris investment banks and London merchant banks, including the firms of N. M. Rothschild and Morton Rose, both involved in the placement and service of Brazilian external debts.
Figueiredo pressed for the creation of a private central bank, based on European models, with the aim of having it act as lender of last resort and serve as agency for the Treasury and regulator of the money market. In June 1889, the minister of finance, Viscount Ouro Preto, promoted the reform of the banking law of 1888 with regulations that allowed for the creation of a new issuing bank to be called the Banco Nacional do Brasil, whose banknotes were to be backed by government currency and bonds, and which was to help retire the bulk of Treasury notes in circulation.Footnote 26 The new bank absorbed the Banco Internacional, headed by Figueiredo, and soon opened offices in both Rio de Janeiro and Paris. The powerful Banque de Paris et Pays Bas (Paribas) was charged with issuing half of the huge original capital of 10 million pounds sterling of the Brazilian bank on European capital markets.Footnote 27
The objective of Prime Minister Ouro Preto in granting such important financial concessions to Figueiredo was part of his strategy to assure the continued inflow of European capital, something that seemed highly probable after the successful restructuring in 1888 of the Brazilian external debt of 20 million pounds sterling, a spectacular financial operation carried out by the London firm of N. M. Rothschild. But this deal did not actually bring new cash for the Brazilian government, with the result that Ouro Preto was forced to negotiate a short-term 5-million-pound-sterling loan via Figueiredo with a European banking syndicate led by Paribas in July 1889. This operation, however, was not anything new, since Figueiredo had been providing advances of European funds to the government for several years. In addition, the viscount became a key agent in promoting the sale of bonds abroad of the governments of the Province of Bahía and the Province of Pernambuco in alliance with multinational European banking syndicates organized by Paribas in June 1889.Footnote 28
At the same time, Ouro Preto also decided to carry out a series of domestic financial reforms, following the abolition of slavery in 1888, which provoked widespread protests by plantation owners who sought financial indemnities to be granted after slaves abandoned plantations. According to Summerhill, the prime minister put in motion a “large subsidy program to encourage banks to engage in mortgage lending to rural producers, concentrated heavily in coffee- growing regions where the wealth of planters had been most adversely impacted by the abolition of slavery.”Footnote 29 The plan was negotiated with the millionaire entrepreneur and banker Francisco de Paula Mayrink, who helped negotiate contracts with seventeen banks from various regions of Brazil that were signed between June and October 1889. In toto, Ouro Preto authorized the Treasury to transfer bonds worth 172 million contos to the banks on the condition that they would also contribute part of their capital for the provision of credits to landowners who were willing to mortgage their properties to get funds necessary to expand operations.Footnote 30 Among the favored entities was the Banco do Crédito Real, owned by Mayrinck, who made huge profits in this public–private business, which involved virtually no risks and helped him to invest in a great number of new entrepreneurial ventures.
The financial reforms mentioned are considered to have been responsible for stimulating a sudden and spectacular boom on the Rio de Janeiro stock exchange – soon known as the Encilhamento – which began in late 1889 and was to continue for three years. Most of the share capital raised was channeled into the formation of new companies, leading to the establishment of fourteen new banks before the end of the year as well as into railroad and real estate projects, both urban and rural.Footnote 31 In the view of The Rio News, a leading commercial newspaper, the speculation in Brazil mirrored the ongoing financial euphoria in Argentina and Uruguay. An article published on July 8, 1889 stated: “there is now a very dangerous epidemic raging in this country and the River Plate republics, the peril of which cannot be overestimated – the creation of credit foncier banks for the distribution of unnecessary loans to an improvident class … speculators and men who are seeking to carry on large enterprises on borrowed capital.”Footnote 32
The political and financial complexity of the last months of the long-lasting imperial regime in Brazil was notable. The Empire ended as a result of a military coup, headed by Marsall Deodoro da Fonseca, that instituted the Republic on November 15, 1889. Two months later, on January 17, 1890, the new Brazilian government decreed abandonment of the gold standard, a measure that caused a marked decline in the stock market boom. As a result, the new finance minister of the young republic, Rui Barbosa, a famous abolitionist, decided to counter the temporary crisis by adopting a loose and inconvertible monetary regime that provoked rampant speculation as well as a new surge in the stock exchange. The minister ratified a banking law in January 1890 that created three new banks of issue in the north, center and northeast of Brazil, being authorized to jointly issue up to 450,000 contos de réis, doubling the paper currency in circulation at that time, presumably to meet the demands of landowners in a number of Brazilian provinces.Footnote 33 Furthermore, Rui Barbosa signed a series of decrees facilitating the formation of new companies and allowing them to register on the Rio de Janeiro Stock Exchange with paid-in subscriptions of barely 10 percent of nominal capital. The stock market boom regained strength and the financial furor intensified.
Rui Barbosa simultaneously reinforced his alliance with his friend Francisco de Paula Mayrink, the most powerful entrepreneur of the Republican regime, and requested him to organize a new banking colossus to be called the Banco dos Estados Unidos do Brasil in January of 1890. Mayrink was a leading Brazilian multimillionaire of the day and served as director of major enterprises such as two important navigation firms, the great railway company of São Paulo, known as the Estrada de Ferro Sorocabana, railways in Minas Gerais, the largest textile firm in Brazil and several agricultural colonization enterprises, among many other ventures. But he was also an experienced banker, having served as director of the venerable commercial bank the Banco Comercial do Rio de Janeiro, which his father had helped establish, and he was an influential director of several other bank companies, several of which were incorporated into his new and massive bank.Footnote 34
The finance minister awarded the Banco dos Estados Unidos do Brasil rights to issue the huge sum of 200,000 contos of banknotes, guaranteed with Brazilian domestic debt. Nonetheless, criticisms of these exclusive privileges mounted and by early March 1890, Rui Barbosa was forced by a group of rival bankers to reduce the monopoly privileges extended to Mayrink and to share the rights to issue banknotes with other entities, to be backed up with public debt instruments that could be acquired at rock-bottom prices.Footnote 35 With these additional funds the Banco do Brasil, as well as the Banco Nacional, entered the financial fray on the stock market. According to an internal and detailed financial report, the Banco do Brasil came to hold on account of its clients a huge volume of the stock and debentures of more than 250 companies registered on the stock exchange by 1893, including dozens of banks, fifteen railway companies, over 100 commercial and manufacturing firms, numerous real estate enterprises as well as many public works and construction firms.Footnote 36 How many of these entities were solid and how many fraudulent is open to question. Contemporary critics argued that most were speculative ventures, but the financial furor was impressive.
By September 1890, three banks, the Banco dos Estados Unidos do Brasil, the Banco Nacional and the Banco do Brasil, controlled 95 percent of all banknotes in circulation by reason of their privileges.Footnote 37 In this way, a surprisingly rapid change had taken place in the Brazilian banking system – traditionally very conservative and dominated by the Banco do Brasil – transmuting into a system with three very large, competing banks. The expansion of the money-issuing powers of these banks tended to introduce a series of potentially dangerous elements for the financial system as a whole, since they engaged increasingly in the stock market binge. To reduce potential problems, the finance minister, Rui Barbosa, now pushed for the creation of a new, giant entity that was named the Banco da República dos Estados Unidos do Brasil (BREUB) as a result of the merger between the Banco dos Estados Unidos do Brasil and the Banco Nacional in December 1890. The government gave the BREUB a virtual monopoly on issue of new banknotes, and also numerous privileges related to the negotiation of foreign loans. However, severe problems began to emerge since this financial colossus pursued a course of increasing circulation of banknotes with insufficient metallic reserves.
Confidence in the new bank also began to falter as news came of the Argentine financial crash, which exploded in November 1890 and was soon baptized as the “Baring crisis” because of the excessive commitments of the prestigious London merchant bank in Argentina and Uruguay with government debts and particularly with local companies that were on the verge of bankruptcy. Despite the crisis in the River Plate, the frenzy on the Rio stock exchange continued for several more months, until the finance minister lost favor and resigned in January 1891.
After February 1891, the government headed by President Manuel Deodoro da Fonseca, the general who had headed the Republic from its inception, attempted to moderate the financial boom, but was largely unsuccessful. Speculative gains led both the major bankers and investors to keep the massive bubble afloat. Eventually, it became clear that the merger between the Banco de los Estados Unidos de Brasil, run by Mayrinck, and the Banco Nacional, formerly headed by Figueiredo, was confronting large losses. Fonseca pressed for authorization for the banks to obtain new and greater privileges for the issue of banknotes in early November of 1891. He also called for the new entity to absorb the Banco do Brasil, now to be called the Banco da República. But a strong political opposition in the Chamber of Deputies attacked the proposed fusion with the Banco do Brasil, arguing that this union could only lead to a greater monopolization of banking and political power. In the event, Fonseca resigned office after a coup orchestrated by his own vice president, General Floriano Peixoto, on November 28, 1891.
The financial situation became increasingly unstable as international markets began to abandon Brazilian government debt, traditionally highly regarded on the London Stock Exchange. According to one incisive quantitative study, the decline of the prices of Brazilian gold bonds on foreign capital markets was not only caused by the domestic financial and political unrest in Brazil, but also by contagion as a result of the formidable collapse of Argentine banks and state finance in 1891.Footnote 38 President Peixoto decided to quell local speculation by persecuting the bankers considered most responsible for the Rio stock exchange furor and the subsequent collapse.Footnote 39 Quite a number fled the country as the government restricted the issue of banknotes and put in place severe rules regarding the use of finance on margin in the stock exchange. In December 1892 the Finance Ministry pressed the directors and shareholders of the Banco do Brasil (which remained the strongest bank) to merge with the Banco da República in January 1893, despite considerable internal opposition by leading shareholders.Footnote 40
The creation of the new and massive banking entity marked a move toward extreme concentration in the banking system. As historian Gale Triner has stated: “By 1893 the Banco da República concentrated note-issuing rights within one organization and expanded its capital to accommodate public-sector financial needs, while still maintaining its reach into the private sector. The Banco da República also provided a net to other banks and often acquired assets of failing smaller organizations.”Footnote 41 During several years, the Brazilian banking system was obliged to attempt to cover the huge losses stemming from the crash that marked the end of the stock market boom of the Encilhamento. In this regard, there is debate among historians as to the circumstances that later led to the virtual collapse of both the Banco da República and most Brazilian commercial banks in 1900, at which date the government intervened forcefully to reorganize the banking system. This also implied paying off foreign investors.Footnote 42 In fact, it would not be until 1906 that the state authorities were finally able to clean up the financial mess and launch a new Banco do Brasil as a public bank, essentially under government control, but also dealing with a great range of private clients. It continued to operate as a leading commercial bank in Brazil, as well as being the dominant government bank, for much of the rest of the twentieth century.
Banks in Argentina: Rivalries between Two Major State Banks
In the case of Argentina, we have already seen that the first important commercial bank was the Banco de la Provincia de Buenos Aires, a public–private company created in 1854 with strong participation of the provincial government. The bank soon established branches throughout the vast province, which had experienced an economic boom for many decades based on cattle and sheep ranching, agriculture and trade. As a commercial bank, it managed to attract and gather the savings of most of the landowners and merchants by offering to pay 2 to 4 percent annual interest on medium-term deposits and, at the same time, offered credit to businessmen from all over the province. In 1883, Michael Mulhall, editor of The Buenos Aires Standard and a leading expert in international statistics, underlined the extraordinary success of the Argentine bank and affirmed that: “The Provincial Bank of Buenos Ayres is equal both in capital and deposits to the Imperial Bank of Germany. Its deposits are, moreover, equal to the annual average of deposits in the Bank of England during the years 1840–1850. Its issue is superior to that of all the banks of Scotland (1882) in the aggregate.”Footnote 43 However, after the election of Julio Roca as president of Argentina in 1880, the new head of state began to press for the expansion of the Banco Nacional (1872) in order to compete with the Banco de la Provincia in both operations of public and private finance and even to attempt to replace it as the preeminent financial entity in the country. This was no easy task, for it should be recalled that during the bank panics of the 1870s, the Banco Nacional had lost most of its private clientele, as well as its privileged relationship with the government, since the latter no longer accepted its bills for the payment of taxes. Its operations were therefore quite restricted for several years, although the minutes of the Board of Directors indicate that by the end of 1879 it had resumed some operations in the discount of commercial bills to a maximum of ninety days, with strict amortizations, and numerous guarantees. Subsequently, it began extending several modest loans to various provincial governments for which it opened accounts. Finally, in April 1881, the Banco Nacional was able to announce that once again it was issuing banknotes convertible to gold, and was on its way to becoming – again – a true national bank, finally closing the long crisis that had begun in mid 1876.
During the decade of the 1880s, the Banco Nacional established branches in the capitals of all the Argentine provinces as well as a growing number of agencies in secondary cities. The capital of the bank was held by several hundred shareholders, mainly wealthy individuals from the city and province of Buenos Aires, although the state also held a varying percentage of the stock.Footnote 44 In 1883, the national government approved a new charter for the bank, increased its capital from 8 to 20 million pesos, and took half of the new shares. The charter also established that the bank would open an account for the national Treasury and would fulfill important public functions, including reception of taxes and payment of salaries of public employees.Footnote 45 Furthermore, the explicit intention of its statutes was to promote a unified, national monetary and credit system.Footnote 46
The surviving records in the historical archive of the Banco Nacional provide information on the loans advanced by the bank to a great number of clients, but have not been studied in detail by historians.Footnote 47 By 1884, the new bank had twenty-seven provincial branches, which were quite profitable.Footnote 48 The minutes of the weekly meetings of the directors make it clear that the majority of loans went to large landowners and leading merchant houses but, in addition, they indicate that there was frequent insider trading since credits were extended regularly to select directors, who were themselves owners of trading firms.Footnote 49 The concession of loans increased year by year, in most cases with simple promissory notes as guarantees, although a large number were also backed up by deposit accounts. The loans were often renewed, including many of the largest credits that had been awarded to important landowners or to politically influential entrepreneurs.
Special challenges for all of the players in the Argentine money markets came as a result of abrupt shifts in monetary regimes. During the years 1881 to 1884 all banks were obliged to maintain gold reserves for the privilege of issuing banknotes, but this was followed by a subsequent regime of inconvertibility between 1885 and 1890. In a detailed historical study of Argentine finance, the economic historian Roberto Cortes Conde demonstrated that the Banco Nacional began to expand its credit operations on a considerable scale during the years 1885 and 1886, but that even so the public continued to trust its management insofar as the bank received large injections of public debt securities to bolster its reserves.Footnote 50 The confidence in the performance of the bank and of state finance reflected the optimism generated among domestic entrepreneurs and investors in the rapid growth of the economy, reinforced by the enormous increase in foreign direct investments, as well as the successful negotiation of a string of foreign loans issued on European capital markets. Nonetheless, the head of the Argentine Office of Public Credit, Pedro Agote, a specialist in banking statistics, argued that after 1887 the Banco Nacional had exceeded prudent levels in its concession of loans to private clients, at least as calculated in relation to reserves.Footnote 51
Official reports on the banks and on public debt of Argentina demonstrated that as of 1887 the two large government banks, the Banco de la Provincia de Buenos Aires and the Banco Nacional, were clearly dominant in the local banking system, controlling together 67 percent of the capital of all commercial banks, 41 percent of cash, 59 percent of deposits, 64 percent of loans and 89 percent of banknotesFootnote 52 (see Figure 6.3).
Bank assets and liabilities in Argentina, 1887 (thousands of pesos, moneda nacional).

Figure 6.3 Long Description
The horizontal axis represents liabilities, increasing from 0 to about 195,000. The vertical axis represents assets, also increasing from 0 to about 195,000. A single continuous line connects all data points, emphasising their alignment along a roughly linear relationship: banks with higher liabilities also report higher assets. The background features evenly spaced vertical gridlines for readability, and each bank label appears adjacent to its corresponding point.
The Banco Nacional’s expansion was not only based on domestic growth, since it also relied increasingly on foreign business.Footnote 53 It became the main international financial agent for the government, taking charge of the external debt service and the negotiation of new loans of Europe. In 1886, for example, the directors took a bold step by issuing bonds of the bank to the tune of 10 million gold pesos in European markets, in collaboration with a syndicate of German bankers. The following year it assumed responsibility for a similar transaction on behalf of the Buenos Aires municipal government, thereby rapidly multiplying its activities in foreign capital markets. In June 1887, the government authorized a large increase in the capital of the Banco Nacional, using the receipts of the privatization of a small state railway to increase the gold stock of the bank. In principle, there was no authorization to increase banknote issues (which were no longer convertible), but the directors of the bank promoted a notable increase in credit to clients at a time of vigorous economic growth, rapidly expanding the discount of commercial paper and the circulation of banknotes.Footnote 54
The pivot of the financial frenzy in Buenos Aires soon spread to other Argentine provinces as local politicians and capitalists moved to profit from the real estate and banking boom. It should be noted that the new president, Miguel Juárez Celman (1886–1890), and many of his closest collaborators came from the midwestern province of Cordoba, and that they had retained extensive business interests there, a fact that explains their interest in expanding access to credit at the provincial level. Until 1887, however, local banking capital had been scarce in most regions of the interior of the country, and virtually all entrepreneurs relied heavily on Buenos Aires banks as well as merchant firms for credit. So successful had the Banco Nacional proven to be in its international operations that the political and entrepreneurial elites of many provinces began to press for foreign capital to stimulate their economies. In 1887, the law of national guaranteed banks was ratified, authorizing the creation of numerous provincial banks, which were allowed to issue banknotes, provided that they purchased government gold bonds to the full amount of the notes to be issued. As a result of this law, seven provinces that previously had no banks (Santiago del Estero, La Rioja, Mendoza, San Juan, Catamarca, San Luis and Corrientes) set up new banking enterprises with public support. In addition, thirteen previously existing financial institutions also took advantage of the law to increase their issue; among these were the older provincial banks of Cordoba, Santa Fe, Entre Rios and Buenos Aires as well as several private banks.Footnote 55
The new legislation was, with some modifications, an attempt to emulate the national bank system (1864) of the United States. Argentine politicians and businessmen were aware of the enormous expansion and multiplication of banks in North America and of the decisive contribution they had made to economic development there. Nonetheless, it should be observed that several important differences existed between the basic guidelines used in the Argentine and the United States banking systems. One common point consisted in assuring that, like the American national banks, each of the official provincial banks of Argentina would guarantee its note issue with acquisition of negotiable government bonds to be held as a reserve fund. However, those provincial governments that owned the banks were then obliged to look for the financial resources to be able to acquire the bonds, and all of them sought foreign gold loans for this purpose. The gold obtained in this way was deposited in the coffers of the Banco Nacional as safekeeping to back up the issue of the provincial banknotes. But in contrast to the United States, where the banknotes could be exchanged for gold, in Argentina convertibility was suspended.Footnote 56 Moreover, another major difference was that in this period of plurality of issue, the Banco Nacional in Argentina stood behind all the provincial banks, whereas in the United States the Treasury was the ultimate guarantor of the public debt held on account of the national banks.
In Argentina the greatest financial problem in the late 1880s was the growing dependence on foreign loans. The regional banks actually raised most of their capital through the sale of foreign bonds – payable in gold – that were nominally guaranteed by state revenues. For example, between 1886 and 1888, Cordoba politicians authorized three successive bond issues in Europe, totaling 16 million gold pesos. Similar measures were adopted by the authorities of practically all the Argentine provinces (see Figure 6.4). As a result, the value of the external debts of these provinces surpassed the nominal sum of 30,000,000 pounds sterling by the year 1890. These funds were intended to finance regional economic expansion and they did so, but the mechanisms used to guarantee the provincial banknotes were quite complex. The banks could issue banknotes by buying national government bonds payable in gold that would become their reserve funds, but simultaneously they had to deposit the gold obtained through foreign loans in accounts of the Banco Nacional in order to pay for the domestic bonds. In theory, the bulk of these funds were to be used to strengthen the capital base of more than a dozen provincial banks, yet this depended on a prudent management of the gold reserves held by Banco Nacional in order to assure solvency. The risks involved in this complicated financial mechanism were great and soon began to create significant financial problems.
Share of banknote issues in the total, Argentina, 1887.

Figure 6.4 Long Description
Two pie charts are connected visually by thin diagonal lines, illustrating the distribution of the banknotes issued in total in Argentina among various institutions. Each pie chart displays the shares of different banks, with labels placed either inside or just outside the slices. This chart shows the percentages among the largest banks, divided into three main segments: Banco Nacional - 54 percent, Banco de la Provincia Buenos Aires - 35 percent, and Others - 11 percent. The right chart displays a more granular distribution of smaller banks’ shares. The slices are labelled with small percentages between 0-4 percent, reflecting their relatively minor impact compared with the largest institutions. The slices and labels include: London and River Plate Bank - 4 percent, Banco Provincial de Santa Fé - 3 percent, Banco Provincial de Córdoba - 1 percent, Banco Provincial de Entre-ríos - 1 percent, English Bank of the River Plate - 1 percent, Banco Méndez Hnos. y Cía de Tucumán - 1 percent, Banco Provincial de Salta - 0 percent, and Banco de Cuyo - 0 percent.
By the end of the 1880s, the number of public entities competing for loans on European financial markets had surpassed all expectations. Apart from the federal government and provincial governments, numerous state enterprises also sought money abroad, including the Banco de la Provincia de Buenos Aires, the Banco Nacional, the Ferrocarril Oeste de la Provincia de Buenos Aires, the state railways of Santa Fe province as well as provincial banks in Catamarca, Cordoba, Corrientes, Entre Rios, Mendoza, San Luis, Santa Fe and Tucuman. Between 1880 and 1890, the diverse Argentine public entities had issued foreign bonds worth a total nominal value of 400 million gold pesos, equivalent to approximately 80 million pounds sterling at the time. The issue of international bonds by Argentine public entities was quite evenly split between the national and provincial governments, with a marked peak in the years 1887–1889. But the Argentine financial frenzy went much further since large quantities of bonds were also sold in Europe by ten municipal governments, to which must be added the role of the state mortgage banks that succeeded in selling huge quantities of mortgage bonds (known as cédulas) in European secondary markets.Footnote 57 One detailed source calculated that the value of cédulas of the Argentine mortgage banks placed in Europe between 1886 and 1890 surpassed the enormous sum of 170 million gold pesos.Footnote 58
An important factor in the banking boom of the 1880s therefore was the expansion of the mortgage bank business. Here, again, the role of foreign capital proved critical. British, French and German bankers entered the fray and strove to obtain control of the provincial loans and mortgage business of Argentina. Nonetheless, rivalry was not the only characteristic of this business since there was also frequent collaboration between banks of different European nationalities as can be confirmed by analyzing the composition of the syndicates of the cosmopolitan banking groups.Footnote 59 In 1886, the Argentine congress approved a law creating the Banco Hipotecario Nacional (National Mortgage Bank), modeled on its provincial counterpart, the prosperous Banco Hipotecario de la Provincio de Buenos Aires (Mortgage Bank of the Province of Buenos Aires).Footnote 60 During the years 1886–1890 these two land banks sold mortgage bonds (cédulas) on various European markets, including those of Belgium, Holland, France, England and Germany.Footnote 61 The mechanics of the sale of these securities proved to be one of the most efficacious instruments of speculation ever conceived. The large landowners of the pampa region and the real estate operators at Buenos Aires (who were the main clients of these banks) received mortgage bonds in exchange for deeds of the specific properties on which the transactions were based. These bonds were negotiable cash instruments that could be sold by financial agents on the Buenos Aires exchange or abroad.Footnote 62 Given the complex nature of the financial jugglery, it was difficult to determine whether the money was invested productively or whether it had been employed in speculative ventures. Moreover, since the mortgage banks were public institutions, the government soon found itself indirectly involved in providing backup to an immense number of private debts that had been generated by the spiraling prices of rural and urban properties.
The number of fortunes built on the basis of mortgage bond speculation during the later 1880s was legion and included a varied cast of characters: wealthy landowners, urban property owners, out-and-out speculators, politicians and bank directors. The same could be said of the large number of clients who benefited from the increasingly lax policies applied by the Banco Nacional and the Banco de la Provincia de Buenos Aires. So widespread did the corruption become that, according to one contemporary report, the unscrupulous governor of the Province of Buenos Aires, Maximo Paz (1886–1890), made it a daily habit to ask the director of the Banco de la Provincia de Buenos Aires to his home to provide him with a list of persons who were to be granted financial favors on the following day.Footnote 63
In summary, the legislation to create provincial banks as well as mortgage banks did not strengthen the autonomy of the Argentine banking system but rather weakened it by accentuating dependency on foreign money markets. At the same time, the finances of the national government were compromised by the irresponsible policies of the bank directors. All told, the national government delivered 200 million gold pesos of bonds to the banks as a guarantee for a similar quantity of banknotes. But the latter actually paid less than 80 million gold pesos for these securities. The national treasury thus found itself in the position of having to guarantee a huge domestic debt with metallic reserves equivalent to less than 40 percent of that sum. Not surprisingly, depreciation of the paper money began almost at once, driving the gold premium upwards from the exchange rate of 35 paper pesos per gold peso in 1887 to 48 in 1888, 91 in 1889, 151 in early 1890 and, finally, 310 by April 1890. The minister of finance, Rufino Varela, authorized the Banco Nacional to begin selling its gold reserves to calm the markets, but as the inflation accelerated, gold speculators in Buenos Aires added fuel to the fire, causing havoc in currency markets, in the stock exchange and in the real estate market.Footnote 64
That the most important financial institutions, the Banco de la Provincia de Buenos Aires and the Banco Nacional, were on the verge of bankruptcy had been suspected as early as March 1890. In order to avoid the collapse of the provincial bank, the governor of the Province of Buenos Aires ordered the sale to British investors of the Ferrocarril Oeste, a profitable railway company owned by the provincial government, and instructed the funds to be deposited in the coffers of the bank, which was able to avoid collapse for another year. In the case of the Banco Nacional, the situation was much graver as it had debts to the national government and to foreign creditors that eventually surpassed the huge figure of 50 million gold pesos.Footnote 65 Furthermore, its commercial business was deep in the red as most of its clients were not fulfilling payments on their credits. To make matters worse, the issue of banknotes by the Banco Nacional, the most expansionist of all Argentine banks, surpassed all reasonable limits. In order to avoid a new bank run, Finance Minister Uriburu proposed that 60 million pesos of treasury bills be issued to support the Banco Nacional on condition that the much-criticized bank president should resign. Juarez Celman, however, refused to take the latter measure. Instead, he pressed for the resignation of Minister Uriburu and authorized a series of clandestine note issues by the Banco Nacional, to be backed up by three short-term loans negotiated with French and Belgian bankers.Footnote 66
In June, the directors of the Banco Nacional notified Baring Brothers & Co. of London, Argentina’s main creditor, that they would be forced to suspend payment of the quarterly debt service. This announcement was followed by a second run on the deposits of the official banks. The government tried to continue with its policies of rediscounts and fiscal deficits despite the default on foreign loans, but this time Congress did not support it, triggering a political crisis.Footnote 67 A military rebellion with considerable popular support took place in Buenos Aires.Footnote 68 Almost four years after his assumption as president of the nation, Juárez Celman presented his resignation on August 5, 1890. Carlos Pellegrini, the vice president, took charge of the executive branch.
After the ouster of Juárez Celman, the new president, Pellegrini, and his finance minister, Vicente López, once again confronted the prospect of an imminent collapse by the national and provincial banks. Pellegrini decided to carry out Uriburu’s old plan, issuing 60 million pesos in treasury bills to bolster bank reserves. This stabilized public finance for several months, but in November came the unexpected news of the collapse of the firm of Baring Brothers, shaking the London market to its foundations. The governor of the Bank of England pressed the Argentine government to transfer 43 million pesos of treasury notes held by the Banco Nacional to pay outstanding short-term debts in Europe, a large portion made up of acceptances due to Barings.Footnote 69 The result was that the leading Argentine bank was now fatally debilitated. In early January of 1891, Pellegrini received news of an imminent run by depositors on the Banco de la Provincia de Buenos Aires. In response he instructed the already weak Banco Nacional to transfer a part of its reserves to the former institution. To raise additional funds, he imposed a 2 percent tax on all deposits held by foreign-owned banks as well as a 7 percent tax on their profits. The executive branch justified the latter action by arguing that private firms like the Bank of London and the River Plate refused to recognize the urgency of the moment and were not willing to assist the public banks.Footnote 70 The nationalistic measures won Pellegrini political support but did not solve the banking crisis.
The managers of the Bank of London and the River Plate, as well as those of other private banks, had good reason to protect themselves, building up their gold reserves and restricting credits, rather than helping the state banks. They were aware that the long-awaited Buenos Aires banking collapse had finally come home to roost.Footnote 71 On March 6, having been informed that the leading state institutions were once again on the verge of suspending payments, Pellegrini and López declared a banking holiday and asked the financial and merchant community of Buenos Aires to save the public banks by subscribing to a “patriotic loan” of 100 million pesos. Domestic investors took 40 million pesos of the bonds, but this was not enough. On April 4 the Banco Hipotecario Nacional suspended payments on its cédulas, and on April 7 both the Banco Nacional and the Banco de la Provincia de Buenos Aires announced a ninety-day moratorium on all transactions. The Buenos Aires newspaper El Diario noted: “While the news [of the bank moratorium] has made a large impression on commercial circles, it has provoked great alarm among the working classes and the small depositors subject to the impact of street rumors … On Florida Street the agitation was intense among the circle of stockbrokers and merchants.”Footnote 72
At this point it became clear that the entire public banking system would have to be dismantled. Pellegrini’s close friend Vicente Casares, who had been conducting an investigation of the financial state of the Banco Nacional, issued a withering report on the extraordinary degree of corruption in this banking institution.Footnote 73 He did not mention, however, that at the start of the crisis, while he was a director of the bank, he had received a huge loan for half a million pesos to finance one of his own private companies!Footnote 74 Evidently the collusion and corruption was so widespread among entrepreneurs and politicians that there was no way of establishing legal responsibilities.
In any case, Pellegrini and López had no alternative but to close both the Banco Nacional and the Banco de la Provincia de Buenos Aires. Initially the authorities proposed the merger of both banks, but this strategy did not prosper. As a result, the government declared a moratorium of five years to allow the Banco de la Provincia de Buenos Aires to reorganize and attempt to collect outstanding debts. On the other hand, the Banco Nacional was summarily closed and a financial investigation launched to determine what real assets it still retained. Simultaneously, the government authorized the creation of an exchange commission (Caja de conversion) that would take charge of the supervision of operations on the monetary market. More fundamentally, in October 1891, the National Congress ratified the creation of a new national bank, to be called the Banco de la Nación Argentina (BNA), which became the centerpiece of the financial system thereafter. It inherited all the branches of the old Banco Nacional that did not require major modifications, and was authorized to operate those offices in most of the provinces. Subsequently, the BNA maintained close relations to the government, but also became the largest public commercial bank in the country, and continues to be so down to the present day.Footnote 75
The Banking System in Chile and the Role of the Banco Nacional
As we have seen in previous chapters, the initial development of banking in Chile was legally structured as a free banking system from 1860, when the first banking law was ratified. While a considerable number of private banks were authorized to issue banknotes, quite soon this privilege was dominated by two privately owned firms, namely the Banco Nacional and the Banco de Valparaíso, although the Edwards private bank also participated in a smaller proportion. Despite the legal framework of free banking, one well-capitalized private commercial bank, the Banco Nacional de Chile, came to assume a position as the largest financial institution from 1865 onwards, with certain fiscal privileges and a preponderance in paper currency issue. It provided important loans to the government from 1865, and four years later it provided a credit of 1 million pesos to finance a state-owned railroad, as well as receiving the privilege of opening a regular checking account for the Ministry of Finance, after which it became the main government bank.Footnote 76
Throughout the 1860s and the 1870s, the Banco Nacional de Chile exerted a clear leadership within the banking structure, providing finance to private clients, the government and public railroads. The main funds used to construct the state railroads came from three foreign loans negotiated with the London merchant bankers J. S. Morgan and Co. in the years 1866, 1867 and 1870, and it may be presumed that much of the money from the public debt operations passed through the coffers of the Banco Nacional, providing support for its issue of banknotes, although it also counted on funds from the formidable rise in deposits in its accounts and a large credit business.
In the 1870s, the Banco Nacional was profligate in the expansion of loans to its many clients but also due to insider lending by directors. The balance sheets of the three leading banks indicate that the Edwards financial firm and the Banco de Valparaíso maintained higher reserves, including bullion as well as solid securities, and were less liberal in the issue of their banknotes, but maintained a dynamic business in commercial loans.Footnote 77 On the other hand, the Banco Nacional increased its loans enormously from 1871 onwards, a fact that may be attributed to the increase in its deposits, which advanced very rapidly, probably derived from its close links to government finance. For example, in 1873 the state financial authorities requested the bank to organize an international syndicate of banks to issue Chilean gold bonds in London to the tune of almost 2.3 million pounds sterling, and it did so in combination with two British banks, the Oriental Bank Corporation and the City Bank. This demonstrated that the Chilean bank had finally been recognized as a relevant actor on international markets. Two years later, in 1875, the government again requested the Banco Nacional to negotiate a foreign loan of 1 million pounds sterling on the London capital market to convert domestic debt into foreign gold bonds and to cover interest payments on the outstanding foreign loan of 1867.Footnote 78
All of this business placed the Banco Nacional in a class of its own in Valparaíso, where it had its main offices, and made it equivalent in importance to the leading national banks in other Latin American countries. By 1877, however, the directors of the bank went overboard with speculative operations. According to the leading Chilean financial historian of that era, “the directors of bank supplied themselves abundantly” with loans totaling more than 7 million pesos.Footnote 79 The same author stated the Law of Inconvertibility was promulgated (1878) at a most critical moment since the directors had already loaned to themselves half the capital of the bank. This circumstance marked the apex of the crisis of 1878, and almost led to the bankruptcy of the Banco Nacional. In the middle of the financial collapse of the stock market and of various smaller banks, capital flight became so intense that metallic reserves were all but exhausted and the government was forced to declare the inconvertibility of the banknotes of the leading financial entity, as well as those of its rivals, despite many protests.
The Banco Nacional did not go under because it received substantial support from the state, which benefitted from the war with Peru (1879–1883), permitting Chile to acquire an enormous number of valuable nitrate fields in the northern Atacama Desert. But, in the meantime, the government was obliged to seek new sources of finance in order to cover the war expenses, given the weakness of the banking system following the panic of 1878. Fiscal certificates were issued by the national treasury and guaranteed by the nitrate taxes, and in this way the state became responsible for the circulation of a large volume of paper money, which competed with the notes issued by the private banks. The Treasury certificates were accepted because they were backed up by the notable increase in public revenues during the 1880s. The Banco Nacional gradually recovered and remained quite powerful since it remained the main entity in which the Treasury deposited its surplus funds. Furthermore, the bank continued to be the leading issuer of banknotes, as can be seen in the data from 1887 presented in Figure 6.5.
Share by banks of total of banknote issues by Chilean banks, 1887.

Figure 6.5 Long Description
Two linked pie charts illustrate the distribution of banknote issuance by Chilean banks in 1887. On the left, the larger pie chart shows the major issuers. The biggest segment represents Banco Nacional de Chile with 36 percent of total banknote issues. A slightly smaller segment represents Banco de Valparaíso with 31 percent. A large white segment labelled Others accounts for 33 percent, and this slice connects to a second pie chart that breaks down that Others category. The smaller pie chart on the right displays numerous banks with relatively minor shares. Each slice is labelled directly on the chart, and a legend beneath the image lists all banks with corresponding shading styles.
In overall commercial terms, however, the Banco Nacional was soon matched and even surpassed in some years by the Banco de Valparaíso in capital, reserve deposits and loans. Although both were privately owned banks with many shareholders, most of whom were relatively large property owners and merchants, the two entities had different business strategies. The directors of the Banco de Valparaíso were more conservative in their loan business and prudent in accumulating large bullion reserves, both factors that allowed them to attract deposits on a large scale.Footnote 80 But much remains unknown about the internal strategies and decisions adopted by the directors of each of these banks. In a word, there is a need for more detailed research on the history of these two leading banking enterprises, the Banco Nacional and the Banco de Valparaíso, particularly during the 1880s. Nonetheless, there is considerable difficulty in reconstructing their precise trajectories because of the lack of surviving historical archives of these firms, as well as of practically all nineteenth-century Chilean banks.Footnote 81 Fortunately, there remains a considerable volume of legal documents regarding the banks on the website of a Chilean monetary agency, which provides complementary information.Footnote 82 In the event, a few economic historians have done major spadework bringing together documentary sources to begin to put together a coherent analysis of some key facets of their history (see Figure 6.6).Footnote 83
Shares of National Bank of Chile, Valparaíso Bank and other banks in currency issue, 1860–1893.

Figure 6.6 Long Description
A thick line with diamond markers represents the National Bank of Chile, a line with circular markers represents the Valparaíso Bank, and a dark line with X-markers shows the share of Other banks. The horizontal axis lists each year from 1860 to 1893, while the vertical axis ranges from 0 to 100 percent. The chart visually contrasts shifting dominance among the three groups across three decades of Chilean currency issuance.
Another important feature of the Chilean banking system was that it was highly politicized. On the basis of an extensive database of the Chilean deputies and senators between 1876 and 1882, historian César Ross has established that of 156 deputies, 50 percent were closely linked or directly engaged in the banking business, while of a total of 43 senators, 60 percent had close links to banks. Of the total 199 members of Congress registered in the database, 89 were actually stockholders in different banks. Among important bankers in the Chamber of Deputies were José Nicolás Hurtado, director general of the Banco Chileno Garantizador de Valores, Agustín Edwards Ross, director of the Banco A. Edwards, Pedro Lucio Cuadra, manager of the Banco de Valparaíso in its Santiago offices, as well as four directors of the Banco Mobiliario. Among the leading senators were such figures as Pedro Marcoleta, a director of the Banco Nacional de Chile, Rafael Larraín, president of the Banco de Valparaíso, José Besa, president of Banco Nacional de Chile, and Agustín Edwards Ossandón, president of the Edwards bank, as well as owner of the Banco de Ossa y Cia.Footnote 84
The astoundingly high participation of bankers in politics did not diminish over time, as is shown by similar data from 1885 to 1888, when a total of 121 deputies were closely linked to banks (51 percent of the Chamber of Deputies), and 77 senators (58 percent of the Senate).Footnote 85 While this close interface between political and financial elites has been studied for Chile at the end of the nineteenth century, deeper research is required to explore the real influence of the bankers on public policies. The information available on Chile also suggests possibilities for comparison with other Latin American countries, but research in this specific field of the historical sociology of the ties between political elites and banking directors is yet in its infancy.
The entire Chilean banking system was deeply affected by the civil war of 1891, when the majority of the congressional deputies allied with the navy in a movement determined to oust the head of the government, José Manuel Balmaceda (1886–1891). As president he had used the nitrate revenues to push forward an ambitious public works program as well as expanding public education. But the religious tolerance espoused by the head of state garnered the opposition of the Catholic Church, as well as of many new deputies. Perhaps most importantly, the private nitrate companies considered that the government threatened their interests, and they were backed up by leading bankers and powerful British interests. A decisive moment came when the majority of the Congress refused to ratify the budget, and drove the executive branch into an impossible situation. During the year 1890, as various rebellions broke out, most bankers came to favor the rebels, especially after the president began to impose a series of emergency measures that were intended to increase the issue of fiscal certificates to cover both administrative and military expenses. The army supported the executive branch, but was defeated in a series of battles – led by officers of the navy – that led to the fall of the government and eventually to the suicide of Balmaceda.
The civil war of 1891 inevitably led to growing fears that both the monetary system and the banks were headed toward collapse. As a result, the leading bank directors began to discuss future reforms to bolster the financial system. Toward the end of 1893 an important event occurred in the country’s banking development with the merger of three of the leading commercial banks: the Banco Nacional, the Banco de Valparaíso and the Banco Agrícola. Their entire commercial business passed to a new entity, which was baptized as the Banco de Chile. The capital of the new entity was 40 million pesos, with contributions of 50 percent by the shareholders of the Banco de Valparaíso, 40 percent from the owners of the Banco Nacional and 10 percent from the shareholders of the Banco Agrícola. At the same time, there was created a new mortgage company denominated the Banco Hipotecario de Chile, which brought together all the mortgage resources of the three banks and had a capital of 10 million pesos. For decades these entities would dominate the Chilean financial system.Footnote 86
A Late Arrival: The Banco Nacional de México
In comparison to other Latin American nations, Mexico was a latecomer in banking, a fact that bespeaks the consequences of the slow development of capitalism there. A first commercial bank had been set up in the 1860s by British investors, the Bank of London and Mexico, but it long remained a relatively small enterprise. A banking system only began to emerge years later, beginning in 1882, when several new banks were set up in the nation’s capital. Of considerable interest is the cosmopolitan nature of the investors in these enterprises. Among the largest stockholders of the newly founded Banco Nacional Mexicano in late 1881 were several Parisian-based banks that held 26 percent of the initial capital, including the Banque Franco-Egyptienne with 16,500 shares and the Société Générale with 3,000 shares. Among the individual French investors there were also a series of major financial figures, including Frédéric Grueninger (2,000 shares) of the Comptoir d’Escompte, Ernest May (1,425 shares), Henri Bamberger of the Banque de Paris et Pays Bas, and Edouard Noetzlin (2,000), director of the Banque Franco-Egyptienne, as well as many other members of the Parisian financial elite. But a number of important bankers from other countries also participated, including Sir Ernest Cassel of London, banker to the British Crown, and the firm of Drexel Morgan of New York and Philadelphia, which took 1,000 shares.Footnote 87
When news of the creation of this new bank began to circulate in Mexico, a rival group of wealthy merchants of Spanish origin, who controlled much of the wholesale business in Mexico City in textiles, tobacco and food products, decided to create their own financial institution, known as the Banco Mercantil Mexicano. The capital of the latter bank was subscribed in early 1882 by a total of 305 merchants and entrepreneurs, of whom 156 had firms in Mexico City, 82 in the port of Veracruz and the rest in various cities of the republic.Footnote 88 Among the major shareholders were quite a number of politically well-connected entrepreneurs, and it should be noted that the head of state, General Porfirio Díaz, received a hundred shares as a gift, presumably to obtain his political support for the new enterprise. The majority of the larger investors were leading firms of Spanish, French and German merchants, although the bulk of the shareholders were directors of medium-sized commercial firms from all over the republic.
The two new banks operated independently until 1884 when, as a result of a fiscal and financial crisis, they merged, thereby creating what would become the largest banking enterprise in the nation, the Banco Nacional de México (Banamex), soon surpassing the Bank of London and Mexico in virtually all spheres of financial activity. The merger and consolidation of Banamex reflected the convenience of a close association between foreign and domestic capitalists in a key economic institution and sector, establishing a pattern of transatlantic financial alliances that would later be followed by other leading banks in Mexico.
It is important to note that Banamex was built largely on a French banking model that combined public and private functions, but it cannot be characterized as either a free-standing company, as a branch of a European bank or as a domestic bank. It was something different and, in fact, its originality was in part due to the influence of the French financiers who were so important to the firm. The combination of public and private financial transactions carried on by Banamex reflected an experiment that may be classified as a prevalent French model in overseas banking in the 1880s, quite common in various countries in different world regions for some time. The idea was basically to promote the establishment of banks that would operate in a given country both as government banks and as commercial banks with regional branches.Footnote 89 The individual most directly responsible for the creation of the Mexican entity was Edouard Noetzlin, a French Swiss banker who proposed the negotiations with the Mexican government for the establishment of a national bank with the aim of obtaining concessions over public finance and a monopoly on the issue of banknotes, both elements that would guarantee its future power and profitability.Footnote 90
The Mexican Finance Ministry opened a regular account with the bank, which allowed the Treasury to draw for large sums. In exchange, the bank was to take charge of the accounts of the national customs houses, including the sale of traditional customs certificates as well as of the accounts of the stamp tax offices in the nation’s capital. In effect, Banamex became the government banker, and, in principle, only its banknotes were accepted at the fiscal offices.Footnote 91 Furthermore, the bank was also granted a monopoly of banknote issue throughout the entire republic. This would eventually create intense conflicts with the Bank of London and Mexico that were only resolved after almost a decade of complex negotiations. But Banamex always managed to maintain its predominance in the issue and circulation of banknotes, increasing dramatically shortly before the outbreak of the Mexican revolution in 1910 (see Figure 6.7).

Figure 6.7 Long Description
The vertical axis represents amounts in thousands of pesos, ranging from 0 to about 60,000,000 pesos. The horizontal axis lists the years sequentially from 1884 on the left to 1910 on the right. Overall, the chart shows that Banamex consistently issued more banknotes than the Bank of London, and its circulation expanded sharply in the late 1900s, while the Bank of London’s circulation peaked around 1900 and declined afterwards.
From the start, the federal government began to pressure Banamex to provide short-term loans to supplement irregular tax revenues and to cover large expenses such as the provision of subsidies to the British and American companies that built major railroads throughout Mexico during the 1880s. The latter firms were offered guaranteed annual payments of 5 percent on all investments in the building of new tracks, bridges and stations. But Banamex did not limit its loans to the federal government since it also provided funds for the state governments of Veracruz, Zacatecas and Coahuila, among others. The government also began calling upon the bank for assistance with its international finances, in particular to resolve the old controversies on Mexican gold bonds that had been sold many decades before on the London market but had long been in default. The finance minister, Manuel Dublán, made arrangements in 1887 with Banamex for the renewal of the biannual payments on old and unpaid external bonds in combination with the London merchant bank of Glyn, Mills & Co. in order to pay the bondholders. But this was not the only contribution of the bank to the restructuring of Mexican finance on the international scene for, once again, the ubiquitous Noetzlin, head of the Banamex board in Paris, was charged by the government with the negotiation of a foreign loan to issue new gold bonds that would replace the old securities. He was able to pull off a financial coup by arranging the issue of the great Mexican conversion loan of 1888, valued at 10 million pounds sterling, with the sale of bonds in both London and Berlin. This deal was instrumental in attracting a growing flow of foreign capital to Mexico, something that many contemporaries considered essential to the overall economic expansion of the national economy. And it was from this time that Banamex became the formal agent for the government for all its foreign debt operations and payments, a role it would continue to exercise until 1913.
Despite the importance of the ties with Noetzlin and other European shareholders, a review of the bank correspondence between the Mexico City and Paris boards of Banamex tends to indicate that after 1884 the opinions of Noetzlin and the other foreign-based directors were considered as welcome business advice by the Mexican bank managers, but not as instructions. Most important was their counseling on external financial operations such as the issue of international loans. In those cases the participation of the Paris-based directors was essential as they were charged on many occasions with placing Mexican external gold bonds on European financial markets between 1888 and 1913. On the other hand, the Mexico board took responsibility for the majority of key decisions on domestic business, a fact that reflected the advantages local bank managers could have in terms of information on local economic conditions and clients.
Noetzlin was initially nonplussed to find that the Mexican merchant bankers had taken quick control of domestic business without paying overmuch attention to recommendations from Paris. Nonetheless, it is clear that European stockholders were not entirely displeased with this arrangement, insofar as the bank was able to post earnings that averaged well over 10 percent every year from 1884 to 1910, and its stock quotations in Paris tended to rise substantially over time. Not surprisingly, this profitability led various European banks to increase their participation in the stock of this Mexican financial firm, particularly after the turn of the century. By 1913, for instance, the archival documents indicate that the Banque de Paris et Pays Bas (Paribas) had increased its stake to 9,775 shares and the Banco Hispano Americano of Madrid to 9,436 shares, making them the largest stockowners of the biggest Mexican bank.Footnote 92
A final issue that is well worth exploring is whether Banamex learned gradually to operate as a virtual central bank. Banking historian Noel Maurer has argued to the contrary, but there are many shades (and possible sides) to the discussion on the historical antecedents of central banking in Mexico.Footnote 93 It is quite clear that from the 1880s down to 1914, Banamex operated simultaneously as the government bank and as the largest commercial bank in the republic. This meant that the bank directors in Mexico City (who were all Mexicans or resident merchants of foreign extraction) had extremely detailed information on both the future direction of public financial policy as well as on the overall evolution of the private-sector economy. Evidently, the directors of the bank acted in terms of their own interests and therefore cannot be seen as impartial. However, they were so heavily engaged in both government finance as well as in the business of numerous regional banks – which began to develop from the late 1880s and particularly after the new banking law of 1897 – that it may be argued that they tended to act in such a way as to conciliate the particular interests of the bank with the general interests of the banking system as a whole. In other words, it is possible to argue that while this national bank was conceived from its origins as a combination of government bank (albeit remaining a private bank) and a commercial bank, its key role in the rapidly growing banking sector eventually led its directors over time to adopt policies that indicated that they were beginning to operate as a kind of central banker (in the absence of a real central bank).
In fact, it is of interest to note that by the turn of the century, Banamex had actually begun to exercise several of the functions that characterize modern central banks. As argued by Spanish financial historian Pablo Martín Aceña: “The functions of a central bank are essentially four: issuer of paper money; banker to the government; conductor of monetary policy; and banker of banks and lender of last resort.”Footnote 94 Banamex evidently fulfilled some of these functions but not necessarily all. It was the dominant entity in the issue of banknotes and it also held the bulk of metallic reserves of the Mexican banking system, on which the issue of banknotes depended.Footnote 95 It was also principal banker to the government, both in the management of most fiscal accounts and in the handling of most public debt, domestic and external. However, it was not the conductor of monetary policy, which was managed quite effectively by the revered and long-lasting Mexican finance minister José Yves Limantour (1893–1910), who oversaw the formulation and approval of the banking law of 1897 as well as the adoption of the gold standard in 1905, among many other monetary measures.
With regard to the function of lender of last resort, on the other hand, there appear to be grounds for dispute, but the directors of the bank had no doubts. An example is the report sent in 1906 by the Mexican Board to the Paris Board (Comité de París), in response to a request for information with regard to the outstanding investment portfolio of Banamex. In a letter directed to M. Huard, president of the Parisian Board, the Mexican directors emphasized several aspects indicative of the regulatory functions that they considered the largest bank in the republic should fulfill. They insisted that their bank was fulfilling a special role within the Mexican banking system and affirmed that Banamex: “is in fact an important regulator of national credit, public and private; in the broadest sense, it has high responsibilities that it fulfills, without ever sacrificing the interests of its shareholders that it always conserves, obtaining the illustrious protection and benevolence of the public powers.”Footnote 96 The directors underlined the fact that they had important interests and much influence over many other banks in the republic. For example, they noted that they had substantial holdings in the stock of no fewer than fifteen of the principal regional banks (of a total of twenty-four). Their links with the important Banco Mercantil de Veracruz were especially important.Footnote 97 In addition, they listed the large blocks of stock held in several other banks and asserted: “Our interest is of quite some consideration in the Banco del Estado de México (12,094 shares), in the Banco de Morelos (3,050 shares), in the Banco de Jalisco (4,350 shares), in the Banco de Sonora (1,440 shares) and in the Banco de Durango (1,170 shares).” They added that apart from the Banco de Morelos, “the other banks are among the best administered in the country; they are in the hands of strong local capitalists and our considerable interest in them allow us not only to avoid rivalries but to influence their business strategies.”Footnote 98
Finally, the Banamex directors commented on the stock they held in the Banco Peninsular Mexicano, the largest bank in the state of Yucatan, an interest that had increased as a result of the commercial and financial crisis of 1907. The precipitous fall in the prices of henequen (the major local export) had obliged them to intervene in order to impede the collapse of that regional banking system.Footnote 99 They pointed out that: “our interest (3,734 shares and 30,787 stock certificates in the Banco Peninsular) have been accumulated as a result of the necessity in which we were obliged to intervene in the crisis in Yucatán (in 1907) that caused the bankruptcy of the merchant firms of Escalante and Peon.” But the directors also significantly added: “Without our direct intervention, this crisis would have been a true calamity that would have affected the entire Republic.”Footnote 100 In sum, the internal correspondence of these bankers at the beginning of the twentieth century clearly indicates that they believed their financial firm was fulfilling a set of functions that today would probably be considered as something proximate to the functions of a central banker. The original model of Banamex had clearly evolved as the Mexican banking sector expanded and became much more complex over a period of thirty years (1880–1910).
Epilogue: The Crises of the 1890s and the Travails of National Banks
This chapter has suggested that in the last quarter of the nineteenth century there was a kind of coevolution of state structures and banking development across much of Latin America.Footnote 101 Specifically, we suggest that attention should be paid to the parallel process of growing consolidation of national states and the history of the creation and expansion of national banks, although these experiences were diverse. Our rapid review of the cases of Argentina, Brazil, Chile and Mexico suggests that there was a high level of banking concentration in all cases, explained by the notable predominance of the largest banks. These entities dominated the issue of banknotes in each country, although it is clear that in each case plurality of issue continued to exist down to the end of the century. A quantitative comparison of the banking systems of Argentina, Brazil and Chile indicates that the Argentine system was the largest in size and had the highest level of concentration. This is explained by the preponderance of the Banco de la Provincia de Buenos Aires and of the Banco Nacional in terms of total liabilities and assets. In 1887, Argentina’s banking assets tripled the amount of assets of the Chilean banks and represented 2.7 times those of the Brazilian banks.Footnote 102
There were, however, many latent risks in the establishment of large banks with close ties to their respective governments. These materialized during the financial crises that shook each nation during the early 1890s, when most of the national banks collapsed or were transformed due to close linkages with unstable public finances. In Argentina, the two leading banks went under in mid 1890, in the midst of a huge financial debacle marked by various bank panics, a stock market collapse, a real estate crash and a colossal debt crisis. These events affected the entire region of the River Plate, as was confirmed by the failure in 1891 of the privately owned Banco Nacional de Uruguay (1887–1890), which during its brief existence had rapidly positioned itself as the largest banking institution in the small Uruguayan economy. They also ricocheted across the Atlantic, causing considerable havoc in the money market of London during the Baring Panic of 1890/1891. This debacle was closely linked to the excessive commitments of the famous British merchant bank in loans and investments in Argentina and Uruguay.
Important studies have also demonstrated that the financial crisis in the River Plate shook the Brazilian markets. According to two financial historians, the contagion can clearly be established by looking mainly at two factors.Footnote 103 First came the reaction of foreign investors who saw increased risk in acquisition of Argentine and Brazilian gold bonds, causing steep drops in quotations and curtailing new loans. Second was the contagion that spread outward from the financial and monetary collapse in Buenos Aires, spurring a currency crisis in Brazil. The latter led to chaos in the domestic banking and equity markets in Rio de Janeiro and contributed to the end of the financial boom known as the Encilhamento in 1892. That the leading banks were in deep trouble was confirmed by the decision of the Brazilian Finance Ministry to force the shareholders of the strongest entity, the Banco do Brasil, to merger with the Banco da República in January 1893, despite considerable opposition. For the following decade the Brazilian banking system would suffer from the legacy of this crisis.
In Chile, both the Banco Nacional de Chile and the Banco de Valparaíso, which were the dominant entities within the local banking system, were brought to their knees by the civil war of 1891, and two years later were forced to merge with the smaller Banco Agrícola to form a much larger enterprise, the Banco de Chile, that came to be the dominant financial enterprise in the nation for decades. On the other hand there is, as yet, no study that might indicate a connection between the financial problems of Chile in the early 1890s with the Argentine or Brazilian debacles.
In Mexico the authoritarian administration headed by Porfirio Díaz survived milder financial crisis in the 1890s and, as a result, the Banco Nacional de México (Banamex) continued to prosper until the outbreak of the Mexican revolution (1910–1920). In the 1920s, it was able to restructure, and continued to be the largest commercial bank in the republic for many decades. Finally, it is important to note that there are as yet few studies of financial collapse during the 1890s in other Latin American countries, but a significant occurrence was the prolonged financial crisis that took place in Colombia, where the relatively weak Banco Nacional (1880–1895) collapsed in the midst of brutal civil wars during the last decade of the century.
Clearly, the number of unanswered questions regarding the emergence and trajectories of the different national banks in the late nineteenth century in Latin America is extensive, but they surely merit future comparative research and analysis. Particularly relevant is the issue raised by financial expert and historian Charles Goodhart, on asking to what extent the national banks actually exercised the functions of central banks.Footnote 104 A comprehensive response based on the Latin American experience is not yet available in the current historiography, although it is sufficiently clear that by the end of the century a few of these banks were fulfilling some of those functions, which suggests the importance of exploring the historical antecedents of central banking. In this respect, it should be kept in mind that while Latin American financial ministers of the age did not have a very broad grasp of the principles of central banking, they found it necessary to authorize given bank(s) to assume responsibility for the implementation of monetary and debt policies that were essential to the development of efficient fiscal and financial administrations in each state. The increasing complexity of formulating institutional frameworks for such policies was thus a major factor in promoting privileged relations between national governments and given banks. In the Epilogue we will return to this crucial development of Latin American banking in an era of globalization of capitalism.


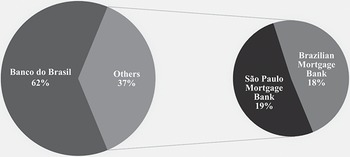
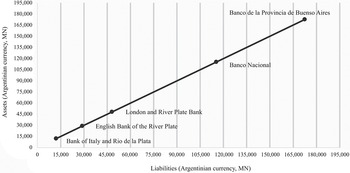
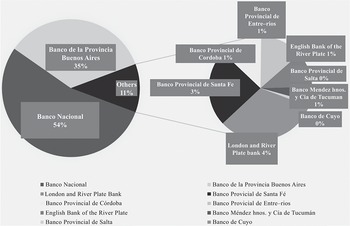
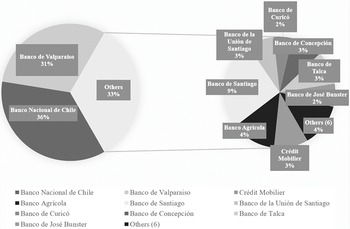
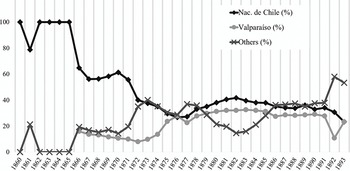
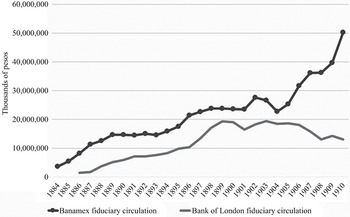

 Open access