


1. Background
The move from theory to measurement in economics is almost always fraught with difficulty and its attendant compromises. The exercise in Arrow et al. (Reference Arrow, Dasgupta, Goulder, Mumford and Oleson2012) was no exception. There we reviewed (and to some extent extended) the theoretical finding that movements in intergenerational wellbeing are tracked by movements in a comprehensive notion of wealth. We also identified conditions under which the finding could be sharpened to imply that wealth per capita and intergenerational wellbeing averaged over the generations track one another exactly; that is, wealth per capita increases if and only if intergenerational wellbeing averaged over the generations increases. We then put the theory to work by estimating movements in wealth per capita over the period 1995 to 2000 in five countries (Brazil, China, India, United States and Venezuela). Our choice of countries was in part designed to reflect different stages of economic development and in part to focus on particular resource bases.
We are particularly grateful to the Editor, Anastasios Xepapadeas, and the participants in the symposium that Professor Xepapadeas built around our paper (Duraiappah and Munoz, Reference Duraiappah and Munoz2012; Gundimeda and Shyamsundar, Reference Gundimeda and Shyamsundar2012; Hamilton, Reference Hamilton2012; Smulders, Reference Smulders2012; and Solow, Reference Solow2012) for their reflections on the methods we used to estimate wealth and its movements in our sample of countries. In this note we take the opportunity to clarify some of our methods and offer a few observations that may prove to be useful in future work.
2. Shadow prices as marginal rates of substitution
The objects that link intergenerational wellbeing to wealth are shadow prices. Because they combine ethical values with forecasts of future economic possibilities, shadow prices have long proved to be contentious – for example, in social cost-benefit analysis.Footnote 1 Problems are compounded in sustainability analysis, because in estimating wealth one is obliged to impute prices to stocks of capital assets. Moreover, the notion of wealth that has to be deployed requires that we estimate shadow prices not only of reproducible and human capital, but natural capital too.
For many types of natural capital there is a paucity of good data on physical stocks. And attaching shadow values to those stocks is exceptionally difficult because of the prevalence of externalities associated with the use of their services. Because of data limitations, the types of natural capital we were able to include in our study were restricted to land, forests as stocks of timber, sub-soil resources and carbon concentration in the atmosphere.
A good portion of our paper was devoted to estimating shadow prices. As in Dasgupta and Mäler (Reference Dasgupta and Mäler2000), we developed our account of shadow prices in the context of imperfect economies. That meant we had to consider marginal variations from an existing path (and its extension into the future) which is itself not optimal.Footnote 2 In policy analysis the variations are induced by marginal policy changes at a point in time; in sustainability analysis (the concern in our study) the variations are caused by the sheer passage of time.
Solow (Reference Solow2012: 354) draws attention to the fact that we evaluated the variations in terms of marginal rates of substitution (MRSs), not marginal rates of transformation (MRTs). Although he suggests this as a problem, it should be seen as a virtue. Had we been studying perturbations from an optimal path, a change could have been evaluated using either the MRSs or the MRTs, since the two would be equal. However, as we were in fact studying variations around non-optimal paths – in particular, paths that are called ‘business as usual’ – the MRTs do not determine shadow prices, as they do not reflect the change in utility from a perturbation from the business-as-usual path. In contrast, the MRSs do measure the utility change.
The variations to be studied need to be feasible. Variations in quantities of goods and services in our study actually occurred, so their feasibility shouldn't be in question. But estimating shadow prices today even of past stocks requires peering into the future. We took market prices of reproducible capital assets to reflect their shadow prices, assuming implicitly that markets in each of the countries aggregated information concerning the feasibility of future economic trajectories. In estimating the shadow prices of human and natural capital, we implicitly assumed that the forecasts were feasible. That move isn't unique to sustainability analysis; it is an implicit requirement in any exercise involving the future.
Smulders (Reference Smulders2012: 369–370) is right to remind readers that forecasts can't be built on air. Good forecasts require the forecaster to attend to counter-factuals (what would the forecast be if the inherited stock of assets were to have been otherwise?). Smulders is in favour of arriving at shadow prices on the basis of explicit intertemporal models (e.g., computable general equilibrium models) and says that, if we had them in hand, it would have been far simpler to use the outcomes of the models to directly calculate movements in intergenerational wellbeing. So he asks if there is any need to resort to shadow prices.
The intertemporal modelling approach endorsed by Smulders is a complement to our approach, not a substitute. In intertemporal simulation models, one assesses the impact on intertemporal wellbeing of a perturbation in the initial stock of each capital asset. For each asset, this impact is its shadow price. However, the estimates obtained from intertemporal models are only as good as the technological and behavioural assumptions built into them. The information underlying those assumptions may be good, but it will be less than perfect. Our approach relies on a different (and also imperfect) source of information, namely, the information inherent in today's market prices. Using both approaches should be expected to offer more insights than relying entirely on one.
In several cases, estimating shadow prices compelled us to rely on important theoretical predictions about economic equilibrium. For example, we assumed that the scarcity rent for crude petroleum will rise at the rate of return on reproducible capital. This is a central prediction in the theory of optimum extraction (Hotelling, Reference Hotelling1931). Hamilton (Reference Hamilton2012: 358–359) suggests that this move on our part went against the emphasis we placed when developing the theory underlying our empirical exercise that the economies being studied were imperfect. However, the empirical evidence on movements of their market prices, reported periodically since the classic by Barnett and Morse (Reference Barnett and Morse1963), is remarkably varied. To be sure, the price of extracted crude oil has not been rising at the rate of interest. A number of factors – including technological changes that lower extractions costs, as well as changes in market structure and discoveries of new deposits – have influenced the time path of extracted crude oil. It is very difficult to discern what component of that price is the scarcity rent. Still, to assume (in keeping with the Hotelling Rule) that the scarcity rent has tended to increase at the rate of interest would seem to be at least as reasonable a basis for a forecast on which to have built our empirical work than any of the very many ad hoc rules we could have followed.
3. Is time an asset?
Solow (Reference Solow2012: 354) takes issue with our decision to model time as a capital asset on the grounds that one cannot choose to alter the stock of time, which simply ‘marches on’ exogenously. What should be included on the list of capital assets is in part a matter of convenience. One could, for example, regard knowledge and institutions as assets. After all, people use the term ‘institutional capital’ often enough, and ‘knowledge capital’ is a commonplace term today. If in the absence of an overarching social theory it is assumed that they change exogenously over time, knowledge and institutions would be mathematical transformations of time itself. In that case, to regard knowledge and institutions as capital assets would in effect be to add ‘time’ to the list of state variables. This is sometimes done by analysts when the systems they are studying are non-autonomous.
Alternatively, those exogenous changes could be absorbed in the way we measure the more grounded categories of assets, namely, (i) reproducible capital, (ii) human capital and (iii) natural capital. The idea is to measure stocks of assets in efficiency units. That makes the dynamical system appear as autonomous. Shadow prices are then defined for the quality-adjusted assets, and wealth is defined as the sum of the shadow values of quality-adjusted assets.Footnote 3
In the first part of our paper, where we developed the pure theory of wealth accounting, time was taken to be an asset. We viewed time that way so as to develop the theory without modelling the economy explicitly. (The latter meant it wasn't possible to identify how the exogenous changes in economic variables ought to translate into adjustments in the quality of the more grounded assets (i)–(iii).) However, in the second half of our paper, where we came to estimate wealth changes for the five countries in our sample, we restricted the use of the term ‘asset’ to categories (i)–(iii). The task we faced thereby was reduced to estimating the shadow prices of the quality-adjusted assets in categories (i)–(iii).
The two methods are equivalent. We illustrate this by way of a simple, imperfect economy.
Assume population to remain constant over time. Output Y(t) at time t is taken to be a power function of an aggregate (scalar) index of capital stocks in categories (i)–(iii), which we write as K(t). Thus
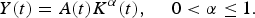 $$Y\lpar t\rpar = A\lpar t\rpar K^{\alpha}\lpar t\rpar \comma \; \quad 0 \lt \alpha \le 1.$$
A(t) is total factor productivity (TFP) at t. It reflects the economy's institutions and knowledge base. Imagine that A(t) grows at a constant, exogenous rate γ.
If consumption is a constant proportion, (1-s), of output, the dynamics of the economy would be given by the equations
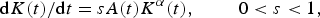 $${\rm d}K\lpar t\rpar /{\rm d}t = sA\lpar t\rpar K^{\alpha }\lpar t\rpar \comma \; \quad \quad 0 \lt s \lt 1\comma \;$$
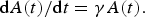 $${\rm d}A\lpar t\rpar /{\rm d}t = \gamma A\lpar t\rpar.$$
One way to interpret the dynamical system (1)–(3) is to regard both A and K as state variables. In that view of things, the model has two capital assets. Intergenerational wellbeing, which we write as V, is therefore a function of A and K:
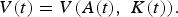 $$V\lpar t\rpar = V\lpar A\lpar t\rpar \comma \; K\lpar t\rpar \rpar.$$
Shadow prices of the pair of assets are then, respectively,
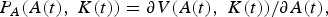 $$P_{A}\lpar A\lpar t\rpar \comma \; K\lpar t\rpar \rpar = \partial V\lpar A\lpar t\rpar \comma \; K\lpar t\rpar \rpar /\partial A\lpar t\rpar \comma \;$$
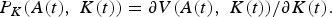 $$P_{K}\lpar A\lpar t\rpar \comma \; K\lpar t\rpar \rpar = \partial V\lpar A\lpar t\rpar \comma \; K\lpar t\rpar \rpar /\partial K\lpar t\rpar.$$
Comprehensive wealth at t, which we write as W(t), is
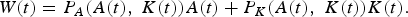 $$W\lpar t\rpar = P_{A}\lpar A\lpar t\rpar \comma \; K\lpar t\rpar \rpar A\lpar t\rpar + P_{K}\lpar A\lpar t\rpar \comma \; K\lpar t\rpar \rpar K\lpar t\rpar. $$
Taken together, equations (1)–(5a–b) appear to be an autonomous dynamical system. But that is an illusion, inasmuch as we have merely re-measured time for our purposes (equations (3) and (5a)). Equation (5a) is then to all intents and purposes the shadow price of time. In estimating comprehensive wealth (equation (6)), we would then be required to estimate the shadow value of time, a feature of the theory that Solow (Reference Solow2012: 354) found distinctly odd.Footnote 4
However, there is an alternative way to express equations (1)–(5a–b). It would be to acknowledge that there is a single quality-adjusted capital asset. The task would then be to estimate the shadow price of that single asset. That is what we did in the empirical part of our paper. The idea is to create a single capital asset out of A and K by measuring the quantity of K in efficiency units. To see what that involves, define the variable A* as
 $$A^{\ast\alpha} = A.$$
Using equation (7) we may then re-write equation (1):
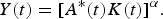 $$Y\lpar t\rpar = \lsqb A^\ast\lpar t\rpar K\lpar t\rpar \rsqb ^{\alpha}.$$
Now define the variable X as
 $$X = A^\ast K.$$
Using equation (9) we may then re-write equation (1):
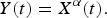 $$Y\lpar t\rpar = X^{\alpha}\lpar t\rpar.$$
Equation (10) tells us that we have so transformed the accounting system for the economy that it is now seen to have only one capital asset, X. Intergenerational wellbeing V is now a function solely of X. Thus
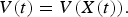 $$V\lpar t\rpar = V\lpar X\lpar t\rpar \rpar.$$
The dynamical system is autonomous.
Define X's shadow price as
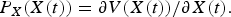 $$P_{X}\lpar X\lpar t\rpar \rpar = \partial V\lpar X\lpar t\rpar \rpar /\partial X\lpar t\rpar.$$
P X(X(t)) is the shadow price of K in efficiency units. Using equation (12), comprehensive wealth, W(t), is
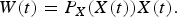 $$W\lpar t\rpar = P_{X}\lpar X\lpar t\rpar \rpar X\lpar t\rpar.$$
In sustainability analysis over short intervals of time we are interested in the sign of the time derivative of W at constant prices. In our empirical exercise we went further. We estimated the percentage rate of change in W at constant prices. Equation (13) says that the corresponding exercise would involve estimating the percentage rate of change in X(t).
Let us express g(Z(t)) as the percentage rate of change in the variable Z(t). From equations (7) and (9) we have
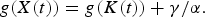 $$g\lpar X\lpar t\rpar \rpar = g\lpar K\lpar t\rpar \rpar + \gamma/\alpha.$$
As K is an aggregate of all three categories of capital assets in a world of constant population, α should plausibly be taken to equal 1. But in that case capital grows super-exponentially, an awkward feature unless s is so small that the data are not at variance with super-exponential growth. In Arrow et al. (Reference Arrow, Dasgupta, Goulder, Mumford and Oleson2012: 327) we noted that if s is small and α ≈ 1, the second term in equation (14) is approximately γ, the value of Solow's ‘residual’. Equation (14) says that in that case the residual should be added to the growth rate of wealth to obtain the index of sustainable development: g(X(t)).
TFPs are typically estimated on the basis of models that don't have natural capital in them (e.g., Collins and Bosworth, Reference Collins and Bosworth1996). If natural capital in fact declines over a period, the TFPs obtained from regressions based on those models would be overestimates. Vouvaki and Xepapadeas (Reference Vouvaki and Xepapadeas2009) observe that the implication is more than just ironic: the regressions would misinterpret degradation of the environment as an increase in knowledge and an improvement in institutions!
4. Health as consumption
Both Solow and Hamilton are alarmed by the huge size of health capital in our empirical estimates. We confess we were startled by the result initially, but are not persuaded by their (very different) remarks that there was anything fundamentally misleading about our finding. Indeed, that health swamps all other forms of capital in importance in our sample of countries might well be the most important and striking implication of our work. The results make use of the (high) values of statistical life reported in the literature. Those values (ably reviewed in Viscusi and Aldy, Reference Viscusi and Aldy2003) are used in practice, for example to set standards in air quality, and do not seem to have led to any absurd results. The value of a statistical life (VSL) reflects the willingness-to-pay for marginally reducing the risk of death. Solow's comparison of estimates of VSL with those of the discounted value of wages (Reference Solow2012: 355) seems to us to be irrelevant (compare W in equation (16) and U in equation (19), below). Hamilton (Reference Hamilton2012: 357) takes VSL to mean the demand for the good things that come with living, not just the demand for good health. But that observation is not at variance with our findings. Nor does our procedure involve double counting, contrary to what Hamilton suspects. Living is complementary (in a very strong sense) with consumption, which means that the marginal value of longevity includes the marginal wellbeing of a good life made possible by living.
To illustrate, consider a two-period model in which (for further simplicity) future wellbeing is not discounted and there is no return on holding capital. Imagine someone who is alive in period 1 and will survive to period 2 with probability π. We are interested in the case where expenditure in health can raise π. Suppose the price that must be incurred to obtain π is H(π). We assume H is an increasing (and, plausibly, a convex) function of π, and that H(0) = 0. To make our point sharply we now imagine that health expenditures yield no benefits to the person other than an increase in the probability of survival.
Wellbeing in any period is an increasing function of consumption in that period, and is unaffected by the state of health, which only affects the probability of having survived to that period. We write that as U(C). Imagine that the person faces competitive markets for consumption in period 1 (labelled as C(1)) and for contingent consumption in period 2 (labelled as C(2)). The market price of C(2) relative to C(1) is P. By ‘contingent consumption’ we mean consumption that would be available to the person should he survive. He pays P in period 1 for the right to a unit of period-2 contingent consumption.
The person begins life with total wealth W, expressed in period-1 consumption. His expected lifetime wellbeing, which we write as V, is assumed to be
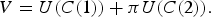 $$V = U\lpar C\lpar 1\rpar \rpar + \pi U\lpar C\lpar 2\rpar \rpar.$$
To have a meaningful problem we now assume that there is a consumption level C*, such that C* > 0 and U(C*) = 0. C* has been called the ‘welfare subsistence rate’ (Meade, Reference Meade1955). That means U(C) < 0 for low values of C and U(C) > 0 for high values of C. From the perspective of preparing national accounts, this requirement, which is forced upon us when we consider variations in life expectancy, makes health an unusual capital asset.
For simplicity of calculations we assume that the population consists of a large number of identical people and that the survival probabilities are independent of one another. In period 1 the individual chooses C(1), C(2) and π so as to maximize (15) subject to his budget constraint
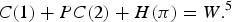 $$C\lpar 1\rpar + PC\lpar 2\rpar + H\lpar \pi\rpar = W.^5$$
Before proceeding to the optimization exercise, we note that (trivially) the rate of change in π U(C(2)) when π is increased marginally is U(C(2)). Equation (15) then says that the benefit to the individual of a marginal increase in survival probability π is U(C(2)). In our paper we noted that health economists express U(C(2)) in terms of consumption goods and then estimate it by uncovering a person's revealed willingness-to-pay for a small increase in the probability of survival. That of course is what is meant by the VSL.
H′(π), in contrast, is the VSL when the latter is measured in terms of rate at which the person is able to transform wealth into an increase in the probability of survival (the budget constraint, equation (16)). At a personal optimum the two are the same (equality of the MRS and the MRT).
Assuming that the individual's optimum π is positive, the first-order conditions of his optimization exercise are
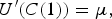 $$U^{\prime}\lpar C\lpar 1\rpar \rpar = \mu\comma \;$$
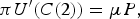 $$\pi U^{\prime}\lpar C\lpar 2\rpar \rpar = \mu P\comma \;$$
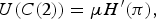 $$U\lpar C\lpar 2\rpar \rpar = \mu H^{\prime}\lpar \pi\rpar \comma \;$$
where μ (>0) is the multiplier associated with the budget constraint (16). Equation (17a) says that μ is the value of period-1 consumption in terms of period-1 wellbeing.
Recall that the person in question is one among a large population of identical individuals and that mortality risks are independent of one another. It follows that in market equilibrium P equals the individual's optimum choice of π. So P is the actuarially fair price.
Equations (17a)–(17b) and the fact that P = π imply
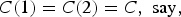 $$C\lpar 1\rpar = C\lpar 2\rpar = C\comma \; \hbox{say}\comma \;$$
and equations (17a) and (18) allow us to re-express equation (17c) in consumption units as
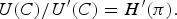 $$U\lpar C\rpar /U^{\prime}\lpar C\rpar = H^{\prime}\lpar \pi\rpar.$$
In competitive equilibrium either side of equation (19) can serve as the VSL. The equation also confirms that U(C) > 0 in equilibrium.
It may prove useful to illustrate how the welfare subsistence rate (C*) could be estimated from data. For example, VSL in the United States has been estimated to be US$6.3 million. From equation (19) it follows that
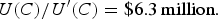 $$U\lpar C\rpar /U^{\prime}\lpar C\rpar = \$6.3\, \hbox{million}.$$
For simplicity of computation assume that the elasticity of U′(C) is 2. That implies
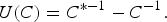 $$U\lpar C\rpar = C^{\ast-1} - C^{-1}.$$
Taking very rough figures, suppose C = US$50,000 (current per capita consumption in the US). From equations (20)–(21) it then follows that C* = US$400, which translates into just under US$1.2 a day – the World Bank's current definition of the absolute poverty line.
The above model conforms to Hamilton's demands. We have ascribed no value to good health as such. The entire value of longevity π has been taken to be the additional wellbeing a person can enjoy by living longer. There is no double-counting.
Note too that our analysis yielded a high value to health even without including any of the direct benefits of good health. It is an intriguing and fortunate fact that expenditures that bring relief from pain, or help to soften the blow of disability or immunize someone against infectious diseases also help to extend their life. Medication, immunization and medical treatment thus give rise to joint products of direct benefit. In our work we ignored all benefits other than longevity. Our estimates of the size of health capital, large as they were, are biased on the low side!
5. What is investment?
Hamilton (Reference Hamilton2012: 358) raises a different point in his discussion of health investment. As he observes, the improvement in longevity is not associated in any simple way with an investment. It is true that the word ‘investment’, as customarily used, embodies a sense of robust activism. But that is only because national income statisticians have traditionally limited the term's use to the accumulation of reproducible capital. When a government invests in roads, the picture that's drawn is one of bulldozers levelling the ground and tarmac being laid by men in hard hats.
Our paper's attention to natural and human capital obliged us to stretch the notion of ‘investment’ to mean any increase in the flow of services that the asset can provide over its lifetime. To leave a forest alone so that it can grow is in our extended sense to invest in the forest. To allow a fishery to restock under natural conditions is to invest in the fishery. To give food to someone hungry no doubt enhances her current wellbeing, but it also increases her future productivity – which means that to prevent hunger is to invest in human capital. And so on. That all may sound odd, but theory and empirics taken together should determine our usage of technical terms, not preconception nor customary usage.
6. International trade and transnational externalities
International trade enables a country to expand its capacity beyond what it is domestically capable of. As trade is an adjunct of domestic production, it doesn't play a special role in sustainability analysis. By trade we mean recorded trade. As Smulders (Reference Smulders2012: 371) notes, the problem is that countries interact with one another not only via recorded trade but also via transnational externalities. Two types of externalities may be distinguished: unidirectional and reciprocal.
Classic examples of transnational unidirectional externalities involve pollutants transported by wind and water. Acid rains and river pollution have been much studied, but as yet there are few reliable data for use in national wealth estimates.
Exports of primary products can come allied to domestic unidirectional externalities. Logging in upstream watersheds gives rise to soil erosion and increased fluctuations in the supply of water downstream. If compensation were not paid to downstream farmers and fishermen, the export price of timber would be less than its shadow price. The export would therefore contain a hidden subsidy, amounting to a transfer of wealth to the importing country from farmers and fishermen in the exporting country (Dasgupta, Reference Dasgupta1990). Pattanayak (Reference Pattanayak2004) provides one of the few reliable quantitative estimates of such unidirectional externalities. Until more empirical estimates are available, unidirectional externalities and the corresponding international wealth transfers will remain absent from studies on the wealth of nations.
Reciprocal transnational externalities have received greater attention, most especially those accompanying carbon emissions. In our analysis of the external impacts stemming from carbon emissions, we estimated the extent to which global emissions of carbon dioxide over a period of time affect the stock of ‘environmental capital’ in each country. To the extent that global emissions reduce this stock, a nation's wealth is reduced. A key consideration is by how much and whose emissions are responsible for the reduction.
The theory of public goods tells us that the way carbon emissions should be included in estimates of movements in the wealth of nations depends on international property rights and the extent to which those rights are enforced. Our estimates of wealth changes in each of the countries in our sample were based on the assumption that in the foreseeable future countries would continue to regard the atmosphere as an open-access resource. For the United States, for example, we first calculated global emissions over the period 1995–2000, and then, using estimates from Nordhaus and Boyer (Reference Nordhaus and Boyer2000), we attributed to the US a fraction of global damage from the global emissions (in our base case the global damage was assumed to be US$50 per ton of global emissions).
Hamilton (Reference Hamilton2012: 359–360) contrasts that with the approach in Hamilton and Clemens (Reference Hamilton and Clemens1999) and World Bank (2011), in which the wealth reduction a country experiences over a period of time is taken to be the global damage associated with the country's carbon emissions. He says that such damages would be a real cost to residents of a country if there were a global agreement in which nations were required to pay a price for their emissions equal to the global damage associated with their emissions. And he cites an entire body of international law that would require countries to make such payments.
There are two problems with Hamilton's position. First, none of the countries in our sample makes or receives international payments for the carbon that nations emit.Footnote 6 Secondly, even if the countries in question did face the prices required by ‘international law’, Hamilton's approach would not correctly capture changes in the wealth of each country: it would neglect the domestic wealth changes caused by changes in emissions beyond its own borders.
7. Stocks and flows
Wealth is hard to measure. So hard, that Solow (Reference Solow2012: 355) wonders whether it may not be more reliable to conduct sustainability analysis in terms of a study of movements in consumption per capita, which are easier to measure and would be subject to fewer uncertainties. It is hard to see how such an approach would be predictive of the future. Such estimates would yield no information about whether growth in consumption per capita could continue. The prospects for continued growth in per capita consumption (or wellbeing) in a country presumably depend on whether its productive base is expanding. An economy's productive base is a mirror to intergenerational wellbeing. A corollary to the equivalence between movements in wealth per capita and movements in intergenerational wellbeing averaged over the generations is their equivalence in turn with movements in the sign of a comprehensive measure of investment in stocks of capital assets per capita. However, as they are equivalence relationships, estimating the latter would involve the same set of uncertainties as the ones that bother Solow by wealth estimates.
8. Concluding comments
These are early days in the preparation of wealth accounts. It is sobering to realize that 60 years ago estimates of national incomes were subject to uncertainties of a magnitude people are minded to think no longer exists in current estimates. But we take contemporary estimates of national income too much at face value. Official estimates are silent on the proportion of incomes that are unrecorded.
The supply of data responds to demand. That there is a dearth of data on natural capital is a reflection of the fact that national accounts do not record our use of environmental resources. In a review of the empirical literature on forest services (carbon storage, ecotourism, hydrological flows, pollination, health and non-timber forest products), Ferraro et al. (Reference Ferraro, Lawlor, Mullan and Pattanayak2012) have found little that can be reliably used in wealth estimates. However, as Gundimeda and Shyamsundar (Reference Gundimeda and Shyamsundar2012: 375–376) note, there are now studies that focus on sharper problems, such as estimates of the value of forest resources to the poor who live in or near forests. Those studies are a start.
Water and fisheries are two further resources that cry out for inclusion in wealth estimates and may yet prove to be tractable. However, although the United Nations has adopted a system of environmental-economic accounting for water (SEEAW), to date only one country, Australia, has a detailed implementation plan (Perry, Reference Perry2012).
When we began our collaboration that led to Arrow et al. (Reference Arrow, Dasgupta, Goulder, Mumford and Oleson2012), we were surprised that data on fisheries' stocks are so patchy as not to be usable. A beginning has been made by Anantha Duraiappah and Pablo Munoz, who report fisheries data for use in wealth estimates in four countries in their sample of 20 (UNU-IHDP/UNEP, 2012).
That said, even if figures for natural resource stocks were available, the deep problem of imputing values to them would remain. Market prices may be hard facts, but shadow prices are soft. The issue isn't merely one of uncertainty about the role environmental resources play in production and consumption possibilities, it is also a matter of differences among people in their ethical values. We should expect wealth estimates to be presented as bands, not exact figures. That people may never agree on the wealth of nations is, however, no reason for abandoning wealth as the object of interest in sustainability analysis.


