1. INTRODUCTION
Computing upper bounds on the expected value of a convex function E[f(X)] for a random variable X with mean μ and variance σ2 is a classical problem in probability and optimization. One such commonly studied function is the two-piece linear convex function f(X) = max(0, X). A simple mean–variance bound in this case is

which is obtained from the Cauchy–Schwarz inequality. The two-point distribution that attains the bound is
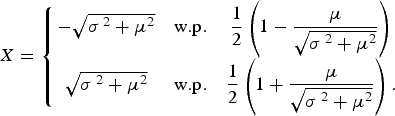
Scarf [Reference Scarf6] used this bound for the function f(X) = max(0, X − z) in a min-max newsvendor model wherein X denotes the random demand for a product and z denotes the order quantity. Likewise, Lo [Reference Lo3] used the bound to obtain an upper bound on a call option price where X denotes the stock price and z denotes the strike price.
We extend this result to find a new closed-form upper bound on the expected value of the three-piece linear function

The bound is tight and, in certain cases, is shown to be attained by a three-point distribution. In the remaining cases, it reduces to the two-point distributions as earlier. We indicate an application of the bound to price a strangle option in finance. We alsobelieve that the bound can be used in newsvendor models with recourse opportunities (cf. Gallego and Moon [Reference Gallego and Moon1]) and multiple simple recourse problems in stochastic programming (cf. van der Vlerk [Reference van der Vlerk7]), but we have not explored it as yet.
2. A NEW MEAN–VARIANCE BOUND
We are interested in solving the primal problem

where the maximization is over the set of probability distributions, of the random variable X satisfying the given mean and variance requirements. The related dual formulation is

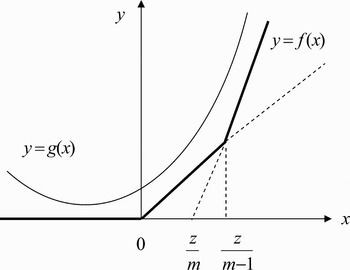
where y 0, y 1, and y 2 are the dual variables corresponding to the probability-mass, mean, and second moment constraints. The dual constraint implies that the quadratic function g(x) is greater than or equal to f(x) = max(0, x, mx − z) for all x. We assume that σ > 0. It is then well known that the two formulations have the same optimal objective value (cf. Isii [Reference Isii2]). Our approach to finding Z is based on solving the primal and dual formulations in closed form. Before proceeding, we make the following assumption.
Assumption 1
Let m > 1 and z > 0.
This ensures that each of the lines in f(x) is maximum in some nonempty interval. All other cases can be easily handled by simple linear transformations of the function. The graphical representation of the functions f(x) and g(x) are provided in Figure 1.
Graphical representation of the functions f(x) and g(x).

A classical result due to Rogosinsky [Reference Rogosinsky5] states that there there exists an extremal distribution for problem (4) with at most three support points. However, finding this in closed form is typically not possible (cf. Popescu [Reference Popescu4]). We now identify these distributions and the corresponding bounds in closed form for our problem of interest.
Theorem 1
Define

The tight upper bound Z in (4) reduces to the following four cases:
Region 1: Three-point distribution. If max[(x 2 − μ)(μ − x 1), (x 3 − μ)(μ − x 2)] ≤ σ2 ≤ (x 3 − μ)(μ − x 1), then

Region 2: Two-point distributions.
(2a) If σ2 ≤ (x 2 − μ)(μ − x 1), then
(2b) If σ2 ≤ (x 3 − μ)(μ − x 2), then
(2c) If σ2 ≥ (x 3 − μ)(μ − x 1), then


Proof
Our proof is based on constructing a primal and dual feasible solution to (4) and (5), respectively, with the same objective value. Using strong duality, we can then claim that this is indeed the tight upper bound.
Region 1: Three-point distribution. The dual feasible function g(x) lies above the lines y = 0, y = x, and y = mx − z, respectively. From Figure 1, it is clear that this function can intersect each of these lines at, at most, one point. Suppose that the points are x 1, x 2, and x 3, respectively. Equating the derivative of the function g(x) with the slope of the lines at these points, we get
(6)Similarly, equating the value of the dual function g(x) and the lines at these points, we get(7)By substituting (6) into (7), the dual variables are obtained as(8)The objective value for this dual feasible solution isWe next construct a primal solution using the three points x 1, x 2, and x 3 found in (6). From (8), we have(9)Let p 1, p 2, and p 3 denote the probabilities of these three points. To satisfy the probability-mass, mean, and variance requirements, we haveSolving for the values of pi that satisfy these three equations, we get(10)For the solution to be primal feasible, we need to ensure that the values of pi are nonnegative. From (10), this is ensured ifAssuming that the above condition is satisfied, the objective function for this primal feasible solution is given asBoth the primal and dual feasible solutions have the same objective value, implying that these are the primal and dual optimal solutions.Region 2: Two-point distributions. The remaining three bounds correspond to different two-point distributions. We indicate the proof for region (2a) only.


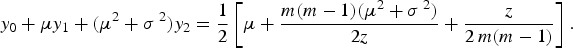


Suppose that the dual feasible function g(x) touches the lines y = 0 and y = x only. Let these points be a and b, respectively. In this case, equating the derivatives and the values as earlier, we get

The best dual solution of this form is obtained by minimizing the dual objective y 0 + μy 1 + (μ2 + σ2)y 2 with respect to y 2. This yields

The corresponding primal solution is

The primal and dual objectives are equal to

In this case, we still need to guarantee that the dual feasibility condition is satisfied by checking y 0 + y 1x + y 2x 2 ≥ mx − z for all x ∈ . Let Δ be the discriminant of the quadratic function y 2x 2 + (y 1 − m)x + (y 0 + z). Then we have

Since Δ is less than or equals to zero and y 2 > 0, the dual feasibility condition is satisfied. Thus the two-point distribution is feasible and the optimal solution in this case.■
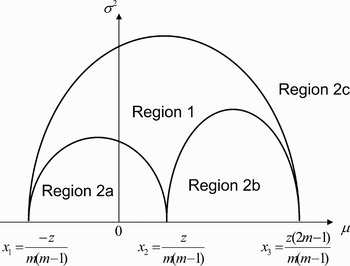
Figure 2 provides a graphical representation of the different cases in Theorem 1 in the mean–variance space. We can interpret the result in Theorem 1 as follows: Suppose that we fix the mean of the random variable μ in the range [x 1, x 2]. As we increase the variance σ2 of the random variable, the extremal distribution moves from region 2a (two point) to region 1 (three point) to region 2c (two point). These can be interpreted as regions of low variance, medium variance, and high variance, respectively, for the particular mean. The characterization of region 1 with the extremal three-point distribution is new. This occurs due to the three-piece structure of the objective function. The support points for the three-point distribution in region 1 in fact remain unchanged. It is also easy to verify that the bound in region 1 is also an upper bound for the remaining three regions (although not necessarily tight).
Characterization of the different regions in Theorem 1.

3. AN Application IN Finance
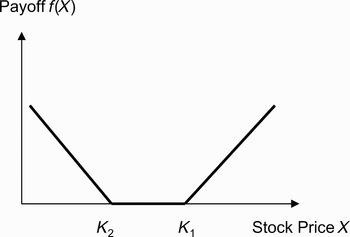
We indicate an application of the bound to price a strangle option in finance. Suppose X denotes the random price of a financial asset at a future time T > 0. Consider an investor who at time 0 buys a call and a put option on this asset, both expiring at the same maturity T. Let K 1 and K 2 be the strike prices of this call and put option, respectively. In options terminology, with K 1 > K 2 this is known as a strangle. Such a strangle option is valuable to the investor when the asset price is expected to be volatile, but the exact direction of the price movement is unknown. The payoff of the strangle is plotted in Figure 3 and given as

The three-piece payoff structure makes it suitable to use our bounds for this option.
Payoff of strangle.

Suppose that we know the mean and the variance of the asset price under the risk-neutral distribution. The exact distribution is, however, unknown. A simple upper bound on the expected payoff of the strangle is obtained by using (1):

Such option prices bounds are termed “semiparametric bounds” (cf. Lo [Reference Lo3]). However, this is not the tightest possible upper bound on the strangle price because the two-point extremal distributions for the call and the put options are different. We obtain a tighter estimate on the price of the strangle option in this setting.
Proposition 1
The tight upper bound on E[max(K 2 − X, 0, X − K 1)] with K 1 > K 2and X ∼ (μ, σ2) is

It is possible to strengthen the bound slightly for the strangle using the additional information that the stock price X is always nonnegative (see Lo [Reference Lo3]). However, for the numerical example we consider next, this information is not useful in tightening the bounds.
Numerical Example
We consider a single-asset example taken from Lo [Reference Lo3] with a current stock price of S 0 = $40. Call and put options are trading on this stock with a time to maturity of T = 1/52 year (or 1 week). The annual risk-free interest rate is r = 6% with an annual compound standard deviation of s. We consider two cases: s = 0.2 (small) and s = 0.8 (large). Assuming a lognormal distribution for the asset price, the mean and variance of the terminalstock price under the risk-neutral distribution (cf. [Reference Lo3]) is given as

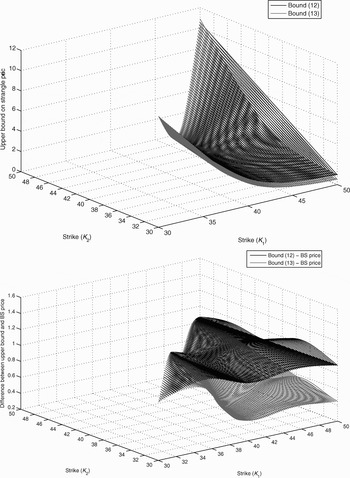
We compare the mean–variance bounds for the strangle price

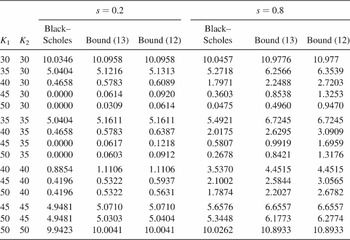
from (12) and (13) with the closed-form Black–Scholes price. The strike prices K 1and K 2 are varied between 30 and 50 with K 1 ≥ K 2. The results are provided in Table 1 and Figure 4. From Table 1, it is clear that the improvement using the new bound (13) is larger as the variance increases. For s = 0.8, the best improvement over bound (12) is obtained for a strangle with strike price K 1 = 45 and K 2 = 35. In this case, the tight bound is 0.9919 with the three-point distribution:

Under this extremal distribution, the strangle is in the money at X = 30 and 50, whereas it is out of the money at X = 40. On the contrary, using the simple extension of Lo's [Reference Lo3] bound in this case provides a weaker upper bound of 1.6959.
Upper bound and difference with Black–Scholes (BS) price for strangle for s = 0.8.

Price and Bounds for the Strangle Option

Acknowledgments
The authors would like to thank Professor Teo Chung-Piaw for his helpful discussions regarding the problem formulation and its applications. The research of the first author was partially supported by the Singapore-MIT Alliance, NUS Risk Management Institute and NUS Startup Grant.