I. Introduction
Fine wines have been widely regarded as an alternative asset class. Thus, an abundance of research in finance and wine economics examines their price behavior (Jones and Storchmann, Reference Jones and Storchmann2001; Dimson, Rousseau, and Spaenjers, Reference Dimson, Rousseau and Spaenjers2015; Breeden and Liang, Reference Breeden and Liang2017; Cardebat et al., Reference Cardebat, Faye, Le Fur and Storchmann2017; Faye and Le Fur, Reference Faye and Le Fur2019), investment attributes (Sanning, Shaffer, and Sharratt, Reference Sanning, Shaffer and Sharratt2008; Masset and Henderson, Reference Masset and Henderson2010; Bouri, Reference Bouri2015; Masset et al., Reference Masset, Cardebat, Faye and Le Fur2017; Le Fur, Ameur, and Faye, Reference Le Fur, Ameur and Faye2016; Bouri et al., Reference Bouri, Gupta, Wong and Zhu2018), capabilities to hedge against inflation (Erdős and Ormos, Reference Erdős and Ormos2013), interdependencies with other markets (Faye, Le Fur, and Prat, Reference Faye, Le Fur and Prat2015; Bouri and Roubaud, Reference Bouri and Roubaud2016), and trading environment (Czupryna and Oleksy, Reference Czupryna and Oleksy2018).
En primeur is one of the possible methods of fine wine trading, where transactions conclude in the early summer following the vintage, up to two to three years before the wine has become a finished product ready for delivery. This make an en primeur agreement an unconventional forward contract. More precisely, it is a prepaid forward contract with no guarantee of quality of wine to be delivered (Ali and Nauges, Reference Ali and Nauges2007) and with an approximate execution date (resembling the features of embedded timing option): the parties agree to provide a bottled wine at a settled prepaid price at an approximate future date (after bottling) and the seller holds the right to set the final date of the official vintage release and commencement of wine delivery. Although both practitioners and researchers tend to call en primeur agreements wine futures (Baciocco, Davis, and Jones, Reference Baciocco, Davis and Jones2014; Noparumpa, Kazaz, and Webster, Reference Noparumpa, Kazaz and Webster2015; Ashton, Reference Ashton2016; Cyr, Kwong, and Sun, Reference Cyr, Kwong and Sun2017), we consider them formally forwards, as they lack the salient features of futures traded on derivative markets, such as rigorous standardization (specified quality, quantity, delivery date), high market transparency, marking to market, margin payments, daily settlements, and rollover.
In the research on en primeur wines, special attention is paid to wine critics’ evaluations, which are normally carried out before the primeur selling price is determined and, thus, have a major influence on price formation (Jones and Storchmann, Reference Jones and Storchmann2001; Ashenfelter, Reference Ashenfelter2008; Ali, Lecocq, and Visser, Reference Ali, Lecocq and Visser2010; Dubois and Nauges, Reference Dubois and Nauges2010; Noparumpa, Kazaz, and Webster, Reference Noparumpa, Kazaz and Webster2015; Masset, Weisskopf, and Cossutta, Reference Masset, Weisskopf and Cossutta2015; Cyr, Kwong, and Sun, Reference Cyr, Kwong and Sun2019). In nominal terms, as estimated by Ali, Lecocq, and Visser (Reference Ali, Lecocq and Visser2010), the impact of Parker scores attributed in 2003, was equal to 2.80 euros per bottle of wine. Correspondingly, Ali and Nauges (Reference Ali and Nauges2007) indicate the informative role of en primeur prices, as a 10% increase translates into a 3% increase in subsequent prices on the market for bottled wines.
In this article, we examine the differences in the quoted fine wine prices traded on wine exchange depending on a predefined market scenario. More specifically, based upon Bayesian modeling, we compare the prices (present values) of prepaid forward contracts (en primeur) with spot prices, both theoretical and observed, for each wine producer and vintage. By employing the cost of carry concept we consider general storage costs to be the differentiation factor between forwards and spot values. In addition, we provide analysis covering price dispersion around mean values over three distinct periods: (i) when forwards are exclusively subject to trading, (ii) when forwards and spot trade in parallel, (iii) when spot contracts are exclusively subject to trading.
II. Trading en primeur on the Liv-ex Exchange
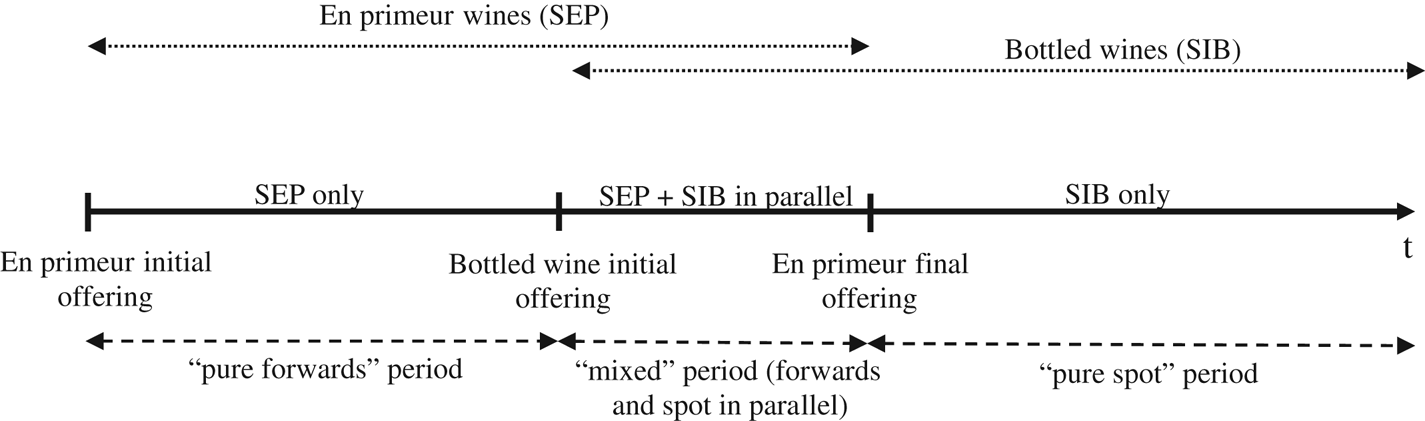
All trades on Liv-ex are based on three types of contracts: Standard in Bonds (SIB), Standard En Primeur (SEP), and Special (X). In practice, due to the wine production cycle, the SEP contracts for a given producer and vintage are the first to be transacted on the exchange, just after the en primeur initial offering has been made by the chateau. They remain trading for a period of approximately two years, until the pre-ordered en primeur stocks have been finished by the last trader. When the bottled wines enter the market, SIB contracts begin to trade. As some merchants will receive their stock before others, SEP and SIB contracts trade in parallel on the exchange for several months. Figure 1 illustrates a simplified timeline with trading periods for particular types of contracts. The phase in which trade is only for SEP contracts is called a “pure forwards” period. In turn, the subsequent and shortest phase, in which both SEP and SIB contracts trade in parallel may be marked as a “mixed period.” Thereafter, the longest period during the lifecycle of fine wine commences, with only SIB contracts being traded—a “pure spot” period.
Trading SEP and SIB contracts on Liv-ex

III. Methodology and Data
A. Data
Our dataset includes prices of Premier Cru fine wines from the Bordeaux region (Haut Brion, Lafite Rothschild, Latour, Margaux, Mouton Rothschild), vintages 1992–2008, traded under SEP and SIB conditions on the Liv-ex exchange. The time span covers a ten-year trading period (2005–2014). All data has been collected directly from the Liv-ex trading platform.
B. Problem Setting
The problems we consider are: (1) what is the value of cost of carry when both SEP and SIB contracts for the same wine and vintage traded in parallel, and (2) what is dispersion of the prices around the mean price (value)?
As the data on exact delivery dates for SEP contracts was not available in the trading platform, we set the fixed delivery date for en primeur wine at 31.05.X (where X denotes vintage + 3 years), which is compliant with the general Liv-ex terms. Additionally, we assume that the delivery period is at least two months (60 days), based on the typical (expected) delivery dates as received from Liv-ex.
Based upon market observations, we hypothesize that:
H1
en primeur wines (forwards) are traded at higher prices than bottled wines (spot) due to the cost of carry (we assume a positive value for cost-of-carry).
H2
the dispersion is lowest for standard bottled wines (spot), intermediate for en primeur wines (forwards) traded in the “mixed” period, when bottled wines are being traded in parallel (SIB enables an arbitrage and acts as an “anchor”), and highest for en primeur wines (forwards) when no bottled wines (spot) are being traded in parallel (highest uncertainty referring to the unobserved mean spot price).
Assuming, that en primeur are prepaid forward contracts, we calculate the en primeur price, which is the time zero prepaid forward price for wine delivery at time T, as (McDonald, Reference McDonald2013):

Considering cost of carry, assuming continuous storage costs of λ to be incurred continuously and proportionally to the value of the wine, and substituting F0,T by:

we finally express ${\rm F}_{0,{\rm T}}^{\rm P}$ as:

where:
${\rm F}_{0,{\rm T}}^{\rm P}$
 is the en primeur price at time zero to be delivered at time T (pre-paid forward price),
F0,T is the theoretical forward (SEP) price,
S0 is the (theoretical) spot (SIB) price,
T is the time to expiration,
r is the risk free interest rate, and
λ is the cost of carry.

Now let us assume that the investor has two choices: either to buy SEP or SIB, and then to hold it to the delivery date of the en primeur wine.
Then we may observe that:

Therefore, the rate of return of en primeur prices should differ from the rate of return of (hypothetical) prices of SIB.
IV. Estimating Hypothetical Fine Wine Value
We assumed that the (unobserved) value of wine (per individual bottle) for each producer/vintage changes proportionally with the Liv-ex 50 index, with a proportionality coefficient βp,v, where p indexes the producer and v indexes the vintage.
This value is then adjusted in a single transaction, depending on the amount of wine being transacted, number of en primeur days remaining, and—for en primeur wines—whether a parallel trade occurs. More formally:

where:
• ${\rm w}$
indexes the transactions,• ${\rm lnVal}$
is the log value in a given transaction,• ${\rm index}$
is the value of the Liv-ex 50,• ${\rm q}$
denotes the total number of bottles sold,• ${\rm epr}$
is a dummy variable set to one for wines traded as en primeur,• ${\rm par}$
is a dummy variable set to one for en primeur wines if a market for bottled wines co-existed,• d is a (negative value) variable denoting the remaining days of en primeur trading, and
• βp,v, Eq, Eepr, and Epar are parameters to be estimated.


We further assume that the actually observed price is generated from a symmetric distribution around the value, that is, around exp(lVal). To account for the possibility of fat tails, we assumed this distribution to be a generalized t-Student distribution with the number of degrees of freedom, df, to be estimated. To reflect the fact that we expect larger deviations of prices for more expensive wines, we assumed that the standard deviation of this distribution is proportional to the exp(lVal). Finally, we assumed that the proportionality coefficient differs for wines traded as en primeur and may further differ if a parallel bottle market coexists.
The model was specified in a Bayesian framework with non-informative priors (Kruschke, Reference Kruschke2014). The model convergence was tested with PSRF statistics (no problems were identified).
V. Results
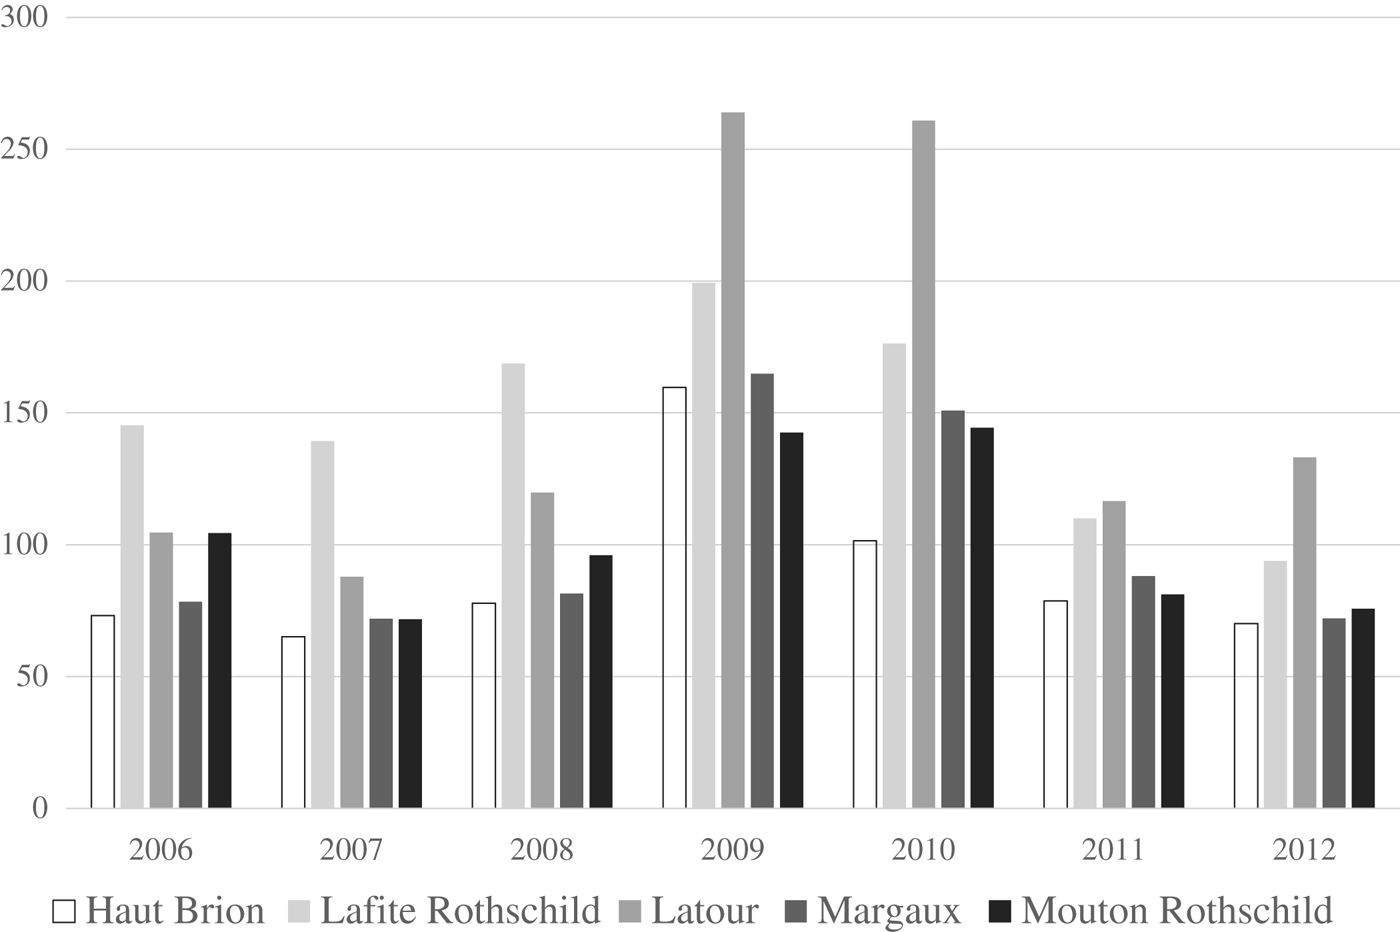
Presented in Figure 2 are the results of the β parameters estimation. Clearly, vintages 2009 and 2010 provide the most value, especially for the Latour producer. For earlier vintages, Lafite Rothschild offers greater value.
The ${\beta}$ Parameters for the Analyzed Producers and Vintages (in Percent)

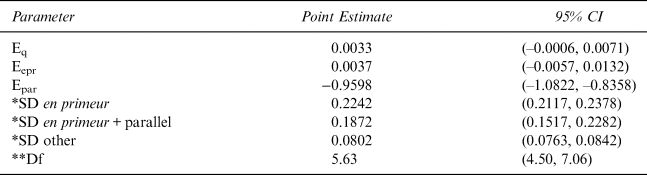
Table 1 presents the estimated values of other parameters. Surprisingly, the point estimate of the amount elasticity is positive, suggesting a price increase for larger transactions. However, the absolute value is very small, and the 95%CrI contains zero, suggesting no significant impact of the transaction size on the price.
Estimated Values of Parameters
(Eepr and Epar Expressed as a Per Annum Basis)

Notes: *SD is the standard deviation; **Df is the degrees of freedom.
The impact of the en primeur trading on price is also non-significant. The impact of the parallel trading is significant and negative: the prices for the en primeur wines when the bottled wines are also available tend to be higher by 0.26% on average for each day.
We can observe that the price dispersion around the mean value (measured by the standard deviation) has the highest value for SEP (forwards) contracts traded in the “pure forwards” period (22.42%), followed by SEP contracts traded in parallel with SIB (spot) contracts (18.72%). The additional information included in the spot prices reduces the price dispersion. We also observe that the dispersion for SEP contracts is significantly higher than the dispersion for SIB contracts, which is equal to 8.02%. This could be caused by the limited confidence in experts’ judgments, uncertainty about the ultimate quality of the wine, and general risks associated with future economic conditions.
The estimated value of cost of carry for en primeur contracts traded in the “pure forwards” period is zero (0.0037). As no spot contracts (SIB contracts) are available in this period no arbitrage is ultimately possible. One explanation for this is that en primeur contracts substitute for missing spot contracts. Another possible explanation is that the cost of carry is offset by the missing opportunity to trade. Admittedly, it is possible to make transactions in one SEP contract several times, but usually it trades only once at the outset, because the buyer does not have any direct allocation and there is then very little incentive to trade it again because prices remain flat.
Cost of carry for SEP contracts is significant and positive (the negative value in Table 1 results from the convention we used in Bayesian modeling for time, namely we modeled time before delivery as a negative value) when SIB contracts are traded in parallel. SEP contracts are traded at prices around 17% higher than the analogous SIB contracts.
VI. Conclusions
In this article we have positively verified two hypotheses. In our first hypothesis, we postulated that en primeur wines (forwards) are traded higher than standard wines (spot) due to the cost of carry. Our results indicate that the cost of carry equals zero in the first (“pure forwards”) period and increases up to 0.9598 in the second (“mixed”) period, when en primeur and bottled wines are traded in parallel. Furthermore, our findings confirm that the price dispersion around the mean value (as measured by the standard deviation) has the highest value for en primeur contracts traded in the “pure forwards” period (22.42%), followed by en primeur contracts traded in the “mixed” period (18.72%), what is consistent with our second hypothesis. The additional information included in the spot prices reduces the price dispersion.