


1. PROBLEM AND MOTIVATION
In a recent Econometric Theory problem proposed in Anatolyev (2003), it is demonstrated that under conditional heteroskedasticity (CH) the use of lagged values of regressors as instruments may not increase the efficiency of generalized method of moments (GMM) estimation relative to ordinary least squares (OLS). Carrasco (2004) proves this result using the Hansen (1985) optimal instrumental variables (OIV) approach, whereas Dhaene (2004) derives it from the instrument redundancy criteria of Breusch, Qian, Schmidt, and Wyhowski (1999).
It appears that an analogous phenomenon can occur in models with serially correlated errors, with the OLS estimator being replaced by the GMM estimator that would be OIV in the absence of CH. Consider the following stationary time series regression similar to that in Anatolyev (2003):

where all variables are scalars. Note that et−1 is missing in the conditioning information, which implies that the error et is serially correlated, in contrast to Anatolyev (2003), where the error had the martingale difference property. Suppose that the error et is conditionally heteroskedastic with

The object of estimation is β, and the class of GMM estimators we consider contains elements that use the regressor xt and its lags as instruments, possibly an infinite number thereof. Let us compare two estimators from this class. The first one is the OIV estimator that acknowledges the presence of CH in the form described previously. It is an analogue of the OIV estimator in the Anatolyev (2003) problem. The second one is the GMM estimator that is constructed to be OIV in the absence of CH, i.e., in exactly the same problem as before except that the conditional variance and first-order autocovariance are thought to be constant. This is a legitimate GMM estimator, but, of course, it need not be asymptotically as efficient as the OIV in general. It is an analogue of the OLS estimator in the Anatolyev (2003) problem; indeed, OLS is OIV when martingale difference errors are conditionally homoskedastic.
Assume that xt can be represented as

where ηt's are independently and identically distributed (i.i.d.) standard normal. Determine under what restrictions placed on parameters the two estimators are asymptotically equally efficient.
2. SOLUTION AND DISCUSSION
Let the representation of the optimal instrument that acknowledges the presence of CH be

and the representation of the instrument that would be optimal in the absence of CH be

We are looking for optimal instruments in these forms because the space of present and past xt is exactly spanned by the present and past innovations in xt. In other words, instead of the system of moment conditions E [xt−k et] = 0 for k ≥ 0 we exploit the equivalent system E [ηt−k et] = 0 for k ≥ 0. Such reformulation is more convenient because the innovations are mutually orthogonal, and as a result the system of optimality conditions simplifies greatly as in West (2001, Sect. 3).
The optimality condition for zt is (Hansen, 1985, eqn. 4.9; West, 2001, Prop. 1)

Note that exactly three terms figure in the right-hand side because the moment functions ηt−k et are conditionally serially correlated of order one. Indeed, by the law of iterated expectations, for k ≥ 0 and j > 1,

Denote

and τ ≡ E [ηt4] − 1 (in our case, τ = 2). The left-hand side in (1) equals φk. The components of the right-hand side in (1) are equal to

and

Therefore, the system (1) can be written in matrix form as follows:

where

, and

Similarly, the optimality condition for

is (recall that it is optimal under conditional homoskedasticity)

Again, the left-hand side in (3) equals φk. In the right-hand side in (3),

Therefore, the vector of weights

implied by

is a solution of the system

where

is a Toeplitz matrix with ω0 + λ0(μ02 + σx2) on the main diagonal, ω1 + λ1(μ12 + σx2) on the two diagonals next to the main diagonal, and zeros elsewhere.
Now when τ = 2, some algebra shows that
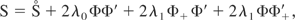
where Φ+ is Φ with elements shifted one position up (i.e., (Φ+)k = Φk+1, k ≥ 0). Then equation (2) may be written as

Suppose that Φ+ = φΦ for some scalar φ; then

This is the same as (4) up to the multiplicative scalar factor 1 − 2(λ0 + 2λ1φ)Φ′G. In this case, the solution G of (2) differs from the solution

of (4) only by a multiplicative factor, which implies that zt and

are essentially the same instrument.
The condition Φ+ = φΦ implies the AR(1) process for the regressor xt, including the case of a serially independent regressor. Note that the derivation takes advantage of the fact that the distribution of ηt is symmetric with τ = 2, although it may not be normal.
The author doubts that it is possible to solve the problem via the redundancy of moment conditions criteria as in Dhaene (2004).


