



1. Introduction
Let  $\mathbb{Z}_{+}$ be the set of non-negative integers and
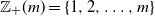 $\mathbb{Z}_{+}(m)=\{1,2,\ldots, m \}$. We consider a discrete-time level-dependent GI/M/1-type Markov chain
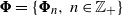 $\boldsymbol{\Phi}=\{\boldsymbol{\Phi}_n, \, n \in \mathbb{Z}_{+} \}$ on the state space
 $S=\bigcup_{i=0}^{\infty} L_i$, whose transition matrix is of the form
 \begin{equation}P =\left(\begin{array}{c@{\kern+12pt}c@{\kern+12pt}c@{\kern+12pt}c@{\kern+12pt}c@{\kern+12pt}c}A_{0}^{(0)} & A_{1}^{(0)} & & & & \\[4pt] A_{-1}^{(1)} & A_{0}^{(1)} & A_1^{(1)} & & & \\[4pt] A_{-2}^{(2)} & A_{-1}^{(2)} & A_{0}^{(2)} & A_1^{(2)} & & \\[4pt] A_{-3}^{(3)} & A_{-2}^{(3)} & A_{-1}^{(3)} & A_{0}^{(3)} & A_{1}^{(3)} & \\[4pt] \vdots & \vdots & \vdots & \vdots & \vdots & \ddots\end{array}\right),\end{equation}
where  $L_i=\{(i, j);\,i \in \mathbb{Z}_{+}, j \in \mathbb{Z}_{+}(m)\}$ and
 $A_{d}^{(i)}$ for
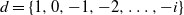 $d=\{ 1, 0, -1, -2,\ldots, -i \}$ are m-dimensional square matrices with non-negative elements. It is apparent that the process exhibits upward skip-free behavior within the levels. In the context of a state represented as (i, j), the terms ‘level’ and ‘phase’ correspond to the values i and j, respectively. If
 $A_d^{(i)}$ is independent of i, then
 $\boldsymbol{\Phi}$ is called level-independent.
We study stability and instability issues concerning the Markov chain with transiton matrix (1). For stability, we consider recurrence, positive recurrence, and geometric ergodicity; see, e.g., [Reference Asmussen2,Reference Latouche and Ramaswami9,Reference Mertens, Samuel-Cahn and Zamir14,Reference Neuts17]. Conversely, for instability, we consider transience and geometric transience; see, e.g., [Reference Choi and Kim4,Reference Latouche and Taylor10,Reference Liu, Li and Li12]. Geometric ergodicity characterizes the geometric convergence rate of the transient distribution  $P^{n}$ to its limit distribution
 $\boldsymbol{\pi}$. In contrast, geometric transience characterizes the geometric convergence rate of the transient distribution
 $P^{n}$ to zero. The concept of geometric transience is also related to another issue of quasi-stationary distribution; see [Reference Collet, Martnez and San Martn5].
Much research has been conducted on investigating ergodicity (i.e. aperiodicity and positive recurrence) and transience in level-independent block-structured Markov chains. Ergodicity and transience play a fundamental role in deriving a diverse range of limit theorems and analyzing long-time behavior in Markov chains. Ergodicity criteria for such process have been investigated by a number of scholars: [Reference Mertens, Samuel-Cahn and Zamir14] provided necessary and sufficient conditions for recurrence and transience of countable Markov chains, in terms of inequalities; [Reference Neuts17] investigated level-independent quasi-birth-and-death (QBD) processes in a Markovian environment and derived an average drift condition for stability; [Reference Latouche and Ramaswami9] established conditions equivalent to positive recurrence, null recurrence, and transience for level-independent QBD processes; and [Reference Asmussen2] presented equivalent conditions for recurrence and positive recurrence for the level-independent GI/M/1-type Markov model. Meanwhile, some researchers focused on criteria for transience. For instance, [Reference Choi and Kim4] established criteria for non-ergodicity for countable continuous-time Markov processes; [Reference Latouche and Taylor10] provided criteria for recurrence and transience of level-independent Markov chains of GI/M/1 type based on appropriate drift conditions; and [Reference Liu, Li and Li12] presented transient classifications for the aforementioned Markov chains.
There is not too much research on the investigation of ergodicity and transience in level-dependent block-structured Markov chains. Criteria for recurrence, positive recurrence, and transience of a type of level-dependent QBD process were established in [Reference Cordeiro, Kharoufeh and Oxley6]. We are motivated to explore more complicated processes, specifically level-dependent GI/M/1-type Markov chains, to present and extend the results investigated in [Reference Cordeiro, Kharoufeh and Oxley6] by employing drift criteria and matrix-generating functions. Moreover, we investigate other issues, including geometric ergodicity and geometric transience, which were not covered in [Reference Cordeiro, Kharoufeh and Oxley6]. The main contribution of this paper is to provide equivalent conditions for recurrence, positive recurrence, transience, and geometric ergodicity, along with a sufficient condition for geometric transience in a class of level-dependent GI/M/1-type Markov chains with a lower-Hessenberg structure.
The remaining sections of this paper are structured as follows. In Section 2, we introduce several definitions and notation relevant to discrete-time Markov chains. We also introduce four assumptions that specify the characteristics of the level-dependent GI/M/1-type Markov chains under consideration. In Section 3, we establish equivalent conditions for classifying chains, considering recurrence, positive recurrence, and geometric ergodicity. Additionally, we provide a sufficient condition for geometric transience. Furthermore, we provide equivalent conditions for transience, recurrence, null recurrence, and positive recurrence based on the average drift for some levels and the limiting average drift. The proofs of all the results in Section 3 are presented in Section 4. Some concluding remarks and the extension of the main results to the continuous-time case are provided in Section 5.
2. Preliminaries
We will adopt the following symbols and notation. Let  $\boldsymbol{1}$ and
 $\boldsymbol{1}^\top$ be the vector composed of all ones in its columns and the transpose of
 $\boldsymbol{1}$, respectively. Next, we denote the set of real numbers, the set of non-negative real numbers, the set of positive integers, and the complement of a set A by
 $\mathbb{R}$,
 $\mathbb{R}_{+}$,
 $\mathbb{N}$, and
 $A^\mathrm{c}$, respectively. Define
 $L_{\leq i}=\cup_{d=0}^i L_d$. Denote a set
 $\{1,2, \ldots, k \}$ by
 $\mathbb{N}_{k}$ for
 $k \geq 1$. Let the symbol
 $|\cdot|$ stand for the absolute value,
 $\| \cdot \|$ represent the sum of absolute values of elements for a column vector of dimension m, and
 $\| \cdot \|_{1}$ denote the maximum absolute sum of elements in a row of a matrix of dimension m. Furthermore, the identity matrix and an indicator function are denoted by I and
 $1_{(\cdot)}$. We denote by
 $\boldsymbol{0}$ and
 $\infty$ a matrix or a vector with each of its components being equal to 0 or infinity, respectively. Finally, let
 $\boldsymbol{x}_i$ denote the ith component of the vector
 $\boldsymbol{x}$; the inequality
 $\boldsymbol{x} \leq \boldsymbol{y}$ then represents
 $\boldsymbol{x}_i \leq \boldsymbol{y}_i$ for all i.
Suppose that  $X= \{X_n, n \in \mathbb{Z}_{+}\}$ is a discrete-time Markov chain on a countable state space S, whose transition matrix is irreducible and stochastic, denoted by
 $P=(P_{ij})_{i,j \in S}$. Let us denote the first hitting time to set A and the first hitting time to set A after time 0 as
 $\sigma_{A}=\inf\{n \geq 0\colon X_{n} \in A\}$ and
 $\tau_{A}=\inf\{n \geq 1\colon X_{n} \in A\}$, respectively. In particular, if A is the singleton
 $\{i\}$, then
 $\sigma_{A}=\sigma_{i}$ and
 $\tau_{A}=\tau_{i}$. When
 $X_{0} = i$, the conditional expectation and conditional probability are represented by
 $\mathbb{E}_{i}$ and
 $\mathbb{P}_{i}$, respectively. We noe recall some definitions of recurrence and transience.
A chain X is said to be recurrent if  $\sum_{n=0}^{\infty} P_{i i}^n = \infty$ for some (then for all) state
 $i \in S$, otherwise X is said to be transient. A recurrent chain X is called positive recurrent if
 $\mathbb{E}_i[\tau_i] < \infty$, otherwise X is called null recurrent. A positive recurrent chain X is called ergodic if it is still aperiodic. For an ergodic chain
 $\boldsymbol{\Phi}$, there exists a unique stationary distribution
 $\boldsymbol{\pi}$ such that, for any
 $i \in S$,
 $\lim_{n \rightarrow \infty}\big\|P_{i,\cdot}^{n} - \boldsymbol{\pi}(\cdot)\big\| = 0$. The ergodic chain
 $\boldsymbol{\Phi}$ is called geometrically ergodic if, for some
 $s>1$, we have the geometric convergence
 $\lim_{n \rightarrow \infty}s^{n}\big\|P_{i,\cdot}^{n} - \boldsymbol{\pi}(\cdot)\big\| = 0$. Different from ergodicity, transience implies that, for any
 $i,j \in S$,
 $\lim_{n \rightarrow \infty} P_{i, j}^{n}= 0$. A transient chain
 $\boldsymbol{\Phi}$ is further called geometrically transient if there exists some
 $r>1$ such that, for all
 $i,j \in S$,
 $\lim_{n \rightarrow \infty} r^{n} P_{i, j}^{n}= 0$, that is,
 $P_{i, j}^{n}$ decays to zero at a geometric rate as n goes to infinity.
We now consider an irreducible GI/M/1-type Markov chain  $\boldsymbol{\Phi}= \{\boldsymbol{\Phi}_n, n \in \mathbb{Z}_{+}\}$. The stochastic transition matrix is given by (1), and then it follows that
 \begin{equation*}A^{(i)}\,{:\!=}\,\left\{ \begin{array}{l@{\kern+12pt}l} A^{(0)}_{0}+A^{(0)}_{1}, & i=0, \\[1mm] \sum_{d=-i}^{1}A^{(i)}_{d}, & i \geq 1, \end{array}\right.\end{equation*}
is also a stochastic matrix. The first return time to level i is defined as  $\tau_{L_i} = \inf\{n \geq 1\colon\boldsymbol{\Phi}_n \in L_i\}$,
 $i \geq 0$. Let
 $f_{(i, j),(i^{\prime}, j^{\prime})}(n)=\mathbb{P}\{\tau_{L_{i^{\prime}}}=n,\boldsymbol{\Phi}_n=(i^{\prime}, j^{\prime}) \mid \boldsymbol{\Phi}_0=(i, j)\}$,
 $n \geq 1$, and
 $f_{i i^{\prime}}(n)=(f_{(i, j),\left(i^{\prime}, j^{\prime}\right)}(n))$. Denote the generating function by
 $$F_{i i^{\prime}}(s)=\sum_{n=1}^{\infty} s^n f_{i i^{\prime}}(n) 1_{(\tau_{i^{\prime}}
< \infty )}, \quad s \in \mathbb{R}.$$
Let  $F_{i A}=\sum_{n=1}^{\infty} f_{i A}(n) = \mathbb{P}\{\tau_A<\infty \mid \boldsymbol{\Phi}_0=i\}$ denote the probability of
 $\boldsymbol{\Phi}_n$ returning to A. Let
 $F_{i A}(s)=\sum_{n=1}^{\infty} s^n\,f_{i A}^n 1_{(\tau_{A}< \infty )} = \mathbb{E}_i\big[s^{\tau_A} 1_{(\tau_{A}< \infty )}\big]$ and
 $\tilde{F}_{i A}(s)=\mathbb{E}_{i}\big[s^{\sigma_{A}}1_{(\sigma_{A} < \infty)}\big]$ denote the exponent moment of
 $\tau_A$ and
 $\sigma_{A}$, respectively.
Prior to presenting the main results, we introduce four assumptions that will be used to investigate the specific class of the Markov chain in the subsequent sections.
Assumption 1.  $\lim_{i\rightarrow \infty} A^{(i)}_{-d} = A^{*}_{-d}$,
 $d=-1, 0, 1, \ldots$, where the limit holds element-wise.
Assumption 2.  $A^{(i)}$,
 $i \in \mathbb{Z}_{+}$, and
 $A^{*}\,{:\!=}\,\sum_{d=-1}^{\infty} A_{-d}^{*}$ are irreducible.
Assumption 2 is imposed for the considered model, which is consistent with the setting in [Reference Cordeiro, Kharoufeh and Oxley6] for QBD processes. It ensures that  $A^{(i)}$ and
 $A^{*}$ have unique stationary distributions (up to constant multiples), which are usually adopted in the literature. For example, this assumption is imposed in [Reference Cordeiro, Kharoufeh and Oxley6, Theorem 3] to investigate recurrence and positive recurrence.
Let  $f_{n}(i)=\sum_{d=-1}^{n}-dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)}$,
 $n, i \in \mathbb{Z}_{+}$, and
 $f(i)=\sum_{d=-1}^{\infty}-dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)}$,
 $i \in \mathbb{Z}_{+}$. We now give the probability explanations for
 $f_{n}(i)$ and f(i). The jth component of vector f(i) represents the one-step average drift of the chain starting from (i, j). Likewise, if
 $n<i$, the jth component of vector
 $f_{n}(i)$ represents the one-step average drift of the chain starting from (i, j) and before returning to the set
 $ L_{\leq i-n-1}$. Otherwise, the jth component of vector
 $f_{n}(i)$ represents the one-step average drift of the chain starting from (i, j), which shares the same probability explanations as f(i).
Assumption 3. The sequence of vector functions  $f_{n}(i)$ converges uniformly to the vector function f(i) on a set
 $\mathbb{Z}_{+}$, i.e., for any
 $\varepsilon > 0$, there exists a positive integer N (that could depend on
 $\varepsilon$ but is independent of i) such that, for all
 $n>N$ and for all
 $i \in \mathbb{Z}_{+}$,
 \begin{equation} \| f_{n}(i)-f(i) \|
< \varepsilon.\end{equation}
Assumption 3 guarantees that  $\lim_{i\rightarrow\infty}f(i)=\lim_{i\rightarrow\infty}\lim_{n\rightarrow\infty}f_{n}(i)=\lim_{n\rightarrow\infty}\lim_{i\rightarrow\infty}f_{n}(i)$, i.e.,
 \begin{equation} \lim_{i \rightarrow \infty} \sum_{d=-1}^{\infty}-dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)} = \lim_{n \rightarrow \infty}\lim_{i \rightarrow \infty} \sum_{d=-1}^{n} -dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)} = \sum_{d=-1}^{\infty}-dA_{-d}^{*}\boldsymbol{1},\end{equation}
which will be employed in the proof of Theorem 1. A detailed discussion of (3) is provided in Lemma 4. Additionally, Assumption 3 also guarantees that  $\lim_{i \rightarrow \infty} \sum_{d=-1}^{\infty}A_{-d}^{(i)}z^{-d}1_{(d \leq i)}=\sum_{d=-1}^{\infty}A_{-d}^{*}z^{-d}$, which will be used in the proof of Theorem 2(i).
Remark 1. It is apparent that Assumption 3 holds if either of the following two conditions is met:
(i) the matrix P described in (1) takes the form of a
 $k+2$ $(k \geq 1)$ diagonal matrix, where $A_{d}^{(i)} = \boldsymbol{0}$ for each $i \geq k+1$ and $d\leq -(k+1)$.
-
(ii)
$A_{-d}^{(i)}=\mathcal{O}(d^{-\alpha})$, i.e. two constants c and C belonging to $\mathbb{R}_{+}$ can be determined such that $cd^{-\alpha} < \big(A_{-d}^{(i)}\big)_{x,y}< Cd^{-\alpha}$ for some $\alpha>2$, $x,y \in \mathbb{N}_{m}$, and $i \in \mathbb{Z}_{+}$.


Define  $A^{(i)}(z)=\sum_{d=-1}^{i} A_{-d}^{(i)}z^{d}$ and
 $A^{*}(z)=\sum_{d=-1}^{\infty} A_{-d}^{*}z^{d}$, and define
 $\phi_{A^{*}}=\sup\{z>0\colon A^{*}(z)< \infty \}$ to be the convergence radius of
 $A^{*}(z)$. For any fixed
 $z \in (0, \phi_{A^{*}})$, we consider the generating functions
 $F_{n}(i)=\sum_{d=-1}^{n}A_{-d}^{(i)}z^{d}1_{(d \leq i)}$,
 $n, i \in \mathbb{Z}_{+}$, and
 $F(i)=\sum_{d=-1}^{\infty}A_{-d}^{(i)}z^{d}1_{(d \leq i)}$,
 $i \in \mathbb{Z}_{+}$.
Assumption 4. For any fixed  $z \in (0,\phi_{A^{*}})$, the sequence of matrix functions
 $F_{n}(i)$ converges uniformly to the matrix function F(i) on a set
 $\mathbb{Z}_{+}$, i.e. for any
 $\varepsilon > 0$, there exists a positive integer N (that could depend on
 $\varepsilon$ but is independent of i) such that, for all
 $n>N$ and for all
 $i \in \mathbb{Z}_{+}$,
 $\| F_{n}(i)-F(i) \|_{1} < \varepsilon$.
For any fixed  $z \in (1, \phi_{A^{*}})$, Assumption 4 guarantees that
 $\lim_{i \rightarrow \infty} \sum_{d=-1}^{\infty}A_{-d}^{(i)}z^{d}1_{(d \leq i)}=\sum_{d=-1}^{\infty}A_{-d}^{*}z^{d}$, i.e.
 $\lim_{i \rightarrow \infty}A^{(i)}(z)=A^{*}(z)$, which will be utilized in the proof of Theorem 2(ii).
(i) If Assumption 4 holds, then Assumption 3 holds automatically.
-
(ii) It is obvious that Assumption 4 holds if one of the following conditions applies:
(a) the matrix P described in (1) takes the form of the
$k+2$ $(k \geq 1)$ diagonal matrix $A_{d}^{(i)} = \boldsymbol{0}$ for all $i \geq k+1$ and $d\leq -(k+1)$;-
(b)
$A_{-d}^{(i)}=\mathcal{O}(z^{-d+\beta})$ for some $\beta<-1$ and $i \in \mathbb{Z}_{+}$.


3. Main results
Let  $\boldsymbol{\Phi}$ be an irreducible, discrete-time, level-dependent, GI/M/1-type Markov chain with the transition probability matrix defined in (1). We aim to present the criteria for recurrence, positive recurrence, geometric ergodicity, and geometric transience of the considered Markov chain
 $\boldsymbol{\Phi}$.
3.1. Recurrence and positive recurrence
By (10) in Lemma 4, we have  $A^{*}= \lim_{i \rightarrow \infty}A^{(i)}=\sum_{d=-1}^{\infty}A_{-d}^{*}$. Since
 $\boldsymbol{1}=\lim_{i\rightarrow \infty} A^{(i)}\boldsymbol{1}=A^{*}\boldsymbol{1}$,
 $A^{*}$ is stochastic. From Assumption 2, it follows that, for all
 $i \in \mathbb{Z}_{+}$, there are two stationary distributions, denoted by
 $\boldsymbol{\pi}^{(i)}$ and
 $\boldsymbol{\pi}^{*}$, satisfying
 $\boldsymbol{\pi}^{(i)}A^{(i)}=\boldsymbol{\pi}^{(i)}$ and
 $\boldsymbol{\pi}^{(i)}\boldsymbol{1} =1$, and
 $\boldsymbol{\pi}^{*}A^{*}=\boldsymbol{\pi}^{*}$ and
 $\boldsymbol{\pi}^{*}\boldsymbol{1}=1$. Define
 \begin{equation} D^{(i)}= \boldsymbol{\pi}^{(i)}\sum_{d=-i}^{1}dA_{d}^{(i)}\boldsymbol{1}.\end{equation}
By (11) in Lemma 4, it follows that  $D^* =\lim_{i \rightarrow \infty}D^{(i)} = \sum_{d=-1}^{\infty} -\boldsymbol{\pi}^{*}dA_{-d}^{*} \boldsymbol{1}$, which indicates that the limiting average drift is equivalent to the limit of the average drift of level i as
 $i\rightarrow\infty$.
The following theorem somewhat parallels [Reference Cordeiro, Kharoufeh and Oxley6, Theorem 3] by extending the QBD process to the more general Markov chain  $\boldsymbol{\Phi}$ here. By [Reference Meyn and Tweedie16, (8.42)], we can show the following results.
Theorem 1. Suppose that the Markov chain  $\boldsymbol{\Phi}$ satisfies Assumptions 1–3. Then:
(i)
$\boldsymbol{\Phi}$ is recurrent if and only if an integer N can be chosen such that, for every integer $i \geq N$, $D^{(i)} \leq 0$.-
(ii)
$\boldsymbol{\Phi}$ is positive recurrent if and only if, for some $\varepsilon>0$, an integer $N_{\varepsilon}$ can be found such that, for every integer $i \geq N_{\varepsilon}$, $D^{(i)}<-\varepsilon$.


Remark 3. The results of Theorem 1 naturally extend those of [Reference Cordeiro, Kharoufeh and Oxley6, Theorem 3] from simpler level-dependent QBD processes to the current model. THe proof therefore needs some modification compared with the proof in [Reference Cordeiro, Kharoufeh and Oxley6]. Firstly, due to the lower-Hessenberg structure, when considering the limit of  $D^{(i)}$ as
 $i\rightarrow \infty$ there is a challenge in interchanging the order of the infinite-term summation and the limit operation. To address this, we introduce Assumption 3. Secondly, another challenge lies in determining the appropriate constant term of the linear drift function in (12), which requires a more skillful selection of a subsequence to meet the requirements.
Based on Theorem 1, it is straightforward to demonstrate the following result.
Corollary 1. Suppose that the Markov chain  $\boldsymbol{\Phi}$ satisfies Assumptions 1–3. Then:
(i)
$\boldsymbol{\Phi}$ is recurrent if and only if $D^* \leq 0$ and $D^{(i)}>0$ for only a finite number of i.-
(ii)
$\boldsymbol{\Phi}$ is positive recurrent if and only if $D^*<0$. -
(iii)
$\boldsymbol{\Phi}$ is null recurrent if and only if $D^*=0$ and $D^{(i)}>0$ for only a finite number of i. -
(iv)
$\boldsymbol{\Phi}$ is transient if and only if $D^* \geq 0$ and $D^{(i)}>0$ for an infinite number of i.


3.2. Geometric ergodicity and geometric transience
In Remark 4, we discuss several other types of ergodicity and transience for the GI/M/1-type Markov chain  $\boldsymbol{\Phi}$.


(i) The condition in Theorem 2(ii) is sufficient but not necessary. The proof in the sufficiency of Theorem 2(ii) naturally extend the proof of [Reference Liu, Li and Li12, Theorem 4(i)] from level-independent GI/M/1-type to the current level-dependent model, necessitating some modifications in the drift function. But we are unable to prove the necessity. From the sufficiency proof in [Reference Liu, Li and Li12, Theorem 4(i), p. 1332], it is easily seen that
$\widehat{\mathbb{P}}(s)< \infty$ for some $s_1>1$. This constitutes a critical step in the proof. However, for the current level-dependent case, we are unable to get the corresponding results, thus making it impossible to establish necessity.-
(ii) We may consider some other types of ergodicity and transience. Since the transition matrix P given by (1) is stochastic,
$A^*\boldsymbol{1}=\sum^{\infty}_{d=-1}A^{*}_{-d}\boldsymbol{1}=\boldsymbol{1}$. Then, for any $\varepsilon >0$, an integer N can be determined such that, for all $n> N$, $\sum^{\infty}_{d=N+1}A^{*}_{-d}\boldsymbol{1} = \boldsymbol{0}$, which implies that, for any fixed integer k, $\lim_{i \rightarrow \infty} A^{(i)}_{-i+k}= \boldsymbol{0}$, i.e., for any fixed j, $\lim_{j \rightarrow \infty} A^{(j+k)}_{-j}= \boldsymbol{0}$. Consequently, P is a Feller matrix; it then follows that the process cannot be strongly ergodic by [Reference Hou and Liu8, Propositions 2.2 and 2.3]. For a general discrete-time Markov chain, geometric ergodicity (transience) implies algebraic ergodicity (transience) directly. Hence, it is evident that if the process is geometrically ergodic (transient), it is also algebraically ergodic (transient), and consequently ergodic (transient). Therefore, the process described in Theorem 2(i) is geometrically ergodic if and only if it is algebraically ergodic or ergodic. Under the same assumptions in Theorem 2(ii), the process is also algebraically transient.


Under Assumptions 1 and 2, for the QBD process,  $\phi_{A^{*}}>1$ and Assumptions 3 and 4 hold automatically. Therefore, we directly have the following corollary.


4. Proof of the main results
4.1. Proof of Theorem 1
Before proceeding further, we first denote a vector function  $\Gamma^{(i)}$ by
 \begin{equation} \Gamma^{(i)}(\boldsymbol{c}) = \bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\bigg)\boldsymbol{1} + A^{(i)}\boldsymbol{c} - \boldsymbol{c},\end{equation}
where  $\boldsymbol{c}$ is a column vector. Furthermore, let
 $\mathcal{N}^{+}\big(\Gamma^{(i)}\big) = \big\{\boldsymbol{c}\in\mathbb{R}^m\colon\Gamma^{(i)}(\boldsymbol{c}) =\boldsymbol{0}\big\}\bigcap\mathbb{R}_{+}^m$. The proof uses the following four technical lemmas. We shall return to the proof later. By suitable modification to the proofs of [Reference Cordeiro, Kharoufeh and Oxley6, Lemmas 1 and 2], we now have access to the following two lemmas.
Lemma 1.  $D^{(i)}=0 \Leftrightarrow \mathcal{N}^{+}\big(\Gamma^{(i)}\big) \neq \varnothing$.
Proof. For the sufficiency, for any fixed level i, assume that a vector  $\boldsymbol{c}\in\mathcal{N}^{+}\big(\Gamma^{(i)}\big)$ can be selected such that
 $\big(\sum_{d=-i}^{1}dA_{d}^{(i)}\big)\boldsymbol{1}=-A^{(i)} \boldsymbol{c}+\boldsymbol{c}$. Left-multiplying both sides by
 $\boldsymbol{\pi}^{(i)}$ yields
 $$ D^{(i)}=\boldsymbol{\pi}^{(i)}\Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1}=0. $$
Now we prove the necessity. Suppose that  $D^{(i)}=0$; then we aim to prove that a vector
 $\boldsymbol{c} \in \mathbb{R}_{+}^m$ can be chosen such that
 $\big(A^{(i)}-I\big)\boldsymbol{c} = -\big(\sum_{d=-i}^{1}dA_{d}^{(i)}\big)\boldsymbol{1}$. Obviously, if
 $\boldsymbol{c}=\boldsymbol{1}$, then
 $\big(A^{(i)}-I\big)\boldsymbol{c} = \boldsymbol{0}$. It follows from Gordan’s theorem [Reference Cordeiro, Kharoufeh and Oxley6, Theorem 5] that, for all
 $\boldsymbol{y} \in \mathbb{R}^m$,
 $\boldsymbol{y}^\top\big(A^{(i)}-I\big) \leq \boldsymbol{0}$. By Assumption 2,
 $\boldsymbol{y}^\top=\boldsymbol{\pi}^{(i)}$ is the unique (up to a constant multiple) solution of the equation
 $\boldsymbol{y}^\top\big(A^{(i)}-I\big) = \boldsymbol{0}$. Necessarily,
 $$ -\boldsymbol{y}^\top\Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1} = -\boldsymbol{\pi}^{(i)}\Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1} = 0. $$
As a result, no  $\boldsymbol{y} \in \mathbb{R}^m$ can be determined such that part (ii) of Farkas’s lemma [Reference Cordeiro, Kharoufeh and Oxley6, Theorem 4] can be satisfied. Consequently, we conclude that part (i) of Farkas’s lemma holds true, which completes the proof.
For every  $i \in \mathbb{Z}_{+}$, we write
 $\mathcal{C}_{\varepsilon}^{+}\big(\Gamma^{(i)}\big) =\big\{\boldsymbol{c}\in\mathbb{R}^m\colon\Gamma^{(i)}(\boldsymbol{c}) \leq -\boldsymbol{\varepsilon}\big\}\bigcap \mathbb{R}_{+}^m$, where
 $\boldsymbol{\varepsilon}=\varepsilon \boldsymbol{1}^\top$ for some positive number
 $\varepsilon$.
Lemma 2. For some positive number  $\varepsilon$,
 $D^{(i)} \leq -\varepsilon \Leftrightarrow \mathcal{C}_{\varepsilon}^{+}\big(\Gamma^{(i)}\big) \neq \varnothing$.
Proof. For sufficiency, assume that a vector  $\boldsymbol{c}\in\mathcal{C}_{\varepsilon}^{+}\big(\Gamma^{(i)}\big)$ can be determined. Then
 $\Gamma^{(i)}(\boldsymbol{c}) \leq -\boldsymbol{\varepsilon}$. Left-multiplying both sides by
 $\boldsymbol{\pi}^{(i)}$ gives
 \begin{equation} \boldsymbol{\pi}^{(i)} \Gamma^{(i)}(\boldsymbol{c}) \leq -\varepsilon. \end{equation}
It is apparent from (4) and (5) that
 \begin{equation} \boldsymbol{\pi}^{(i)} \Gamma^{(i)}(\boldsymbol{c})=D^{(i)}. \end{equation}
Combining (6) and (7), it follows that  $D^{(i)} \leq -\varepsilon$.
For necessity, it is straightforward from that last inequality that  $D^{(i)}\boldsymbol{1} \leq -\boldsymbol{\varepsilon}$. Our goal is to demonstrate the existence of a vector
 $\hat{\boldsymbol{c}} \geq \boldsymbol{0}$ that can be selected such that
 \begin{equation} \big(A^{(i)}-I\big)\hat{\boldsymbol{c}} = \boldsymbol{b} \,{:\!=}\, D^{(i)}\boldsymbol{1} - \Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1}. \end{equation}
Analogous to the proof of Lemma 1, only when the equality sign is taken does  $\boldsymbol{y}^\top\big(A^{(i)}-I\big) \geq \boldsymbol{0}$ hold true, and the unique solution is
 $\boldsymbol{y}^\top=\boldsymbol{\pi}^{(i)}$. Thus, we only need to prove that
 $\boldsymbol{y}^\top\boldsymbol{b} \geq 0$. By computation,
 $$ \boldsymbol{y}^\top\boldsymbol{b} = \boldsymbol{\pi}^{(i)}\Bigg[D^{(i)}\boldsymbol{1} - \Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1}\Bigg] = D^{(i)} - \boldsymbol{\pi}^{(i)}\Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1} = 0. $$
As a result, no  $\boldsymbol{y} \geq \boldsymbol{0}$ can be found such that
 $\boldsymbol{y}^\top\boldsymbol{b}<0$ can be satisfied. By Farkas’s lemma [Reference Cordeiro, Kharoufeh and Oxley6, Theorem 4], there is a solution
 $\hat{\boldsymbol{c}} \geq \boldsymbol{0}$ to (8). By the fact that
 $D^{(i)} \boldsymbol{1} \leq -\boldsymbol{\varepsilon}$, the proof is complete.
Lemma 3. By Assumption 2, we conclude that  $\lim_{i\rightarrow \infty}\boldsymbol{\pi}^{(i)} = \boldsymbol{\pi}^{*}$.
Proof. For any i, define the fundamental matrix by  $R^{(i)} = \big(I-A^{(i)}+\boldsymbol{1}\boldsymbol{\pi}^{(i)}\big)^{-1}$. Let
 $\Delta^{(i)}=A^{*}-A^{(i)}$. By computation,
 \begin{align*} \boldsymbol{\pi}^{*} \Delta^{(i)} R^{(i)} & = \boldsymbol{\pi}^{*}( A^{*}-A^{(i)} )R^{(i)} \\ & = \boldsymbol{\pi}^{*}A^{*}R^{(i)}- \boldsymbol{\pi}^{*}(R^{(i)}+\boldsymbol{1}\boldsymbol{\pi}^{(i)} R^{(i)}-I) \\ & = -\boldsymbol{\pi}^{*}\boldsymbol{1} \boldsymbol{\pi}^{(i)} R^{(i)}+\boldsymbol{\pi}^{*} = \boldsymbol{\pi}^{*} - \boldsymbol{\pi}^{(i)}. \end{align*}
It follows from this that  $\|\boldsymbol{\pi}^{*}-\boldsymbol{\pi}^{(i)}\| = \|\boldsymbol{\pi}^{*}\Delta^{(i)}R^{(i)}\| \leq \|\Delta^{(i)}\|\|R^{(i)}\|$. It can be easily seen from Assumption 2 that
 $\|\Delta^{(i)}\| \rightarrow 0$ as
 $i \rightarrow \infty$. Consequently,
 $\lim_{i\rightarrow \infty}\boldsymbol{\pi}^{(i)} = \boldsymbol{\pi}^{*}$. This completes the proof.
Lemma 4. Under Assumptions 1 and 3,
 \begin{align} \lim_{i\rightarrow\infty}\sum_{d=-1}^{\infty}-dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)} & = \sum_{d=-1}^{\infty}-dA_{-d}^{*}\boldsymbol{1}, \end{align}
 \begin{align} \lim_{i\rightarrow\infty}\sum_{d=-1}^{\infty}A_{-d}^{(i)}1_{(d \leq i)} & = \sum_{d=-1}^{\infty}A_{-d}^{*}. \end{align}
 \begin{equation} \lim_{i \rightarrow \infty}\sum_{d=-1}^{\infty} - \boldsymbol{\pi}^{(i)}dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)} = \sum_{d=-1}^{\infty} - \boldsymbol{\pi}^{*}dA_{-d}^{*}\boldsymbol{1}. \end{equation}
Proof. For every n, let  $a_n \,{:\!=}\, \lim_{i\rightarrow\infty}f_{n}(i) = \sum_{d=-1}^{n}-dA_{-d}^{*}\boldsymbol{1}$. Since
 $a_n$ is a sequence of monotonically decreasing vectors,
 $\mathbb{A}\,{:\!=}\,\lim_{n \rightarrow \infty} a_n = \sum_{d=-1}^{\infty}-dA_{-d}^{*}\boldsymbol{1}$, which, in conjunction with inequality (2), yields that, for any
 $\varepsilon > 0$, an integer N can be determined such that, for all
 $n>N$ and for every i,
 $\|f_{n}(i)-f(i)\| < {\varepsilon}/{3}$ and
 $\|a_n-\mathbb{A}\| < {\varepsilon}/{3}$. In particular, take
 $n=N+1$; then
 $\|f_{N+1}(i)-f(i)\| < {\varepsilon}/{3}$ and
 $\|a_{N+1}-\mathbb{A}\| < {\varepsilon}/{3}$. Since
 $\lim_{i\rightarrow\infty}f_{N+1}(i)=a_{N+1} $, an integer
 $M_{1}$ can be selected such that
 $\|f_{N+1}(i)-a_{N+1}\| < {\varepsilon}/{3}$,
 $i>M_{1}$. For
 $i>M_{1}$,
 \begin{equation*} \|f(i)-\mathbb{A}\| \leq \|f(i)-f_{N+1}(i)\| + \|f_{N+1}(i)-a_{N+1}\| + \|a_{N+1}-\mathbb{A}\|
< \frac{\varepsilon}{3} + \frac{\varepsilon}{3} + \frac{\varepsilon}{3} = \varepsilon, \end{equation*}
i.e.  $\lim_{i \rightarrow \infty}f(i)=\mathbb{A}=\lim_{n \rightarrow \infty}a_{n}$. Hence,
 $\lim_{i\rightarrow\infty}\sum_{d=-1}^{\infty}-dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)} = \sum_{d=-1}^{\infty}-dA_{-d}^{*}\boldsymbol{1}$. Let
 $h_{n}(i)=\sum_{d=-1}^{n}A_{-d}^{(i)}1_{(d \leq i)}$,
 $n, i \in \mathbb{Z}_{+}$, and
 $h(i)=\lim_{n\rightarrow \infty}h_{n}(i)=\sum_{d=-1}^{\infty}A_{-d}^{(i)}1_{(d \leq i)}$,
 $i \in \mathbb{Z}_{+}$. By (2), we have that, for any
 $\varepsilon > 0$, an integer N can be determined such that, for all
 $n>N$ and for every i,
 \[ \|h_{n}(i)-h(i)\|_{1} = \Bigg\|\sum_{d=n+1}^{\infty}A_{-d}^{(i)}1_{(d \leq i)}\Bigg\|_{1} < \Bigg\|\sum_{d=n+1}^{\infty}-dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)}\Bigg\| = \|f_{n}(i)-f(i)\|
< \varepsilon, \]
i.e.  $h_{n}(i)$ converge uniformly to h(i) with
 $\|\cdot\|_{1}$. Under Assumption 1, using similar arguments as for (9) yields
 \begin{equation*} \lim_{i \rightarrow \infty}A^{(i)} = \lim_{i \rightarrow \infty}\sum_{d=-1}^{\infty}A_{-d}^{(i)}1_{(d \leq i)} = \sum_{d=-1}^{\infty}A_{-d}^{*}=A^{*}. \end{equation*}
Let  $g_{n}(i)=\sum_{d=-1}^{n}-\boldsymbol{\pi}^{(i)}dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)}$,
 $n,i\in\mathbb{Z}_{+}$, and
 $g(i)=\sum_{d=-1}^{\infty}-\boldsymbol{\pi}^{(i)}dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)}$,
 $i \in \mathbb{Z}_{+}$. From the fact that
 $\boldsymbol{0} < \boldsymbol{\pi}^{(i)} < \boldsymbol{1}$ and by (2), we have that, for any
 $\varepsilon > 0$, an integer N can be found such that, for all
 $n>N$ and for every i,
 \[ |g_{n}(i)-g(i)| = \Bigg|\sum_{d=n+1}^{\infty}-\boldsymbol{\pi}^{(i)}dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)}\Bigg| < \Bigg\|\sum_{d=n+1}^{\infty}-dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)}\Bigg\| = \|f_{n}(i)-f(i)\|
< \varepsilon, \]
i.e.  $g_{n}(i)$ converge uniformly to g(i). By Lemma 3,
 $\lim_{i\rightarrow \infty}\boldsymbol{\pi}^{(i)} = \boldsymbol{\pi}^{*}$, and then
 $$ \lim_{i \rightarrow \infty} -\boldsymbol{\pi}^{(i)}dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)} = -\boldsymbol{\pi}^{*}dA_{-d}^{*}\boldsymbol{1}. $$
Under Assumption 1, using similar arguments as for (9) yields
 \begin{equation*} \lim_{i \rightarrow \infty}\sum_{d=-1}^{\infty} - \boldsymbol{\pi}^{(i)}dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)} = \sum_{d=-1}^{\infty} - \boldsymbol{\pi}^{*}dA_{-d}^{*}\boldsymbol{1}. \end{equation*}
This completes the proof.
As stated in the previous section, our proof of sufficiency for (i) is not only similar to that of [Reference Cordeiro, Kharoufeh and Oxley6, Theorem 3], but also more complicated. To make it more convenient for readers to understand the whole proof, we would rather write down similar parts again here than just say ‘refer to [Reference Cordeiro, Kharoufeh and Oxley6]’. With the help of Lemmas 1–exchange-limit, we now turn to the proof.
Proof of Theorem 1. To prove (i), it is essential to verify that the conditions stipulated in the drift criterion for recurrence, i.e. [Reference Meyn and Tweedie16, (8.42)], are fulfilled. For this reason, we define the drift function as follows:
 \begin{equation} \boldsymbol{v}_i= \begin{cases} \boldsymbol{k}_{0}, & i=0, \ j \in \mathbb{N}_m, \\ i\boldsymbol{1}+\boldsymbol{k}^{(i)}, & i \geq 1, i \in \mathbb{N}, j \in \mathbb{N}_m, \end{cases} \end{equation}
where  $\boldsymbol{k}^{(0)}=(k_{0 1}, k_{0 2}, \ldots, k_{0 m})^\top$ is a row vector with
 $k_{0 j}>0$ and
 $\boldsymbol{k}^{(i)}=(k_{i 1}, k_{i 2}, \ldots, k_{i m})^\top$ with
 $k_{i j} \geq 0$. By simple calculation, for
 $i \geq 1$,
 \begin{equation*} \Delta^{(i)} \,{:\!=}\,{(P\boldsymbol{v})}_i - \boldsymbol{v}_i = \sum_{d=0}^{i+1}A_{-i+d}^{(i)}(d\boldsymbol{1}+\boldsymbol{k}^{(d)}) - (i\boldsymbol{1}+\boldsymbol{k}^{(i)}) = \Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1} + \sum_{d=0}^{i+1}A_{-i+d}^{(i)}\boldsymbol{k}^{(d)} - \boldsymbol{k}^{(i)} \end{equation*}
and  $\Delta^{(0)} \,{:\!=}\, A_0^{(0)}\boldsymbol{k}^{(0)} + A_1^{(0)}\boldsymbol{1} + A_1^{(0)}\boldsymbol{k}^{(1)} - \boldsymbol{k}^{(0)}$. Replacing
 $\boldsymbol{k}^{(i)}$ by a strictly positive vector
 $\boldsymbol{c}$ for all i,
 $$ \Delta_h^{(i)}\,{:\!=}\, \Gamma^{(i)}(\boldsymbol{c}) = \Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1} + A^{(i)}\boldsymbol{c} - \boldsymbol{c}, \quad i \in \mathbb{N}. $$
By (12),  $\lim_{i \rightarrow \infty}\boldsymbol{v}_i = \infty$. Then we only need to prove that a sufficiently large number N can be chosen such that
 $D^{(i)} \leq 0$ for every
 $i \geq N$. Equivalently, by Lemmas 1 and 2, we only need to show that a set
 $\{\boldsymbol{k}^{(i)}\colon i \in \mathbb{Z}_{+}\}$ can be found such that
 $\Delta^{(i)}\leq\boldsymbol{0}$. To accomplish this, for every
 $i \in \mathbb{Z}_{+}$, define
 $$ \Lambda^{(i)}\big(\boldsymbol{k}^{(i)}\big)\,{:\!=}\, \Delta^{(i)} = \Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1} + \sum_{d=0}^{i+1}A_{-i+d}^{(i)}\boldsymbol{k}^{(d)} - \boldsymbol{k}^{(i)}. $$
For sufficiency, suppose that an integer  $N \in \mathbb{N}$ can be selected such that, for every
 $i \geq N$,
 $D^{(i)} \leq 0$. Our purpose is to demonstrate that an integer
 $N^* \geq N$ and
 $\mathcal{K}=\big\{\boldsymbol{k}^{(i)} \in \mathbb{R}_{+}^m\colon i \in \mathbb{Z}_{+}\big\}$ can be determined such that, for
 $i \geq N^*$,
 $\Delta^{(i)} = \Lambda^{(i)}\big(\boldsymbol{k}^{(i)}\big) \leq \boldsymbol{0}$. First, for a certain
 $\mathcal{K}$, we need to verify that the limits of
 $\Gamma^{(i)}\big(\boldsymbol{k}^{(i)}\big)$ and
 $\Lambda^{(i)}\big(\boldsymbol{k}^{(i)}\big)$ exist element-wise. The next thing to do in the proof is
 $\lim_{i\rightarrow\infty}\Gamma^{(i)}\big(\boldsymbol{k}^{(i)}\big) = \lim_{i\rightarrow\infty}\Lambda^{(i)}\big(\boldsymbol{k}^{(i)}\big)$, and when it has been demonstrated that
 $\lim_{i\rightarrow\infty}\Gamma^{(i)}\big(\boldsymbol{k}^{(i)}\big) \leq \boldsymbol{0}$, then we can establish the sufficiency of Theorem 1(i).
Before finding the sequence  $\mathcal{K}$, we need to construct the sequence
 $\mathscr{K}=\big\{\boldsymbol{\mathfrak{K}}^{(i)}\in\mathbb{R}_{+}^m\colon i \in \mathbb{Z}_{+}\big\}$. To achieve this goal, we commence with the inequality
 \begin{equation*} \Gamma^{(i)}\big(\boldsymbol{\mathfrak{K}}^{(i)}\big) = \Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1} + \big(A^{(i)}-I\big)\boldsymbol{\mathfrak{K}}^{(i)} \leq \boldsymbol{0}. \end{equation*}
The given condition implies that  $D^{(i)}$ is a non-positive number for all i. Therefore, the inequality can be satisfied by solving the equalities represented as
 $\Gamma^{(i)}\big(\boldsymbol{\mathfrak{K}}^{(i)}\big) = D^{(i)}\boldsymbol{1}$; then
 \begin{equation} \big(A^{(i)}-I\big)\boldsymbol{\mathfrak{K}}^{(i)} = D^{(i)}\boldsymbol{1} - \Bigg(\sum_{d=-i}^{1}d A_{d}^{(i)}\Bigg)\boldsymbol{1}. \end{equation}
From the fact that  $A^{(i)}-I$ is non-invertible, and by [Reference Meyer15, Theorem 2.1] and Assumption 2, a unique group inverse
 $(B^{(i)})^{\#}$ can be identified, where
 $B^{(i)}=I-A^{(i)}$. For (13), it is easily seen from [Reference Rao and Mitra18, Theorem 2.2] that
 \begin{equation} \boldsymbol{\mathfrak{K}}^{(i)} = -\big(B^{(i)}\big)^{\#}\Bigg(D^{(i)}\boldsymbol{1} - \Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1}\Bigg) + \big(I-\big(B^{(i)}\big)^{\#}B^{(i)}\big)\boldsymbol{z_i}, \end{equation}
where  $\boldsymbol{z_i} \in \mathbb{R}^m$ is an arbitrary constant vector for each
 $i \geq 1$. By [Reference Meyer15, Theorem 2.3], we can further simplify (14) by
 $\boldsymbol{1}\boldsymbol{\pi}^{(i)} = I-\big(B^{(i)}\big)^{\#}B^{(i)}$. Substituting this into (14),
 \begin{equation*} \boldsymbol{\mathfrak{K}}^{(i)} = -\big(B^{(i)}\big)^{\#}\Bigg(D^{(i)}\boldsymbol{1} - \Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1}\Bigg) + \boldsymbol{1}\boldsymbol{\pi}^{(i)}z_i. \end{equation*}
For some  $\bar{\zeta}_i \in \mathbb{R}^{+}$, let
 $\boldsymbol{z_i} \,{:\!=}\, \bar{\zeta}_i \boldsymbol{1} \in \mathbb{R}^m$; then
 \begin{equation*} \boldsymbol{\mathfrak{K}}^{(i)} = -\big(B^{(i)}\big)^{\#}\Bigg(D^{(i)}\boldsymbol{1} - \Bigg(\sum_{d=-i}^{1}dA_{d}^{(i)}\Bigg)\boldsymbol{1}\Bigg) + \bar{\zeta}_i\boldsymbol{1}. \end{equation*}
Next, we demonstrate that a positive sequence  $\big\{\bar{\zeta}_i\colon i \in \mathbb{N}\big\}$ can be selected such that
 $\boldsymbol{\mathfrak{K}}^{(i)} \geq \boldsymbol{0}$. By Assumption 1, the sequence
 $\big\{A_d^{(i)}\big\}$ is convergent as i approaches infinity for any fixed
 $d \in \{-i,-i+1,\ldots,1\}$, and hence also
 $I-A^{(i)}$ is convergent. By [Reference Cordeiro, Kharoufeh and Oxley6, Lemma 3 and Proposition 4],
 $$ \lim_{i\rightarrow\infty}\big(B^{(i)}\big)^{\#} = \Big(\lim _{i \rightarrow \infty}B^{(i)}\Big)^{\#}, $$
which guarantees that the sequence  $\big\{{-}\big(B^{(i)}\big)^{\#}\big(D^{(i)}\boldsymbol{1}-\big(\sum_{d=-i}^{1}dA_{d}^{(i)}\big)\boldsymbol{1}\big), i\in \mathbb{N}\big\}$ is convergent. Based on (10) and (11), the limit can be defined as
 $B^*\,{:\!=}\,\lim _{i \rightarrow \infty} B^{(i)}$ and the function
 $\kappa$ can be defined as
 \begin{equation*} \kappa(x) \,{:\!=}\, -\big(B^*\big)^{\#}\Bigg[D^*\boldsymbol{1} - \Bigg(\sum_{d=-1}^{\infty}-dA_{-d}^{*}\Bigg)\boldsymbol{1}\Bigg] + x\boldsymbol{1}. \end{equation*}
Select an adequately large value for M so that  $\kappa(M) \geq \boldsymbol{0}$, as
 $-\big(B^*\big)^{\#}\big[D^*\boldsymbol{1}-\big(\sum_{d=-1}^{\infty}-dA_{-d}^{*}\big)\boldsymbol{1}\big]$ is a definite vector. In addition, it is easy to see that
 $a_n = \sum_{i=1}^{n}{1}/{i^{2}}$ is convergent, so, for any
 $\varepsilon>0$, an integer
 $\bar{N}$ can be chosen such that
 \begin{equation} \bigg|a_n - \sum_{i=1}^{\infty}\frac{1}{i^{2}}\bigg|
< \varepsilon \end{equation}
for  $n>\bar{N}$, i.e.
 $\big|\sum_{i=n+1}^{\infty}{1}/{i^{2}}\big| < \varepsilon$ for
 $n>\bar{N}$. If
 $\bar{\zeta}_i = M$, then the sequence
 $\big\{\boldsymbol{\mathfrak{K}}^{(i)}\big\}$ is convergent, which ensures that an integer
 $J>\bar{N}$ can be found such that, for every
 $i \geq J$,
 $\boldsymbol{\mathfrak{K}}^{(i)} \geq \boldsymbol{0}$. Thus, define
 $$ \mathscr{K} \,{:\!=}\, \{\boldsymbol{\mathfrak{K}}^{(i)}\colon i=0,\ldots,J-1\} \bigcup \big\{\boldsymbol{\mathfrak{K}}^{(i)}\colon\bar{\zeta}_{i}=M, i \geq J\big\} \subset \mathbb{R}_{+}^m, $$
where  $\big\{\boldsymbol{\mathfrak{K}}^{(i)}\colon i=0,\ldots,J-1\big\} \subset \mathbb{R}_{+}^m$ are arbitrary. Taking into account (9) and (11), it can be inferred that
 $$ \lim_{i\rightarrow\infty}\boldsymbol{\mathfrak{K}}^{(i)} = -\big(B^*\big)^{\#}\Bigg[D^*\boldsymbol{1} - \Bigg(\sum_{d=-1}^{\infty}-dA_{-d}^{*}\Bigg)\boldsymbol{1}\Bigg] + M\boldsymbol{1}. $$
By employing this method, we get a sequence denoted as  $\mathscr{K}$ such that
 $\Gamma^{(i)}\big(\boldsymbol{\mathfrak{K}}^{(i)}\big)$ is a non-positive vector for all i. Because
 $\boldsymbol{\mathfrak{K}}^*=\lim_{i\rightarrow\infty}\boldsymbol{\mathfrak{K}}^{(i)}$, it follows that, for any
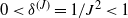 $0<\delta^{(J)}={1}/{J^{2}} <1$, an integer
 $\bar{N}_{J}>J$ can be found such that
 $\big\|\boldsymbol{\mathfrak{K}}^{(i)}-\boldsymbol{\mathfrak{K}}^{*}\big\| \leq \delta^{(J)}={1}/{J^{2}}$ for every
 $i\geq\bar{N}_{J}$. Furthermore, for any
 $0<\delta^{(J+1)}={1}/{(J+1)^{2}} <1$, an integer
 $\bar{N}_{J+1}>\bar{N}_{J}$ can be found such that
 $\big\|\boldsymbol{\mathfrak{K}}^{(i)}-\boldsymbol{\mathfrak{K}}^{*}\big\| \leq \delta^{(J+1)}={1}/{(J+1)^{2}}$ for every
 $i \geq \bar{N}_{J+1}$. Therefore, for a decreasing sequence of positive real numbers
 $\delta^{(i)} = {1}/{i^2}$,
 $i \geq J$, there exists an increasing sequence of integers
 $\bar{N}_{i}$ corresponding to
 $\delta^{(i)}$ such that
 $\big\|\boldsymbol{\mathfrak{K}}^{(i)}-\boldsymbol{\mathfrak{K}}^*\big\| \leq \delta^{(i)}={1}/{i^2}$ for all
 $i \geq \bar{N}_{i}$. Through this construction, it is evident that the sequence
 $\big\{{\boldsymbol{k}^{(i)}}=\boldsymbol{\mathfrak{K}}^{{(\bar{N}_{i})}}, i \geq J\big\}$ converges to
 $\boldsymbol{k}^*\,{:\!=}\,\boldsymbol{\mathfrak{K}}^*$ as i goes to infinity. Therefore,
 $$ \mathcal{K} \,{:\!=}\, \big\{\boldsymbol{k}^{(i)}=\boldsymbol{\mathfrak{K}}^{(i)}\colon i=0,\ldots,J-1\big\} \bigcup \big\{\boldsymbol{k}^{(i)}=\boldsymbol{\mathfrak{K}}^{{(\bar{N}_{i})}}, i \geq J\big\} \subset \mathbb{R}_{+}^m. $$
Since  $\boldsymbol{k}^*=\lim _{i \rightarrow \infty} \boldsymbol{k}^{(i)}$, it follows that the two sequences
 $\big\{A_d^{(i)}\boldsymbol{k}^{(i)}\colon i \in \mathbb{Z}_{+}\big\}$ and
 $\big\{A^{(i)}\boldsymbol{k}^{(i)}\colon i \in \mathbb{Z}_{+}\big\}$ are also convergent. Clearly, we obtain the convergence of
 $\big\{\Gamma^{(i)}\big(\boldsymbol{k}^{(i)}\big)\colon i \in \mathbb{Z}_{+}\big\}$ and
 $\big\{\Lambda^{(i)}\big(\boldsymbol{k}^{(i)}\big)\colon i \in \mathbb{Z}_{+}\big\}$. In light of (9), as
 $i \rightarrow \infty$,
 $$ \Gamma^{(i)}\big(\boldsymbol{k}^{(i)}\big) \rightarrow \Bigg(\sum_{d=-1}^{\infty}-dA_{-d}^{*}\Bigg)\boldsymbol{1} + \big(A^*-I\big)\boldsymbol{k}^* \leq \boldsymbol{0}. $$
Since  $\lim_{i\rightarrow\infty}A^{(i)}\boldsymbol{1} = \lim_{i\rightarrow\infty}\sum_{d=-i}^{1}A^{(i)}_{d}\boldsymbol{1} = \boldsymbol{1}$, we have that
 \begin{equation} \lim_{i \rightarrow \infty} A^{(i)}_{-i}\boldsymbol{1}=\boldsymbol{0}. \end{equation}
For any  $\varepsilon>0$ and for a sufficiently large integer i,
 \begin{align*} \big\|\Lambda^{(i)}\big(\boldsymbol{k}^{(i)}\big) - \Gamma^{(i)}\big(\boldsymbol{k}^{(i)}\big)\big\| & = \Bigg\|\sum_{d=-i}^{1}dA_{d}^{(i)}\boldsymbol{1} + \sum_{d=0}^{i+1}A_{-i+d}^{(i)}\boldsymbol{k}^{(d)} - \boldsymbol{k}^{(i)} - \sum_{d=-i}^{1}dA_{d}^{(i)}\boldsymbol{1} \\ & \qquad - \sum_{d=0}^{i+1}A_{-i+d}^{(i)}\boldsymbol{k}^{(i)} + \boldsymbol{k}^{(i)}\Bigg\| \\ & = \Bigg\|\sum_{d=0}^{i+1}A_{-i+d}^{(i)}\boldsymbol{k}^{(d)} - \sum_{d=0}^{i+1}A_{-i+d}^{(i)}\boldsymbol{k}^{(i)}\Bigg\| \\ & = \Bigg\|\sum_{d=0}^{i+1}A_{-i+d}^{(i)}\big(\boldsymbol{k}^{(d)} - \boldsymbol{k}^{(i)}\big)\Bigg\| \\ & \leq \Bigg\|\sum_{d=0}^{J-1}A_{-i+d}^{(i)}\big(\boldsymbol{k}^{(d)}-\boldsymbol{k}^{(i)}\big)\Bigg\| + \Bigg\|\sum_{d=J}^{i+1}A_{-i+d}^{(i)}\big(\boldsymbol{k}^{(d)}-\boldsymbol{k}^{(i)}\big)\Bigg\| \\ & \leq J\eta\frac{\varepsilon}{J\eta} + \Bigg\|\sum_{d=J}^{i+1}\big(\boldsymbol{k}^{(d)} - \boldsymbol{k}^{*} + \boldsymbol{k}^{*} - \boldsymbol{k}^{(i)}\big)\Bigg\| \\ & \leq \varepsilon + \Bigg\|\sum_{d=J}^{i+1}\big(\boldsymbol{k}^{(d)}-\boldsymbol{k}^{*}\big)\Bigg\| + \big\|\boldsymbol{k}^{*} - \boldsymbol{k}^{(i)}\big\| \\ & \leq \varepsilon + \sum_{d=J}^{i+1}\frac{1}{d^{2}} + \varepsilon \leq \varepsilon + \varepsilon + \varepsilon = 3\varepsilon, \end{align*}
where  $\eta \,{:\!=}\, \max\big\{\big\|\boldsymbol{k}^{(d)}-\boldsymbol{k}^{(i)}\big\|=\sum_{j=1}^{m}|k_{dj}-k_{ij}|, d=0,1,\ldots,(J-1)\big\}$ and, by (16),
 $\big\|A_{-i+d}^{(i)}\big\| < {\varepsilon}/{J\eta}$ for
 $d=0,1,\ldots,(J-1)$ and
 $\big\|A_{-i+d}^{(i)}\big\| < 1$ for
 $d \geq J$; and, by (15),
 $\sum_{d=J}^{i+1}{1}/{d^{2}}<\varepsilon$. Thus, an integer
 $N^*>N$ can be determined in such a way that
 $\Lambda^{(i)}\big(\boldsymbol{k}^{(i)}\big)$ is also a non-positive vector for each
 $i \geq N^*$. Therefore, we conclude the proof of sufficiency.
For the necessity, as in the proof of necessity for [Reference Cordeiro, Kharoufeh and Oxley6, Theorem 3(i)], this proof is omitted.
For (ii), the proof closely parallels that of (i), with the major difference being the substitution of [Reference Fayolle, Malyshev and Menshikov7, Theorem 2.2.3] for the drift criterion for recurrence.
4.2. Proof of Corollary 1
Proof. For (i), according to the given condition, it follows that
 \begin{equation} D^*=\lim _{i \rightarrow \infty} D^{(i)}. \end{equation}
Then an integer  $N>0$ can be found such that
 $D^{(i)}$ becomes non-positive for each
 $i \geq N$, and hence also that
 $\boldsymbol{\Phi}$ is recurrent from Theorem 1(i).
Given that  $\boldsymbol{\Phi}$ is recurrent, from Theorem 1 an integer N can be selected such that, for every
 $i \geq N$,
 $D^{(i)}$ becomes non-positive. By (17), it follows that
 $D^* \leq 0 $.
For (ii), given that  $D^* < 0$, it can be deduced that an integer N can be determined such that
 $D^{(i)}$ becomes strictly negative for all
 $i > N$. Consequently, from Theorem 1(ii),
 $\boldsymbol{\Phi}$ is positive recurrent.
Given that  $\boldsymbol{\Phi}$ is positive recurrent, by Theorem 1, for
 $\varepsilon > 0$, a large enough number N can be determined in such a way such that
 $D^{(i)} \leq-\varepsilon$ for every
 $i\geq N$. By (17), it follows that
 $D^* \leq-\varepsilon$.
Part (iii) can be derived directly from (i) and (ii), and finally (iv) can be inferred directly from (i).
4.3. Proof of Theorem 2
Proof of Theorem 2(i). For the sufficiency of (i), define the matrix functions by  $\mathcal{A}^{(i)}(z)= \sum_{d=-1}^{i}A_{-d}^{(i)}z^{-d}$ and
 $\mathcal{A}^{*}(z)= \sum_{d=-1}^{\infty}A_{-d}^{*}z^{-d}$. For
 $z\geq 1$, define
 $\sigma^{*}(z)$ as the Perron–Frobenius eigenvalue of
 $\mathcal{A}^{*}(z)$. There exists a vector
 $u^{*}(z)$ such that
 \begin{equation} \mathcal{A}^{*}(z)u^{*}(z)=\sigma^{*}(z)u^{*}(z). \end{equation}
Choose  $u^{*}(z) \geq \boldsymbol{1}$, due to its component being strictly positive.
For any fixed  $z>1$, based on Assumption 3,
 \[ \big\|\mathcal{A}^{(i)}(z)-\mathcal{A}^{*}(z)\big\|_{1} = \Bigg\|\sum_{d=n+1}^{\infty}z^{-d}A_{-d}^{(i)}1_{(d \leq i)}\Bigg\|_{1}
< \Bigg\|\sum_{d=n+1}^{\infty}-dA_{-d}^{(i)}\boldsymbol{1}1_{(d \leq i)}\Bigg\| = \|f_{n}(i)-f(i)\|. \]
By Assumption 1, we use similar arguments to (9) to yield that  $\lim_{i\rightarrow \infty} \mathcal{A}^{(i)}(z)= \mathcal{A}^{*}(z)$. Then, for any
 $\varepsilon>0$, an integer N can be determined such that
 \begin{equation} \mathcal{A}^{(i)}(z)\leq \mathcal{A}^{*}(z)+\varepsilon E, \quad i>N, \end{equation}
where E consists entirely of elements with a value of 1. Since  $\mathcal{A}^{*}(1)\boldsymbol{1}=\boldsymbol{1}$, it follows that
 \begin{equation} u^{*}(1)=\boldsymbol{1} \quad \mbox{and} \quad \sigma^{*}(1)=1. \end{equation}
Differentiating both sides of (18) with respect to z gives
 \begin{equation*} {\mathcal{A}^{*}}'(z)u^{*}(z)+\mathcal{A}^{*}(z){u^{*}}'(z)={\sigma^{*}}'(z)u^{*}(z)+\sigma^{*}(z){u^{*}}'(z). \end{equation*}
Premultiplying both sides of this by  $\boldsymbol{\pi}^{*}$ yields
 \begin{equation} \boldsymbol{\pi}^{*}{\mathcal{A}^{*}}'(z)u^{*}(z) + \boldsymbol{\pi}^{*}\mathcal{A}^{*}(z){u^{*}}'(z) = \boldsymbol{\pi}^{*}{\sigma^{*}}'(z)u^{*}(z) + \boldsymbol{\pi}^{*} \sigma^{*}(z){u^{*}}'(z). \end{equation}
Substituting from  $z = 1$ into (21) obtains
 \begin{equation*} \boldsymbol{\pi}^{*}{\mathcal{A}^{*}}'(1)u^{*}(1) + \boldsymbol{\pi}^{*}\mathcal{A}^{*}(1){u^{*}}'(1) = \boldsymbol{\pi}^{*}{\sigma^{*}}'(1)u^{*}(1) + \boldsymbol{\pi}^{*} \sigma^{*}(1){u^{*}}'(1). \end{equation*}
Substituting from (20) into (21) shows
 \[ \boldsymbol{\pi}^{*}\Bigg(\sum_{d=-1}^{\infty}-dA_{-d}^{*}\Bigg)\boldsymbol{1} + \boldsymbol{\pi}^{*}{u^{*}}'(1) = {\sigma^{*}}'(1)+\boldsymbol{\pi}^{*}{u^{*}}'(1), \]
i.e.  ${\sigma^{*}}'(1) = \boldsymbol{\pi}^{*}\big(\sum_{d=-1}^{\infty}-dA_{-d}^{*}\big)\boldsymbol{1} = D^{*}$. From Corollary 1(ii),
 ${\sigma^{*}}'(1)$ is strictly negative. Combining this with (20), we can deduce that a number
 $z > 1$ can be found such that
 $\sigma^{*}(z)$ is less than 1. Let
 $V_{i} = z^{i} u^{*}(z)$,
 $i \geq 1$, and
 $\lambda=\sigma^{*}(z)+\varepsilon \boldsymbol{1}^\top u^{*}(z)$ for any
 $z>0$ and any
 $0 < \varepsilon < ({1-\sigma^{*}(z)})/{\boldsymbol{1}^\top u^{*}(z)}$. For
 $i \geq N+1$,
 \begin{equation*} (PV)_{i} = \sum_{d=-i}^{1}A_{d}^{(i)}V_{i+d} = z^{i}\Bigg(\sum_{d=-i}^{1} z^{d}A_{d}^{(i)}\Bigg)u^{*}(z) = z^{i}\mathcal{A}^{(i)}(z) u^{*}(z). \end{equation*}
Applying (19) to this implies
 \begin{align*} z^{i}\mathcal{A}^{(i)}(z) u^{*}(z) & \leq z^{i}(\mathcal{A}^{*}(z)+\varepsilon E) u^{*}(z) \\ & = z^{i}\mathcal{A}^{*}(z) u^{*}(z)+z^{i} \varepsilon E u^{*}(z) \\ & = z^{i}\sigma^{*}(z) u^{*}(z)+ z^{i} \varepsilon E u^{*}(z) \\ & = \sigma^{*}(z) V_{i}+ z^{i}\varepsilon [\boldsymbol{1}^\top u^{*}(z)]\boldsymbol{1} \\ & = \sigma^{*}(z) V_{i}+ z^{i}\varepsilon \boldsymbol{1}^\top u^{*}(z)u^{*}(z)
< (\sigma^{*}(z)+\varepsilon \boldsymbol{1}^\top u^{*}(z)) V_{i}. \end{align*}
Hence, we conclude that  $(PV)_{i} \leq \lambda V_{i}$. For
 $i=0$,
 \begin{equation*} (PV)_{0} = A^{(0)}_{0}V_{0} + A^{(0)}_{1}V_{1} \leq \lambda V_{0}+\Big\{\max_{1\leq j\leq m}\big(A^{(0)}_{0}V_{0}+A^{(0)}_{1}V_{1}-\lambda V_{0}\big)_{j}\Big\}\boldsymbol{1}, \\ \end{equation*}
and for  $i \in \mathbb{N}_N$,
 \begin{equation*} (PV)_{i} = \sum_{d=-i}^{1}A_{d}^{(i)}V_{i+d} \leq \lambda V_{i}+\Bigg\{\max_{1\leq j\leq m}\Bigg(\sum_{d=-i}^{1}A_{d}^{(i)}V_{i+d}-\lambda V_{i}\Bigg)_{j}\Bigg\} \boldsymbol{1}. \end{equation*}
Hence, the drift condition holds, with  $V_{i}=z^{i}u^{*}(z)$,
 $\lambda = \sigma^{*}(z) + \varepsilon\boldsymbol{1}^\top u^{*}(z) < 1$,
 $C=L_{\leq N}$, and
 \begin{align*} b & = \max\Bigg\{\max_{1\leq j\leq m}\big(A^{(0)}_{0}u^{*}(z)+A^{(0)}_{1}zu^{*}(z)-\lambda u^{*}(z)\big)_{j}, \\ & \qquad\qquad \max_{i\in\{1,2,\ldots,N\}}\max_{1\leq j\leq m} \Bigg(\sum_{d=-i}^{1}A_{d}^{(i)}z^{i+d}u^{*}(z) - \lambda z^{i}u^{*}(z)\Bigg)_{j}\Bigg\}, \end{align*}
where  $z>1$ satisfies the inequality
 $\sigma^{*}(z)<1$. Therefore, we have that the process is geometrically ergodic.
For the necessity of (i), it is apparent that if the process is geometrically ergodic, then it is ergodic. This completes the proof.
Before proving (ii), we first introduce the following lemma taken from [Reference Chen3, Proposition 2.14], which will be used later.
Lemma 5. The series  $\big\{F_{i,L_{\leq n}}(s), i \geq 0\big\}$ are the minimal non-negative solution of the equations
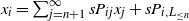 $x_i=\sum_{j=n+1}^{\infty} s P_{i j} x_j+s P_{i, L_{\leq n}}$,
 $i \geq 0$,
 $s \geq 0$, where
 $$ \left\{ \begin{array}{l@{\kern+12pt}l} F_{i,L_{\leq n}}(s) = s\displaystyle\sum_{d=-i}^{-i+n}A_d^{(i)}\boldsymbol{1} + s\displaystyle\sum_{d=n+1}^{i+1}A_{-i+d}^{(i)}F_{d,L_{\leq n}}(s), & i \geq n, \ s \geq 0, \\ F_{i,L_{\leq n}}(s) = s\displaystyle\sum_{d=-i}^1 A_d^{(i)}\boldsymbol{1}, & 0 \leq i<n, \ s \geq 0. \end{array}\right. $$
Proof of Theorem 2(ii). Based on Assumptions 1, 2, and 4, we use similar arguments as for (9), yielding  $\lim_{i \rightarrow \infty}A^{(i)}(z)=A^{*}(z)$ for any fixed
 $z \in (1,\phi_{{A}^{*}})$. Based on this, it can be deduced that for any
 $\varepsilon>0$ an integer
 $\hat{N}$ can be determined such that
 $A^{(i)}(z)\leq A^{*}(z)+\varepsilon E$,
 $i>\hat{N}$. Define
 $\sigma(z)$ as the Perron–Frobenius eigenvalue of
 $A^{*}(z)$; two vectors
 $v^\top(z)$ and u(z) can be determined such that
 $v^\top(z)A^{*}(z) = \sigma(z)v^\top(z)$ and
 $A^{*}(z)u(z) = \sigma(z)u(z)$. We also choose
 $v^\top(1)=\boldsymbol{\pi}^{*}$ and
 $u(1) = \boldsymbol{1}$. When
 $\phi_{A^{*}}$ is greater than 1, for any
 $z \in (1, \phi_{A^{*}})$, it follows that
 $\sigma(z)< \infty$ is continuous with respect to z, so
 $u(z)<\infty$. Choose an integer
 $N>\hat{N}$ such that
 $z^{N}\boldsymbol{1} \leq u(z) \leq z^{N+1}\boldsymbol{1}$, since each component of u(z) is positively non-zero. Define W to be a column vector, with ith component denoted by
 $W_i$, where
 $W_i=({1}/{z^{i}})u(z)$ for any
 $i \geq N+1$ and
 $z \in(1,\phi_{A^{*}})$, and
 $W_i=\boldsymbol{1}$ for any
 $0\leq i \leq N$. For
 $i \geq N+1$,
 $W_{i}<\boldsymbol{1}$, and
 \begin{align} (PW)_i & = \sum_{d=-i}^{-i+N}A^{(i)}_{d}\boldsymbol{1}+\sum_{d=-i+N+1}^{1} A_d^{(i)} z^{-d-i} u(z) \nonumber \\ & = \sum_{d=-i}^{-i+N}A_d^{(i)}\boldsymbol{1} + \Bigg(\sum_{d=-i}^{1}A_d^{(i)}z^{-d-i} - \sum_{d=-i}^{-i+N}A_d^{(i)}z^{-d-i}\Bigg)u(z) \nonumber \\ & \leq \sum_{d=-i}^{-i+N}\big(A_d^{(i)}\boldsymbol{1} - A_d^{(i)}z^{-d-i}u(z)\big) + \sum_{d=-i}^{1}A_d^{(i)}z^{-d-i}u(z) \nonumber \\ & \leq \sum_{d=-i}^{1} A_d^{(i)} z^{-d-i} u(z) \nonumber \\ & \leq A^{*}(z)z^{-i}u(z) + \varepsilon E z^{-i}u(z) \nonumber \\ & = \sigma(z) W_i + \varepsilon z^{-i} \boldsymbol{1}^\top u(z)\boldsymbol{1} \nonumber \\ & \leq \sigma(z) W_i + \varepsilon z^{-i} \boldsymbol{1}^\top u(z)u(z) = (\sigma(z) + \varepsilon\boldsymbol{1}^\top u(z))W_i
< \infty. \end{align}
Since  $\sigma(1)=1$,
 $\sigma^{\prime}(1)=-D^{*}<0$ and
 $\sigma(z)$ is a continuous function on
 $z \in (0,\phi_{{A}^{*}})$ on account of the continuity of
 $\sigma(z)$, it follows that a number
 $\hat{z} \in (1,\phi_{{A}^{*}})$ can be selected such that
 $\sigma(\hat{z})<1$. Taking
 $\varepsilon < ({1-\sigma(\hat{z})})/{\boldsymbol{1}^\top u(\hat{z})}$, we have
 $\sigma(\hat{z}) + \varepsilon\boldsymbol{1}^\top u(\hat{z})<1$; then
 $\lambda \,{:\!=}\, \sigma(\hat{z}) + \varepsilon\boldsymbol{1}^\top u(\hat{z})<1$, and the drift condition (22) holds. Let
 $\hat{V}_i=F_{i,L_{\leq N}}({1}/{\lambda})$. By Lemma 5 and the comparison theorem for the minimal non-negative solution [Reference Chen3, Theorem 2.6], we have
 $\hat{V}_i \leq W_i$. Actually, for any
 $i \geq N+1$, since
 $\tilde{F}_{i,L_{\leq N}}(s)=F_{i,L_{\leq N}}(s)$, it can be inferred that
 \begin{equation} F_{i,L_{\leq N}}\bigg(\frac{1}{\lambda}\bigg) = \hat{V}_i = \frac{1}{\lambda}(P\hat{V})_i \leq \frac{1}{\lambda}(PW)_i
< \infty. \end{equation}
It can be derived from [Reference Mao and Song13, (2.5)] that
 \begin{equation} F_{N,L_{\leq N}}(s) = s\sum_{d=-N}^{0}A_{d}^{(N)}\boldsymbol{1} + sA_{1}^{(N)}F_{N+1,L_{\leq N}}(s), \quad s \geq 0, \end{equation}
and for any  $0\leq i < N$,
 $F_{i, L_{\leq N}}(s) =s\sum_{d=-i}^{1}A_{d}^{(i)}\boldsymbol{1}$,
 $s \geq 0$, which, in conjunction with (23) and (24), implies that
 \begin{equation} F_{i,L_{\leq N}}\bigg(\frac{1}{\lambda}\bigg)
< \infty \end{equation}
for  $0 \leq i \leq N$. Given that the chain is transient, it can be concluded that
 $(F_{i, L_{\leq N}}(1))_j < 1$ for
 $0 \leq i \leq N$ and some
 $j \in \mathbb{N}_{m}$. From this and (25), it follows that a number
 $s_0$ can be determined such that
 \begin{equation*} (F_{i,L_{\leq N}}(s_{0}))_j = \mathbb{E}_{(i,j)}\Big[s_{0}^{{\tau_{L_{\leq N}}}}1_{\{\tau_{{L_{\leq N}}}<\infty\}}\Big]
< \infty, \end{equation*}
for  $0 \leq i \leq N$,
 $j \in \mathbb{N}_{m}$, for some
 $s_0 \in (1, {1}/{\lambda})$. From this and [Reference Liu, Li and Li12, Remark 2], we conclude that the process is geometrically transient.
5. Concluding remarks
We have established a classification of the stability of the specific class of level-dependent GI/M/1-type Markov chains based mainly on drift criteria and the limiting average drift. Specifically, if only Assumptions 1 and 2 hold, then all the results presented in this paper still remain valid for a matrix P in the form of a  $k+2$
 $(k > 1)$ diagonal matrix.
It is equally important to investigate the stability and instability for level-dependent continuous-time chains of GI/M/1 type, which can be done easily. Given a continuous-time Markov chain (CTMC)  $\boldsymbol{\Phi}_t$ with uniformly bounded generator
 $Q=(q_{ij})$ and transition function
 $P(t)=(P_{ij})(t)$, for any
 $h<{1}/{\sup_{i\in S}(-q_{ii})}$, the transition matrix
 ${_h}P=({_h}P_{ij})$ for its h-uniformized chain
 ${_h}\boldsymbol{\Phi}_{n}$ can be determined by [Reference Anderson1, Proposition 2.10] as
 $_{h}P=I+hQ$. By [Reference Liu and Hou11, Lemmas 2.2 and 2.3], the given CTMC
 $\boldsymbol{\Phi}_t$ is geometrically or algebraically ergodic if and only if its h-uniformized chain
 ${_h}\boldsymbol{\Phi}_n$ is. It has been shown [Reference Liu, Li and Li12, p. 1325] that
 $\boldsymbol{\Phi}_t$ is geometrically or algebraically transient if and only if
 ${_h}\boldsymbol{\Phi}_n$ is. By using the results in Section 3 and the technique of uniformization, we can establish the criteria for the corresponding stability and instability for CTMCs of GI/M/1 type.
Acknowledgements
We are very grateful to two anonymous referees for helpful comments, which helped us to improve the presentation of this paper.
Funding Information
This research was supported in part by the National Natural Science Foundation of China (Grant No. 12471148), the Innovation Program of Central South University (Grant No. 2021zzts0039) and the Hunan Province Postgraduate Innovation Program (Grant No. 150110039).
Competing Interests
There were no competing interests to declare which arose during the preparation or publication process of this article.


