


I. INTRODUCTION
In early 1813, Samuel Tertius Galton (1783–1844), a merchant and banker from Birmingham, published a pamphlet entitled A Chart, exhibiting the Relation between the Amount of Bank of England Notes in Circulation, the Rate of Foreign Exchanges, and the Prices of Gold and Silver Bullion and of Wheat; Accompanied with Explanatory Observations. With the exception of a brief abstract in the Monthly Review, this pamphlet remained quite unknownFootnote 1 and seemed to have been ignored by major characters of the Bullion Controversy. Actually, unpublished materials held in the British Library show that Galton’s manuscript had been commented on—sometimes extensively—by important figures of the period: Francis Horner (1778–1817), Robert Mushet (1782–1828), and David Ricardo (1772–1823) in private correspondence.
Ricardo’s comments on Galton’s Chart were particularly interesting insofar as they dealt with important issues of his thought. Ricardo first developed a significant aspect of his monetary theory in relation to the fiduciarity of the coin by introducing a distinction between a deteriorated and a depreciated currency. In the next set of remarks, he considered the determination of the real par of exchange between countries admitting two different standards of money. On this occasion, the particularly complex practical problem of the determination of the relative value of gold to silver was treated in a more exhaustive way than in any of his published writings. Finally, Ricardo turned to the relation between variations in the issues of the Bank of England and variations in the price of gold and in the foreign exchange since 1797. He thus explained why, according to him, Galton should not have included small notes in his chart of the amount of money in circulation.
The two letters by David Ricardo published and commented on in this paper were written on 6 December Reference Ricardo1812 and 3 March 1813. The first one was sent to Leonard Horner (1785–1864) and the second one to Samuel Tertius Galton. Ricardo’s letter to Horner is rather long (more than 900 words) and is devoted entirely to questions of monetary theory. Ricardo’s letter to Galton is very short (sixty words) and formal (written in the third person and unsigned). Ricardo wrote it to thank Galton for having sent him the recently published Chart. It has no theoretical content but is very useful to identify the work commented on by Ricardo in his letter to Horner.
These two letters used to be included in the famous collection belonging to Sir Thomas Phillipps (1792–1872)Footnote 2 and were part of a set of letters sold by Sotheby’s on 13 June 1991. Their current owner(s) and location(s) are unknown.Footnote 3 Fortunately, there are photocopies of these letters, as well as of other items obviously coming from Galton’s papers. They are all stored in the British Library under the quote R.P. 4978. Among the ten items with this same shelf mark are photocopies of:
—the two letters by David Ricardo published in this article (R.P. 4978/2);
—one letter by Francis Horner to his brother Leonard on 30 November Reference Horner1812 (R.P. 4978/6);Footnote 4
—two letters by Robert Mushet, one written to Leonard Horner on 16 December Reference Horner1812 and the other to Galton on 27 February Reference Mushet1813 (R.P. 4978/3); and
—one letter by Leonard Horner to Galton dated 17 December Reference Horner1812 (R.P. 4978/4).Footnote 5
All these letters deal with the manuscript or the publication of Galton’s Chart. Of the six letters composing this set, only the two written by Ricardo will be fully published here. They are the only known writings from Ricardo to these two correspondents. Indeed, there is no letter from Ricardo to Leonard Horner or to Galton in Piero Sraffa’s edition of Ricardo’s Works and Correspondence, and the few letters by Ricardo published after Sraffa’s masterpiece was released were addressed to other figures.Footnote 6 Other unpublished items mentioned above will be referred to and quoted, sometimes extensively, in the commentary when relevant.
Given the historical and analytical importance of Ricardo’s letters, their publication will be followed by an extensive commentary. Section II will give a material description of the letters based on the photocopies held in the British Library. It includes their in extenso transcripts. Section III will summarize the historical context in which the letters were written and bring to light a hitherto unknown episode in the co-operation between three prominent figures of the Bullion Controversy: Ricardo, Francis Horner, and Mushet. Finally, section IV will comment on the analytical content of Ricardo’s letter to Leonard Horner. References will be made to passages from Galton’s pamphlet or from Mushet’s letter to Galton when relevant with regard to Ricardo’s remarks.
II. THE LETTERS: DESCRIPTION AND TRANSCRIPTSFootnote 7
From the photocopies of the two letters by Ricardo kept at the British Library, it appears that these autographs were bounded in one or two different volumes. The first letter, to Leonard Horner, was glued on page “319” of a volume (with 319 written on the top right-hand corner of the page). At the bottom of this page is an allograph writing: “David Ricardo Merchant & political Economist Born 1772. Died 1823.” It appears that the letter itself is composed of a bi-sheet in-2° and of a sheet in-4°. It was written full-page. The bi-sheet measures 448 mm by 370 mm and the in-4° sheet 185 mm by 224 mm. None of them bears a mark of wax seal. The second letter to Galton is also glued in a volume on page “43” (with 43 written on the top right-hand corner of the page). At the bottom of this page is the allograph writing: “David Ricardo Merchant & Political Economist. Born 1772 Died 1823.” The letter itself is a single sheet in-4° written full-page. It measures 124 mm by 200 mm and bears no mark of wax seal.
Ricardo, David. ALS to Leonard Horner, discussing bullion, the circulation of currency and exchange rates, 6 December 1812, British Library, R.P. 4978/2 f. 1-5
[1r]
Upper Brook Street
6.th Dec.r 1812.
My dear Sir
I have looked over your friend’s MS with much attention and find but very few positions with which I do not entirely agree. I differ from him on one or two points which do not in the least affect the main question, and which, if altered to what I consider critically correct, might perhaps tend rather to perplex than to enlighten those for whose perusal it is intended. My objections, however, shall be stated.
It does not appear to me to follow as a necessary consequence that in proportion as the coins in circulation are diminished in weight by wear, they will become depreciated in value. It is possible that a currency might consist wholly of coin diminished in weight by wear, 10 or even 20 pct., without any effect being produced on the price of bullion. Whether the price of bullion would rise under such circumstan[1v]ces would depend entirely on the abundance of such coin. Coin is never depreciated but by excess of quantity. The assertion therefore at the bottom of page 2 though practically correct, because worn coins have always been accompanied by an excess of paper money, is not correct in theory. Coins may be deteriorated without raising the price of bullion, but |the standard| bullion cannot rise above the mint price unless the currency is depreciated.
If these remarks are correct it will follow also that the definition (Page 3) of the par of exchange is not theoretically true. If the currency of one country were clipped or worn, but existed in such a degree of scarcity as to preserve its standard value a given weight of such clipped coin would be equivalent to more than an equal weight of the more perfect coins of another country, and the par of exchange would be regulated not by what the quantity of pure bullion which the coins actually contained but by the quantity which they ought to contain. Ninety pct. of one might be of equal value with 100 pct. of the other. With [2r] this reservation I should agree with the author in all his observations on the exchange.
Mr. Mushet’s tables may be considered as an approximation to truth but by no means as critically correct. In making his calculations on the exchange he has been sometimes obliged to estimate the proportional value of silver to gold by comparing the price of dollar silver to |the price of| standard gold, – sometimes to the price of Portugal gold coin, or to the price of doubloons. At other times he has compared the price of standard silver with one or other of the above description of gold. He has indeed by calculation reduced them all to our standard, but it is obvious that each of the above species of gold & silver is liable to its peculiar variation in the general market on account of local demand, not deviating much from a common standard but still enough to prevent any thing like great accuracy in calculations on the exchange. Mr. Mushet I believe was aware of this and would have always chosen the same quality of gold & silver as the basis of his [2v] calculation, had he been able at all times to have found the prices of them. Not being able to do so he was obliged to be satisfied with such prices as he could obtain. Mr. Mushet’s tables are nevertheless highly valuable, and if they could be divested of this source of error, would, I believe, in every instance, prove the truth of the theory which they were meant to defend.
The variations in the price of gold and in the foreign exchanges would I apprehend accord more exactly with the variations in the issues of the Bank of England since 1797 if in all cases we were to reject altogether the amount of notes in circulation of £5 and under, and it is quite just that they should be so rejected when we consider that the greater part of these notes have been issued as a substitute for the gold coin exported they cannot be accounted as so much added to the amount of currency. If the circulation consisted of notes above £5 to the amount of 15 millions & of 5 millions in specie, – and if in lieu of the specie 5 millions of [3r] notes under £5 were substituted, the circulation would not be augmented, & consequently no effect would be produced on the exchange. In the scale on the Chart such issue would be called an augmentation of 5 millions, and the truth of the theory might be questioned because there would not appear a rise in the price of bullion, or a fall in the exchange proportioned to such an augmented issue. When once the circulation consists wholly of paper it will |be| of little consequence whether the smaller notes are retained or rejected, as the proportions will be precisely the same. These are all the observations which I have to offer. – I hope your friend will be induced to publish his chart & explanation, as I think it very strikingly illustrates the theory which we are both anxious to establish. I trust you will make due allowance for whatever is faulty in this hasty production & believe me
Yrs very sincerely
David Ricardo
Leonard Horner Esq.r
Ricardo, David. AL in the third person to Samuel Tertius Galton, 3 March 1813, British Library, R.P. 4978/2 f. 6
[1r]
Upper Brook Street
3 March 1813
Mr. D. Ricardo presents his respectful compliments to Mr. Galton and begs to return his thanks for the Chart which he has been so good as to send to him. Mr. Ricardo trusts that it will assist to dissipate the cloud of error which at present prevails on the subject of which it treats.
III. THE HISTORICAL CONTEXT OF THE LETTERS
These two letters belong to the early part of Ricardo’s career as a political economist when his writings were devoted to monetary subjects.Footnote 8 Ricardo argued that there was a depreciation of the Bank of England notes, which was caused by an over-issue that the suspension of convertibility in 1797 had made possible.
Ricardo, Mushet, and Francis Horner: Three Prominent Figures of the Bullion Controversy
Ricardo’s first contribution to political economy was an anonymous article published in the Morning Chronicle on 29 August 1809, entitled “The Price of Gold.” According to Sraffa, it “marked the beginning of what came to be known as the Bullion Controversy” (in Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 3). Ricardo’s first publication was followed by an exchange of letters with his friend Hutches Trower. Part of this exchange was published in the Morning Chronicle and the rest of it was private correspondence. In late 1809, Ricardo’s concern about the depreciation of Bank of England notes was echoed in a pamphlet written by Robert Mushet of the Royal Mint: An Enquiry into the Effects produced on the National Currency and Rates of Exchange, by the Bank Restriction Bill. This pamphlet went through three editions (1809, 1810, and 1811). In January 1810, Ricardo published The High Price of Bullion, a Proof of the Depreciation of Bank Notes, which went over the whole content of his letters to the Morning Chronicle again.
These publications produced the expected effect: Francis Horner took the issue to the House of Commons and delivered a speech on 1 February 1810, which led to the appointment of a parliamentary “Select Committee … to enquire into the Cause of the High Price of Gold Bullion” (in Cannan Reference Cannan1969, p. 3). Horner presented the conclusions of the Bullion Committee on 8 June, and wrote the Bullion Report with Henry Thornton and William Huskisson (Horner Reference Horner, Bourne and Taylor1994, p. 643). The Report gave rise to a great deal of controversial writings. On the anti-bullionist side, the most significant publication was the “very unfair but dextrous” (Horner Reference Horner, Bourne and Taylor1994, p. 657) pamphlet written by a merchant of London and governor of the South Sea Company, Charles Bosanquet, who published his Practical Observations on the Report of the Bullion Committee in November 1810.Footnote 9 Horner’s purpose was then to recourse to the Edinburgh Review. He expressed to Francis Jeffrey, editor of the review, his wish “to keep the subject in [his] own hands … for it would be only a continuation of the little [he] did before in the articles upon Thornton and Lord King.”Footnote 10 He promised Jeffrey he would write a short article “to do justice to Mr Ricardo and Mr Mushet, who called the public attention to this very important subject at the end of last year” (Horner Reference Horner, Bourne and Taylor1994, p. 645).Footnote 11 This project was finally abandoned and Horner decided “to do justice to Ricardo” by offering him to publish an article in the Edinburgh Review. However, as he wrote on 3 December: “Ricardo has taken such fright at the notion of writing in the Review, that I have not succeeded in that point; he prefers publishing in a separate pamphlet” (Horner Reference Horner, Bourne and Taylor1994, p. 659).Footnote 12 The pamphlet mentioned in this quotation was Ricardo’s Reply to Bosanquet, which was published in January 1811.
On 9 May 1811, the House of Commons voted to reject the sixteen resolutions moved by Horner. The last one called for the repeal of the Restriction Bill within two years, whether the war was at an end or not. On 13 May, Nicholas Vansittart’s seventeen counter-resolutions were adopted. Vansittart was against the bullionist position and proposed the Restriction Bill be continued for six months after the peace agreement.
In spite of this vote, the questions raised during the Bullion Controversy continued being debated by major bullionist figures. Ricardo’s correspondence between May 1811 and March 1813 shows that he discussed monetary questions with Thomas Robert Malthus, James Mill (Ricardo 1951–Reference Ricardo and Sraffa73, 6, pp. 48–60), and Francis Horner (Ricardo 1951–Reference Ricardo and Sraffa73, 6, pp. 78–81). The correspondence with Malthus shows that Ricardo was in contact with Henry Thornton. Indeed, Ricardo wrote to Malthus on 17 December Reference Ricardo1812 that Thornton “has fixed on monday [21 December 1812] for our meeting but he wishes us to meet at his house as there is to be a debate in the House of Lords on the Bullion question and he is not sure that his presence may not be necessary in the Commons” (Ricardo 1951–Reference Ricardo and Sraffa73, 6, p. 88). Ricardo was also in contact with Mushet, to whom he intended to introduce Malthus in February Reference Mushet1813:
I will endeavor to get Mr. Mushet to meet you at my house at breakfast on sunday morning [28 february]. At any rate I shall expect you, and if Mushet is engaged, I shall be able to tell you whether he will meet us on monday or tuesday in the City. He is exceedingly obliging, and would I am sure not mind trouble, if he could contribute to throw light on the subject of exchanges. (Ricardo 1951–Reference Ricardo and Sraffa73, 6, pp. 88–89)
The Role of Leonard Horner in the Diffusion of Galton’s Manuscript
It is at this time that Samuel Tertius GaltonFootnote 13 published his Chart. The chart itself was a single graph running from January 1760 to January Reference Galton1813. It showed: 1) the amount of Bank of England notes in circulation, 2) the rate of exchange between London and Hamburgh, 3) the market prices of an ounce of gold bullion and of silver bullion, and 4) the average market price of a quarter of wheat. Thirty-two pages of explanatory observations were added to this chart. The publication was thus described by the Monthly Review:
Mr. Galton confines his observations in a great measure to the explanation of his engraved chart.… Mr. Mushet’s tables of bullion and exchange have served for the ground-work of this Chart; and the chief difference between the two is that the one represents by line and spaces that which the other exhibited by numbers. A few observations are added to explain the principles of currency. (Monthly Review 1813, 71, pp. 217–218)
This was Galton’s first and only publication dealing with political economy.
It seems that before writing his Chart, Galton was not personally acquainted with the important figures of the bullion party. He was nevertheless one of Leonard Horner’s closest friends, Francis Horner’s younger brother. Leonard entered the High School of Edinburgh when he was nine years old. At the age of fourteen, in November 1799, he “began to attend lectures at the University of Edinburgh, the Mathematical class of John Playfair, and Dugald Stewart on Moral Philosophy and Political Economy. In 1802 he entered as a student Dr. Hope’s class of Chemistry” (Lyell in Horner Reference Horner and Lyell2011, 1, p. 3) and began to study the Huttonian theory of geology. In 1808, he became a member of the Geological Society of London, and was chosen in 1810 to be one of the two secretaries of the Society. From then on, “the progress of Geology, and the prosperity of the Society, claimed his most zealous attention, and became the chief occupation of his leisure hours” (Lyell in Horner Reference Horner and Lyell2011, 1, p. 13).Footnote 14
Galton and Leonard Horner first met in spring 1803 before the young Scot moved from Edinburgh to London: “Leonard made the acquaintance of Samuel Tertius Galton, who had been sent by his father to pass a winter at Edinburgh University. This acquaintance gradually warmed into a friendship which continued with their lives” (Lyell in Horner Reference Horner and Lyell2011, 1, p. 11). Leonard probably first met Ricardo in 1808 when they both became members of the Geological Society of London. Francis Horner became a member of the Society in 1807. Leonard played an important role in the exchange of letters that involved Galton, Francis Horner, Ricardo, and Mushet. Indeed, it is clear from his letter to Galton dated 17 December 1812 that it is Leonard who sent Galton’s manuscript to his brother Francis, to Ricardo, and to Mushet. Then, Leonard assembled all their comments and forwarded them to Galton. This explains why all these materials were finally found in Galton’s papers:
I took the earliest opportunity after the receipt of your chart, to put it into my brother’s hands. As soon as he returned it to me, I sent it to Ricardo. When it came back from Ricardo.… I went with it to Mushet & within the last half hour he has returned it to me. As you must be anxious to know what I have been about with it, I lose not a moment in forwarding it to you. It shall go by the mail tomorrow. You will find along with it some observations from each of the above gentlemen who have perused it, & I trust you will now have no difficulty in laying it before the public. (R.P. 4978/4, f. 1)
Francis Horner and Mushet agreed that the Chart deserved to be published. Francis Horner judged “Galton’s idea of a Table … very well conceived, for placing before the eye, at once, and in a striking manner, the main proof of depreciation.” He considered it “quite necessary that he [Galton] should accompany it with an explanation, such as he |has| drawn up which is very perspicuous and ? neat” (R.P. 4978/6, f.1 reproduced in Horner Reference Horner, Bourne and Taylor1994, p. 747). He nevertheless suggested “to have the Exchange and the Amount of Notes in two separate ? of divisions of the Table,” for “the way in which they stand at present (upon the same compartment with the price of Gold) is apt to suggest, what is not correctly true; that a given variation in the price of gold is accompanied by a variation, arithmetically the same, in the amount of Notes and course of Exchange” (R.P. 4978/6, f. 1-2, reproduced in Horner Reference Horner, Bourne and Taylor1994, p. 748). He finally criticized Galton for not having “adverted, in the observations which accompany the Table, to the principle which ? legal |makes Gold our present| standard, instead of Silver as anciently” (R.P. 4978/6, f. 2, reproduced in Horner Reference Horner, Bourne and Taylor1994, p. 748).Footnote 15 Then, Mushet answered Leonard Horner that he thought the Chart “calculated to do a great deal for the Bullion cause. His chart is ingenious and gives a very clear & comprehensive view of the subject” (RP4978/3, f.1). Mushet enclosed a copy of his tables running until 4 December Reference Mushet1812 for Galton and added: “I have endeavoured to answer some Queries in M G. letter; and have made a few observations on a part of his MS” (R.P. 4978/3, f. 1). However, there is no trace of Mushet’s answers or observations, or of Galton’s queries, in R.P. 4978.
The day Galton’s Chart was published remains uncertain. Ricardo received it on 3 March Reference Ricardo1813 or earlier. Mushet wrote to Galton on 27 February Reference Galton1813: “I have before this expected to see your M.S. in print; I hope you will not deny the good cause the assistance which it would undoubtly give by its publication” (R.P. 4978/3, f. 5). These indications suggest that Galton’s Chart was published at the end of February or at the beginning of March Reference Galton1813.
IV. THE ANALYTICAL CONTENT OF RICARDO’S LETTER TO LEONARD HORNER
Ricardo agreed with Francis Horner and Mushet that Galton’s Chart deserved to be published. However, there were a few theoretical points which, according to Ricardo, were not “critically correct.”Footnote 16 Although he recognized these points did “not in the least affect the main question” and, if corrected, “might perhaps tend rather to perplex than to enlighten those for whose perusal it is intended,” Ricardo believed his objections had to be stated.
Ricardo’s comments on Galton’s manuscript may be divided into three parts. In a first set of remarks, Ricardo considered the relation between worn coins and depreciation of the currency (internal and external). He first established a distinction between deteriorated (worn coins) and depreciated currencies and showed that this distinction was consistent with his definition of the par of exchange. Then, Ricardo commented on Mushet’s tables of exchange rates between London and Hamburgh. He focused more particularly on the practical problem of the determination of the relative value of gold to silver, which was necessary to ascertain the real par of exchange—and thus the deviation of the exchange rate from the real par. This part of the letter may be seen as a complement to the analysis of the exchange between London and Hamburg developed in the Reply to Bosanquet. Footnote 17 Finally, Ricardo dealt with the distinction between an increase in the issues of Bank of England notes and an increase in the quantity of money in circulation. This distinction allowed Ricardo to explain why, according to him, Galton should not have included the small notes in his graph representing the issues of the Bank of England.
Ricardo’s Analysis of the Relations between Worn Coins, the Price of Bullion, Currency Depreciation, and the Definition of the Par of Exchange
Ricardo’s first set of remarks started with the issue of worn coins and the definition of a depreciated currency. Ricardo commented on the following extract from Galton’s Chart:
If the Coins in circulation should be diminished by wear, they will become depreciated in proportion to the diminution they have sustained. Although they may still pass by the same name, they will be worth only their actual weight of uncoined Gold as before. The difference between the Market and Mint prices will measure the degree of depreciation.
In the early part of the present King’s reign, our Guineas were much worn, and a reference to the Chart will show that the Market price of Bullion exceeded its Mint price. In the year 1774 there was a general recoinage. All the Guineas in circulation from that time, having been recently issued from the Mint, were of Standard weight, and the Market price of Gold continued for a long series of years afterwards nearly to coincide with the Mint price. (Galton Reference Galton1813, pp. 9–10)
According to Ricardo, there was no necessary connection between the diminution of the weight of coins and the depreciation of the currency. Indeed, in a situation of mixed circulation—where worn coins and Bank notes convertible into full-bodied coins were both in use—such as the one experienced by England before 1774 and considered in Galton’s quotation, the range of variations in the market price of domestic gold bullion, noted po, is:
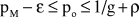 $$p_M \, - \,\varepsilon \, \le \,{\rm{1/g + }}\rho $$
In this equation, pM is the Mint price of gold, g represents the actual bullion content of one unit of domestic currency, while ε is the cost of mintage, and ρ a premium to compensate for the risk of melting coins down.Footnote 18
As seignorage did not exist in England (neither before nor after 1774), ε represented the loss of interest experienced during the period necessary for the Mint to convert gold bars into coins. Ricardo and the Bullion Report estimated this loss of interest to be 1% (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 175; Cannan Reference Cannan1969, pp. 12–13). The minimum price of bullion was then pM – ε. Indeed, if po fell under this level, it became profitable to buy gold on the market and to bring it to the Mint to receive coins. Turning now to the maximum price of gold, it was defined by the actual gold content of these coins, g, and the risk of melting coins down: ρ. Both melting and exporting coins were then prohibited by law. Since seignorage did not exist, the gold content of the coins “fresh for the Mint” was equal to 1/pM. However, before the recoinage of 1774, no full-bodied coins were in circulation and the difference between g and 1/pM corresponded to the level of debasement of the coins. The range of variations of the price of gold was then more important than in the case of full-weight coins.
The amount of gold present in the coins and how worn they were mattered insofar as they determined the highest level the market price of gold could reach and its maximum deviance from the Mint price. However, according to Ricardo, within this margin, the market price of gold was not fixed according to the gold content of the coins, but rather according to the quantity of money in circulation.
This principle was the base for the circulation of a currency bearing a seignorage (Ricardo 1951–Reference Ricardo and Sraffa73, 3, pp. 222–223). Indeed, the seignorage can amount to 100% of the value of money, as in the case of Bank notes, provided that the amount of money in circulation was not increased by false coiners. As a consequence, and as Ricardo concluded: “Coins may be deteriorated without raising the price of bullion, but |the standard| bullion cannot rise above the mint price unless the currency is depreciated”—which could occur in the case of excessive quantity.
Although Galton’s statement was “not correct in theory,” Ricardo nevertheless admitted that it was right in practice, “because worn coins have always been accompanied by an excess of paper money.” However, such a statement needed qualification. Contrary to Galton’s assertion, the depreciation of coins in circulation was almost never “in proportion to the diminution they have sustained.”
In a situation of mixed circulation of worn coins and Bank notes convertible into full-bodied coins, the Bank of England had a real interest in increasing its discounts—and then, the quantity of issued notes—as long as the market price of gold did not reach pM + ρ. However, when the price of gold reached this limit, it became profitable for Bank notes holders to change them at the Bank for full-bodied coins, to melt them down into bullion, and to sell gold bullion on the market at the price of pM + ρ or higher. This created an influx of bullion on the gold market and a fall of its relative price in terms of other commodities. Gold became the “cheapest exportable commodity” and was sent abroad (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 64 and pp. 212–213). The decrease in the quantity of money in circulation was then supposed to make the market price of gold po fall under the limit pM + ρ.
A problem could appear if the Bank of England attempted to maintain the returned notes in circulation by re-issuing them. In such a case, the Bank would run the risk of seeing all its guineas drawn out of its coffers. The Bank would then be under the necessity of replenishing its reserves, and of buying gold on the market at a high price (between pM + ρ and 1/g + ρ). This would lead to what may be called Adam Smith’s “Penelope effect.” Bank notes holders demanded coins at the Bank, melted them down into bullion, and sold bullion to the Bank instead of exporting it. In this situation, no transportation cost had to be incurred and the profit was then higher.Footnote 19 The only possibility for the Bank to stop this from happening was to reduce the quantity of notes in circulation. As Ricardo pointed out:
The Bank would be obliged therefore ultimately to adopt the only remedy in their power to put a stop to the demand for guineas. They would withdraw part of their notes from circulation, till they should have increased the value of the remainder to that of gold bullion, and consequently to the value of the currencies of other countries. All advantage from the exportation of gold bullion would then cease, and there would be no temptation to exchange bank-notes for guineas. (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 59)
As a consequence, in the case of a mixed circulation of debased coins and of Bank notes convertible into full-bodied coins without seignorage, the market price of gold was usually comprised between po and pM + ρ, and this, whatever the degree of debasement of coins. As Ricardo stressed in his Principles four years later: “in the history of the British coinage, we find, accordingly, that the currency was never depreciated in the same proportion that it was debased; the reason of which was, that it never was increased in quantity, in proportion to its diminished intrinsic value” (Ricardo 1951–Reference Ricardo and Sraffa73, 1, p. 353).Footnote 20
The letter Mushet wrote to Galton on 27 February Reference Galton1813 (R.P. 4978/3, f. 3-5) offers additional information on the matter of the 1774 recoinage. In some respects, it illustrated the principle highlighted by Ricardo. This letter was obviously an answer to a series of questions from Galton. Among other queries, Galton asked Mushet the reasons why the market price of gold did fall to its Mint price at the beginning of July 1773; that is, nearly one year before the 1774 recoinage.Footnote 21 According to Mushet, the explanation lay in the withdrawal from circulation of the guineas weighting under 5 dwts and 3 grains, a withdrawal that led to a decrease in the quantity of money in circulation. This lowered the market price of gold to its Mint price even though worn guineas (weighing between 5 dwts and 3 grains and 5dwts and 9 grains) were still in circulation:
The circumstance of the price of Gold falling to its Mint price by the 2d July 1773 as recorded in my tables was occasioned I have no doubt, by the Bank of England, withdrawing from circulation, all Guineas under 5 dwts & 3 grains. This they were enabled to do, by an order from Treasury, dated 23d July 1773; and as part of these light Guineas, may have been withdrawn, upon the faith of this order, and previous to its date, the market price of Bullion, may have been affected in consequence. The amount withdrawn from circulation by this order, was £3. 796. 458˶ 17˶9. This together with the general expectation of a reform in the currency, I think, may be sufficiently to explain the cause of the fall of the price of Bullion, preceding the recoinage. (R.P. 4978/3, f. 3)
As a consequence, from the beginning of July 1773 to the end of June 1774, the market price of gold coincided with its legal price even though some worn coins were in circulation (the lightest allowed weighing 5wts 3 grains). This gave a perfect illustration of the principle advanced by Ricardo that the market price of bullion had no necessary connection with the gold content of coins, but was a direct consequence of their quantity—otherwise the market price of gold would have been above its official price.
The next remark developed by Ricardo in his letter follows from this principle. It deals with Galton’s definition of the par of exchange, which was:
By the Par of Exchange between two Countries is meant that quantity of the Currency of the one which is equal in intrinsic value to a given quantity of the Currency of the other. If the Coins of the two countries are made of the same metal; the Coins whose denominations express the Par will contain equal weights of that metal; if the Currencies of both countries remain unimpaired, the Real Par will be fixed. (Galton Reference Galton1813, pp. 11–13)
In the case of full-bodied coins, this definition was right. As Ricardo stated: “While the currency of different countries consists of the precious metals, or of a paper money which is at all times exchangeable for them; and while the metallic currency is not debased by wearing, or clipping, a comparison of the weight, and degree of fineness of their coins, will enable us to ascertain their par of exchange” (Ricardo 1951–Reference Ricardo and Sraffa73, 3, pp. 70–71). However, when coins in circulation were clipped or worn, the par of exchange was no longer calculated by comparing the actual metallic contents of coins (as suggested in Galton’s definition), but by comparing the legal weights and degrees of fineness of the currencies considered.
The first principle stressed by Ricardo, that it was the quantity of money and not the metallic content of the coins that mattered, led to the conclusion that, if the quantity of money was correctly managed, a worn or clipped currency might be worth more than its metallic content. In such a case, Galton’s assertion—“Coins whose denominations express the Par will contain equal weights of that metal”—was wrong.Footnote 22
Mushet’s Tables and the Deviation of the Exchange Rate from the Par between London and Hamburgh
In his letter, Ricardo next considered the exchange rate between London and Hamburgh. In his Chart, Galton represented how the exchange rate deviated from the real par. He based his graph on the tables published in Mushet’s Enquiry. However, as Ricardo had indicated in his Reply to Bosanquet: “there are objections … to offer against the perfect accuracy of Mr. Mushet’s present tables” (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 168).Footnote 23
In this pamphlet, Ricardo first showed that the determination of the rate of exchange between London and Hamburgh was faulty, for it was calculated “by a reference to … bills at 2½ usances” and not “from a comparison of the actual value of the coins of the two countries, payable at the same time in both” (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 168), as it should have been. Another problem mentioned by Ricardo was Mushet’s calculation of the real par of exchange. The great difficulty was that London and Hamburgh adopted different standards of money: gold was the standard in London whereas silver was used in Hamburgh. Therefore, Mushet was wrong in considering that the real par of exchange was fixed in the first edition of his Enquiry. It fluctuated according to the relative value of gold to silver on the market. Therefore, to ascertain the real par of exchange, at a specific time, it is necessary 1) to determine the silver par of the English pound, and 2) to ascertain the relative value of gold to silver at that time. As Mushet explained in the second edition of his Enquiry, the method consisted in determining the silver parity of the pound sterling, then the silver par of exchange with Hamburgh, and, finally, in applying a factor corresponding to the deviation of the relative value of gold to silver in the market from their Mint parity:
if 34 schillings, 11 grotes and a ¼, of Hamburgh currency be equal in value to a pound sterling, or 20/21 of a guinea, when silver is 5s. 2d. per oz. they can no longer be so when silver falls to 5s. 1d. or 5s. per oz, because a pound sterling in gold being then worth more silver is also worth more Hamburgh currency.
To find the real par, therefore, we must ascertain what was the relative value of gold and silver when the par was fixed at 34 11 ¼, and what is the relative value at the time we wish to calculate it.
For example, if the price of standard gold was £3 17 10 ½ per oz. and silver 5s. 2d. an ounce of gold would then be worth 15.07 ounces of silver, being the mint proportions, 20 of our standard shillings would then contain as much pure silver as 34 schillings, 11 grotes and a ¼; but if the ounce of gold was £3 17 10 ½ and silver 5s. (which it was on the 2d January, 1798) the ounce of gold would then be worth 15.57 ounces of silver. If £1 sterling at par, therefore, be worth 15.07 ounces of silver, then at 15.57 it would be at 3 per cent. premium, and 3 per cent. premium on 34 11 ¼ is 1 shilling, 1 grot and 9/16, so that the par when gold is to silver as 15.57 to 1 will be 36 shillings, 1 grot and 1/10.
The above calculation will be more easily made by stating as follows:
As 15.07 : 34 11 ¼ : : 15.57 : 36. 1 1/10. (Mushet Reference Mushet1810, pp. 94–95)
One difficulty encountered when calculating the real par of exchange was that the relative value of gold to silver was not exactly the same in London and Hamburgh. However, as these relative values were “always tending in all [countries] to … equality” (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 175),Footnote 24 Ricardo assumed they were equal. Another problem was determining the par of each currency. According to Ricardo, Mushet’s determination of the silver par of the pound sterling was not correct (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 168), for he estimated the silver par of the pound sterling to be 34 11 ¼ while, according to Dr. Kelly’s table, “actual essays,” and “computation” (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 168), it was 35 schillings 1 grote.
However, the main practical issue Ricardo addressed in his letter was how to determine the relative value of gold to silver. The difficulty lay in the lack of regular quotations of the prices of gold and silver bullion in London and in Hamburgh. In London, gold bullion was quoted irregularly from 1800 to the beginning of 1820 and silver bullion was not quoted regularly until the end of the year 1820 (see House of Lords 1819, pp. 330–354; Boyer-Xambeu, Deleplace, and Gillard Reference Boyer-Xambeu, Deleplace and Gillard2010). In Hamburgh, silver bullion was quoted regularly, as it was the monetary standard, but gold bullion was not quoted until 1833 (Boyer-Xambeu, Deleplace, and Gillard Reference Boyer-Xambeu, Deleplace and Gillard2010). As Ricardo explained in his letter, the relative value of gold to silver had then to be ascertained by looking either at:
1) the price of silver bullion in gold coins, determined with the quotation of a silver bar in Portugal gold coins or in doubloons (Spanish gold coins), or
2) the price of gold bullion in Spanish new dollars (Spanish silver coins), or
3) the quotation of Spanish new dollars in Portugal gold coins or in doubloons (when the prices of gold and silver bullion were not available).
As Ricardo indicated, the problem with this kind of calculation was that, in addition to the variations occasioned by changes in the value of the metal out of which coins were made, their value also depended on the changes in the value of money. The value of an un-coined piece of the same metal, weight, and fineness would not have been affected by these changes. Therefore, the way Mushet calculated the relative value of gold to silver and established the real par of exchange was not as accurate as one could wish. As a consequence, his calculation of the deviation of the exchange from the par was not “critically correct.”
This problem was well illustrated by the example of the years 1811 and Reference Mushet1812 discussed in Mushet’s letter to Galton (R.P. 4978/3, f. 4-5):
I notice your observations on the state of the Exchange in 1811 & 12. The quotation for 1811, which states the Exchange at 38 p Cent against London, may be an inaccurate representation of the market, because the Gold quoted in Doubloons, and latterly they have been valued in the market as high as standard Gold Bars, and Portugal coin, tho’ inferior in value nearly 5/ per oz.[Footnote 25] In this case, if[Footnote 26] Portugal Gold should be the test by which to construct the par of Exchange, the price of which on the 29th. March 1811. (Seven days previous to the quotation in question) was £4”16., the reduction of the unfavourable Exchange would be about 5 p Cent.… The quotation … at 21 p Cent unfavourable to London [in 1812], is occasioned, by the quotation being Doubloons; and if subject to the same reduction as the quotation of 1811 the Exchange would be something about 16 p Cent against London; and as the price of Portugal Gold was 6 days after this quotation £4” 16p 3, the deduction is warranted.
The figures communicated by Mushet and used in Galton’s Chart were the result of a calculation of the par of exchange made by estimating the relative value of gold to silver. This estimation was determined by focusing on the price of doubloons in standard silver or, more likely, in Spanish dollars. The problem raised by this calculation was that, on 5 April 1811, the doubloons were at 5% premium with regard to their actual gold content. The same phenomenon happened in mid-1812. However, if the relative value of gold to silver had been estimated by the price of Portugal gold coins in Spanish dollars or in standard silver, the par of exchange would have had to be increased by 5%. The unfavorable exchange would then have had to be reduced by the same amount.Footnote 27
The Distinction between an Increase in the Issues of Bank of England Notes and an Increase in the Quantity of Money in Circulation: The Case of Small Notes
Ricardo’s last remark deals with the construction of Galton’s chart and the choice of the different aggregates represented on it. Galton aimed to show that “there is a degree of parallelism between the several irregular lines denoting the price of Gold and Silver Bullion …, the rate of the Exchanges, and the amount of Bank of England Notes in circulation” (Galton Reference Galton1813, pp. 20–21). According to Ricardo, this parallelism should have been even more complete if, instead of considering the amount of all Bank of England notes in circulation, Galton had rejected those of £5 and under after the suspension of cash payments had become effective.
The reason why Ricardo supported this point of view was that he distinguished between an issue of Bank notes and an increase in the quantity of money in circulation. This was explained in the Appendix to the High Price of Bullion (Ricardo 1951–Reference Ricardo and Sraffa73, 3, pp. 115–121) where Ricardo discussed Malthus’s article “Depreciation of Paper Currency.” In this review, Malthus was opposed to Ricardo’s position, which was that a redundant currency caused a fall in the exchange. Malthus argued: “it is certainly not easy to explain an improving exchange under an obviously increasing issue of notes; an event that not infrequently happens, and was much insisted upon by the Deputy Governor of the Bank [John Pearse], as a proof that our foreign exchanges had no connexion with the state of our currency” (Malthus Reference Malthus1811, p. 359).
Ricardo answered that a redundant currency invariably caused a high price of bullion and a depreciated exchange. However, an increase of Bank notes did not necessarily lead to an increase of money in circulation, and to a redundant currency. A clear distinction then had to be made between these two phenomena: “[I] do not contend … that the increase of bank notes will permanently lower the exchange, but that such an effect will proceed from a redundant currency. It remains, therefore, to be considered whether an increase of bank notes is necessarily, at all times, accompanied with a permanently increased currency” (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 114).
To show that this was not a necessary connection, Ricardo considered the situation of England after the suspension of cash payments in 1797. Before the Restriction Bill, no Bank of England notes of £1 or £2 were in circulation, but full-bodied guineas (of 21s.), half guineas (of 10s, 6d.), seven-shilling gold coins, and abraded silver coins or tokens (Cannan Reference Cannan1969, p. vii) were in circulation.
The suspension of cash payments led to an increase in the issues of the Bank of England notes. This raised the price of gold and lowered the rate of exchange. As soon as the price of gold reached its limit of 1/g + ρ or when the rate of exchange reached the export gold point, coins were hoarded, or melted and exported. The amount of money in circulation was thus reduced. The price of gold and the foreign exchange returned to their former level. The increase in the issues of Bank notes led only to small Bank notes' being substituted in the circulation for coins, but did not increase the amount of money in circulation. The consequence was that such an increase of Bank notes had no permanent effect, neither on the price of gold nor on the rate of exchange. Thus, the inclusion of small notes in the figures of the quantity of money in circulation conveyed a misrepresentation of facts and could have led to ill-advised criticisms of important principles of monetary theory. Indeed, in the case analyzed by Ricardo, there was no contradiction between the bullion principle and an increase of Bank notes that was not followed by a rise in the price of gold or by a fall in the foreign exchange. As Ricardo considered that the amount of high denomination notes in circulation was always bearing “some tolerably regular proportion to the whole circulation” (Ricardo (1951–Reference Ricardo and Sraffa73, 3, p. 115), the rejection of small notes did not create any problem even after the substitution was brought to an end. When small notes were redundant compared to high-denomination notes with regard to the needs of circulation, they were exchanged for high-denomination notes at the Bank of England. The proportion was thus restored.Footnote 28
V. CONCLUSION
The set of letters studied in this article originated in Galton’s project to publish his Chart. It involved three of the most prominent figures of the Bullion Controversy. Francis Horner was appointed president of the Bullion Committee and, as he wrote to Jeffrey (Horner Reference Horner, Bourne and Taylor1994, p. 645), it was Ricardo and Mushet who “called the public attention” on the question of the depreciation of Bank notes at the end of 1810.
From an historical point of view, these letters add to our knowledge of the connection between Ricardo, Mushet, and Francis Horner. Furthermore, they bring new characters to light: Leonard Horner and Galton. Indeed, although Leonard’s acquaintance with Ricardo was highly probable, there was, until now, no material proof of a correspondence between them. Likewise, no material proof of any connection between Ricardo and Galton existed before the discovery of these letters and, as far as I know, even their being acquainted was unknown to scholars.
From an analytical point of view, Ricardo’s letter to Leonard deals with three important monetary points:
—The question of worn coins, which led to Ricardo’s distinction between a deteriorated and a depreciated currency. This distinction was then used by Ricardo to show that a good management of the quantity of money in circulation, even if it consisted in a deteriorated currency, could prevent the circulating medium from internal (the price of gold) as well as external (the rate of exchange) depreciation.
—The determination of the real par of exchange, which implied, in cases of countries having different monetary standards, the need to ascertain the relative value of gold to silver every time. Ricardo’s remarks on this practical issue complemented those developed on the calculation of the par of exchange between London and Hamburgh in his Reply to Bosanquet.
—The distinction between issuing Bank notes and increasing the quantity of money in circulation. The consequence of this distinction was the rejection of small notes from the amount of money in circulation, which Ricardo advocated all along his career.
Finally, Ricardo’s letter to Leonard Horner is particularly interesting from a methodological point of view. It shows Ricardo at work with empirical issues and illustrates the fact that, contrary to what commentators have sometimes claimed, Ricardo’s abstractions were not so far removed from reality. His comment on Mushet’s estimate of the relative value of gold to silver confirmed he was as comfortable dealing with the details of the bullion and foreign exchange markets as with the more abstract principles of political economy. His distinction between a depreciated and a deteriorated currency illustrates that it is only through cautious induction that Ricardo derived the necessary cause (an excess in the quantity of money) of an observed phenomenon (the depreciation of a currency) with certainty instead of being misled by a coincident but accidental fact (the deterioration of the coins). Ultimately, Ricardo’s rejection of small notes from the amount of money in circulation shows how principles of political economy (the substitution of small notes for coins) may be used in turn as “standard[s] of reference” (Ricardo 1951–Reference Ricardo and Sraffa73, 3, p. 181), which are necessary to ascertain what particular facts (the amount of money in circulation since 1797) exactly are. Ricardo’s comments on Galton’s Chart thus exemplified the complex relation between facts and theory and demonstrated once again that the usual charge of rash abstraction laid against Ricardo is unfounded.Footnote 29


