


1. Introduction
Despite the stir that Spirtes, Glymour, and Scheines Reference Spirtes, Glymour and Scheines2001 or Pearl Reference Pearl2000 prompted in the philosophical community, it must be recognized that, in one way or another, Bayesian networks can contribute to inference of causal knowledge from statistical data (see Williamson Reference Williamson2002 for a suggestion to that effect). Still, Bayesian networks can be used for causal inference purposes only when the causal Markov condition (CMC) holds. Roughly, this condition states that every phenomenon is probabilistically independent from all its noneffects, conditional on its direct causes. Whether or, rather, when it holds remains a debated question.
It is usually mentioned in favor of the CMC that it holds for deterministic systems with jointly independent exogenous variables.Footnote 1 Reciprocally, counterexamples to the CMC often involve indeterminism. Now, Daniel Steel (Reference Steel2005) claims to establish that the deterministic clause of the case for the CMC is unnecessary—or, in other words, that the CMC is satisfied as soon as exogenous variables are jointly independent. If correct, Steel's claim should constitute an important contribution to the debate on the CMC and to the larger debate on the possibility to infer causal knowledge from statistical data.
In the present article, I ponder the correctness of Steel's claim and the contribution of Steel Reference Steel2005 to the CMC debate. A general presentation of the CMC-determinism issue is given in Section 2. Then, Section 3 sets out Steel's argument. Section 4 assesses it and leads to conclude that Steel's claim cannot be accepted unless standard terminology is abandoned. Nevertheless, Section 5 supports that Steel makes an interesting suggestion as to the representation of causal systems and shows how this suggestion sheds new light on the relationship between determinism and the CMC.
2. Determinism and the Causal Markov Condition
The CMC is the causal version of the more general Markov condition:
Definition 1 (Markov condition). Let V be a finite set of variables, G a directed acyclic over V, and p a probability distribution over V; (G, p) satisfies the Markov condition if and only if every variable in V is probabilistically independent from all its nondescendants in G, conditional on its parents in G.
Let us now consider a system—that is, in the present context, any group of causally interrelated phenomena. A simple example introduced by Halpern and Pearl (Reference Halpern and Pearl2005, 848) consists of a forest that can catch fire because of either lightning or a match lit by an arsonist. This system can be represented by:
1. The variables L, A, and F representing, respectively, whether lightning strikes, whether an arsonist lights a match in the forest, and whether there is a forest fire. More precisely, L is the binary variable taking value 1 if and only if lightning strikes and value 0 otherwise, and similarly for A and F. These variables are meant to represent relevant observable aspects of the situation under consideration. Other variables could be considered, giving rise to different representations of one and the same system. This aspect is not discussed in the present article, and I will assume that the set of variables representing relevant observable aspects of a given system is univocally determined.
2. The directed graph
representing the direct causal relations among L, A, and F. This graph is “the causal graph” over {L, A, F}—or, equivalently, the causal graph for the system under consideration.
3. The probability distribution over {L, A, F}.

More generally, any system can be represented by a set of variables and the causal graph and probability distribution over this set. Correlatively, the causal version of the Markov condition can be defined as a property of systems (or, rather, of systems with an acyclic causal graph):
Definition 2 (CMC). Let S be a system represented by the set of variables V, the acyclic causal graph CG, and the probability distribution p over V; S satisfies the CMC if and only if (CG, p) satisfies the Markov condition.
Let me introduce some vocabulary before I set out the usual result concerning the CMC and determinism:
• A system S whose relevant observable aspects are represented by the variables in V is:
• acyclic if and only if CG is acyclic;
• deterministic if and only if the values of the V variables having direct causes in V are functionally determined by the values of these direct causes.
• The exogenous variables of S are the variables in V that do not have direct causes in V.
• The variables in V are jointly independent if any two nonempty distinct subsets of V are probabilistically independent.
The classic result beyond which Steel pretends to go can now be stated:
Theorem 1 (classic result). Acyclic deterministic systems with jointly independent exogenous variables satisfy the CMC.
Here is a proof for Theorem 1: Let S be an acyclic deterministic system with jointly independent exogenous variables, and let S be represented by {V, CG, p}.
The system S satisfies the CMC if and only if any variable in V is independent for p of its nondescendants in CG, conditional on its parents in CG.
Thus, let us consider any  $V_{1}$ in V and show that it is indeed independent of its nondescendants in CG, conditional on its parents in CG.
• If
$V_{1}$ is endogenous, then (because S is deterministic) its value is functionally determined by those of its parents in CG. Therefore, it is independent of any of its nondescendants in CG, conditional on its parents in CG.• If
$V_{1}$ is exogenous, the set of its parents in CG is empty. Therefore, one must simply show that $V_{1}$ is (unconditionally) independent of any of its nondescendants in CG. Let $V_{2}$ be such a variable:• If
$V_{2}$ is exogenous, the independence of $V_{1}$ and $V_{2}$ stems from the hypothesis of joint independence of S's exogenous variables;• If
$V_{2}$ is endogenous, its value is determined by those of its direct causes in V. Beyond, and by acyclicity, this value is determined by those of the variables of a subset—say W—of exogenous variables of S. $V_{1}$ does not belong to W since $V_{2}$ is not a descendant of $V_{1}$. Therefore, the joint independence hypothesis entails that $V_{1}$ is independent from W and therefore from $V_{2}$.


As a consequence, any variable in V is independent of its nondescendants in CG, conditional on its parents in CG: S satisfies the CMC.
3. Steel's Argument
What is claimed in Steel Reference Steel2005 is that the deterministic clause in Theorem 1 is superfluous. In other words, a system would satisfy the CMC as soon as its exogenous variables are jointly independent. The present section sets out Steel's argument in favor of this claim.
Steel's argument is stated in the framework of causal functional models (CFMs). Let me explain what they are by first introducing functional models (FMs). An FM is defined over a couple of sets of variables, say  $\mathbf{X}=\{ X_{1},\,X_{2},\,\ldots ,\,X_{n}\} $ and
 $\mathbf{U}=\{ U_{1},\,U_{2},\,\ldots ,\,U_{k}\} $. An FM over (X, U) is (E, p), where:
• E is a set of n equations such that each
$X_{i}$ appears as a function $f_{i}$ of a nonempty subset of $[ ( \mathbf{X}\cup \mathbf{U}) / \{ X_{i}\} ] $;• p is a probability distribution over U.


For instance, one FM over  $( \{ X_{1},\,X_{2},\,X_{3}\} ,\,\{ U_{1},\,U_{2}\} ) $ is composed by the equations


together with a probability distribution p over  $\{ U_{1},\,U_{2}\} $.
Steel (Reference Steel2005, 9) describes  $( \mathbf{E},\,p) $ as “causal” if (1) all the equations in E are causal generalizations and (2) any
 $X_{i}$ in X is such that the set DirectCauses(
 $X_{i}$) of its direct causes in
 $( \mathbf{X}\cup \mathbf{U}) $ is included in (but not necessarily equal to) the set of its functional parents in
 $( \mathbf{X}\cup \mathbf{U}) $.
Four remarks should be made before I actually come to the result established by Steel.
• As made clear by the example, there is no one-to-one correspondence between X and U variables of a given FM. This is an important difference between Steel's functional models and more traditional causal models that I shall consider later on.
• As noticed by Steel himself (Reference Steel2005, 7), there is a “straightforward correspondence between functional models and directed graphs”: for
$M=( \mathbf{E},\,p) $ over $( \mathbf{X},\,\mathbf{U}) $, there is a unique directed graph $G_{M}$ over $( \mathbf{X}\cup \mathbf{U}) $ such that graphical parents in $G_{M}$ exactly correspond to functional parents in E. For our example FM, this graph is as follows:


• If
$G_{M}$ is acyclic (as is the case here), $M$ as well as systems it represents can themselves be labeled acyclic.• If
$M$ is a causal functional model, then $G_{M}$ is an overgraph of the causal graph $CG_{M}$ over $\mathbf{DC}_{M}=\cup _{X_{i}\in \mathbf{X}}\mathbf{DirectCauses}( X_{i}) $.• If
$G_{M}$ is acyclic, then the equations in E can be restated in such a way that X variables are functions only of the U variables from which they descend (Steel Reference Steel2005, 8). As a consequence, p univocally extends to a $p^{\prime }$ over $( \mathbf{U}\cup \mathbf{X}) $, which itself univocally restricts to $p^{\prime \prime }$ over $\mathbf{DC}_{M}$.


In terms of CFMs and following the notations already introduced, the result established by Steel is the following:
Theorem 2 (Steel's result). Let  $M=( \mathbf{E},\,p) $ be a CFM over (X, U). If
 $G_{M}$ is acyclic and variables in U are jointly independent for p, then
 $( CG_{M},\,p^{\prime \prime }) $ satisfies the Markov condition.
Steel does not distinguish between systems and models representing them. This is unproblematic as long as one assumes that the correspondence between systems and models is functional, which he implicitly does. Yet for reasons that will become clear later on, I will keep systems distinct from models and independently state Steel's result in terms of systems:
Theorem 3. Let S be a system represented by the CFM  $M=( \mathbf{E},\,p) $ over (X, U). If S is acyclic and the variables in U are jointly independent for p, then S satisfies the CMC.
A proof that differs slightly from the one given by Steel, but makes it particularly clear what the rationale for the result is, is made up of:
1. A proof of the fact that
$( G_{M},\,p^{\prime }) $ satisfies the Markov condition—in other words: a proof of the fact that $( G_{M},\,p^{\prime }) $ is a Bayesian network. This proof runs exactly as the proof that was given for Theorem 1, with the role of determinism played by functional determination.2. A derivation of the probabilistic conditional independencies that are required in order for
$( CG_{M},\,p^{\prime \prime }) $ to satisfy the Markov condition. Those independencies are established by d-separation in the Bayesian network $( G_{M},\,p^{\prime }) $.


The relationship between Steel's result and the (in)determinism-CMC issue consists exactly of the following: CFMs can represent indeterministic as well as deterministic systems. In order to make it clear, Steel gives the following example. “Imagine a special type of car, the quantum car. The ignition of the quantum car works by means of a fundamentally indeterministic process: when the key is turned, there is an irreducible probability of .85 that the car will start” (Steel Reference Steel2005, 13).
Then Steel (Reference Steel2005, 13) explains that the system constituted by the quantum car can be represented by a CFM M over  $( \{ X_{1},\,X_{2}\} ,\,\{ U_{1},\,U_{2}\} ) $, where
•
$X_{1}$ is “a binary variable indicating whether the key is turned ($X_{1}=1$ indicates that it has been)”;•
$X_{2}$ is “a binary variable representing whether the car starts ($X_{2}=1$ indicates that it does)”;• (as far as I understand Steel's treatment of the example)
$U_{1}$ represents the possible causes of the car being started;•
$U_{2}$ is a binary variable whose possible values are 0 and 1 and which represents whether the car starts once the key has been turned.


The CFM  $M$ is composed of the equations

together with a probability distribution p over  $\{ U_{1},\,U_{2}\} $, which is such that
 $p( U_{2}=1) =.85$. With p thus defined, it becomes clear that
 $U_{2}$ represents the probabilistic nature of the action of
 $X_{1}$ on
 $X_{2}$. More generally, the example makes it clear that (and how) any indeterministic system can be represented by a causal functional model, with U variables representing the probabilistic nature of the action of indeterministic causes on their effects. Consequently, Steel considers that Theorem 2 implies that the CMC is satisfied by any acyclic system with jointly independent exogenous variables, be it deterministic or not. This is what I bring into question. More precisely, I question neither the truth of Theorem 2 nor the validity of Steel's proof, but rather the way Steel interprets this result.
4. Assessment of Steel's Argument
Obviously, a necessary condition for Steel's result to be interpretable in terms of any acyclic system with jointly independent exogenous variables satisfying the CMC is that the U variables of a CFM are the exogenous variables of systems represented by that CFM. This is assumed by Steel. Yet he has a hesitation when introducing U, referring to “a set of exogenous variables or error terms” (Steel Reference Steel2005, 5). I take this hesitation to be meaningful. But this view will be justified only after I have told the standard story about exogenous variables, error terms, and the way they differ.
The standard definition of exogenous variables was introduced in Section 2. One has (0) a system S, (1) a set  $\mathbf{V}=\{ V_{1},\,V_{2},\,\ldots ,\,V_{n}\,\} $ of variables representing its relevant observable aspects, (2) a graph CG representing the direct causal relations within V. The exogenous variables of S are those variables in V that do not have any parents in CG. All this has already been stated. But from there on one can go one step further in the representation of S and consider a set of
 $n$ equations such that each
 $V_{i}$ appears as a function of its parents in CG plus one variable
 $T_{i}$. This set of equations together with the probability distribution over
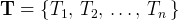 $\mathbf{T}=\{ T_{1},\,T_{2},\,\ldots ,\,T_{n}\,\} $ constitutes a representation of the system under consideration that is common in the field of causal modeling—see, for instance, Pearl's causal models (Reference Pearl2000, 27). Therefore, this pattern of representation will be referred to as that of standard causal functional models (standard CFMs). The T variables of a standard CFM have a precise function: they enable a functional representation of the relations between V variables. Indeed, each
 $T_{i}$ represents everything that contributes to the determination of the value of
 $V_{i}$ and yet is not represented by the variables in
 $\mathbf{V}/ \{ V_{i}\,\} $. More precisely, and following Cartwright's analysis, T variables “represent, in one heap, measurement errors, omitted factors, and whatever truly probabilistic element there may be in the determination of an effect by its causes” (Cartwright Reference Cartwright1999, 9); T variables are usually called error terms.
This was the standard story. Let us now come back to Steel's. Are his U variables “exogenous variables or error terms”? Stated in other words: what do Steel's U variables represent? It is clear from Steel's paper that U variables can represent two very different kinds of things:
• Some of them, like
$U_{1}$ in the quantum car example, represent relevant observable aspects of the system under consideration that happen not to have direct causes in the system. Those variables are exogenous variables in the standard sense of the term.• The other ones, like
$U_{2}$, represent the way probabilistic causes act on their effects. Those variables are not exogenous variables since they do not represent observable relevant aspects of the system under consideration. Moreover, they represent one of the three kinds of influences that error terms in the standard sense represent. But they represent only one of the three kinds of influences that are represented “in one heap” by error terms. As a consequence, they are not error terms, standardly speaking.


This analysis easily accounts for Steel's hesitation when introducing U: U is a composite object whose elements either are exogenous variables in the standard sense or represent part of what standard error terms represent. Consequently, U cannot be called “the set of exogenous variables” if one conforms to standard terminology. Stated in another way, Steel's result can be interpreted in terms of satisfaction of the CMC by any acyclic system with jointly independent exogenous variables only if one abandons the standard pattern of functional representation of systems and the sense “exogenous variables” has in this context. Therefore, it cannot be said without qualification that Steel establishes the superfluity of the deterministic clause in Theorem 1. Omitting qualification, as Steel does, is seriously misleading.
Still, it could be that all this does not matter much. This would be the case, in particular, if Steel showed the way toward a proof of the fact that the CMC is satisfied by any system with jointly independent exogenous variables (in the standard sense). More likely, it may be that the result can be proved in a way similar to the proof that was proposed for Steel's result. This seems all the more likely since the given proof sketch is modular and has already been used to prove a result that is quite different from Theorem 2 (Pearl Reference Pearl2000, 30). However, quick examination of the sketch reveals that one can obtain a final result in terms of joint independence of exogenous variables (standardly defined) only if one adopts a pattern of representation from which error terms are absent. But we saw that the first part of the proof relies in an essential way on the functional determination of the values of endogenous variables by those of their direct causes. In the absence of error terms, such functional determination is exactly equivalent to determinism. In other words, the proof sketch is no use for one who wants to establish that all acyclic systems with jointly independent exogenous variables satisfy the CMC.
Of course, this does not imply that the claim is false. What it implies, by contrast, is the fact that, under standard terminology, it remains possible for an acyclic system with jointly independent exogenous variables to fail to satisfy the CMC—provided it is indeterministic. This is the case of Nancy Cartwright's classic example: “Cheap-but-Dirty employs a genuinely probabilistic process to produce the chemical [a chemical that is consumed in a given sewage plant]. The probability of getting the desired chemical on any day the factory operates is eighty percent. … [Moreover] pollutants are emitted as a by-product whenever the chemical is produced” (Cartwright Reference Cartwright1999, 7).
Relevant observable aspects of the systems are represented by three binary variables with value 0 or 1: O indicating whether Cheap-but-Dirty operates, S indicating whether sewage is produced, and P indicating whether pollutant is produced. It is easily seen that only one of them is exogenous in the standard sense: O. Hence, trivially, exogenous variables are jointly independent. Moreover, the system is clearly acyclic. And yet it does not satisfy the CMC:

whereas

As a consequence, the result Steel claims to have established remains false under standard terminology.
Acyclicity and joint independence of exogenous variables are sufficient for the CMC only if one accepts, as exogenous variables, variables that represent the way probabilistic causes act on their effects. It could be argued that there is nothing wrong with this and, quite the opposite, that this modeling proposition constitutes the very innovation in Steel's paper. This is precisely the position adopted by Steel himself: “The basic insight is that exogenous variables in an FM can be interpreted either as representing causes or genuine indeterminism” (Steel Reference Steel2005, 4). The matter is that variables representing the way probabilistic causes act on their effects already existed before Steel's paper and that they were never called “exogenous variables.” Conversely, “exogenous variables” and “systems with jointly independent exogenous variables” already had a meaning before Steel's paper, and this meaning is different from the one they have in Steel Reference Steel2005. Moreover, Steel does not give any independent justification for substituting his conception of exogenous variables for the usual one. Then, his modeling innovation should not be accepted unless the associated terminology were carefully distinguished from the usual one and he were careful not to claim to enter a preexisting debate—two things that Steel fails to do.
5. What Steel's Paper Suggests
I would like to end with more positive considerations. Indeed, I think that Steel's paper actually contributes to the CMC debate, in spite of the difficulties hitherto highlighted. As the difficulties, the contribution lies in Steel's U variables—and, to be more precise, in those U variables that are neither exogenous variables nor error terms in the standard sense of these notions. I have already stated that these variables represent only one of the three kinds of influences that standard error terms represent “in one heap,” and this appeared to be problematic. But there is another way of looking at this: while standard error terms clearly fail to represent any real entity, Steel's U variables lean toward realism in the use of error terms—by which I mean that error terms are used in such a way that the structure of a given causal model matches the real causal structures it represents. More specifically, Steel's U variables suggest the disjoining of influences that are represented “in one heap” by standard error terms and the representation of distinct influences by distinct error terms.
Following this suggestion, to each variable V representing a relevant observable aspect of the system under consideration would correspond:
• an error term representing the forgotten direct causes of what V represents;
• an error term representing the possible errors in the measurement of V;
• for each of V's probabilistic direct causes, an error term representing the way it acts on V.
These nonstandard error terms lead to define nonstandard causal functional models. Given a system S whose relevant observable aspects are represented by  $\mathbf{V}=\{ V_{1},\,V_{2},\,\ldots ,\,V_{n}\,\} $, a nonstandard CFM for S is (E, p), where:
• E is a set of n equations such that each
$V_{i}$ appears as a function of (1) its direct causes in V and (2) nonstandard error terms $T_{i,1},\,T_{i,2},\,\ldots ,\,T_{i,m}$; $m$ varies with the variable $V_{i}$ that one considers;• p is the probability distribution over the set T of nonstandard error terms.


Nonstandard CFMs complete Steel's CFMs so as to ensure that everything standard CFMs represent is actually represented. This is enough for nonstandard CFMs not implying the important redefinition of usual terminology that Steel's CFMs did convey, and that was identified as problematic. But as for the rest, the two patterns of representation are largely similar. First and foremost, nonstandard CFMs allow a characterization of determinism that relies on the very intuition conveyed by Steel's “definition of deterministic functional models” (Reference Steel2005, 9):
Definition 3 (characterization of determinism). A system is deterministic if it is represented by a nonstandard causal functional model with no error term representing the way a probabilistic cause acts on one of its effects.
Then, as Steel's CFMs, nonstandard CFMs are in “straightforward correspondence” (Steel Reference Steel2005, 7) with directed graphs. Accordingly, they and the systems they represent will also be labeled acyclic when corresponding directed graphs are acyclic. Moreover, acyclicity of nonstandard CFM  $M=( \mathbf{E},\,p) $ over
 $( \mathbf{V},\,\mathbf{T}) $ remains sufficient for the probability distribution p over T to univocally extend to
 $p^{\prime }$ over
 $( \mathbf{T}\cup \mathbf{V}) $ (and then univocally restrict to
 $p^{\prime \prime }$ over
 $CG_{M}$). Finally, and still as with Steel's CFMs, the graph
 $G_{M}$ corresponding to
 $M$ is an overgraph of the causal graph
 $CG_{M}$ for systems represented by
 $M$. (Notice that this causal graph is now univocally determined by
 $M$.)
Does this tell anything new about the relationship between determinism and the CMC? Here, one may first notice that, under the notations that have just been introduced, the following result holds:
Theorem 4. Let  $M=( \mathbf{E},\,p) $ be an acyclic nonstandard CFM over
 $( \mathbf{V},\,\mathbf{T}) $. If variables in T are jointly independent, then
 $( CG_{M},\,p^{\prime \prime }) $ satisfies the Markov condition.
Theorem 4 is the equivalent, in the framework of nonstandard CFMs, of Steel's result. It holds for exactly the same reasons and can also be stated in terms of systems:
Theorem 5. Let S be a system represented by the nonstandard CFM  $M=( \mathbf{E},\,p) $ over
 $( \mathbf{V},\,\mathbf{T}) $. If S is acyclic and variables in T are jointly independent for p, then S satisfies the CMC.
By way of illustration, let us consider a classic (nonquantum) car, that is, a car that starts each time the key is turned and there is fuel in the tank. Let S be this system. Three variables are needed in order to represent S:  $V_{1}$ representing whether the key is turned,
 $V_{2}$ representing whether there is fuel in the tank, and
 $V_{3}$ representing whether the car starts. Let
 $M=( \mathbf{E},\,p) $ be the nonstandard CFM representing S. Equations in E are as follows:

with  $T_{1,1}$ representing the omitted causes of
 $V_{1}$,
 $T_{1,2}$, the possible errors in the measurement of the value of
 $V_{1}$, and correspondingly for
 $V_{2}$ and
 $V_{3}$. Given the acyclicity of S, Theorem 5 states that a sufficient condition for it to satisfy the CMC is that the variables in
 $\{ T_{1,1},\,T_{1,2},\,T_{2,1},\,T_{2,2},\,T_{3,1},\,T_{3,2}\} $ are jointly independent.
Now, this condition can be refined. Indeed, and as already stressed by Cartwright (Reference Cartwright2001, 18) in another context, what is needed for a proof in the style of the ones we gave is only joint independence of the net effects of error terms. In our example, net effects of error terms correspond to  $\{ T_{1,1},\,T_{1,2}\} $,
 $\{ T_{2,1},\,T_{2,2}\} $, and
 $\{ T_{3,1},\,T_{3,2}\} $. Then, following Cartwright, it is sufficient that any way of combining them into two nonempty sets is into two independent sets of variables. To be explicit, it is sufficient that:
1.
$\{ T_{1,1},\,T_{1,2}\} $, $\{ T_{2,1},\,T_{2,2}\} $, and $\{ T_{3,1},\,T_{3,2}\} $ are pairwise independent;2.
$\{ T_{1,1},\,T_{1,2}\} $ is independent from $\{ T_{2,1},\,T_{2,2},\,T_{3,1},\,T_{3,2}\} $;3.
$\{ T_{2,1},\,T_{2,2}\} $ is independent from $\{ T_{1,1},\,T_{1,2},\,T_{3,1},\,T_{3,2}\} $; and4.
$\{ T_{3,1},\,T_{3,2}\} $ is independent from $\{ T_{1,1},\,T_{1,2},\,T_{2,1},\,T_{2,2}\} $.


Joint independence of  $\{ T_{1,1},\,T_{1,2},\,T_{2,1},\,T_{2,2},\,T_{3,1},\,T_{3,2}\} $ is unnecessarily too strong a condition for a proof following the sketch given above to be available. In particular, it is not necessary for
 $T_{1,1}$ to be independent from
 $T_{1,2}$, for
 $T_{2,1}$ to be independent from
 $T_{2,2}$, or for
 $T_{3,1}$ to be independent from
 $T_{3,2}$.
Stated in terms of a nonstandard CFM  $M$ over
 $( \mathbf{V},\,\mathbf{T}) $, the proof only requires the following: for any two distinct nonempty
 $\mathbf{V}^{\prime },\,\mathbf{V}^{\prime \prime }\subset \mathbf{V}$, the sets of error terms corresponding, respectively, to the variables in
 $\mathbf{V}^{\prime }$ and to the variables in
 $\mathbf{V}^{\prime \prime }$ are independent. More rigorously, and with
 $\varphi ( i) $ the number of error terms in
 $M$ for
 $V_{i}\in \mathbf{V}$, the result is as follows:
Theorem 6. Let  $M=( \mathbf{E},\,p) $ be an acyclic nonstandard CFM over V. If for any two
 $\mathbf{V}^{\prime }=\{ V_{i},\,\ldots ,\,V_{j}\,\} $ and
 $\mathbf{V}^{\prime \prime }=\{ V_{k},\,\ldots ,\,V_{l}\,\} $ nonempty disjoint subsets of V,
 $\{ T_{i,1},\,\ldots ,\,T_{i,\varphi ( i) },\,\ldots ,\,T_{j,1},\,\ldots ,\,T_{j,\varphi ( j) }\} $ is independent from
 $\{ T_{k,1},\ldots ,\,T_{k,\varphi ( k) },\ldots ,\,T_{l,1},\ldots ,\,T_{l,\varphi ( l) }\} $, then
 $( CG_{M},\,p^{\prime \prime }) $ satisfies the Markov condition.
For simplicity's sake, let me refer to the antecedent of the implication stated by Theorem 6 as: “V satisfies JI.” Now, in terms of systems represented by nonstandard CFMs, we have:
Theorem 7. Let S be a system represented by the nonstandard CFM  $M$. If S is acyclic and
 $M$ satisfies JI, then S satisfies the CMC.
Under Definition 3, Theorem 7 reveals a sense in which determinism is more favorable than indeterminism for the CMC. Indeed, while I agree with Steel that “it is hard to see why deterministic causal systems would be more likely to be acyclic than indeterministic ones” (Steel Reference Steel2005, 16), I will explain why deterministic systems are more likely than indeterministic ones to have nonstandard CFMs satisfying JI. To that effect, let me introduce a system  $S^{\prime }$, which is identical to just-introduced S except for the fact that turning the key has “an irreducible probability of .85” of doing its job (exactly as in Steel's quantum example);
 $S^{\prime }$ is represented by nonstandard CFM
 $M^{\prime }=( \mathbf{E}^{\prime },\,q) $. Under previous notations, equations in
 $\mathbf{E}^{\prime }$ are:

with  $T_{3,3}$ a binary variable with possible values 0 and 1 and such that
 $q( T_{3,3}=1) =.85$. As a result,
 $M^{\prime }$ satisfies JI if:
1′.
$\{ T_{1,1},\,T_{1,2}\} $, $\{ T_{2,1},\,T_{2,2}\} $, and $\{ T_{3,1},\,T_{3,2},\,T_{3,3}\} $ are pairwise independent;2′.
$\{ T_{1,1},\,T_{1,2}\} $ is independent from $\{ T_{2,1},\,T_{2,2},\,T_{3,1},\,T_{3,2},\,T_{3,3}\} $;3′.
$\{ T_{2,1},\,T_{2,2}\} $ is independent from $\{ T_{1,1};\,T_{1,2},\,T_{3,1},\,T_{3,2},\,T_{3,3}\} $; and4′.
$\{ T_{3,1},\,T_{3,2},\,T_{3,3}\} $ is independent from $\{ T_{1,1},\,T_{1,2},\,T_{2,1},\,T_{2,2}\} $.


Now suppose that all these independencies hold. Then, all the independencies stated by list points 1–4 also hold. This stems from the following simple probabilistic fact: for any X, Y, and Z disjoint and nonempty sets of variables, if  $\mathbf{X}\cup \mathbf{Y}$ is independent from Z, then X is independent from Z. Then, if M′ satisfies JI,
 $M$ does too. The converse, however, is not true:
 $\{ T_{1,1},\,T_{1,2}\} $ (for instance) can be independent from
 $\{ T_{3,1},\,T_{3,2}\} $ while not being independent from
 $\{ T_{3,1},\,T_{3,2},\,T_{3,3}\} $.
These are no facts particular to the chosen example. Quite the opposite, the example makes clear that for any two S and  $S^{\prime }$ differing only by the probabilistic nature of some causal relations in
 $S^{\prime }$, the nonstandard CFMs M and M′ representing them differ only by the absence from M of the nonstandard error terms standing for indeterminism in
 $M^{\prime }$. In such a case,
 $M$ satisfies JI if
 $M^{\prime }$ does, while the converse does not hold. In this sense, nonstandard CFMs representing deterministic systems are more likely than nonstandard CFMs representing indeterministic systems to satisfy JI. To this exact—and acknowledgedly narrow—extent, determinism is more favorable a context than indeterminism for the CMC.
6. Conclusion
Steel's claim to enlarge the usual result concerning the relationship between determinism and the CMC from the deterministic to the general case proved unacceptable. More precisely, it was shown that Theorem 3 can be interpreted in terms of satisfaction of the CMC by any system with jointly independent exogenous variables only if one uses the expression “exogenous variables” in a nonstandard, uncommon way. Still, this way of using the expression suggested that error terms could be employed in a way more realist than the standard one. I defined the pattern of representation that stems from this suggestion and explained how the determinism-CMC debate can take advantage of this new framework. Determinism was easily characterized in this framework, and a sense in which determinism is more favorable than indeterminism for the CMC emerged: the sufficient condition we have for the truth of the CMC is such that if two systems differ only by determinism, then the deterministic one satisfies the condition whenever the indeterministic one does—and the converse does not hold.
Hinting at nonstandard causal functional models and at Definition 3 probably constitutes the most significant contribution of Steel Reference Steel2005 to the debate concerning the CMC in general, and its relationship to determinism in particular. But this definition as well as the sufficient condition for the truth of the CMC that was derived from it are valid only for systems represented by causal functional models—nonstandard ones in the case in point. Hence, this definition and this condition are useful exactly inasmuch as causal functional models can represent real systems, and they are interesting exactly inasmuch as causal functional models can represent interesting real systems. Whether they can is a difficult question that is not tackled here and would deserve more attention.


