Introduction
China produces more than 40% of all the eggs in the world, making it the largest producer, and its annual production keeps increasing (Aho, Reference AHO2002; Magdelaine, Reference MAGDELAINE2011). Rapid economic growth, improved supply chains and favourable prices have led to a constant rise in egg consumption. Improving national food security is a major long-term strategy of the Government and this has encouraged the development of the laying hen industry within the country (Iddamalgoda et al., Reference IDDAMALGODA, HAYASHI, GOTO, SUGIYAMA and OGURI2001; Windhorst, Reference WINDHORST2006). China has a 5000-year history of egg production but, for almost all of this time, this has been achieved by small-scale backyard family units. However, since the 1980s there has been a rapid expansion of the egg production within the country. Early expansion of the egg industry was led by state-run farms, but the private farming sector now dominates production (Yang, Reference YANG2000). The numbers of large-scale, vertically-integrated, intensive egg production units have increased significantly at the start of the 21st century. However, smaller husbandry systems that are owned and operated by individual farmers continue to represent a significant part of the overall egg output in the country and still play a key role in a large number of people's livelihoods (Yang, Reference YANG2011).
China is self-sufficient in egg production, although a significant proportion of feed ingredients needed for this production is imported. Outbreaks of high pathogenic H5N1 avian influenza virus in China since 2004 have caused serious concerns in the industry and for the Chinese Government (Martin et al., Reference MARTIN, PFEIFFER, ZHOU, XIAO, PROSSER, GUO and GILBERT2011). The Government has taken measures to improve biosecurity by, when necessary, prohibiting all live bird markets in the cities and closing many small egg production farms (Tan et al., Reference TAN, SHEN and YANG2013). These regulations have hastened change in the Chinese egg industry in the early years of the 21st century.
The objective of this review is to examine the recent changes in the egg industry in China. A further objective is to understand how the industry manages to supply their eggs to the areas of demand and to explain the methods used by poultry farmers for egg production within China.
Production and demand for eggs in China
Egg production in China has continued to increase in each of the years since 2000. The average annual growth rate of egg production was approximately 0.6 million tonnes per year from 2000 to 2016 (FAO, 2017). In 2016, the total eggs produced in China reached a peak of 31 million tonnes. The increase in egg consumption has been achieved by increasing the amount of domestic production. China is self-sufficient in shell egg production and has a very small number of imported eggs that is offset by a larger, but still relatively small, net export of eggs (FAO, 2017). In 2013, the quantities of imported and exported eggs were 175,000 and 100,000 tonnes, respectively. More than 70% of imported eggs were hatching eggs destined for breeding stock. The majority of exported shell eggs were sent to Hong Kong (90%) and Macau (10%). Exported eggs accounted for only 0.5% of the annual domestic production (USDA, 2014).
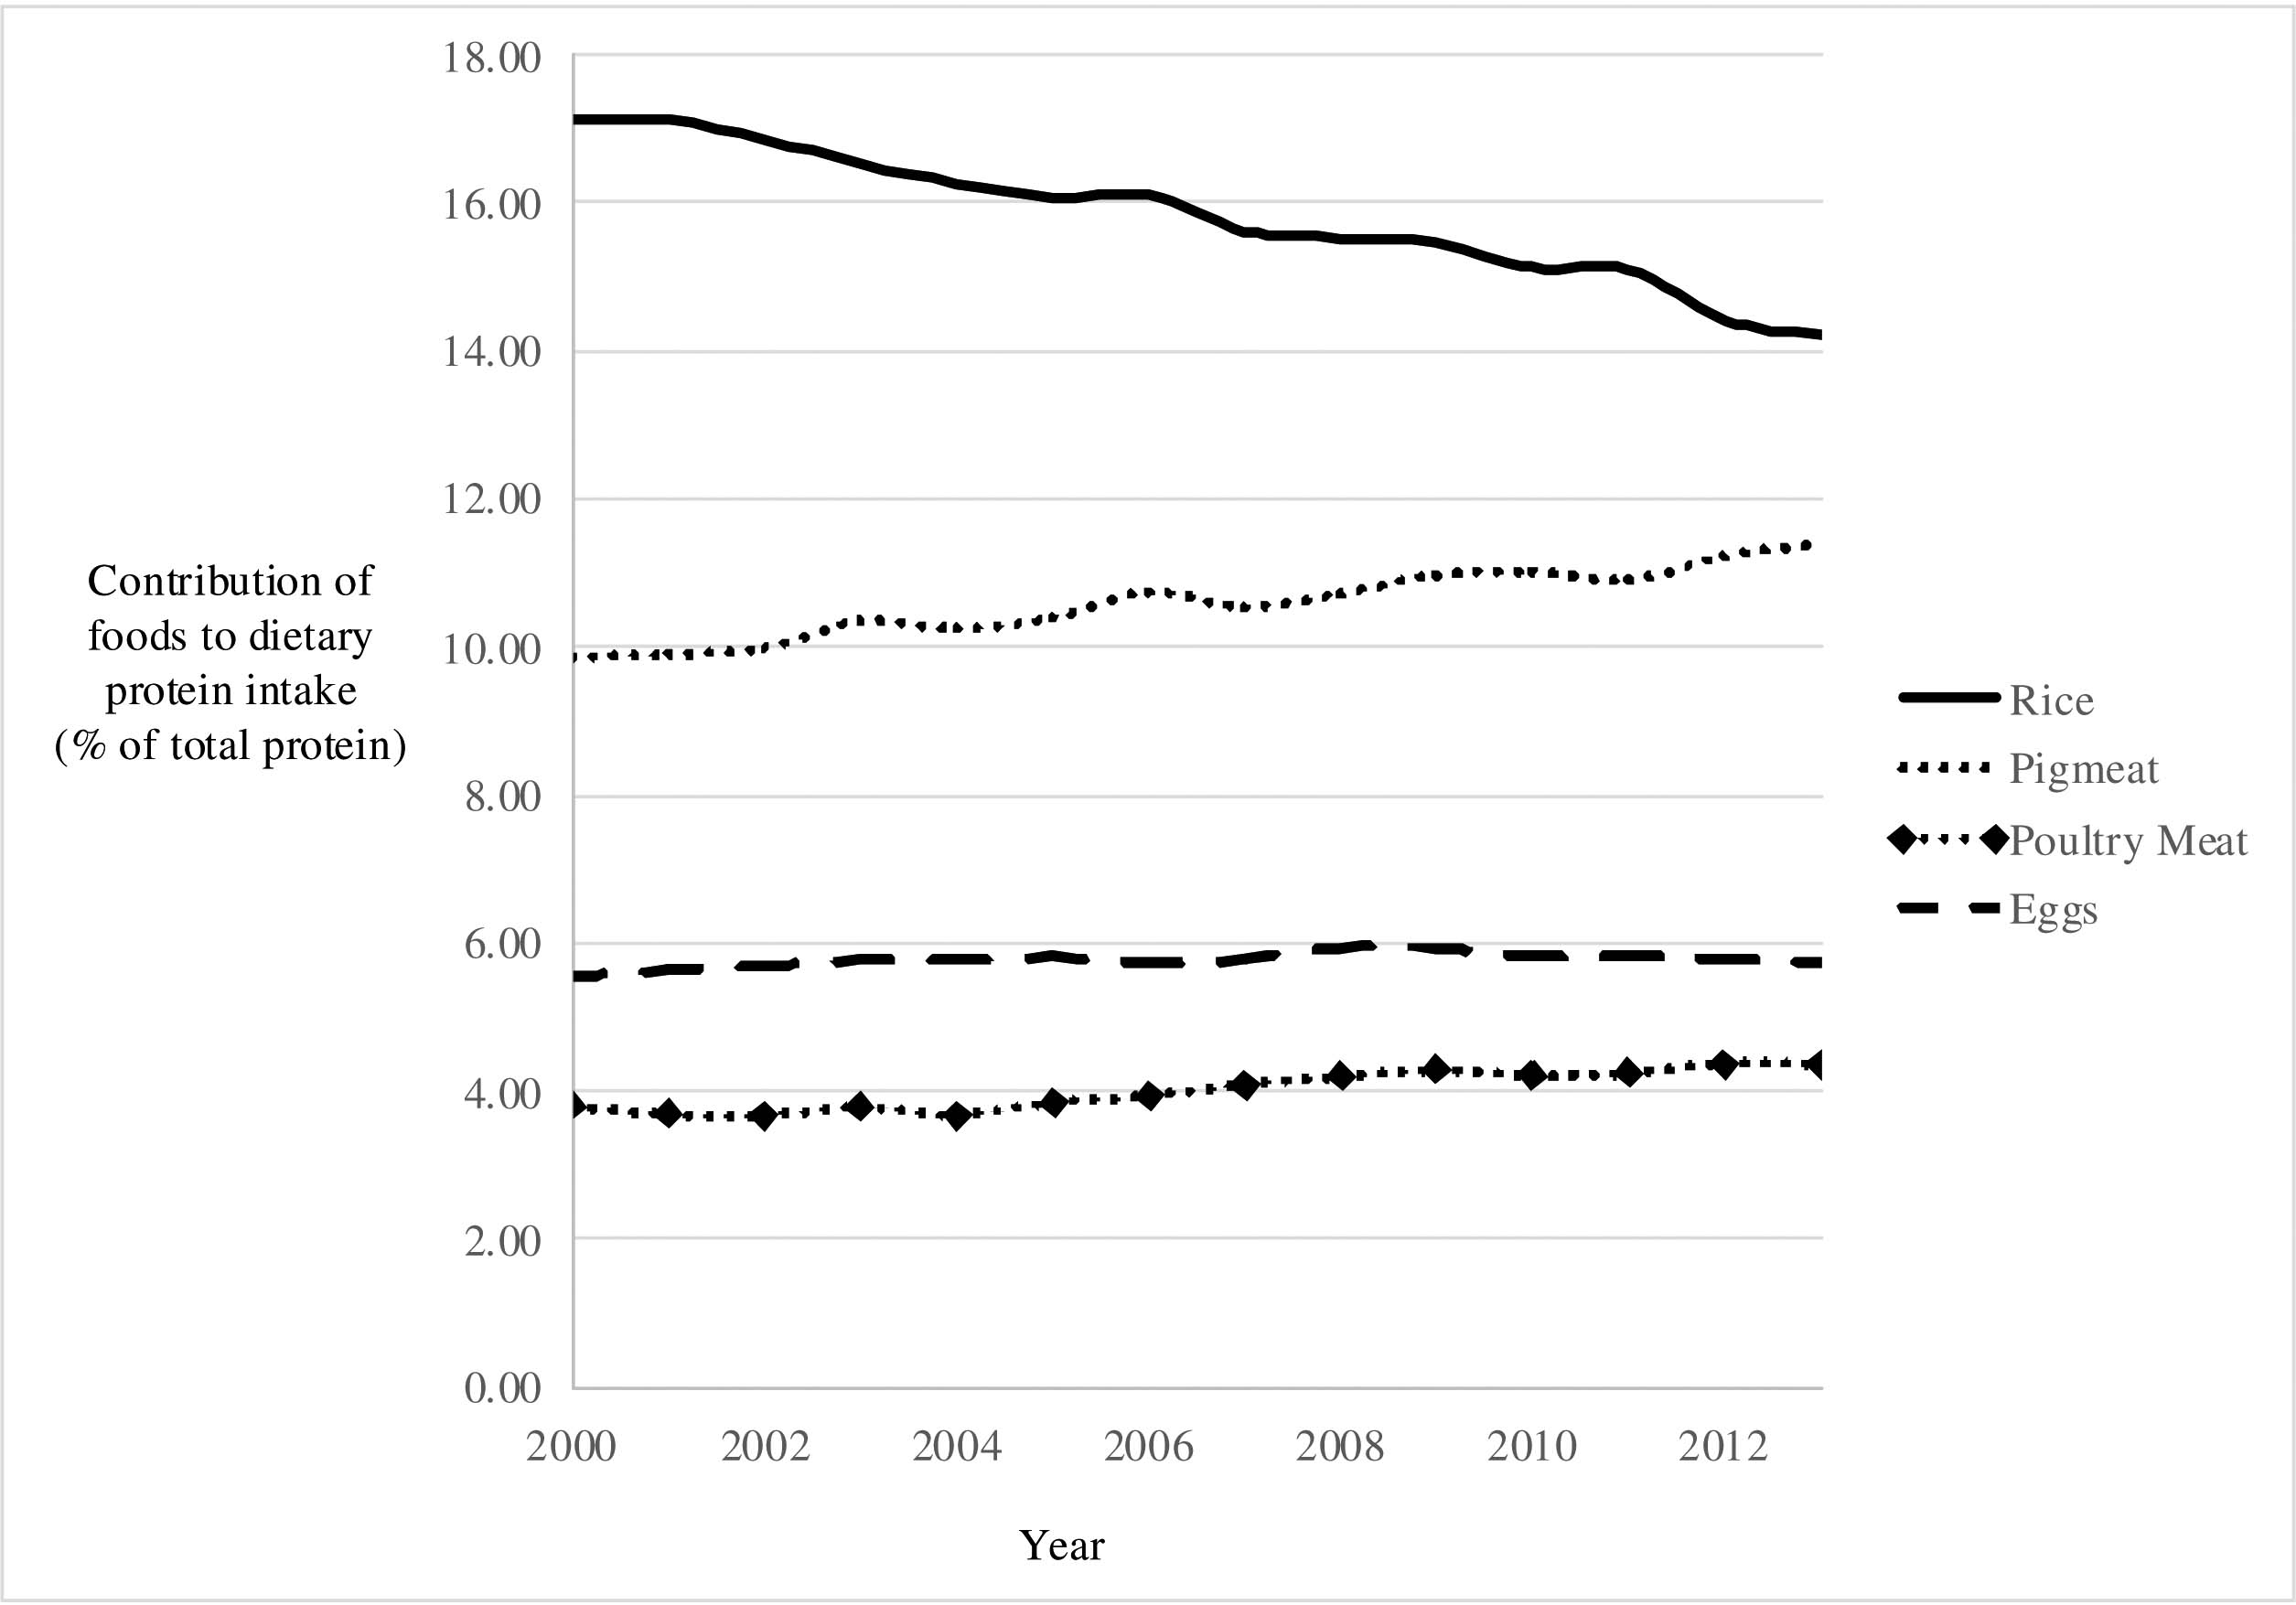
The egg consumption of the Chinese people has continued to increase in recent years. Eggs contribute approximately 6% of the protein in the diets of Chinese citizens. This proportion has increased slowly in recent years, although not at the same rate of increase that has occurred for pig and poultry meat (Figure 1).
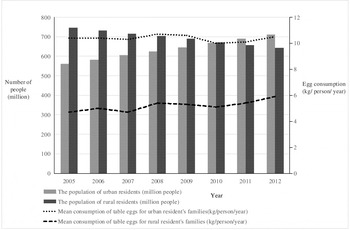
Meanwhile, the contribution of protein from cereals has markedly decreased. Urban residents eat approximately 70% more eggs than rural residents but this difference is rapidly changing; The greatest increases in egg consumption have been seen in the population living in rural areas, whereas egg consumption in the urban population has remained approximately stable (Figure 2).
The contribution of different human foods to the total protein supply in China (Adapted from FAO, 2017).

Egg consumption of urban and rural people in China (Adapted from National Bureau of Statistics of China, 2017).

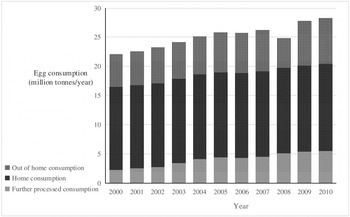
Egg consumption in rural families is still much lower than that in urban families (5.9 kg eggs per capita vs. 10.5 kg eggs per capita in 2012), but with the rapid increase in urbanisation it is expected that the future demand for eggs will increase (Wang et al., Reference WANG, CHEN and LIU2015). In 2010, home consumption of eggs accounted for 53% of egg sales with ‘dining out’ consumption accounting for 28% and 19% for further processed egg (Figure 3). Home consumption of shell eggs increased slowly whereas further processed egg consumption more than doubled (144% increase) between 2000 and 2010, and dining out consumption rose by approximately 40% during this time.
Egg consumption in China from 2000 to 2010 (Adapted from National Bureau of Statistics of China, 2017).

In the five years since 2012, the annual revenue for the poultry industry has grown at an average rate of 8.7% per annum (NBSC, 2017). Eggs are mostly sold by the farmers to wholesalers. The proportion of eggs sold through supermarkets is increasing, although not at the same rate of the wholesale market for eggs. There is an increasing number of small shops or street stalls that sell poultry products and this remains the dominant route for egg sales.
The retail egg price is approximately 30-40% greater than the price received by egg producers. Urban families with high incomes are becoming increasingly concerned about their long-term health and the state of the environment and some are now prepared to buy organic or free-range eggs. Speciality eggs are emerging in response to the demand from these affluent urban consumers (Zhang et al., Reference ZHANG, CHEN, ZHAO, XU, CHEN and YANG2016; Godfray et al., Reference GODFRAY, BEDDINGTON, CRUTE, HADDAD, LAWRENCE, MUIR, PRETTY, ROBINSON, THOMAS and TOULMIN2010). Approximately 5% of eggs are branded and this yields a two to five-fold premium in margin over the generic product (Ke and Han, Reference KE and HAN2007).
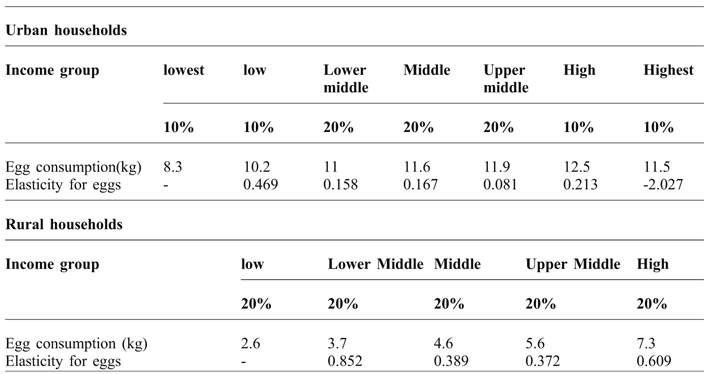
Egg price has relatively little effect on consumer demand for eggs: The egg market in China is relatively inflexible for price and this is particularly the case in urban residents and most profound in those in high income brackets (Table 1) (Ke and Han, Reference KE and HAN2007). Demand for eggs is more elastic in price in rural communities but this is less evident in high income households who favour high protein intakes. Low income households have relatively low protein intakes (Popkin and Du, Reference POPKIN and DU2003), and at times of high animal protein prices, they would change to buy cheaper foods, such as pulses and a higher proportion of grains. The farm price of eggs is therefore highly sensitive to changes in production levels and the supply of eggs. There are seasonal fluctuations in egg price, with lowest prices in late spring and highest in the autumn (Li et al., Reference LI, XU, DONG, LI, LIU and WANG2010; CAAA, 2017).
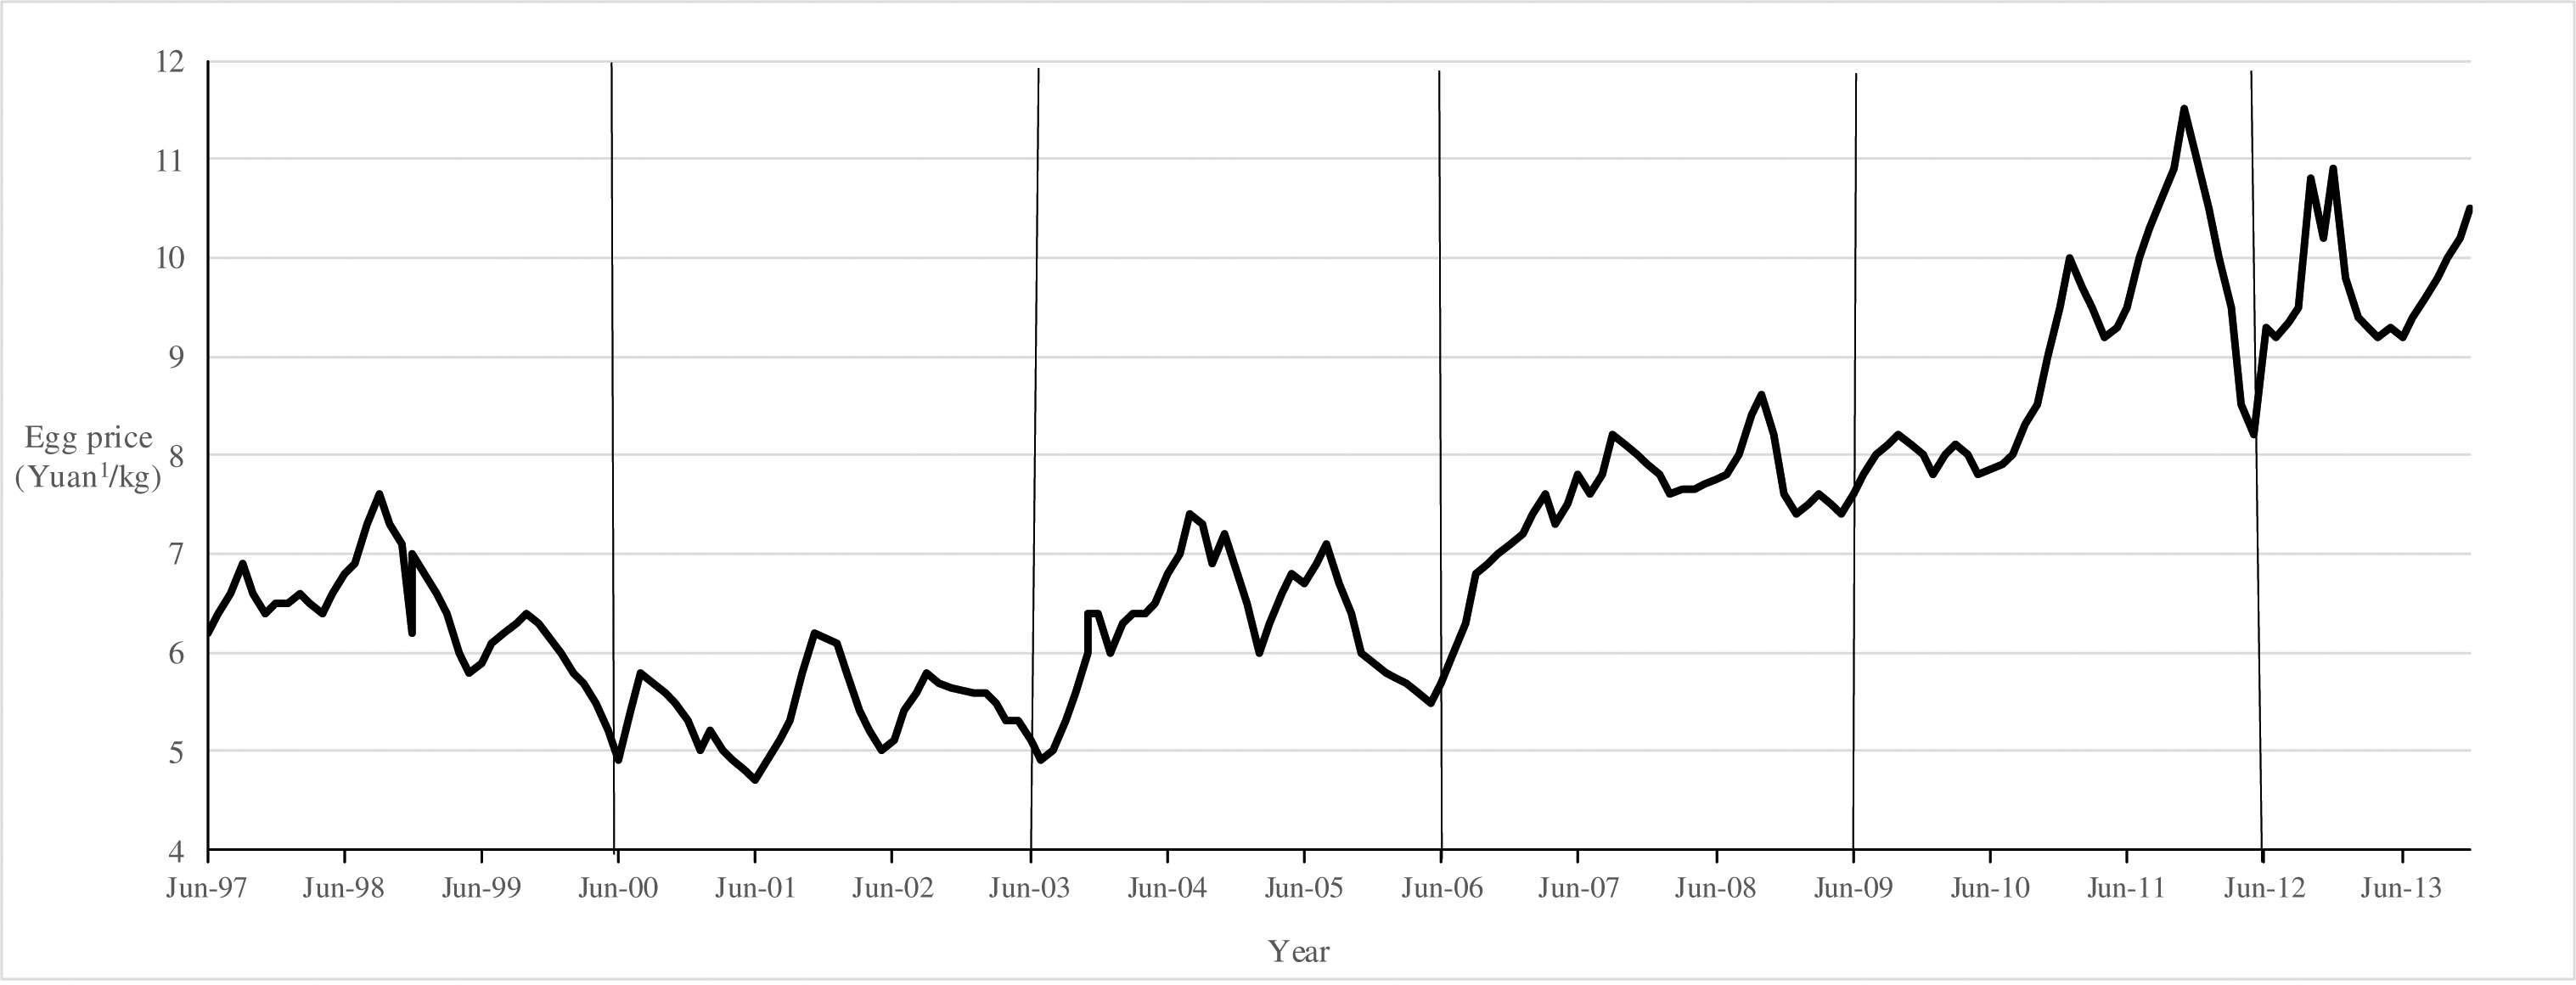
There is a significant proportion of egg production systems that do not use fully environment-controlled buildings. These systems can have large seasonal changes in production from spring to autumn and hence have a significant effect on the numbers of eggs that enter the wholesale market at these times. A three-year cycle in egg prices is evident in the Chinese market (Figure 4). Smaller egg producers tend to have low-cost poultry houses and so have low fixed capital costs in their business. These producers may delay restocking their houses at times of low egg prices and this results in this cycle of changing egg prices (Gueye, Reference GUEYE2009; Zhou and Li, Reference ZHOU and LI2012).
Income elasticity estimates for eggs for urban and rural households in China, 2005 (Ke and Han, Reference KE and HAN2007).

The decision to restock may be affected by changes in the costs of production. In the last decade, costs at farm level have generally changed in line with layer feed prices, which reached a peak in 2013. Average cost of egg production was 8.7 Yuan/kg (US$1.31 /kg) and feed was 2350 Yuan/ tonne (US$352 /tonne) (IEC, 2017). Variation in feed costs remain the major, but not the only, influence on production costs.
Annual trend of egg price in China from 1997 to 2013 (Yuan1/kg) (Adapted from China Animal Agriculture Association, 2017).
1Currency conversion used: One Chinese Yuan =0.15 US$
2Vertical lines indicate the duration of egg price cycle.

Structure of industry
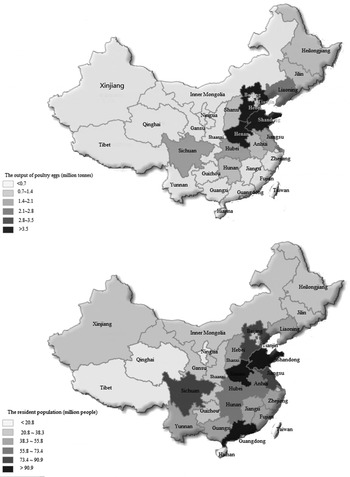
Egg production in China has grown steadily over recent years, with a 24% increase in production from 2006 to 2015. Eggs are produced in all provinces of China but now production is concentrating in a relatively few provinces (Figure 5), whereby 10 Chinese provinces produce 80% of the national eggs.
The output of poultry eggs (million tonnes per year) and the resident population (year-end) of China in 2015 (Adapted from National Bureau of Statistics of China, 2017).

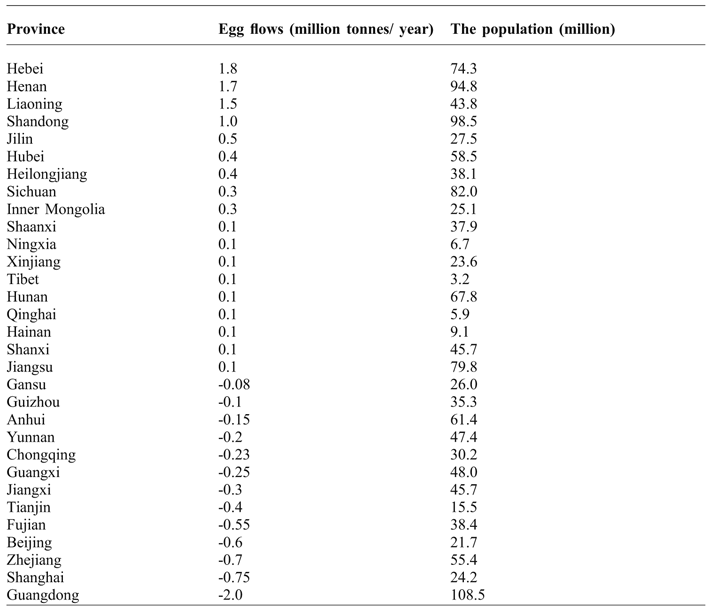
In order to meet the demands throughout the whole nation there is a substantial movement of eggs around the country. Eggs are transported from North and Northeast China to Southeast and Southern regions as well as into big cities like Beijing, Tianjin and Shanghai. The province of Guangdong, in the south of China, has the largest gap between supply and demand with an inflow of two million tonnes of eggs each year, followed by Shanghai (0.75 million tonnes), Zhejiang (0.7 million tonnes) and Beijing (0.6 million tonnes) (Table 2). The concentration of egg production in the North and North-East of China is likely due to the availability of locally produced cereals as well as good access to ports for imported feedstuffs. Recent major improvements in the transport infrastructure by the Chinese Government have facilitated this centralisation in the egg production industry (Démurger, Reference DÉMURGER2001).
Net egg flows (million tonnes/year) and resident population (year-end) (10 000 residents) of each province in China in 2015 (Adapted from China Animal Agriculture Association, 2017 and National Bureau of Statistics of China, 2017).

*Positive number represents the quantity of the exported eggs to other provinces; Negative number represents the quantity of the imported eggs to the province.
Henan, Shangdong, Hebei, Liaoning, Sichuan and Jiangsu, the six largest egg-producing provinces, accounted for nearly 61% of the total production of the country (NBSC, 2017). Most of these provinces have increased their egg production in recent years, except for Hebei. The reduction in egg production in Hebei may be due to the relatively large number of small egg producers in this province that may be ceasing production due to Government legislation, the poorer viability of relatively small-scale production methods and the availability to them of other employment opportunities in the nearby, rapidly developing, urban areas (Li et al., Reference LI, XU, DONG, LI, LIU and WANG2010).
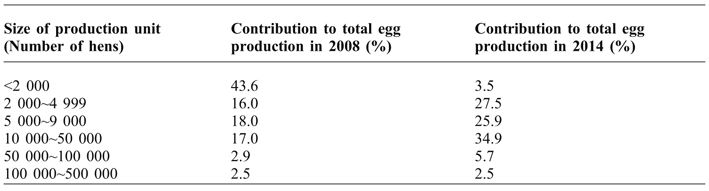
Intensification of egg production has occurred throughout the country. In 2008, 43% of all eggs produced were from flocks with sizes less than 2,000 hens, but in 2014 this size of egg producer only supplied 4% of all eggs produced in China (Table 3). Large numbers of relatively small independent egg producers still exist and, in 2014, over 50% of all eggs produced were from flock sizes of less than 10,000 hens. However, large integrated companies have been established which manage large operations.
The top six largest egg producers (Beijing Huadu Yukou Poultry Company, Beijing Pinggu Charoen Pokphand, Beijing Deqingyuan Poultry Company, Anhui Rong Da and Shanxi Dajiang Nongke) have flock sizes of more than five million laying hens. Such companies are mostly vertically integrated and manage the bird husbandry, feed milling, transport and distribution of the eggs. Recent increases in the average size of Chinese egg production units are similar to the way which the egg production industries in developed countries, such as European Union and United States, developed (Mench et al., Reference MENCH, SUMNER and ROSEN-MOLINA2011).
Size of laying hen units and their contribution to the proportion of total eggs produced in China in 2008 and 2014 (Adapted from China Animal Agriculture Association, 2017).

Management methods
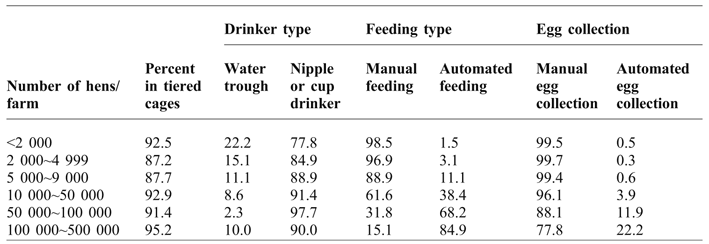
Eggs are primarily produced in cage systems, regardless of the size of the enterprise. Around 90% of eggs are produced from cage systems with 9% from free-range systems and 1% from barn systems (IEC, 2017). Large, modern egg production farms increasingly use environment-controlled buildings in which cages incorporate automatic feed delivery and automatic egg collection equipment (Table 4). Recently-built egg production farms are typically on sites housing up to half a million hens. There are only a few sites that have more than a million birds.
Small egg production farms (less than 10,000 hens) typically use polythene tunnels, old greenhouses, or other farm buildings for hen housing that have none or poor environmental control. The tiered cages that are installed in these buildings often have little automation and feed is delivered and eggs are collected manually (Table 4). This type of production requires a high labour input, which is provided by farmers who are keeping birds as a side-line activity. However less people are now willing to work in the countryside as there are better employment opportunities in urban areas. Hence, many small farmers have given up egg production.
There has been growth in the free-range and organic chicken production over the past five years, but these account for a small number of chickens farmed. However, this is slowly shifting as Chinese consumers are now increasingly willing to buy cage-free eggs (Wang et al., Reference WANG, YUE, WU, ZHANG and QI2017; Rakonjac et al., Reference RAKONJAC, BOGOSAVLJEVIĆ-BOŠKOVIĆ, PAVLOVSKI, ŠKRBIĆ, DOSKOVIĆ, PETROVIĆ and PETRIČEVIĆ2014; Zhang et al., Reference ZHANG, CHEN, ZHAO, XU, CHEN and YANG2016). Laying hen strains that produce brown shelled eggs are the predominant stock used in the Chinese industry. Approximately 70% of eggs sold are brown shelled (IEC, 2017). Hyline supplies 77% of all the laying stock (brown and tinted brown shelled eggs) whereas a local breeding company, Jinghong and Jingfen, supply 12% of the birds (tinted brown shells) (NBSC, 2017). The remaining 11% of laying stock are supplied by Lohmann (brown shelled eggs), Nongda (white shelled eggs) and there are some traditional breeding companies that produce stock that lay green shelled eggs.
Management methods in different scale farms (Yang et al., Reference YANG, QIN, XU, ZHAO, XUE and ZHOU2014).

There are no formal regulations for animal densities in laying hen units, so farmers tend to stock to the economic optimum. Most large integrated companies keep flocks for a 60 to 70 week laying period, whereas small independent producers may use extended laying periods depending on the market conditions that prevail.
Conclusions
Egg production continues to provide the Chinese population with a high proportion of their intake of high quality dietary protein. Egg consumption is expected to continue to increase with the rise in the human urban population. It is probable that the major increase in demand for eggs will be for ‘dining out’ consumption and their use in further-processed food products. The poultry sector is no longer dominated by hundreds of millions of smallholders keeping birds as a side-line activity. Many small farmers have given up production, especially in the economically more developed Eastern provinces of the country. In the future, it is expected that intensification will continue. Small-scale and non-commercial farmers will continue their exit from the industry. It is possible that the number of poultry farmers in China could halve by 2020. Egg production is concentrated in certain regions of China and the logistical network continues to evolve that distributes the eggs to the consumer. Chinese consumers are becoming more focused on the quality. traceability and safety of eggs, and future developments in the egg production market may concentrate on these aspects.
Acknowledgments
This review was produced as part of the Project of Jiangsu Province Policy Leading Program of the People's Republic of China (SZ-HA2017010) and the Scientific Research Foundation of PhD Student of Yangzhou University.