


1. Introduction
Credit default swap (CDS) has been widely used by market participants to manage and hedge credit risks. The CDS contract is generally a contract signed between the credit protection buyer and the credit protection seller. The reference asset held by the credit protection buyer has default risk. When there is only one reference asset, it is called a single-name CDS contract. While there are multiple reference assets, it is called a basket CDS contract. In order to transfer the risk, the credit protection buyer signed an agreement with the counterparty. The agreement stipulates that if the reference asset does not default, the credit protection buyer shall pay the premium to the seller, but if the reference asset defaults, the credit protection seller shall compensate the buyer for his loss. With the outbreak of the subprime mortgage crisis, people realize that counterparties also have the default risks. So the study of pricing the CDS with counterparty risk has attracted more and more researchers. There are two common models to study the pricing of credit derivatives in the literature, namely the structural models and the reduced-form intensity-based models.
In the structural model, the default of the firm is deemed to be triggered when the asset value falls below a certain prescribed level. Black and Cox [Reference Black and Cox1] proposed the first passage model in which the default time was assumed to be the first time that the firm value broke down the constant barrier. Gökgöz et al. [Reference Gökgöz, Uğur and Okur7] studied the evaluation of a single name CDS via the discounted cash flow method based on Merton [Reference Merton23] and Black-Cox [Reference Black and Cox1]. Chen and He [Reference Chen and He3] proposed the multiscale stochastic volatility (SV) model to price the CDS premium. Under the framework of structural model, Wu et al. [Reference Wu, Sun and Mei26] proposed a new double exponential jump-diffusion model with fuzziness for CDS pricing. He and Lin [Reference He and Lin11] derived an analytical approximation for the price of a CDS contract price by assuming that the reference asset followed a regime switching Black–Scholes model.
The reduced-form intensity-based model was introduced by Jarrow and Turnbull [Reference Jarrow and Turnbull16], in which the default intensity is described by an exogenous stochastic process. Lando [Reference Lando19] used a Cox process to model the default intensity and assumed that the risk-free rate satisfied the Vasicek model. Malherbe [Reference Malherbe22] applied a Poission process to describe the default intensity. That is, the default intensities were constant between defaults, but could jump at the times of defaults. Herbertsson and Rootzén [Reference Herbertsson and Rootzén14] derived a closed-form expression for a basket CDS by the matrix-analytic method. Zheng and Jiang [Reference Zheng and Jiang27] used the total hazard construction method to derive an analytic formula for the joint distribution of default times.
Since the counterparty default can explain the sudden worsening of the credit crisis after Lehman bankruptcy in September 2008, more and more scholars consider counterparty default risk in CDS pricing. Jarrow and Yu [Reference Jarrow and Yu17] introduced the concept of the counterparty risk and illustrated the effects of the counterparty risk on CDS price. Leung and Kwok [Reference Leung and Kwok20] perform valuation of CDS with counterparty risk using the reduced form framework with inter-dependent default correlation. Huang and Song [Reference Huang, Song and Zheng15] priced the basket CDS with counterparty risk under a multi-name contagion model. Some scholars used copula function to describe the default correlation between the reference asset and counterparty. Crépey and Jeanblanc [Reference Crépey, Jeanblanc, Zargari, Kijima, Hara, Muromachi and Tanaka4] studied CDS pricing with counterparty risk under a Markov chain copula model. Harb and Louhichi [Reference Harb and Louhichi8] used the mixture copula to price the basket CDS with counterparty risk. Brigo and Chourdakis [Reference Brigo and Chourdakis2] assumed the defaults of reference asset and counterparty were connected through a copula function. They found that the default correlation had a relevant impact on the counterparty-risk credit valuation. Jorion and Zhang [Reference Jorion and Zhang18] pointed out that the introduction of counterparty risk can explain the observed clustering of default. They also provided an empirical analysis to verify this fact.
When some extreme events occur or some important announcements arrive, they will cause a sudden jump in the price of an asset. Meanwhile, other assets related to this asset will also jump. This correlation of asset prices may lead to concentrated default events. Take the global financial crisis occurring in 2008 as an example, the crisis in the US can trigger simultaneous losses of most firms in other countries. Moreover, the COVID-19 pandemic that began in 2020 makes the risk of one country or region spread to all parts of the world and affect almost all sectors. Clearly, such risks can be regarded as systemic risks, which have significantly different characteristics compared with the firm-specify risks. Firstly, the impact scope of risk is different. The firm-specify risk usually only affects the assets of its own firm, but the impact scope of systemic risk is very wide. Secondly, the systemic risk makes the default events more drastic. For example, the second largest subprime mortgage institution new century financial, the fourth largest investment bank Lehman Brothers and the real estate investment trust company American home mortgage all went bankrupt during the American subprime mortgage crisis, which is extremely rare in financial history. Finally, the impact of systemic risk is more lasting. It is known that the impact of the COVID-19 pandemic has lasted for 2 years and will continue to affect the global asset prices. Therefore, combined with these three main characteristics, we believe that the systemic risk and firm-specific risk should be treated separately and should not be confused, because their characteristics are significantly different. Our paper pays special attention to the research on the impact of systemic risk. Since the common jump process can describe the systemic risk, we decided to choose a jump process with a common jump and firm-specific jumps, which can be used to simulate the default intensity of firm affected by systemic risk. Finger [Reference Finger5] assumed that the common macro factor affected the default times of all the reference assets in the portfolio. Giglio [Reference Giglio6] showed how to use CDS prices and bond prices to verify the existence of systemic risk and an idiosyncratic risk. However, there are few literatures that take systemic risk into account in the reduced-form intensity-based model to price CDS contract.
In this paper, we study the CDS pricing with counterparty risk when there are two firms in the market. In previous studies about reduced-form intensity-based model, most researchers assumed that the default probabilities of reference assets and counterparties are correlated by Brownian motion, that is, the default of one party would cause the default of the other party. In the actual market, rare events can cause the firms’ default events to be highly correlated instantaneously. In fact, this kind of risk can be regarded as the systemic risk, which has a great impact on CDS prices and should not be ignored. The main contributions of this paper are as follows. (1) We model the extremely rare events using a common jump process in a reduced form model. The default jump intensities of the reference firm and counterparty are both assumed to follow the mean-reverting CIR processes with independent jumps respectively and a common jump. The process is a general process that contains the CIR process and a jump-diffusion process. (2) Using the PDE method, we obtain two PDEs for the joint survival probability density, the probability density of the first default between the reference firm and counterparty. The approximate analytic solutions of the relevant default probability densities can be derived from PDEs. Then with the expressions of the probability densities, we can get the formula of the CDS price with counterparty risk. (3) Our model describes the source of jump risk more carefully. After introducing the common jump process, it can be verified that the default of the reference asset has a greater impact on the CDS price than that of the default risk of counterparty in the numerical analysis. This may be because counterparties often default passively. In practice, we should pay more attention to controlling the default risk of reference assets. It is worthy of note that our model can be extended to the jump model with stochastic volatility. For the introduction of this model, readers can refer to He and Lin [Reference He and Lin12,Reference He and Lin13], He and Chen [Reference He and Chen9,Reference He and Chen10]. Stochastic volatility model can describe the phenomenon of volatility clustering of default intensity, but the derivation of CDS price is quite difficult. When the volatilities of the default intensity of the two firms are stochastic, the number of state variables will increase to four. The increase of the number of parameters makes the calculation more difficult. The solution for the PDE satisfied by the relevant default probability density does not necessarily have an analytical solution. If so, the CDS price can be solved by Monte Carlo simulation and other numerical methods.
The article is organized as follows. In Section 2, we describe the setting of our CDS and assume that there are two firms in the market, the default jump intensities of the reference firm and counterparty follow the mean-reverting CIR processes with a common jump process. We obtain two PDEs for the joint survival probability density and the probability density of the first default. In Section 3, we derive the closed-form formula of the CDS price with counterparty risk. In Section 4, we do sensitivity analysis under our model. Finally, we offer concluding remarks in Section 5.
2. Default probability density under reduced-form intensity model
Let  $T>0$ be a finite time horizon and fix a probability space (
 $\Omega, \mathcal {F} , P$), the probability measure
 $P$ is the risk-neutral measure. The canonical filtration generated by the underlying stochastic structure is denoted by
 ${\mathcal {F}_t}$, which defines the information available at each time. The conditional probability measure given
 $\mathcal {F}_t$ is denoted by
 $P_t$ and the associated conditional expectation operator is
 $E_t$. Let default time
 $\tau$ be a stopping time associated with the filtration
 $\mathcal {F}_t$. For sufficiently small
 $\Delta t \geq 0$,
 $\lambda (t)$ is an intensity process for
 $\tau$ if there holds
 $$P_t\{\tau \le t+\Delta t\, |\,\tau>t\}=\lambda(t)\Delta t.$$
Suppose  $\lambda$ is a
 $2$-dimensional Markov process of càdlàg state variables drawn from space
 $V \subset \mathbb {R}^{2}$. We assume that the reference asset is a bond which is issued by company
 $F_B$. The bond may default with the default intensity
 $\lambda _1(t)$. There is a credit protection seller named
 $F_C$ who will compensate if the reference asset defaults. The seller
 $F_C$ has a stochastic default intensity of
 $\lambda _2(t)$. The default intensity
 $\lambda _1(t)$ and
 $\lambda _2(t)$ may jump due to the sudden systemic risk which may be triggered by some important announcements. Therefore, we use the jump process with a common jump to simulate the default intensity of reference assets and counterparty, respectively. This process can describe the phenomenon of concentrated default caused by systemic risk. Both the default intensities
 $\{\lambda _i(t), i=1,2\}$ are assumed to follow the CIR type processes with common jump risk
 \begin{equation} d\lambda_i(t)=a_i(b_i-\lambda_i(t))\,dt+\sigma_i \sqrt{\lambda_i(t)}\,dW_i(t)+\epsilon_i(dJ_i(t)+dJ(t)), \end{equation}
where  $a_i,b_i,\sigma _i$ are positive constants. Respectively,
 $a_i$ is the mean reverting rate.
 $b_i$ represents the long-term level of jump intensity.
 $\sigma _i$ is the volatility of the jump intensity. Each
 $W_i(t)$ is a standard Brownian motion.
 $dW_i(t)\,dW_j(t)=0$ for
 $i\ne j$. The common jump
 $J(t)$ is a Poisson process that
 ${\rm prob}(dJ(t)=1)=\lambda ^{J} \,dt$ and
 ${\rm prob}(dJ(t)=0)=1-\lambda ^{J} \,dt$. Similarly, we have
 ${\rm prob}(dJ_i(t)=1)=\lambda _i^{J} \,dt$ and
 ${\rm prob}(dJ_i(t)=0)=1-\lambda _i^{J} \,dt$.
 $J_1(t), J_2(t), J(t)$ are independent. Without losing generality, we assume that the jump intensities
 $\lambda _1^{J}$,
 $\lambda _2^{J}$,
 $\lambda ^{J}$ are constants for simplicity of calculation.
 $\epsilon _i$ is the percentage jump size (conditional on a jump occurring) and we assume that
 $\epsilon _i$ are constants.
Let  $\tau _1$ denote the default times of reference asset
 $F_B$ and
 $\tau _2$ represent the default time of counterparty
 $F_C$ throughout this article. Given
 $\mathcal {F}_T$, the default times
 $\{\tau _i(t), i=1,2\}$ are conditionally independent. The initial time and expiration date are represented by
 $t$ and
 $T$ (
 $0\le t \le T$). Before we price the CDS, we need some conclusions about the relevant default probability densities as shown in Theorems 2.1 and 2.2.
Theorem 2.1 (Joint survival probability density)
If the reference asset (firm  $F_B$) and counterparty (firm
 $F_C$) do not default until time
 $s(t\le s \le T)$, the joint survival probability density
 $P(t,\lambda _1,\lambda _2;s)$ has an approximate closed-form solution as follows:
 \begin{equation} P(t,\lambda_1,\lambda_2;s)=\exp\left\{A(t;s)+\sum_{i=1}^{2}B_i(t;s)\lambda_i(t)\right\}, \end{equation}
where
 \begin{equation} B_i(t;s)=\frac{-2(1-e^{-\zeta_i(s-t)})}{2\zeta_i-(\zeta_i-a_i)(1-e^{-\zeta_i(s-t)})}, \end{equation}
and
 \begin{equation} A(t;s)={-}\sum_{i=1}^{2}\frac{a_ib_i+\lambda_i^{J} \epsilon_i+\lambda^{J} \epsilon_i}{\sigma_i^{2}}\left[2\ln \left(1-\frac{(\zeta_i-a_i)(1-e^{-\zeta_i (s-t)})}{2\zeta_i}\right)+(\zeta_i-a_i)(s-t)\right], \end{equation}
here
 \begin{equation} \zeta_i=\sqrt{a_i^{2}+2\sigma_i^{2}}. \end{equation}
Proof. If no default events happen, the CDS buyer will pay the CDS fee continuously until the expiration date. The conditional independence means the joint survival probability at time  $s(t\le s \le T)$ can be given by
 \begin{equation} P_T\{\tau_1>s,\tau_{2}>s\}=\exp\left\{-\int_t^{s}\sum_{i=1}^{2}\lambda_i(u)\,du\right\}. \end{equation}
Because  $\mathcal {F}_t \subset \mathcal {F}_T$, we have
 $E_t(1_{\{{\rm Event}\}})=E_t(E_T(1_{\{{\rm Event}\}}))$. We denote the probability density
 $P(t,\lambda _1,\lambda _2;s)$ as
 \begin{align} P(t,\lambda_1,\lambda_2;s)& =P_t\{\tau_1>s,\tau_2>s\} =E\left[\left.\exp{\left\{-\int_t^{s}\sum_{i=1}^{2}\lambda_i(u)\,du\right\}}\,\right|\mathcal{F}_t\right]\nonumber\\ & =E_t\left[\exp{\left\{-\int_t^{s}\sum_{i=1}^{2}\lambda_i(u)\,du\right\}}\right]. \end{align}
By using Feynman–Kac theorem, we can get the follwing PDE
 \begin{equation} \left\{\begin{aligned} & \frac{\partial P}{\partial t}+\frac{1}{2}\sum_{i=1}^{2}\sigma_i^{2}\lambda_i\frac{\partial^{2} P}{\partial \lambda_i^{2}}+\sum_{i=1}^{2}a_i(b_i-\lambda_i)\frac{\partial P}{\partial \lambda_i}-\sum_{i=1}^{2}\lambda_i P\\ & \quad +\lambda_1^{J}E[P(t,\lambda_1+\epsilon_1,\lambda_2;s) -P(t,\lambda_1,\lambda_2;s)]\\ & \quad +\lambda_2^{J}E[P(t,\lambda_1,\lambda_2+\epsilon_2;s)-P(t,\lambda_1,\lambda_2;s)]\\ & \quad +\lambda^{J}E[P(t,\lambda_1+\epsilon_1,\lambda_2+\epsilon_2;s)-P(t,\lambda_1,\lambda_2;s)]=0,\\ & P(s,\lambda_1,\lambda_2;s)=1. \end{aligned}\right. \end{equation}
According to Øksendal [Reference Øksendal24],  $P(t,\lambda _1,\lambda _2;s)$ has a solution with the following form
 $$P(t,\lambda_1,\lambda_2;s)=\exp\left\{A(t;s)+\sum_{i=1}^{2}B_i(t;s)\lambda_i(t)\right\}.$$
Substitute the above formula into Equation (2.8) to obtain
 \begin{align} & \frac{\partial A(t;s)}{\partial t}+\sum_{i=1}^{2}\frac{\partial B_i(t;s)}{\partial t}\lambda_i+\frac{1}{2}\sum_{i,j=1}^{2}B_i^{2}(t;s)\sigma_i^{2}\lambda_i +\sum_{i=1}^{2}a_i(b_i-\lambda_i)B_i(t;s)-\sum_{i=1}^{2}\lambda_i\nonumber\\ & \quad +\lambda_1^{J}E[e^{B_1(t;s)\epsilon_1}-1]+\lambda_2^{J}E[e^{B_2(t;s)\epsilon_2}-1] +\lambda^{J}E[e^{B_1(t;s)\epsilon_1+B_2(t;s)\epsilon_2}-1]=0. \end{align}
With the approximate formula for sufficient small  $\epsilon _i$
 \begin{equation} E[e^{B_i(t;s)\epsilon_i}-1]\approx E[B_i(t;s)\epsilon_i], \end{equation}
and
 \begin{equation} E[e^{\sum_{i=1}^{2}B_i(t;s)\epsilon_i}-1]\approx E\left[\sum_{i=1}^{2}B_i(t;s)\epsilon_i\right]. \end{equation}
For other numerical treatments of the jump items, readers can refer to Ma et al. [Reference Ma, Zhu and Chen21]. We substitute (2.10) and (2.11) into (2.9) to obtain two ODEs
 \begin{equation} \left\{\begin{array}{ll} \displaystyle\dfrac{\partial A(t;s)}{\partial t}+\sum_{i=1}^{2}(a_ib_i+\lambda_i^{J} \epsilon_i+\lambda^{J} \epsilon_i)B_i(t;s)=0, & A(s;s)=0;\\ \displaystyle\dfrac{\partial B_i(t;s)}{\partial t}-a_iB_i(t;s)+\dfrac{1}{2}\sum_{i=1}^{2}B_i^{2}(t;s) \sigma_i^{2}-1=0, & B(s;s)=0.\\ \end{array}\right. \end{equation}
Theorem 2.2 (The probability density of the first default)
For the reference asset (firm  $F_B$) and counterparty (firm
 $F_C$), if the first default happens at time
 $\tau _i(s\le \tau _i \le s+ds)$, the default probability density
 $\{q_i(t,\lambda _1,\lambda _2;s),i=1,2\}$ at time
 $s$ has an approximate closed-form solution as follows
 \begin{equation} q_i(t,\lambda_1,\lambda_2;s)=(C_i(t;s)\lambda_i+D_i(t;s))\exp\left\{A(t;s) +\sum_{k=1}^{2}B_k(t;s)\lambda_k(t)\right\}, \end{equation}
where
 \begin{equation} C_i(t;s)=\exp\left\{{-}2\ln \left(1-\frac{(\zeta_i-a_i)(1-e^{-\zeta_i (s-t)})}{2\zeta_i}\right)-\zeta_i(s-t)\right\}, \end{equation}
and
 \begin{align} D_i(t;s)& =\int_t^{s}(a_ib_i+\lambda_i^{J}\epsilon_i+\lambda^{J}\epsilon_i)C_i(u;s) +\lambda_i^{J}\epsilon_i^{2}B_i(u;s)C_i(u;s)\nonumber\\ & \quad +\lambda^{J}\epsilon_iC_i(u;s)\sum_{j=1}^{2}B_j(u;s)\epsilon_j\,du. \end{align}
 $A(t;s)$ and
 $B_k(t;s)$ are expressed as in (2.4) and (2.3).
Proof. The default probability of the first default which happens at time 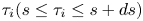 $\tau _i(s\le \tau _i \le s+ds)$ is
 \begin{align} P_T\{\tau_1>s,\tau_{2}>s,\tau_i \le s+ds\}& =P_T\{\tau_1>s,\tau_{2}>s\}\lambda_i(s)\,ds\nonumber\\ & =\exp{\left\{-\int_t^{s}\sum_{j=1}^{2}\lambda_j(u)\,du\right\}}\lambda_i(s)\,ds. \end{align}
Because of  $E_t(1_{\{{\rm Event}\}})=E_t(E_T(1_{\{{\rm Event}\}}))$, the probability density of the first default at time
 $s$ is
 \begin{equation} q_i(t,\lambda_1,\lambda_2;s)=E_t\left[\exp{\left\{-\int_t^{s}\sum_{j=1}^{2}\lambda_j(u)\,du\right\}}\lambda_i(s)\right]. \end{equation}
With the help of Feynman–Kac theorem, we can get the following PDE
 \begin{equation} \left\{\begin{aligned} & \frac{\partial q_i}{\partial t}+\frac{1}{2}\sum_{j=1}^{2}\sigma_j^{2}\lambda_j\frac{\partial^{2} q_i}{\partial \lambda_j^{2}}+\sum_{j=1}^{2}a_j(b_j-\lambda_j)\frac{\partial q_i}{\partial \lambda_j}-\sum_{j=1}^{2}\lambda_jq_i\\ & \quad +\lambda_1^{J}E[q_i(t,\lambda_1+\epsilon_1,\lambda_2;s) -q_i(t,\lambda_1,\lambda_2;s)]\\ & \quad +\lambda_2^{J}E[q_i(t,\lambda_1,\lambda_2+\epsilon_2;s)-q_i(t,\lambda_1,\lambda_2;s)]\\ & \quad +\lambda^{J}E[q_i(t,\lambda_1+\epsilon_1,\lambda_2+\epsilon_2;s)-q_i(t,\lambda_1,\lambda_2;s)]=0,\\ & q_i(s,\lambda_1,\lambda_2;s)=\lambda_i. \end{aligned}\right. \end{equation}
According to Øksendal [Reference Øksendal24],  $q_i(t,\lambda _1,\lambda _2;s)$ has a solution with the following form
 $$q_i(t,\lambda_1,\lambda_2;s)=(C_i(t;s)\lambda_i+D_i(t;s)) \exp\left\{A(t;s)+\sum_{k=1}^{2}B_k(t;s)\lambda_k(t)\right\}.$$
Substitute the above formula into Equation (2.18), we have
 \begin{align} & \frac{\partial C_i(t;s)}{\partial t}\lambda_i+\frac{\partial D_i(t;s)}{\partial t}+(C_i(t;s)\lambda_i+D_i(t;s))\nonumber\\ & \quad \times \left\{\frac{\partial A(t;s)}{\partial t}+\sum_{j=1}^{2}\frac{\partial B_j(t;s)}{\partial t}\lambda_j+\sum_{j=1}^{2}a_j(b_j-\lambda_j)B_j(t;s)\right.\nonumber\\ & \quad +\frac{1}{2}\sum_{j=1}^{2}B_j^{2}(t;s)\sigma_j^{2}\lambda_j-\sum_{j=1}^{2}\lambda_j +\lambda_1^{J}E[e^{B_1(t;s)\epsilon_1}-1]\nonumber\\ & \left.\quad \vphantom{\frac{1}{2}\sum_{j=1}^{2}}+\lambda_2^{J}E[e^{B_2(t;s)\epsilon_2}-1] +\lambda^{J}E[e^{B_1(t;s)\epsilon_1+B_2(t;s)\epsilon_2}-1]\right\}\nonumber\\ & \quad +a_i(b_i-\lambda_i)C_i(t;s)+B_i(t;s)C_i(t;s)\sigma_i^{2}\lambda_i +\lambda_i^{J}C_i(t;s)\epsilon_iE[e^{B_i(t;s)\epsilon_i}]\nonumber\\ & \quad +\lambda^{J}C_i(t;s)\epsilon_iE[e^{\sum_{j=1}^{2}B_j(t;s)\epsilon_j}]=0. \end{align}
With (2.9)–(2.11), we can obtain two ODEs
 \begin{equation} \left\{\begin{aligned} & \dfrac{\partial D_i(t;s)}{\partial t}+(a_ib_i+\lambda_i^{J}\epsilon_i+\lambda^{J}\epsilon_i)C_i(t;s) +\lambda_i^{J}\epsilon_i^{2}B_i(t;s)C_i(t;s)\\ & \quad +\lambda^{J}\epsilon_iC_i(t;s)\sum_{j=1}^{2}B_j(t;s)\epsilon_j=0, D_i(s;s)=0;\\ & \dfrac{\partial C_i(t;s)}{\partial t}-a_iC_i(t;s)+\sigma_i^{2}B_i(t;s)C_i(t;s)=0,\quad C_i(s;s)=1.\\ \end{aligned}\right. \end{equation}
Substitute (2.3) into the above ODEs and obtain (2.14) and (2.15).
3. CDS pricing
In this section, we will discuss the CDS pricing with defaultable counterparty under the jump model in (2.1). We assume company  $F_A$ holds the bond issued by company
 $F_B$. At initial time
 $t$, company
 $F_A$ buys a CDS contact with the credit protection seller
 $F_C$. The maturity of the CDS contract is
 $T$. During time
 $t$ to
 $T$, the CDS buyer
 $F_A$ will pay the CDS fee continuously to the CDS seller
 $F_C$ until
 $T$ if no defaults happen. Once the reference asset
 $F_B$ defaults first, the CDS seller
 $F_C$ will compensate to the CDS buyer
 $F_A$. However, if the CDS seller
 $F_C$ defaults first, the CDS buyer
 $F_A$ will stop paying premiums and not receive any compensations from
 $F_C$. The default events considered in this section include two types of defaults, namely the default of company
 $F_B$ and the default of company
 $F_C$. That is, we need to consider the default order of company
 $F_B$ and company
 $F_C$.
Now, we analysis all the possible default events once the CDS contract becomes effective from time  $t$:
Situation 1: The bond issued by company  $F_B$ is the first to default at time
 $\tau _1 (t\le \tau _1 \le T)$,
Situation 2: Counterparty  $F_C$ defaults firstly at time
 $\tau _2 (t\le \tau _2 \le T)$,
Situation 3: No defaults happen until the maturity  $T$.
Next, we will show how to compute the CDS price that the credit protection buyer  $F_A$ pay to counterparty
 $F_C$. We assume that the CDS costs are continuously paid by
 $F_A$ if no defaults happen and denote the cost rate to be
 $W$. CDS contracts generally involve two directions of cash flow, that is, premium payment and default compensation. The CDS premium is paid by CDS buyer
 $F_A$ to counterparty
 $F_C$. When company
 $F_B$ defaults before company
 $F_C$,
 $F_C$ shall compensate CDS buyer
 $F_A$ for the losses. Therefore, the value of CDS contract for CDS seller
 $F_C$ is the expected value of premium received by the company
 $F_C$ minus the expected value of compensation paid by company
 $F_C$.
Firstly, we need to analyze the present value at time  $t$ of the CDS costs received by counterparty
 $F_C$ under different situations. Under Situation 1, if company
 $F_B$ is the first to default at time
 $\tau _1$, the present value of the CDS costs received by counterparty
 $F_C$ is
 $\int _t^{T} We^{-r(s-t)}q_1(t,\lambda _1,\lambda _2;s)\,ds$. The default probability density of the default event is
 $q_1(t,\lambda _1,\lambda _2;s)$ according to Theorem 2.2. Similarly, the present value of the total CDS costs received by counterparty
 $F_C$ is
 $\int _t^{T} We^{-r(s-t)}q_2(t,\lambda _1,\lambda _2;s)\,ds$ under Situation 2. Under Situation 3, the present value of the CDS costs received by counterparty
 $F_C$ is
 $\int _t^{T} We^{-r(s-t)}P(t,\lambda _1,\lambda _2;s)\,ds$.
 $P(t,\lambda _1,\lambda _2;s)$ is the joint survival probability density according to Theorem 2.1.
Then, we will analyze the present values of compensations paid by counterparty  $F_C$ under different situations. Denote
 $R$ to be the recovery rate and
 $L$ to be the face value of the reference asset. Under Situation 1, counterparty
 $F_C$ will compensate
 $L(1-R)\int _t^{T} e^{-r(s-t)}q_1(t,\lambda _1,\lambda _2;s)\,ds$ to the CDS buyer
 $F_A$. If counterparty
 $F_C$ is the first to default, there will be no compensations paid by counterparty
 $F_C$. There will be no compensations paid by counterparty
 $F_C$ if no defaults happen from time
 $t$ to
 $T$.
According to the no-arbitrage pricing principal, the value of CDS contract at the initial time  $t$ should be zero. The present value of the total CDS costs received by counterparty
 $F_C$ should be equal to the present value of the total compensations paid by counterparty
 $F_C$. Thus, we have
 \begin{align} & \int_t^{T} We^{{-}r(s-t)}q_1(t,\lambda_1,\lambda_2;s)\,ds+\int_t^{T} We^{{-}r(s-t)}q_2(t,\lambda_1,\lambda_2;s)\,ds\nonumber\\ & \quad+\int_t^{T} We^{{-}r(s-t)}P(t,\lambda_1,\lambda_2;s)\,ds =L(1-R)\int_t^{T} e^{{-}r(s-t)}q_1(t,\lambda_1,\lambda_2;s)\,ds, \end{align}
so the CDS price  $W$ the buyer
 $F_A$ paid to counterparty
 $F_C$ is
 \begin{equation} W=\frac{L(1-R)\int_t^{T} e^{{-}r(s-t)}q_1(t,\lambda_1,\lambda_2;s)\,ds}{\sum_{i=1}^{n}\int_t^{T} e^{{-}r(s-t)}q_i(t,\lambda_1,\lambda_2;s)\,ds+\int_t^{T} e^{{-}r(s-t)}P(t,\lambda_1,\lambda_2;s)\,ds}. \end{equation}
4. Numerical analysis
In this section, we will do some numerical analysis to show the impacts of main parameters such as the initial jump intensity, recovery rate, jump size and jump intensity of common jump on CDS price. We compute the CDS price using formula (3.2). Some of the parameters values we used in the following numerical analysis refer to Wang and Liang [Reference Wang and Liang25] and Leung and Kwok [Reference Leung and Kwok20]. The basic parameters values used in the following analysis are  $L=1$,
 $R=0.4$,
 $r=0.05$,
 $T=1$,
 $\lambda _1(t)=\lambda _2(t)=0.02$,
 $a_1=a_2=0.5$,
 $b_1=b_2=0.02$,
 $\sigma _1=\sigma _2=0.06$,
 $\lambda _1^{J}=\lambda _2^{J}=0.01$,
 $\epsilon _1=\epsilon _2=0.01$. In order to verify the correctness of our Formula (3.2), we do Monte Carlo simulation. In order to do Monte Carlo simulation, we use the following formulas in a discrete time form to simulate the paths of the default intensities.
 \begin{align} \lambda_1(t+\Delta t)& =\lambda_1(t)+a_1(b_1-\lambda_1(t))\Delta t+\sigma_1\sqrt{\lambda_1(t)} \xi_1\sqrt{\Delta t}+\sum_{i=1}^{J_1(t)}\epsilon_1^{i}+\sum_{i=1}^{J(t)}\epsilon_1^{i}, \end{align}
 \begin{align} \lambda_2(t+\Delta t)& =\lambda_2(t)+a_2(b_2-\lambda_2(t))\Delta t +\sigma_2\sqrt{\lambda_2(t)} \xi_2\sqrt{\Delta t}+\sum_{i=1}^{J_2(t)}\epsilon_2^{i}+\sum_{i=1}^{J(t)}\epsilon_2^{i}, \end{align}
where  $\xi _1$ and
 $\xi _2$ are independent and follow standard normal distributions.
 $J_1(t)$,
 $J_2(t)$ and
 $J(t)$ are independent Poisson processes with constant intensities
 $\lambda _1^{J}$,
 $\lambda _2^{J}$ and
 $\lambda ^{J}$. The jump sizes
 $\epsilon _1^{i}$,
 $\epsilon _2^{i}$ are constants for simplicity. By simulating the default intensities, we can calculate the joint survival probability density and the probability density of the first default numerically, so as to obtain the price of CDS. In the procedure of the Monte Carlo simulations, we set the number of time step to be 100, and the number of simulations to be 100,000. In Table 1, we show the relative percentage differences are all less than
 $1\%$. Therefore, formula (3.2) is effective to compute CDS prices.
Compare the CDS prices derived from formula (3.2) and that from Monte Carlo method. Parameters values are  $L=1$,
 $R=0.4$,
 $r=0.05$,
 $T=1$,
 $\lambda _1(t)=\lambda _2(t)=0.02$,
 $a_1=a_2=0.5$,
 $b_1=b_2=0.02$,
 $\sigma _1=\sigma _2=0.06$,
 $\lambda _1^{J}=\lambda _2^{J}=0.01$,
 $\epsilon _1^{i}=\epsilon _2^{i}=0.01$.

Figure 1 shows the impact of initial default intensity of reference asset on CDS price when  $\lambda _2(t)=0.02$. The larger
 $\lambda _1(t)$ it is, the greater the default probability of reference asset will be. In this situation, the CDS seller
 $F_C$ may face more compensation, so the CDS buyer will pay higher fees. In Figure 2, we analyze the impact of the initial default intensity of the CDS seller on the CDS price when
 $\lambda _1(t)=0.02$. If
 $\lambda _2(t)$ increases, the CDS buyer should pay less for the CDS contract. This is because when the initial default intensity of the counterparty becomes greater, the CDS buyer may not receive any compensation and will be willing to pay less for the CDS contract.
The CDS prices under different  $\lambda _1(t)$.

The CDS prices under different  $\lambda _2(t)$.

Figures 3 and 4 show the impact of long-term level of default intensity on CDS price.  $b_1$ represents the long-term level of default intensity of the reference asset and
 $b_2$ represents the long-term level of default intensity of the counterparty
 $F_C$. It can be seen from Figures 3 and 4 that the CDS price increases with the increase of
 $b_1$ and decreases with the increase of
 $b_2$. The method of analyzing this phenomenon is similar to the previous analysis of initial default intensity
 $\lambda _1(t)$ and
 $\lambda _2(t)$ in Figures 1 and 2.
The CDS prices under different  $b_1$.

The CDS prices under different  $b_2$.

Figure 5 investigates the impact of recovery rate on CDS price. Recovery rate  $R$ reflects the extent of loss. The greater the recovery rate is, the smaller the loss of CDS buyer
 $F_A$ will be. Therefore, the CDS price decreases when the recovery rate increases. Figure 6 discusses the impact of risk-free interest rate
 $r$ on CDS price. When the risk-free interest rate increases, the discount price of CDS will be smaller. Moreover, the increase of risk-free interest rate will increase the financing cost of company
 $F_B$, so the default risk of company
 $F_B$ may increase. Thus, the increase of risk-free interest rate will reduce the CDS price.
The CDS prices under different rates of recovery.

The CDS prices under different interest rates.

Figures 7 and 8 show the impact of jump amplitude  $\epsilon _1$ and
 $\epsilon _2$ on CDS price. In Figure 7, we let
 $\epsilon _2=0.01$ be fixed. The increase of
 $\epsilon _1$ will increase the default intensity of reference asset, which will increase the CDS premium. If
 $\epsilon _2$ increases when
 $\epsilon _1=0.01$ is fixed in Figure 8, the higher default probability of credit protection seller will make the CDS buyer unable to get compensation, thus the CDS contract may become worthless.
The CDS prices under different recovery rates.

The CDS prices under different correlations.

Figures 9 and 10 show the impact of jump intensity  $\lambda _1^{J}$ and
 $\lambda _2^{J}$ on CDS price without common jump (
 $\lambda ^{J}=0$). In Figure 9, we set
 $\epsilon _ 1=\epsilon _ 2 = 0.01$. In this situation, the default probability of reference asset and counterparty will increase because of the bad news. When
 $\lambda _2^{J}$ is fixed, the CDS price will be higher with larger
 $\lambda _1^{J}$. The reason is that the CDS buyer will need to pay more for the CDS contract if the default risk of reference asset is larger. Conversely, when
 $\lambda _1^{J}$ is fixed, the CDS premium will be lower with larger
 $\lambda _2^{J}$. Intuitively, the CDS buyer will get less compensation when the counterparty's default risk increases. We can analyze Figure 10 in a similar way. The result indicated in Figure 10 with
 $\epsilon _1=\epsilon _2=-0.01$ is contrary to that in Figure 9.
The CDS prices under  $\epsilon _1=\epsilon _2=0.01$.

The CDS prices under  $\epsilon _1=\epsilon _2=-0.01$.

Figures 11 and 12 discuss the impact of the common jump intensity  $\lambda ^{J}$ and the jump intensity
 $\lambda _1^{J}$ of reference asset on the CDS price. We can find that the two variables have similar effects on the CDS price. In Figure 11, the CDS price increases with the increase of
 $\lambda ^{J}$ when
 $\lambda _1^{J}$ is fixed. When there is a common jump caused by bad news (
 $\epsilon _1>0, \epsilon _2>0$) in the market, although the default probability of reference asset and counterparty will increase at the same time, the impact of the default event of reference asset is greater than that of counterparty
 $F_C$, and finally, the CDS premium increases. When there is a common jump caused by good news (
 $\epsilon _1<0, \epsilon _2<0$) as shown in Figure 12, the CDS premium will decrease with the increase of
 $\lambda ^{J}$ using the analysis method in Figure 11.
The CDS prices under  $\epsilon _1=\epsilon _2=0.01$.

The CDS prices under  $\epsilon _1=\epsilon _2=-0.01$.

Figures 13 and 14 investigate the impact of the common jump intensity  $\lambda ^{J}$ and the jump intensity
 $\lambda _2^{J}$ of counterparty on the CDS price. As seen from Figures 13 and 14,
 $\lambda ^{J}$ and
 $\lambda _2^{J}$ have the opposite effects on the CDS price. After the bad news (
 $\epsilon _1>0, \epsilon _2>0$) triggers a common jump as in Figure 13, the impact of the default of the reference asset will be greater than the default of CDS credit protection seller. Therefore, when the common jump intensity
 $\lambda ^{J}$ increases, the CDS premium will still increase. Moreover, the CDS premium changes faster with
 $\lambda ^{J}$ than with
 $\lambda _2^{J}$. When there is a common jump caused by good news (
 $\epsilon _1<0,\epsilon _2<0$) as shown in Figure 14, the analysis method is similar with that in Figure 13.
The CDS prices under  $\epsilon _1=\epsilon _2=0.01$.

The CDS prices under  $\epsilon _1=\epsilon _2=-0.01$.

Figures 15 and 16 show the curves of CDS premium with different maturity under different jump intensity  $\lambda _1^{J}, \lambda _2^{J}, \lambda ^{J}$. It can be found that the CDS premium increases with the increase of maturity if bad news (
 $\epsilon _1>0, \epsilon _2>0$) happen. When bad news exists, the CDS buyer and seller are more likely to default with a long term, so the CDS premium is more expensive for a long-term contract. Among three jump intensities
 $\lambda _1^{J}$,
 $\lambda _2^{J}$,
 $\lambda ^{J}$, the influence curve with
 $\lambda _1^{J}$ and
 $\lambda ^{J}$ are close to each other when only one jump intensity becomes larger and the curve with
 $\lambda ^{J}$ is between the other two curves. This indicates that the default of the reference asset has a greater impact on the CDS price than that of the default risk of counterparty. We should pay more attention to controlling the default risk of reference assets in practice.
The CDS prices under  $\epsilon _1=\epsilon _2=0.01$.

The CDS prices under  $\epsilon _1=\epsilon _2=-0.01$.

Figures 17 and 18 help us understand the CDS prices under different reduced-form intensity-based models. There are two classical models in the existing literature, namely the CIR model (i.e. there is no jump) and the jump-diffusion model (i.e. there is only one jump). We select these two classical models to compare the CDS price with that derived from our model. Figure 17 shows that if there is bad news ( $\epsilon _1>0, \epsilon _2>0$) in the market, the CDS price obtained under the CIR model is the lowest, while the CDS price increases significantly under our proposed model with the firm-specific risks and systemic risk. This is because that if there is bad news in the market, the default risk will be underestimated when using the CIR model, resulting in the low calculated CDS price. And with the increase of the contract term, the CDS price will be underestimated more. On the contrary, if there is good news (
 $\epsilon _1<0,\epsilon _2<0$) in the market, the CDS price under the CIR model is the highest. While the CDS price decreases significantly with our model. This is because when there is good news in the market, the default risk will be overestimated when using the CIR model, resulting in the high calculated CDS price. And with the increase of the contract term, the CDS price will be overvalued more. In summary, considering common jump in CDS pricing can help us better understand the impacts of different kinds of jump risks on CDS premium.
The CDS prices under  $\epsilon _1=\epsilon _2=0.01$.

The CDS prices under  $\epsilon _1=\epsilon _2=-0.01$.

5. Conclusion
In this paper, we mainly study the pricing of the CDS with counterparty risk based on the CIR processes with common jump risk. Using the PDE method, we obtain the approximate closed-form formula of the CDS price under our model. In the numerical analysis, we analyze the impacts of main parameters such as the initial jump intensity, recovery rate, jump size and jump intensity of common jump on the CDS prices. We do sensitivity analysis and find that our model has the ability to explain some empirically phenomenons. The numerical results show that the default of the reference asset has a greater impact on the CDS price than that of the default risk of counterparty when the common jump exists. Moreover, our model can help us to better understand the impact of common jump risk on the CDS price. Considering empirical analysis and extending the model to a jump model with stochastic volatility is our future research direction.
Acknowledgments
This work was supported by Philosophy and Social Science Research in Colleges and Universities of Jiangsu Province (2021SJA0362), the National Natural Science Foundation of China (71871120), Open project of Jiangsu key laboratory of financial engineering (NSK2021-13, NSK2021-15), Applied Economics of Nanjing Audit University of the Priority Academic Program Development of Jiangsu Higher Education (Office of Jiangsu Provincial People's Government, No.[2018]87), and the Major Natural Science Foundation of Jiangsu Higher Education Institutions (20KJA120002).
Competing interests
The authors declare no conflict of interest.



