




No CrossRef data available.
Article contents
A PROOF OF THE POWER OF KIM'S TEST AGAINST STATIONARY PROCESSES WITH STRUCTURAL BREAKS
Published online by Cambridge University Press: 23 September 2005
Abstract
In this note we show that, when the true data generating process is a stationary one around a constant term with a break, the stationarity test of Kim (2000, Journal of Econometrics 95, 97–116) against the alternative hypothesis of change of persistence rejects the null of stationarity asymptotically with probability one.I am grateful to an anonymous referee for his useful comments, which have helped to improve the content and presentation of this note. I acknowledge financial support from Ministerio de Ciencia y Tecnología, project SEC2003-09205.
Information
- Type
- Notes and Problems
- Information
- Copyright
- © 2005 Cambridge University Press
1. MOTIVATION AND RESULTS
With a correction in Kim et al. (2002).
Despite the fact that the null hypothesis is stationarity, these tests are known as change of persistence tests to distinguish them from stationarity tests such as Kwiatkowski, Phillips, Schmidt, and Shin (1992), which have nonstationarity as the alternative hypothesis.
In this note we show that, similarly to other stationarity tests (e.g., Kwiatkowski, Phillips, Schmidt, and Shin [KPSS]), Kim's test (2000) rejects the null of stationarity asymptotically with probability one, whenever the true data generating process is a stationary one around a constant term with a break. This provokes an indeterminacy in identifying the source of the rejection: is it due to a true change of persistence, or is it due to a break in the deterministic components?
The next section shows the properties of Kim's test (2000) when the true data generating process is I(0) around a constant term, suddenly shifted by a structural change.
2. PROOFS AND DISCUSSION
2.1. Kim's Tests
In the context of Kim's tests (2000), the null hypothesis can be described as

for t = 1,…,t, where rt = r0, or rt = r0 + γt, where r0 is a constant and t is a linear time trend. The variable zt is a stationary variable satisfying some regularity conditions. The alternative hypothesis implies that the variable zt becomes a more persistent process at some moment [τT]. For simplicity, we assume that the null model corresponds to rt = r0.
Now, let us define the residual series3
If the null model includes a linear trend, the residuals are obtained from the separate regression of yt against an intercept and a linear trend for each subsample.


where y0 and y1 are the sample means of each subsample. To test the null hypothesis, Kim (2000) designs the statistic

where

, for t = [τT] + 1,…,T.
However, because the true τ value is unknown a priori, Kim (2000) proposes three alternative ways for testing structural change. Following the notation of Busetti and Taylor (2004):


which are called maximum-Chow type, mean score, and mean-exponential test, respectively. In the actual computations, the integrals are replaced by sample averages, where

is a compact subset of [0,1],

.
Kim (2000) derives the asymptotic distribution of these statistics under the null hypothesis, and he shows that the tests are consistent against the alternative hypothesis of change in persistence.
2.2. Stationarity and Structural Breaks
The properties of the proposed tests under neglected structural changes are unknown, although we would expect the effects to be similar to the effects on the KPSS test (see Lee, Huang, and Shin, 1997).
Let us assume that the true data generating process is defined by the following equation:

where Dt = 1 for t ≥ λT + 1 and zero otherwise, εt is a stationary process of constant persistence, and λ is the fraction of the sample where the structural change occurs (0 < λ < 1).
The main results can be summarized in the following theorem.
THEOREM. If the time series is generated by process (7), then Hj(ΞT(·)) = Op(T), j = 1,2,3. Therefore, Kim tests (2000) would reject the null asymptotically with probability one.
Proof. To prove the theorem, we analyze Kim's tests under two different assumptions. First, let us assume that τ = λ, i.e., the fraction of the sample where the process presumably changes persistence equals the fraction of the sample where the structural break occurs. The residuals for each subsample can be written as

Then,

where (see Kim, Belaire-Franch, and Badillo Amador, 2002)

and where W denotes a standard Wiener process. This result directly follows from Theorem 3.1 in Kim (2000).
Next, let us assume that τ < λ < 1. Then, if we neglect the occurrence of a structural break, the residual series for each subsample is

for j = 1,…,[τT] and j = [τT] + 1,…,T, respectively. Let us compute the partial sum residuals processes for the numerator in (3).
(i) If τ < b < λ, then

where ε1 and D1 are the sample means of εt and Dt, respectively, computed for the second subsample. The first two terms are of order Op(T1/2), whereas the third term is of order Op(T). Thus,

.
(ii) If λ < b < 1, then

Again, the whole expression is asymptotically dominated by the deterministic terms involved. Hence,

, as before.
In both cases,

where W denotes a standard Wiener process. Then, the denominator of the Kim (2000) statistic is Op(1). It follows that (ΞT(τ))−1 = Op(T−1) and, hence, (Hj(ΞT(·)))−1 = Op(T−1), j = 1,2,3.4
As pointed out by an anonymous referee, we can emphasize the divergence of the ratio statistic by arguing that (ΞT(τ))−1 = Op(T−1). In this manner we can get rid of counterexamples satisfying ΞT(·) = Op(T).
Therefore, in both cases, if the tests were actually computed in the set

, e.g.,

, the Kim (2000) Hj(ΞT(·)), j = 1,2,3, tests would reject the null asymptotically with probability one, unless the fraction of the sample where the structural change is located is equal to or smaller than the lower end of the prespecified range (i.e., unless λ ≤ τ1).
Finally, let us assume that λ < τ < 1. The corresponding residual series are

for j = 1,…,[τT] and j = [τT] + 1,…,T, respectively. The computation of the partial sum residuals processes is established as previously. But under the present assumption,
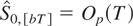
for 0 < b < λ and λ < b < τ, whereas, in both cases,

Therefore, ΞT(τ) → 0 as T → ∞. Then, if λ < τ1, the one-tailed tests Hj(ΞT(·)), j = 1,2,3 would have zero power, asymptotically.
References
REFERENCES
Busetti, F. &
A.M.R. Taylor
(2004)
Tests of stationarity against a change in persistence.
Journal of Econometrics
123,
1–193.Google Scholar
Kim, J.-Y.
(2000)
Detection of a change in persistence of a linear time series.
Journal of Econometrics
95,
97–116.Google Scholar
Kim, J.-Y.,
J. Belaire-Franch, &
R. Badillo Amador
(2002)
Corrigendum to “Detection of a change in persistence of a
linear time series.”
Journal of Econometrics
109,
389–392.Google Scholar
Kwiatkowski, D.,
P.C.B. Phillips,
P. Schmidt, &
Y. Shin
(1992)
Testing the null hypothesis of stationarity against the alternative
of a unit root: How sure are we that economic time series have a unit
root?
Journal of Econometrics
54,
159–178.Google Scholar
Lee, J.,
C. Huang, &
Y. Shin
(1997)
On stationarity tests in the presence of structural breaks.
Economics Letters
55,
165–172.Google Scholar
 You have
Access
- 3
- Cited by