




No CrossRef data available.
A RESIDUAL-BASED TEST FOR STOCHASTIC COINTEGRATION
Published online by Cambridge University Press: 15 March 2006
Abstract
We consider the problem of hypothesis testing in a modified version of the stochastic integration and cointegration framework of Harris, McCabe, and Leybourne (2002, Journal of Econometrics 111, 363–384). This nonlinear setup allows for volatility in excess of that catered for by the standard integration/cointegration paradigm through the introduction of nonstationary heteroskedasticity. We propose a test for stochastic cointegration against the alternative of no cointegration and a secondary test for stationary cointegration against the heteroskedastic alternative. Asymptotic distributions of these tests under their respective null hypotheses are derived, and consistency under their respective alternatives is established. Monte Carlo evidence suggests that the tests will perform well in practice. An empirical application to the term structure of interest rates is also given.We are most grateful to the Associate Editor and two anonymous referees for providing helpful comments on earlier versions of this paper.
Information
- Type
- Research Article
- Information
- Copyright
- © 2006 Cambridge University Press
1. INTRODUCTION
The cointegration framework of Engle and Granger (1987) is characterized by two widely held stylized empirical facts. The first is that, of the set of economic time series that exhibit trending behavior, many are adequately modeled by processes that are integrated, usually of order one, I(1). The second is that, despite this trending behavior, such series often tend to comove over time according to a stationary, or I(0), process; that is, they are cointegrated. Many empirical tests of important economic hypotheses are carried out within the Engle and Granger framework, for example, the relationship between long-run and short-run interest rates—the term structure. The Engle and Granger approach has, perhaps surprisingly, however, uncovered only very limited empirical evidence in support of the term structure (see Campbell and Shiller, 1987). An explanation often put forward for this is that bond market series tend to be too volatile to be compatible with the I(1)/I(0) framework. That is, the individual series often appear visually to be more volatile, or less smooth, than would be consistent with I(1) and when comovements between series are analyzed (most simply by examining the spreads) these also tend to display periods of volatility in excess of that typically associated with stationary behavior. In the words of Campbell and Shiller, the spreads tend to “move too much.”
One possible approach to dealing with the presence of extra volatility is within the stochastic integration and cointegration framework of Harris, McCabe, and Leybourne (2002). Here, the restrictive stationarity requirement of first differences of individual series and cointegrating error terms of the Engle and Granger (1987) setup is replaced with a looser condition that these are stochastically trendless; that is, they are simply free of I(1) stochastic trends. This notion, of course, encompasses the Engle and Granger setup as a special case. We outline this framework in Section 2.
In Section 3 we turn to the issue of hypothesis testing in a regression model representation. The central hypothesis of interest is whether series are stochastically cointegrated (either stationary or heteroskedastic), or not cointegrated. We suggest a residual-based statistic to test the null of stochastic cointegration. Within stochastic cointegration, we also consider the hypothesis that the cointegration is stationary against the alternative that it is nonstationary heteroskedastic, and we suggest a second statistic to test this. Moreover, when applied to first differences of an individual series, this same statistic can also be used to test the null of I(1) against heteroskedastic integration. The asymptotic null distributions of these two test statistics are derived under weak regularity conditions. Both are shown to have normal limit distributions that, unlike most cointegration tests, do not depend on the number of regressors involved. Their consistency properties under associated alternative hypotheses are also established.
Some Monte Carlo studies that examine the finite-sample size and power characteristics of the new tests, along with those of their conventional counterparts, are provided in Section 4. These highlight clearly the benefits to be gained by adopting the new test procedures, together with the shortcomings of using conventional ones, in the stochastic cointegration framework. Finally, in Section 5 we apply our tests to bond market data from several major economies. Our new testing framework uncovers supporting evidence in favor of the term structure in the bond market, in the same situation where conventional tests yield inconsistent results. Notably, for all the interest rate series we consider here, we conclude they are better modeled by heteroskedastically integrated, rather than I(1), processes.
2. STOCHASTIC INTEGRATION AND COINTEGRATION
We first consider a variant of the model introduced in Harris et al. (2002):


for t = 1,…,T. Here zt, μ, δ, and, εt are m × 1 vectors; wt and ηt are n × 1 vectors; ht and υt are p × 1 vectors; Π and Vt are m × n and m × p matrices, respectively. Only the process zt is observed. The disturbances εt, ηt, υt, and Vt are mean zero stationary processes, which may be correlated with one another; wt and ht are vectors of integrated processes. So, apart from deterministics, zt consists of an integrated component, Πwt, together with a shock term, εt + Vtht. This latter term has a linear component, εt, and a nonlinear component Vtht that is nonstationary heteroskedastic through its dependence on the I(1) process ht. Note that it is entirely possible throughout our analysis that wt and ht contain identical processes, though we do not enforce this restriction.1
In Harris et al. (2002), ht = wt. Here if any element of wt is identical to that of ht we would simply delete the corresponding element of υt from Assumption LP.
As regards the statistical properties of the disturbance terms in (1), we make the following linear process assumption. This allows for general forms of serial correlation, cross-correlation, and endogeneity.
Assumption LP. Let ζt = [υt′,vec(Vt)′, ηt′, εt′]′ be generated by the vector linear process

, where
- with C0 having full rank.2

Here and throughout
.
- ξt is an independent and identically distributed (i.i.d.) sequence.
- E(ξtξt′) = I.
- For all i, E(ξit16) is bounded.
To examine the properties of the model more clearly, we make the temporary simplifying assumption that μ = δ = 0. Next, let ei be an m × 1 vector with 1 in its ith position and 0 elsewhere, so that ei′zt = zit, the ith element of the vector zt. Then, from (1), we have
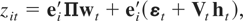
and if ei′Π ≠ 0 then zit is said to stochastically integrated. If, in addition, ei′E(VtVt′)ei > 0, zit is said to be heteroskedastically integrated (HI) due to the term ei′Vtht, whereas if ei′Vt = 0 then zit is simply I(1). So, a stochastically integrated variable encompasses both ordinary and heteroskedastic integration.
To model linear relationships between the variables in zt, let c be a nonzero m × 1 vector and consider
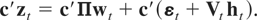
If c′Π = 0 then the variables of zt are said to be stochastically cointegrated. Under stochastic cointegration c′zt = c′(εt + Vtht) behaves like a stochastically integrated process net of its stochastic trend component, and we refer to such a process as being stochastically trendless.3
More formally, a vector stochastic process, ut, is said to be stochastically trendless if, as s → ∞ (t fixed),

where

is the sigma field of information of all the elements in the vector up to time t. This implies that the mean square error optimal s step ahead forecasts of a stochastically trendless process converge to the unconditional mean of the process as the forecast horizon s increases. Following the Beveridge and Nelson (1981) definition, such a process has no stochastic trend (or permanent component), hence the terminology “stochastically trendless.” An analogous definition has also been used in the literature on economic convergence; see Bernard and Durlauf (1996). Trendlessness is similar to the concept of a mixingale and the associated notion of asymptotic unpredictability, with the minor difference, in practical terms, that the convergence of the conditional expectation in our definition is in probability rather than in an Lp norm.

In other words, the behavior of the process up to time t has a negligible effect on its behavior into the infinite future.4
A proof of this result is available upon request.
When c′E(VtVt′)c = 0, then c′zt = c′εt is stationary. If, in addition, Vt = 0, the variables are all integrated and cointegrated in the standard Engle and Granger (1987) sense. Because of the stationary behavior of c′zt in either case, we simply refer to this as stationary cointegration. When c′E(VtVt′)c > 0, the variables zt are said to be heteroskedastically cointegrated. Thus, stochastic cointegration encompasses both stationary cointegration (possibly of the Engle and Granger kind) and heteroskedastic cointegration.
To further position our concept of heteroskedastic cointegration, note that I(1), HI, and the closely related stochastic unit root processes all share the properties of having trends in their variances although not being stochastic trendless.5
There is a growing body of evidence that many economic and financial time series previously considered I(1) are more appropriately modeled as HI or stochastic unit root processes. See the results in Section 5 of this paper and, inter alia, Hansen (1992a), Leybourne, McCabe, and Tremayne (1996), Granger and Swanson (1997), Wu and Chen (1997), and Psaradakis, Sola, and Spagnolo (2001).
3. HYPOTHESIS TESTS AND TEST STATISTICS
Our primary goal is to determine if the system is stochastically cointegrated. This null, and the alternative of noncointegration, may be stated as H0 : c′Π = 0 and H1 : c′Π ≠ 0. Within stochastic cointegration, we may wish to know whether stationary or heteroskedastic cointegration pertains. The null of stationary cointegration against the heteroskedastic alternative may be tested by partitioning H0 as H00 : c′E(VtVt′)c = 0 and H10 : c′E(VtVt′)c > 0.
It proves convenient to interpret these hypotheses within a regression model. Partition zt into a scalar yt and an (m − 1) × 1 vector xt as zt = [yt,xt′]′. Then partitioning (1) conformably, and rearranging, we obtain
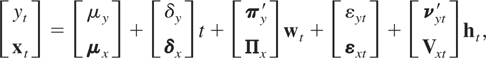
where yt, μy, δy, and εyt are scalars, xt, μx, δx, and εxt are (m − 1) × 1 vectors, and πy′ and νyt′ are 1 × n and 1 × p vectors, respectively, whereas Πx and Vxt are (m − 1) × n and (m − 1) × p matrices. Letting c = [1,−β′]′, α = μy − β′μx, κ = δy − β′δx, et = εyt − β′εxt = c′εt, q′ = πy′ − β′Πx = c′Π, and νt′ = νyt′ − β′Vxt = c′Vt, then we have

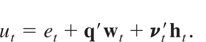
Thus, the regression error term ut is composed of the stationary term et, the integrated term q′wt, and the heteroskedastic component νt′ht. Note that ut need not have zero mean, so that α is not an intercept in the usual sense. In the regression framework we assume that there is only one cointegrating vector, so that rank(Πx) = m − 1, which imposes the restriction that n ≥ m − 1. This implies that further subrelationships among the xt variables in (3) are excluded.6
A special case of this model is studied by Hansen (1992a). When q = 0 and Vxt = 0, (3) corresponds to a regression model when the regressors variables are all I(1) and the error term is heteroskedastic, so that the regressand and regressors are treated asymmetrically.
For later use, we also define the lag covariances for an arbitrary process {at} by
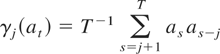
and define a heteroskedasticity and autocorrelation consistent (HAC) estimator of the long-run variance (LRV) by
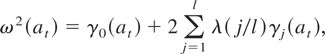
where λ(.) is a window with lag truncation parameter l. We also assume that Assumption KN, which follows, holds.
Assumption KN (Kernel and lag length).
- λ(0) = 1.
- 0 ≤ λ(x) ≤ 1 for 0 ≤ x < 1.
- λ(x) is continuous and of bounded variation on [0,1].
- l → ∞ as T → ∞.
3.1. Testing H0 against H1
To test stochastic cointegration against noncointegration we need to test whether q = 0 in

Here, the null hypothesis is composite, encompassing both stationary and heteroskedastic cointegration; whereas the alternative is I(1) or heteroskedastic integration. Because of the level of generality being entertained it is, however, not clear as to how to construct an optimal test statistic with a tractable limit distribution (even if we restrict ourselves to making Gaussian i.i.d. assumptions about the distributions of the unobserved variables). These complications lead us to examine instead a simple statistic for which we can at least determine a limiting null distribution free of nuisance parameters and also establish consistency. To this end, we consider
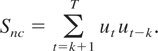
In the situation where all the disturbance terms are i.i.d., Snc with k = 1 would test for zero autocorrelation in ut against the correlation induced by the I(1) term q′wt. When the disturbance terms are not i.i.d., Snc needs to be modified to eliminate nuisance parameter dependence resulting from autocorrelation and also from the presence of νt′ht. This is accomplished by allowing k to increase with T.7
The form of the statistic Snc was earlier considered by Harris et al. (2003) in the context of stationarity testing in a deterministic regression.
Cointegrating versions of KPSS stationarity tests, such as that of Shin (1994), suffer from the fact that it is not possible to remove the effects of nuisance parameters in the partial sum process of ut under the null of heteroskedastic cointegration, leading to incorrect size. The simulation studies of Section 4 confirm this.
Because yt and xt are observed, we estimate b = [α,κ, β′]′ of (3) by means of the estimator

given by
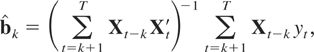
where Xt = [1,t,xt′]′. This estimator, described in Harris et al. (2002), is called an asymptotic instrumental variables estimator (AIV). Under H0, a minor modification of the proof of Harris et al. (2002) shows that

is consistent as k and T → ∞, in contrast to the ordinary least squares (OLS) estimator, which is not consistent under heteroskedastic cointegration unless xt consists entirely of I(1) processes. We now construct (6) using the AIV residuals:
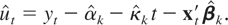
We then have the following result.
THEOREM 1. Assume that the model (3), Assumption LP, and Assumption KN hold. If k = O(T1/2), l = o(k), and l < k, then
(i) under H0;

(ii) under H1, the distribution of

diverges as T → ∞.
Here

is defined in (8) using (7); ω2(.) is defined in (5).
The first part of this theorem states that a properly standardized statistic,

, is asymptotically normal under stationary cointegration (which includes Engle and Granger cointegration) and also under heteroskedastic cointegration; the second part shows that the test is consistent under H1. The same results arise if linear trends are excluded from (3) and the fitted model.
3.2. Testing H00 against H10
In decomposing the composite hypothesis H0 into the null of stationary cointegration against the heteroskedastic alternative, we need to test whether E(νt′νt) = 0 in (4), maintaining q = 0. Under the temporary assumption that et, νt, ηt, and υt, are all jointly Gaussian i.i.d. and uncorrelated with each other, it follows from a straightforward application of McCabe and Leybourne (2000) that a locally most powerful test of H00 against H10 is given by
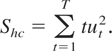
We then have the following result.
THEOREM 2. Under the conditions of Theorem 1,
(i) under H00,

(ii) under H10, the distribution of

diverges as T → ∞.
Here

is defined in (5).
Notice that

is calculated using

, rather than simply

, as (9) might suggest. This alteration is needed to center the statistic and render it invariant to the variance of ut under H00.
The structure of Shc can also be used to test the null of I(1) against the alternative of HI for any given individual series by simply constructing

by redefining

as

where

is an estimator of the trend coefficient δy given by

. We denote this statistic

. It is a straightforward special case of our results to show that

if yt is I(1) and

diverges if yt is HI. The same results arise if linear trends are excluded from (3), in which case

.
9Analogous statistics can of course be constructed for each element of the vector xt.
4. SIMULATION RESULTS
In this section we investigate, via Monte Carlo simulation, the finite-sample behavior of our new tests, comparing these with tests applied assuming the conventional paradigm. To test for the null of conventional cointegration we apply the Shin (1994) adaptation of the Kwiatkowski et al. (1992) (KPSS) stationarity test. This test uses an efficient OLS estimator in which [T1/4] ([.] denoting the integer part) lead and lag terms in Δxt are added into the regression equation of yt on xt; see Saikkonen (1991) for details. We denote this test Kc. The tests

, and Kc all require the use of a kernel and a lag truncation parameter in their respective variance estimators. For all tests we use the Bartlett kernel for λ(.). As regards choice of l, we allow two schemes. The first simply fixes l = [12(T/100)1/4], which is a fairly mainstream choice in the literature, whereas the second is the automatic data-dependent selection method of Newey and West (1994).
10In the context of stationarity testing, this has been demonstrated by Hobijn, Franses, and Ooms (1998) to remove many of the well-documented oversizing problems associated with KPSS tests.
The simulation model we examine is (2) with m = n = p = 2. Specifically, our data-generating process is
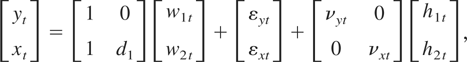
and the stochastic processes of (10) are generated according to

with (ε1t,ε2t,ε3t,ε4t,ε5t,ε6t,ε7t,ε8t)′ a multivariate standard normal white noise process. Here the di, i = 1,2,3 are constants. Within this setup, if d1 = d2 = d3 = 0, then H00 is true and stationary cointegration between two I(1) series pertains, whereas if d1 ≠ 0, H1 is true and yt and xt are not cointegrated in any sense (irrespective of the status of d2 and d3). If d1 = 0 with d2 ≠ 0 and/or d3 ≠ 0, there is heteroskedastic cointegration. This may exist either between two HI series (d2 ≠ 0 and d3 ≠ 0) or between an I(1) and HI series (e.g., d2 = 0 and d3 ≠ 0). The model is generated over t = −99,…,0,1,…,T, with the first 100 startup values discarded. We consider sample sizes of T = 200,400,600, and the number of replications for all experiments is 10,000. Table entries represent empirical rejection frequencies of the various tests, based on regressions allowing constants but not trends, at the nominal asymptotic 0.05 level (these being two-tailed tests in the case of
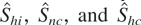
). For brevity, we only report results for the

tests applied to yt. In terms of notation in the tables, if φi,j is not explicitly given, its value is set to zero. Variants of the tests based on the automatic lag selection are superscripted with an a.
In Table 1 we have d1 = d2 = d3 = 0 throughout, so that H00 is true—stationary cointegration between two I(1) series. The

test has near nominal size, indicating that I(1) rather than HI series are present, and any additional serial correlation in the form of nonzero values of φε,y clearly has little effect on its size. As regards the test

, its size is well controlled apart from when φε,y = 0.9 and φε,y = φε,x = 0.9. Here, when k = [0.75T1/2] it is moderately oversized and thus too frequently indicates absence of cointegration. However, setting k = [T1/2] or k = [1.25T1/2] virtually removes the oversizing problems, especially if the automated variants are considered. When we examine the test

, we find that the choice of k has far less effect on the size. For φε,y = 0.9 and φε,y = φε,x = 0.9, all three choices (whether based on automated variants or not) produce oversized tests and thus indicate spurious heteroskedastic cointegration, although the degree of oversizing is not particularly serious and is mostly ameliorated as the sample size increases. On the basis of these results then, specifically those pertaining to

, we would conclude that setting k = [0.75T1/2] is realistically too low to maintain reliable finite-sample size. Notice that the nonautomated KPSS cointegration test, Kc, is quite badly oversized when φε,y = 0.9 and φε,y = φε,x = 0.9, and automating the lag choice struggles to correct this to a satisfactory degree. Interestingly, the automated Kc test can be badly oversized in the presence of negative autocorrelation, unless the sample size is large. None of the other tests, however, appear to be adversely affected by negative autocorrelation.
Size of the tests under stationary cointegration: d1 = d2 = d3 = 0

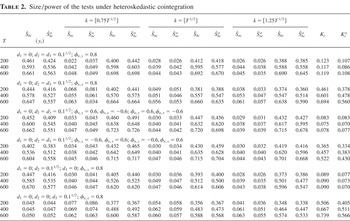
Table 2 examines the size and power of the tests under six different models of heteroskedastic cointegration, H10. In the first four, both yt and xt are HI (d2 ≠ 0 and d3 ≠ 0); in the fifth yt is HI (d2 ≠ 0) and xt is I(1) (d3 = 0), with these roles being reversed in the sixth model. The size issue relates to

, and it is clear that the test does not appear particularly sensitive to k, with size being controlled reasonably well for all choices, across all model specifications. If anything, setting k = [0.75T1/2] sometimes leads to slight oversizing; setting k = [1.25T1/2] occasionally yields slight undersizing. When considering the power of

, both fixed and automated variants exhibit consistency. The power does not appear to change particularly dramatically across model specifications either. Power does tend to decrease monotonically as k increases, although the rate of decrease is fairly low. The test

is also seen to be consistent (aside obviously from when yt is I(1)). The behavior of the Kc test is much less predictable, however. This is because, as mentioned in Section 3, the distribution of Kc in the HI case depends on nuisance parameters. This test can have very low or reasonably high power to reject its null of stationary cointegration, depending on the nature of the heteroskedastic cointegration. For example, if xt is I(1) as in the fifth case, its power is trivial. If, on the other hand, if xt is HI and νxt is persistent, as in the second or sixth case, it can reject stationary cointegration very frequently. This differing behavior is due to the inconsistency of the OLS estimator of β (= 1) whenever xt is HI.
11Busetti and Taylor (2003) demonstrate that the KPSS tests applied to an individual series with heteroskedastic errors can overreject the null of stationarity. In the current context, the cointegrating KPSS statistic actually diverges because of the inconsistency of the ordinary least squares estimator when xt is HI.
Size/power of the tests under heteroskedastic cointegration

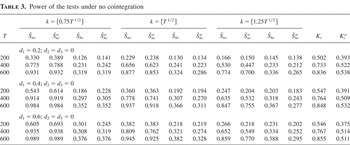
In Table 3, we examine the power of the tests under the case of no cointegration, H1, here between two I(1) series (

is not included now). Consistency of

is clearly evident, as is the role of k in determining its power. The power is seen to fall fairly rapidly with increasing k for both fixed and automated variants.
12These observations also apply to

, though it has rather less power than

because it is not constructed to detect this alternative.

often exceeds that of Kc. There is no contradiction here, however: the optimality properties associated with the raw form of the KPSS statistic, on which Kc is based, do not necessarily carry over to the current empirical version of the statistic, which needs to be robustified both to serial correlation and to endogeneity. It is also apparent that the power of Kc drops quite sharply when moving from the fixed to automated lag selection.
Power of the tests under no cointegration

In unreported simulations, we also examined the properties of the tests when some endogeneity is introduced. The first case revisited H00, stationary cointegration between two I(1) series, where we set cor(ε1,ε5) = −0.7 and cor(ε2,ε5) = 0.7, such that the increment processes of εyt and εxt are correlated with that of the random walk w1t. The sizes of

were largely unaffected by introducing such correlation. A second case revisited H10, heteroskedastic cointegration between two HI series. Here we made w1t and h1t identical random walks, so that the I(1) process driving part of the heteroskedasticity also drove the level of the processes. In addition, we set cor(ε4,ε8) = 0.7, such that the increment process of νxt was correlated with that of the random walk h2t it multiplies into. Again, the size of

remained reasonably accurate, and consistency of

(and

) appeared unaffected. Full details of these simulations are available upon request.
All the preceding simulation results concerning
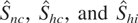
are pretty much in line with what we would expect given our theoretical results of Section 3 regarding asymptotic normality of the tests, their robustness to serial correlation and endogeneity, and their consistency. They all detect the appropriate departures from their respective null hypotheses. The choice of k remains an issue, however. Predominantly led by the behavior of

, the facts are that setting k too low can, in certain situations, induce size distortions (cf. Table 1), whereas setting k too high leads to a loss of power (cf. Table 3). Moreover, it seems rather unlikely that such a trade-off can be entirely avoided however k is chosen. A reasonable compromise would appear to be the middle value of the three we have considered, and so we recommend setting k = [T1/2] as a matter of practice. Whether l is selected using a fixed or an automated method does not appear particularly crucial to our test's performance, and we would not favor one approach over the other.
Our results also highlight the problems of using OLS-based procedures such as Kc to test for cointegration. Inconsistency of the OLS estimator whenever the heteroskedastic cointegration involves xt that is HI causes the test to reject, so that Kc is unable to discern between this situation (i.e., when series “differ” by a heteroskedastic but stochastically trendless term) and noncointegration (i.e., when series “differ” by a stochastic trend term). Of course, we may take the view that because neither situation represents a stationary cointegrating relation, a rejection of the null of stationary cointegration is an appropriate outcome. However, if the heteroskedastic cointegration involves xt that is I(1), the same test tends to no longer reject this null, which clearly cannot also represent an appropriate outcome. This of course means that the inference drawn can become crucially dependent on the ordering of the I(1) and HI variables, even asymptotically. Such considerations do not apply to our new tests as their asymptotic distributions are free of nuisance parameters. It is also important to remember that when applying

, we never actually need to distinguish between which series are I(1) and HI. That is, we do not need to calculate the test

for individual series. Perhaps the only rationale for calculating

is that it may provide early warning of situations where it would be unwise to apply conventional cointegration tests.
5. AN EMPIRICAL EXAMPLE: THE TERM STRUCTURE OF INTEREST RATES
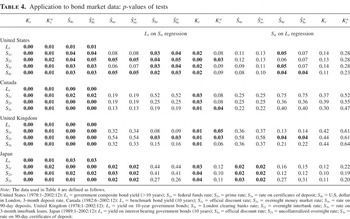
A necessary empirical condition for the expectations theory of the term structure of interest rates is that long-run and short-run interest rates cointegrate. We test this empirically using monthly data from the United States, Canada, the United Kingdom, and Japan, taken from the OECD/MEI database. A single long-run interest rate, Lt, and a variety of short-run rates, Sit, are used for each country, and we consider bivariate regressions of Lt on Sit and also the reordered regression of Sit on Lt.13
See the note to Table 4 for a full description of the data.
The results are given in Table 4, where the entries are p-values of the tests based on the asymptotic distribution. Bold print indicates a p-value of 0.05 or less, and in the current context we will consider this to represent a rejection of the associated null hypothesis. As regards the individual series, we first note that the KPSS test, Ks, indicates rejection of I(0) for every one of the 17 individual interest rate series considered. In addition, the

test shows that all of these interest rate series appears to be HI rather than I(1), so that excess volatility would certainly appear to be an issue for this data set.
14It is easily shown that the KPSS stationarity test is consistent when the alternative is HI.
Application to bond market data: p-values of tests

Turning now to the bivariate regression results, first Lt on Sit, we see that according to

, stochastic cointegration is not rejected for eight of the 13 pairs. In both Canada and the United Kingdom, the nonrejection is unambiguous. In the case of the United States the evidence is mixed; rejections are found for two of the four pairs considered. No evidence of stochastic cointegration at all is found for Japan, though the peculiar nature of Japanese short-run interest rates in recent times (being effectively zero) may partly explain this finding. According to the

test of the eight pairwise regressions that do not reject stochastic cointegration, five represent stationary cointegration between HI series (three for Canada, two for the United Kingdom) and three represent heteroskedastic cointegration between HI series (two for the United States, one for the United Kingdom). This pattern of results is the same whether the lag selection is fixed or automated. When we consider the regressions of Sit on Lt, qualitatively, the results for Canada, the United Kingdom, and Japan are unchanged. The United States now shows no rejections of stochastic cointegration, with one of the four being stationary cointegration, one being heteroskedastic cointegration, and two being indeterminate. This makes the total of nonrejections now 10 out of the 13 pairs. Thus, there is certainly a reasonable consensus of support for the term structure of interest rates in these data, particularly if the somewhat anomalous case of Japan is excluded from consideration.
A less coherent picture emerges if we examine the outcomes from the OLS-based KPSS cointegration test, Kc. For regressions of Lt on Sit, conventional cointegration is rejected for every one of the 13 pairs of long- and short-run rates if a fixed lag selection is used (this drops to four rejections if lag selection is automated, though as shown earlier the power of this test can be a good deal lower than that of the fixed lag test). However, no rejections at all are obtained for the reordered regressions of Sit on Lt. Hence, the differing degrees of excess volatility of long- and short-run interest rate data appear to exert a substantial influence on the outcomes for conventional OLS-based cointegration tests, to the extent that inference can be crucially dependent on variable ordering. By way of a contrast, the new procedures we have proposed in this paper are designed to provide inference that is rather more robust when analyzing this sort of data.
APPENDIX: Proofs
Notation and Conventions.
In what follows we assume that Assumptions LP and KN, the model (3), and k = O(T1/2) hold. For the model specified by equations (1)–(3), with ζt = [υt′,vec(Vt)′, ηt′, εt′]′, let

and define covariance matrices

. Also define St to be the partial sum of the ζt, that is, ΔSt = ζt. Selector matrices Rυ, Rν, Rη, and Rε are defined implicitly such that υt = Rυ′ζt, νt = Rν′ζt, ηt = Rη′ζt, and εt = Rε′ζt. When taking expectations through an infinite summation sign, we generally do not remark on the operation when obviously square summable linear processes are involved.
For transparency, we analyze the regression model without a time trend included, though all our results can be shown to extend to the trend case. We also make repeated use of the following representations:

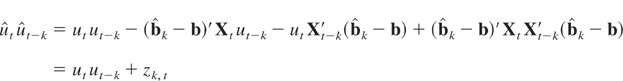
with

and where zk,t is defined implicitly.
When dealing with LRV terms it is convenient to utilize the following results. First, in manipulating expressions involving kernels we adopt the notation λ+(j/l) = 2λ(j/l), j > 0, λ+(0) = 1. Next, for any sequences {at} and {bt} define
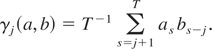
We use the convention that γj(a) = γj(a,a). Then for the sequence {at + bt} we have

Also define for any sequences {at} and {bt}

again with the convention that ω2(a) = ω(a,a). So, we have for the sequence {at + bt},
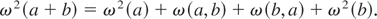
Thus, for δ > 0 we can write
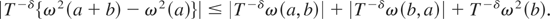
Note too that
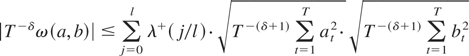
with the obvious modification for a = b.
In our applications at is often a product sequence, at = ct ct−k, say. The summation in s starts at k + j + 1 and in t starts at t = k + 1. Then, (A.4) yields

Proof of Theorems.
We also use the following lemmas in establishing the results of Theorems 1 and 2.
LEMMA 1. Under
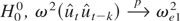
where

Proof. In this case

. Setting δ = 0, at = et et−k, and bt = zk,t we have that

is bounded by (A.3). The first term in (A.3) is bounded by (A.5). That is

where the order of the first right-hand side term is O(l) (Assumption KN.2) and the second term is Op(1), independent of k, by Markov's inequality and Assumption LP. As for the third term, recalling the expression for zk,t in (A.2), note that

is Op(1) where

as follows from Harris et al. (2002). Thus, in (A.2), the quadratic form in

is of a lower order than the two linear terms in

. The linear terms are of the same order. So the two dominant terms in

are

. But

and it is clear that the second dominant term is of the same order. So,

. Hence
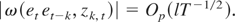
The same method of proof shows that |ω(zk,t,et et−k)| and ω2(zk,t) are also Op(lT−1/2).
Thus,

Applying Theorem LRV of Harris, McCabe, and Leybourne (2003) (with n = 1, α = 2, and μ = 0) then shows that
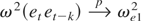
. █
LEMMA 2. Under
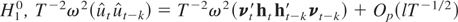
.
Proof. Now

. Setting δ = 2, at = utut−k, and bt = zk,t we have that

is bounded by (A.3). The first term in (A.3) is bounded by (A.5). That is,
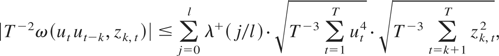
where the first right-hand side term is O(l) and the second Op(1). The dominant term of

is

where the first two Op(1) results can be shown to hold via a simple modification of the approach of Harris et al. (2002). Thus

and so |T−2ω(utut−k,zk,t)| is bounded by an Op(lT−1/2) variable. That |T−2ω(zk,t,utut−k)| and T−2ω2(zk,t) are also bounded by an Op(lT−1/2) variable follows similarly. Combining these results gives

Because et is of a lower order of magnitude than νt′ht it follows by similar arguments that

LEMMA 3. Under

where

with B1 a Brownian motion process.
Proof. Write


The key to the proof lies in replacing vec(ζtζt−k′)vec(ζt−jζt−k−j′)′ in (A.6) by E {vec(ζtζt−j′)}E {vec(ζtζt−j′)}′ in (A.7). This means that the convergence in square brackets is nonstochastic and thus the continuous mapping theorem (CMT) is sufficient to deduce the asymptotic distribution. Also the quantity in square brackets converges to Ω22 because it can be shown to be a consistent estimate of the long-run variance of vec(ζtζt−k′), which is the definition of Ω22, that is,

. Then ΩPP = (Rν [otimes ] Rν)′Ω22(Rν [otimes ] Rν) by definition.
The validity of replacing vec(ζtζt−k′)vec(ζt−jζt−k−j′)′ by the double expectation involves establishing the following sequence of results (expressed in the scalar case for simplicity). That is,

The complete proofs of these steps are available from the authors on request. Notice that the last equality shows the virtue of using the expectation device as the CMT and then delivers the result in a very straightforward way. █
LEMMA 4. Under
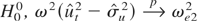
where

and σe2 = E(et2).
The proof is similar to that of Lemma 1 and is thus omitted.
LEMMA 5. Let ζt satisfy Assumption LP and let k = O(T1/2). Then, as T → ∞,

where W = Rυ′B1 and P = (Rν [otimes ] Rν)′B2 where B1 and B2 are independent Brownian motion processes.
Proof. First rewrite using ΔSt = ζt, so that

The proof proceeds by applying the Beveridge–Nelson decomposition to the first term and showing that the second term is asymptotically negligible. We use the notation
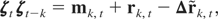
where

and the coefficients are defined by

Apply Theorem BN of Harris et al. (2003) to vec(ζtζt−k′) to get a martingale approximation, mk,t, a remainder term rk,t, and an overdifferenced factor

. The idea is that the martingale term is dominant and that the dependence on k is absorbed into its variance. In this way the proof of convergence to a stochastic integral can be treated by conventional methods of analysis. Thus,

We find

The first result follows directly from Theorem SI of Harris et al. (2003), and the second is established along very similar lines. The last follows by writing

where at = νt−kνt′υt. The first term can be shown to disappear on exploiting the properties of the increment process, that is, that Et−k{at − Et−k(at)} = 0; the second term disappears by applying Theorem 3.3 of Hansen (1992b).
Thus,

Now, because k = o(T), it follows from Theorem FCLT of Harris et al. (2003) that

jointly with

where MT,[Ts] = T−1/2 [sum ][Ts]mk,t. Thus Theorem SI of Harris et al. (2003) applies, and setting BQ ≡ (Rν [otimes ] Rν)′B2 = P and U ≡ Rυ′B1 [otimes ] Rυ′B1 = W [otimes ] W we have that
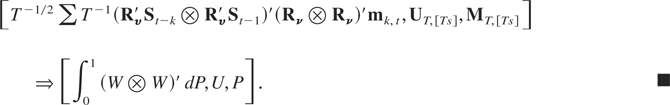
Proof of Theorem 1.
Part (i) (Null distribution). Sections (a) and (b) derive the asymptotic null distribution of

under H00 and H10, respectively.
(a) Under H00, ut = et and from Harris et al. (2002),

, Op(T−1)] and

are all Op(1). Consequently, using (A.2) we find

Because et = c′εt is a linear combination of a vector linear process, it follows from an application of Theorem FCLT of Harris et al. (2003) that

where by Lemma 1,

. Thus,

(b) Under H10, ut = et + νt′ht, and from a minor modification to the results of Harris et al. (2002),

are Op(1). Hence, using (A.2) we find

Now, substituting ut = et + νt′ht, we can write

where W = Rυ′B1 and P = (Rν [otimes ] Rν)′B2 and B1 and B2 are independent Brownian motions with covariance matrices Ω11 and Ω22. The weak convergence follows from Lemma 5. The covariance matrix of P is ΩPP = (Rν [otimes ] Rν)′Ω22(Rν [otimes ] Rν).
Combining the results of Lemmas 2 and 3 shows that

We now require the distribution of the ratio of

. As shown in Lemma 5,

Next the CMT, with the preceding vector as argument and the ratio as the map, applies to conclude that
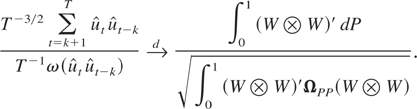
As
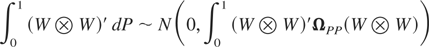
conditional on W, the distribution in (A.8) is unconditionally N(0,1).
Part (ii) (Consistency). Under H1, ut = et + q′wt + νt′ht where q ≠ 0. Here, it is easy to show that

, and, using (A.2), this implies that

is of the same order in probability as utut−k. It is then straightforward to deduce that

Now we require a bound for the order of probability of

, which again is the same as the order of probability of ω2(utut−k). Setting a = b = utut−k and δ = 2 in (A.5) yields

Thus we conclude that

at most. Hence the distribution of

diverges at least as fast as

. █
Proof of Theorem 2.
Part (i) (Null distribution). Under H00, ut = et we have

. Then, it follows from (A.1) that
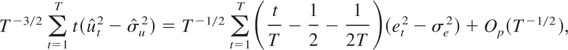
where σe2 = E(et2). Write

Here FT(s) is the partial sum process of {et2 − σe2} that weakly converges to F(s) by Theorem 3.8 of Phillips and Solo (1992). Then, noting by integration by parts that

, we can use the CMT to deduce

where F(s) is a Brownian motion with variance ωe22, as defined in Lemma 4. Hence,
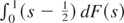
is normally distributed with mean zero and variance

which shows

From Lemma 4,

, and so the result follows.
Part (ii) (Consistency). Under H10, ut = et + νt′ht we have

. We may write

From (A.1),

is of the same order in probability as ut, and it is then straightforward to show that

and hence

In the denominator,

(where

) are of the same order in probability. Setting a = b = ut2 − σu2 and δ = 2 in (A.4) yields

It is easily shown that both

are Op(1). Hence ω2(ut2 − σu2) and consequently

are Op(lT2) at most. So, the distribution of

diverges at least as fast as

. █
References
REFERENCES
Bernard, A.B. &
S.N. Durlauf
(1996)
Interpreting tests of the convergence hypothesis.
Journal of Econometrics
71,
161–173.CrossRefGoogle Scholar
Beveridge, S. &
C. R. Nelson
(1981)
A new approach to decomposition of economic time series into
permanent and transitory components with particular attention to
measurement of the business cycle.
Journal of Monetary Economics
7,
151–174.CrossRefGoogle Scholar
Busetti, F. &
A.M.R. Taylor
(2003)
Variance shifts, structural breaks and stationarity tests.
Journal of Business & Economic Statistics
21,
510–531.CrossRefGoogle Scholar
Campbell, J.Y. &
R.J. Shiller
(1987)
Cointegration and tests of present value models.
Journal of Political Economy
95,
1062–1088.CrossRefGoogle Scholar
Engle, R.F. &
C.W.J. Granger
(1987)
Cointegration and error correction: Representation, estimation and
testing.
Econometrica
55,
251–276.CrossRefGoogle Scholar
Granger, C.W.J. &
N.R. Swanson
(1997)
An introduction to stochastic unit root processes.
Journal of Econometrics
80,
35–62.CrossRefGoogle Scholar
Hansen, B.E.
(1992a)
Heteroscedastic cointegration.
Journal of Econometrics
54,
139–158.Google Scholar
Hansen, B.E.
(1992b)
Convergence to stochastic integrals for dependent heterogeneous
processes.
Econometric Theory
8,
489–500.Google Scholar
Harris, D.,
B.P.M. McCabe, &
S.J. Leybourne
(2002)
Stochastic cointegration: Estimation and inference.
Journal of Econometrics
111,
363–384.CrossRefGoogle Scholar
Harris, D.,
B.P.M. McCabe, &
S.J. Leybourne
(2003)
Some limit theory for infinite order autocovariances.
Econometric Theory
19,
829–864.Google Scholar
Hobijn, B.,
P.H. Franses, &
M. Ooms
(1998)
Generalizations of the KPSS-Test for Stationarity.
Econometric Institute Working paper,
Erasmus University,
Rotterdam.
Kwiatkowski, D.,
P.C.B. Phillips,
P. Schmidt, &
Y. Shin
(1992)
Testing the null of stationarity against the alternative of a unit
root: How sure are we that economic time series have a unit root?
Journal of Econometrics
54,
159–178.Google Scholar
Leybourne, S.J.,
B.P.M. McCabe, &
A.R. Tremayne
(1996)
Can economic time series be differenced to stationarity?
Journal of Business & Economic Statistics
14,
435–446.Google Scholar
McCabe, B.P.M. &
S.J. Leybourne
(2000)
A general method of testing for random parameter variation in
statistical models. In
R.D.H Heijmans,
D.S.G. Pollock, &
A. Satorra (eds.),
Innovations in Multivariate Statistical Analysis: A Festschrift for
Heinz Neudecker, pp.
75–85.
Kluwer.
Newey, W.K. &
K.D. West
(1994)
Automatic lag selection in covariance estimation.
Review of Economic Studies
61,
631–654.CrossRefGoogle Scholar
Phillips, P.C.B. &
V. Solo
(1992)
Asymptotics for linear processes.
Annals of Statistics
20,
971–1001.CrossRefGoogle Scholar
Psaradakis, Z.,
M. Sola, &
F. Spagnolo
(2001)
A simple procedure for detecting periodically collapsing rational
bubbles.
Economics Letters
72,
317–323.CrossRefGoogle Scholar
Saikkonen, P.
(1991)
Asymptotically efficient estimation of cointegration
regressions.
Econometric Theory
7,
1–21.Google Scholar
Shin, Y.
(1994)
A residual based test of the null of cointegration against the
alternative of no cointegration.
Econometric Theory
10,
91–115.CrossRefGoogle Scholar
Wu, J.-L. &
S.-L. Chen
(1997)
Can nominal exchange rates be differenced to stationarity?
Economics Letters
55,
397–402.Google Scholar

Size of the tests under stationary cointegration: d1 = d2 = d3 = 0
Size/power of the tests under heteroskedastic cointegration
Power of the tests under no cointegration
Application to bond market data: p-values of tests
 You have
Access
- 5
- Cited by