


1. Introduction
Let
 $X \geq 0$
be a loss random variable with probability density function (pdf) f(x), cumulative distribution function (cdf)
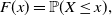 $F(x)=\mathbb{P}(X \le x),$
and tail function
 $\overline{F}(x) = 1-F(x) = \mathbb{P}(X>x)$
. Moreover, let
 $\mathbb{E}(X) = \int_0^{\infty} x \, f(x) \, dx = \int_0^{\infty} \overline{F}(x) \, dx$
be the mean value and
 $m_X$
a mode of the distribution of X satisfying the condition
 $f'(m_X) = 0$
. The weighted premium principle introduced by Furman and Zitikis (Reference Furman and Zitikis2008) is defined and denoted by:
 \begin{equation} H_w(X) =\frac{\mathbb{E}[X \, w(X)]}{\mathbb{E}[w(X)]},\end{equation}
where
 $w\;:\;[0, \infty) \rightarrow [0, \infty)$
is a nondecreasing function such that
 $0<\mathbb{E}[w(X)]<\infty$
. One option to obtain a weighted premium principle is to take the mean value of a weighted loss random variable
 $X_{w}$
with pdf:
 \begin{align*} f_{w}(x) = \frac{w(x)}{\mathbb{E}[w(X)]} \, f(x), \;\; x > 0.\end{align*}
Since w is nondecreasing by assumption, it holds that
 $H_w(X) = \mathbb{E}(X_w) \geq \mathbb{E}(X)$
. We recall that, for different choices of w, some well-known premiums follow directly. For example, we can get the net premium
 $\mathbb{E}(X)$
(when
 $w(x) =c$
,
 $c>0$
is a constant), the modified variance premium
 $\mathbb{E}(X) + \mathbb{V}ar(X)/\mathbb{E}(X)$
(when
 $w(x) = x$
), the Esscher premium
 $\mathbb{E}(X \, e^{\lambda X})/\mathbb{E}(e^{\lambda X})$
(when
 $w(x) = e^{\lambda x}$
,
 $\lambda>0$
), and the Kamps premium
 $\mathbb{E}[X \, (1-e^{-\lambda X})]/\mathbb{E}[1-e^{-\lambda X}]$
(when
 $w(x) = 1-e^{-\lambda x}$
,
 $\lambda>0$
); see Furman and Zitikis (Reference Furman and Zitikis2008). Furthermore, for
 $w(x) = g'(\overline{F}(x))$
, we obtain a large class of premium principles based on distorted expectation theory (when
 $g\;:\;[0,1]\rightarrow [0,1]$
is a continuous and differentiable function such as: (i) g is increasing and concave function, (ii)
 $g(0)=0$
and
 $g(1)=1$
). On the other hand, there are premium principles such as the exponential premium principle
 $\ln \mathbb{E}(e^{\lambda X})/\lambda$
, where
 $\lambda>0$
and ‘
 $\ln$
’ means natural logarithm, which are not obtained for some function w. For more details on premium principles, see Gerber (Reference Gerber1979), Bühlmann (Reference Bühlmann1980), Goovaerts et al. (Reference Goovaerts, de Vylder and Haezendonck1984), Newton et al. (Reference Newton, Bowers, Hickman, Jones and Nesbitt1986), Gerber and Shiu (Reference Gerber and Shiu1994), Denneberg (Reference Denneberg1994), Wang (Reference Wang1995, Reference Wang1996, Reference Wang2003), Kamps (Reference Kamps1998), Denuit et al. (Reference Denuit, Dhaene, Goovaerts and Kaas2006), Laeven and Goovaerts (Reference Laeven and Goovaerts2008), Castaño-Martínez et al. (Reference Castaño-Martínez, López-Blazquez, Pigueiras and Sordo2020), and references therein.
The ordering is important in studying premium principles. Next, we recall two well-known stochastic orders, which imply the mean ordering; see the classical books of Müller and Stoyan (Reference Müller and Stoyan2002), Shaked and Shanthikumar (Reference Shaked and Shanthikumar2007), and Belzunce et al. (Reference Belzunce, Martínez-Riquelme and Mulero2016). Let X and Y be two continuous random variables with pdf’s
 $f_X(x)$
and
 $f_Y(x)$
, and tail functions
 $\overline{F}_X(x)$
and
 $\overline{F}_Y(x)$
, respectively. A random variable X is said to be smaller than Y in the usual stochastic order, denoted by
 $X \le_{st} Y$
, if
 $\overline{F}_X(x) \le \overline{F}_Y(x)$
for all x. Moreover,
 $X \le_{st} Y$
, if
 $\mathbb{E}[\Phi(X)] \le \mathbb{E}[\Phi(Y)]$
for all nondecreasing functions
 $\Phi$
such that the expectations exist. Furthermore, we say that X is smaller than Y in the likelihood ratio order, denoted by
 $X \le_{lr} Y$
, if
 $f_Y(x)/f_X(x)$
is nondecreasing with respect to x. The connection between these stochastic orders is given by the following diagram:
 \begin{align*} X \le_{lr} Y \;\; \Rightarrow \;\; X \le_{st} Y \;\; \Rightarrow \;\; \mathbb{E}(X) \le \mathbb{E}(Y) .\end{align*}
Calculating weighted premium principles, Furman and Zitikis (Reference Furman and Zitikis2008), applied the ordering
 $X \le_{lr} X_w$
, where w is a nondecreasing function, and introduced the premium given in (1.1) by using the mean of
 $X_{w}$
, that is,
 $H_w(X)=\mathbb{E}(X_w) \geq \mathbb{E}(X)$
. An important advantage of this method is that given the distribution of risk X, one can determine the distribution of
 $X_w$
, namely, an actuary has more information from just the knowledge of premium principle
 $\mathbb{E}(X_w)$
. A natural question here is: Can we use a different statistical measure instead of mean value on the distribution of a weighted random variable to obtain a premium principle?
The contribution of this work is to highlight the role of mode of a weighted risk in calculating premium principles. Our method is not only a complementary theory but also a generalization calculating weighted premiums. A challenging problem here is the mode ordering for two unimodal distributions. For this aim, we study how we can use the usual stochastic order to construct a family of unimodal weighted distributions, into which we can order the modes in the strict sense (i.e., for two unimodal random variables X and Y with modes
 $m_X$
and
 $m_Y$
, we say that
 $X <_{mode} Y$
, if
 $m_X < m_Y$
).
This paper is organized as follows. In Section 2, we calculate the mean value premium principle by using the mode of a weighted risk, and we provide some distributional properties. In Section 3, we give a generalization of the mean value premium principle, which also generalizes the method of calculating weighted premium principles proposed by Furman and Zitikis (Reference Furman and Zitikis2008). Furthermore, we give a generalization of the exponential premium principle and we provide a two-side bound for it in terms of the Esscher premium. In Section 4, we study the comparison of modes between two unimodal distributions, by introducing the concept of mode ordering.
Throughout the paper, we give some examples to illustrate the theoretical results and discuss how the mechanism of our method works. Furthermore, whenever we use an expectation, we are tacitly assuming that it exists. Moreover, we use the terms nondecreasing and nonincreasing in a wide sense, that is, a function g is nondecreasing (resp., nonincreasing) if
 $g(x)\leq g(y)$
(
 $\geq$
) for all
 $x < y$
. We also use the terms increasing and decreasing in a strict sense, that is, a function g is increasing (resp., decreasing) if
 $g(x) < g(y)$
(
 $>$
) for all
 $x < y$
.
2. Calculating the mean value premium principle from the mode of a unimodal weighted distribution
Let X be a continuous nonnegative random variable with pdf f, distribution F, and tail
 $\overline{F}=1-F$
. Let also
 $w\;:\;[0,\infty) \rightarrow [0, \infty)$
is a continuous, increasing, and convex function such that
 $0<\mathbb{E}[w(X)]<\infty$
. We consider the weighted random variable
 $X_{\tilde{w}}$
with mode
 $m_{X_{\tilde{w}}} = \tilde{m}_{w}$
and pdf:
 \begin{equation} f_{\tilde{w}}(x) = \frac{\tilde{w}(x)}{\mathbb{E}[\tilde{w}(X)]} \, f(x) = \frac{\overline{F}_w(x) - \overline{F}(x) }{\mathbb{E}(X_w) - \mathbb{E}(X)}, \;\; x>0,\end{equation}
provided that
 $\mathbb{E}(X_w) > \mathbb{E}(X) > 0$
. Here, the weight
 $\tilde{w}(x)$
is
 \begin{align*} \tilde{w}(x) = \frac{\overline{F}_w(x) - \overline{F}(x) }{f(x)}.\end{align*}
Furthermore,
 $X_{\tilde{w}}$
is unimodal, with mode
 $\tilde{m}_w = w^{-1}(\mathbb{E}[w(X)])$
. Therefore, the premium principle
 \begin{equation} T_{\tilde{w}}(X)\;:\!=\; \tilde{m}_w = w^{-1}(\mathbb{E}[w(X)])\end{equation}
is the well-known mean value principle; see for more details Goovaerts et al. (Reference Goovaerts, de Vylder and Haezendonck1984). Since, by assumption, w(x) is convex, we have (by Jensen’s inequality) the property
 $\tilde{m}_w \geq \mathbb{E}(X)$
.
Remark 2.1.
-
(i) An interpretation of the density
 $f_{\tilde{w}}$
in applied probability is the following. Let X and Y be two nonnegative continuous random variables with
$X \le_{st} Y$
and
$\mathbb{E}(X) < \mathbb{E}(Y)$
. Let also
$\overline{F}_X(x)$
and
$\overline{F}_Y(x)$
be the tail functions of X and Y, respectively. Then, by Theorem 4.1 of Di Crescenzo (Reference Di Crescenzo1999), there exists a suitable nonnegative random variable U such that (2.3)provided that g is a measurable and differentiable function such that
\begin{equation} \mathbb{E}[g(Y)] - \mathbb{E}[g(X)] = \mathbb{E}[g'(U)] \, [\mathbb{E}(Y) - \mathbb{E}(X)],\end{equation}
$\mathbb{E}[g(X)]$
and
$\mathbb{E}[g(Y)]$
are finite, and that its derivative g
′ is measurable and Riemann-integrable. Here, the pdf of the random variable U is Recalling that the mean value theorem states that if g is a function continuous in [x, y] and differentiable in (x, y), then there exists a point
\begin{align*} f_{U}(x) = \frac{\overline{F}_Y(x) - \overline{F}_X(x)}{\mathbb{E}(Y) - \mathbb{E}(X)}.\end{align*}
$u \in (x, y)$
such that formula (2.3) is a probabilistic analogue of the mean value theorem. Hence, applying this probabilistic analogue of the mean value theorem between X and
\begin{align*} g(y) - g(x) = g'(u) \, (y - x),\end{align*}
$X_w$
(i.e.,
$X_w$
plays the role of Y), we obtain the new random variable
$X_{\tilde{w}}$
(i.e.,
$X_{\tilde{w}}$
plays the role of U) with pdf
$f_{\tilde{w}}$
. For more details, see Di Crescenzo (Reference Di Crescenzo1999), Psarrakos (Reference Psarrakos2022), and reference therein. It is worth mentioning that the relation
$\mathbb{E}(X) \le \mathbb{E}( X_{\tilde{w}}) \le \mathbb{E}(X_w)$
does not hold in general (see Proposition 4.1 in Di Crescenzo, Reference Di Crescenzo1999), which implies that the relation
$X \le_{st} X_{\tilde{w}} \le_{st} X_w$
does not hold in general.
-
(ii) The premium
$T_{\tilde{w}}(X)$
for
$w(x) = e^{\lambda x}$
gives the exponential premium
$\ln \mathbb{E}(e^{\lambda X})/\lambda$
(
$\lambda>0$
). Furthermore, for
$w(x) = x^{a}$
(
$a \geq 1$
),
$T_{\tilde{w}}(X)$
yields the premium
$(\mathbb{E}[X^a])^{1/a}$
; see Goovaerts et al. (Reference Goovaerts, de Vylder and Haezendonck1984, p. 123).


It is well known that if the mean is greater than the mode, then the distribution is positively skewed. We recall that Pearson (Reference Pearson1895) proposed
 $(\mu-m)/\sigma$
as a measure of skewness for a univariate distribution with mean
 $\mu$
, mode m, and variance
 $\sigma^2$
. Next, we compare the mode and the mean of
 $X_{\tilde{w}}$
, under the hypothesis that
 $X \le_{st} X_{\tilde{w}}$
.
Proposition 2.1. If
 $X \le_{st} X_{\tilde{w}}$
, then
 $\tilde{m}_w \le \mathbb{E}(X_{\tilde{w}})$
.
Proof. Let
 $X \le_{st}X_{\tilde{w}}$
. Recalling that w is an increasing and convex function, we have
 \begin{align*} \mathbb{E}[w(X)] \le \mathbb{E}[w(X_{\tilde{w}})] \le w[\mathbb{E}(X_{\tilde{w}})],\end{align*}
where the second inequality follows by Jensen’s inequality. Therefore,
 \begin{align*} w^{-1}(\mathbb{E}[w(X)]) \le \mathbb{E}(X_{\tilde{w}}),\end{align*}
or equivalently,
 \begin{align*} \tilde{m}_w \le \mathbb{E}(X_{\tilde{w}}),\end{align*}
which completes the proof.
In the following theorem, for
 $w(x)=x$
, we provide a characterization result for the case where
 $X_{\tilde{w}} =_{d} X_w$
, where
 $=_d$
means the equality in distribution. This condition gives that
 $\tilde{w}(x) = w(x)$
is increasing in x. Hence, (keeping in mind that likelihood order
 $\le_{lr}$
implies the usual stochastic order
 $\le_{st}$
) the assumption
 $X \le_{st} X_{\tilde{w}}$
in Proposition 2.1 is satisfied.
Theorem 2.1. Consider the weighted risks
 $X_w$
and
 $X_{\tilde{w}}$
, where
 $w(x)=x, x>0$
. Then,
 $X_{\tilde{w}} =_{d} X_w$
if and only if X follows a Gamma distribution.
Proof. (
 $\Rightarrow$
) Let
 $X_{\tilde{w}} =_{d} X_w$
. Then, we have
 \begin{align*} f_{\tilde{w}}(x) = f_w(x),\end{align*}
for all
 $x>0$
, and using formula (2.1) we get
 \begin{align*} \frac{\overline{F}_{w}(x) - \overline{F}(x)}{\frac{\mathbb{E}(X^2)}{\mathbb{E}(X)} - \mathbb{E}(X)} = \frac{x}{\mathbb{E}(X)} \, f(x).\end{align*}
By differentiating and after some computation, we conclude that
 \begin{align*} \frac{f'(x)}{f(x)} = \frac{\mathbb{E}(X)-x-\frac{\mathbb{V}ar(X)}{\mathbb{E}(X)}}{\frac{\mathbb{V}ar(X)}{\mathbb{E}(X)} \, x}.\end{align*}
An alternative representation of the latter expression is
 \begin{align*} \frac{f'(x)}{f(x)} = \frac{k-x-q'(x)}{q(x)},\end{align*}
where
 $k=\mathbb{E}(X)$
and
 $q(x)=\frac{\mathbb{V}ar(X)}{\mathbb{E}(X)} \, x$
. Therefore, by Ruiz and Navarro (Reference Ruiz and Navarro1994), X follows a Gamma distribution.
(
 $\Leftarrow$
) Suppose that X follows a Gamma(a, b) distribution with parameters
 $a>0$
,
 $b>0$
, and pdf
 \begin{equation} f(x) = \frac{b^a}{\Gamma(a)} \, x^{a-1} \, e^{-bx}, \;\; x>0,\end{equation}
where
 $\Gamma(a) = \int_0^{\infty} x^{a-1} \, e^{-x} \, dx$
is the Gamma function, and tail
 \begin{align*} \overline{F}(x) = \frac{\Gamma(a,bx)}{\Gamma(a)},\end{align*}
where
 $\Gamma(a,x) = \int_x^{\infty} y^{a-1} \, e^{-y} \, dy$
is the upper incomplete Gamma function. Then,
 $X_w$
follows a Gamma(
 $a+1,b$
) distribution. Recalling that
 \begin{align*} \Gamma(a+1,x) = a \, \Gamma(a,x) + x^a \, e^{-x},\end{align*}
formula (2.1) yields
 \begin{align*} f_{\tilde{w}}(x) = \frac{\frac{\Gamma(a+1,bx)}{\Gamma(a+1)} - \frac{\Gamma(a,bx)}{\Gamma(a)}}{\frac{a+1}{b}-\frac{a}{b}} =\frac{b^{a+1}}{\Gamma(a+1)} \, x^{a} \, e^{-bx} = f_{w}(x),\end{align*}
and the result follows.
Example 2.1. Let X follows a Gamma(a, b) distribution with parameters
 $a>0$
,
 $b>0$
, and pdf f(x) given in (2.4). The r-order moment of X is
 \begin{align*} \mathbb{E}(X^r) = \frac{\Gamma(a+r)}{b^r \, \Gamma(a)}.\end{align*}
Let also
 $w(x) = x^c$
, where
 $c\geq 1$
. Then,
 $X_w$
follows a Gamma(
 $a+c,b$
) with mean
 $\mathbb{E}(X_{w}) = \frac{a+c}{b}$
. Furthermore, we have
 \begin{align*} f_{\tilde{w}}(x) = \frac{\frac{\Gamma(a+c,bx)}{\Gamma(a+c)} - \frac{\Gamma(a,bx)}{\Gamma(a)}}{\frac{c}{b}}\end{align*}
and
 \begin{align*}\mathbb{E}(X_{\tilde{w}}) = \frac{\mathbb{E}(X_{w}^2)-\mathbb{E}(X^2)}{2(\mathbb{E}(X_{w})-\mathbb{E}(X))} = \frac{\frac{\Gamma(a+c+2)}{b^2 \, \Gamma(a+c)} - \frac{\Gamma(a+2)}{b^2 \, \Gamma(a)}}{2(\frac{a+c}{b} - \frac{a}{b})} = \frac{2a+c+1}{2b}.\end{align*}
It is clear that for
 $c=1$
, we have
 $\mathbb{E}(X_{w}) = \mathbb{E}(X_{\tilde{w}})$
(see also Theorem 2.1), and for
 $c>1$
, we have
 $\mathbb{E}(X_{w}) > \mathbb{E}(X_{\tilde{w}})$
. Furthermore, the mode of
 $X_{\tilde{w}}$
(see (2.2)) is
 \begin{align*} \tilde{m}_{w} = \bigg( \frac{\Gamma(a+c)}{\Gamma(a)} \bigg)^{1/c} \, \frac{1}{b}.\end{align*}
In Table 1, we give the values of
 $\mathbb{E}(X)$
,
 $\mathbb{E}(X_{w})$
,
 $\mathbb{E}(X_{\tilde{w}})$
, and
 $\tilde{m}_w$
for
 $a=3$
,
 $b=2$
, and
 $c=1,2,3,4$
. Furthermore, in Figures 1 and 2, we drew the pdf
 $f_{\tilde{w}}(x)$
, giving also the values of mode and mean of
 $X_{\tilde{w}}$
(see the vertical lines).
The values of
 $\mathbb{E}(X)$
,
 $\mathbb{E}(X_{w})$
,
 $\mathbb{E}(X_{\tilde{w}})$
, and
 $\tilde{m}_w$
of Gamma distribution in Example 2.1, for
 $a=3$
,
 $b=2$
, and
 $c=1,2,3,4$
.

The pdf
 $f_{\tilde{w}}(x)$
given in Example 2.1 for
 $a=3$
,
 $b=2$
and
 $0 \le x \le 7$
, when (i)
 $c=1$
(left part), and (ii)
 $c=2$
(right part).

The pdf
 $f_{\tilde{w}}(x)$
given in Example 2.1 for
 $a=3$
,
 $b=2$
and
 $0 \le x \le 7$
, when (i)
 $c=3$
(left part), and (ii)
 $c=4$
(right part).

Example 2.2. Suppose that X follows an Exponential(b) distribution with parameter
 $b>0$
, and pdf
 \begin{equation} f(x) = b \, e^{-bx}, \;\; x>0.\end{equation}
For
 $b>\lambda>0$
, let also
 $w(x) =e^{\lambda x}$
. Then,
 $X_w$
follows an Exponential(
 $b-\lambda$
) distribution, and the pdf of
 $X_{\tilde{w}}$
is
 \begin{eqnarray*} f_{\tilde{w}}(x) &=& \frac{e^{-(b-\lambda)x} - e^{-bx}}{\frac{1}{b-\lambda} - \frac{1}{b}} \\[5pt] &=& \frac{b}{\lambda} \, (b-\lambda) \, e^{-(b-\lambda)x} (1 - e^{-\lambda x}), \;\; x>0. \end{eqnarray*}
It is worth mentioning that
 $X_{\tilde{w}}$
belongs to a family of weighed exponential distribution introduced by Gupta and Kundu (Reference Gupta and Kundu2009). We recall, see Gupta and Kundu (Reference Gupta and Kundu2009), that a nonnegative random variable X is said to have a weighted exponential distribution, with the shape and scale parameters as
 $\alpha>0$
and
 $\beta > 0$
, respectively, if the PDF of X is
 \begin{align*} f_X(x;\; \alpha, \beta) = \frac{\alpha+1}{\alpha} \, \lambda \, e^{-\beta x} (1 - e^{-\alpha \beta x}), \;\; x>0.\end{align*}
Therefore,
 $X_{\tilde{w}}$
follows a weighed exponential distribution with parameters
 $\alpha = \lambda/(b-\lambda)$
and
 $\beta = b-\lambda$
. A probabilistic interpretation of the
 $f_{\tilde{w}}(x)$
is that
 $X_{\tilde{w}} =_{d} X + X_w$
; see Di Crescenzo (Reference Di Crescenzo1999); for further interpretations and properties, see Gupta and Kundu (Reference Gupta and Kundu2009). The mode and the mean value of
 $X_{\tilde{w}}$
are
 \begin{align*} \tilde{m}_w = \frac{1}{\lambda} \, \ln \mathbb{E}(e^{\lambda \, X}) = \frac{1}{\lambda} \, \ln \frac{b}{b-\lambda}\end{align*}
and
 \begin{align*} \mathbb{E}(X_{\tilde{w}}) = \mathbb{E}(X) +\mathbb{E}(X_w) = \frac{1}{b} + \frac{1}{b-\lambda}.\end{align*}
One can also verify that the ratios
 \begin{align*} \frac{f_{\tilde{w}}(x)}{f(x)} = \frac{b-\lambda}{\lambda} \, (e^{\lambda x} - 1)\end{align*}
and
 \begin{align*} \frac{f_{\tilde{w}}(x)}{f_w(x)} = \frac{b}{\lambda} \, (1-e^{-\lambda x})\end{align*}
are increasing functions. Hence,
 $X \le_{lr} X_w \le_{lr} X_{\tilde{w}}$
. In Figure 3, we drew the pdf
 $f_{\tilde{w}}(x)$
for
 $b=2$
and
 $\lambda=1$
, giving also the values
 $\tilde{m}_{w}=0.693147$
and
 $\mathbb{E}(X_{\tilde{w}})=1.5$
.
The pdf
 $f_{\tilde{w}}(x)$
given in Example 2.2 for
 $b=2$
,
 $\lambda=1$
and
 $0 \le x \le 5$
.

Example 2.3. Suppose that X follows a Pareto(a, b) type I distribution with parameters
 $a> 3$
and
 $b>0$
, pdf
 \begin{align*} f(x) = \frac{ab^a}{x^{a+1}}, \;\; x> b,\end{align*}
and
 $r-$
order moment
 $\mathbb{E}(X^r) = ab^r/(a-r)$
for
 $0<r<a$
. We also consider the weight function
 $w(x) =x^c$
, for
 $1 \le c < a-1$
. Then,
 $X_w$
follows a Pareto(
 $a-c,b$
) type I distribution, and the pdf of
 $X_{\tilde{w}}$
is
 \begin{eqnarray*} f_{\tilde{w}}(x) &=& \frac{\frac{b^{a-c}}{x^{a-c}} - \frac{b^{a}}{x^{a}}}{\frac{(a-c)b}{a-c-1} - \frac{ab}{a-1}} \\[5pt] &=& \frac{a-1}{c} \,\, \frac{(a-c-1) \, b^{a-c-1}}{x^{a-c}} \, \bigg (1 - \frac{b^{c}}{x^{c}} \bigg ), \;\; x> b. \end{eqnarray*}
Keeping in mind the definition of weighed exponential distributions in the Example 2.2, an alternative representation of
 $f_{\tilde{w}}(x)$
is
 \begin{align*} f_{\tilde{w}}(x) = \frac{\frac{c}{a-c-1}+1}{\frac{c}{a-c-1}} \,\, \frac{(a-c-1) \, b^{a-c-1}}{x^{a-c}} \, \bigg [1 - \bigg(\frac{b}{x} \bigg)^{\frac{c}{a-c-1} \, (a-c-1)} \bigg], \;\; x>b,\end{align*}
and hence, in a similar way as Gupta and Kundu (Reference Gupta and Kundu2009), we can say that
 $X_{\tilde{w}}$
follows a weighed Pareto type I distribution with parameters
 $c/(a-c-1)$
and
 $a-c-1$
. The mode and the mean of
 $X_{\tilde{w}}$
are
 \begin{align*} \tilde{m}_w = [\mathbb{E}(X^c)]^{1/c} = \bigg( \frac{a}{a-c} \bigg)^{1/c} \, b\end{align*}
and
 \begin{align*} \mathbb{E}(X_{\tilde{w}}) = \frac{(a-1) \, (a-c-1)}{(a-2) \, (a-c-2)} \, b,\end{align*}
respectively. Furthermore, the ratios
 \begin{align*} \frac{f_{\tilde{w}}(x)}{f(x)} = \frac{(a-c-1) \, (a-1)}{acb^{a+1}} \, (b^{a-c} \, x^{a+1} - b^a \, x)\end{align*}
and
 \begin{align*} \frac{f_{\tilde{w}}(x)}{f_w(x)} = \frac{(a-c-1) \, (a-1)}{(a-c) c b^{a-c+1}} \, (b^{a-c} \, x - b^a \, x^{-c+1})\end{align*}
are increasing functions. Hence,
 $X \le_{lr} X_w \le_{lr} X_{\tilde{w}}$
. In Figure 4, we drew the pdf
 $f_{\tilde{w}}(x)$
for
 $a=5$
,
 $b=2$
and
 $c=2$
, giving also the values
 $\tilde{m}_{w}=\sqrt{5/3}$
and mean of
 $ \mathbb{E}(X_{\tilde{w}})=8/3$
.
The pdf
 $f_{\tilde{w}}(x)$
given in Example 2.3 for
 $a=5$
,
 $b=1$
,
 $c=2$
and
 $0 \le x \le 7$
.

3. A generalization
By using a generalization of (2.2), we obtain a large class of weighted premiums, which includes the weighted premiums proposed by Furman and Zitikis (Reference Furman and Zitikis2008). In fact, let
 $w\;:\;[0, \infty) \rightarrow [0, \infty)$
and
 $v\;:\;[0, \infty) \rightarrow [0, \infty)$
two continuous functions such that
 $0<\mathbb{E}[w(X)]<\infty$
and
 $0<\mathbb{E}[v(X)] <\infty$
. Furthermore, assume that w is increasing, v is nondecreasing and
 $\xi(x) = w(x)/v(x)$
is increasing and convex function. Let also consider a nonnegative weighted random variable
 $X_{\widetilde{wv}}$
of X with pdf
 \begin{align*} f_{\widetilde{wv}}(x) = \frac{\widetilde{wv}(x)}{\mathbb{E}[\widetilde{wv}(X)]} \, f(x) = \frac{\overline{F}_w(x) - \overline{F}_v(x) }{\mathbb{E}(X_w) - \mathbb{E}(X_v)},\end{align*}
provided that
 $\mathbb{E}(X_w) > \mathbb{E}(X_v) > 0$
. Here, the weight
 $\widetilde{wv}(x)$
is
 \begin{align*} \widetilde{wv}(x) = \frac{\overline{F}_w(x) - \overline{F}_v(x) }{f(x)}.\end{align*}
The mode of
 $X_{\widetilde{wv}}$
follows by solving the equation
 \begin{align*} \frac{w(x)}{\mathbb{E}[w(X)]} = \frac{v(x)}{\mathbb{E}[v(X)]},\end{align*}
or equivalently,
 \begin{equation} \xi(x) = \frac{\mathbb{E}[w(X)]}{\mathbb{E}[v(X)]}.\end{equation}
Since the function
 $\xi(x) = w(x)/v(x)$
is increasing (by assumption), the solution of Equation (3.1) is unique. Denote by
 $m_{X_{\widetilde{wv}}} =\tilde{m}_{\xi}$
the unique mode of
 $X_{\widetilde{wv}}$
. Then the generalized mode premium is defined by:
 \begin{equation} T_{\tilde{\xi}}(X)\;:\!=\;\tilde{m}_{\xi} = \xi^{-1} \bigg(\frac{\mathbb{E}[w(X)]}{\mathbb{E}[v(X)]} \bigg).\end{equation}
Proposition 3.1. Under the assumptions given above for the functions w(x), v(x) and
 $\xi(x)=w(x)/v(x)$
, it holds that
 $\tilde{m}_{\xi} \geq \mathbb{E}(X)$
.
Proof. Since
 $\xi(x)$
is increasing and v(x) is nondecreasing, we have
 \begin{equation} \frac{\mathbb{E}[w(X)]}{\mathbb{E}[v(X)]} = \frac{\mathbb{E}[\xi(X) \, v(X)]}{\mathbb{E}[v(X)]} \geq \mathbb{E}[\xi(X)].\end{equation}
Furthermore, recalling that
 $\xi(x)$
is convex, applying Jensen’s inequality, it follows
 \begin{equation} \mathbb{E}[\xi(X)] \geq \xi(\mathbb{E}(X)).\end{equation}
 \begin{align*} \frac{\mathbb{E}[w(X)]}{\mathbb{E}[v(X)]} \geq \xi(\mathbb{E}(X)),\end{align*}
and keeping in mind that
 $\xi(x)$
is increasing, we obtain
 \begin{align*} \xi^{-1} \bigg (\frac{\mathbb{E}[w(X)]}{\mathbb{E}[v(X)]} \bigg) \geq \mathbb{E}(X),\end{align*}
which completes the proof.
Remark 3.1.
-
(i) For
$v(x)=a$
, where a is a positive constant, we have
$\tilde{m}_{\xi}=\tilde{m}_{w}$
. -
(ii) For
$w(x)=x \, v(x)$
, we have that
$\tilde{m}_{\xi}$
is the unique solution of the equation: Therefore,
\begin{align*} \frac{x \, v(x)}{\mathbb{E}[X \, v(X)]} = \frac{v(x)}{\mathbb{E}[v(X)]} .\end{align*}
for more details, see Furman and Zitikis (Reference Furman and Zitikis2008).
\begin{align*} \tilde{m}_{\xi} = \frac{\mathbb{E}[X \, v(X)]}{\mathbb{E}[v(X)]};\end{align*}
-
(iii) For
$w(x)=e^{\lambda \, x} \, v(x)$
, we have that
$\tilde{m}_{\xi}$
is the unique solution of the equation: Therefore, we obtain the premium:
\begin{align*} \frac{e^{\lambda \, x} \, v(x)}{\mathbb{E}[e^{\lambda \, X}\, v(X)]} = \frac{v(x)}{\mathbb{E}[v(X)]} .\end{align*}
(3.5)which is a generalization of the exponential premium principle. In the following section, we study further this generalization for
\begin{equation} \tilde{m}_{\xi} = \frac{1}{\lambda} \, \ln \frac{\mathbb{E}[e^{\lambda \, X}\, v(X)]}{\mathbb{E}[v(X)]},\end{equation}
$v(x)=e^{\gamma \, x}$
(where
$\lambda>\gamma>0$
).
-
(iv) An analogous interpretation as the one given in Remark 2.1 for the density
$f_{\tilde{wv}}$
is the following. Applying a probabilistic analogue of the mean value theorem between
$X_v$
and
$X_w$
, we obtain the new random variable
$X_{\widetilde{wv}}$
with pdf
$f_{\widetilde{wv}}$
.


3.1. A generalization of exponential premium principle
For
 $\lambda>\gamma>0$
, we consider the functions
 $w(x)=e^{\lambda \, x}$
and
 $v(x)=e^{\gamma \, x}$
, and hence,
 $\xi(x) = e^{(\lambda-\gamma)x}$
. By (3.2) (or (3.5)), it follows that
 \begin{equation} \tilde{m}_{\xi} = \frac{1}{\lambda - \gamma} \, [\!\ln \mathbb{E}(e^{\lambda \, X})-\ln \mathbb{E}(e^{\gamma \, X})],\end{equation}
where
 $\tilde{m}_{\xi}$
is the (unique) mode of
 $X_{\widetilde{wv}}$
with pdf
 \begin{align*} f_{\widetilde{wv}}(x) = \frac{\int_x^{\infty} \frac{e^{\lambda \, y}}{\mathbb{E}(e^{\lambda \, X})} \, f(y) \, dy - \int_x^{\infty} \frac{e^{\gamma \, y}}{\mathbb{E}(e^{\gamma \, X})} \, f(y) \, dy} {\frac{\mathbb{E}(X \, e^{\lambda \, X})}{\mathbb{E}(e^{\lambda \, X})} -\frac{\mathbb{E}(X \, e^{\gamma \, X})}{\mathbb{E}(e^{\gamma \, X})}}.\end{align*}
Theorem 3.1. The mode
 $\tilde{m}_{\xi}$
of
 $X_{\widetilde{wv}}$
given in (3.6) satisfies the following properties:
-
(i) A two-side bound is
(3.7)
\begin{equation} \frac{\mathbb{E}[X \, e^{\gamma \, X}]}{\mathbb{E}[e^{\gamma \, X}]} \le \tilde{m}_{\xi} \le \frac{\mathbb{E}[X \, e^{\lambda \, X}]}{\mathbb{E}[e^{\lambda \, X}]}.\end{equation}
-
(ii) It holds that
\begin{align*}\frac{d \tilde{m}_{\xi}}{d\gamma} \geq 0 \;\; \mbox{and} \;\; \frac{d \tilde{m}_{\xi}}{d\lambda} \geq 0.\end{align*}
-
(iii) For
$\gamma \to 0$
and
$\gamma \to \lambda$
, we have respectively.
\begin{align*} \lim_{\gamma \to 0} \tilde{m}_{\xi} = \frac{1}{\lambda} \, \ln \mathbb{E}[e^{\lambda \, X}] \;\; \mbox{and} \;\; \lim_{\gamma \to \lambda} \tilde{m}_{\xi} = \frac{\mathbb{E}[X \, e^{\lambda \, X}]}{\mathbb{E}[e^{\lambda \, X}]},\end{align*}


Proof.
-
(i) We have
Since,
\begin{eqnarray*} \tilde{m}_{\xi} &=& \frac{1}{\lambda-\gamma} \, [\!\ln \mathbb{E}(e^{\lambda \, X}) - \ln \mathbb{E}(e^{\gamma \, X})] \\[5pt] &=& \frac{\lambda}{\lambda-\gamma} \, \frac{1}{\lambda} \, \int_0^{\lambda} \frac{\mathbb{E}(X \, e^{s \, X})}{\mathbb{E}(e^{s \, X})} \, ds - \, \frac{\gamma}{\lambda-\gamma} \, \frac{1}{\gamma} \, \int_0^{\gamma} \frac{\mathbb{E}(X \, e^{s \, X})}{\mathbb{E}(e^{s \, X})} \, ds \\[5pt] &=& \frac{1}{\lambda-\gamma} \, \int_{\gamma}^{\lambda} \frac{\mathbb{E}(X \, e^{s \, X})}{\mathbb{E}(e^{s \, X})} \, ds.\end{eqnarray*}
$\frac{\mathbb{E}(X \, e^{s \, X})}{\mathbb{E}(e^{s \, X})}$
is nondecreasing in s, the two-side bound in (3.7) for
$\tilde{m}_{\xi}$
follows.
-
(ii) After some computation, we get
and
\begin{align*} \frac{d \tilde{m}_{\xi}}{d\gamma} = \frac{1}{\lambda-\gamma} \, \bigg[\tilde{m}_{\xi} - \frac{\mathbb{E}[X \, e^{\gamma \, X}]}{\mathbb{E}[e^{\gamma \, X}]} \bigg]\end{align*}
Therefore, by using formula (3.7), the result of part (ii) follows.
\begin{align*} \frac{d \tilde{m}_{\xi}}{d\lambda} = \frac{1}{\lambda-\gamma} \, \bigg[ \frac{\mathbb{E}[X \, e^{\lambda \, X}]}{\mathbb{E}[e^{\lambda \, X}]} - \tilde{m}_{\xi} \bigg].\end{align*}
-
(iii) The result follows directly.


Example 3.1. Suppose that X follows an exponential distribution with parameter
 $b>0$
and pdf f(x) given in (2.5). Consider the following options for the weights w(x) and v(x), when
 $b>\lambda>\gamma>0$
:
-
(i)
$w_1(x) = x \, v_1(x)$
and
$v_1(x) = e^{\gamma \, x}$
, -
(ii)
$w_2(x) = x \, v_2(x)$
and
$v_2(x) = e^{\lambda \, x}$
, -
(iii)
$w_3(x) = e^{\lambda \, x}$
and
$v_3(x) = e^{\gamma \, x}$
.


For each
 $i=1,2,3$
, we also consider the random variable
 $\tilde{X}_i =_{d} X_{\widetilde{w_i v_i}}$
with pdf
 $\tilde{f}_i(x) = f_{\widetilde{w_iv_i}}(x)$
and its mode
 $\tilde{m}_i$
, respectively. In Table 2, for
 $i=1,2,3$
, we determine the distribution of the above random risk trough its pdf:
 \begin{align*} f_{w_i}(x) =\frac{w_i(x)}{\mathbb{E}[w_i(X)]} \, f(x), \;\; f_{v_i}(x) =\frac{v_i(x)}{\mathbb{E}[v_i(X)]} \, f(x) \;\; \mbox{and} \;\; \tilde{f}_i(x) = \frac{\overline{F}_{w_i}(x) - \overline{F}_{v_i}(x)}{\mathbb{E}(X_{w_i}) - \mathbb{E}(X_{v_i})}.\end{align*}
We note that
 \begin{align*} \tilde{f}_3(x) = \frac{\overline{F}_{w_3}(x) - \overline{F}_{v_3}(x)}{\mathbb{E}(X_{w_3}) - \mathbb{E}(X_{v_3})} = \frac{b-\gamma}{\lambda-\gamma} \, (b-\lambda) \, e^{-(b-\lambda) x} [1-e^{-(\lambda-\gamma) x}], \;\; x>0,\end{align*}
and hence,
 $\tilde{X}_3$
follows a Weighted Exponential
 $(\frac{\lambda-\gamma}{b-\lambda}, b-\lambda)$
; see Example 2.2. Furthermore, we have
 $\tilde{X}_1 =_{d} X_{w_1}$
,
 $\tilde{X}_2 =_{d} X_{w_2}$
, and
 $\tilde{X}_3 =_{d} X_{w_3} + X_{v_3}$
. For
 $i=1,2,3$
, in Table 2, we also provide the mode of
 $\tilde{X}_i$
,
 \begin{align*} \tilde{m}_1 = \frac{\mathbb{E}(X \, e^{\gamma X})}{\mathbb{E}(e^{\gamma X})} = \frac{1}{b-\gamma}, \;\; \tilde{m}_2 = \frac{\mathbb{E}(X \, e^{\lambda X})}{\mathbb{E}(e^{\lambda X})} =\frac{1}{b-\lambda} \;\;\end{align*}
and
 \begin{align*} \tilde{m}_3 = \frac{1}{\lambda - \gamma} \, [\!\ln \mathbb{E}(e^{\lambda \, X}) - \ln \mathbb{E}(e^{\gamma \, X})] = \frac{1}{\lambda-\gamma} \, \ln \frac{b-\gamma}{b-\lambda}.\end{align*}
For
 $i=1,2,3$
, the distribution of
 $X_{w_i}$
,
 $X_{v_i}$
,
 $\tilde{X}_i=_{d} X_{\widetilde{w_i v_i}}$
and the mode
 $\tilde{m}_i$
of
 $\tilde{X}_i$
.

In Figures 5 and 6, we drew the pdf
 $\tilde{f}_i(x) = f_{\widetilde{w_iv_i}}(x)$
, for
 $i=1,2,3$
,
 $b=2$
,
 $\lambda=1$
, and
 $\gamma=0.5$
. We observe that
 $\tilde{m}_1=0.66667$
(the lower bound in (3.7)),
 $\tilde{m}_2 = 1$
(the upper bound in (3.7)), and
 $\tilde{m}_3=0.81093$
(the exact value of the generalized exponential premium).
The pdf
 $\tilde{f}_1(x) = f_{\widetilde{w_1v_1}}(x)$
(left part – dashed line),
 $\tilde{f}_2(x) = f_{\widetilde{w_2v_2}}(x)$
(center part - dotted line), and
 $\tilde{f}_3(x) = f_{\widetilde{w_3v_3}}(x)$
(right part – solid line) given in Example 3.1 for
 $b=2$
,
 $\lambda=1$
,
 $\gamma=0.5$
, and
 $0 \le x \le 5$
.

The pdf
 $\tilde{f}_i(x) = f_{\widetilde{w_iv_i}}(x)$
given in Example 3.1 for
 $i=1$
(dashed line),
 $i=2$
(dotted line),
 $i=3$
(solid line),
 $b=2$
,
 $\lambda=1$
,
 $\gamma=0.5$
, and
 $0 \le x \le 2$
.

4. Mode ordering for a class of unimodal weighted distributions
Let X and Y be two continuous nonnegative random variables with pdf’s
 $f_X$
and
 $f_Y$
, distributions
 $F_X$
and
 $F_Y$
, and tails
 $\overline{F}_X=1-F_X$
and
 $\overline{F}_Y=1-F_Y$
, respectively. We assume that
 $X \le_{st} Y$
and
 $\mathbb{E}(X) < \mathbb{E}(Y)$
. Let us also assume that X and Y are unimodal with mode
 $m_X$
and
 $m_Y$
, respectively.
Definition 4.1. We say that the mode of X is smaller than the mode of Y, denoted by
 $X <_{mode} Y$
, if
 $m_X < m_Y$
.
Next, we present a class of unimodal weighted distributions for which the mode is the mean value premium principle.
Definition 4.2. Let
 $X_w$
be a weighted random variable of X, where
 $w\;:\;[0, \infty) \rightarrow [0, \infty)$
is a continuous and increasing function such that
 $0<\mathbb{E}[w(X)]<\infty$
and
 $\mathbb{E}(X)<\mathbb{E}(X_w)$
. Consider also the nonnegative weight function
 \begin{align*} \tilde{w}(x) = \frac{\overline{F}_{X_w}(x) - \overline{F}_X(x) }{f_X(x)}.\end{align*}
We say that
 $X_{\tilde{w}} \in \mathcal{A}_w(F_X)$
if the pdf of
 $X_{\tilde{w}}$
is
 \begin{align*} f_{X_{\tilde{w}}}(x) = \frac{\tilde{w}(x)}{\mathbb{E}[\tilde{w}(X)]} \, f_X(x) = \frac{\overline{F}_{X_w}(x) - \overline{F}_X(x) }{\mathbb{E}(X_w) - \mathbb{E}(X)}.\end{align*}
The mode
 $m_{X_{\tilde{w}}} = w^{-1}(\mathbb{E}[w(X)])$
of
 $X_{\tilde{w}} \in \mathcal{A}_w(F)$
is unique. Let also
 $Y_{\tilde{w}} \in \mathcal{A}_w(F_Y)$
, that is, the pdf of
 $Y_{\tilde{w}}$
is
 \begin{align*} f_{Y_{\tilde{w}}}(x) = \frac{\tilde{w}(x)}{\mathbb{E}[\tilde{w}(Y)]} \, f_Y(x) = \frac{\overline{F}_{Y_w}(x) - \overline{F}_Y(x) }{\mathbb{E}(Y_w) - \mathbb{E}(Y)},\end{align*}
where
 \begin{align*} \tilde{w}(x) = \frac{\overline{F}_{Y_w}(x) - \overline{F}_Y(x) }{f_Y(x)}.\end{align*}
In the following proposition, we prove (under some assumptions) that
 $X_{\tilde{w}} <_{mode} Y_{\tilde{w}}$
.
Proposition 4.1. Let X and Y be two continuous nonnegative random variables with distributions
 $F_X$
and
 $F_Y$
, respectively. Let also
 $X \le_{st} Y$
, and w be a continuous and increasing function such that
 $0<\mathbb{E}[w(X)] < \mathbb{E}[w(Y)]$
. If
 $X_{\tilde{w}} \in \mathcal{A}_w(F_X)$
and
 $Y_{\tilde{w}} \in \mathcal{A}_w(F_Y)$
, then
 $m_{X_{\tilde{w}}}< m_{Y_{\tilde{w}}}$
.
Proof. By assumptions, we have
 $\mathbb{E}[w(X)] < \mathbb{E}[w(Y)]$
. Hence,
 $w^{-1}(\mathbb{E}[w(X)]) < w^{-1}(\mathbb{E}[w(Y)])$
, which completes the proof.
Remark 4.1. The mode order can be also applied when the nonnegative continuous function w(x) is decreasing such that
 $\mathbb{E}(X)>\mathbb{E}(X_w)$
. In this case, we say that
 $X_{\tilde{w}} \in \overline{\mathcal{A}}_w(F)$
if the pdf of
 $X_{\tilde{w}}$
is
 \begin{align*} f_{X_{\tilde{w}}}(x) = \frac{\tilde{w}(x)}{\mathbb{E}[\tilde{w}(X)]} \, f_X(x) = \frac{\overline{F}_X(x) - \overline{F}_{X_w}(x)}{\mathbb{E}(X)-\mathbb{E}(X_w)},\end{align*}
where
 \begin{align*} \tilde{w}(x) = \frac{ \overline{F}_X(x) - \overline{F}_{X_w}(x)}{f_X(x)}.\end{align*}
By using similar arguments as in the proof of Proposition 4.1, we can obtain that if
 $X_{\tilde{w}} \in \overline{\mathcal{A}}_w(F_X)$
and
 $Y_{\tilde{w}} \in \overline{\mathcal{A}}_w(F_Y)$
, then
 $m_{X_{\tilde{w}}} > m_{Y_{\tilde{w}}}$
.
Acknowledgments
The author wishes to thank the referees and the editor for their comments, which improved the paper. This research was financially supported by the MSc program in Actuarial Science & Risk Management of the University of Piraeus through the grant C.908: Development of new methodologies in insurance and risk management.



